Small Cap Value Report (Thurs 30 Mar 2023) - REVB, SHOE, SDG, MOON, TWD, XLM, AQX, LTHM, RBN

Good morning from Paul & Graham.
In case you missed it, here's my audio interview with Belvoir (LON:BLV) recorded yesterday afternoon.
I'll be talking to Portmeirion (LON:PMP) (I hold) today. EDIT: my interview with Portmeirion's CEO has also now gone live.
I enjoy your feedback on these interviews, so do leave a comment if you wish.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Main Sections -
(summaries here, main sections further down)
Moonpig (LON:MOON)
Trading Update - up 17% to 133p (market cap £455m) - Paul - RED
This market leader in online greetings cards & gifts issues a reassuring update for FY 4/2023 - it's trading in line with expectations. It expects a return to growth in FY 4/2024, with an H2 weighting. The market likes MOON a lot more than I do! In the section below I flag up a terrible balance sheet, overloaded with debt, hence no prospect of meaningful divis any time soon. Thumbs down from me, due to poor finances.
XLMedia (LON:XLM)
Final Results - down 9% to 13.4p (market cap £35m) - Graham - AMBER
Reasonable results but 2023 forecasts are downgraded today. The market rates this as if it were a Chinese stock which may be too harsh. Management team is entirely new.
Aquis Exchange (LON:AQX)
Final Results - down 2% to 381p (market cap £105m) - Graham - AMBER
Excellent results. This UK exchange also facilitates trading of EU equities in lit markets and dark pools. High rating justified by extraordinary profitability of successful stock exchanges.
James Latham (LON:LTHM)
Trading Statement - up 5% to 1225p (market cap £246m) - Paul - GREEN
In line with expectations. I have a thorough ponder of how trading might fall back once the bumper profits from pandemic-related factors unwind. I'm a bit worried that 2024 forecasts might be too high, so increased risk of a profit warning. Despite this, the balance sheet is so strong (£100m surplus liquid capital in my view) that shareholders have an immensely big and soft cushion underneath them! Valuation stacks up, even if we assume earnings halve. So it has to be a thumbs up.
Robinson (LON:RBN)
Final Results FY 12/2022 - up 3% to 100p (market cap £17m) - Paul - AMBER
Prompted by a reader request below from MarkT, I've had a quick skim through these numbers, which look quite good. Outlook also seems fine, and in line with expectations. Balance sheet has too much debt, but offset by surplus freeholds. Main downside is lack of liquidity & wide bid:offer spread. Why get involved when larger companies in the sector are also strikingly good value?
Quick comments -
Revolution Beauty (LON:REVB) - Paul - suspended - says it hopes to publish long delayed accounts at end April 2023. Hopes to restore trading in its shares after that. Bank facilities reduced from £40m to £32m, revised covenants, fully drawn, but has £11m cash. Nothing said about trading, but at least it is still trading! Will be interesting to see what happens when the shares return.
Shoe Zone (LON:SHOE) - Paul - GREEN - £3m share buyback starts today. Management owns 55.4% now, and confirm their waiver from the Takeover Code not to be compelled to make an offer for the company (since they hold over 30%). This implies trading is in line with expectations, I think - “The Company confirms that it currently has no unpublished price sensitive information.”
Sanderson Design (LON:SDG) - Paul - GREEN - “Major licensing agreement” with Sainsburys, to provide designs for “a wide range of licensed products” for the Habitat and Tu brands owned by Sainsbury. Products to be launched in Spring 2024. This is the second major licensing deal signed this year (FY 1/2024). No numbers provided, so I assume it won’t affect the current year’s performance? A note from Progressive today says no change to forecasts until next results/outlook details are published.
Trackwise Designs (LON:TWD) - Paul - RED - down c.50% today to only 0.6p - yet more contract problems & delays. Looks set to be out of cash (again) imminently (May 2023), or possibly later depending on what happens with customer re-design of product. Such a pity, as this looks promising technology, but as usual with UK startups, it hasn't been properly funded, so looks set to fail. I suspect it's very near the end of its time as a listed company. too risky to get involved I think.
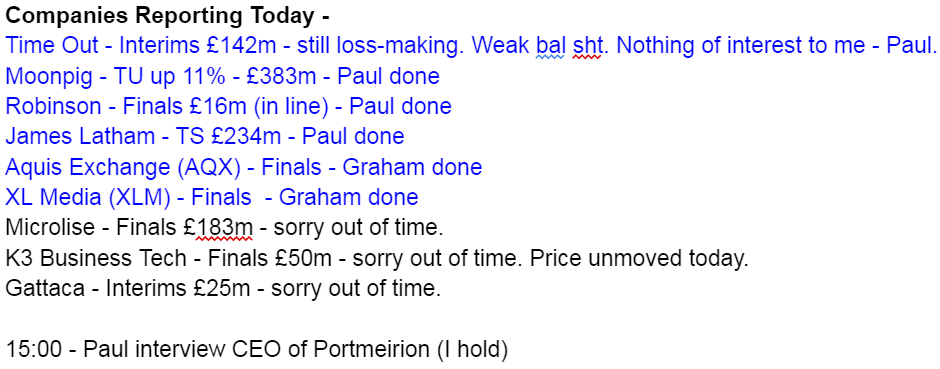
Here's today's to do list -
Paul's Section:
Moonpig (LON:MOON)
128p (up 12% at 08:23)
Market cap £435m
I last looked at this online greetings card/gifts company here on 7 Dec 2022. I viewed it negatively (RED) because interim results showed a balance sheet that had been wrecked with a bad acquisition, and carrying too much debt. Plus I think it’s been impacted by Royal Mail strikes.
The shares are up 11% this morning though, so maybe it’s time to change stance on it?
Trading update -
Moonpig Group plc (the "Group"), the leading online greeting card and gifting platform in the UK and the Netherlands, today provides an update on its trading performance in the current financial year.
This is FY 4/2023.
It looks more like a relief rally that things aren’t getting worse, as this is just in line with expectations (I would have expected more for a +12% share price movement) -
Trading performance has been resilient across the second half of the year to date and Moonpig recorded its largest ever week of sales in the UK ahead of Mother's Day. Accordingly, we confirm that our expectations for Group annual revenue for the financial year ending 30 April 2023 remain unchanged at around £320 million.
Expectations for full year Adjusted EBITDA also remain unchanged, reflecting our disciplined approach to indirect cost management and our flexible business model.
Outlook - not madly exciting -
Looking forward, whilst we remain mindful of the macroeconomic environment, we expect revenue to be in growth across FY24, with the rate of growth weighted towards the second half of the year…
We are excited to return to revenue growth in the year ahead, underpinned by continued investments in our technology, marketing and operational capabilities. As the clear online leader in greetings cards, Moonpig Group is well positioned to benefit from the long-term structural market shift to online."
Re-platforming now complete, so focusing now on driving revenue growth.
Valuation - I can’t find any broker notes. The Stockopedia consensus forecasts graph shows that EPS expectations for this year (FY 4/2023) have been reduced in stages from about 13p last summer, to 10.5p now.
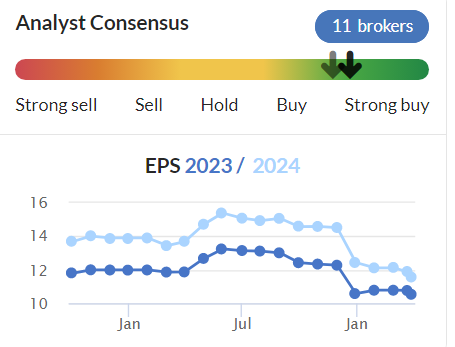
So at 128p per share, that’s a PER of 12.2x - which looks quite a moderate valuation. Although one look at the balance sheet will put off value investors from going near it - NAV was negative at £(57)m at 31 Oct 2022. That included £213m of intangible assets. Write those off, and NTAV is negative a mind-boggling £(270)m - one of the worst balance sheets for any company on the market.
The long-term debt was £230m, which will takes years to repay. Senior bank facilities are committed until 6 Jan 2026. It has partially hedged its interest rate exposure.
That’s far too much debt, with no asset backing. Hence why there are no dividends, and unlikely to be any meaningful dividends in future.
For these reasons, I think a low PER is justified, and this is not an attractive investment to me. I want to receive divis whilst I wait for capital growth, especially now that inflation is taking a chunk out of the purchasing power of our money - investments need to be generating a return to compensate for that. So with MOON shares, it’s a bet on the share price rising, with no income likely from dividends.
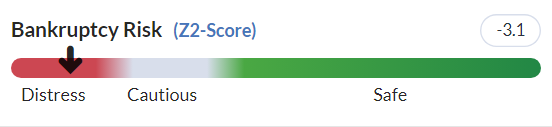
The Z-score is flashing a financial distress warning - remember this isn't infallible, but it's flagging potential risk - to take this risk, I would want seriously good upside potential, which isn't obviously present in my view -
My opinion - I can’t get excited about this. Getting debt down to reasonable levels is likely to take several years, so no divis for now.
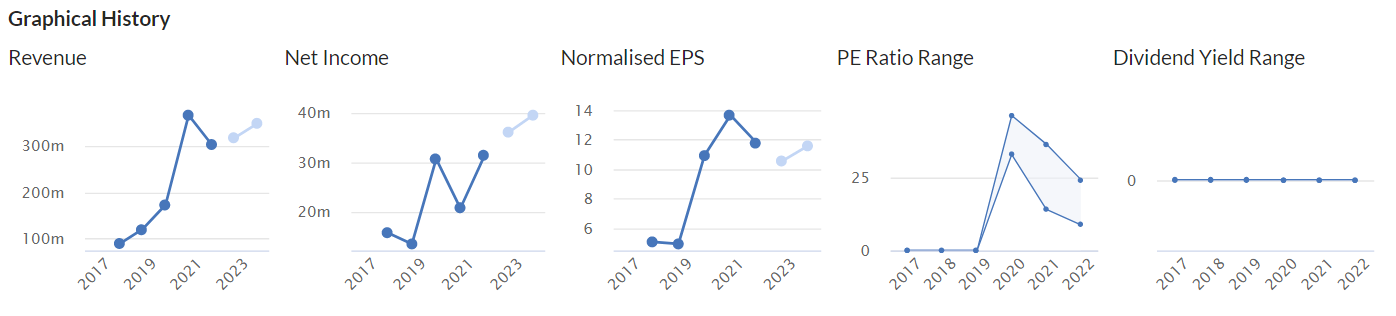
As you can see from the graphs below, the revenue and profit growth has been impressive. The big growth was achieved in the pandemic, but MOON seems to have held on to that growth, instead of slipping back again, so that's a positive -
Today’s update reassures, but doesn’t inspire me to see this as anything particularly exciting.
The extremely weak balance sheet puts me off too - to get comfortable with such poor finances, I’d have to see much stronger profit growth in evidence.
So it’s still a thumbs down from me, due to the awful balance sheet mainly.
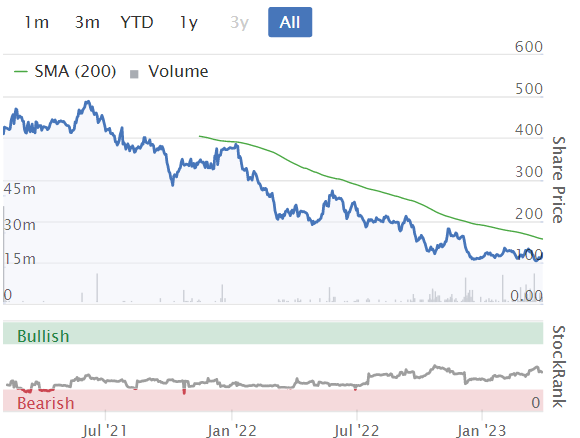
One of many failed 2021 floats - not a vintage year for IPOs! -
James Latham (LON:LTHM)
1225p (up 5% at 10:02)
Market cap £246m
We like LTHM here at the SCVRs, because it’s a well-run, owner-managed business, very conservatively financed, and with a terrific long-term track record -
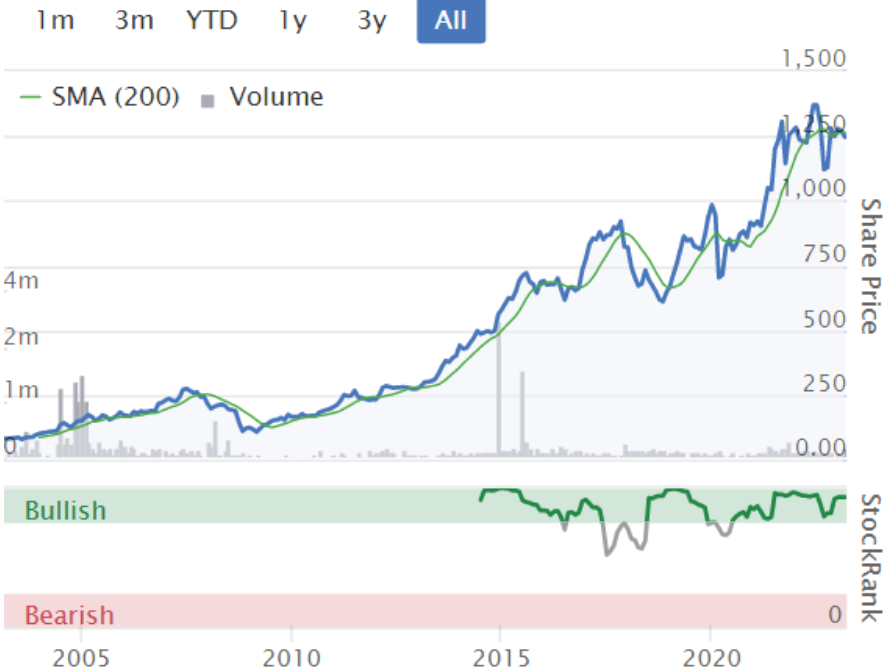
As you can see above from the StockRank chart below the share price chart, the Stockopedia computers are also positive to very positive since they started.
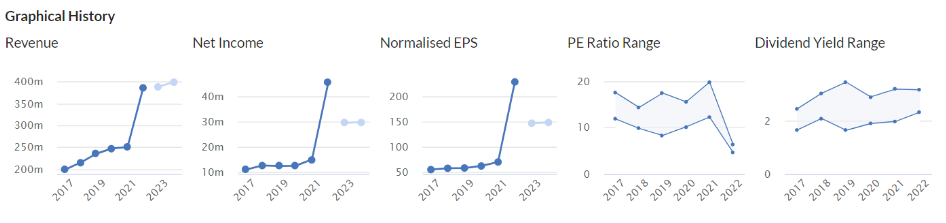
So I’m approaching this with a positive overall impression. However, as you can see from the Stockopedia graphs, it had a massive bonanza during the pandemic, when it was able to greatly increase selling prices, due to strong demand for home improvements, and competitors struggling with supply constraints. This is inevitably going to unwind, as the boom time profits won’t be sustainable -
We’ve seen this same one-off boom effect wreak havoc as it unwinds, on the whole eCommerce sector, and other suppliers of things to the home improvement market - Luceco (LON:LUCE) springs to mind.
So valuing shares like this is really all about ascertaining what future profitability is likely to settle at, and how much of the growth is structural, and how much one-off in nature? Tricky.
There’s also a further complication where companies and their suppliers built up inventories to ensure access to product. Which has now caused some companies to warn on profit, as customers retrench their new orders, and resulted in gluts of finished goods (readers, especially planetx have been discussing this in the comments - apparently there’s a glut of bicycles right now, so maybe a good time to negotiate a discount?!)
So I’m approaching LTHM with all those uncertainties in mind.
Looking at those graphs, a return to trend profit/EPS would suggest something like 60-70p EPS might be a reasonable level to value the shares on. That would be a PER of about 19, which seems high until you look at LTHMs balance sheet. It’s stuffed full of cash, which accumulated in the boom, and is still in the company’s bank account. So we need to add on an extra amount to the shares valuation above what we would value it on based solely on future likely earnings.
Current broker consensus EPS is around 147p for both FY 3/2023 and FY 3/2024. That’s about double what I see as the normal trend level, so clearly we shouldn’t be valuing this share on a multiple of these bloated earnings forecasts, as those levels of profit are extremely unlikely to be sustained as supply chains & costs normalise.
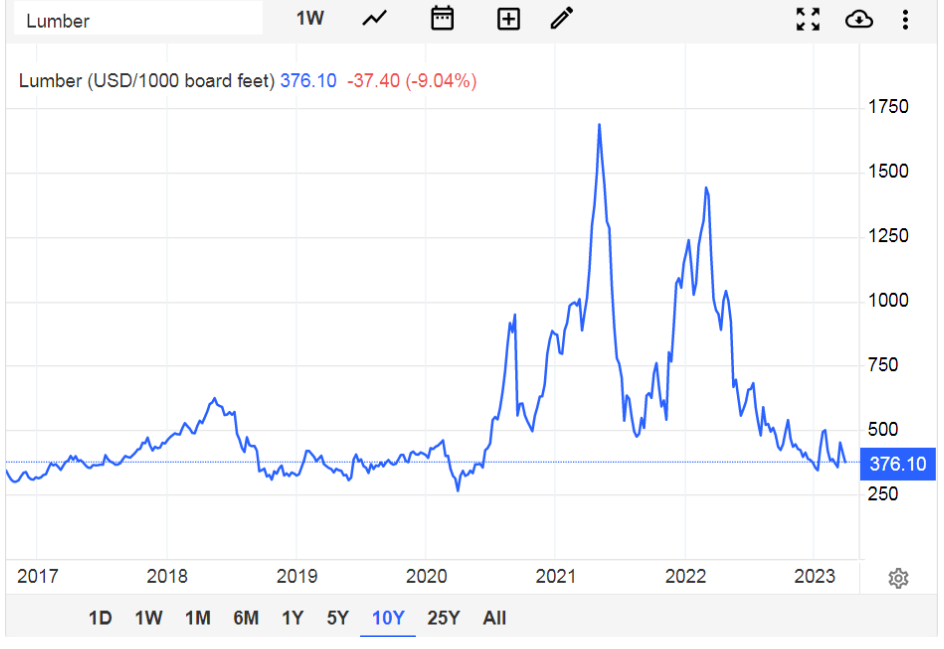
Here’s the chart of lumber (wood) courtesy of TradingEconomics website here. The price is now back to normal, after some crazy gyrations during the pandemic -
It’s all getting a bit complicated isn’t it!
Enough background musings, let’s get onto today’s update -
The Board of James Latham provides the following trading statement ahead of the Company's results for the year ended 31 March 2023.
Revenues - strong, slightly ahead of market expectations.
“Cost prices have stabilised”
“Few signs of price weakness in the immediate future”
Sales volumes similar to last year.
Overheads continue to rise (as expected).
Profit before tax (PBT) will be in line with market expectations.
Balance sheet & cash “remain strong”.
Diary date - 29 June for publication of FY 3/2023 results.
That’s light on detail, but tells us the key thing we need to know, in line with market expectations.
As mentioned above Stockopedia has consensus of 147p for this year, so the PER is only 8.3x, but as we know, this level of profitability is highly unlikely to be sustainable in the longer term.
Hence I would say the 148p forecast for FY 3/2024 (next year) looks very vulnerable to a profit warning. because supply chains are easing, input prices are falling, and sooner or later that’s bound to see excess profit margins eroded back down to more normal historic profitability.
Balance sheet - no figures provided today, but it’s such a big part of the valuation of this company, I need to flag it.
Last reported as at Sept 2022, NAV was £181m (which will have gone up since). Intangibles were only £3m, so NTAV was £178m, or 72% of the market cap.
NAV jumped from £119m to £164m in just one year, from Mar 2021 to Mar 2022. Then up again to £181m 6 months later in Sept 2022. So we can clearly see how the assets are piling up, due to bumper pandemic trading. That’s real shareholder value accumulating. A lot of it has been sucked into inventories and receivables though.
The March 2022 Annual Report shows that fixed assets is mostly freehold land, with a book value (at cost) of £26m. I bet that’s worth well above book value too. Lathams was founded a long time ago, and floated in 1986 apparently.
I do like old school, family controlled businesses, as their balance sheets can be a treasure trove of value, and they’re usually super-conservative, not taking the risks that hired hands often take to trigger their lucrative share options, or just walk away with no consequences if it goes wrong.
By now, NTAV is probably knocking on the door of £200m, and something nice could happen - special divis, buybacks, acquisitions, who knows?
How much value to attribute to the excess capital on the balance sheet? I think there’s about £100m of surplus capital on the balance sheet. I’ve worked that out by applying a current ratio of 2.0x to the balance sheet, so £84m current assets, instead of actual of £181m.
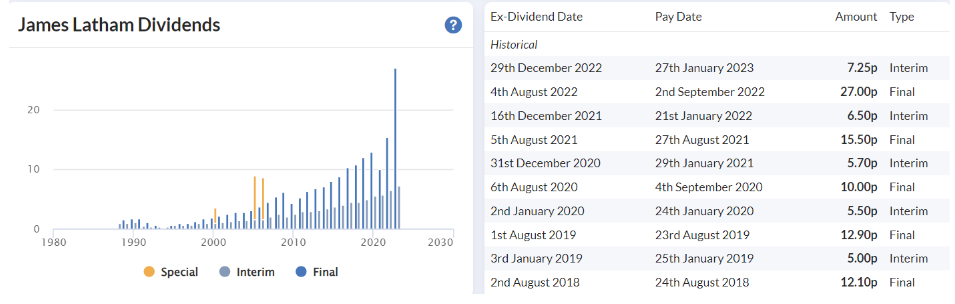
It did pay special divis in 2000, 2005, and 2006, so that could happen again maybe?
Even if the family decide to just sit on the cash pile, at least now they can earn some interest from it.
The 2022 final divi was much larger than usual, as you can see below, so I imagine shareholders should receive good divis in future due to the almost embarrassingly strong balance sheet -
My opinion - wrapping this up, my preferred method of valuation would be to ignore current trading as still untypical, and instead assume EPS might be heading for about 70p as a long-term, sustainable level - less than half current trading, so I’m being really prudent here.
I’d be happy to put that on a PER of 12 times, which fits into the PER bands of previous years, towards the lower end, which is necessary given that interest rates are now much higher, so PERs should be lower than we got used to in 2008-2022 zero-interest rate world.
That’s 840p value for the company.
I’ll then add £50m (248p per share) for half of the excess value (since the family will never pay out all the surplus capital I reckon is about £100m.
That gets me to a total (prudent) valuation for LTHM shares of 1088p.
The actual current price is 1225p, which is 13% above my theoretical valuation.
I think that’s close enough for me to go GREEN on this share, as there are so many things I like about it, and I’ve been really quite conservative with my valuation method. Thumbs up.
Robinson (LON:RBN)
100p (up c.3% at 13:52)
Market cap £17m
Robinson plc ("Robinson" or the "Group" stock code: RBN), the custom manufacturer of plastic and paperboard packaging, is pleased to announce its audited results for the year ended 31 December 2022.
To save my re-typing it, here’s a picture of the highlights table -
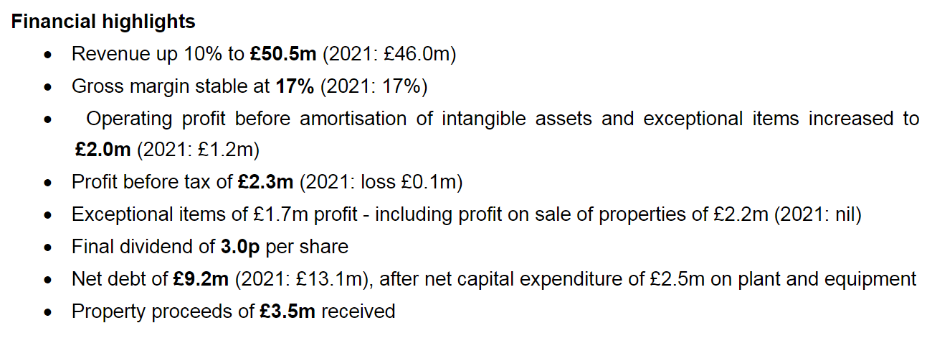
Looks promising.
Pension scheme - previously announced, this has been hived off, so no longer an issue at all.
“Substantial capital investment” in 2023 for new projects. Will increase revenues from 2024, but it does highlight the capital-intensive nature of this sector. I prefer to see companies leveraging existing assets for growth, not having to spend up-front.
Cost inflation - it’s “seeking substantial price increases from all customers for 2023” - I’d prefer to be hearing that cost increases have already been agreed, not that they’re being sought.
Outlook - expecting 2023 operating profit to exceed 2022, and be in line with expectations - sounds good , given the macro uncertainty.
Medium term target to achieve 6-8% adj operating profit margin. Great, if that’s do-able. It’s a competitive sector though, so might be harder to say, than do.
Surplus properties - it says today £8.1m fair value, versus £2.8m net book value. Disposals ongoing, and could take time, but that should cover most of the bank debt, so it’s material for valuing the shares.
Dividends - very good, total 5.5p, excellent for a 100p small cap. But as others have pointed, out the wide bid/offer spread on the shares would probably consume at least a year’s divis. Although the actual market price is often well inside the quoted spread, so it’s worth checking with a dummy trade. I just tried, but was rejected with an “insufficient funds” reply!
Balance sheet - pretty solid. There’s too much bank debt, but that’s mostly supported by the surplus property value, so I think it’s fine to offset those.
My opinion - worth investigating further I think. Although personally I don’t see a lot of point going right down to something this tiny, when other packaging companies like Macfarlane (LON:MACF) and the larger ones, are such good value, and you won’t have problems with liquidity or bid/offer spread with those larger companies. Hence I’ll just say I’m neutral on RBN. But there's nothing serious wrong with it, so I wouldn't try to talk anyone out of investigating this share further.
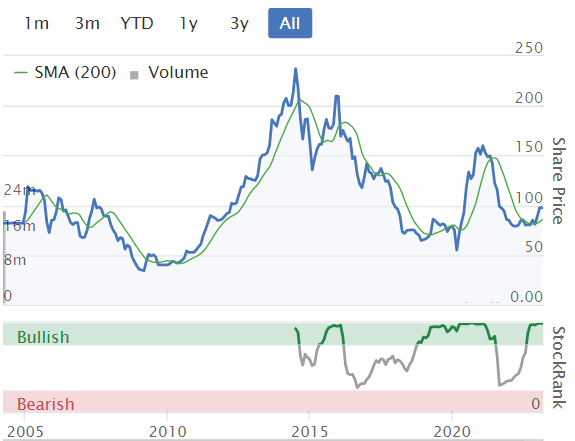
Very high StockRank of 98, and the share price chart looks like it might possibly be starting an uptrend?
Graham’s Section:
XLMedia (LON:XLM)
Share price: 13.36p (-9%)
Market cap: £35m / $43m
This stock has been trading very weakly in recent times:
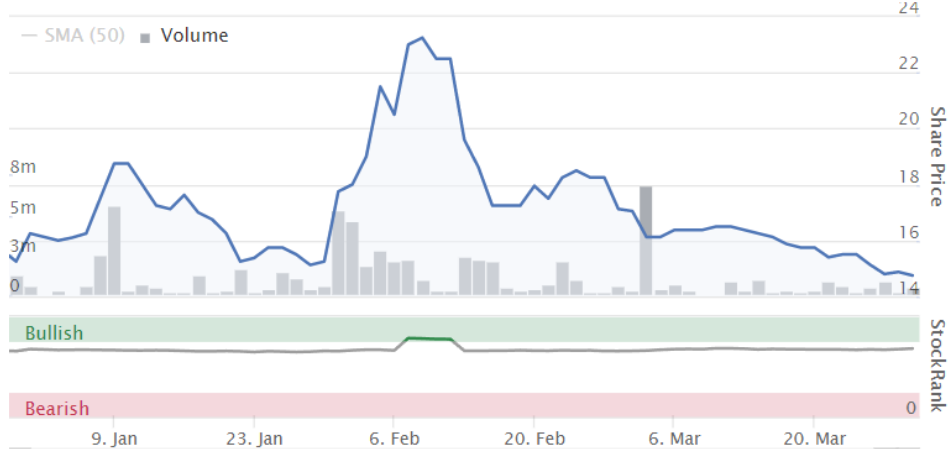
At 21p in early February, I thought it could potentially offer some value. So I’m intrigued to see it below 15p!
Let’s find out if today’s full-year results for 2022 can help to illuminate matters.
Financial highlights for continuing operations, focusing on XLM’s sports and gambling-related activities::
Revenue +24% to $72m
Operating profit $5.1m
Cash balances $10.8m
NB: XLM is treating its personal finance websites as discontinued operations, so their contributions are excluded from the revenue and profit figures above. However, the personal finance websites have not yet actually been sold.
US expansion: XLM is now active in all 19 regulated online sports states in the US.
Management team: 2022 saw the installation of a new Chairman, CEO, CFO, COO, CMO and Company Secretary. This all follows a collapse in trading in 2020, after Google manually demoted 100 of its casino websites.
Google doesn’t do that sort of thing lightly, so I interpret this as reflecting very poorly on XLM’s prior management and on the quality of the demoted websites [disclosure: I’m a shareholder in Alphabet ($GOOGL).]
Another change is that an entire layer of management was removed both in XLM’s US and European operations. Overall headcount is reduced from 267 to 193. So it is a very different company compared to two years ago.
Outlook:
The Group has made a solid start to 2023 with the launch of online sports betting in Ohio on 1 January 2023 with early performance in-line with management's expectation. The immediate focus is now on growing revenues from the recent launch of online sports betting in Massachusetts which went live after the NFL season had finished, and as a result, we expect revenues in this state to grow more gradually.
No other states are expected to launch in 2023.
And a quick excerpt from the CEO comment:
"We made good progress in 2022, having re-engineered the business to become one of the leading sports betting affiliates in North America and our US business is expected to continue to evolve at a rapid pace as the market starts to migrate from up front acquisition payment to revenue share agreements.
It's nearly always preferable to generate revenue that is more recurring and predictable each year, rather than one-off in nature.
XLM is therefore negotiating with US operators to achieve a “hybrid” model, which will have a lower upfront payment and then an ongoing revenue share.
My view
I’m very tempted to change my rating on this from Amber to Green, since the valuation has reduced significantly. The enterprise value is now only $33m.
However, it’s important to understand that the word “spike” is mentioned eleven times in today’s report, referring to the short-term bounce in revenues that XLM experiences when online sports betting is legalised in new states. The revenue figures achieved in 2022 may not be very easily repeatable, without new state launches.
Indeed, the broker Cenkos has this morning reduced its FY 2023 revenue estimate from $72m to $70m. So it is now expecting revenues to decline marginally in the current year.
Cenkos also reduces its adjusted profit estimate for FY 2023 from $10m to $8m.
Despite these downgrades, the stock could still be viewed as very, very cheap quantitatively speaking. I almost feel forced to give this stock the thumbs up when it is so cheap.
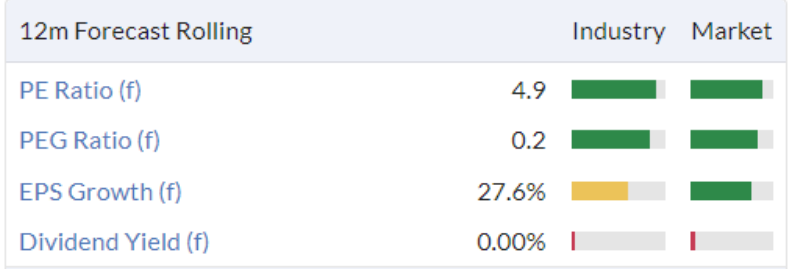
If we had something between Amber and Green, that’s what I would choose. I will stick with Amber for now. It is rated like a Chinese stock, which may be unfair:
Aquis Exchange (LON:AQX)
Share price: 381p (-2%)
Market cap: £105m
Some nice results from this stock exchange:
Net revenue +24% to £20m
PBT +27% to £4.5m
Cash £14m
2022 was a very difficult year for AIM and for many other equity markets, which I think puts these results in an even better light. Aquis had 22 IPOs, “the most of any growth company exchange in the UK”.
Current trading is in line with expectations.
The company has just finished a rebrand and now has three divisions:
Aquis Markets: a subscription-based service that offers secondary trading for 16 European markets, now including dark pools. Impressively, the company claims that in Q4 it achieved a 5.2% market share of all EU secondary market trading.
Aquis Technologies: software and technology division.
Aquis Stock Exchange: this is the bit that most of us are already familiar with. It’s the exchange below AIM. You can find a list of its stocks here, including their market caps. This exchange moved into profitability ahead of schedule during 2022, and there is a pipeline consisting of a further 50-60 companies who are looking to IPO.
Balance sheet: net assets of £23m, almost fully tangible.
My view: investors will be aware that a successful stock exchange is a life-changing investment. Here’s the share price for the London Stock Exchange:
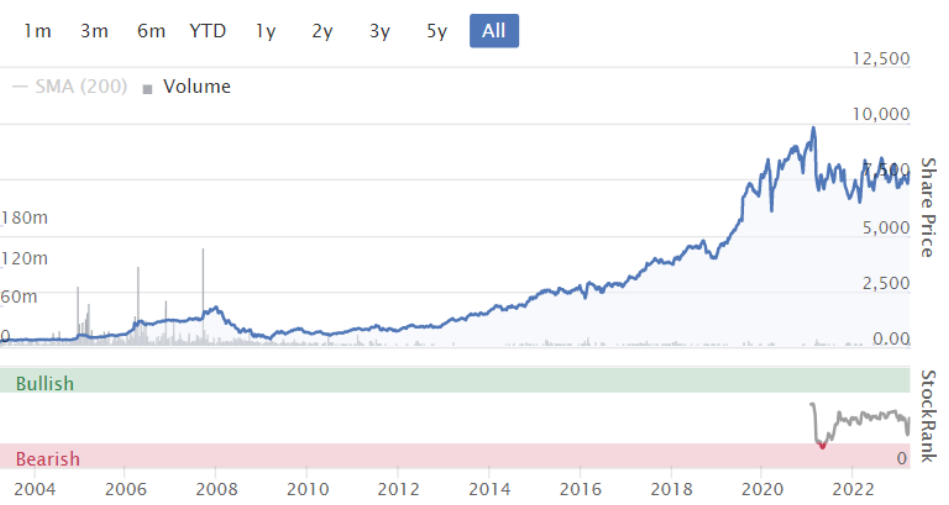
The key word here is “successful”. Aquis might fall by the wayside. However, it claims to have a differentiated business model that is working:
[The Aquis trading facilities] apply a non-aggressive trading model, which means that certain types of trading behaviour are not allowed, and it encourages more passive trades to rest in its order book. This creates greater depth of liquidity and less potential for information leakage or "toxicity" in the market. Independent studies have verified that Aquis' non-aggressive trading model has materially lower toxicity than its competitors, which reduces adverse price movements thereby lowering the implicit costs of trading for the end investor…
The principal competitors to Aquis' business are the incumbent national exchanges and other pan-European trading venues. In secondary markets they charge customers on a per transaction model to allow fully aggressive trading.
Given that Aquis is profitable and growing, and given that stock exchanges can be some of the most incredibly successful investments when they work out, I think the high rating here might be justified.
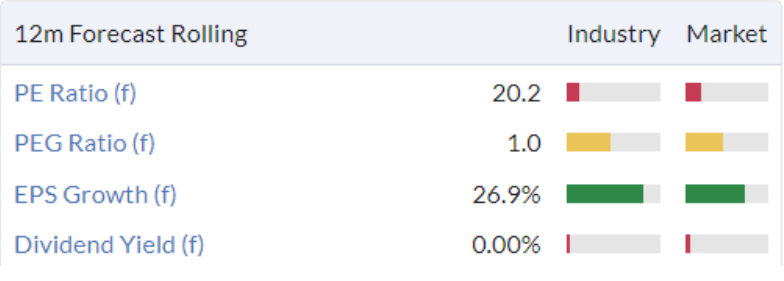
Consolidation is a major trend in this sector, so it’s unlikely that Aquis will maintain its independence if it does continue this positive momentum.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

40 comments
Many thanks for the thinking on James Latham (LON:LTHM) Paul, it's something I've been happy to hold for a while now. Your comment about long term family businesses, reminded me of a post from Motley Fool a long, long time ago where someone was running a portfolio of family businesses with their child as a learning exercise. I recall (maybe incorrectly) they they had used a list of UK listed businesses with a significant family holding/invovlement as a starting point for further research. I've tried looking, but not found anything similar - anyone know of anything like this? Thanks in advance!
Just listened to your interview with Belvoir (LON:BLV) Paul, was very good - a big thumbs up !!
The latest RNS yesterday from Inland Homes (LON:INL) reminded me of my good fortune in selling in Feb 2021 at 56.25p taking a 35% loss.
I was strongly influenced by Paul Scott who in the SCVR of 26th October 2020 commented very negatively on the behaviour of the then CEO of Inland Homes who he described behaved "like a petulant child" when challenged. This turned out to be a Company which was run for the benefit of the Directors and certainly not the Shareholders. I suspect in the fullness of time there will be a lot of very disturbing behaviour uncovered here.
Paul, could you look at EAAS – Eenergy who came out with excellent figures yesterday? Thanks. Chris
Quiz (LON:QUIZ)
Just noticed this is on the move upwards today with higher than average volume. I guess people are hoping for a good TU next week - and to be fair if they hit forecast they look good value.
Only have some beer money in here at present but if the story continues positively I'll be adding.
Phil
(NB huge spread {normally can get well inside} and liquidity can be a problem)
Up 15% currently - maybe an element of "risk on" today in the markets but it does seem like a big uptick. Volume currently 3x higher than daily average so that's good too. I can't see any other relevant news about.
Quiz (LON:QUIZ) always seems to trade upwards as it moves towards TU/Results and then drifts in-between. Mainly liquidity driven.
Is it possible that IC has tipped Quiz (LON:QUIZ) ?
Just checked IC. No mention of Quiz (LON:QUIZ)
I would also expect a good trading statement from CCC tomorrow.
This has been chosen twice by Rolalnd, in his sustainable dividend and Buffet like share over the last month.
May well be to do with H&M doing so well & thus overall sentiment in this sector...I see Boohoo up too.....
Trackwise Designs (LON:TWD)
I have followed this since it was ascending towards the 100p mark and was close to pressing the buy button a couple of times but mercifully didn't. As Paul writes: Such a pity, as this looks promising technology, but as usual with UK startups, it hasn't been properly funded, so looks set to fail.
This has prompted me to send this to the green button -
This morning's further bad news from Trackwise Designs (LON:TWD) once again highlights the idiocy of your policy of not removing forecasts that have been suspended/discontinued. When are you going to change this? In this case we have a share price that has halved this morning to 0.6p and you are showing finnCap's eps 5p and PT 315p both suspended on 30/9/22. This gives a forward p/e of 0.12 no doubt helping the Value Rank of 74 and an upside of 52,400%. If only!
Paul, congratulations on your interview with Dorian a Gonsalves of Belvoir (LON:BLV) . A great interview, very open and engaging. Dorian comes across as such a genuine and honest individual. I fully admit to an element of bias in that I do hold the shares and have done so for sometime.
I look forward to your interview with Mike Raybould, CEO of Portmeirion (LON:PMP) that I was fortunate to buy towards the bottom of its trading range. I like the strategy that the management team has put in place to increase the geographical spread of its sales and improve margins, ultimately to 12.5%,or thereabouts. The principal negative for me is the minimal management share holding, which I find difficult to fathom, given the progress the company appears to be making
Strikes me as a 'sitting duck' for an acquirer at the current price, given its heritage brands. Time will tell.
All the best
I also hold Portmeirion (LON:PMP) and will be interested in the interview. Shares do look cheap and hopefully selling crockery is a fairly defensive business and one that is difficult to muck up (although mistakes were made in the past - eg allowing paralell sales into South Korea). My household has recently bought a new set (Royal Worcester) and we are very happy with it.
I do have some doubts about the management. The CEO is a chartered accountant and the ex-CFO and seems on top of the numbers - but (I know this is subjective) does not to express a lot of passion for the product. For example, they did what may be a clever acquisition of a brand out of administration last year - it is justified on the recent ImC call for increasing factory utilisation (very valid) - but not in terms of here is a useful brand we can develop. Being cruel and a bit unfair, it seems as if the company has two CFOs.
Also, targets have been reduced. In the Feb 2021 CMD (I think slide 46), the target was to get to 13%+ margins. On the recent ImC presentation, the long-term target (although sometimes it seemed downgraded to an aspiration) was 12.5%. They were asked explicitly (Q2 in the Q&A - not by me) why the target had been moved down - the CEO said that the targets had not been changed. I could not reconcile this.
But the P/E is low, growth in the US and RoW has some momentum and given the long-life of most of the products, I am not too worried by the inventory levels. I own it on the basis that the share prce could rise 50% and it would still not seem expensive.
Wimbledonsprinter re: Portmeirion (LON:PMP) (I hold) I too am looking forward to the interview with the Portmeirion CEO. I note your concerns about management. I always have concerns about management - having learnt the hard way.
I note your concerns about the CFO becoming the CEO. Doesn't always work well. When previously researching Portmeirion (LON:PMP) I had a look at his CV - and liked his previous experience with multi-brand manufacturer (Vax etc iirc). I get the feeling that he does understand the brands and is very keen, perhaps more than he seems, to get the most from them. I'm also impressed that for an ex-CFO he seems to be willing to invest seriously in the business.
He has previously said that he saw no immediate reason to acquire further brands - as there is so much further to go with the existing brands. Then they bought a small fragrance manufacturer from the receiver.
So I took his explanation of why they made an acquisition - in the context of his previous statement that they didn't need to make one. But in this case they do to get the most from their existing brand? I thought that they were quite positive about AromaWorks - to the extent that they may almost think its better than the brand they already had - but then I prefer management to be understated and over-deliver and I'd prefer an ex-CFO to an ex-sales director. But thats just me.
I've had a look at last year's presentation and slide 13 presents the 'ambitions'
AMBITIONS
OUR BUSINESS MODEL
By delivering on our strategy we will:
• Sustainable sales growth
• Increased operating margins
− Short term target - back to 10%
− Medium term target 12-13%
− Long term 13%+
• Reduce further our impact on environment
and then this year with
2022
Medium & long term targets for significant operating margin growth
• Operating margin medium-term target 10% and long-term 12.5%
I did wonder why he repeated 12.5% in the Q&A, it's an oddly specific number as a target?
It is fair to say he's changed the numbers. A little bit. I mean are we splitting hairs over 0.5% or is it more about trusting management?
For me its more about trusting management (as far as I am able) and I think it's quite likely that he didn't mean to give the impression that the numbers had changed. In that he's actually changed the time-scales rather than the numbers, and 13%+, ie a little bit above 12.5% is still quite possibly the aspiration, even if it takes a bit longer to achieve. So when he said that the numbers haven't changed he did mean it, in his mind they haven't. I did wonder about this during the presentation - because 12.5% seems so odd - I am willing to give him the benefit of the doubt and assume that its a case of mis-presentation? But I shall be listening to Paul's interview all the more after considering this,
cheers
Mark
Thank you Graham for your considered opinion on XLMedia, we'll spin the wheel as it were for another year, we might add to too many already if it goes much lower, in for a penny and all that.
XLM - good luck, JASVFS! I'm very curious to find out what is the "catch" at this market cap! G
Petrotal (LON:PTAL) a few interested folk on this one I think. Results out today were excellent. Company has fully repaid its bonds and should have around $100m of net cash equiv position, now embarks on a capital return program that looks like it will be a 10% share buyback as well as a quarterly dividend equating to around 10% yield on todays price. Feels to me that production guidance has been set deliberately low in case of low waterlines in river shipping later in the year again. At the moment they are way outstripping guidance by about 30%. Expectations on oil price are around $84 for the year which feels about right/slightly conservative but they have low opex and hedging in place.
Morning All,
Robinson (LON:RBN) 2022 FY results look good this morning. A divi paying 99 stockranker that qualifys for the tiny titans screen. Sales and profit up, margins stable, debt down, and trading at under T. Book. Surplus property disposals and pension scheme buy-in completes the picture. 2023 outlook "ahead of 2022". Deep value? History chequered? I'd be interested to hear from other holders and also whether Paul or Graham had a comment?
Agree Mark. I hold . Their emphasis on sustainable packaging will be a big growth area
A great company but the spread is about 10%. So you need to hold for perhaps more than 4 years to make this viable.
Thanks Mark T,
That's a very nice summary of Robinson (LON:RBN) - I'll have to take a look at it, now you've whet my appetite!
Regards, Paul.
Thank you for summarising Robinson (LON:RBN) - I have considered buying in the past but as Macfarlane (LON:MACF) is one of my largest long term holdings I've not done so. Though it would have paid me handsomely to be in RBN instead of MACF for the last year.
As a readacross to MACF I keep half an eye on RBN and took a look this morning, The results headline some very healthy looking numbers. £2.3m pbt which comes out in the P&L as 14p statutory eps - but is apparently in line with the forecasts shown on the stocko report as (underlying adjusted) 1.2m and 7.2p.
It's taken me a while to figure that out as there is no reconciliation in the results. But it does indeed look to be in-line. The statutory eps is flattered by the 1.7m exceptional profit and zero tax charge this year. Adjusting for exceptionals and amortisation and adding a notional 20% tax charge gets to the underlying adjusted 7.2p putting the shares on 13.8x current profits - which seems quite fully valued for the sector?
The company certainly has an impressive history and I hope they do well. I've driven past the old Chesterfield mill site - quite huge. They have got quite a lot of property still to sell off - so perhaps they can keep this going for a couple of years yet?
Some of the other statements in the report are a little bit more concerning? The revenue gain of 10% is almost entirely down to the Danish acquisition - the effect of increases in their prices mean that the underlying volumes were down 10%.
The gross margin is 'stable' at 17% - but that's not high for a manufacturing business and the new Danish subsidiary is said to be below this. Looking at MACF's manufacturing division which had revenues of £30m in 2022 - the gross margin was around 40% .
Cashflow of 7.6m (5.4m) is said to have improved primarily through squeezing suppliers (though I can't immediately reconcile the £1.9m increase in payables in the cashflow statement with the decrease of 700k in the balance sheet).
They need to keep paying down the debt as well as invest in the business - so the proceeds from the property sales are not really surplus to requirements ? And they are paying a chunky dividend of 5.5p annually which seems high given the performance of the underlying business?
There seems to be a lot of work still to do - to pay down the debt and to raise the performance of the underlying business to support the current share price (which has done very well in the last year) let alone continue the upward trajectory? It remains to be seen whether their large customers will take the price increases they need to put through without further falls in volume? I hope that they can do it - but I'd need to look in a lot more detail to understand what's so special about their products - the current margins suggest their don't have a large moat?
But perhaps I've misunderstood, certainly the market seems to think so?
cheers
Mark
It looks as though the early bounce in H&T might be belated recognition of the CEO spending £107,000 on shares on the 28th? We hold Ramsdens so I watch both companies announcements.
Share price drift + Joint broker announcement Equals (LON:EQLS) what usually?
To counter my earlier bleating somewhat, we hold Getech which imo has potential to be a multi-bagger. It's RNS today on receiving a Government grant of £500,000 towards development of a green hydrogen hub in Inverness, should help to raise it's profile in this and its other very worthwhile projects.
I never quite understood why Getech (LON:GTC) is strategically placed to succeed with hydrogen hubs?
I know they can provide the seismology data to find good locations for hydrogen storage underground.
But do they have expertise in everything else required to get a hydrogen hub live?
Basically - why are they going to be able to make good money from this exciting idea, and not someone else?
My morning smallcap tweet: Come the Revolution
Revolution Beauty (LON:REVB) Trackwise Designs (LON:TWD) Genedrive (LON:GDR) James Latham (LON:LTHM) Sanderson Design (LON:SDG) Trakm8 Holdings (LON:TRAK) John Lewis of Hungerford (LON:JLH) Tasty (LON:TAST), Nexus Infrastructure (LON:NEXS), Moonpig (LON:MOON), Robinson (LON:RBN)
◄Revolution Beauty (REVB)► FY22 audit publication now expected before end of April, not March. Debt facility reduced to £32m from £40m, and is fully drawn. "This reflects the Group's cash requirements." [SP=8.25 Cap=26m]
◄Trackwise Designs (TWD)► delay to delivery of large order while the EV OEM undertakes a redesign and validation of the Parts to meet their revised design requirements. Guides FY22 rev £7.52m and pre-tax loss of £7.71m. In line? Co expects to recognise a 100% impairment of its investment in Stevenage Circuits Limited andn. a 100% impairment of the inter-company loan. [SP=1.15 Cap=6m]
◄Genedrive (GDR)► MT-RNR1 ID test receives positive final recommendation by NICE Test identifies babies with the MT-RNR1 genetic variant who may be at risk of hearing loss if given aminoglycoside antibiotics. [SP=36.89 Cap=34m]
◄James Latham (LTHM)► guides FY-Mar rev slightly ahead of market expectations but pretax in line. Few signs of price weakness in the immediate future. [SP=1167.5 Cap=235m]
◄Sanderson Design (SDG)► major licensing agreement with Sainsbury's for its Habitat homewares and Tu clothing brands. [SP=122.22 Cap=87m]
◄Trakm8 (TRAK)► contract extension to 2027 with Iceland Foods. [SP=14.8 Cap=7m]
◄John Lewis Of Hungerford (JLH)► H1-Dec. Guides FY rev c.£12m amd adj pretax up. In line? [SP=1.56 Cap=3m]
◄Tasty (TAST)► FY-Dec. Current trading ahead of management expectations. [SP=2.3 Cap=3m]
In line: NEXS, MOON, RBN
Thanks for the Belvoir (LON:BLV) interview Paul, looking forward to listening to that.
Today Secure Trust Bank (LON:STB) issue Full Year 2022 results. The share price has been hit hard by the bank turmoil but these results look excellent compared to forecasts. I see David McCreadie, CEO a very safe pair of hands. He was a NED before becoming CEO. Video & podcast.
Secure Trust Bank (LON:STB) is indeed interesting and after watching the CEO's presentation (thanks Tamzin) I agree he seems like a safe pair of hands. I held briefly until I discovered why the market has been pricing the shares so low for such a long time. It seems to be nothing to do with the recent (current?) banking crisis. I think the answer is that the bond market really does not love them - they recently had to pay 13%. I took that as a warning signal. The relevant RNS is here: https://www.londonstockexchang... I am absolutely useless at navigating bonds, therefore if anyone knows more about how to interpret this bond issue I'm all ears.
I bought STB, held for a while, then sold and took profits on the capital raise announcement. My question now is whether it is worth buying back in at the new, lower, price.
At a macro level, it is worth reading the Pershing Square annual report today. There is a lot more trouble brewing in the US mid tier bank market. The news doesn't seem to have reached the UK.
At a stock level, I would say that these results are pretty well in line with expectations. I don't like the presentation of the results; impairments are a feature of banking and should simply be included in all numbers.
So what of the results? In my view; revenues up, impairments well up and likely to worsen, margins down and may well go a good bit lower because of the increased cost of capital (which is only mentioned in respect of customer deposits). EPS slightly ahead of expectations, which have been well managed.
There is a serious push into retail finance of lowish quality. Interest rates will have to be high to cover the cost of capital.
Likely outcome? Who knows, but I would guess fairly static profits for a year or two on increased revenue, because of the increased cost of capital allied with higher impairments. EPS will struggle to keep up.
I'm afraid that this is all a guesstimate by me though; I'm no expert.
Share value? I'd have thought that the share price is on the low side, despite the risk. The yield is excellent. I'm not falling over myself to buy back in.
To save you the bother, here is the headline bank comment from Bill Ackman of Pershing.
'There are reportedly ~$620 billion of mark-to-market losses on banks’ security portfolios that are not currently reflected
on bank’s financial statements'
Yes, but not every bank. The problem is that some banks were chasing yield and buying long duration which are highly sensitive to interest rate rises. Those are where the large losses lie particularly in the US where the rate of rate change was over aggressive and the liquidity ratio isn't mandatory.
In the UK if you take Arbuthnot Banking (LON:ARBB) for example who had great results out today you won't find that, nor the likes of Osb (LON:OSB
Secure Trust Bank (LON:STB) always looks cheap but for me is too far down the retail credit quality curve for my liking. You have to be very comfortable with their credit model and funding to own it in my view. I guess thats why the bonds are 13%.
Like in every business sector not all companies are equal.
Arbuthnot Banking (LON:ARBB) better results to come made 4million in September at lower interest rates. I hold
agreed - in the results there was also a loss on a property that won't repeat and a share of subsidised profits not included. I think actual results would have been 150p eps if these weren't there. Then combined with the circa £4m p/m profits coming through we could see EPS double to 200p. Need to check this out a bit more thoroughly. But nonetheless has book value of 1411p so trades at a big discount to book, conservative business model and 4 or 5* earnings. Dividend increasing too - should be 5%+ over coming year.
On Bill Ackman and Pershing Square he is a great investor and well worth following on Twitter. I hold some PSH as well. I agree with his excellent comments on the US banking crisis. Central bankers could well have a busy year...again.
US banks have to disclose the fair value of their held to maturity assets on the face of the balance sheet and so its easy to get to the numbers. I looked at SVB and Bank of America and the problem is plain to see. BoA has over US100m of unrealised losses for example, which would wipe out nearly half of its capital if marked to market. If, or more likely when, property companies default in the US and commercial property losses end up on a banks balance sheet its going to get ugly. This is all highly likely to cause a global recession as the everything bubble finally bursts, in my view, so I'm still cautiously positioned. Sandy Nairn is worth following on this and his excellent book The end of Everything Bubble if you want a depressing read.
Of course the Fed might still achieve a soft landing, but it looks more like wishful thinking with recent events and such a massive inversion on the yield curve.
So...this inevitable doom scenario I take issue with...
Most of the value of commercial real estate is not encumbered with debt. Much is debt free and much of it has low LTV ratios. Its the minority that has high debt underpinning it with a US bias to office and malls. The former is the most at risk particularly in old urban centres (new urban centres tend to have gone back to work in office much more). The median loan is to a smaller city office space, whereas the average office value is more in old centre like NY but with low to zero LTV.
Banks are pensions who have a high exposure to this stuff are odd animals in an economic sense and can sort transmogrify financial risks over time. Neither need to be hindered by write downs and losses short term depending on their funding situation. Its a million miles from us and our homes. Where a bank has a loan secured against a building they can take possession and resell. This is actually a source of potential profit though it does create short term volatility as resolution is worked through.
I'm not saying its all okay...and it could go very bad...but horse and cart...if liquidity and/or other asset values hold up okay in nominal terms then asset values in CRE don't need to plunge....and for the disaster scenario to occur there needs to be a plunge...reflexivity...
PS Sandy Nairn is a mediocre investor with a penchant for be a misery. His main argument is mean reversion of value which is a highly dodgy perspective IMO.
Oversimplifying I know, however Secure Trust Bank (LON:STB) and S&U (LON:SUS) are in similar businesses but the former is raising bond finance at 13% whereas on Tuesday the latter said it is paying around 7% (on the IMC presentation). STB has the additional cost of complying with banking regs although it also has around £2.5 billion of lower cost finance through retail deposits from savers. Perplexing and probably shows how little I understand about the banking industry! Although the £90m at 13% is a tiny part of their capital base -why did they need it at that price? Can a specialist put the rest of us out of misery please!
Secure Trust Bank (LON:STB). The £90m is Tier 2 capital and so its quasi-equity for regulatory purposes. Double the cost of the redeemed bond unfortunately. Timing not great, but if they needed growth capital this was probably the cheapest option given the low share price.
It's also worth noting that the 2021 results benefited signfificantly because of the one-off credits on impairment charges following the 2019 covid-19 impairments that turned out not to be necessary.
Interesting that they are exploring M&A merger opportunities.
The two subsequent events are not very positive.
Nevertheless, I continue to hold as its one of the safer UK banks originally from the Arbuthnot or Henry Angest stable.
Yesterday was quite rewarding, thank you for your comments on MBH Paul. Today is medicine day, could you or Graham find time to devour Tasty (it still has money in the bank) and XLMedia which is looking increasingly like a gambler's last throw (continuing operations up 364% though!) ? What with INL's £4.6 million surely forlorn subscription at twice the market price it's a big boys pants day.