Small Cap Value Report (Thurs 6 May 2021) - SOM, NXT, SDRY, JOUL, VINO, GTLY, RCH, BILB

Good morning, it's Paul and Jack here with the SCVR for Thursday.
Timing - we'll aim to be finished by 1pm. Quite busy for company updates today. Today's report is now finished.
Agenda -
Paul:
Somero Enterprises Inc (LON:SOM) - a very good update, with forecasts for FY 12/2021 raised 16% by Finncap. Looks cheap, for a high quality company.
Next (LON:NXT) - Q1 update. No section below, this is just to flag up that I've created a separate article here for Next's Q1 update, as we're trying to keep the SCVR focused just on small caps.
Superdry (LON:SDRY) - FY 04/2021 trading update, which cherry-picks positives, and doesn't tell us anything at all about profitability (or losses, rather). I'm impressed with online growth, and wholesale has done better than I expected. So a mixed bag overall.
Joules (LON:JOUL) - an intriguing announcement, saying that borrowing facilities with Barclays have been extended in time, and have been linked to ESG targets, which if met would trigger a lower interest rate. It's new to me, so thought I'd have a ponder.
Virgin Wines Uk (LON:VINO) - a positive update from this recently-floated direct-to-consumer wine merchant. A nice business, and I like management. But how much of the growth is from lockdowns & is it sustainable? I don't know.
Jack:
Gateley Holdings (LON:GTLY) - great update, trading materially ahead of consensus expectations with a clear strategy for growth going forward and a resumption of dividend payments.
Reach (LON:RCH) - digital transformation progresses and operating profit for the year now expected to be slightly ahead of market expectations
Bilby (LON:BILB) - net debt is coming down and improving financial health frees Bilby up to pursue growth opportunities, although operational costs increased due to lockdowns.
.
Paul's Section
Somero Enterprises Inc (LON:SOM)
(I hold)
422p - mkt cap £237m
Strength in US market driving healthy trading ahead of previous guidance
This is a smashing update, from AIM-listed Somero, which is headquartered in the USA, selling laser-guided concrete levelling equipment. It is used to make perfectly flat floors mainly for warehouses. This share has long been a favourite of ours here at the SCVR, producing prodigious cashflows, divis (including specials), with high margins, and high returns on capital. The shares always seem to languish behind other companies displaying high quality traits.
Today’s update covers the first 4 months of FY 12/2021. It looks very good, saying;
The Board is pleased to report that as a result of stronger than anticipated trading momentum in the US in the first four months of the year alongside signs of improving activity levels in Europe and Australia, it now expects to exceed previous guidance for FY 2021 established in the 10 March 2021 final FY 2020 results statement.
The Company's previous guidance for FY 2021 indicated revenues were expected to grow in the single mid-digit percentage range from the US$ 88.6m reported for FY 2020, adjusted EBITDA would grow modestly from the US$ 26.1m reported for FY 2020 and ending net cash would approximate US$ 27.4m. The Board now expects FY 2021 annual revenues will approximate US$ 100.0m, adjusted EBITDA will approximate US$ 31.0m, and a consequential improvement in the anticipated year end net cash position.
The StockReport is showing forecast revenues of $93.3m existing, so upgrading that to $100m is an impressive move coming well before the half year end. Could there be more to come later this year?
Broker update - Thanks to Finncap for publishing an update note this morning, which gives the more meaningful EPS forecasts (I find adj EBITDA fairly useless in valuing shares). This update shows:
FY 12/2021: forecast EPS raised from 34.5c to 39.9c, up nearly 16% - a sizeable increase in forecast. Converting into sterling, at £1 = $1.39, gives 28.7p.
At 422p per share, that’s a PER of 14.7 - which looks very cheap.
My opinion - I think this share justifies a PER of 20, which implies a target share price of 574p (upside of 36%). There could be more upside on that, as the rest of today’s update sounds positive about European markets opening up, new product launches, etc. Hence I suspect we might see more upgrades as 2021 progresses. Management tend to be prudent with guidance.
The macro picture seems very positive for SOM, with lots of infrastructure spending, and huge QE/deficit fuelled Govt stimulus means we probably have several years of boom times coming. What happens after that, who knows? Inflation becoming more of a problem, maybe, but we can worry about that later. For now, SOM is one of many companies reporting strong updates, which generally justify the big rise in share prices we’ve seen in the last 6 months. In this case, I think SOM shares could have further to run - the improving fundamentals justify it.
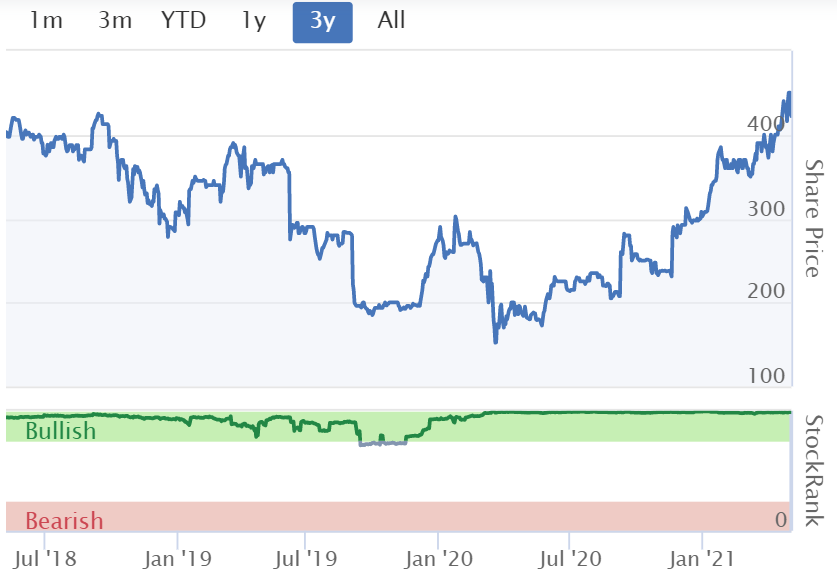
Note below how the StockRank has been on maximum for the last year!
.
.
It's categorised by Stockopedia as a "Super Stock".
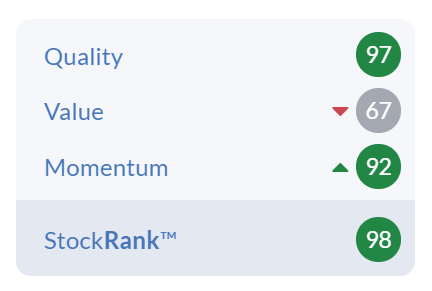
Note also that, when the upgraded broker forecasts come through, the value score below should rise further.
.
Superdry (LON:SDRY)
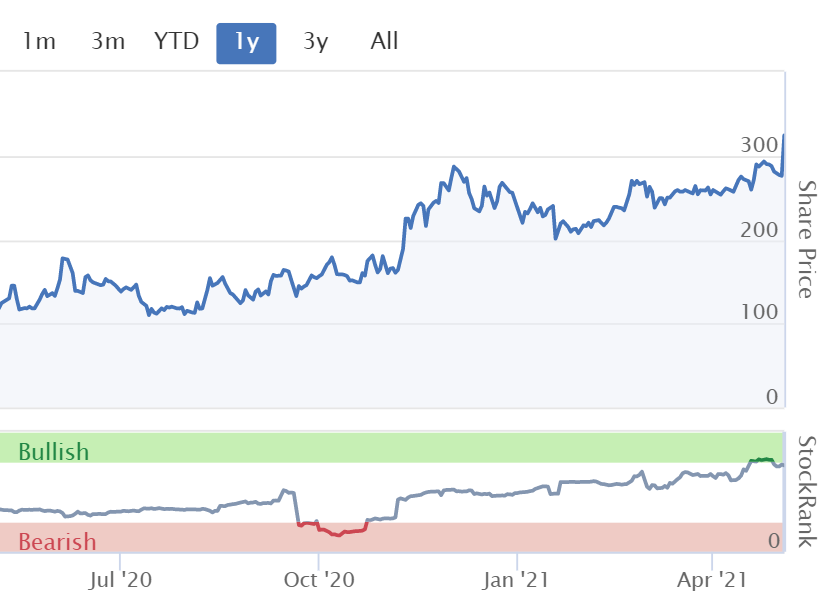
326p (up 18% today, at 10:16) - mkt cap £267m
Superdry announces a trading update covering the 52-week period from 26 April 2020 to 24 April 2021 ("FY21").
Returned to revenue growth in Q4. However, remember that the Q4 last year comparative was hit hard by lockdown 1, from 23 March 2020 closure of all non-essential shops. Hence beating that comparative is not quite as good as it sounds - although physical shops were closed for almost all of Q4 in 2021. Comparisons are difficult. Maybe it would have been better to use comparatives from 2 years ago, as Next has done?
Online sales are growing nicely - this is a key thing I look for, as retailers have to be able to demonstrate a successful shift to selling online, to be investable, in my opinion. In FY 04/2021, SDRY sold £203m online, up 34% on last year, and that’s 36% of the total sales - starting to look interesting!
Gross margin - SDRY is trying to sell at full price, instead of discounting. It says this was successful in Q4 -
… our commitment to a full price stance over the period has seen significant online margin improvement.
That’s encouraging, but remember that retailers don’t price discount product because they want to, they drop prices because they have to, to shift slow-selling lines. Therefore, we need to see strong sales, combined with strong margins. Otherwise, everything not sold is just dumped into the end of season sale at half price, in July. Therefore, sticking to full price at this stage could just be deferring the gross margin problem. Time will tell on that. I tend to find that SDRY announcements are full of upbeat comments, and aspirations, but with not much concrete evidence that the business has actually turned around.
Remember it was struggling, and trading around breakeven, before the pandemic struck, so it’s got a mountain to climb to get anywhere near being a profitable business again.
Liquidity - good, but what about all the deferred creditors, such as VAT, etc? It's curiously silent on that important point.
Our liquidity remains strong, with closing net cash ahead of last year and our facilities remain undrawn.
Re-opening - going well, but no figures provided -
The early signs following the reopening of our UK stores are encouraging, as lockdown restrictions start to lift, and we can clearly see the light at the end of the tunnel. In short, we are on track with our reset of the brand and there's a lot to look forward to."
Rents/leases - this is the biggest issue - it’s locked into a load of flagship, big rent stores. Some have been renegotiated, and big reductions in rents, but what about all the others?
Renegotiated a further 48 leases (~1/5 of the estate) in FY21 achieving a weighted average saving of 52% (65 lease negotiations have now been completed in total), in addition to substantial one-off Covid-related rent waivers.
We’ll have to wait until the actual results come through, to properly assess the situation. For all my criticisms of it, IFRS 16 does have some use when looking at struggling retailers, to see the extent of the leasehold commitments. Its big failing though, is that IFRS 16 doesn’t distinguish between lease commitments on profitable and loss-making shops, which is what actually matters! A lease is only a problem if you’re trading at a loss from that site. If it’s trading profitably, then the future lease liabilities don’t matter.
Wholesale - this is better than I was expecting -
Positive signs are being seen across Wholesale, with in-season orders up 142% and SS21 forward orders up 10% in Q4 year-on-year, both driving an overall increase in Q4 21 which is up 13.5% year-on-year.
Cash collection has tracked ahead of expectations, making a significant contribution to year-end net cash.
Wholesale FY21 revenue was down (19.9)% year-on-year, with our partners suffering the same headwinds in physical trading locations and carrying forward higher levels of stock than normal.
Outlook - no figures given, so investors are in the dark about the current level of trading losses. SDRY left wildly inaccurate forecasts in the market for a long time. I reckon it’s heavily loss-making at the moment, because it didn’t make any money before the pandemic -
There remains significant uncertainty given the varying impacts of the pandemic in our markets particularly to the trajectory and phasing of the consumer recovery. However, we are confident of growth in FY22 revenue and profitability compared to FY21 assuming no further material national store lockdowns and a continuing recovery in footfall and consumer demand through the period.
Profitability will be supported by higher gross margins from our restored full price discipline and positive operating leverage from reduced store costs, partially offset by the end of government support and our ongoing brand marketing investment.
My opinion - mixed. First the positives - I’m impressed with the growth online, and wholesale has fared better than I expected. Liquidity is OK for now, but we’re not told what all the backed-up creditors are, which is crucial information omitted from this update.
Negatives - SDRY was struggling before the pandemic, with its highly profitable glory days well behind it. Big-rented flagship stores remain a millstone, although some progress is being made on renegotiations. Again, we’re only told the positives, not the full picture. SDRY updates do read as mainly PR material, not giving any indication of overall profitability, or the true underlying liabilities. They can’t hide these points when the full year numbers come out, so there's a good case for investors banking the profits before the numbers are published, as I reckon they’ll probably not look very nice.
Checking the last (interims) balance sheet again, it looks to me as if there’s too much in inventories, and maybe some provisions for bad debts might be needed against the large receivables book?
Lease liabilities are horrendous, at nearly £300m, with only £111m in right of use assets, showing the key importance of getting out of those leases, wherever possible. That could takes years, and be very expensive, and is likely to be a dead-weight on this company for years to come.
Overall, I think the company is right to say that there’s light at the end of the tunnel. My assessment is that it looks unlikely to go bust, and has managed so far without having to dilute shareholders at all. That could come later though, as once everything’s back to normal, and creditors have to be paid, new stock bought, etc, then the cash pile and borrowing facilities are going to be needed.
It’s been a good trade so far, on survival & hopes for re-opening, but I think there’s still a lot to be proven about the long-term fundamentals, which remain weak, in my opinion. Let’s see what the actual numbers look like when they’re published. Today’s PR release is really just edited highlights, carefully avoiding mentioning anything about liabilities, or losses. Compare this with the Q1 update from Next (LON:NXT) today - it’s like chalk & cheese.
Still, in a bull market, when everything's going up, do fundamentals matter? Not at the moment they don't! That comes later.
.
.
Joules (LON:JOUL)
(I hold)
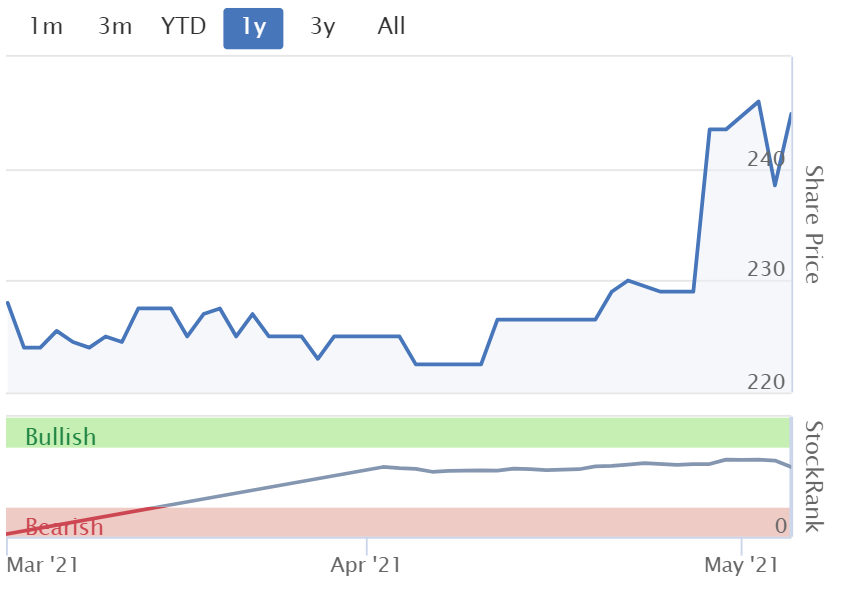
240p (up 1.5% today, at 12:44) - mkt cap £266m
Joules establishes ESG-linked financing facility
This is such an unusual announcement (first time I’ve heard of it), that I have to look into this.
Joules, the premium British lifestyle brand, is pleased to announce that it has extended its current funding arrangements with Barclays Bank Plc ("Barclays"), that include a £25 million revolving credit facility and £9 million term loan, to September 2024, and has converted the facility to an ESG-linked financing arrangement.
The new financing agreement links the margin on the facility with Joules' performance against three Sustainability Performance Targets (SPTs) that are aligned with Joules' ESG focus areas. Under the terms of the agreement, Joules will benefit from a lower interest rate loan margin if the Group delivers on the following targets:
- reducing its carbon emission intensity;
- delivering 100% more sustainable materials in the manufacturing of its products; and,
- increasing its employee engagement score
The details of the targets and progress against them will be reported alongside the publication of the Group's annual results and its Responsibly Joules update each year.
I don’t know enough about this to form a view on it. Instinctively, I’m uneasy about bank facilities being linked in any way to ESG. Taken to an extreme, could this give banks an excuse to withdraw borrowing facilities, using ESG as a smokescreen, if a company were to get into trouble?
That said, this could be an initiative launched by Barclays, which offers better interest rates than regular lending, in which case it could be a nice way for Joules to save some money, and implement useful ESG policies.
I’m all for ESG generally speaking, and think it’s great that companies are getting serious about these topics. Although it does seem to be almost becoming something of a mania at the moment, with everybody desperate to prove their ESG credentials. I do wonder how much of it is sincere and meaningful, as opposed to, oh this is what we have to say, and pretend to care about?
In the case of Joules, it’s very much a middle-class, outdoorsy type of brand, where customers virtue signalling about their green credentials is almost socially mandatory! (ignoring the gas-guzzling SUV of course). Whereas the BOO customer clearly doesn’t care two hoots about ESG (as evidenced by record results, despite a media feeding frenzy over its supply chain problems), the Joules customer I think would be very receptive to a meaningful ESG strategy. Therefore this is probably a good thing for JOUL shareholders, as it may well enhance the business over time. And do good, so everyone should be happy.
I’ve googled Barclays, and found plenty of stuff on its website about green lending, but I can’t find anything specific about ESG-related borrowing facilities. If anyone has a link, please do post it in the comments, as this looks an interesting area.
.
Virgin Wines Uk (LON:VINO)
245p (up 3%, at 12:53) - mkt cap £137m
This direct-to-consumer wine delivery company floated recently. I had a look at it here on 16 Feb 2021, delving into the company’s history from filed accounts at Companies House. What I discovered is that it historically made very little profit, compared with the bumper profits achieved during lockdown in 2020. Hence I think it looks like an opportunistic float, on the back of bonanza profits which may not be sustainable, perhaps?
More recently, on 26 March 2021, VINO held a webinar on InvestorMeetCompany, which I tuned into, and enjoyed. Management struck me as exactly what I look for - hands on entrepreneurs, who know their sector well, with plenty of experience. Also it particularly struck me how open & honest they were in the Q&A, including the CEO reading out word-for-word a moderately inflammatory question that I had submitted! The CFO replied, in a slightly prickly way, rejecting my assertion that the business is making one-off profits from lockdown.
Who knows though, time will tell, maybe VINO has won new customers in lockdown who will remain loyal? It is handy having wines delivered, as they’re quite bulky & heavy to buy from supermarkets in quantity. Of course I’ve sampled the range too, with a selection of 12 bottles, and they were fairly good actually, as far as I can remember. As with Naked Wines, they offer a generous discount to attract new customers. So it’s really all about customer lifetime value, versus cost of acquisition.
This diagram from the Admission Document seems to show good repeat orders from each year’s cohort of new customers -

.
On to today’s news from VINO -
FY21 sales and EBITDA ahead of expectations. Strong customer demand continues.
Virgin Wines UK plc (AIM: VINO), one of the UK's largest direct-to-consumer online wine retailers, today provides an update on trading to date for the year ending 30 June 2021 ("FY21").
The Board is pleased to announce that the strong levels of customer demand experienced in the first half of the Company's financial year have been maintained in the second half of FY21 so far [benefiting from pleasing order frequency among existing customers and good levels of new customer acquisitions]. As a result of the continued strong performance, the Board anticipates revenue and profitability for FY21 will be ahead of its previous expectations, with turnover for the year expected to be no less than £73m and an improvement in EBITDA margin.
Whilst remaining mindful of the potential impact from the easing of lockdown restrictions on consumer spending patterns over the coming months, the Board remains confident that the underlying growth drivers, which the DTC wine sector is experiencing, alongside the accelerated shift in consumer behaviour towards online retailing, will continue. Against this backdrop, the Board is confident that Virgin Wines, underpinned by its unique customer proposition and growing, subscription-weighted customer base, remains well positioned to continue to deliver its growth strategy and meet the Board's expectations for FY22.
It’s a bit vague on the numbers. I would have preferred more specific guidance on profit before tax (not bloody EBITDA!). Still, I suppose we could work out the numbers.
Taken from the Admission Document;
H1 (6m to 31 Dec 2020) revenues £40.6m, EBITDA £4.5m
Therefore “at least £73m” for the FY 06/2021, implies that revenues fell from H1 to H2, to c.£33m. Maybe that’s because H1 includes Christmas, and people were busy getting tipsy at home, due to not being allowed to go out to parties & pubs?
H1 saw EBITDA of £4.5m. It’s not clear from today’s update what they mean by an improved EBITDA margin? Since they don’t tell us what the original expectation was.
Putting that together, my guess is that the company is probably heading for £7-8m EBITDA for FY 06/2021, a year which would have been helped a fair bit from lockdowns. Checking through historic accounts, VINO has very little in fixed assets, so the depreciation & amortisation charges are only about £0.7m pa, and the IPO should have wiped out its debt, so finance charges won’t be much, therefore I think profit before tax could be something like £6-7m for FY 06/2021?
What a waste of time, having to plough through the admission document to work out what real profits are, because they only report EBITDA today. When are companies & advisers going to listen, and provide full information, instead of just EBITDA, in their trading updates?
EDIT: I've just found an update from Liberum, many thanks to them for making it available for us on Research Tree. Analyst Wayne Brown estimates £6.3m EBITDA, and £5.0m PBT, so it looks like my guesses above could be too optimistic. This translates into 9.0 EPS (diluted) of 9.0p. At 245p per share, the current year PER is 27.2 - a valuation that seems a bit toppy to me. End of edit.
My opinion - I’m really warming to this share, and reckon it looks pretty good.
The current valuation looks about right to me, or possibly a little toppy - it depends if earnings growth continues in future years, or not.
This is quite a competitive space, with Naked Wines (LON:WINE) to consider, plus Laithwaites and The Wine Club being larger competitors. Plus of course huge competition from the online supermarkets.
.

.
On balance, I like VINO, but don’t think the current growth rate looks sustainable. For that reason, I’ll sit on the sidelines and watch what happens next.
.
.
Jack’s section
Gateley (LON:GTLY)
Share price: 186.5p (pre-open)
Shares in issue: 117,888,007
Market cap: £219.9m
A short but sweet ‘materially ahead’ update from legal and professional services group Gateley Holdings (LON:GTLY) today.
The group is predominantly legal services through Gateley Legal (currently 90% of revenue) advising over 5,000 clients across five core business groups including Corporate, Banking and Financial Services, Property, Business Services and Employment, Pensions and Benefits.
Its origins can be traced back to the 19th Century when the commercial law firm of Stephen Gateley & Sons was established in Birmingham. The family firm grew its business across the surrounding region before merging with Wareing in 1974.
It listed in 2015 following changes to the law in England and Wales to adopt an Alternative Business Structure (ABS), allowing non-lawyers to own and invest in law firms.
As with Rbg Holdings (LON:RBGP) , the company is busy adding complementary businesses to its network. Since the 2015 IPO, the group has acquired:
- Capitus and Hamer Associates in 2016,
- GCL Solicitors, Kiddy & Partners, and International Investment Services in 2018,
- Persona Associates and T-Three in 2019, and
- Paul Tweed and The Vinden Partnership in 2020.
Gateley has built up a 12.5% compound annual revenue growth rate over that time, although profit and cash generation have been more mixed.

The group has also attracted a couple of institutional names, including Liontrust, which is now its biggest shareholder at 10.24%.
On the back of today’s update, it looks like this roll up strategy is working well.
Following a strong end to the financial year, revenue in FY21 is expected to be materially ahead of consensus market expectations.
Consensus market expectations, per the company, are revenue of £111.7m, adjusted profit before tax (PBT) of £14.7m and net cash of £8.4m.
Profitability is expected to be more significantly ahead of consensus market expectations with a cash position at 30 April 2021 substantially ahead of consensus market expectations.
Dividend payments are recommencing, with a policy of distributing up to 70% of profit after tax (PAT). An interim dividend payment of 2.5p will be made and a more detailed trading statement will be announced later this month.
Conclusion
This is a good update and the company is worth investigating in more detail.
Law changes made in 2015 have unshackled the group and it is now consolidating the market and building out its services platform at pace.
Directors have been selling a lot of shares though. I can’t begrudge successful business owners for wanting to realise some of the value they have helped to create over the years, but the scale and frequency of selling is notable.
Davies and Ward on the Major Shareholders page are group COO and executive director, with a combined c3.5% of the company.
The balance sheet looks ok, but for such an acquisitive company I would want more of a cash buffer. The vast majority of current assets are accounts receivable… £54.6m of current assets, £48.7m of which is accounts receivable (as of FY20). Net plant, property & equipment of £24.8m, plus about £18m in goodwill and intangibles.
Against that we have £26.6m of current liabilities £29.3m of ‘debt’ (mostly in fact £22.1m of capital lease obligations) and some other smaller line items taking total liabilities up to £53.7m.
I suppose that gives some scope to continue executing on its strategy. But compare it to Judges Scientific (LON:JDG) for example. This is the gold standard in frequent acquisitions, and probably acquires more resilient and higher quality businesses with less key person risk.
As of FY20, JDG had about 19% of total assets in cash (£15.5m/£82m). Gateley on the other hand had 3% of assets in cash (£2.92m/£98.5m).
A large receivables balance is probably par for the course given the business model. And the group is cash generative. It also uses this cash gen to pay out healthy dividends in more normal conditions - 8p in FY19, which would be a yield of 4.3% at this morning’s share price.
Gately offers middling value for now, but the outlook is very good and it looks like there’s a clear catalyst and related strategy for growth, so it’s a growth-at-a-reasonable-price (GARP) candidate.
The legal and services sector in general appears to be doing very well at the minute.

Reach (LON:RCH)
Share price: 221p (+0.45%)
Shares in issue: 312,067,649
Market cap: £690m
(I hold)
Reach (LON:RCH) is midway through an important transformation. It is pivoting from the structurally challenged Print newspaper industry and is re-focusing on Digital Advertising. And it has a lot of digital assets, mostly in the form of regional news titles (see here).
Reach gets a lot of traffic through these sites but until recently had not made a great effort to monetize this traffic or harness the data in any meaningful way. Now it is working to improve customer engagement online and create a more informed impression of its readers. This is more valuable to advertisers as it paves the way for more targeted and optimised advertising spend.
The company was very cheap when pitched to the Investment Club. It has since rerated and is now consolidating, so the emphasis is less on whether Reach is a viable business and more on how much growth it can unlock via this shift to digital.

Trading update for the four months to 25 April 2021
Good start to the year with digital and print revenue performing slightly ahead of our expectations
- Continued growth in registrations; now at 6.2m, versus 5.8m reported at the beginning of March (target is 10m by the end of 2022),
- Customer Value Strategy progressing well with continued increase in loyalty and engagement,
- High level of interest from brands in new 'plus' portfolio of products; building strong pipeline for H2,
- Transformation programme efficiencies and digital mix support growth in operating margin.
Q1 print revenue was down 15.2% year-on-year and digital revenue was up 25.2%. Group revenue fell 8.7%. The mix marks a deceleration in print decline and an improving pace in digital, which is probably what is priced into the shares right now. Soft comps due to lockdowns last year should also be factored in.
Customer engagement has continued to grow and will be supported by increased strategic investment in data and analytics, including a focus on customer journey mapping to help drive average revenue per user.
The business is also benefiting from the efficiencies driven by last year's transformation programme, which together with a growing mix of digital revenues, means that operating profit for the year is now expected to be slightly ahead of market expectations (of adjusted operating profit of £137.1m for 2021).
Conclusion
Digital now accounts for more of Reach’s advertising revenues than print. It’s a bit of a symbolic milestone.
There is sometimes a lack of financial data in Reach’s updates though. It’s not required to go into great detail here but, given the market uncertainty around its transformation plan, it would be appreciated. Perhaps that is behind the static share price today - you’re unlikely to change your position on this stock based on the words in this trading update alone.
Either you think there’s potential here or you remain skeptical.
This is an interesting turnaround situation with an unusual opportunity. The group’s declining legacy business in fact gives it a solid, cash-generative base from which it can execute its digital strategy, based on what is a deep portfolio of potentially valuable local news sites.
But there are risks too. The group has accumulated several pensions and the deficit here is around £255m. Meanwhile, there is no guarantee that the group’s transformation strategy ends up being as profitable as investors are hoping for.
How will a fully transformed, digital Reach fit into an evolving online ecosystem dominated by a couple of large tech players like Facebook?
Whatever your thoughts on that point, the management team here is executing with digital ad revenue now exceeding print for the first time, and promising initiatives like ReachID that will be applied to a large and previously untapped readership.
Margins will rise as this transition progresses. And Reach is still far from expensive even after the rerate, trading on a forecast PE ratio of just 6.3x with a useful forecast yield of 3.28%. As ever though, DYOR.
Bilby (LON:BILB)
Share price: 37.2p (+0.54%)
Shares in issue: 61,214,703
Market cap: £22.8m
Bilby (LON:BILB) is a leading gas heating, electrical and building services provider.
The share price here became too cheap over the lockdowns and this has since been recognised by the market, with the stock rerating by 50% or so over the past few months.
But if you take a longer term view, the chart suggests further turnaround potential.

Shares in issue have gone up by about 50% over this period, too. But even accounting for that a full recovery to previous levels would be a share price of about 77p or more than 100% upside.

The group has managed to grow revenue in recent years, but profit margins have been an issue. The new management team (led by David Bullen) is more focused on winning profitable contracts at good margins.

And, with trailing twelve month revenue of £59m, a market cap of £22m for this company really isn’t that demanding if it can execute. I think it’s worth keeping tabs on.
Bilby delivered essential, regulation-driven maintenance and building services for its clients, through the lockdowns. It expects to report a ‘solid’ performance for the financial year and a ‘strong’ performance in the second half, with FY21 revenues of c£60m
However, margins were affected by higher operational costs arising from the increased no access rates and mix of works resulting from Covid disruption.
Therefore adjusted EBITDA for the full year is expected to be c£3m. The group is seeing signs of more ‘normal’ trading activity in the new year.
Net debt reduction remains a priority and Bilby is focused on working capital efficiencies, cash conversion, and cost management. This has enabled Bilby to repay an additional £2.3m of its term loan.
Over the last 18 months, net debt has fallen by £8.4m to £2.7m as at 31 March 2021. There is a £1m VAT liability to take into account as well, and this is now being paid.
Bilby says the strengthened balance sheet is allowing it to seek future growth opportunities.
Full Year Results will be announced in early July 2021.
Conclusion
This is a solid update and I think there is decent growth potential at current levels.
Net debt is coming down. This paves the way for dividend payments and is opening up doors in terms of opportunities.
The group has operated through the lockdowns and so has been less disrupted than others.
Things did go wrong at Bilby though, and they can go wrong again. What I would say is that it looks like the new management team appears to have a good handle on the mistakes that were made (going after too many low margin contracts in the pursuit of top line growth) and the company has a fair chance of improving its financial health and increasing its profits in the year ahead.
On that note, this is the kind of cyclical value trade I would hope to spend a little more time on.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

74 comments
Hi Paul - been on the platform for a year, but this is my first post. Thanks for all your blogs - they are fantastic and I look forward to reading (and acting on) them every day. Please keep them up.
Just noticed your comments re Joules/Barclays/ESG. As someone from the debt financing industry, I wanted to say that these ESG linked loans (aka sustainability linked loans - SLL’s) are now becoming very common - particularly for PLC’s. - and most large corporates will have/be thinking about having them. The key difference between a SLL and a Green loan is that with the former, the purpose of the loan/RCF can be ‘general corporate purposes’, rather than a specific green project, which makes them accessible to more companies. The interest margin ratchets are actually relatively modest in amount (and any benefit received is often agreed to be ploughed into projects/charities - rather than benefitting the corporate - and failure to hit the targets is not usually an event of default (but it could mean a modest increase in the margin). As well as being the right thing to do for the corporate, it is a big area for Banks and Funds who are keen to show they are making themselves and their portfolios sustainable. Worth saying that Banks/funds have layers of governance before signing of on a SLL as they do not want to be accused of ‘greenwashing’. The targets agreed therefore have to be stretching/ambitious, rather than BAU to prove that by achieving them, a difference is really being made. Over time, I expect more and more financing agreements will be linked to ESG and medium/smaller companies will start to adopt. Down the line, you can see sustainability becoming a credit/selection factor for funders, with ‘unsustainable’ companies and those not ‘on the journey to sustainability’ finding it harder to access financing. Overall this is a relatively new area, but one that will only grow from here. Hope this helps. If you want to chat more, happy to speak.
Paul,
A quick google of "Barclays ESG loans" gets this backgound info about applying ESG to trade:
https://www.barclayscorporate....
Reach (LON:RCH) looks like it may be on the verge of breakout now.
There was probably an overhang holding back the stock earlier in the day following Richard Desmond disposing of 1% of the company yesterday. (Having disposed of another 1% a few weeks ago.)
Desmond got the shares as part of the deal to buy the Express, Star etc. and still has a 4% holding.
You might suspect that he'll be selling the rest of those in the near future.
Just wanted to say thanks for posting the links out to articles of interest for larger caps in the headlines, I find it really useful. It keeps the SCVR on point but helps flag other great commentary on mid and large cap shares that many have an interest in. It's a editorial style that really works for me so just wanted to call it out!
Just a quick note on Somero Enterprises Inc (LON:SOM) (I Hold)
Dividend paid 30th April being 18 cents extra and 13 cents final. I was struggling to make the maths work on the UK £ I actually received into my ISA. My assumption was that, being an ISA, divis would be received gross, i.e. no tax deducted. Just shows one should never assume! Apparently US Dividend witholding tax is a heady 30% (!!) but if you hold shares in an ISA and have completed a W8-BEN form then you are entitled to the 'Treaty Rate of Tax' which is 'only' 15%.
If you already knew this please don't say so as I'll look like a lemon.
This is similar to Ferrexpo (LON:FXPO) which applies Swiss withholding tax, which you cannot get back in an ISA but can if it is just a plane share dealing...
So not a numpty, just a painful lesson
Paul / Jack, appreciate this is solid mid-cap territory, but any view on Aston Martin Lagonda Global Holdings (LON:AML) who are in the apparent early stages of a turnaround and announced a trading update this morning?
Aston Martin Lagonda Global Holdings (LON:AML) Hardly a small cap as it's over £2bn mcap.
Sec Newgate Spa (LON:SECN)
Trading update provided today year end 31 December 2020 it does surprise me that this has not been covered, discussed since 2018? The stock first came to my attention using the excellent Stockopedia Screener and I was fortunate to have had a small punt earlier in the year at sub 50p (now over £1).
Quality86Value83Momentum90StockRank™98
The growth & value 12m forecast rolling has pe ratio of 0.2 and from trading update today it looks in line with a profit of 3 million?
All stats look good margin, roce, cashflow, cash, turnover all increasing, market updates all positive.
The PE Ratio is forecast as 0.224 & 0.176 and PEG 0.008 & 0.014 which appears extremely low?
Paul forgive me if I am wrong, but I don’t think you have covered this before. If you have the opportunity to review and provide your expert analysis and comments it would be appreciated it is certainly in the small cap scope at 23.28m! The last time the stock was covered was by Graham on 2nd January 2018.
I had a bad experience with Porta Communications, which merged into Sec Newgate Spa (LON:SECN)
The trading updates from Porta were dreadful - they adjusted the figures to oblivion, shouted from the rooftops about how well the business was doing, which sucked in mugs like me, only to later discover that the real numbers were dreadful, and the company was close to bankruptcy.
Hence I wouldn't go near anything linked to Porta, with your bargepole.
Sec Newgate Spa (LON:SECN)
Many thanks Paul and also to other contributors with their input very much appreciated. I must admit the old adage if anything looks too good to be true and I did approach with a fair degree of caution having fallen foul of a similar experience with Naibu. Lessons learned always best to get second opinions. Kind regards all and in the main stats, fundamentals, ratinsgs provided both by Stockopedia and coverage by Paul etc are superb.
Sec Newgate Spa (LON:SECN) It looks like there’s an error in the PE calculation, by a factor of 100x(ish) . EPS IN cents looks wrong.
Sec Newgate Spa (LON:SECN) I think the 2020 and 2021 EPS is overstated by a factor of 100 on the StockReport which is why the PE and PEG appear so low. I was excited about its valuation too until I realised the error...
Yes, eps for SEC Newgate SpA (LON:SECN) is shown in Euros, not Euro cents in the SR - I will try the green button.
For the record Arden is their Nomad and you can get free reports if you register with them. They currently forecast eps of 4.8c to 12/20 and 6.7c to 12/21
For any takers in the recent PrimaryBid offer for prospective lithium miner Bacanora Lithium (LON:BCN) , it looks as though you’ve just been gobbled up by your strategic partner, Ganfeng International.
https://www.investegate.co.uk/....
Almost a bit of a disappointment as they had a good story to tell but the 50% premium to the PB offer price is reasonable compensation. Looks like a done deal from the tone of the release, although the shares are still trading at 59.4p offer against a putative takeover price of 67.5p per share.
Gus.
Bacanora Lithium (LON:BCN) Quite a big disappointment I'm afraid as bought end of 2017 at 104.45p! Had hoped it would be a long term beneficiary from the development of electric vehicles and energy storage which are essential to have any chance of hitting the various government's Climate Change targets. It looks like the Chinese will now get the benefit of any long term growth in demand for the Lithium. To add to a bad day my other lithium play, Albemarle (NYSE:ALB), one of the top 3 lithium producers in the world, is down 9.5% despite reporting Q1 results well ahead of expectations.
Hi ACounsell.
Sorry to hear about your double bu**er on Bacanora Lithium (LON:BCN) and Albermarle. Given the strategic interest in lithium long term I think there was a lot of potential beyond the 50% bid premium in Bacanora Lithium (LON:BCN) at 45p a share but it’s no real surprise that Ganfeng wants the whole cake rather than just a „partnership“. A similar stream of logic makes me think that the principal condition of the bid (approval by the Chinese authorities) will be a formality. (Given nobody even sneezes without the blessing of the CCP these days I would be surprised if Ganfeng hadn’t already been given the nod).
With this in mind, it seems strange that the Bacanora Lithium (LON:BCN) share price finished at 56/58p today. By my simple numbers, if you bought at 58p a share and waited for the bid to complete at 67.5p (expected by calendar year end give or take) you would be up 16.4%. Not without completion risk but seems a relatively decent risk:reward for tying up a bit of capital for 8 months or so. (Talking my own book here as I topped up my holding this afternoon).
Gus.
Investornot1 and others - what company are you commenting on?
This is a polite reminder to everyone that Stocko provides seven different ways of reading these boards and if you use one of the four non-threaded versions then comments like this are lost.
I find it pretty easy to pick up the thread if I'm using one of them, so it doesn't bother me much.
Oh well, that's all right then.
"if you use one of the four non-threaded versions then comments like this are lost." (sharw)
I find it pretty easy to pick up the thread if I'm using one of them, so it doesn't bother me much.
But you are not the only one reading these boards and lots of us don't use threading. In practice it means that I mostly ignore any comments that don't make clear what they are talking about, I don't have time to spend tracking things down. And since I'd imagine that most people posting here do so because they want people to read and take notice of what they say simple self interest should mean that people posting make clear what they are responding to, for the many who don't read threaded. It's not difficult.
Hi peterg, thanks for taking the time to respond, and in a way that shows the benefit of what is being asked. I do see the point, and agree that it's easier, just saying that there are ways around it if people reply without context. I can see by the number of thumbs up that the feeling is behind what you and Laughton are saying rather than what I'm saying, so fair enough.
Now, back to reading about small caps!
Meant to say...
Somero Enterprises Inc (LON:SOM) The latest update is very good but this stock has been a very frustrating investment. I no longer hold Somero Enterprises Inc (LON:SOM) which I originally purchased 21/12/2017 and sold at a smallish loss after two profit warnings in June 2019 and September 2019 which saw 20% drawdowns each time. The second profit warning followed by further share price weakness (see graph below) prompted me to act!
The price history shows the big falls and the subsequent weakness - there is even a technical sell signal with the 50d MA falling below the 200d MA at the end of 2019. Perhaps this share is an outlier but Stockopedia's research on profit warnings (and the associated e-book publication) indicated that profit warnings and especially two consecutive ones are usually followed by third! Not in this case - the absence of perfect foresight has cost a 150% gain and reinforced my view that unless a business is heading for complete failure a 'buy and hold' strategy is the only way forward even through difficult periods for a decent business.
Saga (LON:SAGA) (I hold) RNS just out that its CEO has bought £198k-worth of shares in the market, at 386p. Nice.
Paul, £Saga also appointed a new Marketing Director yesterday as part of its step up in digital marketing - https://www.marketscreener.com...
Hi RajanP,
Nice find, thanks for flagging up that SAGA (I hold) has appointed an experienced digital marketing manager, she sounds an impressive person.
I like the way SAGA has previously flagged its desire to do much more stuff with all its data, but wasn't convinced it would necessarily have the right skills in-house. Hence it's encouraging to hear about this appointment.
Regards, Paul.
He did run Superdry for about 5 years and the share price was not a beneficiary. On the other hand, in between him starting and finishing he bought and sold shares doubling his money!
And prior to Superdry (LON:SDRY) he was CEO at Kingfisher (LON:KGF) - he didn't produce a profit fountain for shareholders there either! But I agree, the purchase at Saga (LON:SAGA) is very encouraging (I hold).
Regarding Somero Enterprises Inc (LON:SOM) oh how inertia has cost me. Not inertia from company performance, but me being too lazy to complete a W-8ben form to allow me to buy.
Me too!
You can do it online. Takes less than 30 seconds!!!
My broker require me to download the w-8ben, print it off, fill it out and post to them. Unfortunately it’s been an expensive bout of laziness on my part.
Somero Enterprises Inc (LON:SOM)
Rotala (LON:ROL) Had figures this morning. I would like to tell you they were good or bad, but having read the figures I have no idea. They seem to have got through the lockdowns relatively unscathed though.
Looks underwhelming first glance - back into profit but debt is very high and not expecting passenger numbers to recover fully until 2023
Property Franchise (LON:TPFG) FY20 results presentation with Q&A from last week. Gareth Samples, CEO & David Raggett, CFO give an overview of the results and outline thoughts going forward. Lots of positive drivers: a very strong property market, the acquisition of Hunters, the strategic partnership with LSL, and strong expectations for EweMove. Worth a listen. Nice play on the strong property market, they quote Savills who expect 1.5m house sale transactions this year v 925k in 2019; and project 1.25m in 2022. Video & podcast.
Like everyone here I really appreciate Paul and Jacks hard work each morning - essential reading and worth the price of admission alone. I notice that with Boohoo and Next Paul has started a new section to keep this daily update for small caps. I don't know about anyone else but I think it would be better to remove the arbitrary phrase 'small caps' as I'm sure as investors we interested in any company that you guys report on from tiny to gargantuan. Many times there will be a read across from a large cap to small caps and I think by allowing you guys free reign to report what you want here it makes it easier for us and you - most of the time I'm sure it will be 'small caps' but I don't see the need to limit yourself and would rather see it all in the same place. Or is it just me?!
I have no issue with larger caps occasionally being featured, but very keen for this to stay firmly focused on small caps and to keep small cap in the title - for many reasons, small caps offer by far the richest source of opportunities in my opinion. Larger caps are covered by armies of analysts so very difficult to uncover hidden opportunities, or to find something the wider market may have missed.
I agree with Leebod. I see no need for arbitrary rules. Some small caps, such as gold companies, tend not to get covered anyway. The benefit of this report (in my view anyway) is the insights that are brought out of results and trading updates by Paul & Jack. If they believe they can usefully add valuable commentary to a company's reports then I'm happy for it to be included.
Sylvania Platinum (LON:SLP) not a gold producer but lumped in there with small cap miners and doing very well indeed. I hold.
Reach
An enormous pension fund with a newspaper business attached.
Redde Northgate (LON:REDD)
I don't hold, but if there are any holders out there, you might be interested in any read across from ALD who reported this morning.
https://www.aldautomotive.com/...
https://www.aldautomotive.com/...
Redde Northgate (LON:REDD)
Thanks for the link there abtan. It's been a long time since we have heard from Redde( i hold). Have just been on their website and they are due to report a pre-close trading update on May 19th.
I gave a full appreciation of why I thought Somero was a"no brainer' a month or so ago after management's video conference. Rarely do I have the pleasure of being so right, and how! This being said, it's not because I'm particularly smart. It's really because I am a devoted subscriber to Stockopedia. Without this marvelous database, I never would have heard of Somero or several of the other investments I've made which are doing pretty well, nor would I have been able to conduct the necessary due diligence exercises. So hats off to the Stockopedia team, and feel free to use these comments in your promotions, if they can be useful
An interesting trading update from Tyman (LON:TYMN) today that states
The Group now expects that full year adjusted operating profit will be above the top end of the current range of analysts' expectations1.
Helpfully, they provide a link to those estimates on the company website so there is no need to guess. Link
They also comment on buoyant construction activity in the US, strong recovery in the UK and growth across Europe.
Yes, good trading update from Tyman (LON:TYMN) . I think this was the first stock I bought back in 2016 using Stockopedia factor analysis to screen for quality companies that I have never previously heard of. It’s a bit of a bellwether share tracking the stock market and perceptions of what may or may not be happening in the wider economy. Pretty much what you would expect from a consumer cyclicals building products supplier. It got hammered spring 2020 but is now up over 100% in the last year or so. Nice geographic spread as well with a strong US presence. A bit like Norcros (LON:NXR) but without the pension overhang.
Gus.
Here are my SCVR heat maps for today (prices as at ~8:25am).
I share these heatmaps with the intention of giving a visual indication of what is going on in the SCVR world: who’s reporting (and it's impact on the share price); and what’s moving more than 'normal'. There are no associated recommendations, implied or otherwise, just information. How, or indeed if, you choose to use that information is up to you.
Please read my heat map thread for more (non-SCVR specific) heat maps, and an explanation of how I use heatmaps to guide me with my research.
I have added a MarCap category to the heat maps, along with a high spread indicator. The key to the symbol heat maps is now:
The heat maps are also now sorted alphabetically by EPIC.
Small / Micro Caps reporting today:
Big movers today in the SCVR world (moving more than a 20d EMA of the ATR against either yesterdays close, or today's open):
Warm regards, stay safe, and best of luck!
greensiax
Gateley Holdings (LON:GTLY) N+1 Singer note
"Anticipating material earnings upgrades We will update our forecasts alongside the pre-close update later on this month. Tentatively, we expect to lift our revenue forecast towards £120m (vs. our current £110.1m forecast), potentially pushing our PBT and EPS forecasts up by a mid-teens percentage."
When attempting to buy Somero shares I'm told by my broker to fill in a W-8BEN form for US shares. Is this correct? Surely not with an AIM listed company?
It is indeed correct Nick. In order to receive dividends from a US domiciled businesses without tax deducted, you'll need to fill the form out and renew every couple of years or so. It's the same for Spectra Systems (LON:SPSY) (I hold)
cheers
Francis
Somero Enterprises Inc (LON:SOM)
When attempting to buy Somero shares I'm told by my broker to fill in a W-8BEN form for US shares. Is this correct? Surely not with an AIM listed company?
as fwyburd has confirmed it will be necessary - one additional important note you may find less tax (nil) is deducted from dividends if shares are held in sipp rather than an isa - this is a bit of quirky non standard situation so bear that in mind - to further complicate matters i think only some sipp providers let you get divis tax free for this company ! - bit of a quirky situation all in all.
I have my SIPP with AJ Bell and hold Somero Enterprises Inc (LON:SOM) in it. I have completed a W-8BEN for them which is very simple to do and by my calculations the recent dividend paid did not have any withholding tax deducted.
Somero Enterprises Inc (LON:SOM) Yes it is correct, it is a US company. It will reduce the amount of tax you pay on dividends.
Good point about holding in a SIPP, which I do which reduces the tax further to 0.
Further to a strong pre-close update from SWG and Schroder's becoming the largest holder recently more good news about 5 year extended framework:
Shearwater Group plc, the organisational resilience group which provides
cybersecurity, advisory and managed security services, announces that its
group company, Brookcourt Solutions Limited ("Brookcourt"), has extended its
framework arrangement with a leading British multinational investment bank and
financial services company, headquartered in London, England for a further
five years.
Shearwater (LON:SWG)
I am a somewhat happier holder here the last couple of weeks , must admit still not fully convinced on this one but they are in the super sexy organisational reseliance sector (come on guys and gals please rebrand that as cyber security). This is the very pleasing that they can retain long term customers (15 years) - in itself normally i would take this kind of run of the mill stuff with a pinch of salt , i feel with Shearwater i should cherish every bit of good news that comes along so i must admit i have cracked open a can of Rubicon to celebrate although i suspect i may be over reacting somewhat here.
RMilaree. I'm sure you are not alone in your suspicion. Ex gold miner turned organisational resilience organiser! They have at least added a footnote to that description to make it a little longer. Have you looked at the traffic light signals today on SWG? We have some and they look pretty good to me.
Regarding Somero Enterprises Inc (LON:SOM)
I’m impressed that they are not content to simply ride the wave of demand for the highly flat floors needed for warehouses for the rapid growth of e-commerce and are continuing to try to innovate to develop the high rise market.
In particular, their new product, SkyStrip, basically a machine that assists in the removal of overhead plywood sheets that have been used when forming concrete floors, indicates to me that they are thinking beyond floor levelling technology. Hard to evaluate the likelihood of success for this product but, even if this one is not particularly successful, the intention to develop additional markets by innovation is the right path in my view.
I hold.
Somero Enterprises Inc (LON:SOM)
Hard to evaluate the likelihood of success for this product but, even if this one is not particularly successful, the intention to develop additional markets by innovation is the right path in my view.
100% agree here - one of my negatives here was that i always got the impression that they seemed to be stuck in a bit of a rut trying to find the magical conistent growrth into new market segments without really delivering - perhaps they have now found that magical ingredient going forward - hopefully someone who closely monitors the sales splits here might offer an opinion as to how much the new stuff is likely to add - must admit having a quick look on the facebook page of skytstrip had very pleasing results and they had 5 star reviews - just a shame its a diffent kind of stripper i think :(. - damn i appear to have lost my train of thought here. Must remember to go incognito next time i do my som research.
Superdry (LON:SDRY)
Interesting comments reference lease renewals here - with rent costs being more than halved for the leases they have renewed. I am guessing they previously had some shockingly high payments going out but still a pretty staggering change in fortunes between tenant and landlord here.
Renegotiated a further 48 leases (~1/5 of the estate) in FY21 achieving aweighted average saving of 52% (65 lease negotiations have now been completed intotal), in addition to substantial one-off Covid-related rent waivers.
Looks like there is some turnaround potential. Was at Rushden Lakes at the weekend, and the SDRY store was extremely busy!
Those one fifth of leases would be low hanging fruit. The remaining four fifths of Superdry (LON:SDRY) is the worry. They're paying double the market rent on those, probably long lengths till a break event, compared to other fashion retailers taking up new empty units now.
My morning smallcap tweet:
Superdry (LON:SDRY) Virgin Wines UK (LON:VINO) Somero Enterprises Inc (LON:SOM) Gateley Holdings (LON:GTLY) Quixant (LON:QXT) Reach (LON:RCH) Hansard Global (LON:HSD) GetBusy (LON:GETB) Bilby (LON:BILB), Costain (LON:COST)
Superdry (SDRY) guides FY(Apr) rev down 21%. Q4 rev up 1%. Outlook "Confident...Profitability will be supported by higher gross margins from our restored full price discipline and positive operating leverage from reduced store costs, partially offset by the end of government support and our ongoing brand marketing investment." [SP=276 Cap=226m]
Virgin Wines UK (VINO) guides FY(June) rev and profit ahead of its previous expectations, with rev at least £73m and better EBITDA margin. Outlook "remains well positioned to continue to deliver its growth strategy and meet the Board's expectations for FY22". [SP=238.15 Cap=133m]
Somero Enterprises (SOM) guides FY(Dec) rev up c.13% and adj EBITDA c. $31m up 19%. Prev guidance was single mid-digit % rev rise and modest EBITDA rise. Cites strong US and signs of improving activity levels in Europe and Australia. [SP=435 Cap=244m]. I hold.
Gateley (GTLY) guides FY(Apr) rev materially ahead of market expectations and profit 'more significantly ahead'. Will resume divs with interim of 2.5p. F/C consensus was rev £111.7m and ad pretax £14.7m [SP=186 Cap=219m]
Quixant (QXT) AGM stmt - "Order intake remains strong, providing us with further improved order coverage for our internal full year budget. The global shortage of semiconductors is impacting many industries, including our own, and remains a risk we are continuing to manage." [SP=143.96 Cap=96m]
Reach (RCH) guides FY op profit slightly ahead of market expectations of £137.1m. [SP=220 Cap=687m]
Hansard Global (HSD) new business up 23% in Q3(Mar) from 12% in Q2. [SP=63.45 Cap=87m]
GetBusy (GETB) last 4 months rev up 10%. SmartVault new business rev up 44%. [SP=95.05 Cap=47m]
Bilby (BILB) guides FY(Mar) rev c. £60m after strong H2 but adj EBITDA only £3m due to higher operational costs arising from the increased no access rates and mix of works. Outlook good. [SP=36.1 Cap=23m]
In line: Costain (LON:COST)
Curious RNS from £JOU entitled "Joules establishes ESG-linked financing facility"
https://www.investegate.co.uk/...
So does this mean Barclays (LON:BARC) see themselves as at less risk if £JOU improve their ESG behaviour? Seems quite bizarre to me but these two factors are in some way related, I guess this is not completly ridiculous? Or is it just an Emperor with no clothes on situation?
Well yes, given that none of this directly impacts business or profitability, it is a bit ‘Emperor’s New Clothes’....but only a bit. In reality this is smart marketing on the part of both businesses, as they can both claim success against the same ESG stuff. Some ESG activity is of dubious value, but much of it can relate to business outcomes, eg we would usually prefer to invest in a business with high staff satisfaction, rather than low satisfaction. For the time being in these frothy markets (ie when loads of profits are being made all over the place) ESG is the institutions biggest theme....other things will become fashionable over time, but for now ESG is the wave to ride.
Morning all. Very positive year end update from Bilby this morning. Got through 2020 in one piece, reduced borrowings, strengthening the balance sheet and now talking about growth opportunities going forward. I hold.
Anexo (LON:ANX) webinar today at 12pm. Alan Sellers, Executive Chairman, Mark Bringloe, CFO and Nick Dashwood-Brown, Head of Investor Relations, will provide an introduction to Anexo Group Plc and an update on company performance following the 2020 full-year results which were released on 27 April.
Register: https://us02web.zoom.us/webinar/register/7616167470281/WN_NOV3Z2gKR7eyTA96UjynsQ
Maybe have a look at Sec Newgate Spa (LON:SECN) please? Good progress reported in RNS just now from emerging comms group. I hold.
Somero Enterprises Inc (LON:SOM)
Nice upgrade this morning
The Company's previous guidance for FY 2021 indicated revenues were expected to grow in the single mid-digit percentage range from the US$ 88.6m reported for FY 2020, adjusted EBITDA would grow modestly from the US$ 26.1m reported for FY 2020 and ending net cash would approximate US$ 27.4m. The Board now expects FY 2021 annual revenues will approximate US$ 100.0m, adjusted EBITDA will approximate US$ 31.0m, and a consequential improvement in the anticipated year end net cash position
This company definitely has hit a bit of a purple patch at present - I must admit I am very unsure as to whether their prior investments are now starting to pay fruit (they are continuing to invest for the future too) or whether their is a sort of temporary spike in demand that is not sustainable long term ?
Must admit that I did put a limit sell order in here yesterday at 450p - due to share price weakness in another share that delivered pretty stellar results - although a solid company they are subject to the whims of the construction sector and traditionally the share have never really commanded a premium rating so it seemed to be the easiest fruit to ditch while price was at historic highs - I have cancelled My sell order and will see how the dust settles. I suspect if the price does spike up today it won’t be by a huge %.
Bullish outlook from Somero Enterprises Inc (LON:SOM) this morning. It all looks good for Somero. What do you think?
Bullish outlook from Somero Enterprises Inc (LON:SOM) this morning. It all looks good for Somero. What do you think?
Revs et al,
I have owned Somero since the share price was just above £1 and benefitted from a strongly growing dividend, despite a wobble in the share price over the last couple of years before its latest upward move.
This Company is world leader, with strong patent cover in its small chosen field of flat concrete floors, where it is the undisputed world market leader. Most of its revenue is generated in the USA. The IP is in the design of the machines which are assembled from bought in parts. They provide training for operatives (contractors who win flooring contracts) using their kit in a purpose built facility located in Florida.
I think a case can be made rather like metals use (non ESG friendly but providing clean energy for EV cars) that flatter concrete floors in warehouses allow products to be stored higher, and more quickly, which reduces logistics costs of getting products from source to final end user.
The "Sky" Product range has been developing over a couple of years now, and attacks a more general market of concrete floors in residential buildings. I've no idea of its potential size for Someor would be were it to become the "go to" system in the USA. The Management will only say it would be substantial. Education of flooring operatives will be part and parcel of their plans to commercialise the system they are proposing and elimination of labour costs will be a target
SM
I know CEO Jack Cooney talked about about patent protection in most recent results but previous he had inferred that the greatest asset they have was the support they can give the contractor after they have laid the concrete (bearing in mind as soon as its laid the contractor is up against the clock as its sets dry).
Paul Scott did an excellent interview with him some years ago (in 2016) and he outlines their position that its more about the after service rather than patents that give them their ‘USP’:
PS: Okay. Could you touch on the competitive position?
JC: Yes. We had our first competitor in 1989, he was a Somero customer out of Holland, and basically anybody can reverse engineer our equipment, any mechanical piece of equipment. And we still have competitors today, and we anticipate that we will always have competitors. The difference that we have seen is that when a competitor copies a piece of equipment, he thinks of himself as an equipment manufacturer. So he copies a piece of equipment, puts it in his product line, and sends it out in his brochure. For us we are much more than just an equipment company, because what we do is we provide a piece of equipment to our customer, but we also supply the education, the training, and the ongoing technical support to make his business highly successful. Because our customer only does concrete floors, that is his whole business, and that is our only business. So it is up to us to not only just sell him a piece of equipment, but to make sure he uses it so that he can meet the specifications, the flatness specifications, that building owners want, and to be a highly successful business. And that is what separates us from the other people who are just making machines. What also goes along with the technical support is that since we sell in 95 countries/93 countries around the world, we have 24/7 phone support. And in that period of time we will guarantee that you will get a certified engineer on the phone in ten minutes, and we have a translation system built into our phone system, so we can talk to people in 65 different languages. That is not something that any of our competitors have.
full transcript of the interview can be found at:
http://qualitysmallcaps.co.uk/wp-content/uploads/2016/03/2016-01-20-SOMERO-AUDIOCAST-TRANSCRIPT.pdf
For what it’s worth I sold out when the blamed bad weather on poor financial results and then bought back in a year ago when I realised they had been actually telling the truth!!
Morning all,
Excellent update from Gateley Holdings (LON:GTLY) this morning. Legal sector seems to be flying!
Regards.
I don't hold by the way...