Small Cap Value Report (Thursday 5 January 2023) - DTY, MTW, NXT, BME, GLV, GRG, AGL

Good morning from Paul & Graham! All done for today, see you tomorrow!
Agenda
Paul's Section:
As usual for this time of year, I'm going to focus on the first retailer trading updates, which are mid caps - this is to test the water, and give us something to benchmark the smaller companies against, when they report. So today I'll be reporting here on -
Next (LON:NXT) - an excellent update, with strong sales over Christmas (helped by cold weather driving demand for outerwear). Profit guidance is raised, but higher corporation tax takes a hefty bite out of guidance for FY 1/2024. Inflationary pressures beginning to ease for H2 of calendar 2023 has positive read-across for many sectors. Lots of interesting stuff in here, so I go through it in a fair bit of detail below. Thumbs up for a great quality business, although forward PER of 13.2 is probably a fair valuation right now, given that it's a mature business.
Greggs (LON:GRG) - in line with expectations update for FY 12/2022. But within the detail, there's a lot of positive stuff. It's coping with inflationary pressures, and clearly gaining market share, with very strong LFL sales growth. I'll give it a thumbs up for the quality of the business, and good growth potential, although the valuation is looking stretched after a strong recent run. More detail below.
B&M European Value Retail SA (LON:BME) - a positive Q3 (Oct-Dec 2022) update, and FY 3/2023 EBITDA guidance is raised. I continue to like this share, which seems reasonably priced, and has a particularly strong 8.3% dividend yield, when you include special divis. Thumbs up from me. More detail below.
This is in addition to our reporting on small caps, not instead of!
Dignity (LON:DTY) - bid approach is announced, almost 3 months after discussions started, which is an outrage I think, and has resulted in a false market in the shares, causing losses to sellers who were not told that takeover talks were underway. The regulations on disclosures of takeover approaches are appalling, in my view - we need to press for regulatory changes. More detail below.
Angle (LON:AGL) - profit warning, shares down 31%. I run through the detail below, but whilst it sounds an interesting project, the timescales are now extended out even further, and the cash pile looks set to run out in 2024. This type of share rarely pays off, other than as a speculation in a bull market. So it has to be a thumbs down as an investment idea I'm afraid, because I don't think they'll be able to commercialise it before the cash runs out.
Graham's Section:
Mattioli Woods (LON:MTW) (£324m) - this financial services provider releases an H1 update that is in line with expectations. We don’t cover this stock often, but I’m impressed by what I’ve seen from it today. Its asset management businesses enjoyed net inflows despite the very poor investor sentiment during the period and while organic revenue growth was modest, the company’s string of recent acquisitions have helped to boost the top line. This is a founder-led business with a strong cash position that is positioned to benefit from a bounce in asset prices. It all looks very credible to me and so I think this one is worth researching in further detail.
Glenveagh Properties (LON:GLV) (€584m) - this Irish homebuilder posts a profit warning for 2023, as 20% of the suburban housing units it planned to deliver this year are still trapped in the planning process. Despite that bad news, and the fact that it now has a small net debt position, the company plans to carry out a fresh buyback for up to 10% of its outstanding shares. It’s a sign of confidence in its cash generation abilities and also its determination to achieve an ROE target of 15% in 2024 (one surefire way to boost ROE is to reduce your equity!). I find this stock interesting: if the planning system can speed up and if Glenveagh can still afford to fund their growth plans, their shareholders could see very nice results from 2024 onwards.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul’s Section:
Dignity (LON:DTY)
535p (up 26% yesterday)
Market cap £268m
Advanced discussions regarding a potential recommended cash offer
This was announced shortly before the market close last night.
Two major shareholders, Castelnau and SPWOne (who together hold 29.7% of DTY via Phoenix Asset Mgt) want to take DTY private in a cash bid priced at 525p.
It discloses that this 525p offer was made to DTY ages ago, on 13 November 2022. That followed previous takeover proposals at 475p (on 13 October 2022), then improved to 500p, 510p, and finally 525p.
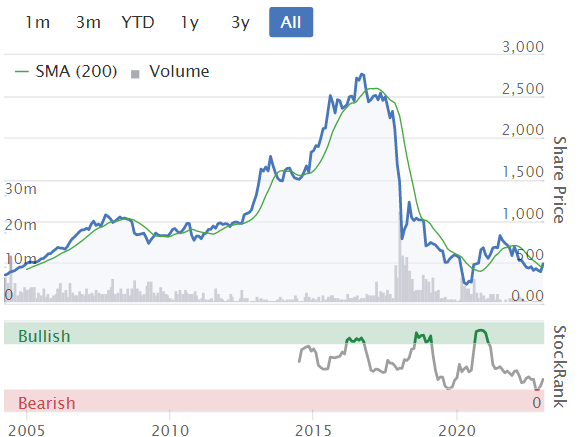
Yet none of this was disclosed to the market until yesterday, 4 January 2023. This is outrageous, and is a glaring flaw in UK regulation. To my mind, there has, since 13 October, effectively been a false market in DTY shares. Crucial price-sensitive information (that a premium priced takeover bid had been proposed by a consortium of the 2 largest shareholders) was being discussed with management, yet nothing was disclosed to the market. So people selling their shares between October 2022 and yesterday, were selling at a falsely low price, unaware of the active takeover proposals. This is wrong!
Also, are we seriously meant to believe that a takeover approach can be negotiated over almost 3 months, and nobody did any insider dealing? There must have been hundreds of people involved in some form, who knew about this price sensitive information, and somebody somewhere will probably have quietly tipped off a friend, or relative. Hardly anyone gets prosecuted for insider dealing of course, but the victim is the person selling their shares at an under-valuation, unaware that there’s going to be a surge in share price from a takeover bid. Whilst the insider dealer makes free money, and as long as there’s no paper trail, and no obvious connection to an insider, can plausibly deny any wrongdoing.
This is an outrage, and we need to lobby harder to get the rules changed for takeover bids.
I suggest that we all write to the Takeover Panel, and our MPs, to make it clear that the rules have to change, as they’re glaringly, obviously unfair and unreasonable at the moment. I'm sure that everyone who sold their DTY shares in the last 3 months will be motivated to write, and should do so, as they've been fleeced!
I’ve myself written to the Takeover Panel already on this topic, but will do so again. Their response was dismissive, saying that companies receive takeover approaches all the time, and they only have to disclose something if it’s leaked to the press! How pathetic is that?!
ShareSoc and Lord Lee have been campaigning on this issue, and I urge anyone concerned about this grotesquely unfair situation, to get involved.
In my view, companies should be obliged to immediately inform the market whenever they receive a credible takeover approach. Such an announcement should indicate what stage the proposals are at, and have the usual warnings that an offer may or may not occur. Why is it voluntary for companies to disclose (or not) such crucial information?
Statement from the (possible) bidder - also issued last night, and confirmed that it has approached DTY with a bid proposal (not yet firm).
It’s very interesting actually, and outlines why it thinks DTY could be better developed in private ownership - with better access to long-term capital, and less public scrutiny.
This is another example of where low valuations, and regulatory costs & hassle are making public markets less & less appealing. Hence I think we’re in a new era where the number of public companies is likely to considerably shrink, as the best (and the worst) companies leave the public markets, through either takeover bids, or going bust/delisting due to lack of follow-on capital.
That should provide plenty of opportunities to make money from takeover bids, if you can identify probable bid targets in advance - much easier said than done!
DTY has had an unhappy time as a listed company. My view is that financial engineers tried to be too clever, loaded the company up with excessive debt, and tried to exploit vulnerable people (bereaved families). Then it was hit with regulatory action by Govt (good!). So it's one of the last companies that I would have imagined would interest a buyer, but who knows what they're planning to do with it once the glare of the public markets has been removed? There's obviously some angle that the buyers think can be lucrative, otherwise they wouldn't be trying to buy it.
.
Next (LON:NXT)
6600p (up 8% at 08:39)
Market cap £8.5bn
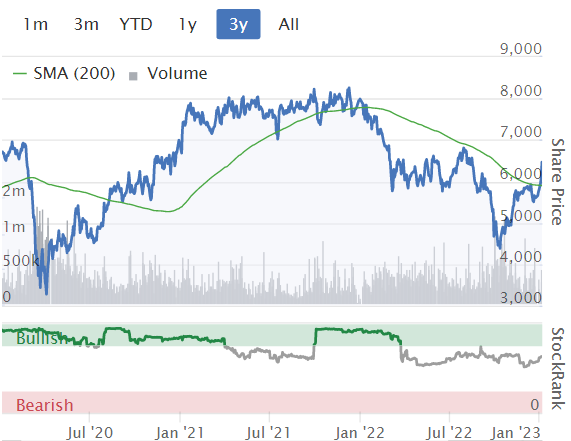
Amazingly, this share is up 51% from the recent low (in Oct 2022). It’s obviously the sector leader in terms of being so well managed, and providing the best and most timely guidance to the market. I always report on it here, so we have a benchmark to measure the small cap retailers against, and to provide ammunition to ridicule all their excuses for poor performance!
Next seems to have an uncanny ability to serenely navigate any macro conditions, no matter how bad.
Key points -
Christmas period sales “better than we anticipated”.
Profit guidance raised by £20m to £860m for FY 1/2023 (up 4.5% vs LY)
FY 1/2023 EPS guidance 567p (up 6.9% vs LY) - PER of 11.6 (at 6600p per share) - looks good value.
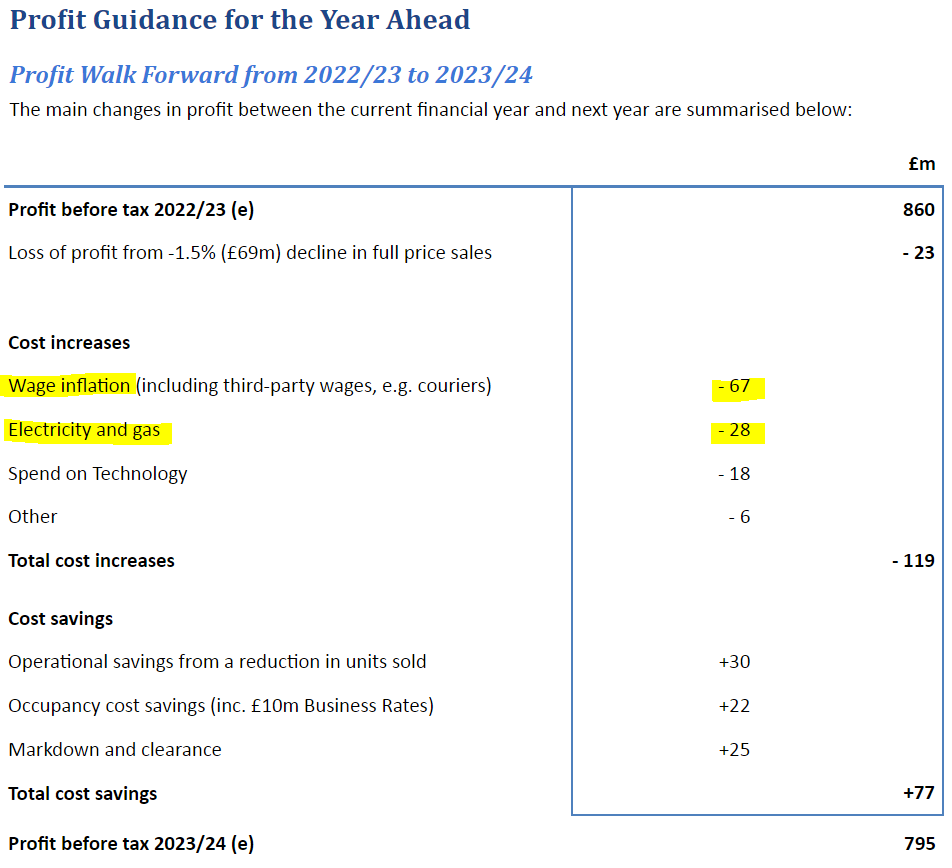
Cautious outlook - initial guidance for FY 1/2024 is PBT £795m (down 7.6% on this year)
EPS guidance for FY 1/2024 is down 11.7% to 501p (PER of 13.2, at 6600p per share) - with higher corporation tax being a significant impact - something we need to factor in at other companies (and check that broker forecasts have done so).
Sales growth came from the shops (+12.5% in Q4), not online (which was flat) - the opposite of the usual trend for online powering growth.
Strikingly strong sales growth in the cold weather in December (which drives demand for coats, etc)
Overstocked, so more had to be cleared at discounts in the end of season sale.
Cautionary note says that FY 1/2023 outcome is “almost exactly in line” with original guidance given in Jan 2022. So NXT says don’t assume guidance for FY 1/2024 is too cautious (which people apparently did a year earlier).
“Not anticipating a collapse in demand or any increase in bad debt…”, due to full employment.
Obvious headwinds to customer demand mentioned - inflation (esp energy), rising mortgage costs, and passing on its own higher costs.
Inflation outlook for NEXT products - peaking at c.8% in spring/summer 2023, then expected to fall to a maximum of +6% in H2. That’s encouraging, as previous guidance was for higher inflation in H2. “Cost pressures are now easing…” due to -
- Lower freight costs
- Lower factory gate prices (benefit from recent weaker dollar)
- Commodity prices lower (e.g. cotton, polyester)
- Surplus capacity in factories, due to slowdown in global demand
- New (cheaper) sources of supply.
That’s all confirming what we already suspected - that inflation has probably peaked, and is likely to fall in 2023. NXT says that the underlying reason for 2023 inflation is dollar strength, with a table showing the adverse forex movements compared with the prior year - remember that there’s a time lag, due to hedging.
Outlook for inflation in 2024 is a further move downwards, if the recovery of the pound vs dollar persists, and factory gate prices remain subdued.
Clearly all of this has widespread read-across to many other sectors, and is encouraging news.
Inflation for overheads - wage inflation and energy costs are mentioned as the main problems, no surprises there. Energy is fully hedged for FY 1/2024, but “at rates significantly higher than the current year”. A superb profit bridge shows all the moving parts anticipated - isn't this fantastic, and it just shows what superb control management has over the business, to guide at this level of detail for the year ahead -
.
Corporation tax increase is obviously quite significant, and is expected to dent EPS by -6.8% for FY 1/2024, more than offsetting the +2.7% benefit of share buybacks.
My opinion - an excellent update, but we should now be valuing NXT shares on the lower 501p EPS guidance for FY 1/2024. The PER is 13.2, and I’m struggling to see why the valuation should be much higher than that, given the current macro position.
Also bear in mind that, despite being the best in class operator, NEXT is a mature business, and profitability is only really going sideways.
Therefore, I give the business overall a thumbs up, but in terms of valuation, it’s probably about right for now - maybe some traders might want to bank the big recent % gains?
An interesting angle on this, is whether online fashion has now peaked? NXT says its shops are recovering nicely, and I am wondering if consumers are getting tired of online shopping, and are more eager to return to physical shopping? Only anecdotally, but I had some interesting chats with family over Christmas, where the younger generation said they’re tiring of online shopping for clothes, and having to return so many items, one describing it as a “faff” compared with conventional clothes shopping, where you try things on, so usually don’t need to return things. Plus they think it’s more enjoyable, and more social, to actually physically visit shops. This theory seems to be backed up by the bombed out share prices of the whole eCommerce sector.
OR, are eCommerce shares oversold, and due a recovery? Who knows.
A final thought, I wonder if NXT could be a takeover target? It's a highly cash generative business, which financial buyers tend to like, so that's a possibility I'd guess.
EDIT: I see the strong update from NXT has given a boost to Sosandar (LON:SOS) which is a top-5 supplier to Next's third party brands online business. That doesn't make sense to me, since NXT said the growth has come from in-store, not online! Also I see Superdry (LON:SDRY) has also bounced today. SDRY is only operating a whisker above breakeven, so is highly geared to changes in demand.
Greggs (LON:GRG)
2450p (up <1% at 11:12)
Market cap £2.5bn
Let’s finish off my mid-cap early bird retailers reviews with a big fat pasty & a doughnut!
Greggs is a leading UK food-on-the-go retailer, with around 2,300 retail outlets throughout the country
Strong quarter ends a year of encouraging strategic progress
Robust financial position supports growth plans
Profit guidance - it’s as expected, in line with expectations -
Given our strong trading in the year, together with careful cost control, we anticipate reporting a full year outcome for FY22 in line with our previous expectations when we report our preliminary results for 2022 on 7 March 2023.
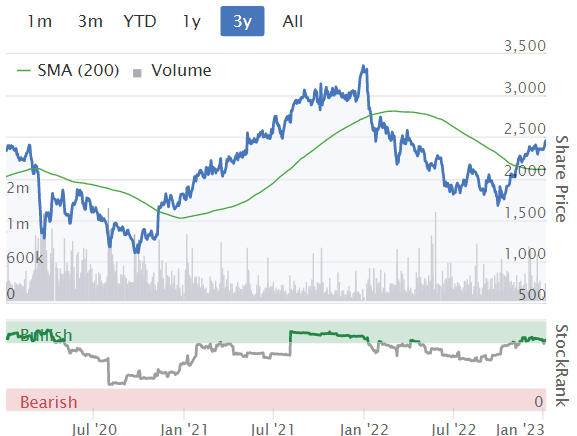
There’s no footnote to say what expectations are, and no research available on Research Tree. So using Stockopedia’s broker consensus of 118p (only slightly above LY actual), gives us a PER of 20.8x which looks punchy (as it nearly always does with this share).
Little change in EPS is currently expected by brokers, with it rising only slightly to 122p in FY 12/2023 - not very exciting, and not justifying a PER of just over 20, in my view. So shareholders must be expecting it to beat current forecasts.
Having said that, the update today is full of bullish points -
Superb LFL sales growth of +17.8% for FY 12/2022 - that’s the highest sales growth I’ve seen for any retailer so far. We’re not told the split between price rises, and volume changes. But it’s clearly showing that Greggs must be gaining market share, as it should, as pretty much the only remaining affordable fast food outlet out there. That’s a big competitive advantage. Places like Pret have become so expensive, that I’ve switched to Greggs myself, and I bet plenty of other people have (although Pret is launching a new value range of sandwiches, I see in the news today)
Store roll-out - it already has 2,328 shops, but is planning on opening c.150 net new stores in 2023, so there’s growth coming from there. I wonder what the maximum market size is?
Growth from online app, delivery services, later opening, and broadening product ranges, growth in veggie/vegan products, etc.
Absorbing inflationary cost pressures it seems, with the strong revenue growth compensating.
Shrugged off rail strikes and bad weather in Dec 2022.
It’s all about value for money - we’re seeing this with BME above, SHOE, and others - retailers that provide value for money products are doing fine, as customers trade down.
Cash of £191m is good, and last balance sheet is OK (not especially strong) in my view.
My opinion - this update sounds really good. There sounds continued growth potential at Greggs, and it really has very little direct competition - selling quite nice product, at very competitive prices. I think that’s clearly a winning formula, so there is an argument for over-paying for the shares, to get a slice of that delicious, calorie-laden pie.
So from me it’s a thumbs up for the business, but the valuation is at the top end of what I’d consider reasonable. Hence it’s going on my watchlist, not my buy list.
B&M European Value Retail SA (LON:BME)
447p (up <1% today at 10:34)
Market cap £4.5bn
That’s an impactful title for the announcement!
I last briefly reviewed this mid-cap value products retailer here in Nov 2022, on a solid H1 trading update. It had a tough Q1 (Apr-Jun 2022), but things improved in Q2.
What I find attractive about this share is - strong long-term growth, reasonable valuation, and quite good divis. Also selling value products from large sheds should be a resilient area of retail in tough macro times.
This is what it says today, for Q3 (13 weeks ended 24 Dec 2022) -
Q3 revenue up 12.3% vs Q3 LY
UK like-for-like (LFL) revenue up 6.4% at B&M stores (main part of the business)
France trading well, but not clear if +25% revenue growth has been helped by new store openings or not?
Heron Foods - similar thing, +23% revenue, but no info on LFL performance. Why not?
Supply chains flexible, and “executed well” in Q3.
Special dividend of 20p declared - that’s significant, at a 4.5% yield, and when you include the 5p interim, and maybe c.12p final (my guess, based on a small uplift on LY), that would be a total divi yield of 8.3% - terrific for income investors. Although I’m not sure what to make of this footnote -
The dividend declaration is subject to completion of Luxembourg regulatory procedures and will be subject to a deduction of Luxembourg withholding tax of 15%.
Profit guidance for FY 3/2023 is raised -
FY23 Group adjusted EBITDA4 (on a pre-IFRS16 basis) now expected to be in the range of £560m to £580m, ahead of current analysts' consensus estimate of £557m
My opinion - thumbs up from me. This seems a good growth business, reasonably priced. It did enjoy a boom during the pandemic period, but seems to have held on to most of those gains. Note that the forecast divis don’t include specials, which more than doubles the actual yield to over 8%. Hence very attractive to income seekers. It should also be able to continue growing, and I think value products will never go out of fashion.
I must do a mystery shop of my local store, that’s going on my to do list.
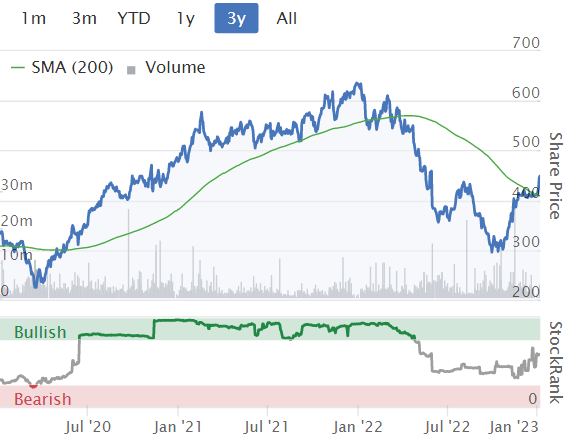
Angle (LON:AGL)
33p (down 31% at 12:23)
Market cap £86m
Business Update (profit warning)
ANGLE plc (AIM:AGL OTCQX:ANPCY), a world-leading liquid biopsy company, is pleased to provide a review of business progress, an unaudited trading update for 2022 and prospects for 2023.
Bad luck to holders today, with £39m wiped off the market cap in a 31% fall, triggered by this disappointing update. I try to report on all profit warnings, so we have a record of what happened, and sometimes there can be spectacular gains from the low points.
It starts off by reiterating the positives of this development project (it’s still largely pre-revenues, and heavily cash-burning).
A fundraise of £18.9m (net of fees), and cost-cutting, means it claims today to have enough cash to last until H2 2024.
R&D has been centralised in the UK, with Canadian operations closed, due to favourable UK R&D tax credits.
Decision to outsource some analysis to third party platforms (to save money).
Cost-cutting will save £2.6m in 2023, and £4.0m pa thereafter - not enough to make that much difference.
“Impact of wider market conditions” has slowed down commercialisation, although it now has FDA clearance (which took over 6 years to achieve).
2023 sounds like it will be another year of preparation for growth, rather than actual growth!
Cash at end 2022 in line with expectations at £32m, with no debt. Not bad for an £86m market cap company, but bear in mind the cash is all likely to be spent in 2023 and 2024.
Heavy loss of £22m expected for 2022.
Revenue for 2022 below expectations, as some sales were delayed, but this is immaterial overall, as only £2.0m revenues were expected in 2022.
Demand - has softened as macro conditions mean customers are being cautious.
Revenue for 2023 - strong growth expected, “but likely to be materially below current market expectations” (which are only £5.9m, so revenues likely to be very modest again in 2023, and continuing heavy losses & cash burn).
Growth opportunities are explained in some detail, which I won’t repeat here.
My opinion - Angle has always struck me as a plausible-sounding project, not that I’m fit to judge, having no medical knowledge.
The trouble with this type of share, is that development takes many years, and cash burn is a recurring problem. Thankfully AGL got a fundraise away just before the window was slammed shut by Mr Market. So it’s OK for the time being, but realistically, it’s likely to be looking for more money in about a year, in preparation for running out of cash again in 2024.
So risk just got considerably worse, after today’s news that commercialisation is not happening any time soon.
This looks risky to me, but there’s always the remote chance it might do well. People have been saying that ever since it listed in 2004, and all that’s happened so far is massive dilution from repeated fundraises, and losses that seem to worsen every year.
The problem with this type of share, is if it does hit the jackpot commercially, someone will just come in and buy it, taking away the upside. So we have to take all the risk, and fund the project over a huge timeframe, but someone else gets the benefit if it does work. Maybe I’m too cynical about this type of share, but they can make good speculations in a bull market, but the long-term holders are rarely rewarded, because the dilution has eroded so much of the upside along the way.
Almost 20 years this has been listed!
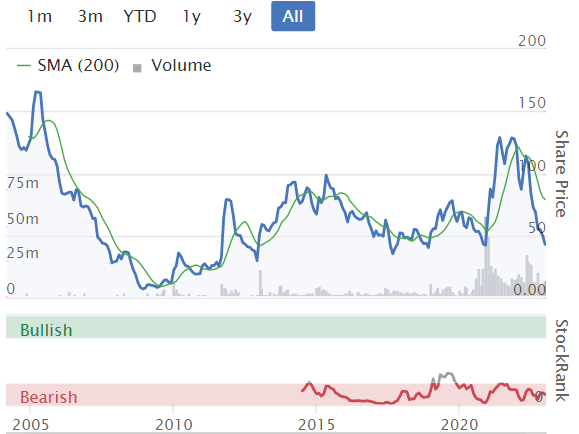
Graham’s Section
Mattioli Woods (LON:MTW)
Share price: 632.2p (+0.3%)
Market cap: £324m
This is a “specialist wealth management and asset management business”. It offers a wide range of services across retirement accounts, business planning, employee schemes, insurance, etc.
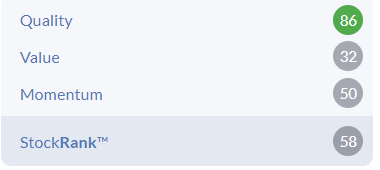
We don’t usually cover it in this report. However, it has a very high QualityRank, so perhaps we should? Let’s take a closer look.
Today brings an in line with expectations H1 update for the period ending November 2022. Key points:
2% fall in client assets.
Organic revenue growth 2%.
Total revenue +10% (due to acquisitions) to £54.9m.
Organic revenue growth that’s below inflation is never very encouraging, but we have to bear in mind the effect of falling stock markets on a company like this. Mattioli earns both fixed fees for the advice and services it provides, and asset-based fees that are a function of its clients’ portfolio values. So when markets are falling, Mattioli shares in the pain.
The outlook for H2 revenue is better: there’s usually a seasonal H2 weighting as clients organise their affairs and need extra help around the end of the tax year (H2 ends in May).
The company also indicates that its management fees will be higher in H2 thanks to “market value improvement”, which I guess refers to an increase in average asset prices compared to H1.
The full-year revenue estimate is £116.5m, i.e. H2 revenues are expected to come in at £61.6m. This forecast is left unchanged by the analysts at Singer, whose latest note I’ve managed to get a copy of today.
Reasons for optimism
There are several points in this trading update that strike me as positive:
The company’s “discretionary” AUM fell 4% in the period but this was due to falling asset prices, not clients moving their money out. The company enjoyed net inflows from clients during the period, as inflows were slightly higher than outflows.
Acquisitions are performing “in-line or ahead of budget”.
Strong cash position of £38m. No borrowings.
CEO comment
The outlook for bottom line profitability seems resilient, as the CEO confirms that Mattioli ”maintained profit margins through prudent cost management and in realising further operational efficiencies”.
The adjusted PBT estimate for the current year is £30.8m, a 5% increase on last year.
My view
I’ve repeatedly pointed to the fund management companies as a nice sector in which to bet on a stock market recovery. Perhaps Mattioli, despite being involved with many other activities in addition to asset management, could also offer decent upside when markets recover?
For example, Mattioli owns 49% of Edinburgh-based Amati Global Investors, the boutique fund manager.
Amati is a small-cap investor whose £700m ”UK Listed Smaller Companies Fund” has fallen 23% over the past year. Top holdings include Osb (LON:OSB) , accesso Technology (LON:ACSO) and Craneware (LON:CRW) . I would expect this fund to participate in a small-cap rally, whenever it arrives!
I’m also encouraged by Mattioli’s track record when it comes to M&A: it has reportedly made nine acquisitions in the last 2.5 years, and all of them are doing well, and all of them “delivered earnings to support full payment of any contingent consideration, building upon our track record of 34 successful acquisitions to date”. Sounds good!
The company is still led by its co-founder Ian Mattioli, who retains a 6% stake. According to Stockopedia, Mr. Mattioli is still only 59 years old. It’s always nice to see a successful, founder-led business on AIM.
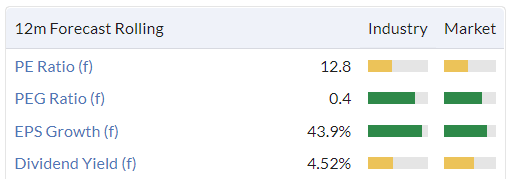
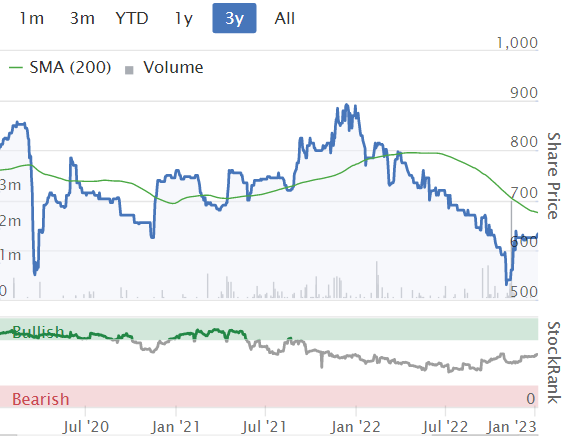
In conclusion, I’m inclined to take a positive view on this company. As for the stock, I think it may offer an opportunity at these levels, as it has fallen 27% over the past year and now offers a healthy yield and an average earnings multiple. Remember that it has plenty of cash, too, which gives some extra comfort:
Glenveagh Properties (LON:GLV)
Share price: €0.82 (-7%)
Market cap: €584m
We’ve never discussed this one before - but why not take a quick look? Please note that despite being listed on the LSE, this one is quoted in Euros and cents.
Glenveagh is “one of Ireland's leading homebuilders… focused on delivering high quality homes in flourishing communities.” It develops suburban houses, urban apartments and other government-partnered construction projects.
Here are the highlights from today’s full-year update, which includes a profit warning for 2023.
Revenue +36% to €649m
1,354 suburban units closed, +50% higher than the number of units closed last year.
Slight reduction in gross margin from 17.4% to below 17% (input cost inflation mostly being passed onto buyers!).
Profits for 2022 are in line with expectations:
Operating profit €70m (last year: €50.6m)
EPS consistent with guidance at 7.6 cents.
Landbank value decreases to €465m, “with further reductions anticipated”.
FY 2023 update
The forward order book of 408 suburban units contracted or reserved for the current year does not sound like it offers much growth for the company this year.
Indeed, if we do a like-for-like comparison with last year’s trading statement, the company had 605 suburban units in the order book then.
The company confirms that it’s not expecting suburban unit growth this year:
…planning delays will have a near term impact on suburban unit completions for FY 2023 and in this context we now anticipate suburban unit deliveries in line with FY 2022 levels
The company had previously anticipated that suburban unit deliveries would increase to 1,700.
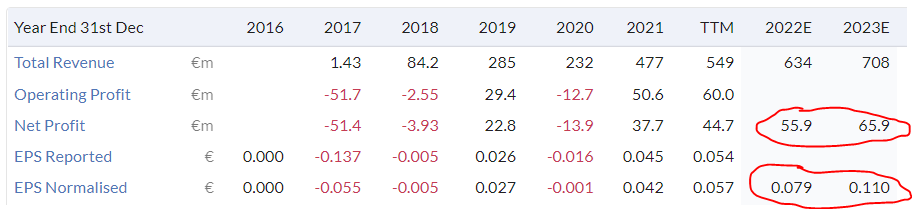
EPS is also now expected to stay flat in 2023. The StockReport suggests that EPS growth had previously been pencilled in:
Buybacks - the company apparently believes that it is undervalued, and that it has more cash than it needs.
It already reduced its share count from 772m at the end of 2021, down to 638m at the end of 2022, spending €145m in the process. For a company of this size, that’s a very big buyback!
Today it announces that it will buy back up to another 10% of its shares, i.e. another 64 million shares could be bought back.
Note that the company does currently have a small net debt position (“less than €15m”).
CEO comment - the CEO is clearly unsatisfied with the planning delays, describing planning policy as “dysfunctional” and calling for reform, “to solve the longer term structural supply issues”.
20% of the units which Glenveagh previously planned to deliver in 2023 are now more than 10 months late in receiving planning permission.
Outlook
The company still believes that it can deliver 2,000 suburban units in a year, and it still wants to achieve ROE of 15% by 2024 - this explains why it needs to buy back lots of shares, to reduce the denominator in the calculation!
The Group has a very healthy land portfolio and continues to have strong confidence in its capacity to achieve its 2,000 suburban unit target, as well as the continued delivery of urban projects and first revenue from its developing Partnerships business for FY 2024. We will also continue to focus on generating greater balance sheet efficiency which supports our confidence in achieving a Return on Equity of 15% by 2024.
My view
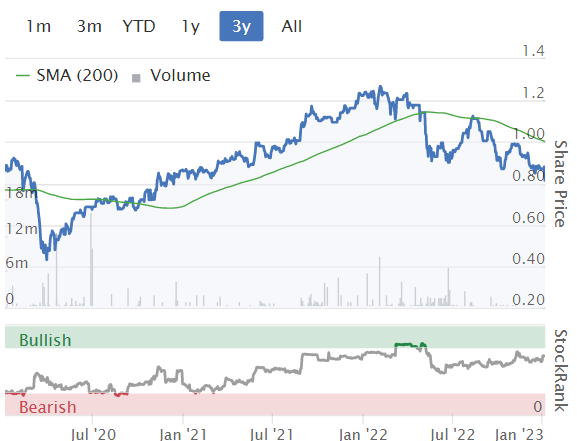
My interest has been piqued in this one. The size of last year’s buyback stands out, and the fact that the company is planning another one.
As things stand, if they aren’t investing too much in land, then they might not be overstretching themselves and taking on too much risk, and the buyback strategy could turbo-charge EPS over the next few years.
Your view on the overall property market is of course another important variable.
First-time buyer rules in Ireland have changed this month, meaning that lenders can now offer up to 4 times household income as standard (for several years, this was stuck at 3.5 times!). I think this will do a lot for homebuilder margins, as a couple on (say) €80k can now immediately increase their house buying budget by €40k.
Of course the point of the policy is not just to increase homebuilder margins. It’s also supposed to do things like increase supply! And supply depends on other variables including, as pointed out by the Glenveagh CEO, the planning process.
I’ll sit on the picket fence when it comes to Glenveagh, as I need to learn more about them. But my initial impressions are positive: they have maintained decent margins during an inflationary period, their developments are attractive, and they are focused on achieving a strong ROE (even if that means accepting some financial risk).
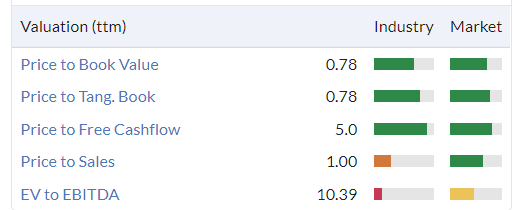
At a discount to tangible book value and a P/Sales multiple of 1x, according to the StockReport, I think this could be interesting.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

39 comments
Wynnstay (LON:WYN)unfortunately a further fall of almost 10% would indicate more than a few small trades; an adverse trading statement coming up perhaps, which would be a surprise given the last trading statement from the company.
Great news for holders of Doric Nimrod Air Three (LON:DNA3) and Doric Nimrod Air Two (LON:DNA2) today as reports suggest that delays in delivery from Boeing will mean that Emirates will have to continue with their fleet of A380s. 19% dividend yield and a 50% increase in stock price over the year have made these two my best performing stocks of 2022.
Doric Nimrod Air Two (LON:DNA2) (I hold)
Hi Graham
Thanks for sharing.
Here's an article from the WSJ on the Boeing delays for any holders or interested buyers:
https://www.wsj.com/articles/b...
Additional information and commentary here:
https://www.lemonfool.co.uk/vi...
A
Interesting to see a divergence between US and UK indices with the former consistently off and the UK turning around a bit. To some degree it does make sense as UK was nowhere near the over-valuation we saw state side pre QT and rate rises, but unusual to see us going one way when the US is doing the opposite.
Some of the US stocks are even looking relatively cheap, such as Apple (NSQ:AAPL), Alphabet (NSQ:GOOG) and Microsoft (NSQ:MSFT, I have been buying some.
B&M European Value Retail SA (LON:BME) Mystery shop may be a good idea Paul, many empty shelves, dated interiors, untidy stores and in many cases prices higher than say privately owned "Home Bargains" and several others. A "Peter Lynch" type check-up ?
I have one near me, big shop but not many customers, I don't find it that cheap for many items and quite a few products I want, they never have in stock. I think Wilco's are far better. I agree dated and have not really changed in the last 5 years. The don't even have what's in stock on the website for each store, many other stores manage that now, even a similar local brand has that.
B&M European Value Retail SA (LON:BME)
Agree mystery shop would be a good idea but bear in mind they vary enormously in size - the one near me is small and just does food and household goods whereas the Bournemouth one is massive having taken over a previous Homebase and does eveything from a garden centre to this nice line in Teddies:
https://www.bmstores.co.uk/sto...
Deep dive into SCS - worth reading imo
Sofa Carpet Specialist | Not another value trap
https://alaric.substack.com/p/sofa-carpet-specialist-not-another?utm_source=profile&utm_medium=reader2
Thanks for posting this eParo, and perhaps its just me, but the link doesn't lead me to the article. Please could you kindly re-post? Much thanks
SCS (LON:SCS) - try this
https://alaric.substack.com/p/...
Wandered through Primark recently and they have Gregg's branded clothing - t-shirts, etc.
Is Greggs's cool?
The kids love the Greggs clothing. When it was launched the clothes were snapped up. Go figure!
Seeing a few breakouts last few days: Bodycote (LON:BOY) , Wilmington (LON:WIL) , Jupiter Fund Management (LON:JUP) ,Ricardo (LON:RCDO) , Wickes (LON:WIX) , hopefully can push on!
Regarding Dignity (LON:DTY) I think the underhanded way Castelnau (is this French?) and SPWOne have gone about it means they could have bought up the shares unknowing PI's sold on the duration on the cheap.
The chart makes it absolutely clear that there was insider trading on 13 October.
Paul, Thanks for your comments of the need for reform of the disclosure rules on takeover approaches. Why isn't this already covered by existing rules on disclosure of material market sensitive information? It seems to me that a series of approaches at steadily increasing price would affect the market's view of the value of the company in just the same way as "ahead of market expectations" profit forecasts.
Is there a better way to contact the takeover panel than their advertised email address supportgroup@thetakeoverpanel.org.uk?
A better way is unknown to myself but I have written to the email suggested.
I must play Devil’s Advocate on this.
More and more listed companies are going private because of the cost of listed company regulation. (Indeed Dignity might be a case in point.)
The proposed solution to many problems is more regulation - but should there be more regulation, rather than the enforcement of the current law against insider trading.?
As the Takeover Panel says listed companies do often get lowball, unserious, boat floating takeover approaches. If an approach is made it can be deeply unsettling to staff, suppliers and customers. To make all such approaches public would be a significant additional disruption (and so implicit cost) of being a listed company.
None of this is to condone or minimise the cost of insider trading. But it needs to be considered if the cost of the cure to UK plc would be greater than the cost of the disease.
Any ideas why Wynnstay (LON:WYN) has just taken a nosedive?
Wynnstay (LON:WYN) "nosedive" @Indie? It looks like a few very small trades, so maybe it's just PIs rebalancing their portfolios for the new year.
Wynnstay one of my favourite steady eddy companies .
Just topped up at 559p.
If falls to 500p level then that’s where my Crestchic windfall will go .
Morning Paul,
I welcome your commentaries on Greggs, BME, NEXT. Think they are important bellwethers for the economy as a whole. With specials, LON:BME has had a pretty exceptional yield over the couple of years. The success of its newer businesses also bodes well.
As good as it is to see retail big players doing well, it feels like a bitter sweet pill. It likely means we are going to continue to fight an unwinnable fight against the hawkish Fed (and B of E) for a prolonged period of time.
Inflation really is the key to unlocking a return to a bull market, and I am unsure as to whether a sharp shock now or a slow grind through 2023 is the better course.
The good News is, it appears a buoyant Christmas is helping the population to burn through is COVID accumulated cash reserves, which hopefully will slow spending sooner and thus inflation.
The current consumer spending signals are waving Red flags to the already Hawkish Fed (See minutes released last night), with food inflation at its highest on record.
My only hope is that Next (LON:NXT) and the like is the cream rising to the top, rather than a large scale continued consumer spend. My local town remains rammed with people, with cafes, pubs and restaurants still full! While this continues I am unsure how inflation is supposed to fall quickly, and seems to indicate a difficult 2023 for many equities.
I keep hearing feedback about pubs being busy and people eating out. Maybe it won’t tank as badly as being predicted. Rishi saying he will cut inflation in half. I heard that and thought he said it as an easy win of his 5 as it will happen anyway and he can claim it. Next (LON:NXT) is encouraging and it is certainly helping others such as Sosandar (LON:SOS)
Then you hear other stories that pubs are not doing food because of staff staff shortages.
So the ones that are doing food are busy.
Pubs are closing at a rate of around 50 per month, this is up from 30 a year ago.
The problem seems worse outside towns and cities. Lack of public transport is an issue in some areas.
Supply side inflation - even when it comes to staff. I was in a small burger establishment recently and they had to turn people away due to lack of staff to serve/cook. Lack of staff appears to be the trend in most places, which affects their ability to take advantage of demand.
My morning smallcap tweet: Flogging companies
Proteome Sciences (LON:PRM) Angle (LON:AGL) Live (LON:LVCG) Seeing Machines (LON:SEE) Checkit (LON:CKT) React (LON:REAT) Galliford Try Holdings (LON:GFRD), Mattioli Woods (LON:MTW)
◄Proteome Sciences (PRM)► gets milestone payment of £0.87m from licence and distributor agreement with Thermo Scientific. [SP=3.62 Cap=11m]
◄Angle (AGL)► FY trading: "market conditions has slowed down ANGLE's commercial acceleration post FDA clearance". Rev £1m, op loss c.£22m, in line excluding closure costs for Canada. Several new orders confirmed in the first week of Jan. [SP=47.5 Cap=124m]. I hold.
◄Live Company (LVCG)► guides FY22 loss. BRICKLIVE rev flat YOY despite the reduction in tours. BRICKLIVE will look at new markets in the Middle East, not currently covered with existing partners. Plans to offer 3 K-POP events in major European cities. [SP=3.11 Cap=8m]
◄Seeing Machines (SEE)► integration of SEEs'in-cabin monitoring system technology with the OMNIVISION (a leading global developer of semiconductor solutions) OAX4600 system-on-chip platform. "We are very confident that this will give our customers a highly optimized silicon platform that can target the driver as well as the wider interior sensing market." [SP=6.66 Cap=274m]
◄Checkit (CKT)► wins 3 contracts worth 1m over 3 yrs. Also renewed contract worth c.£2.1m over 4 yrs. [SP=22 Cap=24m]
◄REACT (REAT)► wins 2 yr contract to perform deep cleaning, window and façade cleaning across c.350 mainland UK locations. Worth £0.8m in FY-Sep. [SP=1.03 Cap=11m]
◄Galliford Try (GFRD)► wins £95m contract to deliver a new prison facility, [SP=164.5 Cap=179m]. I hold.
Well Mr Contrarian, what is it that makes perhaps die-hards like you and me hold Angle (LON:AGL) do you think?
I started off because a close relation had breast cancer and I believed the company had an important and unique part to play in reducing unnecessary biopsies, helping target specific programmers. Research results form a very wide range of institutes in Europe and USA especially in breast cancer - the main target for FDA approval - and also small cell lung cancer and prostate cancer were very promising. The US market awaited, apparently eagerly, on both clinical and economic grounds..
No doubt the FDA process was delayed by Covid and that may have turned out to be critical? Anyway FDA approval was finally achieved after an extremely demanding programme and the world, seemed to be the oyster for Angle (LON:AGL) after all. However, perhaps by wanting to be very independent and have too many strings to its bow have proved to create more problems than they have been worth. I always believed that FSA approval should have been followed very quickly by a listing in the US on one of the alternative markets because the US markets have always valued this type of company so much more highly and the US was always the No 1 market on economic gerunds too - but it didn't happen, and the opportunity, if it did exist, was lost.
Neither clinical nor big pharma have come up with the goods when apparently after FDA approval they were beating at the company's door. Today's market response to more jam tomorrow has been particularly painful.
Is the company saleable, and what other organization would be able to do a better job than the current management and advisors on further, more rapid monetisation?
Angle (LON:AGL)
Well that’s a great start to my year.
I don’t disagree with Paul’s summary or ridavies’s comments. My initial reaction FWIW was:
We know the technology works. Plugging Parsortix into other existing offerings for downstream analysis may get the system into the field much quicker but at a significant dilution to the potential revenue stream. It also highlights that other companies and technologies are not standing still.
No doubt market (and general world) conditions have played a part but many of the potential collaborators have huge amounts of cash available. Does look like the ‘rapid expansion’ will be delayed until 2024 – when existing cash runs out – or a takeover happens (with help from the new NED).
The two labs providing Pharma Services may provide the income stream to keep the company going but I get the impression that full CLIA accreditation is a tad further away than anticipated.
Seems like a takeover is the most likely option.
Heiq (LON:HEIQ) - CEO spends £84k buying 300k shares at 28p
Takes his total to 14.2m shares, 10.1% of the company.
Might shore up confidence in some investors, after yesterday's bad profit warning?
I thought that originally - then realised that if by "spending" £84k he lifts the price by 1p (or reduces the decline by 1p) then he is up £54k on his total portfolio. If it improves the price by 2p, that £84k "makes" almost £200k "profit"!
So it is "nice" to think he thinks it isn't going much further down but it isn't really confidence building enough for me. Now if he showed real confidence in the brand, product, sales pipeline and mopped up al the sell off shares yesterday - that would be a "nothing to worry about here" statement!
Hi wolfspirit,
Yes, I take your point, well made.
I normally like Director buys of c.£100k+, but as you point out, if this is a small buy relative to a Director's existing holding/wealth (as this one is), then it probably signifies little.
Also this type of purchase could be seen as a way for Directors to get institutions & other shareholders off their backs by saying, look we're confident and we've demonstrated this by making a material purchase in the market. So it could just be for show.
Regards, Paul.
Maybe the broker even lent him the cash against his existing position and it all cost him next to nothing.
I'm at a loss to understand why buying anything using borrowed money cost somebody next to nothing!
For what it is worth, I liked the prospects for the Heiq (LON:HEIQ) business when it came to market, but thought it was overpriced - as I seem to remember you did. Now at about a quarter of the market cap it looks a bit more interesting. Profits were volatile before they came to market, so there could be recovery prospects. Still, I agree with you that this purchase is too small to mean much, and the directors have not impressed by bringing the company to market at the peak of their trading cycle. I don't hold.
I had high hopes for this company as they produce antiviral clothing (contains silver thread).
Greggs (LON:GRG) has a store in Tesco (LON:TSCO) Burseldon now might be the start of a join venture to use supermarket space up old food counters etc.
I see on the local news Greggs (LON:GRG) are applying for permission for a drive through centre. They seem to be quite keen on expanding into new areas.