Small Cap Value Report (Tue 1 Feb 2022) - ODX, VLG, REAT, JOUL, TPFG, BAG, W7L

Good morning, Paul & Jack here again, to review today's trading updates & results statements. Plus a couple of stragglers left over from yesterday, which I prepared last night.
If you're a new subscriber to Stockopedia, then firstly welcome! Secondly, could I ask you to read the brief "explanatory notes" below, as this explains a lot of the things that we're asked questions about by newcomers.
Agenda -
Paul's Section:
Omega Diagnostics (LON:ODX) - interesting comments from this company about potential difficulty raising fresh equity. This looks likely to become an issue for other companies which need to raise money, so beware.
Venture Life (LON:VLG) - what drove yesterday's 35% share price recovery, and was it justified? The short answer, is no! Its trading update looked superficially very good, but was actually only in line with lowered expectations, and growth seems to have come from an acquisition.
React (LON:REAT) - a small cleaning company. Results for FY 12/2021 were out yesterday, and don't show anything interesting. Looks over-priced to me, and not a convincing story. Hyped up during the pandemic.
Joules (LON:JOUL) (JOUL) (I hold) - oh dear, it's another profit warning. Current trading revenues look OK to me, but the company says it's trading below expectations, and supply chain/logistics problems seem to be continuing to play havoc. No great surprise, as the share price has been relentlessly falling, and we've all seen the poor customer reviews online. Broker forecast for FY 5/2022 is halved, so no doubt the market looks set to punish JOUL shares further. However, outlook comments do suggest the worst might now be over. So I remain bullish on the long-term outlook, and we shouldn't be far away from a turn in sentiment, as people begin to look beyond short-term supply chain issues.
Warpaint London (LON:W7L) - a positive trading update for FY 12/2021, ahead of expectations. Although looking at valuation, W7L seems fully priced, with a PER over 20 looking warm, given the recent market valuation reset downwards. I think investors need to rely on further out-performance to justify the current price, let alone see further upside.
More to follow, as we work through today's news.
Jack's section:
Property Franchise (LON:TPFG) - I hold - profit expected to be ahead of expectations. Business has been helped over lockdowns by government initiatives such as the Stamp Duty holiday, but the group’s pipeline remains strong going forward. Post-Hunters acquisition, there’s an attractive mix of stable lettings revenue and sales revenue. Further acquisitions are being considered, and Ewemove is also building momentum. Valuation remains modest given the mix of quality and growth, in my view.
A G Barr (LON:BAG) - another modest upgrade to profits. It’s a family owned business with a long history, the Irn-Bru brand, and good profitability metrics, so there’s a lot to like. Meaningful growth has been hard to come by over the past decade though, and I think signs of this are needed in order to take the share price significantly higher in the long term.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Omega Diagnostics (LON:ODX)
Not a share (or sector) that we follow here, but there was an interesting announcement yesterday, which could have wider read-across.
Speculation regarding a potential fundraise
Omega (AIM: ODX), the specialist medical diagnostics company focused on industry-leading Global Health (CD4 and COVID-19) and Health and Nutrition products , notes the recent online speculation and confirms that it is in discussions with certain investors and shareholders regarding a potential equity fundraising.
This highlights the absurdity of the UK system, where shares remain trading, whilst behind closed doors companies are secretly trying to raise funds. It’s totally wrong, and of course this price-sensitive information often leaks out, because so many people know about it - creating a false market in the shares.
I believe shares should be suspended immediately when a company begins a fundraising. We need a new, high speed system brought in, with low fees, via an online auction, to do fundraisings fast - offered first to existing shareholders, then anything left over going to other investors. The only reason this hasn’t been implemented, is because vested interests (the army of overpaid advisers) make so much money from the current system, at our (investors) expense. If we remain saddled with an outdated system, London looks set for a downward trajectory.
Discount - ODX flags that it might have to raise money at a discount. This is a warning to all of us, I think we’re now in an environment where companies that need fresh equity could struggle to raise it. So checking balance sheets, and making sure companies we invest in don’t need to raise fresh equity, looks a sensible approach right now.
I doubt we’ll see many IPOs from now on, either. Good thing too, as most of the ones over the last couple of years have been opportunistic & over-priced. As one broker memorably told me a while ago, "Why on earth would you want to list on the stock market, if you own a decent private company?!". That's worth bearing in mind when looking at new floats - what is the reason they're listing? Often, it's so founder/major shareholders can cash out at a high price. The only recent float I like, is Facilities By Adf (LON:ADF) (I hold) which looks sensibly priced, and raised new money mainly for expansion.
Although it doesn’t sound as if ODX is desperate for cash -
Market conditions remain challenging and accordingly any issue of equity would be at a discount to the current share price. Any fundraise would include an open offer to accommodate retail investors.
As per the announcement of 19 January, the Company has significant cash resources . Accordingly, there is no immediate need to raise additional capital and the Company may choose not to proceed with a fundraising until such time as conditions are more favourable..
They wouldn't be trying to raise money, if they didn't need it, would they? So that's less than 100% convincing!
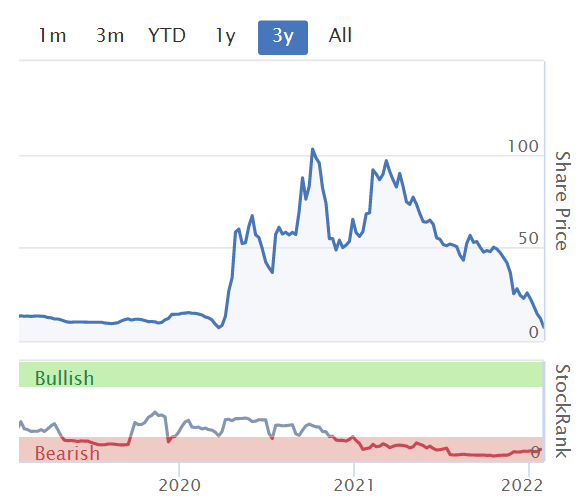
The chart for ODX is remarkable - a major multi-bagger from when covid started, which has since managed to come all the way back down again. It's a similar story with so many other covid bandwagon stocks.
.
Venture Life (LON:VLG)
50.5p (up 35% yesterday) - mkt cap £64m
Full year trading & commercial update
Venture Life (AIM: VLG), a leader in developing, manufacturing and commercialising products for the self-care market, is pleased to provide the following trading and commercial update for the year ended 31 December 2021 ("FY21").
To refresh my memory, I’m reading Jack’s notes from VLG’s profit warning here on 1 Dec 2021.
The headlines in today’s update from VLG read very well, but remember that it made a large acquisition of BBI Healthcare last year, for £36.0m, more than half the current market cap. So of course the numbers are improving in H2, due to this acquisition being newly added to the group numbers. Maybe some punters are reading the big growth numbers reported today, and wrongly assuming they’re organic growth?
Revenue of £32.6m for FY 12/2021 is only £0.6m above Cenkos forecast.
Adj EBITDA we’re told today is in line with market expectations, which Cenkos reckons is £6.25m, which reduces considerably to £1.6m statutory PBT - but some of the amortisation charge (for acquisitions) can legitimately be reversed out of that. The broker figures are a bit confusing, so I’m not entirely sure which profit figure to lock onto.
There are a lot of adjustments, and £1.0m in exceptionals in the forecasts. I’ll need to check the published numbers when they come out to be sure, but it looks as if the adj EPS figures from Cenkos of 2.63p for FY 12/2021, and 4.32p for FY 12/2022 are possibly the most appropriate figures for valuation purposes.
At 50.5p share price, that gives us a current 2021 PER of 19.2, falling to 11.7 times, if 2022 earnings rise strongly and hit target. That might be possible, since 2022 will include a full year of the large acquisition.
Net debt of £3.2m doesn’t sound a problem.
Order book significantly ahead, but no figures provided, and no indication of what organic growth is like.
Details are provided of new product launches.
Diary date - “The Company expects to publish its results for FY21 on 24 March 2022.”
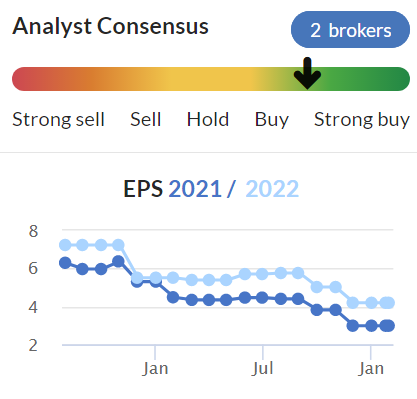
My opinion - this update is a good example of PR - dressing up an in line update to sound more positive than it actually is! It’s strange to see a 35% share price rise triggered by an update that is only in line with (lowered) expectations.
I think this company has a lot to prove, before it would interest me.
Also, don’t forget the Directors dumped a lot of their shares at a much higher price.
It's easy to hit targets, when they've been lowered so much beforehand:
.
React (LON:REAT)
I’ve had a quick look at results for FY 12/2021, but there’s nothing much of interest here. It’s a small contract cleaning company, with the shares getting hyped up during the pandemic. It only made £277k adj PBT in FY 12/2021 (up 46%).
Outlook comments mention new contract wins.
There’s nothing much on the balance sheet (note the cash is offset by deferred consideration creditor). So it would need to raise fresh equity to do any more acquisitions.
My opinion - too small to be listed, and not a very convincing story. £10m market cap looks too high.
Joules (LON:JOUL) (I hold)
118p - mkt cap £132m
I’ve been expecting another profit warning here, because it’s obvious that the company has been suffering from supply chain issues. We can all see this from overwhelmingly negative reviews on review sites. Although the quantity of negative reviews is tiny compared with the number of customer shipments there would have been over the last few months, so should always be treated with caution.
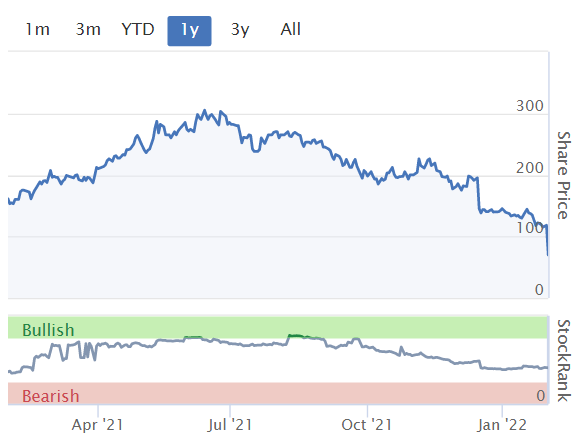
My view is that, with the share price down almost two thirds from the peak in mid-2021, the market is being very short-termist, and has already over-reacted to temporary, fixable supply chain problems. Hence I’m ignoring the share price, taking a long-term view of what seems to me an excellent, and differentiated brand, that has been successfully selling at least half online since before the pandemic. It also has a growing marketplace of third party brands, called Friends of Joules, which is growing strongly.
Hence this share is very much for people who understand the long-term attractions, and can cope with short-term bumpiness.
Today’s update shows there are still problems - it's served up another profit warning, coming hot on the heels of a previous warning in Dec 2021. So things are not good right now. However, JOUL is still profitable, and today's disappointments set up the soft comparatives for next year's recovery, assuming it gets on top of supply chain delays & excess costs.
Joules, the premium British lifestyle group, provides a trading update for the second half of the financial year to date as well as an update on the timing of its FY 2022 Interim Results.
The current financial year ends May 2022.
H1 results -
Further to the Group's Trading Update on 14 December 2021, the Group confirms that its financial results for the six months ended 28th November 2021 were in line with previous guidance, with revenues of £127.9m (H1 FY2021: £95.4m) and PBT pre-adjusting items of £2.6m (FY 2021: £3.7m).
No change to interim figures (to 11/2022), which should be released shortly. Why on earth do they mention completion of the going concern notes (below)? That could spook some investors. It’s seems almost as if this update today has been designed to drive the share price lower (which does make me wonder if they want to take it private?) -
The Group is in the process of finalising its Interim Results, including completing its going concern analysis, reflecting the impact of trading performance up to the end of January. The Group intends to release its Interim Results as soon as this is concluded.
Current trading - I find this confusing. At the start, it says H2 revenue to date (9 weeks to 30 Jan 2022) was up 31% against last year - unsurprising considering the shops would have been shut in Jan 2021 due to the lockdown.
However, it says sales this year are also up 19% against the 2-year, pre-covid comparative, which seems good to me.
… however, this performance, along with the Group's PBT performance over the same period, is behind the Board's expectations.
These following factors are mentioned, and it’s clear that the problems are supply chain related, causing delays & extra costs. That’s to be expected to some extent, and fits in the category of fixable problems, so I’m not particularly worried by any of this -
· Weaker than expected revenue in January, in part as a result of the negative impact of the Omicron variant on retail footfall (down 36% vs. the comparable period two years ago);
· Delays to new stock arrivals as a result of global supply chain challenges, resulting in a lower full price sales mix, in turn impacting revenue and gross margin;
· Lower than expected wholesale revenue due to delayed stock and customer cancellations;
· The continued impact on gross margin of increases in freight, duties and distribution costs; and
· Continued operational disruption, lower productivity, and higher than expected costs within the third-party operated Distribution Centre (DC). DC costs for December and January were c.£1.2m above expectations, which is more than double compared to the prior year. In the second half of FY22 so far and post peak trading, wage rates have reduced but are still higher than seen in the comparable prior year period.
Action taken looks sensible, and remember Joules has an exceptionally high marketing spend, so it has a lot of cost flexibility. Also Joules is a brand, not just a retailer, which I think gives it a lot more pricing power - because customers don’t buy Joules product on price. It’s bought primarily on quality & brand image, which should allow it to pass on cost increases better than the competitive price-led end of the fashion market.
· Cost restraint in marketing, head office and capex;
· Liquidation of aged and slow-moving stock via outlets and third parties;
· Simplifying wholesale operations including exiting selected UK and EU agent and third-party stockist arrangements, introducing minimum order value requirements in the US, and the cancellation of unprofitable orders; and
· Selected appropriate price increases for SS22 reflecting the higher cost environment.
Outlook - the good news is that the company remains profitable, despite all these issues.
Also, it sounds as if the supply chain & logistics issues are now improving.
The Board's base case expectation is for trading for the balance of the year to recover in line with its previously stated expectations, supported by recovering footfall and an improved level of newness in the stock position. The wholesale orderbook for Spring / Summer 22 remains strong and the DC operation is normalising with delivery times back to standard service levels and productivity improved.
Assuming the Board's base case is met, adjusted PBT for the full year is not expected to be less than £5.0m (FY 2021: £6.1m).
That’s quite a significant drop from the last guidance, which was £9-12m profit. JOUL is now saying at least £5m adj PBT, so basically a halving of profit guidance this year - ouch.
Liquidity - I’d like to see this net debt figure come down, but there doesn’t seem to be any particular worry here -
As at 31 January 2022, the Group had net debt of £21.5m, with £11.5m of total liquidity headroom.
Based on the expectation set out above, the Group has sufficient liquidity headroom for the foreseeable future.
My opinion - disappointing, but I was expecting more bad news, and so was the market - because the share price has been relentlessly falling.
Obviously this is going to hit the price today, although I think the problems impacting this sector are so widely known now, and possibly have peaked (supply chain issues), that the market really should be starting to look beyond short term problems, and see the bigger picture longer term. As soon as sentiment does go that way, we should see good recoveries in bombed out share prices from companies that have suffered the most from supply chain issues.
When that happens though, I have no idea. In the meantime, JOUL shareholders are likely to take a bath today.
Many thanks to Wayne Brown at Liberum for an update note this morning, available on Research Tree. He’s obviously lowering forecasts, to only 3.6p for FY 5/2022, recovering somewhat to 7.4p, and 11.4p in the following years.
I reckon we could see sub-100p today, as weak holders move on, but I remain very happy with the long-term potential of this company. Once its supply chain & logistics problems are sorted out, then the profit recovery could be much better than forecast. And despite all the problems, it remains profitable, and doesn’t have an overhang of problem stores.
Holders will just have to continue to be patient, and brace for a bad day today, as inevitably the price is likely to take another leg down.
It’s a very good recovery situation though, in my view, once supply chains normalise. The brand, and high margins, remain valuable, and profits/growth are likely to return, once conditions normalise.
I have to say, this is not the first time JOUL has suffered logistics & supply problems, which does lead me to believe its management seem weak on management of supply.
Poor current performance looks excessively priced-in now. Remember we're not buying only this year's earnings. We're buying all future earnings, which should improve once supply chains normalise.
.
Warpaint London (LON:W7L)
165p (up 7%, at 09:45) - mkt cap £127m
Full Year Trading Update
Warpaint London plc (AIM: W7L), the specialist supplier of colour cosmetics and owner of the W7 and Technic brands is pleased to announce an update on trading for the year ended 31 December 2021.
Company’s headline -
Strong 2021 trading and results expected to be ahead of market expectations
Just as a general aside, we do have to be careful with this latest fashion of companies putting a headline at the top of trading updates. They’re PR, and should be seen as such - i.e. stressing the positives only!
Usually, headlines are sensible, but I have seen a few that are misleading - e.g. CARD recently gave an upbeat headline, but then put a bombshell profit warning right at the end of the announcement due to big cost increases in the pipeline. That was the key point of the update, but wasn’t mentioned in the headline.
If however, in this case with W7L, the result is ahead of market expectations, then flagging that in the headline is a good thing, and saves investors time, by quickly spotting the positive updates, when we have loads of company updates to look at from 7-8am.
Revenues - FY 12/2021 is now a slight beat against previous guidance, with £50.0m actual, being £0.7m ahead of previous guidance. This is back to (slightly) above pre-pandemic revenues, and 24% ahead of FY 12/2020 revenues - good stuff.
Gross margins at 33.8% also slightly ahead of pre-pandemic levels (despite increased freight costs), and usefully up on 31.1% achieved in 2020. Even so, this gross margin seems low to me, in a sector that is known for high margins.
Profit guidance - almost top marks here, for giving precise figures, and we’re provided with both EBITDA, and real profits, Profit Before Tax (PBT). Excellent, but the only thing missing is EPS, which is my preferred profit measure, as I can quickly work out valuation from EPS.
For the year ended 31 December 2021, subject to audit, the Group's Adjusted EBITDA*is expected to be approximately £7.7 million (2020: £4.2 million, 2019: £7.0 million) and Adjusted Profit Before Tax** (2020: £2.3 million, 2019: £5.2 million) is expected to be approximately £6.6 million, both of which are ahead of market expectations.
As you can see, PBT is now £6.6m, well ahead of pre-pandemic £5.2m in 2019.
A lot of businesses restructured, and became better businesses under the pressure of the pandemic, maybe this is one of them?
Cash looks fine -
The Company's cash balances as at 31 December 2021 totalled £4.1 million (31 December 2020: £4.9 million) and the Company had no debt, after significant stock purchases to satisfy anticipated Q1 2022 demand.
Diary date - imprecise, but we’re told FY 12/2021 results will be out in April 2022. That seems a rather slow reporting schedule, but I note from pre-pandemic results that the 10 April 2019 results for 2018 were audited results, not just preliminary results.
Outlook comments sound upbeat, with some good growth initiatives in the pipeline by the sounds of it -
Commenting, Sam Bazini Chief Executive, said: "I am pleased to report that we ended 2021 ahead of current market expectations. In 2021 we enjoyed particularly strong sales growth in the UK, significant growth internationally and further increases in online sales. It was pleasing that we were able to maintain our margins at pre-pandemic levels, despite some inflationary headwinds, particularly with freight costs.
"We expect to see a continuing improvement in performance in 2022 and have started the year strongly. In line with our stated strategy we have significant opportunities for further growth, both with our existing retailers, and those such as Boots where we are expecting to launch very shortly, together with others that we are in discussions with. I look forward to providing further updates at the time of the release of the Group's results in April."
Broker updates - many thanks to both Singers, and Shore Capital, for releasing update notes today via Research Tree. This is tremendously helpful, and the more information private investors have, the more likely we are to buy the shares.
Singers has 6.3p ADJ EPS (FD) for FY 12/2021, going to 7.2p and 7.9p in 2022 & 2023, which don’t seem aggressive forecasts, so hopefully there might be scope for upgrades, rather than profit warnings.
At 165p per share, we have PERs of 26.2, 22.9, and 20.9 times - for 2021, 2022, and 2023.
My opinion - it’s good to see W7L trading well, and having an upbeat outlook.
However, given the big downward valuation reset which has happened in the market over the last 6 months, I see the valuation of W7L shares as currently looking unappealing.
It looks fully priced, and investors here will need to bank on earnings beats. Which may or may not happen. So nice company, trading well, but fully priced for now. Although looking at the outlook, and the investment in stock to meet demand in Q1, it does sound as if the newsflow in 2022 is lined up to be positive, from W7L.
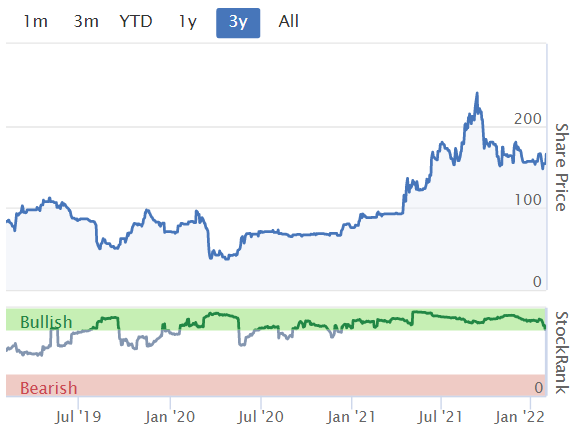
Stockopedia likes it, see the high StockRank in the lower part of the chart below. For anyone new to Stockopedia, the charts I copy into these reports show the share price in the top part, and the Stockopedia StockRank in the lower part.
Like so many companies, the share price got ahead of events last year -
.
Jack’s section
Property Franchise (LON:TPFG)
Share price: 327.2p (+2.89%)
Shares in issue: 32,041,966
Market cap: £104.8m
(I hold)
TPFG is the largest property franchisor in the UK and manages the second largest estate agency network and portfolio of lettings properties in the UK. It’s similar to Belvoir, which reported yesterday, although its finance arm is probably a bit behind, and TPFG has a hybrid estate agency called Ewemove.
The company was founded in 1986 and has since grown to nine brands operating throughout the UK. These are Martin & Co, EweMove, Hunters, CJ Hole, Ellis & Co, Parkers, Whitegates, Mullucks & Country Properties.
Trading update for the year to 31 December 2021
Profit anticipated to be ahead of market expectations
It’s been a strong 2021, with a very active residential housing market and the fortunately timed Hunters acquisition, which bolsters the group’s sales revenue. That market has been helped by government initiatives over lockdowns, as well as the growth in remote working.
Like-for-like (LfL) revenue and management service fees (MSF) were ‘significantly’ up on 2020 and 2019.
- Group revenue +119% to £24.1m (+26% LfL on 2020 and +23% LfL on 2019),
- MSF +57% to £14.7m (+19% LfL on 2020, +16% LfL on 2019),
- Network income +67% to £157m (+17% LfL on 2020 and +18% LfL on 2019),
- Ewemove sold 58 territories, up from 11 and taking the total so far to 167,
- The number of offices has grown by 72% to 591, including 209 Hunters offices,
- Sales agreed pipeline of £26.5m, up from £15.3m,
- Rental properties managed up from 58,000 to 72,000,
- Net debt down from £8.8m to £2.7m.
It is encouraging to see the strong sales agreed pipeline, as initiatives such as the Stamp Duty holiday ended in September and there has been a question mark over how sustainable the current property market conditions are.
Ewemove’s good progress is similarly encouraging, as the deal initially raised some eyebrows. TPFG says it is on track to double sales here to 230 by the end of 2022.
Post-period end we launched a new hybrid franchise model, 'Hunters Personal Agent'. This model follows our established, successful hybrid model and complements the Hunters brand. Hunters Personal Agent is designed to provide agents with greater flexibility in running their business from a low-cost base and the initial response to its launch has been encouraging.
Diary date - preliminary results for the year ended 31 December 2021 on Tuesday 5 April 2022.
Conclusion
TPFG has great profitability and financial health metrics over time. It has also demonstrated an ability to grow year-on-year. It’s in a big market and is investing for expansion. Meanwhile, its business model is shored up by a good proportion of lettings revenue, which is relatively secure. That stable cash generation comes through in the group’s steady net debt reduction throughout the year.
So I think when you take all that together it probably warrants a higher valuation.

The Hunters acquisition was significant, and there has been an increase in share price on the back of that, but the valuation of the enlarged enterprise still remains fairly modest in my view. There’s likely plenty of scope for additional acquisitions as well, plus organic growth in line or slightly ahead of the market.

There is the health of the wider property market to consider. Sales prices are at historically high multiples of earnings thanks to decades of low interest rates and other monetary policies inflating asset prices. Rents too have become a larger part of people’s spending. So there’s clearly a limit to how far that can run.
We are encountering a wave of wage inflation though, so perhaps that can provide a slightly sounder footing for price growth. If you take the longer term view and expect to hold through multiple cycles, then this franchise network model is probably more robust than most. I expect TPFG, Belvoir and the like to be able to weather downturns or quieter markets as and when they arise, and use them as opportunities to emerge, ultimately, with stronger market positions.
A G Barr (LON:BAG)
Share price: 496.28p (+0.26%)
Shares in issue: 112,028,871
Market cap: £556m
AG Barr produces and markets drinks brands, including IRN-BRU, Rubicon and Funkin. It’s got an exceptional Quality Rank of 98, with a strong track record of profitability.
And yet it has been a poor investment over a five-year period. This is because the company has struggled for growth, grappling with sugar taxes, price cuts, and subsequent price increases.


However, shares in issue have reduced slightly, while the group has continued to be profitable throughout the period. And Irn-Bru is obviously a brand of no little value. So there are points of interest here, but the lack of growth and poor share price returns makes me more cautious.
Trading update for the year to 30 January 2022
Revenue for the year is expected to be c.£267m, a 17.5% increase compared to the prior year (2020/21: £227.0m) and marginally ahead of the revised guidance issued in November 2021. This means AG Barr is now ahead of the pre-pandemic revenue of 2019/20 (£255.7m), despite disruption from Omicron-related restrictions.
Both the Barr Soft Drinks and Funkin business units have traded well, particularly during the periods when restrictions were eased.
Cost pressures:
The inflationary pressures highlighted in our November 2021 update have materialised as expected, particularly across packaging and energy linked commodities. We have initiated several cost control actions to reduce the impact of these rising costs and have adjusted our pricing with customers where appropriate. With the published rate of inflation in the UK now above 5%, the highest level for 20 years, we will continue to seek opportunities across the coming year to offset the impact on our business.
AG Barr strikes me as the kind of company that should be better equipped than most to handle reasonable levels of inflation.
Operating margin before exceptional items for the financial year is expected to be around 15.6% (2020/21: 14.8%), delivering profit before tax and exceptional items marginally ahead of our November 2021 guidance.
The group expects to end the financial year with c.£66m of net cash following the completion of the previously announced equity investment in MOMA Foods Limited.
Conclusion
This strong trading performance was achieved despite the increased UK Government restrictions related to the Omicron Covid variant. I think it goes some way to validating the quality and resilience of the company.
For me, the key here is for the group to prove it can grow over the medium term. AG Barr is trading well right now but results are still affected by the nuances of lockdowns and Covid comparators.
While marginally ahead of expectations, diluted normalised EPS is still forecast to be below FY19 levels.

That said, if it can grow revenues, then AG is likely a promising long term hold candidate. It’s been in business for a long time, retains a degree of family ownership, and has some valuable brands that allow it to generate decent double-digit operating margins.
The group comments:
We plan to further invest in our business in 2022/23 and remain confident in our ability to deliver continued growth in both revenue and profit in the coming year.
Quality companies can struggle to grow though. When that happens, there is the risk of a further derating. It’s entirely possible to realise a sub-market performance with quality stocks. I can’t say I’m overly familiar with AG’s brands beyond Irn Bru, so I wonder what their potential might be?
Based on what I know, the share price looks about right for a profitable, long-standing company that has struggled for growth in recent times.

Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

101 comments
Could some more familiar with £joul help me with how they went from £4m net cash at FY2021 to £21m net debt at HY22 (announced today), despite £2.7m pbt.
It doesn’t look like they’ve had such big seasonal cash swings in the past and can’t find anything about additional capex. There was an acquisition of Garden business and freehold but that appears to be in previous period.
Only thing I can think of is a lot more cash tied up in inventory that has been paid for but not yet delivered?
Thanks
Just my two-cents worth, two points really.
Firstly, where is the bulk of the inventory being sourced in Asia? If they are mostly sourcing from the newer producers like Bangladesh and Vietnam, they are probably in a better position going forward. However, Chinese logistic problems are far from over. Covid restrictions are only going to cause more problems there.
https://www.ft.com/content/0e6...
Secondly, following on from hjg123, in the worse case would some inventory need to be partly written off if it cannot make it to the stores in time for the coming summer season and if so is the balance sheet strong enough?
£Joul Good point. According to their website, Joules uses around 150 suppliers, the vast majority being in Asia. 80 are based in China.
I just mentioned the profit warning from Joules (LON:JOUL) (I hold) to Mum, and after explaining what it meant (that I've just lost £50k basically!) she said that she'll go on their website and buy a couple of cardigans in the sale, if that helps! :-)
That triggered me having a look also, to see if there's any nice stuff in the menswear sale (previous purchases have been excellent - the product is very nice, well made, with good fabrics), and noticed that these underpants are now branded as "Crown Joules" - "KEEP YOUR CROWN JOULES SAFE" - rather fun, I thought! Could this be their FCUK moment, I wonder?
Actually, they're only £14.95, so I'll order some now, and will be able to show everyone my purchase at the next investor show LOL!
I got some for Christmas. Decent quality and comfy.
No position in Joules!
My better half has just bought one of those 'duvet coats' (long, padded, very warm etc) from Joules - the quality and attention to detail is excellent as far as I can tell.....and more importantly of course, it looks nice so she's very pleased! No issues re delivery/sizing/availability etc...They've just won themselves two new customers. Onwards and upwards from here hopefully.
Just had a look Paul. At Joules (LON:JOUL) website and Noticed the pants were not in the clothing section but instead appear in accessories. Who classes mens underpants an accessory,short of a kilt wearing highlander?!
I might get some myself now… you’ve stated something :)
Here's today's agenda. As usual, we've focused on the main above/below expectations updates, which tend to be the most price sensitive. We can't cover everything, but to please feel free to post your own comments on anything we haven't managed to fit in.
Another cracking effort today team. I don't know how you find the energy :)
JOUL
Not sure what to make of the Directors buying at 222 in September. That included the founder, Tom Joules £107,000 and another person, £34,000.
Joules (LON:JOUL)
The other person was the CEO and his was made in November. Although the amount involved is not particularly significant, the fact that he made a purchase and within two months or so had made two awful profit warnings suggest that this is not a business in control.
Same could be said for the purchase by TJ. Of more interest I think, in hindsight, is the sale by TJ of £12m of shares in April 2021 at £2.32. Really wished I had taken much more notice of this !
Anyone have thoughts on Robert Walters (LON:RWA) ? Not a sector I know much about.
Fundamentals look good. Long uptrend on the chart has been broken but a nice trading update 'comfortably ahead' and outlook statement seemed very bullish to me-
"The fourth quarter was another very strong period for the Group with net fee income increasing by 39%* year-on-year. We are seeing candidate shortages across all locations and disciplines, a fierce competition for talent and wage inflation kicking in which together create huge opportunities across the recruitment market.
"Group net fee income for the full year was up 21%*. Following a strong quarter including a record December, trading is now comfortably ahead of current profit expectations."
2022 forecast of 53p EPS so on a PER of 13.2
Has had a string of ahead updates since the start of 2021. Looks like theres a seller working away in the background so may offer a nice entry?
.
.
There seems to be quite a few recent trading 'ahead' or at least strongly 'in line'. I dont see the point in looking to buy anything which hasnt reported yet
Sanderson Design (LON:SDG) 'profitability to be significantly ahead'. Net Cash. Fwd PER 11.9
Sureserve (LON:SUR) 'In Line' 73% of FY22 revenue booked already. Net Cash. Fwd PER 11
Somero Enterprises Inc (LON:SOM) In line. Net Cash. Fwd PER 11.4
Alliance Pharma (LON:APH) 'comfortably ahead'. Fwd PER 16.5
Im sure theres lots of others but it does take some of the risk of a profits warning out of the equation.
Hi gringo,
Yes, we like Robert Walters (LON:RWA) here at the SCVR, Jack has covered it many times, with positive updates. Also Sthree (LON:STEM) looks similar - performing well, and reasonably priced, which we looked at yesterday.
I also only usually make new purchases after a positive trading update, it's a very good strategy, as you say, reducing the risk of a profit warning. It's my long-term holds which are currently getting clobbered with profit warnings, well a couple of them anyway.
I agree with you that Sanderson Design (LON:SDG) and Somero Enterprises Inc (LON:SOM) (I hold both) plus Sureserve (LON:SUR) (I don't hold yet, but want to buy some at some stage) all look decent companies, trading well, good recent updates, and still attractively priced.
I haven't looked at Alliance Pharma (LON:APH) so will take your word for it!
Regards, Paul.
Interesting article from Roland Head on £RWA on the home page
I was just looking at the CEO sales myself. The 3 largest were October 12th 2017 - £5.7m. The share price rose for another 10 months or so before the top was reached.
Next was £1.3m June 15 2018 (along with 2 other directors). This was sold with only 2 months left of the rally so very well timed.
Last was Aug 2021. £2.8m
Judging past record the cyclical top will probably be in this year.
FY Results are on 8th March so may be a good price for a trade into the results. Im not sure Id be holding long term tho, especially now the uptrend on the chart has been broken.
I'm not sure I'd be holding long term tho, especially now the uptrend on the chart has been broken.
Isn't that true of every stock on the market? The whole world is down at least 10% - 20%, many much more. If that's your logic, shouldn't we sell everything?
Consider this: the inflation that everyone is frightened of isn't of the supply chain disruption type - it's from potentially spiralling wage demands with accompanying labour shortages. In that situation, Robert Walters (LON:RWA) is a perfect hedge.
My thoughts on Roland's article are that he's allowing himself to be bounced out of a quality stock because his strict rules don't accommodate a macro-driven stock-agnostic correction.
Isn't that true of every stock on the market? The whole world is down at least 10% - 20%, many much more. If that's your logic, shouldn't we sell everything?
There are many shares that are still in an uptrend even after losing 10-20%. RWA has lost the 200dMA but is still in its uptrend (just).
Paul/ Jack,
First, let me start by thanking you for the high quality of the reports through January - you have covered so much and in quite some detail. This is such a high quality resource for subscribers. Then, on top of this, you have added a weekly audio (breaking into video?) update which I find that even after reading the reports through the week, a really useful re-cap after some of the dust has settled. Thank you both so much for this work and this latest innovation.
Onto one stock comment and related to Joules (LON:JOUL) , I was perplexed by the Interim Results comment:
"The Group is in the process of finalising its Interim Results, including completing its going concern analysis, reflecting the impact of trading performance up to the end of January."
Why specifically mention you are reviewing the going concern aspect of the company unless you were uncertain this was assured, or you were perhaps warming up the market to a potential capital raise? If all is ok, why mention this one item? I did not see this covered by Paul in the above commentary and I wonder if you would like to address it please?
Hi - Paul does mention this point, in the H1 results section -
Why on earth do they mention completion of the going concern notes (below)? That could spook some investors. It’s seems almost as if this update today has been designed to drive the share price lower (which does make me wonder if they want to take it private?
Hi 1james1n1,
As Davnocas mentions in his reply, I did actually flag up the going concern point in my section on Joules (LON:JOUL) (I hold)
Another reader points out that JOUL had originally said it was going to publish interim (to 30 Nov 2021) results today - I've just confirmed that from the trading update of 14 Dec 2021, which said -
The Group anticipates providing its Interim Results on Tuesday 1st February 2022.
Therefore, it makes sense that a short delay in publishing interim results would need an explanation today.
Today it says -
The Group is in the process of finalising its Interim Results, including completing its going concern analysis, reflecting the impact of trading performance up to the end of January. The Group intends to release its Interim Results as soon as this is concluded.
As I said in the main report, I'm not surprised that has rattled some investors.
Although it then reassures us by saying this today -
As at 31 January 2022, the Group had net debt of £21.5m, with £11.5m of total liquidity headroom. Based on the expectation set out above, the Group has sufficient liquidity headroom for the foreseeable future.
So it sounds as if the going concern note (which remember is normal, most companies seem to put these out, and they're useful, you only have to worry if it says there's a "material uncertainty" over going concern) is likely to say that on the base case, everything is fine - which is what they tell us above.
However, I suppose it's possible that a downside scenario stress test might require action to be taken to protect liquidity. I think JOUL should be fine, since it has such a large, discretionary, marketing budget. So if trading got unexpectedly tough, it could slash marketing spend, to conserve cash.
[Oh God, just spilt tea on my keyboard, today is going from bad to worse. Luckily this happens frequently, so I buy cheap keybords in bulk, and have a stack of them behind me, in case individual keys start to malfunction]
Just to be on the safe side, I'll re-check JOUL last balance sheet, as at 30 May 2021. It looks OK to me, nothing of concern: NAV £44.2m, less intangible assets of £31.0m = NTAV of £13.2m, which is OK.
Strip out the IFRS 16 lease entries, which are £28.3m RoU asset, and £40.0m lease liabilities, so a deficit on IFRS 16 of £11.7m, add that back to NTAV, and it becomes £24.9m, which is fine.
Also note that fixed assets includes £21.7m in "land & buildings" quite a bit of that (probably most) would be the new head office, which is freehold. Banks like lending against, or having security over, freehold property.
Iv'e also read through the going concern notes in the 2021 Annual Report, which mentions mitigating actions if cash gets tight -
.
I think it's possible that JOUL might need to ask the bank to relax its EBITDA covenant. It said this in the Annual Report (approved on 2 Aug 2021) -
.
Given that forecasts have been reduced a lot recently, that could possibly put pressure on this covenant?
Does that matter though? As you know, I'm the first investor to run for this hills if I sense any solvency questions at any company. However, needing a little relaxation of a banking covenant during a soft patch is not a cause for alarm, especially when the overall level of net debt is fairly modest for the size of business.
JOUL today reports £21.5m of net debt, which is not a concern to me. If it had £50m+ net debt, then I wouldn't be so comfortable.
So are we likely to see an emergency placing, at a deep discount? That seems highly unlikely to me. Note that JOUL has already refinanced early in the pandemic, raising £15(gross) from issuing 18.75m new shares at 80p early on in the pandemic, in April 2020. It then went on to trade OK throughout the pandemic, as it was already big in online sales, and lost store sales shifted online to a considerable extent.
Looking at the heavy loss of £25.3m in FY 5/2020, that was almost all caused by non-cash impairment charges, and the business actually moved into a net cash position at the time.
Overall then, I'm pretty comfortable that everything should be fine long term.
Also to disclose, that I've placed an order with my broker, to increase my JOUL position by over 60% today. Hopefully that's a rational decision, based on the facts, but as always there could be unconscious bias, as we're all human, and human minds work in strange ways!
Regards, Paul.
You are an incredibly brave man Paul. You have lost £50,000 on this share today and are increasing your exposure by 60% ?
Since you wrote that, the shares have fallen by at least another 5%, costing you another five figure sum I'm guessing.
I am pretty new to this game but I'm going to stick my neck out and predict that the fall has some way to go and will take at least two years to recover from.
Management are in panic mode, do not have the skillsets required to address the problems that they themselves have at least partially caused and are now engaging in questionable behaviour for a listed company in terms of being open with the market.
Strangely enough, I too bought some gear from Joules in the last couple of days. Within ten minutes of my order, I had received three seperate e mails all acknowledging my order. Very strange.
He is a brave man Paul.
He likes his averaging down!!
But because he diversifies his portfolio and runs his winners, I am pretty sure he will always make money.
Paul, many thanks for the very detailed and informative response to my question. Much appreciated.
AG Barr - we live in Cumbria - very top of the Pennines, within the vast tracts of land there that are either owned or controlled by the RSPB - apart from our house and a few dozen others spread around the area. Our Grandchildren live in Fife. We always enjoy going to visit in Scotland. The subtle cultural differences in Scotland are something that I both enjoy and find interesting. For example, small invertebrates commonly known around here as insects or creepy crawlies, up in Fife are know as 'wee beasties'.
Irn Brun - is very much a minority niche product south of the border. North of the border, Irn Bru remains hugely popular, not just as a soft drink, but also as a strong drink mixer, often mixed with whiskey in fact. This is mainsteam, go into a Scottish bar and order, say, Irn Bru and whiskey and that would be a standard request.
The need for AG Barr to generate growth is mentioned. I presume that this is the usual focus on earnings growth. There is a widesapread focus upon earnings growth by UK stock analysts, too much so. As long as earnings are 'apparently' growing, tangible equity can be falling and the directors can be steadily issuing shares, constantly diluting down shareholders and yet everybody seems happy. A business can be consistently eroding shareholder wealth year after year, but so long as 'declared' earnings appear to be growing, all is good!
AG Barr - net tangible equity has grown at an average rate of c2.9% pa realtive to MCap over the past 4 years - not bad considering the challenges that AG Barr has faced over the past couple of years. If the dividend returns to pre-covid levels relatively quickly that is about 3.5%. So the tangible surplus relative to MCap is already up to c6.4% (admittedly I have made sssumptions about the forward dividend) before share issuing or buy backs are considered.
It gets better, AG Barr have bought back shares at an average rate of c1.1% pa over the past 4 years - the share buy backs continued over the past 2 years as well, which is impressive. Put it all together and the forward tangible surplus is over 7% of the current MCap. AG Barr won't break into my relatively concentrated portfolio at this point, but this is not bad you know, not bad at all, there is wealth creating value on offer here.
Robert Walters is often mentioned here and elsewhere, thought that I would take a look.
Net tangible equity growth has been around 2.7% pa relative to the current MCap. Dividend about 2.4%. Small amount of share issuing over the past 4 years, about 0.6% pa. Put it all together and there is a net tangible surplus of aroun d 4.5%.
Seems like a well run business, can't have been easy in recruitment over the past 2 years. Yet the business has strong net cash and that is without any signifcant share issuing over the past 2 years.
Despite the business being strong, the tangible surplus of c4.5% indicates that this is not a good entry point. Yes trading and tangible wealth generation should recover strongly from here, but Robert Walters has that recovery already priced in, the net tangible surplus for Walters would need to grow by c50% from here for the current share price to represent bargain territory.
“Omega Diagnostics (LON:ODX) - interesting comments from this company about potential difficulty raising fresh equity. This looks likely to become an issue for other companies which need to raise money, so beware.”
Raising money to survive, rather than to grow, could, in my view, become a serious problem in the US. According to research from Jefferies, some 31% of companies in the Russell 2000 Index were unprofitable as at the end of 2021. While some 5.7% of companies in the Russell 1000 Index, covering the largest quoted US companies, had no earnings. For sure, most of the huge US tech stocks that drive the major indices are cash-rich but there are large numbers of companies that appear to require access to cheap money simply to operate. With the US stock markets making up over half the world's total stock market capitalisation, it’s probably not something to be ignored.
Incidentally, it would be interesting to know whether there is any research into listed companies that need to raise finance simply to keep the lights on. If we are entering a period of credit tightening, it seems reasonable to presume that many of these businesses will not survive.
Thanks for Property Franchise (LON:TPFG) view Jack. Here's their H1 presentation from September 2021. True to their word, management fulfil their guidance. Looking forward to hearing more with FY results on 5th April.
Here is Sthree (LON:STEM) FY 21 presentation given to analysts, yesterday, by new Interim CEO, Timo Lehne & relatively new CFO, Andrew Beach. Video & podcast. A super set of results from this STEM (Science, Technology, Engineering & Maths) recruitment specialist. With STEM talent highly sought after, and as far as I'm aware, STEM the only recruitment specialist in the sector. They have invested and continue to invest in their platform to provide accelerated margins and are very positive looking forward.
Wynnstay (LON:WYN) announce full year results tomorrow (period ended 31.10.21). Till now they've remained under the radar to some extent. Next Monday 7th February at 12 noon, CEO, Gareth Davies and CFO, Paul Roberts will give a results presentation with Q&A. You can submit questions in advance to Dan.Mahoney@ktz.co.uk or can submit during the webinar. Register here.
Duke Royalty (LON:DUKE)
Pleasing Q3 update this morning showing Royalty income growing nicely following increased investment activity.
I've been increasing my holdings in royalty companies (here and in £APF ) as these seem attractive as we move into the new inflationary environment - anyone else got any thoughts on this?
Phil
Agree Duke Royalty (LON:DUKE) looks very interesting as an inflation play as income streams are directly linked to top line revenues. I'm currently looking for business that should actually benefit from inflation - beyond the obvious (energy and commodities), I think recruitment is another area - rising wages not only lead to higher fees, but also encourages workers to look for new jobs. Sthree (LON:STEM) and Robert Walters (LON:RWA) look by far the best names in this area in my opinion.
I hold both Duke Royalty (LON:DUKE) and Anglo Pacific (LON:APF) and I think both will be at least 20% higher in two years, having paid good divs along the way. I think they are safer than banks, aren't going to double, but then, it depends on your strategy. I will be very happy for my portfolio to do 15% TR a year, year after year, with just one or two moonshot shares for fun.
I think Duke Royalty (LON:DUKE) has good first-mover advantage over here, with North Amrican experience to draw on. And Anglo Pacific (LON:APF), well, I can see Julian Treger's frustration. In Canada they would be valued at 200p min. And today I see RBC has raised their TP to 245p. That wouldn't be pedestrian!
I have quite a bit of both, recommend them to family and will not be selling anywhere near these prices.
Of course, if 15% is enough, just buy Bmo Private Equity Trust (LON:BPET), Nb Private Equity Partners (LON:NBPE) and Oakley Capital Investments (LON:OCI) as your Private Equity allocation...
Hi Jack
If you have time, please would you take a look at £CRDL following their trading update today.
Used to be called Maestrano and you last commented in the SCVR on 12/10/21.
Thank you!
Hi mjfgs,
Jack's moved on to other duties now, and I don't have much more time today, as I have to take Mum to hospital for some physio on her broken wrist (recovering well, I'm pleased to report!)
But I've had a very quick glance at Cordel (LON:CRDL) for you, and really don't like the look of this at all.
Jam tomorrow, loss-making
Tiny revenues historically, and recently (only £629k for H1 to 31 Dec 2021 announced today).
£1.3m loss in H1
With loss-making companies, I look for a big cash pile to get them through. This hasn't got one. Only £935k cash at 31 Dec 2021. So looks almost inevitable it will need to raise fresh equity - on what terms? Probably not good.
On the upside, it does seem to have some credible, large customers. Outlook sounds reasonable -
The Group is carrying a large backlog of work into the second half, which we expect to produce growth for the full year. We are targeting to be cashflow positive in the fourth quarter."
Overall - it looks speculative, but not ridiculously so. Mkt cap £13.6m after today's share fall.
Unless you know the sector very well, and have researched management, products, competition, etc, then this looks nothing more than a punt, I don't know how the average investor could gain an advantage with this type of share?
It might be worth revisiting, once it's refinanced, has plenty of cash in the bank, and moving into profits. So I'll happily revisit this when the next results come out, to see if it has indeed moved into cashflow positive trading in Q4?
These type of jam tomorrow shares are very much out of fashion at the moment, and are better suited to a roaring bull market like we had early last year, so generally I wouldn't be chasing things like this right now.
More shenanigans at Dx (group) (LON:DX.) by the looks of things. This morning the two NEDs resigned with immediate effect!! Something doesn't smell right but with no update on the corporate governance issue previously identified hard to tell what it is.
Well spotted David! Shares in Dx (group) (LON:DX.) still seem to be suspended, after that weird episode where the previous (unexplained) corporate governance problem was half-revealed.
Maybe we'll find out more in tomorrow's trading update.
2 NEDS resigning immediately today, with no explanation as to why, looks concerning.
I wouldn't want to guess what's going on at this company, but it all smells bad, as you say. Mgt has handled the situation very badly indeed, so don't think I'd be interested in buying share in DX at any price.
Regards, Paul.
Hi Jack - are you going to be looking at Xlmedia (LON:XLM) this morning? Many thanks
Now is probably the time to be looking at some shares which, despite trading ahead of market expectations, are being sold off or the volume just isn't there.
So with that, my holding Elixirr International (LON:ELIX) gave a trading update today once again saying that results for FY21 will now be ahead of expectations (which were upgraded previously).
Revenues are coming in 7% ahead of expectations.
Adj EBITDA 6% ahead.
Cash, which is the more interesting thing to consider, is ahead 18% of broker FC's to £31m.
High margins maintained.
There are hints of further upgrades to come in FY22 both organically and through acquisitions.
@MGinvestor on Twitter
Elixirr International (LON:ELIX) has been a great performer this past year, but so has Accenture. And you can buy the brand, moat, balance sheet and vast contact book of the global no 1 for a similar price and with a superior earnings outlook.
Report yesterday of delays to couple of high profile London IPOs due to market volatility https://www.cityam.com/mishcon...
If you look at the companies concerned, I don't think we PI's will be too upset not to be able to invest in them!
In the case of Mishcon's their record fine in January likely meant their IPO was dead in the water in any case.
The high-profile law firm’s decision to delay its IPO comes after the firm was fined a record £232,500 at the start of January, for breaching anti-money laundering regulations.
Re Joules (LON:JOUL), to be fair Paul did anticipate another profit warning but this is a big one. Fortunately I took earlier comment at face value and left the scene.
For interest after Paul's comments on logistics management, which I assume related to internal company management of supply, the distribution centre in the U|k is managed by Clipper. Management of supplies from Asia is by a company called SEKO, and they have on their website a case study for Joules (LON:JOUL) and the link is https://www.sekologistics.com/...
Hi ridavies,
Yes I should have sold JOUL, as I was expecting another profit warning, just didn't expect it to be this bad. Never mind. They should have the supply chain problems fixed in months rather than years, so it won't actually matter in the long term.
Also, although it's been rather drowned out today by the halving of forecast profit for FY 5/2022, the outlook comments today from JOUL are quite encouraging -
The Board's base case expectation is for trading for the balance of the year to recover in line with its previously stated expectations, supported by recovering footfall and an improved level of newness in the stock position.
The wholesale orderbook for Spring / Summer 22 remains strong and the DC operation is normalising with delivery times back to standard service levels and productivity improved.
Hence if we can get through the shock & emotional upset of 2 profit warnings in rapid succession, then I see the outlook looking better than it has done for a while - remember that anyone buying today, could be lining up a fairly easy 50% gain in the next 6 months, based on the improving outlook referred to above.
Sorry this one has crapped out in the short term, but it's not a bad, or broken company. These short term issues are already being fixed, looking at the above. So definitely one to stick with, and I'll be buying more, as the valuation now seems to reflect positive risk:reward.
Terrible so far though of course, I certainly jumped the gun, buying at 200p, but doubling the position will bring down my breakeven to 135p.
Averaging down is a terrible idea as an impulse reaction to bad news, but has served me very well in the past, when fundamentally good companies get oversold on temporary/fixable bad news.
Regards, Paul.
P.S. The comments from JOUL about additional costs from third party distribution centres are indeed interesting. It sounds as if Clipper Logistics (LON:CLG) must have cost+ type contracts with its customers, allowing it to pass on cost increases, if they have to pay a lot more for seasonal spikes in labour, etc. Good news for CLG, but maybe a drawback of outsourcing? It must have been extremely difficult for CLG to have balanced up the competing demands of many customers, all experiencing varying degrees of supply chain problems. Maybe they have been able to take advantage of supply chain problems, by charging customers more for priority service?
I remember back in my Pilot days, how our warehouse used to come dangerously close to collapsing every year at peak trading in Nov & Dec. It doesn't take much to see things completely fall apart - with HGVs backed up in the car park, unable to offload, warehouse staff tearing their hair out, people phoning in sick, etc. The only way to sort it, is to bring in loads of expensive temps, who don't know what they're doing, and eventually there's no choice than to run the warehouse 24 hours per day, and close the doors to new stock intake, until the people have cleared some space in the warehouse.
All of which ends up being very expensive!
Paul - Thanks for your views on Joules (LON:JOUL) today.
Let's hope they have laid it all out now, and decided to take the kicking, before trying to re-establish credibility against soft comps in 2022/23. Just picked up two chunks of these at 69.8p so we will see. It seems good risk reward at this level.
I do worry about management competency......these Supply issues and costs should have been largely known and forecasted at the last update (other than perhaps the extended omicron impact, in fairness).
I have spent my career leading global Supply Chains. It is common to see businesses, run by commercial/ marketing types, who invest all their energy in range and shiny new 'on-brand' offices, while totally taking their eye off the rigor and detail of the Supply machine, and it kills them.
Supply Chain is about excrutiating detail - and in good businesses the Chief Supply Officer (or Operations Director in the UK) needs to be all over it. It is always remarkable how few businesses have good ERP systems, good Demand Management & InventoryTeams, disciplined logistics professionals that are all over 3PL costs and global shipping, and a Sourcing team that manages risk and builds in contingency. This is tough in a high SKU apparel business, so the function needs to be excellent.
I appreciate there have been extraordinary, infationary costs in terms of labour and shipping through the pandemic period, but these are usually visible 6 months out in well run businesses - especially DC costs run by a contracted 3PL!
Thanks for that, BritishExpat70,
You're absolutely right, it's abundantly clear that the main weakness at Joules (LON:JOUL) is managing their supply chain. Compare how JOUL has got into a muddle, with 2 profit warnings, whereas bigger, better run outfits like Next, just sail through.
JOUL is primarily a design-led business, and as you say, those people tend not to be best at micro-managing the whole process of actually getting the product to the end customer efficiently.
This got me thinking about previous problems at JOUL re logistics, and I've found an old SCVR from 2 years ago, when JOUL put out a profit warning on 10 Jan 2020 - my coverage here was quite scathing,
It's like deja vu re-reading that report. At the time, 2 years ago, I was encouraged that JOUL was out-sourcing logistics to Clipper Logistics (LON:CLG) but that doesn't seem to have solved the new supply chain problems which emerged with the pandemic.
Long-term shareholders must be getting pretty fed up with JOUL management who have now, for the second time in 2 years, proved incapable of tightly managing the supply chain. Maybe that's why the share price has been so brutally smashed down, on very high volume, so perhaps an insti or two have decided to bail out in the open market?
Anyway, this is all fixable, but it seems to me JOUL needs to recruit some more robust top people to get the business better under control. Too many avoidable things seem to have gone wrong.
I still think the share's wonderful value at 67p now though, hence why I'm a buyer at this level.
Regards, Paul.
Hi Paul
Following previous reports on Joules (LON:JOUL) I thought I’d check out the store in Cheltenham with an idea to invest if I was impressed.
I went with my wife who was more than happy to go browsing the high street clothes stores.
There was absolutely nothing in the store for men and my wife was not impressed. We were in and out in 5 mins.
We used to buy frequently from them particularly for the children when they were younger but now we can’t find anything we are interested in, regardless of price.
The boys are now older teens and so definitely not interested the Joules brand or style.
I’d be careful averaging down on Joules. They’ve damaged their customer base and don’t appear to have a desirable offering. Past figures may be hard to achieve.
But I think todays update recognises this, the second bullet says:
'Delays to new stock arrivals as a result of global supply chain
challenges, resulting in a lower full price sales mix, in turn impacting
revenue and gross margin;'
so you would be right to observe less stock and less choice. But the point is this is transitory and right now beyond their control.
Re Joules - My wife expressed the same indifference to their offering. She described them as MOR - which is a good place if you're trying to win a general election but I couldn't comment whether this is good in a fashion brand - Next seems to do well however.
Paul - I respect your honest views re Joules (LON:JOUL) and admire your strong conviction that it remains a sound investment. Your intention to double down certainly supports that conviction.
However, for those of us who are now sitting on 50%+ paper losses there is clearly a risk of throwing good money after bad. For my part I adopt a maximum cash investment in any one share so doubling down is really not an option in a share where I'm already fully invested.
I agree that the fundamental business is sound but management has inflicted damage to the brand and its reputation over recent months through poor management of the supply chain / stock control issues. Repairing this damage will not be easy and will take time.
My main concern here is do I think the management are up to the job? The CFO is relatively new and the CEO only 3 years in situ so both have yet to prove their worth. Also the founder Tom Joules is now very much a back seat observer.
Is this a strong management team? The jury is still out.
Snazzy
Hi Snazzy,
Fair comments, I think we are all justified in asking management some serious questions. There are clearly shortcomings over management, I agree.
Apologies to you & everyone, if your investment decision was influenced by me. Plenty of share ideas do go wrong unfortunately, along with plenty that go right. It's so difficult to know in advance which ones are going to work.
Regards, Paul.
Thanks for your update on Joules (JOUL) Paul.
My view tends to be more pessimistic about the future here, and more in line with pertinent comments from Revs8, Snazzytime and British Expat.
There is now an element of shambles and chaos in the business in my opinion, and the credibility of management is very much a concern.
The business decided to outsource its whole logistics operation to Clipper and SEKO in early 2020 , only 3 months after the current CEO joined the business. This was a big step to take, one full of risk for all sorts of reasons but with understandable aims to "drive efficiencies and expand capacity"(Nick Jones) at their Corby DC. They have been very unlucky with the timing but it appears so far to have been a disaster and has not been handled at all well.
This decision followed a profit warning issued in Jan 2020 about which the new CEO said "We have identified the root cause of this one-off issue and have taken steps to prevent its recurrence" !! Note also that, whilst the new CEO came from very high quality previous roles, his competency was welcomed by Joules as being for "retail, brand and strategy " credentials. Not too much evidence of nitty gritty stock management, logistics or supply chain control.
At the same time, from early 2019 onwards,the business was working on moving all its HO operations into a new shiny £20m Head Office, presumably again to improve efficiencies. Another big project with risk attached. This was only completed in Nov 2021, and in the meantime of course, along has come working from home.
During this period, there appear to have been a number of changes in the top team. As well as the CEO joining late 2019, the previous CFO Marc Dench gave his notice to move on after over 5 years in place in Jan 2021, leaving in May that year. The FC also took on interim CFO duties before a new CFO Caroline York joined in August 2021. So no handover or smooth transition. I am sure the CFO is very capable, but her background shows no experience of retail, clothing, stock management, global supply chains or logistics from what I can gather. Her previous role was at Moneysupermarket.
Looking at the supply side and logistics, the company's Supply Chain Director who had been in place since 2017 , left the business in Jan 2020 (presumably carrying the can for the above mentioned profit warning). That left in place a "Head of Supply Chain Development " who had been with the business since 2016 and who had very significant and relevant prior experience. She left the business in August 2021 to become Head of Supply Chain at Holland and Barratt.
Looking at the current composition of the Board of Directors and the Senior Operating Management Team, it is unclear who now has overall responsibility for managing the supply chain and logistics.
We have now received a muddled and concerning profit warning showing a 50% lower profit guidance for the year of £5m compared to previous guidance of up to £12m provided only 7 weeks ago ! Not only that, the interim accounts are now 'late' , with no date being provided when they will be made available. And todays statement ends with the truly shocking revelation that the company is reviewing its going concern status !!
There is no question that Joules has been pretty unlucky with the timing of some of its big decisions. And has had some tough circumstances to deal with. But at the end of the day, this is what competency of management is all about and it is these circumstances which ultimately test the quality of that management.
Whilst in theory, the problems that Joules currently have are solvable, the question has to be "who is going to solve them and when ?" Because it is clear that, to have got themselves into this mess in the first place, it shows they do not have the skillsets in place for this fundamental side of the business.
In the meantime the brand is taking a battering , with every indication that this will continue for quite some time and all the while the customer base is gradually being eroded.
Excellent summary of the Joules (LON:JOUL) management team RutlandRam.
Your implication (and I agree) is that the CEO and CFO are square pegs in round holes and have made several (difficult) wrong calls, resulting in the supply chain issues being mostly self inflicted.
Additionally their communications to the market leave much to be desired. To fail to provide the usual January Trading Update (with no explanation why), then announce a profit warning on the day the Interim results were due to be announced and without giving any indication of when the Interim results will be finally be released is just awful communication.
Then to add (as a reasoning for delayed Interims) the mystifying comment that the company is '.....completing its going concern analysis......' is simply baffling.
All the above suggests the Management Team are simply not up to the job. I doubt matters will improve without heads rolling.
I topped up on Joules (LON:JOUL) at 69, I think there is some short term upside to this fall. But I worry about the management team long term.
Could this be a takeover target for Marks and Spencer maybe? Bring it in house and use the M&S logistics to sort out some of the problems? Just a thought.
I bought some Omega Diagnostics (LON:ODX) before the second spike last year at 65p
It rose to over 100p at one point if I remember correctly. I put a stop loss at break even and decided to just let it run, which didn't last long as it was back to 65p fairly quickly.
I know lots of people don't like stop losses but unless the company has a long track record of profit during all economic conditions I think they're vital, especially with speculative or loss making shares. A look at Omega Diagnostics (LON:ODX) chart says it all.
As a former pharmacy owner I had a look at Venture Life (LON:VLG) about a year ago when ST was recommending them. As their portfolio of products consisted of “dust collectors” I decided not to bother. Ultradex could only be sold with a combination of discount, media campaign and recommendation by sales staff as it is overpriced and relatively unknown. Dental will sell if at discount but listerine is cheaper and more well known. The rest you would struggle to give away.
That’s not to say it can’t be done as I know of several companies eg Thornton & Ross that expanded by buying other companies unloved products. Then when established buy more well known brands and sell of the previous junk to other up and coming business. Just not for me.
Another misleading statement about Simon Thompson , someone that has beaten the markets for over 15 years.
Get your facts right and investigate ( firstly) when , and at what price he started covering Venture Life.
I didn’t say anything about ST other than his recommendation prompted me to look at the company and do my own research and found it not to my liking.
Where is the evidence that he beats the market?
If he tips something then he keeps tipping it as a buy until he finally admits defeat when the shares are almost worthless.
You are joking right!!
You can research everything these days.
DYOR
No more comment on this subject
You are joking right!!
You can research everything these days.
DYOR
No more comment on this subject
I didn't know Simon was on Stocko.. :)
nice one!!
Simon Thompson is a bad joke. I can't believe PI's follow his tips. Its quite unsightly people hoping he tips one of their illiquid micro caps. The guy runs a spreadsheet not a portfolio, tips illiquid micro caps to his v large and gullible following and then claims that means he's got a track record.
Did I say I think it's all hot nonsense?.....
Surely its not about following his tips blindly, but confirming your own research.
I was iffing about buying Sylvania Platinum (LON:SLP) the Jim Slater screen had thrown it up, but just couldn't make my mind up. Read a ST recommendation for it, and it made me hit the buy button circa, 30p. Its taken a couple of years of my retirement target, so for me, I thank him for that.
If you are going to buy everything he recommends, a bit like the Small Company Sharewatch, you are going to come unstuck. Its just another tool.
I agree with sentiment...but disagree in fact as I believe his work is really shoddy so reliance on it is dangerous imo. Venture Life (LON:VLG) shows this...it is clear he did not analyse anything in depth re this company when he tipped at 92p. The problems were very obvious. There have been many other examples. But in a bull market when buying power is high and people hungry for more the balance of probabilities goes with you particularly if you have legit profile.
You were about a year late on Venture Life.
He started coverage at 25p.
Thanks ST - you are a legend.
Ummm...you've got a strange attitude to investing...so you're saying I was wrong to point out ST and Venture Life (LON:VLG) nonsense at 100p as the price was once 25p?
Is it good value today? Do you understand anything substantial about stocks yourself or do you just follow tips?
He started coverage of the stock when it was 25p.
He first recommended it when it was 25p.
What exactly is that you don’t get???
As for my stock picking knowledge, 25+ years as a broker/investment advisor , there is only one thing that makes the difference in any portfolio :
Diversifyyyyyyyyyyyyyyyyyyy
OVER
haha…how many clients did you wipe out with your inshite?
He started coverage of the stock when it was 25p.
He first recommended it when it was 25p.
What exactly is that you don’t get???
As for my stock picking knowledge, 25+ years as a broker/investment advisor , there is only one thing that makes the difference in any portfolio :
Diversifyyyyyyyyyyyyyyyyyyy
OVER
Unfortunately this is what exactly happens.
People follow one of his recommendations , and then they blame ST and not themselves.
No one will ever lose any money if you follow ALL of his recommendations but do it when he starts the coverage and not after it quadrupled.
The same counts with Paul & Jack- follow all of their recommendations and not just Boohoo or Joules. You will make money.
Diversifyyyyyyyyyyyyyyyyyy
Stockopedia is not a tips site, nor are Paul or Jack tipsters.
A promise of making money should NEVER be made - are you going to cover losses if they are made?!
And for anyone new to this website or investing, don't just replicate what others do - use this as a basis for further research and make your own mind up. If you don't want to do this, then buy a fund or ETF.
I thought that but then looked at what they are flogging on Amazon and the reviews are really impressive (and there are thousands of them) so their could be something worth keeping an eye on here - especially as they start doing the same thing in Germany. I dont know what the stripped out figures for Amazon are though.
I don’t disagree and I am not saying they are bad products just that they didn’t sell very well in my “bricks n mortar” pharmacy. I did sell a few via my online pharmacy. The interesting thing is products that sold online didn’t sell well in store and vice versa. My guess was that it was because the products weren’t widely stocked in local pharmacies ( for reason mentioned before ) so customers went online to find them.
A rather superficial dismissal of React (LON:REAT) [I hold] from Paul this morning, in my opinion. Yes, they are small, yes they were hyped up in the early stages of COVID, but look a bit deeper and there is an interesting story here.
Further, management seem to be very credible, have a clear strategy that seems to give genuine differentiation in a commoditised sector, and are very happy to engage with private investors.
Are they going to set the world alight in the short-term? Are they screamingly good value at present? The answer to both these questions, in my view is "no". However, I see great potential here and am in to follow the story for the long-term.
For anyone interested, there is a management presentation scheduled on 3 February:
https://www.investormeetcompany.com/react-group-plc/register-investor
I looked at this company and I had this nagging fear they were lining themselves up for lots of litigation in the future. The stuff they get their staff doing is, well, horrific in some instances. If I was to invest I'd want to make sure they had fully costed provisions for the prevention and treatment of mental health issues of their staff and that they had extremely robust health and safety policies across the board with regular inspections of the same.
It could well be that this is all in hand and I haven't seen anything to suggest it isn't. I would want to make sure before investing though. I would check the annual report for this sort of thing, but they don't make it generally available online.
React (LON:REAT) (I hold) I first heard of React (LON:REAT) via a Mello event. Chairman Mark Braund (ex CEO of Redstone - now Smartspace Software (LON:SMRT)), can come across a bit rampy, but I've bought in to their growth strategy. They are aiming to consolidate and achieve a market cap that then wins larger contracts. There is a gap in the market for cleaning at scale; large FM companies have the burden and cost of managing engagement with lots of small local cleaning companies; React (LON:REAT) are aiming to be the defacto go-to company here. This is where the risk lies (imo); given their current size are they capable of growing further, without continual fund raising. Fedelis was a great start, but its a long road. For those who are interested, React (LON:REAT) are due to appear on Mello on the 21st of Feb: https://melloevents.com/mellom...
Hopefully, Rivaldo won't mind me copying his comment on the LSE BB. I thought this was useful
Here's the link to today's 12 page update from Allenby Capital:
Https://www.allenbycapital.com/our-research/?fwp_research_client=1756
They have a 3p target price. I note that their 0.17p EPS forecast is prepared "prudently".
They summarise:
"REACT Group plc (REACT), a leader in the specialist cleaning, decontamination and
hygiene sector, has reported full year results to September 2021 which shows strong
year-on-year growth, generated from both the core REACT business and the earnings
enhancing acquisition of Fidelis.
In line with its strategic focus, the majority of Group revenues are now under multi-year contracts providing good revenues visibility and this focus is expected to continue both organically and from targeted earnings accretive acquisitions. The current year looks very promising with a full 12-month contribution from Fidelis and further growth from the core REACT business with momentum continuing through 2023. We have a fair value on the shares of 3p."
Hee Hee...well I'm going to disagree with Effortless Cool again on React (LON:REAT) ! This time I'm more bullish than he is.
I had previously been negative as I thought they'd overhyped their turnaround. Then high profile small cap people promoted the stock too (...they tend to be rampers...but imo also bit loose in their work so always potential for nasty surprise) and it went on Mello. The sp lost its sh1t! By end of 2021 though the comedown had been really hard. Some points...
Fidelis acquisition for all cash bar £200k of stock looks a real astute bit of biz. And likely to be on a run rate of c.£7m of revenue. One word of caution is that Fidelis seem to have doubled their revenue in quite a short period of time...clearly this could also indicate that forward revenue expectations are undercooked too. React need to manage their cash carefully for the next year on earn out payments for Fidelis so I'd be surprised if there's another sizeable acquisition for at least 12 months (unless there's a boon that is meantime)
The core React biz has, contrary to perception, had a mixed time due to covid. Yes they got covid work (which they term 'ad hoc' reactive biz) but they lost quite a bit of 'contract reactive' business in period as judicial system not working (clean cells and transport), housing association not active moving problem people on, etc. As the biz had just put itself on a recovery trajectory before covid struck (with better sales team and strategy) its hard to know where that was going exactly but the balance of probability is that business lost to covid was similar (probably more trying to account for what-if wins) than gained. Just dunno. What is clearer though (I believe anyway from memory) is that the ad hoc business is less profitable at the op profit level (even though it looks good at gross profit) as it comes with a less manageable/predictable cost element in doing the unexpected rapid turnaround 'emergency' ad hoc work. They see ad hoc work as a shop window to impress new potential prospects too.
On balance I think the expectations for fy22 and onwards are somewhere between a bit and a lot undercooked at least in terms of revenue. Its clear that management are going to try and invest excess cash as it comes in growth both internal sales capability and bolt on acquisitions so that will drag on short term profitability potentially (for example a senior salesperson at £100k pa has a big impact on forward sales...but an immediate drag on costs).
I don't expect a smooth ride as the unwind of covid and return to normal working practices is uncertain plus they were already on a turnaround growth trajectory and covid splatted into the middle of it.
There was a concern somewhere on here re the traumatising of workforce. The trauma work is all highly certified stuff...can't just send a regular cleaner in. Plus a lot of these people are independent business units that React hire when needed for job. People aren't being sent to clean up body parts on a railway as work experience or on first day.
The overall mgt and board team for the company is good quality relative to size and needs of this business.
HOWEVER, this is a real microcap and I think Paul's prior caution around should it be listed is something to think about. My view is that there's quite a nice long runway to being a bigger company. A lot of niche growth and consolidation whilst keeping margin due to type of work they do. But its not a stock for trading and beware high profile PIs shouting about it ramping price (TBH I'd rather they didn't do Mello too!)...and if it goes wrong getting out will be v hard.
PS pretty feisty in SCVR today. I thought it would be more jolly in a bit of market relief period
I bought Creightons (LON:CRL) at a £5M market cap because they seemed to have established a business that had the capacity to grow. React (LON:REAT) at £10M seem to be in the same position. They have started to cover costs and next year the PE starts to make sense. Now they are profitable the earnings should continue to grow rapidly - the PEG ratio is 0.11! The only slight worry for me is whether they will struggle to replace the covid hygiene sales a situation that would delay where they are heading but not prevent it.
The very nature of the business, contract and reactive professional cleaning should be sustainable, and the size and reach of the company should now allow growth on a national basis. Although growth companies are out of vogue at the moment, this could quietly and quite quickly become substantial and make the current valuation look trivial. If they can maintain a growth rate above 30% we are looking at a multi-bagger in the next couple of years. There is many a slip between cup and lip but this looks to be an excellent risk reward combination to me.
Checkit (LON:CKT)
Wins first large contract in USA for minimum £2.8m with subsidiary of Grifols.
Deal further confirmation of CKT technology
Recent placing end 2021 @ 46p to raise £21m to fund expansion in USA and product development for this £47MCap minnow.
£21m does not seem to appear in Stockopedia figures.
Grifols is a global leader in the production of plasma-derived medicine and transfusion medicines. Headquartered in Spain, it has a worldwide network of over 350 plasma centres, including more than 50 in Europe. With revenues of €5.3bn (of which €3.6bn were generated from US operations during 2020), Grifols employs 24,000 people providing products and services in more than 100 countries worldwide.
Euro expansion with Grifols at advanced stage
3 yr deal signed new Egypt ops
Checkit CEO Kit Kyte said: "We look forward to the continued growth of our relationship internationally. Our partners at Grifols already appreciate the power of our monitoring services and the future addition of workflow management will give them unprecedented levels of digital control and data-driven insight, as we look for ways to streamline their complex, globally distributed operations. This deal provides further confirmation of the importance of our technology in enabling intelligent operations across deskless workforces."
Deal further confirmation of CKT tech
Several large profile clients including BP, NHS, Waitrose
High margin, recurring revs
This is the baby of Exec Chair and major shareholder Keith Daley and was originally Elektron Technology.
I hold
I like the Checkit (LON:CKT) tech and it certainly has plenty of market space to grow into. I suspect revenues are highly sticky as once the optimisation tech gets embedded into process and software you take a lot of pain removing and replacing for something else. So it either has to stop doing its job effectively or be priced badly to lose customers.
The contract with BP got expanded and now it seems Grifols is going to effectively test and expand too. I think if they can win a couple more high value clients then they should be a self funded, highly profitable business with long term recurring revenues. Usually the market rewards that with a high PE but still some way to go.
EDIT: Also I note it is now a £50m market cap with about £27m of net cash. I estimate ARR should now be up over £10m and sales pipeline had grown from £3m to £13m
so basically trading on about 2.3* EV/ARR and growing fast.
Actually having looked at it a bit closer I like it more than I thought.
Hi davidjhill
I agree. Once on-board clients seem to be very sticky.
I do not think the valuation is stretched at 3.2 x sales for a company with 27m cash, increasing ARR and high margins.
I went to the Checkit (LON: CKT) CMD last year which was a physical event.
I was impressed by both the product expertise and also passion for the product of the product development team. This is coupled with the commercial acumen and experience of Chairman Keith Daley who had great success with Elektron and as a private investor himself.
The BP contract is going global which will attract the attention of many other companies. They also acquired a company called Tutela in the USA to accelerate expansion in the USA and several American hires. This win seems to be the beginning of the success of this plan.
Michael
Ah bummer. I've been tracking Checkit (LON:CKT) for a while looking for a good entry point to get in. My buy price was 40p, and it got close at 43.5p, before this announcement has now sent it back up. Will be re-evaluating now to see what entry higher price is acceptable, with the news of this contract.
Fairly disasterous Joules (LON:JOUL) update as the company says: 'PBT now not less than £5m for the full year' when they had already downgraded full year pre-tax profit on Dec 14 (yes one and a half months ago) to 'in the region of £9m to £12m notwithstanding any further significant covid restrictions.'
So it's halved in one month!
Today was supposed to be their interim results but instead we are told 'The Group is in the process of finalising its Interim Results, including completing its going concern analysis, reflecting the impact of trading performance up to the end of January.'
Joules (LON:JOUL) The lack of usual January Christmas trading update was indeed a forerunner of this awful update and now delayed Interim results. (I hold - but regret not selling)
£W7L
Warpaint starting to look like the company it promised to be a couple of years ago. The team they brought in (at great cost - I wasn’t happy with how much they paid for the advice) seems to really have got a grip of sales and they’re expanding into the very biggest retailers now, the likes of Tesco and Boots.
Revenue and PBT ahead of market expectations, not massively but enough, and the outlook commentary for 2022 suggests there’s more to come.
I’m long
£JOUL
Nothing soothes a jittery market like throwing in the phrase
'The Group is in the process of finalising its Interim Results, including completing its going concern analysis,'
Broker slashed EPS by 58%. Bit of a car crash all round.
Morning gringo,
I know, reading the JOUL trading update, it's almost as if they've deliberately written it to scare investors to the maximum possible extent! Is there an agenda here (taking it private?)I wonder?
Anyway, it's a lousy update in the short-term, but all the problems are fixable, supply chain related stuff, and it's still profitable. Hence I think we're getting a buying opportunity today, if you look beyond current issues.
Obviously wishing I had sold previously, as I was expecting another profit warning, but just have it parked in a siding as a long term investment - maybe that's not such a good strategy - it would have been better to wait on the sidelines for a better buying opportunity, but never mind.
I didn't expect the market to just keep smashing the price down, over and over, for the same issues. Part of the problem was that Liberum put out very aggressive forecasts a while ago, which the market didn't believe anyway, yet we're now seeing those forecasts slashed, and it whacks the price every time.
Ho hum.
It's an excellent company though, once they get the supply chain side of things sorted, so there's no change to the long-term outlook, which is important to remember when short term disappointments happen.
Regards, Paul.
I completely agree Paul - I'm seeing this in Thg (LON:THG) massive rumours that it will be taken back privately - everyone wins apart from shareholders.
Morning Paul
I like the company and will be a buyer at some point in the next few weeks I imagine. Whole sector is being hammered, this will change eventually.
Have to agree on the wording of the update. If they wanted to scare investors they've done an excellent job
Don't forget they were supposed to publish their interim results today as they had previously announced. Which does make me think there is some kind of potential balance sheet worry here.
£Joul
Profits behind over the last nine weeks but from what I can discern the full year picture is a beat?
Struggles on the revenue front attributed to wholesale customers cancelling, footfall being lower, DC disruption, stock issues etc
Profitability issues from DC costs doubling to 1.2m in December from prior December. I'd like to see the contractual arrangement here as it seems to have come out of the blue. 3rd party fulfillment seems a good strategy to keep capex down but risky in this inflationary environment. Perhaps a model along the lines of Boohoo (LON:BOO) Asos (LON:ASC) would be less risky.
Mitigation measures include increases in prices, reduction in capex and marketing. Also liquidation of inventory and restructuring their wholesale operation.
Interesting update on the whole. I think cost control could better and price increases better/ earlier telegraphed e.g £NXT
Joules (LON:JOUL) Not a beat for the full year apologies. Trying to review on my phone with a 2 year old climbing over me will get a proper look at this on the laptop later. It could be a good day to get better acquainted with this one.
Coincidentally, read an article today that said cotton futures (in the USA) are at highs never seen since 2011?
https://www.zerohedge.com/comm...
Cost inflation might be a headwind for Joules (LON:JOUL) but also other clothing retail for some time to come still.
If the story on the way up to 200p+ was that the above average middle classes, older demographics were spending more in 2020 and 2021. Are we seeing the start of a big squeeze on discretionary incomes and/or spend being diverted back to other industries like hospitality?
Or was it a Joules specific bubble?
Sureserve (LON:SUR) which got the thumbs up from Paul in last Tuesdays (25th Jan) SCVR issue new RNS for 10 year 20M contract from Tower Hamlets.
Nice to read that the rns also includes "...apprenticeships, training, work experience placements and other projects that support the community" excellent from an excellent company
Venture Life (LON:VLG) an Investors Chronicle buy tip from ST drove the price yesterday - as usual. It will probably reduce significantly over the next week as it often does. Xpediator (LON:XPD) was another one.
ST was tipping Venture Life (LON:VLG) when it 92p last year - and continued to tip as it collapsed, eventually to 30p!
When did he start covering this share?????
He started covering it at 25p.
You are misleading this forum and blaming someone that has beaten the markets for over 15 years.
Shameful indeed.
Just stating that he tipped last year at 92p and despite obvious problems kept stubbornly tipping it. I accept he may have previously tipped it at a lower price, but you also need to know when to get out. I've nothing against Simon Thompson and accept his record is good, but find it very irritating the way share prices spike 20-30% when companies are featured in his column - not sure if this is due to investors sheepishly following what he says or market makers moving the price.
Maybe, if that is the case, you should buy on the spike and sell them soon afterwards?
Just a thought.
They tend to immediately spike as soon as the tips are published, so you definitely wouldn't want to buy straight after a tip. However, I have occasionally used his post-tip spikes to sell positions that I was thinking of getting rid of.
Venture Life (LON:VLG) continually mislead investors and I certainly don't trust management. For example, their RNS highlights included:
· Revenue of £32.6 million
· Revenue in the second half of the year was £18.7 million
· Adjusted EBITDA in line with market expectations.
Why put figures for some items and not others? It wouldn't have been difficult to say "Adjusted EBITDA of £XX, in line with market expectations." You only take this approach if you're trying to hide something...