Small Cap Value Report (Tue 1 June 2021) - CHH, SAA, GHH, SPR

Good morning, it's Paul here with the first SCVR for this bank holiday week.
Timing - update at 14:09 - I'll leave it there for today, as Tamzin wants to chat to me for PIWorld at 3pm, and I want to have a cup of tea & soak up some sunshine before we get stuck into that. Therefore, today's report is now finished.
Agenda -
Paul's Section:
Churchill China (LON:CHH) - in line with expectations trading update. Healthy order book. Upbeat-sounding, but noticeable for a complete lack of figures! This is a good company, but the share price now fully prices-in a recovery to 2019 performance.
M&c Saatchi (LON:SAA) - shares are up today, on a strong trading update. This one is a bit too complicated for me, with previous accounting issues, I'd rather leave it alone. Although macro conditions now seem to be good for PR/marketing companies, so it could have further upside perhaps?
Gooch & Housego (LON:GHH) - improved H1 profits, but that's due to excluding restructuring costs, including them gives a result barely above breakeven. Solid balance sheet, and upbeat outlook. I'm struggling to justify the valuation though, it does look as if upside is already priced-in, as with many shares I look at currently.
Springfield Properties (LON:SPR) - strong trading update, significantly ahead of expectations. Looks good.
Paul’s Section
Churchill China (LON:CHH)
1708p (pre market open) - mkt cap £188m
AGM Statement (trading update)
Churchill China plc (AIM: CHH), the manufacturer of innovative performance ceramic products serving hospitality markets worldwide, will hold its Annual General Meeting at 12 noon today. At the meeting, Alan McWalter, Chairman, will make the following statement...
It’s upbeat-sounding, but in line with expectations -
Whilst the Company is currently trading in line with the Board's expectations, we remain mindful of the potential for further impact on our revenues and operations from future market restrictions and therefore continue to maintain operating flexibility and a sound financial base…
… We believe our decision to maintain operating levels will stand us in good stead and that the level of momentum within the business will allow us to meet our target performance levels both in the short and longer term."
- Quiet Q1, due to lockdown
- Growing evidence of recovery (as reported on 19 April 2021)
- Increased activity has continued in last 6 weeks
- Healthy order book (no figures provided)
- UK leading the recovery, export markets also now improving
My opinion - I would have preferred to be given some actual numbers, instead of this rather vague update with no figures. Bottom line, it’s trading in line with expectations, so that’s OK.
Key question at the moment for all companies we look at - did CHH dilute its shareholders with a fundraising during the pandemic? No, it doesn’t seem to have done - the great benefit of having a strong balance sheet. The share count seems to have remained static at 11.0m in issue, the same since 2015 according to the StockReport (see “Average Shares” row on the table of figures, then the most recent position is at the bottom of the StockReport, “Shares in Issue”).
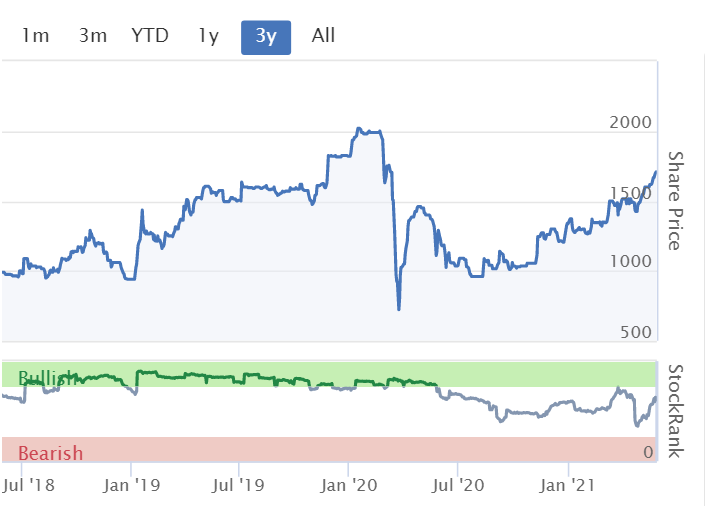
In 2019 CHH reported 80.8p normalised EPS. Assuming it recovers to the same level in due course, then the PER would be 21.1 times - i.e. full recovery is already fully priced-in. How does that make sense, given that full recovery hasn’t happened yet, and there are still risks?
Nice company, but I don’t see risk:reward being attractive at this price, unless you think the company can achieve better than pre-covid profits. I'd say the re-opening trade has now happened, with the smart money buying 6 months ago, not today.
.
.
M&c Saatchi (LON:SAA)
142p (up 11%, at 08:51) - mkt cap £174m
We navigate complex change, to create new opportunities with technology and creativity, and to lead the way forward. We Navigate, Create and Lead Meaningful Change for our clients and the world.
[from mcsaatchi.com]
Or the way I look at things, it’s a PR company.
Positive trading -
Trading in the first four months of the year has been stronger than anticipated. As a result, the Board now believes the financial results for the full year will be ahead of consensus expectations.
No asterisk provided, to tell us what those expectations are. So not very good communications there, from this communications company.
Stockopedia shows 0.49p forecast EPS for FY 12/2020, and 2.65p for FY 12/2021.
See the graph below, for how drastically lower the broker consensus forecasts are now, than pre-covid. Hence today’s update needs to be seen in the context of stepping over a very low bar.

.
Other points in today’s update -
- New business performance is robust, with example client names given
- Diary date - results for FY 12/2020 due end of June 2021 - a very slow reporting timetable again
- Refinanced bank facilities, from £38m to £47m NatWest/Barclays, 3-year term
- Liquidity - currently holds £30m net cash - impressive
Dilution - yes, it has raised fresh equity during the pandemic. The latest share count is shown as 122.3m on the Stock Report, which compares with c.90m in 2019 (pre-pandemic). Hence pre-pandemic earnings need to be adjusted for this c.35% increase in share count. I would divide previous peak earnings by 1.35, to get to the equivalent figures now, with the larger share count - that’s quite a material adjustment, and I wonder how many people might overlook this point and hence over-value the share?
Put options scheme - I tried to unpick what’s going on with this ill-fated options scheme, here whilst covering the reasonably good interim results published on 28 Oct 2020. This shows how put options could cause large dilution, although the rising share price since has reduced the potential number of shares to be issued. At that time, the company was negotiating with holders of the put options to get them to switch the cash payments instead. I’m not sure what the current status is of this issue, but am flagging it here as a material problem, which anyone considering buying the shares needs to be aware of, and properly investigate for yourself, to ensure you’re happy with things. I see from an update on 4 May 2020, some of the new shares issued are due to conversion of put options. Another similar announcement was made on 20 April 2020. It would be good to find out how many put options remain.
My opinion - checking back through my notes here, there have been big problems at SAA in the past, which the market seems to now be happy to ignore. Its shares were suspended, due to a delay in publishing 2019 accounts, then resumed trading on 7 Dec 2020.
There’s also the material issue of the put options, mentioned above.
Positive current trading, and a more favourable macro environment are bull points. I can see why people would be keen to invest in PR companies, as the general economic situation seems to be improving strongly, as a V-shaped recovery appears underway in the UK, and USA, and presumably Europe, when their vaccination programmes allow re-opening.
Overall, I’ll just say I’m neutral on SAA.
I prefer simple, clean accounts, and don’t really want to invest in companies where you have to make guesses about key issues, and where there have been accounting issues previously.
Note that highly regarded investor Vinodka Murria holds 12.5% of SAA shares, a big vote of confidence, so she must have investigated the above issues and been happy with the situation, I assume.
.

.
Gooch & Housego (LON:GHH)
1330p (up c.2% at 11:00) - mkt cap £332m
Gooch & Housego PLC (AIM: GHH), the specialist manufacturer of optical components and systems, today announces its interim results for the six months ended 31 March 2021.
Sustained recovery in industrial lasers contributes to profit growth and positive outlook.
We’re just starting to catch the start of the pandemic in prior year comparatives, with 31 March period ends, so that needs to at front of mind from now on - i.e. as the prior year comparatives get softer (from lockdown 1), performance this year should be much stronger. Comparisons with 2019 are also useful, to give a comparison with the last normal year, so I very much encourage City folks reading these reports to bear that in mind when advising your clients.
The highlights section contains some positives (that’s what it’s there for!) - revenue only slightly up, but profits & EPS are strongly up (although note most underlying profit comes from excluding £4.2m restructuring costs). H1 statutory profit is negligible, at £670k, only 2.1p EPS.
Net debt mostly paid off, and divis resuming, all good -
.

.
Points of note -
- Restructuring to deliver £1.75m profit benefit in FY 09/2022
- Order book up 1.3%, or 7.9% at constant currency - note the difference is quite significant there, due to the considerably strong pound I suppose
- Full year expectations unchanged, despite currency headwinds
- Good demand, apart from commercial aerospace (I’m guessing that is likely to improve, as travel opens up again)
- Growth in contribution from new products
- Investment in capex, R&D, “moving up the value chain”, and possible acquisitions
Balance sheet - looks strong. NAV £111.4m, less intangible assets of £51.6m, gives NTAV of £59.8m, which strikes me as more than adequate.
Working capital is strong, with the current ratio a very healthy 3.42, although there is £19.95m borrowings lower down, in non-current liabilities.
Overall, no issues here, it looks fine to me.
I doubt very much GHH would have needed to raise fresh equity in the pandemic. Sure enough Stockopedia figures show the share count static for years, at 25.0m - that’s what I like to see.
After all, as a shareholder generally, I want to benefit from the future upside, not see myself diluted every time there’s a financial downturn of any kind.
Valuation - as always, this is the tricky part. GHH seems a nice enough business, but the Stockopedia graphical history below shows that it wasn’t really demonstrating any profit growth pre-pandemic.
An (expensive at £7.5m anticipated full cost for FY 09/2021) recent restructuring programme to deliver £1.75m profit growth, doesn’t jump out at me as necessarily money well spent, but management must know what they’re doing.

.
My opinion - I always think of this company as a really high quality outfit, but am starting to wonder if that’s correct? The history isn’t particularly special, although it has proven resilient throughout the pandemic.
Finncap has put out an update today, 36.4p EPS for FY 09/2021, and 42.9p next year. At 1330p current share price, that’s a PER of 36.5 and 31.0 times - a rating that is hard to justify.
Although as David Thornton of Growth Company Investor (which is very good actually, I’ve recently subscribed after being impressed with David’s commentary on PIWorld interview) points out, many broker forecasts are currently way too pessimistic, misleadingly so, to use his words.
It all therefore boils down to whether you think GHH could thrash existing forecasts or not. I have no idea, as I cannot reliably predict the future. I’d rather pay a PER in say the high teens, and then out-performance against forecasts is my upside, if it happens. Here, we’ve being asked to pay up-front for future out-performance against at least this year & next year’s forecasts. I’m reluctant to do that, but good luck to holders.
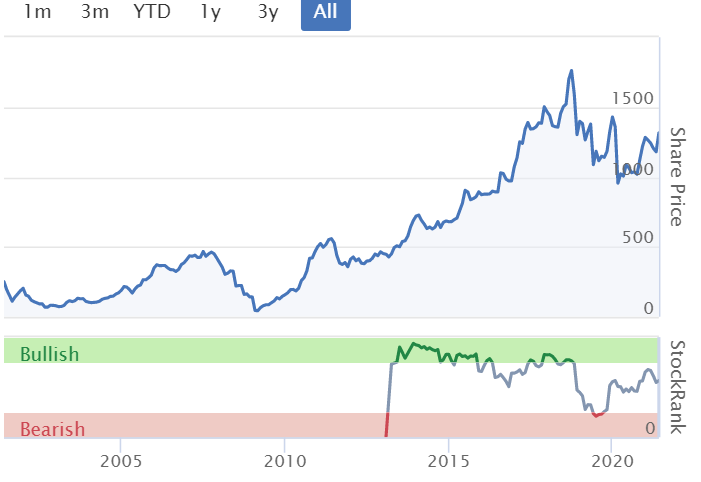
Mind you, look at the long-term chart below - staggering gains from the March 2009 low in particular. Maybe it's worth paying up for companies with superb long-term track records? There's a lot to be said for that.
.
.
Springfield Properties (LON:SPR)
168p (up 12% at 13:44) - mkt cap £171m
This is a housebuilder in Scotland. I’ve only looked at it once, here on 23 Feb 2021, and quite liked it, concluding: It’s got a solid balance sheet, outlook comments sound upbeat, and valuation seems reasonable..
Trading update today has put 12% on the price, so must be good.
SPR’s year end is 31 May 2021, hence this is a year end update.
Strong build & sales activity has continued in H2
Sold 200 plots of land to national housebuilders
Overall - contradictory messages here. It’s ahead, then significantly ahead -
... the Group expects revenue and profit to be ahead of market expectations, reflecting significant year-on-year revenue growth....
... the Group expects to report revenue and profit for full year 2020/21 significantly ahead of market expectations, reflecting significant year-on-year growth. The Group has also continued to substantially reduce net debt throughout the year.
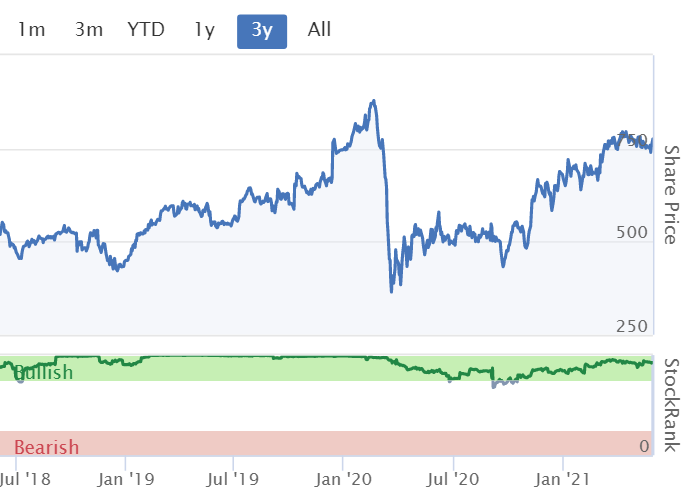
There’s lots of green on the Stockopedia growth & value section, which I like very much. Also earnings forecasts will be raised after today’s strong update. There’s also a high StockRank.

.

.
My opinion - looks good, I like the numbers here, and it’s worth readers taking a closer look.
Obviously we know that the housing market is benefiting from Govt stimulus measures, so that might need to be factored into calculations.
Much larger housebuilder Barratt Developments P L C (LON:BDEV) is on a forward PER of 10.2, with a 4.9% dividend yield, so it’s worth bearing in mind that the sector looks cheap overall. How SPR compares, would be worth considering - if they’re all cheap, then I’d lean towards a larger share, as it’s easier to go in & out of, for a minimal spread. Although smaller companies might have faster growth potential possibly? Your money, your choice!
.
.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

55 comments
Hope somebody can answer, is there any way of screening for stocks where the Quality, Value, Momentum or StockRank has moved up or down by a specified amount over the last 30 days?
Is anyone out there following/have any insight into the developing car crash that is Amigo Holdings (LON:AMGO) ? This sub prime/lender sponsored finance company fell victim (self inflicted perhaps?) to substantial customer complaints/liability claims that it has been unable to pay and has been seeking to settle via a protracted court process. For a while the shares rallied on a speculative wave that there would be a favourable court ruling backed by some high profile commentators such as Simon Cawkwell/aka Evil Knievil (usually a very savvy judge of a special situation) but has subsequently tanked following an adverse court ruling (the proposed settlement isn’t generous enough) and an acknowledgement by the company today that it won’t appeal the ruling and may as a result face insolvency. Not sure if this is becoming a decent risk:reward deep value play or something best left well alone. No position and probably disinclined to take one.
Gus.
RE: Amigo Holdings (LON:AMGO)
The FCA changed its mind on supporting the original deal, presumably because it was pointed out to them that their responsibility is actually to protect customers rather than back a lousy deal that protected shareholders and ensured the directors could pick up a future bonus.
This was the FCA's submission to the court proceedings:
https://www.fca.org.uk/publica...
Note the paragraphs from 5.3 on in the section entitled "Contribution of other stakeholders", ending with:
"The FCA considers the absence of any shareholder compromise to be a material consideration for creditors and the Court in relation to the overall fairness of the Scheme"
A deal may emerge out of this, but if it does it'll have to be considerably less generous to shareholders than the previous one. Anyone who claims they know what will happen is talking through their trousers. Although, frankly, that's always been true.
timarr
I have been following the sub-prime (politely "non-standard") finance space for some time. The interesting thing is that as regulation has progressively tightened, a lot of previous suppliers, some with exploitive business models, have been forced out eg pay day lender like Wonga but also many doorstep lenders like Provident and many smaller players. Others have had to retrench and run down loan books eg Non-standard Finance (LON:NSF) (I hold)
Personally, I think claims companies have their claws in so deep that Amigo is too damaged to come back, at least for existing shareholders. The brand still has value despite all the issues attached to it in the financial press and I think the guarantor lending concept was good since it enabled especially young borrowers access to money at a 50% APR vs >100%. (Moralists will say they should not borrow at all at these rates and save up but I think that is unrealistic and unfair. Instead, as the FCA is doing, a burden of care needs to to be regulated onto providers.) It may well be snapped up out of administration but not before.
However, demand to borrow by credit impaired customers who are not served by mainline banks, is still very large - especially once travel and holidays are back on the agenda. The winners will be those with good brands that are left in the regulated and so less competitive market when the FCA-lifted dust settles. My bet is Morses Club (I hold).
I think Amigo is dead in the water. It reminds me of when i was working on a remediation project for one of the large banks dealing with the fallout of PPI mis-selling. The FCA did not cap compensation then, and everything the FCA does will have the customer in mind and a 'tough luck' attitude towards Amigo. As their update says, essentially, if they dont cap the payments, then insolvency is pretty much their only option as they dont have the funds to cover it.
Morses club is a much better business and had a strong balance sheet (from what i remember - also, i have no position in MCL anymore as there is far too much regulation and scrutiny currently).
The problem is that the system is so stacked in favour of consumers. If the consumer makes an appeal/application to the Ombudsman, the company has to pay £750 fee to the Ombudsman, regardless of the decision. Therefore its a case of damn if you do (roll over and pay out the claim) or damn if you don't.
Hi gus1065m
Re Amigo Holdings (LON:AMGO) - I've been caught on many of special situations over the years, and whilst you might make money on the odd one, I've come to the conclusion that it's best to just avoid everything like this.
You only need the odd 100% loss to make a real dent in your portfolio. I'm still scarred from blowing £30k on Conviviality. It didn't even look that bad, but it unravelled incredibly quickly & disastrously. Or of course Patisserie Valerie#. That one was unique in my 20 year experience - an apparently great business, backed/owned by guru Luke Johnson, yet the management were cooking the books! Lots of people were wise after the event, but I cannot remember anyone ringing alarm bells about the accounts beforehand. Hiding liabilities is a very effective way of fiddling the profits, and almost impossible to spot.
As for Amigo, personally I'd just treat is a complete bargepole, not worth the risk. But if people do take a punt on it, then best to use money you can afford to lose, or only get involved if you have some genuine expertise about that sector.
I did meet someone who works at Amigo, who used to rent a room in the flats where I live in Bournemouth, but I cannot remember anything about the conversation (after the pub), and soon after he moved on.
Regards, Paul.
# Edit - I didn't lose any money on CAKE, but it was luck more than judgement. It looked to expensive to me, on a PER of about 20. If it had dropped to say a PER of 12, I would have filled my boots, and got massacred. Although, as we did discuss here pre-insolvency, the operating margin at CAKE didn't look right.
I think you'll find Tom Winnifrith has been following Amigo Holdings (LON:AMGO) for some years and has consistently called it out as an un-investible barge-pole. Wether you like the man or not (I quite enjoy his comments and insights), I am inclined to avoid anything he has his teeth into as more often than not he is proven correct. I def don't hold.
Tom only looks at the dregs, so almost everything he covers is an automatic bargepole for me, before he has even looked at it. The only exception I can think of in many years, is DISH, where the whole sector got shut down by covid, and I made a mistake - exiting around breakeven, so not too bad. Everyone gets things wrong from time to time.
We just filter out all the dross here automatically, and don't even bother reporting on it. It's not difficult! So I fail to see how it's a great credit to spot & avoid obvious junk. That's just a basic skill set.
Hi gus1065, I don't know if you listen to Moneybox every Saturday 12noon on BBC Radio 4 (Freeview 704, I think). Its a 30 minute programme on current real life financial problems which people are experiencing. The various topics can be on any money related matters. I record it every Saturday 12noon and Wednesday at 3pm because I find it very educational. This Saturday just gone 29th May, Paul Lewis did a section on Amigo Holdings and the decision by the FCA. I don't know whether it is available to listen to on the BBC iPlayer. I seem to remember that the FCA reckoned the 10% deal on offer was naff and the company needed to come up with better options.
Hi Logical David.
I hadn’t heard the MoneyBox discussion on Amigo Holdings (LON:AMGO) first time around but listened to it just now. Here is the link if anyone else didn’t catch it - the relevant bit is from 18:55 minutes in.
https://www.bbc.co.uk/sounds/p....
It’s a slightly one eyed discussion on the grounds that there’s no one there to put the Amigo Holdings (LON:AMGO) case across (other than a vintage sound bite of the CEO threatening insolvency if the Scheme of Arrangement doesn’t go through). I think the market reaction yesterday focused on the high likelihood of insolvency/potentially nothing for shareholders hence the sharp mark down in the shares. Seems today that a possible alternative offer that gives the customer plaintiffs a bit more while preserving something tangible for shareholders is the focus of the speculators as the shares are up 25%. Not for the faint hearted!
Gus.
Hi Gus, good to hear you managed to find the Moneybox programme on the BBC iPlayer. I assume you have set up your PVR to record the show every Saturday and Wednesday going forward ;-)
David
M&c Saatchi (LON:SAA) - Thanks Paul for your deep analysis - jut shows the pitfalls an average investor can fall into - not knowing about the tricks clever guys can come up with - I would be tempted into £SFOR - but its the unknown that worries me.
Lord Lee sold out of Gooch & Housego (LON:GHH) on 3 August 2020
RE: Gooch & Housego (LON:GHH)
I've always struggled to see the attraction - the financials have never looked like those of a quality company and earnings growth has been nothing spectacular.
Of course, GHH qualifies for AIM BPR for IHT relief, and along with a number of other popular AIM stocks that may well have inflated its price. Octopus, who specialise in AIM IHT funds hold over 13%, Investec have over 11%, at least some of which will be for AIM IHT management.
It's a bit of a head scratcher. A John Lee stock mind, and that's always risky to bet against.timarr
Positive sounding End of Year update from Coral Products (LON:CRU) (I hold too many).
They are featured on Shares Magazine Investor Evening today, Joe Grimmond, Executive Chairman presenting.
https://www.sharesmagazine.co.uk/events/event/shares-investor-evening--webinar-080621
I also note that Mark Bartlett, CEO of Strix (LON:KETL) is also on - I know a few here are invested (as am I).Apologies. Just seen Shares Magazine Evening is next Tuesday and not tonight!
OK. Whilst I'm here, as it were, some good news for holders of Stock Spirits (LON:STCK) over the weekend with the re-opening of the on-trade in the Czech Republic which accounts for 25% of revenue:
https://praguemorning.cz/czech...
All the best, Si
Calnex Solutions (LON:CLX) FY21 results presentation to analysts on 25th May 2021. CLX is benefitting from the 5G rollout and cloud computing, which drive growth for test and measure instrumentation and solutions. Revenue +31% to £18m, adjusted PTP +43% to £5.1m. Strong cash generation of £9m. Little impact from CV19, although a change in spending patterns from some key customers, with some orders bought forward into FY21. Looking forward management are confident to make further progress in the current financial year and beyond. Video & podcast.
Was mello a pump and dump by one of the presentors ?????
Sorry Springfield [SPR] getting over excited ! Tony
Morning Paul, I recently mentioned Springwood to you,and you followed with a good writeup. You might like to look at today's statement. It's always music to my ears when 'results ahead of expectations' comments are made. Cheers stay safe Tony
Hi tony,
Thanks for flagging up Springfield Properties (LON:SPR) I wasn't going to cover it, but your comment re results ahead of expectations steered me towards it. Section is up now.
Best wishes, Paul.
Hi Paul thanks for covering, SPR , stoko's figs are curently very strong . My first buys were just before the pandemic,sold out along with anything i thought might grind to a halt during lockdown.
Saw it in S.Thompson value portfolio at turn of year,decided on a wee holding again,but after the feb. figs and yesterdays have taken a decent holding again,as it more or less fits zulu selection principles. What took my eye in particular from S. Thompson's comments was the no. of plots,and their value in the accounts. I'm wandering if the sale of 200 of these ,to bigger boys,is the reason for the major drop in debt. have to await full figs.
Cheers stay safe Tony
Picking up on Simoan's note on interest rates. This is my Benson & Hedges calculation so there may be massive assumptions and errors which are all mine in creation and execution.
Assuming there are 30,000,000 people in some form of employment in the country right now.
With an average wage of £20,000 per annum.
They contribute 2% per year to DC pension fund.
That would give £1000,000,000 per month going into the market via various pension funds.
Now obviously there is a withdrawal effect of those who have retired, are buying houses, paying for their kids education, houses, holidays and all that.
This obviously ignores that a lot of folks are putting savings into the market rather than the Building Society, what is the point of telling the kids to put their £50 birthday money away for a rainy day when it is going to get 50p interest that year?
Yes a rising tide does not rise all boats, so this is probably all driving the massive wealth divide even further, but that is a subject for a separate diatribe. Just as only with a falling tide do you see who is swimming naked...
Tommy
"That would give £1,000,000,000 per month going into the market via various pension funds."
That's true, Tommy H, but which market? Just looking at a couple of reports, Schroders say "The average default DC fund of a FTSE 350 firm invests just under 67% of its total assets in developed equities, as of May 2016, with this proportion breaking down to an average of 25% of assets allocated to UK equities and 41% to global equities."
According to the EU Commission, "From an asset exposure perspective, the pension funds market in the United Kingdom is mostly invested in bonds (debt and other fixed income securities account for 63,0% of total Investments), followed by equities and other variable-yield securities that also constitute a substantial part of the investments (32,8%). Real estate investments form the remainder of the investment portfolio."
So yes, £1bn per month of new money is significant, but while we might think that UK equities would be the place to put it pension fund trustees have other ideas (and constraints).
References: https://www.schroders.com/en/s... and https://ec.europa.eu/finance/d... both PDFs. Information on withdrawals e.g. from mature DB funds is harder to come by, I haven't found any similar reports on that topic.
Whitebourne the links seem to be for Occupational Schemes only many of which will be DB, where high exposure to F.I. is required. Other than public sector schemes I think most employers have moved to Group PPs which are not classed as Occupational Schemes. I suspect a very low % of money going into DC pensions at the moment is going into Fixed Interest.
Hi Tommy H,
In June 2020 there were 5.5 million public sector workers in the UK, representing 16.7% of all people in employment.
These are likely to be better paid than average and enrolled in a pension scheme with higher than average employee contributions (my wife pays 13%!) - most of which are spent instantly by the government on current expenditure. I think the only public body scheme of significance, which purports to be a funded scheme, is the Local Government Officers scheme. My local police force, 3,000 strong, regularly reports a deficit of £3.2 billion on its "funded" pension scheme.
Pension Fund's Flight To Gilts a Tragic Farce
It is this kicking the can down the road approach that hobbles the UK economy today. Gordon Brown is not the only culprit, Kenneth Clarke is equally as guilty.
FTSE 250 - has returned an average of 11% over the past 25 years - the S&P 500 much the same and there have been two major crashes in that time frame. Why is pension fund management so difficult and highly paid? I still remember the proud boast of the Prudential actuary that once again the investment growth performance of our DB pension scheme was closer to 2.5% than 2%!
What has this to do with the SCVR you may ask? These actions taken decades ago make the UK a far less attractive place for investment today than it could and should have been, the result is higher taxes, lower pensions, poorer people (Messrs Brown & Clarke excepted).Bonitabeach
Disclosure: Lots of investments in Fund Managers.
So Boohoo (LON:BOO) buy the Debenhams brand name and website and the taxpayer picks up the pension liability via the Pension Protection Fund. Funny old world.
In 2019 CHH reported 80.8p normalised EPS. Assuming it recovers to the same level in due course, then the PER would be 21.1 times - i.e. full recovery is already fully priced-in. How does that make sense, given that full recovery hasn’t happened yet, and there are still risks?
Paul,
I appreciate what you're saying and on a daily basis I look at share price charts and PER's that show exactly the same thing, but we're being a bit over simplistic using this approach. You have to also bear in mind that interest rates have dropped from 0.75% to 0.1% in the same timeframe. So, when you take into account the equity risk premium there is a good case for the rating of equities being higher than they were 2 years ago.
All the best, Si
Hi Simoan,
You have to also bear in mind that interest rates have dropped from 0.75% to 0.1% in the same timeframe. So, when you take into account the equity risk premium there is a good case for the rating of equities being higher than they were 2 years ago.
Fair point, I see where you're coming from.
Although I would counter that by saying we now have much higher inflation expectations, and that may pull interest rates up. Personally I think the idea of central banks raising rates a lot, is probably outdated now, since policymakers seem to have bought into the whole Modern Monetary Theory (MMT) stuff, at least in deeds, if not in public pronouncements.
So could we have higher inflation, and central banks leave interest rates at rock bottom? Possibly. Although if that scenario pans out, I reckon real world interest rates would rise, as banks are not likely to want to lend at negative real interest rates in terms of what the customer actually pays.
Also, would a fall in interest rates from already extremely low 0.75% to 0.1% really have that much effect on equity valuations? It might do on a spreadsheet, but I would say that by 2019, PERs had already risen a lot due to low interest rates, so any further benefit might be quite limited?
It seems to me that we've got a lot of animal spirits in equity markets right now, and some valuations are just getting chased up too high. With Churchill China (LON:CHH) I think you can probably justify a PER of 21x peak earnings, but what I'm saying is that I don't see upside from this level to make me want to buy the share at that price, because the upside seems in the price. I'm looking to buy things where the upside is attractive, not pay a full price that already reflects the upside from an economic recovery.
Regards, paul.
Although I would counter that by saying we now have much higher inflation expectations, and that may pull interest rates up. Personally I think the idea of central banks raising rates a lot, is probably outdated now, since policymakers seem to have bought into the whole Modern Monetary Theory (MMT) stuff, at least in deeds, if not in public pronouncements.
So could we have higher inflation, and central banks leave interest rates at rock bottom? Possibly. Although if that scenario pans out, I reckon real world interest rates would rise, as banks are not likely to want to lend at negative real interest rates in terms of what the customer actually pays.
Also, would a fall in interest rates from already extremely low 0.75% to 0.1% really have that much effect on equity valuations? It might do on a spreadsheet, but I would say that by 2019, PERs had already risen a lot due to low interest rates, so any further benefit might be quite limited?
Don't get me wrong, I'm not a macro type person and I regretted making the comment on interest rates as soon as I hit the "Add Reply" button :). However, it's a factor we must take into account when comparing the current rating of equities with those of two years ago, and even very conservative investors such as Howard Marks make the same point; that as things stand equities are not especially expensive overall.
I have to keep things simple for my simpleton brain, and for me it just boils down to where do you put your money to make a return in a zero interest rate world? It's a question I ask myself every day because I'm not comfortable sitting on 30% cash (having transferred ancient pensions into SIPPs recently) and apart from a few long held bank preference shares still yielding 5.5%, the rest is invested in shares, REITS etc. To be honest, I am struggling to deploy new cash currently because when you look in the rear view mirror, nearly everything looks overpriced.
With Churchill China (LON:CHH) I think you can probably justify a PER of 21x peak earnings, but what I'm saying is that I don't see upside from this level to make me want to buy the share at that price, because the upside seems in the price. I'm looking to buy things where the upside is attractive, not pay a full price that already reflects the upside from an economic recovery.
I don't have a particular view on Churchill China (LON:CHH) and agree today's statement was not clear - I assume in-line still means a big drop down from historic profit levels and still with an uncertain outlook. FWLIW like you I'm currently only buying quality companies with strong balance sheets which have underperformed the market for no good reason i.e. just the kind of thing the Stocko ranks tell you to avoid, but then I've always been a contrarian...
All the best, Si
Hi simoan,
Don't get me wrong, I'm not a macro type person and I regretted making the comment on interest rates as soon as I hit the "Add Reply" button :). However, it's a factor we must take into account
Not at all, it was an interesting & thought-provoking comment from you. I enjoy anything that makes me think, and I imagine others do too :-)
Regards, Paul.
Good morning!
I read your comments with interest and find the feature a valuable part of Stockopedia's services. I also notice that your readers, in addition to commenting on your evaluations, suggest their own subjects of interest.
May I, therefore, make my own suggestion - Bilia AB, a Swedish multiservice car dealer? They have come out of nowhere (at least for me) and represent by far the best investment I have made these past two years. Again, thanks to Stockopedia's impressive database.
Yes but it is the UK small cap report, I don't think Paul is going to be looking at European shares, I could suggest MIPS, EUZ and Bouvet but it's not the right place.
You could start a new post about European stocks.
Quite right. My apologies for not observing the essence of this good report. Victim of my own enthusiasm. Will stick to Somero and Platinum in the future.
Hi, do you and herbie47 know a good resource for European stocks?
"Hi, do you and herbie47 know a good resource for European stocks?"
Stockopedia?
I also agree having discovered Cliq Digital whilst looking at stock ranks in the technology sector as a starting point for my research and buying last summer. Valuation still not looking demanding but sadly can't be held in an ISA.
Be careful with Cliq Digital.
From my notes:
"Is a massive scam. Check out red24mobile (it's UK subsidiary)"
I can't find any connection between red24mobile and Cliq Digital, perhaps you could provide some more information rather than "From my notes"?
Re: Cliqdigital and Red24 mobile.
I suspect abtan means to refer to red27mobile. A brief Google search will give the flavour of the potential issue.
timarr
Wholeheartedly agree, abtan. For the past four years Stockopedia, although based in Oxford and staffed by Brits, has been a precious resource for me in the search for companies throughout Europe as well as the UK.
Bilia AB
This one looks quite interesting actually. The company looks like it has some stellar metrics and certainly worthy of more research.
Thanks for sharing.
My own 2 largest non-UK holdings are West Wing and Hellofresh.
I think that both still have plenty of upside to go.
Hopefully.
A
Angle (LON:AGL) Yet more significant news from Angle. https://www.stockopedia.com/sh...
Good morning. Encouraging set of results from CNIC.
Morning Simon,
In what way are Centralnic (LON:CNIC) results "encouraging"?
I've had a quick look, it's reporting Q1 revenue $84.4m (up 48%, but it mentions acquisitions), and Operating profit of only $1.4m (down 52%). Loss after tax of $(1.4)m - 8% worse than prior year Q1.
Not encouraging enough for me to want to dig any deeper, I'm afraid.
Not sure why it reports quarterly? Maybe it has a dual listing abroad where that is required?
Regards, Paul.
Markets are made from disagreements and I am (like Simon Rowan) encouraged by progress at Centralnic (LON:CNIC) (I hold).
Too few UK companies have the ambition and grit to become major world level businesses and I admit to being positively inclined towards those that do. It is an expensive ambition and CNIC is heavily reinvesting in being an acquirer in a consolidating market. This does result in lower profits and, as primarily a software buyer, it also means a large intangible asset base, I believe that the result is shown to be worth it.
But the plan needs to quickly raise both revenue levels and operating cash to pay for its expansion and CNIC is doing both of these things. Of course this carries more risk but their high levels of recurring cash flow allows an ability tap markets and avoid being overloaded on debt , which is held to manageable levels.
The risk which worries me most is the heavy reliance on one customer (Google?) and I would like to see this addressed at their ShareSoc presentation on June 10th.
But only in line with expectations
'twould be nice to hear your views on Tekmar (LON:TGP) interim statement. Seems as though the ship has steadied: the cable wearing problem seems to have disappeared (and seems to have stimulated a new division for the company): the new FD sounds OK: generally it seems a good, confident statement
Tekmar (LON:TGP) again - really disappointing start, despite solid buys - guess Schroders must be selling down more of their 16% holding
I held Tekmar for a while - i believe i came across the company when looking at Lord Lee's interest discolure on the parliament website for inspiration (no longer on there now?). Turns out to have be my worst investment ever - having first suffered a delayed contract and then this problem with the cabling (to do with installation of cable, so not even TGP fault, but the SP has suffered terribly).
Turns out i dont have the stomach for such a high risk business. as the saying goes, when it rains it pours... and bad things come in threes. guess i need to consider myself superstitious, because i kept thinking what could possibly go wrong next? in the end was happy to take a loss simply to stop thinking about it haha.
best of luck to everyone still holding this one!
Andy
Lord Lee's interests are still on the parliamentary website, as they are required to be.
Hi sheeza,
Sorry I didn't get round to looking at Tekmar (LON:TGP)
It's so small & illiquid that I decided to focus on bigger stuff that people can actually trade if they want to.
Regards, Paul.
My morning smallcap tweet:
M&C Saatchi (LON:SAA) Ten Lifestyle (LON:TENG) Avacta (LON:AVCT) Sareum Holdings (LON:SAR) Zaim Credit Systems (LON:ZAIM) Sensyne Health (LON:SENS) Immotion (LON:IMMO) Hyve (LON:HYVE) Scholium (LON:SCHO) National World (LON:NWOR) Avingtrans (LON:AVG) Coral Products (LON:CRU), OTAQ (LON:OTAQ), Churchill China (LON:CHH)
M&C Saatchi (SAA) guides FY ahead of consensus expectations after strong first 4 months. Also increased 3 year bank financing. [SP=128 Cap=156m]
Ten Lifestyle (TENG) client contract increased to Medium contract, with the potential to develop into Large. Also launch of new concierge programmes with a Scandinavian bank and a Fintech card product under an existing Medium contract. No material impact on H2 though. [SP=109 Cap=89m]
Avacta (AVCT) confirms rumour of error (by partner Mologic) in CE mark submission for professional use of rapid covid test. Does not expect that the error will cause a delay to first commercial sales. However the test referenced in a social media post was an unrelated Mologic covid test. [SP=236 Cap=598m]. I'm short.
Sareum (SAR) £900k subscription at 2.8p, a 8% premium, to progress SDC-1801 TYK2/JAK1 inhibitor drug development and to keep the lights on. [SP=2.56 Cap=85m]
Zaim Credit Systems (ZAIM) hails strong Q1 with loans issued up 34% on Q4. In line? "Focus of the Group is now to maximise growth and customer numbers over profitability and gain as much market share as possible over the near term." [SP=4.35 Cap=19m]
Sensyne Health (SENS) UK Gov't contract to use MagnifEye AI technology for reading COVID rapid tests. "Phased national roll-out over a three-month period in care homes, GP practices and selected private sector organisations with large workforces." [SP=151 Cap=249m]
Immotion (IMMO) all Covid related capacity restrictions lifted in Las Vegas, home to co's largest location-based installation. Also continues to see revenues recover strongly at Location-based Entertainment sites. [SP=5.65 Cap=23m]
Hyve (HYVE) confirms rumour of placing/funding talks. "Board will prioritise minimal dilution to existing shareholders as well as the optionality to move quickly as earnings accretive acquisition opportunities arise." [SP=131.4 Cap=348m]
Scholium (SCHO) guides H2(Mar) loss marginally lower than H1. Expects H1 loss too. [SP=30 Cap=5m]
National World (NWOR) after a superior torrent of MBA BS ('Delayering and flattening management structures'..commercially homogeneous markets ...leveraging existing Group resources') it finally says trading is in line. [SP=22 Cap=57m]
Avingtrans (AVG) second phase of the contract to provide high integrity stainless steel storage boxes for Sellafield, 'underpins' outlook for FY22 and beyond. [SP=330 Cap=106m]
Coral Products (CRU) guides FY(Apr) rev-cont at least £10.7m, up 23%, pretax £3m (-£0.8m). Current year in line. [SP=13.85 Cap=12m]
In line: OTAQ (LON:OTAQ) Churchill China (LON:CHH)