Small Cap Value Report (Tue 1 Oct 2024) - GRG, PEEL, JHD, EAH, RNWH, WRKS

Good morning from Paul & Graham!
Explanatory notes -
A quick reminder that we don’t recommend any shares. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech, investment cos). Although if something is newsworthy and interesting, we'll try to comment on it. Please bear in mind the "list of companies reporting" is precisely that - it's not a to do list. We typically cover c.5 companies per day, with a particular emphasis on under/over expectations updates, and we follow the "most viewed" list of readers, so if you're collectively interested in a company, we'll try to cover it. Obviously with the resources available, we can't cover everything! Add you own comments if you see something interesting, and feel free to discuss anything shares-related in the comments.
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to, if they are using unthreaded viewing of comments.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. And/or it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Others: PINK = takeover approach, BLACK = profit warning, GREY = possible de-listing.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom), Video update of results so far, June 2024.
** New SCVR summary spreadsheet for calendar 2024 ** This is the live one! (updated 6/9/2024)
Archive - SCVR summary spreadsheet for calendar 2023.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Phil Hanson's data analysis measuring performance of our colour-coding system in the SCVRs, from July 2023- Mar 2024 (with live prices). My video explaining/reviewing it.
My other video (June 2024) - How to screen for broker upgrades on Stockopedia. More stock screening strategies here (possible bargains?) - 21/9/2024.
Companies Reporting
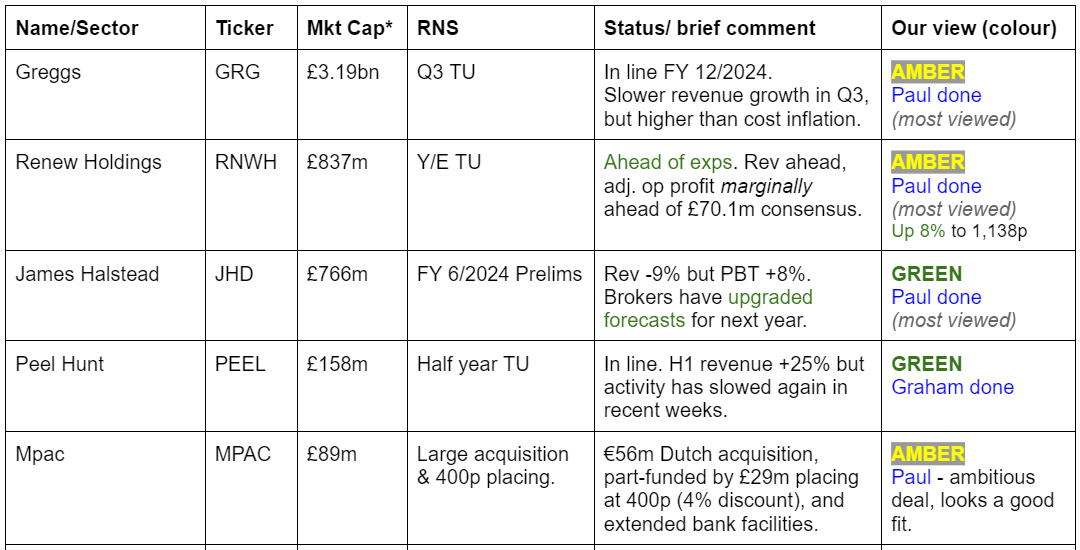
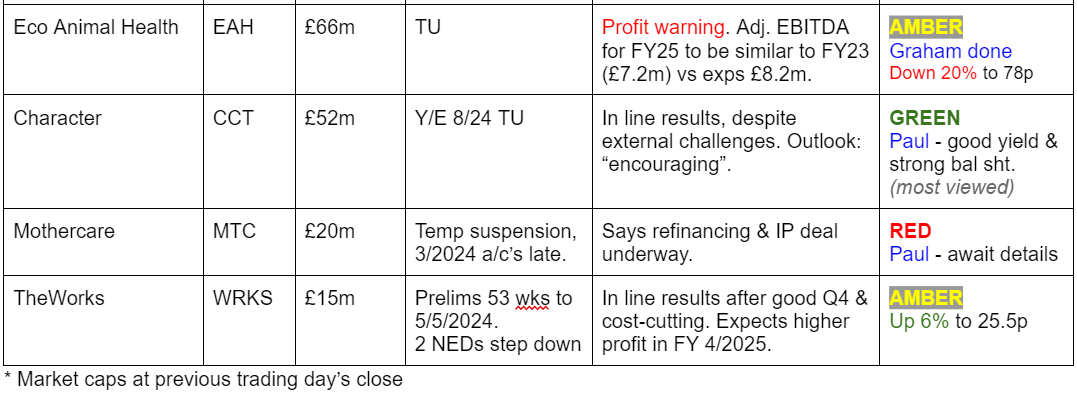
Summaries
Greggs (LON:GRG) - Down 5% to 2,870p at 08:13 (£3.03bn) - Q3 Trading Update - Paul - AMBER
Revenue growth slowed in Q3, but is still good. Maybe that's to be expected as inflation moderates? Profit expectations are in line for FY 12/2024. Is "in line" good enough when shares are on a punchy 21.6x forward earnings? Lovely company, but shares look fully priced.
Peel Hunt (LON:PEEL) - down 1% to 127p (£160m) - Half Year Trading Update - Graham - GREEN
It’s an “in line” update, although investors may be discouraged to learn that a recovery in activity has been followed by a slowdown (blamed on the UK budget and US election). I’m patiently staying positive on this for now, hoping for a recovery, but my patience won’t last indefinitely.
James Halstead (LON:JHD) - up 1% to 178p (£774m) - Audited Results FY 6/2024 - Paul - GREEN
I'm moving back up from amber to GREEN, as these numbers demonstrate a strong & resilient business with good margins, lovely balance sheet, and a reliable 5% dividend yield. The PER isn't exactly a bargain, but overall this looks a reasonably entry point into a business with a long & good track record. Cyclical upside could stimulate a share price recovery perhaps?
ECO Animal Health (LON:EAH) - down 22% to 76p (£57m) - Trading Update - Graham - AMBER
A disappointing update as this animal pharma company once again suffers from weaker demand in China than had been baked into forecasts. This track record of profit warnings here shakes my confidence, but I’m happy to stay neutral on the basis that the company’s R&D programme has the potential to produce a higher-quality product portfolio.
Renew Holdings (LON:RNWH) - up 8% to 1,138p (£899m) - Year End Trading Update - Paul - AMBER
"Marginally ahead" of profit expectations for FY 9/2024 doesn't really justify an 8% share price rise, on top of a very strong run since last autumn. RNWH has a strong order book, but nothing in assets overall on its balance sheet. I recognise its amazingly good track record, but feel valuation is now at the top end of reasonable, so have shifted down from amber/green to AMBER.
Works co uk (LON:WRKS) - up 6% to 25.5p (£16m) - Prelims 53 wks to 5 May 2024 - Paul - AMBER
Despite tough conditions, it managed to end the year in line with expectations, and reckons it can improve profits in FY 4/2025. I think this is a very marginal business, but am impressed it has survived. The balance sheet actually looks OK, once you strip out IFRS 16 entries. Doesn't appeal to me, but AMBER seems fair for now. I have little confidence it will be a good long-term investment, but there might be a trade here for a bounce, if it has a good Xmas maybe?
Paul’s Section:
Renew Holdings (LON:RNWH)
Up 8% to 1,138p (£899m) - Year End Trading Update - Paul - AMBER
Renew (AIM: RNWH), the leading Engineering Services Group supporting the maintenance and renewal of critical UK infrastructure, provides the following trading update for the financial year ended 30 September 2024.
A positive headline today has propelled RNWH shares to what looks like an all-time high -
“Strong organic growth resulting in financial performance ahead of market consensus with continued momentum into FY25”
This is then moderated by saying operating profit is “marginally ahead”, and a helpful footnote to tell us what consensus is -
“1Company derived consensus for adjusted revenue is £1,081.0m, adjusted operating profit of £70.1m and pre-IFRS 16 net cash of £22.1m.”
Broker updates - none available to us. Stockopedia has 65.7p consensus, so marginally ahead suggests c.67p perhaps? That gives a punchy (for the sector) PER of 17.0x. I wouldn’t pay that for a contracting business, but you might be tempted, given RNWH’s superb long-term multi-bagging track record.
Talking about acquisitions, this seems to have been the secret of RNWH’s success - it has done lots of acquisitions over the years, and they have clearly added value.
Balance sheet - next to nothing, with NTAV only £14m at 31/3/2024, so you don’t have any support here from assets. The business is funded by its trade & other creditors, rather than equity. That seems to be an ongoing (and positive) thing, since finance costs on the previous P&L statements were minimal. This is why, despite a fairly low operating margin of about 6%, RNWH delivers high ROCE and ROE, since it’s figured out how to get creditors to fund the business!
Investors like high ROCE, but it’s worth pointing out that this also increases the risks, since there’s no surplus capital to fall back on if things go badly wrong. A good example of that recently was Headlam (LON:HEAD), where despite awful performance, it’s not in any danger due to having loads of surplus capital. Whereas companies with “efficient” balance sheets can get into serious or even terminal trouble, if they run into major, unexpected problems, and have no surplus capital to fall back on. My view on this might be unpopular and old-fashioned, but it makes sense to me - finding good companies where there’s also a ton of free stuff sitting on the balance sheet, if that value can be unlocked in some way. But each to their own. For the avoidance of doubt, I'm definitely not saying HEAD is a good company! It looks a mess actually, as covered here recently (yesterday).
Like a lot of companies with weak balance sheets, RNWH management like to pretend it’s strong, instead of admitting what we can all see - that it’s got next to nothing in net tangible assets, but doesn’t actually need any assets to generate a great return, which is actually a stronger message than pretending that weak is strong. So I think they should rethink their communications on this issue -
“The Company's balance sheet continues to be strong with net cash at 30 September 2024 anticipated to be ahead of market expectations.1
...pre-IFRS 16 net cash of £22.1m.
Outlook - sounds good -
“momentum into the new financial year is underpinned by a robust order book which benefits from the UK's committed infrastructure spending programmes and to client's long-term operating budgets.”
Paul’s opinion - as always, kudos to RNWH management, which has built an excellent business in an often horrible sector. This share has been all about raising margins over the years from originally only about 1%, to now 6-7%, together with multiple acquisitions plus organic growth. It’s been stunningly successful, as you can see -
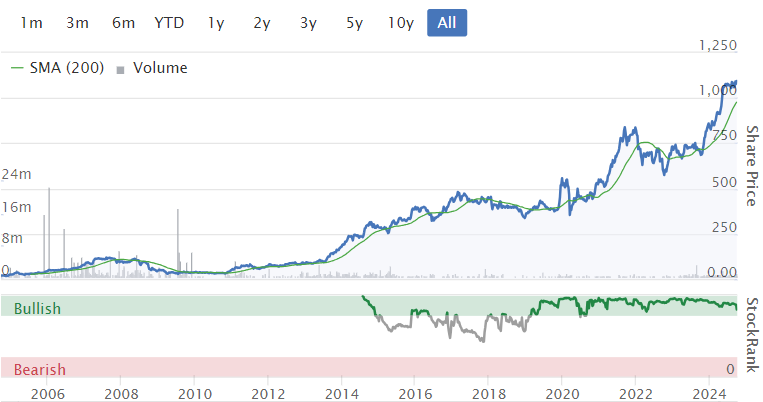
RNWH has delivered amazing shareholder value, usually in quite concentrated bursts upwards (like the one we’ve just had in the last year), then treads water for typically 2-3 years. For that reason I’m not really interested in joining the party this late on, so it can’t be higher than AMBER for me personally, because I don’t see how there can be much short term upside on the share price at this valuation (c.15x fwd PER).
Longer term, RNWH has been a big winner, so there’s also a strong argument for just holding it forever, which has worked great so far! Lots of other contracting businesses have re-rated strongly this year too, but sit at much lower PERs than RNWH, some having much better balance sheets than RNWH too (although sometimes with legacy issues too). There’s a limit to how highly we can value contracting businesses, and for me 15x PER is the limit, which is where RNWH sits currently.
James Halstead (LON:JHD)
Up 1% to 178p (£774m) - Audited Results FY 6/2024 - Paul - GREEN
James Halstead plc, the AIM listed manufacturer and international distributor of commercial flooring, announces its results for the year ended 30 June 2024:
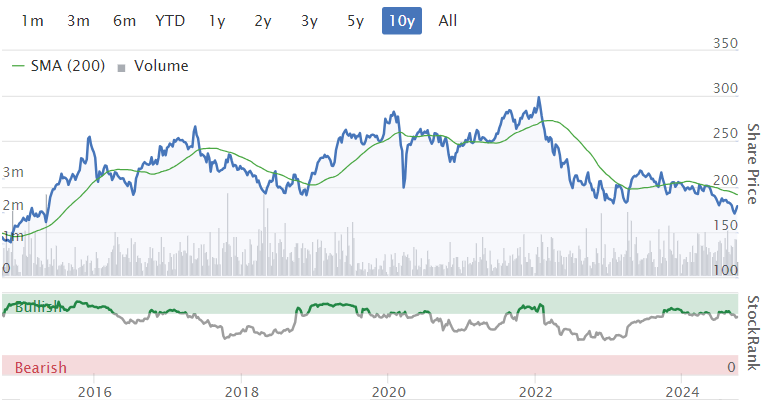
JHD has an excellent very long-term track record, but its shares became over-valued I think, and have actually gone nowhere for the last 9 years (although paying good divis along the way, to be fair) -
What a lovely progression of divis here -
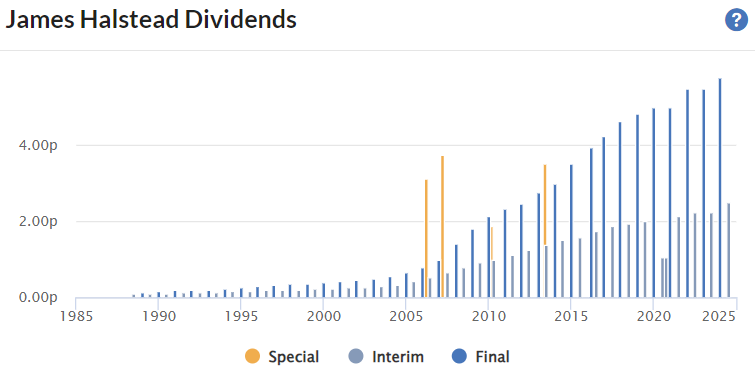
The current forecast divi yield is 4.94%, so given the company’s outstanding long-term track record for looking after its shareholders with growing divis, it’s almost worth just buying some shares for the long-term on this point alone. It pays out almost all earnings as divis.
Checking my previous notes, I was GREEN at 201p on 31/1/2024 with a positive TU, and forecasts that looked too low set to be beaten.
More recently on 2/8/2024 I shifted down to AMBER (on reflection maybe a mistake?) at 191p, with me worrying that PER of 19x looked too high for a company that seemed to be going ex-growth.
On to today, we have FY 6/2024 results (discussed earlier in the reader comments below). Key points -
Revenue down 9% to £275m
Gross margin saved the day, up impressively from 38% (FY 6/2023) to 44%
Profit before tax up 8% to £56.2m
Higher tax rate caused EPS to fall slightly, down 2% to 10.0p - PER 17.8x
Dividend - 2.5p interim already paid, final 6.0p proposed (up 4.3% vsLY), so again almost all earnings are paid out in divis (total 8.5p) -
“Our proposed dividend continues our unbroken chain of dividend payment increases from 1974.”
Outlook - a bit vague, but sounds positive -
“Prospects continue to look positive giving the board confidence in the outturn for the financial year ahead…”
I like this bit, which suggests there could be opportunities to grow further, globally, which may address my concern about it previously looking ex-growth -

“During the year we have secured many prestigious projects around the world, demonstrating the continued demand for our high quality offering on a global scale.”
It doesn't seem to provide numbers on order book, pipeline, etc, unless I missed it.
Balance sheet - looks superb, with NAV of £181m, or NTAV £178m. This includes £74m of net cash, which I would say is pretty much all surplus to requirements, as net current assets are £142m overall - ie inventories + receivables far exceed all creditors, with the cash sitting on top of that. I would say that £82m inventories looks far too high, being over half the £154m full year’s cost of sales on the P&L. Does it really need over 6 months sales’ in inventories? Maybe it has stocked up to get around supply chain delays, but it needs to be questioned. I would have expected to see inventories maybe half that level, so about £40m in capital looks tied up in excess inventories. That might be a problem, but at this type of family run, conservative company, the accounting is usually prudent & we rarely have to worry about black holes in the books.
Cashflow statement - looks very good. It strikes me that JHD generates a lot of genuine cashflow, on a fairly lean fixed asset base, so it’s not as capital-intensive as I would have thought. Capex is only about £3m pa, which seems low considering the commentary talks a lot about having the latest equipment, and being efficient.
Dividends stand out as the massive number (compared with everything else) on the cashflow statement. So this is quite an unusual setup - a business that throws off prodigious cashflows, and doesn’t really need it for anything else, so it almost all gets paid out as divis. I like that business model a lot!
Paul’s opinion - it’s quickly become obvious to me that I made a mistake lowering JHD from green to amber in Aug 2024. So I’m going back up to GREEN today- this is a cracking business, and it sounds like its markets should return to growth as macro improves around the world. It stands to reason that capital projects which typically use JHD specialist floorcoverings might have been curtailed due to higher interest rates, pandemic disruption, etc. So the more I think about it, the resilient performance of JHD in recent years is all the more impressive, with cyclical macro factors suppressing its growth, rather than the business having gone ex-growth structurally.
Zeus has slightly raised forecast for FY 6/2025, from 10.2p to 10.5p, mainly due to plugging higher gross margins into its spreadsheet, given the strong FY 6/2024 gross margin.
Overall then, I think this looks a good quality business, at a fair price. Not a bargain, but worth the price, and it could rise over the next few years if demand improves with the economic cycle. Bulletproof balance sheet, and a c.5% dividend yield are further attractions.
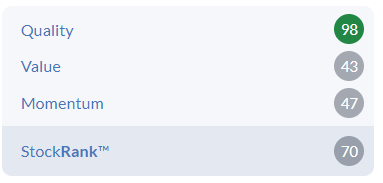
Upper-middling StockRank -
Greggs (LON:GRG)
Down 5% to 2,870p at 08:13 (£3.03bn) - Q3 Trading Update - Paul - AMBER
This share is top of your "most viewed" list, so I thought we should give a view early.
Bakery & fast food chain, now trading from 2,559 shops (2,016 company, 543 franchised).
Impressive speed of reporting Q3 trading, given that the quarter only ended yesterday.
It’s in line with expectations for FY 12/2024.
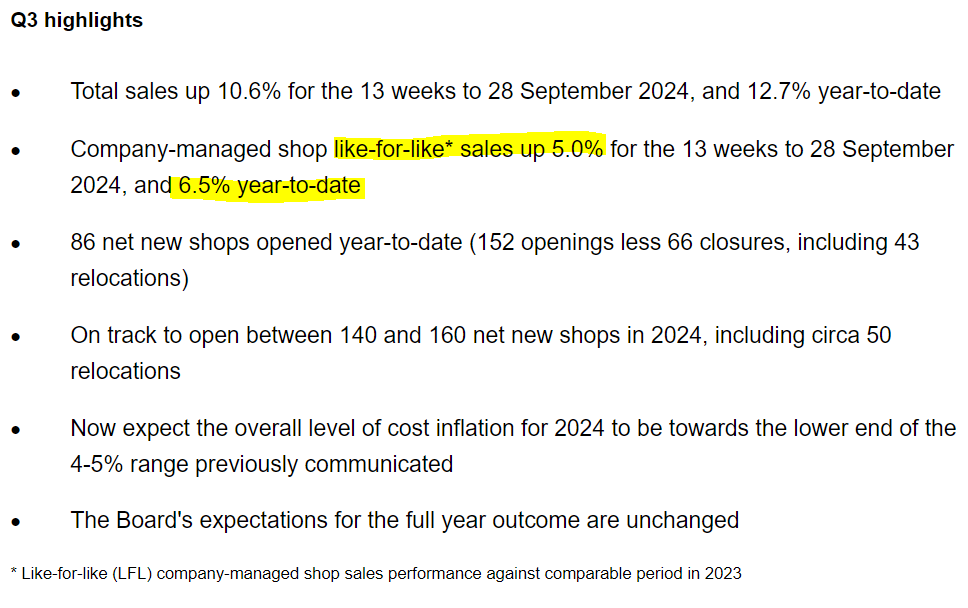
Q3 LfL sales growth has slowed to 5.0%, but is still above cost inflation (guided at c.4%) -
The commentary today talks about its continuous product innovation, which is great I think. Funnily enough I bought a chicken slice (delicious) from the new, much larger, relocated Greggs in Bournemouth yesterday. I was drawn in by a sign advertising “Katsu Chicken Slices” which sound lovely, but they had sold out. So that demonstrates product innovation does pull people into the store. Plus few people would argue that it’s the best value fast food outlet on the High Street. A bit like the Wetherspoons (I hold) of the fast food sector. I’m looking forward to trying the new “All-Day Breakfast Baguette”.
Outlook -
“Whilst acknowledging ongoing economic uncertainty, the Board expects the full year outcome to be in line with its previous expectations. The Board remains confident in the long-term growth opportunity for Greggs, and we are investing to support that growth.”
Is that enough to keep the bulls interested, given that GRG shares have had a good strong run, and are now priced on a full multiple of 21.6x forward PER?
Shares were down 5% in early trades.
The dividend yield is only 2.3%, because it’s in a heavy capex phase.
Paul’s opinion - Greggs is an excellent business, and still expanding with new, and larger sites. Although at c.£2bn revenues, and with probably many/most UK locations now already having a Greggs, the % growth rate is only c.10%. Is it better to invest in something smaller, but with more exciting roll-out potential maybe? Or go with Greggs, which dominates its space with decent quality, and value for money offering?
I’d be interested to know what the shoplifting rate is like, as I’ve seen plenty of times how the dishevelled of Bournemouth brazenly help themselves to free food & drinks, with no consequences. Many shops are reporting a shoplifting epidemic, so that would be an interesting question to ask GRG management if they do a webinar, as it could be a significant hidden cost.
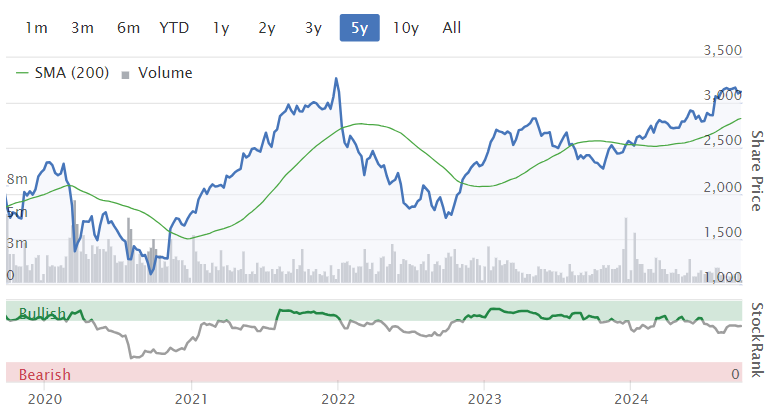
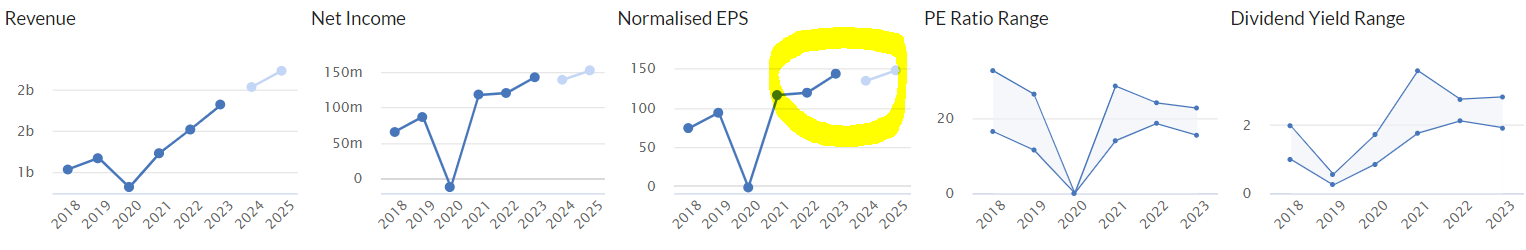
There’s no doubt GRG is an impressive business, but I’d only want to buy its shares if the price was say 15-17x PER. At almost 22x, with fairly unexciting EPS growth in the last 3 years, I can’t see much of a value opportunity right now. It’s a good share to have on a watchlist though, as when something bad happens to macro/markets, any plunge in this share is usually a buying opportunity. But personally I wouldn’t want to buy right at the top of this 5-year chart -
Works co uk (LON:WRKS)
Up 6% to 25.5p (£16m) - Prelims 53 wks to 5 May 2024 - Paul - AMBER
I was expecting to write off this crafts & books retailer as a lost cause, but the numbers are not as bad as I expected.
The trouble is, revenue growth is elusive, with only +1% to £283m in FY 4/2024, and negligible +0.2% in the first 21 weeks of FY 4/2025.
It’s still profitable though at £3.2m adj PBT (down from £5.3m LY).
Note that the adjustments to profit are stripping out (artificial) profit from writing back previously booked losses on leases. The curse of IFRS 16 strikes again. It’s really good that WRKS adjust out these artificial profits though, showing the true, lower profit as the adjusted profit.
Is it likely to go bust? Well actually the balance sheet isn’t bad. NAV is £10.1m, including intangible assets of £1.9m, so that’s £8.2m NTAV. However, there are also heavy lease net liabilities on there - £57.7m RoU assets, less £77.8m lease liabilities, nets off to a -£20.1m deficit. This can be eliminated I think as IFRS 16 entries are nonsense, so that would adjust the NTAV up to a surprisingly healthy £28.3m.
Just looking working capital shows the reality, and this is £42.9m current assets (including £1.6m cash), mainly made up of £31.4m inventories, less £31m total creditors (excl leases). Hence a useful surplus of c.£12m in working capital. What does that mean? If they can keep turning the inventories quickly, then the business should generate enough cash to keep paying its creditors in an orderly fashion. So I see currently little insolvency risk, unless trading were to deteriorate a lot further - which we sometimes see happen at this type of business.
WRKS reckons that 96% of its 511 stores are profitable, which doesn’t sound credible to me, given that it has a thumping great deficit on the balance sheet lease entries (implying some fairly significant loss-making sites).
Outlook sounds fairly upbeat -
“Strong product margin growth and cost savings are being delivered, more than offsetting ongoing cost headwinds. As such, we remain on track to deliver improved profitability in FY25 and meet Group compiled market forecasts of pre-IFRS16 Adjusted EBITDA of £8.5m.”
Paul’s view - I was expecting to mark this as red or amber/red, as it seems such a marginal business that has done well to just survive. However, its numbers are far from disastrous, and I think it could tick along and survive for maybe a few more years? Is it going to suddenly turn into a great business? I very much doubt it. It’s dependent on people getting out into the High Streets again, and not nicking everything on display. So an improvement in consumer sentiment as real incomes have now become positive again, could help WRKS maybe. It says that things are “well-positioned” for the busy Xmas period.
Good luck to them, I am impressed that The Works has survived the last few years, when so many other smaller retailers have gone bust, some several times. £16m market cap looks cheap, especially if you value companies on EBITDA multiples. But for me, it has little to no appeal. I’ve invested in so many struggling, smaller retailers in the past, and they hardly ever work out to be good investments. So good luck to holders here, you could have a nice short-term trade on your hands if it reports strong Xmas performance.
I do mystery shop my local Works branch occasionally, and always come out with something, some pads or pens, or a book - the prices are attractive. But as a long-term investment I doubt WRKS shares will do well.
I see that 6.2% shareholder Kelso had 2 NEDs on the Board helping to advise management, but they’ve both stepped down today. Aside from the warm words in the RNS, it would be nice to know the real reasons! Maybe it was a question of committing the time to a holding worth only £1m? Or maybe they’ve decided to move on and sell their position, I don’t know.
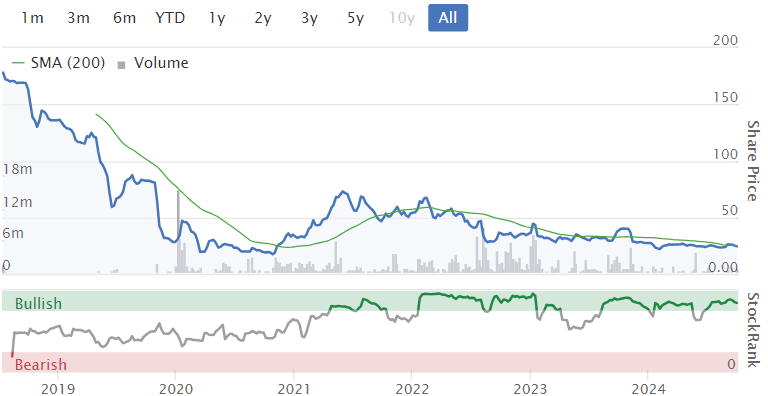
This was an over-priced float in July 2018 that started going wrong almost immediately & has never recovered -
Graham’s Section:
Peel Hunt (LON:PEEL)
Down 1% to 127p (£160m) - Half Year Trading Update - Graham - GREEN
This is a brief H1 update to the end of September.
Key bullet points:
H1 revenue £53.3m, up 25%.
Investment banking: improved performance as PEEL worked on a main market IPO and an AIM IPO.
Research & Distribution: revenues “modestly up… despite continued outflows from UK equities”.
Execution: trading activity was up, but has slowed in recent weeks in advance of the UK Budget and US election.
When it comes to strategic progress, PEEL says that it has made “targeted investment in talent” and notes that the average market cap of its retained client base has increased from £620m to £860m. This is thanks to client wins and the growth in market cap of existing clients. It now has 4 FTSE 100 clients and 42 FTSE 250 clients.
Outlook is in line:
Market activity has slowed again in recent weeks ahead of the upcoming Budget and US election. Consequently, despite better first half revenues, we expect full year performance to be in line with market expectations and we remain well positioned across all parts of our business to take advantage of increased activity when market confidence returns.
Graham’s view
I put this on my best ideas list for 2024, banking on a return to health in the UK equity market.
An important feature of this stock is its balance sheet strength, covering most of the market cap.
Full-year results to March 2024 showed balance sheet net assets of £92m, including cash of £38m, with very few intangibles (less than £2m) and the vast majority of its assets being equivalent to cash.
However, the company did post a small loss and I’m not convinced that FY25 will have much to cheer about in terms of profitability.
Finding sell-side estimates of PEEL’s financial results is tricky, however. That’s hardly a surprise since PEEL doesn’t make its own research widely available to investors. If you’re want forecasts for PEEL, you’ll want to get in touch with Nomad Grant Thornton or broker Keefe, Bruyette & Woods
My inclination is to leave my GREEN stance unchanged here. There could come a point when I need to throw in the towel and downgrade to AMBER or AMBER/GREEN, if there is still no sign of a meaningful resurgence in activity, although I haven’t yet decided when that might be.
Today’s update is a little disappointing, in the sense that green shoots of recovery were followed quickly by another slowdown. But who knows, maybe after the budget and the US election, a more sustained pickup might emerge?
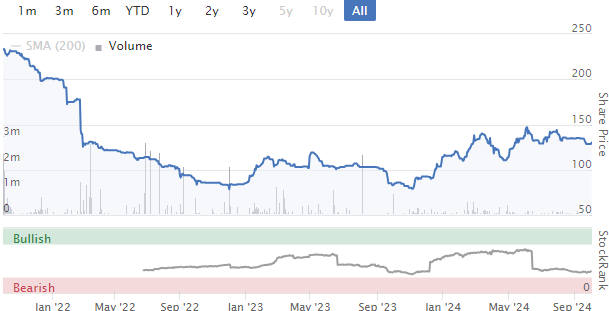
These shares continue to trade at a 40%+ discount to the price at which they were offered to the market in 2021:
ECO Animal Health (LON:EAH)
Down 22% to 76p (£57m) - Trading Update - Graham - AMBER
ECO Animal Health Group plc (AIM: EAH), a rapidly growing global animal health company with a portfolio of marketed veterinary products and a maturing proprietary R&D pipeline, today announces an update on its trading for the six months ending 30 September 2024.
This update starts positively but quickly goes downhill.
Aivlosin® is “a proprietary, patented medication which is effective against both respiratory and enteric diseases in pigs and poultry”.
This prescription medicine has gained market share for EAH in Brazil, India and the US. Revenues in Brazil and India are ahead of expectations. These markets are expected to remain strong in H2 and Aivlosin will also enter Paraguay, having received regulatory approval there.
That’s most of the good news out of the way. And now for the bad news:
We are however, encountering challenges in China, due to low disease incidence in the summer months, and in Southeast Asia, where sales have slowed reflecting some customer churn.
The ECO Group is second half weighted and this pattern will continue in FY 2025. Nevertheless, the recent challenges we've faced in China and Southeast Asia lead us to believe that revenue for the full year will be materially below market expectations.
Adj. EBITDA for FY March 2025 is therefore likely to be “in the region of that observed in FY23”, i.e. around £7.2m.
New estimates: thanks to Equity Development for publishing on EAH this morning. Their new revenue estimate is £84.3m (last year: £89.4m, previous consensus estimate: £92.6m).
The new adj. EBITDA estimate, as indicated in today’s announcement, is £7.2m (last year: £8m, previous consensus estimate: £8.2m).
Graham’s view
We don’t cover this one particularly often. I was neutral on it back in March 2023, pointing to poor EPS estimates momentum and a high earnings multiple.
Today it seems as if little has changed.
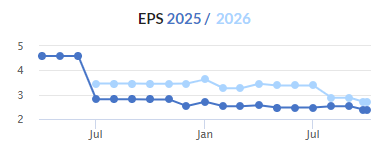
EPS momentum before today’s downgrade. After today's downgrade, it won't look any better:
The share price is down by a third since I last covered it, but the stock is still unable to offer a normal earnings multiple:
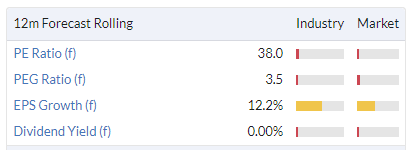
The company had a £22m cash balance at March 2024, but only £8m of this was held outside of China and the directors said that they considered ”the cash held in the Group's joint venture subsidiary in China to be unavailable to the Group outside of China”. So while I accept that the company is able to self-fund its R&D, I think it would be a stretch to say that EAH is cash-rich or has a large surplus of cash. That largely depends on how much it could extract from its Chinese JV.
According to last year’s income statement, it spent £4m on R&D that year. It spent nearly £6m the prior year. This says to me that the non-Chinese cash balance might not survive several years of heavy R&D spend, without support from profits from existing or new products.
Once again I find myself leaning towards a neutral view on this stock. Its current earnings aren’t able to justify the market cap but it does have an R&D programme with new medicines hopefully coming on stream in due course. The current product set is not producing the most reliable results but is at least performing well in some geographies.
I can see both sides of the argument here, and AMBER once again seems to be the fairest stance.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

74 comments
Any thoughts anyone where the bottom is for Gulf Marine Services (LON:GMS)?
I liked what the board did on Sep 12 and I read it as an upgrade on the way: "As for our guidance for 2025, we are in the process of revisiting it and shall share it with you in the next couple of months".
Since then, the price has softened even more. The tide has to turn sooner or later doesn't it?
Any thoughts anyone where the bottom is for Gulf Marine Services (LON:GMS)?
How do you discount for war on their patch? It’s a complete unknown right now
Sorry im not that familiar with the company's operations, how do you mean on their patch?
Sorry im not that familiar with the company's operations, how do you mean on their patch?
The clue is in the name
Bicycle Industry woes continue
Another top UK brand / distributor bikes the dust
I-ride who have the Orro brand and. Fulcrum wheel business .
They made a big investnent during covid into new warehouse banking on increased sales lifted the overhead and added debt , then when demand dipped game over .
Big read across to tandem very similar story though they have the luxury of owning their big warehouse they cant fill .
Have to say bicycle market is still a good sector on a. 5-10 year timing but still 1-2 years of pain .
I have noticed a few green shoots and whilst bicycle sales are terrible there is a good thriving market in consumables which I guess is a small dopamine hit if you are a member of the bicycle fetish club .
Saga (LON:SAGA)
Delay to publication of H1 2024 results
Saga plc continues to explore partnership opportunities to support the Group's capital-light growth ambitions, crystallise value and enhance long-term returns for shareholders.
While this process remains ongoing, the Group today announces that it is delaying its half year results, which were due to be published on 2 October 2024. The results will be announced at the earliest possible opportunity. Saga confirms that performance for the first half is in line with expectations and the Group remains on track for the full year.
Wait for the inevitable SKY scoop then!
Saga (LON:SAGA)
normally a delay would be bad news - but price has been creeping up recently so it kinda suggests to me there might be material news in the offing so reasonable reason for delay?
my idle speculation and that speculation is copied and pasted fromn the other place.
over to sky news first to report odds 5/6 ten hag sacked 5/6 something or material interest ref saga. which is your money on happening first ?
And here it is from SKY:
Exclusive: Saga, the over-50s travel and finance specialist, is in advanced talks with Ageas, the Belgian insurer which abandoned a bid for Direct Line this year, about a deal for its insurance arm that will allow it to pay down a chunk of its huge debt pile. Full story up soon.
As its a dreary day, we all need a laugh.
National World
Incredibly tight spread buy at 15.1 sell at 15.06 and lots of stock available .
Quite unusual normally a wide spread and moves on no volune
Despite my distaste for David Montgomery who clearly sees it as his “vehicle” have been buying quite a few .
Im relying on the fact a more savvy shareholder base imcluding Rockwood and Dowgate will put a stop to a cow milking boot filling mentality .
Deep value territory on offer albeit in a clearly declining market but it has tons of cash and is a cash making machine . In 4/5 years will have generated its entire market cap in cash .
The value should come through at some point and rerate guess ill just need to love the great leader Monthomery and his vehicle albeit as a backseat passenger with no control of the guy in the front .
Iran launching ballistic missiles to Israel. Hence, the change in market sentiment. Bloomberg live reporting right now Israel preparing defence.
MPAC (LON:MPAC) - "Major acquisition and equity raise. Fair Value raised to 865p" - link to new research report: https://www.equitydevelopment....
Mpac has announced an offer to acquire CSi Palletising, a specialist in the design, manufacture and installation of end-of-line automation and palletising solutions, for a maximum consideration of €56.0m (£50.0m).
Subject to approval at a General Meeting, the acquisition will be financed through the issue of equity to raise up to £30.0m (gross) at 400p per share, and drawdown from Mpac’s debt facilities.
The addition of CSi continues Mpac’s track record of growth augmented by major acquisitions; we estimate that by FY26 the Group will have achieved its 5-year goal of doubling FY23 revenue and profit, ahead of plan.
Upon completion, the deal will be significantly earnings accretive, with our revenue and adj. EBITDA estimates for FY25 and FY26 all rising by at least 40%. Accordingly, we materially raise our Fair Value per share to 865p (from 550p).
MPAC (LON:MPAC)
Thanks equity development as a small shareholder your efforts in providing us with detailed company information is most appreciated - shame every listed company doesnt utilise your services - i do like to see forecasts into the future so we have clear yardstick by which we can judge managment - and see how numbers are chaging over time.
Looks like the narrative company from the company here is uber positive in that there is an expectation that "adjusted pre tax profits" in 2026 will be up to £21.7 million - so certainly no lack of ambition being shown here with what management think they can deliver for shareholders. If they generate that level of sustainable profit without further dilution i think we would all agree it will be job wel dolen by management.
Lets hope for shareholders they deliver. I have bought a small positioin here pre this news recently - i am 100% on the fence ref the acquisition - the reality is plans for global domination dont always work lets hope they do succeed ref the numbers they expect to deliver come 2026 !!
Note one minor confirmation ialluded too in my prior post was the sketchyness of the earnings boost being accretive - equity developments seem to be confiming it will not be EPS accretive till 2026 at the earliest - so no immediate bang for your buck that one would like to see with complimentary acquisitions - it is about the long game though in business!
The terms of the acquisition indicate an undemanding 7.6x (adj.)EBITDA multiple, with EPS accretive from FY26
MTC Is that thing still in business? Go figure.
I would say that £82m inventories looks far too high, being over half the £154m full year’s cost of sales on the P&L. Does it really need over 6 months sales’ in inventories? Maybe it has stocked up to get around supply chain delays, but it needs to be questioned. I would have expected to see inventories maybe half that level, so about £40m in capital looks tied up in excess inventories.
Paul,
I've just checked and it seems James Halstead (LON:JHD) always have roughly this ratio of inventories to cost of sales. So this looks normal for the company, and perhaps is just a factor of manufacturing in the UK and holding stock at various locations around the world. Chart below going back to 2010:
All the best, Si
Bank of Cyprus Holdings (CSE:BOCH) Hi, I don't know if anyone else has been caught out by this but BOCH recently delisted from the LSE in order to list on the CSE(Cyprus stock exchange). My current ISA provider won't allow trading on the CSE and I have been contacting other brokers to see if I can transfer the stock to them and trade. I cannot seem to find a broker who will allow me to do this under the ISA wrapper. Of course I should have sold them before the delisting but took my eye off the ball! Anyone know of a broker I could use?
Bank of Cyprus Holdings (CSE:BOCH)
Listed on the Athens Stock Exchange instead and I have written about this as I found it very important that a Cypriot Bank has opted to leave the UK market for liquidity purposes!!
The listing on the Cyprus one was always there.
If you call Eurobank in Greece they will help you out.
Don’t know if I am allowed to give names and phone numbers here to help you further.
All the best
PS You can post your email if you need further assistance.
Bank of Cyprus Holdings (CSE:BOCH) Many thanks yiannos1, I'll do as you suggest. stevejohnsondoc@gmail.com
Docj, hope you’re able to sort this out. I had no idea about delisting but recently sold Bank of Cyprus Holdings (CSE:BOCH) because I missed purchasing at a pound a share and watched it raise to 350 attempting to get on board with no luck. And now they have delisted…
As ever, Paul’s thoughts on Greggs (LON:GRG) were incisive and interesting And clearly he is correct to point out that it is an expensive share. [by my standards, I hold a lot]
But I would like to repeat Buffet’s famous and wise sentence: It is better to buy an excellent company at a fair price, than a fair company at an excellent price. Perhaps this applies to Greggs
In an attempt to big up the company, I will add that the Scuttlebutt is good Eg Paul’s enjoyment of his snack. Almost as important is the fact that the Queen’s foodie-journalist son gave Greggs a tremendous write-up. Cleverly, the company is appealing to an ever-widening section of society.
In case you are not yet impressed, I will add that I once wrote Greggs a critical email about their bonus dividend. Immediately I was sent a thioughtful (though disagreeing) answer.
Hi Paul, I've just finished listening to your weekend podcast. Please do not change the format. I find it very helpful to hear about all the companies you've reviewed during the week, both good and bad. I listen to a lot (too many) podcasts each week and yours is my joint favourite along with Merryn Talks Money (highly recommended to anyone who hasn't listened). Keep up the great work!
Agreed - love the coverage - honest opinions without the BS and lots of laughs (and hiccups!!!). Keep up the great work Paul!
Totally agree. Love the podcast, definitely want to keep being told about the bad companies aswell as the good one. Keep the format exactly as it is and you can go on for as long as you want.
Thanks also for the other things you do - videos and the summary spreadsheet which I find very useful. Thanks again.
Hargreaves Services (LON:HSP) has a major prospect in Tungsten West (LON:TUN) . Tun has just announced that "trading on AIM for the under-mentioned securities has been temporarily suspended from 01/10/2024 7:30am, pending publication of the Company's annual audited accounts."
... which may be just a minor delay but makes me nervous as a holder of Hargreaves Services (LON:HSP)
Over the last few days, reporting on Hargreaves Services (LON:HSP) projects has been a bit like snakes and ladders. Last week I posted that the lower Thames crossing is likely to be cut as part of the capital projects review. More recently there are reports that the Government will revive the Euston leg of HS2 https://www.newcivilengineer.c...
I hold
I do think its an interesting company with a few strings to its bow, recently visited a development site in Edinburgh area looks successful. Good mgt team, respected Chairman. Maybe a time to buy more?
I hold
There have been a few dodgy miners down in Cornwall, could Tungsten West (LON:TUN) be the latest I wonder?
I've held Greggs for a good while and enjoyed watching its profitable expansion. I have one criticism. Can they please turn the nuclear-fueled ovens they use to heat the steak slices? It is worse than Macdonals fruit pies.
iomart (LON:IOM) Having bought into this company recently, I've sold out for a 12.5% loss today. Update was terrible imo. Ignoring the acquisition announced today, debt has risen from 42M to 49M while the company announced a profit warning. With the acquisition, debt is now increased to 106M! The acquisition will give iom an additional 3.3M EBITDA (which obviously is not the full profit), but the additional loan will increase interest payments by another 2M. Looking back at the previous results, if you take out the previous acquisition, then iomart (LON:IOM) had a decrease in revenues and profit. So in theory, this is really a second profits warning, and how much actual profit will this new acquisition provide when you take away the increased interest payments? BIGGER, BOLDER, BETTER! Well the debt is certainly bigger. Even if the new company does well, I do not see the sp doing well for some time now. Next results will not look pretty, which will hamper the sp, so I do not see the sp going any where but down then sideways until the company actually puts out some good news.
You are not the only one gmtrader. What a complete shambles at iomart (LON:IOM) . Consistently underdelivering on revenue growth and profits for years, I twice got sucked in here believing that this was a 'cheap' value stock with a plausible turnaround story. I won't be returning again!
The only positive has been the fairly strong cashflow that has financed acquisitions in the past but this latest deal takes debt to uncomfortable levels at a time when the underlying business is struggling - a dangerous cocktail! Bad enough that we have a profit warning accompanying this deal but just six days ago the company was reassuring the market that it was looking to make an acquisition but didn't require an equity issue to do so. Highly dubious that they didn't warn on profits then, since the announcement was clearly designed to stabilize a falling share price.
Totally agree with what you have said sparkler regarding iomart (LON:IOM) . With debt at £106m, how long will it take the company to pay it off? Too long imo, which means it is too much of a risk now for me. I did make good profit in the company in the past, but you only need to see the chart on a longer time frame to see the sp has been in a decline now for 6 years.
Agree with everything said above.
I exited for a 20% loss today. Balance sheet was shakey before the deal and afterwards it just got worse. Rationale for the deal seemed odd.. essentially "bought a good business to make up for the existing lacklustre business". Not convinced.
Painful to take the loss, but cannot see how tomorrow will be different given their track record and outlook for H2.
MPAC (LON:MPAC)
Looks interesting, but I am unimpressed by the lack of management’s holding in the shares. The CEO, Adam Holland is shown as holding a paltry 12,500 shares on Sharepad!
Jonno, whilst I always like to see directors buying shares, I don't worry much when they don't, especially when they are exec guns for hire rather than the entrepreneurs who created a company.
It's a high risk investment strategy to invest a large amount in the company that is paying your wages. If things go wrong you might lose your job as well as your investment. And if things go well Adam Holland will benefit financially from generous share options and probably an increase in salary and bonuses.
Well worth a watch wrt MPAC (LON:MPAC) 's €56m acquisition of CSi Palletising.
Here CEO Adam Holland runs through the strategic rationale and integration plans of both deals, alongside the targeted sales/cost synergies and how the transactions are being funded.
Disclosure: Mpac are a Vox Markets client
Interesting I do think with Labour in power, business will look for more automation to improve productivity and reduce direct labour costs. As a long holder I will top up my holding.
Nothing to do with Labour. Business is looking to automate anyway - saves the cost of recruitment, HR management, pay pressures and social taxes (employers' national insurance liability).
So Labour in favour of reducing jobs then!
Is there not a shortage of skilled employees in this country? - i almost never here the term long term unemployed (perhaps unemployable?) being mentioned much. Hopefully brexit and minimum wage increases mean that there is plenty of room for efficiency improvements to be implemented without going back to the bad old days where many areas has mass unemployment - heck it wouldnt be hard to tax the robots and auomated machines like people - i kind of think thats an eloquent way of spreading the tax burden fairly - then pension off in geerous fashion all workers over 57 who would rather throw in the towl and leave it to the next generation.
More automation is the answer, so I have heard, to bringing back off-shored industry which depended on low paid labour mainly in the far East. The idea of taxing the automation and robotics reminds me of the Luddites in the Nottingham lace industry breaking the machines that threatened their livelihood.
Regarding you plan to pension everyone off at 57, I wonder what world you are living in. How could this ever be afforded?
How could this ever be afforded?
by taxing the robots that do the donkey work :) in similar manner as staff.
If robot does the same job as human whats to stop that bot being taxed in similar manner to a human ?
That's nuts. So nobody will use robots to on shore production and leave it off shore to be done by low paid. And you think that would cover an army of over 57 year olds staying at home to mow the lawn? Utter madness.
Its killing two birds with one stone - we are currently letting just about any overseas business suck spending money out of the uk to never return paying little to nothing in taxes - while a uk based busines is trying to compete and has to pay vat , corp tax and employment taxes.
A fit and proepr system would not discriminate against uk based business - if that was doen properley that would be a good foundation to charge reasonable fees on any overseas stuff wanting to extract cash from the uk.
Hive any uk based business a decent incentivce to be based here and pay full taxes here.
Our system at present is a joke and most of propsoed moaning at present doesnt even mention this real damage to the economy,.
My post is slightly ahead of the times in thinking so probably too soon to implement practicably speaking but at the end of the day plenty of scope for an automation tax and it doesnt need to be much harder than vat - if its all semi atiomated anyway doing the calcs should be a piece of hiss.
You diagnose the problem of an unlevel playing field re the UK v ROW and your solution is add another level of tax to any company that dares to try and improve productivity by using automation to do the boring , repetitive tasks in manufacturing. The benefits of which would be better quality and more throuhput using the same staff. This goes completely against trades union policy of protecting the bargaining power of the unions by recruiting more members and yet it looks like we are drifting back to the industrial relations of the 1970's with all it's strikes which nobody dared vote against, the car factories and shipyards being ruled by openly communist shop stewards. I'm curious of your industrial experience, have you ever worked in industry?
Being honest is just a somewhat flakey idea - to me though as we move towards more automation and less need for people to actually work it does make complete sense. as ever though striking a fine line that works is always the tricky bit.
note you can tax the robots and still make them cheaper than labour so i simply dont get any of your quasi socio arguments ref unions whjats that got to do with anything.
I think if most people were offered the option of working a 4 day week and taxing robots to make up the shortfall i kinda think that would be a vote winner imho. each to their own though in that regard though i am not forcing anyone to work les if they want to put in a proper week of graft
You never answered my question on your experience of industry. Your solutions seem to come from a book written by Ed Milliband. I can't be bothered anymore. Nothing you say makes any sense to me.
MPAC (LON:MPAC)
Ooh that is transformational !! I like the deal - looks very value accretive even without the synergies and cross sell opportunities that should come from it. Remember Adam was looking to buy so that they could offer customers an end to end solution and they now have that.
I note brokers have significantly moved target prices up to over 900p at top end and still claim forecasts are conservatively set.
I think their numbers do look light. It appears they have put last full year ebitda into the new forecasts whereas the CSi palletiser company appears to be doing well in excess of that at H1 stage this year with an order book that doesn’t suggest that was a one off half.
Be interesting to see market reaction this morning.
On a quick initial skim read, I agree David. CSi appears to be growing strongly with healthy margins. The price being paid looks very reasonable too. Crucially, this deal (plus the other two recent smaller bolt-ons) will achieve two things at once. Firstly it helps MPAC (LON:MPAC) offer a complete end to end solution for their FMCG customers and secondly, it brings sufficient scale to the business to take some of the 'lumpiness' out of the order book. I think the market will like this deal.
I commented yesterday on MPAC (LON:MPAC) as I had been investigating it over the weekend. The one reservation that I alluded to was the patchy historical record of cash flow generation. Nothing is guaranteed in this world, but it would appear that the normally negative working capital of the acquisition target would have an immediate boosting effect on cash flows and hopefully quickly achieve the deleveraging that management promises following the increase in debt explicit in the transaction. If that eventuates, and once achieved, future cash flows should be progressively greater. As it happens, I bought yesterday following my enquiries, so that’s one piece of bad news investors need to digest ;-)
David, I think you might have visited the company in the past. If you are planning another visit and don’t object to attending mob-handed in the interests of saving management’s time. I’d be interested in tagging along. Product offering now looks very comprehensive and client list very blue chip. Do please let me know and thanks for championing the name so eloquently. I’m at Mello in Derby if you’d like to share thoughts in person.
Hi BnB,
Agreed - that’s an important point to note re: change in cash flow dynamic on MPAC (LON:MPAC).
I’d like to get to see them again in person so if I do manage to sort that I’ll be happy to extend the invite.
Am hoping to attend Mello Derby, depending on some other travel. So if I can get there would be great to catch up in person. Will let you know.
Cheers David
Hi
If you do meet mgt I would interested to learn what is happening in their battery business? Is still R&D or a saleable product?
Yes, certainly changes things at MPAC (LON:MPAC) . This year has seen battery cell assembly (clean energy) added to their existing served markets of food & beverage, and healthcare.
In the recent accounts, it was pretty clear that they had some big ambitions as these notes all pointed in that direction:
Dividends
Having considered the trading results to 30 June 2024, together with the opportunities for investment in the growth of the Group, the Board has decided that it is appropriate not to pay an interim dividend in respect of the Period. No dividends were paid in 2023. Future dividend payments and the development of a new dividend policy will be considered by the Board in the context of trading performance and when the Board believes it is prudent to do so.
Pension Schemes
UK surplus £33m
USA deficit £1.6m
Acquisition strategy
The Board continues to actively evaluate potential acquisition opportunities that strategically fit the Group, and which will enhance our global presence in packaging solutions serving the Healthcare and Food and Beverage markets. Good progress was made during the Period in developing the pipeline of potential acquisition opportunities. The Company will provide updates on acquisitions whenever appropriate to do so.
It is good to see that the market regards this positively and there is a retail element to the offer. Also, that they are confident about the fund raise as only 4% discount with no underwriting.
I hold
MPAC (LON:MPAC)
Ooh that is transformational !! I like the deal - looks very value accretive even without the synergies and cross sell opportunities that should come from it
hmmmm - here is what they said
the Acquisition will provide strong EPS accretion to the Group over a five year strategic cycle
to me the wording here is very fluffy without much substance - you would loody hope that such an acquisition would be earnings accretive over 5 years period wouldnt you -normally?
Often if not pehaps the majority of the time companies say its earnings accretive year 1 - the fact they have to spin this out to 5 year period sounds to me like its only accretive if things go to plan over the longer term - over 5 year timeframe you can probab;ly make any reasonable assumptions you want to make the numbers fit the narrative you want to portray.
Note with one customer making up over 50% of sales this looks like a somewhat hail mary kind of acquisition imho unless it brings other stuff to the table (it may do)
I am not saying this aqcuisition isnt great - it might be great but it does not strike me as NOT being obviously cheap and certainly seems to be "risky" due to being so reliant on one customer - imho you would perhaps have to be barking mad to pay top dollar unless the acquired buisness brings extra to the table ref efficiencies and cross selling - in that regard its might be a no brainer froim an operational efficiency point of view.
to be fair the underlying profit made by the acquired buisness is not too shabby - but that kinda needs to be the case really if there are customer concentration risks etc. So hopefully - the immediate cashflow gains/signed contracts minimise the actual risk here - they indicate that will be so with drop in debt/ebitda - but i wander if those numbers are skewed somewhat by the extra ebitda that the new business will bring to te table (ie does 2.0 higher figure ignore ebitda being brought in by acquired business) - if ebitda jumps 60-70% the debt/ebita will obviously reduce
Probably what matters here is how much one trusts management to know their buisness and know this will work - hopefully they are suitably competent in that regard?
On the plus side if this can turbo charge profits and pay for itself over 6-7 years if earnings if it does work out as they have portrayed it.
I'm judging that 1-0 to davidjhill so far. Seconds out, round two!! MPAC (LON:MPAC)
MPAC (LON:MPAC)
Good morning, Paul
I see you’ve already noted the news that MPAC have announced a large acquisition and a 29£ million placing. Although it is only 4% under the current SP, somebody questioned on this board last week why suddenly the SP had dropped circa 20%.
Now we know why. Certain holders must have been informed.
I would still like to know what you make of the acquisition, Paul. Is it really transformational?
All the best. (I hold)
Hi mcav82,
"I would still like to know what you make of the acquisition, Paul. Is it really transformational?"
I wasn't intending on adding any more detail on the MPAC acquisition. It's not really possible for outside shareholders to be sure whether acquisitions are good or bad, as we're only told cherry-picked details from the acquirer's perspective, who are trying to convince us that they've pulled off a good deal. It's subsequent performance that matters, and judging from how many companies have to book impairments of goodwill, the reality is that lots of deals don't turn out to be as good as the acquirer had hoped.
Key questions I think generally for all acquisitions are -
Why is the vendor selling? Both parties clearly think they're getting a good deal, otherwise they wouldn't have agreed it. So I'd be surprised if both sides really are getting a good deal. When the people who know the business best are happy to sell it, then that suggests risk to me.
Synergies & cost savings on deals often don't happen, or as not as easy as expected, and acquirers can sometimes damage businesses they acquire.
That said, sometimes companies do pull off genuinely "transformative" acquisitions which work out well.
What is the track record of management at doing deals? Have they demonstrated that they are capable & have created value from previous deals? This latest deal at MPAC is relatively very big, and requires taking on more debt & some equity dilution. So it's riskier than doing just a small bolt on deal.
Overall, I think today's announcement sounds sensible, and with only very little information, my hunch is that this acquisition seems a good fit, but none of us really know, it's just educated guesswork. You have to trust management to have done a good deal, and to execute well post-acquisition.
For me, MPAC's track record has been too patchy, and cashflows not good. Lumpy orders. I don't think it's a particularly good business overall, but a lot of people seem to like it, and of course the shares have performed very well in the last year, doubling from the late 2023 lows. Let's hope they don't go all the way back down again, as they did in the last bull run that peaked in Sept 2021.
Hence personally I remain on the fence with MPAC. I can't see anything bad, just not good enough to get me excited, hence it would be another AMBER from me. Good luck to holders, it sounds like a few of you are excited about it.
Regards, Paul.
Hi Paul
Re MPAC (LON:MPAC) I think you have to look at the context. It is true that orders come in a relatively lumpy fashion so scale is important. However, the other thing that management have done is move the needle on service revenue (which is not lumpy) to 30% of the business. That alone reduces a lot of the previous volatility but is only a couple of years in.
The acquisition adds both scale but also a business with negative working capital. So play that off against the existing business dynamic and you get a nicely cash generative and balanced business. The CEO has been on about this as strategy for a while.
Today the shares trade at 10* PER which is low for a quality engineering business. Make no mistake MPAC (LON:MPAC) engineering is world class and in a space where demand is growing and they have a blue chip client base. Today’s acquisition is EPS accretive.
None of this factors in the battery assembly business which is super difficult to achieve and if it becomes commercial is transformative in its own right.
So not dissimilar to Zotefoams (LON:ZTF) a very reasonably priced business with potential for a big upside. A large acquisition always comes with integration risk but I’d hope that a company known for its engineering can manage that!! It also looks like broker forecasts are set up for a beat and they have just massively upgraded target prices (by some 50-60%) for what that’s worth.
The other point I’d make is that deals don’t have to be “I win you lose”. Private businesses sell for all sorts of reasons. I don’t like to see businesses transfer shareholder value - ie company with a low PER buys one with a very high PER but in this case MPAC (LON:MPAC) are buying a business on a lower multiple so both sides can win.
My morning smallcap tweet: TRYB to the Moon*, or into a ditch more likely
[edit] * maybe Somethin' Stupid is more appropriate.
Tribe Technology (LON:TRYB) Roadside Real Estate (LON:ROAD) Mulberry (LON:MUL) ECO Animal Health (LON:EAH) Jaywing (LON:JWNG) Allergy Therapeutics (LON:AGY) Tavistock Investments (LON:TAVI) Spaceandpeople (LON:SAL) Mothercare (LON:MTC) iomart (LON:IOM) MPAC (LON:MPAC), Character (LON:CCT), Peel Hunt (LON:PEEL), Works co uk (LON:WRKS)
◄Tribe Technology (TRYB)► the first autonomous drill rig shipped to Australia needs "significant software development and systems integration work" to meet specifications. Demo to customer pushed back to Dec. No contingency then? Co will cut opex to meet costs of extra work and delay. Seeking more funding. [SP=4.4 Cap=11m]
◄Roadside Real Estate (ROAD)► exits pub business with sale of Barkby Pub Co for a nominal £1. ROAD will pay £0.4m of liabilities. Also sells a further 1k shares in Cambridge Sleep Sciences for £8.5m + £1.5m contingent. Cuts ROAD's holding to 48% from 61%. [SP=21.3 Cap=29m]
◄Mulberry (MUL)► rejects possible 130p offer from Frasers Gp. [SP=124 Cap=71m]
◄ECO Animal Health (EAH)► warns FY-Mar materially below market expectations of £92.6m. Blames "recent challenges in China and Southeast Asia". [SP=96 Cap=72m]
◄Jaywing (JWNG)► warns weak consulting performance has cause a cash squeeze. Talking to its shareholder lenders to secure additional financial headroom. [SP=2.49 Cap=2m]
◄Allergy Therapeutics (AGY)► extends its cash runway into late-October. "There remains a further £12.5m of uncommitted funding available under the Amended Loan Facility and the Company is at an advanced stage on further debt funding to support its ongoing operations and development pipeline." [SP=4.7 Cap=186m]
◄Tavistock Investments (TAVI)► proposed sale of 2 subsidiary businesses for up to £37.75m, subject to shareholder approval. [SP=2.01 Cap=14m]
◄SpaceandPeople (SAL)► Network Rail contract renewed for 5 years. [SP=86 Cap=2m]
◄Mothercare (MTC)► suspended due to late finals. In final stages of refinancing talks. [SP=3.4 Cap=20m]
◄Iomart (IOM)► warns FY-Mar below market expectations. Buys Atech for £57m. A 'game changing' deal natch'. [SP=115 Cap=129m]
◄Mpac (MPAC)► makes 'transformational' (is that as big as game changing?) acquisition of CSi Palletising for €56m. Strong EPS accretion expected over a five-year strategic cycle. [SP=411.37 Cap=86m]
In line: CCT, PEEL, WRKS
MUL So, they'll issue shares at 100p, but reject a takeover at 130p. Based on the attitude of the directors, I'm going to guess that the share price will be materially lower in a year's time.
ECO Animal Health (LON:EAH) - Trading Update: headwinds in China - new research note: https://www.equitydevelopment....
In a Trading Update for the six months to 30 September 2024, ECO Animal Health reports reduced demand in China and SE Asia markets for its proprietary Aivlosin® porcine treatment, reflecting lower incidence of disease and some customer churn. The Group expects the customary H2 earnings weighting (H2 FY24: 57.5%), whilst Aivlosin® continues to gain market share in India and Brazil. However, the combination of demand, foreign exchange and other factors across the full range of EAH’s global market presence leads the company at this stage to assess that revenue for the full year should be below market estimates: a consensus indicated of £92.6m and (adj.) EBITDA of £8.2m. Consequently the Group expects FY25 (adj.) EBITDA to be close to FY23 levels (£7.2m).
At this stage we have adjusted our FY25 outlook accordingly. Our FY25 revenue estimate is reduced by 7%, and (adj.) EBITDA by 10%. We remain prudent but will review further as H2 develops.
Rightmove (LON:RMV) , why am I surprised to note this:
* Shares of Australia's REA Group REA.AX rise as much as 4.4% to A$209.79, its biggest intraday pct gain since Aug 9
** The Australian property listing firm on Monday said it was dropping pursuit of real estate portal Rightmove RMV.L after the UK company rejected its sweetened $8.29 billion fourth proposal."
I hold, held on while I didn't fancy the offer at all.
I thought profits were down at first for James Halstead but management say "FY24 was a year of profitable growth". Could've fooled me.
Nuances of which measure you choose to comment on I guess.
A bit like "Lies, damned lies and Statistics" you can make a set of numbers reflect whatever you want if you present it in a certain way. PBT is 7.9% up, growth by any standard! The guy is retiring after an amazing growth period for the company so I'll forgive him this time :)
I thought profits were down at first for James Halstead but management say "FY24 was a year of profitable growth"
Revenues are down and profits up. So, by my reckoning, FY24 was a year of “profitable shrinkage”
Richard
Profit before tax is up. Profit after tax is down. So it's profitable growth, just not for shareholders!
The headline for James Halstead (LON:JHD) says -
"Profit before tax of £56.2 million (2023: £52.1 million) - up 7.9%"
But profit after tax down 2.1%, and EPS down 2.0%. So I suppose it depends which profit measure is most important.
Revenue was down 9.4%.
"FY24 was a year of profitable growth..."
Stupid of JHD to let the PR put this ambiguous phrase in. It wasn't a year of growth, as revenue shrank. However, it was still profitable. PBT was up, PAT slightly down, so a mixed bag.
They should have crossed out "profitable growth" and replaced it with "increased profit before tax". More precise, and more accurate.
Profitable growth is just a lazy, ambiguous PR phrase that we need to push back against.
Pity as JHD has produced decent numbers. A big rise in gross margins more than offset the reduced revenues.
Then they use a different phrase -
"We look ahead to FY25 in good stead and after delivering another year of profits growth."
Which is true, if you look only at PBT (probably the most important profit measure). There's a sharply higher tax charge, which is why PAT fell slightly.
EPS of 10.0p looks a slight beat, or in line anyway. PER 17.6x looks reasonable for a good quality business. Much better than the excessive valuations in the past. It's looking a bit ex-growth at the moment, but the long-term track record is superb. Shares are back down to where they were in 2015. Dividend yield almost 5% now, I think this looks quite good actually.
Regards, Paul.
I like James Halstead (LON:JHD) as a stable, well-run family firm. But where is the growth, past or future? It looks, and is priced, more like a bond-proxy. Eventually falling interest rates might help the SP if they eventuate. But we are not returning to previous levels without zero rates or a transformation in the “growth” rate.
James Halstead (LON:JHD) almost certainly has an AIM IHT premium baked into. As one of the most reliable and largest shares on AIM it's a natural home for IHT funds whose main aim is not to lose money. Note Octopus as 2nd largest shareholder , AIM's biggest IHT fund. Relative to other UK businesses , a 17.6 x multiple for an ex-growth company looks very expensive. High ROCE not that valuable if you are just returning all your earnings to shareholders
James Halstead (LON:JHD) almost certainly has an AIM IHT premium baked into. As one of the most reliable and largest shares on AIM it's a natural home for IHT funds whose main aim is not to lose money. Note Octopus as 2nd largest shareholder , AIM's biggest IHT fund.
I keep reading this but the fact is it’s far less exposed to Octopus than many other AIM companies regularly discussed here - I listed 18 of them last week. My information tells me Octopus currently hold only 6.6% which is far less than many other AIM companies and about the same as Gamma Communications (LON:GAMA) . The other two large AIM IHT funds run by Canaccord Genuity and Close Asset Management do not have disclosable holdings, so below 3%. Both hold ~7% of Somero Enterprises (LON:SOM) for instance.
James Halstead (LON:JHD) is currently near the top of my “Auntie Rachel’s Great October Giveaway” list :-)
Does a recent history of 4% revenue growth and 3% EPS growth at James Halstead (LON:JHD) really warrant a high multiple. ? This is not one where you can really blame macroeconomic factors as the performance pre-Covid was very similar for many years
Does a recent history of 4% revenue growth and 3% EPS growth at James Halstead (LON:JHD) really warrant a high multiple. ?
I don't understand? Where did I mention anything about valuation in my post? Please at least reply to something I wrote rather than make a completely random different point!
RE: James Halstead (LON:JHD)
EPS of 10.0p looks a slight beat, or in line anyway. PER 17.6x looks reasonable for a good quality business. Much better than the excessive valuations in the past. It's looking a bit ex-growth at the moment, but the long-term track record is superb. Shares are back down to where they were in 2015. Dividend yield almost 5% now, I think this looks quite good actually.
I agree Paul. Increase in tax rate was just about offset by interest on the cash balance.
The quality here is clear. In a tough year to achieve near 30% ROCE and 20% operating margin shows good management. They really need to grow revenue though, and if they do, the operational gearing will kick in and drive profit growth.
All the best, Si