Small Cap Value Report (Tue 1 Sept 2020) - BOO, MKS, DNLM, SAGA, AA., G4M, CBOX

Good morning, it's Paul here with the SCVR for Tuesday.
Estimated timings - sorry, I nodded off mid-morning, having had a poor night's sleep, so am running a bit behind schedule. I should be finished by 3pm. Today's report is now finished.
I hope you enjoyed the long weekend. I made good use of the time to spruce up my flat a bit, which has gone to rack & ruin during lockdown. This year, my entire focus has been on covid, and trying to work out what on earth is going on with the markets, hence I had overlooked the fact that home had become an increasingly cluttered (buying stuff on Amazon all the time), unkempt, pigsty! It's slightly better now anyway, but won't be winning any Ideal Homes awards for the foreseeable future. As mother put it, "It's very you!"
Boohoo (LON:BOO)
I see the Guardian has really got it in for Boohoo (LON:BOO) with a couple more damning articles published on Friday, causing a plunge in its share price (I hold), before a rapid partial recovery. I'm amazed that repeated revelations about its supply chain are still having any impact at all on the share price. It's been known for decades that the fashion sector has a murky supply chain. Practically every garment that all of us have ever worn, will have probably been made by someone being paid very little for their labour, irrespective of whether it's cheap fast fashion, or high end designer clothing.
I've seen some ridiculous commentary from journalists & analysts who clearly don't understand this sector, speculating that BOO's profits are built on sweatshop labour in the UK. Hence profitability would collapse once suppliers are forced to properly pay minimum wage. This is nonsense. Even if the allegations are true that some of BOO's suppliers only pay £3.50-£4.00 per hour, this would still make UK production high cost, compared with overseas. The reason UK factories are used, is speed to market, and convenience (e.g. designers/buyers at BOO can check production samples by jumping in a car and inspecting production themselves).
As the Guardian suggests, BOO is apparently already moving production to suppliers overseas (Morocco and Turkey have been mentioned), which are cheaper production areas, because wages are even lower than in Leicester, and lorries can bring the product into the UK at reasonable cost & speed.
Hence I don't see this issue as having any lasting impact on BOO. Other than reputational damage with people who don't buy BOO's product anyway. How many people wearing a BOO figure-hugging polyester £7 dress read the Guardian?! Not very many, I would wager. The Guardian's readership is more likely to be wearing hemp, or have upcycled something from Oxfam.
So-called ethical investors should never have invested in the fast fashion sector anyway, as the issues concerning landfill, water usage in fabric production, low wages in factories & poor H+S overseas, etc, are long-standing & widely known. I salute the efforts of people trying to improve these things, but one way or another BOO's business model looks bulletproof to me, and the shares are likely to be big long-term winners as it extends its geographic reach, and adds multiple brands to the well-oiled machine.
.
Eat Out to Help Out (EOTHO)
This scheme during August seems to have been a rip-roaring success, judging from press reports of large take-up by customers. It seems to have galvanised plenty of people into returning to restaurants. What I like about this scheme, is that (at relatively small cost to the taxpayer), it has enabled many restaurants to re-open that might not have done otherwise. Therefore the Govt is getting people back to work (and collecting in payroll taxes again, rather than paying out furlough money). Combined with the temporary VAT drop in the sector, it gives the better operators a fighting chance of survival.
I've not seen any evidence that restaurants have been identified as places where the virus is spreading. So hopefully the social distancing measures are working, and of course this time of year windows & doors can be left wide open, creating airflow, which I imagine must help somewhat. Restaurants and pubs I've visited do seem to be taking additional cleaning measures too, with plenty of disinfecting & wiping down of surfaces in evidence. I am worried about what happens in the autumn/winter though, with colder temperatures, and more enclosed spaces.
I got emails from both Franco Manca (owned by Fulham Shore (LON:FUL) ), and Revolution Bars (LON:RBG) (I hold) over the weekend, saying that they are extending EOTHO at their own cost, for September. That's really good news, as I enjoy eating at Franco Manca, and it's cheap at full price, so half price is a terrific bargain. I'm holding back on buying its shares though, as the valuation is far too high right now, given the risks ahead.
.
.
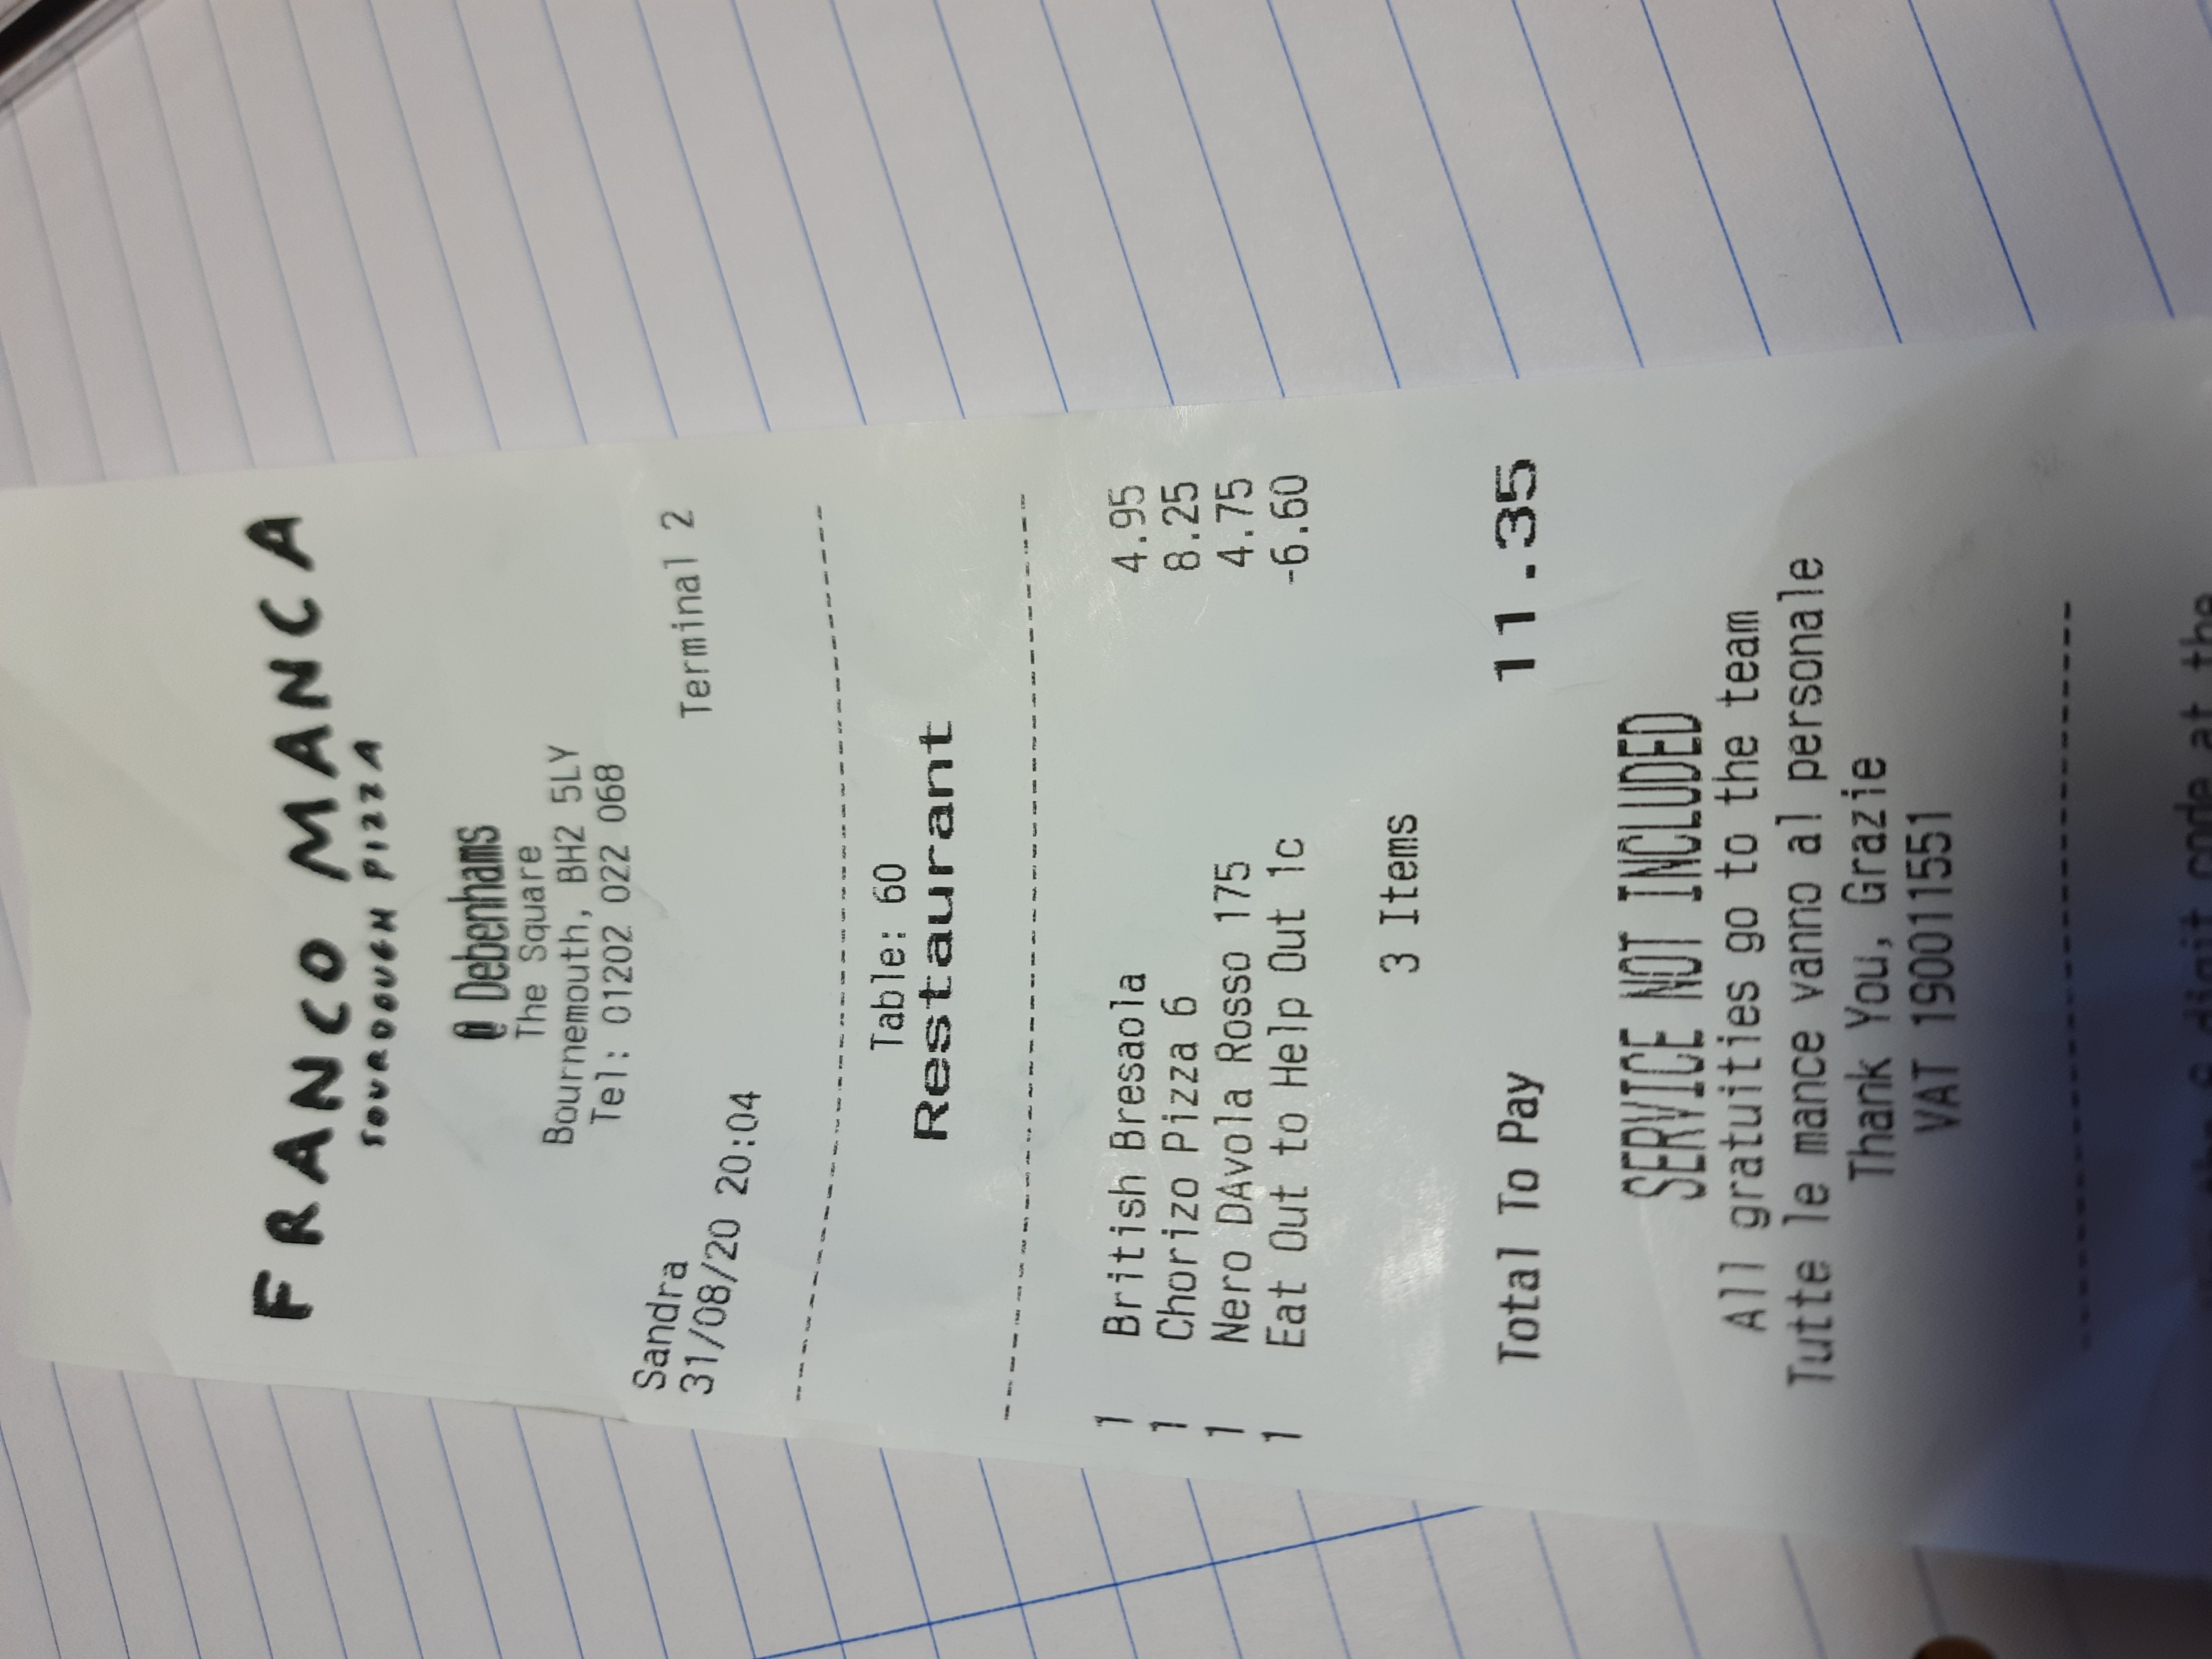
Here's my bill from last night. Bear in mind that the food & house red wine at Franco Manca is really good quality too, with a lot of emphasis placed on the provenance of ingredients. Anyone who claims it's just another pizza chain, clearly hasn't actually eaten there (or went when the chefs were having a bad day)! It's a nicely differentiated product offering. I think the business is likely to do very well, long-term, once the brand is better known outside of London.
Anyway, discounts are here to stay, for Mon-Weds. This is vital for restaurants to spread the business more evenly over the week, as peak trade on Fri & Sat is necessarily less busy than before, due to reduced density of tables required to social distance.
Mind you, last night in Bournemouth I saw plenty of groups of young people hugging & kissing each other, totally ignoring social distancing.
Also, the retail park (called Tower Park) was absolutely heaving on Saturday, with a full car park. M&S was many times busier than when I last visited, and plenty of middle aged & older people shopping, everyone wearing face coverings once inside the shops. It looks to me as if retail is getting back to normal, hence I'm toying with the idea of opening some new positions in that sector, if the valuations and balance sheets are attractive enough.
I am intrigued by the M&S/Ocado food offering, which is launching imminently. I suspect that could be a big success, and possibly lead to a re-rating of Marks And Spencer (LON:MKS) maybe? It's tempting to have a punt on that. Although I reckon M&S is likely to have made horrendous losses throughout the lockdown period.
.
Dunelm (LON:DNLM)
Very strong sales figures for July (up 59%!) and August (up 24%) are announced this morning, from this homewares retailer.
Dunelm confirms that its mainly retail park sites are performing strongly, which is clearly the best place to be located at the moment - with plentiful parking, and large, spaced out internally shops. We've seen from other company announcements that shopping centres & town centres are doing less well, and commuter city/towns. especially central London of course, are doing the worst, due to lack of commuters and tourists. Pret is really suffering apparently, given that it has sites approximately 50 yards apart throughout London, and footfall is still heavily down.
DNLM does point out that the July/August performance is pent-up demand, and that the outlook is uncertain. I'm wishing now that I held onto my DNLM shares, bought near the market bottom in March, but I banked the profit a while back. It's a fantastic business that should do really well long term.
.
Saga (LON:SAGA)
Share price: 19.0p (up 40%, at 08:34)
No. shares: 1,122.0m
Market cap: £213.2m
Statement re equity raise and strategic investment
Several newspapers ran stories over the weekend, saying that this insurance & travel group for seniors, has secured funding from a previous owner. This is confirmed with an RNS today;
Saga plc ("Saga" or the "Company") notes recent media speculation and today announces that it is at the advanced stage of a prospective £150 million equity capital raise (the "Proposed Equity Raise") in order to strengthen its balance sheet, improve liquidity and support the execution of its reinvigorated strategy under its strengthened management team.
Details;
- Raising £150m in fresh equity
- Firm placing, and placing/open offer to launch c. 10 Sept 2020
- Former CEO (20 years service), Sir Roger De Haan intends to invest up to £100m - of which;
- £60.6m at 27p per share (a 98% premium! [good, but why?!])
£14.9m at 15p or less (will be same price as open offer, TBC)
£24.5m at 15p or less, which looks like partial underwriting of the open offer (£74.5m total OO), subject to clawback for other shareholders participating in the OO, if I've understood this correctly - Sir Roger to become new Non-Exec Chairman, subject to a shareholder vote (who I imagine will welcome him with open arms & a thunderous round of applause, for rescuing the business!)
- Existing Board unanimously supports the above
Summary of progress made in last six months;
- Non-core disposals done, providing sufficient liquidity for severe disruption to travel business
- Costs cut by £20 p.a. run rate
- Amended debt facilities
- Sold Saga Sapphire cruise ship, but new ship "Spirit of Adventure" arriving end Sept 2020
- "continued progress" in insurance business
- Strategy review to be announced with interims c. 10 Sept 2020
- Focus on "investment" in brand, data & digital, efficiency, organisational & cultural change
Recent trading;
Recent trading has been in line with expectations and consistent with the commentary in the AGM trading statement, published on 22 June 2020.
Aborted bid approach;
... recently evaluated and rejected an unsolicited and highly conditional 33p indicative approach for the Company from a consortium of two US financial investors. This 33p offer followed several earlier indicative approaches from the consortium which commenced at a significantly lower valuation. The investors have since confirmed that they are no longer considering an offer for the Company.
How interesting. This provides a nice valuation benchmark.
My opinion - SAGA has been in my "potentially interesting, but I haven't had the time to properly go through the numbers in enough detail" tray for a while.
Whilst not yet a done deal, this looks close enough to justify a re-assessment of the risk (i.e. now much lower). I like the look of this, and think it could be worth a modest punt, but I'll try to do some more work on the numbers when time & energy permit.
Generally speaking, and I have no firm evidence to support this view, I like situations where a founder returns to a business, in order to sort it out. That Sir Roger is also injecting £100m of his own money, at a 98% premium for most of it, looks very encouraging to me.
I think a lot of people are itching to go back to cruise ships, when it's safer to do so. The brand loyalty generally to particular cruise lines, is remarkable to behold. I remember talking to some elderly neighbours years ago, and they loved cruising. One lady said, "We're very much P&O people", and another replied, "Oh we only go on Cunard", etc. . Hence I think the cruise line sector could bounce back very strongly at some point in the future. The trouble is, what shape will their balance sheets be in? Ruinous debt, currently being refinanced at exorbitant interest rates for the larger operators, could leave little upside for equity though. That probably won't stop a speculative frenzy in the shares though, as the US stock market (where Carnival & Royal Caribbean are listed) is very much in a speculative euphoria phase at the moment.
With Saga I like the fact that it has a cash generative insurance business alongside the cruise line, thus balancing the risk a bit more.
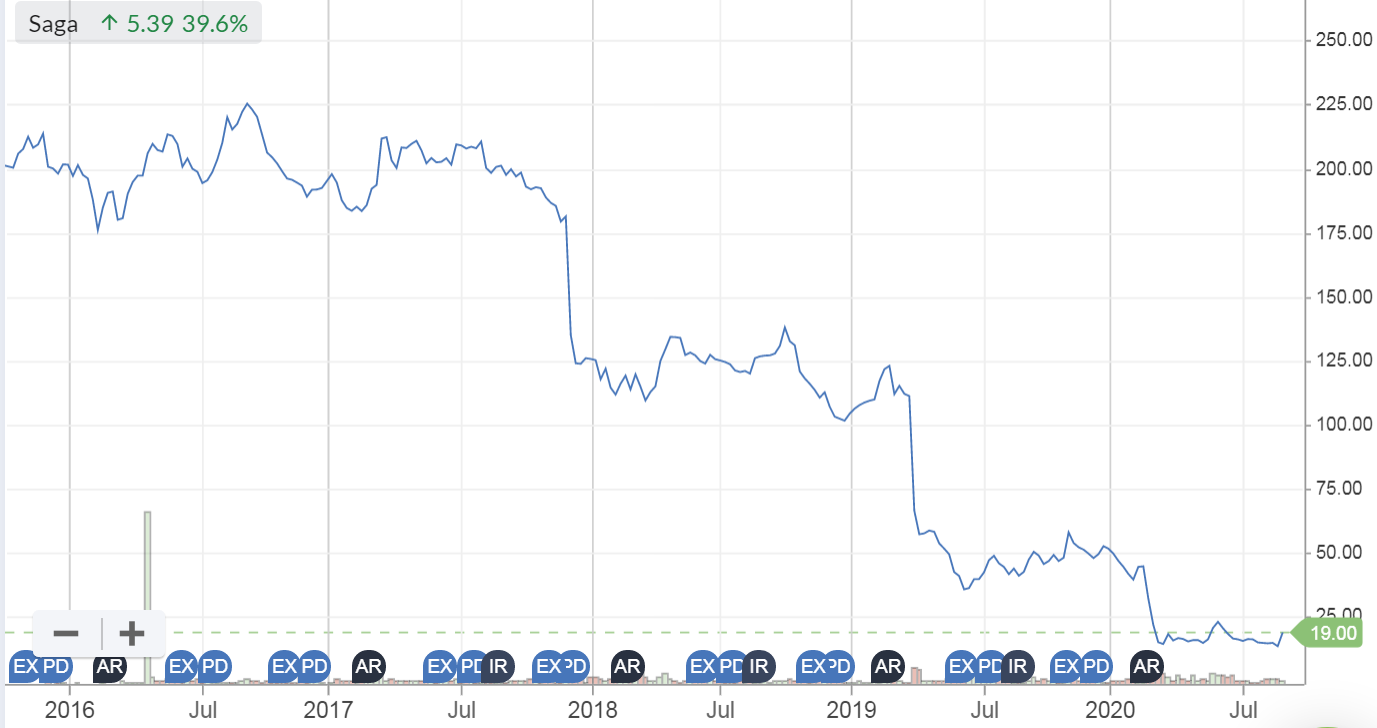
As you can see from the 5-year chart below, management seem to have been making a hash of things well before covid kicked the company in the proverbials*, by forcing its ships to become stationary for an extended period of time.
Overall - looks potentially interesting.
(* = shins, before we start getting complaints from the usual offendees)
.
.
Aa (LON:AA.)
Share price: 31.1p (down 10%, at 13:01)
No. shares: 621.5m
Market cap: £193.3m
Today's deadline to put up or shut up, has been extended to 29 Sept 2020 by the Takeover Panel, at the request of the AA. It says it is still in discussions with 3 names parties re possible cash takeover bids.
As I mentioned here on 4 Aug 2020, it's far from clear that the equity in AA has any value at all. Given its debt mountain, of £2.65bn, then it would make sense for a bidder to just buy up the debt, possibly at a haircut from par, and then force a restructuring that involved wiping out equity holders.
There again, with private equity awash with cash, and 3 competing potential bidders, anything could happen.
It's such an inherently impossible situation to gauge, I think the equity must be considered uninvestable. Shareholders might get lucky, and receive a bumper payday, but would that be big enough, or likely enough, to justify the risk of being wiped out if it goes wrong?
I heard that there's been a bearish note from Jeffries, who must be avid readers of the SCVR, because they echoed my thoughts more recently, putting a price target of only 5p on this share.
Overall - way too risky, and I wouldn't want to touch it either long or short. It's pure guesswork at this stage - not a good strategy generally speaking. If there's a strong argument for valuing equity an nil, then personally I wouldn't go near it. That logic would still be intact, even if a blockbuster takeover bid does happen, because that would be a lucky outcome, not a logical outcome.
.
Gear4music Holdings (LON:G4M)
Share price: 580p (up 2.7% at 13:54)
No. shares: 20.95m
Market cap: £121.5m
This is a separate announcement, looks like a non-regulatory one, providing commissioned research on the company. I'll have a look at that later.
AGM Statement & Trading Update -
... the largest UK based online retailer of musical instruments and music equipment
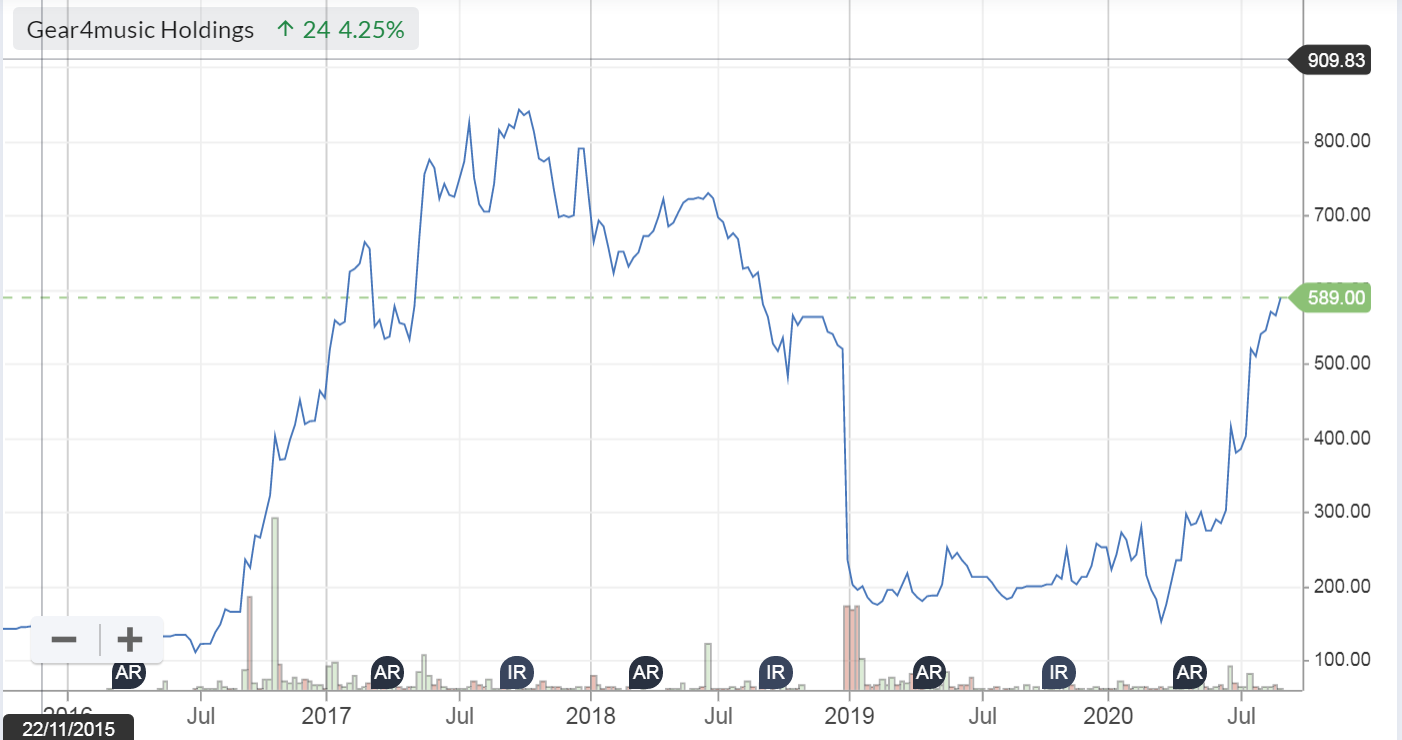
This is one of those lovely shares, where we've had two chances to multi-bag our money, as you can see from the chart below. That's if you managed to sell before the profit warning in Dec 2018. The business is very much back on track now, and the focus on margin over sales growth has been very successful. Plus lockdown has helped this year. Even so, the recovery in earnings & forecasts has been really impressive this year, with a number of positive consecutive updates.
.
.
Today's update is pleasing, showing that positive momentum is continuing;
"Following the exceptional period of revenue growth during Q1 FY21, I am pleased to report that trading has remained strong throughout July and August, with the Group continuing to generate improved margins alongside proportionally lower marketing costs compared to the same period in the prior year.
Whilst still relatively early in the current financial year, the Board remains confident that results for the full year will be at least in line with our recently upgraded expectations."
My opinion - as regulars know, I'm positive on this share. It's a good GARP share (growth at reasonable price), in my view. Management are excellent, and it's operating in a good growth niche.
N+1 Singer research notes are very good, available on Research Tree. Forecasts are 23-24p EPS for this year, but it sounds like the company could beat that. I reckon we're probably looking at more like 25-30p for this year, with good momentum, hence at 580p we might be on a PER of only about 19, if the top end of that range s achieved. That's not at all expensive for an international eCommerce business that is now becoming decently profitable.
I'm kicking myself for selling out a while back, and will possibly buy back in if the price has a wobble at any stage, if that coincides with me having some spare cash. Existing holders should be feeling justifiably pleased with this latest positive update.
.
Cake Box Holdings (LON:CBOX)
Share price: 178p (up 2% at 15:23)
No. shares: 40.0m
Market cap: £71.2m
Trading Update
Cake Box Holdings plc, the specialist retailer of fresh cream cakes, today announces a trading update covering the first five months of its financial year, to 30 August 2020.
This update reads well, and the share price has now fully recovered to pre-covid levels - impressive for a (franchised) retailing business.
All stores closed for 6 weeks in the period
Trading very strong since re-opening: LFL +14.1%, and online +74%
Not clear if deliveries via Uber Eats, Just Eat, and Deliveroo are included in the online growth, I imagine they probably are
5 new stores opened since 1 June, I can't remember if they're all franchised stores or not, will check later & update this bit (am trying to type this whilst on my exercise bike LOL!)
£156k furlough monies returned
Good outlook
Special divi of 3.2p to be paid, replacing previously withdrawn final divi
My opinion - an impressive update in the circumstances.
That's me done for today. Thanks for all your interesting comments.
Best wishes, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

45 comments
"I am intrigued by the M&S/Ocado food offering, which is launching imminently. I suspect that could be a big success, and possibly lead to a re-rating of Marks And Spencer (LON:MKS) maybe? It's tempting to have a punt on that. Although I reckon M&S is likely to have made horrendous losses throughout the lockdown period."
Paul
I reckon you might be right. It's Sunday night and there is some choice language coming from my wife in the kitchen. The reason? She is struggling to get a delivery slot on Ocado (LON:OCDO), and quite a few of the Marks And Spencer (LON:MKS) items are out of stock anyway. It's been like that quite a bit this week as well since they switched to Marks And Spencer (LON:MKS) (the stock-outs I mean; the choice language has been going on for years).
PK
Hi Paul, thanks for your comments on £SAGA. I too think this is an interesting play and also particularly like a founder returning and putting a significant amount of their own money at risk. Generally a very good sign. Thanks, Alex
Looking for alternatives to £ASOS and Boohoo (LON:BOO) and N Brown (LON:BWNG) looked likely to benefit from online retail and down in the dumps. But went on the web and very drab. Boohoo (LON:BOO) to TikTok and lots of marketing on social media so perhaps (1) not somewhere I go and (2) ask your kids who spend all day on it - mine said don't touch but heh, take away the allowance they become capitalists!
Anybody trashes the Guardian has a thumbs up. Hemp would be the only thing left (and lycra) if they had their way.
Went on DLR/District Line/Jubilee Line today and due to no crowds quite pleasant - but two people sneezing into their masks. The Covid fear factor will kick in if starts getting crowded and can you imagine you start coughing - might get thrown off at the next station! I like Pret's food (sorry too lazy to see who owns it) and so perhaps move to quality and good price may win the day.
I feel it will be about the 'great outdoors'. Buy shares in those patio heater things famous at West Quay.
why would saga turn down a bid of 33p mind boggling reminds me of rev bars rejecting takeover. Delusional boards
Interesting comments on £AA Paul. There is one fly in the ointment of buying up the debt to take control. As a bilateral market, its akin to many small cap equities, ie just because you want to buy doesn't mean that any holder will engage with you. I would guess distressed debt funds have been buyers of the subordinated debt given its rally back to near par over the last few months. So for them to take full control the most rational way is to make an offer for the equity. To that end one of the potential buyers may well take the view that the cheque they have to write for the equity is not so great as to be a deal breaker.
I think the Jeffries note was mistaken as it was predicated on the inability to refi the Class B debt. Currently, the debt markets are open to subordinated debt and I guess a high single digit coupon for a 9x levered business would be attractive when you consider vanilla high yield is printing at sub 3%.
Regards,
Paul
Great points, thanks Paul!
No comments here yet on Centralnic (LON:CNIC) (I hold) which reported today. The huge increase in top line numbers followed from their large acquisition late last year. This has not fed through to bottom line profits yet, but they are doing exactly what they said they would do as they continue to invest in the business.
Forecasting appears to be on the mark (which I like) and their key role in the expansion of the net and our digital lives leaves me comfortable that they can pull off some major growth in both top and bottom lines over the next few years.
Hi Paul, hope you're well. Are you still covering Gear4music Holdings (LON:G4M) today? I just assumed that g4m would be before Saga and AA , per the order of report title, cheers!
I tweaked the running order, so have amended the title now, and section on G4M is now up.
I've done business with Roger de Haan and his brother Peter (who was FD and founder of the SAGA insurance business). An extremely bright and personable pair, with terrific practical vision. SAGA is firmly better off with him/them.
New subject; Fevertree and Double Dutch.
Waitrose are now stocking Double Dutch, which seems to be privately owned. Look them up.
New competition for Fevertree?
Boohoo (LON:BOO) (I hold)
Interesting comments on the ramifications of moving production abroad, but I'm wondering whether anyone knows how import duties would work, specifically:
A
Turkey and Morocco are duty free currently. The provisonal tariff published by HMG last year indicated that would remain the case, despite the UK dropping out of the EU trade deals that achieved this (a unilateral reduction in tariffs by the UK). There is still some kerfuffle around customs transit rules but I think that will get solved.
Trucking costs are around £4000, so about 30p per item to truck. Takes 5 days on average.
If a BooHoo item average cost price is around £2.50, £1.00 of that will be labour. Turkey/Morocco will be half the cost (50p), so overall they will see a gross margin increase of about 10% from the shift but with the penalty of a longer lead time, more hassle and disruption risk.
CAUTION extreme back of fag packet calcs!
hasn’t realised Paul did a similar analysis. We aren’t miles away!
Paul - don't get concerned about reduced number of thumbs up today - that facility not working on the old site (yes there are still a lot of us Luddites).
The thumbs up/down isn't the only thing not working on the old site. Want to check on Paul's last comment on, say, Boohoo (LON:BOO) ? Go there and press the 'discuss' tab and you will see that the last comment was by Graham on 3/12/19. Try putting Blackbird or Airtel in the search box and it will come up with anything except Blackbird (LON:BIRD) or Airtel Africa (LON:AAF) After that try clicking on Accounts Dividends or Accounts Directors Dealings of any share and you will be met with a blank page.
Nevertheless I am happy to be a Luddite with Laughton - on the old site it is much easier to navigate and takes less than half the time to load.
Completely agree on Boohoo (LON:BOO) and generally on ESG. There were similar comments on the Value After Hours (well worth a listen, it is entertaining and informative at the same time IMO) podcast last week - basically all BS.
I won’t be topping up as it was a 10% position before this recent fall and I have learnt my lesson on not being overweight one stock.
However, it is interesting to compare Boohoo (LON:BOO) with £ASOS using the Stockopedia compare feature. (See screen grabs below)
Of course at some point Boohoo will become a mature business but that time is a long way off. A quick google shows that the ONS estimates that retail sales in the U.K. in 2019 were £59.329bil (double 2005). Is it unreasonable to think that Boohoo could take 10% of those by 2030. The market seems to have forgotten that Boo built a distribution centre that is capable of handling £3 bil of sales; I don’t think that they would have allocated capital to that degree without a clear idea of how they were going to get there.
Finally, 45% of Boo’s sales are outside of the UK to people in places who probably haven’t even heard of Leicester (Apologies to Leicester). If this proportion was to be maintained then we could be looking at a £12 bill turnover company by the end of the decade. A certainty of course not (I am listening to Superforecasters on Paul’s recommendation at the moment, so I know I should not be making long term predictions) but I would give it better than a 50% chance.
Also agree 100% with Paul on BOO. Much better to read his well informed comment on a sector he knows back to front ahead of sometimes ill informed journalists and posters elsewhere. One on another site that I like and use a lot has driven me to distraction with his nonsense about this being the ruin of BOO (based solely on the Sunday Times and Guardian articles) while at the same time admitting that until recently he hadn’t heard of the Company! Yet that didn’t stop him posting nonsense with total conviction that he was right That sort of thing happens so often on other bulletin boards. When Paul is equally forthright it is with the benefit of experience and genuine knowledge.
Also agree with Paul on Saga. I already held at a loss until today, and have added more today.
Note that SAGA have a big travel general travel business as well as their cruise and insurance.
Some might not know that Saga’s 2 new state of the art luxury cruise ships are (afaiaa) THE first where every cabin has a balcony. That is a big plus for cruisers and the more so post covid as it is far better being confined to a cabin with access to a balcony and fresh air than an inside cabin or outside with portholes that can’t be opened. Also the ships are exceptionally high standard, yet the prices are a lot lower than other luxury brands. Another big plus for those hating the idea of those floating “tower blocks” with sometimes 6000 passengers, is that their new ships are still small with excellent space to passenger ratios. They hold just 999 passengers. Saga service is very good and a lot of extras with other cruise Companies are included in the price. And bookings were very encouraging. Many of their customers have not opted for refunds but have gone for the use it for future cruises alternative.
We’ve only used Saga once, as the negative was that their passengers were often very elderly, and though we’re not spring chickens,we felt out of place, but apparently these new ships were, pre covid, attracting a lot more younger, though 50 plus, cruisers too. Paul is also right about cruiser loyalty. The cruise industry should thrive again BUT THE big worry is if covid returns with a vengeance, as then more could go under. Value brand Cruise Maritime has already gone bust. Saga with insurance as well, and their 3 year policies selling well, is better placed overall than the likes of Carnival who own so many of the big cruise brands, though that recent Saudi stake might prove significant for Carnival?
The news today should put Saga on a much stronger footing. They were floated at too high a price but the 14p pre the news today, and over 90% down from the peak was pricing in near disaster.
Finally I don’t understand their explanation about shareholder involvement in the further 15p placing. All shareholders?
The only people making money from cruise liners at the moment are the enterprising folk on the south coast who are running sightseeing cruises out to see all the liners at anchor.
The fleets are being reduced by sending ships to scrap or selling them cheaply to smaller competitors - I saw Fred Olsen picked up one recently but they are removing another ship from their fleet. I can't really see how cruising can start up again this side of a vaccine.
https://edition.cnn.com/travel...
John
Cruises have started again. Cruise ships leave (and start and finish) all over the World. So best to look beyond just the UK. UK cruises have indeed been cancelled, and Cunard at least until April and May next year. But Carnival who own Cunard have a worldwide cruise business. AND they too are seeing many of their customers going for the enhanced offer on their next cruise and not refunds.
The cruise Industry business model has a very big weakness in that they rely on forward bookings, and cruises have to be fully paid for well in advance. So the big worry for the sector imo is not what is happening now, .but the risk of covid returning with a vengeance. Then cruise companies would be in big difficulties, along with much of the travel and hospitality sectors.
This is a common mistake when posters comment on shares with International businesses like BOO too. They either don’t know or do not take into account that these are International businesses.
Ken,
There aren't a lot of ships actually at sea anywhere are there?
https://www.traveloffpath.com/...
John.
Agree right now, but as your link shows many of the cruise lines intend starting cruises again from this month. Cunard are a big exception to that with no cruises at all until next April.
Also Saga depart from UK ports which is a negative from start date angle.
A big question is how many of the cruises scheduled from this month will actually go ahead. So much depends on what covid does next.
Cruises may have started again, but that can't be at anything like the levels before - or those ships wouldn't all be moored of the South Coast - they are not just there waiting for UK trade. The big question is if levels will get back to "normal", and increase as they were. I can't see either of those happening while Covid worries persist. This could trun out to be a good time to buy into cruise companies - but the uncertainties and risks remain high. I don't find it hard to see the popularity of cruises being reduced for somne time to come.
Re £boo I think the issue isn’t so much the low wages but whether the business is more integrated than they let on and whether there has been potential for margin leakage in the operating model. I own Next (LON:NXT) and B&m European Value Retail Sa (LON:BME), both of which have better operating margins and have had solid gains recently. Just a thought as I prepare for the ‘dislikes’ !
Hi kgb,
Next (LON:NXT) and B&m European Value Retail Sa (LON:BME) are both fine businesses, I agree, but neither has anything like the growth rate of Boohoo (LON:BOO) (which I hold).
Can you clarify what you mean by this?
whether there has been potential for margin leakage in the operating model
I thought we'd covered that point. BOO is responding to the Leicester issue by moving production abroad, to lower cost countries. Hence margins will if anything be going up, not down. They'll just lose some speed to market, by maybe a week (time to shift product overland from Turkey or Morocco).
Transport cost is cheap in lorries. Back of envelope - I've just weighed a T-shirt, it's 176 grammes. So a cheap dress, might perhaps weigh say 300-400g. If a lorry can carry say 30 tonnes at a guess, take off 10% for packaging/pallets, etc, that would be 27,000 kg of clothing, or about 77,000 dresses. If it costs the lorry say £7k (probably too high an estimate?) to go there & back (usually empty on return) then we're looking at about 9 pence per dress in freight cost.
If it takes a fabric cutter & machinist say 10 minutes (a complete guess, I admit!) to make each dress, at £4 per hour, then the UK labour cost is 67p in the UK.
Google says that Morocco minimum wage is $1.39, or just over £1 per hour. So the labour cost per garment there would be 16.8p, a saving of 50p per garment, which more than recoups the additional freight cost over 5 times.
The above are just rough estimates. But I think this proves the point that BOO's margins are not likely to go down by offshoring production, they'll go up!
Regards, Paul.
Paul
Bang on the money
I work in UK manufacturing and your assessment is bang on. The minimum wage is due to go up over the coming years to >£10 so unfortunately, whilst the Guardian are attempting to win some sort of popularity contest, what they are highlighting is that in 2 or 3 years time, even more of whats left of the UK manufacturing businesses which employ people on minimum wage will be forced to move even more UK manufacturing abroad to protect their margins. This is nothing new as most people in the UK will realise its been happening since the 90's.
Another example of "The Sun" type sensationalism from the Guardian
What I meant was whether the relationship with suppliers was wholly arms length. That might be reflected in the prices paid for garments. The suppliers could be making high profits from low wages / favourable selling prices. The newspapers are hinting at close relationships with suppliers.
All guesswork until the review. Let’s hope that we get the full picture.
I don't think waiting another week is an option for Boohoo - their model is based on very rapid response times to get initial quantities on their website. I would factor some air freight costs into your numbers rather than assume it all comes by land.
Also there is an import duty to pay - currently 12% on dresses. Edit - scrub that as Turkey/Morocco are apparently exempt.
There are quite a few 747's going cheap at the moment..
https://www.salaryexpert.com/salary/job/seamstress/morocco
29.29 د.م. (MAD)/hr
Average Hourly Rate
= £2.38
https://www.salaryexpert.com/salary/job/seamstress-seamster/turkey
17,76 ₺ (TRY)/hr
Average Hourly Rate
= £1.80
I have no way of checking how accurate these numbers are,
Ian.
I think Boohoo (LON:BOO), and all very low cost online fast fashion, also faces some very under-estimated other regulatory risks from an environmental perspective even in short to medium term.
All political parties were made significant pro-green moves in the last election and, like pricing plastic bags in supermarkets, these can be relatively quick and easy to implement. (I note this easy vote winner is being re-cycled (geddit!) through pricing up plastic bags again and extending the regime to smaller shops.) With climate change and species extenction ever more visible, the environment is a trend that will outlast Covid and is popular with all ages.
It also, perhaps as part of a new overall online tax regime, provides an easy source of new revenue for an innovative chancellor looking to raise significantly more tax without being seen to break manifesto promises on income tax . Rebalancing in favour of bricks & mortar vs online will also likely be superficially popular - especially since as these are relatively favoured by the grey conservative voters (although COVID has probably closed that gap a lot) and employ a lot of young people.
If this online tax were done with a flat rate component (say 50p on every delivery) plus progressive component x% of value) which would make some sense to an economist, it would hit low-cost, high environmental impact disposable product online retailers like BooHoo much harder than forcing them to source ex-Morooco (see Paul's 9p/item finger in the air estimate).
For this reason (amongst others) I favour and hold Next (LON:NXT) (online platform) and Sosandar (LON:SOS) (higher price point online retailer) > £BOO (highly rated, online) > Marks And Spencer (LON:MKS) (bricks&mortar led).
None of this deals with the is it better for fashion to have its 'slave labour in Leicester or Morocco but as others have said fashion is not going to get rid of cheap labour until it all automates (when it will put millions out of work!)
agree 100% with you on Boohoo Paul although I quite welcome the Guardian negative articles as it means I can top up my holdings . Don’t agree with you on eating at Franco Manca though. Early death junk food,quite frankly .
I don't know how you come to that conclusion about Franco Manca? They do excellent salads, and their pizzas are just bread with tomato & a bit of cheese on top, and a sprinkle of whatever other ingredients you've chosen. Nothing is fried, and they use olive oil as a dressing. To my mind that comes nowhere near your flamboyant description of early death junk food! Have you eaten at Franco Manca at all?
yes on two occasions. We have a branch about a minutes walk from my house in Richmond. If you think the food is healthy then your idea of eating healthy food is very different to mine . Not too worry,let’s concentrate on financial matters.
I see Wetherspoons have today launched their own promotion called "Stay Out To Eat Out". The promotion runs for 10 weeks until the 14th November (I guess that date will probably have something to do with the autumn budget). The company is offering around 30% off Deli meals, Pizzas and Burger meals because these meals are their best sellers. Also, all hot drinks are now 99p with unlimited refills.
For anyone researching Gear4music Holdings (LON:G4M) the company has pointed us to a helpful broker note this morning which contains a lot of helpful detail e.g. about the company's competitors in Europe. It also expects EPS for FY21 of 26.8p which is a bit higher than I had pencilled in. Available here. (I'm long)
Patrick,
How have you (or Paul or rest of community) found Progressive Research? Its new-ish to me.
Obviously it is paid for "puff" vs 'independent' research but its website's front page says it will focus on giving "small to mid size private companies not getting the attention they need especially in the new regulatory environment" - sounds like good for private investors in small cap ie us !!
The report on G4M took a long time (30 pages!) but had a good summary and some good tables with interesting and detailed info . (Personal gripe - why do so few companies put tables into their releases - so much faster and clearer to comprehend.)
This is the first time I've come across them so I have no view on them as an outfit. As you say the note is detailed though and has some useful information that'll save hours of personal research.
Yes, Progressive is 'paid for' and thus in the same mold as Equity Development (see comment 4 for Paul's endorsement here https://equitydevelopment.co.uk/about-us/testimonials/ ). As long as you bear in mind that they are not going to be rude about the company that pays them they will give you plenty of extra material to inform judgement.
If you go straight to their website you will need to register (free). You will then get an email alert when they publish a report, e,g, at 07 37 this morning I had one subject 'Equity Research Alert - Gear4music (Holdings) plc'. With the company in the subject line you can just delete without opening if it is one that does not interest you.
Apologies - I am unable to upload V10 of my news code last week and this morning.
I just want to say a big thank you to the 16 individuals who have taken the time and effort to “buy me a coffee” or five! I know it doesn’t look like I’m making much progress but each day I’m slowly adding a few extra lines of code to make the process smoother and more automated.
When the site was down last week, I did think about batch emailing you all the news but held off as I have not tested this and didn’t want my first email to you been a bit of squeegee-beef code.
More effort will be put into this and I will reward these guys with something one day! :)
Cheers!
Thx HS.
You have been missed :-)
Paul is dead right you only have to look at other companies hit with such scandals and how fast they recovered e.g. Nike's history the perfect example. BOOs future will be no different to Nikes, a rising share price. BOO has a ROCE of over 20% similar to Nikes. ROCE alone will power this stock to new highs after a few potential dips today and maybe even wheb BOOs investigation is complete but highly possible this will be 500p by chrimbo.
My morning smallcap tweet: AA T/O PUSU extended
Urban Logistics Reit (LON:SHED) Nanoco (LON:NANO) Immotion (LON:IMMO) Location Sciences (LON:LSAI) £G4M Cake Box Holdings (LON:CBOX) AA (LON:AA.) AFC Energy (LON:AFC) Cambridge Cognition Holdings (LON:COG) Image Scan Holdings (LON:IGE) Eden Research (LON:EDEN) Induction Healthcare (LON:INHC) Avation (LON:AVAP)
Urban Logistics REIT (SHED) plans fundraise for more acquisitions. [SP=146.5 Cap=276m]
Nanoco (NANO) CEO resigns but will remain available to the Company as a Special Advisor, He is thanked. CFO becomes CEO. [SP=16.8 Cap=51m]
Immotion (IMMO)ImmotionVR sites have operated on limited opening times, but have all traded strongly, generating a profitable contribution after all local costs. A number of attractions in key Partner sites still closed. Expects to launch the Let's Explore in-home consumer product later this month. [SP=4.6 Cap=17m]
Location Sciences (LSAI) wins first customer to its Verify Audience platform. [SP=0.44 Cap=2m]
Gear4music (G4M) last 2 months trading has remained strong, guides FY at least in line with recently upgraded expectations. [SP=565 Cap=118m]
Cake Box (CBOX) last 3 month LFL rev up c.14% in franchise stores. Online up 74%. Will pay special dividend equal to the withdrawn final div.. [SP=176.4 Cap=71m]
AA (AA.) Discussions with each of the Potential Offerors have continued to progress and their due diligence is on-going. PUSU deadline extended to 29 Sept. [SP=34.7 Cap=216m]
AFC Energy (AFC) sells bespoke 100kW alkaline fuel cell system for delivery and commissioning in Q3 2021. Mainly funded by German govt. No £££. [SP=19.5 Cap=132m]
Cambridge Cognition (COG) wins £2m contract for three late phase schizophrenia trials. [SP=39.5 Cap=12m]
Image Scan (IGE) H2 better than expected. Guides FY rev £3.3m to £3.5m, profit 0 to £100k. [SP=2.4 Cap=3m]
Eden Research (EDEN) gets regulatory approval for anti nematode product Cedroz in Spain. [SP=6.7 Cap=25m]
Induction Healthcare (INHC) subsidiary Horizon achieves earn-out target ahead of schedule, triggering £1.5m payment. [SP=89.95 Cap=37m]
Avation (AVAP) Virgin Australia unsecured creditors to get 9%-13%. AVAP claims $74.7m. Five of the 13 aircraft have been re-leased. [SP=125 Cap=78m]
Completely agree with your view, I bought more BOO on the dip on Friday.
And I shall buy more if it dips again today!