Small Cap Value Report (Tue 10 Oct 2023) - RCH, TET, IPX, WIN

Good morning, it's Paul & Graham here!
It's striking how nearly all the updates today are "in line" - see our agenda below. EDIT - also interesting how it seems almost a lottery as to whether things surge strongly on in line updates (as we see today from Treatt (LON:TET) ) or in other cases, nothing happens, or they even fall on in line updates. The market isn't being rational at the moment, I think because there still seems forced/sentiment selling in some shares, but not others. So if you're trying to make sense of share price movements, don't bother, they often don't make sense right now! It's just supply and demand, driven by all sorts of factors.
I wonder if we are now seeing the capitulation phase of this bear market, with people just giving up and selling in despair? It feels a bit like that doesn't it? You won't find any despair from me or Graham, with such attractive value on offer. Equity investors have to be resilient, and accept that the market quite often takes fright, and experiences big falls. It always recovers though, that's the thing to remember. If you're holding good quality shares with no gearing (both at the companies, and in your portfolio) then we can ride out patches like this, and probably catch one or two takeover bids too. So it's not all doom and gloom by any means.
Some might argue that we need to take some pain now, as a necessary precursor to central banks reducing interest rates in future. As mentioned in my last podcast, I think political pressure is likely to build on central banks to loosen, especially as inflation is now coming down, as supply problems ease, and elections loom. One thing is certain though - nobody knows what will happen, and it will probably surprise everyone, as events of the last year have demonstrated! So the fewer predictions, the better - especially when they're forcefully expressed with total certainty - a sure sign that the commentator is clueless!
Graham Youtube show today (starts 11:30, but recorded) is covering Reach, Impax, and maybe Treatt.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Amazingly, nearly everything is "in line" - so we'll just cherry-pick the companies that we think offer good value/GARP from this list, and the ones that readers tend to discuss the most, and the biggest price movers -
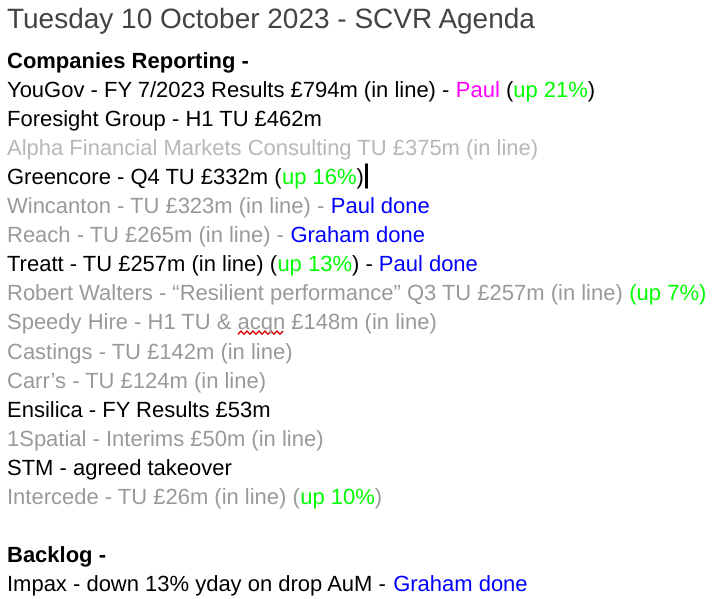
Summaries
Reach (LON:RCH) - up 2% to 82.55p (£262m) - Trading Update (in line) - Graham - GREEN
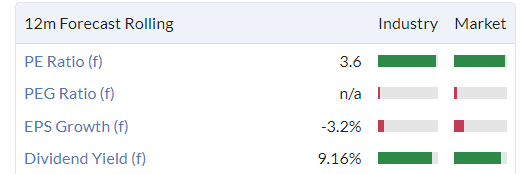
I remain positive on this, although I do believe that it’s a low-quality punt. More details on the scheduled pension contributions are needed and should be out with the full-year results next year. Enterprise value is probably over £500m but adj. operating profit forecast is c. £95m.
Treatt (LON:TET) - up 13% to 477p (£289m) - Trading Update - Paul - AMBER/GREEN
Despite some de-stocking by customers in H2, it's still managed to achieve FY 9/2023 profit expectations. It's a capital-intensive business (large fixed assets, and excessive inventories stand out), but generates a fairly decent return. There could/should be further upside from the new factory that's not come on stream, and the valuation has at last come down to something a bit more palatable, so I'll move my opinion up from neutral to moderately positive!
Impax Asset Management (LON:IPX) - 408.5p (£540m) - Q4 AUM Update - Graham - GREEN
I’m excited to see this fund manager with a “sustainability” focus trading at value levels. Given the popularity of the niche and the success of Impax, I think this deserves a higher rating than other managers. Inflows are marginally negative but AUM is still up year-on-year.
Wincanton (LON:WIN) - up 1% to 261p (£325m) - Trading Update - Paul - GREEN
Reassuring, in line with expectations year end update. Attractively low PER, good divis, and with the pension scheme now fully funded, the outlook looks bright. I could see earnings rise in future, as this year was hit by a lucrative contract loss. So I remain positive, although I don't like its balance sheet still, but that's not a deal-breaker.
Paul's Section:
Treatt (LON:TET)
Up 13% to 477p (£289m) - Trading Update - Paul - AMBER/GREEN
Treatt, the manufacturer and supplier of a diverse and sustainable portfolio of natural extracts and ingredients for the beverage, flavour and fragrance industries, today publishes a trading update for the year ended 30 September 2023 ("FY23").
Profit growth returns with resilient revenue performance
I don't see revenue as resilient, it fell in H2! So this headline is a bit off. I think they should have flagged that profit is in line with expectations, despite softer revenue in H2, that's the key, and stronger message.
A nice 13% surge in share price this morning has grabbed my attention, although it’s in the context of a sharp fall in recent weeks, here’s the year-to-date chart -

To further set the scene, you can see below that forecasts were considerably lowered in autumn 2022, but have been stable since -
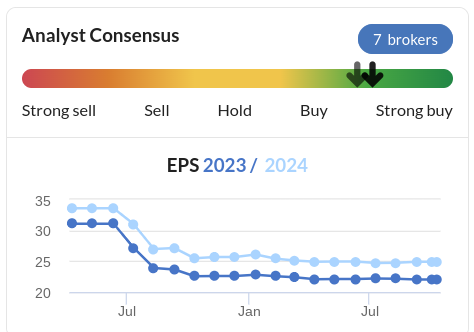
This share has previously struck me as too expensive, based on lacklustre forecasts. However, the bull argument was always that the forecasts understated the revenue and gross margin growth potential from its new factory that’s been coming on stream this year.
Graham reviewed its H1 (6m to March 2023) results here on 10/5/2023, key points being - H1 in line with exps, adj PBT up 15% to £7.3m, shares too expensive at 650p (27x forecast PER), outlook in line, and order book strong. He viewed it AMBER at the time.
What’s today’s news then? For starters, even after today’s surge, the price of 477p is much more palatable to me (lower!) than the 650p when Graham last looked at it.
FY 9/2023 revenue £147m, growth of only 5% (3% at constant currency), which it calls “resilient” after “industry de-stocking headwinds”.
(note that H1 revenue growth was +14.6%, so H2 works out at -3.7%, a sharp deterioration versus H1, and this is at a time of food/drink price inflation, so revenues shouldn’t be going down).
Adj PBT guidance is fine though, at c.£17m, in line with Board expectations. That’s a healthy 11.6% PBT margin, indicating some pricing power I’d say.
Passed on cost price inflation successfully.
Good cash generation evidenced by net debt of c.£10.5m (down from £22.4m a year earlier, and £18m at end H1.
Completed refinancing of £25m HSBC facility for 3 years minimum, so liquidity sounds fine, no concerns there, especially as the big capex has now been completed.
New UK factory - “transition now complete”.
FY 9/2023 results due out on 28 November - a fairly prompt reporting cycle.
Why would food/drink makers be destocking? I don’t understand that bit, surely it’s a continuous flow of ingredients? That might be a good question to ask in a webinar. The commentary said customers wanted to hold less inventories, due to higher interest rates - makes sense I suppose, and “early signs of a reversal of this temporary destocking effect..” OK I think that satisfactorily explains it. I was worried talk of de-stocking might be an excuse for an underlying drop in demand, but probably not.
Broker updates/ forecasts - nothing available. Come on Treatt, you need to keep your smaller shareholders & potential investors informed, so get something onto Research Tree please!
As it’s in line, then we can probably rely on the 22.0p broker consensus shown on the StockReport. That gives me a PER of (477p/22.0p) = 21.7x - hardly a bargain.
Although given that the new factory should be kicking in with better margins, and higher production capacity, then I think it’s reasonable to suggest that future earnings might rise to say 25-30p. That gives a PER range of between 15.9x and 19.1x - still not madly exciting. So bulls must be anticipating further growth beyond that - which is a reasonable assumption, as otherwise there wouldn’t have been much point in building & equipping a new state-of-the-art factory.
Balance sheet - as I keep emphasising in my podcasts, we can avoid companies with wobbly balance sheets and debt, which have been some of the worst profit warnings of late, which breach covenants and need more equity funding.
I’m pleased to report that TET’s last balance sheet is really strong, but note it’s tying up an awful lot of capital in both fixed assets, and excessive inventories. The return on that heavy net asset base doesn’t seem exciting. Hence I personally wouldn’t see this as a particularly high quality company, although Stockopedia gives it an upper–middle quality score of 72. Although maybe returns on capital could improve as the new factory beds in?
Paul’s opinion - mildly positive, taking a long-term view, I’ll go with AMBER/GREEN.
Today’s update reassures, and I particularly like that it’s coped with a downturn in H2, blamed on de-stocking, that has been absorbed within existing forecasts - due to nicely offsetting price rises, and cost savings. Note that headcount has reduced by 12%.
It seems reasonable to expect FY 9/2024 figures to further improve on FY 9/2023, so I can see some appeal to this share.
Wincanton (LON:WIN)
Up 1% to 261p (£325m) - Trading Update - Paul - GREEN
Wincanton plc, a leading supply chain partner for UK business, updates on trading for the six months ended 30 September 2023.
This is one of my least successful stock picks for 2023, being down 23% year-to-date, mainly due to a profit warning from the loss of a lucrative contract. Although shares have been making some recovery progress since, despite hideous small cap market conditions.
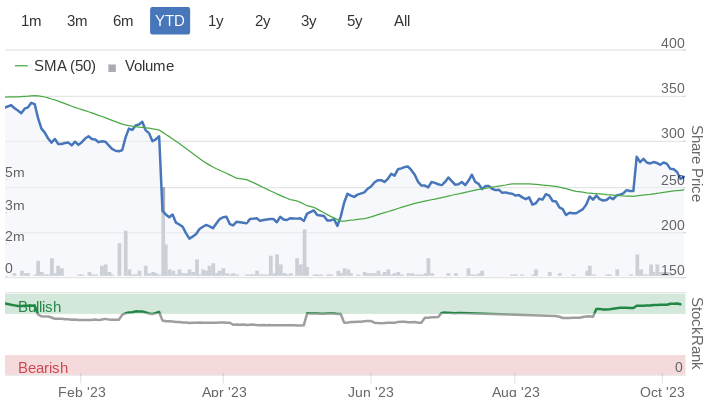
We had excellent news recently (see SCVR 21 Sept here), confirming what had previously been indicated, that the very cash hungry pension scheme is now fully funded.
A brief update, which strikes me as reassuring -
The Group continues to trade in line with market expectations.[1] As in prior years, profit is expected to be weighted towards the second half of the financial year, reflecting our seasonal peaks and the onboarding of new customer wins.
In line with the Q1 Trading Update, total revenue is expected to be lower year-on-year, reflecting the strategic reorganisation of the Group's transport operations.
[1] Current market consensus for FY24 PBT of £50.3m
This works out at about 31p adj EPS.
I don’t mind H2 weightings if that’s the normal seasonal pattern.
Very helpful also to have a footnote, telling us what market consensus forecast is, thank you for this, all companies should be doing this, to be investor-friendly, no excuses!
Has there been a change of policy at Numis I wonder? Normally they actively repel private investors, and don’t let us anywhere near their clients (which is crazy for small caps!). However this bit below sounds as if it might actually be possible for investors to penetrate the inner sanctum of Numis’s offices to meet Wincanton management. Or am I dreaming?!

Valuation - based on 31p EPS forecast for FY 3/2024, the PER is 8.4x, and I think there’s recovery potential in the future earnings, as this year was hit with the unexpected contract loss.
Paul’s opinion - I still don’t like the balance sheet, but it probably doesn’t matter. The PER is attractively low, and the dividend yield attractive, and sustainable or increasable, given the end of pension cash contributions.
Looks a nice business, and shares seem good value, so I’m happy to stick with my usual GREEN view.
Graham’s Section:
Reach (LON:RCH)
Share price: 82.55p (+2%)
Market cap: £262m
This is an in line update for Q3. Profit expectations are for an adjusted operating profit of £95m.
Revenues remain in reverse, both online and in print:
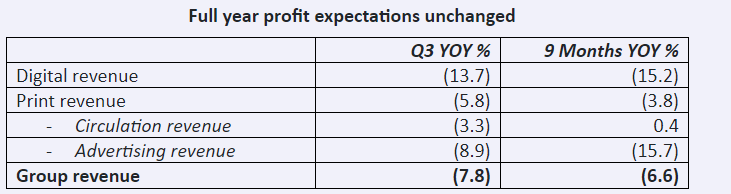
The explanation is simple enough, and the same as last time:
The factors affecting Q3 digital revenue are unchanged from those outlined in our half year results. These include depressed open market yields and the well-publicised declining digital referral volumes, in particular from Facebook's de-prioritisation of news. As a result over the nine-month period, year-on-year page views declined 21%.
Capital reduction - this is a technical accounting trick whose typical purpose is to allow a company to pay more dividends than its balance sheet would otherwise allow. It’s pleasant news when a company applies for this, as Reach announces that it is doing.
MGN pension scheme - this enormous pension scheme had a deficit of £476m as of December 2016 - you might ask why I’m using a number from 2016, but the company has been taking its time giving us updates on this one!
We are pleased to report that we have now concluded the 2019 triennial valuation for the MGN scheme, and at the same time concluded its 2022 triennial valuation.
The deficit for December 2022 is a mere £219m. Payments to eliminate this deficit will increase from £40.9m to £46m p.a., and will stretch until 2028.
The other pension schemes at Reach - “Trinity” and “MIN” are the subject of ongoing discussion. They are smaller but still material.
Outlook: “confident” of meeting profit expectations.
We do not anticipate the market backdrop to change materially in the near term and as a result we remain focused on the areas within our control; improving customer engagement, diversifying revenues and driving efficiencies. Our plans to reduce full year operating costs by 5-6% remain on track. We expect a High Court judgement on time limitation relating to historical legal issues in the next few months.
The fallout from the phone hacking scandal has been going on for about a decade. I don’t know what the legal position is but surely it must come to an end at some point? There is a six-year statute of limitations for many types of civil lawsuits.
CEO comment:
"This quarter we see continued evidence that our data driven strategy is working, supported by our resilient print business. Through this challenging period we have remained focused on the controllables. We are delivering our Customer Value Strategy and have made progress diversifying our audience. We continue to review our cost base so that we can accelerate our digital transformation."
Graham’s view
As I did before, what I want to do is add up the scheduled pension contributions (ignoring time value of money) to get a simple estimate of the enterprise value here.
The previous total contributions were £300m.
There are some new factors I have to take into account.
Firstly, the MGN scheme contributions are increased by £5m p.a. and are being extended for an extra year.
Secondly, 2023 is nearly over so I’m wondering if nearly all of the 2023 payments have been made already.
Thirdly, the other pension schemes could see adjustments announced in the next few months.
My best guess of future pension contributions is:
2024: £61m
2025: £61m
2026: £62m
2027: £60m
2028: £55m
2029: £9m
Add all of this up and I get £308m. This is a very rough estimate, probably with lots of errors, but hopefully it is somewhere in the ballpark. We will know more when the full year results are announced.
This means my estimate of Reach’s enterprise value is little changed vs. the last time I looked at it: £570m (vs. £540m last time).
With an adjusted operating profit of £95m, even in terrible market conditions and facing an enormous headwind from Facebook, I’m going to maintain my positive stance on this one.
As I said last time, I do consider this one to be a low-quality “punt” but I think the risk:reward is interesting.
The computers love it, for obvious reasons:
And remember that it somehow reached 400p in the post-Covid boom, five times the current share price:

Impax Asset Management (LON:IPX)
Share price: 408.5p
Market cap: £540m
My thoughts turned to Impax the other day when I saw that ESG funds were suffering some significant outflows: £500m withdrawn in August, a record amount for a sector that had been in uptrend like no other.
In a tough environment for flows generally, it seems that ESG is finally beginning to struggle.
Ethical funds and similar mission-oriented investments have been around for decades, but ESG really took off during the last bull market. I’ve previously suggested that after a punishing bear market, investors might want to put a higher immediate priority on returns than on ethics/ESG. Perhaps this is where we are today?
This is the context in which Impax released its Q4 AUM yesterday.
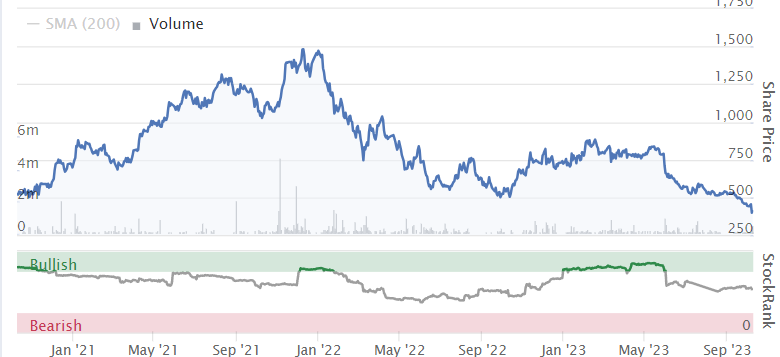
Note that the Impax share price is already down by more than half from the high it reached earlier this year. This brings it comfortably back within the domain of the small-cap report. The share price fell by another 13% yesterday.
In total, it is down by c. 72%:
Latest update:
On 30 September 2023, the Company's AUM totalled £37.4 billion, representing a decrease of 5.8% over the three-month period since 1 July 2023 and an increase of 4.8% over the financial year since 30 September 2022.
CEO comment excerpt:
"Investment conditions continued to remain challenging during the final quarter of our financial year, when moderate redemptions from several of our distribution partners compounded market-driven falls in net asset values…
"Although the macro environment is leading some clients to delay deploying their capital, we remain confident in the strength of our pipeline and our ability to convert. Meanwhile, we continue to develop new investment capabilities while enhancing our operating model to ensure that the business is efficient and scalable."
Checking the tables, I see that net flows are negative for the quarter (minus £893 million) and marginally negative for the full financial year (minus £92 million).
Market movements are negative for the quarter but positive for the year as a whole.
So the full-year performance shows an increase in AUM. It’s remarkable that the market cap can fall so precipitously even though AUM has increased!
Graham’s view
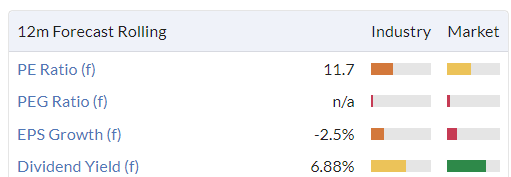
Let’s do my standard calculation, and divide AUM by the market cap. I get £69, i.e. for every £1 invested in Impax, the investor gets £69 of AUM.
This might be the cheapest I’ve ever seen Impax trading at. In May, you only got £42 of AUM for every £1 invested in Impax. The share price had already been cut in half by that point from its all-time high, and I was willing to give the stock the benefit of the doubt then.
So I am certainly going to give it the thumbs up today. Nothing is certain, but personally I think this looks like excellent value here, for a high quality stock.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

72 comments
Treatt (LON:TET) (no position)
For any holders of artificial additive companies you may be interested in slide 4, which was published today by an international supermarket company called Jeronimo Martins SGPS SA (ELI:JMT):
https://www.jeronimomartins.co...
I never knew this was something supermarkets were striving to achieve.
1Spatial thanks Aislabie I missed the announcement and I agree with you will watch the update tomorrow on investor meet company good story to date
We seem to have got through the day without talking about 1Spatial (LON:SPA) (I hold) who published in line interim results today. Of course this is a tiddler and so only a few holders may be represented here and as with all micro caps quite small single events can provide nasty financial surprises. Having said that I am becoming increasingly confident that this company can grow to be a successful larger business.
The revenue growth is occurring not only in most geographies but 50% is in recurring contracts. It has a small net cash position and made a small net loss in H1 as it invested in the people necessary for further growth. To be convincing it needs to show that it can make the small net profit forecast for the year. There is a quiet confidence about how the management has gone about steadily building its “911” traffic management software business in the US with wins in successive States against US competitors. Their UK business of tracking utilities lines asa basis for planning and maintenance can surely have a great future. I am not “all in” on this investment yet, but if they can build a bit of financial heft in the next 18 months there could be far to go.
Hi Aislabie,
Yesterday was one of those days where we got overwhelmed with the volume of trading updates. I did have a very quick look at 1Spatial (LON:SPA) and thought it might be interesting. So I might have a look at that one next time it issues a TU - feel free to give me a nudge at the time!
Thanks for flagging.
Regards, Paul,
Calnex Solutions (LON:CLX) have put out a trading statement, which is actually a profit warning, at 15:17:06 this afternoon. I did not see this until now (17:35) and I note the share price was down 30% at the close today. Not really a great surprise that there was a profit warning, as other companies in the sector have reported issues, but putting out a trading statement mid afternoon seems a little underhand to me. (Sadly I hold).
Makes sense with Spirent's previous warnings i guess.I looked at the last presentation on investormeet and really liked the ceo and the growing area they are in.It seems it's cyclical to an extent at the moment at least as i guess the big telecoms companies are cutting back on capex for the moment.A lot of good companies getting hit by profit warnings lately.
Depressingly predictable PW incoming this afternoon from Calnex Solutions (LON:CLX. Cavendish revise PBT forecast to zero. Revenues will have to grow by 50% in FY25 to bring the PER down to low 20s. A pity and not really the rather likeable management's fault. Unless you blame them for listing near the top of the cycle. But there it is.
Once bitten (Spirent Communications (LON:SPT) ) twice shy!
Impax Asset Management (LON:IPX) - A slightly disappointing Q4 update got brutal treatment yesterday in this market. For the year as a whole they have done OK.
I've still a sizeable stake purchased at about 50p although I sold about 60% or so. They still need a private markets deal / fixed interest deal to rebalance the business in my view. They should have more than £564m in private assets AUM, particularly given the better fee rates on this side. I feel this was a missed opportunity as they should have done a deal with equity at £15!
Anyway, I am sitting tight with the rest. A painful drawdown since the high, that's for sure. It should start growing again at some point, but could have a few more tricky quarters. At least there is a chunky dividend.
Ah, interest rates. I was talking to a mate in America who knows a lot about (US) bonds. I'm a duffer at all that, but this is what I gather ...
He said that the bond markets are pretty crazy right now. For example, the US 10-yr bond yield is 4.7% right now, whilst the German 10-yr bond yield is 2.8%. It doesn't make any sense is what he's saying. I asked him why folks don't just buy US bonds and sell German bonds to make a gain, but he said that there is a huge bet that the (US) Fed will sell bonds, meaning that they'd be fighting the Fed, which has unlimited firepower.
I see that both German and US bond yields are up today, even. So it looks like the markets really really thinks that interest rates are headed higher.
But contrarianwise .... I did see that the US is in the greatest Treasury bear market of all time. Historically, treasuries have then gone on to produce a good profit (except for the 2002 trough, where they were flat).
So whatever happens, it's unlikely to be boring.
This mate of yours does he know the actual rates for the Eurozone and the Fed rates and hence the reason of the spread?
Does he know what international capital flows mean for the pricing of the bond markets?
Thanks
No idea. I just asked him noddy questions to see what he thought. He's a pretty smart guy, so I assumed he knew what he was talking about.
I heard that earlier today the Fed announced that it wasn't likely to sell more bonds, so maybe the contrarian trade of buying 10Y US treasuries is actually has legs.
But like I say, I know squiddly about bonds, so I've really just been asking questions rather than formulating any kind of strategy. So it's a case of DYOR, caveat emptor, your home is at risk if you do not keep up the mortgage payment on them, etc.
US bonds price in at the moment a government debt that is not sustainable and very difficult to come down without some hard sacrifices.
I'm not sure what US govt bonds are pricing...but its more likely higher sustained growth and associated 'healthy' inflationary pressures in the US than anything to do with debt unsustainability as in that regard UK, Europe, Japan and China don't look healthy either...
fwiw I think level of govt debts can be significantly ignored particularly if you are issuer of the global currency as the ability to to do 'imaginative' things with/to it are fairly endless (2008 and after proves that money is fantasy not real/tangible...and where debt touches the money issuing magic it too becomes at least part fantasy). If we look at private debt then there has been a lot of self-healing on a relative basis in US and Japan, somewhat in UK and much less in Europe.
Overall I'd bias more to the idea that low yields in Europe show it has a problems relating to lack of growth and structural deflationary pressures (that could prove stagflationary). HY and weak USD denominated sovereign debt (generally frontier markets) hasn't cracked yet. If they do then the blow back into global credit risk could be interesting. I'd bet USTs get a strong bid....and Europe probably has another sovereign debt crisis (maybe compounded this time by it blowing up private credit seeing the yield of european corporate debt move significantly above US, and probably UK, from its current c.1.5-2% lower yield)
But I don't really know....and only time will tell
This time it is real and not a fantasy as this excess debt is actually circulating in the real economy; but I do get your point on the 2008 example and tend to agree.
I don’t know as well (just a personal opinion based on actually experiencing similar events) and yes time will tell!
We will probably have a clearer view (regarding growth and inflationary pressures) in a couple of weeks when the top 5-6 companies start to report their latest earnings.
Re SDI (LON:SDI)
I've been a long term sceptic on the quality and so high valuation of this business in the past. For most of that time the share price has told me I'm wrong. I don't like the CEO and I'm sceptical of rollups that are a public-private valuation arbitrage and lack a 'synergistic' driver (I know there are examples where this has worked and created loads of return for shareholders...I'd argue that some combination of luck, timing and/or underlying 'magic' in logic and/or management have likely assisted these situations a lot and they aren't nearly as cookie cutter repeat as they appear)
Around current price is probably a good time to buy SDI from a long term perspective. Caution though as I say that without doing work. Also, in the short term I see some things that could weigh and make for lower price too (some emotion driven and some fundamental):
So, on balance of probabilities I think SDI is likely a buy (unless there's a real stinker or two businesses that are dying on them that we've yet to find out)...but it may not feel comfortable for a while as more than many businesses they need the economic and market mood music to lighten (as they are function of it rather than 'idiosyncratic' value creators)...
...and TBC...I'm unlikely to buy SDI personally for the biased stated above. To change my mind I would need a really sweet incentive price...so lop a good few 10s of pence off current price. I'd also like there to be some outward signs of stress or failure in bits of the business before I'd get involved as that would allow the sort of visibility that is lacking currently behind the wizard's curtain of rollup
The latest British Retail Consortium and Kantar data out today suggests we might be in for some soft revenue data among some consumer stocks for the last calendar quarter:
"Big ticket items such as furniture and electricals performed poorly as consumers limited spending in the face of higher housing, rental and fuel costs. The return of the summer sun also meant sales of autumnal clothing, knitwear and coats, have yet to materialise."
Also worth noting how bad online non-food retail sales are - down -3.6% in September despite inflation!
https://brc.org.uk/news/corpor...
Impax Asset Management (LON:IPX)
Graham says:
'I’ve previously suggested that after a punishing bear market, investors
might want to put a higher immediate priority on returns than on
ethics/ESG. Perhaps this is where we are today?'
Surely the priority for investors should always be on expected returns. Anything else is secondary at best.
Investing solely or primarily for other reasons e.g. tax savings (IHT), moral or ethical reasons, a biased liking for the product etc does not in itself make any sense (unless you like to have a cavalier approach to investing).
I tend to view ESG investing through a similar lense. Same for climate change investing and all the nonsense greenwashing that companies then feel obliged to spout forth.
Will ESG investing eventually turn out to be a passing fad?
An Emperor with no clothes?
The jury is out.
Snazzy
Investing solely or primarily for other reasons (than maximising returns... does not in itself make any sense (unless you like to have a cavalier approach to investing).
Nonsense. Plenty of investors prefer portfolios that skew to a certain factor, like quality or value, because they sleep better that way. One group knows they own only great, proven but expensive companies, which probably won't blow up on them; the other is happier holding possibly undervalued ones and staying patient. Each strategy is guaranteed to underperform at times. And they can't both be maximising returns!
Agree re investing in differing strategies.
However ESG investing isn't a strategy. It's simply joining a fashionable bandwagon on the uptrend. Wont take much for followers to jump ship.
There did seem to be an overpriced marketing gimmick look to ESG in 2020/21. Investors seem very fickle, willing to pay large premiums when the market is bullish but selling when things head south. Morals can only hold up for so long before self interest kicks in.
Don't hold but I quite like the look of Impax Asset Management (LON:IPX) so I'm keeping an eye on it. Net retail sales in "responsible investments" are interesting.
YOU: Well, Mr Market appears to have called these results completely wrong. We're up 143p +21% as I post. As RDHowarth mentions below - looks like fundholders' redemptions might have played a part in driving the shares down. YOU is high quality and usually highly rated so this has been a great opportunity to get on board. It's difficult to buy when the share price is on the slide - there's always that nagging doubt - 'what does Mr Market know that I don't?'
YOU are buying the consumer panel business unit of GfK - that are a forced seller due to Neilsen takeover - hence at a reasonable price. This should increase their revenue by a half for a cost of a third of YOU's valuation. It should thus be value -adding .
YouGov (LON:YOU) Another holding that I've been topping up this last month, and a little more today. I had been thinking of devoting a post on here to it, so low had the valuation fallen relative to the quality of its earnings and operating leverage. But the market reaction, and hopefully Paul's analysis, going by the agenda, have done my work for me. Revenues are still constrained by low demand out of the very important US tech sector, so I see potential for continued growth. And, as a growth stock, the potential for falling yields - eventually - would also be constructive for the price. Finally, according to Sharepad, Liontrust are no longer holders, so perhaps the overhang of disposals is behind.
I'm working on YouGov (LON:YOU) as we speak, but have missed the cut-off for today's report, but it should be ready for tomorrow. Been a while since I last looked at it, and the business has achieved remarkable growth. Quite a few accounting issues though! See tomorrow''s SCVR :-)
I’ve just been on our Grahams YouTube show- lots of great info on todays report with the added treat (geddit?) of Paul and I bantering in the comments section
A recommended listen either live (or later as it’s recorded)
Yes I also enjoyed Graham's youtube show today - basically a half-hour SCVR summary! I thought that was too long, but it actually went by in the blink of an eye. Being able to heckle/banter from the chat box was also a bonus LOL! :-D
Graham, great insights and I certainly agree with your take on Impax Asset Management (LON:IPX). I wrote about this in a note yesterday with some fairly detailed market data of the sustainable investing space if anyone is interested in that (disclosure - I am the Equity Development analyst covering Impax and a shareholder).
A couple of points I highlight is that the UK retail investor outflows are certainly not replicated everywhere. Flows into sustainable investing funds (including from institutional investors, Impax's main market) in greater-Europe (by far the largest sustainable investing market) have held up well compared to conventional funds, and there is a flight to quality that should benefit Impax ('dark green' fund flows stronger than 'light green', and climate funds especially are looking strong).
So looking strong longer term in my opinion. But most recent quarter was indeed a tough one!
Summary blog here: https://investingintheinvestor...
Equity development note here: https://www.equitydevelopment....
re: £IPX
Thanks Paul - I've grabbed a copy of your note. Cheers!
Sosandar (LON:SOS) Down 25% over the last month and I cannot see a reason why. Capitulation selling?
It hasn't updated the market for ages, revenue growth had been reducing markedly, other online retailers are performing poorly, and the warm weather this summer & autumn means no-one's buying coats/jumpers etc yet?
I noticed this too - but also saw that broker forecasts appear to have been raised by circa 27% in the past few days which all doesn't quite add up. A half-year trading update was provided mid October last year - perhaps the broker has already seen this?
September retail sales were bad, especially for fashion. Too warm still for AW clothing sales.
And the barrage of bad/soft trading updates from other fashion retailers of late.
So not surprised Sosandar (LON:SOS) have drifted; and they're more exposed than others, as the forecasts have baked in a good sales growth rate, which is in potential jeopardy.
Perhaps Sosandar (LON:SOS)'s end of the market is holding up better? e.g. Next (LON:NXT)'s recent results were more positive than expected.
Still confused why Stocko is showing broker forecasts up yet the share price is going down...
I don't 100% trust the broker forecast numbers in Stocko. Especially small caps where there's only one or two brokers forecasting.
The market values Treatt (LON:TET) not as a typical food producer, but instead as an ingredient manufacturer. These companies have high valuations because of the resilience of their income - their ingredients make up a very small proportion of the cost of food manufacturers products, but are hard to displace owing to their importance to the ultimate taste.
A comparison to larger peers Symrise and Givaudan shows that all constituents of this sector have been suffering a destocking cycle. Treatt’s recent difficulties are not idiosyncratic and recent fluctuations in demand, both up and down, are symptomatic of the pandemic distortions rather than an indicator of typical cyclicality.
A further comparison will show that Treatt is hugely undervalued next to its larger competitors, despite better growth forecasts. As Treatt counts the larger competitors amongst its customers - its ingredients go into their ingredients - it is not a big leap of imagination to see that any peer seeking better vertical integration would see Treatt as a clear target for synergistic and, at this valuation, highly accretive acquisition. Whether this occurs or not, I like the prospects for this quality name.
I have been building a good sized position at these values and topped up to full size today on what I saw as a very reassuring update.
Warpaint London PLC - 27 Sep 2023 - YouTube
For anyone who may have missed this vid with Sam Bazini CEO of Warpaint London (LON:W7L)
I liked his straight talking style, honest and a safe pair of hands I would think. I also like the capital light business model that Warpaint runs.
abrdn also dumping XP Power (LON:XPP) but that's a bit different. Might be killing two birds though - exiting an unwanted position while suppling cash for redemptions.
Paul I'd suggest arbdn have finally woken up to Motorpoint (LON:MOTR) being the next pile of Cazoo and will probably exit completely if they can salvage anything. As for Naked Wines (LON:WINE) well that hasn't got any legs has it? They've probably sold to get a round in! Basket cases and poor business models should surely be avoided at the best of times, more so now.
Morning all,
Inline statement from Alpha Financial Markets Consulting (LON:AFM) today- growth has slowed from historic levels but this looks to be trading on a single digit PE (ex cash) and yielding around 5%. I've historically had the impression that this was a high quality outfit but always looked quite expensive.
Not one that the SCVR has looked at before (as far as I can see)- are there any insights/thoughts from holders on the potential for a resumption of growth nearer to historic levels? Performance looks fairly resilient for a consultancy focused on the asset management industry
Thanks
I agree on the capitulation Paul. I thought we'd see a grind lower as most sellers were already out but the last 7 days or so has looked like sellers dumping at any price just to stop the pain. No buyers and yet more redemptions. Even midcaps like YouGov (LON:YOU) all sellers then bounces 14% today on decent update.
Quite a few companies look like possible multibaggers to me if markets normalise in the next couple of years. But it's a very difficult macro environment to predict (guess)all sorts of things could go wrong so I don't blame people moving to increase cash. Would be a minor miracle if the rapid rise in interest rates didn't break something and cause a panic somewhere next year. I loved a phrase I think you said on a podcast "posh gambling" That about sums it up. Really we don't have a clue what's going to happen.
While the UK small caps in particular have been throwing in the towel the S&P has been finding buyers right at the point you'd expect. Just off the 200day ma and October uptrend. MACD now triggered a good looking buy signal also. I'm leaning towards a decent year end rally but if the recent low doesn't hold I'd become much more bearish.
Re YouGov (LON:YOU) I would argue go to major shareholders tab under accounts....top of the list is Liontrust, who are experiencing huge outflows. So you have a stock that had weak guidance before today...and a forced seller every day ... longer term I thought YouGov (LON:YOU) might be interesting.
I also had a quick look at PRS Reit (LON:PRSR, it trades at 40% discount to NAV. Interesting perhaps? The thing is that's a rental yield of 4.5%. Even though occupancy is 97% and rent collection is 99%...financial markets want a higher return, hence the discount...so the dividend yield compares better to say Gilts or Bonds. And there is the problem in a way.... but if you are investing today you get that higher return. Im not saying it's a buy, I'm just saying you get a much better return than you did. As long as nothing goes wrong it will be a much better investment today. As to whether that turns out to be good investment depends on all sorts of stuff like inflation and interest rates....
I have no interest in either stock.... just stuff im thinking about.
I like PRS Reit (LON:PRSR) too, but yeah, there's not much more they can squeeze from 99% occupancy. Its a bet on rental yields continuing to rise fast.
Currently yielding 6% dividend, but not fully covered by earnings. Even if it was, why would I buy PRS when I could get 6%+ in a 1-year fixed savings? Especially as house prices look like they'll drift lower or stay stagnant over the next year.
So I expect it to drift to be cheaper - at 6.5%, 7% yield it then is tempting enough.
Boon Do you think in 12 months time you'll still be able to get 6%+ on a 1 year fixed savings deal? And what price will PRS Reit (LON:PRSR) be then? Could lock in that 6% yield now for the longer term and possibly see a little capital growth as rates head back down in 12 months or so? Not that I have but that is where I'm seeing the trade off.
Of course if rates stay higher for longer the opportunity should exist to switch too. For me this is similar to housebuilders and the like. Feels like I should invest in the sector soon but maybe not just yet. Let's see what the FED do at the next meeting - 'cos the brilliant Bailey will surely follow suit.
love your graph. I used to be able on all share I was interested in automatically over lay with 50d sma and 200d sma. Temporarily lost the ability with HL and Stockopedia can't understand of let me just have that ability. Is it easy to just have it plumbed in on my computer? You look to be a wizard (hopefully not too complicated) with this issue?
Any thoughts on how much of AIM's fall is due to IHT portfolios being unwound? Seems that the IHT tax benefits may disappear in the next year or so.
Do we have any data on if, and by how much, IHT portfolios are being unwound? I'd be surprised if they are being unwound. Given that any potential abolition of IHT would only really be an aspiration, for what statistically is reckoned to be an outgoing Govt, with the likely replacement highly likely to reverse any IHT abolition, then I don't see it as a likely contributor to AIM falls, but who knows, we need to see some numbers, rather than our hunches!
We can see from the RNS that some open (edited) ended institutional funds are bailing out of small caps, probably due to client redemptions. Just yesterday I noted that abrdn had reduced its position in Motorpoint (LON:MOTR) from 10% to under 5%. Something similar was announced in Naked Wines (LON:WINE) shares too, a big institutional sell.
It'll all wash through in the end though, the same thing happened in 2001-2, then in 2003 small caps had a stellar year once the sellers had been cleared out, and new money was attracted by rapid gains. With so much money parked on the sidelines in cash, I think the rebound next time could be just as good as 2003, but no idea on timing.
Regards, Paul.
Apologies for typo, now corrected, I meant open-ended funds, but wrote closed-ended for some bizarre reason!!
Agree with Paul.
No real evidence of this.
At this point the internal Tory conversation centres on whether to adopt an aspiration to abolish or substantially reduce IHT. If this were to happen it would undermine one of AIM's USPs of being relatively liquid and qualifying for 100% BPR in 2 years, but realistically it would take time if at all so I don't see that driving any current selling.
All parties are likely to shift the burden of taxation more onto capital - the Tory's have already started this process with reduced CGT allowances. Expect an incoming Labour government to follow this trend, probably under the banner of "we have no real choice". I wouldn't be surprised if they reform IHT to become a transfers tax (bring lifetimes gifts into scope as well as death estates - although if it were me I'd abolish IHT but make death or lifetime transfers a chargeable event for CGT) and increasing CGT rates. However, CGT is currently a very deferable tax and a significant increase in rates won't lead to sustainably larger tax "takes".
Funnily enough those who have worked, saved and invested tended not to regard themselves as a useful milch cow.
We still recommend AIM shares at work. Its bad financial planning to base decisions on conjecture. I think the weakness in UK small caps is due to the UK being regarded as a basket case in the international investing community. At least it means there's good yields and value to be had at present.
I think IHT impact is potentially low, Paul has said many times recently "why take the risk" when it comes individual companies, many of which are listed on AIM. Retail investors and funds are thinking exactly that and bailing out of anything that looks debt heavy, isn't making a profit or is just generally a bit shit... the lower lows in AIM shouldn't be a surprise. When the turnaround happens in AIM (hopefully sooner rather than later) I don't think we will see a case of a rising tide raises all ships, but the very best companies could certainly go on a tear.
paul: it was ballie gifford that were selling their chunks of Naked Wines (LON:WINE). from 9% to 3% i want to say. but yes, quite a lot of selling down by those sorts of institutions
although, putting this (im)politely: it does not surprise me that the likes of aberdeen & ballie gifford are being fair-weather and bailing out. their fund houses are eh and they rely on one or two funds having a standout half-decade or decade to pull up the other 1,572 funds (or however many they have now) that are dross
speaking of Motorpoint (LON:MOTR), stockopedia have punch card management as the largest shareholder at 32.27% i.e a massive stake. their actual holding is 3.23% (3.227% rounded up) as per the latest annual report - so slightly out of line!
i am guessing it is a mis-placed decimal point!
If you spot a data error, then do raise a "Green blob" at the bottom RHS of any Stockopedia page, to let the team know, and they get things corrected promptly with the data provider (who are *not* perfect!) I find.
thanks paul, will give that a look!
I think I read in the Telegraph that Starmer said would abolish BPR (Business Property Relief) that also applies to most AIM companies (if held for 2 years). It seems a very damaging change - vindictive even - for small businesses for not much gain to the exchequer. And would potentially hurt the hurting AIM investor community at a time they are down.
My conclusion is that it is a worry but not very likely. I am fairly certain the current bear in AIM stocks is much more to do with macro factors and in particular increased interest rates tempting investors out of equity - particularly illiquid companies with thin balance sheets - and into interest bearing investments.
I am a bit surprised index linked stocks have not been more popular.
My guess is approximately zero.
PayPoint (LON:PAY) update today is interesting. Appreciate acquisition - Park christmas savings and Love2shop being rolled out aggressively to PayPoint independent retailer sites. Looks a good situation. Paypoint are able to do what Appreciate (previously Park) couldn't!?
This for me validates the investment case for PayPoint (LON:PAY) - that is really is the offline equivalent of "network effect" that we see with the large tech platforms.
As it has a monopoly and deep seated position in many small corner shops, all it needs to do is keep adding more and more services to its network. No-one else has the scale it has in terms of physical locations, except maybe some big national chains like Tesco and McDonalds.
For example, they could sign a deal with Gousto or Hellofresh. For boxes to be delivered to nearest store to pick-up. This solves customer problem (i'm not in take delivery) and Hellofresh delivery cost problem (each box is heavy and expensive to deliver direct to door). Also maybe the icepack cost problem (as most convenience stores have fridges to store the meals waiting for collection). With the parcel drop-off/pick-up infrastructure in place already, and also a ready-made 25,000+ locations nationwide, no-one else in the UK can offer this. And it will be incremental for the Paypoint shops - more foot traffic coming in to pick up food parcels. How about adding a pack of beer or a bottle of wine to your dinner tonight?
The possibilities are endless when you have a Network as a moat.
(I hold in the Boon Fund)
Surely it cannot be long until the government make it mandatory for all transactions in stores to go through an EPOS system, to prevent those who utilise cash transactions to swerve taxes. I still know of a number of corner shops and takeaways that do not take card and it can only be for this reason. This could be another bonus for PayPoint (LON:PAY).
Edit
top vest i have owned paypoint for year i love his divis but must admit he is always been totally unloved
years
Good morning Paul
Just read up on Reach (LON:RCH) and they mentioned a £605 million share capital reduction.
Is this a good thing or bad thing. Did google it this morning and it has frazzled me.
Curious because Graham mentioned awhile back that it might worth keeping an eye on it.
Thankyou
Hi Oliver. The share premium account does not form part of a company's distributable reserves of capital (in English this means it cannot go towards paying dividends). Hence the cancellation of the share premium account is from a non distributable reserve to a distributable reserve ( retained profit/loss reserve) and therefore can be used to support dividend payments. Therefore in simple English it's a good thing. It can enable companies to pay a dividend and stay within the law!
The more I learn the less I Know...............One day it will be all clear
Gimmers I appreciate your swift response and thank you for a very simple conclusion.
No worries. Been a chartered accountant for 25 years and still learning!!
Thank you Gimmers for this. Very clear explanation.
I hold Reach (LON:RCH)
Regards
Michael
My morning smallcap tweet: Punnet of fruity RNSs
STM (LON:STM) Foresight group (LON:FSG) Cyanconnode Holdings (LON:CYAN) Image Scan Holdings (LON:IGE) React (LON:REAT) Oxford Cannabinoid Technologies Holdings (LON:OCTP) Crimson Tide (LON:TIDE), Speedy Hire (LON:SDY), Carr's (LON:CARR), Treatt (LON:TET), Intercede (LON:IGP), Reach (LON:RCH), Robert Walters (LON:RWA), Wincanton (LON:WIN), Castings (LON:CGS), Alpha Financial Markets Consulting (LON:AFM), 1Spatial (LON:SPA), YouGov (LON:YOU)
◄STM (STM)► offer agreed at last at 60p + up to 7p deferred. [SP=46.65 Cap=31m]
◄Foresight (FSG)► H1-Sep trading stmt - core EBITDA (pre-Share Based Payments) 20-25%. Outlook - "In comparison to retail fundraising, the market for institutional fundraising remains challenging and this has necessarily slowed the pace but not the size or scope of our institutional fundraising activities. Indications are that this should start to improve in the first half of 2024." [SP=400 Cap=465m]
◄CyanConnode (CYAN)► another 300k modules ordered under 3m unit Framework Agreement. [SP=10.38 Cap=28m]
◄Image Scan (IGE)► guides FY-Sep rev up c.50% and pretax £0.1m (-£0.35m). Co 'very pleased'. "The uplift in market activity as mentioned in the Interim Results has continued and government opportunities which were suppressed or delayed, by COVID and its aftermath, are now actively progressing." [SP=1.72 Cap=2m]
◄React (REAT)► get £3.8m PA 3 yr contract extension. [SP=1.59 Cap=17m]
◄Oxford Cannabinoid Technologies (OCTP)► Phase I, single ascending dose study for OCT461201 has been successfully completed. [SP=0.76 Cap=7m]
◄Crimson Tide (TIDE)► contract extensions. [SP=1.81 Cap=12m]
In line: SDY, CARR, TET, IGP, RCH, RWA, WIN, CGS, AFM, SPA, YOU
I appreciate there has been no news on SDI (LON:SDI) but I would welcome any thoughts or discussion. It looks like good value to me at present. Even if it just consolidates or adds some small acquisitions.
SDI (LON:SDI) looks cheap, but so do most UK small caps given the continued mauling by the market. I watched the presentation of the recent prelims on investor meet company and was uninspired by the body language of Mike Creedon and the CFO, which seemed lack lustre. I also found that part of the presentation that dealt with Group synergies somewhat vague. I have successfully owned SDI (LON:SDI) previously and acquired a small holding more recently at 87p.
Given the limited funds I had to decide whether to retain SDI (LON:SDI) or take a small loss and invest in companies where I have more confidence in management and the trading outlook. After some consideration I decided to exit at 79p and use the proceeds to top up existing investments in Porvair (LON:PRV) and Card Factory (LON:CARD)
A difficult call, I may well be wrong and often am.
Good luck.
I agree with you on SDI (LON:SDI) . When Mike Creedon was asked if rising interest rates would affect profits he simply said, 'Probably' or something of that nature. He did not appear to have given the matter any consideration. I also found the way the CFO repeatedly leapt in to say, "I'll take this one" interesting.
I found the last webinar from SDI (LON:SDI) very peculiar - as you say, the CEO behaving in quite an odd way - I wouldn't back him. The fact that he dumped all of his shares some time ago was a huge red flag too, which was glossed over at the time, but sure enough it showed that the outlook wasn't what we were being told at the time.
I also disliked his reaction to a question about the profit warning. He refused to take responsibility for it, saying that we did tell everyone that one-off orders from covid would dry up. That glosses over the reality that their forecasts (and hence broker notes) should have factored in the ending of covid-related orders, which they clearly bungled, with overly optimistic forecasts that then resulted in a profit warning.
Probably one of the worst impressions any company CEO has ever made on me, actually, although it's subjective of course.
Funnily enough jonno, that is pretty much exactly what I did ... excited SDI for reasons mentioned here - financial analysis and the less than inspring Board - and invested the proceeds in Card Factory.
Hopefully we are right in our assessment James.
Time will tell, but I feel more confident adding to Porvair (LON:PRV) and Card Factory (LON:CARD) than continuing to hold SDI (LON:SDI)
I thought I was the only one who was concerned about Mike Creedon at SDI but it appears that others including Jonno and Paul also share this. My concerns stemmed from an earlier presentation when he admitted he was not interested in financial markets. It was also clear from what he said that he has very little knowledge or interest in IT. I am in favour of honesty from CEOs and whilst praising him for this, I wonder if such comments help when the share price is falling. To say his performance in the presentation was unpolished would be an understatement. I'm not sure how many owners of companies which might be acquired by SDI would view his lighthearted "cheeky chappie" character, but I find it irritating, although perhaps that is just me. Anyway, I also sold my holding earlier this year as a direct result of my concerns. However I continue to find the company's business model attractive and it has of course performed well in the past. I agree with Jonno's decision to invest in Porvair, another serial acquirer which I find attractive.