Small Cap Value Report (Tue 10 Sep 2019) - SBIZ, ARE, RAI, TPG

Hi, it's Paul here.
Estimated timings for today's report - similar to yesterday. I'll start writing sections from late morning, then will work mainly in the afternoon. Estimated completion time: 5 pm.
Update at 16:44 - today's report is now finished.
SimplyBiz (LON:SBIZ)
Share price: 200p
No. shares: 96.8m
Market cap: £193.6m
SimplyBiz (AIM: SBIZ), the independent provider of compliance and business services to financial advisers and financial institutions in the UK, today announces its unaudited results for the six months ended 30 June 2019.
The headline figures look great, but the growth has almost all come from an acquisition. Organic revenue growth was only 3%. Net debt looks a bit high too, so I'll check out the balance sheet below.
Very good adjusted EBITDA margin, of 23.4%
Note that exceptional costs are very high, at £3.0m in H1 TY, and £3.8m in H1 LY - that's worth checking out, to determine how exceptional these costs really are.
Outlook - sounds fine;
Trading has continued in line with the Board's expectations, since the end of the period. The Group remains on track to achieve market expectations for earnings for the full year.
Stockopedia is showing 12.6p forecast EPS for FY 12/2019, giving a PER of 15.9 - probably about right.
Balance sheet - this is where it goes wrong for me. It's very top-heavy, with £106.6m intangibles.
NAV is £63.3m, so once we write off the intangibles that becomes heavily negative, with NTAV of -£43.3m
It has £11.6m of cash, and £41.5m of debt, giving net debt of £30.1m - that looks too high to me. Although the acquisition RNS in Mar 2019 indicated that net debt should reduce to under 2 times EBITDA by the end of 2019.
Given that revenues are recurring in nature, then maybe a stretched balance sheet doesn't matter that much? Although it makes me uneasy, as there's no cushion if anything were to go wrong.
Cashflow statement - it doesn't look very cash generative. Maybe there's an H2 weighting to cashflow? Note that £930k of development spending was capitalised in H1 2019, more than double the prior year H1 comparative.
My opinion - for me, the stretched balance sheet puts me off.
Did SBIZ over-pay for the large acquisition earlier this year? It seems to have been an aggressive price to pay.
I like the business model though, of providing subscription services for financial services companies. That makes obvious sense, given the complexity of regulation.

Arena Events (LON:ARE)
Share price: 20.5p (down 26% today, at 12:23)
No. shares: 152.7m
Market cap: £31.3m
Arena Events Group plc (www.arenagroup.com) is a provider of temporary physical structures, seating, ice rinks, furniture and interiors. The Group has operations across the UK, the US, the Middle East, and Asia, and current clients include Wimbledon Tennis, The Open, PGA European Tour and Ryder Cup.
I'm not familiar with this company. It floated in July 2017, and as you can see, it's been a flop;

H1 results today are lacklustre. It made an operating loss of -£0.8m, down from a profit of 0.3m in H1 LY. The company has a strong H2 seasonal weighting, and has decided to extend its year end to 31 Mar 2020, to better balance future half years.
Outlook - this looks like a mild profit warning;
...Given the increasing concerns about the general political and economic environment, which may affect several markets, we have taken a slightly more conservative view of the overall outlook for 2020, which we believe is prudent. Our core focus is on further organic and more profitable growth and the Board remains confident about the future prospects for the wider business.
The second half of 2019 contains a number of significant contracts that are under negotiation and not yet finalised that may or may not be secured over the coming months. Despite some project delays into 2020 and slight margin pressure due to the increased reliance on agency labour, the Board believes that adjusted EBITDA (excluding IFRS 16 adjustment) for the year ended 31 December 2019 will be approximately £13 million and we anticipate further significant growth in 2020.
The problem with that, is there's a large depreciation charge, due to this being a capital-intensive business. So EBITDA is pretty meaningless. There was a £5.2m depreciation charge in H1, so if we double that to annualise it, that's £10.4m, which consumes most of the forecast £13m EBITDA.
Balance sheet - has too much debt, in my view.
NTAV is £12.3m.
My opinion - it's not the sort of thing that attracts me at all. Lumpy, uncertain contracts, low margins, and tying up a lot of capital, funded by debt.
Having said that, the market cap is now quite low, so if it puts out good news re contract wins, then the share price might recover somewhat, perhaps.
It just looks a bit of a punt to me, hence not of interest.
RA International (LON:RAI)
Share price: 40p (down 12% today, at 15:05)
No. shares: 173.6m
Market cap: £69.4m
RA International Group plc (AIM: RAI), a leading provider of services to remote locations in Africa and the Middle East, is pleased to announce its interim results in respect of the six months ended 30 June 2019.
The description is enough to put me off. But since several readers have mentioned this company today, I'll check out the numbers, even though I wouldn't ever invest in something like this.
As you can see, the figures are poor (apart from the nice cash pile, which is good), with profitability having dropped by two thirds;
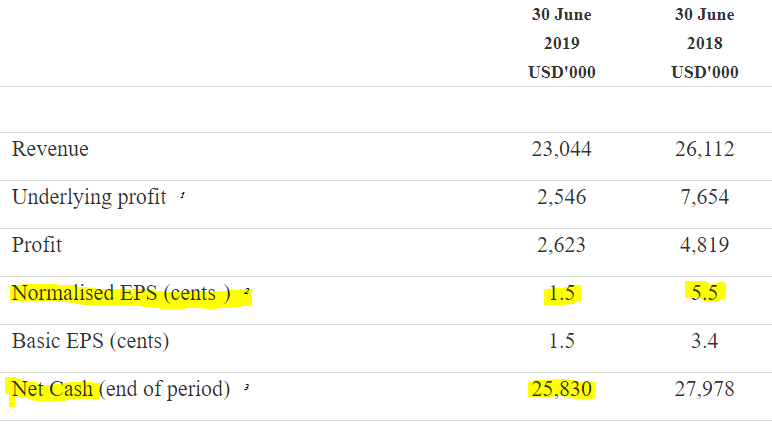
The contracted order book is looking healthy (although it would be useful to see a table of how the total breaks down into individual future years);
Contracted revenue backlog of USD 166m at 30 June 2019, up 39.5% from USD 119m at 31 December 2018
Outlook comments sound fairly decent;
We are pleased and encouraged by the value of contracts awarded to the Group in H1 19 and whilst the delay in being awarded a particular contract has impacted on first half financials, the Company is set for a strong second half of the year.
All contracts expected to significantly contribute to H2 19 revenue have now commenced and we continue to bid for large, long-term contracts in line with our strategic plan.
That last sentence seems to provide good evidence that a profit warning in H2 is probably unlikely.
Balance sheet - looks excellent;
NAV: $59.2m
NTAV: $59.1m (includes $25.8m cash, and no interest bearing debt, ignoring lease liabilities)
Current ratio (i.e. working capital) is outstandingly strong, at 7.39
Therefore a big thumbs up for this very strong balance sheet.
Dividends - given the strong balance sheet, it seems to me that the company has plenty of scope to increase future divis. The forecast yield is currently about 3.5%
Cashflow statement - unusual presentation, of 3 half years, which I quite like actually.
It looks a genuinely cash generative business, and is spending its cashflow mainly on capex.
My opinion - this actually looks quite good! My main worry is the whole issue of companies with overseas operations listing on AIM. And let's be honest here, Africa is not exactly low risk!
That said, the risk seems to be well factored into the valuation, which assuming it hits the full year numbers of 8 US cents EPS, puts it on a PER of 6.2 - which looks very cheap, considering it also has a lovely balance sheet with plenty of cash.
Investors also have the risk of large, lumpy contracts, and the possible problems that can cause - as indeed it has, with a delayed contract causing a two-thirds drop in interim profits.
If you're prepared to tolerate the risks, then this share certainly looks attractively priced.
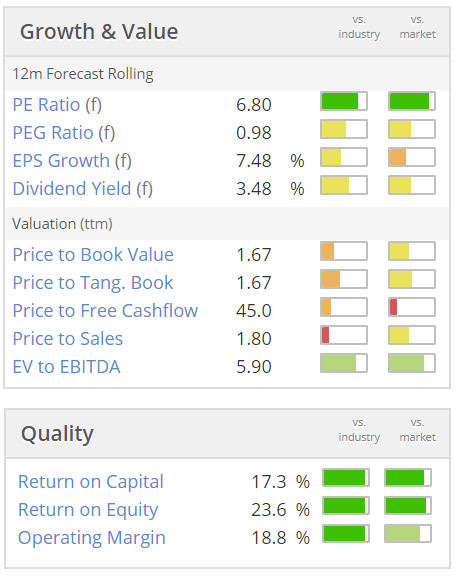
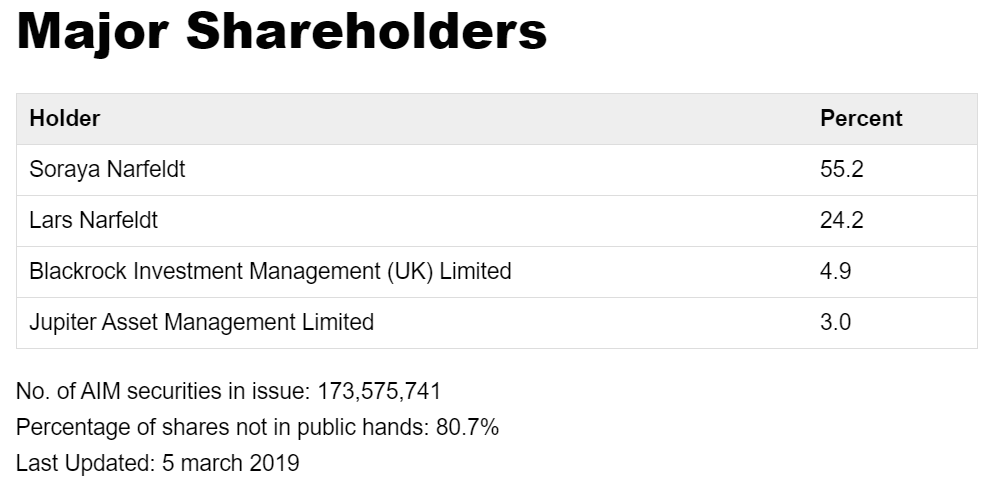
EDIT: A reader helpfully pointed out that the 2 (presumably related) biggest shareholders are the CEO & COO, who combined own 79.4% of the company. This means that, since they hold over 75%, they have complete control over the company. Outside shareholders are therefore completely in their hands.
From the company's website;
TP (LON:TPG)
Share price: 6.8p (up 1% today, at 16:12)
No. shares: 779.2m
Market cap: £53.0m
TP Group (AIM: TPG), the providers of mission-critical solutions for a more secure world, today announces its unaudited interim results for the six months ended 30 June 2019.
That's a pretty useless self-description, telling us precisely nothing about what the company actually does. Thankfully there's a "note to editors" paragraph which is more useful, saying;
TP Group designs and develops advanced technologies, engineers complex equipment and systems, and provides support throughout their operational life. The Company's shares have been traded on AIM since July 2001.
This used to be called Corac, but changed its name to TP Group in 2015. After years of poor performance, there seems to be a nice turnaround underway here;
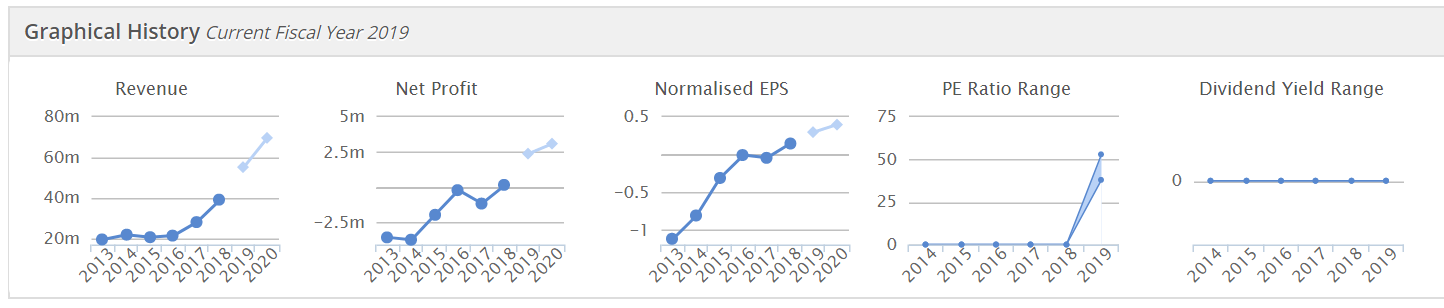
H1 figures -
Very good revenue growth;
The Group generated record revenues in H1 2019 of £26.0m, up £10m (63%) on H1 2018 with growth in both of the Group's business streams. Of this, organic growth was £5.6m and revenue from the acquired companies contributed £4.4m.
Adjusted operating profit of £2.4m, up 161% - impressive stuff.
I am raising a query over the adjustments though. Here is the reconciliation, which seems to exclude depreciation in arriving at adjusted profit, which doesn't seem valid to me;
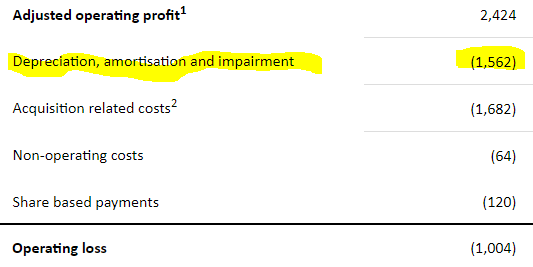
I'm not sure if this is the entire depreciation charge, or just some of it? Looking at the cashflow statement, the £1,562k seems to be the entire depreciation & amortisation charge.
Therefore I think readers need to check how realistic the adjusted profit figure actually is?
Order book statistics sound impressive too;
Pleasingly, the Group's order book continues to grow, increasing to £78.9m at the period end (31 December 2018: £48.3m). This includes £15.5m from Sapienza in addition to 31% organic growth from the existing business.
This strong order book provides visibility of approximately 94% of the full year 2019 market expectations for revenue. There is also approximately £50m in the order book that will carry forward into future years' revenues, alongside an expanding pipeline of sales opportunities valued in excess of £700 million over many years.
Outlook - the key part says;
...The Board is confident in the Company's prospects for the rest of this year and anticipates delivering a full-year performance in line with market expectations."
Given that 94% of revenues are already in the bag, then I wonder if there might be a chance of beating market expectations, if some more orders are won before the year end?
Balance sheet - reasonable, with c.£7.75m in NTAV.
The cash pile of £9m seems to have come from customers paying up-front - because there's an £11.5m creditor called "amounts due to contract customers". Therefore the cash balance makes the balance sheet look stronger than it really is.
My opinion - potentially interesting. I like the strong order book & upbeat commentary.
Worthy of a closer look, I think.
That's it for today. See you tomorrow!
Regards, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

32 comments
A good write up Paul!!
Just one point on TP (LON:TPG) (which I hold), doesn't pretty much every company adjust their profit by both depreciation and amortisation? If so, then TP Group don't seem to be out of line in this respect.
I think adjusting by amortisation of acquired goodwill is OK, since an acquisition resulting in goodwill is something that has been done and completed, and is reflected in the balance sheet and/or equity statement depending on how it was financed.
Depreciation of equipment in ongoing use, or amortisation of intangibles in ongoing developement though would be a different matter, and IMHO would not merit an adjustment unless there was some clearly expressed reason why this was genuinely exceptional.
I hold TP (LON:TPG), but haven't yet formed an opinion as to whether the adjustments are OK or not in this case.
Hi andrea34l,
Just one point on TP (LON:TPG) (which I hold), doesn't pretty much every company adjust their profit by both depreciation and amortisation? If so, then TP Group don't seem to be out of line in this respect.
No. When reporting adjusted profits, most companies remove goodwill (and similar) amortisation charges, but leave in depreciation charge.
The depreciation charge is only removed when reporting EBITDA, but not for adjusted profitability.
Therefore the adjusted profit figure for TP (LON:TPG) appears to actually be an EBITDA number, which isn't correct, not standard practice. Hence why I flagged it in the report above.
Regards, Paul.
Hi: Revolution Bars (LON:RBG) Prelims for the 52 weeks to 29 June will be out on 1 October.
Cheers, Andrew
Solid to good Interim Announcement from Property Franchise (LON:TPFG) today for holders of which I am one.
They say they expect their usual heavier weighting to H2 to be repeated, which promises on the back of a good H1 to be decent.
They are increasing their interim dividend by 8%, and according to Stocko their current overall annual dividend yield is circa 5.22%. Not growing spectacularly, but a solid performer to date.
Only cloud on the horizon is their CEO is leaving but not for a while yet.
Are you reviewing Luceco who came out with interims yesterday?
Hi Chrisspencerphilips,
Are you reviewing Luceco who came out with interims yesterday?
At your prompting, I've just had a very quick skim of the interims from Luceco (LON:LUCE)
They look good. A strong improvement in profit, and a good outlook statement (currently trading ahead of expectations, but keeping guidance unchanged due to uncertain macro outlook).
Balance sheet has a bit too much debt for my liking, but not dangerously so.
Forward PER of 10.2 looks reasonable.
Nice StockRank of 84, and a "High Flyer" classification.
Overall, this looks quite good - worthy of a closer look, I'd say.
Thanks for flagging it up.
Regards, Paul.
Re: Revolution Bars (LON:RBG)
I am little bit surprised by the fact there has been no trading update from Revolution Bars (LON:RBG) (last three years there was an update in June/July)
I think Paul's view when we last kicked this around was that this may be good news (or not bad news), inasmuch as the last few updates concerned disappointing performance news.On the optimistic side it could be that maybe the new CEO (on board since Jun last year) wants to stretch reporting as far as possible to take in any new initiatives that may be bearing fruit, to offset the historic performance of the last two years. Or it could be that he doesn't think there is anymore to be added to the slightly downbeat statement they made at the last trading announcement:
'The uplift in like-for-like* sales performance over the festive period gives us momentum going into the second half and I'm pleased with the progress being made in refreshing the Revolution brand proposition. However, given the uncertain economic and political outlook we are adopting a more cautious outlook on trading in the coming months.'
They should report preliminary results in Oct, so not too far away.
I am a holder
Revolution Bars (LON:RBG)
I would agree that no news is presumably not bad news unless its going to be along the lines of "trading since the start of the new year has been below expectations" - so hopefully (surely) last years numbers are in the bag.
One additional glimmer of hope is that for the first time broker forecasts have nudged slightly up in the last month - not sure if this is a new broker - removal of a broker or whatever. As ever though the future trading needed to match up to current expectations and i guess we won't know the tone in that regard till they report next - the Durham outlet was rammed last time i was doing my listed beer pubs research tour the other saturday. One needs to put in a proper 6 or 7 hour session minimum to get the gist of the flow of bods flowing between the different listed outlets during the day in that regard tho.
Tough job, but someone has to do it! Mark Brumby and his sons take this approach to a professional degree.
Hi Trident,
Revolution Bars (LON:RBG) (in which I hold a long position) must have traded in line with expectations for FY 06/2019, otherwise they would have been obliged to inform the market.
They're up against soft comparatives from last summer, and no longer have the distraction of bid talks, nor new site openings. Therefore they really should be able to deliver positive LFLs from now on.
If so, that should trigger a re-rating (or another takeover bid). But as always, we can't guarantee that the upside case will actually play out.
Regards, Paul.
I see that Hipgnosis Songs Fund (LON:SONG) have today released an analysis of their music catalogue income https://www.rns-pdf.londonstockexchange.com/rns/7396L_1-2019-9-9.pdf Showing quite strong growth, eg streaming income up 49% in two years (though I'm unclear whey 'streaming' is deemed to be 50% 'mechanical' sale and 50% 'performance' sales). Another RNS today talks of a further £300m equity fund raise and appointment of JP Morgan as joint broker. Clearly there's institutional demand for this novel investment but it is rapidly growing beyond small-cap territory.
RA International (LON:RAI) interims are surprisingly weak, but with strong order backlog, management says that it is confident of strong H2 to get there or thereabouts to market estimates. Re-reading the generally upbeat-sounding, 24 June trading update (on which the stock rose slightly), I am drawn to the phrase “As last year, we expect financial performance to be weighted in the second half of the year, but we are confident in delivering on market expectations for 2019.” What that now appears to mean is that the H2 weighting will be even more pronounced than last year. The market has taken this poorly, with stock off around 20% first thing.
The company looks cheap on many metrics, and seems to have a strong niche position in building for and supporting Western/ UN aid agencies in parts of Africa. The company’s growth strategy appears logical. There are a couple of major negatives: the corporate governance issue of having a husband and wife team in the top two positions, and the still heavy dependence on contracts in the Federal Govt controlled parts of Somalia (from which it is trying to diversify). To this must now be added poor communication to the market.
(I hold and despite negatives am more tempted to add than sell with the stock in the 30s).
Hi Wimbledonsprinter
I agree with you about the poor RA International (LON:RAI) communication in the 24-Jun-19 TS (unimpressed).
However, an order book of over 2.5 years turnover, and an ex-cash P/E of 4 based on next year's forecasts, meant I added this morning.
RA International (LON:RAI)
An interesting share. The CEO and COO (the husband and wife team presumably given they have the same surname) own 79.4% of the shares. Bit of a lifestyle business then. Probably should have kept it private.
Yes, they certainly talked up the revenue value of recent deals in the pipeline. Loads of cash on hand. Usual risk with a services firm reliant on constantly winning contracts.
I did buy a small amount just to see what happens from here.
In relation, to whether RA International (LON:RAI) should be quoted, the interim report states that the cash raised through the IPO, which “strengthened [our] balance sheet has enabled us to bid for larger contracts which if awarded to the Group would be transformational in nature. Being a quoted company has also enhanced our profile and brought us a number of new opportunities, particularly with western governments.”.
The key rationale at the time of the IPO was that the strengthened balance sheet would allow it to bid for and win these new larger transformational contracts. So far no such transformational contracts have been secured since the IPO in June 2018. The large fall in the share price around the turn of the year was related to earnings downgrades and the brokers removing any future transformational contracts from their forecasts. Hence, the key rationale for the IPO could be argued to have disappeared.
Obviously, the company hasn’t given up hope of winning such contracts and so, with the rose-coloured spectacles on, there is now potentially a significant upside potential to forecasts.
Because of the lack of very large contract wins, the actual and current broker forecasts are well below those at the time at the IPO for basically all lines, apart from the dividend. The higher dividend payments maybe a sign that management itself is becoming sceptical of the benefit of sitting on such a large pile of cash.
Therefore, I think it is a worry that the 80% shareholders might one day decide that life was easier as a private company. But, on the other hand, the current dividend pay outs, also give me some comfort that the Narfeldts are not out to abuse the minority shareholders.
Well outside the market cap you normally look at, but I know retail is of interest, therefore wondered what you made of another sparkling performance from JD Sports?
Morning all,
May I put forward £RAI, £TPFG and £SBIZ for thoughts/comments today. Busy morning, I hold all 3. Also - anyone interested in "turnaround" £TST, whose turnaround appears to be progressing?
I would be interested in views on the final results of Litigation Capital Management (LON:LIT), which is on my watch list.
Hi FREng,
I'd also be interested in Litigation Capital Management (LON:LIT) if anyone has any views. They make a big deal about NOT applying fair value accounting like Burford Capital (LON:BUR) in the accounts and give the impression their's is the model to follow in this sector (cause we is honest).
Given how many people were keen on Burford Capital (LON:BUR) judged by the 400 odd comments on the 'exception to the rule' thread I am assuming some of the readers will have run the slide rule over Litigation Capital Management (LON:LIT) ?
Is Litigation Capital Management (LON:LIT) good value now, worth a look, as they have been tarred with the same brush?
Hi John - There's been quite a bit of discussion on here previously on Litigation Capital Management (LON:LIT) versus Manolete Partners (LON:MANO) and Burford Capital (LON:BUR). I have argued for a while that I much prefer Litigation Capital Management (LON:LIT) ahead of the others for a few reasons, principally that relate to value rather than quality of business.
1) PNAV is only 1.9* and that is based on a cash investment accounting, not fair value adjustment. Assuming the existing 135% ROIC continues anywhere close to those levels then the shares look cheap to me. I previously compared this to the others whose PNAV was between 4 & 6 but on a more aggressive fair value basis (Litigation Capital Management (LON:LIT) would be 1.4* PNAV on same accounting treatment).
Whilst Litigation Capital Management (LON:LIT) looked cheap in comparison I couldn't justify to myself why the others should trade so richly. It really assumes perfect execution and that is usually set up to fail. My analysis suggested I was happy to pay up to 2* book on a fair value basis as I felt this gave me a decent risk/reward.
What I also quite like is that on a more traditional valuation metric Litigation Capital Management (LON:LIT) trade on a fwd PE of 14 and have strong cash position. Doesn't feel expensive.
When I compared the sector I did like the Manolete Partners (LON:MANO) business model, just not the valuation. If they had a fall towards 300p I would be a buyer but will keep powder dry unless they either get there or the relative forward value changes.
I did buy Litigation Capital Management (LON:LIT) slightly higher than current price but was also encouraged in the results to see that they now also intend to act as a competitor and do similar insolvency business to Manolete Partners (LON:MANO) in both the UK and AUS. That puts them in the middle of the Burford Capital (LON:BUR) & Manolete Partners (LON:MANO) business model and means more of a mix of capital light short duration cases and longer duration bigger investments.
SimplyBiz (LON:SBIZ) Half Year results
-- Group Revenue up 20% to GBP29.1m (H1 FY18: GBP24.2m)
-- Operating profit up to GBP3.2m (H1 FY18: GBP1.3m)
-- Adjusted EBITDA*(1) up 30% to GBP6.8m (H1 FY18: GBP5.2m)
-- Adjusted EBITDA*(1) margin increased to 23.4% (H1 2018: 21.6%)
-- Adjusted profit after tax*(1) increased 41% to GBP4.9m
-- Adjusted earnings per share (EPS) *(1) increased by 8% to 5.52p
-- Group net debt of GBP30.1m at 30 June 2019
-- Interim dividend of 1.41p per share
Centra financial planning software surpasses 3,000 users, up from 2,300
"The Group has delivered a positive first half performance, and we are delighted to have completed the acquisition of Defaqto in March 2019. The integration of the business is progressing well and in line with management expectations.
Paul,
I also like SBIZ and would be interested to read your comments.
'Strong growth in revenue and adjusted EBITDA'
'Trading has continued in line with the Board's expectations, since the end of the period. The Group remains on track to achieve market expectations for earnings for the full year.'
https://www.investegate.co.uk/simplybiz-group-plc--sbiz-/rns/half-year-results/201909100700127349L/
I hold
Michael
obviously not a small cap, nor UK - but keep a look out at whats happening on some large borderline investment grade companies in the US... Ford for instance. This has a large issuance out there and Moodys downgraded to junk last night. most funds require a 2 out of 3 main rating agency IG rating to keep holding. They have cUSD80bn of total debt. yes 80bn
I think Ford may be a canary. Other macro data points which chime with me are mostly USA:
But then I'm naturally a pessimist, or so my wife says.
Edit: This will be relevant to some of the UK small caps if there is a long-term mood shift away from "jam tomorrow" businesses.
Boeing continues to confound me. It should be an obvious short but it keeps going up. I assume shareholders are believing the company line that the 737 Max will soon be cleared to return to service. But if you look at the European regulatory concerns that seems very unlikely. There's an almighty political and regulatory crunch brewing with potential for major market fall-out. The LEAP engines supplier is 50% GE owned and they are already in a fragile state.
Ford has been downgraded by Moody's but S&P Global and Fitch still rate as investment grade so the bond yield only increased 15 bp on the news. Yes they have $100B out there, but not so much really.
I think the real excitement is in BBB where US corporates have issued just over $3 Trillion to fund the last few year's share buybacks. About the same size as the $3.2T CDO and MBS sub-prime mortgage market in the 2009 crisis.
Now, from a balance sheet perspective, swapping equity yielding ROE 8%+ for 3% debt makes sense on an EPS accretive basis. Also the BBB debt current enjoy low default rates so all is fine.
The bomb would be a default rise, this round of BBB is covenant light so downgrades to junk follow, bond funds typically have a 'no junk' mandate and would become forced sellers, thus splat. Interestingly, a lot of 'safe' blue chips hold BBB, I picked up on this the other day with some UK firms, epic gap between long term pension liabilities and assets if this happens.
Funny if it happened, imagine 'solid' companies coming back to shareholders 'remember those lovely defined benefits schemes we scooped up at juicy margins and then dished out 9% divy's to you, well, errmmm...... we need it all back again and more to recapitalise'
I have no idea where the next crisis will come from, but each time it's something new !
I'd be interested in your thoughts on the turnaround at TP Group (LON:TPG)
TP Group (TPG) . Stockrank 85 - High Flyer
• Revenue up 63% to £26.0m (H1 2018: £16.0m)
• Operating loss £1.0m (H1 2018 operating loss: £0.7m) - the increase arising from fees and accrued earn-out payments relating to acquisitions.
• Order intake up 33% to £39.3m (H1 2018: £29.5m) underpinned by a number of major contract wins and new business initiatives.
• Closing order book up 63% to £78.9m (31 December 2018: £48.3m), providing visibility of c. 94% of FY2019 revenue expectations.
• Cash balance of £9.0m (31 December 2018: £22.4m) - after acquisitions.
Interesting business in the smallcap universe. Good visibility of organic earnings and from acquisitions. Bought a small opening position yesterday after monitoring for some time. Any thoughts?
Positive H1 results from Trinity Exploration and Production (LON:TRIN) this morning.
Here's Jeremy Bridglalsingh Managing Director & CFO giving us a bit of colour.
https://www.piworld.co.uk/2019/09/10/trinity-exploration-production-trin-h1-2019-results-interview/
Jeremy runs through the highlights of H1 19, their focus, and what investors can expect ongoing.
It covers:
What are the key developments in H1? – 00:27
With strong revenue & profitability where does that leave the balance sheet? – 01:52
Where will growth come from? – 02:37
Sustainable and significant cash flow generation – 03:44
Where does that sit alongside SPT? – 04:36
What is it that TRIN does differently, in the region? – 06:12a
Production volumes – 7:53
Offshore production – 08:22
Summary and outlook – 10:50
My morning smallcap tweet:
Renewi (LON:RWI), Itaconix (LON:ITX), Concurrent Technologies (LON:CNC)
Renewi (RWI) sells Reym industrial cleaning business for an EV of £57m, a book loss of £25m. FY op profit was £4m.
Itaconix (ITX) H1 has going concern stmt.
Concurrent Technologies (CNC) H1 has going concern stmt.
Ignore the going concern stm for Concurrent Technologies (LON:CNC), it's just a regular one.