Small Cap Value Report (Tue 11 Feb 2020) - WATR, XPD, WGB, NMC, BIDS, ARE

Good morning, it's Paul here with Tuesday's SCVR.
Please see the header for the running order.
Estimated time of completion - 1pm
Edit at 12:51 - today's report is now finished.
Please note that I ran out of time/energy to look at off topic stuff, namely AA., CNEL & OCDO, so will probably write up something about them this evening, for tomorrow's placeholder, as that seems to work quite well - giving you something to get stuck into first thing tomorrow morning!
BBC licence fee
Before we start today, I just need to get one thing off my chest, about the BBC licence fee. I can’t do that through Twitter any more, since they didn’t appreciate my banter, and their computers mis-classified it as “hate speech”. I mean, honestly! Anyway, it’s probably for the best, so I haven’t appealed.
De-criminalising the BBC licence fee (as is being mooted) does not make payment voluntary, as is being widely mis-reported (fake noooz!). It simply means that any unpaid licence fees would be chased in the same way as any other unpaid bill - e.g. a court summons, CCJ, etc, instead of being punishable (ludicrously) by imprisonment. Therefore, it’s a common-sense reform, that’s long overdue.
Subscriber feedback
I was delighted to read Ben’s article here, and even more thrilled to see how highly the SCVRs scored in a recent Stockopedia subscriber survey. Look at this:
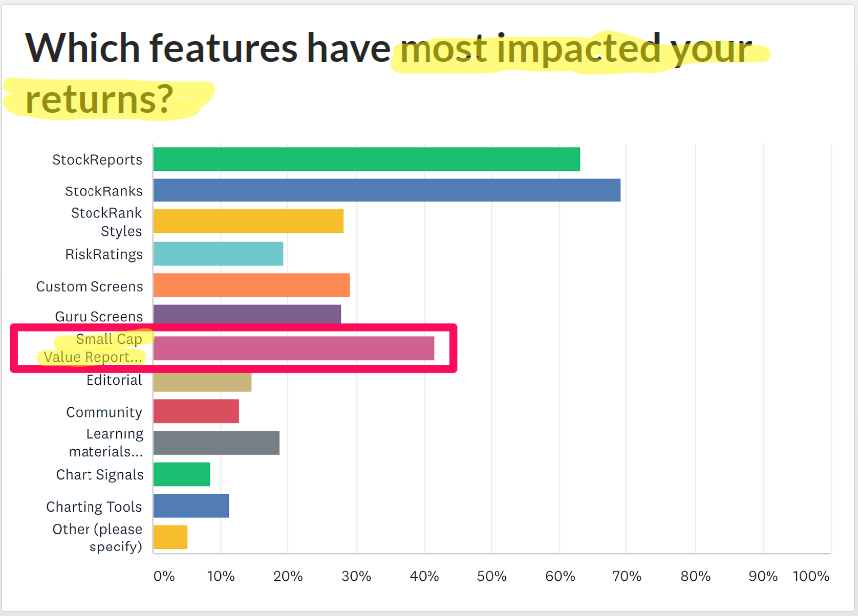
This is not just people saying they like the SCVRs, they’re saying we’ve boosted their returns! Or at least I think that’s what they mean? “Most impacted your returns” could mean the opposite! :-O
A couple of bits left over from yesterday to start with...
Water Intelligence (LON:WATR)
Share price: 337.5p (up 6% yesterday)
No. shares: 16.9m
Market cap: £57.0m
2019 Full Year Trading Results
Water Intelligence plc (AIM: WATR.L) (the "Company" or "Water Intelligence"), a leading multinational provider of precision, minimally-invasive leak detection and remediation solutions for both potable and non-potable water is pleased to provide an unaudited Trading Update for full year 2019. Audited results for 2019 are expected during mid-May as traditionally released.
There’s quite a lot of detail in today’s update, making it not the easiest to interpret.
Thankfully, WH Ireland have done the work for us, with a useful update note (on Research Tree). The upshot is that this is a 9% beat against forecast revenues and profit for FY 12/2019.
The FY 12/2020 forecasts now look modest, given out-performance in 2019, so I imagine we could see forecasts raised again – which could be a catalyst for further share price rises, perhaps? Or maybe it's already in the price? Obvious things usually are.
My view – I’m warming to this one, as it’s established a very good track record in recent years. Consider this sequence of EPS growth in US cents;
12/2016: 7.8c
12/2017: 10.3c
12/2018: 12.7
12/2019: 16.4c (beat forecast of 15.3c) = 12.6p EPS, a PER of 26.8
That’s impressive – more than doubling earnings in 3 years. The valuation reflects that, so shareholders now have the quandary that strong growth is already factored into the price, so growth has to continue.
Overall, this looks an impressive company, that is out-performing. I can see why bulls like it.
Xpediator (LON:XPD)
Share price: 28.25p (up 1% yesterday)
No. shares: 136.1m
Market cap: £38.4m
Xpediator (AIM: XPD), a leading provider of freight management services across the UK and Central and Eastern Europe…
It’s an in line update;
... is pleased to confirm that trading for the year ended 31 December 2019 is expected to be in line with market expectations.
Revenues up 19% to £212m, of which 10.4% is organic, and 8.6% from acquisitions
More importantly;
Adjusted pre-tax profit expected to be slightly above £5.0 million, in line with management guidance provided in the Company's 2019 interim results.
Note that forecasts were reduced considerably in the autumn 2019, from c.5p to c.2.93p EPS – that’s a PER of 9.6
Net cash looks OK, at £6.9m
My opinion – I don’t invest in haulage companies, because the profit margin is wafer thin (2.4% here), as there’s so much competition.
I had a chat with the CEO a couple of years ago, at a Mello investor event. He was telling me all about an exciting new product they were developing, something to do with aggregating eCommerce deliveries, I think. There doesn’t seem to be anything about that in today’s announcement, so maybe it’s fallen by the wayside, or isn’t so exciting any more? Do readers know anything about this? If so, please comment in the comments below.
Anyway, this share doesn’t interest me, because generally I want to invest in growth companies with decent margins.
On to today's news...
Walker Greenbank (LON:WGB)
Share price: 73p (up 3%, at 08:10)
No. shares: 71.0m
Market cap: £51.8m
Trading update (full year)
Walker Greenbank PLC (AIM: WGB), the luxury interior furnishings group, announces its full year trading update for the financial year ended 31 January 2020.
This is a reassuring update, given how bombed out the share price has been since the big profit warning in late 2017 (see 5 year chart below);
The results for the year are expected to be in line with the Board's expectations.
In line is good, for a low-rated share like this, because a low rating suggests the market is expecting more bad news. Absence of bad news is therefore quite bullish.
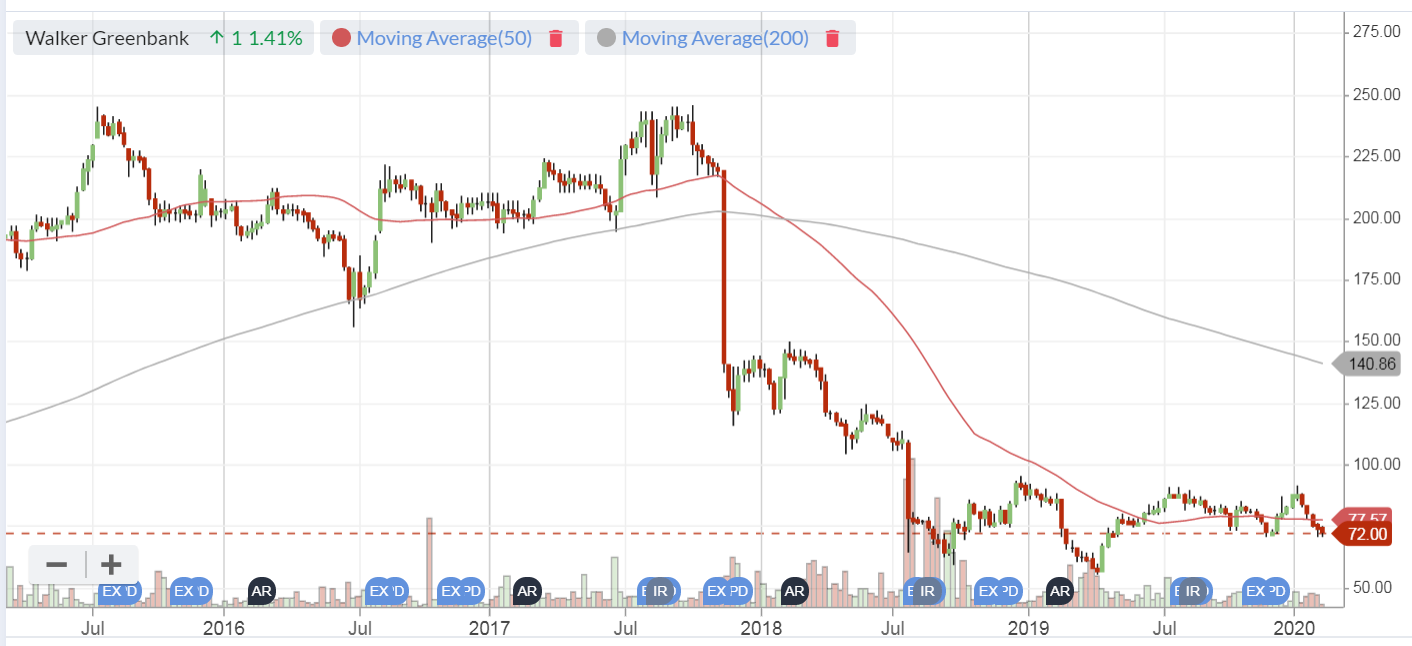
.
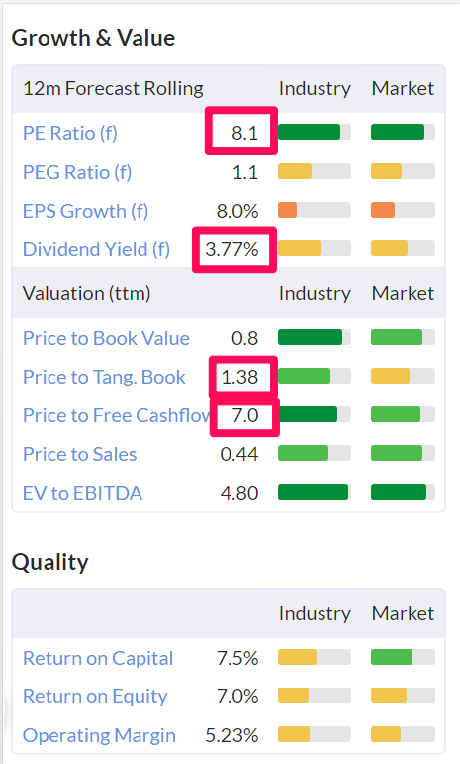
Looking at valuation, here are the usual stats below. As you can see, this is an attractive value share;
- Low forward PER of 8.1
- Dividend yield of 3.77% is pretty good, and importantly it's covered over 3 times by earnings
- Decent asset backing - Price to Tangible Book of 1.38 is good (generally speaking, the lower this figure is, the better)
- Cash generative
Quality scores are middle of the road, as denoted by the yellowish colour bars below (or lighter shaded bars, for those who struggle with colours)
.
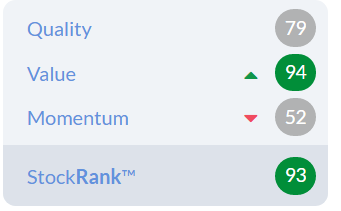
Overall, Stockopedia likes it a lot (as do I);
.
Why is it cheap?
- Lack of growth - e.g. revenues of £111m for FY 01/2020 are down 2%
- Current trading - market conditions are generally difficult, especially in the UK
- Not yet recruited a replacement CFO - people often get jittery when CFOs walk away (as it can be a precursor to problems emerging)
- Turnaround strategy not yet proven (although things do seem to have stabilised at least)
- Niche products which can go in & out of fashion - some brands can be viewed as either iconic, or very dated, it's down to personal taste (although the commentary today does mention revival of interest in the arts & craft movement, which helped its Morris & Co brand grow sales by 22.3%)
My view - there's a brief broker update out today, saying no change to forecasts, and reiterating that it looks cheap.
I agree, this is a decent company, on a bargain rating. I've long suspected that it might make a takeover bid target for a larger group.
The downside risk is that current trading could continue to be soft, and bring with it another profit warning in 2020.
As you can see below, forecasts have lurched down twice in the last year, although held steady for the last year, which combined with the in line update today, does reassure that things seem to have stabilised.
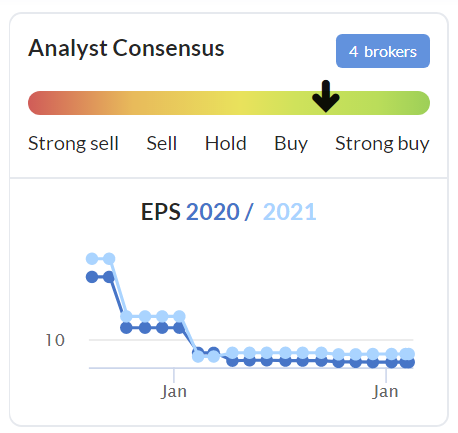
Y-axis clarification - light blue line falls from 16.4p to 8.8p, dark blue line falls from 14.95p to 8.15p, going left to right.
NB. Ed has promised me that fixing the y-axis on these charts is top of the list for the coding boffins! I'm nagging them relentlessly on this, so I think they want to get it done just to shut me up LOL!
On balance, I feel risk:reward looks favourable for this share.
Nmc Health (LON:NMC)
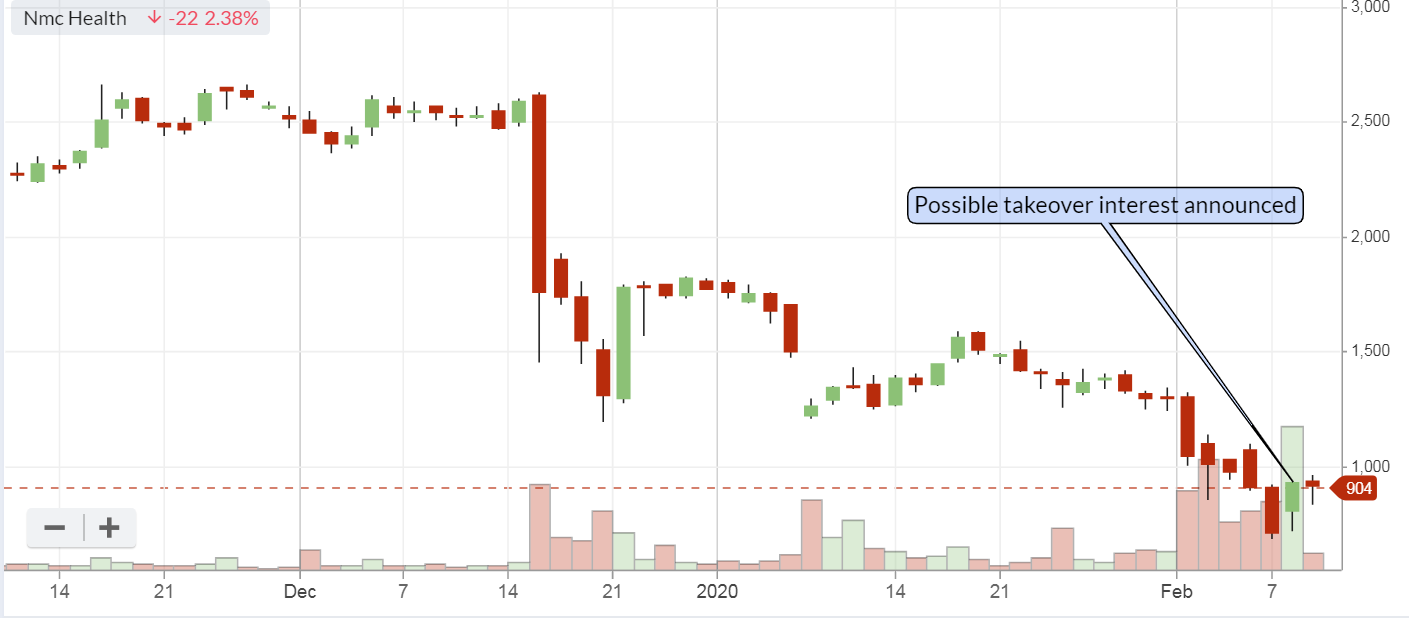
A quick update from yesterday. This is the Middle Eastern hospitals group that has been shorted. It said yesterday that two large investor groups had initiated early stage bid talks.
Today, one of those investors, GKSD (which is apparently backed by Italian hospital chain, Gruppo San Donato (GSD)) has confirmed it is;
... in the preliminary stages of considering an offer for NMC.
NMC shares put in a huge rise (c.30%) yesterday afternoon, with a strange delayed reaction to the bid news. Who knows where the price goes next?! The short closing trade seemed quite obvious to me, as mentioned yesterday morning, but sadly I didn't pluck up enough courage to follow my hunch.
EDIT at 09:56 - Breaking News! My broker has just advised that KKR (mentioned in yesterday's RNS from NMC) has announced it is not bidding for NMC. So that just leaves GKSD in the running. Share price is all over the place, down 14% today, at 797p. End of edit.
I've been playing with the new chart features, and have managed to work out how to do callouts on charts - nifty eh?!
Bidstack (LON:BIDS)
Share price: 6.5p (down 16%, at 10:24)
No. shares: 244.5m
Market cap: £15.9m
I'm keeping an eye on this one, as it looks an interesting concept.
Bidstack Group plc (AIM: BIDS), a leading provider of in-game advertising technology for the video games ecosystem, provides a trading update for the year ended 31 December 2019.
Urgh, this is a catalogue of woes;
Revenues only £150k (although previously disclosed that 2019 revenues would not be significant, so this is as expected)
Operating loss of £5.3m!
"Available" cash of £3.14m - caution needed here, as "available" can mean including overdraft facilities. Although I cannot see any debt on the last balance sheet, and no mention of banking facilities in the interim results. So it looks like the £3.14m figure is genuine cash.
Looking back, I see that it raised £5m in a placing, May 2019 at 12.5p, plus £0.7m raised from warrants at 20p. Cash balance was £6.0m at 30 June 2019. So it has burned through half the cash it had at end June. Therefore by extrapolation, it's probably going to run out of cash in mid-2020. Therefore, expect another fundraising.
Outlook - not good;
The Company is also progressing discussions with other global advertising agencies. However, giving the world's leading advertising agencies the comfort to buy and report on this new inventory takes time and the Board believes further building blocks are still required before those revenues can be fully exploited. While this may be frustrating for investors, the Board and Bidstack's commercial partners can see evidence of positive benefit ahead for the Company.
Immaterial revenues in H1 2020 too - pity, as the cash looks likely to have run out by the end of H1 2020;
The Board expects that revenues in H1 2020 will continue to be minor and that material revenues for 2020 will occur only in the second half. Bidstack's focus remains on securing significant commercial and technological deals that will position the Company well for growth in the medium to long-term.
My view - yet again, we have a tiny AIM blue sky company, which has promised the world, whilst being under-funded to execute its business plan.
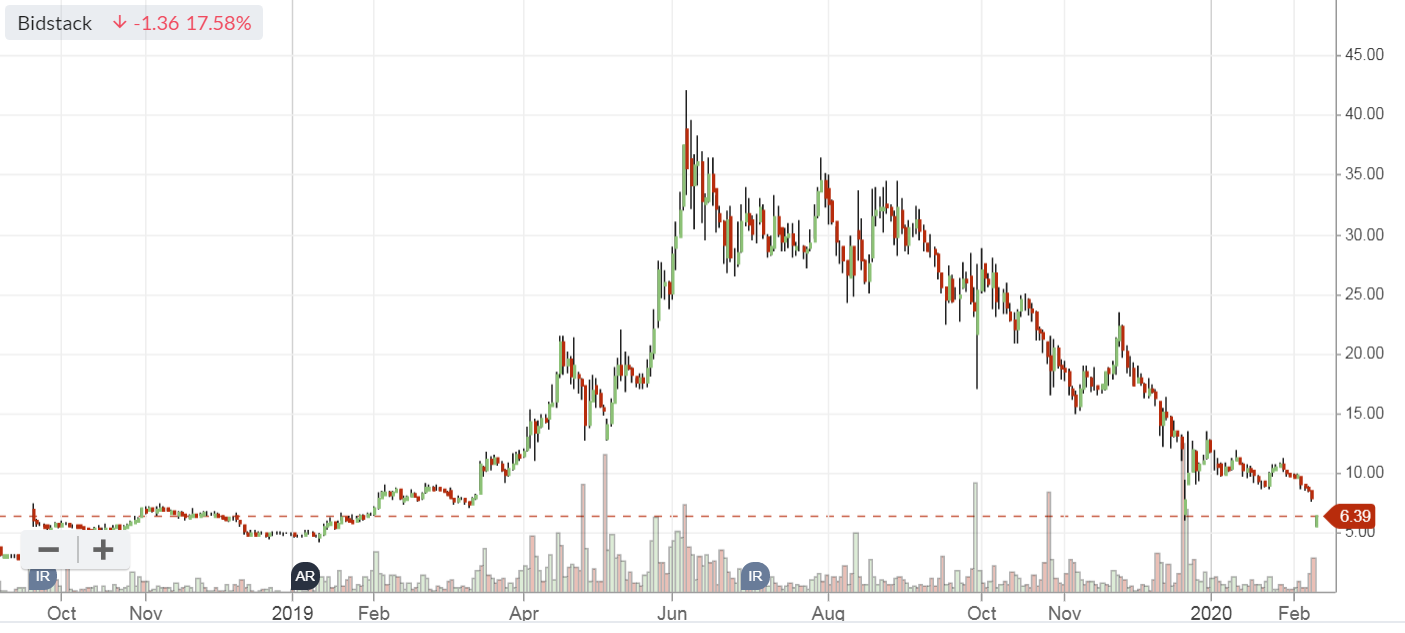
I think announcements in the last year have been far too rampy, causing an insane spike in share price. The company now needs to raise more money, from a position of weakness, which is likely to lead to considerable dilution.
Maybe the company's plan is too ambitious, for the limited funding it has available?
Time for a tea-break! Next up I'll look at;
Arena Events (LON:ARE)
Share price: 26.25p (up 7% at 11:01)
No. shares: 152.7m
Market cap: £40.1m
Unaudited Interim Results for the six-months ended 31 December 2019
Arena Events Group plc (www.arenagroup.com) is a provider of temporary physical structures, seating, ice rinks, furniture and interiors. The Group has operations across the UK, the US, the Middle East, and Asia, and current clients include Wimbledon Tennis, The Open, PGA European Tour and Ryder Cup.
Many thanks to Lord Gnome who flagged up this share to me in the comments below, at 07:36, pointing out that interims look fine, and that it might be a recovery situation. That aroused my curiosity, so I've taken a look, and it does indeed look potentially interesting.
Graham's notes here in Jan 2018 provide useful background, as he touches on the structure of the IPO.
My notes here in Sept 2019 show me unimpressed, after a mild profit warning.
Change of year end - this is a bit confusing, but it looks like the company has published 2 sets of interim results, due to a change of year end. So we have;
Interim results for the 6 months to 30 June 2019 here.
Interim results fo the 6 months to 31 Dec 2019 here.
Audited results for the 15-months to 31 March 2020 will be issued in due course.
Seasonality - this is causing me a few headaches. The 6m to 30 Dec 2019 are the busy, more profitable half. Hence analysing these numbers alone is not terribly meaningful. 12 month figures to 31 Dec 2019 are also provided, so I'm going to focus on those, and prior year 12 month comparatives, to eliminate seasonality.
IFRS 16 - as we know, this boosts EBITDA, and then shoves a load more costs down the P&L into finance costs. So we have to make sure we're comparing like with like. In this case, the prior year figures are not adjusted for IFRS 16, so the apparent increase in EBITDA isn't real. Operating profit is also misleading, for the same reason, because it's one line above finance costs, where some of the property rental costs now rest.
Profit before tax (PBT) - Therefore, the most meaningful number to me is the £1.8m PBT for 12m to Dec 2019. Nowhere near as impressive as the numbers in the highlights section!
You could add back any of the following costs if you wish;
Exceptional costs £0.3m
Acquisition costs £0.1m
Intangible amort £0.7m
That would take (my calculations) adjusted PBT up to £2.9m for the year, which looks a fair benchmark.
I'm struggling to work out how that compares with FY 12/2018, because the company's adjustments are different, and I really don't want to have to put all this into a spreadsheet to work it all out. Let's see if there are any broker notes out today? Hooray, we're in luck, good old Cenkos (I'm long) have crunched the numbers for us.
Cenkos is coming up with adjusted profit of £2.6m for 12m to Dec 2019. I'm not sure why that's slightly different from my £2.9m adj profit above, but it's near enough, so let's park this bit.
Overall, it's a small earnings miss at the EBITDA level (down 2% vs forecast), but a 27% percentage miss at EPS level (1.7p actual, vs 2.3p forecast, for 12 months to 12/2019).
Forecasts - new forecasts for FY 03/2021 have been reduced today - adj EPS down 25% to 2.9p - for a PER of 9.1 - which looks about right.
Balance sheet - has heavy fixed assets (as you would expect for this type of business), part funded by debt.
NAV is £71.7m, less intangibles of £55.7m, gives NTAV of £16.0m - adequate, but not particularly strong.
Depreciation policy would be key here. That would need to be looked into. Are the PPE assets useful, or does that contain assets which are no longer generating revenues? We have to rely on the auditors being on top of that issue, as it's a key risk with what is basically an equipment hire business.
Outlook - Jan-Mar is seasonally quiet, which is handy because of the potential disruption which could emerge if coronavirus gets a lot worse.
We expect this to lead to a broadly flat year on year result in the first calendar quarter, which completes the reporting period for the fifteen-months ending 31 March 2020.
Looking further forward, despite some concerns about the general trading environment in a number of markets including the UK and Hong Kong, the Group expects to see further revenue growth in the year to March 2021 as a result of several major events already secured. These include the return of the US Open, the Ryder Cup, the Dubai Expo 2020 and further work for the Tokyo Olympics. Further progress year on year is also expected in Saudi Arabia on the back of the significant events delivered in 2019.
My opinion - obviously the main concern is whether coronavirus spreads, and leads to major events being cancelled? Particularly as a conference in Singapore seems to have been the source of the virus case in the UK. Investors would need to look at the geographic spread of Arena's events, and the type of events - e.g. indoor events in the Far East would probably be seen as more likely to be cancelled, than outdoor events in the USA. We just don't know do we?
My other concern here, is that the highlights & commentary for these interim results, presented them as if everything is going great. But on closer inspection, this was actually an earnings miss, and next year forecasts have been cut today. That seems misleading to me. Companies should not issue positive-sounding announcements, whilst simultaneously guiding brokers down. This does raise the question of whether we can trust future commentary from this company?
Overall, I think it looks quite an interesting company. But I would have preferred a much more straightforward presentation of the results, rather than buffing them up to shine so brightly, that the truth of this being a small earnings miss, and a downgrade, was obscured.
All done for today, see you tomorrow!
Best wishes, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

46 comments
Hi Paul,
i wouldnt worry too much about twitter. i think all media outlets are massively biased and actively engage in manipulation of news to suit their own agenda. A few days ago I found myself seemingly banned from the Guardian CiF merely for pointing out that Greta Thunbergs father has an active business in a Carbon credits scheme. Obviously legislative changes that may spin out from a wider apprieciation of the whole issue of climate change are likely to provide a financial boost for said scheme. I may have compounded the sin by further pointing out that her mother who is by profession an actress, may have been coaching young Greta in the techniques of acting out 'emotional outbursts' on demand.
My coments on their public forum were , as stated, enough to get me an unconditional 'for life ' ban from CiF. No warnings , no challenges. It does make you wonder sometimes about this whole 'fake news' thing!!
The BBC licence fee model is looking pretty well defunct now that we have a multi-channel, internet based TV world. Amazon Prime, Netflix , Sky etc.
Let's face it, the reason the BBC pays hugely for stars like the excellent Graham Norton or Gary Lineker, is they feel the need to give all licence fee payers something they'd like. But there's no public service aspect to that sort of programming. It's just a circular thing to justify the licence fee.
I recon they could do all the bona fide public service stuff (radio3, kids TV, regional) for under £50 p.a. max. Why not have the BBC separate off the public service element and then have an optional subscription for anything else? It's been suggested that the licence fee could be replaced by say a mandatory levy on each electricty meter. Easy to collect, though arguably a back door poll tax.
I can't stand Gary Lineker and don't know anyone who does so can't follow your logic. worth around £50k pa. tops.
Your comments on Water Intelligence are interesting and I wondered whether you have ever reviewed a company called Modern Water. It has had its problems but has a product which could become important in the world.
Modern Water ( Modern Water (LON:MWG) ) I can certainly see the attraction.
Pedestrian so far, but growth in FY 2020 is going to see them net profits of nearly £5 trillion (American) on revenues of £6.5 million.
Truly impressive.
Must be a lot of adjustments though as EPS will still be negative,
One of the issues seemingly lost in the discussion about the BBC/television licence is that it was never intended as a commercial transaction.
It is a tax to pay for a specific set of government services, but never appears in calculations about the tax take. The BBC independence is designed to avoid direct control by politicians in government. Maybe the BBC has used its independence poorly with low value broadcasting of no benefit to the nation or taxpayers, and maybe it has allowed too many opinionated programs and presenters. But the government won't want to lose the BBC as an available service. It may want to change the way it works, it may be shrunk, it may be funded differently, but it will continue and it will be funded. If making licence non-payment a civil matter reduces the income too much, the funding arrangements will be rethought.
It is a tax to pay for a specific set of government services, but never appears in calculations about the tax take.....
Quite, and the latest moves look like being a smoke screen to hide what is effectively what the Mail likes to call a stealth tax. The govt has cut funding to the BBC to cover free licences for the elderly, and effectively said the BBC has to collect the funds instead from their licence fee payers - so the BBC can take the flak and the govt can duck it.
And rightly so. The BBC have moved so far to the left, with their woke pro Labour/Liberal agenda, why should a Conservative government continue to help fund it?
Paul,
Thanks for the analysis on AREna and the heads up on the Cenkos report (I had missed that). I am happy to stick with them on the basis that I think they are a fundamentally sound company, good at what they do. They have a decent moat in that it would be high risk for new market entrants to invest in equipment in the hope of winning contracts and they are well-regarded by their sticky customers - having said that, whilst I have been aware of Arena for some years, I am not that aware of their competition.
They certainly have a bit of a debt pile - they have overstretched themselves both operationally and financially and I think this has been the root of their problems - growing pains. I'll stick with them and add on weakness if progress is maintained.
Thanks again.
I think a prison sentence is probably appropriate for anyone caught watching reality tv.
Reality TV, was there ever a more ironic use of the term Reality, compared to the construct. Virtual Reality TV may be more appropriate.
I know a number of people who don't have a TV license who have to constantly put up with home invasion (warrants of entry) and the threat of jail for something they have no interest in. I get more out of my Amazon Prime for £75 a year than I do from the BBC at twice the price. It's appalling that people can be threaten with jail in order to pay celebrities and footballers wages.
re post as posted to Friday SCV in error.
Volvere (LON:VLE) transaction announced on Friday.
They have bought Indulgence Patisserie for £1.25m plus taking on £1m of debt. The business has property of £3.2m and annualised revenue for 2020 of £5m. Back in 2017 it had revenue of £7m and made 0.5m. Being in receivership has clearly held it back. VLE have a strong track record so Im happy to back their judgement.
For 2019 Shire Foods, their existing food business could well do £21m and £1.3m profit if a strong H1 translates to a good H2. I have upside to £22m and £1.5m. Skipping 2021 and thinking of a full year 2022 including Indulgence, you could well have £30m revenue and an operating profit north of £2m. This makes Volvere look cheap even if it wasn't trading at a discount to book value, the majority of which is cash. As more deals follow there should be upside to these numbers.
I think that underestimates the position with regards to both Indulgence Patisserie and Shire.
Indulgence had FH property of £1.35m held at cost, looking back in the accounts this was purchased before 2013 and so should be worth significantly more. Also £1.4m of FH 'adaptations' which should enhance the FH value, and £0.5m of plant and equipment. According to the RNS the property assets will be held in a separate entity which i think bodes well for Volvere Volvere (LON:VLE) rationalising these assets and realising value if their is excess capacity.
Indulgences revenues have declined quite a bit over the last few years from £8m in 2016 to currently circa £5m. This would indicate that it has quite a bit of manufacturing spare capacity, and so possibly surplus manufacturing property assets. However, there could also be great sales synergies with customers of Shire which is a much bigger business, and so this could help utilise Indulgence's manufacturing capacity.
For Shire, based on its H1 turnaround and assuming a similar rate of revenue/profit growth as per H1, I think it could get close to £2m pbt.
So a year or two down the line, based on Indulgence's historic profitability and Shire's growth, we could be seeing combined £3m- £3.5m pbt. That's with £20m or so cash and a market cap of £22m.
All very speculative of course, but that is essentially the reason Volvere (LON:VLE) comprises about 30% of my portfolio!
DYOR
Hopefully just setting a low bar - the food business is notoriously difficult with such customer concentration and margins tend to be tight. The H1 revenue growth was very high so am happy to see how H2 turns out but if growth is maintained at the high level then some investment in cost will be required. The fact the earnings story is building is positive and moving on from the NAV +/-. Obviously EV valuation is extremely cheap but doesn't mean much when the company retains high cash balances.
The 'Made in Britain' tag refers to the design not the manufacture.
Are they allowed to do that?
Sounds as dodgy as the co-op sting that collared me last night in their bargain bin section.
Nice looking pair of Hoison Duck wraps for 50p each - happy days i thought.
Got home to notice it wasn't Duck but actual Du'k wraps - Du'k wraps contain no duck - or any other meat come to mention it :(
Be careful when you buy your meat in the supermarkets now thats all i can say!
A well known German supermarket had "Produced in the UK" on their bags of rice. Now I've seen a few rice paddies, but never in the UK. I presume they mean packaged in the UK, but since the consumer is only going to consume the contents, this really should be illegal.
Another trick is to label food as "Produce of more than one country". Which presumably is better recieved than "Mostly grown in China"
Actually China does not export much rice, India and Thailand are the largest exporters.
Same sort of suggestive "association" which is all too common when you see a Union flag on an advert. Made in UK, designed in UK? No chance, sold in UK more like.
BIDSTACK.
It will be very interesting to read Paul's comments on BIDS . VERY popular on poor quality bbs. Rubbish bb threads often = rubbish share. Is that the case with BIDS?
Their update today is more of the same. i.e tiny revenues of just £150,000 and operating loss of £5.3 million incurred by" laying the foundations for the Company's growth." (They've been laying those sometimes "transformational" foundations for years).
Then "nothwithstanding the Company having failed" (AGAIN... my add) "to meet its revenue targets for 2019 the Company is pleased with Bidstack's progress."
Bidstack will "continue with its strategy of prioritising technical investments over seeking short term revenues."
So that's telling you! We're not bothered about those minimal revenues. So very likely yet another placing ahead.
Confession time. For a short time last year I held BIDS. Bought small "fun punt" based only on posts on a generally good quality bb and not ADVFN.
Share price went down and so decided to find out more . The results from only a quick check showed the incredibly chequered history of this Company, and that fun stake was sold for a £250 loss. .
Their update today shows that another placing looks inevitable. It will be their 9th!
Below is very brief history of BIDSTACK:-
WOW!
2009. Then called ADDLEISURE. Change of name to FITBUG. (It became a disastrous investment).
2011. "Transformational/Pivotal," trading update followed by (from brief check) bullish results comment.
2011. Soon after...... a PLACING.
2014. Needed and got what looks like a rescue loan.
2015. Legal dispute with Fitbit. They lost and eventually settled out of court but with no details given.
2016. New shares and another PLACING.
2016. Big board changes
2016. ANOTHER FUND RAISING and another LOAN.
2017. Another PLACING.
2017. Another change of name. This time to KIN WELLNESS. This was soon followed by further big share price falls.
2017. SO yet ANOTHER PLACING!!
Then shares SUSPENDED for 4 months. Then share consolidation. BUT
2018. March. Shares SUSPENDED again.
2018. AUGUST. All share acquisition of Bidstack.
AND YET ANOTHER (oversubscribed) PLACING
2018. September. ANOTHER change of name. This time to BIDSTACK.
2019. MAY. YET ANOTHER PLACING!
QUESTION?
Do Institutional investors who support so many placings for the same Company do the obvious and check out the past record of that Company?. Presumably they don't?
Do those posters who ramp such shares elsewhere ever do it either? Going by the poor quality some probably don't even read or understand basic Company announcements!
The above also shows the folly of relying on poor quality bbs for our investment decisions ahead of quality sites like Stockopedia and the excellent detailed and informed comment every day right here.
btw... the BIDS 6p share price is now down 80% from 2019 peak. Heading for zero IF no support for yet another placing?
"2009. Then called ADDLEISURE."
I'm afraid I read this as ADDLE SURE
though that would have been more accurate as it turned out
Readers may wish to do (as I have just done on our portfolios) and run a 'China audit' on the last financial statements of their holdings. This will quickly show where there is potential for supply chain or end-market disruption as a consequence of the quarantine measures that China is imposing and the consequent reaction of its workforce.
It is simple to open the last annual report for a company from its website and to find all references to China in it by using CTRL + F.
i thought I had a pretty fair idea about the exposure of our holdings but was surprised by some of the results of my audit. For example, Joules (LON:JOUL) (which we no longer hold), makes quite a lot of its British pedigree. Most of its clothes are manufactured outside the UK including a significant amount in China, The 'Made in Britain' tag refers to the design not the manufacture.
As Paul highlighted yesterday, markets should look through current market disruption (especially, as one reader pointed out, in an era of low interest rates which make the future dividend streams more important) and look at the longer-term returns. But, in reality, markets, especially for small caps, are not as rational as this and I imagine that profit warnings as a consequence of the measures being taken in China will not be shrugged off so lightly, particularly if measures in China drag on.
As Paul highlighted yesterday, markets should look through current market disruption (especially, as one reader pointed out, in an era of low interest rates which make the future dividend streams more important) and look at the longer-term returns. But, in reality, markets, especially for small caps, are not as rational as this and I imagine that profit warnings as a consequence of the measures being taken in China will not be shrugged off so lightly, particularly if measures in China drag on.
Which sounds as though you are forecasting some excellent opportunities for value investors! Is that your view?
Definitely! ATM, companies with quality, repeating income streams with no exposure to China supply-chain or end-market are holding up. But a general market sell-off could change that. Anything with such exposure may suffer from a failure to look through short-term disruption.
I don't hold, but I am surprised that £ASOS seems resilient given the amount that it imports from China (described as a 'main sourcing region' in its 2018 annual report)
I thought along these lines when I first concluded that the impact of the virus would be much greater than the market was reflecting.
Then I thought that it will be much wider too, so maybe sell off a wider range of the portfolio.
And that's what I would have started to do if I were actively trading.
But I'm not. And I don't particularly want to. Many of my bigger mistakes have come from good profitable ideas at the time that I then didn't track closely enough. Probably not a danger in this case because I think the market will be going lower at some point anyway, but I don't feel the need either.
So I'l just wait for opportunities. It's a one off event, manageable for businesses with balance sheet strength. Some permanent risk as the market prices in underappreciated supply chain risks.
The really big issue is corporate and national debt. It won't take much for that to become a mega problem, and this could be it.
Totally agree re BBC licence fee. As it happens I think a lot more people will join me in not paying the licence fee once it is decriminalised but your sentiments are spot on nevertheless. It is iniquitous and should be changed to a civil matter.
So as you're not intending to pay your licence fee are you saying you'd be prepared to accept a CCJ? Have you any idea how difficult that would make your financial life?
I'm often flabbergasted at people's resentment at paying the BBC licence, what is it £150/£160 a year for multiple channels and radio which is often of a high quality, desired by broadcasters abroad and often ad free.
Yet these people who resent it can often be found paying up to £100 a month for satellite/cable TV which is often full of American junk and reality tv (sorry not trying to judge but reality tv is really not my thing). What is that ~£1k a year for ad filled foreign programmes and some sport which you could probably watch down the pub.
Don't get me wrong, I subscribe to Sky too but I don't resent the BBC licence fee and think it is excellent value for money.
I don't watch terrestial TV. I am not committing a crime by not paying the TV licence. The same reasoning will apply if non-payment is dealt with in a civil court.
Whether you are a fan of the BBC or not I believe there should be choice in the matter. Why should those who do not watch TV be forced to pay for others enjoyment? It strikes me that many people of the same view have nevertheless ponied up each year merely because of the threat of a criminal record.
Why should those who do not watch TV be forced to pay for others enjoyment?
Is that not the whole point though that if you don't watch tv then you don't need to pay - roughly speaking.To have a tv and be able to watch it then there is a licence similar to many other pleasures in life. You make your choice and pay or not pay based on the rules which from memory are reasonably fair. Whats the problem?
Not sure if there is any interest in LON:SHED and the proposed large placing etc. Followed this one but put off by the deal in September to buy and leaseback a number of Depots from the disastrous Tuffnells parcel division of Connect ( would not be surprised if Tuffnells was closed down given its large continual losses) Yes these were bought at an attractive yield but that says a lot. The new issue will dilute the roll from this company-so arguably this improves the risk profile. Has looked far too expensive until the reaction on this New issue news
I looked into purchasing SHED, however the purchase & running costs were enormous - 10% annual costs.
Good morning Paul, with HS2 getting the go-ahead this morning I wonder which small cap contractors might be set to benefit from confirmed contracts. A useful list of the contracts awarded so far is shown here https://www.building.co.uk/foc... and presumably, more contracts will be awarded now. It may be different companies involved but I suspect the same JVs will be successful. Do you have any thoughts on this potentially lucrative development. I hold Morgan Sindall (LON:MGNS) and Nexus Infrastructure (LON:NEXS)
I was wondering that as well. One stock came to mind LPA (LON:LPA) which makes lights for trains. Might be good for them. Orders though could depend on who builds the trains..Bombardier/Hitachi?
Morning Paul
Your views would be appreciated on trading update from Walker Greenbank (LON:WGB), that looks okay in the face of a difficult trading environment, which is reflected in the share price..
I have a small holding and will look to add at some point. The attraction for me is in the value of its brands, particularly Morris and Sanderson, which to my mind unique. The balance sheet is improving with net funds expected to be £1m at the year end end. Also it continues to pay a reasonable dividend.
At the current price it would not be a surprise if it attracted an opportunistic bid.
All the best
Morning all,
Paul, could you please take a look at ARE this morning? Today’s 12 month interims look fine to me. A recovery situation? I hold and I am looking to add.
Good morning, Lord Gnome!
Yes, I'll have a look at Arena Events (LON:ARE) for you. On an initial quick skim of the interim figures, it does indeed look a good turnaround vs H1 LY.
On the downside, it's got a lot of debt. Also, given that it provides structures for large events, then it's likely to be very vulnerable to any escalation of the coronavirus, given that events could be cancelled.
More later, probably mid-morning.
Regards, Paul.
Edit: Have now added.
My morning smallcap tweet:
Proteome Sciences (LON:PRM) Nakama (LON:NAK) Gaming Realms (LON:GMR), OPG Power Ventures (LON:OPG), S&U (LON:SUS), AA (LON:AA.)
Proteome Sciences (PRM) guides FY beat with rev up 57%and post-tax profit £0.2m (-£1.3m).
Nakama Group (NAK) guides FY broadly in line with management's expectations after weak Q4. "The cash position remains severely constrained and the Company faces a short-term cash challenge until the full impact of the recent cost reductions has come through. The Board are considering several alternative sources of funding to improve the Group's cash position, but the Group still urgently requires an injection of capital."
Gaming Realms (GMR) guides FY rev modestly ahead of the Board's expectations. Adj EBITDA loss ~£0.5m. The positive momentum has continued into the start of FY20. CEO scarpers. He is thanked.
In line: OPG Power Ventures (LON:OPG) S&U (LON:SUS) AA (LON:AA.)
Wow - Proteome Sciences, that takes me back. Didn't realise they were still going.
Morning Paul, am interested to know if you have any thoughts about the situation at Scs (LON:SCS) (I hold) and the seller announced last night ? I know it is a company you have commented on over the last year. It all seems a bit turbulent to me, principal holder selling out completely and subsequently losing their board member too.
I see the bookbuild got the large holding away at £2:20 so am guessing we'll see a price drop beyond the after hours £2.28 yesterday. But the last trading update seemed to be OK so wonder if this is one to sit out, or would one suspect underlying / hidden reasons ?
Good morning, LumpedOn.
I wouldn't want to speculate on why a major holder decided to ditch their stake in Scs (LON:SCS)
There's an RNS this morning saying that Shore Capital got the secondary placing away at 220p, raising £21.68m for the seller, Parlour Products. That looks to be about 25% of the company - I've tried to find the exact figure on its website, but cannot find it. The new feature on Stockopedia shows Sun Capital Partners owning 25.92%, which has to be the same holding, as it's way bigger than any other holding.
I think it's impressive that Shore managed to get away 26% of the company at a modest discount. That shows strong demand for the shares I'd say.
It's also generally a good thing when a large holding is dispersed, as it could improve liquidity, if one big holding becomes lots of smaller holdings. We'll have to watch the RNS to see what new "Holding in company" announcements pop up.
A key question to find out, is what exposure SCS has to China, for its manufacturing? Quite a lot of furniture is made in China, and sold in Europe, I believe. A salesman in Oak Furnitureland told me that recently.
Regards, Paul.
Thanks - great point regarding the likely demand for shares given the modest discount. I guess I was a bit "glass half empty" about it all and thinking the worst. That for me is a great reason to be part of the Stocko community - the chance to share thoughts and views, and get sensible comments back.
Price doesn't seem to have tanked (yet) so indeed, await news of holders and try to ascertain supply chain situation.
Have just had a look at the major holder in SCS (LON:SCS) .
Parlour is Sun Capital's holding company for SCS, which it bought out of administration in 2008:
https://www.independent.co.uk/news/business/news/struggling-scs-bought-out-by-sun-capital-partners-860058.html
SCS was refloated in January 2015 with Sun selling 58.4% at 175p. No new money was raised for SCS.
In November Sun sold 6.25m shares @ 220p in a placing and the remainder last night.
Regarding Paul's point about China the risk section of the last annual report says:
"The majority of the products we sell are sourced from a small number of key suppliers based in the UK. If a supplier is unable to keep up with demand or ceases to trade this would disrupt our supply to customers.
A proportion of the products sold by the Group are manufactured in the Far East. There is a risk of difficulty enforcing compliance and the assurance over ethical practices".
Nice work, sharw!
Thanks for adding to our pool of knowledge, much appreciated, it's a team sport after all :-)
Best wishes, Paul.
You don't think that the salesman in Oak Furniture Land told you that a lot of furniture is made in China so that you'd buy your dining table and chairs (or whatever it was) from him....? ;-)
I went to OFL with my ex-bf last year looking at furniture, and we got quite an arrogant reception. He didn't buy in the end, partly because the salesman wouldn't budge even a smidgen on the delivery charge even though ex-bf would have been buying £000s of goods. So he looked, and bought, elsewhere.