Small Cap Value Report (Tue 11 July 2023) - DWF, HAT, STM, BEG, EYE

Good morning from Paul & Graham!
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £1bn. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk.
Summaries of main sections below
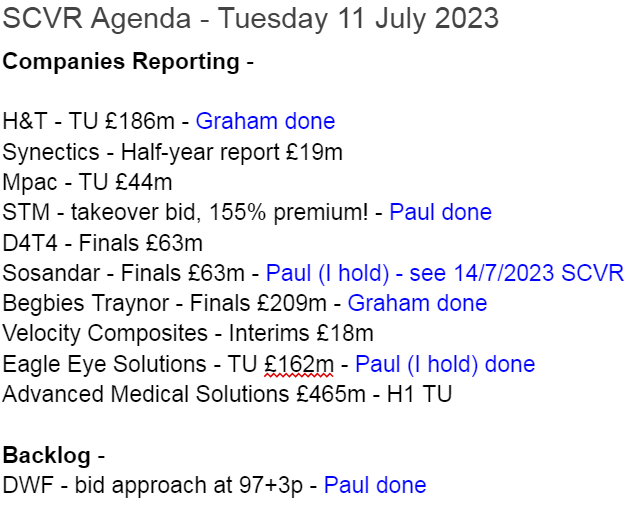
DWF (LON:DWF) - up 34% to 88p y’day (£300m) - Bid talks announced - Paul - AMBER
Private equity firm Inflexion is sniffing around with a possible 97+3p takeover approach. It’s not clear at this stage whether talks will proceed to a formal offer. Share price of 88p suggests some shareholders are happy to bank their profit in the market, in case talks fall through. The whole legal services sector could be getting interesting, as valuations are low.
H & T (LON:HAT) - 422p (pre-market) - Trading update - Graham - GREEN
The leading pawnbroker confirms that strong pledge book growth continues. Additionally, the softness in demand for luxury watches has hopefully been resolved by a reduction in an inventory. Estimates are unchanged and put the stock on mid-single digit earnings multiples.
Begbies Traynor (LON:BEG) - 132p (-2%) (£205m) - Finals - Graham - AMBER
This professional services company (an insolvency specialist) reports good numbers and no change to its forecasts for the year, although the EPS outlook may have worsened slightly. Adjusted PBT is 250% larger than actual PBT, and I think valuation is up with events here.
Eagle Eye Solutions (LON:EYE) (Paul holds) - Up 3% 570p (£167m) - FY 6/2023 Trading Update - Paul - GREEN
Ahead of expectations trading update for FY 6/2023, so broker upgrades EBITDA forecasts by 6-8%. This share is expensive on 40-50x forecast EPS, but it looks one of the best growth companies on the London market, in Paul's opinion, so could be worth this premium valuation in the long-term, maybe?
Paul’s Section:
DWF (LON:DWF)
Up 34% to 88p y’day (£300m) - Bid talks announced - Paul - AMBER
As usual, our daft rules on takeover approaches mean that shareholders only have to be told if news leaks to the press, thus often creating a false market in shares where active discussions are underway for a takeover bid.
This is what legal services group DWF said yesterday afternoon -
The Board of DWF Group plc ("DWF") notes the media speculation regarding a potential offer for DWF and confirms that it is in discussions with Inflexion Private Equity Partners LLP ("Inflexion"), on behalf of funds managed and / or advised by Inflexion and its affiliates, regarding a possible cash offer for the entire issued and to be issued share capital of DWF (the "Proposal").
Under the terms of the Proposal DWF shareholders will be entitled to receive a total consideration of 100 pence per share, comprising:
· cash consideration of 97 pence per share (the "Cash Consideration"); plus
· a dividend for the six month period ended 30 April 2023 of 3 pence per share which is conditional on the Proposal becoming effective ("the Special Dividend") that eligible DWF shareholders will be entitled to receive.
Whilst it’s only bid talks, the “proposal” sounds quite well developed, in terms of naming a price. The share price only rose to 88p though, suggesting that the balance of buyers and sellers in the market means there’s some deal risk of this not going ahead, and some investors are obviously banking their profits in the market. That may be sensible, given how many takeover approaches are falling through at the moment.
We commented before here that DWF looked very cheap on a PER basis, but we didn’t like the debt. So it’s quite surprising a private equity buyer is sniffing around, as their modus operandi is usually to load target companies up with more debt.
DWF only had £6m NTAV in Oct 2022 (last interims), and had £118m of bank borrowings, less £32m cash, so net debt of £86m, quite a significant starting point re debt.
Paul’s opinion - legal services shares have mostly been very poor investments, and many look remarkable cheap at the moment. Given this bid approach for DWF, maybe we should be looking at the legal services sector with fresh eyes, for some more bargains? I see that several others rose in sympathy yesterday, including £RGBP and Knights group (LON:KGH)
DWF put out an in line with expectations trading update on 30 May.
I wonder if, in a slowing economy, lucrative deal revenues/profits for legal firms might dry up?
STM (LON:STM)
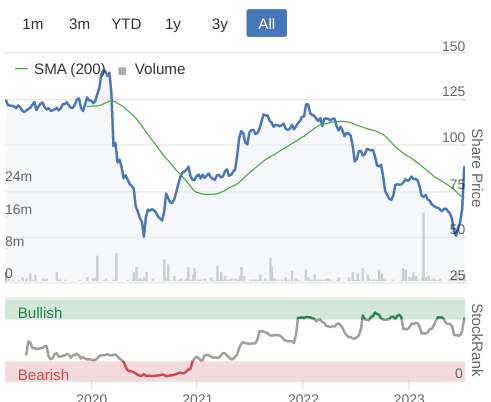
Up 109% to 57.5p (wide spread) £34m - Bid approach(es) - Paul - AMBER
Sky News reported this last night -
Pension Superfund Capital, a vehicle controlled by Edi Truell, is among a number of parties to have approached AIM-listed STM Group about a takeover, Sky News learns.
This morning STM issues a statement re possible cash offer, which sounds like it’s close to being a proper offer -
The Boards of STM Group Plc (AIM: STM), the cross border financial services provider, and PSF Capital GP II Limited as general partner of PSF Capital Reserve LP ("Pension SuperFund Capital") announce that they have reached agreement in principle on the key terms of a possible cash offer for the entire issued and to be issued share capital of the Company ("Possible Offer") at a price of 70 pence per share.
The Board of STM Group has confirmed to Pension SuperFund Capital that, should a firm offer be made on the financial terms of the Possible Offer, it would be minded to recommend it unanimously to STM Group's shareholders.
Paul's opinion - We flagged STM here in Jan 2023 as a potentially interesting special situation, with the market cap almost covered by its own net cash, at the time. A potential takeover bid at a 155% premium has to be seen as an excellent outcome, so well done to holders.
Eagle Eye Solutions (LON:EYE) (Paul holds)
Up 3% 570p (£167m) - FY 6/2023 Trading Update - Paul - GREEN
Eagle Eye (LSE: "EYE"), a leading SaaS technology company that creates digital connections enabling personalised, real-time marketing, is pleased to provide an update on the Group's trading for the year ended 30 June 2023…
Strong revenue and profit growth ahead of expectations
An impressive table here -
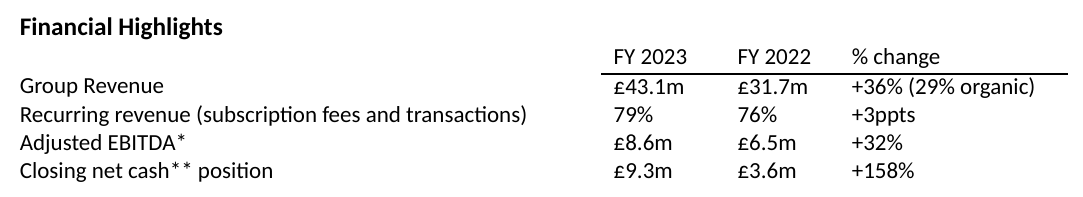
Adj EBITDA was £4.7m in H1 so H2 actually fell sequentially to £3.9m.
Note that EBITDA is a nonsense number, because EYE capitalises about £5m pa into intangible assets, which is probably mostly payroll costs. In H1 adj EBITDA was £4.7m, but that only became £0.9m profit before tax.
The closing net cash position looks healthy at £9.3m.
Untie Nots acquisition has gone well, as planned.
Outlook comments are rather general -
The market in which Eagle Eye operates is expanding, as retailers globally develop their omnichannel capabilities to address the rapidly changing consumer shopping behaviours, particularly in the current cost conscious climate. With new technology, such as AI, rapidly increasing the sophistication of promotions, Eagle Eye's central position as the technology that enables the execution of these programmes increases. Eagle Eye expects this shift towards digitisation and personalisation to continue to accelerate and for Eagle Eye to be a beneficiary of that acceleration.
Eagle Eye enters the new financial year in a very strong position, with a growing presence in North America and Australasia, alongside its long-standing European customers. The acquisition of Untie Nots has provided an additional channel for growth, as well as bringing valuable AI capabilities into the Group. Together with the Group's growing ARR, profitability and cash generation, the Board, therefore, looks to the future with confidence.
Broker update - many thanks to Shore Capital for crunching the numbers.
It upgrades EBITDA forecasts today by 8% for FY 6/2023, and 6% for FY 6/2024.
Equivalent EPS are 11.3p and 14.4p.
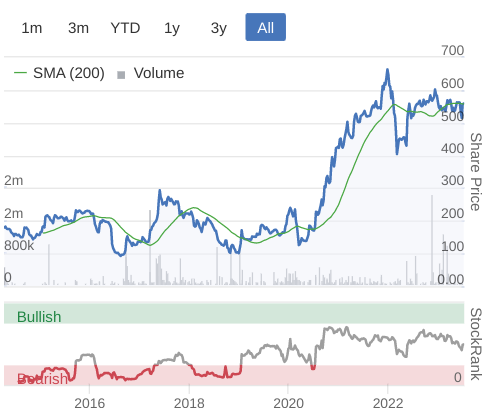
At 570p per share, you can see this is very highly rated on a PER basis, of 50x and 40x, so make no mistake this is an expensive growth share.
Paul’s opinion - it’s rare to find a genuinely exciting growth company, mainly growing organically, and achieving a snowballing of recurring revenues, from blue chip clients, around the world.
It’s self-funding now, so there shouldn’t need to be any more dilution (unless it comes across more acquisitions), and I don’t mind a bit of dilution anyway, from shares being issued at such a valuation premium - arguably it should be using its expensive paper to raise more cash and buy good value complementary acquisitions.
Loyalty schemes are getting much more sophisticated now, and EYE seems to be at the forefront of this niche. So I’m happy to stick with it. Definitely not a value share though!
Graham’s Section:
H & T (LON:HAT)
Share price: 422p (pre-market)
Market cap: £186m
Business has been booming in the pawnbroking trade, and the largest pawnbroker issues an H1 trading update this morning. So let’s take a look.
Demand for pledge lending remains at record levels and continues to gather momentum. Gross lending grew 22% to £128m (H1 2022: £105m). As expected, the exceptional level of redemptions experienced in late April and early May did not continue. Following strong growth, particularly in May and June, the pledge book was c.£113m as at 30 June 2023 (June 2022: £85.1m, December 2022: £100.7m). Growth was achieved across the customer spectrum and in all geographies, with key pledge book metrics remaining consistent.
It’s a remarkable growth story for a mature business - the book growing by c. 12% in just six months - and it continues to support the thesis that pawnbrokers are in a sweet spot in the lending market. They are serving customers that for whatever reason need funds that mainstream banks aren’t willing to provide. However, unlike payday lending (which faces a hostile regulatory environment), the pawnbroking product is able to serve these customers in a manner that is sustainable for both the customer and the lender. If a customer can’t afford the repayments or is unwilling to make them, they have every right to walk away!
In the current inflation/cost of living crisis, the demand for credit is evidently outstripping supply. Also see recent trends at Ramsdens Holdings (LON:RFX) (who are hoping to muscle in on H&T’s territories in the south of England).
In retail, H&T’s sales are up 10%, i.e. keeping up with inflation.
In May, I noticed some worrying comments from the company about margins for high-end watches. They confirm today that in Q2, they “chose to prioritise stock turnover ahead of margin” (in blunt language, they were dumping stock!). But it was hopefully just a temporary measure in response to short-term changes in the market. They go on to say: “We have recently increased sale prices across the majority of our retail stocks and margins are expected to improve in the second half of the year.”
FX volumes rose 19% and are at record levels, implying that there is no shortage of people taking foreign holidays.
Estimates - the RNS makes no reference to performance against expectations, but a broker note form Shore Capital confirms that estimates are unchanged. They think the shares are trading on a PER of 7.3x for 2023 and 6.0x for 2024.
Graham’s view - I was positive on the stock last time, so there is no reason for me to change my tune on it today. Growth continues without interruption and the softness in luxury watches was hopefully just a blip.
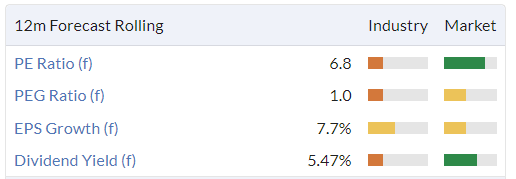
Judging by these metrics, investors are unconvinced that the recent growth seen here is sustainable, and I’d be the first to admit that recent tailwinds (inflation, regulation, price of gold) cannot be counted on to last forever. But on the other hand, even without permanent growth, I like this company as a candidate for a long-term hold. So I’m staying positive on it!
Begbies Traynor (LON:BEG)
Share price: 132p (-2%)
Market cap: £205m
This professional services consultancy (known as an insolvency specialist) issued a positive trading in May that was covered by Paul. As a result of that detailed update, the headline figures in today’s full-year results shouldn’t come as a surprise:
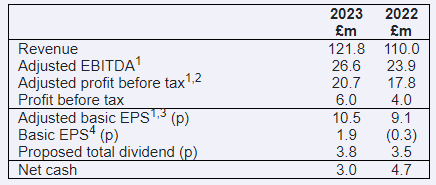
Some other key points:
Of the 11% total revenue growth, 6% is organic and 5% is acquired.
Operating margin improved from 16.9% to 17.9%; this “reflected the continuing increase in our scale and service offerings”
Free cash flow £14.1m enabling £10.6m of acquisition spend and £5.4m of dividends.
Total dividend for the year 3.8p (last year 3.5p).
Outlook: in line with expectations, helpfully compiled by the company and disclosed as being revenues of £127.5m - £131.4m, and adjusted PBT of £21.9m - £22.7m.
There is some dilution to watch out for, though, and changing tax rates, and this impacts EPS even if it doesn’t impact PBT! I note that our friends at Equity Development have nudged downwards their recently released FY April 2024 estimates: the adjusted EPS forecast reduces by 5% from 10.8p to 10.3p, and the dividend per share estimate reduces from 4p to 3.8p (correction: the dividend forecast for 2024 increased from 3.8p to 4p!). Another example of where the note from the analyst gives a fuller picture than the RNS!
Revenues are expected to grow from £122m to £129m; Begbies say they are now the second largest in the administration market, with 11% market share. It’s an impressive growth profile over five years: revenues have doubled, and adjusted PBT has grown from £7m to £21m. Speaking of which…
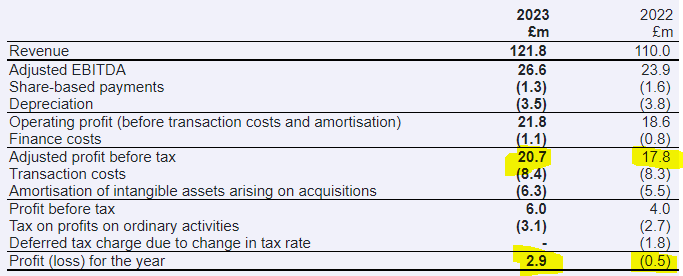
The adjustments here remain enormous, with £20.7m of adjusted PBT translating into less than £3m of after-tax net income.
Last year, £17.8m of adjusted PBT meant an after-tax loss.
The major adjustment is “transaction costs”. These costs include payments to sellers of businesses that are contingent on the sellers continuing to provide services to Begbies after the sale.
According to the accounting standards, they should be treated in a similar way as employee remuneration. There is good logic for that, but it’s not helpful for companies who wish to deduct these payments from adjusted earnings!
Graham’s view
The company has previously been very helpful in explaining the accounting treatment of these “transaction costs” and I mostly agree that they are one-off in nature, although I also think these payments highlight the importance of key employees at acquired businesses. The professional services sector, after all, depends entirely on the quality of the people providing the services.
The other major adjusting item is the amortisation of acquired intangibles: these include things like brands, customer relationships and order books.
Some other people might not get hung up on these two adjusting items but I think it’s really important to form a view on them, in cases where there is a large discrepancy between adjusted and statutory profits.
Even if you want to skip these items and go straight to the cash flow statement instead, that doesn’t entirely settle matters: operating cash flow is £17.4m only if you exclude the special transaction costs I mentioned above. If you include those transaction costs, it’s only £6.8m.
I’m not inclined to give companies full credit for adjustments such as these; there are other companies which don’t need to adjust their numbers, and I find that life's easier when I own shares in them.

The PER uses the adjusted numbers so in my view the “real” PER is somewhat higher than this. How much higher is a matter of judgement.
Overall, I do like this company but with a PER that’s probably in the mid-to-high teens, I certainly wouldn’t call it cheap for a professional services business. The StockReport agrees, giving it a ValueRank of 21. This being the Small Cap Value Report, I have to stick with a neutral view on these shares.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

60 comments
Hello Paul, the tags have dropped off again, apart from one.
Very good management presentation Sosandar (LON:SOS) (I hold). Good things happening and more to come. I really like their style.
Hi Paul, I would welcome your thoughts on Kinovo (LON:KINO), which has reported full year results today which I thought were very positive.
In response to NewInvestor1972 yesterday
Re @ XP Factory (LON:XPF)
I wonder if their investor marketing needs more work, I didn't even know about Dubai till you just mentioned it, I assume its Franchise?
ESCAPE HUNT has been operating internationally across 4 continents since 2013. Its 26 international venues are a mix of Franchise (23) and Company Owned (3) sites. The first international BOOM BATTLE BAR is due to open in Dubai’s Jumeriah Beach Resort in 2023.
See their Annual Report 2022 https://www.xpfactory.com/_files/ugd/bf4dfd_9f95ee4f57f544bfb6de1bc51a5649be.pdf
SDG Sanderson and Colefax
Both getting somewhat hammered past few weeks presumably on upcoming macro worries .
Sanderson doesn’t half jump around on price and has revered from 130s to just above 100.
Big fan of both I am at a full position in Colefax which I think is more bulletproof and is a steadier ship both share price wise and business wise .
Sanderson of it falls below the 1 pound barrier and goes anywhere near the 80s would feel like bargain buy territory and I would be a heavy buyer .
Probably not the best portfolio position as I would have 10% SDG snd 10% Colefax giving 20% exposure to two very similar companies who are both potentially exposed to downturn .
However there are no actual signs of any real issues so it is starting to look tempting .
Best place for Cash ?
Read sone comments on gilts etc below and interest accounts .
My cash was sat in NSI for a long time but I’ve blown the lot in the past 6 months on a start up I’m working on revolving around recovering naturally fallen huge trees in Java and turning into live edge itens . Somewhat on the high risk / what the hell have I got into situation but really interesting and great fun .
On the reverse is my risk averse missus who is sat on a fair chunk of cash in NSI getting a paltry and taxable 3% ish .
Given she is terrified of stocks which is akin to gambling and totally uninterested in sorting it out what are the best bullet proof safe places to put cash these days that doesn’t involve any risk ?
Any top tips other than Chase which is giving 3.8% but I’m sure there is better .
Premium Bonds - combines a gamble with safety and tax free too
planetx - 1/2/3 year cash E-ISA's with Virgin Money paying 5.3/5.4/5.5%. I think that is outstanding. Money is secured by FSCS Guarantee up to £85,000. As topinvest says why would you bother with a dividend when you can a guaranteed sleep at night return. I've already taken out one of each of the above.
https://uk.virginmoney.com/sav...
I agree Bouden54. As a dividend investor I'm starting to find it very difficult investing in equities at the moment when you can buy 5%+ very short dated gilts through interactive investor cheaply and for no risk, particularly with a recession likely. A 5% or less dividend yield no longer looks very attractive. It needs to be 7- 8% and growing.
Hi topvest I have accounts with Interactive Investor but have little experience of short dated gilts would it be possible for you to provide some examples. would be much appreciated
Hopefully topvest will provide some good examples, but if you're on II then you can start from the list here:
https://www.ii.co.uk/bonds
To work out the Yield To Maturity (YTM) you do:
YTM = (C + (FV-PV)/t)/((FV+PV)/2)
(https://corporatefinanceinstit...)
Many Thanks
Each to their own and I fully understand the attraction of fixed interest investments, but the best time to buy shares in well run companies is when there is pervading gloom and nobody wants them. To quote Howard Marks stock market sentiment goes from hopeless to flawless and I would suggest we pretty close to the former in the case of UK mid and small caps.
As for yields there are several cash rich small caps, some with the benefit of recent in line updates that yield 7% and can be bought on single digit PEs, examples being PayPoint (LON:PAY) and IG group (LON:IGG) . There is also the likes of Polar Capital Holdings (LON:POLR) that yields 9%ish and has exposure to the NASDAQ darlings via its Polar Capital Technology Trust (LON:PCT) that makes up a significant percentage of its AUM.
The stock market is forward looking and has to an extent priced in much of the anticipated gloom.
No guarantees and of course the above shares may get cheaper, but I would suggest that they are pretty cheap now. I hold all of the above bought around current prices give or take a couple of pence.
Just my view and it works for me. Good luck in whatever you decide.
Thanks Jonno - Good thoughts and I do actually hold all of those companies you mention, other than Polar Capital Technology Trust. Small caps definitely have big attractions and I'm still invested directly and through small cap trusts. Personally, I am trying to keep over 30% "cash" until the yield curve flattens as its predicting much more pain, so there may be even better bargains to come. The trouble at the moment, from my perspective, is that most of the pain is in the UK. The US is still blowing bubbles and is 69% of the MSCI World Index versus a 15% GDP weighting. Quite scary for the UK if the index funds go into reverse and that pops! The UK is on a 40-60% discount. Anyway, it's very difficult to time the market, so I will probably get it wrong. Good luck yourself!
From his televised interviews fairly recently Marks' sees right now as the best opportunity in his beloved private credit market since 2008 and low rates pushed up competition for yield for the last decade.And there has to be some decent bargain basement hunting here in good old blighty too still!Impressive that Polar are offering 9%.
Well you could knock me with a feather, Forterra (LON:FORT) has recovered all its fall from this morning's profit warning. Those who bought in the mid 140s have been rewarded. Whether it holds around yesterday's close remains to be seen. Perhaps someone knows something I don't?
Strange market indeed! I will continue to sit on my hands regarding my holding.
Cheers for that update.I haven't been following them in detail of late.But they're definitely on my buy list for a decent probability of a 'double' in the next few years hopefully...
Anyone else interested in the TU from Advanced Medical Solutions (LON:AMS) ? Never been a value share, and has taken time for customers to normalise from Covid. H2 weighting, but outlook now looks back on track for progress. I hold.
D4t4 Solutions (LON:D4T4) FY Results (I hold)
Doesn’t seem to be much excitement at todays D4T4 preliminary results for the year to end of March 23?
This small cap software company seems to have fallen out of favour. Which always interests me. It’s been in my sights for a while, but has remained quite expensive relatively, hence my small holding.
Share price is up a little as they seem to have met expectations – lowered by a profit warning at the April update, on the basis of 2 contract signings delayed and expected in the current H1 24 period. No update on them in the current results though.
As a result of the share price falling 35% in the last few months stocko rates it as a falling star. No arguments there. But I’m more interested in where its going to go next. Stockos algorithms are firmly historical, so cant take account of reasons for underlying performance when companies are in turnaround so it doesn’t necessarily worry me.
Despite the profit warning the company delivered increased profit on falling revenue. Forecast P/E for the current year to is around 14x – not value territory. But certainly not expensive for a software company. There might be good reasons for that though!
Profitability has fallen off a cliff with ROE of 2x, ROCE of 3 and operating margin of 3% (ttm). Not good for a software company.
Cash generation has been high. P/FCF is around 5x. Some of this has been returned to shareholders with 1m in dividends, 5m in special dividends and 2m in share buybacks (in treasury for future options).
So what to make of it?
The business is in transition in 3 ways:
[1] From third party software and hardware to vendor of proprietary software
[2] From perpetual licences to 3 year contracts for licence, support and maintenance paid annually (ARR)
and [3] from sales through partner channels (terradata, pegasystems) who integrate with their software to sales through more direct channels (salesforce), consultants and direct to customers.
The transition through [1] and [2] are essentially complete. ARR will continue to rise, though probably not at a great rate, via sales through partner channels. Longterm I view direct sales as the only way for their software to achieve high sales growth. Software developments allowing direct sales have only just been released so I expect there to be some time before the sales and marketing now in place generates results, and a further period before these sales gain good traction.
Gross margin rose to 60% (51.9%) as sales of hardware fell (partly due to the delayed contracts) while underlying gross margin on software rose to 68.8& (67.8%). Highly profitably which explains the growth in profits despite the fall in revenue. And if they do achieve an increasing in rate of growth through partner and/or direct channels the operating leverage will be very high.
In the meantime the share price has fallen sharply. It’s in my sweet spot as it seems reasonable value but not cheap, I particularly like the prodigious cashflow, for the modest growth already underway – but the potential for higher growth via the direct channel and the new products is now in for free? Where they appear to have a market leading niche in cookie-less customer data acquisition potentially big for new customer such as US health industry, and in near real-time fraud data allowing potentially allowing prevention prior to the event, big for their existing international bank and finance customers.
Accordingly I backed up the truck this morning and took a little nibble. I’d like to buy a larger holding but remain fully invested – and so will need to sell something – and am also keen to buy more Science (LON:SAG) and perhaps Macfarlane (LON:MACF). Not easy to decide to sell given just about everything seems on sale right now?
Cheers
Mark
I just want to point out how difficult it is to move from selling perpetual licences to ARR. If you do £10m in perpetual licences one year and switch to ARR the next, setting the annual price at one third the perpetual licence, then revenue goes down to £3.3m assuming you sell the same amount of product. The next year it is £6.6m and in year three it is back to £10m. Typically, of course, the company does not make a sudden switch like that, but the point is that it is a multi-year transition and the company is in a good place when it is over.
Not really, you're not supposed to recognise the revenue of perpetual licenses until they're consumed.
D4t4 Solutions (LON:D4T4) actually a very misunderstood business. ARR is now already over £16m and will be closer to £19m this year. These are all long term no cancellation contracts so are genuine ARR and not just auto renewal subscriptions which are much lower quality. Retention is good and clients are sticky. So it’s not a business in transition to ARR it has already happened.
Net cash is high and if you strip this out you have a high quality ARR business on a cash adjusted PER of about 10, capable of growing mid teens ARR on a long term compound basis. You might need to be patient as the market isn’t functioning atm (liquidity driven in the UK) but has the hallmarks of a long term winner that should at some point get re-rated.
There was a really good interview with mgmt a while back that was a lightbulb moment for me on this stock. Will see if I can find the link as I’d say it is imperative for anyone thinking about owning it.
David - not sure if it's the same one but there was an interview on the Master Investors podcast in July 2022 - granted a little dated now. I hold D4t4 Solutions (LON:D4T4) - this is the spotify link: https://open.spotify.com/episo...
David/Gary, thank you both - very helpful,
cheers
Mark
Zeus did one later in Dec 2022 with the CEO and CFO for D4t4 Solutions (LON:D4T4)
it is on Research Tree too
Most people will already know but worth pointing out you can get 4%+ on regular savings/current accounts now.
IG and a few others offer flexible ISAs so you can transfer out cash youre holding in a share ISA , as long as you put it back before April you dont lose your annual allowance. Im about 30% cash just now so transferred a chunk out last week, only took a day to transfer and can move it back in a couple of minutes if needed. Id rather I had the cash than IG.
6% when I looked yesterday via raisin with FCS protection.
Yes but that was on a 1 year fixed, this instant access is 4.11% and it takes a few days to get the money back as they pay into the Starling Account and then you have to get it out to your normal current account.
You can get north of 5% on gilts - the good thing with these is you can sell whenever you like so cash not tied up like most savings accounts. Exempt from CGT too - I would focus on the low yielding gilts, where most of the return will come from capital gains (rather than income) when they redeem at par.
Very useful advice.
No Zoo Digital (LON:ZOO) results, there were due out today.
Bloomberg had them "expected" on Friday. No set date though. I presume an update is due at some point soon. A lot of bad news now priced in to share price.
STM (LON:STM) finally! I have nearly sold out a few times for no better reason than "it doesn't seem to go up". Luckily I hung on and it is a great reminder of the importance of patience with value stocks....it is only in the long term that the price reflects worth, it can be ignored for a long time.
Very positive update from Galliford Try Holdings (LON:GFRD) that should benefit from infrastructure demand in the water industry resulting from the current 'sewage debacle'.
Unsurprisingly challenging conditions for Forterra (LON:FORT) reflected in the trading update, but the demand for bricks whilst subdued is not going away and in time it will return. To an extent the share price reflects the tough trading conditions.
I hold both although Galliford Try Holdings (LON:GFRD) is a much larger position.
Graham/Paul,
Could you add Galliford Try Holdings (LON:GFRD) to you list please (I hold)? As Jonno mentions, a very positive update provided this morning, including a strong order book. Thanks
Morning Paul,
Would welcome yours / others thoughts on Kinovo (LON:KINO), which has reported full year results. On the face of it they look good, with revenue and profit up with strong visibility for 3-year revenues and paying down debt.
Keep up the great work with the Podcast - continues to make my Monday morning drive to work enjoyable!
Thanks, Rich
Begbies Traynor (LON:BEG) - a quick reminder that we are hosting management for an investor presentation on 12.30pm on Wednesday 19th July - you can sign up here: https://www.equitydevelopment....
Good Begbies Traynor (LON:BEG) results today, but I have decided to sell the rest of my holding. Its been a good holding for me and, fortunately, I have tripled my money over the years. Ric Traynor is a good leader of this insolvency group and they have much improved their share of the market. Business continues to trend upwards. Anyway, what I don't like is the adjusted EPS of 10.5p. The company virtually fully distributes its real cash profits (3.8p DPS). A big chunk of the difference is deemed remuneration - i.e. the staff costs of the sellers who are still running the acquired businesses. This is a real cost of running the business and shouldn't be added back in my view. This makes the valuation look a bit more toppy. Any thoughts?
That's an interesting point re staff costs - I'd forgotten about the way they have structured deals previously. Have you worked out how much this is in total and whether this is a temporary or permanent ongoing expense?
Hi Patrick - Acquisition consideration (deemed remuneration in accordance with IFRS 3) is £12.3m in 2023 and £10m in 2022 so very material indeed. You can argue the case either way, but my view is that adding it all back is very misleading as you still need a manager for an acquired business, otherwise they wouldn't structure the deals in this way in the first place. Presumably the vendors are still acting as management, so there should be a normalised cost. The reality is that the answer is somewhere between 2p and 10.5p EPS, maybe 6 or 7p EPS would be more reflective, but that's just a personal view. Obviously, that adjusts the P/E to more like 20.
BEG,
The cost , essentially paying themselves well, has always been an issue with Begbies. Paul and Graham have reviewed the company in the past and have noticed lack of tangible asset and high valuation.
Begbies Traynor (LON:BEG) - new note here: https://www.equitydevelopment.... FY23 results demonstrate how effectively BEG’s diversified professional services base performs across the cycle. Revenues have more than doubled over the past five years, adjusted PBT is up over three-fold. An 11% y‑o‑y increase in revenues in FY23 was driven by a broadly balanced mix of organic growth and contributions from acquisitions which have built complementary skills and extended geographical reach. Revenues from non-insolvency work (Advisory and transactional services) now contribute 40% of group revenues and comprise a mix of defensive, counter, and pro-cyclical sources, c 75% of which is derived from recurring sources.
A confident outlook is underpinned by an 80% income weighting towards counter cyclical and defensive activities. The next few years are likely to be busy for BEG’s insolvency operations as the UK faces a challenging economic environment. We also see potential upside from further acquisitions. We have adjusted 24e EPS for tax rates and issuance, but retain our 175p/share fair value estimate, equivalent to 17.0x FY24 EPS and a 2.3% yield.
The bear case here are three-fold:
Despite this, I think this offers a sweet spot of three things at the moment - counter-cyclical revenues, growth potential, and acceptable valuation. So I continue to hold, having help from 90p-ish. My target price is 180p to start selling, and 220p for full exit (not refreshed based on today's result, haven't analysed yet, but don't think there are any major surprises).
(I hold in the Boon Fund)
@peston
Pay continues to be squeezed in real terms, when adjusting for inflation. It is down 1.2% - including bonuses - in latest three months. We are still getting poorer, on average. But in cash or nominal terms, it is still rising at rates deemed inflationary by the Bank of England - or by 7.3% excluding bonuses. So there is no chance the Bank will pause the current cycle of interest rate rises.
https://twitter.com/Peston/status/1678653328685662210?t=Vy3b0f7Wc0zGukNUhj0Dpw&s=19
MPAC (LON:MPAC) - new note here: https://www.equitydevelopment....
In a Trading Update for the first half to 30 June 2023, Mpac reports that trading was in line with management expectations, reiterating - as stated at the AGM in May - that performance remains second half weighted, supported by the strength of the order book and projects underway. The Group closed H1 with a strong balance sheet and positive net cash.
Mpac notes that order intake for the year to date is significantly ahead at £62.4m compared to £32.8m a year earlier, with the H1 closing order book at £78.4m, +25%YoY above the start of FY23 (£62.7m). The performance of (higher margin) Service operations has also been strong, whilst the Group is able to report that supply chain issues that impacted completion of Original Equipment projects have now largely eased. This adds confidence for second half performance and a return to normalised margins: our FY23 gross margin outlook is 28.9%, for FY24 31.3% (FY19: 29.3%; FY20: 29.0%). We expect net debt of £4.7m to revert towards a positive FY23 net cash position of £7.5m. On site commissioning of the assembly line at FREYR’s Battery Customer Qualification Plant in Norway continues.
Our FY24 outlook remains 11%YoY revenue growth and 35.0%YoY growth in (adj.) EBITDA with fair value for Mpac seen at 485p/share, indicative of a FY24 EV/EBITDA multiple of 7.9x.
My morning smallcap tweet: Heavy winners
STM (LON:STM) Eagle Eye Solutions (LON:EYE) MyCelx Technologies (LON:MYX) Riverstone Energy (LON:RSE) Cornerstone FS (LON:CSFS) Forterra (LON:FORT) Galliford Try Holdings (LON:GFRD) Ondo InsurTech (LON:ONDO) H & T (LON:HAT) Norman Broadbent (LON:NBB) WANdisco (LON:WAND), Transense Technologies (LON:TRT), MPAC (LON:MPAC), EMIS (LON:EMIS), Sosandar (LON:SOS), Begbies Traynor (LON:BEG)
◄STM (STM)► 70p possible offer. a 155% premium. [SP=27.9 Cap=16m]
◄Eagle Eye Solutions (EYE)► guides FY-June rev up 36% and adj EBITDA up 32%, ahead of Board expectations. [SP=546.53 Cap=160m]
◄MyCelx Technologies (MYX)► contract extension for wastewater treatment in Middle East. Helps underpin market forecast. [SP=35.85 Cap=8m]
◄Riverstone Energy (RSE)► portfolio co Anuvia goes bust - $14m writedown. [SP=544 Cap=254m]
◄Cornerstone FS (CSFS)► Q2 continued strongly so guides H1 rev up 89% and a maiden positive adjusted EBITDA. [SP=10.15 Cap=6m]
◄Forterra (FORT)► guides H1-June rev c.£183m and adj pretax c.£18m, broadly in line with mgmt expectations. Market improvement less pronounced than expected. Guides "only a modest improvement in trading conditions in H2". [SP=163.4 Cap=348m]
◄Galliford Try (GFRD)► guides FY-Sept adj pretax at the upper end of forecasts (£22.1m to £23.3m). [SP=198 Cap=207m]. I hold.
◄Ondo InsurTech (ONDO)► agrees restructuring of 5-year loan notes with its largest shareholder, Homeserve Assistance. This "supports our accelerated drive to profitability". [SP=21.69 Cap=16m]
◄H&T (HAT)► mixed H1-June trading. "As expected, the exceptional level of redemptions experienced in late April and early May did not continue." In Q2 co prioritised stock turnover ahead of margin but margins are expected to improve in H2. Scrap volumes were particularly strong. [SP=421.26 Cap=185m]. I hold.
◄Norman Broadbent (NBB)► guides H1-June net fee income up 57% though Q2 was up only 50%. Guides EBITDA over £250k. CEO delighted with progress. [SP=5.5 Cap=3m]
◄WANdisco (WAND)► wins contract worth $7,680 with FordDirect. "Though small in initial value, this is the first contract the Company has signed with FordDirect." [SP=1310 Cap=9m]
In line: TRT, MPAC, EMIS, SOS, BEG
In other RNS wins, WANdisco (LON:WAND) office vending machine provided 2 kitkats in a stacking error when only one paid for.
Living the dream
It was one actually - the CFO overstated the number!
Good morning Paul, Graham
Sosandar (LON:SOS) have released their final results this morning.
Having had a quick scan through them, all seems to be going well with the growth story. 44% increase in revenue and a positive PBT.
I’d be grateful if you have the chance to review it please.
Sosandar (LON:SOS) the slowdown in growth to 10% y/y in Q1 is worrying for me but maybe I am missing something
They generally don't invest much in advertising during Q1 however a full year jump from £42m to £57 million looks challenging with Q1 only at 10%.
More of the top line detail Sosandar (LON:SOS) Full Year 2023 results today.
Management online presentation today 12.30pm. Register here. When you can ask about the 'Strong start to full year 24 with Q1 revenue +10%, £11.4m'.
#FORT - Major 20%-30% profit warning today from UK brick maker Forterra, who are now guiding to FY'23 adjusted EBITDA & PBT of approx £60m-£62m (Cons £75m) and £36m-38m (Cons £52m) respectively with -£50m of H1'23 net debt too.
#FORT - Major 20%-30% profit warning today from UK brick maker Forterra, who are now guiding to FY'23 adjusted EBITDA & PBT of approx £60m-£62m (Cons £75m) and £36m-38m (Cons £52m) respectively with -£50m of H1'23 net debt too.
Nasty warning but seems to have been well anticipated in the market price, hence moderate fall today
Forterra (LON:FORT)
The market seems to have punished Michelmersh Brick Holdings (LON:MBH) more than it has FORT. MBH has recently had much stronger momentum so I think that's probably why.
Both FORT's and MBH's AGM updates in May were basically "in-line" updates, so it does feel like there's at least a chance that MBH will be issuing a similar warning to FORT in the near future.
Great podcasts at the weekend Paul - always a helpful take stock of events and ideas and trends.
I hope Paul can get these podcasts back on the Google podcasts feed. If it doesn't automatically fall into my feed I don't download/listen to them. I know you had website problems a while ago Paul so hopefully you can find a way to feed the podcasts into the distributer channels. Since the feed went down I've only once remember to manually look and download from a link you provided.
There have been some comments (I think) about Acast but I don't really understand this app and can't find the podcast there either.
I listen via Google podcasts - but I think a name change from ‘Quality small caps’ confused the app. Try searching for “Small caps podcast with Paul Scott” and that should locate it. Essential listening, thanks Paul!
Hi wildshot, yes MrBrian is correct above. I had some technical problems with my website, so my podcasts are now going out on Google under a different podcast name, so if you unfollow the old dormant account, and search for Paul Scott small caps or something like that, the new one should come up on google. I know it works, because I use it myself, to check for errors, etc.