Small Cap Value Report (Tue 12 Dec 2023 ) - SUS, HEAD, MSI

Morning all! Graham here. I think I'll stop here - today's report is now finished (12.30).
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. OR it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
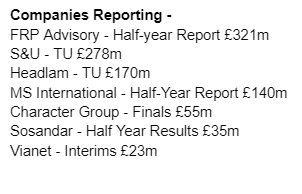
Summaries
S&U (LON:SUS)- £21.41 (-6.5%) £260m - Trading Statement - Graham - AMBER
I am switching to a neutral stance on this one, hopefully on a temporary basis. I am spooked by the mention of a Skilled Person Review, which recently led to the collapse in the share price of another one of my favourite small caps (JIM). I also note that the bearish language used by the Chairman seems to be even more bearish and exasperated than usual. Collections and repayments are ahead of budget but defaults are increasing while S&U's borrowings have also significantly increased. So I would now apply additional caution towards this stock.
£HEAD - 201p (-5%) £162m - Trading Update - Graham - AMBER
Results are only "broadly" in line, implying a small miss against prior expectations. Prior expectations, after a profit warning in the summer, already pencilled in a sharp slowdown in profitabilty on flat revenues. Revenues are failing to match inflation, with lower volumes currently tracking the performance of the floorcoverings market as whole. This is a tricky sector but the depressed pricing of this stock (P/S only 0.25x) should allow for significant upside if conditions improve.
MS International (LON:MSI) - 882p (+3%) - Half-year Report - Graham - GREEN
Paul and I have consistently championed this one and it's pleasing to see that it's delivering for shareholders. The cash balance has grown, H1 profits are very considerably higher, and the prospect of deliveries to the US Navy has been crytallised with the announcement of naval gun production, maintenance and support contracts. Valuation is considerably higher than before but personally I don't see it as being overvalued here. So I'm keeping our positive stance on MSI.
S&U (LON:SUS)
- Share price: £21.41 (-6.5%)
- Market cap: £260m
This motor finance and property bridging company issues a trading update with arguably even more downbeat language than usual:
Following a very good first half, S&U continues to make steady, if more cautious, progress despite the "current economic, tax and regulatory burdens weighing on business" we reported at half year.
The company's financial year-end is in January, so today's update refers to progress since the half-year results for July.
Growth continues in the loan books:
- Motor finance: £327m (up from £313m at the half-year results).
- Property bridging: £119 (up from £104m at the half-year results).
S&U's borrowings increase to £209m vs. committed facilities of £280m - perhaps another increase in the facilities might be prudent soon? Although S&U say that the curent facilities will "comfortably" allow them to carry out their plans over the next year, I would nevertheless be on the lookout for an increase.
Chairman Mr. Coombs continues in his usual style:
...caution is necessary. Those burdens weighing on business are reflected in a lack of consumer confidence, cost-of-living pressures, persistently higher rates of interest, and a new raft of regulation, all of which inevitably affect profitability.
Further out, an anaemic outlook for growth in the UK, recently predicted by both the Office for Budget Responsibility and by the Governor of the Bank of England, combined with restrained growth in household expenditure over the next two years, make S&U's focus on working with our customers, credit quality and appropriate forbearance more essential than ever before. The volume of consumer finance used-car market transactions fell by 5% in the year to October 2023 according to the Finance and Leasing Association ("FLA"), whilst prices in the housing market remain subdued and, in many areas, actually in retreat. Hence, whilst we remain ambitious and optimistic, it would be unwise to plan for major growth until these trends have stabilised and economic prospects improved.
In the outlook statement, he refers to "the obstacles all businesses face in times of feeble growth, pressures on the consumer, high taxation and inflation, and regulatory changes and political uncertainty" (don't worry - this is normal!). He finishes with the promise that S&U will emerge "as successful and as strong as ever".
Motor finance
Live collections have fallen to 91% of due (vs. 94% last year). Despite this, "the number of bad debts and voluntary terminations" (i.e. handing back the car keys) remained below budget.
The FCA is currently taking an interest in S&U's motor finance business: a review "has developed into a more formal interaction wit the FCA". There is now going to be a "skilled person review" (this is explained here). The timing of this is interesting, as the long-standing CEO of this business has just retired.
Property bridging
Higher rates "have put a break on recent profit growth", and one additional loan is now extended or technically defaulted. So 16 out of 130 loans are now extended or technically defaulted. But recent repayments are "20% above budget".
Graham's view
I am normally very positive on this share; however, I believe that additional caution is warranted today in light of the "skilled person review". Recent events at Jarvis Securities (LON:JIM) are very fresh in the mind - the skilled person reviews can be a "lengthy and costly process", as S&U acknowledge today.
Purely on the financials, I remain a fan of S&U, despite the many short-term economic headwinds. However, some additional cautious is justified when the FCA are taking an interest. Therefore, I will (temporarily, I hope) switch to a neutral stance today.
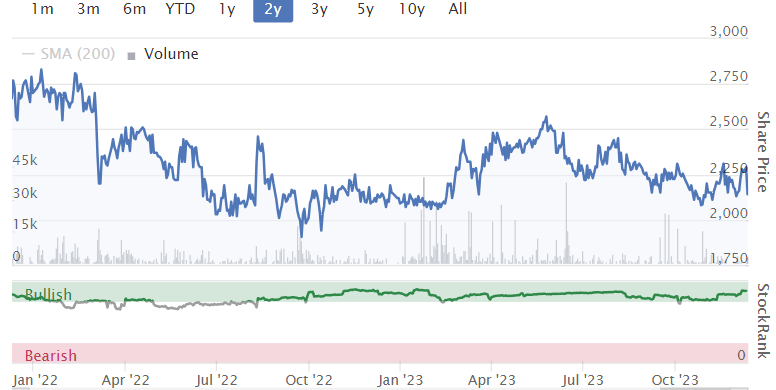
I hope I don't miss a sudden re-rating in this stock while on a neutral stance. But S&U shares have been trending sideways for some time:
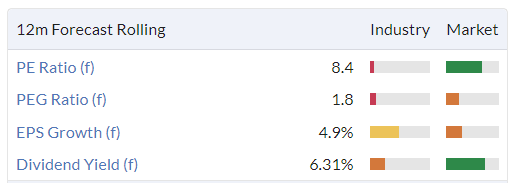
This stock may seem cheap but in the context of current valuations in the banking sector, it is arguably on a premium rating:
Headlam (LON:HEAD)
- Share price: 201p (-5%)
- Market cap: £162m
Headlam Group plc (LSE: HEAD), the UK's leading floorcoverings distributor, is providing a trading update in respect of the eleven months of the year to 30 November 2023 (the 'Period').
The financial year-end here is December.
FY 2023 is expected to be "broadly in line with expectations" (this often means a slight miss).
September and October were "weaker than expected" due to consumers cutting back on home improvement projects.
Key points:
- Revenues flat year-on-year (UK slightly positive, while Continental Europe saw a decline).
- Volumes down 5% in the UK (thought to be in line with the market as a whole). Compared to 2019, UK market volumes are thought to be 20% lower.
Margins and costs "remain well controlled" despite cost inflation still being "elevated".
Graham's view
The official announcement doesn't add too much; expectations have likely been lowered (see if you can get your hands on a Peel Hunt note for more information).
As of 12th October, consensus expectations for 2023 were revenues of £664m and underlying PBT of £11.9m. This implies an equal weighting between H1 and H2 for the current year, and overall a very sharp deterioration in profitability versus 2022 results.
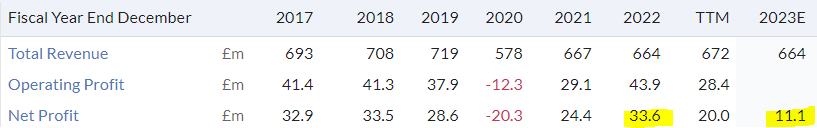
Checking Paul's notes in July, he observed that the company has "very solid asset backing", including freehold property. So hopefully it can weather these conditions without suffering any financial distress.
Even though inflation has cooled, I still have higher revenue growth expectations for companies than I would have in low-inflation conditions, and Headlam's flat revenue performance this year must be seen as a disappointment against that.
And while it says that margins are costs are controlled, the slowdown in profitability clearly demonstrates that higher operating costs are taking a toll.
As with every low-margin business, small differences in performance can lead to enormous swings in bottom line performance, and that is what we are witnessing here.
I will maintain Paul's neutral stance on this one. The price to sales multiple is only about 0.25x and that does allow for shareholders to do well if margins and the operating cost profile can improve.
MS International (LON:MSI)
- Share price: 882p (+3%)
- Market cap: £144m
This is an unusual collection of seemingly unrelated businesses, with heavy insider ownership (Chairman Michael Bell owns 18%).
Its four divisions are as follows: Defence, Forgings, Petrol Station Superstructures, and Corporate Branding.
Share price momentum this year has been excellent:
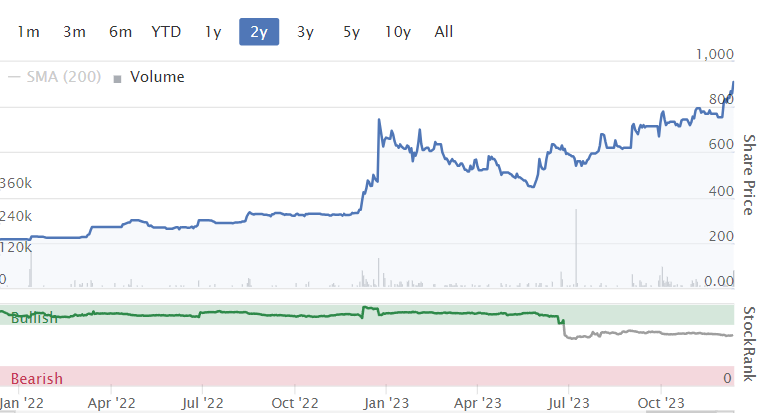
This morning we have confirmation of production order contracts with the US Navy, relating to a 30mm naval gun, along with a related contract for maintainenance and support. Delivies will commence in the new year.
Given the share price trajectory, I think it's clear that the market has been attempting to price in this news in recent months.
The Chairman has been working on the project since I was a toddler:
I first reported on our efforts to break into the US Navy market in my Chairman's Statement of 25th July 1988, when I stated, "The first unit built to suit the US Navy specific requirements awaits ships trials in the United States". It has been a long haul, but vision; persistence; determination and capability has resulted in success.
Separately, MSI reports the first sales of a counter-drone weapon: this should have been achieved last year but was delayed by the war in Ukraine.
Here are the financial highlights for H1:
- Revenues £57m (H1 last year: £42m)
- PBT £7.7m (H1 last year: £3.5m)
Net cash is £50m, covering a significant chunk of the market cap.
News from the other three divisions (excluding Defence) is less dramatic, and very little is said about them. Note that MSI acts in many ways as a private company: there are no broker forecasts and the company often appears to say the bare minimum that it must regarding its operations. There has been no increase in the share count for many years. If anything, the share count has declined over time. As it has little need to raise funds, we can understand why it would seem to take little interest in the stock market's opinion of its performance.
With the share price having multiplied several-fold over the past couple of years, perhaps it will now start to catch the attention of more prospective investors, whether it wants to or not! Paul and I have been consistently positive on this one and I can't consider changing stance on the back of today's excellent results. The step-change in profitability and the very healthy cash balance (still over one third of the market cap) strike me as sufficient grounds to think that the valuation here remains reasonable.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

125 comments
Given there are discussions re FCA and consumer duty/fair value on todays SCVR I think the light should be shining on S&U also. This is where the fair value thing has the potential to be a mess. I dont know much about S&U but see they are catering for lower and middle income groups that may have impaired credit records.... Who are they supposed to benchmark themselves against Barclays !!! Coutts will have fun with this duty as well I bet at the other side of the wealth divide. And according to the guidelines if they are making excessive profits from one segment of customers (who might be offically classed as "vulnerable") thats an issue.
So far I dont think there are any fines coming out of the FCA yet but as time goes on much will depend on how stringently they expect firms to apply this duty. The FCA is not above retrospective compensation of interest either but would have expected some sort of offical warning or Dear CEO letter to be issued before they go down that route.
Having said all that, knowing how they think, it is possible the FCA will consider interest on customer deposits as being "client money", not the firms!
incidentally while S&U's Ombudsman complaints may have been spurious you might find the following publically available info interesting:
https://www.financial-ombudsma...'t%20need%20to,case%2C%20regardless%20of%20the%20outcome
You won't need to pay a case fee for the first 3 complaints against your business that we deal with in each financial year. From the 4th complaint onwards, we charge a case fee of £750. If a case does need to be investigated, it becomes a chargeable case, regardless of the outcome.
- ouch !
Thank you Mark. Your thoughts on MS International (LON:MSI) have always been excellent and much appreciated.
Zotefoams (LON:ZTF) I only have a very small interest in these but it is up 30% since it's steady as she goes trading update on November 7th. Either someone knows something about the REZORCE proposition or the market for small caps is just maybe looking a tad more accommodating.
The guy asked to head up the Rezource project just bought 100k of shares this afternoon. Make of that what you will... (I hold)
Thanks Ben , I hadn’t noticed that. That would seem a meaningful purchase. Interesting.
MS International (LON:MSI) Interim results.
My largest holding by quite some way, now...... 40%+ ....... in my concentrated folio of a dozen UK small/micro caps. Though to be fair it would not be quite so large if the rest of the porfolio hadn't progressed ......backwards...... so much!
Great, if a little disconcerting, to see so much discussion of MSI interims. Not something I've got used to yet having been a holder for over a decade. So you might with reason suggest I started buying in a little early? But if anything is hard to time - MS International (LON:MSI) is! And I'm a johnny-come-lately comparatively. In his commentary the chairman claims that work started on the US market in 1988! How does it go...... If at first you don't succeed......? Anyway fwiw here's my take on todays results
Not bad.
And the slightly longer version. Came in a little below my estimate of 40p eps with revenue also below my expectation. All the same it's clearly a big step up from last year and even on the last FY results (25p) - though that's almost entirely due to taking the revenue and profit on the delayed payment for the systems now in service in Ukraine. From the receivables jump to £27m it looks as though payment was approved by the multi-country consortium in September but had yet to land in the bank by the balance sheet date (end of October).
Understandably the defence division is the center of attention. Operating profit for the other 3 divisions came in around my expectation, on lower revenues than I'd expected - which is not a bad thing? I see plenty of potential for revenue and margin growth in these divisions, and not just in defence.
The scale of the opportunity in defence is clearly in a different league. Though excluding the delayed payment - revenue and profits in defence were muted in H1. There looks to have been few if any further deliveries made. That looks to be about to change given the massive jump in contract liabilities - up by £42m - and the jump by £3m in contract assets - there looks to be a lot of work in progress (and I'm assuming its almost entirely due to defence). The cash pile also grew, though how much will be used in working capital is never clear to me.
It all bodes well for H2 - though as we saw last year contract deliveries and payments make for very lumpy outcomes when measured on a single day. The recently announced USN contracts will not contribute significantly to H2, but start contributing from FY25 onwards. In my view the biggest unknown is the delivery and payment on the two contracts announced in July totalling £54m and I suspect that this accounts for most of the contract liabilities?
Makes estimating a fools game? But foolishly I like to have a go, and fwiw I have pencilled in 50p eps in H2 - for an FY total of 85p. Assuming delivery of one - or part of - the large contracts currently in progress.
The outlook for the defence division looks more secure now that the USN longterm contracts are in place. I think it likely that the roll out across the US fleet will also bring in other sales. The longterm success of the land-based C-UAS* capabilities has the potential to double defence sales again as we've seen with the initial contracts - £78m orders placed within a year. But will the sales continue? It's a fast moving market and there is a lot of competition out there. Management says that they are 'pleased and encouraged' by the number of enquiries for availability and potential supply. Whether they can convert this into another order in H2 would give me a lot more confidence in the longterm success of land-based sales. And make the company very undervalued currently!
There is always so little information with MSI statements that I end up reading the tea-leaves and coming up with speculation based upon a few words. In that vein - what to read into the change of division name to 'Defence and security'?
cheers
Mark
* C-UAS - Counter Unmanned Arial System refers to the counter drone ability. The system may also have potential C-RAM - Counter-Rocket, Artillery and Mortar ability to some as yet unquantified extent.
Thanks Mark
Not so sure on the anti-drone gun system that there is a lot of competition out there to be fair. I think MS International (LON:MSI) is seen as best in class on a relatively modern gun type and that’s why they have so many forward orders and enquiries. The fact the US have bought it for the long term acts as a very solid reference. Usually defence companies with such moats trade at much higher multiples.
Anyway I take an even more cautious estimate to EPS than you - I think 75p EPS this year is likely (if your 85p number comes in then happy days) but I see 100p+ in the next year or so as being pretty likely. Who knows what the market will price that at of course but if you take peer type valuations of 15-20* and add the cash you get to a 1800 - 2300p potential price. The current 900p looks pretty miserly in comparison.
Anyway, none are for selling for me at this price. I will start having a headache at 1400-1500p but we are still miles off that so I’ll just sit tight. Kind of feel if it breaks the 1000p psychological barrier it could move up there quite quickly. We are seeing momentum in a number of stocks - I have been trying and failing to get in to Rolls-Royce Holdings (LON:RR.) since 220p and it just has gone up every day - almost no pull back, so I feel MS International (LON:MSI) could re-rate quickly 30-50%, particularly if they announce another material order in the coming couple of months.
Is anyone having any difficulty using AJBell’s new website? I have been trying to increase my Oakley Capital shares and the site refuses to deal saying that I have to complete a Complex Dealing form It does not give me one and I cannot find any on the site Very unimpressed so far!
Hi Benson, I filled on ages ago when I bought Oakley Capital Investments (LON:OCI) . As I recall it was an online form on the AJ Bell site. Call or email support, they are pretty helpful I find.
I had the same issue when trying to buy Rockwood Strategic (LON:RKW) on Hargreaves Lansdown. Eventually managed to buy the shares, but had to complete their 'complex dealing form' or whatever it is called. Absolute pain in the backside. No doubt Hargreaves are trying to protect theirs, which is rich after the Woodford debacle.
Hey Ho!
Hi Benson, In case your still struggling
Hover over ‘My Account’ at the top of the page.
Click ‘Update My Details’
From here scroll down until you see ‘Complex instrument appropriateness assessment’
Then click ‘Take Test’
Yiannis. You and I had a set to yesterday with your usual directness to the fore. I thoroughly enjoyed it and am always entertained by your slightly confrontational approach. It's clearly not to everyone's taste but a good variety of guests makes the party. Stay the course with us.
I pay for SCSW. If their content was freely posted here, I’d cancel it. If early news by an editor here was shared on advfn and everyone there sold before I had seen said bad news, I’d be pretty peeved. But, it’s stuff that just can happen and a knuckled got wrapped. That’s all.
I like his useful contributions. Not a fan of the tone sometimes, but that’s on me. I ruffle feathers in my own way. We all do. We’re not here to balm chapped lips.
AJ Bell (LON:AJB) response would appear to be supportive since measures being introduced are NOT a downgrade.... will be interesting to see what Hargreaves Lansdown (LON:HL.) say, I suspect nos may be under pressure.
It sounds from the RNS as though AJ Bell (LON:AJB) had this package ready (hence baked into their forecasts) but were waiting to confirm that the FCA was not going to apply a salami slice approach of taking one element - namely the payment of interest - of a bundled offering and judging whether the amount paid was fair relative only to the costs of distributing the interest. The RNS states twice that AJB is clear that the FCA is not doing that. This point should never really have been in doubt: I don't earn interest on funds in my current account because the bank has to fund the "free" banking bundle of services on a cross subsidised basis.
The FCA's announcement this morning was very sweeping in nature. This created something of a disorderly market -- contrary to the FCA's remit. It made no sense that AJ Bell (LON:AJB) and Hargreaves Lansdown (LON:HL.) sold off in parallel this morning because AJ Bell has a scale economies shared strategy (customer benefits) and HL has (in my view) a milking strategy.
Talk by regulators is cheap and they may welcome hard hitting headlines. However, taking action against any individual company would require more careful consideration of how a Court would regard the position. Moreover, the FCA is, I think, being somewhat remiss in jumping straight to the consumer duty without first ensuring that competition is working effectively by ensuring transparency of charges and enabling rapid, reliable switching between providers. The FCA has not enabled rapid, reliable switching of share dealing accounts as a recent 2 year (not a typo) delay in switching from Barclays attests (compensation was paid for the delay following a complaint to the regulator). This may well be a market where making competition work effectively does not adequately protect consumers but the FCA should not jump straight into off-the-cuff price regulation (under the guise of its consumer duty) without sorting out the underlying market.
The FCA's announcement this morning was very sweeping in nature. This created something of a disorderly market -- contrary to the FCA's remit. It made no sense that AJ Bell (LON:AJB) and Hargreaves Lansdown (LON:HL.) sold off in parallel this morning because AJ Bell has a scale economies shared strategy (customer benefits) and HL has (in my view) a milking strategy.
I'm sorry, but as someone that has been a customer of both companies for over 10 years this is absolute garbage. AJ Bell are WORSE than HL in just about every regard. This marketing brochure masquerading as a RNS is just such as case. The interest rates they have "advertised" in the RNS that they are gleefully introducing from April 2024 are not even as good as the interest rates that HL offer right now, and that they have done so for the past few months at least. But let's not let facts get in the way of a good rant, eh?
https://www.hl.co.uk/charges-a...
DG Innovate (LON:DGI) Just a general comment - small R & D company with Enhanced Drive Technology (EDT) and Enhanced Battery Technology (EBT) components worth a look at, review? Shot up massive percentage yesterday on news that three former Tesla men appointed, apparently took interest due to leading technology. Interesting up a further 35% today to date.
These US CPI numbers have "supposedly" come in at 0.1%... which I think is everything the market can want. Seasonal adjustments etc seem to be making more of a difference and a little hard to work out exactly what's going on.... anyway, over to the Fed... don't see anything here for them to have to be more hawkish....
santa delivering some MOMENTUM in time for christmas, no?
although iwill still maintain that e.g apple, microsoft, nvidia etc. look very pricey.
fortunately - as long as you are not an investment professional and/or you are not managing 9/10/11 figures, you have the whole market and the whole world to browse and pick from and are not forced to stick to mega caps...(hence this blog!)
May I clarify your comment as follows "Overall inflation climbed 0.1 percent on a monthly basis, making for a 3.1 percent increase compared to a year earlier. That was cooler than the 3.2 percent annual figure in October." From the New York Times.
Finally got the Non seasonally adjusted no is actually -0.2% ....§which is why the annual rate fell which I didn't understand at first ...from 3.2% to 3.1%....makes me even morerelaxed about the Fed to be fair.
Cohort (LON:CHRT) one that Paul likes and has interviewed the CEO recently. Webinar open to all tomorrow at 4.15pm after release of H1 results. To hear about those, defence spending and geopolitics - register here: https://www.equitydevelopment....
Eneraqua Technologies (LON:ETP) sneaky profit warning just out while everyone is at lunch. Look out holders
Another one...
I wonder what the FDA do sometimes. Surely their activities over the last year deserves an investigation.
Eneraqua Technologies (LON:ETP)
Hi Meghan ,
I wanted to share your message to me with the community and my views about the issue-
“Request that you don’t share tips from other publications on this space. It is very unfair to the publication and its subscribers”.
I totally get your point but I do not understand your response. There must have been at least 100 times that people are asking here why a certain stock has risen 10% without any news-and many people here answer that this has been tipped by different newsletters, newspapers etc , naming them and it had NEVER been an issue, as we are all trying to help each other with any extra information we have (at least this is exactly what I am doing).
Also every weekend there is a podcast(I do not listen to it as I understand it’s just repeating what was written here) that everyone all over the universe can listen to it for FREE that includes basically what is covered here with a paid subscription over the week!
It seems that there is one rule for me and one rule for others and this is unacceptable. You have however , stated in another message that it is something that the management is working on it.
Lastly , I have decided to stop commenting on this forum as I find the response by one of your writers insulting (calling people obnoxious , unstable characters, etc , etc).
However, I will still be reading the comments especially from Davidjhill , PlanetX , Boon and some other clever people.
It’s one thing to strongly disagree with someone and another thing to call people different names.
All the best everyone and good luck with your investments.
yiannos1 - your contributions here are most greatly valued by me - please dont let some stick in the muds get you down. As you say if someone is asking about a stock rising and its due to tip sheet i think its ridiculous to moan about about someone commenting thats why its risen - similarly if its public knowledge (eg on advfn or the like) - that tipster x has tipped it you cant put the genie back in the bottle and ignoring the genie is imho doing more bad than good. I have to presume all of these "paid for tips" have an extremley short shelf life as being kept privvy as i would expect if they are looked at the adjustment as approrpiate will normally be done that day - i preume that the reslity is these tipster buy then tip so they i would guess will be happy that these tips are relayed once subscribers have had theior momentary chance to act - all seems a fuss over nowt imho . The fact management may be working on it says nowt to may they may simply be looking and deciding that there is no case to answer for. Anyway heres hoping if you are lurking that you may once in a while chip in if you have something to say.
I share the concerns raised by Yiannos here actually Meghan…….. when an institutional broker brings out a broker note and us retail investors don’t have access we rely on someone with access telling us that the price has gone up/down because of said broker note. Research Tree helps tremendously with this dislocation of information but can’t cover all.
In the same way when a stock goes up because it has been tipped (eg Investors Chronicle) I see no reason why a reader should not confirm the reason for that. It is information that may help readers not buy on froth. The MMs have access to this info and immediately mark up prices so this information is both known and traded upon immediately when published so therefore has to be public.
Where you should draw the line from a regulatory and legal perspective is front running that information. I don’t believe you can or should be trying to censor sharing of public information. In my view readers should not be pasting the rationale etc. but not the fact that it has been tipped.
Stockopedia should tread very carefully here. Investors are already at a distinct information disadvantage - you should not be trying to worsen this.
Edit : I have separately mentioned this to The Stocko team
Tipsheets
I think the issue here is that it was not retrospective (i.e. Why has the price gone up? A. SCSW have tipped it). It was posted between 07 00 and 08 00 yesterday and so readers here would have the same awareness as SCSW subscribers at market open.
In that case it has to be deemed as speculation as to what might happen, as the tip had not yet had an opportunity to effect the market, it may or may not have had an impact on the SP. I personally have no issue with the sharing of such information.
"Where you should draw the line from a regulatory and legal perspective is front running that information. "
I would agree - but I cant see how a small company like Stockopedia could police this?
I also think that Yiannos has a point. It would surely be impossible to censor material that is already in the public domain, albeit via a subscription publication
They don’t have to police it. In fact I don’t want them censoring - I accept they have to moderate based on abuse and anything they see that may breach copyright or regulation / law. But Stocko should not be telling people what they can/can’t mention based on someone’s perception of ‘fairness’
"I accept they have to moderate based on abuse and anything they see that may breach copyright or regulation / law"
I think that was my point. I couldnt see how front running (information) could be moderated. You mentioned "drawing a line" - but I couldnt see who was in a position to draw this line. I assumed that you were referring to Stockopedia.
Meghan, I also share the concerns Yiannos1 raises. Your approach represents the "thin end of the wedge" to something that would reduce the quality of Stockopedia. What about when forecasts from broker notes are repeated by the writers of this column? That's also (often) subscriber information that shouldn't be disclosed. They obviously don't disclose the detail of notes, but neither did Yiannos1 when he mentioned the SCSW buy recommendation. The other thing to add is the reason I continue to renew my Stockopedia subscription is the information and insight I get from the Small Cap Value Report, not only the analysis by Paul, Graham and Roland but also the posts by subscribers like Yiannos1. Please could you rethink.
I get that copying and pasting articles from other websites might possibly breach of copywright but as others have said commenting that a reason for a price move may be a tip elsewhere is basically just reporting the news and should be fine,
"...stock goes up...tipped (e.g. Investors Chronicle)" - has that ever happened ? IC tips are a sell signal !
;-)
Don't go Yiannos! Whilst I don't agree with everything you write, nor sometimes the way that you write, I do enjoy and value your contributions and your oft-contrarian (not in the investment sense of the word) posts. Perhaps it's because my Mum used to b8llock me and say "It's not what you say young man, but the way that you say it!"...... ;-)
I agree. Published share tips or broker recommendations are not confidential information and can be shared freely. Trying to supress sharing tips would be ineffective and creates a disadvantage to (typically) private investors.
When you pay, for example, for Investors Chronicle the customer gets to read the text and analysis behind share tips. Duplicating this would indeed be unfair and probably a breach of copyright. But the tips themselves are fair game.
Well, the free version of Investor Chronicles actually shows the tip and the first few paragraphs of the text. It used to be the case that they didnt show anything at all. Thats says it all really. Its not the tip itself but the copy of the main text that should be suppressed that contains the reasoning of the analyst for giving the tip.
Also Meghan used to work for Investor Chronicles so perhaps there is a little bias towards that publication and similar ones.
Yiannos
Come on have a rethink , need you here .
Your in my top of the pops stock pickers .
Take the dog for a walk, do sone yoga, or something suitably cleansing .
Stick around yiannos1 - the community needs more like you that dont fear to speak against the crowd - in investing the alternative view should be all the more valued. Sometimes you are a bit prickly, but I would prefer that many times over to some of the the other posts where vested interests are clearly being played. From a personal perspective, I would view 'tips' from any source just as information to be accumulated (subscription or not), rather than a firm investment trigger. Maybe Megan wanted to show some sort of fairness to other companies in the same space, and eliminate any possibility of criticism for the site - anyway, overdone in my opinion. People expressed their views at the time, sufficient in my opinion.
First time poster here who feels compelled to speak out in defence of yiannos
I'm a relatively inexperienced investor aged 39, gotten quite serious the last couple of years with my contributions and now have a reasonably sized portfolio that I'm hoping to grow to help with my planned aged 50 years retirement
I visit these boards several times a day and am happy to pay the yearly subscription for what I perceive as the education and lessons I get from the platform, editors and increasingly from the community posting
Yiannos is one of the many contributors I always look out for and I appreciate his opinions greatly even if I or others disagree with his comment in certain matters
Lse and advn although I visit them for shares I own are a bloody nightmare full of screaming kids and as Paul would vouch in respect of plexus there's pages everyday full of nonsense which has nothing to do with investing or the company
The discussion here is always investment based and it takes all sides of view (bull and bear) to assist people form an opinion
Surely as a community if we get information from another source that we want to share with our fellow civilised investment community here then in my opinion it should be encouraged (do you believe other sources feel the same as Megan's comment and wouldn't do the same if the tip came from stockopedia?)
Paul is an absolute asset to stockopedia and his workload here and on the podcast go over and above, I appreciate and respect the content provided by him however I suspect he had a few to many when the comment was posted last night (it's not the first time there was a late night crass comment against yiannos, subsequently deleted)
I want to make clear I'm not getting on at Paul (please dont take it that way paul), we all do things as adults that we may look back on with a frown (me more so than others)
I hope yiannos rethinks his posting stance knowing Paul's comment wasn't posted at 1pm in the afternoon and everyone on this board just draws a line in the sand and we can move on as before
I feel the Members contributions here as important as the content provided, sometimes even more so, the last thing I'd like to see is us loosing knowledgeable members who are prepared to put there hand up and give a different point of view
Sorry for the long winded post and as it's written I feel i should finally say hi to everyone
Callum
Great 1st post Callum - welcome. And I agree 100% with everything you say.
Whilst Yiannos can be prickly, argumentative & blunt he has some well thought through arguments and being a contrarian thinker has never been a crime.
I don't always agree with many of his views, the world would be a far worse place without some good and honest debate.
I also echo PlanteX's comments and recognise him as another great contributor.
Yiannos I appreciate the counterpoint you regularly offer…& would be appreciative if you could reconsider your recusement…not everyone here posts a great deal…but from the peanut gallery we value a diversity of opinions
Yiannos,
What he (Rhom) said! Couldn't put it better myself so I won't try,
I appreciate the counterpoint you regularly offer…& would be
appreciative if you could reconsider your recusement…not everyone here
posts a great deal…but from the peanut gallery we value a diversity of
opinions
cheers
Mark
Sosandar (LON:SOS) I don't hold but have just watched their H1 2024 results webinar. Does anyone else who watched have any thoughts?
FWIW mine are ;
The two founders have done a great job building the brand, however is the actual market for their product as large as they think?
To my mind even forgetting profit, the revenue increase over H1 23 was very poor for a 'new' brand that has opened new channels in 3rd party websites and bricks and mortar retailers ( TBF some of this is post period end). When you compare their recent performance with Next (LON:NXT) or possibly Marks and Spencer (LON:MKS) it is pedestrian and regardless of economic conditions a young brand like Sosandar should be growing revenue by 20% at least to show it had legs. I felt all the slides were formatted to make the numbers and comparisons look better than they were and there was loads of self congratulation about the brand etc but when will it bear fruit.
I imagine that the physical store role out is possibly the last throw of the dice? When asked whether they needed a fund raise for this roll out the initial answer was we don't think so .
Maybe I am being too harsh.
Good assessment and I’m a holder. They have built up a head of steam, are taken seriously by bigs co’s that hate to make mistakes and the international partnerships are just starting.
I think a retail roll out will add value.
LTBH for me.
What I would say about Sosandar (LON:SOS) is this…..
Commendable that they pivoted to an Omni-channel when it became abundantly apparent that online only consumer preferences have changed. Shoppers like going to a store, browsing and trying things on. Next do it brilliantly and no reason Sosandar (LON:SOS) can’t make it work either. Much lower return rates and higher margins - their demographic probably prefer physical shopping and online browsing.
However - this was clearly not the business plan so they should own it rather than gloss over it. Market has changed, trends pre Covid that were exacerbated during Covid are reversing. Footfall is returning to high streets and particularly retail parks/centres so we have to as well type thing.
But they have grown a strong and well liked brand from nothing and no reason this won’t continue. They’ve sacrificed growth for full price sales in the short term but now they need to demonstrate they can grow 15-20% per annum.
What I don’t like is that this change of trends didn’t happen in a 3 month period between one update and another. I’m not sure management can be trusted to give a ‘non dressed up’ message and that’s a problem. Neither of them are used to public markets so I’ll make some allowance for that but they need to aspire to the type of commentary Next provide and less hyperbole.
All in all I retain a very small position and think they have a decent future but I’m irritated by the messaging.
Thanks David. Many great points.
I don't agree about opening their own shops; instead they should use their 3rd party agreements with M&S to do the touchy feely thing at this stage (pre profit). Trying to run before they can walk comes to mind ...
MS International (LON:MSI) Graham, thanks for the MSI write up. It's been an excellent day for holders. There's an error in the write up. "With the share count having multiplied several-fold over the past couple of years" I think you mean price, not count.
Thank you very much spglet, fixing it. G
S&U (LON:SUS)
These methods have been validated by Advantage's excellent record with the Financial Ombudsman Service which at an uphold rate of just 15% is, by some margin, the best in the motor finance industry.
They are proud that 1 out of 6 people that go to the trouble of contacting the ombudsmen win their case. I would like to think that for a proper company nothing needs to go to the ombudsman - imho 1 of 6 times kloosisng and being deemed to have "scammed" presumably someone seems to high ? - am i being unfair in thie viewpoint?. Being less of a scammer than the company next door isnta greta advert. Note i would have thought that they would be actively looking to settle without going to umbudsmen - so so should they not be taking pride in winning nearly all cases - if they want to say they aint spivvy.
"review of Advantage's, collecting processes,procedures and policies" we noted at half year, has developed into a moreformal interaction with the FCA.
Along with many other lenders in our market segment, Advantage has appointed a Skilled Person
Should this business not have have had a skilled person in place or quite some time?
Note they have gone out the way to say how oustanding then profit generation has been - that should not sit will if they are being taken to task for practices and are losing regualrly non immaterail amount of decisions where peeps have taken the trouble to go to the regulator
per company previously
reflecting good collections and lessutilisation of the impairment provisions made in the dark days of January
2021. Thus, over the past two years of Covid, Advantage has been able toproduce an average of over £30m annual profit, quite remarkably just lessthan 10% lower than in the previous two years.
I am well aware their "customers" may be trying to pull a fast one and may be succeeding here on technicalities - any money lending company should know fine well they dont want to be dealing with the regulator though and when they are doing so they should be taking all active steps to avoid that level of supervision being upped.
It may be that times have changed quickly and they are being harshly treated by the regulator - must admit i am actually quite impressed that the FCA regulation for these type of companies does seem to be more fit for purpose than it used to be - imho if its not 100% by the book legit with no room for sketchy arguments then i am happy the regulator is taking such a line with these firms.
Where this ends i know not i have made a modest investment in CMC Markets (LON:CMCX) recently - if they get srecwed over by regulator i only have myself to blame - all companies in this regulated sector are really very at teh mercy of the regulator not coming after them next.
This is a total misunderstanding of ombudsman process and industry.
Only gets to ombudsman if company has refused to accept complaint from customer / settle. A 1 in 6 failure rate on an unresolved disagreement is good…particularly if one considers how far the FCA guidance goes in terms of forbearance and forgiveness for consumer.
It’s also a misunderstanding of capitalism where more risk/niche activity should have higher reward. If the world were as chocolate box as you imply the banks would be hoovering up this business at a lower price but nevertheless great profit to them…
I here where you are coming from mojomogoz - they clerarly may not be the bad boys here by any stretch of the imagination - but i stand by my comments - that if 1/6 of peeps who feel the need to go to the ombudsman succeed that is still far from immaterial pool of customers that have clearly been wronged by this company - if the same proportion again have had dispute settled internally due to the fact the company knew they would lose thats 1/3 of peeps who have had to raise formal complaints due to unfair treatment with only half having been dealt weith fairly by the company
IMHO its in very few peoples interests to be borrowing money at apr's that are such that its not in their interests to proceed. I understand there may be a amrket out there for 40% apr on car loans over several years - the fact peeps can borrow doesnt mean its in their best interests to get themselves into that situation though. Note i am not totally against these companies existing - its just from my point of view a bit of karma if they screw customers and then get screwed over by regulator. I take the viewpoints the the bank factor reputational risk into things when making decisions - they probably know fine well at niche stuff banks probvably cant compete with more nimble players.
Note i am not saying there is any particular issue with this company to a ceretain degree it comes withn territory - not sure if one or both the listed pawbrokers have been through similar "oversight" and from i think have come through ok ? - so i am not really even saying this is a big deal - just that if it was we wouldnt rally know it - i 100% bow to your judgemnet in this area being different level compared to my uninformed pub type rant.
I encourage you to read the Ombudsman reports that were upheld. They are publicly available. A very good proportion are complaints because the car broke down after purchase - clearly not something the finance company is directly 'to blame' for - but where reasonable people can have a dispute about who should shoulder the burden.
My personal favourite was the guy who requested a 3 month deferral, during COVID - which was granted. At the end of that, he requested another 2 month deferral, which was granted, because he said he wasn't working. At the end of that, he requested another deferral, at which point Advantage Finance asked for some evidence he wasn't working and couldn't afford it. That was deemed a heinous over-reach on Advantage Finance's part, and the Ombudsman said there should be £150 compensation as a consequence. Advantage agreed to pay it, but the claimant said that wasn't enough, and he is entitled to more for emotional distress.
Ultimately the Ombudsman decided that 150 quid was enough, but it counts as a 'upheld' case in the stats.
Ahaaaaa - we can view em online great stuff - didnt realise that.
Good news from Jubilee Metals (LON:JLP) this morning, up 10 percent as I type.
Bought spot on at the bottom, and targeting a price move to initial resistance at 6.5-7p .
Long term hold for me, looks super cheap, and as metal prices recover, strong candidate for a multibagger.
Lets hope so Guybrush - i was suckered into Jubilee Metals (LON:JLP) at the top! Its going to be long way back…
S&U (LON:SUS)
Who am I to disagree with Graham!...but I'm much more sanguine about the update from S&U and take a different perspective on available information as there is little indication of specific significant problems with S&U and the FCA review likely just flows from mess elsewhere in the sector....at times the FCA goes full in on an area ...(famous last words). And the sp/valuation of S&U given its financial metrics suggests that negatives are expected.
They've actually grown the value of receivables in Advantage (motor finance) during a period when prices have been falling faster than the rise in nominal used car sales - exact industry figures that coincide with S&U reporting period not available but in Q3 sales up c.2.8% QoQ and average sales price for cars 3yo and older falling c.8.5% over Oct and Nov this year (and given the price weakness seen in Q4 to date its probable there has been weak volume too). Yeah I know the data series don't match up with each other or S&U's reporting period but the picture is one of decline in market.
Against this background receivables up 3.4% for Advantage looks decent. It indicates that despite caution they are taking market share. We don't know what their exact volume v price (loan) metrics are until they report but seems likely that volume is robust. This indicates S&U are a top business in the area.
The more formal FCA review and appointment of a 'Skilled Person' was probably coming given the FCA's general negative disposition to non prime finance and the mess in the area left by Vanquis Banking (LON:VANQ) and others. Some (minor) things will be found wrong with S&U and remedy sought...this is the nature of the exercise. But for S&U this is likely to be an exercise in kowtowing to the all mighty all dysfunctional FCA (...and sadly that has a cost associated with it as highlighted in TU). But the probability they are found to be malevolent lenders of some form is low...and non prime needs lenders as consumers ain't going to magically up their credit scores to prime....so the FCA can't close down lending to non-prime (the bigs banks ain't going to fill the gap)
So overall this is an ongoing industry process that is likely to cement S&U's prime competitive position. Prices of used cars falling and supply improving is a good strategic thing for S&U as it makes cars more affordable to customers. Tough economic times are positive for strong businesses. Live collections were always likely to normalise and had been unsustainably high (and a huge outlier relative to some in the industry).
The (highly) speculative negative I would fear coming from FCA is they have a view that S&U is profit gouging in some way and charge too much as, by implication, their customers are higher credit quality than the official credit scoring (from agencies) says. This is actually the heart of the S&U business - the inefficiency and inadequacy of credit ratings. For the FCA to go there would be very perverse...it would mean they need to acknowledge there is a systemic problem in that credit rating does not fit the consumer well. This last paragraph is likely silly by me...but really the whole non prime credit area is dysfunctional due to the regulatory system and role of credit reference agencies and their poor ability to score risk...and this is why there is a highly profitable and sustainable opportunity for S&U.
PS I like the chair...but I'm not a fan of his political rambles...a bit of a rod for his own back.
PPS speculating on the reason for FCA review...I wonder if it was triggered by live collections sustaining at such a high level? I might be doing 2+2=5 but live collection reduction from 94% to 91% was made in the context of FCA review. Over robustness in collections and lack of forbearance for non prime customer is a favourite beating stick of FCA
Vertu Motors (LON:VTU) Cinch just announced increased holding to just over 7%
As I suspected, they will have been well aware of the recent softness in used car prices and will not be concerned about this, seeing it as a short-term issue which will correct itself shortly. Very happy I did not panic sell here and still think these are worth over 100p.
Does anyone know if there's a typical benchmark/ threshold that tends to be when a bid comes in at?
Or different horses for different course scenario?
If you have any interest in this morning's headlines about the FCA warning on platforms retaining interest then please have a read through the comments section of Dec 7th's SCVR.
In one of my posts I do the calcs to demonstrate that Hargreaves Lansdown (LON:HL.), warning how it is hugely vulnerable in this regard:
In FY 2023, £268.7m of HL's £735m annual revenues was derived from net
interest margin on client accounts (they skimmed 192bps). That's 37% of
revenues.
That's £268.7m of revenues that probably flowed through to the £403m of PBT at verging on zero marginal cost.....
I also discussed AJ Bell's interims in depth - it isn't as easy to measure the impact as they don't break it out - you have to make some assumptions on average rates & balances over the year and then subtract their own funds before backwarding it out from their interest sensitivity analysis.
Worth a read of the whole discussion, with many people chipping in.
I agree with you tbh ... it's not just the platforms though, the private client brokers et al are all at it. Always have been but I think the new issue is that cash "may" have been included in portfolio charges since interest rates fell to zero. This now "could" be double charging which needs addressing. Coming up with a fair interest rate is also not that easy, your cash is pooled and on call. It's a bit of can of worms to be fair.... but certainly none of these accounts have ever been offered on the basis of cash interest rates ....
IMHO the issue of sharing interest earned with clients should be entirely between the client and the broker/platform. Possibly there is an argument for making the commercials clear but I recon the market would do that efficiently enough.
For a normal private investor the tax position stinks too (unless protected by SIPP or ISA). If a client pays £1,000 in commission and receives £500 interest, he might then have to pay an additional £200 of income tax and go through the hassle of reporting it in, and filing, a tax return (many don't otherwise have to file one). Much better to just be charged, say, £600 of commission, which is also more profitable and less admin for the broker.
To be clear, as a private investor, I do not want to earn interest on my cash balance with broker. If it is substantial I will withdraw it and do something else rather than lose value to inflation and if that isn't enough, pay a chunk of it to HMRC!
Quite an interesting article in FT Alphaville (you can register free for access) about Defined Benefit Pensions (DB Pensions).https://www.ft.com/content/00d...
It seems to be saying that because many DB schemes closed to new entrants some time ago many such schemes are close to 'Buy Out' i.e. there are surplus funds, and Company sponsors can walk away from making further Special Contributions i.e. deficit reduction payments.
It alleges £14.5 bn is paid annually by Company for such special contributions, and with the likelihood of increased Buy-outs, there may be more capacity for Companies to reinvest, or make dividend payments etc.
No doubt quite a complicated subject, but might also be a boost for the UK economy also if true.
It is a bit of a two-edged sword really.
DB pension schemes in deficit often had a higher allocation to risk assets in an attempt to close the gap. Once those schemes move to "buy-out" (and its various cousins) the funds get invested in "safer" assets that are designed to be a cashflow match for the scheme's forecast cash outflows to pensioners. These assets will generally be in fixed income ( & other assets aiming for a dependable income lie housing & infrastructure) rather than equities.
So yes, potentially more cashflow availability within companies for capex/divis, but also less cash being invested into listed equities.....
I'm hoping this is good news for DB Pension consolidators like Phoenix group (LON:PHNX) who buy up Closed DB pensions.
I hold Phoenix and loving the reliable dividends, and the stability of their revenue visibility. However, I am mixed about their change in strategy from just buying up closed "Books" (pensions, life insurance, annuities, etc) to now writing new policies. For me, the latter market is already too competitive. But it does give more assurance that their "books" are growing in size, rather than always declining (as policies mature or pay out).
Still, I'm a bit of a suffering shareholder on this one. Bought in Feb22, have seen -15% capital depreciation. Dividends have cancelled that out, but a 0% return on an almost 2 year holding is pitiful - could have gotten 5-6% pa putting it into a fixed savings account.
(I hold in the Boon Fund)
Pennant
Just a quick one on anyone interested in pennant
Buy price normally 31-67
But everyday about 3-5k pounds worth of shares become available at 30.22
think this is a slow selller tricking away
Not going to interest many but might save someone a few quid
Slowly slowly catches the cheeky monkey or something like that
Pennant International (LON:PEN)
Several fund managers have been buying into this over the last year as see high potential to grow it. Check the share register on their website for yourselves.
Been massive operational improvement from 2 years ago but not reflected in share price. Margins have more than doubled and now close to 50%. More high margin software development and old legacy rubbish contract completed earlier this year. Management focusing on quality of work over quantity. A couple of decent contract wins can move the share price of a £10m nano cap significantly. Costs reduced and roughly net debt neutral. I think there will be plenty of activity coming here.
I hold so biased.
The FCA announcement regarding the skimming of interest by the likes of AJ Bell (LON:AJB) and Hargreaves Lansdown (LON:HL.) goes some way to explaining why the latter is the 5th most shorted UK stock with almost 5% short. It was noticing this that led me to sell out recently and has kept me on the sidelines despite my desire to build a position in the investment platforms, which I believe have good medium and long term potential. I know that Graham and Roland are positive on Hargreaves Lansdown (LON:HL.) and I wonder at what point the drop might be overdone and if anyone can provide a framework for understanding the likely impact to their business model.
The way I read the announcement, it sounded like little more than a warning shot across the bows . The statement said: "If they cannot make that case, they need to make changes.
If they don't, we'll intervene." So really, it doesn't sound like there is much appetite for retrospective action. It would be foolish for the platforms not to make changes going forward but presumably if they do, then that should be the end of it. I suppose there might be a concern of a potential class action lawsuit to recoup lost interest for customers. At the moment, it's in the too difficult box for me but I'd be interested to hear about how others are assessing the risks and opportunities here.
In Hargreaves Lansdown (LON:HL.) results they disclosed a revenue margin on cash of 192bp. Their active savings account is only 14bp....their fund accounts are 40bp. Banks pre GFC and ZIRP always earned 150bp .... significant amounts through current accounts obviously. I fail to see why there would be any justification for class action...but who knows. I think it's up to the companies to get on the front foot....make sure there are no double charges...communicate any changes ...and move on.
Was gonna comment on HL (down 7%) and AJB (down 9%) today. What's interesting is that IG group (LON:IGG) is actually up today. I own IGG, but not the first two. HL looks reasonable value to me, and IGG looks cheap. AJB is the most expensive, but presumably is considered to have the greatest growth potential. I stick to my rule of not buying shares until it has been floated for 7 years.
The thing I don't like about AJB is that they charge a percentage of your portfolio. This can work out expensive. So I've never tried it, and have little reason to try it out. They're advertising this thing called Dodl, which costs £25pm. No thanks.
HL is a good platform. It's dealing charges are very reasonable, and doesn't charge a platform fee. So I don't really understand what the fuss is all about. IGG has a quarterly charge, lessened depending on how many deals you do. I don't deal often, so the charge is irksome to me.
The fact that the companies keep the interest is neither here nor there to me, as I don't tend to keep much cash on my platforms anyway. So personally I don't really see what all the fuss is about.
I'm OK with my holding in IGG. Over the last 5 years it had FCF of ~95p, giving it a free cashflow yield of nearly 13%. That seems like good value to me. If and when UK markets pick up again they should do OK.
As usual the FCA are barking up the wrong tree with this cash in platform issue. Never has there been so much competition for cash savings, combined with ease of account opening/switching. Anyone not getting decent interest on their cash deserves what they (don’t) get!
Not quite as easy as you suggest if the spare cash is in an ISA. I have one ISA where interest is paid and one where it is not. I’m not about to move the second one for the sake of some interest.
You could easily just put spare cash in short-dated gilts which effectively acts like cash - that's what I do with any spare cash and more flexible than a savings accounts where you'll normally be locked in for at least 12 months.
With the new ISA season approaching at the end of Q1 2024 is it not possible to withdraw the spare cash from your Stocks & Shares ISA and open a fixed rate cash ISA paying in excess of 5% (there are likely to be some of these even at the end of Q1 2024)? This assumes you don't need access to the cash for the fixed term.
I tend to agree with JonBeddell - also many people will hold cash in their ISA & SIPPs in order to invest in attractive opportunities as they see them arise. This is a personal decision to forgo higher interest rates in order to perhaps invest in one of those multi baggers we are being told about on Stockopedia. I think the technical term for this type of strategy is optionality.
A Counsell
I did indeed open a Cash ISA (4.15%) instead of adding this years’ allowance to my Stock ISA. I assume when the Cash ISA reaches 1 year I can either keep it running or transfer the proceeds to the Stock ISA. (FWIW, I also have an IFISA with a P2P site that is being closed to PIs and will have to decide if I want to xfer that tax wrapper).
In a share account, yes easy to switch cash but with ISAs it takes some weeks, I only just made the deadline. Another ISA, I did miss the deadline. A few years ago it took about 3 months to transfer some cash, from HL, they really did drag it out. HL don't do flexible ISAs either.
I think many people are missing numerous points here....
1. Cash balances in a SIPP are, from a practical perspective, trapped. You can't easily transfer to another provider for better rates. SIPP clients in drawdown may have large cash balances. True for ISAs as well to a lesser degree.
2. Interest skimming could be viewed double charging. The platforms already charge you a custody fee to look after your assets, why are they dipping into your income stream as well?
3. How much of your interest a platform will retain for itself is not clearly declared in advance, nor is there any consistency. In my Dec 7th posts I highlighted how AJ Bell admitted to keeping most of the interest in 2022 but started passing through rate hikes in 2023.
4. It is anti-competitive - it is impossible to compare apples with apples when comparing platform charges if they make most of their money through the back door by skimming client cash balances. The cross-subsidy is opaque.
5. There would be an outcry if platforms helped themselves to a variable proportion of your dividend income each year as & when they pleased- why is interest so different? (yes, there are additional costs to managing cash so I personally think they should be able to retain something provided they are clear about it....)
6. Several major players out there (e.g.. Transact) have gone public in stating that they see interest retention as being contrary to their interpretation of the new Consumer Duty rules. Aviva are also shouting about their zero-retention policy.
7. There is a clear precedent for this - the FCA has already cracked down on fund managers making a turn through stock-lending programs (i.e. taking a fee for lending out client assets), forcing fund managers to hand over any revenue in excess of their expenses.
8. There are times when clients are forced into almost 100% cash - for instance during transfers between platforms that can't transition the securities in-specie, either side of property transactions in SIPPs, or when dealing with the estate of someone who has passed away etc etc.
There is a clear precedent for this - the FCA has already cracked down on fund managers making a turn through stock-lending programs
This kind of things gives the jitters, actually, due to counterparty risk. A few months ago I looked for companies that did certificated trades, but couldn't find any. I'd really prefer to have title to the assets, rather that it being pooled, or worse, leant out. If the FCA want to do something, they should look into that.
I can't even find an option to materialise (dematerialise?) my shares into certificates. If anyone knows of such a thing, let me know.
Tbh despite your concerns this is not a good idea, your shares are segregated electronically and held in crest, which enables you to settle. It is impossible to settle in paper ... so you have to wait for share certificate and signed transfer form to be received by a broker ...
Most nominee accounts are pooled not segregated. Ownership is legally muddled in case of any problems. We need a reform of share registration - see https://www.sharesoc.org/campa...
Take a look at Equinitti Shareview - "Corporate Sponsored Nominee (CSN) service", certainly you can link certificated shareholdings which they act as registrar to a shareview account, Its not as cheap as the usual platforms.
Given the historic treatment of interest and platform charges I don't agree that the FCA are barking up the wrong tree.
Perhaps a little uncharitable to AJ Bell (LON:AJB) . Their service is generally excellent and the online platform is easy to use. As regard charges for a Stocks & shares ISA if you invest in individual shares, ETFs, Investment Trusts, Corporate Bonds and Gilts the shares custody charge is 0.25% capped at a maximum of £3.50 per month. So if you have more than £16800 invested the maximum annual charge is £42 per year which seem s pretty reasonable to me. More of an issue is the charge for funds which can be a bit steep at 0.25% up to £250,000 though falls to 0.10% for £250-500K..Above that for very wealthy investors there is no charge. For their SIPP the custody charge is a bit higher at a maximum of £120 with fund charges at the same level as the ISA.What with the additional fund managers charge for OEICs which fail to outperform passive ETFs the motto would seem to be don't invest in OEICS/Unit Trusts within an ISA or SIPP!
OK, thanks, I'll take another look at it again. I didn't realise it was capped at £3.50pm.
H&L has similar cap on shares/ETFs & ITs but can be expensive on funds.
Thanks for your thoughts on S&U (LON:SUS) this morning Graham. I too was struck by the unusually downbeat tone that feels even more negative than usual. Given that used car volumes are declining (along with prices) and the continued cost of living crisis I suspect that the company will struggle to make headway in the near future. Remains a wonderfully run outfit though so worth watching for the first green shoots.
Many thanks for the feedback and extra thoughts on S&U, Damian. I always feel reassured if you agree with me! And I hope things turn out well at S&U despite the headwinds you mention (speaking as a former shareholder). G
Interesting goings on at software firm Smartspace Software (LON:SMRT) this morning. They have had several bids for the company that have been rebuffed so looks like bidder has gone hostile at 82p cash. Given share price of 33p prior to announcement it nominally looks like a premium offer.
However, Directors clearly think it is worth much more having rebuffed it and holding a decent chunk of shares themselves. ARR is now above £6m p/an and business should be profitable so I have some sympathy for that view with net cash of £2.5m supporting balance sheet. I’m inclined to think 100p might possibly get it though and given bidders inclination to go public they must be expecting to pay more than the 82p offered.
Market clearly thinks current bid will fail. If I can get some at below 60p in coming days might not be a bad risk/reward. Even if bid fails then unlikely to fall back to 33p imo as this bid clearly demonstrates the value of the product they’ve got, so I’d anticipate maybe 45-50p. Situation to watch I think
Smartspace Software (LON:SMRT) I hold - 82p would put me at a loss of about 50%! I think the market completely undervalues this one - a bit like EQLS a few years ago. As far as I can see the management are doing it right, and although growth is slower than we might wish, break even should be reached in just over a year, positive cash flow perhaps a little before that.
For me the takeover, even at 100p, would feel like snatching defeat from the jaws of victory!
Morning MS International (LON:MSI) wow!
One of my accounts is with IG index. Recently I've noticed a lot more stocks have the little telephone label against them showing you need to call to deal. Is this an issue that goes across all platforms and is about liquidity or is it more of an IG issue where I suspect the clients are more trading-oriented and are not as prevalent as two years ago? Is it actually becoming harder to get a position in a small cap in reasonable size electronically?
IG index get worse and worse. Not surprised if it is a way to increase charges.
I think this is a red herring to be honest, sorry to say so. Reason being: I use IG and just noted three stocks displayed as Phone Only. Sanderson Design, SDG, James Lathem LTHM and Loungers LGRS.
I just checked Level 2 screen and all three are/were in auction at that point, so it is more a facet of the underlying market, than an issue attributable to IG.
So probably due to thin liquidity at this time of year, and market makers trying to balance trades as more action is occurring in the markets..
the comment about it being a way to increase charges is unfounded and misguided at best!
Also I've noticed there is the phone symbol in IG when there are market/exchange issues - so might just be temporary phone only dealing while the online dealing is down.
Yes this has been happening quite a bit, in the last week or so, not just at opening time. Mainly on small caps. Lack of liquidity?
Liberum has kicked-off coverage of On Beach group (LON:OTB) at a 'buy', setting a 560p target price for the online travel operator's shares in the process.
https://www.sharecast.com/news...
Ignore the above. The article is from 2019! Apologies
I'd love for On Beach group (LON:OTB) to get back up to 560p :)
Market is definitely getting more competitive - all the airlines investing in them next year for their own-brand holiday packages, seeing them as growth and margin drivers. Is there still a market for a "travel agent" player like OTB?
Could potentially see one of the Online Travel Agents, keen on M&A, make a bid for OTB. There would be plenty of cost synergies, and maybe better hotel supply procurement margins.
There's still a good growth tailwind here, so results should be pleasing at least for the next two halves (including the next high season - summer), so that offers some comfort.
In addition - there's probably a glut of airline capacity next year (all airlines ramped up recruitment, plane ordering). Plus the moderation of oil prices, means much cheaper flights, which might spur more demand for holidays as it gets cheaper YoY (might also hit Average Order Value for OTB though).
Overall, I'm still very positive on the prospects, and keep holding. The price has risen very strongly, closer now to my sell target (which is in the 200-250p range).
(I hold in the Boon Fund)
RefHargreaves Lansdown (LON:HL.) I had not seen the FCA Statement.
Thank you.
Why the big drop in Hargreaves Lansdown (LON:HL.) today 50p over 6% on no news?
There is some news: https://www.stockopedia.com/sh...
Hargreaves Lansdown (LON:HL.)
FCA investigation into whether firms are skimming too much interest income from customer cash balances.
Why are Hargreaves Lansdown (LON:HL.) getting hit when they pay interest, on cash to their clients but IG group (LON:IGG) are not, when they don't pay any interest on cash in the share accounts?
From an article I just read on citywire, their issue is that platforms chg a platform fee on balances incl. cash and then also take a margin on cash. It's the double charging that is under attack....and so I would say / guess that one option is just to wave the platform fee on cash... this of course does mean that revenue becomes more volatile and tied to current interest rate levels. Why, well the margin will fall as/if interest rates fall and is therefore somewhat cyclical. The other option is just to charge the platform fee. This would downgrade earnings - but arguably one reason the stocks have been derated anyway.
On a personal note my Sipp is with AJB. I checked the cash and last I looked I was getting 3%. I actually consider this ok for instant access. Transaction charges etc would consume some of the difference between using a money market fund.... which all seem to be paying somewhat sub standard yields anyway. I wouldn't be thinking of changing my account over this, im happy enough at AJB and like the ease of dealing and the simple platform.
I cannot establish how much cash AJB have on their platform but would guess it's 5-10% .... and so losing the platform fee on this would seem the least painful solution.
I don't hold either Hargreaves Lansdown (LON:HL.) or AJ Bell (LON:AJB) but could argue this is positive as the solution will put the issue to bed...somewhat....but likely still leave them with a revenue stream sensitive to interest rates.
As far as I know IG group (LON:IGG) do not charge a fee to be on the platform but I'm not an account holder.
Hargreaves Lansdown (LON:HL.) don't have a platform fee on the share account unless you hold funds. On ISA share account there is fee capped at £45 per year on shares and cash. I get more interest per month than that.
IG group (LON:IGG) I get nothing. IG group (LON:IGG) should be paying some interest on cash. No platform fee.
If Hargreaves Lansdown (LON:HL.) got rid of the £45 platform ISA, fee then there would not be a problem?
Re IG group (LON:IGG) they charge a custody fee (£100 for the year i think), so it is not a free service to hold stocks. It is a flat fee, but no interest on cash.
I think that only applies if you do 3 trades or less a quarter. So for most clients it won't be charged.
If it is not free, then why can they get away with, paying no interest?
Hargreaves Lansdown (LON:HL.) They have no platform fee or indeed transaction fee with a JISA.
FCA looking to get tougher on investment platforms retaining interest on cash balances.
interest charges on news page https://www.stockopedia.com/sh...
FRP ahead but looks to be a seller for now. Loads of buys going in and price not moving.
SCS (LON:SCS) Just noticed that HL (via message on my account) have enabled me to vote on the takeover of SCS. Thinking of declining the offer as the Divs are good and it's likely worth more. Am I just being ready?
MS International (LON:MSI) H1 FY24 results out this morning . Exceptional but maybe not surprising numbers given the number of contract wins it has had recently, but still good to see it executing on those. Worth a read. H1 rev up 35.7% - PBT up 123% - EPS up 106% - net cash of £50m.
http://newsfile.refinitiv.com/...
Superb MS International (LON:MSI) results. I reckon they will be well ahead of 70p EPS for the full year now.
Net cash is 1/3rd of the market cap. So strip out 250p cash and this is on a PER of just 9.
That’s gotta be too cheap for a defence stock with a product that is clearly in demand from blue chip military. Forward orders sound like they are good too.
I’d expect this to trade more like 15* plus cash and that would be what 1300p or the like? Seems undervalued here.
Thanks David for sharing this with the community.
No problem Yiannos1
Interestingly (well to me at least) the MS International (LON:MSI) development has thrown up a conundrum for me about my investment philosophy. I’ve found myself looking at portfolio performance recently and where I can improve it, and one of the ideas I am leaning towards is the argument of “dead money” - ie not owning the right business at the wrong time, but really only buying businesses with momentum and being prepared to sell as momentum dies down. I quite like Cockney rebels bowl type approach……and adding a 50 day MA to time the trades.
However, the likes of MS International (LON:MSI) where I spotted the opportunity years ago and have held from below 200p as well as my purchase of 4Basebio (LON:4BB) also below 200p are examples of investments I suspect I would never have owned by taking this approach, and yet whilst they have both had periods of under performance they have still compounded very nicely but only with considerable patience.
So I wonder if anyone has solved for this in their own investment style or has another take on stock picker style investment?
Sometimes you just have to talk the Warren Buffet approach: buy quality companies cheaply and park them for the long term. Doesn't mean your entire portfolion needs to be like this, but there's a lot to be said for stocking up on a few stocks of that nature.
MS International
Cracking results
My FD used to have a saying “cash in the bank doesn’t lie”
Unfortunately for me I bought at 240 and sold at 300 a few weeks later thinking I was smart (admittedly it was very hard to build a stake so gave up ) . Probably need to learn sone patience but also was a touch uncomfortable owning a company that makes things that are destined to kill people .
Executive pay was also very high so that was three flags raised .
Anyway what a cracking set of results and 50 million in the bank and a mountain of orders and getting the US orders going they are smashing it so well done to them and to holders .
10% rise is nice but i kind of expected a bit more? maybe i am being too greedy!
MS International (LON:MSI) Great interim results this morning. Bought in here after listening to Paul Scott. Thanks Paul.
My morning smallcap tweet: The Price is Ripe
Smartspace Software (LON:SMRT) MaxCyte (LON:MXCT) Headlam (LON:HEAD) S&U (LON:SUS) PCI- PAL (LON:PCIP) Acuity RM (LON:ACRM) MS International (LON:MSI) Character (LON:CCT), Vianet (LON:VNET), Image Scan Holdings (LON:IGE), Sosandar (LON:SOS)
◄SmartSpace Software (SMRT)► bidder has made several approaches, recently at 82p/sh, a 145% premium, seemingly rebuffed. [SP=34 Cap=10m]
◄MaxCyte (MXCT)► guides FY23 rev $38-40m or more as SPL program-related bests expectations. [SP=392 Cap=521m]
◄Headlam (HEAD)► warns FY-Dec only broadly in line with expectations. First 11 months was like its products, flat. "Gross margin and costs remain well controlled and good progress has been made in the mitigating actions set out in H1." [SP=210 Cap=170m]. I hold.
◄S&U (SUS)► vague update as co makes "steady, if more cautious, progress" in H2. Receivables £446m (end H1 £417m). "Nevertheless, caution is necessary. Those burdens weighing on business are reflected in a lack of consumer confidence, cost-of-living pressures, persistently higher rates of interest, and a new raft of regulation, all of which inevitably affect profitability." [SP=2290 Cap=278m]
◄PCI-PAL (PCIP)► AGM stmt: "New business sales are ahead of the prior year, with several highlight enterprise customer wins now in deployment phase." Rose 7% yesterday in (well informed?) anticipation. [SP=50.65 Cap=33m]. I hold.
◄Acuity RM (ACRM)► wins its largest contract worth £561k for the use of Acuity's software platform, STREAM over 5 yrs. [SP=4.6 Cap=6m]
◄MS International (MSI)► H1-Oct rev up 36%, pretax up 125%. Outlook positive. [SP=865 Cap=141m]. I hold.
◄Character Group (CCT)► FY-Aug. Outlook - "Christmas demand has been later than usual and is clearly very sensitive to discounting." [SP=281.6 Cap=55m]
In line: VNET, IGE, SOS
"First 11 months was like its products, flat". Simply love it