Small Cap Value Report (Tue 12 Jan 2021) - Dr Martens, APP, ACRL, SAG

Good morning, it's Paul here with the SCVR for Tuesday.
Thank you to everyone involved in Mello Monday investor webinar last night. The numbers are steadily growing, not far off 500 investors attended last night, a new record. The highlights for me were veteran fund manager from Schroders, Andy Brough, who is always a terrific speaker, full of insights and often very amusing anecdotes! Also, Stephen Clapham continues to impress, with interesting perspectives. I must read his new book, The Smart Money Method. Has anyone here read it? Views please!
Our own Jack gave a good review of Foxtons (LON:FOXT) (I hold) which is an interesting share. I think a lot of people are coming round to the view that the work from home (WFH) trend could gradually reverse. Anecdotally, I'm hearing that the novelty, even joy, of being at home with their children all the time, has worn rather thin with many city workers, who can't wait to get back into the office & bars/restaurants, once normality returns later this year (April/May roughly, is looking likely, given good progress with vaccine roll out).
I almost forgot, of course the boss's review of 2021 Share competition picks was interesting too. A lot of subscribers here clearly share my conviction for Boohoo (LON:BOO) , Saga (LON:SAGA) , and Volex (LON:VLX) - three of my five largest personal holdings, which are at the top of the list of shares picked by subscribers in this year's competition. Let's hope we're right, otherwise I'll have to keep a low profile at investor conferences later in the year lol! However, if those shares do well, I'll be able to excitedly hold court in the bar again, without buying a single pint all day, and repeat my previous performance of accidentally spraying fragments of salt & vinegar crisps over my adoring fans (sorry about that again Peter!).
Timings - an all-day job today, to catch up with a backlog from yesterday. Today's report is now finished.
Agenda -
Dr Martens - intention to float, for this well-known brand of boots.
Appreciate (LON:APP) - Trading update
Accrol Group (LON:ACRL) - Half year results
Science (LON:SAG) - Trading, business, and board update from yesterday
.
Dr Martens
This iconic boots brand is going to float on the London main market. There were 2 announcements yesterday, a summary document, which I've reviewed, and a full 200-pager admission document style thing, which looked too daunting for me to get stuck into late yesterday afternoon, after I got back from my constitutional along Bournemouth beach - running the gauntlet of over-zealous rozzers, given that I took a thermos of coffee with me, dangerously close to constituting a solo picnic. Although as an aside, I note in today's paper that the Derbyshire Two have been pardoned by the police, for taking a stroll in the woods, 5 miles from home.
Here are my notes from an initial review, which mainly serves the purpose of flagging up areas to scrutinise in the main admission document. Although press reports of a £3bn price tag, look so high, I doubt it's worth pursuing this idea if the valuation is anything close to that.
Intention to Float - my notes
Main market
Revenues £672m FY 03/2020
Direct to consumer strategy - although this terminology confuses me, as it seems to include everything, i.e. retail, online, and wholesale. Confused!
Bought by private equity Permira, in 2014 - oh dear, PE exits via floats can often be horribly over-geared, need to check that.
Quotes EBITDA of £184.5m (high margins), but NB this is boosted by IFRS 16. The pre-IFRS 16 EBITDA is lower, at £164.4m. The press don't seem to have spotted this!
Very strong growth over last 3 years - can it continue, or is this an opportunist float after a good patch of trading?
Listing is all secondary - i.e. selling shareholders, not raising any fresh cash for the business itself, says it doesn't need it due to being highly cash generative, which it is, so maybe this is OK.
7 big name advisers! Fees? Likely to be huge.
Gross margin of 60% is very good. Up from 53.3% 2018 to 2020. Peaked maybe?
eCommerce is 24% of sales mix. Good, but not amazing.
Heavy finance expense on P&L - suggests high debt, as I would expect with a PE funded business. How much debt is being repaid as part of the listing process?
Balance sheet review threw up one large/unusual item - redeemable preference shares of £330.1m - a form of debt. This is probably what gives rise to the heavy finance charge on P&L. Key issue - what happens to this apparently expensive debt? Is it being repaid as part of the float? It needs to be.
Balance sheet - NAV: £100.4m, less intangibles of £259.8m, gives NTAV negative at £(159.4)m. Poor, but given how cash generative the business is, probably acceptable, providing trading remains strong.
Pension funds - query - any defined benefit schemes? I couldn't see any, but pension payments are mentioned somewhere. Need to check this.
My opinion - it all comes down to valuation. If it's £1bn, then I might be interested. If it's anywhere near £3bn, then forget it! Also, the post-float balance sheet needs a look (this should be somewhere in the full admission document), in particular what happens with the redeemable preference shares, which seem to be expensive debt.
Overall, a PE exit is likely to be over-priced, and overly burdened with debt, as that's what often happens. Hence needs a sceptical look before taking the plunge.
.
Covid vaccines thoughts
Matthew Lynn makes the point in today's Telegraph, that the only figure which matters to investors at the moment, is the vaccination rate. Social media seems to be full of armchair critics, lambasting the UK Govt for incompetence over everything they do. Yet such critics are strangely silent about the clear success of the UK authorities in ordering massive quantities of lots of different vaccines (seemingly obvious, but not done by our European cousins), and organising a fairly rapid roll out. Well done to everyone involved, as always especially to the front line medical people actually doing the hard work.
Looking back to last year, I was complacent about the risk of a more serious second wave, as things looked so positive in the summer of 2020, when it looked as if the virus had all but fizzled out. Sadly not the case, as we now know. Hence this is all a learning curve. I'm lucky to have daily notes here in these SCVRs, to refer back to once our memories have faded, which track the changing facts & mood throughout this crisis. Maybe we should do edited excerpts and put it into a booklet?
On the upside, last year I think a lot of us thought the idea of a vaccine by end 2020 seemed pie in the sky. Many experts seemed to be saying that the second half of 2021 was more likely. Hence it's been a wonder of modern scientists, that they've come up with vaccines so quickly, I'm sure everyone is immensely grateful, I know I am. Let's hope it inspires more people to focus their careers on life-saving science & care.
We clearly need to greatly increase the capacity of the NHS to deal with unexpected crises. I read a very interesting (if somewhat flawed) book recently called: Why the Germans Do It Better: Notes from a Grown-Up Country By: John Kampfner. It's a good, wide-ranging, overview of post-war modern Germany. Although spoiled somewhat by his fawning adulation for Germany, and scorn for the UK. The irony of that is lost on him, given that it's the UK's flawed system which helped liberate Germany and allowed it to become the success it is today.
Anyway, why did I mention that, other than as a book recommendation, it gets a 4.5 out of 5.0 from me, as it's a good read? Oh yes, in the section which looks at health, he points out that the German health system is better funded than ours, and has far greater emergency capacity. Whereas, as we're seeing at the moment, the UK system seems to be run & funded on the basis of just about getting by. We have regular winter crises every year, so clearly there's no spare capacity to cope with covid on top of everything else. Health spending is clearly going to have to go up a lot in future. Shutting down the economy, at a cost of hundreds of billions, because we've scrimped on maybe a few tens of billions of NHS funding, doesn't seem very clever now, does it?
As far as investors go, my view is that we need to keep focused on the vaccine numbers, above the awful & tragic short term news about high deaths & new cases figures. With the most vulnerable planned to be vaccinated fairly soon, then we should start to see a rapid decline in deaths in Feb-March. Despite the TV media always highlighting atypical cases (younger, healthy-looking people), the reality is that this virus overwhelmingly kills the old, the already sick, and obese. Hence once they are vaccinated in the next say 2 months, then that should allow restrictions to be eased, so that everything else can get back to normal. As long as companies have enough liquidity to survive the next 2-3 months, then their financial performance should rebound later in 2021, in my view.
Extended restrictions don't seem likely to me (e.g, into the summer/autumn), because once the death rate is very low, the public demand to return to normal is likely to be too strong for Governments to resist.
An article in the Guardian this week (you see, I don't just read the Telegraph!) said that far more people in the UK have already had covid, and hence probably have some level of immunity, than previously thought. It's talking about c.20%. That rings true to me. When my London household caught it, in Mar/Apr 2020, out of 4 of us who were sick with covid, 1 died (74 years old, lots of underlying health problems), and the 3 of us who survived are not on any statistics as having had it at all, because we didn't get tested or seek medical assistance. We just recuperated at home. I'm sure that is true for many other households. Plus of course all the people who have probably had covid, but with little to nothing in the way of symptoms.
Put all this together - i.e. rapid vaccine roll out for the vulnerable, and probably higher herd immunity from undiagnosed cases, and we have a situation that could start to improve in a few weeks. Leading to easing of restrictions possibly in March? Then further easing in April, and maybe back to close to normal in May? Obviously that's just my estimate and may be wrong, based on trawling through lots of news & views from many sources.
At the time of peak crisis, some people tend to be too pessimistic, which may create opportunities now, if some shares sell off for no particular reason. Although I do agree with Andy Brough that many UK shares have recovered too much in the recent market bounce (since vaccine news came out), and now price-in maybe too much recovery before it's even started.
On the downside, the nightmare "sell everything" (or hedge everything) scenario would be if a virus mutation occurs which is very much more deadly than current strains, and is impervious to vaccines. Let's hope that doesn't happen.
Obviously the above comes with a disclaimer that I'm not purporting to be any kind of medical expert. These are just my personal opinions, based on sucking in & digesting lots of views from as many credible sources as I can find, and applying a bit of common sense also, hopefully. Plus a willingness to change our minds, if the facts change, or if we realise we're wrong. Very much the same skills we use for stock picking really.
Apologies for any repetition in the above. I just find it useful sometimes to collect my thoughts by writing up a section on covid developments.
.
Appreciate (LON:APP)
32p (down 1.5% at 08:55) - mkt cap £60m
Appreciate Group plc (the 'Group'), the UK's leading multi-retailer redemption product provider to corporate and consumer markets, today provides an update on its important Q3 trading period for the three months ended 31 December 2020 in the current financial year. [Paul: FY 03/2021]
Strong performance through Q3 peak trading period as momentum continues in digital
Background - Here are my notes from Aug 2020, where I reviewed APP’s results for FY 03/2020.
I didn’t cover it here, but another update on 29 Sept 2020 showed monthly billings very poor in April & May 2020, gradually improving in the following months, then turning positive in Sept 2020. Clearly it’s been impacted hard by covid/lockdowns, but was recovering.
Interim results for 6 months to 30 Sept 2020 look poor, an adjusted loss before tax of £4.6m, but the narrative talks it up, saying this result is ahead of the original mid-range scenario for covid.
Today’s update - this looks quite good, to summarise;
U/l Q3 billings £96.3m, up 13.1% vs LY - continuing the move into positive growth started in Sept 2020
Dec 2020 - best month ever - good, but possibly due to pent-up demand from poor sales earlier in the year?
Digital sales quadrupled to £22.5m - impressive. This shift to digital is the main bull argument for this share, and is a good investing theme in my view - businesses that are successfully shifting online can be very good investments (e.g. Best Of The Best (LON:BOTB) (I hold), which shifted from physical airports, to online, and multibagged as a result).
Outlook - mixed I would say;
The Group is expected to deliver a full year performance for the year ending 31 March 2021 at least in line with the mid-range scenario as set out in its 2020 annual report and accounts, although the latest lockdown measures may delay some revenue and profit until customers have more options to redeem their products.
Directorspeak -
"I'm delighted to report that the Group has delivered a strong performance during its important Q3 peak trading period. As a seasonal business, the Group's performance has reflected the swing to profitability that we typically see in the second half of the financial year and the acceleration of our strategy to strengthen our digital capability has ensured a Q3 performance well ahead of last year.
"We saw our busiest ever month in December. Our Corporate performance has been enhanced by companies seeking ways to reward their hard-working employees as an alternative to traditional Christmas parties.
"The accelerated implementation of our strategy over the last year has helped us deliver an improved performance through this key period, and has strengthened the Group's proposition for consumers and corporates, leaving it well positioned for sustainable growth beyond the current financial year."
My opinion - I’d be interested to know how much business is being achieved through covid? E.g. I know the ONS is giving out Love2shop cards from APP as rewards for people taking part in surveys. I got one for £10, but couldn't be bothered to redeem it, as it was taking up too much time in a complicated process to register, etc. together with worries about what they're going to do with my personal details?
Which makes me wonder, how much profit comes from low value vouchers that are paid for, but never redeemed? A fair bit, I reckon. Also apparently quite large numbers of people are given vouchers (not sure if they’re from APP or not) for taking regular covid tests, and they’re quite decent amounts too, a family member tells me, who is on that scheme. That business is likely to dry up later this year.
APP is on my watch list. It looks potentially interesting, if the digital side of the business can continue growing fast. I haven’t really done enough research on the company to form a view either way, so am currently neutral on this one. Lord Lee speaks highly of APP, and his share ideas are always worth looking into, as he’s been highly successful in the long term.
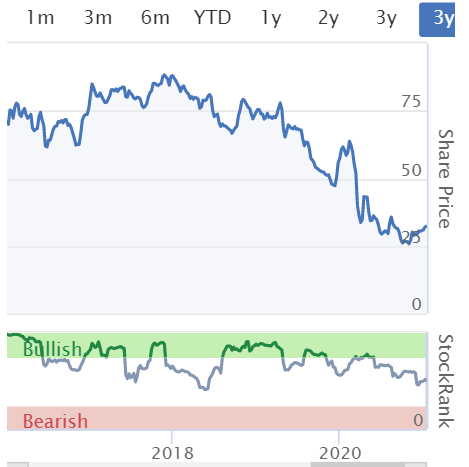
As you can see below, things were going badly before covid struck, and there's been little share price recovery since. So the market remains sceptical for now. That said, if this turnaround is going to work, and digital sales blossom, then the upside could be considerable. As a reader points out below, there doesn't seem to have been any share dilution, with the share count static at about 186m for the last 5 years. That means the share price could recover back up to previous highs, if the business trades well, possibly.
.
.
Retailers, brands, insolvencies, landlords
Jaeger
There’s lots of interesting news at the moment.
Marks And Spencer (LON:MKS) has bought the Jaeger brand from the administrators, which seems a very good fit to me. It’s a pity we’re not told how much they paid for the brand. Although the Guardian says;
The price it paid for the brand is understood to be in the low millions of pounds.
If true, then they’ve got a bargain I think, and obviously BOO didn’t want it!
A brand like that could have decent licensing potential, on top of rejuvenating its products. Whether MKS is good enough to turn it around, is a big question, given MKS’s hopeless multi-year performance in clothing.
MKS is not taking on the 63 Jaeger stores, very sensibly. This is the way of the world now, we’re likely to see lots more well-known brands go bust and then sold to the highest bidder (minus some or all of their physical stores) in the next few months, I think.
Jaeger was part of Philip Day’s group, Edinburgh Woollen Mill. It has been in administration, but a deal seems to be imminent to save parts of EWM. Drapers Record saying that a consortium is bidding, and “will pay for the business in instalments over the next few years” doesn’t sound like a very good proposition. To have accepted that deal, the administrator must have had few, if any other viable options.
It’s particularly interesting that MKS seems to have cottoned on to the multi-brand idea, which Next (LON:NXT) and Boohoo (LON:BOO) (I hold) have pursued so successfully. Maybe there could be more competition for buying failed retail brands in future? How Mike Ashley’s scatter-gun approach pans out, to buying brands & keeping some physical stores open, via Frasers (LON:FRAS) , who knows? It strikes me as the riskiest strategy out of the ones mentioned above.
Moral issue - I can’t help pondering the situation where billionaire owners of retail chains like Arcadia & others, milked the businesses for fancy lifestyles in the good times, but can just walk away from the wreckage when it fails, stuffing landlords & suppliers with the losses. Often they even get priority on the proceeds, as they secured their loans against assets. It doesn’t seem right, but I can’t think of any workable solution.
Ultimately, suppliers have to remember that all sales on credit are a gift until the invoice has been paid.
Landlords - I had a very lucky escape with Hammerson (LON:HMSO) last year, making a decent profit on a short squeeze. Although looking back, my fundamental analysis on the company was completely wrong. I didn’t factor in a second wave of covid, nor how dire conditions would become for landlords, with so many tenants unable, or unwilling, to pay rents, and demanding decreases or even rent-free periods.
I think it's important to beat yourself up, and learn the lessons from mistakes which made a profit, as well as mistakes that made a loss. If the analysis was wrong, but a profit was made purely through lucky timing, then that could lead to future losses, if the same flawed process is used again.
I started looking at Land Securities (LON:LAND) this morning, which put out a detailed announcement re rent collections. It seems to be cushioned by having a good mix of properties, with offices being the largest, and rent collections there being quite good.
Overall, I don’t have any confidence in my ability to pick winners or losers in this sector, so will steer well away from it. Large discounts to NAV for property companies are more likely to be a warning (of over-valued, distressed assets), than an opportunity, maybe.
Insolvency practitioners - thinking about all of the above, I've decided that it's time to take small opening positions in both Begbies Traynor (LON:BEG) and Frp Advisory (LON:FRP) . I couldn't decide between them, so have picked up a little bit of each. It seems to me that we could be coming into the crunch period where, even with Govt support measures, many retail/hospitality/leisure/ travel companies, must be reaching the end of the road. Many need to restructure, so it's not necessarily a negative thing, to call in insolvency practitioners to formally sort out an untenable situation.
Why did I only take small opening positions in BEG & FRP, which would barely move the dial for my portfolio, even if they went up say 50%? Well, I always think a profit is a profit. I scrimp over the price of basic food items when food shopping, and want the cheapest car insurance (via the meerkats), so why on earth would I then consider thousands of pounds in my shares portfolio to be insignificant, just because it's small relative to total assets? That's defective thinking, so in my view, every penny counts in shares portfolios too, when it's your own money.
Andy Brough made another great point last night about small position sizes. He's managing vast portfolios, over £3bn, so asks himself why buy or hold a small position in some tiny small cap, that wouldn't move the dial even if it 5-bagged? The answer is that it's a toe hold, and it means you read the RNSs about that company, hence are more likely to spot something significant happening. He gave the example of Xaar (LON:XAR) where he only spotted the turnaround starting because he already had a small holding, and was able to greatly increase that holding at the right time, because he already held some. Would he have spotted the turnaround if it hadn't been en existing holding? Probably not. Hence small position sizes are a nice low-risk way to closely monitor something potentially interesting. It's then easy to either ditch, or add to the position size as your knowledge about the company grows.
.
I'm just rambling on because the companies reporting today look so boring. Let's have a whizz through some of them, think I'll do shorter sections today.
Accrol Group (LON:ACRL)
68.5p (down c.6% at 13:53) - mkt cap £214m
Accrol (AIM: ACRL), the UK's leading independent tissue converter, announces its results for the six months ended 31 October 2020 ("H1 21" or the "Period").
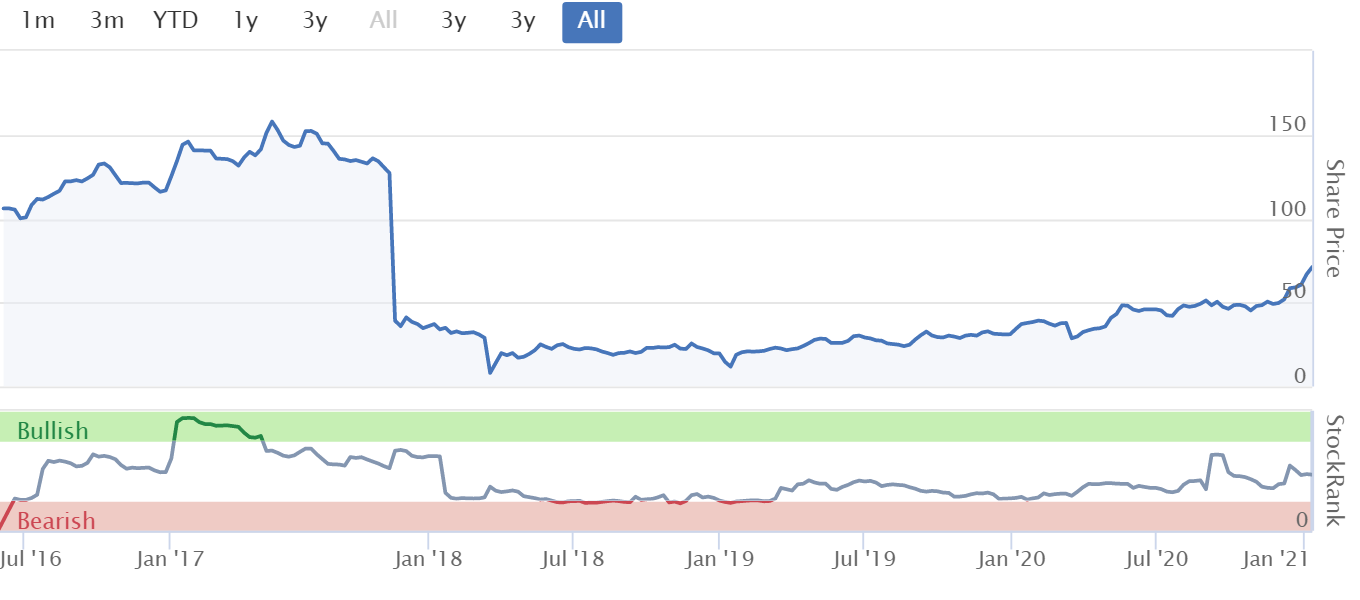
The share price here has more than tripled since 2014. The danger is, that when looking at the chart, you're not comparing apples with apples - i.e. 68p now is equivalent in market cap to 228p per share when it floated in 2016.
This looks a good update -
With margins continuing to improve, LTC contributing positively and the business continuing to deliver strong organic growth, the Board is confident that the Group is fully on track to deliver a strong H2 performance and results for FY21 will be at least in line with market expectations.
(no footnote provided to tell us what market expectations are)
Dividends - restoring a (tiny) final divi of "no less than 0.5p"
Net debt - strangely, it does give us market expectations here;
Net debt (pre IFRS 16) 30 April 2021 is expected to be below consensus market forecasts (currently £12.2m), even after the intended dividend payment.
Interim results - don't look very good to me.
Revenues down 4% to £62.3m
Loss before tax of £(0.5)m
Net debt (pre IFRS 16) of £18.1m
Underlying results are given, but only down to EBITDA, of £5.4m. We can't just ignore depreciation of £1.94m. EBITDA is not a meaningful number at capital intensive companies like this. Note that capex was £5.3m in H1, more than double the depreciation charge.
Gross margin usefully improved, but still extremely low, at 23.8% (LY H1: 19.7%) - so make no mistake, this is a product sold purely on low price, an unattractive business model in my view.
Integration of recent acquisition, LTC progressing "incredibly well"
Balance sheet - NAV: £46.0m, less intangibles of £26.8m, gives NTAV: £19.2m. This looks adequate, although I'd be more comfortable with the bank debt once ACRL has moved into proper profitability.
My opinion - I'm really struggling to connect these numbers with a £214m market cap. At the moment, it looks significantly over-priced to me. Investors must therefore believe in not only the turnaround delivering better results, but also the growth strategy explained in the commentary.
I find this business model unattractive, as it's capital-intensive, supplying low margin, low value-added products to ruthless, price-conscious customers (supermarkets).
The share price seems to hinge on big increases in EPS. Broker forecast is for 2.8p this year (FY 04/2021), then 4.7p and 5.7p in subsequent years. If you're confident that earnings are going to double in 2 years, then this share stacks up.
It's definitely not for me, but good luck to holders.
.
.
Science (LON:SAG)
340p - £138m market cap
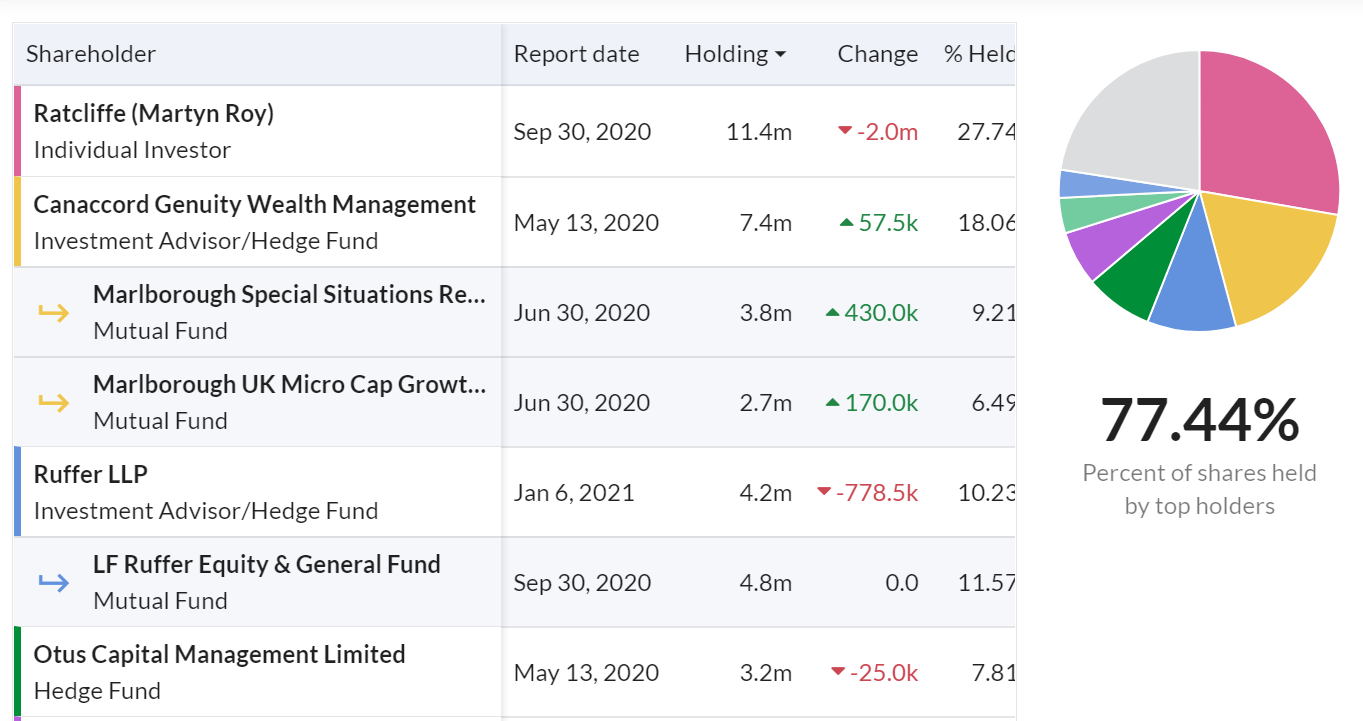
The quoted market spread (bid-offer) looks very wide here, so it must be tightly held. Yes, here we are;
.
Even if a share does have a very wide quoted spread, we can usually deal within that spread, so it shouldn't necessarily put us off. This is due to the ridiculous, antiquated system we have in the London market, where real prices on illiquid shares are hidden from view. It's ridiculous, but there we go.
Trading, Business and Board Update
Science Group provides a trading update for the 12 months to 31 December 2020.
This update was issued yesterday.
It looks rather good;
Group revenue for the year is now anticipated to be in the order of £73 million (2019: £57.2 million). While the Board took the opportunity during the second half of the year to increase investment in infrastructure and personnel, early indications are that, subject to audit, the Group's adjusted operating profit for the year ended 31 December 2020 will exceed the previously upgraded expectations of £10 million (2019: £6.7 million).
Furlough of £0.1m was insignificant, and repaid to the Govt in H2. Very good.
Net funds of £10.6m looks healthy - gives scope to "explore further strategic opportunities, should they arise". It points out a strong track record;
Over the past decade, Science Group's self-funded model has enabled the Group to grow revenue more than 3-fold and adjusted operating profit 4-fold, without shareholder dilution.
Finance Director Rebecca Archer is moving on to a new role. A CFO Designate, Sameet Vohra has been appointed, previously interim FD at Ted Baker (LON:TED) during its restructuring, so he sounds a credible replacement. Changing CFOs can be a sign of trouble, but this one sounds OK, mainly because Rebecca is staying on to complete the 2020 audit, and formal handover is in April 2021. That suggests to me there's probably nothing to worry about.
Frontier - acquired in 2019, restructured, and now "strongly profitable". Orders in 2021 are "very healthy" and may be supply constrained - a good quality problem to have in a way, when demand exceeds supply for any reason, because supply problems can be fixed in time. Mgt are considering all options for Frontier - retain it, sell it, or make it bigger with acquisitions. Open minded, and advisers appointed. Sounds potentially interesting.
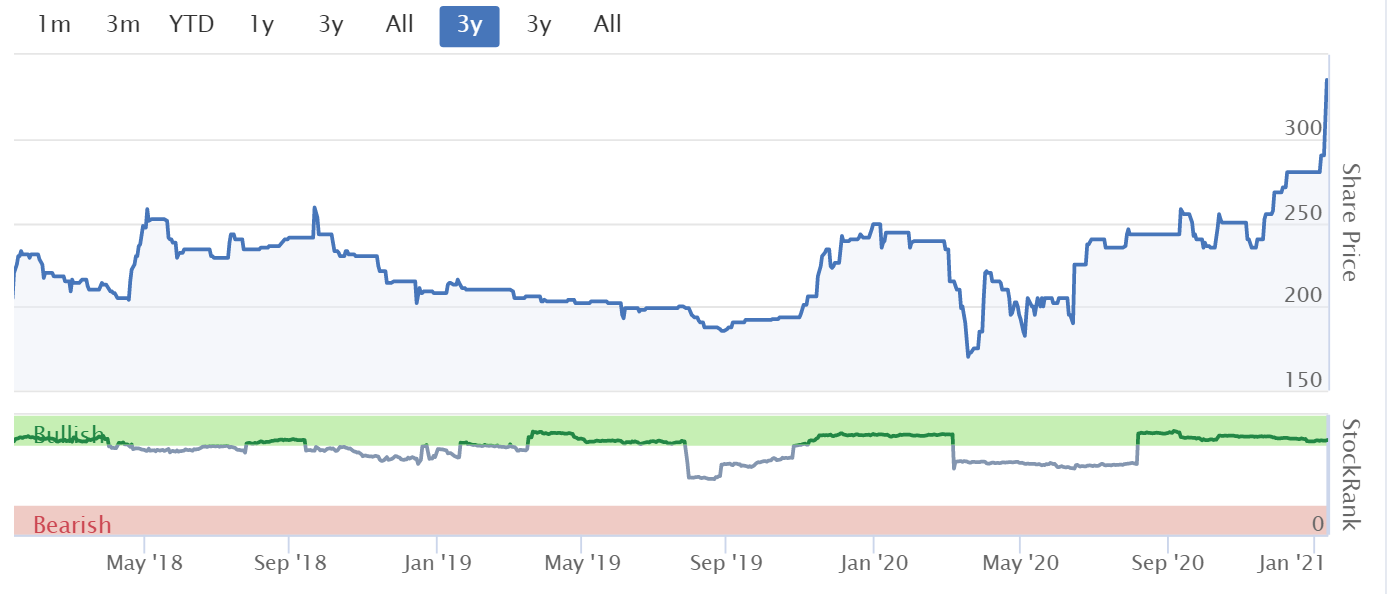
My opinion - many thanks to Liberum, for making an update note available on Research Tree - that's so helpful. It's raised 2020 forecast EPS by 5%, to 18.1p, that's a PER of 18.8 - maybe priced about right? Subsequent years' forecasts are basically saying earnings will be flat for the next 2 years. If that's the case, then it's difficult to justify a higher PE rating.
Therefore this looks a straightforward situation. If you think the company can grow earnings in future, then it's worth buying. If you don't, then it's probably fairly priced at the current level. Management sound shrewd, so could be worth backing, for future out-performance maybe?
.
.
That's all for today, see you in the morning.
Best wishes, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

192 comments
Dear Paul,
Apologies, I'm not sure how to direct this question for your attention! I too hold Saga and I hope they make it through the other side of this.
I've been trying to work out why the Stockopedia rating is 'Value Trap' I've read a bit about what a value trap is but I'm afraid I'm not any wiser about the specifics in Saga's case about what 'the system' is seeing to generate this.
Thanks for your easy to read, enjoyable writing style.
Best wishes and keep safe,
John
Saga (LON:SAGA), value trap is to do with the Stockopedia ratings for Quality, Value and Momentum. Quality is only 24, Momentum is only 36 and Value is 61. So high value, low quality and momentum.
The last results Saga was making a large loss.
There are some articles on Stockopedia about what the terms mean, if you do a search you should find them.
for anyone interested, the FT has a feature on Permira IPOing of Dr Martens todayhttps://www.ft.com/content/aeb...
and this much more interesting comment piece from John Gapper! https://www.ft.com/content/fa9...
Appreciate had £33.5m in cash at 31st December and whilst the business used to have wild swings in cash when it sold Christmas hampers the cash levels should be more steady now. The cash associated with vouchers is kept in a separate trust account so the £33.5m really does belong to shareholders. With reference to redeeming vouchers they only recognise the turnover from this on multi-retailer vouchers when the vouchers are used.
I don't want to get sucked into a covid battle. I remain of the view that we have made an error of not focusing on coping and instead have ended up flitting between panic/eradication measures and all okay....I think we should have long haul tried to manage. This would not magically have made the bug go but it would have helped us prepare and stay focused on that (medically, corporately, educationally, etc). TBH I think we are lucky and bailed out of our error by vaccine...which may have taken much longer.
Anyhow...I haven't kept up to date on conversations here or elsewhere partly as do not wish to be labelled some terrible immoral 'denier' constantly...but I am increasingly curious about one thing and maybe its been discussed...
I can accept that much of Asia coped and managed better. But I suspect this doesn't explain enough. Increasingly I think they may have some better developed body capability to cope with the bug. Has anyone seen good stuff on this beyond conjecture?
I think I've had the bug twice. Neither time too bad though first worse than second just before Christmas. I'm near 100% certain second time I had it as all other family members got tested and were positive (I thought they were over reacting and didn't go with them!)...I felt tiny bit under the weather, enough to stop me outdoor swimming, but not bad.
The doc asked me to have an antibody test a few months after the first time to check it out. I've had a serious injury before that caused dangerous damage to lungs at time and as I'd had some lung like pain he wanted me tested. It came back negative. So I can't prove I had it (Feb time after exposure to both northern Italy couple of times and large groups of Chinese holiday makers at shared buffets etc) but I felt it probable that I did particularly as some Italian based friends I had spent a lot of time with close had classic symptoms including the taste/smell thing. I had the chest pain and breathing thing a bit that felt different from other times with colds or flus (and I don't normally get a breathless easy).
Any info?
Paul,
I think you probably didn't!
There seems to be along queue of people who think they had it last winter. Some probably did, some probably didn't. There are more involved tests than antibodies that look at T-Cell response etc but I think these are being used for research rather than directly to the public.
Other than curiosity, do you have any other reason to want to know?
The thing I'm most curious about is any more recent work re Asians and how they cope and whether they have a higher capacity to cope (perhaps due to proximate prior exposure). As you guys argue a lot about it and have become expert I thought I'd ask ;) I've stopped looking at all this as I don't feel I can prove out anything useful for myself nor change the course of events.
I can't prove I had it just before Christmas either but was highly exposed to 3 others with it (no attempt at in house separation). Nothing but very mildly and briefly under the weather but other 3 felt it a bit more (not too bad). I will see if I can get antibody test again.
(Over 15 years until recently I was very frequently travelling around Asia)
I'm certainly not an expert - probably not on anything likely to be discussed around these parts and definitively not on Virology.
However on the subject of Asia - I did read a "study" early on suggesting that Japanese subjects appeared to show a "T cell response" to the virus much earlier than expected and in advance of the antibody response.
The suggestion was that they had some degree of "immunity" due to earlier exposure to similar viruses in past years.
I haven't seen any more on this recently , so it might have been just another Covid tale, but it did have a ring of credibility about it - In my numpty opinion.
Yup. Saw that sort of stuff. Then read stuff saying it’s mad...vice versa and etc.
Japan do seem to have performed very well without doing too much..yes they are super hygienic (regular visitor...always worried as dirty foreigner I’d trip border health screening!) but they are dense and old. Literary tightly packed
Two important reasons many Asian countries coped better. 1). They mostly all wore face masks when told to do so,especially in Japan,South Korea,Singapore and Taiwan. 2) Obesity is nowhere near the major problem it is in most western countries .
Of course they also had experience of coping with the earlier virus a few years ago which did not spread to western countries .
SARS related T cell response linked to Covid:
https://www.nature.com/article...
Thanks. I had read this sort of thing previously too
Thanks Thornabian - I too had missed that particular article, but had seen other speculation and theories on the subject.
For those that don't want to read the detail, my precis would be that there are reasons to be cheerful, if not absolute proof, about the longevity of the immune response.
Everyone seems to be too busy either getting depressed or maintaining that Covid-19 is a hoax that balanced and informative content gets squeezed out.
Actually that reasons to be cheerful link, royally stinks - this one is much better for anyone uninitiated.
We'd better all hope that you haven't had it twice as it would knock a pretty big hole in assumptions that the vaccine is coming to the rescue..
We'd better all hope that you haven't had it twice as it would knock a pretty big hole in assumptions that the vaccine is coming to the rescue..
In this regard it’s more the overall percentages that matter rather what has happened to one individual - I think there have already been numerous proved cases where people have caught covid twice - so there shouldn’t be any surprise or concern if mojomogoz Turns out to have had it twice. As long as the maths confirms the odds of this happening are very low we carry carry on and not worry too much about these statistical anomalies.
As Gromley says I probably didn’t - erroneous self diagnosis...however if I had it twice it was pretty mild both times...only temporarily acute first time when I thought was over it and decided to chase whatever bug out with a bit of circuit training...then I had about 2 hrs of thinking I might need hospital treatment! A sort of acute short term spiral down (and a bit of suppressed panic)...so slept instead was a bit better but ‘post viral’ like for few days.
However, seems like second time I must have had it.
Anyway, I do wonder if people have resistance other than thro antibody response and that’s partly where the Asian question comes from. Their resistance seems just too good relative to us even allowing for better procedures. It’s so virulent in Europe/US/latam even prior to new variant that it seems Asia should have had more bite than they have
At the beginning of this I looked at studies and scientific papers. I’ve given up on that. Lots of dissonance when seeking to understand the whole imo
According to PHE the re-infection rate is currently around 1 - 2 re-infections per 1000 Covid cases.
We'd better all hope that you haven't had it twice as it would knock a pretty big hole in assumptions that the vaccine is coming to the rescue..
The consensus medical expectation is that immunity will be short lived (i.e. a year or less) in common with other coronaviruses. We'll probably need annual booster jabs.
Obviously there's lots of chat around about antibodies and T-cells, mainly by people who don't know anything about them but the truth will be revealed by the data. There are studies going on at the moment to try and figure out if it recurs.
Probably the most likely to get the answers is a large study going on in the Amazon city of Manaus where CV-19 has run rife. Over 75% of the population have had it and it's being looked at as a field test of what happens when CV-19 isn't mitigated at all. If you scale those numbers up against the age specific case mortality rates in the UK / US you'd get some pretty grim looking numbers:
https://www.npr.org/sections/g...
Unsurprisingly it's also the most likely origin of the Brazilian mutation that's starting to worry people.
The other underlying concern is that Manaus is over the expected herd immunity level (about 66%) of infection but cases are stil increasing. They'll be looking for recurrances of the infection going forward - with such a high percentage of people infected any significant increase in disease rates would be an early warning of a problem.
Finally, there are questions about the data collection method in Manaus - it's certainly not perfect, but I don't think anyone disagrees that the prevelance of CV-19 in the city has been extremely high.
timarr
I can accept that much of Asia coped and managed better. But I suspect this doesn't explain enough. Increasingly I think they may have some better developed body capability to cope with the bug. Has anyone seen good stuff on this beyond conjecture?
I think the biggest factor was probably the far eastern experience of SARS in 2002-3. The result was they were much better prepared than the rest of the world. In contrast the UK ran an exercise in dealing with a pandemic in 2016, which exposed several weaknesses, and did little or nothing about it.
Snazzy new vaccination graph format at: https://ourworldindata.org/cov...
One of the problems with vaccination data has been that it is not daily and so making comparisions between countries more difficult. The new format allows us to eyeball the trend on a per 100 people. See below:
M.
I thought this from Bango (LON:BGO) this evening a little odd and it got my dissonance filters twitching:
https://www.investegate.co.uk/...
Bango, advisors and Sir Eric would seem to know the rules well and not the sort of procedural mistake to make. Then Exec Chair Anderson and CMO Malhotra have a belated revelation too...that they should know to do before given their experience. Makes me feel suspicious that they just didn't want to say anything => probity?
I've looked at Bango in the past and I feel that the company is perhaps problematic. I don't have a smoking gun on that but what caught my eye:
It makes me think the earnings and asset values/potentials at BGO are poor quality. I think Boku Inc (LON:BOKU) is much higher quality (but overvalued and perhaps with some issues round malinvestment and scalability of platform that makes valuation somewhat heroic....rather than BGO's nosebleed).
I feel that BGO will be active with more acquisitions going forward to cover their tracks and keep investors on board.
I don't feel super confident of the above partly as I stopped digging as i realised that BGO wasn't interesting to me and that I wasn't going to chase Boku (sadly at 90p!!!).
DYOR obvs and treat my view above with a bit of scepticism. I haven't dug enough to be sure...just my (often) sceptical vibes
Ciao
Appointments of new Nomad and Broker this morning seems to be proximate catalyst for Bango (LON:BGO) house cleaning update last night
Results from Science (LON:SAG) are very frustrating for former holders of Frontier. Science (LON:SAG) stepped in at the cusp between cash outflow into product development, and cash inflow from product success. Gold star for Science (LON:SAG) management, dunce's cap for Frontier's former management, and harsh lesson for small cap investors.
Also apparently quite large numbers of people are given vouchers (not sure if they’re from APP or not) for taking regular covid tests
People having regular Covid tests as part of the ONS/Oxford Uni survey redeem their vouchers through VoucherShopExchange, which is part of Sodexo Motivation Solutions UK Ltd. Nothing to do with Appreciate (LON:APP) AFAIK.
JET2 cancels all flights and holidays until after March 25th
source - Press Association
"On the other hand, Covid is a once in a hundred year event. It would be unrealistic for governments to carry redundancy and capacity for such an event."
... according to Mr Whitty, it sounds like this may become an annual event - although regional and not (I hope) international.
As such it is the duty of govt to fund the NHS to a an appropriate level that balances the extra cost of the NHS against the costs of another lockdown.
Agreed
Its just the 90 odd years in between which would be difficult to justify.
Moving forward, yes Covid is now a flu type problem. Huge number of vaccinations each year with the vaccine probably requiring modification.
As has been stated, it is with us for good - but hopefully can be mangaged
I thought the average was 3 pandemics every century (I stand to be corrected of course). Last century we had Spanish and 2 Hong Kong variants 1957 and 1968, so I guess on that basis we were sadly due one.
No-one seems to have mentioned Swine Flu, year of pandemic, 2009.
Dr Martens quality is said to be dreadful since the PE guys moved in. The (made in China these days) boots can fall apart within 6 months. Those in the know buy Solovair, who make footwear (DMs, but can't use that name) to the standards that DM used to be renowned for. Wouldn't touch DM shares with a bargepole.
Solovair were the original supplier of soles to Dr. Martens. Both head offices are in Wollaston, Northamptonshire. Solovair still manufacture in the town. :-)
Accrol Group (LON:ACRL) I saw the company turnaround presentation before Christmas at one of the last Mello Mondays of the year. Accrol Group (LON:ACRL) have made a lot of efficiencies in warehouse management (stock movement) and are expecting cost cutting to be significant. They are seeing customer preference is to buy the cheaper end of the toilet paper market; with expensive alternatives like Andrex loosing market share. I came away wondering what the growth prospects are? Surely it’s a saturated market and the only way to grow is to take market share away from others? It they are competing via a cheaper product / cheaper price, then I’m concerned how sustainable it will be long term
I read that the cheap end of the market only made up 25% of Accrol's sales with the rest on medium and best quality. They are also in talks with Tesco to supply. I bought yesterday (doh) and added to my position this morning. You are always going to need arse wipe was my thinking....
"There doesn’t seem to be much relationship between the amount spent on health care and the outcome so far"
Very true. The US spends nearly twice as much per capita on healthcare than other developed countries. This has not prevented the US from severe healthcare delivery shortfalls during the crisis.
On the other hand, Covid is a once in a hundred year event. It would be unrealistic for governments to carry redundancy and capacity for such an event.
Interestingly the US spends the same on public healthcare - Medicaid and Medicare as a proportion of GDP, as we do on the NHS. But then they spend the same amount again on private healthcare. It truly is a wasteful system, as life expectancy and some other healthcare indicators are lower than not just the UK, but Cuba!
.
Paul
Retail Gazette today quoted £5m as £.MKS cost to buy Jaeger though they do not quote the source.
slightly off topic as it is a resource company but did anyone else notice the Ferrexpo (LON:FXPO) trading update today and think wow!
They've gone from a net debt of $280m+ to a net cash of +$4m are paying dividends of something like 7% (including special divi) though one has to watch the WTH as it is Swiss based. The CAPEX programme has just increased net production by 20%+ and with Iron Ore at these prices then given they are one of the lowest cost producers in the world a PE of 5 or 6 feels somewhat absurd. At this rate they will add 30% of their market cap in cash in the next year alone!
Some country risk and some political risk (major shareholder has been involved a number of wrangling leading to prosecutors trying to freeze his shares : something that I think has now been resolved and can't be re-appealed, but who knows). But nonetheless looks mis-priced to me, though admittedly has come up a long way over the last year already. Mining not flavour of month but they are at the cleaner end producing high ore quality pellets.
Compared to best in class peers look very cheap (almost half) despite having same low cost profile, one of the worlds largest ore bodies, high divi and big cash gen. Anyone else looked at this?
Agree David - recently added and thinking about buying more. Looks under priced and could double or even triple and also with a decent dividend payout. Had a small amount in my portfolio and it was doing nothing pricewise for a while and has now come to life and seems to be rapidly re-rating.
Ferrexpo (LON:FXPO)
Hi David
I couldn't agree more with your bullish comments. I don't usually invest in resource stocks, but I did buy some of these shares during the madness that was 2020.
Cash generation looks remarkable - by my estimate, annualised cash generation should easily exceed £200m/$300m going forward, alongside an assumption that demand for iron ore pellets will continue at least for the next few years (with one hopeful eye on China and it's never-ending growth).
The current EV of the company is c£2b.
The dividend is decent too, which should continue to push the share price up.
I'm not sure they will generate 30% of their market cap in cash in the next year (that would be $900m/£600m), but then again you never know.
Cheers for the input
A
Ferrexpo have also been paying special dividends and a near 20% dividend for those of us who bought around the lows last year. Mining sector bear market bottomed in 2016 with share prices well below the lowest points in the 2008 market crash. E.g FTSE share Anglo American fell to £2 and has since multi bagged tenfold. It was an extreme bear market hardly noticed by many, as markets in general were doing OK. Now with soaring commodity prices the sector has been soaring too, but many mining shares are still a good bit lower than the last time commodity prices were this high.
hi abtan
lol, yes I was using £1bn as the market cap for some reason....doh!!
I also reckon circa £300m so maybe 15% rather than 30% but nonetheless pretty prodigious.
I guess the country risk and political risk can't be brushed aside when the going is good so we need to factor that in. I expect that risk is higher than the likes of Rio and BHP but probably by virtue of its concentration to one country so a discount is merited but those guys are trading at what 15* earnings so lets apply a 33% discount to peers and at 57p projected earnings for next year that's = 513p to 570p
Of course a collapse in Iron ore would kill those assumptions
Also - forecasts seem way too conservative for 2021 don't they? $1.5bn at 12m tonnes suggests an iron average price of $130. Given pellets go for a premium of $15-30 tonne given their quality that would put spot iron around $100-115 for the whole of 2021. That seems wrong to me given we are already fairly steady at $170. Wonder if there will be further upgrades as the year pans out.
"Moral issue - I can’t help pondering the situation where billionaire owners of retail chains like Arcadia & others, milked the businesses for fancy lifestyles in the good times"
I recently watch the film Greed https://www.imdb.com/title/tt8... which is a really eye opener in to this type of activity! I think Steve Coogans character is based on Philip Green. IMDB only rate it as a 5.7, but I thought it was worth the watch :)
I was really looking forward to the film, as I think Steve Coogan's brilliant. But for me it was a complete flop.
I wanted to like it, but it seemed that its makers couldn't decide whether it was supposed to be a comedy / satire or a conscience-pricker about the cost of cheap fashion and the evils of unbridled capitalism. It ended up as a fairly dismal combination of mostly unfunny comedy and a patronising and annoying exercise in virtue-signalling.
Not recommended.
I watched the trailer on Amazon Prime, and quickly decided I didn't want to pay £6 to watch the film Greed. Mind you, I find Steve Coogan really irritating, and unfunny.
One very, very minor point that made me simile during Mello last night was the miss pronunciation of Asos (LON:ASC) (I hold) by both David & Ed Croft. "Ass-os" is really pronounced "Ace-os". I would rather invest in an "Ace" that an "Ass" ;)
I have purchased a copy of The Smart Money method. Decided to go for a paperback than Audible as I was afraid it would have too many graphs / tables to make sense as an audiobook (also its not available as an audio book just yet). I quick scan through; i can see roughly about 20 - 30 graphic representations in total
Hi Andy,
David & Ed could always call ASOS by it's full name instead of it's acronym ASOS.
ASOS = As Seen On Screen.
It still seems rather early in the Covid crisis to draw firm conclusions. Just look how Sweden has gone from a star in many people’s eyes to the Swedish now being very annoyed with their government’s response and they have only now started to introduce mask wearing.
However, .....
There doesn’t seem to be much relationship between the amount spent on health care and the outcome so far. Note that the Swiss haven’t had a particularly good crisis despite their high spend on health care. But I cannot help wonder why there isn’t a body of reservists that can be called up to supply medical care in times of crisis (in a similar way to army reservists). Surely that would be more cost effective than staffing the NHS much more highly just in case a pandemic hits.
People still seem to analyse the health outcome in a very binary way - death or life. Little regard is paid to the debilitating effects of long Covid, which many people who survive it seem to have. So, I think the “vaccinate the old and vulnerable and then let it rip through the rest of the population” approach being advocated by some people is too simplistic.
And what about obesity? We are a very fat nation in the UK. If this is such a factor as was claimed in the first wave then surely that needs to be considered in any comparison we make between the UK and other countries.
A fat nation with a more highly contagious variant might actually explain the majority of the differences in our outcome so far versus other European countries.
There was an article in The Times (IIRC) a few days’ ago that expressed the opinion that the outcomes in most Western countries have been fairly similar and that we need to look to Asian countries to see a distinctly different strategy and outcome.
Lastly, our government have made many errors in a panic to get on top of things. It seems that the NHS and PHE have played their part in this too and it’s not just the government. But it also seems to be the case that most European governments have made a right mess of this one way or another.
Just to add to two things you mention:-
ONS put those suffering from 'long covid' i.e. still have some symptom such as tiredness - in the '18-49 year olds' at less than 10%.
This seems low but I have two additional issues with this ONS statistic.
Firstly, 18-49 year old.....that is a big age group and the ONS and PHE seem to use this large range in all of their statistics. Secondly, the symptoms grouping is not very specific. I watched a NewsNight special on 'long covid' and they put the number of severe long covid suffers at around 200.
At which point I decided I was wasting my evening and turned it off.
Maybe it is a problem, but if it is, they don't half do a terrible job of showing the true impact of it.
The second thing I would add to is eating; Japanese have a saying "Hara hachi bu" - it roughly means eat until you are 80% full. I think I am not being harsh when I say that is not the attitude to eating in most other countries.
Permira were behind the IPOs of Aa (LON:AA.) and Saga (LON:SAGA) in 2014. Both with £bn valuations but sky-high debt. The share prices of both are down c.90% since flotation. Buyer beware.
I wouldn't touch anything they float; they are masters at extracting all value for themselves.
Re Marks And Spencer (LON:MKS) Paul, the Times says £5m for just the Jaeger brand.
Very strong growth over last 3 years - can it continue, or is this an opportunist float after a good patch of trading?
It seems all too inevitable. These Private Equity guys really know how to offload their debt-laden merchandise.
yes, only need to look at Debenhams to see what happens
One point - references to "herd immunity" are really not relevant. This is from Chris Whitty's interview with the BMJ last November:
For the great majority of the infections I’ve dealt with—and I’m an infectious disease epidemiologist—you never get herd immunity. You don’t get it for malaria, you don’t get it for HIV, you don’t get it for Ebola. Secondly, it makes an assumption that immunity will be
maintained, at least for some period of time. And this is not clear yet with covid. We certainly know, for example, that antibodies wane quite fast. So, I think scientifically it’s on very weak foundations.
I wander of Chris Whitty is being a bit disingenuous with his comments here or they are being taken out of context if he was concentrating on herd immunity being acheived by natural means rather than being aided by vaccinations ! He specifically references the great barrington declaration in this regard so that seems to be specifically where his beef in that regard lies - and thats not really the route we are taking if we are acheving herd immunity by vaccination rather than natural selection.
He seems to be directly referencing malaria and HIV which are known to be problematic as they mutate so fast that they are hard to pin down. Everything i have seen with regard to covid suggests the main structure is such that its reasonably easy to attack and its not mutating at a rate that suggests we can't find a way to cope with it if it does mutate. Presumably we acheive herd immunity with measles so why can't covid be the same. deffo seems he has cherry picked his comparisons here.
He may be technically correct that more virus's are hard to acheive immunity with than not - but is he being evasive with the truth by ignoring the fact that "every virus" has its own factors in this regard and thats whats important - ie the specific mechanics of this virus rather than another completely unrelated viruses that matters. Also he may correct with regard to lack of any data that immmunity will be retained long term - but even here there is some evidence that those who had sars have maintained some long term immunity - so its not that there is no hope.
I would agree the jury is completely out as far as what the end result is - so warnings are fine - it does appear he is pimping his own viewpoint up though in that regard. We all do have confirmation bias after all, and i do understand why from a psychological viewpoint he would somewhat pimp up the worst case scenario possibilities - i don't have a problem with that as longs as its done in an open and tranpsarent manner.
I wander of Chris Whitty is being a bit disingenuous with his comments here or they are being taken out of context if he was concentrating on herd immunity being acheived by natural means rather than being aided by vaccinations ! He specifically references the great barrington declaration in this regard so that seems to be specifically where his beef in that regard lies - and thats not really the route we are taking if we are acheving herd immunity by vaccination rather than natural selection.
Err .. well, he specifically talks about the difficulty of achieving herd immunity by vaccination in the remainder of his response:
As for the other end of the spectrum—which is, why can’t we just eradicate this virus?—that’s also impractical for a variety of reasons. There are reasons why we have, to date, only managed to eradicate one human disease—smallpox—with two or three others that have been just on the edge for a long time. It’s very, very difficult to do.
I don't think it's an unreasonable inference that we're unlikely to eliminate CV-19 by vaccination and that pushing herd immunity by any means as a solution to the pandemic isn't a viable option.
timarr
Err .. well, he specifically talks about the difficulty of achieving herd immunity by vaccination in the remainder of his response:
I dont think anyone said it was going to be easy ! - anyway being serious with regard to this point i have answered some with the evidence that he is talking apples and pears and ignoring some promising signs - but looking at the last important point - this is simply not relevant if we acheive heard immunity via vaccination its only relevant if we acheive heard immunity via the natural method of letting people become affected- at the minimum here the non precise wording gives a somewhat false impression that herd immunity cannot be acheived without many deaths which is simply not the case if we get there by vaccination.
The third reason I personally have problems with it is that, ethically, it would lead to a significant number of people dying who otherwise would not have died of this virus. And it almost certainly would lead to much higher pressure on the NHS and therefore some of the indirect damage.
I don't think it's an unreasonable inference that we're unlikely to eliminate CV-19 by vaccination and that pushing herd immunity by any means as a solution to the pandemic isn't a viable option.
I thought we were going for some form of herd immunity here though via vaccination method are we not? - I am still of the belief that we are being told that once we get to a certain level of the population being resisant to covid the virus will struggle to keep R0 anywhere near and will die away. Is this not herd immunity - ? perhaps i am missing something hear.
Ok i am not completely losing the plot here Dr Fauci who is probable an equal to Chris witty has gone on record as stating he was hopeful we could get to a herd immunity stage.
https://news.harvard.edu/gazette/story/2020/12/anthony-fauci-offers-a-timeline-for-ending-covid-19-pandemic
Implicitly I suppose we are going for some form of herd immunity (by vaccination) in the sense that there is no expectation of 100% vaccination (and in fact no indication as of yet whether under 18s will be vaccinated).
Very superficial maths, but if 'Original' Covid did have R0 of 3 then you would need around 66% vaccination/infection to get Rx to 1.
It has been suggested that Kent Covid has a transmission 70% higher than the original that infers to me (again superficially) an R0 of c. 5 so 80% to get to Rx = 1.
Nobody should treat any of that as proper science or maths but I think it does at least wave vaguely in the direction of how deep the vaccination efforts needs to go.
According Hancock every UK adult will be offered the vaccine by the Autumn - I don't know what the latest info is on the proportion of the population that will accept the vaccine, but conceivably we could get to the kind of levels that imply herd immunity before next winter, in the UK.
Of course then there comes the question as to whether repeat vaccination is required.
Also, unless we stop travelling all together it is not the UK herd we need to consider, but the global herd.
I don't mean this to be depressing as I remain optimistic; but it does seem to me we can expect Covid-19 to remain an issue for some years - but hopefully it can become background noise akin to influenza.
I have only ever read 3 financial books in 30 years of investing. The Zulu Principle on which i base most of my purchases. The Smart Money Method by Stephen Clapham is an excellent book for novices and experienced investors alike covering a wide base of investing. The final book is Reminiscences of a stock operator by Edwin Lefevre. A fascinating insight into the world of the US stock market through Larry Livingstone around the early 1900s. Predominantly about trading it has opened my eyes to 'tricks' that still go on now. He made and lost a fortune several times and his involvement either short or long had real influence on a share price. A bit like our editors!
Hi Paul
You often mention buying books and have mentioned Amazon. Have you looked instead at supporting local bookshops by buying through Bookshop.org?
I try and use bookshops.org, or other alternatives, where I can. But I do struggle with ebooks. The kindle is the best I've used by far. I do read epubs on my phone, but the format is not as sleek as reading mobi, whether on a phone or a kindle device. If I could crack that I could exist without amazon. That said my family would rise in open rebellion so it would only be a token gesture to big tech.
Hi The skier,
You often mention buying books and have mentioned Amazon. Have you looked instead at supporting local bookshops by buying through Bookshop.org?
I've got lousy eyesight, so I tend to get most of my books on audible, or kindle (where I can enlarge the font to very big, hence comfortable to read). I can't read paperbacks at all now, as the fonts are just too small.
So that only really leaves hardback books, which have a font large enough for me to read if I go outside on a sunny day.
Therefore, Amazon (which also owns Audible as I'm sure you know) is the best bet for me, and also instant, and convenient, and stocking such a gigantic range.
I know it sounds cruel, but I don't really care if local bookshops survive or not. They're nearly all gone now anyway, because online is so much easier.
Regards, Paul.
Dr Martens IPO
Will it be like "The Wolf of Wall Street" Steve Madden IPO? ;-))
https://www.youtube.com/watch?v=n790p8QBfMo
Paul,
I enjoy your ramblings because they often make a lot of sense .
Hi Paul
Interested in your comment on Land Securities (LON:LAND) this morning. I have held a small holding in this for a very long time, on the principle of holding a few "sensible" investments to ballast my more speculative ones. Needless to say, over the long run, the performance of the "sensible" investments, including Land Securities (LON:LAND), has been poor compared with the average of the speculative ones. Nevertheless, their management seems to have done better than most - they had been reducing gearing, and cutting back on new projects, over the past few years, and are probably in a better position than most to take advantage going forward.
This is the first time I've heard someone categorise their investments into Sensible and Nonsensible!
What are your high level criteria, out of interest?
sensibility of course!
Ref vaccines
I think the most important think to keep an eye on at present with regard to how markets will react in this regard is how the Israeli situation pans out - they are vaccinating so fast they will probably be completely done by sometime in march at the latest - so what happens in that country will be the first proof of the pudding as to whether practicably speaking we can completely put a lid on the covid problem with the vaccination route. I think the market is presuming once enough bods are vaccinated the problem mostly goes away for at least the next 6-9 months or so - i am hopeful this will be the case - this being the case hopefully we soon get the news that things are going as they hoped for in Israel - however if there are any indications that the vaccination rollout is not doing the job of putting a lid on it in Israel that will be seriously bad news i would guess with regard to how the markets may react.
Thanks Paul. Any views on Rosslyn Data Technologies (LON:RDT) update today?
I can't comment on Dr Martens as an investment prospect but when I had a spinal injury and surgery some years ago that made walking very difficult and painful their shoes were an absolute godsend.
(Anybody who knows me personally will know that I'm about as far from being a stereotypical DM wearer as could be imagined!)
I realise anecdotes can be very misleading, but I am going to post one anyway.
Have just walked into Farnham, shopped in Lidl, and walked back home; other stores are available. Anyway, whilst for the last week, the town has felt rather busy given the new rules, today it was much closer to lockdown 1. Apart from a couple of occasions over a twenty minute walk, I was at least 50m from the nearest person. Also Lidl was far quieter and pretty easy to keep a good distance from everybody the whole time I was in there.
Hopefully this is part of a wider trend of less societal stupidity, which will help us all in the coming months.
Paul, I spent virtually all of my working life with a company whose practice was to use flexible working hours. This being most of the production workers being on 12-hour shifts and moving them back to 8-hour shifts when demand was unusually low. There were minor adjustments too of course, like when some labour on intense jobs normally on 8-hour shift were transferred temporarily to the Stores. This suited almost everyone as the workers received time-and-a quarter for their extra hours worked during the week and more on weekends. Now it strikes me the NHS operates similarly but with a slight difference which is long hours and low pay in normal times and Management totally lost when something like Covid comes along. Isn't it time the NHS manned up?
Silver
Apologies in advance for posting about Boohoo (LON:BOO) as I know its not on todays topic but I swear someone mentioned an earning coming up soon in a previous days comments that I cannot find. If anyone knows the date and can quickly reply I would be grateful. My googling has no given me the information to date. Thanks in advance!
The update is on Thursday
£BOO TU 14/01
LeePM1985 - Boohoo (LON:BOO) Trading Update due on Thursday this week.
Ooops! beaten to it by two other posters. Just goes to show how popular this company is with readers of SCVR.
Looking at the Stockreport for £BOO the Trading Update doesn't show under Upcoming Events, does anyone know if there is a way to make this appear, otherwise one for Ed to add to the backlog ?
Hi LeeLPM1985. - I know it's been answered but I always try the companies investor page index - In the case of Boohoo (LON:BOO)
https://www.boohooplc.com/inve...
A broker friend gave me a good tip recently. To find results dates, type this into google:
{company name} financial calendar
The first item on the google list is usually a direct link to when next results statement is due.
It may not work for the smallest companies, but I tested it out for my top 5 holdings, and it worked for them all.
Regards, Paul.
Cool Tip! :) I Like using https://www.sharecast.com//com... It only gives a view of what's coming up during the current week. Its a same they don't make it searchable
I use Investigate's Company Events - Today's, Tomorrow's and Month Ahead - usually pretty accurate though caught out occasionally when companies decide to announce early:
https://www.investegate.co.uk/...
https://www.boohooplc.com/inve...
Hi Lee, here’s a link to Boohoo (LON:BOO) financial calendar
Doc Marten's! That brings back memories. I never wore them but Alexei Sayle sang their praises in his tremendous album CAK!
https://www.youtube.com/watch?v=ltjQzMGd6r0
Same here Mr C. I had a couple of pairs back in the 80's. Didn't really realise they were still around. I loved them. They were mostly well made, but for some inexplicable reason the insoles were a sort of compressed cardboard, which disintegrated in months, years before the rest of the shoe. I played around with extra insoles, and then stopped buying. Maybe they've sorted that in the last 40 years!
On the vaccine rollout the only thing that really matters is when hospitalisations fall to a level that relieves the pressure on the NHS. Everything else is immaterial, there'll be no release from lockdown while admissions and occupancy remains high.
Based on Chris Whitty's comments yesterday that's likely to occur in late March or early April and will probably see a reversion to the tiering system where cases remain high. There's unlikely to be an immediate, countrywide reversion to normal (whatever that turns out to be).
I'd agree with some of the other comments here that the vaccine rollout has been excellent, but I suspect many commentators are scarred by the litany of failure and overoptimistic boosterism that's dogged the UK's response up to this point. It's hard to be positive when every previous dawn has proven to be false.
One point - references to "herd immunity" are really not relevant. This is from Chris Whitty's interview with the BMJ last November:
For the great majority of the infections I’ve dealt with—and I’m an infectious disease epidemiologist—you never get herd immunity. You don’t get it for malaria, you don’t get it for HIV, you don’t get it for Ebola. Secondly, it makes an assumption that immunity will be maintained, at least for some period of time. And this is not clear yet with covid. We certainly know, for example, that antibodies wane quite fast. So, I think scientifically it’s on very weak foundations.
https://www.bmj.com/content/37...
timarr
I'm a health economist who works with epidemiologists to model diseases and I wish I could give this comment a hundred upvotes. People are far too optimistic about the impact of vaccines on a return to 'normal'. Former colleagues of mine are working on vaccine efficacy models and their best case for immunity is one year. The best case.
I sold out of Saga (LON:SAGA) recently for precisely this reason. I like the prospect for the turnaround but the in my humble opinion the idea that cruises will be running in April is a non-starter.
You've persuaded me to sell the scrap I still have, having slowly sold out as things got worse. My normal strategy is to invest when a stock has clearly turned and on the move; I'd expect to get into Saga (LON:SAGA) again sometime this year.
Hi IncredibleMosesLeroy,
But if you look at the processes SAGA (I hold) has designed to re-start its cruises, it doesn't rely on any guesswork, or risk-taking. They've designed a belt & braces system, where everyone on the ship is tested 5-days before boarding, has to isolate, then tested again on embarkation.
Plus rigorous distancing, cleaning, isolation wing, etc, on board.
Having said that, you could be right about April being too soon, but May seems credible.
If immunity only lasts a year (best case), then surely the best option is to let it rip through the healthy population & die out naturally, as quickly as possible, once the vulnerable have been vaccinated? Is there not a danger that we could be prolonging the whole thing with lockdowns? You're the expert, I'm only asking the question, I don't know the answers.
Whatever the medical people want, in an ideal world, I just don't think it's possible to keep people locked down for much longer.
Regards, Paul.
Re Saga (LON:SAGA), half of the people on a cruise ship are crew. They usually get ignored - what are the processes for them?
I believe they will be tested too, and daily, and that it is not too difficult to do logistically. This is now starting to happen also on some construction site, where workers and visitors will now get tested daily. I wonder if this is a new outsourced service that the likes of Capita (LON:CPI) or G4s (LON:GFS) will be starting to offer to other SME.
So true. In South Africa we have been in Lockdown of one degree or another for over ten months now. And ,once more, for the last 3 weeks the sale of alcohol has been prohibited and you can only imagine the devastating impact this has had on the South African wine industry,let alone the hospitality industry generally. No chance this will be relaxed anytime soon.
And I suspect with vaccinations at the moment limited to the richer countries it will be at least another 9 months before we are out of Lockdown here.
So you are not too badly off in the U.K.
Why should Covid die out naturally, Paul? It might with a high proportion of the population voluntarily inoculated, comprehensive frequent testing and backed up by fast testing, tracking and local lockdowns for isolated outbreaks. That was how smallpox was eradicated - after centuries waiting for herd immunity, and three hundred years since inoculation started. There is no medical cure for smallpox, and there's none for covid as yet - we can only treat and minimise the symptoms.
The clinical trials suggest that some of those vaccinated for covid might still become infected; how effective temporary immunity for the elderly will be is still to be established; and it's still not certain whether or not those vaccinated can still shed viral loads, although indications are that they can't. Tests will improve, but at the moment the most practical one produces an uncomfortable high proportion of false negatives, especially amongst those who are asymptomatic - and being asymptomatic does not necessarily mean that there are no (non-obvious) negative effects.
A cruise in 2021 seems high risk to me - a small, contained outbreak on board might mean that the ship won't be allowed to visit anywhere... it might take longer for cruises at Saga (LON:SAGA) and other companies to increase volume.
Why should Covid die out naturally, Paul?
Because that's what happened with pandemics in the past, e.g. Spanish Flu, plague, etc. The world has gone long stretches without serious pandemics. So why do you think that is going to change now?
Don’t agree and you should not underestimate the desperate desire of so many cruise customers to go on a cruise ASAP. And a lot of these are very cash rich. My guess would be that cruises will start by June at the latest
Isn't the point though that we don't need full population-level immunity, we're not seeking to eliminate this virus completely (we know we can't)? We only need the old and vulnerable to be protected so the strain on the NHS is reduced to manageable levels. Then the majority of the population can resume their 'normal' lives, particularly where leisure activities are concerned. We can just rinse and repeat each winter or as/when vaccine protection wears off with jabs tweaked to target the most infectious/problematic strain at that time (as we do with the annual flu vaccine).
I wish. That would be a common sense approach but cannot see that happening any time soon.
I share the same sentiment in respect of customer facing businesses that can not start due to covid. Therefore, I sold out Revolution Bars (LON:RBG) , Saga (LON:SAGA) , Escape Hunt (LON:ESC) . I didn't want to wake up see it them up 4% one day and then 4% down the next day - feel my money, for now, is better off in other sectors.
My understanding of the Governement's pledge on Covid vaccines is that by the end of February, the most vulnerable will have received their first jab. Even allowing for mis-steps, by the end of March the it will be largely the under 50s who are totally unprotected.
The vaccines are not 100% effective, but even the Astra Zenenca vaccine reduced the disease severity such that non of the trial participants needed hospitalisation.
The under 50s in good health can still require hospitalisation from Covid, but that cohort have a far smaller hospitalisation rate than the elderly.
Therefore, from around the end of March we can reasonably expect a fair degree of relaxation of Covid related restrictions, and we can afford to have a rather higher ongoing rate of infection than now.
I suspect the Government will err on the slow side of rules relaxation, as it will be very hard to get consent for a fourth lockdown.
So, the hospitality and travel industry is likely to quickly ramp up from late Spring onwards.
But what does that mean? On one hand I think there' s huge pent up demand, and frustration. And a big slice of the population has been saving cash during the pandemic if they a steady income. So it'll be out with the DIY and online shopping, and hello to eating out and fun.
Even so, have travel and entertainment shares already discounted all this? You could argue both ways i.e. pre lockdown consumers were awash with mediocre mid range restaurants, and pubs were steadily closing. Has this really changed? On the other hand, could the pandemic have culled enough competition that remaining entertainment, and travel companies can charge high prices to cash-rich, eager consumers?
Hi Mark
Yes, I'd agree with most of that. My only, broader, point is that we should anticipate CV-19 will be a recurring disease. That should condition our thinking a bit about which sectors to invest in and which to avoid.
Of course, it may turn out that immunity is longer lasting or that the disease mutates into something less deadly but the likelihood is that we won't achieve permanent levels of herd immunity and there will be outbreaks from time to time. We can hope that we will never see the NHS loaded to breaking point again, but it will still be something to manage.
But as you say, there must be huge pent up demand and those face to face businesses that manage to survive until spring will surely see a surge in customers. Against that there's bound to be a rise in unemployment - we're likely to see a lot of small businesses go bust in the next three months, for instance - but hopefully that will be countered by a very rapid ramping up of the economy.
The one note of caution is that under 55's are currently making up 25% of the people being hospitalised. It's possible to imagine that a post-lockdown euphoric return to pubs and shops could cause another spike in infections. I'm certainly intending to be extra careful until I get the vaccine - I probably would be fine if I caught CV-19 but why take the risk?
timarr
Agree, the only other reason why lockdown might be considered necessary is reduce the number of mutations that might occur. As Anthony Fauci said, if it transmits - it mutates.
I am also surprised that little has been said about the future of vaccinations in the UK. Making reasonable assumptions that the vaccine will only provide immunity for 12 months and will require ongoing modification for future mutations, this would mean an annual vaccination programme of about 30 million people in the UK for as far as the eye can see.
As a general point its also worth noting that the German vaccination programme is going less that perfectly and attracting some considerable criticism.
"...antibodies wane quite fast." I am very pleased indeed that I will receive the Pfizer vaccine on Thursday, although I am only 72. There is apparently a local surplus. But I am far from pleased that the second dose will not be provided until April, contrary to the clear views of Pfizer that the science does not support a gap of notably more than three weeks between vaccinations. I am left quite uncertain as to the degree and duration of protection I may reasonably expect. Professor Whitty's quoted statement about the waning of antibodies adds to my uncertainty, and, frankly, anxiety.
I am left quite uncertain as to the degree and duration of protection I may reasonably expect. Professor Whitty's quoted statement about the waning of antibodies adds to my uncertainty, and, frankly, anxiety.
Hi OsullivanB
I'm not a medical expert and I'm not qualified to reassure you - but my understanding is that the first dose should provide some immunity while the second dose is a booster which strengthens and lengthens the response. But I agree that is does add in some short term uncertainty as the trials have been done with a three week gap not a twelve week one.
I'm afraid that it's a measure of the desperate pressure on the NHS that this is deemed necessary.
timarr
Here’s the JCVI report on the vaccines.
tinyurl.com/jcvivaccine
Thanks, timarr and john2.
Antibodies may wane quite fast, but that doesn't mean there is no immune response. Circulating antibodies are only a part of that, and ususally not very long lived. The other part are B and T lymphocytes, killer T cells will kill infected cells stopping virus replications. And critically there are memory B and T cells that retain the memory of past antigen exposures, allowing a much more rapid immune response on a later reexposure. There is evidence coming out that those have been found for covid 19 9 months or more after known exposure (as long as anyone can test for) and so there is evidence that the system is functional.
Hi timarr,
Good points, thanks.
Once the trend is downwards for hospital admissions, they'll have to relax restrictions, even if there are still too many people in the hospitals. Remember that the restrictions themselves do so much hidden damage.
Re the herd immunity comments, obviously I defer completely to the experts, such as the one you quote. All I meant by using that phrase, was that it seems to be a tipping point when these viruses (e.g. Spanish Flu) die out naturally, when enough people have either had the virus & recovered, or are naturally resistant to it.
Presumably, once we've vaccinated all the vulnerable people, then that point would be on the horizon.
Rapid tests seem key as well. If we have cheap, instant tests, then people queuing up to go into a pub, etc, could possibly all be tested. Or have a 24-hour pass if you test negative, in some way.
There's such an imperative to get the economy (which is people's lives remember, not just numbers on a spreadsheet) recovering, that I think the authorities will have to relax restrictions faster than maybe medical experts would like.
Nobody really knows, we'll just have to see how it pans out.
Best wishes, Paul.
With regards lifting the current restrictions I do agree that hospital inpatients is the key metric to be looking at. Matt Hancock made the point yesterday that although priorties 1-4 (over 70s etc) represent the majority of the deaths, the over 60s still represent a significant proportion of the hospitalisations. So I do think it is logical to be looking at March rather than February.
I'm in little doubt however that the schools will be back after half-term unless something goes badly awry.
With some tentative evidence that case numbers are beginning to flatten, as we might expect one week into lockdown and if so this will feed through into hospital levels by the towards the end of January. This could create some pressures to lift restrictions earlier; however the mood music (at least from Hancock) suggests to me that this time around, more caution will be shown. IMV this will be the right path for the economy as another stop-start would be more damaging.
So I am feeling quite hopeful for the spring - but there still uncertainties between now and then, so I'm still quite cautious about some sectors.
Hi Paul
All I meant by using that phrase, was that it seems to be a tipping point when these viruses (e.g. Spanish Flu) die out naturally, when enough people have either had the virus & recovered, or are naturally resistant to it.
You're obviously right - otherwise we'd all be affected by these diseases now.
I think the problem is that the timescales and mortality involved are unknown, and our best approach is to vaccinate our way out of the situation. The best guess is that CV-19 immunity won't be permanent and we'll have to keep on doing it. Still, I'd happily get two jabs a year if I could go down the pub again. Or go to a real Mello. Or see my parents.
On a stock related note I think this all points to a permanent need for better diagnostics and testing regardless of vaccines.
Returning to Spanish flu - when the 1918/1920 pandemic passed people partied like crazy. Maybe the Roaring Twenties are about to repeat themselves?
timarr
.
Great points Timarr, and interesting what Chris Whitty is said re heard immunity and what he thought (in early Nov) that we were heading into now. The market in some sectors seems to be valuing stocks assuming covid is over or will be by Q2, where we are in the eye of the storm at the moment, with case numbers / hospital admissions and covid deaths so high, there will be no easing of lockdown until these numbers are lower / under control. to date with hindsight, the forecasts given by politicians have been far too optimistic. Unfortunately feel we are in this for some time to come, but hope I’m wrong.
As Paul correctly said, the Spanish Flu died out naturally. The reason why it died out naturally is due to the fact that all viruses mutate over time. Fortunately, the Spanish Flu virus mutated into a harmless virus which no longer killed people.
Not meaning to pick on Logical David specifically as there is a lot of unclear communication (including from eminent scientists) about virus evolution (AKA Mutations).
Spanish Flu - did not [directly] evolve to become benign. That's not how mutation / evolution works. When a virus "mutates" it does not mean that the "original" strain ceases to exist; it just means that you have two strains in parallel.
If the new strain is more "successful" then it will increase in numbers relative to the existing strain, but it doesn't (ordinarily) kill off the old strain.
A more accurate description of the end of 'Spanish Flu' I believe is that humanity developed a degree of [herd] immunity to the original strain and those mutations that escaped the enhanced human immune response (similar thing to becoming vaccine resistant) proved to be mostly harmless.
To make science "accessible" it seems common to start to describe a disease or virus as if it were sentient - "the virus decided to do this" - I do get the idea of getting the message across to the general public, but it then gets taken too far.
Some will think I am being overly nerdy on this point (an argument probably not without foundation) , but if you really want to know what is going on it REALLY does not help to ascribe sentience and intent to a virus that essentially is a random number generator.
Weird science addition
The planet earth is still run by humans rather than viruses.
Viruses have a the advantage of a vastly faster evolutionary cycle. However their evolutionary process has not yet learned how to "farm".
Re: Appreciate (LON:APP) I've had a Love2Shop card since 2018 and it will expire soon - I'll have to keep a close eye on the balance and the original terms as it struck me at the time that the money-making element here was left over balances on cards which people had lost track of.
So far as I am aware I've not received any marketing emails as a result of having this card (I use a unique email address for all online accounts).
Neil.
Re Germany, yesterday I was talking to a German mother whose family moved here in September (they are academics). I asked her whether there was the same level of criticism of their governments handling of the pandemic, she replied that there was little criticism despite the fact that when she left Germany there were only 8000 deaths and now there were 40,000 (I have not personally checked the figs). I said that it was extraordinary that there was no baying mob after Mrs Merkel. She was also very unimpressed with the German rollout of the vaccine.
Maybe it is just that The Germans are a very compliant people ? or do we just like criticising Boris ?
The reason is simple. In the first half of 2020, whilst the Westminster government was floundering about, Germany had a strategy, backed by strong communications through the Robert Koch Institute. They were testing and tracing - and bearing down on any outbreak, whilst the British government was making promises about testing that it failed to fulfil, an on occasion lied to cover its inadequacies. Just as with companies, overpromising and underdelivering loses trust. Boris in particular is not even trusted by many of the MPs in his own party because of his past deceits, general unreliability and lack of loyalty. And lack of trust in the population breeds scepticism and and a greater inclination to believe conspiracy theories.
His government then awarded substantial contracts to people unqualified to deliver them, who just happened to be close friends and colleagues of ministers. Instead of delegating part of the management to local authorities, they starved them of resources instead and went for central control and command. Germany did the opposite. Add to that the hypocrisy of breaking the very rules that they expected everyone else to follow - not just Cummings but Jenrick and others as well. If this sounds political, ask yourself this: if you were invested in a company whose management behaved like this, would you tolerate it or expect your directors to take action?
More recently, true, there is the bright spot of being ahead of the game with the vaccine - on a par with Denmark and the US in terms of vaccinations per 100,000 but somewhat behind Israel, the UAE and Bahrain. The NHS is now in an all too predictable crisis, which is why we have the current lockdown - people will suffer and die because serious non-covid treatments can no longer be done. There is some potential good news though - Nadhim Zahawi has been put in charge of the vaccination effort - said by the FT to be "brilliant on detail". We'll see.
The NHS is now in an all too predictable crisis, which is why we have the current lockdown - people will suffer and die because serious non-covid treatments can no longer be done.
Indeed. 91,000 excess deaths in 2020 in spite of economic shutdowns and all of the other personal sacrifices people have made. It's hardly surprising that the government's not being given much credit for the vaccine response ahead of actually delivering on its promises.
https://www.bbc.co.uk/news/uk-...
timarr
I would suppose that smaller populated countries could get everyone vaccinated more quickly. If Monaco had the vaccine available could they not deal with all their population in a few days.
Not particularly aimed at you but other than that we are where we are. I can see the point in discussing where we are going from a point of view of which businesses may get back to what was previously normal (if ever) but not to discuss the politics of what has happened. It is clear from your e-mail that I could not persuade you to think any differently of the government and vice versa. I think that Boris has been faced with the worst situation that any newly elected Prime Minister could face, other than having a world war immediately declared. I think he has done as well as anyone could have done but, so what, that is only my opinion and that matters to absolutely no one here.
It would be nice if we could keep political opinions to ourselves and stick to trying to make successful investments!
The UK figure in this chart is a week out of date. If you feel the need to make a political point it is best to support it with current data.
The chart says the data was updated at 5am yesterday morning. The source was the FT.
Well that's correct but our figure is stated as being as at 3rd January and the top three (not that they are remotely relevant) are at 10th and 11th January, so a completely useless chart. For many years I used to read the FT every day but I cancelled it due to reporting of things like this and also the realisation that I wasn't making any money from reading it.
The only thing to remember is that Scotland had a very vigorous messaging system (I am no fan of the SNP) but have had just as poor statistical outcomes, depending on your view. I think we will need a longer view before the reasons why become clearer
I think the big factor is that though Germany is now seeing high levels of infection, the UK has been near the top of the deaths leader board from the start, and the govt reponse has been clearly late, lacking in clear strategy and inconsistent from the start. So the UK population has had 9 months to appreciate how poor the response has been. The German population may catch up if German rates remain high.
UK is testing double the number of people that Germany are now and both countries have a 7 day average of deaths at around 700ish with several days around 1000 per day but cases in Germany are showing at half that of the UK. This is short-term but just shows the UK is improving.
Germany have certainly done better over the course of the crisis but the biggest contributor is likely to be their healthcare system which is much better equipped. They had diagnostic centers before the crisis and many more ventilators per population because they had planned for super bacteria and mass health outbreaks in preparation for anything happening.
This is likely because Merkel is a research scientist by background.
UK is testing double the number of people that Germany are now and both countries have a 7 day average of deaths at around 700ish with several days around 1000 per day but cases in Germany are showing at half that of the UK. This is short-term but just shows the UK is improving.
I suspect the UK was unlucky in the first wave - most countries had localised hot spots but CV-19 hit the UK everywhere, because of people coming back from winter breaks. Over time this should even out.
However you'd expect UK excess deaths to remain high because our health services don't have the capacity to deal with CV-19 and maintain other treatments. For example at least two London hospitals have cancelled urgent cancer operations - I can't even begin to imagine how those patients must be feeling, especially when there are idiots out there still claiming this is all made up.
But my main problem with the UK government is the constant cycle of overpromising and underdelivering, and then pretending nothing's gone wrong. It's difficult, most governments have struggled, but you can't beat a virus with a positive attitude and a jaunty three phrase slogan.
timarr
Hi Paul, interesting guess work,
Put all this together - i.e. rapid vaccine roll out for the vulnerable, and probably higher herd immunity from undiagnosed cases, and we have a situation that could start to improve in a few weeks. Leading to easing of restrictions possibly in March?
I think there's definitely something in this, especially as we're likely seeing a bump now from Christmas, and after that we had lockdown, so we'd expect numbers to start falling. We need to factor in the time it takes the vaccine to become effective, 14-21 days, but I agree there must be a considerable chunk of people who have already had it. On top of this those most likely to be hospitalised are the older or more vulnerable, exactly the people who are being targetted first. I think you're probably right, schools are off until mid feb, then there's half term, I would have thought the pressure to get the kids back will be overwhelming, especially as it's a bit of a fake lockdown and some schools are more than half full anyway. The weather will also start to change, so that's another factor that will help with more time outside and windows open to allow greater ventilation etc. We are probably at peak pessimism at the moment, as long as the thing doesn't mutate to a form that beats the vaccines, then I think we can look forward to better times ahead. Part of what's going on is the young kids, they've been locked up for nearly a year now, not allowed to meet friends out of school, or even when they were , overprotective parents not allowing it. some older kids are just ignoring rules now, you see teenagers all over the place holding hands etc, (I doubt they're brother and sister), so we do need to get this rolled out asap, as lockdown is becoming less effective. I agree, while most of the governments response has been poor (for example only now starting to test people coming into the UK), the vaccine strategy has been second to none, hopefully they can keep the rollout going as fast as they can get their hands on the vaccine, and we will start to see the effects of higher immunity of the public. One interesting point, what about the 20% who have had it ? do they need vaccinating ? do they have better protection that the vaccine provides already ? which protection last longer ? A useful tweak to the strategy might be not to vaccinate those who are known to have had it until later, to get protection for the maximum number of people we can, as quickly as possible,
I'd agree that loosening of restrictions should be possible once infection rates are brought back down and the over 65/70s plus vulnerable have been vaccinated. But I think the govt needs to be very clear about messaging at that point (and I'd fear for that happening!). If all restrictions are lifted and the world goes partying then we will see high levels of infection amongst the younger age groups. They may not suffer too much from symptoms, though certainly some will die and many more will suffer from long covid symptoms. But with high circulating virus there will be more mutations and there's a real risk that one of those could prove to be more infectious, more lethal or not immunised for by current vaccines. Care will be needed. It's certainly not all going to be over in March, but it should be getting better.
Please can you cover Science (LON:SAG) after their positive trading update yesterday? You commented yesterday that you'd look at this, but don't seem to have had time to.
Hi andrea34,
I've got about 15 companies on my to do list, but have prioritised Science (LON:SAG) - section now up.
Regards, Paul.
Paul,
No need to apologise for the narrative around vaccines. It’s an interesting perspective and I think one we are trying to understand in terms of the tipping point from lockdown to ‘normal life’.
I guess I’m not alone in keeping a keen eye on the hospitality sector but as you mentioned a lot of recovery is already baked into prices. Fuller Smith & Turner (LON:FSTA) is a company that has clearly differentiated itself in the past, hopefully it can recover well in the future.
M
Camtab I also bought a Annual Pass and attended my first Mello evening last night . Thanks to Ed and his team at Stockopedia for the alert.
I always enjoy Andy Brough having been so entertained & informed by his appearances on PI World with Tamzin Freeman.
I think Mello and PI World to name but two demonstrate the quality of information now available to the Private Investor.
When you add the SCVR and the immense time & effort put in by Paul & Jack which I never miss it is no wonder my wife scolds me for spending too much time on my Desk Top!
Dear Paul, I am loving your pre-ambles so please don't apologise for them. Keep smiling
Lashings of common sense, dollops of insight, overlaid with much humanity. You are a national treasure Paul!
On the vaccaination rollout, I was speaking yesterday with a great mate of mine who is a retired consultant (and keen if erratic PI). He is incandescent about the vaccination and lockdown strategy. Like you and me, his son (an active surgeon) and all his family have had the virus, with seemingly no long-lasting effects. My son & dr-in-law too.
He mentioned an 83 year old lady he knew, who had had the jab last week, and he is certain she will die anyway within three months. "Madness" in his words.
Some difficult moral questions.
Remind him that anecdote != data
yes it's certainly a dilema, my mother a nurse often told me of patients given treatments often painful which didn't extend their lives, but made their remaining time worse, I recall an old lady dying inhospital given a hysterectomy, and every one knew she'd be dead in a few days, (and indeed she was). Yet on the other hand we send the teachers back to teach without vaccination, to face groups of kids many of whom will be asymptomatic. Its tough, but who is to make this decision that someone isn't worth vaccinating because they'll be dead soon anyway ? and where do you draw the line ?
Re immunity threshold etc, yes I've long thought we have a useful % already largely immune. worldometers shows UK as having > 3m confirmed cases (ie tested +ve) so reasonable to suppose perhaps double that have been infected in total, especially given the early months tested only the most severe cases, so maybe 10% of population, higher in some areas. And a further 30 days with, say, 70k run rate of underlying infections (v. 50-60k testing +ve) will generate another 2m within a month.
I also heard on the radio yesterday (can't recall the source) that 50% of those who've shared a bed with another who contracted the virus don't catch it themselves, or are totally asymptomatic - another encouraging statistic.
Encouraging article on the left-leaning pop-science email service yesterday confirming what many thought about the duration of protective immunity. Strange this gets little attention in the doom-mongering media but I guess it suits politicians' agenda. I do think those who've recovered should be put towards the back of the vaccine queue to free up space for others https://theconversation.com/covid-19-immunity-how-long-does-it-last-152849?
I am not going to comment on the level of funding appropriate for the NHS going forward (beyond my pay grade) however it occurred to me that the C19 crisis of the past year has not exactly been a great recruitment campaign for the NHS. I don’t mean in terms of the job they have done but in terms of the stress of the job and the conditions that NHS staff have (or potentially have) to work under.
Will that lead to a need for higher (much?) levels of pay and better (short hours, longer holidays etc) conditions of work?
Michael
PS Great pre-amble today Paul.
Yet apparently the number of 18 year-olds applying to medical schools has seen a big increase.
I didn’t know that. Thank you. Nursing staff the same?
Certainly it is known that a lot of the GP population are in their 50s and they know they will need to recruit a lot in the next 10 years. In some ways GP conditions did improve as they no longer have to cover 24 hour cover personally. But the latest challenges and the increasing time needed to deal with an ageing population often with complex multiple medical conditions will I think mean that more have to be recruited than currently. I would think it will be more difficult if the working conditions aren't seen to improve in some way.
My wife left GP 7 years ago and does not want to go back.
You are constantly berated for being so highly paid with the DM quoting salaries of a couple of very senior partners and everyone assuming all people are on that, work very hard, you are a gate keeper and everyone assumes with a search on their phone they know more than you as "Dr Google says..."
That is without having to manage the complaints and wondering when you will get the next malpractice law suit against you...
Rant over
GPs do an amazing job and need thanking more, she is a loss to the profession but has now finished phase 1 of her retraining to go into mental health with the NHS and is practicing again so that all the cost of her training is not lost and some patients get the benefit of her help every day, well Monday to Friday anyway :)
I agree. There will be a lot of NHS staff leaving this year ...... and even if domestic training and recruitment is stepped up this will take years to come through. This will then mean in the short term a lot of filling by (expensive) agency staff plus high levels of overseas recruitment on new post Brexit temporary work visas .....further slowing COVID response in the countries they come from.
As investors, we should look for firms offering to automate/simplifying/make easier/make quicker all medical, care and nursing work ! So not not just digitalisation but machine assisted routine-task care (not 100% robots looking after grannie before anyone starts!!). For instance, I keep seeing videos of 7 staff being required to manually flip a COVID patient in hospital and staff in care home having to lift people from chairs. Lifting patients all day would not attract even a more caring me - and I am 1.8m/90kg. What a job if you are 1.5m/50kg like many nurses and 50+ like many in the adult care sector..
Purely imho, but the current model for delivery of medical care in this country looks over centralised to me, with too much medicine being channeled through hospitals, all being run by a single organisation. Because the amount of medicine that can be done is increasing all the time, they are always running at the limit of capacity. To solve this, you need to diversify the model of how medicine is delivered, so that much more is done before people end up in hospital.
As investors, the future is surely going to see more medicine being delivered out of hospitals. To take the obvious example, which is the better way to address the risk of a future Covid - have more hospitals, or create the capablity to produce and deliver a vaccine quickly?
The Dr Martens' float was covered in the FT yesterday.
Many reader comments highlighted significant increases in the price of the footwear allied with a decline in its quality ever since PE got its hands on it. I believe they're all manufactured out in China now.
Ah, the ol' trick of milking the Brand Equity for short term revenue and profit gains :)
Just in time to dress up the financials for an IPO, to find out only a few years later that they weren't wearing any pants.
One question I asked last night which didn't get an answer and I have spent time trying to establish is does anyone know how a retail investor might get exposure to Long Volatility. Given the risks of inflation and shocks I am looking to diversify specifically with Long volatility and Commodities but in both cases it seems hard to get access unless you are a professional investor. Any positive thoughts much appreciated.
I really know nothing about trading volatility but I can see on my Eqi account that there are various ETF's that appear to go long and short of the VIX index. Also they have many commodity ETF's and I hold a long on one involving grains.
I had a brief think about this and looked at the ETFs, but they're all leveraged and suitable only for day trading.
I decided that the best option for me was the one that I had already adopted, which is to have exposure to the companies that benefit from volatility - e.g. IG (I hold), PLUS, etc, and possibly platforms such as HL.
I think if you look at Eqi you will find one or two that are not leveraged.
hi Camtab - for hard commodities, you have to build a view (''have precious metals run most of their growth, now its about industrial metals'' for example?) then either find a company (many on LSE) or go ETF route (many WisdomTree or iShares products for example, leveraged up to 3x mostly calls and puts)..or you could go passive with the respectable CQS Natural Resources Growth & Income (CYN)...hope that helps as reasonable advice? rgds Phil.
Thankyou guys.
I really enjoyed Mello too, first one I have attended and ordered the book so they did pretty well out of me last night!! Two things for me, 1) mentioned likely Govt will remove business rates from high st and replace it with tax on online business - for all you holders of Boo is this a concern? 2) I really enjoyed the BASH session. 3) Whilst I felt the response was a bit PR ish it was good to see a company respond to criticism re the LTIP which is a good sign for Mello. Happy to sign up for full year.
A very detailed Half-year report from Games Workshop (LON:GAW) out this morning which on the face of it looks very good.
The market seems less than impressed and I wonder if it's because of the statement.
After making appropriate enquiries, the directors have a reasonable expectation that the Group has adequate resources, in light of the level of cash generation, to continue in operational existence for at least twelve months from the date of approval of the condensed consolidated interim financial information
I know with a PE of 32 there is little room for lacklustre growth (Unless you are Tesla) but is it the lack of growth in the last six months that has disappointed investors?
Would be interested in hearing outers thoughts as I am still at learning how to interpret the updates like this.
"After making appropriate enquiries, the directors have a reasonable expectation that the Group has adequate resources, in light of the level of cash generation, to continue in operational existence for at least twelve months from the date of approval of the condensed consolidated interim financial information"
I think you'll find that's standard wording to demonstrate that they consider the company is a going concern and nothing to worry about. Their dividend payments should give you a more granular perspective on their cash generation.
I was also surprised by the drop, fortunate to take some profits a couple days back. Unsure if this is a buy opportunity or a plateau. Appreciate thoughts from others
I was surprised by the drop too. All of the numbers look excellent, with the single exception of the slight drop in royalty income in the period, although this didn't seem to drag down what otherwise seems an sizeable increase in overall profit.
hi Rhodie - might be a few large sellers as Volume so far is 96k8 compared to daily avg. of 89k3 so NOT a mass walkout. But a bit concerning (I hold), in the wake of 2 days market taking a mini-breather..
Hi Vader. I think the market reaction was simply because Games Workshop (LON:GAW) have consistently under promised and over delivered and this half year report was pretty much exactly as signposted in their more recent update. It's priced to perfection so a little profit taking was to be expected given the few slightly negative snippets contained in the report. The one you highlighted I think was a pretty standard boilerplate Going Concern statement and nothing to be alarmed about. The few snippets that perhaps have spooked some might be:
"Our internal measures are being met with the exception of 'out of stocks' which are currently running higher than we'd like."
The ERP project appears to be challenging with a new third party appointed to "help achieve the completion of this long and complex project".
"Royalties receivable in the period decreased by £2.0 million to £8.7 million".
"If current sales trends were to continue for the full year we would have c. 50 stores which would not break even."
"During December our warehouse capacity in Memphis was on occasions stretched to its limits and despite an incredible team performance our service levels were not as great as we would have liked"
IT seems to be a little problematic and has been mentioned in previous reports: "..with a number of significant business projects in play, all of which are dependent on IT support.... We are currently reviewing the structure of our global IT team to ensure the IT support needs of the business can be delivered. This review will be completed and implemented in 2020/21."
Finally the one that has probably caused most anxiety would be this one: "Sales for the month of December are broadly in line with our expectations." Given that December is a key trading period for them ("The Group's monthly sales profile demonstrates an element of seasonality around the Christmas period which impacts sales in the month of December") then it might be flagging the start of a slight slowdown perhaps going forward?
Personally, I'm a long term holder and will continue to hold because it's fundamentally a superb cash generative business with high margins, superb management and clean accounts. I expect the recent frothiness to ebb away and perhaps the price will settle back below recent highs but longer term I see only sunny uplands!
Thank you for such a detailed answer it's certainly been educational and helpful to get yours and other respondents views and thoughts. So kind to take time to do such a thoughtful answer.
Thanks for your insight. What I took away from it was that sales continue to accelerate 25.8% now compared to 18.5% growth (1H to Dec 19), Profit 55.4% compared to 43.6% growth (1H Dec 19), and there is still demand out there that they couldn't fulfil due to production and warehouse capacity, which they are working to address. The analysts forecasts only have FY profit at £98.17m for full year, which seems light given that they declared £91.6m before tax for the 1H. Also agree with you that cash generation looks great, margins strong and growing. I hold and will continue as Rule number 1 is don't sell Games Workshop (LON:GAW), Rule number 2 ...
Re £GAW I generally run for the hills at the first signs of problems with ERP implementations. In this case they could charitably be described as growing pains as they struggle a bit to scale their IT systems and distribution to match the increasing business. Could be a few bumpy months ahead, and decent consultancy will be expensive and not an area to penny pinch on.
Paul, some good observations there, thanks. I have said before that the new case figures are not comparing like with like ( huge increase in number of tests as time has gone on) so the only useful figure is hospital admissions which is not widely used. My concern is that the government will be uber cautious in March/April/May and we will have some kind of restrictions, probably rightly so, for some time.
Can you imagine if the Pub opening ban was just lifted? You wouldnt be able to move in any Pub in the country for weeks and the same would go for many other types of Leisure/Service/Travel venues.
Accrol Group (LON:ACRL) H1: strong cash generation, reduced net debt. FY21 at least in line with expectations. They restore the dividend.
The great management team are making strides. Investor presentation Friday 15.1.21, 1.15pm. With Dan Wright, Executive Chairman, Gareth Jenkins, CEO & Graham Cox, MD Tissue Division, who will present followed by Q&A. Register here.
Corona viruses are all highly seasonal. Sampling results as below.
So why is South Africa’s second wave in the middle of their summer?
Unfortunately, given the new mutation, the answer may be: wait until it gets to winter there!!
I think high levels of a highly infectious COVID with no prospect of widespread vaccination imminent is (one of) the factors holding back recovery of Norcros (LON:NXR) to previous levels which otherwise should be benefitting from a UK DIY boom / vaccine rollout.
herbie47
Hot weather doesn’t seem to help much going by the high cases in India and some other Countries where the weather is never cold. Also apart from extreme south of South America, and to some extent the South Island of New Zealand (along with sparsely populated mountainous areas) Southern Hemisphere Countries don’t have a winter. The drop in cases in Northern hemisphere summer might have been coincidal.
These are all common cold covid viruses, causing upper respiratory tract infections, which everyone knows are seasonal. Covid-19, which is the problem, is SARS-Covid, and causes far more serious lower respiratory tract infections. So this graph tells us absolutely nothing about the seasonality of SARS-CoV-2 (Covid 19).
So this graph tells us absolutely nothing about the seasonality of SARS-CoV-2 (Covid 19).
Scrolling past it is very good exercise for my right index finger on the mouse wheel though :)
All the best, Si
They were a lot less harmless before they became endemic. https://en.m.wikipedia.org/wik...
Gamesys (GYS) pre close update today very positive in hot sector at the moment (online gaming) your views Paul would be much appreciated
Derek
Sdi (LON:SDI) Positive Update:
SDI Group is an AIM-quoted group specialising in the acquisition and development of a portfolio of companies that design and manufacture products for use in digital imaging and sensing and control applications in science, technology and medical markets. Corporate expansion is pursued, through organic growth and the acquisition of high-quality businesses with established reputations in global markets. The coronavirus pandemic has weighed on most group businesses, but one-off COVID-19 related contracts have significantly boosted sales of two product lines and growth has been enhanced by the recently announced acquisition of Monmouth Scientific, leading us to forecast 33% revenue growth and improved profitability in the current financial year, with cash generation also expected to remain strong.
Hi Camraid, for a moment there I thought I'd missed a TU but can see this is a research note about Sdi (LON:SDI) from Progressive. https://www.progressive-resear...
(I hold)
cheers
Francis
Sorry fwyburd - my bad terminology.
For the sake of accuracy, this is not an update, it is the publication of a bit of paid-for research.
Grumpy5 - yes my bad terminology. It is research but positive nonetheless. I think there will be accretive acquisitions going forwards and I do think the PER will move towards Judges. Increased earnings and an increased PER is good. I hold so I am happy with the research.
Paul : You and the readers may be interested in this very recent 30 min video presentation targeting US investors by the CEO of Angle (LON:AGL) I understand they are looking to list on NASDAQ . Interestingly, this morning they have announced the appointment of PricewaterhouseCoopers LLP ("PwC") as their new auditor. Disclosure – I hold.
https://www.youtube.com/watch?v=dmihuELlhDM&ab_channel=ANGLEplc+with+thanks+to+Rhydian+on+Telegram
I have been following Angle (LON:AGL) for some time and am disappointed to have missed the recent bounce. Andrew Newland is a tremendous evangelist for their product and what is a truely innovative approach to capturing circulating tumour cells (CTCs) and therefore being able to treat a cancer better without the need for tissue biopsies.
The difficulty seems to lie in massively changing the way in which the clinicians currently do things; overcoming the inertia of the medical profession. They appear to have needed to spend many millions in this effort and are now resorting to setting up their own labs to undertake testing and show what can be achieved - an expensive exercise.
As to FDA Approval, it seems bizarre to me that it's necessary for what is a physical process; separating cells which is clearly demonstrated to work and is completely different from injecting some concoction of molecules (drugs) into a patient.
So the question in my mind is just how much more money will they need before the market comes round to their way of thinking and is there a danger that some genetic analysis technique applied to blood will render the need for individual cells redundant.
A similar scenario exists in the case of Shield Therapeutics (LON:STX) (entry level holding) but there the case for change is even more self evident.
PS The great thing about Youtube videos is that you can speed them up: settings>Playback speed which makes watching such presentations take half the time.
Re Angle (LON:AGL) I hold a US company in the same liquid biopsy field - Guardant Health. They have been in a sharp uptrend in the last few days also so I wonder if there is some corporate activity expected?
My impression is that GH are more advanced in terms of FDA approvals and partnerships with drug companies to offer individual therapies. But I'm no expert in the area so happy to be corrected. I just bought some GH back in 2019 because I thought it was an exciting idea and they seemed to know what they were doing and it's been an easy share to hold. I'll look into buying a few Angle (LON:AGL) as well.
Thanks John, it was GH I was thinking of when I mentioned the threat of "some genetic analysis technique". What would be interesting to know would be whether GH's approach of "Obtaining clinically relevant genomic information through a blood draw" makes the need to harvest individual cells redundant. Or could the inividual cells be a better source of such genomic data?
So I've sent an email and will share any reply I receive.
Thanks Quilleron, will be interested to read any reply you get. I had wondered whether Angle's shares were going up simply because we were in the New Year and getting closer to the FDA decision date. This was earlier stated to be by the end of March at the earliest. However, I have just started watching the video posted by JimMcLad where Andrew Newland states the earliest is now end June.
Of the companies I know in the liquid biopsy area, my Guardant shares are up similarly. Their market cap is now $16bn. Illumina are buying Grail for $8bn. Foundation Medicine were bought by Roche in 2018 at a $5.3bn valuation.
Angle is clearly an early stage pre real revenue tiddler by comparison and still needs to satisfy the FDA that it's superior technology works. I doubt I would have had Jim McLad's patience or foresight to hold since 2014 but I can see the attraction. If these big boys can do what they do with fragments of DNA then they must be able to do a lot more with complete cells - RNA as well as DNA.
John
Thank you for the kind use of ‘patience’ and ‘foresight’. I’ll accept the latter – the former was a mistake – until now. I take the view that FDA approval is almost a given as they have been working closely with Angle (LON:AGL) on what’s required in the submission as it’s a first for them as well. Bit embarrassing for them if they delay.
I got the link I posted from an ADVFN blog.
https://uk.advfn.com/stock-market/london/angle-AGL/share-chat
There are several sensible posters as well as the usual few troublemakers. There’s been a lot of mention of US companies and their fields of expertise as well as their comparatively huge valuations. The obvious hope is Angle (LON:AGL) we be rerated when US investors join in.
Hi Quilleron,
The YouTube video that JimMcLad linked above answers this query. It's well worth watching the whole thing but the relevant slide is at 10.35.
Andrew Newland says that Guardant and others only capture fragments of DNA from dead cancer cells whereas Angle's Parsortix system captures whole living cancer cells as well as clusters of cancer cells that are thought to be associated with metastatic spread. That must offer superior possibilities in research and in diagnosis. He also talks about the potential for them to form partnerships with other companies in the field as well as drug companies.
I bought an initial stake this afternoon.
Hi JohnEustace,
You beat me to it – I was intending to review the video as I was sure AN mentioned the DNA / RNA scenario and stressed the Angle (LON:AGL) approach was superior. Welcome aboard – I’ve held since 2014 and periodically topped up. As of today I’m breaking even !!
Quilleron : Like yourself, I have no idea why a food and drug agency should be involved but I have to assume the people at Angle (LON:AGL) know what they are doing. For example, they have had to show the device does no damage to the CTCs and clusters rendering further analysis void but even then why FDA ?
Medical inertia may be an issue but I think the huge improvements possible in patient diagnosis and treatment coupled with the enormous savings available to health boards will force change.
A positive Q3 trading update from Appreciate (LON:APP) this morning (I hold) - a company which sells retail gift vouchers for consumers and businesses to reward staff. Unlike a lot of shares it seems, its share price hasn't recovered to anywhere near its Jan 2020 level with the potential for nearly 100% upside and lock in a divi of around 3p if that happens so I am continuing to monitor this with interest. There has been no shareholder dilution during the pandemic - it agreed a new unsecured credit facility with its bank.
This morning it says Q3 (Oct-Dec) has seen strong trading as businesses sought to reward employees and probably had fewer options to do so this year with lack of Christmas parties or being able to provide physical gifts so easily. YoY billings up 13% with a strong performance in December of +41% YoY. YTD to September had been -40%. As this is a key trading period it means billings for gift vouchers now down -7.3% YTD (April-Dec) which isn't too bad.
The company says it expects to finish the year 'at least in line with the mid-range scenario as set out in its 2020 annual report and accounts'. At the HY mark when they said performance remains 'ahead' of its mid-range (note the slightly different language though) the broker edison put the FY21 EPS at 1.9p and 3.1p for FY22 so I am assuming those figures remain but will keep an eye for broker upgrades.
The company holds large amounts of cash for its Christmas savings product so unfortunately when interest rates are low it earns lower interest on this - which partly explains why the EPS predications aren't higher following the pandemic reduction in interest rates and threat of negative rates.
In the immediate term there is probably not massive upside here after the rise this morning but historically it has traded 11-15x EPS and with a likely return to a decent dividend I think this should be closer to 40p at a minimum and is a good long-term value hold.
The Appreciate (LON:APP) update talks mainly about "billings" and reports Q3 billings up 13.1% and December's billings up 42% to their highest ever monthly level.
The company consistently uses "billings" as its preferred measure of performance because revenue is reported differently depending on whether the product is single retailer or multi retailer (2020 AR, p. 77).
Revenue is recognised when the card or voucher is redeemed (2020 AR p. 76). For so long as non-essential retail is shut, redemptions are bound to be depressed.
The TU says "The Group is expected to deliver a full year performance for the year ending 31 March 2021 at least in line with the mid-range scenario as set out in its 2020 annual report and accounts, although the latest lockdown measures may delay some revenue and profit until customers have more options to redeem their products."
I read this (perhaps wrongly) as saying that the billings are well ahead, but the revenues are liable to be lagged because of lock-down.
Since billings are the bit of the business that is under APP's influence, this seems to me a more positive update than the market is recognising.
Liberum have raised 2022 and 2023 forecasts (to 3.5p and 4.4p) but leave 2021 forecasts unchanged at 2.1p. (The tables to their note seem to have confused the column headings.)
If I'm right, I think the accounting treatment at Appreciate (LON:APP) is only to recognise the revenues and profit when the gift cards are used in stores?
So the billings number they play up in the update is just forward sales / deposits.
Seems to have done OK on cash terms. £33m at end Dec compared to £30m at end March. Hard to compare as their cash balance is strongly seasonal. No trading update last year in Jan.
I sold out of £APP recently at a small loss, when the news of more stringent lockdown came in. Inevitably, gift cards are associated with retail and customer facing businesses undoubtedly have been suffering and will continue to suffer.
Additionally, a lot of retail chains are dropping off like flies. Which uncle, auntie, grandpop or grandma or company, would want to give my gift cards of a retail shop that might go close down. Therefore, your choice of retailers are limited. 3rdly, the widest selection on ilovetoshop is in-store cards., leaving revenue to be primarily generated during this period from e-gift cards - this leaves a smaller choice for buyers again.
Overall, obvious that PIs are very buoyish on recovery that the vaccine will work - Shoe Zone (LON:SHOE) ' SP doing well , £RBP has picked up , Escape Hunt (LON:ESC) has picked up whilst opening is far far off. Good luck!
My morning smallcap tweet:
Circassia (LON:CIR) Robert Walters (LON:RWA) Filtronic (LON:FTC) THG (LON:THG) Woodbois (LON:WBI) EKF Diagnostics Holdings (LON:EKF) Distil (LON:DIS) Franchise Brands (LON:FRAN) Belvoir (LON:BLV) Appreciate (LON:APP) Intelligent Ultrasound (LON:IUG) Curtis Banks (LON:CBP) Accrol Group (LON:ACRL), Carr's (LON:CARR), John Menzies (LON:MNZS)
Circassia (CIR) guides FY(Dec) rev-cont £23.9m down 31% due to covid causing restrictions in routine FeNO testing. Q4 down 14%. "On current gross margins this means that the EBITDA breakeven point for the Niox business will be lower than previously indicated at around £30m of annualised revenue, or £32m for the Group." [SP=29 Cap=115m]
Robert Walters (RWA) guides FY (Dec) profit likely to be ahead of mkt exp. Q4 net fee income down 24% in £ cf Q3 30%. "Market conditions do still remain challenging however there were signs of improvement in forward-looking indicators, particularly in Asia Pacific, the Group's largest region." [SP=460 Cap=350m]
Filtronic (FTC) wins 1 year contract for over £1m from new major UK defence customer. [SP=8 Cap=17m]
THG (THG) Q4 rev up 51% cf guidance of 40% to 45%. Cites especially strong performance in THG Beauty and increasing momentum in Ingenuity Commerce contract wins. Guides FY rev up 30-35%, up from 20-25% guidance. [SP=790 Cap=7668m]
Woodbois (WBI) guides FY(Dec) U/L profitability ahead of expectation (whose?) prior to any write-down of inventory. Rev in line. $2m of inventory discovered stolen from third party warehouse in Ivory Coast post period end. Covid caused delays mean FY21 rev target is unchanged at $60m+. [SP=3.1 Cap=44m]
EKF Diagnostics (EKF) guides FY(Dec) comfortably ahead of already upgraded market expectations and Q1 2021 materially above management expectations. Will pay div and expects to implement a progressive dividend policy. [SP=72 Cap=328m]
Distil (DIS) Q3 rev up 22% despite relatively muted Christmas and New Year celebrations. TYD rev up 70%. Launches Botanical Vodka. [SP=2.2 Cap=11m]
Franchise Brands (FRAN) guides FY(Dec) revenue, adj EBITDA, and adj EPS ahead of market expectations of £48.6m, £6.1m, 3.87p resp. B2C frachisees down 18 to 386 due to trading difficulties, mainly in the Barking Mad network. [SP=100 Cap=96m]
Belvoir (BLV) financial services division update: FY rev up 13%, pretax up 26%. [SP=156.02 Cap=55m]
Appreciate (APP) Q3(Dec) billings up 13%. Guides FY(Mar) at least in line with mid-range scenario guidance. [SP=32 Cap=60m]
Intelligent Ultrasound (IUG) guides FY(Dec) rev down 11% and op loss £4.1m and £4.2m (£4.6m). Expects first sales from its Clinical AI division in H1. [SP=15 Cap=40m]
Curtis Banks (CBP) FY(Dec) trading 'robust' says CEO Will Self, probably not the acerbic author. No numbers [SP=225 Cap=149m]
Accrol (ACRL) H1(Oct) rev down 4%, pretax -£0.5m (-£3m). Reducing net debt faster than anticipated. Guides FY at least in line with market expectations. [SP=73 Cap=227m]. I hold.
In line: Carr's (LON:CARR) John Menzies (LON:MNZS)
DMs (Dr Marten's) used to be a good shoe/boot my oldest pair is circa 20 years old. Then they became an expensive poor quality fashion brand, which all my kids started wearing over a space of a few years.
If you miss the old DM quality do try NPS - Solovair they are made in the old DM factory with the original quality for the same price as today's DMs.