Small Cap Value Report (Tue 12 March 2024) - CVSG, PETS, RENX, HAT, SHOE, SYNT, TCAP

Good morning from Paul & Graham!
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. OR it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom),
Paul's 2023 share ideas, with live prices.
New SCVR summary spreadsheet from July 2023 to date, updated at weekends (very useful quick reference tool, search for ticker using CTRL+F). Hover over cell for pop-up notes.
Frozen SCVR summary spreadsheet for calendar 2023.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Other mid-morning movers (with news) -
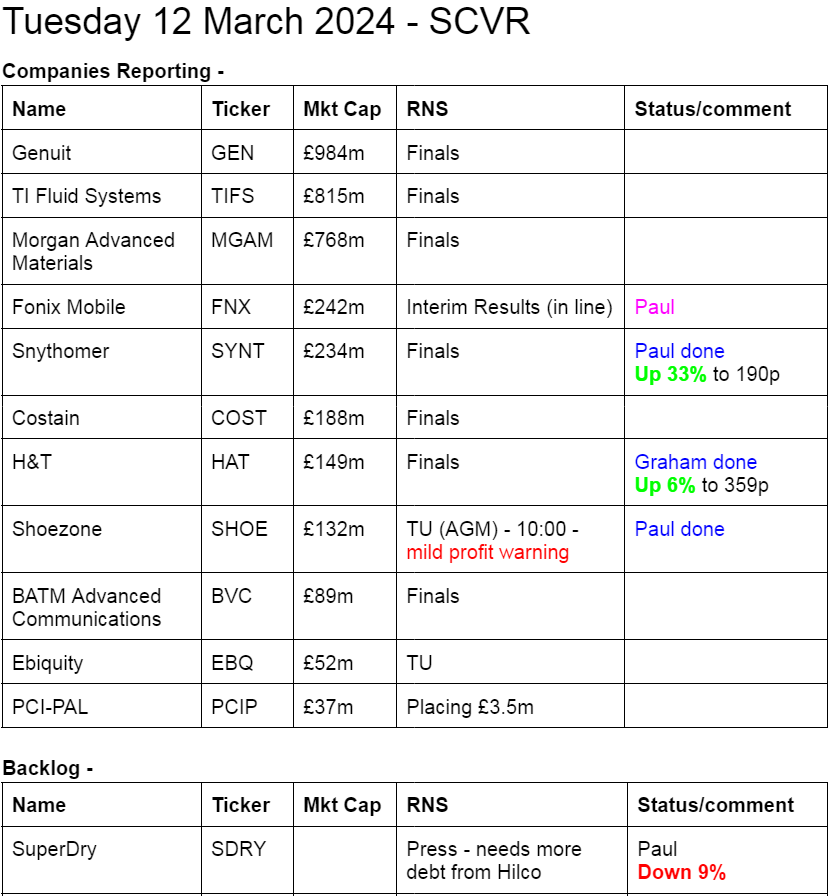
CVS (LON:CVSG) - down 19% to 1178p (£875m) - CMA Report & Response - Paul - AMBER
I’m pleased to see the CMA has issued a report titled “CMA identifies multiple concerns in vets market”, and provisionally says it should launch a formal market investigation. Concerns are: inadequate info, weak competition due to sector consolidation, large corporates acting in ways that weaken competition, overcharging for medicines, outdated regulatory framework.
The CMA says it has powers to “intervene directly in markets” if action is required, which includes requiring disclosure of more info, max fees on prescriptions, and ordering disposal of assets/businesses. That last point could be a threat to market leaders, CVS and MediVet. The CMA does have teeth, eg this case where I recall it forced JD Sports to reverse the acquisition of FootAsylum.
Paul’s view - CVS says it has proposed a package of “possible remedies” (no details), which to me implies that it admits there are failings in the vets market, and probably wants to limit the damage! So people buying/holding CVSG shares now are effectively guessing that any actions from the CMA won’t impact its profits or expansion much. The valuation has been hit hard in 2 sharp falls, with the fwd PER now being c.12x. Note CVSG has almost nothing in NTAVs, so there’s no balance sheet support. All up in the air now, so I cannot value this share, but given it’s already almost halved in price this year, I can’t really flag it as red, so I’ll go with AMBER - it's up to you to decide if the risk is now in the price?
Pets at Home (LON:PETS) - down 7% to 257p (£1.22bn) - no announcements yet from the company, but shares continue the downtrend, no doubt impacted by the CMA announcement mentioned above. It’s a different business model from CVSG though, with vets being only a part of PETS operations, although it would be interesting to know what proportion of its profits (as opposed to revenues) comes from its vets operations? Do leave a comment if you have that information to hand. PETS shares look quite attractively valued (fwd PER c.12x, and a generous c.5% divi yield). So there might be value to be had here, once the outlook becomes clearer on any potential damage from the CMA.
Renalytix (LON:RENX) - down 30% to 28p (£28m) - Discounted placing - Paul - RED
Announces a £7.8m heavily discounted placing at 20p, which will enlarge the share count from 100m to 139m shares. It’s nowhere near enough for this prodigious cash burner, and will only keep the lights on “into Q4 2024”, as opposed to running out of existing cash next month. This is a disaster, but SCVR readers hopefully won’t have been sucked into this share with the recent rampy announcements which caused a spike up in share price, because we vigorously rang the alarm bells here 3 times recently saying it was bust without a fundraise (which was blindingly obvious, to be fair), here on 15/2/2024 RED, 29/2/2024 RED, and 4/3/2024 RED.
It’s certainly not out of the woods, and another fundraising is likely to be in the pipeline before the ink has dried on this one. Bizarrely, it’s listed on AIM and NASDAQ - how much does that cost?!
The company is clearly in a very weak negotiating position with anyone prepared to advance it more cash being able to name their price. So it’s now just a gamble on survival, and/or that someone might take a shine to the technology and bid for the company. Personally risk:reward looks terrible to me, and it’s looking a lot like yet another failing cash burning blue sky project that proliferate on AIM unfortunately. It will be interesting to see if Christopher Mills (10% existing holder) took up any of the placing shares. Yet another example of why it's best to avoid blue sky companies that are running out of cash. As small shareholders we have a massive advantage - we can sell at any time. Whereas the institutions are high & dry with large illiquid holdings, and almost have to keep putting in more cash. So they can't afford to get it wrong, whereas we can salvage some money from our errors, if we're disciplined enough to sell. Mr Market provided two lovely speculative spikes for people to sell into recently too. It just doesn't pay to buy into story stocks, they hardly ever work out well.
TP Icap (LON:TCAP) - up 13% to 224p (£1.73bn) - positive market reaction to FY 12/2023 Results which it says is the highest ever EBIT achieved. PER is only 7.7x 29.2p adj basic EPS.
Says its Parameta Solutions business is “highly valuable” and not reflected in the group share price. Looking at exploring options, including IPO of a minority stake in it. Announces another £30m share buyback today. Total divis for 2023 up 19% to 14.8p, yielding an attractive 6.6%. Stronger sterling vs dollar is a headwind.
Outlook - comfortable with current market exps for 2024, and Jan-Feb were “good”. Impressive cash generation, funding generous shareholder returns. Bal sht is OK, c.£350m NTAV. Has lots of debt (bonds), but exceeded by its cash pile.
Paul’s view - I’m not familiar with TCAP, but a brief review of these numbers has really caught my interest. This is definitely worth a closer look - any readers looked at it in more detail? Why is it so apparently cheap?! I wonder if there might be any regulatory worries?
Summaries of main sections
H & T (LON:HAT) - up 5% to 357p (£157m) - Preliminary Results - Graham - GREEN
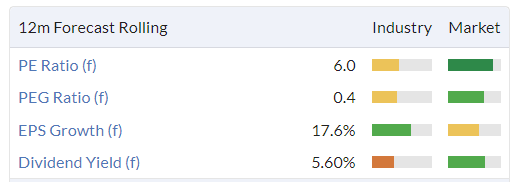
Excellent numbers here as demand for pawnbroking continues to soar. H&T continues to expand gradually into these booming conditions. Retailing is softer; the company has had to carefully manage its exposure to watches. At about 6x earnings I like this very much.
Shoe Zone (LON:SHOE) - down 8% to 260p (£121m) - AGM Statement - Paul - BLACK (minor profit warning) - GREEN on fundamentals
A minor profit warning "marginally below expectations" so far in FY 9/2024. Looks like recent flaky buyers on a couple of press tips are possibly being stopped out! We need an update from Zeus to quantify the shortfall. If it really is only a slight miss, then I'm happy to keep my positive view.
Synthomer (LON:SYNT) - up 30% to 186p (£298m) - Final Results - Paul - AMBER/RED
A big % riser today, but I'm far from convinced as to the attractions of this potential turnaround. Debt has halved, but is still massive, so no divis for now. Outlook seems quite lacklustre. Maybe brokers have increased forecasts, but that hasn't filtered down to pond life like us yet!
Paul’s Section:
Shoe Zone (LON:SHOE)
Down 8% to 260p (£121m) - AGM Statement - Paul - BLACK (minor profit warning) - GREEN on fundamentals
Annoyingly SHOE is one of a minority of companies who release their AGM trading updates when the market is open, so this came out at 10:00. It should be done at 07:00 so that everyone has time to digest it before the market opens. Note that it didn’t issue AGM trading updates in either 2023 or 2022, so it looks like this was released today due to trading being “marginally below expectations”.
Reasons given are (I’ve reformatted it to make a list) -
At this stage of our financial year, trading is marginally below expectations, due to -
a higher than expected increase in the National Living Wage,
an increase in container costs due to the ongoing situation in the Suez Canal,
higher costs associated with upgrading our property portfolio and
the impact of a slower than expected end to our Autumn/Winter season."
I’m surprised at NLW said to be higher than expected, because the increase was announced some time ago, so should have been budgeted for.
Paul’s opinion - a bit of a disappointment, but it doesn’t sound like a disaster. The share price has given up the recent spike, in the few minutes after the 10:00 announcement (I’m writing this at 10:17 with the mid-price currently 250p). I imagine the recent buyers were probably small traders, as it rose due to being tipped in the Times and a small caps tipsheet. Those type of buyers usually don’t stick around for long anyway.
We’ll have to wait and see what Zeus says, they usually helpfully update things after news.
At 250p I remain positive on this share, as the price has already adjusted for a slight disappointment. So I’ll stick with GREEN.
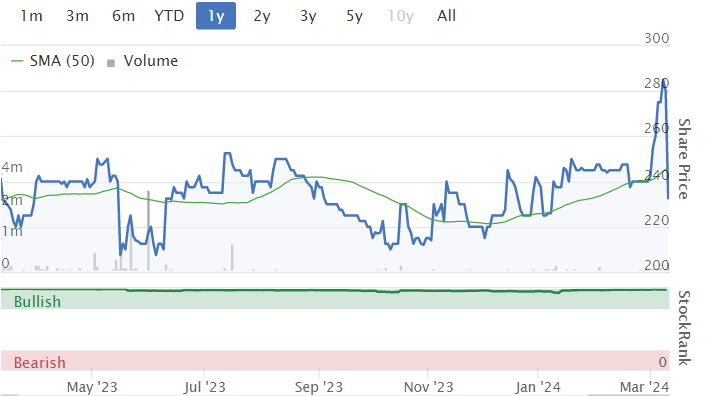
Newspaper tips spike eliminated today -
Synthomer (LON:SYNT)
Up 30% to 186p (£298m) - Final Results - Paul - AMBER/RED
I’m late to the party here, with a 30% rise today (at 10:48) in this chemicals group’s shares. Although after today’s surge, SYNT shares are still over 80% down in the last 12 months, and over 95% down on the 2021 peak. It got into serious problems with wildly excessivde debt (which we warned about here on 13/12/2022).
More recently, I reviewed poor H1 results on 7/9/2023, along with a large (£276m), discounted equity fundraise (rights issue) that still left it with excessive debt. There was a 20:1 share consolidation, as the share price had fallen into mickey mouse territory.
Has it turned the corner now I wonder?
FY 12/2023 Results -
A challenging year, but decisive actions taken for longer-term growth
Revenue down 16% to £1,971m
Underlying PBT is a loss of £(27.2)m vs a profit of £123.7m in (restated) 2022;
Statutory PBT is a loss of £(106.8)m! So large adjustments (mostly goodwill amortisation) don’t even get it into an underlying profit.
So far, this looks grim.
Balance sheet - net debt has fallen 51%, but is still large at £500m, well above the £298m market cap. Lenders have relaxed the covenants. Note that an EU fine of £38.5m was paid just after the year end, which will have worsened the net debt position.
Pension - a hefty £19m needs to be paid in 2024 into its UK scheme, although this involves some catchup amounts.
NAV is £1,162m, including £989m intangibles, so NTAV is £173m - quite thin for the size of company and heavy fixed assets. Gross bank debt is worryingly high still, so this business is entirely dependent on its lenders.
Cashflow - a strong comment here (but it depends how they measure free cashflow) -
in 2023 we were able to increase Free Cash Flow to £85.7m (2022: £69.2m). Important contributors to Free Cash Flow included £18.0m in cost reductions, £45.7m in lower inventories driven by both structural changes in approach and lower raw materials prices, and some other benefits.
Cashflow statement - interest payable consumes about a quarter of the operating cashflow, then capex is a big number at £84m - so clearly a capital-intensive business, rendering EBITDA meaningless.
Operating cashflow after interest and tax was £150m. £84m of that was spent on capex. So I would say free cashflow was £66m. The company’s headline says free cashflow was £86m.
The big reduction in net debt was mainly achieved from the £266m rights issue, and £190m from disposals (net of an acquisition).
Overall then, yes it did manage to generate some free cashflow, despite posting a PBT loss. It will need an improvement in performance to make any further significant reductions in debt, in my view. Or more disposals (several are pending), but that would have an impact on future profits, and I worry it might be selling off the best bits to raise cash?
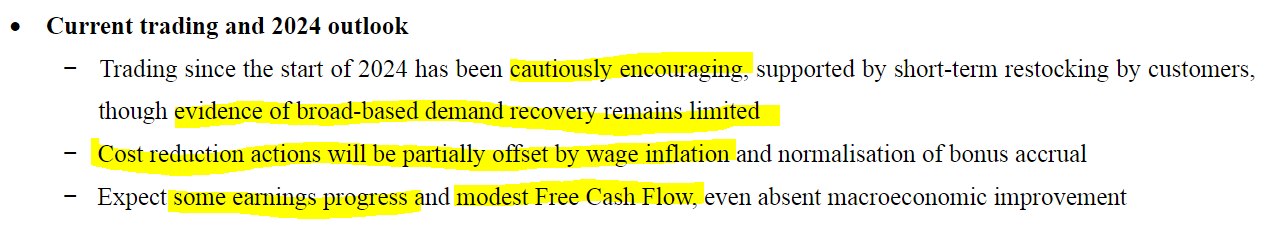
Outlook - hardly scintillating! -
… In the medium term, we remain confident that Synthomer's earnings power is more than double recent levels, through a combination of our near-term self-help actions, end market recovery and delivery of our speciality solutions strategy."
… In addition to further progress with our previously announced actions to reduce cost and complexity and to improve site reliability, we have commenced procurement and production cost optimisation programmes which are expected to deliver £30-40m in additional savings in 2024 and 2025. These actions will be partially offset by some increases in operating costs, mainly due to wage inflation and normalisation of bonus accrual.
As a result, we expect to make some earnings progress and be at least modestly Free Cash Flow positive in 2024, even if macroeconomic demand conditions do not improve.
That depends very much on what measure they’re talking about. Since it made a loss in 2023, does this mean the losses are going to double?! That’s probably not what they meant, but I would have liked more clarity on this.
Reducing leverage further towards our 1-2x medium-term target range remains a key priority.
Dividends are not likely any time soon, yes here they confirm -
The Board has confirmed that dividends will remain suspended at least until net debt: EBITDA is less than 3x.
Finance costs are huge, at £65m underlying - this turned an adj operating profit of £38m into an adj loss before tax of £(27)m. As the rights issue happened towards the end of 2023, with debt now a lot lower, I imagine finance costs in 2024 should reduce somewhat, but it’s still a very large number. So I see this as a business that is being run for the benefit of the bank, the employees, and the pension scheme.
More disposals are pending.
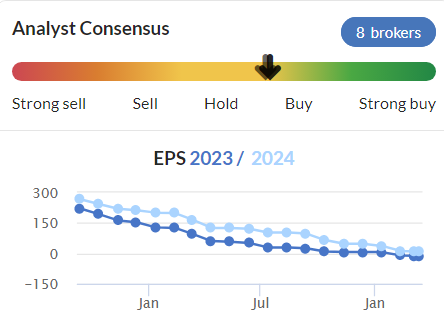
Broker notes - nothing available. Forecasts have been in a continuous decline, although given today’s 30% share price rise, maybe some top brokers (who don’t let plebs like us see their research, despite getting privileged access to and guidance from management) might have raised their forecasts? Let’s keep an eye on the consensus figures, which should update later this week, when we will belatedly find out key information that only the privileged have access to today. Level playing field? Doesn’t look that way to me.
Paul’s opinion - I must be missing something here. Based on the information available, I see a struggling, and overly-indebted business, with a fairly lacklustre outlook. Today’s 30% rise must be due to optimism that a turnaround might gather momentum when its markets recover, and the cost-cutting measures.
It’s a £2bn revenues group, so a pick up in its markets could have nice operational leverage.
I’ve got to flag the risk, so it has to be negative still, but given the change in market sentiment, and the big debt reduction (now just a large problem, not an emergency), I’ve decided to moderate my view from red, to AMBER/RED.
As we saw with McBride (LON:MCB) a dramatic turnaround in trading can have a wonderful geared benefit to the equity at highly indebted companies. So this share could see a similar effect, if trading strongly improves in future, which it might do as economies improve. Hence why my underlying view is amber, but due to the poor financial position, that tips it over into amber/red.
I’m quite surprised the market has taken SYNT shares up 30% today, it doesn’t seem justified to me, based on the information I have available.
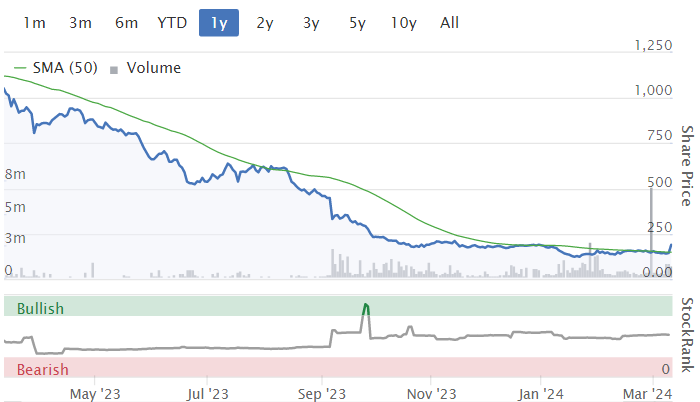
Today is only a blip on the 1-year chart though -
Graham’s Section:
H & T (LON:HAT)
Share price: 357p (+5%)
Market cap: £157m
H&T Group plc (AIM:HAT), the UK's largest pawnbroker and a leading retailer of high quality new and pre-owned jewellery and watches, today announces its preliminary results for the twelve months ended 31 December 2023 ("the period" or "the year").
These are sparkling results: PBT is up 39% to £26.4m.
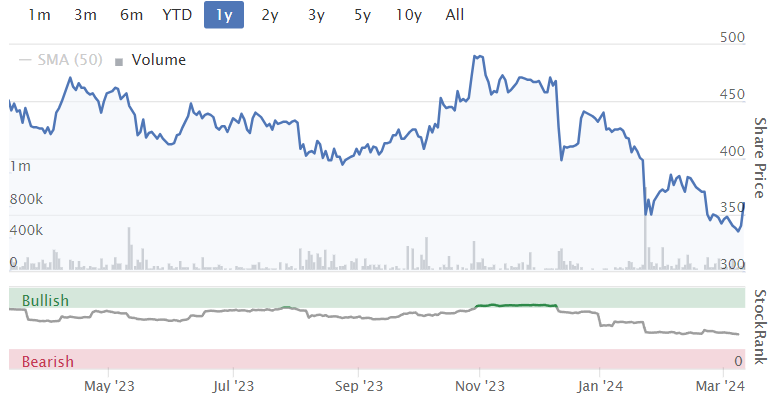
You might not have guessed this from the evolution of the share price over the past year:
Highlights from the major divisions:
Pawnbroking pledge book up 28% to £129m, with pawnbroking net revenue up 36% to £69.5m.
Retail gross profits down 19% to £14.4m
Gold purchasing gross profits up 26% to £8.6m
Foreign currency profits up 11% to £6.3m.
The explanation for poor performance in retailing comes back to watches (and maybe its exposure to watches is a partial explanation for the weak sentiment around this stock):
Margins were impacted by challenging trading conditions for certain watch brands in H1, and jewellery sales mix in H2, which includes the peak Christmas trading period.
Net debt finished the year at £32m (last year: £3m). I’ve said before that rising net debt at H&T is usually a good thing because it means the company is very busy, and that’s clearly reflected in today’s results.
The remaining headroom on borrowing facilities is £30m; that should be enough for anything the company might want to do in the short term. As we discussed last month, H&T has a new £25m loan from a company called Pricoa Private Capital.
Number of stores increases modestly from 267 to 278. Personally, I’d be happy with this gradual expansion in benign trading conditions - the business is doing fine, why take on extra risk with over-expansion?
Net assets rise to a new high of £177m. The company has typically been cheap on a price to book value basis, but that can be justified on the basis that ROCE/ROE haven’t been particularly high (financial stocks need high ROE to trade at a high premium to book).
The company is keen to reassure investors on that front: return on equity improves from 9.9% to 12.4%. “The Group remains committed to delivering on its commitment to achieve a target ROE of mid-teens through- the- cycle.” This is not something it has achieved in the past, so the jury’s out on whether it can be achieved in the future.
Full-year dividend is 17p (last year: 15p), covered nearly three times by earnings.
CEO comment:
Pawnbroking is our core business and is attracting increasing numbers of new customers. Throughout the year, we saw record demand for our pawnbroking service and this has continued into 2024, with January being a new record month for lending.
Whilst retail trading conditions, particularly in the fourth quarter, were challenging given pressure on customers' disposable incomes, sales increased year on year by 8% to £48.6m. Pleasingly, demand has remained robust in the early months of 2024.
Outlook is good:
We believe that demand for our core pawnbroking service will remain high as the ongoing impact of inflation on customers' disposable incomes creates record levels of demand for small sum, short term lending, at a time of severely constricted supply. We are also seeing growing demand from customers who are business owners, seeking finance for working capital against pledged personal assets and this formed part of the rationale for the acquisition of the pledge book of Maxcroft.
Further expansion of our store network remains a focus, although this will always be in a controlled and measured manner. It is likely that between 8 and 12 new stores will be opened in 2024.
Estimates from Shore Capital have been trimmed ever so slightly but are essentially unchanged, e.g. adjusted PBT for the current year is still forecast at £33.5m, rising to £36.7m next year.
Graham’s view
I’m still amazed by the volatility of watch prices over the past year. This article from December 2023 describes second-hand luxury watches as highly geared towards interest rates and economic sentiment, i.e. vulnerable to a bust in a period of higher rates and a weak consumer. A major index of watch prices (the “WatchCharts Overall Market Index”) fell 37%.
The Covid era of 2020-2022 saw an artificial boom in the watch industry; in hindsight we can easily say that it was primed for collapse whenever those conditions ended.
Fortunately, H&T has been proactively reducing its watch inventory and limiting its exposure to this situation.
Furthermore, watches are only one part of H&T’s retailing and lending operations, e.g. only 14% of pawnbroking loans are backed by watches.
Watches did represent 25% of retail sales for 2023 (up from 16%), and at reduced margins compared to historical norms.
For me, the big story is the unprecedented level of demand for pawnbroking loans, and H&T’s leading role in this as the biggest pawnbroker.
Where I’m uncertain is the company’s stated goal to achieve “mid-teens ROE through the cycle”. It hasn’t done this in the past and I’m not sure how it might achieve it in future?
One way to achieve this might be to use the balance sheet more aggressively, e.g. with further acquisitions. This wouldn’t be my first choice of strategy and it would require shareholders to be much more alert to any mis-steps.
As things stand, I’m happy to maintain my positive stance on H&T (as I’ve done with its rival Ramsdens Holdings (LON:RFX)). It’s not every day you find a company that was founded in 1897, posting excellent numbers, and trading at only 6x earnings. I remain a fan.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

136 comments
TP Icap (LON:TCAP) - [I hold] just completely mispriced based on a fundamentals basis with Parameta data provider worth most of the market cap of the entire business that they are now looking to unlock. Cash generation is significant allowing buy backs and a chunky divi ~7%. They had been facing headwinds from the Liquidnet acquisition but even that is now breakeven after action has been taken to reduce the cost base and put in place integration synergies. The current interest rate volatility is also benefitting the core business. It's worth watching the excellent fund manager interviews by Paul Hill on this company. I topped up yesterday before the results after the article in the FT and glad I did. I think the sale or listing of the Parameta business will be a major catalyst for the share price.
TP Icap (LON:TCAP) (I hold). I started a thread/discussion on TP Icap (LON:TCAP) on Sunday to highlight the potential upside to this share. I can’t comment on the accounts and I don’t know the company well but using the Stockopedia report, good news flow and clear technical base on the chart, I doubled my holdings yesterday. My initial target on the SP is 264p but could go much higher.
As I understand it the killer issue with used EVs is that there is no way to gauge the health of a battery. Their life is dependent on a number of factors, temperature the car operates in, what energy source the car is charged from, how much the battery is depleted, what % it’s recharged and whether there is any damage to the battery, and at present there is no way to gauge that…so how does anyone value a used EV? Clearly the answer is very lowly.
I’d imagine it’s easier to test the health of a battery than to test the health of diesel/petrol engine.
well the early adopters are the people who pay the price - however my research indicates 8 year 100k miles warranty seems fairly standard - after that you pay your money and you take your chance. So if you have 8 year warranty is there anything to worry about?
to me that works out fairly well
owner 1 gets brand new car for four years they hand back or part ex - second owner gets 4 years old car for probably close to 1/3 of the price on which they hopefully have 4 year warranty on battery giving them the piece of mind that they have at least 4 years.
After car is 8 years old probably like any 8 year old car - you could get a great deal or get a car that packs in the next day.
Obviously you want to have cars made so that it is practicable and not ott price wise to replace the battery if needs be - the actual cost of batteries aint outrageous - how that tallies with real world costs of paying garge to do the work i know not
https://bookmygarage.com/elect...
Have a look at my local Indy regarding this issue:
https://www.weissachuk.com/thi...
It looks like the Taycans also have the 8 year 100k miles warranty now - so i suspect the 55k quoted price is really simply made up number that suits their purposes for whatever reason whilst practicably speaking no one should at present have to pay that sum. I suspect they cant be bothered with the hassle of giving competitive quotes. Hey ho anyone who buys new tech like this kinda knows the risk they are taking.
Note in the real world the actual costs of the battery packs themselves are a fraction of the price of the silly figures quoted per your link. Ok actual price is probably double that once you factor in paying someone to do it.
https://bookmygarage.com/elect...
I guess thats where the rub lies when chosing one of these vehicles - can you find a garage that will replace the pack for that car type at realistic price if it needs doing ? - the market in that regard should be expected to be in its infancy if everything is mostly still under warranty . Presumably some cars are designed so that pack can be replaced whereas i suspect some are probably designed not to make that task over easy - perhaps regulation in that area might help.
Georgia Capital
Looks like the elastic has finally snapped and now going to play catch up with Bank of Georgia .
Always mystifies me how they don’t move in sync and by my reckoning Georgia capital should move up to circa 1500 and stabilise for a while .
The disconnect Planetx is strange. I hold. Keep meaning to create a chart to monitor the relationship.
Pets at Home (LON:PETS)
Hi Paul
You asked about the Retail/Vet profitability splits for Pets at Home (LON:PETS) .
I'm going to start from the top if that's okay as the Vet Business is split between Company Managed and JV's and I think it's good to see the detail.
----
Below are figures up to FY22 and FY23, split between:
The 17.0% I've circled is the % of JV Consumer Revenue that ultimately turns into Revenue for the company.
For FY23 this ended up being £77.2m, which I assume is mostly profit.
---
I don't want to bore people with the details of the next line, but Vet Gross Profit was actually only £65.6m i.e. less than the aforementioned £77.2m.
Unless I'm missing something this implies that the Company Managed Veterinaries & Vet services are actually loss-making...or yet to reach maturity...or are being apportioned a large % of the rental costs...or something else I haven't thought of.
Ultimately there doesn't seem to be excessive profit here.
---
And here are the profitability splits.
I think it's worth pointing out that there were a lot of one-off costs in the Retail PBT figure in both FY22 and FY23 e.g. a new Distribution Centre, digital investments, etc....
I hold with an expectation that these one-offs will drop off over the coming 12-18 months, and Retail will almost certainly become a larger proportion of PBT in the short term.
Pets at Home (LON:PETS) think also worth mentioning that they are facing increased competition for private equity backed Jollyes - I understand they plan to expand quite aggressively as a cheaper alternative which I suspect could do well. I would definitely want to look more into this if investing in PETS as TDR have very deep pockets.
jollyes-secures-investment-to-supercharge-its-next-phase-of-growth
H & T (LON:HAT) oh no, I've lost my post on FY23 results from this morning, and in the meantime it's been well reported on here. As Graham says, and the SP reaction shows, very good results. There is a management webinar with Q&A on Friday at 12 noon. Register here.
Good and bad news with ESG tailing off. Good to see people losing interest. Bad as the ESG section was just the right length during presentations to make a cup of tea.
big volume on Motorpoint (LON:MOTR) today + first shares bought back in buyback program
Interesting article in the Mail today about Electric Vehicles. Dealers very reluctant to take in Part Ex because of falling prices.
One gent offered £27k for his 18 month old Jag I Pace with just 5k miles which cost him £77k.
This may interest holders of Vertu Motors (LON:VTU) and other holders of big players in the Motor Industry.
this has been the case for a couple of months now so most certainly isnt "new news" - ref £VTU it was the first thing i looked for on their recent update and on the face of it looked like this wasnt a big issue for them. Note i suspect they are covering themselves and offering stupidly low values so they cant becaught holding the can of a batch of cars that depreciate quickly - i suspect they may be partly to blame for low values if peeps are that desperate that they take what is on offer.
Its gone from the ridiculous position of porsche taycan being worth more than list price after 6 months 18 months ago - to depreciating faster than your average new man united signing (50% reduction after 6 months).
hey ho - possibly some decent second hand deals around as a consequence?
Yes, I am in the market, although whilst I have owned EVs and would have one back in a heartbeat, the taycan or cross turismo I fancy costs 55k to replace the batteries if they fail and many dealers aren't offering a warranty longer than a year and the lifespan of them are circa 8 years. Whilst I have no doubt that the batteries will last longer, buying a 4 year old car, which I was going to do, may come with big bills in the not too distant future (hybrid and electric car battery replacements are approx 30-50% of list price).
As a result I'm looking at an XC90 (diesel) as I've never owned a Volvo, and their prices have plummeted too. Given I work from home and walk more miles than I drive, I can't justify shelling out 50k for something that may bite me in the bum (and I have a normally aspirated 911 too).
Cash is king, but some excellent finance offers out there insomuch, if you take finance then you can go on a service plan for free, longer warranties, MOT's etc... And after 6 months you can pay off the finance and keep the benefits.
the taycan or cross turismo I fancy costs 55k to replace the batteries if they fail and many dealers aren't offering a warranty longer than a year and the lifespan of them are circa 8 years.
I thought most manufacturers were doing something akin to 8 year warranties - presuming mileage was not silly? - is that not the case?
I remember looking a couple of years ago at how well the older teslas were doing and it seemed like on average most of the batteries were holding up really well over very high mileage amounts .
My local Volvo dealership advised that a XC90 T8 hybrid would only have a year warranty including battery. If you were the original owner, they would probably be different.
Looking at fully electric models looks like volvo do 8 year warranty on battery that is transferable to subsequent owner . No idea why the hybrid would be 7 years less if its hybrid battery ?
https://www.volvocars.com/uk/l...
For eight years from the date the vehicle is delivered to the first owner or 100,000 miles, whichever comes first, any material defect of the hybrid Lithium battery pack* will be rectified free of charge by an authorised Volvo retailer.
This only seems to refer to (the much smaller) hybrid batteries. Additionally, further down from your quote it says:
“The Lithium battery fitted to Volvo hybrids, like all lithium batteries, will experience gradual capacity loss with time and use. Loss of battery capacity due to or resulting from normal gradual capacity loss is not covered under the Volvo new car warranty.”
This is what I was referring to. As with all batteries this ‘gradual’ capacity loss occurs at quite different speeds depending upon a range of factors.
RE Electric Vehicles
I dont imagine the launch of the Dacia Spring EV will help the secondhand market. It seems a limited urban run-around but at sub 15k I suspect that it is going to be very popular.
https://www.autoexpress.co.uk/...
Vets
Good to see the government take action against the PLC / private equity that are fleecing UK pet owners .
No excuses for racketeering in 2024 and this is long time coming .
My friend recently drove to Spain , price in UK for a pet passport 500 pounds and one trip only , price for cleaning dogs teeth 250 pounds
He then registered the dogs in Spain and price for pet passport 38 pounds lifetime plus 40 euros for teeth clean .
Rip off Britain at its very very worst .
Well done to the regulators and let’s hope they have teeth in their bite.
How many animals have been destroyed because an owner can’t pay the feee ?
I bumped into one of my long serving warehouse guys who was a big dog lover looking rather gloomy, I asked what was up
“Dogs got cancer 3.5k cost of operation I’ll have to get him put to sleep”
Told my missus and she gave me a roasting “get it paid for”
Anyway the end of the story is we paid the bill , the dog survived (a young boxer) and for the next 8 years every time our alarm went off in the early hours Gary and his dog would drive out and the dog would charge round the warehouse looking for burglars, “it’s his responsibility now” Gary would say .
Anyway I digress as usual but UK veterinary market needs sorting and when private equity and PLC try to monetise our love for animals into excessive margin unchecked it’s a total wind up .
Completely agree.
I agree.
Around here, we just shoot our dogs and sheep when it is time. It has just become too damned expensive to get a vet out to a marginally profitable hill farming business. We are just marking the retirement of our local vet, at I think the age of 71. He sold his business to one of the big corporate chains but stayed on for a few years and watched as the prices just went up and up.
I will add a couple of points, if I may, to the defence of vets though. First, we have become immunised to the high cost of pharmaceuticals and medical tech due to the NHS ... I don't think this helps. Second, a lot of farmers have started to buy some medicines online and that is where most of the profit for a veterinary practice is. Finally, it has become increasingly difficult in today's interest rate environment for a young ambitious vet to buy a well equipped practice from a retiring vet. Corporate chains can pay more because they have access to cheaper financing.
Anyway, anything that brings the costs down on veterinary costs for 1,500 sheep and 22 horses is welcome.
Somewhere out there Richard Leonard is punching the air with Synthomer up 35%. He can finally stop averaging down after 3 years :)
You are naughty Wolfie.......but I like it!
Wonder if Synthomer (LON:SYNT) might be in play now, as a strategic acquisition.
They do have a strength in specialty chemicals. Could be acquired by a competitor, or adjacent sector. Someone who has much bigger balance sheet, can refinance the debt at cheaper rates. Take it private and wait for the upswing in cyclical demand.
I wonder when they will get him back on PI,,,,,,,,,,,,,,,,,,,,,
Poor Richard .... that did make me chuckle though.
Paul, replying to your point about TP Icap (LON:TCAP)
This has a long history and was for a while run by the pugnacious and brilliant Terry Smith.
As Tullett, it was a bunch of shouty boys doing phone deals. It was then combined with the shouty boys from ICAP. Not much technology, lots of shouty boys.
A new MD came along and decided to start using technology, so made a few acquisitions of technology businesses.
The integration has been slow and some good techies got the boot or jumped ship.
There were some naughty shouty boys, not many, but mainly at ICAP, I believe, and there is some cum/ex naughty risk, I think. This has left litigation which is typically found at the back of the annual report.
You will understand accounts far better than me, but the accounts are always full of so called exceptionals. I disregard most of them.
So the new MD has to make various legal claims against the old owner if ICAP, and deal with some irritations.
In my view the MD is sorting out the legacy and slowly getting the technology into the market. Shareholders are squeezing him to get better value out of his valuable technology estate.
The whole business does best in volatile markets.
I now have to confess that I need to offset pretty awful losses on Palace Capital (LON:PCA) with profits this tax year. Thanks to a 40% bounce in TP Icap (LON:TCAP) in the last 6 months, I’ve had to sell mine today. But I plan to be back if Mr Market is kind to me with TP Icap (LON:TCAP) prices in a few weeks.
Paul, my impression re TP Icap (LON:TCAP) is that the main issues are 1. It’s a bit dull and complex 2. They overpaid for an acquisition a couple of years ago 3. There hasn’t been an interesting story for investors to get attached to.
The potential floating of a minority stake in their Parameta data subscription service potentially improves 1. and 3., and the company has been quietly improving the acquired business (and its other function).
One of my larger holdings.
Yes they acquired Liquidnet for $700M in 2021 and were then deemed to have paid too much for it. One of my larger holdings too.
Regional REIT (LON:RGL) is looking like it will have to go the the market at a very significant discount to raise around £75 m of which, presumably, £50 m will go to paying off the bond due this year. A complete dog's dinner and Edison and Questor in the Daily Telegraph have got considerable egg on their face on this one. The shares are down another 34%. Thankfully, not one of mine, but I have been following events closely ... I do enjoy a good (corporate) car crash, and once the balance sheet is sorted, this might be investable, depending on your view of the Board and the macro trend for secondary office rental outside the M25. The big lesson, I think is to watch bond prices as they foretold the need for new capital months before the leak. If they raise the capital, the bonds look a screaming buy.
Not one for widows or the farm.
Have a nice day folks.
No mention on here of Fonix Mobile (LON:FNX)
Good set of interims. Very high client retention (virtually no churn). Revenues and earnings growing at double digit/ mid teen %ages. Highly cash generative and growing dividend to boot.
Brokers have upgraded 3 or 4% and call this conservative. Remember this is on top of the recently upgraded forecasts.
More interestingly another European market launch is anticipated in H2 and more in the pipeline so growth could be good/elevated for some time to come?
Trades around 20* PER with good net cash - £12m. One of the few IPOs that has actually done what they said they would!
Nominally looks reasonably priced then but a difficult one to value - will most likely trade on a higher PER as the forward visibility and client base is super sticky plus with 15% growth that’s not particularly demanding. Broker has a 12m target of 300p (up from 275p) for what that’s worth. Can’t help thinking that’s not an unreasonable ask given opportunities on offer. I hold
US CPI data inline but hot, disappointingly .... over to the the GS analysts to pull the number apart and find a positive.... on the face of it, the rate cut thesis continues to weaken. Markets shrug ... no idea why.
Shoe Zone (LON:SHOE)
Given the directors' shareholdings, a concern may be that this company could be taken private.
Somewhat ironically, if their strategies prove successful this may act as a catalyst?
Does this limit the upside potential?
Good luck to holders.
HAT quality =29 on stock report
Regarding HAT thought about investing into giving the positive commentary etc however looking at the stock report it has a scoring of only 29 .and a value trap any thoughts welcome thanks
It'll be interesting to see what the Stocko algorithms spit out for H & T (LON:HAT) when they get the updated data tomorrow (or shortly anyway). The QR fell from 77 to 46 this time last year.
I hold.
I thought Eurocell (LON:ECEL) were reporting FY 23 results today but no news. I emailed Michael Scott (CFO) and he's just replied with:
Our results will be released next Wednesday, 20 March.
Details will be on our investor web site from 7am that morning.
Full-year results from Morgan Advanced Materials (LON:MGAM) are disappointing. Revenue is flat but profit and debt are heading in the wrong direction.
Management appear inept, under "Our Purpose" they say;
"Our products help keep people safe. We are proud to design fire protection in everything from cars to tunnels, and ships to oil platforms."
However they admit...
"An impairment charge of £1.2 million was recognised following a fire in December which destroyed a warehouse and inventory. The assets were subsequently written off."
They also had their systems hacked which resulted in a cost of almost £15M. This should be the direct responsibility of management but there seems to be no accountability.
I hold this but am considering taking my losses and moving on.
I'm also in the same boat as a long term holder. The enormity of the "cyber incident" should have been made as soon as they were aware of it, not have it drag out over years (and the press, as always, seem to know more than investors are told), the total loss is amplified by the distraction to management. As for the fire, although it was only a small hit relative to the size of the company, it should have been advised at the time if the losses weren't covered by insurance.
Ignore, I was later than most in commenting on this! Shoe Zone (LON:SHOE) have put out what seems to be a mild profit warning, 11% off at the moment. No position, but considering. Can anyone give an alternative viewpoint to mine, that it is an over-reaction
Shoe Zone (LON:SHOE) this was the tip on Sunday:
The Sunday Times's Lucy Tobin tipped shares of Shoe Zone to her readers, arguing that the business was set to continue benefitting from the cost-of-living crisis.
Sales at the discount chain's 329 shops had jumped by 39% over the preceding two years.
Furthermore, reviews for its footwear - including £8 Converse lookalikes - on Amazon.com were "glowing", she pointed out.
Shoe Zone was also tinkering with its structure, shifting from small highstreet shops to bigger sites at retail parks or digital sales.
The company had also cut the total number of stores.
It was also "highly" cash-generative with £16.4m of net cash.
Chief executive officer Anthony Smith and his brother own 58% of the shares such that management had a clear interest in seeing shares soar, although the company's free-float was only 32%.
"As the Liberum analyst Wayne Brown wrote this week: “Consumers are actively seeking value for money, spending less per transaction and spending more on lower-priced products,” Tobin said.
"Shoe Zone will benefit: buy."
I concur, and as my buy in price was circa 50p, I can't see me selling as long as the divi holds. I would add more commentary although as it is Cheltenham, I'm busy seeing how else I can lose money!
Edit to add, my 2 kids actually don't mind going here for school shoes etc and even my daughter prefers the school shoes to SHEIN et al.
Decided to review my position in Shoe Zone (LON:SHOE) quickly at the weekend. My scribbled notes:-
"Up about 20% on Times tip.
Forecasts showing falling profits - conservative? ? Fwd PER 12. Marks and Spencer (LON:MKS) 10.
Headwinds - Middle East/Living Wage.
Top slice or sell"
Sold on Monday. One of the few things I've got right this year. (Memo to self: always review after "tip" causes spike)
Good entry point? Would prefer to see a sub 10 PER if its gone ex-growth.
A.
Shoe Zone (LON:SHOE)
Probably bad form to reply to yourself, but I think another point is valid.
Zeus, their house brokers, were obviously blind-sided by this - and might have indeed forced them to issue the late RNS - it speaks volumes that there is no update analysis from Zeus today - at least on Researchtree.
This is a bit of a red flag for me as well.
Also, IMO, uninvestable until we see the new forecasts from Zeus. PW by analyst is becoming very popular - and another bug-bear for me, give me the numbers your finance department is working on - NOT “marginally below expectations” - I'm mathematically literate even if the entire of the city's PR machine is not.
Shoe Zone (LON:SHOE) delayed statement:
At this stage of our financial year, trading is marginally below expectations, due to a higher than expected increase in the National Living Wage, an increase in container costs due to the ongoing situation in the Suez Canal, higher costs associated with upgrading our property portfolio and the impact of a slower than expected end to our Autumn/Winter season.
I have no reason to doubt this statement, but was not expecting it. Might be an entry point for some, I'm overweight so continue to hold.
I have taken the opportunity to increase my holding, having top sliced on a previous spike and missed the October dip last year. Hoping the dip is not sustained but at least I have the cushion of it going ex this week : 8.9p ord + 6p special.
Management seem very competent and open. I was particularly impressed by them securing stores with short leases and rent holidays, allowing them to refit and get to profitability before paying rent. They rode out the much higher container costs during the pandemic, which helped build their online sales, although I do agree with Paul that listing the MLW increase could be viewed as myopic.
Shoe Zone (LON:SHOE) Poor AGM trading update.
"The last financial year was another successful year of further growth, in which we continued to execute our store refit and relocation programme. At this stage of our financial year, trading is marginally below expectations, due to a higher than expected increase in the National Living Wage, an increase in container costs due to the ongoing situation in the Suez Canal, higher costs associated with upgrading our property portfolio and the impact of a slower than expected end to our Autumn/Winter season."
Personally Id be wary, the chart looks a little stage 3ish
Morning,
Costain (LON:COST) looks interesting, large cash balance, revenue and profits up. Looks very cheap? Pension scheme I see and a fair few adjustments.
Thoughts anyone?
The "cash" is almost like "working capital" - can never be disbursed, because they need to show large cash on the balance sheet to win contracts. Same as Galliford Try Holdings (LON:GFRD) .
However, its acceptable in a high interest rate environment, because at least Costain (LON:COST) should be getting tasty interest income.
The key risk for Costain are black swan events - where they screw up a big contract, and penalties/litigation/remedial will be in the tens of millions. Versus the paltry 3-4% margins. So far, so lucky for the last 2-3 years.
Hence, they will perennially be cheap on a P/E basis, because of this black swan event. And always be seen as value, holding lots of cash and rich TNAV.
There are some good trading opportunities though, from time to time. I held briefly last year for this reason.
Talking of elections, it seems that the opposition in Russia is voting in a different way as various resistance groups took action last night. Lukoil Refinery closed down.
https://t.me/liveukraine_media...
Some unusual things happen in Russian elections from time to time .
The story of the cleaning lady who was asked to stand as a token gesture to the official party candidate is one of the more humorous....
https://www.themoscowtimes.com...
…oh yes, the all powerful ‘green button’!
For those invested in the Brick manufacturing/sales area. Noble Francis of the CPA has provided an update on Jan 24.
https://www.linkedin.com/posts...
TLDR:
We surely cant be far from a housebuilding recovery (houses being built not share price recovery - a lot of that has already happened...)
I think the mess it is summed up nicely by the cricitism of one local council near to me where they have too many sites ready for redevelopment where didly squat is happeinng and they have been criticised by opposition councilors . This council in charge has lots of brownfield sites where they have said they cannot force delevelopers to go ahead with redevelopment plans - the landowners clearly want to prioritise greenfield sites nearby.
This sums up the mess we have here right now - we need policy at the top to stop brownfield sites being being hoarded and not redveloped - there should be clear 2 way responsibility - owners should have near term plans to being back into use (or be taxed to hell so they sell to someone who will) and also the planning rules should be such that planning doesnt cause undue delays on top. Either way it seems clear to me that the current powers that be simply havent got the job done here despite tehn length of tikme they have been in charge. This would align with doing something about empty shops and disused shops that blight our high streets - priority plus should be to bring those premises back into use.
I read the Persimmon (LON:PSN) statement this morning and my take away was that they are intentionally holding off on a big push on completions until 2025. When the interest rates have started to decline, one assumes they can sell property for higher margins as house prices escalate. I just get the impression the recovery in building related services is maybe still a few months off. Could get bitten of course and left wishing I'd invested earlier, but until that first rate cut comes in I don't see UK markets moving all that much, particularly in that sector.
Persimmon (LON:PSN)
I just read through today's report and noticed the complete collapse in Gross Margins.
The company is now back to the GM% levels it had back in 2012/2013, with further cost inflation expected in the current Financial Year.
I also noticed that there's going to be some extra debt interest in the accounts for FY24 as the company dips in and out of a net debt position. I remain wary about the claims that it will finish with net cash for the year.
Based on the above I'm actually surprised that there wasn't more of a drop in the SP today.
A
Some people are unhappy about the PCIP placing at 56p saying that it doesn't make sense to dilute when there was a 90p offer a few months back.
The 90p offer was from Sycurio, the company currently suing PCIP, and the price before the lawsuit was announced was 89p. So why would PCIP accept a 1p premium from the company actively trying to lower the share price?
I was supportive of this raise because cash and available liquidity was thin, and any mediation will be done from a position of strength. It removes any doubts on cash (plus there is potentially a further £1m+ coming should the appeal go PCIP's way again).
The original placing in 2021 was to go towards growth - some of this capital has been spent on legal fees and growth has been curtailed. This small raise at less than 10% of shares in issue gives the company capital to grow even faster, with the hope of an eventual higher price than the paltry 90p offered by Sycurio. I hold a small position.
Good FY figures from LSE:HAT, we've had good write ups from Paul and yet Stocko classes it as a value trap. Any comments - I'm a holder.
H & T (LON:HAT) low stock rank appears to be due to poor momentum and quality scores - it scores highly on value. Poor momentum is self-explanatory given recent share price weakness since the profit warning a couple of months ago. More difficult to see what is behind low quality rank, but I can see it has a weak F-Score (which I believe is a big component of the quality metric) - looking into this, this seems to be largely due to poor cash generation and rising debt. However, we know this is because the company is ploughing more cash into the pledge book, which is seeing strong demand. Overall, not too concerned about the low stock rank in this instance.
Hi,
No agenda here - I don't own HAT.
For me to invest, I would need to understand:
2022 vs 2021 year, why
For today's RNS, eps up 39%, but cash at bank has reduced. Also;
Does this mean management have borrowed to fund all of the increase in turnover? This raises more questions to me (unless they only trade the month before year-end?)....
director remuneration scheme - this seems to be based on Total Shareholder Return and EPS. This leads to inappropriate incentives to management (incentive to bump the share price prior to share exercise and manipulation of EPS). This is inconsistent with the health of the business and retail investors. (Perhaps ROCE/ROIC and cashflow incentives would be better?).
Not saying this has happened, but it does increase investor risk.
Good luck!
As briefly mentioned in my previous response, H&T have been putting more money into growing the pledge book which has seen strong demand and should lead to strong earnings growth. This explains the reduced free cashflow and increased borrowing. I see this as a positive development, but I guess looking at it on a purely quantitative basis it might not look good and probably explains the low stock rank.
Some people are unhappy about the PCIP placing at 56p saying that it doesn't make sense to dilute when there was a 90p offer a few months back.
The 90p offer was from Sycurio, the company currently suing PCIP, and the price before the lawsuit was announced was 89p. So why would PCIP accept a 1p premium from the company actively trying to lower the share price?
I was supportive of this raise because cash and available liquidity was thin, and any mediation will be done from a position of strength. It removes any doubts on cash (plus there is potentially a further £1m+ coming should the appeal go PCIP's way again).
The original placing in 2021 was to go towards growth - some of this capital has been spent on legal fees and growth has been curtailed. This small raise at less than 10% of shares in issue gives the company capital to grow even faster, with the hope of an eventual higher price than the paltry 90p offered by Sycurio. I hold a small position.
Gore Street Energy Storage Fund (LON:GSF) . Quarterly update today reaffirming dividend which is promised at 7% versus NAV but now showing 12% against share price. Does anyone have insight into why this stock is so heavily discounted ( approx 40% versus NAV). I hold
Mainly bad news from others in the sector but particularly bad news and a dividend cut from Gresham House Energy Storage Fund (LON:GRID. With money getting pulled from sector ETFs and the whole ESG area .....Gore Street Energy Storage Fund (LON:GSF) gets dragged down with it sadly. Also, not helped by the strong inflation data which has taken the shine off perceived interest rate victims.
Costain (LON:COST)
Good prelims this morning, ahead of market estimates.
In a sector where wafer-thin margins are a concern the policy to improve this is working so far:
"On track to meet our margin targets for FY 24 (run-rate 3.5%) and FY 25 (run-rate 4.5%), having delivered 3.0% adjusted operating margin for FY 23 and 3.8% in H2 23".
Presentation at 09 00: https://stream.brrmedia.co.uk/...
Apologies for the double post - I'm not the only one this morning I see. There was an endless revolving circle eventually followed by "There was an error please try again" but I need not have done so!
I have reported these to the green button.
Duplicate posts:
Keelan replies: I've just sent this through to our developers who are now investigating on our end. Something seems to have flagged up.
Im no forecaster so who knows but I would like to see a return to the 0.2% we were seeing which I believe would support a broader equity strength and better condition for small cap.... but hope isn't an investment policy. The first two data points kind of blew a whole in my thesis that inflation would not be an issue first half. All will be clear rather early today since we are in that unusual period when the US opens an hour early since they have changed their clocks ahead of Europe. If I was still running institutional money Id say its pretty unusual to get a reversal of QTD trends at this stage of the year so Im not that confident....
Good luck all and lets hoe for the right outcome for portfolios.
As a rule I would say companies putting out an RNS Trading update at the market open is unlikely to contain good news. Not so today, re Volvere (LON:VLE) (I Own ) which has given a particularly strong update.
Not a huge amount of detail re the split of profit between Treasury and Shire ...but all encompassed in an increase in NAV from £13.90 to £14.82. Net cash has increased from £20.79m to £23.74m. Positive comments re investment opportunities suggest this is unlikely to be wound up anytime soon. Capital efficiency is referred to which could well lead to a return of capital. I personally see this as low risk due to the cash level and the conservative nature its run although liquidity is an issue.
I have been extremely impressed with Nick, not least coping with the tragic passing of his brother Jonathan last year. Volvere (LON:VLE) is in safe hands. Clearly a reasonable opportunity trading at such a discount with hardly any value being attributable to Shire Foods at current levels. Nice to have some good news...
Volvere (LON:VLE), very good results I would say.
Graham, would you offer some comments on today's update? I understand that this may be a material holding for you.
It looks extremely undervalued now, with a growing cash pile of £23.75, plus a food business with growing profits after tax of £3.6m (which is 80% owned). This food business should be worth 6x - 8x earnings, given all of the investment made into it. That's a sale value of £17.3m to £23m, plus the cash of £23.75m.
I make that £17.30 to £20 per share, versus SP today of £11.20.
H & T (LON:HAT) good FY23 results Graham will do a far more comprehensive overview than me so I won't compete! In summary, NAV ps 403.3p. Strong demand for pawnbroking which is their core business, unlike RFX which is FX and retail sales. HAT have been poor at forecasting which has cost them during the year. The growth is impressive PTP +39%; EPS +31% but they had forecasted more hence the sp hit. The latest acquisition of Maxcroft Securities, which lends to small business owners against personal assets is an interesting one, Maxcroft's average loan value is £4,063. So this presumably increases their risk but would lead to material growth if well executed. HAT current average loan value £201. They stated they wanted to learn from Maxcroft with the suggestion that in the medium term they roll-out their model. (Or that's my understanding).
Latest forecasts today FY24: PBT 33.5 +27%; EPS 57.2 +17.5%. Nice divi 5.4%.
Management will present in a webinar with Q&A on Friday 15th March at 12 noon and can give more clarity. Join here.
Thanks. Directors were buying well above 400p last year. Near term macro environment positive. What's not to like in today's H & T (LON:HAT) update?
My snapshot for Fonix Mobile (LON:FNX) Interim results. A decent set of results I think with good growth on the top & bottom line, with extremely strong growth in their mobile messaging segment. I do have a slight concern about declining growth rate going forward, though it may just be a temporary blip as they have had in the past. Overall I think it's a solid business, though not sure what the share price will do today.
I hold.
I noticed a couple of posts saying that they were quitting the UK market.
I found a site https://siblisresearch.com/dat... which publishes PE ratios by country. Here are TTM PEs for 2023-12-31:
US 21.8
Canada 15.2
UK 10.5
France 13.5
Germany 14.9
Russia 3.2
India 23.2
Japan 16.4
China 12.8
Australia 16.0
UK is even cheaper than China.
I suspect the PE is quite sensitive to how the "E" part is calculated, though. So they need to be taken with a pinch of salt.
Stockopedia shows the ASX (All-Share) on a trailing PE of 13.8, which isn't as bargain-bucket at 10.5. The forecast PE is 12.0, but that assumes an EPS growth of 10%. I wish! I reckon 2% if we're lucky.
Here's what Evenlode said in their recent note for their UK Income Fund, they said that valuations are about as good as it has been at any time over the last decade, except the 2020 Covid sell-off.
https://evenlodeinvestment.com...
I've been running a sample quality portfolio whose selections are here: https://www.stockopedia.com/co...
There's still two-and-a-bit months to go, but I'm pleased to report that it is way ahead of the index. To give an example, MACF is up nearly 19% since the portfolio was formed in late May, yet it is still on a forward PE of less than 11. It's been growing its dividends by 9.3%pa over that last 6 years, and has a ROE of nearly 15%. It has comfortable debt. Nice if you can find them.
I was wondering if any Stocko users had experience of trading US securities using the website screens and other tools and what their experience was?
Any chance of a free trial for existing (UK only) subscribers???
US stocks have all the same data available. The dependability of the Stocko algorithms though seems predominantly centred on UK and European markets, rather than US, is my general impression.
What you don't get is the extraordinarily valuable discussion among some very expert investors highlighting interesting opportunities that don't necessarily show in the rankings ( eg recently Filtronic (LON:FTC), Beeks Financial Cloud (LON:BKS) , Reach (LON:RCH) etc etc. And of course the invaluable daily SCVR.
Im baffled by people throwing in the towel with UK shares at this point, fair enough if youre a trader and prefer liquidity and momentum, but even then Ive only traded UK shares this year, Im up 8% playing it as defensively as I have in years. As long as you pick your spot theres decent looking trades/investments almost every day right now.
Surely buy and hold investors (im not) want to be buying when sentiment is awful, valuations are in some cases at 10-15 year lows. Many sectors look to have troughed, macro looks better, higher wages/lower energy bills will give consumers a boost from April, inflation looks to be heading for around 2% within months and interest rates have peaked/will be cut within months. I think if markets remain relatively stable in the US and theres not some unexpected banking black swan due to rapid rate rises then there's every chance of making a lot of money this year. Fund flows are a drag but will eventually change as prices rise and overhangs are cleared. Doesnt take much to flip from fear to greed. US CEO confidence was lower than during Covid in Autumn 2022, general sentiment was truly awful, that was the time to buy US stocks. Same again in Autumn 2023 when sentiment was very bearish. Not now.
Wolfie
I have to strongly disagree with you on this one.
I do understand that opportunities are still there but :
If for example you hold a S&P ETF and a FTSE one and then you compare them in 10 years time what would the outcome be?
There is no comparison regarding the growth and quality of the two.
All the best
Yiannos, your ability to see so accurately into the future is uncanny ;-)
It’s just history repeating itself!
All the best
It’s better if you provide us with your opinion. I am very much interested..
Where do you see the FTSE100 in the future?
Do you think it will outperform the S&P?
All the best
Agree Wolf of Small Street. Throwing in the towel when a market is bombed out to switch to a market at multi year highs is the exact opposite of the Warren Buffett approach. There are bargains galore on the UK market.
Look at TP Icap (LON:TCAP) share price after their Results today, and that 11% gain is on top of a similar gain yesterday. . TCAP could be bought for just over £1 in summer 2022 and the yield at that price after the further dividend increase today is over 14%. And there’s a 120% capital gain on top. Those saying “Now is the time to buy TP Icap (LON:TCAP)” aren’t wrong EXCEPT for that key word NOW! Those buying now might well do very well but those who bought near the lows are doing a darned site better!
I know nowt about Bitcoin, but there was an article in The Times on Saturday headed “Why it may be the time to gamble on bitcoin. Cyprocurrencies are up 149% in a year, but be prepared to take the rough with the smooth if you jump in.” Same point as I’ve just made for TP Icap (LON:TCAP) And those buying ahead of the big gains have a cushion of paper profits to protect them if that buy now advice proves wrong.
NVIDIA (NSQ:NVDA) market cap is over $2 TRILLION! And the PE ratio nearly 80. That market cap is not much more than the entire FTSE 100. And it’s about half the £3.5trillion total market cap for every share on the LSE!
The clever investors are the ones who have already made and top sliced massive profits on multi bagging shares like NVIDIA (NSQ:NVDA) and not the ones who are now abandoning UK shares to invest in it and similar highly rated US shares.
Hi Ken,
TP Icap (LON:TCAP)
2018 price about £5
Todays price about £2.20
NVIDIA (NSQ:NVDA)
2018 price $50
Todays price $880
Clever investors are the ones that quickly spot the opportunity costs and make money in growth and quality stocks.
All the best
Exactly yiannos1.. The clever NVIDIA (NSQ:NVDA) investors were those who bought ahead of it multibagging and not those buying now. And the clever investors were those who invested in TP Icap (LON:TCAP) after the share price had fallen 80% to £1 and now after 22p gain today are sitting on a 120% share price gain. Your point is valid both for growth and value shares.
Yet NVIDIA (NSQ:NVDA) PEG is only 0.7
Hi all
I hold exclusively UK stocks in my portfolio as I don’t have the confidence to dabble as yet in US stocks. My Uk holdings are up around 20% through no great strategy of mine other than trying to weed out the more obvious non performing stocks. And hugging and holding the steadier ones which have a decent ROCE and some dividends to offer. So I think the early rally has helped - again no genius input from me! NatWest was a bit of a recent speculative punt having said all that and that is up about 12%. I am hanging on for the divi there. The Govt plans for NW may erode or add value - hard to call. But knowing Govts probably the former?
At least one has been the subject of a merger (DS Smith) so will need to keep reviewing that one.
Never had a multi bagger but you can dream - but chasing them is a bit like hunting moonbeams from my experience.
Your strategy seems a good one. I hope it continues to work for you.
I have found that quite a few stock I've sold have then gone on to perform exceptionally well. So the multi-baggers may already be in your portfolio, even if you don't know it yet.
One of the secrets is patience, I think. Sometimes skill and luck can help in the shorter term.
Like Shell (LON:SHEL) , bought Jan 2021. I'm up 90% on that, although it had doubled at one point. Brent was like $55 per barrel, which seemed pretty cheap. I'm thinking of selling, mind, as I think the easy money has been made. If oil is below $40, then you know that the odds are in your favour if the big oil companies are also bombed out.
Other times l just happened to be lucky, like buying BAE Systems (LON:BA.) just before the Ukraine invasion, and 3i (LON:III) just before it began its rapid ascent. Both are doublers after holding for a relatively short time.
I have others that have done even better than +200%, but these have been held for over 5 years. My track record is only mediocre over the last 5 years, though, so in the end, I don't have too much to boast about. But if you hold shares for a long time, there are bound to be some knockout performances.
I agree Wolfie. There is no doubt that the UKs standing in the World has been diminished. I think this has served the purpose of Xi and Putin, who just want everything for themselves. I am very proud of the British outlook and our people (regardless of where they come from) which in many ways sounds odd but I believe it is our biggest strength. We still have some very good people and companies and judging by the amount of people who want to live here a positive political and legal environment. We must continue to strive for our best and kick the negativity being pushed out there. If we do this investors will see our determination and persistence and at some point they will flood back. But we also need to stop putting ourselves down. As you might guess I am a bull of the UK market!!
What about the fact that increased salaries in tight margin businesses that require many employees will reduce profits further for these businesses!? The increased spending won't be enough to offset that.
Thank you for the post, really interesting analysis. British businesses have some real winners, I for one am fed up of the continuous negative view of Britain's business community.
Article in The Times says FCA to allow trading in crypto related products on UK market. They will only be available for professional investors as UK retails investors like us are too thick to understand the risks involved, unlike other retail investors in the US and elsewhere.
- expecting loosened regulation around anything investment or finance related in the UK?! expecting retail investors to be allowed to think and invest for themselves?!
by jove, no! here is how it works old chap:
- you are a helpless, naive retail investor stumbling around in the dark. therefore you require the steadying and guiding hand of the ascended managerial class in order to invest properly
- they will follow the hallowed principles as set down in the sacred tomes (ThE ReGuLaToRy gUiDaNcE)
- the FCA has spoken child, now run along!
Fonix Mobile (LON:FNX) carry on doing what they do! Key metrics showing double digit %growth including interim dividend up 10%, adj PBT up 25% and a positive outlook statement.
http://newsfile.refinitiv.com/...
My concern with this company (I hold) has always been that I reckoned app based payments would obliterate (OK, render rather old fashioned) payment by means of a text message. However, this thought appears to be incorrect as the company continues to grow and is continually talking about new markets. They seem to have an attractive niche.
Quality company and one we could look back at in 10 years time and wish we'd have had even more than perhaps we have today.. Whilst its in my top 5 holdings I have no plans to top slice any at this stage
Paul/Graham, if you have time (and you feel it's appropriate as it's a 'mid-cap'), please would you take a look at Hill & Smith (LON:HILS) full year results released this morning:
Results today our of TP Icap (LON:TCAP) and H & T (LON:HAT) , my two largest individual holdings.
H & T (LON:HAT) results look good to me, and ahead of my expectations. PBT +39%, EPS +31%, NAV + 8%, Divi +13%. My only concern is the increased debt and the price of the acquisition. A strong Hold for me, as an existing shareholder. I might well be buying otherwise. If I release cash elsewhere, I may add. I’d be interested in any comments on the debt, which seems to me to be in line with the increased pledge book.
TP Icap (LON:TCAP) is the usual irritating blizzard of adjustments. In my view revenue is +3% and EPS +about 5%. Divi + 19%, wow. I think that the quality of the business is improving, under the surface, and issues are slowly being ironed out. This process does take a while. I think that the shares are still undervalued, but I have a really big holding by my standards (sitting on a decent gain), and can’t really add. I’m slightly surprised that no one is bidding for this company, which is turning into an electronic plumbing business for the financial services industry. Much cheaper than the LSE, for example.
Agreed GreyInvestor, TP Icap (LON:TCAP) does appear to have quite a lot quietly going on to substantially improve the business. Additionally the prospect of putting a minority of its data subscription service Parameta up for IPO appears to offer us shareholders the best of both worlds, ie unlocking some of the (alleged) value of this premium growth business, while still benefitting from its future growth and networking value to the company.
Meantime, I am happy to enjoy my 7%+ dividend, and, for a moment, the fact that it has a Stocko ranking of 100!
.
My morning smallcap tweet: You've Got to Pick a (Shareholder's) Pocket or Two
Renalytix (LON:RENX) Ebiquity (LON:EBQ) Regional REIT (LON:RGL) PCI- PAL (LON:PCIP) Haydale Graphene Industries (LON:HAYD) H & T (LON:HAT) Narf Industries (LON:NARF), Fonix Mobile (LON:FNX)
◄Renalytix (RENX)► $10m placing at 20p, a 47% discount, to keep the lights on. [SP=40 Cap=53m]
◄Ebiquity (EBQ)► guides FY-Dec rev up 7% and adj EBIT up 31%. 2024 has started satisfactorily - "client spend to remain slightly more subdued until more consumer confidence returns". [SP=36.12 Cap=49m]
◄Regional REIT (RGL)► re speculation - "significant preparatory work has been undertaken to date in respect of both the debt and equity options". A placing would be at a material discount. [SP=20.15 Cap=104m]
◄PCI-PAL (PCIP)► £3.5m placing at 56p, a nil discount, for continued expansion in the US, Europe, the Middle East and Africa + working cap. [SP=56.99 Cap=37m]. I hold.
◄Haydale Graphene Industries (HAYD)► guides H1-Dec rev up 38% to £2.47m, adj op loss £1.61m (£1.89m). In line? US tooling sales disappoint. "Cost savings plan in progress to further hone operations." 'Hone' LOL! As if it was a well-oiled profit making machine. [SP=0.44 Cap=8m]
◄H&T Group (HAT)► FY-Dec. Outlook sounds in line. [SP=340 Cap=150m]. I hold.
◄Narf Industries (NARF)► wins $1.3m contract for US ReSCIND (Reimagining Cyber Psychology Informed Network Defense) Programme. [SP=1.21 Cap=20m]
In line: FNX
£5k ISA may never happen:
Cynical, the Tories have increased taxes beyond belief, but you only get the British ISA if they win the election.
Stunning that an announcement was made about the product with no firm plan.
Shock
Hi NQ,
The government first need to go through a consultation process on its implementation among both trade bodies and providers (where there will be systems and reporting issues) and groups representing investors.
See the link here: https://www.gov.uk/government/...
This takes time as it then does for firms to create new product offerings. You may recall the delay for these reasons once the then Chancellor Osborne decided in principle to merge the historic PEPs and ongoing ISA regimes
It would be alright with a £50,000 annual maximum subscription, it takes a tiny mind to think of £5,000 - or that of a scrooge.
Another idea, if you have a normal trading account, and you invest in approved UK companies, we won't charge you capital gains on your profits for X years, no limit. Instead of the UK ISA.
Agree that these things take time and we're almost into the new tax year. My problem is why didn't Hunt spell that out clearly at the time. The answer is obvious, of course - he wanted the short term gain and the instant headlines. So typical of politicians of whatever persuasion.
Gotta go careful when polishing a t--d, one can get into a right old mess, the Chancellor seems to have got carried away with it.
I think the consultation alone runs till July. I have been asked to contribute to silly questionnaires by a number of parties already! £5k is basically less than inflation since the ISA was set at £20k so no real cost to the Treasury.
Cyclical, the Tories have increased taxes beyond belief, but you only get the British ISA if they win the election.
Much as I enjoy exploring the amoral, post-truth world of Conservative politics, I think we need a firm rule to leave politics to other sites and stick to the small cap investing here. Or at least require an explicit link back to investing. (This is going to be a dirty election year!)
So if the newspaper report is true, do you think this (non!) move will delay a recovery in UK small shares? Personally, I thought it was a gimmick that would only affect the investment decisions of a few thousand small investors at most and as such have no real impact.
(PS I think you meant "cynical" not "cyclical" but it was one of those typos that really worked!)
I agree that posters should ensure any political points made are substantiated and/or referenced to examples as well as explaining the posters’ view of how it will impacts investment sectors or the broader economy.
Related, I’ve explained in my post above why there is a delay in the implementation of the UK ISA announced in the Budget. The consultation doesn’t end until the summer and then there would be a decision in the viable timetable for implementations and launch of products.
Totally agree. Keep politics off this thread please.
A new, different thread would suit, perhaps?
As it’s politics, I assume you meant to type ‘threadbare’ suit ?
Totally agree. Please keep politics off the thread.
All optics. Its far too low anyway, £5k?