Small Cap Value Report (Tue 12 Sept 2023) - GMR, GYM, DX., TPFG, HVO, SUP, CREO

Good morning from Paul & Graham!
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £1bn. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk.
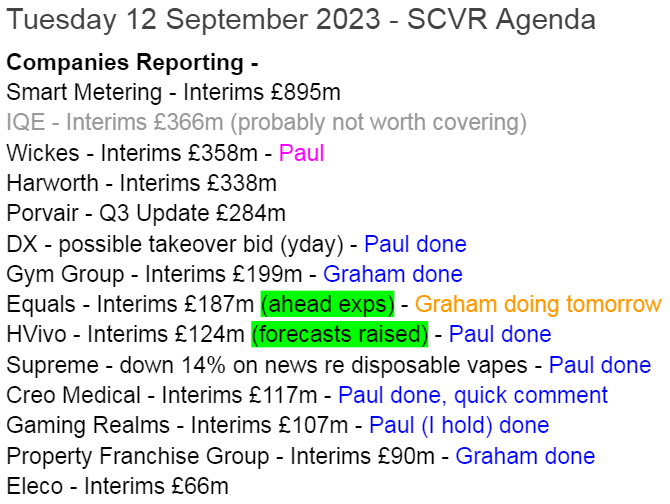
Quite busy today for interim results. We'll pick the most interesting ones (over/under expectations, or if the share looks particularly good/cheap) -
Summaries
Gaming Realms (LON:GMR) (Paul holds) - 36.4p (pre market) £107m - Interim Results - Paul - GREEN
I have a good rummage through the H1 results below, and like what I see. Outlook sounds confident for H2, so risk of a profit warning seems low. Strong balance sheet with growing net cash. Very good organic growth, with a capital-light business model. New clients and products, plus global reach, makes this share look very attractive to me as an excellent GARP share. That's why I own some myself.
GYM (LON:GYM) - 112p (unch.) (£200m) - Interim Results (in line) - Graham - RED
These results are in line, with no change to guidance. I remain negative on this one due to my concern that the company will continue to struggle with 2019 (pre-Covid) comparatives for the foreseeable future. Net debt is c. £70m, with very limited balance sheet strength.
DX (Group) (LON:DX.) - 43.5p (£263m) - Possible Offer - Paul - GREEN
A possible bid approach announced yesterday afternoon at 48.5p gets the support of management, so the potential bidder is now starting due diligence. I think the bid price looks reasonable based on fundamentals. We've reported positively on DX 3 times in the last 10 months, seeing a low PER, good yield, decent balance sheet with net cash, a decent turnaround following previous problems, and solid trading updates. UPDATE: a later announcement has been issued from HIG, which sounds like they're serious, having secured agreement from holders of c.32% of the company for a bid of "at least 45p", so are they trying to trim the price a little maybe?
Property Franchise (LON:TPFG) - 282.5p (+1%) (£90m) - Interim Results (in line) - Graham - GREEN
We had an August trading update and the results for H1 come in as expected. Growth has slowed to a crawl but in the context of the housing market and what has happened with interest rates over the past year, it strikes me as a good performance.
hVIVO (LON:HVO) - Up 6% to 19.3p (£131m) - Interim Results - Paul - GREEN
Good numbers, and Liberum ups the forecasts for 2023 and 2024. I do think this company looks very interesting, and like the high visibility from the forward order book, plenty of clients cash paid up-front, and what seems to be a lucrative niche without much competition, they tell us. I'd like to see a longer track record of profitability, ideally.
Supreme (LON:SUP) - down 14% to 93.5p (£109m) - Possible ban on disposable vapes - Paul - AMBER
We discussed this company late last week, when the Times reported that Supreme’s CEO had made a £350k donation to the Conservatives. Maybe he’ll be asking for his money back now (joke!!) , as the Govt is reportedly set to ban disposable vapes which seem to be aimed at children. I’ve been following the reader discussion on this, and some subscribers seem to think this might actually benefit SUP, whilst others present alternative views.
Is the 14% drop today a threat, or a buying opportunity? Personally I just don’t want to get involved either way with a vaping (and other products) company. I suspect plenty of institutions might take the same view, under ESG pressures, so this share could remain on a low PER permanently, I suspect.
Creo Medical (LON:CREO) - down 4% to 31p (£116m) - Interim Results - Paul - AMBER/RED
Every time a blue sky type company reports its figures, it’s a horrible reminder of the financial risks. CREO has a great story, with what seem very credible new products for keyhole surgery, beginning to gain traction. However, once you strip out its income from consumables, revenue has barely begun for the core products. Yet there are lots of expenses involved to promote the products.
It’s losing about £13m per half-year on the P&L. So the remaining cash pile of £26.5m at June 2023 might only be enough to get to mid-2024. Therefore the March 2023 fundraise almost certainly won’t be the last. Broker forecasts assume it can rapidly increase revenues, and slash costs, to avoid another fundraise. That doesn’t seem likely to me. It’s a pity, because I really like the story here, and the products, but for me the figures just don’t stack up at the moment.
Paul’s Section:
Gaming Realms (LON:GMR) (Paul holds)
36.4p (pre market) £107m - Interim Results - Paul - GREEN
Gaming Realms plc (AIM: GMR), the developer and licensor of mobile focused gaming content, is pleased to announce its interim results for the six months to 30 June 2023 (the "Period" or "H1'23").
The jewel in the crown of GMR’s products is a game called Slingo, which seems very popular, and is widely licensed by online casinos.
Headlines -
Content licensing revenue grew 37% to £8.8m after 12 consecutive half years of growth
37% increase in Adjusted EBITDA1 to £4.8m
The above reinforces that GMR is a good organic growth company, and still reasonably priced, which is why I like it, and bought some myself earlier this year (having previously been sceptical, but the numbers have improved a lot over the last year or so).
Key H1 numbers -
Revenue up 36% to £11.5m
Adj EBITDA up 37% to £4.8m
PBT up 74% to £2.4m
Is EBITDA a sensible number? In a word, no. Here’s the reconciliation from EBITDA to PBT, the bold numbers are H1 2023 (unbolded are 2022 comparatives) -

As I have highlighted above, there’s only one significant number, which is the amortisation charge for intangible assets. If that’s goodwill (or similar) from acquisitions, then happy days! If it’s amortisation of internal development spend, then it’s a valid cost that should not be ignored.
Following it through to the balance sheet, there is £12.6m in intangible assets. Then moving to note 6, I find that £5.1m in goodwill, which is not being amortised. £7.2m of “Development costs” makes up almost all of the remainder. £2.2m was freshly capitalised onto the balance sheet in H1 (costs which by-pass the profit number), and the amortisation charge was lower, at £1.56m in H1.
Therefore this shows that the EBITDA number is nonsense, and best ignored, because it doesn’t account for the substantial development spending.
In cashflow terms, half of EBITDA is being spent on internal development costs, so this is a very important point for valuing this share. You could see that as spending to drive expansion, but I tend to find that development spending is necessary and ongoing at this type of software company, so it's a normal cost for me, not something that could be switched on & off at will. If companies don't spend on continuous development, they go backwards after a while.
All the other costs in the table above are valid costs, so I will be valuing this share on PAT. Although that looks distorted by a negative tax charge of £(160)k in H1, meaning that PBT of £2.35m become PAT of £2.51m. So we need to know if negative tax charges are permanent, or temporary? Is it using up b/fwd tax losses maybe? For valuing the shares, we might need to normalise the tax charge first, to avoid over-valuing them (which is what Canaccord does, so the forecasts are fine).
At this point I normally check what the broker says, and helpfully Canaccord has published an update note today on Research Tree, many thanks for that.
It says forecasts “look well underpinned”, so no changes made. That, together with recurring revenues at GMR, and confident outlook comments, indicates to me that the risk of a profit warning seems low at this point in time.
Broker forecast & valuation - full year forecast for FY 12/2023 is £23.0m revenue (£11.5m already done in H1, so that looks like a number that could be beaten in H2 - good).
Adj PBT forecast is £5.9m, and they’ve forecast a normal tax charge of £1.2m (not a credit as has been reported in H1), giving PAT of £4.7m. At a market cap of £107m, I make that a PER of 22.8x, which I think is reasonable, given the strong organic growth trajectory.
FY 12/2024 sees forecast PAT rising 49% to 7.0m, which would bring the PER down to 15.3x, which strikes me as excellent value for a growth company. As we’re now quite late in 2023, we should be shifting towards valuing shares on 2024 forecasts, providing the forecasts are sensible. I think this switch is a main reason why stock markets often have a Q4 rally.
What would I value GMR shares at? I think 20x 2024 forecast is reasonable, which implies a share price target in the shortish term of about 48p - not bad upside on 36p now. That doesn’t factor in any future years’ growth too, it just assumes that nothing goes wrong in 2024, which can’t be guaranteed of course. This is why we diversify, because something unforeseen is bound to go wrong at one or two companies in our portfolios.
In adj & diluted EPS terms, Canaccord has: 1.6p (FY 12/2023), 2.3p (FY 12/2024), and 3.0p (FY 12/2025). That’s impressive earnings growth. Are the forecasts reasonable? I’d say yes, because GMR is clearly demonstrating growth, with lots of new clients (25 in H1 2023), international expansion, and new games (eg. Tetris) in the pipeline.
In the next bull market, investors might tolerate a higher PER for a growth company like this, maybe 25-30x? That would mean a share price target of 75-90p on 2025 forecasts. Compared with the price of 36p now, I find that a very attractive investment proposition, if we're patient.
Outlook - is in line with market expectations for FY 12/2023 -
Licensing revenue increased 20% in the two months post period-end compared to the same period in 2022…
…we are confident of further growth for the remainder of the year and the Board remains comfortable with market expectations around FY23 financial performance.
…"The Group has a strong pipeline of new business and the outlook for the Group remains positive. We are seeing growth in our existing partnerships coupled with new operator, product and market launches, which gives us great confidence in terms of the longer term prospects for the business."
Balance sheet - it’s capital light, being a licensing business model for protected IP, which is good.
Receivables look high at £5.2m, which is 45% of H1 revenues (I would expect to see something nearer 20-30% of H1 revenues in receivables). This would be a good question to ask management if they do a webinar.
There’s no interest-bearing debt, which is great. Cash has gone up from £2.9m a year earlier, to £4.5m at June 2023, which is excellent - I very much like companies where cash builds up on the balance sheet, as it lowers risk, and shows that management are disciplined, and don’t squander available cash. It also means divis might be on the cards at some point in future, although the current policy is not to pay shareholders anything.
Creditors are very modest, so no issues there.
NAV is £20.5m, less intangible assets of £12.6m, gives NTAV of £7.9m. That may not sound much, but for a capital-light business with negligible fixed assets, this is more than adequate. So a thumbs up for a decent balance sheet, hence lower risk I’d say. It shouldn't need to dilute, unless making a big acquisition.
Cashflow statement - H1 operating cashflow is healthy at £4.5m in H1, more than double last year. Tax payments of £579k reduces this to £3.94m post-tax operating cash generation in H1.
The big outflow is £2.2m in capitalised development spending (which is almost certainly just internal payroll costs), so this is an ongoing, regular cost, the way I see it, although capitalising it is perfectly allowable accounting treatment. We just have to remember that it’s a cash cost, that is not paid for by the tooth fairy!
Overall the H1 result is a £1.6m increase in cash.
Therefore the cashflow statement also gets a thumbs up from me - this is a simple & clear statement, and shows a decently, genuinely cash generative business.
Questions for management -
Why are receivables so high, at almost half of H1 revenue?
Why is there a corporation tax credit in the H1 figures, and will this normalise as a charge in the full year (as Canaccord forecasts)?
GMR looks capable of paying a dividend now, is this being considered?
Paul’s opinion - I really like this, and view it positively, so GREEN.
Management has plenty of skin in the game, and the trigger for me buying was NED Mark Blandford (founder of Sportingbet) making some chunky (over £100k each) buys.
This is a genuinely cash generative, organic growth company, on a moderate valuation multiple. It has a strong balance sheet with net cash (growing). Outlook sounds positive, with good growth drivers that look set to continue.
The only negative I can think of, is that some investors might not want to invest in software for gambling websites, given the social damage that gambling addiction creates (I’ve had to deal personally with the aftermath of 2 good friends recently confiding in me that they’ve squandered tens of thousands, getting into debt, etc, mindlessly playing online casinos).
Changes in gambling regulations could also be a benefit, if loosened, or a threat if tightened up. Although GMR has a wide geographic spread, which should protect it.
Overall, I’d say the numbers and GMR make it look a very convincing GARP (growth at reasonable price) share, I like it a lot. Do remember that I own it personally, so I’m biased, but as always, have tried to appraise it with an open mind. Let me know what you think (good, bad, or middling) after doing your own research - we like to consider a range of views here.
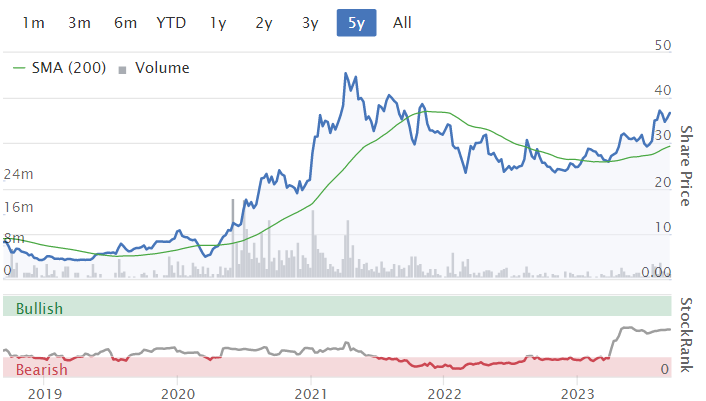
For chart followers, this looks like a bowl to me! (which some prominent investors like, eg CockneyRebel).
Stockopedia's computers looked sternly away, rolling their eyes, until earlier this year, when they raised the StockRank considerably, now upper-middling at 57 -
DX (Group) (LON:DX.)
43.5p (£263m) - Possible Offer - Paul - GREEN
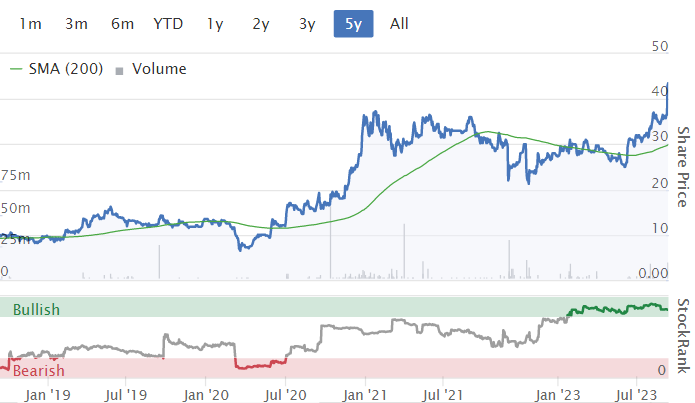
This was issued yesterday afternoon, and has triggered a price rise from c.36p before the news, to 43.5p now, a rise of 21%.
DX says -
“it has received a non binding and conditional proposal from H.I.G European Capital Partners regarding a possible all cash offer for the company at a price of 48.5 pence per DX share”.
DX says it had rejected previous approaches from HIG, but 48.5p is now high enough for the Board to recommend it, should HIG proceed.
So it is now proceeding with giving HIG access to the books, to start doing due diligence (checking the figures and legal stuff like contracts, leases, etc).
Paul’s view - we reviewed DX positively here on 15/12/2022, 1/2/2023, and 18/7/2023 - in all 3 cases viewing it as GREEN, noting the low PER, good yield net cash, and a convincing turnaround. Each investor has to make up your own mind now, whether to sell some in the market now, banking a useful gain. Or whether to hold, and hopefully get another 11% upside from the deal going through, if it does. If it falls through, then I imagine the price would fall back maybe 10-20% to pre-approach levels. Or another bidder might appear, who knows? This type of business will never attract a premium rating.
Personally, I think the bid price looks fair, and management agreeing to it in principle confirms that. It’s your decision as to what to do next - it’s your money, so your choice!
hVIVO (LON:HVO)
Up 6% to 19.3p (£131m) - Interim Results - Paul - GREEN
hVIVO plc (AIM & Euronext: HVO), the world leader in testing infectious and respiratory disease products using human challenge clinical trials, announces its unaudited interim results for the six-month period ended 30 June 2023.
Headlines - this is what we like to see, upgrades to expectations! -
Strong first half performance and record forward visibility
Upgrade of Full Year Revenue and EBITDA Guidance
H1 key numbers -
Revenue in H1 2023 up a very impressive +52% vs H1 2022 to £27.3m
(however, note that H2 2022 was higher, at £30.5m revenues, so sequentially the revenue in H1 2023 is down on H2 2022. It’s difficult to see the historic seasonal pattern of trading, due to lockdowns skewing historic numbers.
Profit before tax of £4.2m is up massively vs £453k in H1 LY.
Note that this year H1 benefited from £530k in finance income, no doubt helped by higher interest rates earning a decent return on the cash pile kindly paid up-front by customers.
Balance sheet - NAV £21.6m. Take off £6.0m intangible assets, give NTAV of £15.6m, or 12% of the market cap, so valuation has only a little support from assets.
Cash of £31.3m is nice, but note 5 shows that £19.4m of this is “deferred income” - i.e. up-front payments made by customers, for services that have not yet been provided (and will cost a lot to provide). So don’t get too carried away with the cash pile. I know the company says it belongs to them, and deposits are not refundable, but most of it will be spent providing services in future.
Or another way to look at it, is that if revenues dried up, then most of the cash would disappear funding services paid for in advance by customers.
On the upside, having a working capital model where customers pay a lot up-front is clearly a very nice business model, so no complaints from me overall.
Overall, I think this is a well-funded business, where dilution or insolvency risks look negligible.
Cashflow statement - looks good, helped by reversal of a receivables increase last year.
Note also the £1.3m boost from R&D tax credits, which is quite a significant help too.
There’s hardly an capex (physical or intangibles).
£3.1m was paid out in divis in H1 2023.
Overall, I’d want to see more of a track record of cash generation. hVIVO is unusual, in that its performance has come from nothing - it was heavily loss-making on small revenues as recently as 2019. Since then it seems to have found a lucrative niche, where it claims to be unique. That could be very exciting if the growth continues, but I’d want to find out more about what competitor activity there is, it doesn’t sound credible to me that there’s none - there must be surely?
Outlook - mainly reiterates previous announcements.
Order book at June 2023 is £78m (up a bit from £70m a year earlier). This could be capacity constrained though, which should be helped by a new facility opening in H1 2024.
Guidance for 2023 is raised (would have been helpful to indicate how much though) -
hVIVO increases its revenue guidance to £55 million (excluding other income) for 2023 and increases its EBITDA margin guidance for 2023 to c.19%...
The outlook for the business remains extremely positive, with revenue for 2023 fully contracted and our orderbook providing excellent visibility over revenue into late 2024
Broker update - many thanks to Liberum for crunching the numbers as follows:
FY 12/2023: forecast revenue upped 2.4% to £55.1m, PBT upped 7.3% to £7.1m. EPS 1.0p, so a PER of 19.3x
FY 12/2024: forecast revenue upped 3.3% to £60.8m, PBT upped 6.6% to £8.2m. EPS 1.1p, so a PER of 17.5x
Webinar - is today, at 18:00 on InvestorMeetCompany, should be interesting.
Paul’s view - I like this share, and flagged it here as GREEN on both 15/1/2023, and 6/2/2023, flagging positive contract wins, cash, and excellent visibility on forward orders. We wobbled a bit in May, going AMBER on the FY 12/2022 results, seeing both bull and bear points, but enthusiasm crept back in on 26/7/2023, with an AMBER/GREEN view, on a good trading update revealing very strong H1 growth, a big order book, and plenty of cash on hand from customers.
Overall now, I think let’s stop beating about the bush, and just get it back to GREEN! The price has gone up a fair bit recently, so personally I wouldn’t want to chase it up beyond a PER of 20x at this stage, which we’re close to. However, I can also see the positives and the story looks very good so far.
Graham’s Section:
GYM (LON:GYM)
Share price: 112p (unch.)
Market cap: £200m
Leading low cost gym operator, The Gym Group, announces its interim results for the six month period ended 30 June 2023.
I’ve been negative on this stock in 2023, due to a failure to match pre-Covid performance levels (especially when adjusted for the inflation seen since 2019).
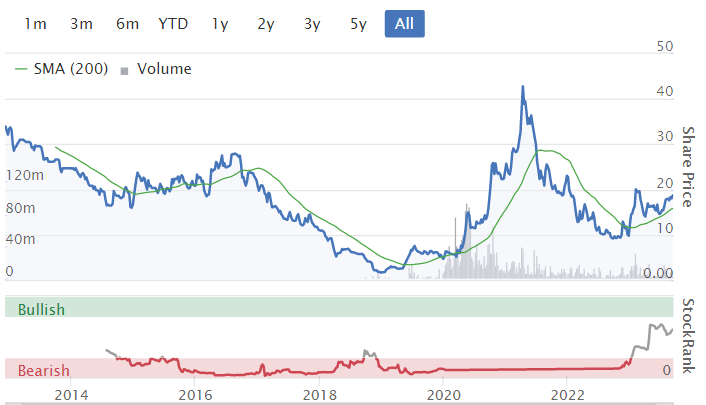
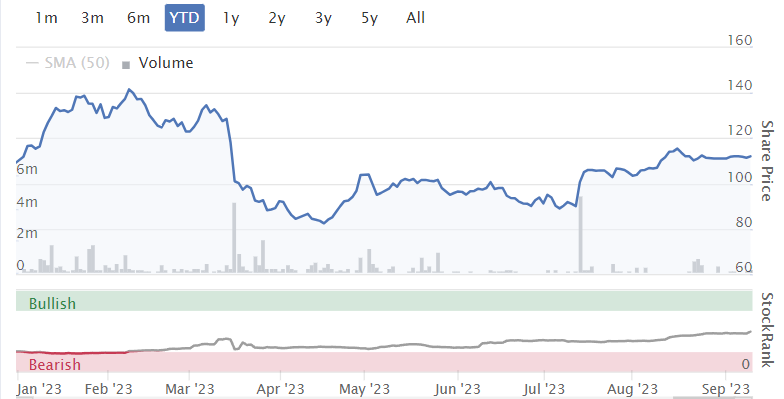
The share price hasn't moved too far:
Here are today’s interim results:
Revenue +18.5% to £99.8m
Adjusted EBITDA is surely irrelevant due to depreciation. Plus 4.8% to £35.1m.
Adjusted loss before tax £5m (around the same as last year).
Actual loss before tax £6m (£7m loss last year).
The total revenue number is much less interesting than like-for-like figures: are members paying more, on average? And are the same sites making more revenues than they did last year?
The answer is that average revenue per member monthly is up 8.4% year-on-year, i.e. keeping up with inflation.
Like-for-like revenue, i.e. revenue from sites which are at least a few years old - is up 6.9% year-on-year, again keeping up with inflation over the past year.
The company has a metric it calls “Adjusted EBITDA less normalised rent”, which I would ignore due to the missing depreciation charge. However, GYM treats it as a key metric.
This metric is almost unchanged in H1 at £17m: “broadly flat, in line with guidance, with revenue growth offsetting inflationary cost increases”.
Outlook -
“...July and August continued in line with expectations, on track to deliver our plans for the year as a whole. We are maintaining our guidance for FY 2023… that revenue growth will broadly be offset by cost inflation; leverage expected to remain within the range of 1.5 to 2.0x (currently 1.82x)..."
Balance sheet - speaking of leverage, net debt finished the period at £70m (it was £58m in June 2022 and £76m in December 2022). The main source of debt is a bank RCF, subject to quarterly covenants.
Cash flow - cash performance is quite good in the period, and better than reported profits, due to the non-cash depreciation charge far outstripping capex.
Cash inflow from operating activities: £42m
Cash spending on capex etc. outflow £11.5m
Lease-related payments: outflow £21m
Add these up and we get a measure of cash flow that I can get behind: just shy of £10m inflow. Not bad at all.
Chairman comment
"The Gym Group has delivered a solid first half, driving growth in both membership and yield, and remains on track for the full year. I am delighted to welcome [new CEO] Will Orr on board. The actions we have taken to strengthen management, our financial position and the Group's customer proposition will enable us to continue to take advantage of the many growth opportunities in our market under his leadership."
Graham’s view
I am tempted to revert back to a neutral position on this one, but I’ll wait a little longer before doing that. My reasoning is the same as July, when I noted that like-for-like site revenues were still trailing 2019 levels:
Revenue in comparable sites is on an improving trend and is now at 97% of 2019 levels.
In other words, like-for-like revenues are still lower than they were four years ago, and that’s before adjusting for compounded inflation over that time.
It’s no surprise that the company is loss-making once we grasp this simple fact.
As noted by “zipmanpeter” in the comments last time, it’s conceivable that the loss-making city centre sites can be jettisoned in a few years once their leases expire, and that performance could substantially improve once that happens. However, I can’t estimate how long we might have to wait until that happens, or how much the company’s financial performance might improve when it happens.
The bright spot in today’s results is the cash flow statement, but I don’t think I should allow myself to be swayed too much by low capex spending over a six-month period. Net debt is up year-on-year.
So it might be harsh, but I’m keeping my negative view on these shares for the time being. It’s loss-making, significantly indebted, and capital-intensive: not a great combination.
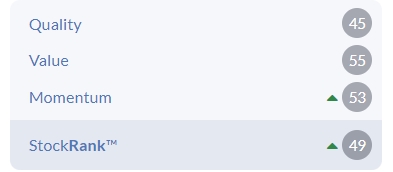
The StockRank takes a more balanced view.
Property Franchise (LON:TPFG)
Share price: 282.5p (+1%)
Market cap: £90m
The Property Franchise Group PLC, the UK's largest property franchisor, is pleased to announce its interim results for the period ended 30 June 2023. [6 months]
We had a trading update from TPFG last month, so had a good idea what to expect today:
Revenue £13.2m, about the same as H1 last year.
Royalty income from franchisees £7.7m (£7.5m in H1 last year).
PBT +11% to £4.2m
Net cash £0.7m
A possible cause of concern might be the lack of top-line growth. I would be inclined to cut the company some slack on that front, given the course that interest rates and the housing market have taken over the past year. The growth in profits is a fine achievement, in this context.
CEO comment:
"It's another period of record revenue for us, outperforming the market in both lettings and sales. Moreover, with continued focus on costs, slightly down despite the pay increases needed by our employees, we have also set another record for profit before tax.”
This year more than any other under my tenure demonstrates the strength of our franchise business model and the power that results from a network of entrepreneurial franchisees seeking to maximise the opportunities in their local marketplaces.
The Board is “confident that trading remains in-line with expectations for the full year.”
The other day, I watched the film The Founder for the first time, about the franchise roll-out of McDonald’s. It showed the early battle between McDonald’s and its franchisees, who were inclined to change the menu from what it was supposed to be. But at the end of the day, the franchise model was unstoppable and the early battles were worth it.
In my opinion, TPFG is working the franchise model beautifully, and has been doing so for years. The model works well both for hamburgers and for real estate! It turns businesses that otherwise might not be very attractive investments (e.g. restaurants) into highly investable enterprises!
Most revenue (61%) in the TPFG network is now from lettings, so this is yet another property-related stock where managing lettings is now the core business. A sign of the times.
Outlook - it’s worth giving you three paragraphs from the outlook statement, as they all seem to be important:
We expect the current market conditions to continue through H2, with a strong lettings market and subdued sales market. That said our resilient business model is well adept to continue to deliver despite the current external trading environment.
The lettings market has shown no signs of cooling, with the lack of supply continuing to increase demand and drive up rents. We have seen double digit growth in H1, a trend we expect to see for the foreseeable future.
The UK sales market is proving to be more resilient than many commentators had been predicting. We have seen an improvement in sales' completion times post period end, with HMRC data for June and July showing an encouragingly positive trend, something we have seen continue through into August.
Graham’s view
No change to my view on this one: a high-quality stock trading at a reasonable price, so I’m positive.
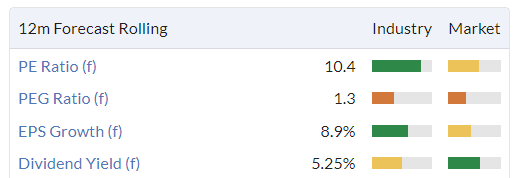
It passes the Stockopedia “Neglected Firms” Screen:
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

60 comments
I invested in Iqe (LON:IQE) years ago. Predictably, I lost money on it. The company is a joke. It is constitutionally incapable of making money. Maybe in the hands of someone who knows what they are doing could actually make it quite successful, but current efforts have fallen far far short of the mark.
The BBC reported this in May 2022: "Newport plant critical to easing microchip shortage, says boss" https://www.bbc.co.uk/news/uk-...
A year-and-a-bit later, City AM reports "IQE: ‘Weak’ global demand hits chipmaker’s bottom line" https://www.cityam.com/iqe-wea...
Clueless. Completely clueless. It just seems to suck in Welsh taxpayer money and produces nothing to show for it.
The shares went up 3% for some reason that I cannot fathom.
Re. Supreme (LON:SUP) got out at 116p a few weeks back. When it kept going up I thought what have I done but feeling vindicated today. The political risk was why I bailed and here it is today. Shame really as the management, distribution chain etc looks rock solid. Massive variance on what happens next to this one. I will enjoy watching from the wings.
HI Paul, I have a question on cash flow Card Factory (LON:CARD) in the light of some comments going round on its strong cash generation. It seems to me that you should be deducting the payment on Lease Liabilities to get to free cash flow as this is the equivalent of rent payment for the stores. Is this right?
If we look at the last reported year, to 31st Jan 2023, the cash flow looks as follows:
So free cash flow is Operating cash flow less Software and Capex less interest paid lessother financing costs paid less Payment of lease liabilities and possibly lease interest too.
This comes out at 99.9 - 18.2 - 6.2 - 1.8 - 52.5 - 4.5 = £16.7m
This is a FCF yield of 16.7/356 = 4.6%. That's OK but not fabulous value for a company that could suffer as the consumer gets squeezed. I'm not sure I understand how the lease accounting works and would be very grateful for any light you can throw on the above if you have time to glance at it. I dont feel confident about my assertions! Thanks, Peter.
PS. I have a small holding!
Card Factory (LON:CARD)
Great post PeterW.
I have to presume they are doing something right to have reduced "net debt" from £143 mill at 2019 financial year to £57 mill same stage 2023. They have deffo dug themselves out of a hole - so even if your specific years cashflow isnt obvuiously great - i dont think you can argue its not material cash generation. Perhaps your figures are out on timing issues here - not sure if they may have had delayed payment cycle ref lease liabilities for example ?
Having quick butchers at 2019 and 2023 balance sheets - looks like they have pimped working capital slightly to reduce "net debt" - inventories are 23 mill lower and trade payables £20 mill higher - so take £43 mill as having come from clever use of cash - that only leaves £43 mill reduction in debt over 4 years - 43/4 is probably less than your annual calcs !!
Overall thought i think they have done afantastic job at getting debt down - not many companies manage to get from where they were to where they are without soemthing else consuming the cash or cheating and getting shrareholders to stump up cash.
Note to me its probably a zero numbers game business that over tyhe next 5 years cant think of any reason for cashflow not to match profits - cant think of any specific need for them to be investing in capital items although i havent looked closely at their future plans. So if they make £45 net profit ye 31/1/2024 perhaps cashflow will be much closer to that sum than your calcs.
Commenting a bit late in the day so who knows if you'll see this - but for what it's worth I agree with your FCF calculation. Lease liabilities are required for the business to operate, and therefore should be deducted when calculating FCF. Either way though I find it better to be prudent when you are unsure.
One thing I'd question is how much of the £18.2m from investing activities is 'discretionary' (i.e. for growth) vs what's required to maintain the business. I think you could argue that some of that £18.2m is possible thanks to last year's FCF (i.e. mgmt decided to use some of the cash generated to grow the business by purchasing/developing something.) I think this is a common consideration in calculating FCF - what is growth capex vs maintenance capex (the latter being required, the former being discretionary.)
I also agree with rmillaree - management now has far better cost/inventory /cash control which has helped them reduce the debt considerably, despite not being a tremendously high margin business. This is a sign of really good management and should give confidence, even if it means debt may decrease at a slower rate going forward (i.e. because all benefits have now been realised.)
Hi Paul - I am genuinely interested in your comments around not wanting to invest in a company that includes vaping from an ethical standpoint. A position that I respect but disagree with.
However, in the same breath you buy Gaming Realms (LON:GMR) which is online gambling with similar addiction/health moral dilemmas but wax lyrical about said company.
I find the contradiction interesting because it highlights what seems to me to be a phenomenon that most investors ethical investing stretches only as far as it suits someone’s investment thesis rather than direct moral concerns. I’m not singling you out as I’m guilty of it myself but wonder what it is that changes your perception of what is ethically ok to invest in?
Gambling is regulated!
Hi David,
Fair questions/points! I have a major personal loathing for nicotine, as it ruined my life for 20 years, so I've never bought any stock that deals in nicotine. Just a personal view, not something I want to impose on anyone else, or virtue signal about. That said, if the dividend yield of Supreme (LON:SUP) got to 20%, would I buy it? Possibly! So yes, I'm a total hypocrite in reality LOL! :-)
You mention Gaming Realms (LON:GMR) too. I suppose with that one, I'm focused solely on the numbers, and in truth hadn't really given much thought to the damage that gaming companies do to society.
So overall, I haven't really thought it through properly, and make these personal judgements on what I want to invest in more on instincts than logic maybe?
Also, I look at SUP now and just think the furore around vaping could well be a big shadow over the share price. So it's partly a practical/commercial worry for me, not just some half-baked moral judgement.
Regards, Paul.
I think all we can expect from Paul (and want, personally) is for Paul to evaluate companies and their results/prospects, he and the team here have great insights and skills and I trust their judgement. Paul is the sort of character who speaks his mind and wears his heart on his sleeve which adds to my enjoyment of his input and many LOL moments in his podcast and writings. He’s not trying to provide an ethical framework for our investment criteria nor would he want to I’m sure, and he shouldn’t be criticised for giving us his opinion. Keep the great work up Paul et al!
Just rejoined Stockopedia last week - took me a week to realise Paul Scott was Paulie Pilot from the old TMF days !
I used to hang around the TMF Oil & Gas boards (wonder what happened to Emptyend and his SOCO obsession ?) but I did read and occasionally respond in Paul's board, it was always a good read and yes he always said what he thought without much reservation ;-)
Hi Paul - re hVIVO (LON:HVO) see my comments at the bottom. Your reading of the cash is not correct. If revenues dried up and all contracts were cancelled tomorrow the company would have net cash of £32m and no liabilities under their contract model.
They also don’t use up this deposit cash in delivering the service. The customer makes stage payments which they use to fund delivery and they are left with a margin on that as well as the deposit cash. In total 19%.
Either way unless margins suddenly halved the net cash is attributable to the company albeit that cash flow is in advance of accounting profit.
You're saying something different to what I said.
My reading of the accounts is correct. The deferred income creditor measures how much of the cash pile is attributable to up-front payments from customers, for services that have not yet been provided.
Interesting macro news today: one points to massive wage inflation, the other to a real slow down. Inflation likely to move in the wrong direction tomorrow, I think, after petrol prices and services wage inflation movements.
Average Weekly Earnings annual growth rates - 8.5% or 7.8% excluding bonuses. Just a thought, but under the triple lock then pensioners get a 0.7% bonus. Nice work!
Unemployment ticking up sharply now to 4.3% (from 3.8%). This should moderate the above labour inflation in due course.
https://www.ons.gov.uk/employm...
Been watching Keywords Studios (LON:KWS) for a possible trend reversal, but there may be some more pain to come first. Cost increases and wobbly outlook havent helped today.
US writers strike "which have begun to impact performance in early H2"...... this is the kind of thing they could use as a cover all excuse for downgrades at the next update I guess.
organic growth "(excluding strike impact) broadly similar to first half"
"Remain confident in the long term growth trajectory" So not so confident short-medium term?
"H2 growth weighted to the fourth quarter; mindful of continuing currency volatility"
Theres plenty there they can use later on as an excuse for not meeting expectations I think. Has been a quality company tho, down over 50% since March. No broker notes so left in the dark until stocko updates EPS forecasts.
Chart wise.... The Trend from Del Monte, it say no!
Although it's another staging a recovery from a big drop today. Theres been a few of those lately.
re Keywords Studios (LON:KWS)
As more of a trader these thoughts are probably of less concern to you than the technicals, but I thought I'd chip in anyway. Clearly there's a bear market in gaming stocks and Keywords is simply catching up with the herd that has been falling for two years now. But the underlying question mark is to what extent AI will harm or abet the business. I don't see shares turning round until the outlook improves, but neither do I see AI wiping the company out. It makes more sense to me that Keywords would become the AI-based supplier of choice for creation, testing and localisation, offering the same services faster and at lower cost, thanks to AI-driven productivity gains - but at a similar profit to itself. At least I hope so, as my shares have now fully round-tripped!
Re DX (Group) (LON:DX.) if we look at the most recent transactions in the industry (Advent acquisition of Hermes UK and GXO acquisition of Clipper) it looks like a low ball offer? (although these were at very different times economically)
Also Fedex and UPS trade on higher ratings and aren't forecast to grow revenues this year?
Suppose we'll soon get an indication by the appearance or non appearance of counter offers...
I see Time Finance (LON:TIME) is flying under the radar. No SCVR coverage today or comments yet!
Another profit upgrade announced today, indirectly. That makes it 4 in a row since Jan23.
As always with growing loan books, the impact is extra revenues over the lifetime of the loans, so we're seeing some amazing tailwinds here for revenue and profit growth for the next 1-3 years of financial results.
Still trading below NAV (36.6p per share). Am not sure why. With the growth they're seeing, should be at least above NAV, so there's a clear pathway to at least a 20-30% gain IMO.
(I hold in the Boon Fund)
Thanks for the Gaming Realms (LON:GMR) review Paul. Very helpful.
For anyone with Ashtead Technology Holdings (LON:AT.) Berenberg has raised it's target price today to 500p (450p)- buy
RBC raised on Thursday to 480p (450p)
Jet2 (LON:JET2) which does look cheap-
UBS raise to 1650 (1580) - buy
Morgan Stanley starts with 1800p target- buy
Personally I don't take too much notice of broker targets but lots of people do so it's useful to keep an eye on.
@Mattioli Woods (LON:MTW) in line FY results out with client assets +2.7%, revs +2.8%, total divs up to 26.8p. Recurring revs are now at 90.9% and synergies coming thru from deals.
They have a private investor Webinar this Friday at 12.30pm - to attend please register here: https://www.equitydevelopment....
See below my latest thoughts wrt Equals.
Disclosure: #EQLS is my largest position, so I'm NOT bearish (or probably impartial either).
-----------------------------------------------------------------------------------------------
There are very few truly scalable, tech rich stocks listed in London - that are generating strong double digit sales growth, 50%+ gross margins and plenty of cash. Equals Money is one.
Indeed for investors, after seeing the shareprice more than triple over the past 3 years, the company is the ‘gift that keeps giving’.
Not only posting record H1’23 results today with adjusted EBITDA & EPS (FD) coming in at £9.8m & 3.27p respectively on revenues up 43% to £45m – driven by standout transaction volumes from large/medium sized clients. But also increasing gross margins (52.4% vs 47.4% LY), closing Jun’23 with £16.6m of net liquidity, upgrading FY’23 guidance and announcing a maiden FY’23 dividend of 1.5p (subject to shareholder approval).
Interestingly, H1 software capitalisation was (£2.4m) in line with amortisation costs (£2.5m) too. Meaning adj. EBIT margins (13%) are now in balance and the group in delivering almost £1m/month of operating free cashflow. Further underlining the Board’s confidence in #EQLS' future revenue visibility, profitability and dividend capacity.
Better still, I believe #EQLS is perfectly positioned to ‘lift & shift’ its best-in-class UK fintech platform (eg own-name multi-currency IBANs & bank-grade connectivity) across Europe following its recent Oonex acquisition (rebranded Equals Money Europe) in Belgium. Which if successful, could literally turbo-charge performance over the coming years.
So where does this leave us?
Well, perhaps not surprisingly I’ve raised my FY’23 forecasts to EBITDA of £19.8m on revenues +33.5% higher at £93m, alongside nudging up the valuation to 170p/share.
Moreover at 100p, the stock trades on modest EV/EBIT multiples of 14.1x and 9.7x for this year & next. Which frankly looks too cheap considering adjusted EPS is set to climb to 12.1p by 2026 (24% CAGR) from an Est 6.2p this year. Equivalent to a PEG ratio of <0.7x , whilst similarly paying a handy 1.5% yield.
CEO Ian Strafford-Taylor commenting: “This is an outstanding set of results with record revenues combining with improved gross profit & continued cash generation. Enabling us to announce our intention to pay our maiden dividend of 1.5p/share for FY23."
“[Elsewhere] the acquisition of Oonex SA allows Equals to widen its distribution & addressable markets, and the integration of the business is proceeding according to plan. Given the current trading, and a robust sales pipeline, we look to the future with increased confidence, and we expect to be [ahead of expectations] for the full year.”
Equals (LON:EQLS)
I am also a large holder and have been since 2020.
Interesting that it appears to be a marmite share in light of the last 3 years operational performance.
Thanks for the summary Paul.
I have bought back into Equals having previously lost money during Covid as the share price cratered. To be fair I think management have made incredible progress growing revenue, profits and cash since pivoting to focus on B2B from B2C.
To temper my enthusiasm and bring some balance here are some other points for consideration.
I'm surprised no comment on Cornerstone FS (LON:CSFS) CSFS
Re Cornerstone FS (LON:CSFS)
Don't be surprised, tell us about it, if you think it's good! :-)
Mkt cap too low for the main report, at under £10m. I see H1 results are out today, which have moved into a £23k PBT, after heavy losses previously. Seems to be a minnow fintech type payments company. Very early stage though, with negligible revenues & profits.
Outlook sounds interesting -
we expect to report full year results significantly ahead of market expectations, representing substantial year-on-year growth as well as a maiden full year adjusted EBITDA.
Tell us more about it, if you think it's good!
Thanks, Paul.
I didn't realise you had a cut off at the lower end on market cap.
It's all there in the interim report. Nothing for me to add. If those facts are to be believed then it's very much worth looking at from a growth point.
Hi eggbaconandbubble,
Firstly, what about the sausages & mushrooms?! :-D
More seriously, thanks for pointing out that our explanatory notes didn't include any reference to our usual £10m low market cap cutoff. I'd never noticed that, so I've now included a reference to this in today's thrilling, updated explanatory notes!
Must admit, I didn't see anything exciting in the Cornerstone FS (LON:CSFS) interims, but only had a quick look. It's a tiny business, that has managed to scrape its way to breakeven. Also, being a 2021 float that has lost more than 3/4 of its original price, I'd be wary. Although the chart shows it's possibly formed a base for over a year, bottoming around 6p, so over double that now. Could be worth doing some more work possibly, but I haven't got the time to cover minnows unless there's something seriously positive jumping out at me, which there isn't here. There are so many forex/payments type companies, highly competitive space where it's difficult (and takes a long time) to achieve scale.
All that said, if you think management and the business model is good, then a £8m market cap could be a nice speculative entry point perhaps?
Share based compensation was an outrageous £4.3m last year, so that needs a careful look. Balance sheet is weak, with negative NTAV. Note there's a £2.17m loan note, so checking the terms of that would be important too.
I see they recently presented on InvestorMeetCompany, so I'll watch the recording when it's published, and if there's time.
Thanks for flagging it, although you could have given us some details, instead of saying it's all in the RNS!
Regards, Paul.
I see Supreme (LON:SUP) has been clobbered this morning on news that disposable vapes are to be banned in the next few days. I wholeheartedly support the ban on disposables to limit the impact of vaping on children. I do however believe that this will be a mid-long term boost for Supreme. A huge number of adults in the disposable market will now move over to non-disposables where Supreme is a big player. The distribution deal for disposables will lose them some money in the short term, but I can't imagine many adults will just stopping vaping at a moments notice when the ban comes in. Who knows, we all thought the money to the conservatives was for a favour, maybe it was to push a ban through ASAP so Supreme can cement a foothold in as the number 1 market leader in non-disposables and rake in some cash before competitors can produce rival products and get them to market... just an alternative perspective.
If memory serves me correct Supreme (LON:SUP) only started their own disposables line recently, and then mainly to keep up with the competition/demand. It generated £12m of revenues so a contributor of maybe £1.5m of PBT. Most of that would convert over time anyway.
Their main product is liquids, for which they are market leader. I think in an ideal world the company prefers the non disposables market anyway. It doesn't really change the size of the market but it will remove some of their competitors. Typical over reaction though in the share price in my view - only £700k worth of shares have changed hands for a whopping 16% change in market cap.
Supreme (LON:SUP) I would be concerned about the UK tax approach towards vaping over the next few years in regards to whether Supreme may or may not be a good long term investment.
At the moment there is no additional 'tobacco duty' on vaping products. The 2022 rate on traditional cigarettes was 16.5% of the retail price plus another £5.26 per packet of 20. These high taxes means that the cheapest product is not that much cheaper than its competitors.
These high taxes are of course in part due to the strain on the NHS through smoking related illnesses - and so some may be comfortable in the belief that these large taxes would never hit the vape industry. In fact if vaping were considered a 'pharmaceutical product' then it could be that VAT is reduced from 20% to 5%.
Personally I think it likely the govt at some point go down the first route, and starts creating additional taxes in the sector (by placing the vape industry within the alcohol and tobacco regulations). They will say it is to deal with addiction or something. It's a very lucrative market and imo they will eventually want their cut. Especially given our current fiscal situation - I would think it could happen pretty soon. I would expect them to see this as a cash cow at some point and slowly milk it to the max - they only need to ensure that the price is still favourable against the alternative.
So what's peoples opinions on whether this is a hidden threat to the business model. Presumably high taxes would impede Supreme's ability to undercut their competition by so much - and then may make other brands more appealing if they are no longer that much more expensive.
I don't really have a strong opinion one way or the other and it probably has no bearing on anyone's decision today (something maybe to keep in the back of ones mind). Just thought it might be an interesting discussion point as I don't think its been mentioned before, and is surely a possible threat at some point in the future.
ps. My reading of todays news is that its very bad for Supreme. Many of the disposable vaping companies will likely now pivot into liquids - creating a lot more competition for Supreme.
Well no, because the overall market size doesn’t really change so 15% market share of a liquids market that has doubled is the same revenue as a 30% current share. But because Supreme (LON:SUP) is cheaper and has much higher quality controls and is a major trusted supply chain distributor those making disposables won’t have such an opportunity. So more likely to be net positive to Supreme (LON:SUP) than negative as a number of competitors just won’t be able to and will go bust. Others will move from disposables to liquids but so will the customers.
I agree with this. Also worth noting that Elf Bar are understood to do around £500m of annual revenue in the U.K. in disposables currently. If just a fraction of those customers pivot to other vape categories (pods, eliquids) then Supreme will pick up a lot of business.
Many thanks David, you make some very good points, and this may be how it plays out. But it will likely concentrate the competition into the liquids area of the market. So who knows how long until another player is able to sort out production and distribution efficiency to compete with Supreme on price (there are some serious deep pocket players in this sector). I think you have to believe that Supreme have a special ability in these areas that cannot be easily replicated - I don't know the answer to this, but the CEO to my knowledge has not claimed any moat type position (in regard to production) so one would assume the area will become more and more competitive as time passes. Also at any moment regulation can unpredictably tank the price and kill the business model. We have seen today how price sensitive the stock can be to changing policy. And I still think the threat of a 'vape tax' could seriously hurt Supreme's model - and its the kind of thing that may not have much upfront warning, you could just wake up to a policy announcement causing a huge share price crash!
But regulatory risk is true of many sectors, big tech included.
I don't rule anything out but remember right now the government is trying to wean people off cigarettes to reduce the burden on healthcare so for smokers it is seen as a clean alternative and you generally don't tax that heavily. At some point if enough smokers come off cigarettes then it's certainly possible but Supreme (LON:SUP) are already embedded as market leader in liquids and brands. The CEO has explained how they are so competitive and the moat around it. The current furore is political but it isn't really an area where Supreme (LON:SUP) make their money.
Remember that Supreme (LON:SUP) are not a vaping business - they are a fast moving consumer goods manufacturer and distributor. In ordinary times batteries, lighting and sports nutrition made up the bulk of their profitability. That seems to get missed in the rhetoric but is a big underpin in its own right. It means they also have a strong cross sell into large multinational chains that others find it hard to get into. They are clearly doing it very well else the likes of Elfbar wouldn't have appointed them master distributor to the UK recently if it were so easy to do it themselves!
I'd also say that Guardian have a more balanced article showing that an outright ban of disposables is likely to cause a much bigger problem as illegal sales will flood the market and they will be of lower quality product, possibly harmful and would be completely unregulated. That's an interesting point I hadn't considered and probably a reason an outright ban may not happen. More likely is much tighter regulation both in terms of sales and packaging/marketing - Supreme (LON:SUP) have been campaigning for that for a while.
Palace Capital
Anyone holding ?
There is sone smart money in this and I have a small position. Looks pretty rock solid and can’t see much to go wrong .
Any alternative views might just increase here as it is bottom of recent range .
Palace Capital (LON:PCA)
I have a reasonable holding and added after the announcement regarding the sale of the Maidenhead office property on 2 August that also contained the update of a negligible net debt position of £0.1.
The company is buying back shares aggressively and as you say there are some smart investors on the register, notably Peter Gyllenhammer and Harwood, aka Christopher Mills. There is also a nice dividend yield.
As to anything going wrong. I agree that it It looks pretty good all round, but there is always risk. Having said that I would still be a buyer.
I hold Palace and think the risk/ reward reasonable,the previous management became very discredited and the current board are liquidating the portfolio.So far they have achieved book values but it may get harder .In the meantime you get 6% to wait
Thanks for the feedback
Provided they are sticking to the plan does look a bit of a no brainer safe play
Palace Capital (LON:PCA)
Any thoughts on what the end game might be?
On completion of the current share buy back programme Palace Capital (LON:PCA) will have bought back 20% its shares since July 2022.
Not sure what the current NAV is but must be well north of 300p.
I think I worked out that on the basis of current sales prices (as opposed to NAV valuations based on a DCF) and share buy back I am anticipating 340-350p of return. Official NAV is a bit lower than this but that’s my fag packet calc based on realised sale prices so far.
Cheers David,
On the basis of your workings, Palace Capital (LON:PCA) seems a tempting acquisition given the virtual absence of net debt and trading at what appears to be a 30% discount or thereabouts to NAV. Patience required as ever.
I have no doubt that this is what Peter Gyllenhammer sees as the end game. Incidentally he recently increased his holding from 11.1% to 12.6%, as did Winton Capital Management (not known to me) increasing its holding from 8.4% to 9%
Good morning all. I note further falls for Supreme (LON:SUP) in early trading this morning, currently below 100p (from circa 129p for most of the second half of August), this after news reports/ speculation this morning of a bill being brought forward to ban disposable vapes in England as early as next week. [I hold]
It will be interesting to get any thoughts on EKF Diagnostics Holdings (LON:EKF) and their trading update today which looks like a mild profit warning with revenue and EBITDA now guided down to £53m (from c£57m) and £10m respectively because of delays in commissioning Life Sciences new equipment. This is something that is on my watch list and is a Harwood owned stock.
Mattioli Woods (LON:MTW) results out today as well - these look ok given difficult market conditions in wealth management. Again, be nice to get any thoughts on these please. I have held these for quite a few years.
topvest,
I have held EKF Diagnostics Holdings (LON:EKF) for a number of years. It has been a real disappointment. The company did very well during the pandemic and generated a significant cash pile. The record post pandemic is very depressing, in my view.
The company blew much of the cash pile on a disastrous acquisition of ADL Health in the US and doubled down by stating that it was pleased with that deal. It then ditched the company in March 2023 and transferred it back to an entity controlled by the original seller for a song. That probably led directly to the removal of Mike Salter as CEO. Ditto the Chief Scientific Officer - a US post that has now been scrapped. Mike Salter has since left the company. There have been far too many management changes of late and even today we have yet another change of plan for the CEO/Executive Chair role. It remains unclear how long Julian Baines will hang around, particularly as he stated in early 2023 that he was only staying on for the short term.
As you say, the TU today was a profit warning because the capacity expansion programme for enzymes fermentation is behind schedule. As recently as 3 May 2023, the company stated that it remained on track to have all new fermentation capacity in South Bend installed and validated towards the end of Q3 2023, with all fermenters other that the largest (14,500L) "operational and revenue generating over the summer".
Shareholders have been very poorly served by management post pandemic. I take no comfort from the involvement of Harwood/Christopher Mills, given the number of times that has led to companies being taken private and private investors left heavily out of pocket.
Nice update from Equals (LON:EQLS) but a little bit sneaky on the July/Aug trading I feel. Sales up 43% in H1, slight drop to 39% YTD including Q3 so far, my maths get this to about 27% growth (or something like that) in Jul/Aug.
Hi Paul. Like your good self I am a holder of Gaming Realms (LON:GMR) and was pleased by the interims this morning which all seemed very positive. I did note there was £2.2m of capitalised development costs this year and a total on balance sheet of greater than £20m. I know it is their business to develop games but at some point these costs should go through P&L. They seem to be in a good place, but is the accounting overly aggressive?
Any thoughts on DX (Group) (LON:DX.) bid are also welcome as I also hold and need to consider strategy (hold for full price bid, or take profits).
Best wishes.
Greyster
Morning greyster,
I've spend a couple of hours going through Gaming Realms (LON:GMR) (I hold), so plenty of detail in the section above. I think you've picked up the wrong figure on intangibles, but see section above for all the figures, and I've also focused on capitalised development spend. Overall, it looks very good to me, so I'm happy to hold (and will buy the dips if I have any funds available, as I'd like to increase my position size).
Thanks for the reminder re DX (Group) (LON:DX.) it has slipped my mind that it got a bid approach yesterday, so I'll do a quick comment on that later.
Regards, Paul.
Thank you Paul. I probably did pick up wrong figures, as skim read and posted from memory (not a reliable tool at my age). However, I agree that PAT is a better valuation basis for GMR.
Morning Paul
Excellent results from Equals (LON:EQLS) and I note that two brokers have upgraded forecasts.
it will be interesting to see how the two acquisitions Oonex and Roqqett compound the growth as they are integrated in the next year.
Morning all,
Good update from Equals (LON:EQLS) this morning.
GYM (LON:GYM) not so good.
No positions in either.
Strong TU from Equals (LON:EQLS) with broker upping revenue forecasts by high single digits. Peer Alpha International (LON:ALPH) tries to steal the limelight by announcing a small acquisition. Both look in vigorous shape as Equals managements forecasts results ahead of expectations.
Super results from hVIVO (LON:HVO) has given us an upgrade for the year on revenues and profitability. EBITDA margins (which were forecast at mid teens are now at 19% so very close to the magic 20%+ for a class CRO)
Order book is up 11% as well so looks like next years revenue visibility is very high.
Net cash of £31m means 25% of the market cap is now net cash. Puts them in a very strong position. Remember this is all their own cash as whilst clients pay a deposit that deposit is non refundable if they cancel.
With EBITDA looking like £11m and EV coming down to £93m this is now a world leader CRO in its area of focus on an EV/EBITDA of about 8* with a nominal regular dividend also being announced.
Just looks too cheap to me given revenue visibility and growth prospects.
hVIVO (LON:HVO)
Remember this is all their own cash as whilst clients pay a deposit that deposit is non refundable if they cancel.
Thats less than half a truth if ever there was one - the reality is that deposits paid in advance will have matching expenses in the next period (they only keep the profit they make after all roghly spekaing ) - thats why the accounting treatment is as it is. Reality here 27 mill is rightly showing as liability on the balance sheet - thats excluding any lease liabilities.
Note i am not knocking the company here - we dont need to pimp up the cash though - facts are its real and in the bank thats probably enough.
I see Yamin Khan of hVIVO (LON:HVO) will present on Master Investor on 20 Sept.
Half true :) again - you have to offset receivables against the current liability though.
The point I am making is that if the contracts are cancelled then the liability disappears but the asset does not so it is the company cash.
The cash does effectively represent some of the forward profit on the contract but they don't need to spend that either to release their liability on the contract. Ie if the contract goes ahead the additional sums dues from the client will pay for both the delivery of that contract and will still make a margin.
So the net cash position is actually hard cash that belongs to the company irrespective of delivery of the liability. Plus they should be getting £1m p/a in interest on it now too.
It's a quirk I agree but the main point to note is that the cash is company money
hVIVO (LON:HVO)
The point I am making is that if the contracts are cancelled then the liability disappears but the asset does not so it is the company cash.
You seem to be missing or ignoring my point that the work is done/earned in the following year and there will be direct costs in that year that will syphon of that cashflow. So the cashflow will be eaten up by the mathcing future costs - practicably speaking thats almost the same as if they had to pay by the cash to their customer (if contracts were cancelled) - they only keep the profit element so i completely disagree with your statement of how much would be left for them.
If we took construction company and they took deposit in advance for all next years income. If they received 30 mill upfront - they would be in the same position. Following year you have say 30 mill sales 27 mill expenses and 3 mill profit - buisness then ceases with everything paid . The cashflow year 2 would be outflow of 27 mill as they had all the cash in the prior year. They would have only £3 million left.
Thats the reality of the situation here from my viewpoint - they simply are paid well in advance of booking costs the following year but those costs are very real. Thankfully accounting principles know this fact and rightfully doint let you ignore the matching 20 odd mill of expenses !
No rmillaree - you are Mis reading what I am saying so I will provide an example
the way hVIVO (LON:HVO) business model is this……
Pharma 1 signs a £10m contract. They have to pay a deposit of 10% (non refundable) so pay to Hvivo £1m upfront. This cash is offset (as you say) by a liability of £1m on the b/s.
In scenario 1 Pharma continue with contract. They pay Hvivo £9m over the duration of the contract. Hvivo make a 20% margin on the £10m so £2m of profit. £1m is already sitting in cash. The other £1m comes from receipt of the £9m which is paid during the project in stages to offset expenses.
So no, Hvivo don’t eat into the £1m they received up front. They have effectively banked that profit on a forward basis.
in scenario 2 Pharma doesn’t go ahead with the contract. The deposit is non refundable so Hvivo keeps the cash and the corresponding liability is eliminated from the balance sheet. Again the cash is not eaten into.
The net effect of this explains how even if the odd Pharma contract gets cancelled it doesn’t hit earnings badly and thus reduces lumpiness. It also means that net cash is generally quite stable and increasing.
So unless they had a sudden major hiccup with margins the net cash is effectively company cash - it doesn’t get eroded by the delivery of the contracts.
hVIVO (LON:HVO)
that situation makes no sense to me - if they are booking that income next year (£20 mill) and its all profit (ie doesnt have matching expenses next year) then the broker forecasts would be showing all of that income as profit - thats clearly not the case . the fact they are not confirms that the vast majority of the "prepayment" when it is reversed will have a matching expense that has to be paid cash at that time.
I am happy to agree to have different opinion here from you - if you dont agree we can agree to differ - but i aint gonna change my mind that this is not like any other prepayment that isnt "all profit" . IMHO its clear that some of the expenses next year that will not be prepaid this year will be booked against that revenue if its not all flowing through as profit.
Practicably speaking i am aware if they do the same every year they will always have the same cash if they have the same upfront payment profile - so practicably speeaking they can spend the cash if they want but that might leave them less solvent (insolvent) might leave them unable to pay expected overheads/expenses that the future profit would be covering if they cant do from next years similar or it might make companies less likely to hand over large wads upfont if they are not happy giving soemone a deposit for that to vanish out the back door.
No it’s not all shareholders cash at all.
Only about £10m is shareholders cash.