Small Cap Value Report (Tue 13 Aug 2024) - JUST, GEN, SYNT, CRST

Good morning from Paul & Graham!
It's another quiet news day, everyone's on holiday I suppose!
In case you missed it, I added a couple more sections later in the day to yesterday's report, on Stelrad (LON:SRAD) [GREEN] and Team Internet (LON:TIG) [AMBER/RED].
Explanatory notes -
A quick reminder that we don’t recommend any shares. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech, investment cos). Although if something is newsworthy and interesting, we'll try to comment on it. Please bear in mind the "list of companies reporting" is precisely that - it's not a to do list. We typically cover c.5 companies per day, with a particular emphasis on under/over expectations updates, and we follow the "most viewed" list of readers, so if you're collectively interested in a company, we'll try to cover it. Obviously with the resources available, we can't cover everything! Add you own comments if you see something interesting, and feel free to discuss anything shares-related in the comments.
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to, if they are using unthreaded viewing of comments.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. And/or it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Others: PINK = takeover approach, BLACK = profit warning, GREY = possible de-listing.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom), Video update of results so far, June 2024.
Frozen SCVR summary spreadsheet for calendar 2023.
New SCVR summary spreadsheet from July 2023 onwards.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Phil Hanson's data analysis measuring performance of our colour-coding system in the SCVRs, from July 2023- Mar 2024 (with live prices). My video explaining/reviewing it.
My other video (June 2024) - How to screen for broker upgrades on Stockopedia.

Other movers (with news)
Crest Nicholson Holdings (LON:CRST) - down 16% to 221p (£569m) - Bellway willnot be bidding - Paul - No view
Bellway says -
Bellway confirms that it does not intend to make a firm offer for Crest Nicholson.
No reason was given.
Crest Nicholson says -
The Board of Crest Nicholson Holdings plc ("Crest Nicholson") notes the recent announcement by Bellway p.l.c. ("Bellway") confirming that it does not intend to make a firm offer for Crest Nicholson under Rule 2.8 of the Takeover Code.
As previously announced, the Board of Crest Nicholson had engaged with Bellway in relation to a possible all-share offer for Crest Nicholson in response to a series of unsolicited proposals from Bellway.
As outlined in its half year results on 13 June 2024 for the period ended 30 April 2024, Crest Nicholson remains confident in its standalone prospects, in particular given conclusion of the review of provisions for completed development sites supported by external consultants, its highly attractive land portfolio and the new leadership of Martyn Clark.
This announcement has been made without the consent of Bellway.
Paul's view - none at present, I need to digest this. We previously liked the discount to NTAV at CRST, but it has been accident-prone with historic issues.
Summaries
Just (LON:JUST) - up 11% to 131p (£1.35bn) - H1 Results - Paul - AMBER
Very upbeat commentary, and says it's going to "substantially exceed" previous guidance. However, the numbers rely heavily on big adjustments. Looking through its large & complicated balance sheet reminds me why I don't touch this sector! On the upside, shares are in a lovely bull trend, and the market has responded very positively to today's announcement.
Genuit (LON:GEN) - down 4% to 448.5p (£1.12bn) - Half-year Report - Graham - AMBER
A mixed bag here. The statutory results are impacted by an impairment charge but if you are willing to look past the adjusting items, the profit result is not bad in the circumstances. The company says it is on track for full-year expectations (underlying operating profit £92-96m) even though it expects its end-markets to remain subdued. I run some comparisons with Marshalls (covered yesterday) and decide that I like Genuit more, although it’s not a high-conviction stance from me.
Synthomer (LON:SYNT) - up 2% to 241p (£394m) - H1 Results - Paul - AMBER/RED
No real sign of recovery in trading yet. Meanwhile its excessive debt means that finance costs consume all the operating profit, leaving nothing remaining to reduce the principal. However, bondholders don't perceive risk, with a normal coupon on the recently refinanced 2029 bond, which is even now trading at a 5% premium. Shareholders have to hope for a big recovery in profits, as currently this is a £2bn pa revenue group that doesn't make a bean in profit or cashflow.
Paul’s Section:
Synthomer (LON:SYNT)
Up 2% to 241p (£394m) - H1 Results - Paul - AMBER/RED
This is a substantial, international business -
“Synthomer plc is a leading supplier of high-performance, highly specialised polymers and ingredients that play vital roles in key sectors such as coatings, construction, adhesives, and health and protection - growing markets that serve billions of end users worldwide. Headquartered in London, UK and listed there since 1971, we employ c.4,200 employees across our five innovation centres of excellence and more than 30 manufacturing sites across Europe, North America, Middle East and Asia. “
However, it got into a serious mess due to reckless, excessive borrowings (which we warned about here in 2022), which combined with a drop in demand in 2023, forced it into a dilutive equity raise, and then a 20:1 share consolidation. As a result of which a great deal of shareholder value was destroyed, as you can see (the chart will have been adjusted for the share consolidation) -

The question now is whether the business is recovering (it was previously a decently profitable business pre-pandemic), or whether former customers are getting their products coated elsewhere? The other key question is whether its overly indebted balance sheet has been fixed? (the answer to that is no!)
The H1 highlights table seems to be showing a fairly static trading situation. 7% EBITDA margin doesn’t seem to demonstrate much pricing power, given it has large fixed assets (whose depreciation charge is ignored by EBITDA), plus very heavy finance costs from all the debt (£27m net finance charge in H1, annualises to £54m).

More realistic numbers further down show adj PBT at breakeven, of £0.1m.
Then there’s £32.5m of adjustments, taking the H1 statutory PBT to £(32.4)m loss before tax. Adjustments are mainly goodwill amortisation, which it’s customary to adjust out. Although note it’s still showing restructuring costs as adjustments, despite being at a similar level to H1 last year at £6.7m.
Note there’s £37.6m on the balance sheet as provisions, which are future cash outflows, for restructuring and onerous contracts.
Pensions are also an issue here, with a net £50.7m accounting deficit.
Debt - the big equity raise last year got SYNT out of immediate trouble, but I think it still has far too much remaining debt, which will take years to reduce from cashflow. Maybe there are more disposals that could help bring it lower?
Although refinancing its bonds is a positive sign, and extends maturities nicely -
“At 30 June 2024, net debt was £560.6m (30 June 2023: £795.8m, 31 December 2023: £499.7m). The increase since the year end principally reflects settlement of the EC fine in January, the divestment proceeds of the Compounds business and the Free Cash Flow movements noted above.
In April, we successfully tendered for €370m of our bonds due 2025 reducing gross debt and extending maturities by issuing €350m of bonds due 2029.”
The coupon on its 2029 bonds is 7.375%, which is a surprisingly small premium to the risk-free rate, so clearly bondholders are relaxed about default risk. In recent months the 2029 bonds have moved to a premium to par, now priced at c.105. I didn’t expect to see that, but there we are. The bond market isn’t worried about the debt at all, by the looks of it.
It’s somewhat different for equity holders though, as we take all the risk, and don’t get paid anything in divis until debt has come down to something more sensible.
There’s more debt beyond the bonds though, and the leverage multiple is way above what I would consider normal -
“As at 30 June 2024, committed borrowing facilities principally comprised: a €300m RCF maturing in July 2027, €350m of five-year 7.375% senior unsecured loan notes maturing May 2029, the remaining €150m outstanding of five-year 3.875% senior unsecured loan notes maturing July 2025 and the UK Export Finance (UKEF) facilities of €288m and $230m both maturing October 2027. At 30 June 2024, the RCF was undrawn and the UKEF facilities were fully drawn. The Group's net debt: EBITDA for the purposes of the leverage ratio covenant increased from 4.2x at 31 December 2023 to 4.7x at 30 June 2024, principally due to the higher net debt at the period end, as described elsewhere.
The RCF and the UKEF facilities are subject to one leverage ratio covenant. For prudence, the Group agreed in March 2024 to extend the period of temporary covenant relaxation to ensure that appropriate headroom was maintained. Accordingly, the net debt: EBITDA ratios required under the covenant have been set at not more than 6.0x in June 2024, 5.75x in December 2024, 5.0x in June 2025 and 4.75x in December 2025. Reducing leverage further towards our 1-2x medium-term target range remains a key priority for the Group.”
Overall then, I view this as a dangerously highly geared business, which has been given time by the lenders to reduce debt significantly. Hence I would forget any idea of shareholders receiving any divis for the foreseeable future.
What if cashflows don’t improve, and it can’t reduce debt? Then it would probably need to do another equity fundraise in maybe 2-3 years’ time. Remember bondholders don’t care about equity being savagely diluted, as it doesn’t affect them. So I think equity dilution risk here is still elevated, although not immediate.
Debt is expensive too, consuming all of the operating profit right now -
“The Group expects net financing costs of c.£60-65m in 2024 and c.£65-70m in 2025 as a result of higher interest rates, the recent bond refinancing and other changes to the Group's financing arrangements. The Group's committed liquidity at 30 June 2024 was in excess of £500m.”
If they’re struggling to pay the interest, then they can’t repay any principal. Trading has to dramatically improve to make this situation comfortable, and there’s no sign of that yet.
Outlook - uninspiring, but at least they’re being realistic here -

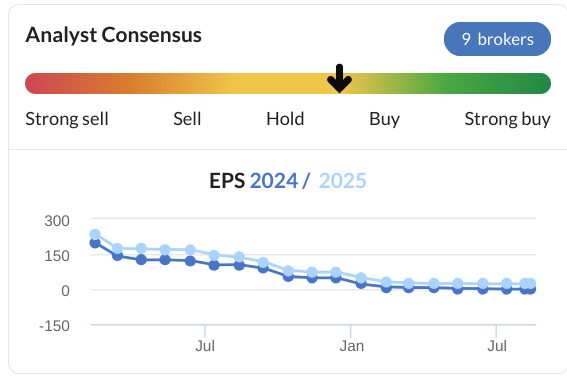
Broker forecasts - note the very poor trend in broker consensus below. Have end markets really fallen this much, or are competitors getting the business instead, or at least forcing lower pricing on SYNT maybe?
Paul’s opinion - I think this is still quite a big mess. Bulls must be hoping to see a dramatic improvement in future profitability, which is needed to reduce debt down to more normal levels.
To me, risk:reward seems poor right now, with a mountain of debt to service, let alone repay.
Cashflow looks very poor in H1, and wasn’t great last year either, with the only significant cash inflows coming from disposals, and the £266m equity fundraise last year. I reckon that probably won’t be the last equity raise.
Remember I’m only analysing the basic numbers, not trying to predict how the business will perform in future. If you think there’s a spectacular turnaround opportunity here, then it might be worth taking on all the risk. Each 1% rise in profit margin is £20m extra profit - not bad if they can raise margins in an economic recovery.
For me, it has to be AMBER/RED again, to flag that this is still an overly-indebted business, and it’s not trading very well either, with no particular upside yet apparent in the outlook comments either. Shareholders have to hope that changes for the better.
Maybe I've missed something, as the StockRanks are mildly positive on this share -

Just (LON:JUST)
Up 11% to 131p (£1.35bn) - H1 Results - Paul - AMBER
“The insurance segment writes insurance products for the retirement market – which include Guaranteed Income for Life Solutions, Defined Benefit De-risking Solutions, Care Plans and Protection – and invests the premiums received from these contracts in debt and other fixed income securities, gilts, liquidity funds, Lifetime Mortgage advances and other illiquid assets.
The advisory segments of the professional services business, HUB, represents the other operating segments.”
This is reflected in a large & complicated balance sheet, which has £31.0bn in financial investments - mainly bonds/gilts. Total assets are £33.4bn.
The creditors side of the balance sheet is mainly £24.9bn insurance contract liabilities - which will be the future payments it has to pay out to pensioners. There are £7.25bn other liabilities.
This leaves only a sliver of equity, at £908m, plus £322m “tier 1 notes” shown separately, giving a total equity of £1.23bn. That means equity is only 3.8% of total liabilities. So it wouldn’t take a large or unexpected change in any of the big assets or creditor lines, to have a very highly geared impact (or benefit) to total equity. This is what puts me off investing in insurers, banks, etc, as their profit figures are a combination of estimates and assumptions, on very large balance sheet numbers. We have to take it on trust that all the accounting is being done prudently, and that nothing untoward is being covered up.
The share price has risen c.11% today, which takes the market cap up to c.£1.35bn, which is slightly above NAV of £1.23bn (there are only £41m of intangible assets, so I’ve ignored that as immaterial).
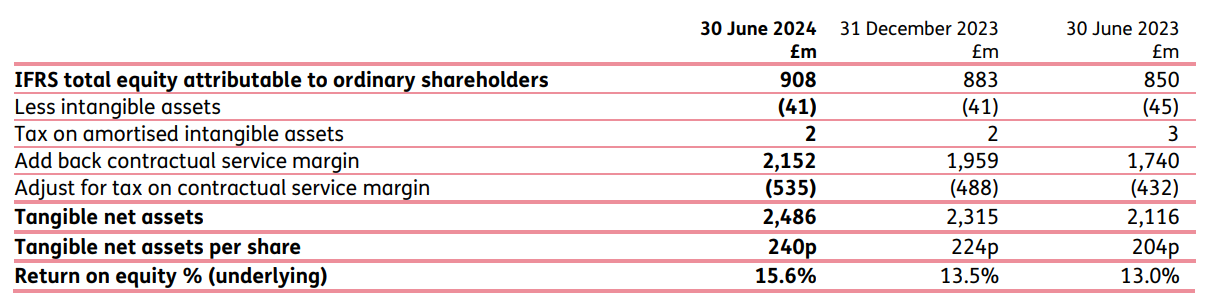
The company reckons it has 240p/share in NTAV, way above how I calculate it. The reason is they’re heavily adjusting this figure! -
I’ve just had a look for comparison at the much larger balance sheet at Legal & General (LON:LGEN) and this is even more extreme, with equity of only £3.9bn, versus total liabilities of £522.6bn! Under 1% equity compared with the huge liabilities. I’m surprised that large insurance companies like this are so weakly capitalised, and yet still meet the capital requirement regulations.
H1 profit - this P&L below is in a format I’m not familiar with - I didn’t really want to review this company (I marked it as too complicated last time I had a look here on 8/3/2024), but given that there’s so little other news, and its share price is so strong, I felt obliged to take a closer look today.
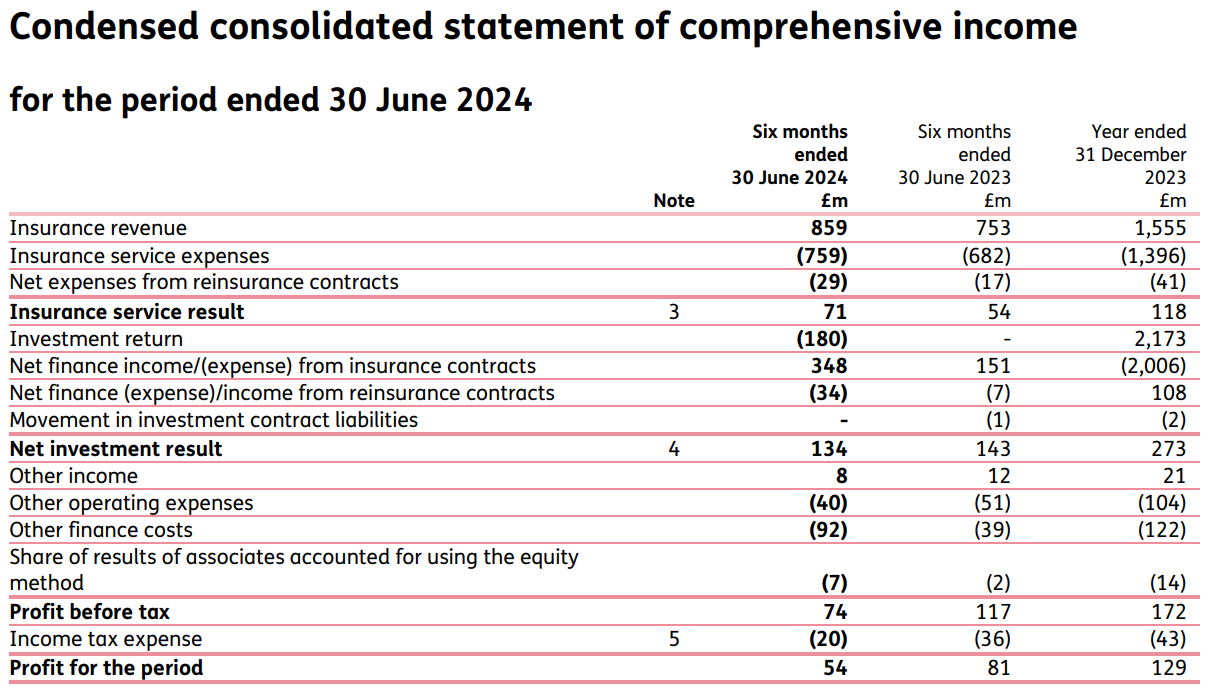
The number that stands out is the £(180)m investment return in H1 this year.
Also how small the PBT figure is at £74m, well down on £117m in the H1 LY. This makes me wary, as the profit number (very much like the balance sheet equity) is a small sliver from much larger numbers, and not necessarily under the company’s control (eg investment returns, actuarial issues, etc), which further puts me off wanting to invest in this sector. It worries me that the bumper dividend yields (9.6% at LGEN) don’t have a lot of backing, so could be vulnerable if something unexpected were to happen.
Most highlighted profit comes from adjustments. Note the £74m H1 profit above, which becomes much larger thanks to big adjustments -

3 Contractual Service Margin.
Outlook - the commentary is bullish, and this bit below is clearly what’s driven the shares up strongly today -
“Given the strong first half outcome, the positive market dynamics, and our forward-looking pipeline, we expect to substantially exceed previous 2024 guidance of doubling 2021’s £211m operating profit in three years.”
“Momentum remains strong as we enter the second half of 2024. We forecast second half new business volumes to be similar to the excellent performance in the first half, albeit with slightly lower margins due to business mix. We expect the strong structural growth drivers of our markets to continue well into the future. “
Given that the profits are mainly coming from adjustments, plus numerous complicated accounting judgements, then personally I wouldn’t be particularly confident about relying on the adjusted numbers.
Paul’s opinion - not my sector at all, so this is just a review of the basic numbers from a generalist.
I can see why this share is in a bullish uptrend, as it seems to be winning plenty of new business, eg from companies wanting to de-risk their defined benefit pension schemes. Higher interest rates have created more favourable circumstances, often reducing deficits, and making it possible and affordable for companies to offload their pension schemes, eg as we’ve seen with several companies we follow here (eg recently Sanderson Design (LON:SDG) disposed of a small pension scheme to an insurer).
The insurers just have to hope that they’ve got all their actuarial calculations right, and that nothing untoward happens in future (eg medical advances) resulting in people living longer than expected.
Just is only paying a modest c.2% dividend yield. So the question for investors in this sector, is do you want a very much larger yield from a bigger insurer (eg LGEN at 9.6%), or do you accept a lower yield from JUST in the hope of it achieving faster growth, and not blowing itself up?!
Interest rates coming down could boost the value of JUST’s substantial bond portfolio maybe?
Another key point is your attitude towards the large adjustments JUST makes to its profit & balance sheet NTAV. If you accept those adjustments, then this share looks cheap.
With so many variable large numbers in the accounts, I question how reliable profit numbers are? It strikes me that these could be very volatile, hence applying a low PER is probably sensible.
As it’s not a sector I would ever invest in, for me it’s not of any interest, so I’ll sit on the fence with AMBER.
Investors are however enjoying a good bull run, so let’s hope it continues. Today’s bullish outlook comments seem to reinforce the upside.
Up until late 2020 the performance of JUST shares was poor. It’s now in an up-trend since then -

Graham’s Section:
Genuit (LON:GEN)
Down 4% to 448.5p (£1.12bn) - Half-year Report - Graham - AMBER
Genuit Group plc…, the UK's largest provider of sustainable water, climate and ventilation solutions for the built environment, today announces its unaudited interim results for the six months ended 30 June 2024.
It’s topical that we look at this one, after covering Marshalls (LON:MSLH) yesterday.
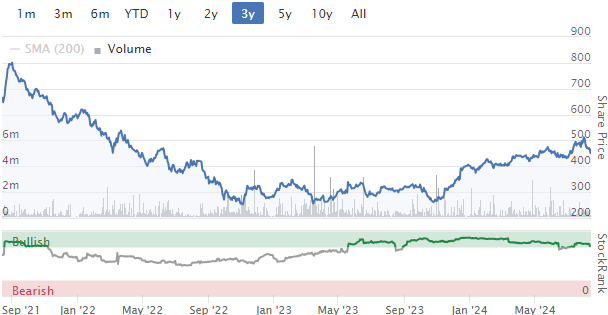
Genuit, formerly known as Polypipe, has enjoyed a share price recovery in 2024, but the long-term picture is uninspiring. Here’s a 3-year chart:
Here are Genuit’s interim results:
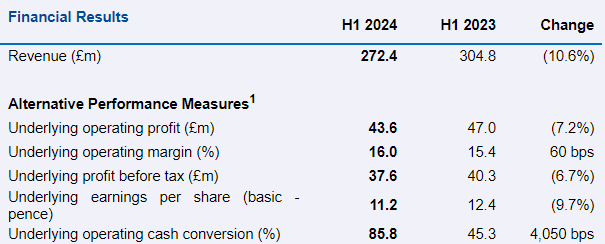
At least in this case we don’t have negative operating leverage: the fall in (adjusted) profitability is no larger (in fact it’s smaller) than the fall in revenue.
Adjusting items: unfortunately, the company has used a heavy set of adjusting items to smooth out the numbers. Actual operating profit is only £21m (down 41% year-on-year) while actual PBT is only £15m, down 48% year-on-year.
The culprit is a big impairment charge (£12m) that has increased the adjusting items from £7m to £19m.
The impairment is at ADEY, a company that makes products for heating and cooling systems (e.g. magnetic filters for boilers).
ADEY was acquired by Genuit/Polypipe in 2021, for a cash price of £210m. It was bought from LDC, the private equity arm of Lloyds.
Unfortunately, ADEY hasn’t lived up to the expectations attached to that buyout price:
Due to the ongoing softness in the boiler filter and chemicals market and a delay to recovery in volumes, related to a suppressed RMI market there has been a reduction in the value in use of the Adey CGU. This has resulted in an impairment charge of £12.4m… any negative changes in key assumptions would result in the recognition of an additional impairment loss.
Impairment is of course a non-cash charge, but It speaks to the success (or failure) of prior acquisitions to create value. So for a company that is likely to engage in more M&A, I think it’s good to be aware of impairment losses.
Genuit has £441m of remaining goodwill on its balance sheet, from all prior acquisitions including ADEY. Let’s hope that the impairment charges stop here.
Balance sheet: emphasising that this company has been built by acquisitions, it has balance sheet net assets of £627m. But if you take away goodwill and other acquired intangibles, and you are left with only around £50m.
Net debt: reduces to £122m (excluding leases). The leverage multiple of 1.1x is already modest but Genuit expects it to fall to 1.0x by year end, “providing further opportunities to deploy capital for accretive M&A”.
CEO comment excerpts:
"Whilst the market remains subdued in 2024, the Group demonstrated continued operating margin improvement in the first half over prior year, as the benefits of our strategic actions continue…
As we look forward into the second half, we currently anticipate these market conditions to remain, offset by continued operational and strategic progress. We continue to expect full year underlying operating profit to be within the range of analyst forecasts. The Genuit Group is exceptionally well positioned to benefit from eventual market recovery, with business simplification complete, at least 20% available capacity to ramp production and improved operational gearing providing confidence in medium term targets."
Outlook
Genuit expects more of the same in H2. “a backdrop of low volumes of new housebuilding, a softer commercial construction sector and an RMI market that has been waiting for interest rate reductions”, but they do expect to generate a profit within the range of forecasts.
The outlook statement from Genuit stands in contrast to Marshalls, who were “cautiously optimistic of a modest recovery” in H2, based on the assumption that the macro environment would improve.
There is no such optimism from Genuit, and I applaud them for it - it’s good to be ready for an economic recovery, but we can’t assume it will happen!
Forecasts: Genuit is forecast to generate an underlying operating profit of £92.1m - £96m this year.
Graham’s view
I apologise that I can’t bring a high-conviction positive or negative stance to this one.
As with Marshalls, I think there are easier ways to find value than to get involved here. But if you are very positive on the economy, then this cyclically exposed stock would probably be a fine way to express that view.
I do have a slight preference for this one over Marshalls. Marshalls seemed to hang their hat on a macroeconomic recovery in H2, and on the basis of that expectation they said their results would be “broadly” in line.
Genuit, on the other hand, seems to have no expectation of a recovery, and yet it says that its results are still trending in line - with no use of the word “broadly”!
Stockopedia’s useful “Compare” tool agrees with me: in a head-to-head battle, Genuit wins 22 out of 37 comparisons.

Marshalls (right hand side) wins on historic value, but Genuit (left hand side) wins on forecast value and growth:
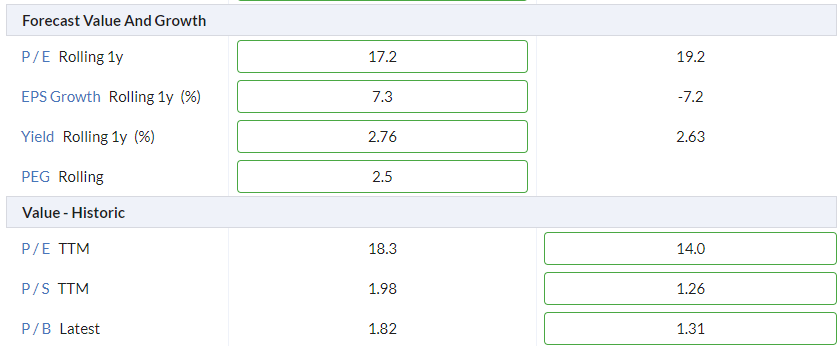
I also have a slight preference for the shareholder register at Genuit: it has more fund managers whose research I’d be happy to piggyback on (and who might not own it simply because it’s needed in an ETF)..

At the end of the day, though, I’m still neutral on this one.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

45 comments
I see both Henry Boot (LON:BOOT) and Harworth (LON:HWG) down today - I suspect could be due to rumours of Labour putting a cap on the amount profit on land sales.
A lot of trades this afternoon in TT electronics (LON:TTG. Is the market belatedly catching up with my somewhat isolated enthusiasm, read-across from another share, or is there a whisper?
Hi Paul - there's a link in the top of the SCVR for the summary spreadsheet:
New SCVR summary spreadsheet from July 2023 onwards.
....but that got too big so hasn't been updated since July this year. Has this been discontinued, or is it just that there's no link to the current one? Personally I find it a useful at-a-glance summary of things for further research, but I appreciate it's just one more thing for you to work on.....
I'm trying to construct a screen to short-list companies with
Any pointers/help in selecting which metrics to use in screening would be greatly appreciated.
US inflation print has come in well under expectations, so the Fed is cleared to cut in September, even by 50 bps though I doubt we’ll see that happen. Initial response in the futures is positive but remember this means that the economy is slowing faster than expected - so the recession question may rear its head again when investors think twice.
2 directors bought shares in Oakley Capital Investments (LON:OCI) recently.
Graham, Genuit vs Marshalls, the key difference is that the former’s growth is supported by important regulatory drivers linked to climate exigences, the latter is waiting for a general improvement in the economy. Or to put it another way, is anyone else experiencing rain ingress, flooding and mould recently? Or are you more worried about the patio?
Nice comment BnB! It's noteworthy that environmental investors Impax Asset Management (LON:IPX) are #1 on the register at Genuit.
https://muckrack.com/simon-tho...
First-half revenue up 17 per cent to £25.6mnAdjusted pre-tax profit up 54 per cent to £2.8mnSales order intake up a third to £24mn£60mn sales opportunity pipelineEarnings upgrades Journeo (JNEO:270p), a leading intelligent transport systems provider, has reported record first-half trading and upgraded full-year earnings guidance. The performance has been underpinned by a raft of contract awards from blue-chip transport operators and local authorities that are backed by government funding.
ignore the review above !
Paul is right that the equity of insurance companies is basically the difference between 2 very large numbers - financial assets and liabilities. The latter is itself based on a large number of assumptions (eg about life expectancy). This does sound quite alarming as a small move in either could in theory wipe out the equity. However, I take comfort from the very resilient performance of the life insurers during recent market shocks, eg during the pandemic and the surge in gilt yields following the Truss budget - their solvency ratios held up very well during both these episodes.
It should be remembered that a lot of their assets are held in very safe assets, such as highly rated bonds, while they will also use a lot of hedging to minimise movements in interest rates. Obviously no-one knows what's really under the bonnet and requires a lot of trust in management and the actuaries, but ultimately these companies have been stress tested like never before in recent years and come through unscathed, so I'm happy to keep a small exposure to some of these companies, currently holding Just (LON:JUST) and M&G (LON:MNG)
Just (LON:JUST) these businesses are indeed complicated from a financial perspective which I understand puts some people off but they are not the same risk profile as banks that may have lots of illiquid stuff off balance sheet that can interfere with book value. You do need to understand the diff between the business models and risk management to take a view. I’m not surprised Paul has avoided commenting as it is quite specialist.
Nonetheless the key driver of value for me will be TNAV and strong solvency ratios.
I note several brokers have upgraded price targets this morning up towards 170/175p so there is a clear upgrade in expectations here.
Just (LON:JUST) I agree. If I can maybe help simplify things on TNAV. The main adjustment is Contractual Service Margin. A new accounting standard recently introduced required all these companies to defer initial day 1 revenue on writing the policy (which was received on day 1 in cash) over the life of the contract until the new pensioner dies. This is stupid accounting and is adjusted by the companies and for the Solvency calculations, presumably because everyone thinks its stupid! That is why there has been a massive reduction in net assets at all these companies. Legal & General (LON:LGEN), for example, has about the same Contractual Service Margin (£13bn!) OR deferred profits as its market cap. The profit unwind of this deferred profit is virtually certain over time and is included in reserves for Solvency calculations. So, they have £13bn of capital just sitting there, but not included in NAV (i.e. Dr Cash or other Assets Cr CSM Liabilities). Previously, the entries were Dr. Cash/Other Assets Cr. Equity.
Just has always been a weaker play than others because it invests most of its day 1 cash in lifetime mortgages. That is why it can't pay a decent dividend as the cash comes in from annuities and goes straight back out in lifetime mortgages. That being said they have made a good recovery. I much prefer the other players in the sector though, but have missed out on the recovery here. Their new business strain is impressive at 1.5% versus 4% at LGEN. Anyone know why? It's interesting that this company's share price performance has been much stronger than the high yield plays. Personally, I prefer to follow the companies that generate cash in this sector, but that hasn't been great in share price performance recently... you just collect the 8-10% dividends.
Just (LON:JUST) changed their business model and sold off large chunks of their lifetime mortgages so there is no longer such a short term cash drain (or at least much less). That is why they are now self capital generating and have a much lighter capital model than they used to. It has also significantly improved sensitivity to interest rates. The new business strain will be down to mix of products and margins - I suspect focussing on smaller portfolios generates lower year 1 costs than the likes of Phoenix group (LON:PHNX) or Legal & General (LON:LGEN).
The flipside is that Just (LON:JUST) should really up the dividend now that they can. I understand the rationale of growing it at 20% a year in a progressive manner but I think shareholders have waited long enough for the turnaround that a bigger income yield would be more appropriate.
Anyway we will see. I’d hope that TNAV can continue growing at the clip it is doing as that would make TNAV closer to 260p by y/e.
Agree that the IFRS17 rules don’t really cut the mustard. A bit like the change in rules on leases becoming net debt - at first glance you can be fooled into thinking the business is in worse shape or making large adjustments when it isn’t. Paul made exactly that leap as a neutral to the sector.
Just (LON:JUST) Thank God someone can make head or tail of it and many thanks for the explanations (I hold).
I don’t think anyone here can really understand the balance sheets of large insurers or banks sufficiently to have an informed view on value. They look great until there’s an accounting/systemic or other problem not specifically foreseeable. For that reason private investors can’t really have an edge investing in such companies because the unknowns are frankly unknowable. I never invest in complex financials. Trade possibly but only immediately after results when clear decks provide a short but uncertain window of relative safety. Endless pontification on complicated balance sheets and solvency ratios is fairly futile in my view.
Thank you davidjhill and strawberrydreams for helping me think about Genedrive (LON:GDR) .
I would like to be positive about this share (dangerous). Herewith the positive case (never buy on just a good story). I don't remember NICE recommending a Genedrive (LON:GDR) test as 'best in show' before. Perhaps that's why Manchester stroke centre have bought it. Good stats from Manchester may persuade the other 39 centres to buy. Similarly, the innovative baby test fast tracked through the FDA, if successful, may bring US sales (no competition, savings for US medical insurers). These may boost Genedrive (LON:GDR) from heavily lossmaking minnow to minnow.
But Genedrive (LON:GDR) has been around a while, declining from major threat to no threat. Existing major players have, however, seen potentially commercial R & D. I guess this expertise is in quite short supply giving some value to Genedrive (LON:GDR) . With a market cap of only £18m, it's probably attractive to several, and may therefore not be left too long in case someone else snaps it up.
But then, I don't know anything about medical testing market (risk comes from not knowing what you are doing}. I shall try to hang on for a year anticipating a sensible bid and a comfortable glow of I told 'em so!
I also see Genedrive as potentially attractive on a risk/reward basis. I bought quite a few at 2p and sold half on the recent spike so I’m in for a free ride. To balance my generally positive view I am concerned by the sudden departure of the CEO which came out of the blue with no real explanation (but with cursory thanks from the board). My other reservation is around IP and whether the technology is easy to replicate. I don’t know the answer but would like to hear from anyone with more knowledge of the sector.
Genedrive (LON:GDR) has always looked attractive on a risk / reward basis but has never generated meaningful revenues, despite several changes at the top. Of course that doesn’t mean it isn’t good for a trade, like any stock but personally I’d want to see genuine signs of proper revenue growth before I got too excited. Their products have been taken by one health trust before with fanfare but that did not translate to other take ups. Anyway, it has a long history of tapping shareholders in dilutive fashion for tests that will change the world…….but never seem to do. At this stage of the companies history proof is really required to restore any credibility for me.
Journeo (LON:JNEO)
Any reason for today’s large rise - doesn’t look like any volume to go with it but that was the same when it was falling recently.
Was it tipped somewhere?
Tipped this morning by Simon Thompson in IC.
Ah thanks Helvellyn - wondered what the jump was
Exec summary, please?
I no longer subscribe to IC however i do still get a daily email from them which gives a short teaser of ST's daily or weekly tips. Sorry I cannot help any further.
Journeo (LON:JNEO) Hopefully this counts as exec summary tipped 12.8.24
Strong earnings growth is making this transport stock a bargain.....
Analysts expect 20 per cent annual earnings growth and the cash pile to swell two-thirds RECORD FIRST HALF TRADING / IUPGRADED FULL YEAR EARNINGS
CONTRACT WINS ETC
THINKS ITS ONBOARD SAFETY / CCTV SYSTEMS ARE DOING WELL IN THE MARKET
SAAS LICENCING
#TIG Bit confused stock rankings have increased significantly today, but momentum ranking will surely fall after yesterday’s fall in share price ? I know it is only an opinion but SCVR has a Amber/Red verdict ?
Team Internet (LON:TIG) If you hover the cursor over the green circle it says how much the four rankings have changed recently. This does not seem to agree with your post, however.
Attended Team Internet (LON:TIG) results presentation yesterday. Must be me, as I came away with little understanding of what they do.
Yes but the Stock Movers states it has moved from 87 to 92 ?
Team Internet (LON:TIG) Q and V are both up. M is down only 3 at the moment. Will be updated overnight.
#TIG
Team Internet (LON:TIG)
Impressive results this morning for Just (LON:JUST). Profits up 44%. Time for a rerating perhaps as still trades on a lowly PE....
Just (LON:JUST) yes very impressive results and substantial increase in guidance - yet trading on a PE under 4 and more than 50% discount to tangible book value. Time for a proper rerating?
@JUST Adjusted results look great but there is a huge adjustment for CSM (Contractual Service Margin?) Can anyone explain exactly what this is and what this adjustment means please
Morning Ned - Afraid it isn't a light topic! Below is a 117 page document!
https://www.actuaries.org.uk/s...
Just (LON:JUST) Many thanks exlifeme and Davidjhill. I think I will skip the 117 pages bur have enough from your summaries. Does seem to be a store of value for the future.
This basically means that the profit needs to be spread over the life of contract service under IFRS17. So the adjustment is the amount saved to be applied in future years. In theory that means you have much smoother profit progression over time and visibility.
Just (LON:JUST)
Agreed - the strength of the results are probably best seen in the change in TNAV - up at 240p.
Compared to peers valuation looks bonkers to me. I know the dividend was up 20% but that still needs to be higher - closer to 4 or 5% (double where it is)
Nonetheless you’d hope for a significant re-rating. Given trajectory of the business it is likely to be trading at a 50% discount to NAV even after todays rise by y/e and I just don’t think that’s justified.
Burned my fingers on Just (LON:JUST) and bailed out when rebalancing my porfolio, I would keep an eye on Director bonuses here.
Also a good read-across to Phoenix group (LON:PHNX) .
DB Pension Buy-in: good to see Just (LON:JUST) having 31% YoY growth here. They do play in different parts of the market (Just has avg transaction value £34m, Phoenix is like £200m-£2bn I believe?) but good that there is buoyant demand.
Retirement solutions / guaranteed income products like annuities. Just saw new business 28% YoY. Which Phoenix are keen on growing with their Standard Life brand.
--------
Phoenix currently on 10% dividend, because the market doesn't quite believe that their New Business generation will offset declining closed-book income.
However, the results from Just suggest that Phoenix will continue to acquire more Closed Book, as well as grow their New Business. Could see that 10% div re-rate to 7%, in which case there's a potential 40% share price gain...
(I hold in the Boon Fund)
On yesterday’s report I referred to a very recent (less than 24 hours ago) meeting with my bank’s industrials analyst. They are bearish on autos and bullish on building technologies. So, if Dowlais (LON:DWL) tanks on its poor TU this morning, or Genuit (LON:GEN) falls on the second half risks to its “in line” outlook, then they would avoid the former and buy the latter. I have been top-slicing Genuit to manage the position size but would top back up on a material fall that doubled last week’s indiscriminate tumble.
On yesterday’s report I referred to a very recent (less than 24 hours ago) meeting with my bank’s industrials analyst. They are bearish on autos and bullish on building technologies. So, if Dowlais (LON:DWL) tanks on its poor TU this morning, or Genuit (LON:GEN) falls on the second half risks to its “in line” outlook, then they would avoid the former and buy the latter. I have been top-slicing Genuit to manage the position size but would top back up on a material fall that doubled last week’s indiscriminate tumble.
For a bit of balance, I would say that the price action in Dowlais this morning suggests it may be finding a bottom. It’s cheap alright and a bit crap but there will be good gains on an upcycle when that eventually occurs.
On Dowlais (LON:DWL) (I hold a small amount) Thought they were hitting bottom at ~75 a few months ago. This turned out to be wrong. I decided to hold for the results today. Not great.
They haven't tanked today so far but I do not see a bottom as they have reduced expectations again. looks like this was expected.
And looking at the chart...
Not a believer in technical analysis but ... what was i thinking?
I see the strategy of providing ice and electric powertrains as generaly sensible, and it is cyclical, but when will they start making money out of it?
Decided to carry on holding until year end results, but would I buy now? - No (If this were colour coded, the colour would be brown)
Good news for UK real incomes & consumer demand, but bad news for inflation & the pace of future interest rate cuts.
Today UK average weekly earnings for June (ex bonuses) came in at 5.4% YoY vs consensus of 5.4% & May 5.8%. Or roughly double the pace the BoE believes is compatible with keeping CPI at its 2% target.
Plus Chancellor Rachel Reeves has already approved pay rises of 5%+ for millions of public sector workers, including a 22% hike for junior doctors over two years in order to resolve long-running strike action.
The wage data is still moving in the right direction and is of course well out of date. Monday's CIPD business leader survey showed business leaders are only expecting to raise wages by 3% in the coming year, the level consistent with 2% inflation (3% services and 0% goods inflation being a typical mix).