Small Cap Value Report (Tue 13 Dec 2022) - CRU, SRC, OTMP, SOS, REAT, BEG, ACC, FCAP, DNM, ZYT, SYNT, GPH, FRP, SNX

Good morning from Paul & Graham! Today's report is now finished.
We've hit the ground running today, as Graham had a second wind yesterday afternoon & has prepared some extra sections for today's report.
Agenda
Paul's Section:
OnTheMarket (LON:OTMP) [quick comment] - announces a new share dealing facility, which looks designed to match up buyers with sellers from the expiry of 5-year lock-ins from the IPO in Feb 2018. This relates to both management, and estate agents that are also shareholders (some were given free shares in return for signing paying contracts). Zeus and Shore Capital will be looking to find buyers for the loose shares which might cause an overhang in the market, if holders try to sell individually. Sounds a sensible plan to me, but it is a reminder of the unusual shareholding structure with this company, which could suppress the share price next year if there are not enough ready buyers to absorb sellers’ shares. (no section below)
Sosandar (LON:SOS) - breakeven interim results (the slower half), and in line with expectations (PBT £2.0m) for FY 3/2023 outlook comments. Things look very good to me. Superb organic growth of +72% in H1 revenues. Big increase in inventories should unwind in H2, and cash looks fine - little if any risk of any more placings. Seems to be shrugging off the consumer downturn. Looks very good to me, as a long-term hold, so a thumbs up. More detail below.
React (LON:REAT) [quick comment] - says that trading in Q4 of FY 9/2022 was “especially strong”, and this has continued into the new financial year, where mgt sees an “optimistic outlook”. Today’s update seems to be a repeat of the TU on 26 October, but with less detail, so what’s the point? Maybe they want to get the share price up, to do another placing? This is the fundamental problem with REAT - it’s too small, and shares too cheap, to add value from acquisitions funded by discounted placings. The business itself actually looks potentially interesting. So if they can crack the problem of excessive dilution in discounted placings, then it might work. Worth keeping an eye on, I reckon. (no section below).
Access Intelligence (LON:ACC) [quick comment] - down 27% to 64p, on a badly received trading update. I took a dim view of this company when last looking at it in Jan 2022 here. Guidance for FY 11/2022 says it's ahead of expectations, with £65.6m revenues, and adj EBITDA of £2.3m. Although bear in mind its breakeven H1 adj EBITDA became a £(4.3)m adjusted loss, and a £(7.6)m statutory loss, so we can take EBITDA with a pinch of salt, as it’s capitalising a lot of costs (£3.5m development spend in H1 alone). Cash position looking tight now at £4.8m (down from £9.3m at end May 2022). Waffly commentary talks about slowdown in order intake in USA, and difficulty converting pipeline into contracts. Weakish balance sheet. Looks risky to me, I’d steer clear. (no section below)
Dianomi (LON:DNM) [quick comment] - this is a new one for me, but it’s come up on the top fallers list today, down 15% on a trading update. It’s another 2021 float that’s done badly - down almost 80% from Sept 2021. Dianomi provides digital advertising services. Adj EBITDA for FY 12/2022 is expected to halve vs LY (LY: £3.1m). That should translate into an actual profit, as the only reconciling item between EBITDA and operating profit, was £250k in share based payments in H1. Cash is £10.8m at end Nov 2022. The last balance sheet was excellent, and it’s not burning cash. This actually looks quite interesting, with about a third of the market cap being net cash. Accounts look clean, with no capitalised development spend. Might be worth a look, if you understand digital marketing. (no section below)
Zytronic (LON:ZYT) [quick comment] - only £14m mkt cap, so we’ll keep this brief. FY 9/2022 results are out today. This bespoke touch-screen maker has suffered from legacy contracts winding down, so £12.3m revenues are now only about half historic levels. Despite that, it remains (modestly) profitable at £0.7m, paying divis too, and has done big share buybacks. Fantastic balance sheet, with freehold & long leasehold property, plus £6.4m net cash. Some supply chain issues persist, but it’s rebuilding the sales pipeline. Risk:reward looks excellent with the balance sheet protecting the downside, and potential upside if new orders are won, which are coming through again in some sectors. Thumbs up from me, if you can cope with something tiny & illiquid - so it’s not one to trade, more a long-term value, special situation I’d say. (no section below)
Synthomer (LON:SYNT) [quick comment] - I’ve been meaning to look at this for a while. Today it announces the disposal of a division for £199m (net), a substantial amount. However, the last H1 accounts show that what looks like a spectacularly badly-timed acquisition was done earlier this year for £760m, increasing net debt from £114m to £993m. Its banking syndicate relaxed covenants to end 2023 (announced 20 Oct 2022). H1 PBT fell by more than half, to £115m. A trading update within today’s disposal announcement doesn’t sound good, with customers de-stocking. It also mentions deteriorating macro conditions originally impacting European operations, now extending to outside Europe. Dividends have been suspended until end 2023. Risk of a dilutive fundraise strikes me as high. This share looks complicated & risky, so I’ll steer clear. (no section below)
Global Ports Holding (LON:GPH) [quick comment] - up 9% to 120p today after interim results announced, which means it’s now bounced c.50% from recent lows. This is another special situation. It owns ports for cruise ships, so revenues have strongly bounced back, and there’s a decent operating profit of $21.9m in H1. The trouble is, finance charges exceed that, at $(27.5)m, so overall it’s loss-making. The group structure looks odds, with a large “Non-controlling interests” line below the P&L. The balance sheet looks horrendous, with large negative NTAV, and mountains of debt. So it looks a high risk:high reward type share, where the equity looks little more than a call option, in the hope that lenders remain docile. The auditors have given it a clean going concern statement today, which is interesting. The main research area would be investigating the terms of the debt mountain. The major shareholder owns 63%, an additional risk. Could be an interesting speculation, for high risk punters. (no section below)
Frp Advisory (LON:FRP) [quick comment] - this is another business advisory services group, like BEG, but higher up the food chain in terms of clients & deals. Hence its shares have been buoyant this year as a counter-cyclical business, benefiting from more insolvencies. H1 results today show adj EPS up slightly at 3.35p (H1 LY: 3.25p). About half is paid out in divis. Net cash of £21.0m, and sound balance sheet. Cenkos has 7.8p adj EPS for this year forecast FY 4/2023. At 159p per share, that’s a PER of 20.4x, which strikes me as over-priced, although in a recession it might out-perform. In line full year outlook. This type of business has a structural conflict between the interests of the partners, and the outside shareholders - e.g. partners were invited to sell 20% of their holdings in a secondary placing, in return for a lock-in extended to June 2024. The risk is, at some stage, the big earners might leave, and outside shareholders are left with the bathwater. It’s not for me. [no section below]
Synectics (LON:SNX) [quick comment] - a £20m mkt cap CCTV company. Today’s update says FY 11/2022 is now expected to be “slightly ahead of market expectations”, due to H2 improving on H1. Says it’s coping OK with inflation & supply chain issues. Net cash roughly flat, at £4.1m. LAst balance sheet at interims looks OK. It sounds as if the business is recovering from the last couple of years’ problems with the pandemic & supply chains. Could be a recovery share from here, quite good value. Thumbs up from me, on the basis that it’s not the best business in our universe, but does look cheap for a recovery that seems to be quite credible. (no section below)
Graham's Section:
Coral Products (LON:CRU) (£17m) - this plastics manufacturing and distribution group announces solid H1 results. It can’t prove organic revenue growth, due to some bad luck in China, but four acquired companies have all performed according to plan so far. There is potential for synergies to start kicking in over the next year, and this could boost the quality of financial performance. Overall, I see more to like than to dislike and think it could be worth researching in further detail.
Sigmaroc (LON:SRC) (£365m) (+3%) [no section below] - this construction materials quarrying group has announced an update for FY December 2022. Revenues year-to-date are up 20% on a like-for-like basis to £498m, and full-year underlying EPS is now expected to come in 10% higher than expectations (these expectations were at 7p). This has been achieved with the help of strong industrial demand, and through cost management. Importantly, the FY December 2023 outlook is unchanged, as visibility is “challenging”. If you’re interested in carbon capture technology, Sigmaroc has released an impressive-looking video on YouTube today - here. This company strikes me as being probably a good, reputable business but operating in a difficult industry, where many important prices and factors are beyond its control. It’s also carrying a heavy debt load that stood at £234m (excluding leases) as of June 2022. Nevertheless, this stock will be of interest to those who are comfortable investing in the construction materials industry. (no section below)
Begbies Traynor (LON:BEG) (£217m) - Begbies releases H1 results and confirms that it still expects to hit its sales and earnings estimates for the current financial year (FY April 2023). I take a look at the organic growth here - which is not bad - and make some broader comments on the state of the insolvency market. Zombie companies are at last being liquidated as the economy cleans itself up after many years of zero interest rates and Covid-related support schemes. When it comes to Begbies shares, I still think that the valuation is at risk of becoming over-cooked. The market possibly agrees with me as the shares have come off a few percentage points this morning, despite an in-line outlook statement from the company.
finnCap (LON:FCAP) (£27m) (-1%) [no section below] - this boutique investment bank announces H1 results in line with expectations. Despite the lack of IPOs, it has been busy with public and private M&A advisory work, debt financing mandates and placings. All of these, however, are at much lower levels compared to last year. Revenue is down 48% to £16.4m. There is an adjusted pre-tax loss of £0.6m and a statutory pre-tax loss of £2.6m. From an investor perspective, I always look for these types of companies to control their cost base in such a way that they can avoid making a loss, even in the bad times. Over this H1 period, however, Finncap has failed to do this, even though its advisory business model has developed to become in theory less cyclical than pure equity broking. I’d be much more impressed if it had reached breakeven: wage inflation for customer-facing staff, insurance and IT costs are all mentioned. Headcount has now been reduced and the interim dividend is cancelled. At around tangible book value and at a paltry multiple of what this company can earn in a bull market, the shares do look undervalued to me, although my first preference is for banks and brokers that can show a small profit even in bear markets. [no section below]
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul's Section:
Sosandar (LON:SOS)
22.5p (pre market open)
Market cap £50m
Sosandar PLC (AIM: SOS), one of the fastest growing fashion brands in the UK, creating quality, trend-led products for women of all ages, is pleased to announce its financial results for the six months ended 30 September 2022 and an update on current trading.
Company’s summary -
Continued revenue growth of +72%, delivering the Company's second six-month period of positive PBT. Momentum has continued into the second half of the financial year with record sales months in October and November, trading in line with market expectations* for the full financial year.
H1 key figures -
Revenue £21.0m, up a remarkable +72% (all organic growth too)
Gross margin 54.4% (down from 56.5% H1 LY) - due to more discounting in the end of summer season sale.
Profit before tax a whisker above breakeven, at £77k (H1 LY: £(1.08)m loss)
H1 tends to be seasonally slower than H2 remember, so we should see a more profitable H2 and hence FY 3/2023.
Balance sheet - huge increase in inventories to £13.5m, but cash position still looks OK, at £4.2m - that should improve as they de-stock over the peak selling period now.
The commentary says autumn/winter stock was brought in early, to avoid supply chain issues, and using slower (but much cheaper) sea freight.
Cashflow statement - absorbed cash of £2.8m, due to increased working capital, £6.2m increase in inventories, partially offset by £3.1m in trade payables. I’d expect to see this reverse in H2, so not a concern.
Overseas - this is the next logical growth area, and could propel the shares much higher (I remember years ago when Asos shares went ballistic after it began overseas expansion). Today SOS says -
Looking ahead, we will continue to invest in our own site, the bedrock of the Sosandar lifestyle hub, whilst also exploring additional third-party partnerships in the UK and abroad.
Current trading & outlook - sounds positive, but light on detail. SOS often refers to record months, but that’s a given, when the company is growing so fast, so doesn’t actually tell us very much!
However, this is the most important bit, confirming market expectations, with a useful footnote too -
We continue to trade in line with market expectations for the full year and remain confident in the longer-term outlook for the business."
* Sosandar believes that market expectations for the year ending 31 March 2023 are currently revenue of £42.8 million and PBT of £2.0 million.
That would represent a very strong H2 performance, with nearly all that £2.0m PBT being made in H2. Also note that SOS accounts are very clean, with no adjustments to profit, so this is real profit. H2 should also be highly cash generative, as those inventories turn into cash, so I could imagine year end FY 3/2023 net cash being close to £10m. Hence the days of placings now look well behind us.
My opinion - it’s lovely to see what was originally a blue sky project actually work (very rare)! Despite this, shareholder returns have so far been quite limited. It floated at 15p, and is now only 22.5p. That’s partly because with hindsight the IPO valuation was way too high for a startup, and also because the number of shares in issue roughly doubled through a series of placings needed when the cash ran out several times during the growth phase.
All credit to management though, for pulling off this huge challenge of creating an entirely new brand.
Shares look attractively priced to me, with a PER of 26.8x for FY 3/2023, and 16.5x for FY 3/2024, based on Singers forecasts (many thanks for making those available). It's unusual to see such rapid growth at a relatively sensible PER.
I’d be inclined to sit tight, and let this success story run. There is fashion risk, and key person risk due to the importance of the joint-CEOs. Apart from that, everything looks very positive to me.
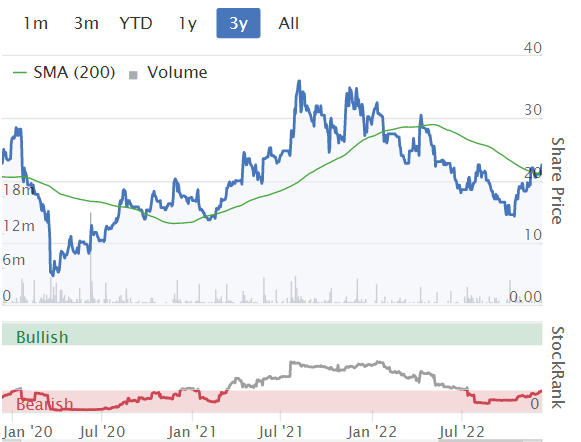
The low StockRank is a flag for us to double-check the bull case, but in this situation I'm happy to ignore the low StockRank, because the balance sheet is fine, and this is a breakthrough year, when the relentless losses of the past are turning into a decent profit for the first time. We know that, but the computers don't (yet)! Hence the StockRank should gradually improve, as momentum and profits flow through into the numbers in due course. We can get in ahead of that.
Graham's Section:
Coral Products (LON:CRU)
Share price: 18.25p (+4%)
Market cap: £17m
We don’t normally cover this one: “a specialist in the design, manufacture and supply of plastic products”. Its website is here.
H1 results issued on Monday show an almost 150% increase in revenues to £17.6m, as newly-acquired businesses now account for most (£10.3m) of its sales.
Impressively, it made both a positive adjusted operating profit (£1.4m) and a positive reported PBT (£0.9m), despite making four acquisitions in 2022. We often see deal-related costs eating up any available profits in at least the first year or two, but not in this case.
Amazingly, all four acquisitions are said to have gone to plan so far.
Organic growth at a group level is not immediately obvious. The company reports that two of its existing businesses saw combined organic growth of 11.1%, but acknowledges that this was offset by weakness elsewhere. Logistical difficulties in China are holding things up.
Based on the level of H1 sales last year (£7.1m), I have the impression that overall H1 organic growth at CRU was low. If not for the problems in China, it might have been a better result on that front.
Capex - the company isn’t resting on its laurels and plans to spend £2.5m on capex, including additional manufacturing capacity of 5000 sq. feet.
Cash - £3.8m, offset by borrowings of £7.5m. So I make that net debt of £3.7m, excluding lease liabilities. The unchanged interim dividend of 0.5p will cost around half a million pounds.
Outlook is upbeat.The company is looking for efficiencies in H1 at the acquired business, has fixed its energy costs (for how long?), and will consider further M&A.
Comment from the Exec Chairman:
Our objective is to build a specialist UK plastics business of scale, targeting profitable, high-demand sectors. We aim to drive growth both organically and via acquisitions, whilst maintaining our commitment to sustainable objectives… We remain prudent with a strong balance sheet, backed by freehold assets and cash, and we look to return value to shareholders via dividends and capital growth.
Investor Meet Company presentation - on Wednesday morning. Here’s the link.
My view
As a manufacturer and distributor, the gross margins at Coral Products are modest. Indeed, gross margins have reduced to 27.1% following the addition of the acquired businesses (last year: 35.7%).
They now have seven subsidiaries, of which four are recent additions. The potential for synergies sounds promising, e.g. sharing expertise and other resources. I don’t see any plans for outright integrations.
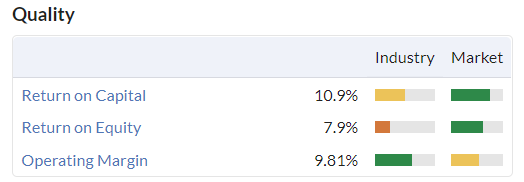
The overall quality seems ok. Some quick back-of-the-envelope calculations suggest that the company might be earning a reasonable return on its invested capital. Although it’s too soon to tell - it all depends on management’s ability to manage four newly-acquired businesses, in addition to the three they already had!
Stockopedia’s calculations like it a lot: it gets a QualityRank of 94.
I’m also impressed that it hasn’t diluted its shareholders much in recent years, has a track record of attempting to pay dividends when it can afford to, and is led by its largest shareholder in the form of the Executive Chairman.
I’ve not seen anything here that makes me want to run away. Even the valuation is reasonable: it looks like shareholders can do well, if management executes their plans. Might be worth tuning in to the presentation on Wednesday.

Begbies Traynor (LON:BEG)
Share price: 140.7p (-4%)
Market cap: £217m
Begbies is “the business recovery, financial advisory and property services consultancy” that many of us are familiar with. Today it releases H1 results for the period to October, confirming the numbers we saw in the recent H1 update.
- Revenue £58.5m up 12% (last year: £52.3m)
- Adjusted PBT £9m (£8m)
- Actual PBT £5m (£2.7m)
Note that Begbies has been busy on the acquisition front, so it’s important to clarify organic vs. non-organic growth.
We can do this by looking at the breakdown of performance at each division:
Business Recovery & Financial Advisory
Revenue in the period increased by 10% to £42.4m (2021: £38.7m), reflecting organic growth (£2.6m) and acquisitions (£1.1m).
Property Advisory and transactional services
Revenue in the period increased by 18% to £16.1m (2021: £13.6m), reflecting the first-time contribution from acquisitions (£1.8m) and organic growth (£0.7m).
By my calculations, organic growth is in the region of 6%, accounting for slightly over half of the reported revenue growth.
For such an acquisitive company, the level of net debt is reassuringly low at just £2.4m. The interim dividend is raised from 1.1p to 1.2p.
Current trading and outlook
As before, they remain confident of delivering full year results in line with expectations.
Begbies helpfully discloses that it believes these expectations to be revenues of £117.7m - £121.4m and adjusted PBT of £19.7m - £20.6m.
Every division appears to be performing well.
Business recovery - many investors appreciate the counter-cyclical nature of a business that thrives during periods of broad financial distress. The order book at this division is up 15% in only six months (i.e. growing very quickly on an annualised basis). It is seeing a “higher level of enquiries and increasing economic headwinds”.
Financial advisory - “encouraging pipeline of engagements across all service lines”.
Property advisory and transactional services - “resilient income streams, continuing flow of new instructions and potential to continue developing its mix of services”.
My view
I think I’ll start to wrap this section up, since little appears to have changed for Begbies and its shareholders. One important observation, however, is the size of the broader insolvency market (and this has read-across to other companies and the economy as a whole):
The number of corporate insolvencies in the 12 months ended 30 September 2022* increased to 20,731, following the removal of the Government's Covid support measures and are now 23% higher than in the comparable pre-pandemic period (2019: 16,836, 2020: 13,781, 2021: 12,492).
Some investors - myself included - have been predicting and betting on an increase in financial distress for what feels like a very long time.
The first and main reason to do this in recent years has been the belief that ZIRP created “zombie companies”, i.e. companies that were ultimately doomed but which could be kept alive temporarily so long as interest rates remained on the floor.
Then, during Covid, support measures such as the job retention scheme provided another mechanism for keeping failed companies alive.
Bank rate is still only 3% but that’s a significant increase from where it was before. The bottom line is that monetary and fiscal supports for zombie companies have now effectively been removed and this is showing up in insolvencies, as you can see from the above figures.
Interestingly, Begbies notes that administrations are still 35% lower than pre-Covid levels. The rise in insolvencies has been seen in the form of much higher liquidations. This is the form of insolvency that’s appropriate for small companies when there is no prospect of the business continuing in any form.
It would make sense for the so-called “zombie companies” to choose liquidation, but administrations are more lucrative for Begbies. So I wonder if it’s actually possible for administrations to recover back to pre-Covid levels?
Overall, I remain a fan of Begbies and I believe that its share price gains in recent years are justified. However, I would return to what I said last time: I would be cautious about paying a very large earnings multiple for a people-based professional services business.
If you’re willing to give the company the benefit of the doubt when it comes to its acquisition-related earnings adjustments, then the PER doesn’t appear overly expensive yet. But those adjustments do have a real effect on the company’s balance sheet, and thus the Begbies balance sheet only has a tangible worth of £8m.

Stockopedia’s calculations also struggle to find much value here, with a ValueRank of only 23. The price to sales multiple is now around 2x.
Don’t get me wrong: I think that Begbies has excellent prospects, and that its share price gains in recent years are well-justified. But I do think we may be reaching an upper limit for its valuation, based on its current size. I’m neutral on the stock at current levels.

Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

77 comments
Coral Products (LON:CRU) - sounds good and nice niche and vertical integration stuff...
But why is it more than a maker of commodity plastic bits? Why is there anything that stops low cost operators from, say, Turkey undercutting their business?
(The Q is asked in fulsome ignorance - thanks)
mojomogoz,
Coral Products (LON:CRU) is nothing but a maker of commodity plastic bits, albeit one that is trying to develop an eco angle. I've no idea if low cost operators from Turkey could undercut their business, but they haven't yet and the current trend towards deglobalisation would seem to be making that less likely.
I bought them originally because analysis showed that they were significantly underpriced, and this became clear to the market once a business and property disposal were completed a year or two ago. I like the way that they have executed a buy and build strategy subsequently, as well as returning large amounts to shareholders through dividends. I don't see any reason why they cannot continue to do this, albeit at a reduced pace.
This is not a share that will multibag in short order, but I do anticipate that it will deliver my target 15% IRR over the medium- to long-term.
PS: It's all horizontal integration; no vertical that I am aware of.
Thanks
Blimey, just woken up in NZ and find I am reading drivel in the comments section about the wrong companies being covered.
As has been pointed out, rather than just complain, write about the companies you find interesting and provoke a debate. If this proves useful, this will no doubt fine tune the VAST NUMBER of companies being covered by Paul and Graham to a HIGH QUALITY level.
It may be water off a duck’s back, but if I were Paul or Graham, I would be fairly unimpressed to say the least, albeit I hope they don’t feel too inclined to spend their time doing something other than the excellent reports we get to read daily.
I've just been catching up on a hectic investing day. And I find that I just want to say thank you Graham and Paul for an excellent coverage of results today. Plenty for everyone I hope with Market Caps from £500m+ down to £14m.
I was not that taken by the short comments to start with - but I've suddenly found that I am addicted to them.
Even though you don't often cover shares I hold (I tend towards the very bottom of the market caps) and I don't always agree with you - on days when I don't quite know where to turn they can start me off in totally unexpected directions. I particularly like that you just tell it as you see it and I very much appreciate your interaction with the community on a daily basis.
Really useful thank you,
cheers
Mark
I find the quick comments from you and Graham enjoyable and helpful Paul. My wife and I are away for a few weeks celebrating our 60th wedding anniversary, I'm suffering cold turkey with a degree of withdrawal from Stockopedia but as long term Zytronic believers I was pleased to read your comment on their results today, thank you.
Synthomer up almost 16%. Can anyone make sense to me of that?
I would guess short covering...
I would definitely favour more mid cap coverage. At the risk of upsetting the apple cart, Graham used to write an excellent mid cap report on his own site - sometimes the way forward is staring you in the face!
Has the rally just started? Positive inflation data in USA
Hargreaves Services
I have just heard on the grapevine (wind farm /forestry) from a very well connected source that Hargreaves are marketing their wind farm portfolio in Scotland for a potential sale .
This will be a very significant transaction which is not factored in the share price .
I have been trying to guess the value but I don’t want to embarrass myself with a wildly inaccurate guess .
On a multiple of potential earnings of wind farms in planning I will simply say I believe it is very significant .
Hargreaves own the land and rent it out to wind farm builders and operators / owners, but don't own any actual wind farms, so if there was a possible sale it would presumably be of the land where wind farm builders have options with Hargreaves.
That’s not quite what I understand .
Its for the property portfolio where there are wind farm applications in progress .
You would THINK they could sell the sites for land value PLUS a multiple of the income that the windfarm builder / operator will be paying the landowner . Around 5-7% I was quoted .
Great long term investment for a pension fund or similar and ticking ESG boxes for them .
Land value maybe circa 10k hectare region .
Income from wind farm on 200 hectares 15 turbines I was quoted around 700k a year based on current values . Apply a multiple to that yearly income numbers scale up nicely !
With Hargreaves Services (LON:HSP) being a recent buy for me I had wondered why the move up in sp this morning with no reported news, looks like there could be some substance in rumour.
Thanks for that Dave.
Richard
Doubt that is the reason , both Christopher mills and Paul scott have been saying good things ? Maybe Paul is the stimulus .
Just to mention another Mello show today and available to all readers here for free.
https://melloevents.com/mello-investment-trusts-and-funds/
The event will feature Fund Manager, Andrew Hollingworth, educational presentations from both Jonathan Davis of Money Makers and Nick Britton of The AIC, as well as company presentations from Arix Bioscience plc and Orchard Funding plc.
The event will also conclude with an Investment Trusts and Funds panel!
Register for free here: https://www.tickettailor.com/events/melloeventslimited/796070
There are lots of interesting sessions and all annual pass holders and individual ticket holders will be sent the recordings within 48 hours of registering.
We hope you can join us.
David
Zytronic (LON:ZYT) (I hold) FY22 Preliminary Results to Sept22
Zytronic is one of my top holdings. Why? Just some quick thoughts as I've been distracted this morning by other things. Hopefully I'll get to update my forecasts shortly.
Turnover and Profit at this micro-cap Newcastle based provider of high-end touchscreens and controllers into the Gaming, Vending, Financial, Industrial and Public Information markets remains well below pre-pandemic levels.
Which on the face of it seems disappointing for a company rated today on
25x the 5.6p FY22 earnings.
Though the company has soundly beaten the – reduced – market estimates it is still struggling to rebuild revenue and profits post-pandemic. Despite this I think there are good reasons to be cheerful for the mid to long term here.
But first an observation. Through the pandemic the company has invested in R&D and launched award winning (and patented) multi-touch multi-user high-end touchscreens. I couldn’t quite ‘see’ why they aren’t they selling like hot cakes? The answer is right in front of me. Or rather its not. It must be very difficult, close on impossible to sell high-end touchscreens without being able to ‘touch’ them and appreciate their usability. Seeing on-line or in a zoom meeting is not believing. Additionally Zytronic sell products to OEM’s who must place their product in front of the end customer. Until trade-exhibitions and face-to-face meetings restarted the ability of the company to gain traction with its new products has been held back enormously.
Those results are now coming through and it seems that the turnaround is underway.
Revenue yoy increase of 5% obscures the 62% rise in gaming revenues to £4.7m and the 38% rise in vending revenues to £3.6m caused by the 59% fall in financial revenues (primarily legacy small format ATM screens).
The rise in vending revenue is particularly interesting - I think - as gaming systems tend to lead the technology takeup with very short product life-cycles whereas vending is undergoing a quiet revolution somewhat brought forward by lockdowns, staff shortages and increasing labour costs as we all transition towards a more automated life-style like it or loath it.
The Financial revenue can't continue to fall at the same rate so its likely near the bottom. In addition there is future opportunity of sales using the encrypted touchscreen product - though the company points out that these are currently impacted by dual-use export controls and concern over dual-use goods finding their way to Russia. Something I'd not considered for these products.
The balance sheet remains rock solid. Net cash of 6.4m is ahead of the 6m guided by the trading statement and EBITDA increased to £1.5m (£1.4m) despite trade receivables and (semiconductor) component inventories increasing ( to assure ability to supply) and indicates that whilst ATM sales have been falling – the company remains a cash-machine by nature.
I admit to a little disappointment – and concern - that the turnaround is taking longer than I’d hoped. It does look as though the turnaround is now gaining traction and that management has done an excellent job for the company and for shareholders in particular in steering through the last few years whilst keeping the focus upon future growth opportunity.
These results are actually better than I'd feared after the trading statement albeit still low. An indication that trading in the last few months has been improving to some extent and the turnaround in sales is underway and in that sense I am very pleased, The increased dividend to 2.2p from 2p also helps.
Cheers
Mark
Zytronic (LON:ZYT) Good summary Mark. The div was actually up from 1.5p to 2.2p, and that along with the positive narrative gives me optimism, like you, that the turnaround is well underway.
I think the pipeline is telling - £59m in September 22, vs £28m September 21 (+110%) - and I would hope that this has been added to as a result of a number of trade shows since then. Their LinkedIn feed has been busy. There are some new products which they are only just starting to showcase now (e.g. Electroglaz and Zybrid Hover) which also look promising.
There is a lagged effect from the pipeline to order intake, and then again to revenue, and of course only a percentage in the pipeline turn into orders, but I an hopeful this will percolate through in due course.
Zytronic (LON:ZYT)
Thank you GavSmith01 - and very well put. Good to hear your views - and the brief positive writeup from Paul above. The pipeline is indeed accelerating which looks very promising. But I'm trying not to count too many chickens right now, having made more than my fair share of mistakes in the last year.
There is a presentation on the Investor meet Company platform this Thursday 15th December at 1pm GMT.
Management have only presented once before and I found them to be open and frank - though nervous at first . The presentation was well worthwhile for me. Particularly for the Q&A which put a lot of colour on the pipeline and sale process.
There looks to be an update on Research Tree from Singer this morning. I can't see it without a subscription - though they refer to updating pbt/eps +45% from a low base. Which looking at the stockreport seems like 3.88 upto 5.6p. Which is not exactly pushing the boat out.
Thanks for correcting my slip up on the increase in dividend 2.2p from 1.5p (not 2p). A healthy increase indeed - especially since since I am dependent upon investment income for living expenses (thanks to the impact of longcovid) and with so many fallen shareprices I prefer to utilise dividend income rather than take capital right now.
I hope to update my forecasts soon and will post here when I manage it,
cheers
Mark
Simoan in case you are reading, you raised a point on Dec 1st about the classification of Next (LON:NXT) by Refinitiv. I followed up on this with Keelan at Stockopedia and Refinitiv initially replied in the vain “it is in the right classification”.
However, yesterday they came back to him with this:
“The TRBC code will be updated as “5340304010-Apparel & Accessories Retailers”.
The TRBC for the companies belonging to the Index Constituents list are changed only during rebalance which takes place twice a year. The next rebalance is scheduled for March/April 2023. Therefore, as of now the TRBC will remain as is, and the next change will be updated in March/April 2023.'”
Regards
Michael
Simoan in case you are reading, you raised a point on Dec 1st about the classification of Next (LON:NXT) by Refinitiv. I followed up on this with Keelan at Stockopedia and Refinitiv initially replied in the vain “it is in the right classification”.
However, yesterday they came back to him with this:
“The TRBC code will be updated as “5340304010-Apparel & Accessories Retailers”.
The TRBC for the companies belonging to the Index Constituents list are changed only during rebalance which takes place twice a year. The next rebalance is scheduled for March/April 2023. Therefore, as of now the TRBC will remain as is, and the next change will be updated in March/April 2023.'”
Thanks, Michael. I heard back from Keelan earlier this morning that the classification for £NXT would be changed in March/April next year. Shame it takes that long but at least common sense will prevail... eventually!
All the best, Si
hi Paul / Graham
Just an admin point from yesterday's SCVR.
Only 2 of 5 the headline company comments were tagged. Also Argentex (LON:AGFX) had some commentary but was not included in the headline list of companies and was also not tagged.
Perhaps you could remedy this?
Thanks.
Snazzy
Hi Snazzy,
That's really helpful, thank you, and well-spotted. I've fixed the title & the tags for yesterday's report now.
The tags are an ongoing frustration - they randomly disappear, either partially, or fully, for a reason nobody can fathom. Absolutely loads disappeared in the past, so I need to go through the last few months and check all the tags, it's on my to do list.
Regards, Paul.
Hey Paul, You should ask Stocko developers to write a script that scans the text for the companies you mention and then insert them in the "securities mentioned" and tags section. It really shouldn't be manual and isn't difficult to do (you already mark them using the "£" feature). You'll spend more time in a week doing it manually than the dev would take to write the script.
Spend your time on the difficult stuff we value, not the paperwork!
Hi wolfspirit,
That's already been done - the tags are put in automatically. The problem is that they seem to randomly disappear sometimes, and nobody can work out why! So I have to double-check when each report is finished, but quite often forget, what with everything else going on.
It is an issue definitely. I went back and checked I think it was Sept's SCVRs, and there were loads of missing tags. So I need to check all of Oct & Nov SCVRs too, it's just finding the time, as we're always so busy.
Apologies for any inconvenience this causes.
Regards, Paul.
I think the characters disappear when the data is transferred and the receiving data type(s) has a different collation/codepage which would then translate it to something else, giving the appearance that the original character has disappeared, where in fact it has been replaced with something else - usually odd looking. I would, as a developer, trace the data and check that all collations/code pages are compatible or the same for the data types on its journey.
Thanks Mark B,
I'll take your word for it! ;-)
Regards, Paul.
" ... no one could work out why ..."
No, I won't get drawn into a debate about debugging as it is done now compared to the old ways! :-)
Futura Medical (LON:FUM) - is this a cup and handle. Makes a medicinal cream and working on regulatory approval for over-the-counter sale. Will need cash for commercialisation but should 'rise to the occasion' once has milestones out of the way.
Just posted to lighten the mood:)
This has long been a jam tomorrow share, and classified by Stockopedia as a momentum trap. However, this is probably a good time to do further research on Futura Medical (LON:FUM) , as they are likely to finally start generating some income next year. They have a novel OTC cream for erectile dysfunction. It has been shown in clinical trials to work. An additional trial requested by FDA was completed last year and regulatory approval is expected in the US in Q1 23. This will be the biggest market. Licensing agreements are in place for many other areas of the world, and production of the product has started. EU launch will happen in the first half of next year. It all depends on marketing and actual sales but the potential market is huge, and broker estimates suggest considerable potential upside. RNS this morning - https://www.stockopedia.com/sh...
Lol, they were supposed to start selling the prophylactics years ago. Remind us what happened. Oh yeah, management screwed it up (pun intended). Zero credibility and deserves bargepole status.
I agree that past 'performance' of management seems very poor. That was then. I would just observe that the current situation seems different . Lessons have been learned, there are different advisers and a different strategy. Of course this remains risky. I still think it is worth people researching further, and I think that 'bargepole status' is too dismissive. On the company website you can see a video of two sexual health experts at a recent conference agreeing that the £FUM product ( Eroxon) could become a first line treatment for erectile dysfunction. FDA approval is highly likely in the next three months and the product is being launched in multiple markets in the first half of 2023. As ever, all of this is a matter of opinion, but I believe that the current risk/reward potential makes this an interesting proposition. Many will disagree. I look forward to revisiting this discussion in a years time......
After a massive rise a few years ago (something akin to a 19th century gold rush) some of the longer term power storage system shares continue to take a battering in terms of valuations and SP , and this sale by Invinity Energy Systems (LON:IES) is not earth-shattering.
However, I have picked up the comments in the last para below about lithium-ion battery fires. In the future, vanadium is also available in large quantities, and lithium sources are unlikely satisfy future demand. I recall a Mello event some time ago when a minerals expert emphasized this comment. Vanadium can be the basis for both a stand-alone or a lithium support system. I believe the Oxford Hub in the UK is an example of the latter.
Invinity Energy Systems plc (AIM: IES) (AQSE: IES) (OTCQX: IESVF), a leading global manufacturer of utility-grade energy storage, is pleased to announce the sale of a 1.5 MWh Invinity VS3 flow battery system to Hyosung Heavy Industries ("Hyosung") for use by Korea Electric Power Corporation ("KEPCO"), Korea's national electricity utility. On 8 April 2022, Invinity and Hyosung announced their intention to initiate a global partnership, and this strategically significant sale is an important next step in that relationship.
Korea is an attractive market for energy storage due to its high per capita energy use, constrained grid infrastructure and significant government support for renewable and energy storage projects. Furthermore, a number of lithium-ion battery fires in existing energy storage sites in Korea has created demand for non-flammable, durable and UL certified technologies such as Invinity's vanadium flow batteries.
Primary Bid had £ATOME due to close today 7pm. Paraguay and Iceland green hydrogen.
Looking at LINDE who make all sorts of gasses inc. helium which is in high demand short supply. £HTWG ETF. Lots going on in the waste to gas space by the majors.
Announcement from Synthomer (LON:SYNT) that it is has agreed to sell its Laminates, Films and Coated Fabrics Business for at total enterprise value of $255m (£208m) with net proceeds of £199m. Proceeds will be used to pay down the substantial debt.
I found the newish CEO and his strategy plan quite beliveable at the recent presentation so it's good to see they are actually following through and selling off the non core businesses with a view to increasing focus on the US. Still a lot of debt to reduce. I'm a despondent but slightly cheered holder.
Colefax .
Has sold off recently and looks pretty good .
Headwinds yes but just looks to have fallen too far .
Long term share reduction plan seems to be excuse the pun “paying dividends” because that’s the opposite to paying dividends .
Just looks very good value .
I do hold Sanderson already which I think is more dynamic and a bit sexier with great CEO , but no denying Colefax looks ok to me .
Any holders got any thoughts ?
Morning planetx,
I remember when we last wrote about Colefax (LON:CFX) we warned that it had a one-off bumper year in FY 4/2022, and that the company was guiding for much lower earnings this year.
So I think it was more a case that the shares got overvalued on the bumper FY 4/2022 profits, and it's now come back down to a valuation that looks about right to me at 630p (fwd PER of 10.5)
It does look quite a nice business though, decent profits most years, and strong asset-backing protects the downside risk. Very illiquid shares. Dividends look stingy, but it's greatly shrinking the no shares by doing buybacks, which doesn't exactly help liquidity. Is there a risk they might decide to take it private, with only 4 big shareholders owning 3/4 of the business?
As you say, strong similarities to £SDG although I think Lisa Montague at SDG stands out as being ambitious for the company, whereas Colefax I'm not sure that comes through so much for them, but haven't met or heard management present.
Overall though, I'd give Colefax a thumbs up - decent business, strong finances, reasonably priced. It remains to be seen whether a consumer/property downturn would impact these 2 companies.
Good luck whatever you decide!
Regards, Paul.
Paul
Thanks
I think your spot on with that though the asset backing and cash is very supportive .
Unless I’ve missed something
44m market cap
35m NTAV
22m cash
This years “high” profit 10m. , normalised say 5m.
Those are a very strong set of numbers (I normally miss something or get it wrong )
So on a long term basis if they keep working on reducing share count PER is going to grow significantly (over time)
It’s very interesting to compare Sanderson v Colefax and the tactics of each .
Sanderson more dynamic with exciting CEO doing great things
Colefax seems steady away, lower valuation, not growing the business but growing earnings by reducing share count using its asset backing .
Previousky I would have only considered Sanderson, having just finished “outsiders” I’m much more comfortable with Colefax . Was never really into share buybacks but I’m seeing more value now if done correctjy.
Re Colefax (LON:CFX) I understand from a v well informed industry source that a large % of their profits have been on mega projects for Oligarchs U.K. mansion fit outs..that obviously has come to a screeching halt…who can say how long for.
Sanderson Design (LON:SDG) had a tiny hit in the last results from the sanctions/cessation of Russia distribution but it was a non material (sorry!) amount .
I hold Sanderson Design (LON:SDG) but both look good options to me
Paul, I wanted to reply to the frustration voiced in your latest entertaining and informative podcast concerning complaints from subscribers about the mix of firms covered on the SCVR. My thoughts are that your frustration is entirely understandable- as you say, who wants to be criticised? But these are your paying customers expressing - in some numbers - their disappointment with the product. It would be dangerous to simply brush those aside. You rightly argue that the SCVR coverage is wide-ranging, but frustrated subscribers - and I count myself amongst them - would suggest that the thresholds for inclusion in the daily discussion, and your special insights into the retail sector, are denying subscribers the opportunity for debate of higher quality and more internationally focused names within our primary share discussion forum. There is a sense that good stocks are being crowded out by bad.
You argue that better established names already have coverage from the likes of Peel Hunt and Numis. But who has access to their analysis? I only get reports from my bank, and that is internationally focused and at a level that UK small and mid caps won’t get a look-in. I sense there is a demand for analysis and discussion of higher quality mid caps in the SCVR that would not be met by a reader simply posting a stand-alone thread entitled “Diploma - quality distributions” or “Kainos - government IT”. The SCVR is where ideas are shared on company updates. And that is when the majority of investment decisions are made.
With fulsome apologies for any offence caused by my observations, I politely request that you review the parameters of the SCVR to best align with your customers’ needs and wishes. I remain an engaged member of the community and hope the forum goes from strength to strength.
I personally prefer contributors to focus on their area of expertise and I feel this is what Paul and Graham gravitate towards. I would not want this to change. There are other contributors such as Megan who have improved and broadened Stockopedia’s offering. My subscription is due for renewal this month and the fee is pretty substantial especially during a difficult year. I do think Stocko needs to continue to evolve and expert stock analyses is part of this but there are many ways this can be achieved without disrupting SCVR.
You can discuss any shares you like here, and people do. So I really cannot see what your problem is, but obviously as a paying customer feel free to express your opinions, and we do listen & take on board all feedback.
Nothing is being crowded out at all, we discuss hundreds of companies here. Anyway, I'm going to crack on writing about lots of companies (we've increased our coverage further, and did a record 42 last week), rather than discussing which companies we should be covering!
I've noted your personal opinions, and we're doing our best to cover as many companies as possible, and doing shorter sections on the smaller stuff. So we do listen & take on board comments. But yes, it is frustrating for the writers when we're facing a daily battle to cover as much as we can.
P.S. I think I'll publish the agenda each day, so people can see what news there is, and what we're writing about (and why). Maybe that might help? Most days we do cover most of the important updates, so I'm struggling to understand specifically what companies BnB thinks we're missing out? Maybe we could work out a voting system, whereby subscribers vote for which companies you'd like us to cover from the list each day? That might work quite well, but I don't know how it would work in practice?
We need specifics - which companies are we missing out? Not just general criticism, as that's impossible to fix.
Thanks for listening and taking the trouble to reply at a busy point in your day. Your and Graham’s analysis is hugely appreciated, as is your natural charm under great pressure.
We need specifics
Fair point.
So let me start by expressing the view that there is a disproportionate balance towards illiquid stocks in the general coverage. For those who invest in larger than average tranches these are a no go and for those operating on a smaller scale the spreads are a deterrent - not to mention that these names typically carry a higher risk of value destruction. For all that we are grown-ups responsible for our own decisions, it’s inevitable that our eyes get drawn to the names discussed within. That has been expensive for many investors here, particularly in the retail space. Let’s start making money again.
Secondly, I wonder if breadth of coverage is compromising depth and quality of analysis. I would prefer 4 reports a day to 12. You could conceivably cover every TU but if that means quoting verbatim extracts from the RNS with limited value-added, then no one is gaining from the exercise. To be clear, I’m not accusing you of being so shallow. But I value your insights and experience as much as your hard work and would greatly appreciate deeper analysis of a reduced number of strong prospects with the odd friendly warning thrown in.
"You could conceivably cover every TU but if that means quoting verbatim extracts from the RNS with limited value-added, then no one is gaining from the exercise." I beg to differ. Plenty of us don't have time to read every RNS. Stocko is personally my first point of call.
Also your comment BnB that you would prefer 4 reports rather than 12 could result in far more readers being disappointed that the shares they are interested in don't get covered.
I will be renewing my subscription.
I would prefer 4 reports a day to 12.
Not sure I agree, I really like the short summary reports.
BnB,
I think that you are being incredibly presumptuous. The SCVR reports are what they are and are what they are always have been. Within the confines of some fairly loose parameters, Paul and Graham write about what the want to write about. If it doesn't meet your brief, why should they care? Why should any of us care? You should address your grumbles direct to Stockopedia, not to Paul.
Further, the SCVRs have never been about in depth analysis; that is our job if we are going to invest in individual shares. They are high level analyses from experts, intended to generate ideas, promote discussion and, sometimes, give warnings. In these respects, I think they are extremely successful, and the discussion often draws in contributions from subscribers who have done the in depth analysis.
So, at the risk of quoting Richard Madeley, "jog on"!
I think that you are being incredibly presumptuous
No. I’m responding to Paul’s grumble that he is receiving a lot of complaints by speculating on the basis for subscribers’ dissatisfaction. And I’m doing so in, I think, a polite and respectful manner intended to foster constructive debate and, ultimately, a better service.
BnB,
A better service for you, perhaps, but not for me and, I strongly suspect, the vast majority of subscribers who value the SCVR in its current form.
If you would like a mid-cap report, then take that up with Stockopedia, not with the author of the Small Cap value Report.
I agree Effortless Cool and it must be dispiriting for Paul and Graham to see this criticism of the fabulous service they provide. Don’t some people take such things for granted, and then want even more.
Have some of the critics even considered for a moment the amount of time Paul spends absorbing Company updates and then writing about them; again very time consuming. And it is often in depth too. Then Paul and Graham even find time to respond individually sometimes. Paul comes across as a workaholic and how does he summon the enthusiasm every day and in adding the weekend extras like his podcasts that he also provides. And then provides it in writing too! It’s a sensationally good service.
The SCVR reports and follow up posts are by far the best and most used on Stockopedia. That says a lot.
Thanks Paul and Graham and concentrate on what you want to and most enjoy doing.
We need specifics - which companies are we missing out?
Fair point.
So let me start by expressing the view that there is a disproportionate balance towards illiquid stocks in the general coverage. For those who invest in larger than average tranches these are a no go and for those operating on a smaller scale the spreads are a deterrent - not to mention that these names typically carry a higher risk of value destruction. For all that we are grown-ups responsible for our own decisions, it’s inevitable that our eyes get drawn to the names discussed within. That has been expensive for many investors here, particularly in the retail space. Let’s start making money again
This exactly has been my problem too BnB, something I've been aware of for some time now and am working hard at putting it right, taking a pinch of salt with everything.
Silver
Paul, don't worry about it. You are never going to be able to please all of the people all of the time. Just write about the companies that interest you. The responsibility really is on the management of Stokopedia to find more high quality writers for a mid-cap value report and a large-cap value report.
The responsibility really is on the management of Stokopedia to find more high quality writers for a mid-cap value report and a large-cap value report.
Strongly seconded with the acknowledgment that Megan is now providing large cap and international commentary. But the companies highlighted so far have been as mainstream as you can get, from Facebook to Alphabet to Vodafone, probably yesterday’s big winners rather than tomorrow’s, and where there is a multitude of alternative coverage.
I personally wish there were more focus on the mid-cap space because this is where I find the sweet spot in UK stocks in terms of quality and profitability.
I personally wish there were more focus on the mid-cap space because this is where I find the sweet spot in UK stocks in terms of quality and profitability.
The clue is in the name Small Cap Value Report.
The clue is in the name Small Cap Value Report
Of course. But that doesn’t answer why the voices of dissatisfaction have grown louder of late. And they certainly have as Paul himself acknowledged.
Perhaps it’s just the end of a long and unprofitable grind for ‘22. But perhaps it’s worth asking what would improve the forum and members’ performance . And yes, I’m all in favour of a MidCapQualityReport if Stocko will oblige!
Probably because small caps have generally not been performing well, if prices were soaring then less people would be complaining. Also a lot of PIs seem to have left the market. Loss of interest in small caps, heard that from various sources.
I would favour more mid cap coverage, maybe Graham could review some mid caps?
Mind you there must a lot more small caps, now share prices have dropped, like Synthomer (LON:SYNT)
For my 2pence worth, as a complete novice I really value Paul and Graham's reports. Aiding me in my decision making and giving ideas. The readers comments are on the whole very good as well, far better than the mud slinging on LSE and other forums. Keep up the good work and thank you.
This is what we've got on our agenda today. As usual, we probably won't be able to cover everything, and let us know if we've missed anything interesting off the list! Thanks.
Another big contract win at WAND. I see this was covered in the SCVR in October here so readers could refer to that if there isn't time to cover it today.
Morning Michael P,
Yes, as we've commented here before, something interesting does seem to be happening at WANdisco (LON:WAND) - after years of struggling to get anywhere & big losses & cash burn, it now seems to be winning much more impressive contracts, and repeat business.
Today's update also says -
"We are seeing an acceleration of interest in our solutions and as a result, our pipeline remains at a record level both in terms of the number of opportunities and the combined value of those opportunities. We believe that the rapid expansion that has followed the initial contract in this Client case is something we expect to replicate with a number of other customers. We expect to report further progress before the year end. "
The market cap is now about £460m (at 673p/share), and given that it's still forecast to be heavily loss-making, valuation looks little more than guesswork.
Is this another false dawn though, as we've seen several times before? Maybe, but the big contract wins seem to be coming in more consistently this time, maybe WAND's time has come? Looks potentially interesting I reckon, for more aggressive growth company investors. Or just as a punt, I can see the temptation to having a flutter on this!
Thanks, Paul. The market certainly seems to have changed its mind on this one a few times. In stock terms, it has a value rank of 1 and a momentum rank of 97, which probably encapsulates different viewpoints on it quite well. Traders might like it as it is above the 52w high and currently up around 8% today on above-average volume. Today's contract upgrade is based on their ability to move automobile sensor data to the cloud. Without knowing the specifics, there are several potential uses for sending automobile sensor data to the cloud that include; better estimation of insurance risks and therefore setting premiums, finding patterns in the data that could lead to earlier identification of faults, and potentially better insights into causes of accidents (which could be particularly important with the growth of self-driving vehicles). The contract upgrade takes the value of this contract to $25.3million over 5 years up from the initial $5million announced in July 2022. Half to be paid up-front. Stocko reports 2021 revenue was $7.31million and 2022 estimate is $12.6million that may need to be upgraded. So that gives a sense that this is a big deal for the company with, as they say, an expectation of further progress to be reported soon. Unlikely to be of interest to value investors but could be of interest to growth investors and/or traders. I hold.
I would personally love it if any subscribers who are about to, or have an interest in, investing in a particular company would post a quick paragraph about the company and why they like it and are investing in it. That way we would get a decent spread of ideas which we could throw into our own melting pot. They should be able to do this without being shot down, unless they welcome comments....
I have gained as many ideas from subscribers (perhaps more in fact) as I have from Paul and Graham who give some specific areas of interest, and I welcome Grahams particular area of expertise to the mix.
Most ideas are not for me, but I appreciate each and everyone from all sources.
There seems to me to be a great spread of expertise on here and I want to tap into your collective experience and views and have my own thought process challenged, and don't mind where it comes from.
And I really appreciated your time to respond on Friday with thoughts about Property Franchise (LON:TPFG) which was just my Friday afternoon wiffle and sold as it broke the 20% barrier and stuck to my current rules and will watch from the sidelines from now. But great to get input from others!
Tommy
Your welcome Tommy, and sorry it did not work out for you.
Good luck with the next one, and hope you had a boost from this bit of a rally today!
Morses Club (LON:MCL) - current shares must surely be effectively worthless now after the company announced today a clear plan for a 19:1 dilution in 2024 - if they can survive that long. This also requires them being able to secure funding now without full FCA approval.
The ambulance chasers have won, having closed the doorstep lending arms of Provident, NSF and now MCL.
A visible, legal, regulated credit market ("doorstep loans") making loans to people otherwise excluded from credit is effectively shut. It was definitely the grubby end of the credit market - but the same people who took these loans will now get loans from unregulated sharks, unregulated new financial products or not be able to get any credit at all and individual financial responsibility takes another knock.
Is that what the white collar, comfortably-employed FCA (and the government regulators behind them) are there to achieve? The claims company lawyers will move on to the next car crash but the our financial and broader economic system has lost again - without the truly vulnerable getting help.
They need higher wages and better mental health / addiction support services and/or better financial products. Removing access to credit won't help these problems but it will send more poorly paid care home staff to foodbanks or to work in Tesco when their washing machine packs up.
Disc. - I lost money on MCL (and more faith in effective UK market regulation)
Totally agree about loans needing be available to people without credit. I live in Northern Ireland and it's a big problem here in some areas with loan sharks (there was a story about it on bbc website today), Morses club was at least trying to improve this.
Thanks for the Coral Products (LON:CRU) write-up, Graham. I have a large holding here, as I see a lot of potential and like the way that the company is run for the benefit of shareholders, rather than management. It no doubt helps that the biggest shareholder is the management!
To pick up on a couple of points you raise:
Yes thanks Graham. You commented that there was no share holder dilution worth noting that there has been quite a few share buy-backs during the year
Yes much appreciated Graham. I stumbled on Coral Products (LON:CRU) a few weeks ago, and did like the look of it. Paul - thanks for spotting my comment yesterday, and adding on to the review list for today.
Coral Products (LON:CRU)
Hi effortless cool, you're welcome (and I appreciate the feedback regarding CRU, thanks everyone).
EC, I agree with the organic growth number you've calculated. That's good extra info regarding the energy fixes, too. Cheers!
Grham
Thanks for looking at Coral Products (LON:CRU) Paul. Very helpful.
Actually ... Graham ...
Begbies Traynor (LON:BEG) have also issued their HY results this morning which look impressive. Would be grateful if either Paul or Graham could cover this today.
Sosandar (LON:SOS) Interims squeeze a small profit pre tax of £77k but there seems to be some discussion as to whether this misses forecast on Twitter
They say overall inline with expectations for the FY
I’ll be listening in to todays results call as the joint CEO’s have good insights into the fashion sector (tho my dresses may not come from Sosander Paul
I'm really puzzled. Sosandar (LON:SOS) did £21m revenue in H1.
They say they're "in line" with market expectations for FY, and they give that too, at £42.8m.
So it implies they think they will only do £21.8m revenues in H2.
Which doesn't quite chime with what should be a stronger H2 trading period, and growth. £21.8m equates to 26% growth for H2 YoY, which is a big slowdown from the 72% in H1.
What am I missing? Are they purposely being conservative and stating "in-line", but on course to beat forecasts?
Good morning Paul, Graham
Sosandar (LON:SOS) released their half-year results this morning. It seems, on the surface, all good. More sales, customers and slightly more PBT.
Will you be covering them today?