Small Cap Value Report (Tue 13 Feb 2024) - SED, ULTP

Good morning from Paul & Graham!
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. OR it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom),
Frozen SCVR summary spreadsheet for calendar 2023.
New SCVR summary spreadsheet from July 2023 onwards.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Thin pickings today so far -
Other mid-morning movers (with news) -
Belluscura (LON:BELL) - up 8% to 21.5p - Distribution agreement with Sunset HealthCare (USA & global). Nothing said about contracted or expected sales quantities or margins. Will be interesting to see if the hype turns into reality or not. Heavy historic losses, and it’s trying to raise cash through buying a cash shell with paper.
Cornerstone FS (LON:CSFS) - up 7% to 32.0p - receipt of regulatory licence, so can now operate in Canada, to accelerate growth (medium to long-term).
Dispensa (LON:DISP) - down 69% to 0.29p (£2m) - only floated in Sept 2022, but says today it plans to de-list. Auditor resigns with immediate effect. We didn’t have the pleasure of reporting on this share, so now can cross it off our to do list forever!
Summaries
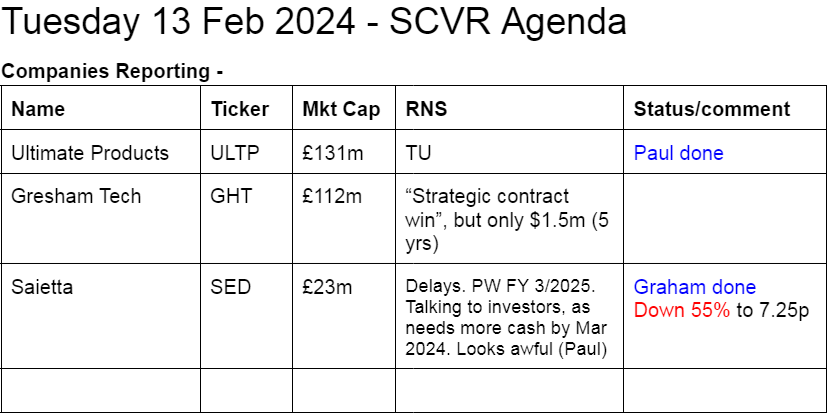
Saietta (LON:SED) - down 53% to 7.58p (£11m) - Commercial Update (PW) - Graham -BLACK (profit warning flag) - RED on fundamentals
If there was a category below RED, Saietta would be a strong candidate for it. Cash is rapidly running out as the company reveals that a contract manufacturing job in Sunderland won’t be happening, and it sells the production line. Endless talk about possible contracts.
Ultimate Products (LON:ULTP) - unch 148p (£131m) - Trading Update [in line] - Paul - GREEN
H1 TU says revenues down 4%, but has recouped the shortfall through efficiency gains & lower freight costs. FY forecasts left the same. Looks a well-managed value share, with an attractive yield of 5.5%, and talk now of doing potentially quite sizeable share buybacks. We like this share here, and remain at GREEN.
Paul’s Section:
Ultimate Products (LON:ULTP)
Unch 148p (£131m) - Trading Update - Paul - GREEN
Ultimate Products, the owner of a number of leading homeware brands including Salter (the UK's oldest houseware brand, est.1760) and Beldray (est.1872), is pleased to announce its trading update for the six months ended 31 January 2024 ("H1 2024").
Full year profit performance in line with current market expectations, planned share buy backs in-line with new capital allocation policy
H1 revenues down 4% to £84.0m
Reasons - strong prior year comp (demand for air fryers), supermarkets ordering less due to overstocking, and “modest” delays recently due to supply chain disruption (interesting to hear this mentioned, I wonder if more companies will start reporting problems with global shipping having to re-route around Africa instead of via Suze?)
Improved operating profit margins, helped by lower freight costs, and improved productivity.
Outlook improving for 2024, as issues above subside.
Net bank debt: EBITDA is now 0.4x (down from 0.7x end July 2023). Remained below 1.0x even during seasonal peak - excellent reporting, we need more of this from all companies, not just a year end snapshot (often unrepresentative of normality).
Capital allocation policy - 50% of earnings to be paid out in divis - but that looks to be pretty much what the company has already been doing in recent years. Supplemented with share buybacks. Maintain bank debt at c.1.0x EBITDA. That all sounds sensible to me. Equity Development estimates there could be substantial scope for buybacks of c.10% of the issued shares, so this could become significant.
Outlook FY 7/2024 -
The Board anticipates a full year profit performance in line with current market expectations*
* Consensus market expectations for the financial year ending 31 July 2024 are, adjusted EBITDA of £21.6m and adjusted EPS of 15.6p.
This is flat vs FY 7/2023, and similar to FY 7/2022, so the risk is that investors might start to view ULTP as ex-growth? Although to be fair, that’s how it’s priced already, on a forward PER of only 9.0x, and a divi yield of an attractive 5.5%.
I like the idea of doing buybacks at this modest valuation, which would enhance EPS and DPS.
Paul’s opinion - I’ve been impressed with how ULTP skilfully navigated major pandemic-related problems. When you talk to many companies, management point out that they don’t know what “normal” is any more, as the last few years have been constant crisis management. For that reason, I’m not worrying too much about the disruption of the Suez Canal route for shipping, they should be adept at handling problems like that. It seems to be adding about a fortnight in delays for some products, hardly a disaster, and customers will probably order earlier, which might help to give a boost and recoup some of the reduced revenues in H1.
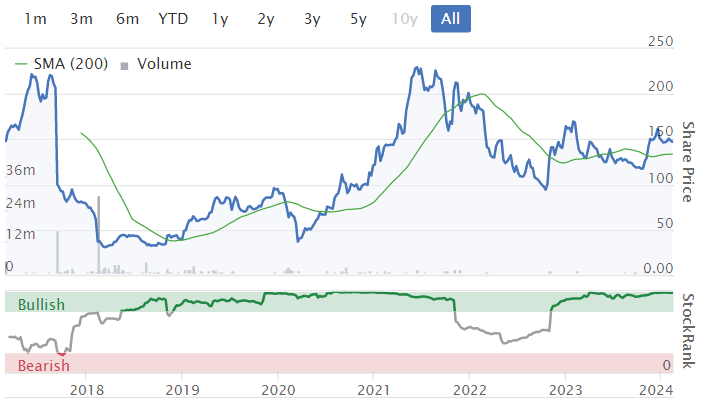
Overall, ULPS is a simple share to understand, looks well-run by owner-management, and seems to have fully recovered from the mishaps which caused the shares to plunge in 2018, soon after floating. It’s a better, larger business now, with a good track record, and priced on a PER of only 9.0x, I can only give it a thumbs up, so GREEN again.
Graham’s Section:
Saietta (LON:SED)
Share price: 7.58p (-53%)
Market cap: £11m
Paul and I have been consistently and frequently RED on this share, most recently on 29th December 2023 when Paul said:
I remain extremely negative, because the company is a big cash-burner, but seems to limp along from one fundraise to the next, with no discernible commercial progress apparent in the figures yet, other than talk about orders, etc.
Today’s news, as you can tell from the share price reaction, is not good.
First, the company has received an offer of £600k for a redundant production line at its Sunderland facility. It seems that the offer will be accepted:
This sale is a result of the Company being unable to reach commercial agreement on an electrical steering pump contract manufacturing opportunity at its Sunderland facility, announced previously.
This contract was supposed to generate £58m of low-margin revenues for Saietta over the next four years. Won’t be happening now.
Second, we have an update on the Indian joint venture. There are three contract opportunities with a major customer, and the status of each opportunity is as follows.
1) purchase order received, pilot production underway, commercial production expected October 2024.
2) purchase order received for pilot, pilot production expected July 2024.
3) purchase order hoped for by end of March 2024.
The company refers us back to their announcement of 27th Nov 2023.
I’ve checked this announcement and it seems to me that even in the case of 1), with commercial production “expected” in October 2024, that this is not yet entirely in the bag and it depends on the success of pilot production.
I also note that the 27th Nov announcement included a fourth contract opportunity with this customer, and it’s not mentioned today - presumably because there is no progress.
Third, Saietta are “in discussions” with another customer about another potential sale. They are hoping for a “proof of concept” letter by the end of next month.
My conclusion from the above is that nothing much has happened in terms of orders and sales. The company continues to hope for contracts being signed and to make plans for pilot production, but I don’t think there are in fact any large non-pilot orders.
Working capital
The company needs more cash soon, and results in FY 2025 are likely to be worse than previously planned:
As previously stated, the Company has positive cash balances that take it through to the end of March 2024. The Company continues to engage with all its stakeholders regarding its funding requirements beyond the end of the quarter.
The Company remains confident in its financial forecasts for the financial year ended 31 March 2024 as set out 27 November 2023, however forecasts for the subsequent financial years will inevitably be impacted by today's update.
CEO comment
The CEO is taking the line of argument that Saietta didn’t really want the contract manufacturing opportunity anyway:
…Being unable to agree terms on a contract manufacturing opportunity is no reflection on the quality of the Company's products. The sale of the redundant production line in our manufacturing hub in Sunderland (UK) makes sense for Saietta in comparison to a relatively low margin contract to manufacture a non-core product under license. This route allows Saietta to remain 100% focused on our strategic focus of providing proprietary eDrive solutions to manufacturers of lightweight electric vehicles…
Graham’s view
There is a space in the market for pre-revenue/early-stage companies, but I dislike the practice of posting dates and indicative contract values for contracts that have not yet been signed and may never be signed.
Some investors may feel that there is a benefit to having the company set out its goals in this way, but I would argue that it’s better to be approximately right than to be precisely wrong - even if this means a company should admit it doesn’t really know when contracts with customers will be signed and how much they might be worth. Maybe a wide range of possible values could be given instead.
As the company’s cash balance dwindles, only the brave and the well-off will be hanging around to see what happens next.

Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

107 comments
The Mag7 and US mega tech can do no wrong...
They are impressive companies with significant global reach. A truly new phenomena in some ways. They may continue to dominate and suck up all the capital in the world. Michael Green makes a very cogent and persuasive argument for why this is the case - here's a recent interview I found...haven't watched but did read his original papers on this years ago:
In some respects Green is commenting on an effect that is similar to the idea of have UK only ISAs and SIPPs...captive capital flowing into a domestic market. The UK has a massive amount of capital tied up in pension funds but we have just about the largest overseas equity investment as part of the equity allocation of any significant country (this is function of our relative openness as an economy including when it comes to capital flows). We've been allocating away from UK for last 30+ years and that is probably a decent explainer of FT100 (...different conversation but maybe the Germans have been allocating to their domestic equity?...they came from a near zero equity position few decades ago as german pension didn't invest in it)
More recently David Einhorn of Greenlight has been making this argument...effectively the US market is permanently broken. A google search will find his analysis I'm sure.
But this vibe that some theme can do no wrong and will continue to dominate for ever is just not how 'the' or 'a' system works....its how mathematicians think about systems and blow us up in finance every now again...systems and their boundaries and stability are a thing for engineers to work out (finance would be better for engineering thinking). Flows and interests always shift for reasons we don't see coming.
The short volatility bet is to chase Mag7....the long volatility bet is to find some cheaper and better growth for the price things. As long as you don't overpay long volatility tends to win....particularly as short volatility tend to panic on their investments and sell badly...
I do like your suggestion Paul Hill that ISAs and SIPPs should have a UK allocation % limit. Why should you be able to get UK tax relief on investing overseas / but have to pay stamp duty on UK shares? It's just wrong.
In my view, stamp duty should be abolished and we should have an adjusted UK ISA rather than a new UK ISA - maybe extended for share investment only and not for a cash ISA. If you want overseas exposure in an ISA or SIPP then you should possibly be allowed to buy a UK listed investment trust investing overseas. At least that helps the investment trust industry in the UK. Make it simple - a shares ISA investing in UK LSE listed shares whatever they do.
The other thing that works well in the UK is Venture Capital Trusts. Why not extend tax relief specifically on investments into AIM UK small caps, not just microcap start-up's?
The UK market needs to adapt or die.
Most wealth managers (Rathbones, Charles Stanley, Brewin Dolphin etc.) are still reallocating to the MSCI World as the US component grows ever bigger - Jan 2024 data: United States 70.14% Japan 6.24% United Kingdom 3.92% France 3.2% Canada 3.14% Other 13.35%.
The US should be about 40% based on fair value in my view, so something ugly is going to happen at some point, like Japan in the 80s. The problem with all the passives is that this is all momentum driven and when everyone exits the Mag 7 "as the clock strikes midnight" then it's going to be brutal. Actually, that is probably the moment that the UK "rebounds" at least on a relative basis.
40% fair value means the US will be trading at about 8x earnings! US has never traded so low but instead always traded on average about 16x earnings so I do not quite understand this assumption.
Dow Jones index around 30000-31000 and on 16x earnings makes more sense on a fair value basis rather than the 20x earnings it trades now.
I think the amount of toing and froing on todays discussion has been a little taxing for the brain, I need to lie down....
Hi is there a an equivalent to companies house database website in the US. I am looking for the accounts for a company called Amenacore LLC based in California company number 202021310734. UK version https://www.gov.uk/government/... is really useful for this but not sure what us equivalent is. Any help appreciated Cheers Dan
The short answer is “no”. For companies that are not selling shares publicly there is no requirement to make accounts publicly available. Private companies are private.
Thanks Aislabiie, If you do a credit check on the company would that provide the accounts?
No, not necessarily, they would obviously give a rating and some payment referencing etc but the accounts can be kept completely private. Some companies might volunteer information. Of course if you are a significant potential investor or major supplier then clearly they would expect to provide the information on a confidential basis.
Today's volume leaders
Re DAX v FT100 - former is total return and latter is price only - its important to consider this and mad to make a comparison that doesn't factor that in.
Historically, the level of GDP growth of a country has a poor correlation to the returns from its stock market. On a cross sectional basis this correlation has tended towards negative. This is well established research. I haven't looked/read for a a few years...but a few years is just a flash in the pan for this sort of analysis.
Historically, UK has been relatively low GDP growth (looking at century rather a few years sort of time frame) but good return on capital.
IMO Germany has benefited from three related effects that don't have durability:
1) Hartz labour market reforms in early 2000s as a response to troubling and sclerotic economic performance (comparing badly to UK). These reforms explicitly suppressed german industrial wages relative to production so driving up price competitiveness regionally and globally and measured productivity (a bit similar to China). This also suppressed German consumption and drove large export and budget excesses (again like China, Asia). (Note, this also explains some relative outperformance of UK since 2000)
2) Massive mercantilism at the expense of many of its EU peers and high consuming countries (like the anglos globally).
3) A very undervalued currency. An undervalued euro relative German needs gives Germany (and The Netherlands, Finland and Ireland) a comparative export and so GDP advantage as long as this state persists....at the expense of countries where Euro is too high (Italy is the prime example, a country with a fantastic industrial capability hollowed out by Germany due comparative currency effects)
1 and 3 powers 2 - 2 makes the economy look better than it can be durably (its inevitable, we are waiting for an economic accident from Germany). We can shoot the breeze on this (perhaps put in separate space from SCVR tho so as not to annoy the stock pickers). A 4 and 5 of v bad demographics and artificially low energy prices could be added.
IMO Germany has reached the pinnacle of its economic 'cheat'. I'd rather be in little old grubby UK prospectively...our headwinds are of our choosing (and idiocy!) so we can more easily do something about them....whereas Germany's position has a much more regional and global dynamic to it that are outside of its control even though the factors will press very hard on it and brings risks of shock downside
Historically, the level of GDP growth of a country has a poor correlation to the returns from its stock market.
I remember reading a very interesting article in the IC a couple of years ago making the same conclusion based on a very long period of statistical data. They concluded that continued growth was generally easier in low GDP economies. This was because high GDP economies attract so much competition. Low GDP economies are unattractive for new entrants, and so strong companies can usually keep increasing market share due to the lower levels of competition. I thought this was fascinating as it seems to go against standard market intuition when thinking about growth markets.
That’s nice!
Re DAX v FT100 - former is total return and latter is price only - its important to consider this and mad to make a comparison that doesn't factor that in.
I think another very important consideration is the cost of our NHS (imo that's a wonderful thing to offer your people). This rarely gets a mention when discussing the stock market. But it is important when comparing the UK with other regions that do not have this unbelievably large financial obligation. If we factor that in (the large financial drain), then the UK has probably not performed as badly as many think, especially when compared to other regions of Europe that have been on their knees for years (and don't have an NHS type expense problem to continually solve). I just don't think we have the funds to drive industry as much as we would all like, and in recent years this has impacted the stock market.
The burden of health expense remains within societies without a public service, it's just transferred to the private sector.
Are you suggesting there is no difference between a free national health service and a private national health service? If someone in Germany doesn't have medical cover, they are likely to be financially fkd! In the UK the tax payer pays for this treatment. The financial burden on the govt is large - and it has a direct corelation to the amount of funds available across a range of industries / sectors. It also factors into things like innovation and also foreign investment. From what I have read over the last 20 years or so, it is unavoidable that the cost of the NHS will have a big impact on how the UK fiscally operates.
I didn't say there was no difference, I said that health expense remain within those societies. The NHS is not "free", only free at the point of need.
A portion of a countries aggregate resources is dedicated to health regardless of whether the government provisions it, or whether individuals (or corporations) pay the private sector entities for it.
It might be the case that there are efficiencies to be had with one system or another, but it ultimately all comes down to available resources within the economy... and we (the UK) aren't creating enough of those resources, hence the strain.
I don't mean to be argumentative, but we clearly see this differently.
imo there is a huge difference, perhaps shown best when you break down the costs and revenues.
For the UK
Cost of buildings / maintenance - Burden is on the govt
Cost of equipment - Burden is on the govt
Cost of staff (has been particularly relevant recently due to salary rise demands and our govt saying they couldn't afford them - this then led to strikes) - Burden is on the govt
Administrational costs and R&D - Burden is on the govt
Patient Invoice - Burden is on the govt (no return for the all the above costs)
For Germany (or a country with a private system)
Cost of buildings / maintenance - Burden is on the private industry
Cost of equipment - Burden is on the private industry
Cost of staff - Burden is on the private industry
Administrational costs and R&D - Burden is on the private industry
Patient Invoice - Received by the private industry to then cover all the above costs
It’s correct what you saying but the argument was that if the German economy has performed better and your argument was yes they did but this is because of their NHS system.
This I disagree as it’s only transferring money from the people to the government and vice versa. Nothing to do with the growth of an economy. Imagine tomorrow morning the taxpayer pays a 14% for the NHS (deducted from basically all salaries in Germany).
The economy will collapse here.
Well, I am certainly not claiming this is the only reason for the outperformance. But I do think it is a relevant factor that is often overlooked.
We do see it differently. Whether the government provisions those services or whether individuals pays the private sector for health services, it all represents a slice of resources from the aggregate UK economic pie.
If it's all private sector there are going to be winners and losers, but not necessarily any savings of net resources for the UK. Is health spending per capita much lower in other countries? (eg USA, Germany)
https://en.wikipedia.org/wiki/...
When you say "Burden is on the government", they don't have a secret bucket of resources... they get the resources from the aggregate UK economy.
Thanks SJRen
Very well explained. It’s just from one pocket to the other one.
The NHS is a cost to the country. Every year it is a balancing act in order to fund it appropriately. In recent years we have not been able to fund it well enough and now we are suffering with the backlogs and all the associated problems (lack of staff, poor facilities, poor patient outcomes).
It is accepted by probably every politician in the UK that the NHS costs money - it is a 'luxury' that is expensive - but that we morally feel is important - it is not free, and there isn't a secret bucket of resources - it comes from the national budget - ie tax payers. That budget is not unlimited - and each year the NHS is both a drain and a strain on our countries resources. If you want a free health service - then obviously it needs to be funded - and much of those funds could have been used elsewhere. Over the last decade we have seen so many budget cuts to so many areas. The police numbers have come down a lot. Teachers are criminally underpaid. There is a huge lack of investment in the north, and for that matter all areas outside the major cities. However at the same time, the NHS costs more each year. Politicians have been discussing this situation for years - and how it is almost at breaking point. There are even those that believe the system will have to be privatised, or it won't survive.
Then why is our health spending per capita unremarkable when compared to other OECD countries?
https://en.wikipedia.org/wiki/...
Politicians might love to draw attention to how much money they spend on the NHS, but I feel (and it is just my opinion) that it's a distraction from the elephant in the room, that successive governments are failing to sufficiently grow the economy (ie the available aggregate resources) from which those services are extracted.
US inflation a touch higher than forecasts so the markets taking a bit of a bath so far. 2nd half to Feb tends to be a little weaker, maybe looking for an excuse to selloff after a huge run as well.
Good chance UK inflation might come in higher tomorrow also?. Be interesting if markets look through this or show all the backbone of a jellyfish. I'm hoping the latter as it should offer a better buying opportunity rather than chasing things higher.
UK is so grim! Didn't enjoy any of the big US rally but participating in the sell-off now. I read recently that recent inflows into funds were invested mainly in the US whilst UK outflows continued.
Yes UK investor sentiment is both awful and fragile at the moment. Falls out of bed at the drop of a hat but participates in rallies on a low beta. A big part of the problem is liquidity. The Govt really need to use a stick and carrot to boost volumes…… they could demand ISAs and SIPPs can’t contain more than a certain %age foreign investment to qualify for tax relief and cap pension fund allocations overseas. That would force some reallocation. Then they could offer some good tax incentives to invest in the UK market but also boost companies coming to market - for example discounted tax rate for listed companies to offset costs etc. Then boost start ups in the new economy companies - invest in tech hubs and so on.
Seems this is another Government blind spot though - doesn’t feel like any politicians have a clue about the increasingly fragile state of the UK financial markets. I think they bury their heads in the sand and just assume it’s all down to rates. It isn’t - but if you will stick your fingers in your ears and whistle loudly it’s unlikely you’ll hear the music…….
The IC were calling for a BRISA (British ISA) to help with the lack of liquidity and interest in UK stocks. Seems a great idea, and I can actually envisage this happening pretty soon.
Initially this can look like a good idea but I believe that it is in fact a really bad idea. At present the shares of UK companies are an open market and the money of investors is free to move where the best returns are to be had. If we force money into UK companies they will inevitably start to carry a false value, even if we feel that some of them are currently below a “proper” value.
The are several concurrent issues:
1. The UK simply does not have the domestic wealth to support the market that we want. The funds invested by Private investors are largely irrelevant and even the investment funds which have moved their money to the US are, compared to the US investor funds available, entirely on a smaller scale. We therefore need a positive, rather than passive, pitch to funds from overseas, especially since we took ourselves out of the EU leaving an impression that we rejected them.
2. In both the US and the UK the drain of investment to tracker funds has taken a large potential measure of individual share liquidity out of both markets . This flight to trackers and similar funds has been exacerbated in the UK by a very unfortunate pressure on Trustees to avoid any kind of risk in managing funds (particularly pensions). There needs to be a rethinking of the liability borne by Trustees when making investments in individual stocks and the potential thereby for increasing returns.
3. Even the government has recognised that we need funding to be there for serious enlargement of companies that have long term potential. The spirit for taking these risks has to come from those who can afford to lose occasionally. We have too many companies that are unable to come by the £50mm to £100mm that will push them to size without falling into the arms of a foreign takeover. It is also difficult to pursue these aims in the spotlight of nervous investors, the deep bench of private wealth in the US allows there to be many, many investors who can take ,say, a $20 million risk on a promising business. An interesting question for us is whether we have made this more difficult in the UK by having no companies that are truly private, in that reporting to Companies House is visible to all , for any company that claims the rights of limited liability. We have claimed a moral principle here but it may be too expensive.
Apologies for length
I fully agree with this - if the Government can't be bothered to bat for its own team, no one else will.
Compare attitudes to investment here in the UK, where no one could tell you the share price of Shell (AMS:SHELL), to attitudes in America where everyone can tell you the share price of NVIDIA (NSQ:NVDA) and moreover are frequently invested.....
This post beats the famous BnB teapot post (sorry BnB).
Look at the discussion today. Trying to find excuses that basically are not there to justify the DAX vs FTSE100 performance! Is it a crime to admit that the DAX returns were better? It’s just an observation that means nothing for future performance or means everything. Who knows?
Speaking about Total Returns (like it’s something unknown). Over the 40 years history in TR DAX has performed about 2000% but the FTSE100 a merely 1400%. That’s a big difference for two economies about the same size most of these 40 years.
Another posted that the GDP has no correlation with the stock market! Over my years in the industry the first thing we used to do when investing in a foreign country was to try and forecast the growth in their GDP and then decide to invest or not. Look at what happened to the GDP in all major US stock market crashes and then………
Attitudes to investment plus liquidity driven (as David said).
This post beats the famous BnB teapot post (sorry BnB).
It was good while it lasted :-)
Not a crime to admit that DAX returns are better, just a crime to compare indices if one is total return and one is not... and imply the comparison says anything meaningful
Over 40 years the FTSE100 was 1400% and the DAX 2000% in Total Returns. I have stated these but still people contradicting.
And the German economy has performed better over the years (unfortunately).
I think I'm 'another poster'...I like how your experience trumps research and facts...impressive. Much academic market work show the poor correlation between GDP and market returns...You can find it too if you're willing to look outside your 'experience'. To be sure, momentum effects and beliefs mean that economic growth can correlate to index returns short term but its a fleeting effects driven by sentiment/expectations (probably based on ersatz non backtested models of what 'feels right')
No need to be embarrassed and disassemble about the fact you didn't realise the difference between DAX and FT100 in terms of total return and not....and then double down with your 40yrs take....which has many problems to it...
Your 40 yr returns for DAX and FT100 work out at 7.78%pa and 6.82%pa so 0.96%pa difference. Certainly compounds over time, however...
DAX only started in 1988, FT100 launched 4 Jan 1984 so just squeaks 40 yrs. So you ain't comparing apples to apples however you've boshed your numbers together (ie you've either used a truncate german history or found a non DAX german return - only 4 years but depending on how those 4 years were in the market they are significant).
But there are other factors to consider in making such a comparison that make shouting DAX beats FT100 over 40 yrs so I win a discussion a bit silly....
1) DAX is 40 stocks and was actually only 30 until 2021. FT100 is and was 100 stocks....less winner bias perhaps
2) Being listed in Germany over the last 40 years is more unusual than in UK.
3) I don't know the construction rules for either index other than the simple points in 1 (I don't track indices so why would I bother) but they will be different and it will make a significant difference
4) There is a significant sectoral difference in exposures.
5) The FT100 has a much more significant global earnings bias over time than the DAX had (DAX been catching up I'd guess but still lags)
Anyway, the whole discussion is a bit silly and I'm not getting into further unless you've got something informative to say....
At least you have admitted that the DAX has outperformed. It certainly compounds as well and that makes the difference much bigger.
As for your previous comment about how Germany have cheated I couldn’t have agreed more but is a subject for another day. Just a brief example that they were borrowing on negative interest rates for years while other €members were paying 5%-10%-15-20%……….
All the best
Completely agree. It is absolutely awful to be an investor in UK stocks. All of my global ETFs have soared in the last couple months, whereas my UK stocks have experienced little upwards movement. Unfortunately, valuations on the LSE are starting to look like a lost cause and I don't blame any company for listing elsewhere.
Does anyone know why there is no stock rank for Greencoat UK Wind (LON:UKW) ?
It's an investment trust - Stockopedia doesn't really cover those. Go to the AIC website and that has everything you could need for investment trusts.
Pendragon (LON:PDG) changes to Pinewood tomorrow according to today's RNS. I have been interested in the stub company ever since listening to the Rockwood podcast but I lack understanding on what happens moving forwards. I didn't want to take on the big divi which would have required ISA rejigging, so held off on buying Pendragon (LON:PDG). Will Pinewood open for trading tomorrow? If so, do we have an indication at what price? I don't hold, but am exploring opening a small position in Pinewood if there is value to be found in doing so.
Hi BenHazz - My understanding is that the dividend is not due until later Q1 or Q2 for Pendragon (LON:PDG) .
All this RNS confirms is that the name and ticker changes tomorrow. That means it will remain at the same price and wouldn’t drop until it goes ex-div. I don’t think that ex date is confirmed yet but if anyone has any better info would be good to hear.
At current price of say 35p then it will go ex-div like any other stock and should then trade at 10.5p. Multiplied by the 1.74bn shares in issue and you get circa £175m market cap once everything is complete. The question is whether it is then good value at that valuation.
Thank you David, much appreciated. I will keep an eye on it over the next few months.
The British arm of Body Shop has gone into administration.
https://news.sky.com/story/bod...
Another one bites the dust. We seem to be losing all our good retail shops, will be confined to Amazon at this rate.
Body Shop UK goes into administration. More work for Frp Advisory (LON:FRP.
Frp Advisory (LON:FRP) maybe get a trading update this week?. Previous couple of updates were pointing to increasing demand.
(December). "Outlook and current trading
· The FRP team is experiencing increased demand for their advice and we have leading positions in our core markets.
· The Restructuring Team are considerably more active this half compared to the same period a year ago, with administration market share gains
· Trading to date has been positive and the Board expects to exceed current consensus market expectations for FY 2024. If current activity levels continue the Board expects the Company to deliver revenue of £123m and adjusted EBITDA of £32m for FY 2024"
Frp Advisory (LON:FRP) maybe get a trading update this week?. Previous couple of updates were pointing to increasing demand.
Yes, any day now should get a Q3 trading update. Last year’s was on 13th Feb.
Ultimate Products (LON:ULTP) I like this company and the management having held for the last few months, however I have banked profit today because I feel that while buybacks show surplus cash flow, and to an extent underline the value here. I am keener on companies that can reinvest at sustained ROIC. I had invested in ULTP on the belief that it may become an acquisition and brand management machine, able to acquire at value, develop and grow brands through product innovation and geo coverage. However there is no sign of another ‘Salter’ type opportunity at this stage and recent mgt comments point to a dearth of such opportunities. Therefore opportunities for reinvestment are limited hence the buybacks. None of this detracts from it being a well managed and nice business to own over time, just not necessarily as exciting as I had hoped. I would certainly invest again if they become very cheap again (currently just cheap IMO!).
Re Ultimate Products (LON:ULTP) I always felt they should acquire horizontally …eg like https://www.rayware.co.uk/abou.... who supply related but different products to similar buyers…based on Merseyside so decently easy to manage …I’m sure they will know each other
Rayware was acquired by PE a few years back https://quoteddata.com/2021/07...
..but there must be other similar privately held groups to go at.
So I think Ultimate Products (LON:ULTP) just gave about as clear a buy signal as you can get if you are willing to squint a little as you look at the TU...tbc I never claim timing ability and my comment is very much fundamental and of the build it and they will come nature.
I’m moderately relieved at the result. Felt like a tricky period (I've said this to people if I talked to them about ULTP). As ULTP never control the short term demand picture (which is magnified both ways by stocking dynamics) its really hard to forecast half on half, even if the sales trajectory is up. But outcome shows their business model is working better than I thought it could given margin improvement (a real good mgt and implemented AI/robotics story that was happening before it was a hot topic)!
I don't think the buybacks are in the forecasts yet as policy not announced so there's a small fy24 eps surprise to come there, growing in fy25. Re freight I was not structurally worried as there is an excess of capacity in the market that is likely to persist (unless anyone's forecasting a global boom) so once it adjusts the extra sailing time is not an impediment (there’s a chance that the current spike suppressed/delayed ordering/shipping of lower value items like cleaning products where the cost of shipping is more impactful on economics).
Overall, they have displayed they are a killer machine in their segment. The forthcoming surprise and upgrade cycle just got stronger…now where’s Godot?
PS re avoid China..fair enough...this is a risk IMO small likelihood but large impact...but IMO its in the price of ULTP as everyone knows the immediate impact. So its like someone pinching your nose...can't be ignored and irritating. But if the China risk materialises the shock to other stocks is less priced and sometime as profound -> more a knockout sucker punch to the side of the head. For example, miners/oil wont be a hiding place. Or take golden child NVIDIA (NSQ:NVDA) and many things AI related- it'll be pretty worthless if it can't source chips from Taiwan. Whereas, ULTP is asset light, no doubt will face duress (potentially terminal for sure...but...) but can re-orientate its business to other sources. And we will all be looking for other sources of goods and paying up for it.
Is Mr Contrarian on holiday? Missing the usual succinct analyses and dry humour....
Yes Dave - apparently in Prague! One of the other mentioned he was away yesterday.
Aha!! But a poor excuse .... !!
Belluscura (LON:BELL) thanks for update Paul. I don't hold other than indirectly through Tekcapital (LON:TEK) , which owns 10% (which seems to be valued at less than nothing already).
You write that they" are trying to raise cash through buying a cash shell with paper." but isn't that a done deal if they now have 95.67% acceptances ( from today's other RNS)?
Thanks Roger for pointing out that Belluscura (LON:BELL) deal now looks close to being done, I wasn't aware of the latest acceptances figure. So as you suggest, that should now go through shortly.
Re: Ultimate Products (LON:ULTP)
In a way they have already been doing buybacks as a result of further regular purchases of shares in the market for Employees Options scheme. They have been doing this for some years.
Of course this basically hedges the options that at some point Employees may exercise, so that the Company does not have to issue new shares- which is generally prudent in my view if the pricing is reasonable, and the cash is there. It doesn't technically mean there are less shares in issue, as these stay the same.
So I am not sure if they will now pause this, if they opt instead to Buy Back. We also don't know if they intend to cancel these shares, as that would technically boost the earnings per share ratio, again a sensible measure.
However, they alternatively could buy these in for Treasury, and these will sit in a Treasury account, and still be dealt with as shares in issue but with no voting rights or rights to dividend. They could then use them at a future date to issue against options. Therefore they would not technically count as cancelled and would not alter the earnings per share calculation.
If they intend to buy in shares for the Employee options scheme and a more formal buy in process that may exert a reasonable amount of upward momentum on liquidity in the market.
It would be interesting to know how they plan to handle this.
ULTIMATE PRODUCTS
Good company and impressed with management at Mello, easy to understand business .
Don’t agree with the analysis that freight rates aren’t an issue should definitely be flagged as it’s an evolving situation
From what I can see it buys almost everything from China and puts it on a ship .
Freight rates whilst not at covid levels are elevated over budget and will reduce margin in the next period .
I checked with my forwarder yesterday and looks like rates are reverting downwards not continuing up , for anyone interested here’s the rates this month
Freight Rate 20ft ex Xiamen Port to Southampton Port USD 2538
Freight Rate 40ft ex Xiamen Port to Southampton Port USD 4471
Countered and offset by an improving GBP v USD which should work in their favour though they have probsbly hedged .
.
I nearly invested based on good management but really just does not interest me in any way shape or form plus the FD was a scouser which put me off .
They are a Northern based company, so a bit strange to hold a bias against scousers. Each to their own I guess. I believe the ex FD for Patisserie Valerie was a Southerner, so all the reassurance you could want there!?
Ultimate products
Any company that buys all it's stuff from China is uninvestible for me, whatever it's performance. Plenty of opportunities elsewhere
Why do you think that way about China’s products. I am very much interested for an analysis on your comment.
Thanks
yiannos, we have allowed our manufacturing to be exported to China, where the playing field is skewed, and the environment concern doesn't exist.
Fair competition is fine, but the relative cost of doing business in China, with the lack of regulation, cheap energy (mainly from coal), means fair competition is impossible.
Result, loss of jobs, our inability to be remotely self sufficient. To add insult to injury, government jumps on the green bandwagon. If it were honest, the environmental damage and CO2 emissions from production in China should be added to ours.
But this forum isn't the right place for this politics!
I thought it was political and makes no economical sense. There are not enough resources to achieve all these.
All the best
brryhayward
and the environment concern doesn't exist.
to be fair to china they are probably adding materially more renewable energy sources than any other country on planet earth - its easy to diss em with outright lies but to say environment concerns dont exist in that country is complete and utter lies evidenced as such by their large renewable investment.
i am not saying China doesnt look after number one - it clearly does - so i would agree we need to look after number one too but I remember having the annoying "if we arent manufacturing everything the company will be bankrupt" argument with my mates in the 90's clearly we have managed ok overall despite the predictions of doom and gloom when stuff first started going to China.
China: Call it energy independence investment and I'll agree with you....there is very little evidence its driven by environmental considerations (there is pressure re pollution)
what got my goat up the fact it was suggested there was nil concern for environment - its pretty obvious they prioritise other things ahead of the evirnoment but its pretty clear to me they are not doing nothing in that regard. Ok they have built a boat load of new coal power plants - but the reality even there is probably that most of the new plants are replacing old plants that are not as efficient so on lfl basis a probably improvement - i had hoped China would be at peak coal consumption by now (i think they hoped so too about 5 years ago ) - they have failed to get there but i dont think it will be long before they have past peak coal. Not really going to over the top stick up for them but the fact they are producing more renewables than all other countries its realy a joke to say they aer doing "nowt". Heck they even publish their 5 year renewable targets which can be critiqued if they miss them - i notice in those plans 50% of incremental consumption ref electric and enery will be renewable - not as much as some may wanty but deffo not zero effort.
During 2021 to 2025, more than 50% of the country’s incremental electricity and incremental energy consumption shall come from renewables.
So you have been watching the Peter zeihan YouTube channel too?
I take his prophecies on China etc with a sack of salt.
But his comments on Canada USA Mexico are more credible
(His view is that China will cease to function as a country within 10 years so good luck relying on imports. He also thinks the same is true of Germany....
He trumpets the virtues of American adaptability and innovation but seems less positive on other countries abilities in the same domains.
Personally I do hold with 'never bet against the us' (ed crofts first boss) but not at current prices and political uncertainty. )
Yes, Andrewdb, I know of Peter Ziehan, but haven't listened to him.
I subscribe to Epoch Times/NTB news, and have friends in China, have spent time there. They have performed miracles, but at the expense of the environment and brain washing of very decent people.
There may well be opportunities to invest in China, but I wouldn't spend a penny.
The other bit I'd add is that as freight rates Ex China flew up due to 'Red Sea issues', there was a missed reality that at the same time we were very much in the run up to Chinese New Year - which always sees a spike in container rates.
Close Brothers (LON:CBG) has come to my intention and wanted to flag. Whilst there has been some self inflicted harm through poor purchase of Litigation finance business, as well as ongoing FCA undefined Motor finance liabilities, these would appear to be relatively small value compared with the huge loss of market cap. The company used to attract a premium valuation, but now is valued at 0.39*BV, which for a well-financed (albeit costly last finance) bank seems excessively cheap. I remember a podcast in November, where Roland Head picked Close Brothers (LON:CBG), stating at £8/share this represented deep value. The reason I flag today was the stock briefly fell below £4/share, before bouncing a little - feels a good entry point (unless I'm missing something ;)
CBG
I have been watching this share daily and I have a reasonable exposure. The company is facing a difficult time because of mis selling the car finance. It reminds us of Personal Protection misselling which started with 1 billion estimate and ended up costing the banks in excess of 50 billion. Whether this happens or not and how much is the damage is difficult to calculate. The market has decided that the penalty is going to be high enough to destroy the company and has priced it for bankruptcy.
Thanks Yadi, I agree with the sentiment here, the FCA creating more chaos than actually achieving results; yes they stopped discretionary selling of these loans back in 2021, but to leave this review open and rolling to the end of the year is causing much more pain than any good it may achieve! I do question the market's perception of quantum for this potential liability. The FCA's own finding was that only a small proportion of loans were provided to vulnerable customers, and much of this "wrong doing" falls on the motor traders, rather than the lenders. The FCA has given a further 9 months to settle outstanding claims, rather than step in with fines, which does not suggest an aggressive approach, however the rolling uncertainty surrounding this topic will ultimately cause much more damage to credit availability than it will solve. Should a Bank fail due to this uncertainty the FCA would be roasted! Also I note that CBG has taken steps to increase financial liquidity.
Close Brothers (LON:CBG)
How do you know the undefined FCA motor/similar liabilities will not be material?
Saietta (LON:SED) a shitshow - yet respected fund managers continue to tout its virtues in interviews posted on Stocko.
Another hopeless case is AFC Energy
agree on AFC Energy (LON:AFC) - Money pit
Saietta (LON:SED) Shitshow is the word. I'd say the wheels came off this when they released a total flip flop operational update mid 2022. Share price was 160p at the time. They then got involved in Conmet truck development for some bizarre reason , tho institutions backed them, raising £20million at 138p
Far too many plates spinning, a hopeless CEO and ridiculous cash burn did the rest.
Worth mentioning broker forecasts after the Conmet deal were £100million revenue and 40p EPS for 2025. Looks laughable now.
This was my best £ trade in 2023, on a large short term spike. Tho I think on reflection it was probably 10% skill on my part and 90% VOX interviews.
Congratulations the other day for spotting Paul Hill’s post Sondrel (Holdings) (LON:SND) early morning and asking if he has sold before or after his post. He has admitted though later that it was late morning he has sold!
Hi Wolf,
Thanks for posting the volume spikes recently. I really wish Stocko offered this facility!! It's the main thing which would attract me to Sharepad. Last week you highlighted a big spike in Sanderson Design (LON:SDG), which I hold. I checked and it was a huge negative volume increase but with zero correlation in the share price. I suspected a leak and sold 20%. If I was a more experienced investor, I would doubtless have sold the whole lot as a couple of days later they dropped 15% or so.
I've not tried Sharepad yet, I will at some point, but the beauty of Stocko is the rankings system that actually does work in filtering out the garbage , however then it becomes when to buy that counts. There is a screen for volume spikes on Stocko(search the screening articles), but it only compares the 10d vs the 3M average volumes, not one day spikes. I personally don't care much for one day spikes but it may be useful for when the trend is very extended as it can indicate a reversal when used in conjuntion with other technical signals. Volume in general is useful in support for confirming a trend in motion, validity of a breakout, or can also indicate churning in a sideways trend, but in isolation not that useful imo.
No worries Rogerh, glad it was some use to you.
Occasionally can get a heads up to some nice trades like Beeks Financial Cloud (LON:BKS) or CMC Markets (LON:CMCX)
Comforting update on Good Energy (LON:GOOD) (I hold) from Canaccord on the impact of yesterday’s acquisition of JPS.
End of FY23 excess cash estimated at £15m after accounting for acquisition proceeds, so EV of £27m at today’s market cap of £42m. FY24 Adjusted PBT boosted to £8.4m from £7m. FY24 forecast ‘Clean net income’ of £6.6m up from £5.5m
So, even valuing the investment in Zapmap at zero (£13m in August 2022), in my opinion, this gives a very attractive valuation by a business led by a very capable management team executing its stated strategy.
Not sure why the announcement from Gresham Technologies (LON:GHT) justifies an RNS. $1.5 million license revenue over 5 years does not sound like a lot for this sort of deal - however that is a minimum, and the professional fees will be rather more than the license revenue. Still, I see they have been ticking up nicely over the past month. Stocko gives a forward PER of 19, which is historically low for them. The new era of generally higher interest rates should be good for them. I hold, and have done for some time.
Oakley Capital Investments (LON:OCI)
Further sizeable buys by directors. Close to £700,000 announced this morning. I hold.
Jet2 (LON:JET2)
I hold
All the anecdotal evidence suggest that business at Jet2 (LON:JET2) is motoring, if this morning's announcement by TUI AG (LON:TUI) is any indication. The former is best in class in its peer group and a trading update should be released soon.
Jet2 (LON:JET2) continues to look seriously undervalued IMO especially when you look at the balance sheet - I know TUI AG (LON:TUI) is also trading on a low p/e but it has a lot of debt. Which? also continues to rate Jet2's customer experience highly and gives it Which? recommended provider status which I think bodes well for positive customer goodwill towards the business.
CEO of Good Energy (LON:GOOD) dips his hand in his pocket to buy a meagre 5k worth of shares after his company drops over 25% this month. Is it just me that sees this more as a show of weakness than strength. I recognise everyone has their own varied financial situations but this guy has had many many years in very well paid senior positions, I'm sure he could have put another zero on that figure if he had real confidence.
GOOD
Ben, it was the Chair and Non-executive Director, William Whitehorn and yes I would've hoped for more conviction.
Hi Lemming,
Good Energy (LON:GOOD) There were two RNS this morning, the first was for the CEO:
FTSE100 VS DAX
I am concerned that there are people that believe that the FTSE100 trading at 3500 in 2002 has matched the performance over the years of the DAX trading at 2500 in 2002.
FTSE100 is now around 7500 and the DAX around 17000.
It depends on the start date, but you knew that didn't you.
So DAX is a total return index.
So DAX is a total return index.
I believe that to be the case. The DAX was based on 30 German shares until recently but is now 40. The way dividends are treated has also changed, so this makes comparisons between indices difficult.
Previous dividend rules
Dividends smaller than or equal to 10% of the
market capitalization of the distributing company
are reinvested in the distributing stock via
adjustments to the c factor.
New rules from March 2023
Dividends are reinvested in the whole index portfolio
via adjustments to the divisor.
It’s very clear what I have written.
Unless you think that they have generated about 700% in dividends the last 20 years.
DAX has always been a better performer Han the FTSE100.
All the best
it's also clear what I have written. The DAX is a smaller sample than the FT100 and consequently is more volatile. Over the long term there is not a great difference between the two unless you cherry pick the start dates to suit your argument. There are other indices that have outperformed the FT 100 but that is a different issue.
Where do you get 700% from? The DAX is up about 160% since 2020 and the FT 100 TR about 170%, a negligible difference over more than 20 years
Numbers are there and it is clear-look at the cycle from the early 2000’s.
The FTSE pays about 3.5 % on average dividend yield-the DAX has increased about 700% and pays about 2.5% dividend yield.
DAX has outperformed and will continue to outperform.
Uploading some random numbers (Covid era to date) is not a valid comparison.
As for the other indices (US ones) no need to comment!
Done with this topic as anyone can go back and look at the 2 indices and their performance.
All the best
According to Google Gemini (FWIW!):"Comparing the performance of the DAX and FTSE 100 since 2000 reveals a more complex picture than a simple "one has performed much better" statement. Here's a deeper analysis:
Overall Performance:
Yet again taking the FTSE100 and then making it into FTSE ALL share index and then reinvesting as well the dividends for a convenient answer!
The German economy has outperformed as well the one in the UK in terms of GDP growth.
All the best
DAX is unusual as it includes dividends so not a like for like comparison
We have covered that before. And you are correct , but still massive underperformance by the FTSE100.
Look at the indices for the last 20 years. The FTSE100 and in general the UK stock market needs to attract some serious listings before it’s too late. These old economy stocks are going nowhere.
This is my point -look at the AIM-number of companies listed has been declining and I do not believe it will survive unless some very serious measures are taken.
All the best
Kier
Huge apologies to Kier yesterday for brain fog moment of the day .
It was Amey that chopped our trees down .
It’s kier that charge us reportedly a whopping 20,000 pounds for installing a park bench .(I’m going to the next council meeting to ask if this is correct )
I’m very probably wrong on that and my due diligence extends to what my mate Tim told me in the fat cat .
Morning Planetx,
Regarding Kier (LON:KIE) valuation
Nice to see we have moved from cutting trees to a park bench.
Centaur Media (LON:CAU) there is some value but yet again an illiquid stock that offers limited options to buy and sell. The problem I have with these stocks is that as soon as you buy them you need the bid price to move +20% to make anything.
All the best
Ylannos
Centaur spread isn’t that bad at the moment
But yes it’s a problem as is getting out of big positions so definitely playing with fire that’s why you really need to get very comfortable with the company . Management . Sector , products. - the only way I can describe is you really have to be prepared to think that you have bought part of a company and not a share to trade .
Anyway centaur will stay a small holding .
I can’t get away from Avingtrans for deploying my funds which will take me up to a maximum holding of course I buy a token 9k of shares and price starts rising !
Who cut all the trees down in Plymouth?
CENTAUR MEDIA - sell the sizzle not the sausage
Decided to have a good look at centaur medua which I’ve held in the past and sold and have bought a few recently following the sell off .
Have to say incredibly disappointing that a media company presumably skilled at communication and marketing is so poor at presenting themselves .
The company website is their front facing portal for investors so you would have hope would have been on the money for a marketing led company .
The main focus is talking about their “2023 plan and targets” full of Waffle and who has a business plan based on a year that has just elapsed .
Also has a big se ruin proclaiming “net cash of 16 million” whereas the net cash is now 8 million according the the last accounts (16m is an old number )
Pretty woeful really
Still looks ok
8m cash
50m assets but 40m is goodwill so can drive a bus through that
1.9 profit after tax for 6 months so say 4p for the year
All sales static or declining
Still looks on the cheap side and. supposedly “the lawyer” is a prized asset worth a lot so if they sold that off that’s the only stimulus I can see for a big increase for shareholders .
How disappointing, come on guys remember to sell the sizzle not the sausage !
Ultimate Products (LON:ULTP) - new note accessible here: https://www.equitydevelopment....
Ultimate Products’ (UP) sales fell by 4% in the first six months of FY2024, with the likelihood of a broadly flat full year. But the company’s FY2024 profit expectations - and our own EBITDA forecasts - remain unchanged as improved gross margins should offset lower sales.
UP’s first half sales setback was caused by 3 important temporary effects. First, the company lapped an unusually strong period a year earlier when demand for air fryers was at a peak. Second, supermarket overstocking has taken longer to dissipate than might be expected. Third, UP was negatively affected by disruptions to global supply chains related to conflict in the Red Sea. In contrast, the gross margin outlook is significantly more positive as the uplift to gross margins achieved in the second half of FY2023 appears likely to be retained in FY2024. We increase our gross margin expectations in FY2024 from 25.5% to 26.6%.
Some idea of buyback potential is available from today’s trading update. The company targets long-term net debt/EBITDA at 1.0x. If our expectations for end-FY2024 net debt of £8.0m are met and £21.6m EBITDA are met, the implied headroom for share buy-backs would be of the order of £13m to £14m – equivalent to around 10% of the company’s current market cap.
With positive news on the scope for buybacks in our view offsetting lower than expected sales revenue in FY2024 we maintain fair value of 250p for the shares.
There is a recent product safety recall on some Beldray and Salter products.
https://www.gov.uk/product-saf...
It is reported that products sold since January 2020 are concerned.
"The brands are Beldray and Salter. The product descriptions are BELDRAY REVO CORDLESS, BELDRAY REVO PET PLUS, BELDRAY REVO DIGITAL and SALTER HANDY PRO HAND VAC. All batches and colours are affected. The defect affects all UK and Ireland adaptors supplied since January 2020. BS, 3-Pin, DC Adaptor Model Number TYBSDC1400500."
https://www.limerickleader.ie/...
Presumably, the costs could be claimed back from the Chinese suppliers but it would be good to have the company's confirmation on this.