Small Cap Value Report (Tue 14 Feb 2023) - BMS, BPM, UPGS, ALT, ADF, PLUS

Good morning. It's Paul & Graham here!
Today's report is now finished.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Agenda/ Summaries
Paul’s Section:
Braemar (LON:BMS)
317p (pre market open)
Market cap £104m
Braemar Plc (LSE: BMS), a provider of expert investment, chartering, and risk management advice to the shipping and energy markets, today announces an update on trading for the year ending 28 February 2023…
It’s only a vague comment today, with no mention on how the company is performing vs market expectations -
The board of Braemar is pleased to report that the Group has continued to trade well since the release of its interim results in November 2022. The integration of the Group's newly acquired Spanish and US businesses announced in December 2022 has progressed well and both businesses are set to make an immediate and strong contribution to the Group's trading in the next financial year.
The board looks forward with confidence to providing a more detailed update on trading for the year ending 28 February 2023 and on expectations for the year to February 2024 in a pre-close update to be announced in mid-March 2023.
Capital reduction - this is just a minor administrative matter. It looks as if the company inadvertently paid out divis incorrectly. This is to be fixed by creating distributable reserves, and a deed of release. Nothing to worry about in my opinion, and it will ensure that future divis can be paid out without breaching the companies act. I’m not aware of there being serious penalties for this kind of thing, as nobody is actually harmed by accidentally not having enough distributable reserves, where a company is comfortably solvent, as is the case here, so I can't see why anyone would take legal action against the company or its Directors in this situation.
My opinion - we covered competitor Clarkson (LON:CKN) here on 6 Jan 2023, which was trading well, enjoying good market conditions for shipping.
Braemar published excellent interim results to Aug 2022, more than doubling adj profit to £10.5m. This was above expectations at the time, and the FY 2/2023 consensus forecast of 41.7p was already three-quarters in the bag from the interim results (H1: 31.8p adj EPS)
Looking back at the last couple of years, there seems to be a strong H1 bias to profits, so the current year looks to be following that same pattern.
The last balance sheet wasn’t particularly good, with negligible NTAV, so the company is relying on its profits to generate the cash for divis, rather than any large reserves of cash (net cash was £1.8m at end Aug 2022).
Overall, BMS looks a decent company, trading well, on a reasonable valuation (forward PER of 9.5, and 4.2% dividend yield). The crux of the investment case, is whether it’s enjoying a cyclical or pandemic-related boom in profits, that is likely to subside? Or whether the much higher profits this year FY 2/2023 are sustainable? I don’t know, as this is not a sector I understand, so for that reason I’m neutral.
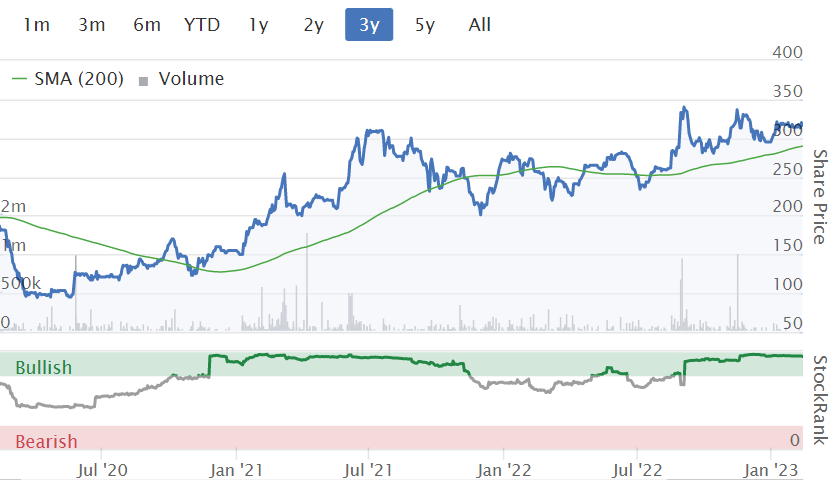
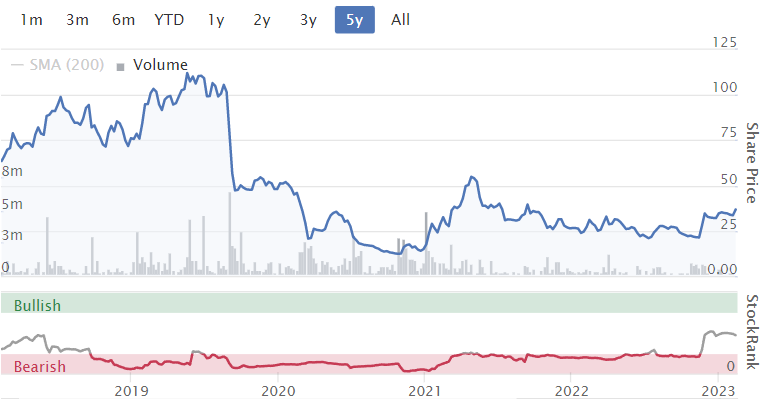
Note below very high StockRank.
As you can see this share has done well since the pandemic lows, which are coming up almost 3 years ago, so I might have to switch to 5-year charts shortly, to include that detail (which is a useful reference point for peak market gloom in March 2020) -
UP Global Sourcing Holdings (LON:UPGS)
154p (down 7% at 08:48)
Market cap £139m
Ultimate Products, the owner of a number of leading homeware brands including Salter (the UK's oldest houseware brand, est.1760) and Beldray (est.1872), is pleased to announce its trading update for the six months ended 31 January 2023 ("H1 2023").
There’s a cheerful headline, but the market doesn’t seem to agree, with a 7% drop in share price so far this morning.
A robust trading performance, boosted by strength in Online and ongoing demand for energy efficient and money saving products for the home
Having gone through the update, I can’t see anything of concern, so maybe this morning’s drop in share price is just a bit of profit-taking? Who knows. Anyway, here are the main points -
H1 revenues up 2% to £87.6m (perhaps this has disappointed? It’s not very impressive in an inflationary environment, so I assume prices are up, but volumes down?)
“Continued normalisation of global supply chains” - good to hear.
Retailers in UK overstocked, but now returning to more normal ordering pattern.
Net debt - no figure provided, but we’re told it’s 1.0x EBITDA, down from 1.3x in July 2022.
Plenty of headroom (£22.4m) on bank facilities.
Inflation being offset by cheaper freight costs, and partial recovery of £:$
EDIT: the update mentions robotics process automation. I raised a query on this, asking if it's automating the warehouses with robots? It's not. Just to clarify this, it's automating processes within administration, that were previously repetitive & manual. End of edit.
Outlook - this is the most important bit, and it reassures -
The Board anticipates a full year performance in line with current market expectations.
There’s no footnote detailing what market expectations are, which is glaring omission - it is best practice to include a footnote, simply because it helps investors, providing clarity, avoids misunderstandings, and saves us time.
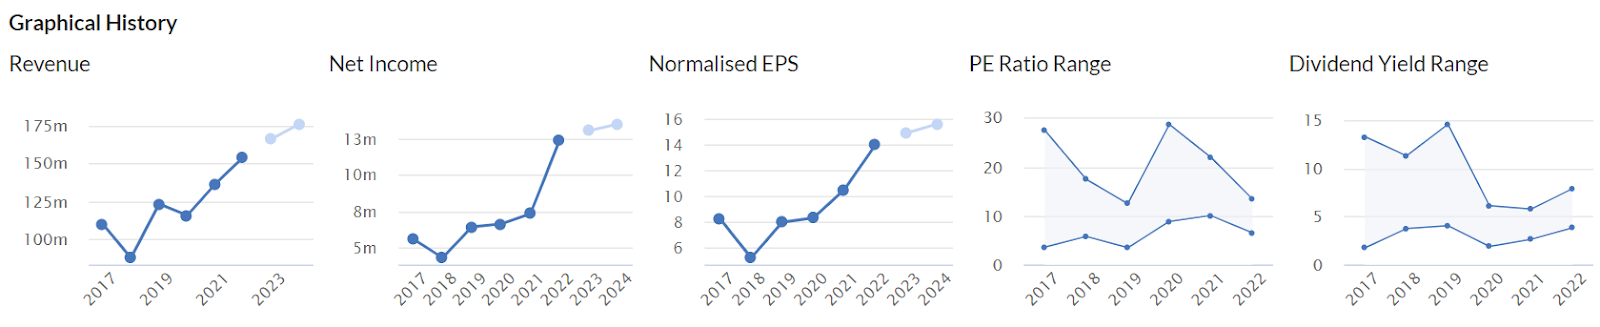
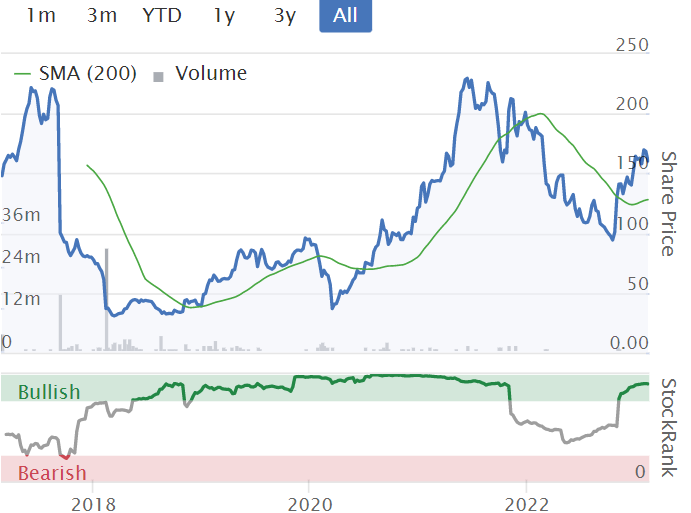
As you can see below, UPGS has developed a nice track record of earnings growth, after an initial disaster shortly after it listed in 2017, which is now a distant memory I’m pleased to see.
My opinion - I like UPGS. It seems an entrepreneurial business, with hands-on management owning big stakes, which is what I like to see - interests aligned through shareholdings, not the all too common overly generous free share options schemes.
When watching webinars, or having calls with management, they always seem on top of the detail, and capable of managing the business through all manner of crises - it’s important to remember that in the last 3 years, many companies have had covid, lockdowns, major disruption to shipping & supply chains, periodic collapses in demand, major uncertainty, an energy crisis, and rampant inflation to deal with. Not to mention gyrations in commodity prices, labour shortages, interest rates shooting up, you name it! UPGS seems to have handled all of this with aplomb. That gives me a lot of comfort in the resilience of the business, and that even if new problems emerge in future, UPGS is likely to cope.
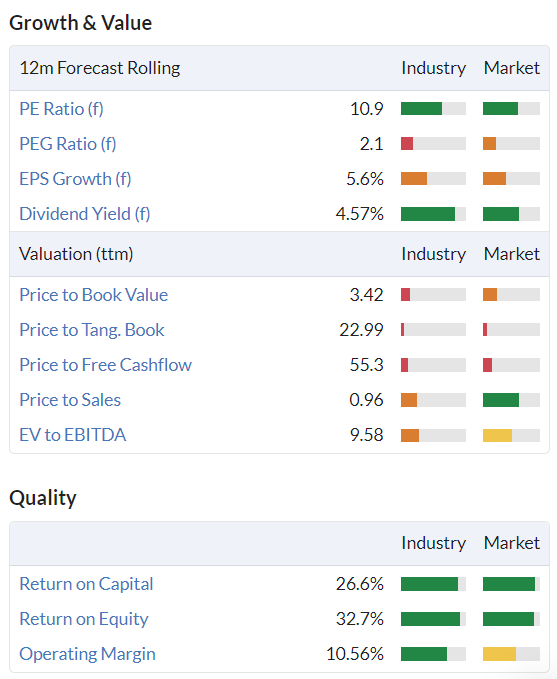
As you can see below, UPGS has attractive fwd PER & dividend yield. There’s not a lot of balance sheet support though. Also note high quality scores too. The StockRank is correspondingly high.
Overall then, all the facts & figures are pointing me towards taking a positive view of this share, so it's a thumbs up from me (please remember our views are just an overview of the fundamentals, we’re not making any predictions on what the short-term share price is going to do - which is in the lap of the gods!) So it’s always up to you to decide if you find the price attractive as a buy, hold or sell, based on your own methods.
Facilities by ADF (LON:ADF)
58.5p (up 7%)
Market cap £46m
Facilities by ADF, the leading provider of premium serviced production facilities to the UK film and high-end television industry, today provides an update on trading for the full year ended 31 December 2022 ("FY22").
Strong trading delivering on all areas of growth strategy
Key points from today’s update -
FY 12/2022 results in line with market expectations.
Revenue up 13% to £31.4m
Adj EBITDA up 3% to £7.9m
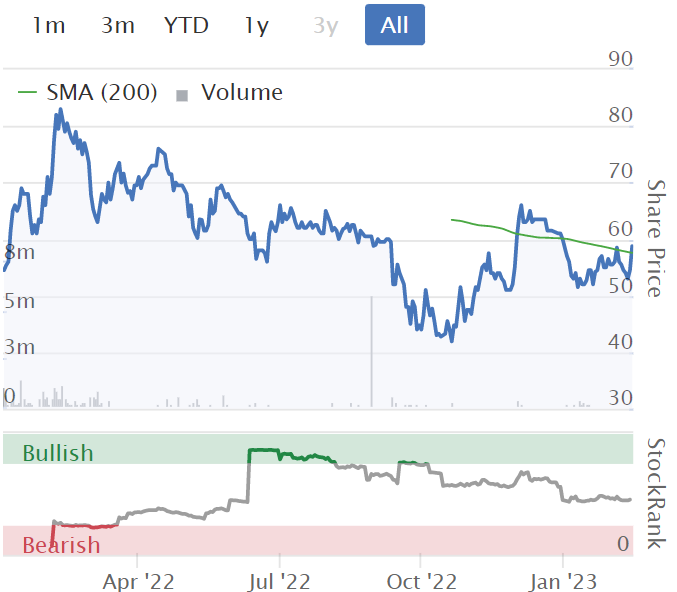
The reason why increased revenues didn’t flow directly through to EBITDA is because (previously announced) smaller individual contracts meant more down-time as equipment had to be moved around between jobs. So this mix effect does show the flaw in the business model - gaps between jobs, which could get a lot worse the next time the industry has a recession (no sign of that at the moment though).
Cenkos (many thanks!) publishes an update note today, showing that the £7.9m EBITDA becomes £4.3m PBT. As it’s an equipment hire business, we cannot just ignore the depreciation charge.
Basic adj EPS is 4.6p, so the PER is 12.7x which seems reasonable to me.
Capex - it spent £8.9m enlarging the hire fleet in 2022, with similar spend expected in 2023. Which raises the obvious question as to whether this is value for money, given that the big capex barely moved the dial on EBITDA in 2022?
Expansion in the UK is continuing, more detail in the announcement. It sounds as if things are going well. There was previous talk about expanding into Europe through acquisitions, which I’m not at all keen on. Better to stick to its knitting in the UK, I reckon.
Outlook - we’re told several times that the order book is strong, but no figures are provided.
Cenkos is forecasting a big increase of 50% in revenues for FY 12/2023, and EPS rising from 4.6p (FY 12/2022) to 6.3p. This type of equipment hire business should probably be valued on a PER of about 12, so I make that a share price target of 76p, a useful 30% ahead of the current share price.
My opinion - I’ve always quite liked this share - it floated at a reasonable valuation, and raised fresh money for the business in its IPO (unlike so many companies which float so that a private equity backer can exit at a premium).
The UK seems to be a popular destination for big TV/film productions, so there seems to be plenty of work available for ADF, and it sounds upbeat about the future.
It’s a cyclical business, so at some stage there’s likely to be a downturn, hence why I wouldn’t over-pay for this type of share. But right now, it looks to be in a good spot, and the shares seem reasonably-priced, hence I have to give it a thumbs up as things currently stand.
Graham’s Section:
B.P. Marsh & Partners (LON:BPM)
Share price: 342p (pre-market)
Market cap: £128m
This is an investor in the insurance sector, where Chairman Brian Marsh owns 40% of the company.
It has often been available to purchase at a discount to NAV and this remains the case today as the company had a NAV of £179.8m as of July 2022, a whopping 40% higher than the market cap (using last night’s share price).
Today’s announcement is a full-year update for the financial year ending January 2023.
The main thrust of the update is that “the Group remains positive regarding its ongoing performance and the outlook for the insurance market”.
We do not yet have a NAV figure for January 2023, but the implication is that we’ll be pleased when we find out what it is.
Shareholder returns: there is a small interim dividend (1.39p) and there should be a final dividend of similar value, if BPM is going to meet its “aspiration” to pay out £1m to its shareholders this year.
In addition, there is a share buyback programme, “to reduce the discount to Net Asset Value at which the Group’s Shares are trading”.
This was initially announced on January 16th of this year, and the BPM share price has already made some progress in closing the discount, even with very few shares having been bought back so far:
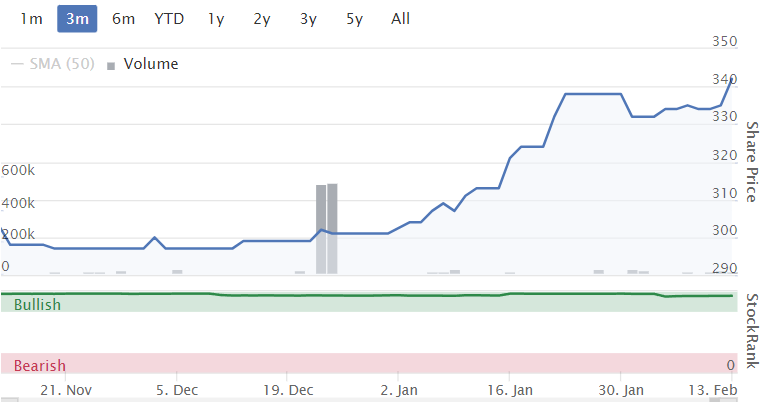
Buybacks will happen when the discount to NAV is at least 20% and to a value of up to £1m.
So for example, if NAV is still £179.8m, the buybacks can happen so long as the market cap is below £143.8m (share price c. 383p).
Investee companies: I am a former shareholder here at BPM. I must admit that I always found it tricky to follow their investee companies. Note that 66% of revenues are generated abroad.
I will only mention developments at the top two investees:
Kentro Capital - this is an insurance agent/broker with two main subsidiaries. It earned EBITDA of over £18m in 2022, up by 14%, and is growing by acquisition.
XPT Group (US-based) - another highly acquisitive company, BPM lent XPT $6m recently, to make yet another acquisition. Total premiums written by XPT in 2022 were over $500m, up 25% compared to the prior year.
Liquidity and new opportunities: BPM has no debt, cash of £7.2m and loans outstanding to investees of £16.4m.
It has “an active pipeline of new business opportunities which are currently being considered”.
Outlook
The company sounds quite bullish on pricing in the insurance sector, especially given the increased costs to insurers arising from recent events and macro challenges (including higher interest rates and inflation).
The insurance market has seen five years of constant rate increases across most lines of business, with the pace of these increases slowing somewhat over the past four quarters.
Accordingly, there have been various market discussions regarding the longevity of these price increases, given the slowing of rate increases over 2021 / 2022. Nonetheless, there has been no drastic downward change in rates, with the decline taking longer than the market expected…
Overall… the Group does not foresee a return to soft market conditions in the near future.
My view
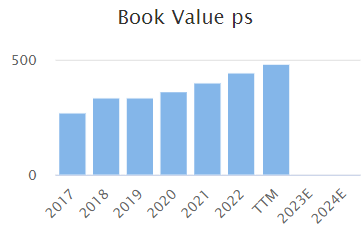
This is a company that I would not mind owning shares in again at some point. Based on the published numbers, the company has been growing book value per share very well over the years (CAGR is 10% recently, according to Stockopedia):
It has also paid a modest dividend.
And with the prospect of buybacks closing the discount to NAV, there is another reason to think that shareholders do well.
Therefore, given its very long history of good performance, I personally would be open to the idea of allocating a percentage of my portfolio to BPM again. I would be cautious about making it a very large position, however, without a really good understanding of the investees.
Altitude (LON:ALT)
Share price: 40p (+19%)
Market cap: £29m
We last covered Altitude in the SCVR back in November. It is a “marketplace for the global promotional products industry”. It runs the “AIM” platform in the US and also in the UK, but most revenues are from the US.
There have been some false dawns in the past:
Recently, the investment thesis has been built around the company finally breaking through to profitability and seeing operational leverage kick in.
Today’s trading update for the current financial year (FY March 2023) is materially ahead of current market expectations, as strong trading has continued in the months since the last update.
The Group continues to deliver on its strategy and has been experiencing continued robust trading via expansion of its Services and Merchanting programmes.
“Services” refers to Altitude generating revenue from serving suppliers and distributors in the industry (connecting them with each other and helping them to get the most competitive pricing or increased revenues).
“Merchanting” refers to the sale of promotional products by Altitude itself, using affiliates as sales agents.
The tone of the outlook matches the current momentum:
…the Board anticipates that the Group will continue to experience revenue and EBITDA growth throughout the remainder of calendar 2023 and 2024.
Cash - the company has an increased (but currently undrawn) credit facility of $1.5m. I would prefer if the company had a more comfortable net cash position.
Estimates - analysts at Zeus increase their FY23 revenue forecast by 4.8% to £17.3m and their adj. EBITDA forecast by 17% to £1.7m.
Adj. PBT is expected to rise from £0.8m in the current financial year to £1.7m by FY March 2025.
My view
This is a short update but it clearly adds strength to the investment thesis that this company can become a profitable “platform” type of business, deriving revenues from buyers and sellers while also using the platform for itself to generate revenues.
I’ll tentatively give it the thumbs up, though it’s more speculative than the type of thing I usually take an interest in. But after so many positive trading updates and with the price/sales multiples still only c. 1.7x, I don’t think the valuation is ridiculous, given the growth prospects.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

39 comments
I'm a bit late catching up...but Altitude (LON:ALT) is just an expensive and low quality version of Pebble (LON:PEBB). Twice now I've tried to speak to IR to clarify some aspects of disclosure/business and they haven't been forthcoming (one recent, the other c.9mths ago). IMO they deliberate obfuscate what's happening in the business and the reason I think they do that is lack of confidence in their own execution.
There recent direct move into merchandising is low margin and high volume. Its a low quality use of their platform. They have struggled for years to adequately 'monetise' their platform services to customers. There will be a high risk of a sudden letdown with this stock...or a punchy raise on elevated price to invest in a better product or acquisition
I saw this and thought it might amuse a few people here:
"Often times when we see presentations from companies, they have little information in them. They might show information about number of users, total downloads, awards the company has won, etc. Many of these companies have raised tens of millions of dollars in financing, and should be able to speak to their traction in some way. To that end, we have created a hierarchy of information included in company decks:"
PLUS500- it has persistent if variable annual free cash flow and massive ROE. That is why it has been such a successful wealth creator over a long period for investors in the shares. I agree that all the other comments here re regulation or disclosure have been or might yet be negative factors. Also there is as yet no visibility as to what net cash flows the US move might produce - or the additional risk factors that might emerge there. Both could be very large.
Paul on Braemar (LON:BMS) you say 'The crux of the investment case, is whether it’s enjoying a cyclical or pandemic-related boom in profits, that is likely to subside?'
I think there is some post-pandemic benefit but I've suspected they are experiencing a benefit from from the awful war in Ukraine as well. In their HY results they referenced 'Revenue for Deep Sea Tankers in H1 FY22/23 is £17.0m, a 93% increase on H1 FY22/23. Sanctions and related volatility have been the main drivers in the Deep Sea Tanker markets, and these factors have led to changes in oil flows and increased ton miles considerably' and 'Clean Tanker markets, particularly in the Middle East and Far East, are seeing multi-year highs thanks to increased demand, and the growth in ton miles due to sanctions on Russia.'
UP Global Sourcing Holdings (LON:UPGS) is my 3rd largest holding (was 2nd yesterday!). Bought in 2018 after the big (post IPO?) fall at about 35p. I reinvest divis and have added steadily since, so only a 3-bagger. The original appeal was a company pandering to a recessionary, low income customer base, which seemed likely in a post B***it environment. That fall seemed overdone and I bought a few thousand.
If I bought some more it could become my 2nd largest holding again, or I could just wait. Decisions, decisions.
Hello, quick question for more knowledgable subscribers related to adding comments/replies on older posts - is there a notification system so that the original person/s who posted know there's a new comment?
Thanks,
Michael
The posts will appear near the top of the topic list when a new comment is added. I have never created a topic but have not been notified if someone replies to one of my comments so I suspect not.
In your profile under Personal settings, there is a field about notifications, however even though mine is ticked, I never get any. It maybe worth asking the Support team about this.
Thanks both for that, will also ask the support team.
I asked the support team about this. They came back saying that it is a dummy functionality, it doesn't work. No idea when they will get round to implementing it... seems like one of the biggest bits of work they can do, compared to all the "updates" they often come out with.
Dummy functionality eh? We had better jargon in my day. Pre-alpha, proof of concept feasibility demonstration. And in my day we kept this sort of stuff hidden away on test systems.
Bobbing and weaving between the lines at UP Global Sourcing Holdings (LON:UPGS) ...a company I like and believe has been and remains a structural growth story:
Flat revenue is headline meh. Shares had repriced a bit of late so they are puking a little on this it seems. At 10x p/e and 5% yield the market implies little structural growth is left. Was today confirmation? I guess there's a little disappointment that nothing effusive has been said about German sales.
Its been a torrid operating time with companies getting squeezed both sides. Suppliers and supply chain experiencing considerable cost pressures. Customers (supermarkets etc) feeling cost of living pressures from their customers and keen to chip away at costs to pass on savings to consumers but maintain their own margin. A bit of a sh1tshow scenario that will squeeze many businesses...
...although sales are meh, margins remain intact at UPGS. Its a balancing act but they will tend to pass up revenues to maintain margin. And they are holding margin in an environment where they are being squeezed both sides.
One of the key things supporting investment imo is they are not beholden to and part of retailer margins. Why? Every transaction is a new deal. They sell what is wanted and agreed at a price...not fulfilling a long term supply contract. UPGS don't like the price offered for the next order, they don't agree it. This can cause some short term volatility and at times will mean that UPGS have an order hiatus when retailers/consumers are retrenching as they are outside the internal or corporately close supply chain. We saw this in 2018. TBH I have been expecting this coming out of covid and into the pressures of the last year or so (inflation, supply, overstocking, etc). So far no negative hit. Maybe it comes....but I believe the whole covid and post covid episode is showing the strength of the franchise and its underlying growth drivers.
Since 2020 sales are up markedly. Near £20m of that is Salter acquisition. That increase has taken place in an environment where there has always been an impediment to fully unleashed sales growth. Europe/Germany was the strongest growth channel pre covid. Unlike in UK supermarkets/discounters were not given special opening privileges. So sales and growth plans suffered. Online was another growth avenue. In late 21 and thro 22 this channel suffered from the supply chain / freight probs and they had to suppress growth there to ensure they could supply the supermarket channel. Discount retailers in UK and Europe have been a historically significant growth channel. This was moderately a little relative to other channels pre covid. Then the European side was particularly hit during covid (big partners had to close). More recently UK discounters appear to be more exposed to consumer pressure of prior overstocking than other channels so a bit of a hiatus in demand for UPGS there. In addition, I conjecture that discounter channel at UPGS also more hit by shipping costs in 21/22 as this is the stack em high sell em cheap part of the business (eg small low cost bits and pieces of household equipment, often laundry and cleaning, that are less attractive to transact when they cost a lot more to put into a hipping container!).
Re german sales: h2 22 and h1 23 were probably the 'land' part of the exercise and h2 23 is the 'expand'. Its been a long time coming in some respects as they were around this stage pre covid. The strategy has been enhanced with the acquisition and development of a german brand, Petra. TBC they have grown over the piece but IMO the covid interruption has made for a rather extended 'land' period without a full phase change to 'expand'. I believe this is coming in next couple of years now and is hopefully a (very?!) significant growth factor.
So...a customer demand hiatus may be ahead of us or it may ameliorate. I don't know. I believe a significant element of hiatus is behind us but somewhat disguised by strong underling structural growth at UPGS. Its my wager that this structural growth is going to show through much more powerfully. I can't tell you its H2 23...but today the price of the stock isn't pricing this growth anyway so you are paid to take your chances and wait...
...that said, no doubt that if there is a cyclical retrenchment in retailer demand for UPGS revenues will take a hit for a period, like they did in 2018 (think was H1). It probably wont be as acute as then as the customer base is broader and they were very reliant on discounters back then (who had expended massively eg B&M European Value Retail SA (LON:BME) were major client) and there was element of the channel being stuffed due to so much new store stocking and them being very exposed to this discounter growth dynamic.
This is now old but is a simple analysis of underlying growth trends:
https://www.stockopedia.com/co...
Parsing the trading update: Strong online as they are now free to fulfil that channel fully given the pressure on supply chain is off. Means that rest of revenue is flat to down (depending on how much extra online sales). If recent past is extrapolated that means growth in Europe/Germany and supermarkets offset by discounters and other sales (like multi retail). I'd hazard a guess that supermarkets have been sticky for them digesting their overall stock positions and feeling a little unsure of ordering given economic headlines (and UK specific events around Mad Liz and KamaKwasi). Discounters may be a positive contributor as they were likely ahead (ie more sensitive) than supermarkets to general global and local factors. So looking into H2 23 will supermarkets regain footing...and is the 'land' moving to 'expand' well in Germany? Results will give more colour (they don't usually say too much in TU that is just couple of weeks into new reporting period)
Graham has been consistently negative on Plus500 (LON:PLUS) but it has absolutely trounced his preferred picks in the sector IG group (LON:IGG) and CMC Markets (LON:CMCX) and is a much better company than either in my view. Share price has risen roughly 20 fold since listing and that's not including the generous dividends - the total shareholder return must be spectacular.
Their advertising is a bit dubious, feels like they rely on new customers blowing their accounts up vs boring repeat business model from IG
Yes a fair point, they have to continually win new customers, which does seem to be getting more expensive recently. I actually sold a while ago after a strong run as feels they are coming out of one of their boom periods, and may find it hard to match recent earnings. Still very cheap though and their long term record is excellent, so probably should have kept a small position.
Plus500 (LON:PLUS) v CMC Markets (LON:CMCX) v IG group (LON:IGG) has been debated here a few times:
I haven't looked at this recently so can't say how much, if any, of the above still applies.
More generally, all spreadbetters are exposed to changes in regulation - it comes with the territory. I hold IG group (LON:IGG) and CMC Markets (LON:CMCX), so I'm with Graham on this, but it's undeniable that holders of Plus have been better rewarded for what, I at least perceive as, accepting greater risk in what is already a risky sector.
timarr
My biggest holding and agree!
Plus500 (LON:PLUS)
Hi Bouden
I'm negative on Plus500 too.
The underlying business actually decreased YOY (-9%), whereas the profits gained from customer trading losses increased significantly ($15.5m ---> $193m.)
I don't really understand how a business in this industry would be allowed to gain from their own customers' losses, especially when they can simultaneously stop those same customers from closing positions, as they have done in the past.
Also, they lied about this for years - Graham did a post several years ago, which included a direct response from the company stating that they do not benefit from their customer trading losses...which turned out to be a lie just a couple of months later when the company announced that they did actually make profits from customer trading losses.
Scandalous.
Unlike the other players in the industry listed in the UK I believe only IG group (LON:IGG) does not benefit when their customers lose.
abtan
"I don't really understand how a business in this industry would be allowed to gain from their own customers' losses, especially when they can simultaneously stop those same customers from closing positions, as they have done in the past."
Huh - thats how they earn their cut , their customers should know they are more likelyt o lose than not!!!
they are basically a bookie and make a margin on everything they do. They also take "risk in the market" by not hedging "everything" customers buy.
Its ultra simple
If they didnt make money from customers they would be out of business surely?
Also, they lied about this for years
Yep amazing how issues like that can be glossed over with the market quickly forgetting - i am not saying they outright lied (dont want to be sued) but the explanations as to why they had little risk then started to take big risks where very waffly. This one is stil on my baregpole list for that very reason - although caution has meant i have missed out on some great potential gains. Well done for those more brave than me.
I still always feel there is the danger of some unforseen (other than by me here now) regulatory clampdown that simply removed their ability to make the easy money they clearly do.
Ah, millaree, you and I know there are far worse actors out there than Plus500 (LON:PLUS) . I've held it throughout a long wilderness having paid too much in the first place but had spread my bet by holding IG group (LON:IGG) and CMC Markets (LON:CMCX) neither of which I feel so lucky with.
I don't really understand how a business in this industry would be allowed to gain from their own customers' losses, especially when they can simultaneously stop those same customers from closing positions, as they have done in the past
Definitely suffered from this in past with Plus500 (LON:PLUS) . Recognise as rmillaree said that they warn customers that 70%+ customers lose money on trades. However, preventing a positions from closing at a preset stop loss because they stopped trading in an instrument and then allowing it to restart at a level well beyond the stop loss is a bit underhand in my view. This means the customer loss is much greater than was originally intended when they set up a stop loss - even allowing for some tolerance around that due to market conditions. As a consequence of this I long ago recognised the Plus500 (LON:PLUS) is a share to hold and not a trading platform to use. Sadly I didn't hold the shares for long enough!
You're correct, the underlying income has actually fallen and that's one of the reasons I sold a couple of months ago - as I said it feels like they're coming out of one of their boom periods.
The other point about customer losses/hedging I feel is massively exaggerated - Plus have demonstrated that over time these will broadly even out and they are not exposing themselves to undue levels of risk - they may face a couple of hundred million loss in a particularly bad quarter, but they can easily cover this and make it up in subsequent quarters. What people fail to grasp is that fully hedging ever single position (the IG approach) is incredibly expensive and will eat into a large part of profits - so smoother earnings yes, but much lower earnings on aggregate.
(Disclaimer: I'm an IGG shareholder.)
Hi Bouden,
Thanks for the comment, however I do feel the need to correct you on the statement that I have been "consistently negative on Plus500".
While I do believe there are issues that investors should be aware of re: the PLUS business model, and I have been very critical of how the company has communicated its risk management processes to investors in the past, I have not been consistently negative on PLUS as an investment.
If you check the records, you will see that I have been price-sensitive and always sought clarity on what I perceived to be the outstanding issues at PLUS, when it comes to taking a positive or negative view on these shares. The last time I discussed PLUS in the SCVR was on 13/8/2019 (link), when I said:
While I had no interest in this at £20 and before we had clarity over customer P&L and the long-term impact of ESMA regulations, I am starting to find this interesting at the current much more reasonable valuation. But I would not bet the farm on it.
The share price at the time was 661p.
Best regards
Graham
Thanks for clarifying Graham and looking through your posts I can see you've become a bit more constructive on the company in last couple of years.
B.P. Marsh & Partners (LON:BPM) can be very illiquid, I tried to buy some a few weeks ago, the most I could buy at a time, was 10 shares.
Re UP Global Sourcing Holdings (LON:UPGS) - good summary Paul. I think UPGS are strongly managed and entrepeneurial. It's always the sign of a strong business when they manage a weaker half-year with modest revenue growth. Looks like they will be moving into H2 with more of a tailwind with reduced freight costs, normal purchasing patterns resuming (It looks like supermarkets overstocked in 2022 and you can see that they have been clearing UPGS old line stock stock at the end of the season in Sainsbury, for example, before introducing new lines), reduced inflation and European growth led by Petra. I suspect today's decline is due to nothing exciting being announced and only modest growth, but we have had a very strong few weeks on the share price. The important trend is long-term growth and there is plenty of that available at UPGS.
Facilities by ADF (LON:ADF) . In line trading update but upbeat on future order book.... 'In 2022, a record GBP6.7 billion was spent on HETV production in the UK, up 11.1% on 2021 and as such, the Group remains confident of further success' . Not sure what HETV stands for but it sounds good.....
Colin1862
In respect of your comments on FacilitiesbyADF (LON:ADF), HETV stands for High End Television. Basically, it means television programmes with movie-scale production values.
Kind regards
Phillip
Thank you for info! On reflection I suppose the 11.1% increase is due to inflation
Be careful - the cyclical downturn in content production might be coming soon to the UK. In the USA, the FT had an article within the last week reporting that Hollywood production activity was down substantially in Q4, as streaming services and content providers commissioned less new work.
Facilities by ADF (LON:ADF) work is obviously tied to amount of film and TV production done.
Facilities by ADF (LON:ADF) - Be careful - the cyclical downturn in content production might be coming soon to the UK
This. I've heard that there's a big cull on new programming as streamers trim their losses. The whole sector is at war with each other and the numbers don't add up.
Hi
Not a UK SCVR in any shape or form, my apologies, but might interest some US/Tech investors
For any Palantir Technologies (NYQ:PLTR) followers, stock price up over +16% in after hours after making GAAP profitability for the first time in their history (a big deal for US markets).
A stock not for the fainthearted but for the deep DYO people, worth digging into deeply IMO.
I hold.
Also Palantir Technologies (NYQ:PLTR) is integrating AL/ML capabilities developed over past 20 years, so not Mickey Mouse stuff at all.
Of particular note, they have placed to the fore data protection and integrity.
A webcast is on their website.
Regards
Howard
Thank you Paul re Braemar. Many analysts think China reopening will boost trade more than expected, the bulk of which is carried on ships so we'll stay with the shares. This is of course if popping their balloons doesn't lead to serious friction.
Paul, with regards to your last two podcasts, I am unable to download, they play ok, but not able to download to listen to at leisure.
Earlier ones still download, since you had a minor hiccup a couple of weeks ago, is there a button that is missing a tick?
In case it helps with the troubleshooting, I confirm the Apple Podcasts app is downloading them successfully for me.
Hi GloucesterBob,
I think there might still be an issue with the SSL certificate on my website, which might be preventing downloads. I publish them both on my own website, and also on Acast (which distributes them to Apple, Spotify, and others). Try this link for Acast - https://open.acast.com/public/...
Most people seem to listen via Apple podcasts, and they download automatically. The link for that is here: https://podcasts.apple.com/gb/...
Regards, Paul.
Good to read Braemar has no intention of suing shareholders for dividends received previously. If you get chance Paul a quick word on how you view today's TU and capital reduction would be appreciated. We hold.
UP Global Sourcing Holdings (LON:UPGS) "Online drives first half growth" - new research note and audio summary here: https://www.equitydevelopment.co.uk/research/online-drives-first-half-growth
Online channels were the main driver of growth for UPGS in the first half of FY2023 with a 2% sales revenue gain - areas of product strength included energy efficient and money saving items, which were cited as being buoyant across all distribution channels. At the same time key indicators of financial strength also improved. The trading backdrop also showed signs of improvement in the first half. Commenting on outlook, the company anticipates that the market’s current expectations for FY2023 will be met. UPGS continues to highlight the positive impact that the company’s automation programme is having on the business.
Despite recent share price strength, we still believe that the current valuation fails to fairly reflect UPGS’s three salient growth drivers - brands, online & supermarkets distribution and international. With external headwinds easing, a second half acceleration is in prospect, plus a robust financial position, the near-term outlook appears positive. We reiterate our 250p fair value per share (based on an FY2023 EV/sales ratio of 1.5x and 12x EV/EBITDA).
My morning smallcap tweet: Altitude on a high
£AMG Braemar (LON:BMS) Palace Capital (LON:PCA) Kanabo (LON:KNB) Altitude (LON:ALT), Facilities by ADF (LON:ADF), UP Global Sourcing Holdings (LON:UPGS)
◄Amigo (AMG)► censured by FCA for failing to conduct adequate affordability checks on borrowers and guarantors. Fine would have been £73m, however Amigo demonstrated that this would cause it serious financial hardship and threaten compensation scheme. [SP=NA Cap=NA]
◄Braemar (BMS)► has continued to trade well. In line? Plans capital reduction to increase distributable reserves. Had paid some divs illegally. Will anyone walk the plank?
[SP=316 Cap=104m]
◄Palace Capital (PCA)► sells industrial property in Plymouth for £3.2m, marginally ahead of book. Sees "encouraging signs of stabilisation in asset pricing in the commercial real estate market". [SP=200 Cap=88m]
◄Kanabo (KNB)► biz update. Plans to launch additional formulations with low-THC compounds over the coming month. Has doubled number of consultations pcm since the acquisition of the GP service. [SP=3.47 Cap=15m]
◄Altitude (ALT)► guides FY-Mar materially ahead of market expectations. Expects rev and EBITDA growth throughout remainder of calendar 2023 and 2024. [SP=33.1 Cap=23m]
In line: ADF, UPGS