Small Cap Value Report (Tue 14 May 2024) - SAGA, HEAD, LUCE, CURY, SND, ZYT, IQG, OTB

Good morning from Paul & Graham!
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. OR it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom),
Frozen SCVR summary spreadsheet for calendar 2023.
New SCVR summary spreadsheet from July 2023 onwards.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
List of companies reporting today
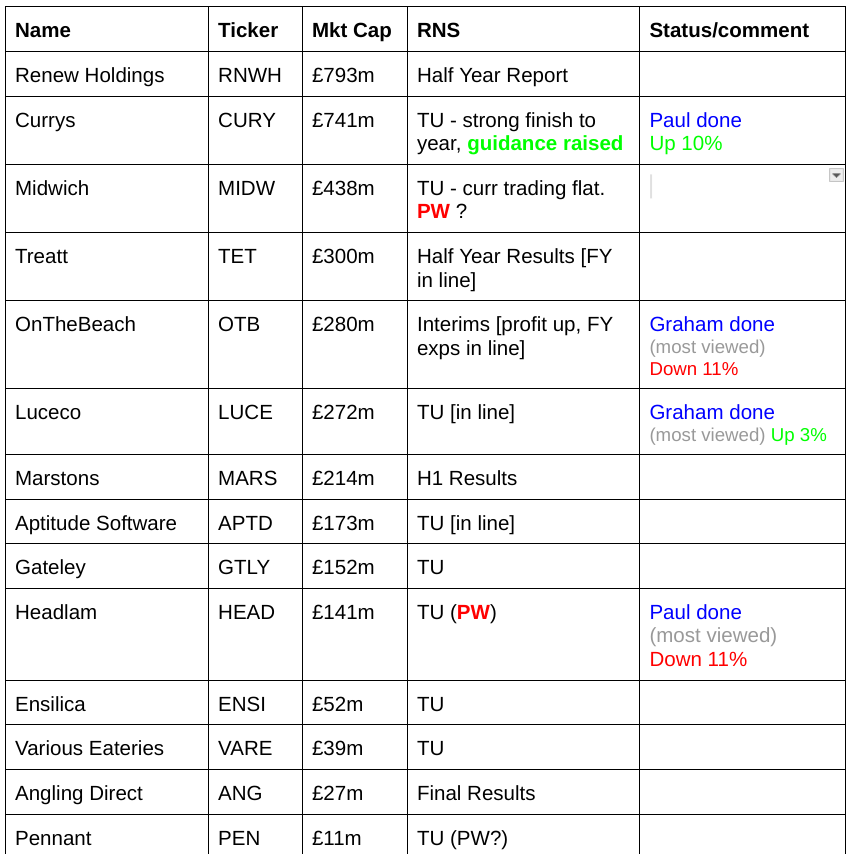
Other mid-morning movers (with news)
BREAKING NEWS! Another takeover bid -
IQGeo (LON:IQG) - up 16% to 470p (£290m) - Recommended Cash Acquisition - Paul - PINK
OK, this is getting ridiculous now. Another takeover bid from America.
Buyer: KKR (according to Wikipedia, it has a total of c.$1 trillion in assets under mgt)
Price: 480p/share in cash.
Premium: only 19% to last night’s close (albeit after a strong run in share price, doubling since autumn 2023)
Recommended by IQG’s board.
Shareholder support: it looks in the bag, with 58% support already. Kestrel is the biggest shareholder. This looks like another situation where institutions want out, with a liquidity event.
Paul’s view - pity it’s going, as IQG was growing on me (see SCVRs 20/10/2023 and 15/1/2024 [AMBER/GREEN]) as an interesting, albeit expensive growth company.
Sondrel (Holdings) (LON:SND) - up 47% to 6.75p (£6m) - Conditional Subscription to Raise £5.6m - Paul - RED
Accident-prone, almost bust chip designer confirms that it’s getting the vital bail-out from ROX Equity Partners, with a big equity raise at 10p. However, the main problem is that, as previously announced, the restructuring associated with this deal involves de-listing its shares from AIM and becoming a private company, as the costs & administrative burdens of the AIM listing are not of any value. A cynic might say it’s served its purpose, of fleecing fund managers in the original over-priced float.
Why would anyone be buying the shares today then, knowing that it’s shortly going to de-list? The only reasons I can think of are that some investors might be prepared to hold shares in a private company. Or they might be gambling on ROX possibly offering to take out private shareholders at the same 10p that it’s putting in fresh funding at? Who knows, but personally I avoid anything that’s likely to de-list.
Zytronic (LON:ZYT) - down 16% to 53p (£5m) - H1 Results - Paul - AMBER/RED
Zytronic used to be a successful, profitable & cash rich maker of bespoke touch screens, for things like ATMs, and casino machines. Unfortunately, it seems to be just withering away, unable to replace end-of-life products with new orders. H1 revenue announced today is down to just £3.3m. The LBT of £(0.6)m isn’t too bad, and there’s £3.7m cash remaining. It’s planning a full business review over the summer, which I imagine should probably include ditching the stock market listing, which should save several hundred £k pa in unnecessary costs that can't be justified for a tiny, struggling company.
Some cautious optimism about new order pipeline, and it does have enough cash to tread water for a while. You need to balance up that tenuous recovery potential against the obvious de-listing risk. I would be amber if I could be sure it would remain listed, since it still has a healthy balance sheet (although inventories now too high). But on balance the de-listing risk carries the day for me, so I have to flag that risk with AMBER/RED. Upside case would be a flood of new orders, taking it back into profit. That’s not looking too credible right now, but you never know!
Summaries of main sections
Saga (LON:SAGA) - 118p (£169m) - Repayment of Bond - Paul - AMBER
£150m bond repaid yesterday. Could it be a recovery situation? Possibly, I'm not sure.
Headlam (LON:HEAD) - down 9% to 160p (£130m) - Trading Update [profit warning] - Paul - BLACK (PW), AMBER on fundamentals
Trading in 2024 to date has been poor, and it serves up a nasty profit warning today. I was expecting trading to be flat, not another big lurch down. No broker updates are available to us. I'm expecting FY 12/2024 to now be loss-making, and with net debt having risen, don't expect any divis for a while. Big freehold property assets save the day though, so with further management action underway, I don't see any solvency risk. That's the only saving grace that allows me to stay at AMBER.
Luceco (LON:LUCE) - up 1% to 171.3p (£275m) - Q1 2024 Trading Update - Graham - GREEN
A confident update from this company. Despite making an acquisition in February, the balance sheet remains strong with leverage multiples below target, so that more M&A is likely in the near-term. As it enjoys very strong bullish momentum currently, I’m happy to leave our positive stance unchanged.
Currys (LON:CURY) - up 10% to 71.75p (£810m) - Trading Update - Paul - AMBER
Giant electrical retailer ended FY 4/2024 with a flourish, so it seems to be managing investor expectations well, reporting that PBT is a bit ahead of expectations. Net cash position healthy after Greek disposal. I run through the bull & bear points, and end up sitting on the fence again.
On Beach group (LON:OTB) - down 10% to 150.9p (£252m) - Interim Results - Graham - GREEN
No change to the outlook although the company does suffer an EBITDA downgrade at Peel Hunt. Existing forecasts did look very challenging to me, as “value” holidays are under some pressure and OTB’s H1 profit figures leave a lot to do in H2. But the stock is cheap and I do think it’s well placed for the long-term.
Saga (LON:SAGA)
118p (£169m) - Repayment of Bond - Paul - AMBER
News yesterday, reported that (as expected) SAGA has repaid the full outstanding £150m on its 2024 senior secured bond. This was cheap borrowing, at 3.375%. There's another bond outstanding, £250m for 2026.
This next bit is rather vague, as it doesn’t say how much has been drawn down, nor how much gross cash remains -
“This bond redemption was funded from Available Cash resources, including a draw down on the £85.0m facility with Roger De Haan maturing in April 2026.”
Paul’s opinion - we’ve had a range of opinions here about SAGA’s debt, which is healthy. My view has always been that, whilst debt is higher than I’d like, most of it is financing the two cruise ships, which are large assets. This should be seen separately as asset financing.
Neville was asking yesterday (in the reader comments) if I see SAGA as the type of share that could re-rate in a bull market, as investors accept a bit more risk. I think that’s entirely possible. The debt has never been as bad as bears made out, because they simply ignored the c.£500m cruise ship assets, which is ridiculous. For example, a sale and leaseback could be done, which would instantly eliminate most of SAGA’s debt (although it would reappear as IFRS 16 entries).
The business is now back in (modest) profit. Although I have been very disappointed with how slow the recovery in its travel division has been, and recurring problems from the insurance division. With the financial clout of its founder family, Chairman Sir Roger de Haan helping to both refinance the equity a few years ago, and replacing bank debt with a loan facility more recently, it seems to me that equity is now reasonably safe. As mentioned in my most recent podcast, as we enter a new bull market, then I think there's money to be made from taking a slightly more tolerant attitude towards debt. I've observed in the past that it can be shares perceived as higher risk that put in the most explosive upward moves in the early part of a bull market, and I think there's already evidence of that happening with some shares.
Overall, this could be worth a punt I reckon, but as I’m not high conviction on this, given the constant disappointments in recent years, am struggling to get above AMBER. However, I'm probably leaning more towards amber/green. Things have undoubtedly improved in the last 3 years, yet the share price remains bombed out. Maybe this could be an opportunity for a profitable trade?
Headlam (LON:HEAD)
Down 9% to 160p (£130m) - Trading Update [profit warning] - Paul - BLACK, AMBER on fundamentals
Headlam (LSE: HEAD), the UK's leading floorcoverings distributor, announces the following update in respect of trading in the 4 months to the end of April (the 'Period) and also announcing the acceleration of the Group's strategy.
Bad luck to holders here, although not entirely unexpected given previous weak trading, and a soft share price. HEAD is one of only 2 laggards on my 2024 Top 20 value/GARP share ideas so it looks like today’s update is probably going to slightly pull down my otherwise rip-roaring average! (Paul up 22% YTD, Graham up 24% YTD) - although people from Twitter say that increasing numbers of investors/traders are catching up with us ;-)
Revenues considerably down, not good in an environment where costs (especially wages) are rising -
Revenue in the Period was down 12.3% year on year, with the UK down 11.6% and Continental Europe down 16.9%1. Revenue in April did not show the expected seasonal uplift usually seen in the Spring period…
Losses incurred for this period (Jan-Apr 2024) look a bit scary, but are not put in context by giving the prior year comparative -
Despite tight cost management and other mitigating actions, the lower revenue has impacted our profitability with a pre-tax loss for the Period of £10.6 million…
Net debt update -
Cash and working capital remain well controlled. At the end of April, net debt was £43 million and the Group had nearly £60 million of cash and undrawn facilities available. This strong liquidity position is expected to be further boosted in the coming weeks with the cash receipts from the disposal of a surplus property in Stockport for around £7.5 million, which is significantly above book value. Following this disposal, the Group will own property valued at £142.1 million.
For comparison, net debt was £29.6m when last reported at Dec 2023, so the rise to £43m is concerning.
Whilst there’s plenty of headroom, the move into losses might put pressure on bank covenants possibly?
Although banks tend to be much more relaxed when they have the security over substantial freehold property assets, as in this case.
Outlook - no recovery imminent, and it’s taking sensible actions to cope -
… a further delay until 2025 for a recovery in the floor coverings market. Accordingly, the Group is accelerating its strategy which will see further integration and simplification across the business.
We expect these initiatives to deliver a material reduction in operating costs along with significant one-off cash benefits from disposal of surplus property and working capital reduction over the next 18 months. The Group will provide a further update on our plans in July.
Overall though, it’s a nasty profit warning -
We expect to report a significant pre-tax loss in the first half based on a double digit decline in revenue. In the second half we expect an improvement based on our mitigating actions, as well as gradually improving market conditions, albeit we do not anticipate the market returning to growth until 2025. For the full year we expect profit to be significantly below current market expectations.
Seasonality - difficult to ascertain due to the lockdowns bust & then DIY boom, but in 2019 there was a small H2 weighting to profits. So that makes the significant pre-tax loss in H1 this year even more worrying, as it’s not in a typically soft seasonal half.
Broker updates - there’s nothing, infuriatingly. So once again preferred customers of the big brokers get the inside information before us plebs. It’s clearly going to be grim though - I can’t see how HEAD is going to generate a profit at all in FY 12/2024, so the £5.8m PAT shown on the StockReport is now out of the window.
Paul’s opinion - I was expecting continuing soft trading in 2024 for HEAD, with a likely recovery beginning in 2025, as that’s what lots of companies in building/renovation type activities have been telling us. However, I definitely was not expecting another serious lurch down in trading, as has been revealed today.
Clearly this worsens risk:reward quite a lot.
However, the freehold property on the balance sheet saves the day, and disposal mentioned above set to raise £7.5m is a useful boost. We need more information from the company about what other cash it could raise from selling other properties - it could become a case of having to sell property, rather than wanting to.
We can’t value this share on a PER basis, as it’s probably now loss-making. Also forget divis for the time being I’d suggest.
Are these problems temporary? I’m no longer convinced they are. We know there’s increased competition from Likewise (LON:LIKE) who look to be taking market share. We need industry data to compare HEAD’s declining revenues with the sector as a whole, to determine if it’s really just a tough market, or whether HEAD is also suffering from competitive strains.
Both Graham and I have colour-coded HEAD as AMBER the last 3 times we looked at it (11/3/2024, 18/1/2024, and 12/23/2023), but trading has significantly deteriorated since then. Also yes it has lots of freehold property, but net debt is rising to uncomfortable levels (although still a lot less than freeholds are valued at, so probably won’t be an issue).
If there was no freehold property, I would definitely be ringing alarm bells with amber/red, but the fact remains that the freeholds are a very substantial asset at £142m, which continues to protect from downside risk.
I’ve just looked at the share price, and am amazed it’s only down 9% to 160p. A profit warning of this severity would normally cause a 30%+ fall, so clearly (so far anyway) investors are not particularly spooked by this PW. That could change though, it only takes one big holder to start selling in the market, and the price could drift down further.
Some of you will probably attack me for this, but I still think AMBER looks just about OK, given the recovery potential, and the very strong net asset backing (main freehold property). Although I don’t think I’ll be buying any personally for a recovery, as there seem much better elsewhere for cyclical recovery shares now.
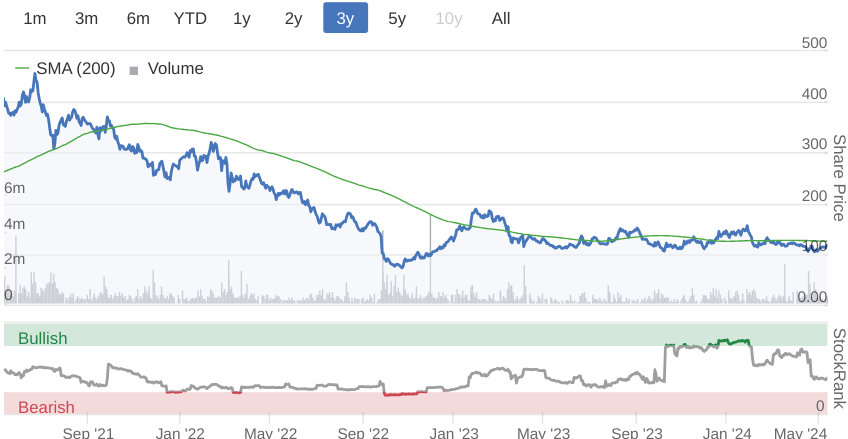
The 5-year chart seems to be saying this is more than just a cyclical movement -
Currys (LON:CURY)
Up 10% to 71.75p (£810m) - Trading Update - Paul - AMBER
Currys plc, a leading omnichannel retailer of technology products and services, today issues the following trading update for the year ending 27 April 2024.
A useful upgrade to FY 4/2024 profit guidance - but remember the profit margin is tiny, on c.£9bn revenues -
Full year adjusted PBT (excluding Greece) expected to be £115-120m (previously guided to at least £105m)
Greece is excluded as it was recently disposed of, for decent cash proceeds that has nicely improved the cash position -
Year-end net cash position expected to be around £95m
Although as I always remind you here, the business is financed by its suppliers - see the huge trade creditors line on the balance sheet - if you can find the results statements that is, as they’re buried in all the 8.3 and 8.5 rule announcements that clutter up the RNS list, due to abortive takeover talks earlier this year. Can’t someone put a button on the RNS feed that says hide all these announcements? They’re a damned nuisance, and irrelevant clutter once a bid situation has ended.
Paul’s opinion - I can see some merit, but also some less attractive things, so let’s do a bull vs bear -
Bull points -
Several positive trading updates recently
Cyclical consumer recovery likely to benefit CURY now customer wages are rising faster than inflation, so operationally geared upside to profit is possible.
Bank debt sorted out from Greek disposal
CURY has performed fairly well, despite the consumer downturn, indicating it’s a better business than I thought.
CEO pointed out its size means it’s first in the queue with suppliers, especially when supply chain problems emerge.
Bear points -
Wafer thin PBT margin of barely more than 1%.
No pricing power, as selling other peoples’ products in a fiercely competitive market.
Huge cash contributions scheduled into pension scheme - could there be an opportunity here, if the actuarial deficit suddenly disappears?
Another big hike in wages costs from April 2024 is bound to blunt profits somewhat.
Overall then, it’s good to see the share price recovering, and I think that’s justified. However, for me I don’t see anything particularly interesting here, so am happy to sit on the sidelines with a neutral view. AMBER again.
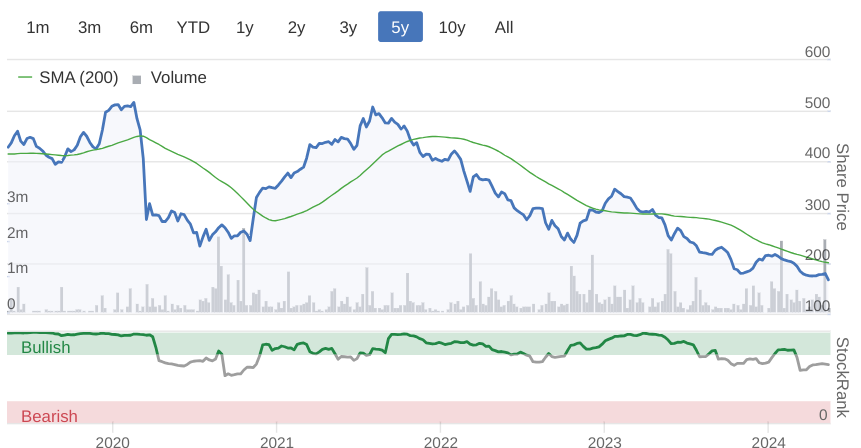
There hasn't been any share issuance over the 5-year period below, so theoretically if the market gets more bullish again, there's no reason why the share price couldn't continue rising - could be a good momentum trade perhaps, now that the negatives & risks are receding? I'm almost amber/green!
Graham’s Section:
Luceco (LON:LUCE)
Up 1% to 171.3p (£275m) - Q1 2024 Trading Update - Graham - GREEN
Full year expectations here are unchanged:
Luceco plc ("Luceco" or "the Group"), the supplier of wiring accessories, EV chargers, LED lighting, and portable power products, is pleased to provide the following update for the three months ended 31 March 2024 ("Q1 2024" or the "quarter").
Key bullet points:
Q1 revenue £51m, +6.2% year-on-year, +4.5% like-for-like.
Adj. operating profit +30% year-on-year, “benefitting from the end of de-stocking pressures which ended in H1 2023”.
“Adj. operating margin improvement year on year, driven by strong operational leverage.”
So many companies spoke in unison about destocking last year, as their customers held too much stock in the aftermath of supply chain worries. But now, most of them seem to be saying that their customers have normalised their inventories, i.e. that the destocking problem is over and that normal orders have resumed.
Other points from today’s update:
Net debt/EBITDA multiple remains at 0.8x, below target range 1-2x.
Checking the most recent full-year results, I see that net debt was £18.4m (Dec 2023), for a leverage multiple of 0.6x.
Since then, the company has made an acquisition for £8.6m (plus defcon), so I imagine that net debt has modestly increased.
However, with the leverage multiple still below 1x, Luceco has “optionality for further M&A consistent with the Group’s stated capital allocation policy”.
Final dividend 3.2p, total dividend for the year 4.8p.
Outlook: performing “comfortably in line with market expectations”.
Key industry metrics, though still in decline, are beginning to trend in our favour, providing some optimism for the second half of the year.
We are pleased with the strength of our order books, which should yield H1 like-for-like organic growth of c. 5%
CEO comment:
"Luceco has performed strongly in the first quarter of the year and we are trading comfortably in line with expectations. Key industry metrics are starting to suggest more favourable conditions, and this provides optimism for the second half of the year. The Group is continuing to identify new organic and M&A opportunities for investment, leveraging our market position and aided by our strong cash flow and balance sheet."
Graham’s view
Paul has been GREEN on this in recent reports. Stockopedia’s calculations also suggest that I might want to take a very positive stance on this one:
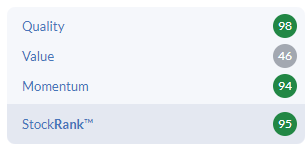
As you might be able to tell from the MomentumRank above, this stock is enjoying a wonderful bull trend:
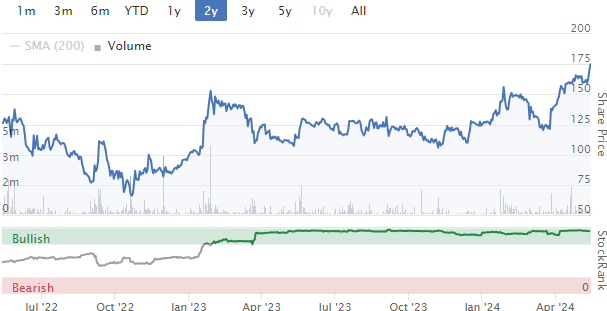
It passes eight bullish stock screens, many of which are to do with momentum, but also the Ben Graham Deep Value Checklist.
So what is the catch?
Well, for a start, valuation has been creeping up:
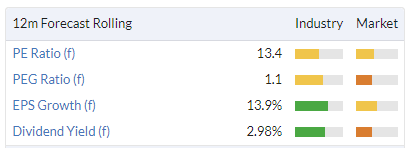
For a cyclical business that is currently enjoying 5% like-for-like revenue growth, this doesn’t appear to offer great value at first glance.
However, I think the argument that wins the day for bulls is the operational leverage at work here: modest revenue growth is translating to very strong growth in adj. operating profit. If this continues for another couple of years, the valuation multiple here should get back to attractive levels (if the share price doesn’t go up!).
Quality metrics are already very good, and should improve further:
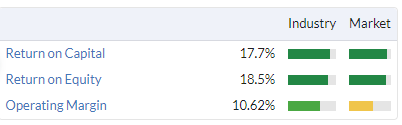
Overall, therefore, I’m happy to maintain Paul’s GREEN stance on this one. However, I should add that lighting (responsible for 38% of Luceco’s revenues) is an industry that makes me very nervous, and personally I’d be quick to jump back to AMBER or AMBER/GREEN at the first sign of trouble!
On Beach group (LON:OTB)
Down 10% to 150.9p (£252m) - Interim Results - Graham - GREEN
There’s a lot to take in here:
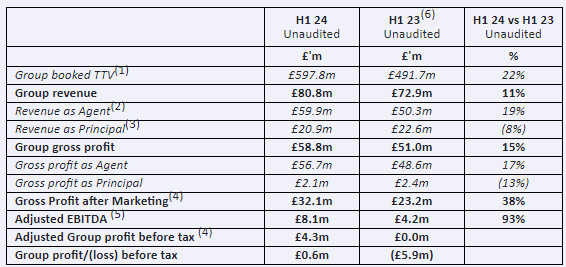
The overall picture is one of improvement.
The recovery from the Covid era is taking some time:
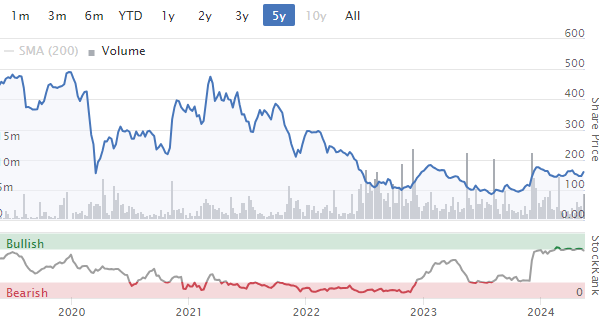
Way back in 2019, OTB generated significant profits in both H1 and H2, despite much lower revenues.
And given the modest profits earned in H1 this year, the company will seemingly have its work cut out to hit targets: the (adjusted) net income forecast for FY Sep 2024 is £24m, according to Stockopedia.
Liberum forecasts published last month suggested full-year revenues £202.6m, adj. EBITDA £44.9m, and PBT of £35.3m. Even allowing for seasonality, these forecasts look very challenging to me.
Indeed, it appears that Peel Hunt have today lowered their adj. EBITDA forecast from £44.1m to £40.5m.
Let’s carry on with the company’s explanation of how it traded in H1:
…increased passenger bookings during the period (+15%) as well as an increase in the average value of holidays sold…
Proforma continuing EBITDA following B2B changes of £10.1m (H1 23: £6.5m).
Interim dividend is 0.9p, the first dividend since 2019.
As mentioned by Paul in February, OTB has a new partnership with Ryanair, “which ensures we have secure access to this increase in [airline] capacity”. The two companies have “moved on” from their conflict over refunds, and customers can now book package holidays using Ryanair “with complete confidence”.
Importantly, there is a divergence between “premium” and “value” holidays; premium holidays are performing “strongly” but “the value market remains challenging, reflecting ongoing cost of living pressures” (growth in this segment is running at just 1%).
And reading through the CEO’s commentary, the premium segment is where OTB is now looking to place more emphasis, seeing as profit margins are bigger there and premium customers book earlier, providing greater visibility.
Long haul is another area of focus, where OTB’s market share is currently small (“low single digit”) but where it sees the potential for more.
Current trading/outlook: “in line with current consensus expectations”, but remember that Peel Hunt have downgraded them anyway.
Trading momentum has continued since the half year date.
Summer '24 forward order TTV currently 22% ahead of last year.
As a result of these factors, and our new Ryanair partnership, we expect to deliver another record Summer.
Borrowings: the company has borrowed £55m across two facilities (from Lloyds and NatWest). The max that can be borrowed is £85m.
The balance sheet is seasonal in nature with customer cash paid up front, money paid to hotels in advance of customers arriving, etc. Thankfully the balance sheet does have a positive net tangible worth (about £100m) and as the holiday season gets into gear, the large working capital balances should unwind as usual.
Graham’s view
Again I’m happy to maintain our GREEN stance on this one.
Travel companies aren’t having it all their own way at the moment, with value customers squeezed by cost of living pressures and a perpetual risk of oversupply. This is reflected in OTB’s weak profit numbers posted today and in the EBITDA downgrade.
But OTB is well-positioned as a middleman (though technically it does provide many holidays as “principal”, rather than as an “agent”). And it’s priced keenly to my eyes:
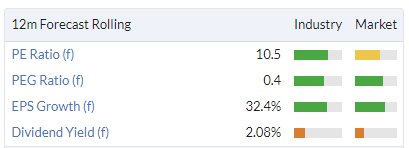
With underlying momentum in the business, and with the overall economic outlook being OK, I’m happy to stay positive on this, looking forward to continued growth and expansion across a range of holiday segments.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

86 comments
Re Headlam (LON:HEAD) vs Likewise (LON:LIKE) - the issue turns on market share and long term profitability
My understanding of the overall structure of flooring market is that Headlam is the clear market leader with 4-5 large competitors, of whom Likewise (LON:LIKE) is now one, with many smaller players. Almost none of them have genuine pricing power based on brands, it is mostly based on price and relationships. Brewster built up Headlam by buying lots of the smaller businesses and retaining their local name/custom and investing in relationships through "inefficient" sales calls. This worked up to a point but left a bit of a mess - loads of tiny companies, inefficient distribution etc. That's why he went and a CFO got the CEO gig.
The current CFO turned CEO has tried to fix a logical, more efficient structure (re-organised delivery network, greater prominence to Headlam brand, diversification into trade counters, building business with national customers). This is all good textbook stuff and seems to be working in a tough market.
However, he also reformed the sales team to get sales team time per smaller customer to more accurately reflect turnover /potential. This again is logical but has a consequence, smaller low margin business gets lost (quickly) when Sales stop coming round for coffee and the longer term benefits with bigger customers - who everyone wants take longer to deliver - esp in a falling volume market, as now. Sales teams are instructed to get smaller customers to buy through larger medium sized customers or drop them. On paper this makes sense for everyone (more efficient) but sales is a surprisingly emotional business, esp at the smaller end.
Long term, I think Headlam (LON:HEAD) is doing the right things and will be rewarded eventually. Likewise (LON:LIKE) is not looking very profitable now and further acquisitions will be tougher to finance. Yes sales growth will deliver operational leverage on an underused national(ish) network (so worth further increasing cost base to add more sales people). Long term, it is all less efficient due to ultimate buying scale than £HEAD.
In the medium run, Likewise (LON:LIKE) has established itself as another Div 2 player. Its CEO has got another 5-7 years as a well paid CEO under his belt ahead of retirement.....but Headlam (LON:HEAD) remains the clear market leader making the most money but has had its margin squeezed for a period. Likewise (LON:LIKE) has not added anything new to the market, just bought some sales by price and excessive headcount.
However, the cost cutting (solar panels), innovation (Appand improved customer service (like that CAPEX for new sortation tables this year) that this has forced on £Head will set Headlam (LON:HEAD) up for the next market boom.
Shareholders might call for some short term blood sacrifice. (If I was CEO, I might be unfairly looking at some pre-emptive blood-letting in my organization, starting with the head of field sales lest shareholder gaze turn my way.)
But I will be looking at buying (more of) the market leader at these prices and waiting for 2025! Man U and Liverpool may have a couple of bad seasons but always come back, Leicester might create a miracle but get related a few seasons later. Life is unfair.
If I had access to a couple of hundred millions like PE, I might look to buy the company, drive through to create a national Headlam brand and more 'capital efficient' structure and sell it back to gullible retail investors in about 2029 - exactly 100 years on from the Great Stockmarket crash.
Man U may have a couple of bad seasons but always come back
hmmmmm - its 11 years since manchester united last won the league and this year in last week of season they are 8th in the league probably their worst placing in like forever. They may come back out on top but it may not be in our lifetime !! (thankfully). heck liverpool have only won the league once in 34 years. Plenty of semi zombie companies past their best - football isnt that disimilar.
I have a friend who is still waiting for Leeds United to get back into the Champions League...! So agreed that once-great entities don't always bounce back, like Zipmanpeter is assuming...
Dowlais (LON:DWL) As an automotive parts supplier it is unlikely to achieve a high rating, but a PE of 7 or 8 should be achievable, which would mean a doubling the current share price if achieved.
Look at the gulf between EBITDA and real profit. That’s a massive red flag for me in an industrial stock and goes a long way to explaining the multiple.
Dowlais (LON:DWL)
Just listened to the webinar presentation on the recent prelims available on the company website. Generally impressed with the CEO, Liam Butterworth and CFO, Roberto Fioroni replies to analysts question.
On the issue of director buying, while much of this may be as a result of corporate remuneration requirements, it is on balance a positive imposition by the company. As an automotive parts supplier it is unlikely to achieve a high rating, but a PE of 7 or 8 should be achievable, which would mean a doubling the current share price if achieved.
Dowlais (LON:DWL)
This looks screamingly cheap for a global leader in its sector, I hold a few at around 80 p and am tempted to back up the truck. Debt appears the main drawback, but is there an invisible elephant in the room?
For those wiser than me and there are many your views good and bad would be very welcome.
Debt levels and the pension deficit are the main bear points. Operationally margins are improving, with costs being progressively reduced.
There has been consistent director buying but another subscribers pointed out some of this is towards satisfying targets for ownership.
I hold, having bought in recently in the 70s.
I think Dowlais is caught in the move from ICE to electric and the inevitable delays / policy changes etc that not only impact the componentry suppliers but the manufacturers themselves, hence the price weakness It does seem cheap, but then so do manufacturers like VW (especially given their shareholding in Porsche). The human need to buy new shiny automobiles will I assume continue (albeit tempered by prevailing economic conditions) and if Dowlais supplies components for both ICE and electric (as I believe they do) they should do well in the long term...
The only automobile manufacturer I'd never touch is Tesla, but that's a whole different story!
I believe it's a fallacy to buy a share (or not sell) based on the belief of their property asset backing. In the case of Headlam (LON:HEAD), where the mkt cap ended up today being the value of the property, you'd want to know a) is the property salable - does someone want it?, b) easy to sell quickly c) valuations in line with mkt value.
So without doing a deep dive into their property estate, you wouldn't know. Major US cities are littered with examples of tall office buildings that no-one wants and sell way below book, shopping malls etc - yes this is different but the principle stands. So it should be red.
Also Headlam (LON:HEAD) were busy buying back shares at a price double the current price, and the ex-CEO (who was well-regarded) ended up setting up a direct competitor...
Hi Cisk, and nice to hear from you :-)
All good points, thanks.
However, in the case of HEAD, I think my original point does stack up, that the freeholds are worth over 3x the net bank debt. Hence the bank manager won't be in meltdown, he'll be relaxed because he has zero risk. It's not a highly leveraged tower block, it's warehouses, with a low LTV, and a cash generative business operating from them (note the hefty depreciation charge).
HEAD should definitely NOT be RED!
However, as you probably gleaned from my original post, I was amazed the share price didn't drop a lot more, so personally I wouldn't be interested in buying today at 159p. This could drift lower, and I'm far from keen on the immediate outlook. However, the freehold backing is remarkably strong vs the market cap, so your comments are overly dramatic I think. Particularly as it said that almost 20% of the net debt would be extinguished from a surplus property sale imminently, and more working capital reductions (inventories).
Not comparable at all to a bankrupt tower block in New York!
Best wishes, Paul ;-)
P.S. It's a hugely important thing when a company gets into trading difficulties, if it has big freehold property, risk:reward is massively improved. "Fallacy" is totally the wrong idea. Loads of freehold assets for a trading business like HEAD (not an over-geared property co) means it can sail through a difficult trading patch, as the bank will be relaxed due to holding security. There's little risk of the bank demanding a dilutive equity raise. Property buys time to sort things out. So, sorry CISK, you're completely wrong! (but I still think HEAD is only AMBER at this stage - so we're on the fence remember, not saying it's positive, which it isn't. There are lots of problems, but the property is a HUGE supportive factor you're completely wrong to dismiss it).
Hello Paul!
Of course towers in cities are completely different, my point is that just assuming that an entry on a balance sheet says that a company is stuffed full of asset backing is a reason to buy a stock that's losing money is nuts. Sometimes it works out, sometimes doesn't. If it's temporarily losing money, then certainly you'd want to take a second look.
Headlam (LON:HEAD) may be forced into selling the family silver to support ongoing losses, and there's a finite period that could go on for. Distressed seller or not, who knows if the balance sheet values are realizable. But it takes one look at the macro environment across the globe to reaffirm buying good companies at fair prices will hopefully make money, but buying companies in structural decline won't! I agree that Headlam (LON:HEAD) probably have further to fall, but will their core business make money / recover in the future?
I've held Headlam (LON:HEAD) for a long time, done well at certain points and received good divis, but sold out a while back because I felt there were just better opportunities out there to buy bombed-out companies suffering at this point in the economic cycle. And that fact that Tony Brewer (ex CEO) left and set up a direct competitor (he knows the market, no idea if his replacement does) is more concerning than just regular board churn. Plus there's a nagging doubt at the back of my mind over whether the flooring market is changing and moving away from the distributor model.
If a red flag means that the company is in dire financial stress and about to go pop, then I absolutely agree, it's not at this point in time.
If red flag = investor beware = you could lose your shirt, then I'd say it's more likely (just my opinion of course).
Hi Cisk!
All good points, I agree with some of that.
AMBER looks right to me. Why? Because freehold property at 3x net debt is comfortable.
Although it's on the watch list, and there are lots of problems which we covered in the main article, re deteriorating trading.
The modest share price reaction today tells you that the asset backing is solid.
Fine to disagree! Remember I'm AMBER - no strong view either way. On the fence. Are you amber/red maybe? If so, why?
P.
Serabi Gold (LON:SRB) taken a bath today down 14%. Big volume. No news that I can find....just a big sale perhaps??
Serabi Gold (LON:SRB) AGM today. Something said has unset the market. Could be to do with licenses? There is a RNS.
AGM statement from chairman mentioned challenges in respect of negotiating with indigenous communities. I thought the drop seemed overdone.
Serabi doesn't have a lot of liquidity so it doesn't take much to smash its bid-ask order book. With the exception of the royalty company Wheaton Precious Metals (TSE:WPM) , none of the gold miners are responding dramatically to the higher gold spot price, but at some point this will change I...
Gulf Keystone Petroleum (LON:GKP)
132p
I have suggested exactly two weeks ago when the SP was at 113.5p that this represented an excellent investment opportunity.
Yesterday the company announced that WITHOUT the resumption of the Iraqi-Turkish pipeline it is generating FCF of about $8m monthly only by selling locally at about $28! And they will initiate a buyback and cancellation of shares of $10m.
Today the KRG President Barzani is visiting Baghdad to have meetings and discuss (amongst other things ) with the Iraqi leadership the resumption of Kurdish oil exports.
Current Gulf Keystone Petroleum (LON:GKP) valuation even WITHOUT these exports is bonkers. With the resumption of exports Gulf Keystone Petroleum (LON:GKP) should be trading at least north of 400p as the cash generation will be over $170m pa,
All the best
I agree about Gulf Keystone Petroleum (LON:GKP) being an excellent investment opportunity. In addition to the plus points in yiannos’s post, Gulf Keystone Petroleum (LON:GKP) were throwing off cash ahead of the pipeline closure, and so much so that they paid 34p in dividends and specials in 2021 and 82p in dividends and specials in 2022. After a 9.57p dividend in early 2023, dividends have been suspended because of the pipeline closure.
Gulf Keystone Petroleum (LON:GKP) is up about 20% since yiannos last posted but at 134p still looks outstandingly cheap. It’s unrealistic to expect a quick return to 82p dividends a year and over 60% yield at current share price when the pipeline reopens, but even the 34p paid in 2021 is a yield of around 25% at current price.
Add on the buyback news and cancellation of $10 million shares and there’s a very compelling investment case as long as that pipeline does eventually flow again.
Gulf Keystone Petroleum (LON:GKP)
The situation for Gulf Keystone in Iraqi Kurdistan is more complicated than the pipeline. Iraq asserts that Western oil companies working in Kurdistan do not have valid contracts.
Here is a statement from the KRG [Kurdistan Regional Government] from three weeks ago: https://gov.krd/mnr-en/activities/news-and-press-releases/2024/april/statement-by-the-ministry-of-natural-resources-of-krg/
This provides a bit more information [February this year]: https://www.spglobal.com/commodityinsights/en/market-insights/latest-news/oil/022224-iraqi-federal-court-ruling-deals-another-blow-to-kurdistan-regional-governments-oil-autonomy
I haven’t thought deeply about risk versus reward here as I don’t need any more excitement in my portfolio at the moment. The wrangling over the oil is not new. I note that the directors of GKP have not been buying shares.
Disclosure: I have held.
It is much simpler actually! Iraq is the first one that needs that pipeline to open as soon as possible.
Because they want everything to go through the Iraqi parliament and government ; hence all the discussions between the USA , Iraq , Turkey , and KRG governments. At the end of the day whether it opens or not Gulf Keystone Petroleum (LON:GKP) have managed to sell locally and generate FCF of $8m monthly. That’s about $100m annually only on local sales. Gulf Keystone Petroleum (LON:GKP) is free of debt and has $96m in cash.
The US and OPEC want that pipeline to open-It will open at some point this year as the revenues and benefits lost from all governments and companies involved are too much to ignore.
All the best
Gulf Keystone Petroleum (LON:GKP) The article didn't read much like an authoritative document. Language like "comically devoid of legal precedent" sounded more like OpEd journalism?
Yiannos
Thanks
I just bought some for the “blame game portfolio “
All your fault if if goes south .
This Gulf Keystone Petroleum (LON:GKP) will do well don’t worry
Be careful with Bank of Georgia (LON:BGEO) cause if they manage to pass the law you will be partner with Putin! :)
Bank of Georgia (LON:BGEO)
The law will be passed.
How it pans after that is a different matter.
My feel is that the country does not want to cuddle up to Russia - the big test is the general election (there) towards the end of the year. Who knows the legislation might be short lived.
BWDIK
Schroeder’s increased their holding in Shoe Zone (LON:SHOE) seems interesting given the recent price performance and threats from Shein etc
https://www.voxmarkets.co.uk/r...
Mello2024...We are being asked for the two day schedule of speakers and presentations which the Mello team are working on today. In the meantime do checkout this listing of which days companies are presenting or exhibiting and speakers appearing in the theatre Mello2024 Line Up – Mello Events
Sorry to intrude but often wonder if there is any possibility of streaming any of your events for those of us out in the sticks and/or too decrepit or incapacitated to be able to attend in person? Without the necessary knowledge I am sure there are numerous reasons why this is totally unfeasible but feel it incumbent on me to at least ask. Back in the day, as people love to say, I thoroughly enjoyed attending but sadly no longer able to.
IQGeo (LON:IQG) Recommended cash acquisiton by large pe outfit KKR.I think this was one of Paul's interesting ones he commented on earlier in the year.Great ip it seems but obviously looks expensive at first sight.Another successful Cambridge based tech company.
The Cash Offer represents attractive enterprise value multiples of approximately:
7.1x IQGeo's revenue of £44.5 million for FY2023; 48.1x IQGeo's Adjusted EBITDA of £6.6 million for FY2023
(Sorry for reposting just seen already been commented on).
Treatt (LON:TET) Pleasing half year numbers from Treatt today, in line with what was expected and cautiously optimistic about future growth prospects. Apart from forex errors a couple of years ago, Treatt has tended (in my over 20 years as a holder) to under promise and over deliver, so I hope to see profit forecast upgrade later this year. New factory now fully operational and capable of at least double present output. Interim CEO and CFO done fine work in difficult circumstances pending new CEO arrival in a few weeks time and he should hopefully be salivating at the opportunities.
Absolutely agreed. Treatt (LON:TET) is one of my favourite stocks and looks back on track again after a couple of slip-ups led to a de-rating from lofty heights. I think there was more to it than just forex errors but nevertheless the company has delivered pretty well over the years. The new facility in the UK and expansion in the US leave plenty of capacity for growth without further cappex required, so all looks promising. I was a little spooked by the departures of the CEO and CFO in quick succession, but I hear good things about the new management due to start soon.
Thanks for the write up on Luceco (LON:LUCE) , Graham, but why does the lighting industry make you nervous? Cyclical nature, reliance on building trade, competition? It’s something all of us use every day with no prospect of that changing.
Headlam (LON:HEAD) Data reported yesterday :
UK housebuilding activity tumbled in the first quarter of this year, new industry data shows, as high interest rates and wet weather hit the construction sector.
A total of 21,967 new homes were registered to be built in the first quarter of this year, the National House Building Council (NHBC) reports today, a 20% tumble on the 27,619 registered in Q1 2023.
IQGeo (LON:IQG) just bid for at 480p. Another UK technology company disappears from the UK market.
Boo.
IQGeo (LON:IQG) I saw that, not much of a premium, the shares were around 457p last week. At least it is a cash offer. Don't know why the sudden dip in the last week. Currently 464p to sell.
Hi Paul, I have been looking at your 2024 share ideas and congratulate you on the performance. Could you add a column with the price at the beginning of the year - maybe I have missed something!
As far as I can see, that column exists (at 29/12/23)
Thanks, column L didn't appear on my spreadsheet when I opened it but I see it now, thanks.
Chrisp: column L on the spreadsheet gives the mid price at the end of 2023
Thanks, column L didn't come up on my spreadsheet but I've found it now!
Probably confused by me freezing the columns & rows, to make the main bit more visible at large font sizes by blind bats like me LOL!
Morning Paul
Your welcomed comment on Huddled (LON:HUD) in yesterday's report. I read your comment and understand why you will watch and wait but I do think the situation here is better than the one you paint.
Chair / CEO / Owner Martin Higginson and his team demonstrate an impressive track record having built and sold 6 businesses.
Most recently they sold the Immotion location based VR business which they managed to get through Covid and lock down without going bust - impressive. He also built from scratch during lockdown a home-based VR business and Uvisan which he has also now sold. The result was returning approx £12m to shareholders, so he does look after shareholders.
After the Discount Dragon acquisition, the company had £6m cash, no debt and MCap £8m so the DD biz was almost in for free. It is growing like the clappers. There is a clear and sensible plan and it is funded. Yesterday's RNS was partly designed to prevent expectations getting ahead of themselves.
Higginson is experienced and clever. His plan is impressive and he has an experienced team behind him. Yesterday's IMC is worth watching.
I own some shares.
Michael
https://twitter.com/InvestorMe...
Re Huddled (LON:HUD) .
For what it is worth, I have bought three times from Discount Dragon and found the service excellent.
Huddled (LON:HUD)
This is good info. They want to grow quickly but not to the detriment of service. Their TrustPilot rating is very high and they have 21,000 reviews.
Thanks Michael for the additional background on Huddled (LON:HUD) - it will be interesting to see if your ideas play out as planned.
As you know, we're not trying to predict the future here at the SCVR, we just look at the facts, figures & forecasts on the day. The losses, and outlook which says continuing losses, means I'll just wait and see what happens next. I'll leave it up to you to predict the future! ;-)
Good luck!
On Beach group (LON:OTB) I haven't had enough time before work to look at this properly but if Paul/Graham you look at I think worth probing why profits remain significantly below 2019 levels. Have some costs become permanently higher?
Very suspicious share price activity yesterday - if it was on results leak then someone got it wrong as today's results are 'in line'.
On Beach group (LON:OTB)
"** The UK-based travel retailer says value market remains
more challenging, reflecting ongoing cost-of-living pressures,
while the premium market continues to perform strongly"
Be interesting to see easyJet (LON:EZJ) results on Thursday, is the value market more challenging, or are Easy Jet holidays eating their lunch.
I did report the rise yesterday in On Beach group (LON:OTB) wish l had sold now. Re profits, the forecast for 2024 is higher 1019. I don't think we have got back to normal yet, some families are struggling with inflation. Oil prices and flights are still higher than pre Covid.
I've done some number crunching this morning for On Beach group (LON:OTB) and think they might be set up for a slight beat for FY24 forecasts; maybe just being conservative and waiting for any risk of summer disruptions (ie strikes, weather, etc) to pass?
I haven't done a deep analysis write-up for OTB before, but will schedule it as my next. But here are four quick points from me:
All this leads me to think a potential 16p EPS is possible for FY Sep24, compared to current Stocko consensus forecast of 14.5p... I don't see why this shouldn't be trading at least 160p minimum, and should be around 180p-200p instead.
(I hold in the Boon Fund)
On Beach group (LON:OTB)
Analysts at Peel Hunt lower their FY24 adjusted EBITDA forecast to 40.5 mln pounds from an earlier forecast of 44.1 mln pounds; says there are some pressures on the consumer of value holidays
Thanks Boon - I think I agree with you. Given that they are 2p ahead at half year mark versus last year then Stocko consensus expectations of 14.5p full year versus adjusted diluted 11.5p last year seem possible and might even head towards your 16p if they can improve margins further. On an adjusted PBT basis I think Graham is right to query whether they can hit full year but again we're already up £4.3m vs last year so £35.3m estimate vs £23.6m might be possible as there's a seasonal weighting? (Last year worth noting marketing costs were much higher as a % of revenue in HY than in second half).
However, I noticed there is a sizeable shared-based payments charge of £1.6m which is adjusted out. Given this is a regular payment (£1.3m last year) I am not sure it's right to adjust it but will defer to the accountants among us! The other adjustments look OK to me (maybe a query about redundancy costs but that's smaller). I imagine some of the past adjustments explain the mismatch between the company's previous adjusted EPS figures and what Stocko shows for financial year end EPS.
Back to my earlier question: their overheads (doesn't include marketing) as a % of revenue are currently about 30% versus 18% in FY19 (on lower revenues) which suggests there might be some permanently higher costs like staffing weighing on profitability versus pre pandemic. I think it would be good to ask them about this on any investor call although I don't think they use investormeet so us muppets might not get invited to any virtual management meeting.
Re : yesterday's fomoing.Could have been some folk were leveraged too with CMC Markets (LON:CMCX).Share price didn't open lower and looks like retail/private investors sold out and a few more traders' stop losses might have been hit..?It did look either like a leak (suspicious on a trading update) or fomoing.It has been a retail favourite share for a while.
I sold out of On Beach group (LON:OTB) after the last update where they stated they were pursuing market share over profit. With the amount of competition that exists I just thought it could end up as a race to the bottom. easyJet (LON:EZJ) are in a position where they can discount their own flights to grab market share more easily than OTB can, if it comes to that.
But if OTB can grab more of the long haul market then they can avoid some of that pressure from the low cost operators. Good luck to those still holding.
Hi Paul, if you have time I would be interested in your thoughts on Marston's (LON:MARS. H1 this morning suggested decent improvement in performance. Its heavily indebted, albeit with a very strong asset base of owned properties, but potentially a candidate for a strong rebound if sentiment towards these types of stock changes.
Ingenta (LON:ING) - anyone know what's going on there. Down 10% at the moment.
Ingenta (LON:ING) Related to the overdue prelim results perhaps?
Ingenta (LON:ING) I thought results were due this Thursday 16th?
Ingenta (LON:ING) hi Doctor Dave - I was going on the fact it was 11/05 last year - was there something official I missed?
Can Paul or Graham cast thir eyes over Renew Holdings (LON:RNWH) please. Seems to be in a sweet spot now, and continually snapping up small bolt ons. I did wonder about the loan repayments on the cash flow however - continuing Bagger
I hold
Gateley (Holdings) (LON:GTLY) - a reasonable update from this Midlands lawyer. Revenue is in line after a strong Q4. It looks like PAT is slightly lower than expectation due to an employee bonus provision. Such bonuses are needed though to retain staff. Chairman designate didn't last long, but not a major problem as there is good continuity elsewehere. Overall, it looks too cheap for me given its a business that hasn't really disappointed, other than its been up against a soft market. Balance sheet and dividend is strong.
Will there be a write-up on Gateley by Paul or Graham?
Headlam (LON:HEAD)
Can't help but feel that something else is wrong here apart from the macro situation - its newer competitor?
Luceco (LON:LUCE) is also subject to the housing market but is growing.
Any thoughts?
A.
(Don't hold)
I have dipped in and out of Headlam (LON:HEAD) and what did appear to be a rock solid company with asset backing is either now in very deep value territory, or as you say, something is up. From discussing the flooring market with friends that own a very large company locally, business is not booming, although there is enough to keep them going. However, I do know that new entrants (especially online only) is starting to eat their market share (at the lower level). If the dividend can be maintained, I will seriously looking at picking up some - if there is a boom that people are suggesting, then this should easily double from here.
I suspect you're right re (Headlam (LON:HEAD) and that management have seriously taken their eyes of the game. I do, however, see there to be limited downside. It's end markets will pick up at some point, perhaps not as profitably as before (due to competitors eating their lunch somewhat), but they will recover. It makes very little sense to me for the market cap to be trading below the value of the land bank - which they've shown (and often appears to be the case) is conservatively valued. I would wager Headlam is acquired before shareholders get a chance to benefit from the upside re-rate when end markets pick-up.
Headlam (LON:HEAD)
Please excuse bias as my largest holding is Likewise (LON:LIKE). I also am a retailer with accounts with both companies.
Headlam Trade counters have been promoted to any trade similar to Howdens business model so almost anyone has been able to purchase from the counters. Anyone loosely connected to a trade like painters and decorators even hairdressers. They also sell to the likes of 'The Range' in their stores which has driven the industry to only order from them as a last resort.
Yes they have massive property and transport assets that they own, totally built around retail distribution I believe this is now becoming unsustainable. How do you value that when it is loss making going in the wrong direction?
Headlam have been revising down now for a good while now through the back door of Brokers while blaming market conditions. Today I believe is the first announced warning. Likewise (LON:LIKE) recently have countered news releases the day after Headlam with positive news but I expect this wont come tomorrow as results are due Monday 20th May.
My fear is that I am totally wrong from seeing things to closely.
I will try and repost my thoughts on Likewise
Likewise (LON:LIKE)
Ex team from Headlam (LON:HEAD) owner led who are ripping through wholesale flooring distribution market. Not profitable yet but are capitalising on mistakes being made at Headlam. They have just added 11 new sales reps. Built in plenty of expansion space into present units so will become far more efficient as they go forward. They should be aiming for tunover £150m this time from £4m in 2018.
£22m of £40m assets is in freehold property. Market Cap £41.65
£200M is short term target sales looking at 5% margin. (But i believe much more turnover to come)
I could continue to bore you for hours but take a listen to Tony Brewer himself with Jeremy McKeown and James Wilson of Phonix Asset Management under In The Company of Mavericks episode 25.
Seconded: just listened to the Tony Brewer interview. Very impressive.
A total different opinion
Likewise (LON:LIKE) does NOT represent an investment opportunity.
Net margin not even 1.5% and cash burning.
Much better opportunities elsewhere.
All the best
hi Mark
Headlam (LON:HEAD)
Headlam have been revising down now for a good while now through the back door of Brokers while blaming market conditions. Today I believe is the first announced warning.
I have previously posted on here of my concerns regarding the lack of proven Management ability. The CEO appears to be another example of a former CFO lacking the necessary CEO skills and the CFO has only been in situ for just over 12 months.
The issues do seem much deeper than macro headwinds and competition from Likewise (LON:LIKE) suggesting that effective strategy and leadership is somewhat lacking at Headlam (LON:HEAD) .
How much longer can the CEO survive?
This could get much worse before any recovery is in sight.
Snazzy
Snazzytime,
I hope CEO survives until people see value in Likewise (LON:LIKE)
LIKE added second broker last year. I have seen stranger things than Likewise bidding for Headlam at some point.
Hi Mark
Can you elaborate please how can Likewise (LON:LIKE) that is 4 times smaller than Headlam (LON:HEAD) will actually bid for it and why will the shareholders of Headlam (LON:HEAD) accept that bid?
All the best
Likewise (LON:LIKE) Headlam (LON:HEAD)
i would take the viewpoint that IF this is akin to the stuff that went on with safestyle or the ice cream wars then i would suggest that perhaps neither business will benefit from intense competition betwen the two. Clearly there is scope for this all to be "very personal" when you have the senior managers of one business departing to work for upstart that is trying to take business away from the the place they used to work.
ok perhaps the poor trading for Headlam (LON:HEAD) has nothing to do with the competition from likewise - but i would start from then viewpoint that Likewise may very well be the reason why headlam is struggling. Likewise have gone from £30 mill revenues in 2019 to short/near term target of £200 mill revenue - so its reaosnably clear they are likely to be muscling in more and more on headlams buisness if its exactly the same kind of jobs (is it?)
Sounds like Tapi and Carpetright.
i like how on Tapi's faq they go the the trouble of answering the - are they connected question? robustly.
q
Does Carpetright own Tapi?
a
No way!
Yes, I did hold but sold realising a 60% loss. Everything looked hard work but the clincher was the fact that the competitor looked like surviving/succeeding, severely limiting upside.
My morning smallcap tweet: Last orders at RBG bring little cheer
EnSilica (LON:ENSI) Aurrigo International (LON:AURR) Pennant International (LON:PEN) Gateley (Holdings) (LON:GTLY) Revolution Bars (LON:RBG) Headlam (LON:HEAD) Midwich (LON:MIDW) Newmark Security (LON:NWT) OPG Power Ventures (LON:OPG) Various Eateries (LON:VARE) £TET Angling Direct (LON:ANG) On Beach group (LON:OTB) Zytronic (LON:ZYT), Luceco (LON:LUCE), EKF Diagnostics Holdings (LON:EKF), Aptitude Software (LON:APTD)
◄EnSilica (ENSI)► guides FY-May rev c.£25m up 22% and post-tax profit c. £1.9m (£1.8m). "H2 mix of business changed reflecting the slower economy and the impact that had on the start of new supply contracts which are now expected to begin in Q1 of FY25...change in sales mix led to a reduced margin overall though management are confident that this will not persist into FY25." Guides FY25 rev over £30m and EBITDA over £5m. [SP=61.4 Cap=52m]
◄Aurrigo International (AURR)► wins c.£2.5m contract that will see a 'fleet' of automated baggage handling vehicles at Changi Airport piloted for underwing operations during 2024 and 2025. Guides FY-Dec in line with F/C rev £6.5m and EBITDA -£3.8m. [SP=104.6 Cap=46m]
◄Pennant International (PEN)► YTD trading in line but non-recurring costs of c.£0.3 for aborted corporate activity. "Key markets are starting to see a significant increase in activity...[but] expected level of order conversion has not occurred in the year to date, which is primarily attributable to extended customer procurement timeframes, not the loss of opportunities." [SP=30.22 Cap=11m]
◄Gateley (GTLY)► guides FY-Apr rev up 6%. U/L pretax £22.8m+ (£25.1m), "reflecting the board's decision this year, unlike last, to make a provision of £4.5m for employee bonuses." [SP=109.8 Cap=145m]
◄Revolution Bars (RBG)► despite 32 parties participating in the Formal Sale Process not one has made an offer for the company or its assets as a whole via a single transaction. Offers for some assets but shareholders would get nowt. Still exploring other strategic options. [SP=1.77 Cap=8m]
◄Headlam (HEAD)► rolls out the brown carpet for holders as it warns FY profit significantly below market expectations. Jan-Apr rev down down 12.3% with Apr not showing the expected seasonal uplift. "Recent macro data has indicated continued weakness in repair, maintenance and improvement, consumer spending on home improvements, and housing transactions, all of which indicate a further delay until 2025 for a recovery in the floor coverings market." [SP=176.5 Cap=143m]
◄Midwich (MIDW)► AGM stmt - first 4 months' organic rev flat, below mgmt expectations. Guides FY adj op profit only broadly in line with FY23. [SP=420 Cap=438m]
◄Newmark Security (NWT)► guides FY-Apr rev £22m+ (£20.3m). Improved profitability and cash flow led to YE cash position of £1.1m (£0.6m). [SP=103.5 Cap=10m]
◄OPG Power Ventures (OPG)► guides FY-Mar rev £160m+ and EBITDA £16m+, above mkt exp. [SP=10.5 Cap=42m]
◄Various Eateries (VARE)► guides H1-Mar rev up 10%, driven largely by new site openings. LFL marginally down, blames wet winter. Co maintained its strategy of absorbing most price increases. Deceleration of food and utilities cost increases has continued. H2 has been resilient. [SP=21.7 Cap=38m]
◄Treatt (TET)► H1-Mar. Guides FY profit in line. [SP=473 Cap=287m]
◄Angling Direct (ANG)► FY-Jan. Outlook - "Resilient Q1 trading against an uncertain consumer landscape and sub-optimal weather conditions: focus on protecting operating margins, cost control and successfully optimising stock levels ahead of the key summer season". [SP=34.41 Cap=27m]
◄On The Beach (OTB)► H1-Mar. Guides FY profit in line. [SP=167.6 Cap=280m]
◄Zytronic (ZYT)► H1-Mar mixed. Outlook - "some grounds for optimism while we undertake a formal business and operational review process". [SP=60.35 Cap=6m]
In line: LUCE, EKF, APTD
Headlam (LON:HEAD) "rolls out the brown carpet" haha x
Pennant
Slightly strange trading update .
Intriguing comment of a 300k one off cost .
“£0.3 million in relation to aborted corporate activity.”
That’s a reasonable chunk for a 10 million market cap.
I did ask Richard Staveley about pennant at Mello last year and he made some reference to some sort of acquisition / corporate activity buying a larger business and fund raise .?
Loads of business as usual out for tender and not converting quickly as is par for the course with MOD and defence clients - not exactly the things you can get a buyer to commit to on a whim .
Ian Dighé moves to full time chairman I think he’s a Rockwood / Gresham guy .
Also note Lawrence Hulse of Dowgate has built a stake which will probably annoy Rockwood as he and Staveley were the guys when Rockwood was Gresham .
Luceco (LON:LUCE) Q1 statement reads like they are quietly confident FY forecasts can be beaten, but just can't bring themselves to sanction upgrades just yet.
Late Brickability (LON:BRCK) news yesterday - more insider buying by D Bryce of another 250,000 shares, taking to their total to 800,000+.
Well you can’t accuse Mr Bryce of not eating his own cooking! He has purchased over 800,000 shares in the last week spending over £550,000. He obviously believes that business is starting to look up.
How much did he pay per share?
Brickability Group PLC, the leading construction materials distributor,
announces that it has been informed that Douglas Bryce, Managing Director
within the Contracting Division, has purchased 250,000 ordinary shares of 1
penny each in the Company ("Ordinary Shares") each at a price of 71 pence per
Ordinary Share.
Anyone any idea how he got them for 71 pence when the share price on the market was 76/77 yesterday? Excuse my ignorance
Brickability (LON:BRCK) 71p was the price shortly before close on Thursday and in the first half hour Friday. I’m not sure how quickly one is obliged to notify. Is he/she even a board member?
Brickability (LON:BRCK) "Anyone any idea how he got them for 71 pence when the share price on the market was 76/77 yesterday? Excuse my ignorance "
James, the RNS says the purchase was made last Friday 10/05/24 not yesterday.
Think you have 3 days grace to notify the market when obliged to do an RNS
I got told off for being late with a TR1 once