Small Cap Value Report (Tue 14 Nov 2023) - FNX, JIM, BILN, FNTL, CGS

Good morning from Paul & Graham!
That's it for today.
Mello Trust & Funds online show (free) - is today from 13:00 - I'm flagging it in particular as the highly regarded Richard Staveley from Rockwood Strategic is giving a presentation. I know he's been favourably discussed in the reader comments here before, hence the mention. I couldn't make last night's Mello, so if anyone has views on Sosandar (LON:SOS) and Solid State (LON:SOLI) then please do post a comment below with your impressions of their presentations last night. Must admit, I am far from convinced by the major change of strategy at SOS.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
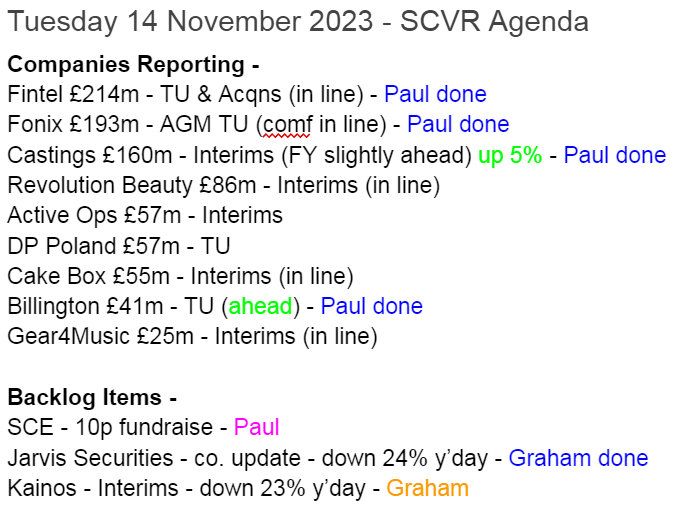
Quite a bit to look at today, so we might grey out some of the unremarkable, in line updates -
Summaries
Fonix Mobile (LON:FNX) - 193p (pre-market) £193m - Trading Update (AGM) - Paul - GREEN
Today's AGM update reassures on positive trading. Sounds like it's a bit ahead of forecast, and with very sticky clients, risk strikes me as low. Capital-light, and paying out a >4% dividend yield, there's a lot to like here. I think it's worth the c.20x PER. The wild card is international expansion, which has worked very well in Ireland. Other countries to follow, I wonder?
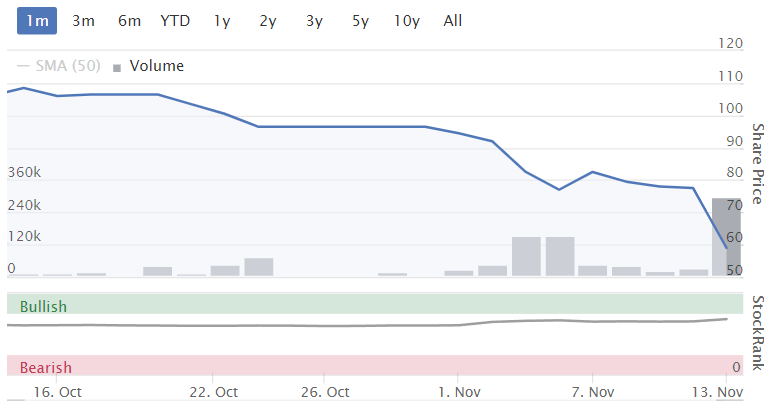
Jarvis Securities (LON:JIM) - down 32% this week to 56.2p (£25m) - Dividend and Company Update (divi suspended, trading in line) - Graham - GREEN
Jarvis suspends its Q4 divi although it claims that this suspension is in line with expectations. It also provides more details on the ongoing regulatory reviews. The market is pricing in awful news; I’m stubbornly remaining Green on JIM until the bad news is revealed.
Billington Holdings (LON:BILN) - up 10% to 350p (£45m) - Trading Update (ahead exps) - Paul - AMBER/GREEN
Another ahead of expectations update, coming on top of a previous one as recently as Sept 2023. It looks stunningly cheap now, but of course cyclical companies often do look cheap just before a recession that causes future earnings to collapse. That's the big unknown here. With a strong balance sheet, plenty of cash, and good divis, I feel forced to go up from amber to AMBER/GREEN.
Fintel (LON:FNTL) - unch 206p (£216m) - Trading Update & 2 Acquisitions - Paul - AMBER
Formerly known as SimplyBiz. Today we get an in line update, and news of 2 new acquisitions (4 in total this year). We've not reviewed it since Jan 2023, so I run through everything below, and come out reasonably impressed - a decent business, but maybe priced about right for now? I can't find anything wrong anyway, but in a deep bear market for small caps, the valuation isn't cheap enough to get me interested.
Castings (LON:CGS) - up 5% to 385p (£168m) - Interim Results - Paul - GREEN
Smashing interim results. Superb asset-backing, and a generous flow of dividends (plus specials). Encouraging diversification away from the dominant truck turbocharger housings. I remain of the view this seems a lovely tuck away and forget income share.
Paul’s Section:
Fonix Mobile (LON:FNX)
193p (pre-market) £193m - Trading Update (AGM) - Paul - GREEN
Positive start to new financial year with strong growth in both the UK and Ireland
Founded in 2006, Fonix provides mobile payments and messaging services for clients across media, telecoms, entertainment, enterprise and commerce.
When consumers make payments, they are charged to their mobile phone bill. This service can be used for ticketing, content, cash deposits and donations. Fonix's service works by charging digital payments to the mobile phone bill, either via carrier billing or SMS billing. Fonix also offers messaging solutions.
The current financial year is FY 6/2024.
A reassuring update today - I’ve highlighted the key points as usual -
Fonix has had a positive start to the financial year, comfortably in line with expectations, with strong income growth from new and existing media clients in both the UK and Ireland. This week will see Fonix once again power donations for BBC Children In Need for the tenth consecutive year.
The business has continued to progress its planned investment in both technology and exploring new international markets, as the business looks to expand its market reach whilst continuing to deliver new and enhanced products and services.
With high levels of repeating revenue and a strong, expanding run-rate from key clients, the Board continues to be confident in the growth potential for Fonix for the rest of the financial year and beyond.
Paul’s opinion - today’s update reassures nicely, which it needs to with a forward PER c.20x.
A stand-out feature of FNX is how sticky its clients are.
Also the international expansion excites me, as this can apparently be done at little cost & risk.
I’d like to speak to management again, and my key question would be how can it dislodge incumbents in international markets (which it must have done very effectively in Ireland), to grow further? Bolting on additional, decent-sized overseas markets, could be transformative, if it’s possible.
Fonix seems to have an excellent business model - capital-light, and cash-generative, so it can self-fund growth at the same time as paying out most of its cashflows as dividends (with cover of about 1.2x).
I’ve reviewed this company 6 times in the last year, in 5 cases going green, with just a slight wobble in Mar 2023 when the share price got a bit ahead of itself at 237p, so I shifted down a gear to amber briefly, purely on valuation concerns.
With the price now more reasonable, at 193p, and the good news continuing to flow, I’m happy to remain at GREEN.
This really does look a very good, high quality company, that’s also paying a c.4% dividend yield. It’s not put a foot wrong since floating in Oct 2020. Management remain big shareholders - there's nothing quite like the owner's eye!
Superb track record actually -
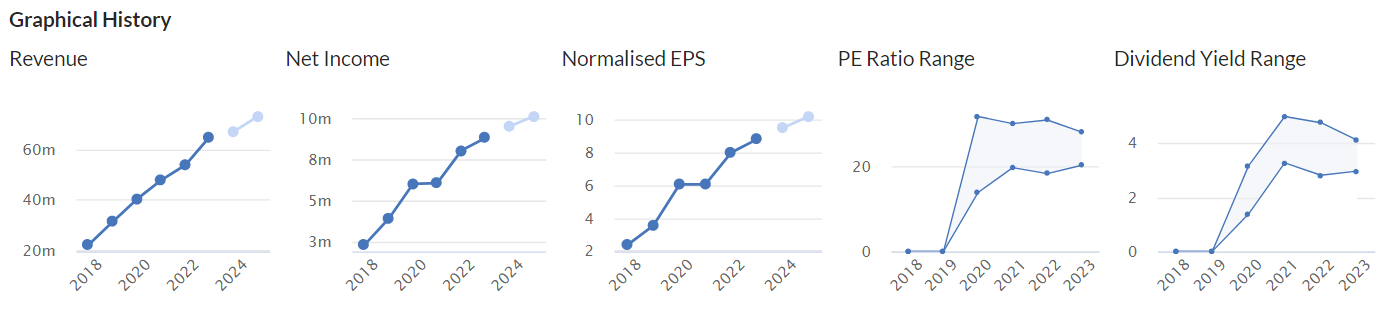
This shre price may not look impressive, but bear in mind there have been divis of about 19p on top of the share price, and the background has been a savage bear market, where many other shares (small and medium) have halved or more. In that context, I wouldn't sniff at this performance -
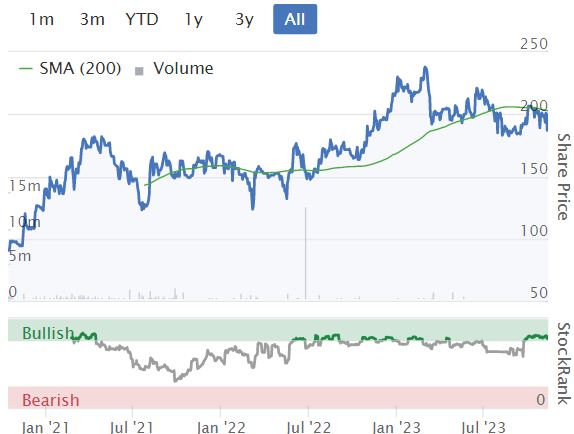
Here it is on a chart - showing FNX since listing (top line, up 96% since listing), and the relevant index, FTSE AIM All Share Index (FTSE:AXX) (down 28% over the same period)
Billington Holdings (LON:BILN)
Up 10% to 350p (£45m) - Trading Update (ahead exps) - Paul - AMBER/GREEN
Billington Holdings Plc (AIM: BILN), one of the UK's leading structural steel and construction safety solutions specialists, is pleased to provide an update on current trading.
Company’s headline -
Strong trading performance continues across the Group and results for the year ending 31 December 2023 are now expected to be ahead of previous market expectations
That’s a good headline above. I like it when these headlines are simple, and factual, as this one is.
As a general point, what we dislike is when a PR has been let loose on a negative update, and has tried to buff it up with some positive-sounding waffle. Investors see straight through that, and it undermines trust in the company’s management. No such concerns here with BILN though, I’m pleased to say.
Background -
From our previous notes, to get me up to speed -
14/12/2022 - 290p - AMBER - Good TU - signif ahead. Good order book & bal sht.
18/4/2023 - 390p - AMBER - In line results. Good outlook.
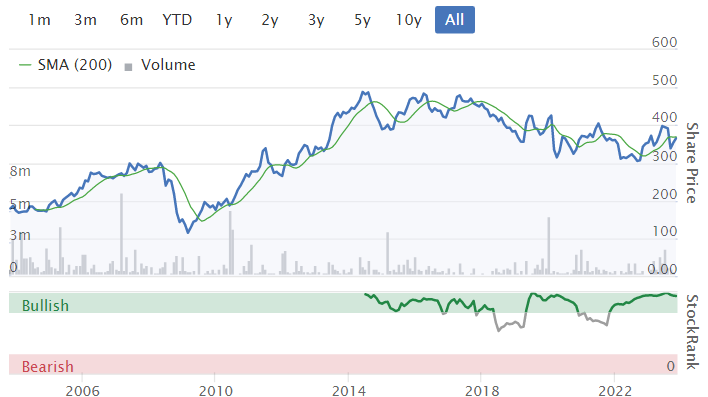
Why were we only amber, considering the newsflow was good, and valuation cheap? Worries about cyclicality - this type of business tends to be very cyclical. We’ve seen in the past how, in recessions, after a time lag as they work through the existing order book, performance falls off a cliff and takes the share price with it, as new orders dry up.
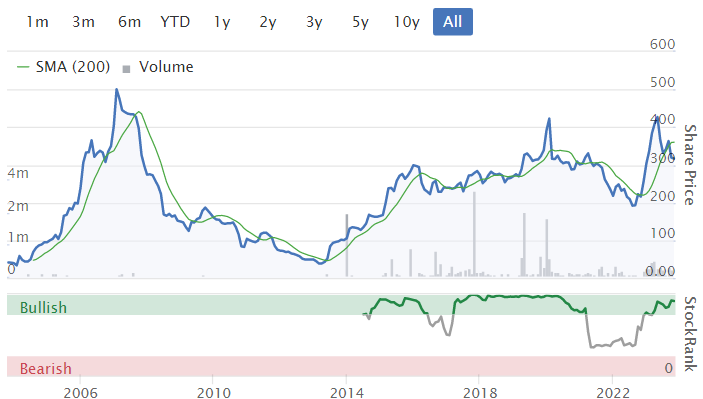
Consider this - BILN shares peaked at 500p in Feb 2007, then crashed to a low of about 38p in April 2013. Since then the shares have almost 10-bagged. So you can see the extreme cyclicality with this type of share. Which is why I’m very wary about something so closely linked to the business investment cycle. Especially given that major building projects are no longer subsidised by the mis-allocation of capital that 15 years of zero interest rates arguably caused. Macro conditions are likely to drive this share price very much, in the medium term I’d say, so investors need to be very clear on what your macro view is.
Interim Results (June 2023) - We didn’t look at the interims to June 2023, so I’ll have a quick look now.
Excellent numbers! H1 adj PBT soared 237% to £5.0m, on £60.2m revenues (up 30%). (adjs were only small, so OK)
Balance sheet at June 2023 looked fairly good, with £36m NTAV. No financial debt, and £10.8m cash is robust. Only query was a £2.2m “Pension asset”, which would need checking to ensure it’s not a real-world deficit.
Cashflow - not great, as growth means that working capital is absorbing cash. Hence little scope for paying divis - divis were negligible in 2020-22, but I see a bigger (15.5p) final divi has just been paid in July 2023, which will fall into the H2 numbers in FY 12/2023 as a £2.0m cash outflow.
Outlook (from H1 results, issued 19 Sept 2023) was quite mixed, with some negatives (softening demand from office & warehouse builders, difficulties with trade credit insurance, deferred or cancelled projects). On the plus side, it mentioned benefits from easing steel, and energy prices (helping margins), stability in securing supplies, and buoyancy in other sectors (energy from waste, high-tech manufacturing, infrastructure, and data centres).
Still, it rounded off the interims with another ahead of expectations update (19/9/2023).
Today’s update at last!
Strong trading performance continues across the Group and results for the year ending 31 December 2023 are now expected to be ahead of previous market expectations
The Company is pleased to report that trading has continued to be strong across the Group, with further good quality orders secured and increased volumes being delivered in the second half of the year.
The Group continues to benefit from improved manufacturing efficiencies from the deployment of its capital investment programme across all the Group's production facilities.
The successful and efficient delivery of high quality contracts, combined with the increased capacity and positive final determination of contract values has seen the momentum gained during the first half of 2023 continue.
Consequently, the Group now expects revenue and profit before tax for the year ending 31 December 2023 to be ahead of previous market expectations.
Subjectively, that seems more positive to me, than the Sept 2023 update, which mentioned quite a few negative factors that are not mentioned today.
Outlook - the CEO says -
Going forward into 2024 we have a healthy pipeline of further opportunties [sic] however, we do remain mindful of continuing inflationary pressures and an uncertain macroeconomic outlook, but with our strong balance sheet I do believe the Group is well positioned for the future."
Broker update - thank to Cavendish for an update note this morning.
It’s a whacking great 33% increase to FY 12/2023 profit forecasts - quite unusual to see when we’re only 9 weeks away from year end.
Adj PBT for FY 12/2023 is now upped to £13.3m (a healthy 10.6% margin on £125m revenue). Forecast EPS is upped from 62.9p to 83.9p.
Net cash is expected to be £16.0m, comparing very favourably with the £10.8m at June 2023. That’s after paying out the £2m divi in H2, I’ve checked the broker’s cashflow forecast to confirm that point.
The PER on FY 12/2023 numbers is only 4.2x - either this share is much too cheap, or the market thinks 2023 is a bumper year before the recessionary rot sets in, as happened in previous recessions.
Cavendish is treating this as a bumper year, since its 2024 forecast is much lower, at 49.3p EPS, bringing the PER to 7.1x, which is probably sensible at this stage of the cycle, where we’re seeing mounting evidence across many sectors of businesses being more cautious about committing to larger contracts.
Paul’s opinion - I’m mesmerised by value like this! A strong, cash-rich balance sheet, a 2023 PER of only 4.2x, and a forecast 5.7% dividend yield (20p per share in both 2023 and 2024) is bound to excite me.
You can make up your own mind about how much macro factors offset the sparkling performance in 2023.
I’d say the balance sheet looks plenty strong enough to ride out a downturn in demand, if that does transpire (which has to be a high probability assumption for 2024 I would imagine?).
With figures this good, I can’t remain on the fence, so have to shift up from amber to AMBER/GREEN. I’d be completely green, if macro had been more stable & predictable.
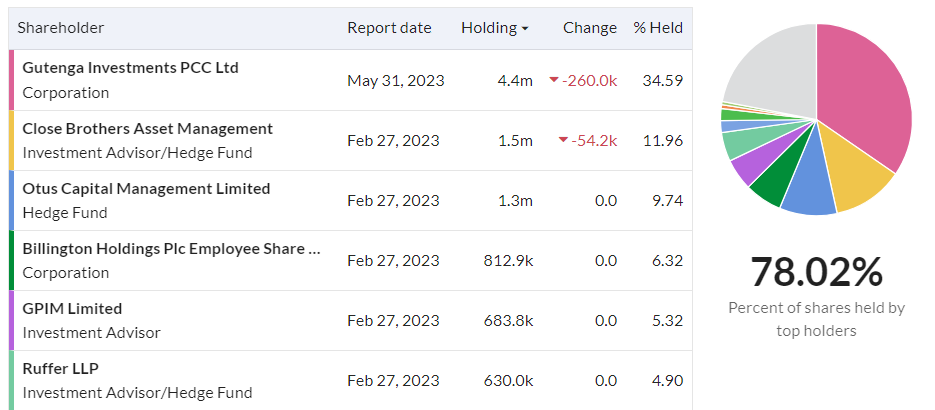
Note the concentrated shareholders - to save me looking it up, does anyone know the background to Gutenga Investments Ltd? Note they sold 260k shares in May 2023 -
Note the cyclicality! -
Fintel (LON:FNTL)
Unch 206p (£216m) - Trading Update & 2 Acquisitions - Paul - AMBER
Fintel (AIM: FNTL), the leading provider of fintech and support services to the UK Retail Financial Services sector today provides an update on two further strategic acquisitions.
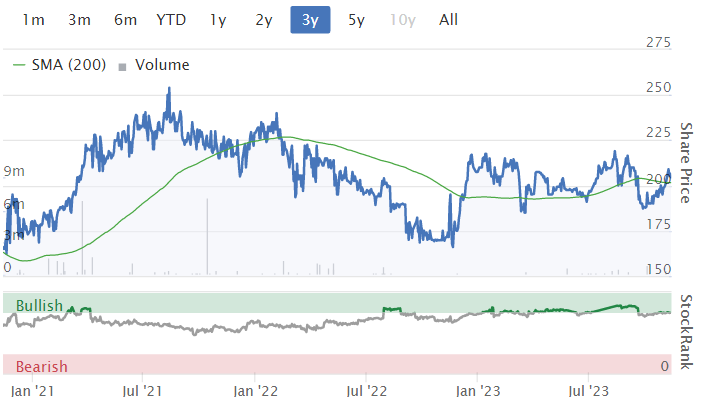
It’s been a while since we last looked at this acquisitive group, which used to be called Simplybiz. I like the reliable recurring revenues here, and it’s sailed through the 2-year small caps bear market relatively unscathed, and with a high StockRank, as you can see here -
Current trading & outlook - sounds OK -
The Core business continues to deliver resilient earnings in line with board and market expectations for FY23, with the ongoing pressures in the UK housing market being largely offset by continued progress in software license sales and acquisitions…
"Our positive trading momentum has continued into the second half, with continued growth in SaaS and Subscriptions revenues, supported by our resilient, diversified revenue base…
With a strong M&A pipeline, underpinned by our balance sheet and cash position, we are confident in making further strategic progress."
Fresh acquisitions - 2 more, making it 4 in total this year -
VouchedFor - FNTL paid £7.5m to acquire this review site for financial intermediaries. 2-year earn-out (linked to recurring revenues), capped at £10m. Currently trading at breakeven, so this could be a drag on margins for the time being?
AKG - a much smaller deal, £1.6m up-front, and £0.4m max earn-out.
Paul’s opinion - I’ve got a generally favourable opinion of this group.
Multiple acquisitions can make it difficult to keep track of what’s going on, and the VouchedFor deal looks quite hefty for something only trading at breakeven, so FNTL must have high hopes to improve performance there.
There’s little balance sheet support, so this share is all about good profit margins and resilient, recurring revenues. Plus a small divi. There’s a large bank facility available for up-front funding of acquisitions, although given macro uncertainty, I wouldn’t want to see the borrowings increased too aggressively. FNTL has stayed the right side of the line in the past though, which reassures.
Overall, this looks OK, and seems priced about right on a fwd PER of 15.7x, so I’m happy to stay at AMBER, and it looks fairly safe (i.e. low risk of profit warning, due to recurring subscription revenues). I can’t see anything wrong with FNTL, but in a bombed out small caps market, it doesn’t offer enough value to tempt me in.
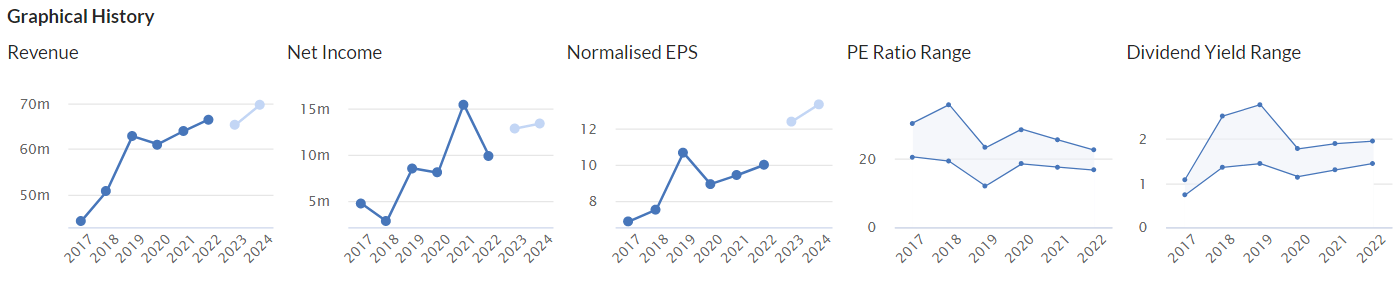
Castings (LON:CGS)
Up 5% to 385p (£168m) - Interim Results - Paul - GREEN
Quick comments - strong H1 numbers with PBT up 38% to £10.3m. Helped by recovery in demand from truck manufacturers. Also note the 5-fold increase in finance income to £648k in H1 from higher interest rates.
Ludicrously strong balance sheet, as always, with NTAV of £127m (76% asset backing vs market cap). Cash of £31.3m, and no interest-bearing debt.
Cashflows good - used about two thirds for dividends, one third for capex.
Forecast yield is 5%+specials, this is the main reason to hold this share.
Chairman stepping down after 63 years with the company, what a slacker! ;-)
Outlook - sounds good, with FY 3/2024 outlook “marginally ahead” of expectations.
Good to see production diversifying, as I was worried CGS was too reliant on truck turbocharger housings, it says -
We have also seen continued progression in our other growth sectors of wind energy, rail, trailer braking and trailer coupling, as well as increasing opportunities to supply parts into the US market.
Valuation - very reasonable, at fwd PER 10.7x, 5% yield, and so strongly asset backed.
Paul’s opinion - GREEN, it’s a lovely business, reasonably priced, for patient investors.
Very long-term chart -
Graham’s Section:
Jarvis Securities (LON:JIM)
Share price: 56.2p (-32% this week)
Market cap: £25m
This stockbroker published an update at 12:52 pm yesterday afternoon: “Dividend and Company update”.
The market dumped the shares another 24% on the news:
Dividend news:
In line with current market expectations, the Company confirms that it is not declaring a fourth quarter dividend (total interim dividend for the twelve months ended 31 December 2023: 8.75p).
Checking the last three updates from the company, including the declaration of the Q3 dividend, there was no mention of the Q4 dividend being suspended.
A broker note published on 10th August by WH Ireland estimated the full-year dividend for 2023 to be 8.75p. As far as I know, they are the only broker covering the stock.
The Q1, Q2 and Q3 dividends do indeed add up to 8.75p. So no Q4 dividend was needed for Jarvis to hit forecasts.
However, I think the broker note might possibly have contradicted itself a little bit, as it also mentioned a 1p dividend being declared in Q4.
And judging by message board comments, it sounds like many investors were still hopeful of a Q4 dividend.
So personally, I’m not 100% convinced that the suspension of the Q4 dividend is entirely in line with market expectations. I think shareholders had a reasonable belief that a small Q4 dividend was still possible.
Company update
The rest of the announcement covers the ongoing regulatory review:
…an additional review (known as phase 1c) ("Phase 1c") is required by the FCA to be undertaken in respect of its subsidiary, Jarvis Investment Management Ltd ("JIML") . Phase 1c will review JIML's approach to uninvested client cash, interest retention and term deposits.
I have had one long unanswered question about JIM when it comes to uninvested client cash. I have always wondered where it places this money to earn interest, as it seems to me that it has earned very attractive returns on client cash. But for good commercial reasons, a stockbroker is unlikely to give you a list of its counterparties.
However, it is normal in this industry for interest on client cash to be an important revenue stream (disclosure: I’m currently a shareholder in Hargreaves Lansdown (LON:HL.) and I’m a former shareholder of Jarvis Securities (LON:JIM) ).
The FCA (see this recent FT article) seems to be of the opinion that providing “fair value” to customers means giving them more of the interest earned on their cash (the FCA might be forgetting that interest earned by brokers on client cash could help to subsidise lower fees and annual charges).
If the FCA wants stockbrokers to earn from commissions and charges alone, rather than from interest on client cash, that will certainly be a difficulty for low-frills, discount brokers such as Jarvis.
The update continues:
The FCA have also provided additional direction for the pre-existing Phase 2, if required. This phase would include a review and assurance report on the remediation work undertaken by JIML on the matters raised in any of the s.166 reports. This review may be required before the voluntary restrictions on JIML's new business and assets can be lifted.
These restrictions impinge on the ability of Jarvis to pay dividends.
Exceptional costs of £1.3m in the current financial year should be the least of shareholder concerns here.
The company “continues to trade in line with current market expectation” which is £6.6m of adjusted PBT (before the exceptional costs).
Graham’s view
The market is telling me that I am completely wrong on this share. The share price is down by 66% over the past year. I gave it the thumbs up in September 2022 at 94p, in March at 139.5p, in August at 125p
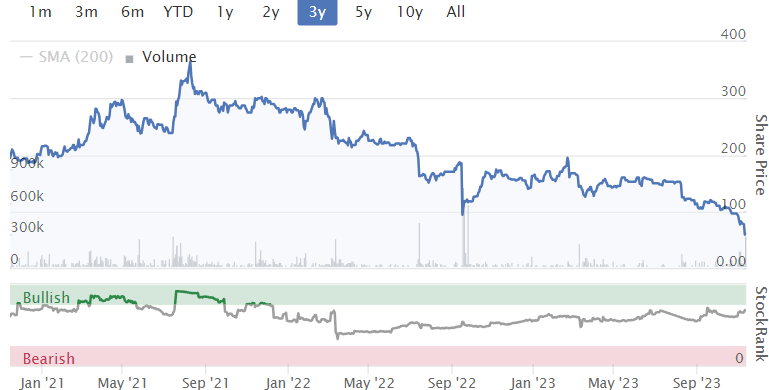
So feel free to ignore my views on this one, as the market clearly disagrees with me.
I can accept that a regulatory review is time-consuming for management. I can accept that where regulatory mistakes were made, this reflects poorly on the company. I can accept that there are exceptional costs and (possibly) fines to be paid. I can accept that all of this makes for poor publicity, which is not good for business.
But then at the end of the day we are left with a company with £5m of its own cash (as of July) and with £6.6m of PBT (before the exceptional costs associated with the review), and it’s trading at a market cap of £25m.
This is a company that has always made a profit for the last 20 years, has paid dividends every year, and more often than not has generated amazingly high quality metrics, thanks to careful cost control and a capital-light business model.
I have had some concerns about the company - were they investing enough in their trading platform to stay competitive? Were they being careful with their choice of counterparty when putting client cash on deposit?
It’s also worth mentioning, as readers have commented on, that the FD recently left the company. The timing of this change was interesting. He was replaced immediately by a company insider, rather than an external hire.
With a major investigation still underway and likely to last for several more months, it would be very easy for me to switch my stance to Amber or even to Red. I can’t predict the outcome of this investigation any better than you can. However, until profitability at Jarvis takes a more serious hit, or the company is fined into oblivion, I have to stick to my conviction that this stock is underpriced. When the facts prove me wrong, I will change my mind.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

102 comments
I watched the Sosandar (LON:SOS) webinar yesterday and was find myself in very a mixed thought process on this.
First to declare my bias I have been invested in SOS for years and it was my biggest position till this drop so I have some definite blind spots on it. Until this latest profit warning I was very positive on the stock and the growth story. Even trying unsuccessfully to buy some more at 11p which I believe was a good price.
The latest update did show growth and the they are still expecting to be profitable however much lower than expected. What I am unsure of is how much of this is Management getting it wrong. My concern in the talk was how self congratulatory they were without admitting actually we got this wrong or not entirely right. The new approach of aiming for higher margins sharply dropped sales growth and didn't really work as well as they tried to convince us.
There was lots of we are doing amazingly well, third party sales are amazing etc but the numbers don't really prove that out. They are definitely not bad but not as good as they say. IMO the new strategy to not focus on where their growth previously came from was not as successful as they want to believe. 10% growth is actually barely keeping up with inflation. I suppose this was what worried me the most, management hubris stopping them from accepting they might not be totally right and failing to pivot or adapt their plans.
The physical shops themselves are a bit of side issue for me, I don't see them being gamechangers but an omni channel with shops being part of it does not seem a bad idea. They seemed pretty sensible about the gradual roll out strategy and giving the process time to bed down to see if worthwhile. The big BUT is if this was on top of hitting their targets it would look great. On top of a material miss it looks like a distraction.
If they learn a lesson and get back to what works or at least combine the best of both strategies they might still be a fantastic investment, I think sitting on the fence till their next results will be my approach.
MPAC (LON:MPAC) [I hold] does anyone have an insight into the low and still apparently weakening price of MPAC? Forward PE 5.6 and PEG 0.2 and balance sheet looks sufficient if not luxury. Superficially, it looks unbelievably cheap to me.
Re MPAC (LON:MPAC) I think there’s likely a read across to https://ir.freyrbattery.com/ir...
Never good when a major customer is facing a liquidity crunch …plus the pension payments by pass the P&L and are still significant
Freya are not really yet a major customer. They are a partner/customer in a speculative new cell battery production line which is discounted to zero in the share price anyway but has potentially strong upside. Secondly a liquidity crunch is a bit much. They have $350m of net cash. May be cutting their cloth to market conditions but not really a crunch!
The existing business ex Freya is expected to do 38p eps next year. The business has net cash. If they achieve this then valuation will turn but it will need patience. The stock is super illiquid so it only takes sellers of 2 or 3k to move the stock down. The inverse will be true when buyers step in.
Fair comment…but MPAC (LON:MPAC) have been banging the Freyr drum vigorously
Agreed though I noted the new CEO was much less at pains to do that. He was focused on the existing business whilst acknowledging the enormous future market the partnership with FREYR could bring without putting any timescales on it. Sensible, as it isn't in the price anyway so no reason to hype it. This business can be much larger and better irrespective of batteries.
The only real foot they put wrong over last 7 or 8 years was during covid with supply chains that hurt margins and required elevated inventory for a period of about 18 months. But out of that came an innovative servicing business (that can also be done remotely) that now makes up 30% of revenues so might actually make them a much more resilient business going forward.
We will see - the CEO wasn't COO for very long before getting the job but he speaks well and seems to have a good grasp of what needs focussing on. Of course as with any new management time will tell. I own a few and looking for signs to buy more. Haven't done so yet - I'd like to see another positive trading update on the core business first
Jarvis Securities (LON:JIM)
Hi Graham
Thanks for your write-up.
I was quite interested to read your positive review as I saw the update yesterday at 13:00 and reactively sold my remaining holding.
The risk to future interest income was evidently the last straw for me.
Client Cash Interest Income
I actually think the company policy around paying out interest on client cash is fair...sort of.
This is what x-o state in their T&Cs:
"Interest accrued on sterling Account Money not immediately committed for investment shall be calculated monthly at 1% below the published HSBC standard current account rate"
That seems pretty reasonable.
Until you realise that HSBC:
Is it Jarvis' fault that HSBC don't pay interest on their basic account?
I held Jarvis Securities (LON:JIM) with an expectation that all client cash interest therefore went straight to the company - somewhere between 4% and 5% of the £227m customer cash balance - but with an assumption that HSBC would eventually increase their current account interest rate.
Now, however, I remain very wary about what is going to happen here.
Is the regulator also going to look into the wording used to describe HSBC's non-existent "standard" current account? What if it does indeed force brokers to pass on most of the interest income they generate? This latter point could be disastrous for a company like Jarvis Securities (LON:JIM).
So for now at least, I'll wait on the side lines until things are clearer. As you've mentioned it's a quality business, at least historically, and it does look very cheap right now. Hopefully if/when the company gets the all clear there will still be time to buy back in whilst the valuation remains relatively depressed.
Thanks again
A
Well so far it’s UBS 1 v 0 market………
Heavens above things must be good - even Ten Entertainment (LON:TEG) has finally broken up above the 300p mark……. Celebration bowling shoes all round in the Hill household
Home construction/goods looking decent. Since October, higher lows.
Unlike the Footsie All Share Index this year to date with it's ever-increasing lows.
It is only down about 1% YTD.
Any idea why the housebuilders are up strongly today? Is it because the UK economy has flatlined for the last 3 months, hence likely at the top of the interest rate rises?
US CPI at 1.30 GMT were better than expected, so expectations of sooner cut in US and UK interest rates . UK CPI out tomorrow.
Russell 2000 up over 5% today.Ocado (as its wont to act like a techie share) and suddenly rallied at the us open- ish and ended up over 10% up too.Was out gardening today.So still catching up!
Starting to see some asset managers perk up in the last couple of weeks. Some with improving volume. Quite like this as a way to play a market rally, with the option of holding longer term also.
Impax Asset Management (LON:IPX)
Liontrust Asset Management (LON:LIO)
Polar Capital Holdings (LON:POLR)
Foresight group (LON:FSG)
I know some people think charts are a waste of time but apart from 1 day in June today's the only time Premier Miton (LON:PMI) has been worth looking at in my opinion.
Timing coming up for Santa rally so the city can vote itself its annual bonuses for XMAS ?
Hi Paul
When convenient, what's happened to one of your old stock favourites Cambridge Cognition Holdings (LON:COG)?
Shares seem to have more than halved over the past 12 months.
ATB mate
Placing Ahoy Captain?
My post from 28th Sept repeated below. Whether management have been honest with us is not for me to say, but they did announce a contract win shortly after:
Cambridge Cognition Holdings (LON:COG)
Following on from my comments a day or two ago, I logged in to the results webinar yesterday, with both CEO and FD on camera.
Key points that weren't in the RNS:
They did refer to the share price reaction briefly, but did not seek to explain it. There were multiple mentions of contracts being delayed longer than they expected.
The subjective stuff? There was some glancing away to the side of the screen - either because corporate finance were there off the side or because some answers may have been pre-scripted. They didn't look entirely comfortable, but then this is a small cap, not an acting school. No live questions, but they didn't appear evasive either.
What still wasn't entirely clear at the end was whether the need to raise working capital was because the integration of the aquisitions had proved more cash consumptive than expected, or because of contract delays had left them exposed.
Any mistakes in the above are because I was cooking two children dinner while listening in....
Many thanks Monty Carlo. Great summary
With the FTSE 250 (MCX) breaking out over 18000 resistance a lot of my holdings have gone up between 5-10% today on the US inflation news, with UK CPI numbers out tomorrow and a few of the bigger inflation culprits to drop out from a year ago if I was sitting mainly in cash ( I am about 16-17% cash) I would be trying to decide whether to bite the bullet this afternoon. Its an easy decision to go to cash but an incredibly hard one to get back in to the market.
Good luck everyone.
I'd expect Georgia to be in the EU waiting list for as long as Turkiye if not longer. Not just the Big Bear next door to worry about but the influence of particular oligarch/s as the power behind the political front. The suspicious change in trading activities post Ukraine invasion and sanctions plus the large number of Russian citizens who have crossed the border, hopefully for the right reasons, all add to risk IMO. Great returns but look out for your capital if things go wrong. Why dabble in this crucible?
Has anyone got any ideas on Coral Products (LON:CRU) other than people getting bored, share price drifting so slow volume is all one way?
Only news was the update following the Cenkos merger acknowledging the broker name change, so it was not a new NOMAD preceding something drastic
Cheers
Tommy
There was a rather not so informative trading statement on the 27th of September , implying a softening in the second quarter.
Ex holder and a company that has saved me money in a bearish market the last couple of years.
I have exited around 17p after I have seen a video and the Chairman speaking on IMC.
Thank you Yiannos
Looks like we could be in for a nice US rally this PM with CPI data showing the US inflation Rate slowing,
Surface Transforms (LON:SCE) So they got a placing and open offer away yesterday evening, with £8.3m raised. It was well telegraphed by the team here, so well done. There is significant dilution and as the SP had already fallen a lot in anticipation, there was only a small additional discount to the prevailing SP yesterday.
I don't hold and am not rushing to get involved, but would love to hear other's thoughts on this now that it seems funded. I'm reluctant to preface the word funded by the word fully!
Definitely a good case study of selling immediately when there is a profit warning (and statements around raising additional funds). The Surface Transforms (LON:SCE) only fell to 16p after that announcement, and drifted down to c12p, before this 10p fundraising announcement.
So even if you intend to hold long term, it would have made sense to sell immediately at 16p, to be able to buy back in shortly after at 10p.
For what its worth, I am gobsmacked that management took so long to figure out they don't have the manufacturing operations chops and didn't beef up that capability. It seems like now they have, hopefully, with a COO. And there has to be a light at the end of the tunnel, in terms of getting a manufacturing capability and process to its run-rate potential? Its not rocket science.
At least the Demand side is covered - plenty there. Just need to get the Supply side sorted. Many companies would kill to have this problem - as supply is fully within your control, whereas Demand is usually not! (think Boohoo (LON:BOO) as an example - despite all their work on warehousing, range, etc - they will struggle if Demand falls because of huge competition and lack of consumer spending power).
(I hold in the Boon Fund)
I've taken a punt on 50,000 shares
Re Jarvis
Over the last few years many online brokers appear to have been tweaking the business plan so that more revenue comes from platform fees whilst reducing transaction fees. Jarvis seems to be like the early IWEB where it has low transaction fees and no platform fees.
As stated, another way for Jarvis to make money is a return on client's cash balances. If this is the major revenue for Jarvis then in theory it will be harder hit by the FCA investigation than online brokers with platform fees.
I would also guess that the number of private client transactions will be declining in the current environment so a further potential headwind.
Some brokers also make money on heavy currency charges when investing abroad. If Jarvis don't have the ability to trade beyond the UK markets then this final revenue stream will also be denied.
From a Marketing standpoint Jarvis doesn't seem to have much of a presence in Google searches. If you didn't know that its trading site was X-O then it would be hard to find. Also the corporate website seems to be old unsecure www? Firefox blocked this - hence denying further online visibility.
Never used or invested in Jarvis, but it looks like a small private client broker who has to compete with the considerable marketing firepower of the likes of HL. It should have a niche in the market but might have to work differently in the future.
The hint that the FCA deem paying deposit interest to clients is 'fair' and thus should be done sends a shiver down my spine - yet another regulatory over-reach. It should be none of their business, just that of broker and client. I suspect there will be the normal unexpected consequences. For e.g. personally, I don't like being paid interest because 40% of it is confiscated by the government when not paid on a SIPP or ISA account. The government give me nothing back on platform charges or commissions of course. Much better to receive lower platform and commission charges but no interest.
It probably makes more sense if viewed from an FCA perspective rather than a customer perspective.
It's an easy gig for the FCA. No difficult investigation to undertake. Just take a broad brush to the subject of cash balances and claim a "success" on behalf of the consumer.
Thank you for your appraisal warts and all of JIM Graham, we hold and being a frequent in for a penny in for a pound investor (I know, haven't I learned anything?!) it's not going to cost much to add a few more.
I think the risks on Jarvis Securities (LON:JIM) are a combination of costs/ management time re 166, potential FCA fine, potential remediation (payment to clients for lost interest) and bust business model. I can’t see that any of those are off the table so I can understand the market reaction. Not one for me at the moment.
I guess does that mean as someone who uses IWeb am I suddenly going to get a nice interest payout? As they are low fees, but no interest, which was great in the last few years of no interest world 100% invested, now in the higher interest world, but not 100% invested need to get my finger owt and move!
Interesting snippet in BBC report on Chancellors Autumn Statement -'He could launch a combined cash-and-shares Isa to encourage more investment in the UK stock market.'
Would be welcome to support UK companies. Could he though change ISA eligibility as part of this?
https://www.bbc.co.uk/news/bus...
Hi Paul, Really enjoyed the weekend podcast. Some very useful things to ponder in what you call the “rambling”. Many thanks
Oxford Instruments (LON:OXIG) looks good to me. Robust performance despite the current slump in semiconductor orders. When that mean reverts, shares should be worth a lot more. Price was 40% higher a mere 4 months ago and the fall is just sentiment-driven rather than operational. Not forgetting that a bid was only withdrawn last year when Russia invaded Ukraine. And they are swimming in cash for M&A of their own. Risk/reward/liquidity/quality all attractive - what’s not to like?
Might just be anticipation of recovery but I notice Asset managers in small cap space are starting to rally. They are probably a leading indicator so perhaps there will be legs to a recovery over next few months…… just musing
I concur , a nice blue colour hitting my recent Asset Managers purchases ...there must be consolidation at some point - I wont get too excited
I think if I hide some columns which are not needed by everyone it might work. I will try and refine it. If it doesn't help anyone, don't worry I will stop the experiment. Be patient.
On a laptop I can see all the hidden columns by moving the slider at the bottom to the right.
On my desktop too, using Chrome.
Bear with me, I am trying an idea. I am going to attach a document which is a Google sheet based on some of todays RNS's. It is intended to give a heads up to those who don't review the RNS's daily. Hopefully it is self explanatory. Just an idea which may or may not work, but if we don't try etc etc.
Good idea but it does not fit on my screen, so difficult to read as have move across to see the columns on the right.
Too many RNS on my news feed, many I don't even hold.
Hi cafcash, like yourself I'm full of ideas, retired so have time to paly with them. Your idea though must surely be followed daily resulting in sheaves of info relevent to the date of published RNS. I scribble on scrap A4 and include any other sources, for instance comments in the SVCR noting possible Buys (or Sells with purchased price against them). Then after a few months I check outcomes, the last check resulted in 5 companies that would definitely have been worth buying into and 17 definitley not. The conclusion I came to is that I should stick to gut feeling or go down the well a la Paul and disect the company accounts with a fine tooth-comb.
Silver
Hi Silver Moon, thanks for your interest. I think I could be making a rod for my own back by publishing here. I was writing down notes on paper re RNS's then I progressed to a Google sheet which is much easier to track and go back to. I have tracked a lot of things on Google sheets one being the recommendations of many commentators. It is very revealing that some contributors have a good record and some have a very poor record. I am a 49'er and spend far too much time at this game but it keeps me occupied and the brain functioning. My farmers wife Grandmother used to bow to the new moon and twist her wedding ring, but it musn't be seen through glass!!! Happy memories. If you want to share stuff my e Mail is charles@woodlandswitney.co.uk
Vesuvius (LON:VSVS) was nicely moving up until todays in line trading statement. so ive exited that trade for now for a small loss. long term still could be a good one though so will keep an eye on it.
I’m new to this. Why is it going down if trading was inline? It makes just no sense to me.
the market looks forward. so traders will exit and look for better opportunities or cut losses like myself. if it had beat market expectations it would likely of gone up by a similar amount
I see Braemar (LON:BMS) (I don't hold) will finally publish its FY Feb '23 results on Thursday a very long time after the shares were suspended on 3 July 2023. That huge period of time makes me think avoid the company at all costs but then it also does look pretty cheap having been sold off ahead of the suspension. Plus I suspect there will be some shareholders who have had enough and will want to ditch their shares when the shares are trading again which could create a further spike down in price. So I am debating whether there could be a quick trade. Any other views?
I think they will be worth a quick trade. These lengthy suspensions are sometimes technical, caused by an acquisition, and lengthy because the auditors can not afford to make another error. Apart from the audit cost the Company seems in good health. I have seen leaps in similar situations - Carrs and Alpha Financial spring to mind.
I am still holding Braemar (LON:BMS) and will review accounts with interest. As an ex-Statutory Auditor I know what happens when a restatement happens and it goes back years. Thankfully, I didn't have many on my clients! It does take time, particularly if there are some questionable transactions as was the case here. Hopefully they will draw a line under this fiasco, but lets see what the annual report says first. Clarkson (LON:CKN) are a better company, but this is cheap. Lets see what Thursday brings but the shipbroking business here is good and worth a minimum of £100m, and probably a fair bit more.
Totoise, I think it is doubtful that holdings will be ditched, the reason being that an interim dividend of 4 p/share (say 1.4%) is proposed which to me clearly shows light at the end of the tunnel. I hold Braemar (LON:BMS) and being underwater am likely to make a quick trade in the opposite direction as Berksbee anticipates.
Braemar (LON:BMS)
Hi Silver Moon , the FY23 dividend of 8p is yet to be paid, so as long as both that and the FY24 interim divi of 4p are agreed there is 12p to be had in fairly short order so I can see punters buying rather than selling .
http://newsfile.refinitiv.com/...
But how many times have we seen the SP dive on the day the share goes ex divi - It rarely pays to hold onto a share just for the next divi
Isn't the full year dividend 8 pence? making the final dividend the same as the interim? Must read the announcement again.
Braemar (LON:BMS)
Silver Moon,
No the final divi of 8p for FY23 which ended Feb 23 was declared but not paid because of suspension. The 4p divi refers to the interim for FY24 ( the current year).
bohenie,
Yes theoretically any SP should drop by the amount of the dividend when it goes XD , but that does not always happen in reality.
Hi Helvelln, I re-read todays RNS:
"The board intends to reconvene the Annual General Meeting of the Company on Monday, 18 December 2023, where a final dividend for FY23 of 8.0 pence per share (FY22: 7.0 pence) will be proposed. Total dividends in respect of FY23 will be 12.0 pence per share, a 33% increase over the previous year (FY22: 9.0 pence).
The Group will seek a restoration of trading in its ordinary shares on the
London Stock Exchange following the publication of the FY23 results and filing
of the 2023 Annual Report and Accounts."
Ah yes, the 4p Interim was paid last January so you are quite correct and I am all the better off for that. Kudos!
Silver
Croma Security
Seems to be getting a bit of a rerating .
Still cheap
Fagpscket
1 million ongoing profit from operations
2 million cash (bit below I think )
Good little business
Incentivised management .
Balance sheet stuffed full of freeholds .
Simple strategy or buy and build bolt ons where mom n pop shops are added on pretty much at freehold price
Those numbers easily justify market cap
The added “bonus ball” is the 5 million deferred consideration from the security division just sold off which is payable in next 3 years. You could argue on the bear side it’s not in the bank till it’s in the bank .
I reckon this will continue its strength up to 75-80p then go sideways for a good while .
Finally market seems to be showing a bit of interest , never was anything wrong with the company just a bit small .
Good point re deferred consolidation which I had missed before but on what basis do you say Croma Security Solutions (LON:CSSG) is cheap? EPS was 2.5p normalised in the most recent financial year which doesn't make the share look particularly cheap.
Looks cheap to me
The EPS this year is not that relevant as it was a year they sold off the security division so you need to look at the stable business that is left .
Ongoing businesses
- 1 million profit I think conservative
- asset value is covered by freehold (I think)
- 2 million cash (bit less )
- 5 million deferred consideration
That looks cheap to me, if you could buy a freehold house for 8 million quid and it had 2 million quid in the cellar , 5 million quid in an outhouse that you might find in next 2 years . , and every year you rented a room for a million quid x and at the house was still an 8 million quid house
I would live there quite happily .
Okay thanks - I will go away and look at the profitability of the remaining business. The strategy seems clear so that is attractive.
Planetx: I watched the Croma video yesterday, not knowing quite what to expect. My notes...
From webinar…. Sold biggest (low margin) 1000 staff guarding Vigilant division. Main growth opportunity is acquiring 2-3 /annum cheap family locksmiths businesses, (with T/O approx. £0.5M/each), with the aim of becoming a niche nationwide network. Claims to have no competition in acquiring the locksmiths. Able to add on the electric security division products. Croma offer improved centralised services, retail and software advantages. Should benefit from operational gearing. CEO says next update will have, “encouraging news”.
I was pleasantly surprised and will accumulate.
Morning all, I took a look at Cake Box Holdings (LON:CBOX) results this morning. Here's a quick snapshot. I make these for myself to keep track of companies I follow, though thought it may be useful to some on here as well. A decent set of results I think, pretty much in line. Looks like they are getting back on track with decent growth in the bottom line and continued demand from franchisee's for new stores.
Great post, Phil P. Cake Box Holdings (LON:CBOX) is of no particular interest to me but this is a very good contribution and I am sure that it will be really useful to quite a few on here.
Thanks DaviStoVest, that's good to hear. I produce these for any companies that are on my watchlist, so I'll upload any that are appropriate to this forum (many are large cap or US based). I forgot to say I hold CBOX.
Don’t fret over large cap or US. Or just a heads up here to look in discussions. Personally hot sectors commodities defence cyber.
Hi Phil,
Thanks, I really like your concise format for summarising results, really excellent actually!
Yes please for more of these posted here :-)
Best wishes, Paul.
Hi Paul, thanks for the feedback! No problem, I'll post any relevant ones from now on.
Avingtrans
Carrying on from yesterday someone commented that profit had halved .
I’m pretty certain that wasn’t the case and the drop related directiy to acquisition of adaptix .
Will try to check today if get time
Morning planetx
Avingtrans You are right. The reduction in forecasts relates to the Adaptix acquisition. See extract from the Cavendish broker note of 27 September below.
"(LON:AVG) We update our forecasts for the recent acquisitions of Adaptix and Parr & Slack, with the consolidation of Adaptix operating losses reducing adj PBT by 73% to £2.3m and development investment moving the group into net debt of £7.3m (from net cash of £6.9m) in FY24E and to £15.0m in FY25E. Underlying trading forecasts are little changed, except for higher interest costs associated with the move into debt."
Amazed at the lack of appetite for Bank of Georgia (LON:BGEO) this is a business with an ROE of 30% and a dividend yield closing in on 10% trading on a PER of 3!!!
It’s not like it is a NIM dependent bank either. Has a strongly growing payments business and good quality loan book with strong digital offerings in an economy with gdp growth exceeding 6%.
You’d think it would trade on at least 6* PER…..crazy imo
Agreed, and can only assume many do not want to own any assets near the Ukraine/Russia theatre
It’s a very leaky border between Georgia and Russia hence Georgia’s outperformance from countries actually sanctioning Russia. There is a large Russian population too in Georgia, this makes this a risky asset.
This has been known for years. Nothing new. Do you really think it is a riskier asset than say SVB that was much larger but based in the U.S.? Or NatWest and its political fall out? Id argue it’s probably a less risky asset than businesses people perceive as low risk. Georgia is also going to be given EU candidacy in December this year so is moving much closer to EU status.
Ive had way more in dividends than I paid for Bank of Georgia (LON:BGEO)
David
I’m with you on bank of Georgia and Georgia capital .
The world feels a bit unstable right now and as I am on an investment level 70% uk invested
I would argue Georgia exposure to a fast growing economy and my other exposure in Java is a good counter to being “overweight” on UK
Especially after the political nonsense going on right now (yes I know this is not a political debate forum) .
Ultimately Bank of Georgia and Georgia capital both look exceptional companies on some very attractive valuations in an economy albeit with geopolitical risk that is one of the best performing .
Given EU candidacy? I would think Russia would invade as it cannot tolerate another potential NATO member on yet more of its border. Perhaps this is one of the reasons for the low valuation…
I think that we have to look that there has been a really good run so far with Bank of Georgia (LON:BGEO) and obviously the related Georgia Capital (LON:CGEO) so far this year, I would figure this is a pull back and just to sit tight for the moment. There has been a lot of shares do this in my holdings, run up to the results then drop back if they don't have a big beat.
There are clearly things which some investors would not openly take for risk such as emerging market status, country stability is not understood by the average person, next door neighbours people will have their views on would they live next to them and general lack of knowledge regarding the country and region. I would ask how many folks if given a blank map could put their finger on Georgia? Or know anyone from Georgia? Or have been to Georgia?
So I am positive, I hold both Bank of Georgia (LON:BGEO) and Georgia Capital (LON:CGEO) in my holdings, but not the family ones.
Good luck!
Tommy
I’ve been to Georgia it’s a stunning country with fantastic food and people. They have a big Russian population and many close ties. A very leaky border with a lot of fuel coming to market in Europe through it. Just an observation I was putting out there.
There was a helpful article in the FT on Nov 11th - search for "EU and Russia square up over Georgia".
Then decide if you fancy Bank of Georgia (LON:BGEO) on 1.18x book value, or Barclays (LON:BARC) on 0.3x book....(I'm just quoting Stocko numbers, I'm sure adjustments should be applied).
I'm not going to comment on political stability....boulders and glass houses, Cameron/Cameroon and all that.
I’d buy Bank of Georgia (LON:BGEO) all day over Barclays (LON:BARC)
One has a ROE of 30% the other…… er well………….probably best not to look. It’s a basket case in my opinion and that’s the reason it trades on 0.3* book.
Barclays is inherently more risky a business as it has a large investment bank and assets that make up book value are difficult to assess. A small change in the real market value of those assets can make a massive difference as to how much equity genuinely exists.
Very different businesses and in no way would I compare book value ratios in determining which to buy.
Hi David,
Bank of Georgia ‘s market cap is about 12% of Georgia’s GDP. The valuation does not make any sense if you compare it with what the country actually produces. Valuation is crazy even if the actual numbers look cheap.
Georgia has seen an amazing foreign investment the last 10 years and all these deposits have to be lend out to locals-seen exactly the same thing in Greece , Cyprus , Portugal , and Ireland. We all know what happened at the end to their banks,
Also we have no idea how the Central Bank of Georgia deals with Non performing loans-very important:
Just a different view but based on facts and history.
Good luck to all holders but this is not for me-UK banks all the way for me(especially if they fall another 10-20%).
Thanks
Sigh....We all know it is apples & pears.
I was making a broad point that we should not be surprised, rather than trying to persuade people of the merits of Barclays (LON:BARC), even if I do believe that a resurgence in fixed income activity should benefit BarCap going forward.
It is just that UK banks in a tried & tested prudential regime are also very cheap on any valuation measure (which basically means we don't trust the book values), so it should be no surprise at all that a bank in a country that is partly occupied by Russia / separatists sympathetic to Russia with some troubling political trends is trading cheaply.
I would add Iceland to yiannos1's list of infamy as well.
Billington and Castings
Two cracking companies putting out lovely results .
Billington in particular just looks the wrong price, fundamentals now look nuts, making 10 million a year with 15 million cash, huge assets and 40 million valuation .
That’s a sitting duck target at those levels though whst an acquirer can buy it for
Castings looks good too .
More upside on Billington though Castings dividend is very good .
Billington jumped to 360 from 320 level on opening still looks interesting .
I do agree with Billington ; the price should have been north of 450p.
Same opportunities are : McBride plc , Nanoco plc , On the Beach group plc, Aeorema plc - all of them are the wrong price.
Jarvis Securities (LON:JIM) As mentioned yesterday, it would be good to see Grahams comment on the news yesterday (no dividend and FCA review). I thought I'd get my request in early today! ATB. Bristolian.
Jarvis Securities (LON:JIM)
Yes please, would be great if Graham could look back at this update from yesterday afternoon.
Jarvis Securities (LON:JIM) Thanks Graham, you've covered all the angles there I think. JIM are my broker and I bought a decent size back in 2016 when the market got it wrong. I've taken advantage of their DRIP to buy a compounding holding over these years and looked on it as a lifebelt to insure against my more speculative holdings going wrong. I hope this little air leak can be patched, I still have faith in the management.
The skilled person review at Jarvis Securities (LON:JIM) is looking at the treatment of uninvested cash...
If they are not segregating and labelling client cash correctly then the fines can be horrible. One major asset manager took a big fine some years back because they labelled properly segregated client cash with an internal ID that could have delayed the return to clients if the asset manager had gone under.....
My morning smallcap tweet: The Flak of dawn
Gear4music (HOLDINGS) (LON:G4M) Fonix Mobile (LON:FNX) Beeks Financial Cloud (LON:BKS) Fintel (LON:FNTL) Billington Holdings (LON:BILN) Byotrol (LON:BYOT) DP Poland (LON:DPP) Kanabo (LON:KNB) Rotala (LON:ROL) Revolution Beauty (LON:REVB) Castings (LON:CGS) Allergy Therapeutics (LON:AGY), Cake Box Holdings (LON:CBOX)
◄Gear4music (G4M)► H1-Sep rev down 6%. Pretax loss £1.9m (£1m). Cuts FY rev guidance to £144m as it focuses on margins but profit in line. [SP=118.1 Cap=25m]
◄Fonix Mobile (FNX)► AGM stmt - trading comfortably in line with expectations. [SP=192.27 Cap=192m]
◄Beeks Financial Cloud (BKS)► wins $1.3m+ 3 yr contract. [SP=104 Cap=68m]
◄Fintel (FNTL)► two acquisitions. Trading in line. [SP=207 Cap=215m]
◄Billington (BILN)► guides FY-Dec rev and pretax ahead of market expectations. [SP=320 Cap=41m]
◄Byotrol (BYOT)► post CEO departure review leads to co warning H1-Sep rev only flat at £2m and EBITDA loss £0.45m (£0.3m). Blames impact of discontinued items (due to expected regulatory changes and to reduce complexity). Guides FY rev £3.9m (£4.3m or £3.7m excluding discontinued items). Cash is tight "but is sufficient to finance current operations" with cost cutting [SP=0.86 Cap=4m]
◄DP Poland (DPP)► Q3 Total System sales up 7% and 14% LFL, down from prev Q growth. Oct strong at up 33%. CEO excitedly comments "It's fantastic to see the business begin to capitalise on the potential of the markets we operate in, but this is only the beginning, and we expect performance to continue improving". [SP=8.5 Cap=57m]
◄Kanabo (KNB)► contract extension for its online telehealth platform, The GP Service. Client is a "leading UK retail business, a provider of health and beauty retail and e-pharmacy services". [SP=1.2 Cap=8m]
◄Rotala (ROL)► PUSU offer deadline extended to 12 Dec. [SP=56.25 Cap=18m]
◄Revolution Beauty (REVB)► H1-Aug rev up 20%. Pretax £0.4m (-£13.7m). Current trading in line with internal forecasts. Material uncertainty going concern stmt. [SP=27.65 Cap=88m]
◄Castings (CGS)► H1-Sept. Guides FY marginally ahead of market expectations. [SP=378 Cap=164m]
◄Allergy Therapeutics (AGY)► Phase III trial to evaluate efficacy and safety of hayfever vaccine meets primary endpoint. [SP=1.49 Cap=71m]
In line: CBOX
Morning. Revolution Beauty (LON:REVB) . Company states "Strong improvement in EBITDA, up £14.3m, due to higher sales volumes, gross margins and cost reduction initiatives." There appears to be some nice momentum in this business despite all their issues with previous managements "wonkiness".
Company outlook: "While the crucial Christmas trading period is still to come, the Group is upgrading its guidance for the full year and now expects adjusted EBITDA to be not less than double-digit millions for FY 24 (an increase from the previously guided high single digit millions)."
I hope Paul or Graham have time to take a look even though I understand they may want REVB to build up more of a history post new management starting. It's a recent new purchase for me and I will be looking to add. I believe the weakness since it relisted was due to legacy holders aggressively ditching, Chart looks good now though. Thanks
But their statement states a material uncertainty.
First thing I noticed in the recorded presentation was that cash has increased by a further £4m since the end of H1 in August to £12.3m (as at 10 Novemmber)
Agree - it's all about funding here. When you look at the period cash did reduce but that include c£12m of one-off fees (supplier and legal). Hopefully this is not likely to repeat which meant they would have been cash generative. The move post period highlights this I believe. If their outlook is delivered that will likely pay off a lot of their o/s debt balance, so 2024 should be good. The only question I have is the £20m medichem debt which is due 2025. Whilst that's >12 months away they will need to fund that payment - hopefully it will come from funds via operations if performance continues.
Thanks for everyones reply, it's given me a lot to think about. Hopefully they wont need more funding if trading is good but with Boohoo a big holder and heavily involved, if they do I'm sure they'll be able to get it (even though I recognise Boohoo have their own issues at the moment)
This is exactly what you were saying in your podcast Paul, Bloomberg stealing your material:)
"The UK is probably already in a recession, Bloomberg Economics analysis suggests, as soaring interest rates and rising unemployment make people more cautious with their spending. Dan Hanson breaks it down"