Small Cap Value Report (Tue 15 Aug 2017) - RBG, CGS, MNZS, MMH, ALY

Good morning, it's Paul here!
I have a diary note this week, written this time last year, advising the future me to book a holiday this week, as it's usually very quiet for results & trading updates. Accordingly, I'm jetting off to Spain tomorrow, just for 4 nights, having found a deal for only £300. Our Graham has very kindly offered to hold the fort here, so that I can relax on the beach for the rest of the week.
I'm hoping that newspaper reports of 8 hour delays to check passports at Barcelona airport may be false. It amused me that right-wing newspapers reported that the delays were due to industrial action. Whereas pro-remain journalists reported that the delays were deliberate punishment by Spain for the UK having voted for Brexit!
It all reinforces my belief that human beings are fundamentally irrational, and simply believe what they want to believe. That creates wonderful opportunities in financial markets, as many shares are frequently priced wrongly due to investors being so irrational.
Talking of which, the situation at Revolution Bars (LON:RBG) has just got a bit more interesting today, so let's start with that.
Revolution Bars (LON:RBG)
Share price: 181.6p (up 4.4% today)
No. shares: 50.0m
Market cap: £90.8m
(at the time of writing, I hold a long position in this share)
Merger proposal - there are 2 announcements relating to RBG today. The first RNS was issued by another company, Deltic Group, suggesting a merger of their company with RBG. That was followed by a response from RBG, which I will cover below.
Deltic Group is the phoenix company which rose from the ashes of overly-indebted nightclub operator Luminar, which went bust in 2011.
Deltic starts off its announcement today by describing itself like this;
Deltic (http://delticgroup.co.uk/) is the leading specialist late-night operator in the UK. Since it was acquired by its current shareholders out of the administration of Luminar plc, its predecessor firm, in 2011, management has refurbished the majority of its estate of 57 clubs, including those operating under the PRYZM, Bar&Beyond, Steinbeck&Shaw, ATIK, and Fiction brands.
It is a highly cash generative and growing business of similar size to Revolution, its major competitor in the UK late-night market. Trading at Deltic continues to reflect confidence in the late-night market and its future prospects.
My sector expert has texted me to advise that Deltic is a hot-potch of brands, with no focus!
I've had a look at Deltic's last filed accounts at Companies House, with a few key points being (this is for the 364 days ended 27 Feb 2016 - the most recent filed accounts);
Revenue £100.8m (RBG was £119.5m for y/e 30 Jun 2016)
Underlying EBITDA £13.4m (RBG was £15.6m)
Underlying operating profit £8.6m (RBG was £9.2m)
So at the P&L level, they look quite similar.
The balance sheets are very different though. Deltic only had net assets of £10.3m, whereas RBG had net assets of £41.2m. RBG has a net debt-free balance sheet, whereas Deltic is carrying a fair bit of debt, which incurred an interest charge of a hefty £4.0m for the year (including a shareholder loan charging 8% p.a. interest).
Therefore, if RBG were to consider a merger with Deltic, it would need to value Deltic's equity at a much lower valuation than RBG's equity, to reflect the considerable debt which Deltic is carrying.
Furthermore, note that Deltic is revamping its sites, thus requiring heavy capex (of £8.6m). Although it does say that most sites are now revamped. Whereas RBG has a fully revamped estate, so requires less maintenance capex - most of RBG's capex relates to new site openings.
The other issue with Deltic, is that its sites seem to be larger than RBG sites, so probably require heavier capex when they need (frequent) refits. The company does however look for a 2-year payback on capex, which is competitive.
Going back to Deltic's RNS today, it sees the Stonegate 200p cash proposal as being opportunistic (which it is!);
Revolution's recent poor share price performance resulted in its 31 July, 2017 announcement of the possible and opportunistic offer by Stonegate Pub Company Limited ("Stonegate") to acquire the entire issued and to be issued share capital of Revolution at 200p per share.
Deltic believes that if a firm offer by Stonegate is made, and is recommended by the Revolution Board, it would be a disappointing outcome after two years of roll out and investment to merely return to its shareholders the same value of the business as at its 2015 IPO.
I think those are absolutely valid points. My view is that the Stonegate offer is not at all generous, if you crunch the numbers. The key point is that Stonegate would be able to eliminate as much as 60% of RBG's central costs (an estimate by a well-respected research firm). Plus it would be able to considerably boost RBG's profit margins by renegotiating drinks supplies at cheaper bulk discounts, and I think also would be able to make staff savings through pooling staff.
Plus of course, RBG has a well-progressed pipeline of new sites on terrific rents, which provides it with 4-years worth of self-funded growth - which would considerably increase its future profitability. That's thrown in for free, with the mooted 200p bid from Stonegate (which is not a formal proposal as yet, they're still doing due diligence).
Deltic then goes on to say that a merger with RBG would create synergies, and be a larger group which might interest stock market investors more. There's some merit in this proposal, in my view. The sting in the tail is that Deltic management want to run the enlarged group!
In a nutshell then, the Deltic proposal to RBG is this - please buy us, using your stock market listed shares. Then we'll kick out your management, and run the enlarged company ourselves! I can see why RBG management wouldn't want to progress that idea. Hence why Deltic has today gone over their heads and appealed to RBG shareholders direct.
Another worry is that a merger which is structured as Deltic shareholders receiving RBG shares, would create an enormous overhang of sellers. It could be seen as Deltic shareholders seeking an exit route by the back door. That could then result in the RBG share price being almost permanently depressed from selling by former Deltic shareholders.
Response from RBG - they've given the Deltic proposal fairly short shrift in this announcement today;
The Board confirms that it received a possible proposal from Deltic and thereafter met with Deltic. Based on these preliminary interactions, the Board had concerns over both the value and deliverability of the combination and did not see any merit in progressing their proposal as the Board believes that a combination of Revolution and Deltic is not in the best interest of shareholders at this time.
The Company continues to engage with Stonegate Pub Company Limited in connection with the possible offer, as announced on 31 July 2017.
I find this rebuttal a bit weak. If I were a major shareholder in RBG, I'd want to know specifically why the proposal was turned down?
It sounds as if the Stonegate approach is likely to result in a formal bid fairly soon, would be my guess. They've had enough time to do due diligence now. Maybe they're arguing over price? It would be rather difficult for RBG management to recommend a 200p bid, given that was the IPO price in 2015. A 200p bid suggests that RBG management has added no value at all in their time as a listed company - not something I would want to explain to shareholders, if in their shoes.
My opinion - the Deltic proposal probably won't work, in my view. I think Institutions would probably prefer a clean exit, for cash. Deltic doesn't seem to be in a position to be able to fund a cash bid for RBG, which is the only serious alternative, so I doubt the merger proposal as it stands would be progressed.
However, the positive thing is that a second potential suitor emerging has reinforced the attractions of RBG to a trade buyer. The stock market has consistently failed to grasp that RBG is a decent quality business, with good growth potential, generating bucket-loads of cash to self-fund its roll-out. So it's encouraging that more than one potential trade suitor is circling the company.
I think there is potential for Stonegate to improve their possible offer, so personally I'd be disappointed if the company sells for less than 240p. So hopefully another, more credible (than Deltic) bidder, might emerge in due course, to force up Stonegate to a higher price?
Personally, I accept the downside risk of bid(s) falling through, as I believe RBG is worth more than the current share price anyway, bid or no bid. So there's maybe 40p downside risk (in the short term), but longer term value with or without a bid is potentially a good bit higher than the current share price. An interesting situation, let's see what happens!
Castings (LON:CGS)
Share price: 461p (down 0.3% today)
No. shares: 43.6m
Market cap: £201.0m
AGM statement- this is a successful UK-based iron casting & machining company. Given its sector, I've always been surprised at how profitable it is - as it's the sort of thing that I would've imagined could be made by overseas companies more competitively. Apparently not!
This company is also noteworthy for its excellent balance sheet.
Its update today doesn't really say a lot;
Demand from our main customers remains steady which represents a continuation of the outlook reported in the Chairman's statement in June.
Our efforts remain focussed on developing work with both existing and new customers, with a concentration on core business that can be produced and machined within the group.
We continue to invest in production techniques and technologies to improve our productivity and profitability.
That seems reassuring, so I think can probably be interpreted as in line with expectations - even though it doesn't exactly say so.
Valuation - whilst I admire the business, and its balance sheet, I don't see any particular upside on the current valuation - this looks about right;
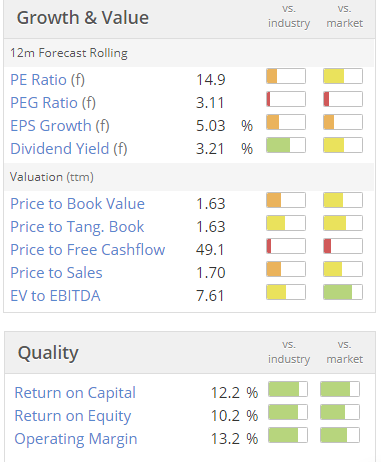
As you can see from the Stockopedia graphs below, revenue and profit are essentially going sideways, to slightly down, in a zigzag fashion.
Meanwhile, the valuation on a PER basis has been steadily rising, and the divi yield reducing. That doesn't sound particularly great to me;
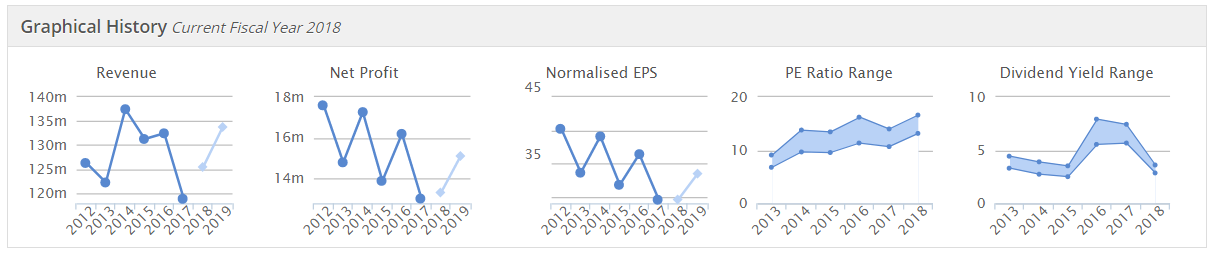
My opinion - this is a good quality company, but I don't see growth here. So a PER of 15 for an ex-growth company? That isn't really attractive to me. It's the sort of share that I would have on my list of things to buy on a profit warning - as it would probably recover, and has a bullet-proof balance sheet.
John Menzies (LON:MNZS) - I've had a quick look at today's interim results. Underlying operating profit is up 43% to £30.1m, although a fair bit of that is due to favourable forex movements. At constant currency the uplift reduces to a (still good) 26% increase.
The trouble is, this profit is a wafer thin margin, on H1 revenues of £1,217m. That's an awful lot of activity, just to make £30m profit.
The interim divi has been raised just over 10% to 6p, but the full year yield shown on Stockopedia is unremarkable, at about 2.8%.
I like the outlook comments, which sound upbeat, concluding;
Overall the Board is confident with the Group's outlook for 2017 and we are firmly on track to meet the Board's expectations for the full year.
That sounds as if there could be an earnings beat, if H2 continues to do well.
My opinion - I can't get excited about a low margin business, in highly competitive markets. Also, bear in mind that the balance sheet is hideous here - with a huge amount of debt, and negative NTAV. There's a pension deficit too. So a thumbs down from me, I'm afraid, not my kind of thing at all. Although it does sound as if the company is trading reasonably well. So if you don't care about balance sheets (many people don't, in bull markets), then it might be worth a look.
Marshall Motor Holdings (LON:MMH) - another one where I've only done a quick skim of the figures. The results look good, and the forward PER seems to only be 5! Car dealers generally appear very cheap at the moment, this one particularly so. The stock market seems to be anticipating a fall in future earnings. Maybe we could be at the top of the cycle for earnings, I don't know.
As with other car dealership chains, this one has plenty of freehold property on the balance sheet too. So it might be worth a closer look, if you are relaxed about the potential for Brexit to disrupt trade. Also there seem to be increasing worries about consumer spending generally, at the moment.
I'm tempted, but have decided to steer clear of car dealers for the time being.
STOP THE PRESS! BREAKING NEWS!!
Laura Ashley Holdings (LON:ALY)
Share price: 8.9p (down 19% shortly after intra-day profit warning)
No. shares: 727.8m
Market cap: £64.8m
NED resignation - I noticed that a NED resigned with immediate effect 5 days ago, which I thought was odd. Well, it looks as if she probably jumped ship because of the bad news which has just been announced:
Profit warning - issued at 13:30, during market hours - which is incredibly annoying & unfair for shareholders. Although I believe there is a stock market rule that price sensitive information has to be released immediately. Something like that, anyway. Surely a sensible company would hold the Board meeting to consider such information after market hours, thus enabling them to inform that stock market at the correct time - i.e. any time the market is closed, basically.
The most important bit says this;
...as previously disclosed, trading conditions have continued to be demanding.
The Board of the Company therefore expect net pre-tax profits for the year ended 30 June 2017 will now be materially below market expectations.
Stockopedia is showing broker consensus of 1.2p for the year in question. So materially below that basically means 1.1p or less.
There's also a £2.8m impairment charge announced today, on the huge office block in Singapore which this company bought, in a bizarre move some time ago.
My opinion - I would need to see the numbers, before forming a firm view. They are going to be released next week, on 23 Aug 2017 - so I'll crunch those numbers on the day.
Graham wrote an excellent section on ALY here on 2 Jun 2017, raising concerns about the share, particularly corporate governance issues.
I visited a store a few weeks ago, and thought the product was seriously over-priced, and a lot of it was just rubbish. So it's no particular surprise to hear that the company is finding trading difficult.
Mind you, with a market cap now only £65m, who knows there could be speculative upside here? Maybe the Malaysian shareholders will take it private? Trouble is, there's no guarantee they would pay much (if any) premium. Someone else might try to buy the business - does anyone have Mike Ashley's phone number, perhaps we could go binge drinking with him & tempt him into buying it!
With consumer confidence apparently waning, and internet competition growing, I wonder if ALY could be sliding permanently downhill? Overall then, I'll look at the figures next week with an open mind, but am not tempted to catch this falling knife at the moment.
Hooray, I've actually managed to finish a report by the 1pm email deadline!
Best wishes, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

45 comments
On the subject of Revolution Bars I have to say that I found yesterday's merger proposal from Deltic utterly bizarre. Who would ever wish to merge with an indebted unquoted nightclub operator that has been in administration once before? This proposal is worthless. I took the opportunity to sell my holding in RBG yesterday as the risk/reward looks unfavourable to me. If Stonegate bids at £2.00 I think that is likely to cap the upside since the share price of RBG has consistently told us that the City is wary of the company and that a rival offer looks unlikely. If they walk away I think the downside is greater than the 40p that Paul suggests. Remember that this company has been through three FD's in a few months and one profit warning. None of the directors bought shares when the price was decimated by a relatively mild warning and we all know how operational gearing can work in reverse in an economic slowdown.
It is also worth considering the implications if Stonegate walks. After all, on the face of it, RBG looks like a self-funded roll-out of a successful format with good cash generation. If this proves not to be the case then all bets are off. Remember that RBG was born out of a less than successful bar operator. I hope that the bid goes through for the sake of patient holders but I am simply relieved to have escaped a potentially nasty situation with a small profit.
Revolution bars have been a round for over 20 years....
I agree that its unlikely to be take private again as it was floated around the £2.00 mark - however I think its an attractive business that didn't need to be bought out to be a profitable share.
Indeed they have been around for 20 years and from time to time they have produced nasty profit warnings. If you search for 'Inventive Leisure' you will see one in 2003 (around the same time as Deltic was warning on profits under the guise of Luminar before going bust in 2011). Revolution Bars is a re-incarnation of Inventive Leisure with 'cocktail' rather than 'vodka' bars.
Thank you Paul for your review of Laura Ashley Holdings (LON:ALY), balanced as ever. Have a great holiday
Laura Ashley Holdings (LON:ALY)
" Someone else might try to buy the business - does anyone have Mike Ashley's phone number, perhaps we could go binge drinking with him & tempt him into buying it! "
Mike Ashley has done a few unusual things but it may take more than a few beers to get him to change his name to Laura !
Also interesting announcement in Thalassa (THAL) regarding the sale of their main business. assuming the sale completes the assets of the company will be cash of about 150 odd p. around spring next year.
Hi Graham,
Agree it's an interesting announcement from Thalassa Holdings (LON:THAL). I am attempting to work from the H1 17 balance sheet and estimate what value would be left after the sale completes, however it's a little tricky as I don't know the subsidiary level detail i.e. what's included in the sale and what remains.
It does look like if the deal goes through there is likely to be some upside here, but my initial estimates vary quite a bit. Do you mind sharing how you got to 150p?
Clearly you have between $20-30m consideration for WGP, plus the $2m for ARL giving an implied further $8m valuation for the remaining ARL stake. There isn't any significant debt, and given the USD Market cap. of around $23m looks interesting.
I could do with more information on the "Investments in associated entities" line on balance sheet around $8.8m at H1 17, the Loans line (appears to be to a related Trust), how much cash might remain at the corporate level, and operating information / potential for ARL. Welcome any insights you have.
Thanks
Hi Clouds,
To be honest I have forgotten how I worked it out. But ,there is cash of about $ 3 million there is about is the 24% stake in LSR which is in liquidation and currently worth £6m there is £400,000 stake in Papua Mining and then there is the hopefully $30 million proceeds of the current sale and nil debt. I suspect that the cash position will be higher to account for earnings and there is also a profitable FX position hedging the LSR investment.
I also am confident that the LSR liquidation will yield at least 36p per LSR share as against 31p currently.
I think all of the above will take us into the region of between £1.40 and £1.60
There is of course the question of what he will do with the proceeds.
Anyone have any thoughts on CAP XX (LON:CPX) ?
Hi runthejoules
Looking at archive SP threads.
There was a thread CAP XX (LON:CPX) in Oct 2010. Two/three people discussed it.
http://www.stockopedia.com/content/capxx-cpx-supercapacitors-for-mobile-phones-and-pdas-49040/
I also noticed someone mentioned it in a thread recently, but can't recall who that was nor which thread it was on.
I had quite a good look at their website. I've added it to one of my watch lists.
I haven't formed an opinion on it yet, other than if they do have something which has a competitive edge, can they protect themselves and capitalise on it before others swarm in?
EDIT - Oh it was discussed here on the 'I read the news today ...' thread 15 Aug. See post #5 and your own #9 post.
http://www.stockopedia.com/con...
Regards
Howard
I like beaten up story stocks but this one is really hard to like:
- the company has lost 90 million AUD of investor money since inception and for all that a deal that may produce 1m annual revenue is news.
- CEO is passionately economical with the truth in interviews (about basic physics and basic economics).
- CEO is way overpaid for a 4m revenue company.
- every year seems transformational for the company. I expect that to be true for many years to come.
Their patents seem to have some value but not anything transformational that would make supercap a replacement for batteries. The problem with supercap with current tech is that the energy density is very low so they are constrained to niches. A supercap Tesla would probably cost a couple million dollars and have a battery in a trailer the size of a bus. It would recharge quicker though.
Someone may find a way to improve on that (many teams are trying) but somehow I feel it won't be the guys at CAP XX (LON:CPX).
HI cig
Nice summary, thanks for the input.
There's too many better options out there to put any money here at the moment. It's a story stock I feel, at this juncture.
Regards
Howard
CAP XX (LON:CPX) I've done a little research and been watching for some time.
It is an Australian company which develops and owns IPR for supercapacitors , any manufacture is put out to 3rd parties or they have license agreements.
An updated note was published to today http://www.allenbycapital.com/research/research-cpx_19_4014717326.pdf , it doesn't give a lot away - the company is roughly at break even and has enough cash to keep it going for the foreseeable future. In terms of expected earnings they haven't included anything that hasn't already been declared - rather cautious which has so far proven to be correct.
The MD Anthony Kongats regularly appears on Stock Tube - search for him on You Tube , he nearly always says the same thing - everything is going well and some large orders are just around the corner.
Todays announcement although good , it isn't a large enough order (for me) to get too excited about.
The market for supercapacitors (SC) is massive I believe , but there are obviously lots of different ones for different applications.
From what I can see there are potentially 6-10 competitors in this area - all look to be quite new and It's not clear if anyone has a competitive advantage and I'd expect that they might specialise ie.,SCs for wearable IoT , cards , phones etc will be quite different from those proposed to be used in the national grid.
There are also competing technologies - fuel cells , but I believe this some way off if ever being commercially available.
So all in all I think there's bags of potential but I haven't bought into this stock yet as I'd like to see some more orders first and that there is clear momentum, accepting that the price will be higher when that happens. but then I'm a cautious investor.
Hi Paul
I have just seen the lamentable RNS from Laura Ashley Holdings (LON:ALY). It reads:
"The results will show an exceptional £2.8m impairment charge due to the revaluation of a freehold property owned by the Group. In addition, and as previously disclosed, trading conditions have continued to be demanding. The Board of the Company therefore expect net pre-tax profits for the year ended 30 June 2017 will now be materially below market expectations."
I used to be long but sold after the last profit warning. But this sort of reporting is appalling IMO, demonstrating zero respect for PI's.
This was entirely foreseeable.
At the time they bought the Singapore property (I assume it is this property), it was very obvious they were buying for top dollar at the peak of the market in Singapore. See the comments posted on here at the time and right back to 2015.
No sympathy for PI's caught out by this, the writing was on the wall, as regards both the property purchase and their poor management and fading brand.
I totally agree this was foreseeable.
My point is that issuing a release like this, at this time of day, with such little detail and containing market sensitive information that they've known about for a while, is very poor. And no, I have every sympathy for PI's being treated like this by Laura Ashley Holdings (LON:ALY) (or any other company).
Paul,
Came through Barcelona last Friday - all fine, the dispute was apparently settled last Wednesday.
Paul, why have you decided to steer clear of car dealers? I do remember that some time ago you were very bullish about them including Vertu Motors (LON:VTU) in which I have a position. I understand that you are generally not too worried about Brexit believing that sense will prevail and there will be a good deal.
Others have raised worries about electric cars, but I cannot see why that should be such a concern. Electric cars will also presumably be sold by dealers, will have a used car marker and will need servicing. Even if there will be less sales etc it all is a long way off before electric cars make a huge difference. And in any case even if a company like Vertu were to just shut up shop it would still have its net assets which it could liquidate and which nearly equate to the share price. That day would presumably be a long way ahead and in the meantime the company should earn decent profits. So what is the argument against buying at these prices?
Car dealers now make much of their profit from servicing, and from providing credit to purchasers. Neither will change as technology shifts. Vertu Motors (LON:VTU) in particular has some nice freehold property, and it has a decent yield (c3%). To me this seems the best of the bunch currently available. The great uncertainty lies with the wider economic situation, and all its inherent uncertainties. This seems to be the cloud hanging over all retailers.
Admittedly there is a general concern over levels of consumer demand. But why would this justify such an exceptionally low pe (about 6.5) with a strong balance sheet? Other consumer goods shares are not on such a low pe as far as I can see (if they have good balance sheets).
I think some people may have also raised worries about regulation of car financing plans. I am not clear exactly what the concerns are but it seems very unlikely that there would be significant restrictions on available finance to buy cars, to the extent that demand would be massively reduced in the way the low pe is suggesting.
So I am still struggling to see why the share price is so low.
Some negatives on car dealerships that come to my mind are:
1. A lot of the new car sales have been to people with PPI refunds to put down as deposits. That is coming to an end eventually.
2. The B of E is concerned about the growth in consumer credit and wants to restrict any further increase.
3. Electric cars require much less maintenance. They have 20 moving parts vs thousands in an internal combustion engine.
4. Consumer confidence is down.
Thanks.
PPI refunds -where do you get this information from?
B of E - I can't imagine they would do anything to drastically reduce availabilty of finance, although of course I may be wrong.
Electric cars - this relates only to aftersales and it will be a long time before there are significantly less previously-bought petrol cars being serviced. And even with electric cars there will still be some repairs (and MoT tests).
Consumer confidence - agreed but all this could change quickly if the Brexit negotiations take a positive turn as they well could - it looks like the Government is accepting the need for an exit payment and wants to move to smooth transitional and (slightly less smooth) long term arrangements. When this becomes apparent (maybe within just a few months) I expect there could be a rapid improvement in sentiment (and indeed the pound).
@dgold
The PPI effect on car sales has been reported quite widely - see this BBC report from 2013
http://www.bbc.co.uk/news/av/business-24397937/ppi-payouts-help-to-boost-uk-new-car-industry
That's a report from 2013. Surely PPI payments peaked some time ago, which means that buyers of recent years were buying without the benefit of PPI payments. It's hard to believe that a significant percentage of buyers in say the last year were using PPI payments for deposits. Do you have any more recent evidence?
PPI repayments per year, per FCA website, in millions:
2016 2015 2014 2013 2012 2011
£3,623.60 £4,475.40 £4,475.00 £5,259.20 £6,281.20 £2,134.10
So yes, peaked in 2012, but still running at 3.6 billion pounds last year, latest monthly figures show about 250 million per month, so slowing but still huge.
I guess we can also expect a bit of a surge in 2019 before the August deadline.
The argument that car purchases have been boosted by PPI payments is interesting. I would be interested firstly to know by what proportion the present PPI payouts are effectively increasing average household incomes.
But it's not clear to me why PPI payments should have been used more for car purchases than anything else. Logically then this would be an argument that spending on virtually everything should decrease as the end of PPI claims means there is effectively a reduction in average incomes. So I still come back to the point that I can't see why car dealers' shares have been more affected than the shares of other consumer goods providers.
Hi again dgold
I think the argument is simply that PPI increased available spend in many households, and cars were one area in which this was spent. Holidays was another.
Going back to the very slim margins, here is a tale I have posted here before, but it does deserve a second telling. A colleague's family ran a Ford dealership for three generations. They had a single site in a provincial town in the grim north. Their trade was generally good. However the manufacturer slowly began to take a greater role in provision and sales from the late 1980s. By the late-1990s my friend was effectively working for the manufacturer, with his ability to trade closely controlled in all possible ways. Terms and conditions were effectively dictated by the retailer, on pain of losing the dealership. The business is now closed, and the site turned over to three smaller businesses, one of which is auto-related. According to my colleague the only way to survive in the business is by benefiting from economies of scale, and lowering fixed overheads, like rents. To me Vertu Motors (LON:VTU) are doing this. The sector is NOT immune from inflationary pressures,very far from it, but there are worse places to be.
(PER = 6.6; Price to book = 0.7; PEG = 1.3 (not great); yield = c4%; ositive cashflow and low gearing)
A low PE in a cyclical industry is often a sign that we are at peak earnings rather than an indication of good value. In other words a classic value trap.
My understanding of the concerns around car financing (Personal Contract Purchase plans especially) is that the increasing popularity of these financing schemes has led to a splurge of car sales over the last few years so when all those vehicles come to the end of their lease plans, the market in second hand cars is going to be completely flooded which will push their prices down.
If the modelling of second hand car valuations which underpins the PCP payments has overestimated those residual values, someone is going to be on the hook for impairments and write downs at that point.
I think it is mostly the vehicle manufacturers rather than the dealerships who provide the actual financing, but even so the fall out from decreasing second hand values will have an impact on anyone who is holding significant inventory of used cars, which includes most of the dealerships.
You can already see the impact of this effect on the likes of Avis and Hertz in the US, although their holding periods will typically be longer than those for car dealerships.
That’s even before you consider the ability of already over-leveraged consumers to continue buying cars at the same rate as they have done in the last few years.
More generally, dealerships have a high fixed cost base and low operating margins, which is never a good mix at the best of times let alone on the cusp of a downturn.
Electric cars are a red herring in the short term, although it’s worth noting for the longer term that they have far fewer parts than vehicles with internal combustion engines, so their servicing requirements are likely to be much lower. That has obvious implications for aftersales, which tends to be where the dealerships have the fattest profit margins.
Thanks for your comments. About the second-hand prices, I do think the crux of the matter is as you yourself say that the dealers only own the cars for a short time thus mitigating the risk. The PCPs will end gradually so prices won't suddenly collapse. Also the dealers will see this coming so will know to only buy the cars for less.
I think the low operating margin is the best answer. But I'm still not sure why everyone is so convinced that a major downturn is coming. It just needs a bit of positive progress in the Brexit talks and things would suddenly look very different.
Re Vertu Motors (LON:VTU)
"So what is the argument against buying at these prices?"
If I had to make a bear case on this one, it would start with the operating margins of just 1.1%.
Basically this is a business with £2.82billion of sales & £2.79billion of costs - this is a very fine margin for error ahead of a UK economic slowdown.
Moreover, any unrecoverable Brexit-related import duty of just 1.2% will turn the profits to a loss.
Definitely a stock to hold coming out of an economic slowdown, less so going into one.
Thanks, you make a good point about the margin. Looking over the last accounts, the gross profit from new and used car sales was £190m. So a reduction of 10% in these (assuming aftersales and admin are unchanged) would mean the operating profit goes down by £19m from £32.1m to £13.1m. Of course the question is whether 10% is the right number.
I would however dispute your statement that "Moreover, any unrecoverable Brexit-related import duty of just 1.2% will turn the profits to a loss." This assumes all profit is from new car sales and that they couldn't increase the sales price. Actually the gross profit from new sales was only £89m out of £313m total. Also, all car importers would be equally be affected by an import duty so would all increase their sales prices to cover the duty, i.e it would not be less competitive as a result of increasing the price. Of course, sales may slightly reduce as a result of this but that is much less significant than your suggestion that the entire margin would be wiped out.
All fair points dgold, I must have suffered a brain freeze on that last post
Another way of looking at the outlook for Vertu Motors (LON:VTU) is to consider the company's operational gearing:
So a 10% drop in sales would eliminate virtually the entire operating profit (-10%*9.8=-98%)
Of course this is too simplified as:
1. you mention the company has a non-cyclical (?) service business
2. not all of the operating costs would be necessarily be fixed if the top line started contracting at a pace of -10%
Have held CGS since Brexit in hope that with a reduction in GDP its a reasonably attractive acquisition for the right company in Europe. In the meantime it's a pretty safe company that pays an okay dividend. In the times of inflated share prices this is likely to go down less than the rest when the shake up happens
Hi Paul,
Good luck with your trip to Spain. We arrived at Malaga today for a five day trip and not a queue in sight!
Thanks for some more great input today, especially re RBG.
Peter
Same with Palma. Newspaper headlines in UK warning of three hour queues but in fact sailed straight through.
Marshall looks good value here. So does all the sector. Ultimately, car dealers may be a quintessential value trap, as margins are razor thin, UK discretionary consumption looks very weak and, structurally, the whole industry is under complete change (direct OEM sales, EVs, self-driving cars, etc.). I've noticed there used to be a lot of insider buying in the likes of Vertu, Marshall, Lookers or Cambria. However, over the last year, not a single share has been bought despite "dirt cheap" valuations.
Regarding Barcelona airport, you shouldn't find queues getting in because passport checks are done by the police. The queues are on the security checks -getting out- which are done by private security employees who are indeed striking to pressure for higher salaries and better workinf conditions. That's Barcelona airport specific, so the rest of Spain should be fine.
CSG, said it before, will say it again. They make a specialist range of castings very well and have the single best plant in Europe to do that. Well managed operationally they have no "thrust" to grow the business and no one on the board who can see a safe strategic way forward apart from doing what they do. Dull and successful, Germany is full of companies like this. If they win more business they would have to spend capax, their kit is amazingly expensive and it just runs 24 7. They did try to up the machining side of the business and found that people don't want to use them much.
HAT, Paul doesn't like pawnbrokers, but HAT is a fine company with pros in charge. I can see highstreet borrowing only go up and gold go up. If it does then the figures will be even better next time. The recent SP jump was just taking us back to where we started after the last announcement. Let's see if it keeps rolling for a change.
I see Deltic published their 2016 results on their website in May last year despite being a private company with no obligation to do so, and rather unusually for a non-listed company they issued their results by way of an RNS extolling their performance (the headline was "Record revenue, profit and EBITDA confirm Deltic’s position as late night bars and clubs industry leader").
That, as well as articles like this one (Times paywall) suggests they were thinking of a listing anyway at some point and in approaching Revolution Bars (LON:RBG) they are doing so opportunistically as a way of coming to market.
They still haven't filed or publicised their 2017 results despite it being 3 months later in the year than they filed last year's accounts. Not sure if there is anything meaningful that can be read into that.
It also occurs to me that Stonegate are in a similar position in that an IPO has been mooted for some time as a way of allowing their private equity backers to realise their investment. Now that Deltic have put the option of a reverse takeover of Revolution Bars (LON:RBG) on the table, I wonder if Stonegate might consider the same approach as a way of killing two birds with one stone - acquire RBG and come to market? An enlarged Stonegate/RBG group would probably be more attractive to investors than a Deltic/RBG group.
This is all pure speculation on my part, so it may well be complete rubbish!
re Revolution Bars (LON:RBG) I think there could be a lot of private equity interest, due to the underlying soundness of the balance sheet and the cash-generative nature of the business. Therefore it seems obvious to keep holding out as there are clearly companies sounding this out as a potential bargain at 200p
I would never under-estimate private equity's ability to cannablise its own, but didn't private equity float Revolution Bars (LON:RBG) in the first place to get a capital exit?
Sorry £3
Is it possible to have a look at HAT today. The results seem fairly robust and they are a good business. That said they never seem to clear £2.
Also have Next gone XD today anyone?
Re Next (LON:NXT), no, can't go XD on a Tuesday anyway, I believe they've been hit by a broker note today.
Next (LON:NXT) were downgraded to sell by Berenberg
On a wider view, is is it appropriate for private company accounts to be comparable with listed company accounts? For example listed/quoted companies much prefer to report high profits as that generally supports the share price whereas private companies should be aiming to 'present' lowest profits possible because high profits simply means more tax to be paid by the owners. In other words, two identical companies would want to report their business finances in a completely different way; unless the private company had an eye on making an IPO in 1-2 years.