Small Cap Value Report (Tue 15 Feb 2022) - SMRT, LOOP, RM.

Good morning, it's Paul & Jack here with Tuesday's SCVR.
Agenda -
Paul's Section:
Smartspace Software (LON:SMRT) - trading update for FY 1/2022 is slightly ahead of expectations, but remember expectations were greatly lowered after profit warnings last year. Still loss-making, and I think it needs to demonstrate stronger growth to become interesting. Worth keeping an eye on it though, as office staff returning is helping boost the sales pipeline.
Loopup (LON:LOOP) - a very poor track record here. The original business hasn't worked, so now they're trying something else (cloud telephony for Teams). Difficult to say if it's likely to work or not. Conserving cash, but has £2.5m net debt. I wouldn't be surprised if it needs another fundraising.
Jack's section:
Rm (LON:RM.) - mixed preliminary results with adjusted progress but a statutory drop in profits. The company has struggled to grow in the past, in my view. The new CEO and strategic plan could rectify this, there has been good progress in the pension scheme valuation, and the valuation remains modest. The shares could rerate at some point, but I’m holding off for more concrete signs of operational momentum.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul’s Section:
Smartspace Software (LON:SMRT)
66p (pre market open) - mkt cap £19m
SmartSpace Software plc, (AIM:SMRT) the leading provider of 'Integrated Space Management Software' for smart buildings and commercial spaces, is pleased to announce a trading update following the Company's year end of 31 January 2022.
Slightly ahead of expectations - but important to remember that expectations were considerably lowered last autumn -

.
Guidance for FY 1/2022 -
Revenue £5.3m (mostly recurring)
Adj LBITDA (loss, not a typo!) c.£(2.5)m
Gross cash £2.76m
Outlook - clearly the figures for FY 1/2022 look poor but the company looks set to be a beneficiary from staff returning to offices -
"Both SwipedOn and Space Connect have continued to achieve strong growth since our last two trading updates in October 2021 and January 2022.
We are encouraged by the strong growth in ARR and ARPU, despite the work from home policies which persisted in the UK and USA until recently. In other markets, such as Australia, we have seen a strong resurgence since coming out of lockdown in the Autumn.
The recent push to return to the office has seen a significant pick up in orders and movement in our sales pipeline, in particular in the UK.
Consolidation in sector - this is interesting - could there be hidden value in SMRT to an acquirer?
Consolidation in our market has continued apace, evidenced by a number of major competitors being acquired at exceptionally high ARR multiples over the past few months.
Forecasts - unusually for such a small company there are 2 good quality broker notes out this morning, from Singers & Canaccord.
They’re both forecasting around £(2.0)m adj loss before tax for FY 1/2023, on revenues up between 23-32%. This reinforces how small the company is, and it’s still a long way short of breakeven.
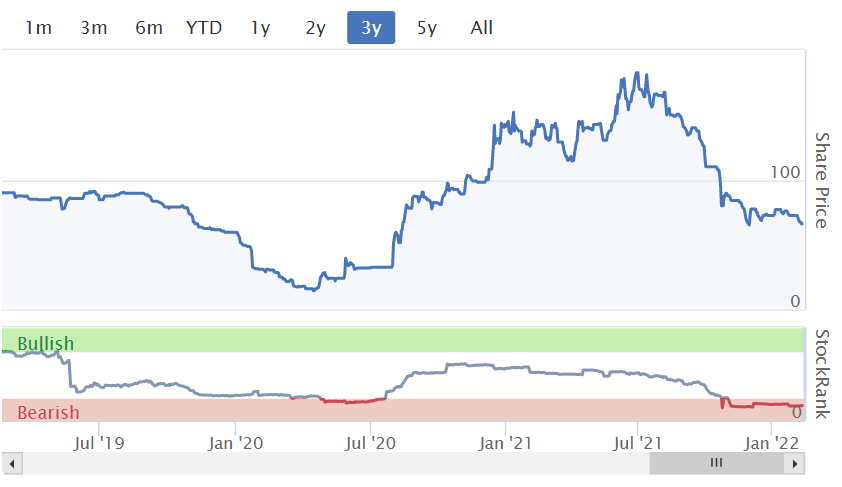
My opinion - the share price of SMRT has come down a lot, reflecting poor performance. However, with offices now apparently opening up again, and positive-sounding outlook comments, I imagine 2022 should be a better year than 2021.
I’ll keep an eye on it, for out-perform trading updates during 2022, but as things stand currently, I think the company needs to demonstrate stronger growth to interest me.
With so many bargains around in small caps right now, why chase a loss-making minnow like this?
It multi-bagged from the lows, but has since failed to live up to expectations.
Note the StockRank has reflected poor performance, by returning to the red.
.
Loopup (LON:LOOP)
9p (down c.30% at 08:16) - mkt cap £10m
LoopUp Group plc (AIM: LOOP), the cloud platform for premium external communications, announces a trading update for its financial year ended 31 December 2021.
Clear guidance for FY 12/2021 -
The Group expects both revenue and EBITDA for year ended 31 December 2021 to be broadly in line with market expectations with outturns at approximately £19.5 million (FY2020: £50.2 million) and £0.9million (FY2020: £15.3 million) respectively.
The Group ended the year with gross cash of £5.5 million (FY2020: £12.1 million) and net debt of £2.5 million (FY2020: £0.7 million), following the successful placing and retail offer for approximately £8.85 million in September 2021.
Outlook -
The Group expects FY2021's strong performance in Cloud Telephony new wins to improve further to at least an additional 50 during FY2022, and the integration of SyncRTC (acquired in October 2021) is progressing well. Due to the longer lag from bookings to revenue in Cloud Telephony, combined with continued expected pressure on its Remote Meetings business, the Group expects FY2022 revenue to be in the £15-16 million range.
The Group is managing its operations carefully during this strategic transition to preserve cash and maintain EBITDA profitability in FY2022, at a higher expected margin than FY2021.
My opinion - there’s more positive-sounding commentary provided, but it’s difficult to put it into context.
The way I see things, the original business of a remote meetings service is withering away, because it’s too expensive for customers.
LOOP’s strategy is to build up its newer cloud telephony service for Microsoft Teams.
Therefore this share currently looks a punt on the cloud telephony service generating enough revenues to allow the company to survive.
Being in a net debt position, even after a fundraising last year, is not ideal. I wonder what the terms of the debt are, and if breached covenants could become an issue?
At this stage therefore, this share looks a gamble. That said, £10m market cap could leave scope for upside, if the Teams cloud telephony service does take off, and they seem to be winning some significant sized contracts.
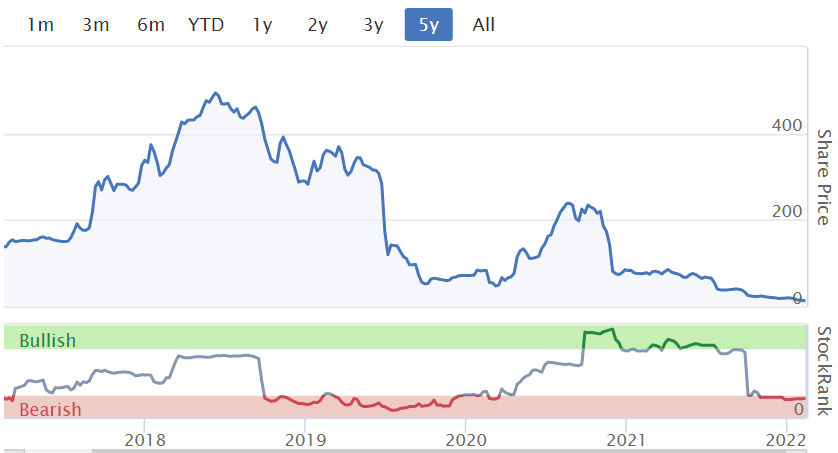
The company & management have such a poor track record, that it’s difficult to have much confidence at this stage.
Several false dawns in the past, make it difficult to believe the positive commentary this time.
.
Jack's section
Rm (LON:RM.)
Share price: 158.1p (-2.11%)
Shares in issue: 82,706,000
Market cap: £130.8m
Preliminary results for the year to 30 November 2021
Highlights:
- Revenue +12% to £210.9m,
- Adjusted operating profit +22% to £18.5m (adj. Operating margin up 0.8pp to 8.8%),
- Adjusted profit before tax +22% to £17.1m but statutory PBT -45% to £4.2m,
- Adjusted diluted EPS +21% to 16.4p; diluted EPS -45% to 5p,
- Proposed dividend up from 3p to 4.7p,
- Net debt up from £1.3m to £18.3m but pension has swung from deficit of £18.7m to surplus of £30.4m.
Following a strategy review, the group is changing how it reports.
- RM Resources remains the same. This is the provider of education resources for early years, primary schools and secondary schools.
- RM Results becomes RM Assessment due to its broadened product portfolio. This segment provides assessment software for exam awarding bodies and governments.
- RM Education becomes RM Technology due to its focus on improving the technology environment in schools with IT software, tech, and services.
Demand for the Resources division was understandably affected by school closures in Q1 but recovered in its UK market following the return to face-to-face teaching, with sales ahead of pre-pandemic levels. Some of this will be catch-up spend but RM does note that the segment ‘has enjoyed a useful gain in UK market share’.
The situation overseas remains trickier however, and supply chain issues have impacted operating costs and margins.
Digital Assessment - again constrained by the absence of formal school examinations in the UK and ‘difficulties in negotiating new contracts overseas’. Performance in 2022 will be affected by a low level of new awards in 2021 and the extent to which UK school public examinations return to normal.
Technology - a steady year as schools maintained their systems. The short-term performance will be relatively flat.
Good progress has been made on the warehouse consolidation project and the group-wide IT investment. The RM Resources distribution facility is complete and should begin to generate efficiencies.
Adjusted vs. statutory
There’s a big gap between adjusted and statutory results, some £11.5m between adj. operating profit of £18.5m and statutory OP of £7m. Here are the adjustments:

This is what the group says on that £8.3m of IT platform costs:
Following the IFRS interpretations committee ("IFRIC") agenda decision, we have changed our accounting treatment and policy for IAS38 Intangible Assets accordingly. The directors determined that £8.3m of SaaS related costs incurred during FY21 no longer meet the criteria for recognition as an asset under IAS38. Accordingly, this amount has instead been expensed to the income statement. A total of £6.9 million SaaS related costs incurred in the year have been capitalised and recognised on the balance sheet as an intangible asset.
I’m unclear on the ongoing impact of this accounting change. It is listed here as an adjustment to underlying operations, so presumably it will not be a feature in future accounts but that will be something to check.
Balance sheet
Around 35% of total assets are goodwill and intangibles, resulting in net tangible asset value of £15m (helped by the large swing in pension scheme valuation). There’s a large amount of payables but stable year-on-year. Cash at bank is a little low at £3.6m, particularly against £66m of current liabilities, but the overall current ratio is just about OK, hovering around the 1x mark.
New CEO:
Following my appointment as Chief Executive in the second quarter of 2021, it was clear that the priority for RM moving forward should be to establish a clear path to long-term sustainable growth for the benefit of all stakeholders.
This is a key point for me: RM has struggled to grow consistently. The CEO brings a new five-point strategic plan to address this, so we'll see if that makes an impact.
Pension Scheme
The notable improvement here was driven primarily by better than expected returns on scheme assets, together with an increase in the discount rate, partially offset by an increase in inflation.
Deficit recovery plan payments in 2021 were £4.4m (2020: £4.1m) - the triennial valuation is nearing completion though and this could result in reduced pension contributions in future.
Cash flow
RM generated cash from operations for the year of £8.4m (2020: £25.9m) after the £6.5m SaaS cost charge and the settlement of £3.5m of deferred VAT liabilities. However, net capex of £11.8m means an overall outflow.
Conclusion
It’s a mixed bag. Anyone with children will be understanding of the Covid impact, but it looks like some areas such as Technology are struggling relative to peers. Resources has done well though, gaining UK market share.
RM says its longer term outlook is positive due to increasing use of technology in schools, spurred on by lockdowns, and a trend towards larger school groups consolidating procurement. Increasing use of tech has been a dynamic for many years now though, and the share price has little to show for that particular tailwind.

The group does say that only around 4% of the $6.5tn global education and training spend is digital, and that ‘schools are at the start of a long digital maturity journey’, so perhaps digital adoption is less advanced than you might expect.
RM has a rich heritage in the education sector but has at times struggled to translate that into a cohesive opportunity going forward. I’m not 100% convinced that capital allocation has been optimal in the past, with some large acquisitions and not much yet to show for it, but a new CEO and revised growth strategy gives some hope. There could also be some good news approaching with regards to pension contributions. The group is cash generative, so if it can deploy that cash wisely then things could change.
It’s modestly valued at these levels, especially for a company included in the Software industry group, so that is an attraction. Perhaps it limits the potential downside from here, and the stock is under the radar so could potentially rerate at some point.

The share price momentum is poor though and the company needs to prove that it has a clear path for growth. I understand the Covid impact, but I’d still rather hold off until there are more concrete signs of positive operational progress.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

58 comments
Has any one any thoughts on why the big drop in Serica energy £SQZ. dropped 12% on no apparent news
okay just seen institution sale from 5.05 to 4.95% Seems a big drop for that % of the company
I assumed profit taking given the recent run, nearly took some myself yesterday, should’ve done!
Oil and gas prices were down considerably today.
Apologies for going off topic.
I’ve been doing some more detailed digging into Tandem (TND) following recent favourable analysis on here.
Their year end was 31 December 2021 and I noticed that one of the senior Directors notified the company that he had sold £182,000 of shares on 24 January 2022. Further, on 31 January the company provided a trading update.
Could someone please set me right ? My understanding was that a close period preventing director share transactions was in place from the date of the year end to the date of the publishing of the year end accounts, which I believe is due to take place on 28 March. I am sure that the company will have followed the appropriate rules in this case so could someone let me know if I have misunderstood close period workings ? Many thanks .
I think it used to be 60 days before the announcement of interim or full year results (or from the period end to the announcement date if that was less than 60 days). It changed with the EU Market Abuse Regulation 2016, which has been carried over to UK law post Brexit, to 30 days prior to a results announcement.
Disclaimer: I am not a lawyer!
Apologies if duplicating - did we get to the bottom of where the Green support blob went and how we get hold of support in its absence?
Did you try signing off and then logging back on again?
My green button never went away and I did not sign off/on, so not sure whats going on.
This is the email: support@stockopedia.com
Problems currently with Hargreaves site with US shares not showing correct prices. Anybody else having problems?
I was not given a timeframe when it should be fixed.
thank you will try that and thx for the email address.
Hi Jack
Centralnic (LON:CNIC)
If you have spare time this week I'd be interested in your take on yesterday's acquisitions and TU. All seems to be falling into place to me and looks good value.
Phil
(Obviously I hold)
Re. (LON:CNIC) Director talk interview with Zeus analyst Bob Liao this morning is worth a listen https://www.directorstalkinter...
Thanks for that Simon.
Interesting.
I think the point about non-reliance on cookies is what some are missing here.
Hi Jack,
Thanks for the review on £RM. (I hold)
Your assessment of Rm (LON:RM.) seems pretty fair. I have been suffering the share price decline hoping for a more significant rebound on the back of the return to school. There is potential here if the internal investments come good and school disruption is a thing of the past but how long will it take and will competitors be more nimble and erode their position? The appointment of a tech savvy Chair might also be a positive move.
Rm (LON:RM.) therefore puts me in a dilemma that many other share holders suffer when holding a losing position. Sell now and accept that you cant win them all (but this might be a low point in the share price) or wait for investment and new management to start making a difference?
I think I'll treat this as a long term slow burner in the background of my portfolio. If and when it does re-rate the lack of liquidity means that small volumes can make a very significant change in the share price.
I have held £RM.L for a couple of years. So far it has been a slightly disappointing investment.
As Jack mentioned, the positives have been a modest valuation and that it is a dividend payer. (If you have to sit on an investment for a few dull years, the income stream helps!)
I think it is reasonable to assume there is a reasonable stability in its income stream and few bad-debts, given the clients are education establishments. That just about compensates for the slightly weak balance sheet.
On the other hand, I wonder if it is struggling to be competitive on the tech side. After all, the covid years have been a boom time for many IT/Software businesses. I guess the next 12 months will tell, as schools etc will (hopefully) be having a much more normal year, and may even have a backlog of investment in processes/IT etc.
Reading the CEO's commentary, I also wonder if there is an element of kitchen-sinking i.e. downplaying things at the start of his term in office. That might be wishful thinking on my part- who knows!
I sold a small part of my holding last week. Just a sense that with the share price consistently falling over the previous week or so, there were poor results coming out and this had leaked into the market, I have no idea if this actually happened or not, but another non-inspiring backdrop if market-sensitive information is not kept confidential.
I will keep holding for now, and monitor trading updates for signs of progress.
Hi Mark
Reading the CEO's commentary, I also wonder if there is an element of kitchen-sinking i.e. downplaying things at the start of his term in office. That might be wishful thinking on my part- who knows!
This also crossed my mind (as you say wishful thinking). If I remember correctly he is on a 3 year bonus package based on TSR when the share price was well over 200p. Therefore it might be wise to get the bad Covid years out of the way and try to build momentum over the next couple of years.
Its also wise to build a business model that works and let the share price take care of itself rather than over promise to boost a share price now possibly at the expense of longer term gains.
Not related to SCVR but is anyone else having problems adding transactions to their folios today?
Trying adding the time, it worked yesterday. It should have been fixed though.
Great thanks, working now with time added
As an investor I am learning, and I make a lot of mistakes. I thought I saw this bear market coming, so took fairly nice profits in Q3 last year, and moved into cash to give me some fire-power for a likely downturn. I have been shocking at holding cash, with it burning holes in my pockets. For the last 4 months I have been looking for deeply discounted opportunities, which has entailed spending said cash on 'bargains' in the form of falling knives, ready for the inevitable bounce (that has not happened). Boohoo at 120p, now 92p. Joules at 120p and then again at 69p - now 60p. Victoria Plumbing at 110p, now 87p. Luceco at 330p, now 267p. Volex at 350p, now 279p. CMC Markets at 277p now 222p. I could go on. Typically I have anchored to previous ATH's, jumped in too early, not waited for a new base to be formed on updated facts, and allowed impatience to affect my judgement. I am not overly worried that my very long list of ill-timed purchases will not come good over the medium term, but it has been good self reflection as I nurse c.20%+ losses on my 'bargain' purchases. How Buffet sits on £100 billion cash is amazing to me. I have now added a few new rules to my investing methodology and live to fight another day.
And to add insult to injury, I was smart enough to invest a full holding in Vin Murria's ADVT investment vehicle at 120p, thinking she woud scoop up some high growth beaten down technology company and apply her midas touch brilliance in the year's ahead........only to find she bids for M&C Saatchi, which the market hated almost as much as Saatchi's board. Now worth 98p and who knows where that will end up if she has to walk away again. Couldn't make it up.
We have all been there to some extent. I read Lord Lee and Keith Ashworth-Lord and similar and found that reading about how they invested helped to formulate a stagy that worked for me
Join the club.
Investing is certainly not for the faint hearted.
It's never easy, BE70 - I've made much larger losses averaging down repeatedly.
Care to share your new investment rules?
Fairly straight forward rule additions:
(1) I will not buy recent IPOs at ANY price, until they have 2-3 years of trading reported.
(2) I will not buy any stock that has issued a profit warning, regardless of the apparent deep discount on the day, director buying or seemingly fixable issues. I will wait until the turnaround is done and I can see it in the numbers. I will gladly miss any dead cat bounces or the first stage up on the chart.
(3) I will ALWAYS layer in an investment going forwards, over several weeks.
(4) I will not average down once I have a full position.
(5) I will not invest in speculative investment vehicles based on the reputation of the CEO/ lead investor and their past success. I will wait for the asset/s to be acquired, and the story to unfold.
In general these rules simply try to protect me from my poor discipline, impulsive buying based on anchoring to previous ATH’s, a high risk tolerance for speculative situations (where I sense I can make outsize gains), and my often flawed view that the market overreacts to bad news. I must get better at managing self.
BE70,
Lots of rules of what not to buy, but you don't appear to have any rules on what to buy.
I like mechanical investing and just add a few extra rules to the Jim Slater screen, the SIF portfolio is also rules based.
Until you come up with rules of what to buy, are you not just chasing the next piece of news, which is already out there before you get to read it.
Hi BE70
I have found that looking for bargains can be an exercise in buying companies that are in decline. Momentum works in both directions and bad news comes in waves.
Totally agree that waiting for a clear breakout before committing significantly. I like to buy small when I think there is a turnaround and add when a breakout becomes clearer.
If its any consolation I've made similar mistakes. I now prefer to look for buying opportunities in companies that are in a positive channel but always worry that I am buying at a top!
If there were no risk there would be no returns.
Sounds like you are a bargain hunter like me - a bottom fisher. One strategy is as a bottom fisher, if it breaks the support line, Get Out Quick! - try not to hang around unless you have complete conviction.
"If there were no risk there would be no returns."
Is that really true?
If riskier investments reliably produced higher returns, would they actually be risky?
Riskier investments don't reliably produce higher returns, they only do so on average, over time (that's the theory anyway and it's mostly true in practice).
And to be pedantic, the correct statement is: "if there were no risk, there would be no returns above the risk free rate".
"if there were no risk, there would be no returns above the risk free rate".
The mention of the risk free rate suggests you are applying the CAPM and taking beta/volatility as a measure of risk.
In which case an obvious challenge is the outperformance of low volatility stocks?
https://en.wikipedia.org/wiki/...
If it makes you feel any better I am down 35% (70k). Sold out of my BP/Shell/Glencore type stocks that did nothing for the year I held them whilst everything else rose to buy into beaten down growth stocks only to watch them carry on through the floor. Still I am told Boohoo, Saga, and COG etc will recover
Time in the Market is better than time out of the market goes the adage.
Interesting and as far as I can tell a positive announcement from Rbg Holdings (LON:RBGP) regarding LionFish Litigation Finance, which currently represents the smallest part of the company versus Convex and RBGP Legal Services. The latter being the main revenue generator.
"Under the terms of the Arrangement, the Firm will participate in all of LionFish's litigation investments, investing up to 75% in each of LionFish's investments across the portfolio over a two-year period. LionFish will be entitled to receive a significant share of the returns of the Arrangement after a high single-digit return hurdle has been met, therefore providing significant additional potential returns to LionFish beyond its own investment." There is an investor presentation on this development to be given by the CEO, Nicola Foulston and MD of LionFish, Tets Ishikawa on Investor Meet Company on 21 Feb.
In my view Rbg Holdings (LON:RBGP) provides a more comfortable way of accessing investment litigation finance than its listed peers, as it appears to provide the potential cherry on the cake rather than being the cake, as the majority of earnings are generated by its Legal Services arm.
I hold as I believe does Jack, so I am clearly a little biased.
Smartspace Software (LON:SMRT)
LBITDA (loss, not a typo!) c.£(2.5)m
phew thought you were gonna say its LBITDARM losses there for a sec
Loopup (LON:LOOP) has to be in your mind when you think of shares that could climb back, just give them a few more months. Touched a high of £5 in 2018, today broke 10p.
I should laminate the share chart and stick in on my desk when I think about picking the bottom of Boohoo (LON:BOO), Avon Protection (LON:AVON), Simec Atlantis Energy (LON:SAE) etc, etc, etc
Loopup (LON:LOOP) , an online meetings/communications business, somehow failed to make their business work during a global pandemic that required everyone globally to conduct all meetings via nothing but ... online meetings/communications platforms. That for me says it all. The world handed them an almost fantastical leg up and they still couldn't make a success of it - for that reason since end of 2020 for me it's been uninvestable.
When a share price drops it does not automatically make it cheap and even if it does look cheap the market may simply have lost faith in the company. The dangers of averaging down.......
Catching a falling knife comes to mind
Crystal Amber Fund (LON:CRS) give details of the mgt reward scheme for wind down today.
all 5 holdings expected realised by Dec 23, with at least 2 realised by June 22.
the interesting bit is that the mgt bonus doesn't kick in unless shareholders get 220p (compared to current 104p) if I read correctly.
it seems their 6th investment (unquoted) has received 2 unsolicited offers materially above NAV
My broker can't seem to buy stock atm
where are you seeing this information on CRS?
The RNS is on investegate.co.uk It is missing here. I have reported that and it is being looked into.
Wow, looks like a money grab by Kistos (LON:KIST) directors ahead.
They want 15% of the shareholder returns as long as they hit a 100% gain over 5 years.
HOWEVER the start point is the average of last years share price, rather than "now". So that means they are already, at the very start of the plan, 47% up! 5 years to get the remaining 53%!
In fact take the recent high (22 Dec) and they were already at 86.8% of the hurdle gain, so a market recovery and they are almost at pay day and the plan hasn't been approved yet.
Hardly the exceptional performance this bonus is meant to create.
Expect a few share buybacks rather than dividends around the vesting period! That should boost the share price.
Re £KIST Yes I agree, this an appallingly easy target especially as the company has just doubled production in January through the acquisition of an interest in the Greater Laggan area the benefits of which will not show up in the accounts until the next interims. The top 4 directors will take out up to £100mm and 9.5% of the company on meeting this easy target. Borders on theft.
Kistos (LON:KIST)
subject to a hurdle of 100% total shareholder return ("TSR") over that period (equivalent to 14.9% TSR p.a.) from a reference starting price of 242 pence (being the average closing share price in 2021).
wow unless i am mising something mitigating (previously having been flagged up?) that is truly outrageous - shareprice is 358p now and was as high as 440p last december!
One option is to play them at their own game and sell on the sharepirce strength before hitting targets.
Hey ho they say dilution only 9.5% and within "guideline limits"
There is an overall cap of £25 million for each participant in the plan and the maximum potential dilution is 9.5%, which is below the limit contained in Investment Association guidelines.
Perhaps one should look at is as being potnetially a good problem to have if it exists as shareprice would have moved from 360p to 480p !
Whilst this does look bad on the face of it - does it create an easy opportunity if, as we believe, the directors are going hell bent on achieving this target share price? Look at what happened to Persimmon. I'm currently considering Cineworld (LON:CINE) for the same reasons - the 'long term' (3 years!) director incentive scheme grants the Greidinger brothers £104 million if the share price hits £1.90 within this period, they have about 20 months left and the current share price is £0.43.... In my mind, following the dropping of covid restrictions together with pent up demand could see an explosion of growth, especially if they do everything withing their power to get bums on seats (why have a 10% full cinema at £10 per ticket, when you can fill all of them at £3...) to hit this goal.
"Whilst this does look bad on the face of it - does it create an easy opportunity if, as we believe, the directors are going hell bent on achieving this target share price?"
That certainly concurs with my thinking "sort of", although i am not minded to make an investment decision based on a megalomaniac boards desires to pump and "presumably" dump alone !!!. It does make ones sell target very easy though - the flip side worry is are they concentrating on the sharepirce targets to the exclusion of everything else - they might do everything in their powers to maximise the % chances of reaching that target if they are close , almost do or die with regard to business decisions at that time. So i would be slightly worried that non rational decisions would be being made if they are overly risk taking on the basis thats the only way to get the pot of gold.
I would also slightly factor in just how key management are here - if they really are seen as mission critical short term to business success well i would be much more minded to say yes ok. For persimmon particualrly i never saw anything specicial about management there infact completely the opposite in that business seemed to be run for ultra short term benefit on very very unethical lines rather than long term susatianable (and fair) basis.
Regarding Kistos, there's no such thing as an easy opportunity in the stock market, especially if it's as a result of following naked greed. I don't think that description adequately does this justice. That they felt it necessary to put a cap on each director's 'reward' for random fluctuations in its share price of GBP25m says it all.
I'm hoping that this is one of those events where we look back and the share price never again reaches even today's price, let alone the price target. Although I have no doubt that if this were the case, mgt. would revise the price target lower (and lower).
Deleted Kistos from my watchlist this morning, never to return under this management.
Each to their own.
Chris
I presume there will be an EGM to approve this Kistos (LON:KIST) money-grab, in which case we can make our feelings known.
Kistos (LON:KIST)
Went to Interactive Investor to check on the share price only to be informed "Your account is not currently set up to trade complex instruments".
Says it all really.
Phil
re Minoan (LON:MIN)
Crickey! Didn’t realise that they were still going try to get ‘The Project’, basically a holiday resort called Cavo Sidero in Eastern Crete, up and running. They’ve been at it for at least ten years now I would think because it feels like about that long since I came across it.
Seems to still be a Greek tragedy. Definitely an ouzo tomorrow stock!
Hi Paul, Jack,
Will you be reviewing £Rm. ? (I hold)
Share price has been hammered over last 4 months and yet they seem to have come through pandemic well. Cash flow is good and 3p final dividend confirmed. IT and warehouse/distribution improvements should bode well for future operating margins.
Only 20% of shares held but small investors which I believe is why the spread can be significant.
Rm (LON:RM.)
It all seems so lacking in focus here - note sure if thats a recurring theme for the educational sector perhaps? are educational types good at making wonga ?- i have my niggling doubts.
To be fair to the company they probably have ben covid wholloped - but perhaps they should have upped their game and transformed quicker - they strike me as lumbering dinasaur they said that themselves ref it costs being higher than competitors. Perhaps they have missed a trick not securing more stuff digitally quicker over covid - perhaps school contracts dont work like that.
Looks like the next 12 months will be meeeeee with lingering covid and them "improving"
Despite price getting cheaper again than when i last looked i am minded not to invest in a company that is not on the money now. Obviously sharrpice will possibly pickup before any obvious material increase in trading but must admit at present i am not realkly convinced by anything this company is doing despite niche amd market presence being very sound - possibly somewhat favourable.
My thoughts are very sketchy of the non deep dive variety so i could easily be mising out on something that may be slightly better than the takeaway i got from the update today - very brief skim read of part of the announcement.
I also had a read through Rm (LON:RM.) this morning as it's been on my watchlist for a while. Also disappointed, no clear strategy, momentum. Digital tests potential and growth pushed out another year. Its a decent enough company, but can't really see the attraction of investing at the moment. Back to the watchlist it goes, and have added to to-do list to update my analysis but in no hurry to do so.
John Menzies (LON:MNZS) - holding out for a lot more:
The Board of Menzies (the "Board") notes the announcement on 14 February 2022 by NAS Holding for Company's Business Management (Holdco) S.P.C. ("NAS"), a subsidiary of Agility Public Warehousing Co. K.S.C. ("Agility"), regarding its all cash proposal for Menzies of 510 pence per Menzies share (the "NAS Proposal").
The Board of Menzies has engaged with its shareholders following its announcement of the NAS Proposal on 9 February 2022. As previously announced, the Board of Menzies has unanimously rejected the NAS Proposal, having concluded that it is opportunistic, conditional and that the terms fundamentally undervalue Menzies and its future prospects.
Think we’ll see a 3rd & final bid from NAS, circa 560p perhaps, then they’ll walk away if MNZS reject again.
Yes my reading was that it’s just a matter of getting the right price now. I get the feel that the shareholders they engaged with were not as averse to an offer as the board was.