Small Cap Value Report (Tue 15 Sept 2020) - CER, BKS, FLTA, SBIZ, AVG, CHRT

Good morning, it's Paul here, with the SCVR for Tuesday.
Timings today - mostly up by lunchtime, but I'll do a bit more after lunch, so let's say final finish at c.3pm.
Update at 16:34 - today's report is now finished.
Today I'll be looking at updates from the following companies;
Cerillion (LON:CER) - Largest ever contract win
Beeks Financial Cloud (LON:BKS) - Final results
Filta Group (LON:FLTA) - Interims, 6m to 30 June 2020
Simplybiz (LON:SBIZ) - Half year report
Avingtrans (LON:AVG) - Q1 trading update
.
Surface Transforms (LON:SCE)
41p - Market cap £63m
Registration link for today's webinar this Thursday at 16:00 - apologies, I misread the announcement earlier, and thought it was today, which was wrong.
A reader suggested yesterday that I need to improve my understanding of carbon brakes, so this looks like the ideal opportunity - a webinar from SCE today this Thursday at 4pm, should be interesting. Anything to do with cars interests me.
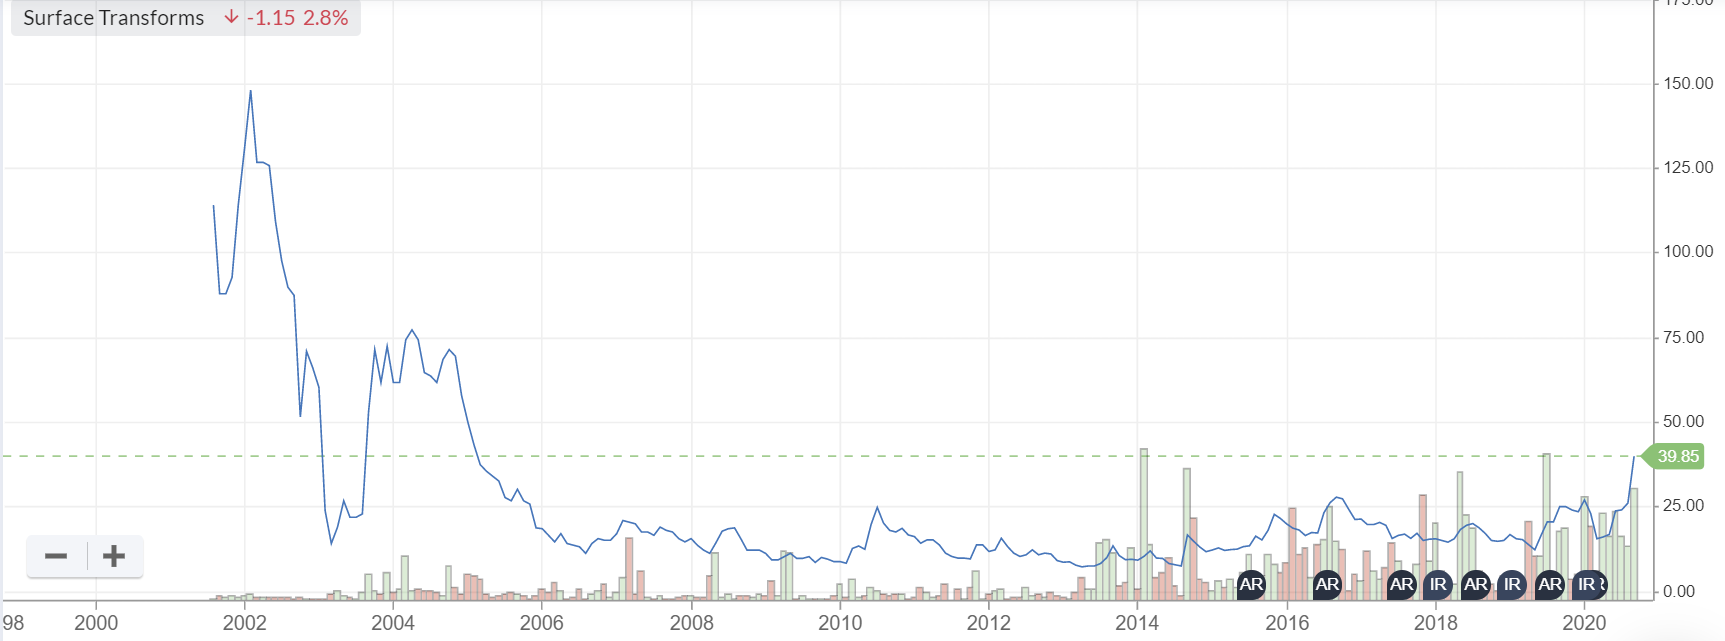
This company floated at almost exactly the time I became a full time investor in Sept 2002. Since then its track record has been lamentable - e.g. it took 10 years just to reach annual revenue of £1.0m. It's lost money every year, and forever promised a bright future for its carbon ceramic brakes, which never seemed to materialise. Until now.
News yesterday of what looks like a decent sized contract, could mean its time may have finally come. I always say that blue sky shares nearly always take far longer, and cost far more than originally planned. 18 years is really pushing the boundaries, but who cares - the contracts now appear to be rolling in for supercars by the looks of it.
So I'll be taking a closer look.
18 year chart below - patience is a virtue!
.
.
Cerillion (LON:CER)
295p - market cap £87m
This is an RNS title that grabs the attention!
Cerillion, the billing, charging and customer relationship management software solutions provider, is pleased to announce its largest ever contract win in an agreement worth £11.2m with a major UK provider of enterprise connectivity solutions. The majority of income, including software licences and services, is expected to be recognised in the next 12 months, and the contract has an overall term of five years....
The contract was awarded following an extended competitive selection process, and delivery is scheduled to begin immediately.
That sounds more like a perpetual licence type of deal, than SaaS, given that the majority of the income is going to be recognised in the next 12 months, although maybe some will be recognised in FY 09/2020 also? This suggests FY 09/2021 is looking to be a blow out year.
To put this in context, current consensus is for revenues of £22.1m for FY 09/2021, so this is a big deal, quite literally.
Clearly good news, but we're not given enough detail to work out how much the share price should go up.
This is the latest demonstration of the ongoing momentum of the business and increasing recognition of the quality of our solutions."
It certainly is. CER shareholders look set to have an enjoyable day (I'm writing this before the market open).
This does look a very good company, which is already decently profitable. This extra major contract should see results rise considerably. I'm impressed.
Broker update - there's a helpful note from Liberum just out, providing additional colour on this contract win. Although I don't understand why Liberum has not raised its forecasts. Maybe this deal was already baked into its forecast, I don't know. It says the pipeline is strong, and expects further contract wins.
Looks like a company on a roll.
.
Beeks Financial Cloud (LON:BKS)
Share price: 92.5p (up 1.7%, at 11:02)
No. shares: 51.2m
Market cap: £47.4m
Beeks Financial Cloud Group plc (AIM: BKS), a cloud computing and connectivity provider for financial markets, is pleased to announce its final results for the year ended 30 June 2020.
I've followed Beeks for a few years now, and it is an impressive little growth company, in an unusual niche.
I last reviewed it, here on 4 Aug 2020, on publication of a trading update. I noted that broker consensus earnings had come down a lot, and because of that felt the share was looking pricey at 96p, a PER of 43.5 at the time - too high.
Results for FY 06/2020 have come in a bit better than expected, with underlying EPS of 2,52p (down slightly on 2.58p LY). That's a PER of 36.7 - still high, but a bit more palatable.
Revenues are up a respectable +27%, and gross margin up more at +30%. That's good. Increased costs seem to have absorbed most of the benefit of that, with underlying PBT up only 8%. Short term profitability isn't everything though, and it can make sense for tiny companies like this to increase spending if that's going to drive future growth. I see that it has opened 7 new data centres internationally, rising from 11 to 18, which is quite a step change.
Outlook - sounds confident about further growth;
· Positive market environment and considerably increased sales pipeline
· Confident in securing additional Tier 1 customers in the year ahead
Share based payments of £312k are questionable as an adjustment. I see that as a payroll cost, not a one-off.
Balance sheet - OK, but note that debt + contingent consideration now total £5.4m, not a problem level, but up quite a lot in the last year.
Cashflow statement - OK, but note increased capex, now at £2.8m for the year, and it capitalised £720k in development spend. So it's not really an asset-light business model any more.
My opinion - a very interesting little growth company. I think it's likely to take several more years to gestate, so I can't see any particular reason to rush out and buy now. Probably priced about right for the time being, but with good long-term potential. Covid is bound to have slowed down new client acquisition.
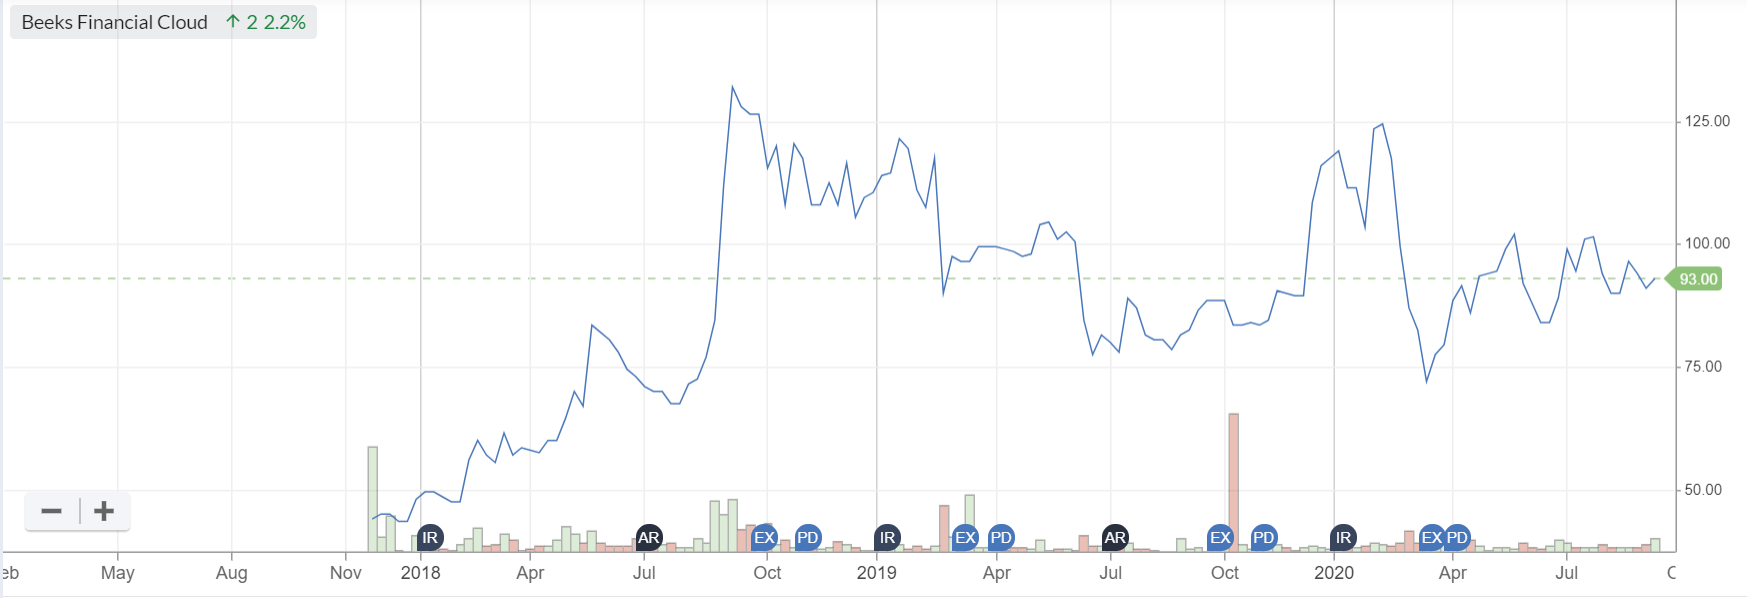
Here's the chart below of Beeks since it floated in Nov 2017. As you can see, investors got excited about growth a couple of times, but expectations then moderated.
.
.
Filta Group (LON:FLTA)
Share price: 98.5p (unchanged)
No. shares: 29.1m
Market cap: £28.7m
Details here of a private investor presentation from the company, on 24 Sept at 14:00 - well done to the company for engaging with investors, and to all the other companies that are now also doing these tremendously useful online results presentations. It really should be standard practice for all companies.
Interim Results - this company provides services to commercial kitchens, so I would expect it to be having a bad year, given closures of restaurants from covid, and the many restructuring/insolvencies in the sector.
H1 numbers look reasonably OK in the circumstances;
Revenues down 32% to £8.3m
H1 loss before tax of £782k (vs H1 LY profit of £474k). This is after charging £468k amortisation, which I'm happy to add back, so the adjusted loss was £34k - near enough to breakeven, so that's OK.
Balance sheet is weak, but not alarmingly so, with NTAV of just £0.2m.
Liquidity looks OK, with cash of £3.2m, although note that this is more than offset by borrowings, giving net debt overall of £0.6m.
Outlook comments are quite vague, and talk mainly about the uncertainty surrounding covid.
My opinion - it should recover in time, and I don't think there's any risk of insolvency. I think the business needs to grow considerably, in order to reach scale where it would interest me as an investment. At this stage, I don't see any appeal to owning this share. I think there are better opportunities elsewhere. Sorry about that.
.
This is a bit of chore today, because I'm not really interested in any of these companies reporting today. But let's plough on regardless.
Simplybiz (LON:SBIZ)
Share price: 155p (up 5% today, at 14:55)
No. shares: 96.8m
Market cap: £150.0m
I'm quite surprised this share has not bounced back after the general market plunge in March. I would have thought its services on recurring revenues, would be quite robust i a downturn.
SimplyBiz (AIM: SBIZ), a leading independent provider of compliance, technology and business services to financial advisers and financial institutions in the UK, today announces its unaudited results for the six months ended 30 June 2020.
Revenue is almost flat at £28.9m (H1 2019: £29.1m). It looks as if this was boosted by an acquisition kicking in this period;
... six full months trading from Defaqto which helped offset a significant reduction in valuation income during the period.
Various performance measures, such as operating profit, and EBITDA are mentioned, but since IFRS 16 came in, these can be distorted. So personally I prefer to work on profit before tax (PBT), and then adjust out goodwill amortisation. By this measure, PBT was £4.4m + £1.0m amortisation related to acquisitions = £5.4m (vs LY of £6.3m). That looks a reasonable result in the circumstances, as some parts of the group were impacted by covid.
EPS is the simplest figure to use, adj H1 EPS was 4.22p (LY H1: 5.57p)
Full year guidance is provided, at no less than 11.0p - a PER of 14.1
Dividends - no interim divi is proposed (LY Interim divi was 1.41p)
Outlook - continues to be in line with expectations.
Cashflow statement - it doesn't look very cash generative, which surprises me a bit. Of the £8.3m increase in cash in H1, £7.0m derived from drawdown of a loan. Although it did pay out £2.76m in divis. £1.36m in development spending was capitalised in H1, thus making EBITDA an optimistic number.
Overall, I think the group should forget divis for a few years, and instead concentrate on paying down some of the debt.
Balance sheet - is weak. NAV is £68.8m, but this includes a massive £106.0m in intangibles, from all the acquisitions. Take that off, and NTAV is heavily negative, at £(37.2m). This gap is financed by bank borrowings, with long-term debt of £44.7m. Liquidity looks fine though, as it is also sitting on a cash pile of £18.9m. Net debt looks more reasonable, at £25.8m, and that is coming down.
A recurring revenues business like this, with little in the way of fixed assets, can arguably operate OK with a negative balance sheet, but it increases risk, and means there's less cash available to pay out in divis. So we do need to adjust for that in the valuation.
My opinion - neutral. The balance sheet is the main negative for me. A PER of about 14 looks about right, in my personal opinion. Adjust for the debt, and that would rise to about 16 or 17, which seems about right. Overall then, I don't see enough upside to get me interested. It's an OK business though.
.
Avingtrans (LON:AVG)
Share price: 240p (up 5%, at 15:54)
No. shares: 31.4m
Market cap: £75.4m
Notice of results;
Avingtrans PLC (AIM: AVG), which designs, manufactures and supplies original equipment, systems and associated aftermarket services to the energy and medical sectors, announces that the Group's preliminary Results for the period ended 31 May 2020 will be published on Wednesday 30 September 2020.
A reader complains in the comments below that today's update from Avingtrans tells us nothing. I'm not keen on the wording used below - it says order intake is in line with expectations, which is not necessarily the same thing as trading being in line with expectations. So this is a little ambiguous.
Overall order intake during the first quarter of the financial year (1 June - 31 August) has been in-line with management expectations and trading conditions are gradually normalising.
Various new contracts are mentioned, but these look quite small, relative to forecast revenues for FY 05/2021 of £135m.
Broker updates - many thanks to N+1 Singer, and Finncap, who have both made available on Research Tree useful update notes today. N+1 point out that the company has previously given guidance for FY 05/2020 at 15.2p EPS, a PER of 15.8 - which seems a reasonable valuation.
Guidance for FY 05/2021 is currently still withdrawn, but expected to be resumed at the time of the results being published on 30 Sept.
My opinion - I've only got limited information to go on, but I can't see anything alarming in any of this. It seems quite a decent group of companies, and trading reasonably well through covid by the sounds of it.
.
Cohort (LON:CHRT)
653p (up 6%) - mkt cap £267m
This is a group of defence-related businesses. It seems to be doing well, and the market likes the update today.
Cohort continued to make good progress in its financial year ended 30 April 2020, achieving a record adjusted operating profit despite the impact of COVID-19 restrictions in the final two months.
Order book has risen from £183.3m to £210m in the last 4 months.
83% of FY 04/2021 revenues now secured
Liquidity is fine.
We continue to expect that our trading performance for 2020/21 financial year will be in line with that achieved in the year ended 30 April 2020, as indicated at the time of the final results announcement in July. We expect net debt to remain flat for the year, after taking account of the acquisition of ELAC.
In the longer term, the Group continues to expect to return to growth, as it recovers the orders and revenue delayed due to COVID-19, whilst benefiting from the acquisition of ELAC.
My opinion - I don't know enough about the company to form a view either way. If the broker forecasts are reliable, then a forward PER of about 17 looks fair.
I'll leave it there fore today. See you tomorrow!
Regards, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

39 comments
Re Manolete Partners (LON:MANO)
HURT FEELINGS
I sold my holding after receiving a rather rude response from the CEO a few months ago, which included the following sentence:
"I am not spending my valuable time conversing with someone who hasn’t the decency to properly introduce themselves."
Despite having emailed him several times before, and received polite responses, this threw me, hurt my feelings and forced me to sell my holding to cope with the emotional pain suffered.
In case anyone is interested, the questions I asked and his responses, which he did not really put much effort into, can be found here.
For reference, my email to him was a few days before the short attack (which had nothing to do with me.)
TRADING UPDATE TODAY
As an aside, I just took a look at the update provided and noted that the company states that there are 40 completed cases so far this year, up from the 23 announced on July 3rd 2020.
I'm baffled on how to sense check this (which I think is important, having questioned moving case numbers in my previous email and not receiving an adequate response).
On July 3rd
A vintage table updated to June 9th (why not July 3rd?) was published and a reference was made to 23 completed cases so far in FY21. See below:
TODAY
A vintage table was published showing an additional 23 case completions vs June 9th (a coincidence on the 23?) (4+41+41+26 minus 23-33-33)and yet a statement that implies only 17 new case completions since the last update (40 -23=17)
Why is there a difference between my calculated 17 vs the extra 23 completed cases implied in the table below?
THOUGHTS
I'm probably too tired right now and the above is actually simple and very easily explained.
In fact in hindsight, it looks like it might even be a timing issue, with a July update containing information only updated to June.
But I guess that's what continues to put me off. Reading these numbers should be simple, and yet I find myself continually confused.
It's a shame as there are lot of positives to read from this company, but sadly I shall continue to watch from the sides.
GLAH
A
Hi Paul, trust you are safe and well. I’m surprised you never covered KAPE today. Some impressive numbers imo. Is there a reason why you don’t cover it?
Hi Andy, i too was hoping for a bit of Kape Technologies (LON:KAPE) commentary from Paul, but no deep dive, not just even a surface level dip.
There’s a number of risks with a this share, and a few don't like from past comments but as long as this isn't a fraud because its Israeli owned, interpol don’t ban VPN’s, the growth potential is huge.
Its down 6% today, maybe thats because the subscriber numbers are not that impressive but it looks due to integration delay from the big acquisition and would seem due to pick up now the new products are on the marketing platform.
Manolete Partners (LON:MANO) issued a positive trading update just before the close.
Hi FREng. Have just been reading through this - I could be wrong but it felt like a response to the SP heading south, rather than a planned update. Manolete Partners (LON:MANO) ended last week at 340p (it was over 500p in July), fell sharply again yesterday and is now back at 340p after the update. All of this turbulence is in response to a short dossier on ShareProphets, to which it responded here.
Apart from the poor timing (why not wait until after markets had closed, or better still 0700 tomorrow?) this is a helpful statement including a "vintages table" of all cases underway and previously completed.
It's not really a TU in the conventional sense - there is no confirmation on whether current trading is above the board's expectations, nor whether the profit contribution of £2.1m from this case was already baked-in to broker forecasts. My reading is that the company would have said if this was the case, so best to assume that forecasts are unchanged. The company has a March year-end so we'll know more at the interims in November.
My take is that this is a well-run company, growing at pace but looking expensive against peers such as Burford Capital (LON:BUR) and struggling to recover from the reputational damage caused by the ShareProphets article. It's on my watch list but no position. Paul did an excellent write up here on 3 July (1st company in the list) factual and impartial as ever.
the short sellers smashed up that valuation basis for Burford, and hauled it down to a P/NTAV of only 1. What's to stop them doing the same thing with Manolete?
Prophetic words! The short dossier was published a couple of weeks later.
Manolete Partners (LON:MANO) I took a look at the latest official insolvency stats and contrary to expectation insolvencies are much lower than prior periods. This will impact medium term leads for Manolete. My assumption is that this due to a combination of government support for firms in distress (I bet HMRC hasn't been aggressive) and the courts and insolvency industry not working at full pace. It is likely to pick up again but the situation won't help sentiment.
I hold
At some point when the "temporary" measures in the Corporate Insolvency and Governance Act 2020 lapse there will surely be companies being wound up as fast as the courts can deal with the cases? Does anyone know when those "temporary" restrictions end - I thought they had already expired but it seems not. Perhaps they will last as long as companies can plausibly blame their woes on Covid?
I imagine all manner of dodgy dealings are being covered up at the moment.
I don't hold Manolete Partners (LON:MANO) and in fact I haven't looked at them in any detail but your comment :
was interesting,
Over and above what you have said about Govt support, hasn't there also been an effective curfew on foreclosing on leases?
When you say "it is likely to pick up again" isn't it more a case of there been potentially substantial pent up demand once companies that are essentially in a persistent vegetative state finally have their life support turned off?
Surely, so long as players like Manolete Partners (LON:MANO) don't themselves become insolvent in the meantime, then for them the "sunny uplands" must surely be in sight?
Terrible close for Carr's (LON:CARR) down 14%. What happened?
Looks like one seller sold 11,000 in tranches between 16.28.20 and 16.28.29, at prices going down from 110p to 105p. There were three purchases after that totalling 9,906 at 103.5p.
I hold.
I am not sure to be honest.
I put Carr's (LON:CARR) on my watchlist along with Wynnstay (LON:WYN) following a write up from Jack a while back. They both went up nicely and then Carr's (LON:CARR) has been just descending since then whilst Wynnstay (LON:WYN) has held the gains.
Planning to pick up Carr's (LON:CARR) once it stops descending and holds for while, then again I missed out on the rise on British American Tobacco (LON:BATS) as watched it go down having sold out and then missed the bounce...
But then I have had similar situation with Headlam (LON:HEAD) today, nicely up about 15:00 and then plunged (second day running) on the run up to close to end up further down...
I got caught with British American Tobacco (LON:BATS) while swing trading it during the last decline. I’ve just held it for last couple of months - my read is these defensive companies with large divi’s are being sold off after the divi - then rebounding in the month before the next ex-date. I might be wrong about this but have seen the pattern play out in most utility/ defensive companies since March (and have profited from it mightily this year). I’d love some more experienced players to weigh in on this - am I just seeing what I want to?
British American Tobacco (LON:BATS) is particularly difficult case - it is obviously benefiting from the decline in Sterling recently and general interest in tobacco sector so not sure how much of rise is divi funds and hunters chasing and my own wishful thinking - targeting 3100p though
Multibaggers with 10 Bagger Potential - Vectura
Vectura (LON:VEC) added to report
BSV
Rotala (LON:ROL) Half year results do not look to bad under the circumstances. Small profit before exceptionals (quite a lot of Covid related exceptionals including Diesel hedging loss ).
Cash positive. Passenger numbers running at 54% of one year ago and rising. Have not resorted to government loans other than the furlough scheme.
A play on Covid and the government success in getting us back to work/school/etc.
I would really appreciate a comment (or two) on Bango from Paul or anybody else please
People probably already know I have been pretty bullish (and long) on Bango (LON:BGO) from around 80p. I think it is a highly misunderstood business that appears to be artificially highly rated but should be doing well over £10m+ of cash profits in the next couple of years. That will put it on 15* cash profits, which I consider pretty cheap. People have waited until this inflection point of positive cash and operational gearing kicking in before giving the company the benefit of the doubt, which I suspect is why it has only really re-rated and then held ground in the last few months as this has been evidenced. The data analytics business Audiens should also do superbly well in my view given its backing and can add a lot more value to the company.
I believe the Surface Transforms (LON:SCE) presentation is on Thursday.
The Brembo-SCL competitor has taken many years growing at 16.6% PA. Obviously the competitor has the benefit of a brand name and a reputation.
Surface Transforms claim their product is technically superior and can be made lighter due to improved thermal conductivity from continuous carbon filaments. That apparently allows the discs to be made lighter, therefore reducing cost.
However, I would estimate that the Surface Transforms manufacturing cost has to be higher, due to more care needed in putting continuous carbon fibre into the mould. Brembo-SCL just tip it in, as can be seen on a You Tube video.
Also, carbon discs will typically be made in the largest diameter that can fit in the wheel, for braking efficiency and appearance, since this expensive option on high performance cars must be something of a manhood extension. I suppose they could save weight with larger vents.
I also think the current share price is already assuming a lot of success, for a company that has being promising jam tomorrow for almost 2 decades.
I'd like to know what projections people make to justify the current valuation, via DCF or whatever. I can't get anywhere near the current valuation, but am always willing to learn....
Surface Transforms (LON:SCE) Read somewhere benefit to electric cars who get energy from braking to top up the battery. F1 tech so maybe look there (Audi). Specialist barrier to entry?
Brake discs are normally made of cast iron and are prone to rust, particularly if hardly used.
Electric cars all have regenerative braking, so if driving very gently, the brakes might not be used much and will be prone to rust.
Carbon Ceramic brakes might help that problem.
However, as far as I can tell, the car makers are paying over £500 per disc for carbon ceramic discs. Which is one reason why they only tend to be an option on high performance cars, like Aston Martins etc.
Meanwhile, I can buy cast iron vented discs for a C-segment hatchback for about £12 to 15. That's the retail price. Car makers will pay less.
Admittedly these are a bit smaller than the discs on an Aston, but are of a size that should be perfectly adequate for the kind of electric car most people will be driving in 10 years.
Obviously spending £500 each for 4 discs on a Tesla model 3 is not going to be economic. It's much cheaper for Elon to say the existing brakes last the life of the car, whilst presumably "forgetting" about the corrosion. Unless they have some other countermeasure. Probably no more fanciful than full self driving, which just isn't going to happen without rendudnancy on safety critical actuation.
An excellent update from William Hill (LON:WMH) after the close last night has seen the shares above 225p today; a 52 week high. These fell to just 28p in March; I was able to buy easily enough at 30p because so many PI's were in panic mode and sold their stocks at any price . I think being older helps in the markets; you have learnt from experience that big shocks are always a buying opportunity given time. Even if there is a second wave, I don't think such falls will be repeated. With a lot of hindsight, we now know that lockdown has been the making of many companies. Unfortunately for the UK, mainly US tech companies. Where are the big techs in UK and Europe? None in the top 20.
Two companies report in the next two days that I am looking forward to (nervously in the first case). £GFRD....a construction company with a large cash pile (maybe) that is hitting 52 week lows regularly. This stock is either very cheap or the sellers know rather more than they should. £TSL....a play on tech giant Afterpay. The market is hoping for another special dividend.
Hi Peter,
I would read Paul's (brief) write up on Costain (LON:COST) yesterday and read across between the two companies.
Whilst they are in different leagues within the UK construction market and operate at times within different sectors they basically do the same thing, large value contracts with limited margin, if they go well then great, if they go badly, such as Aberdeen Western Bypass (which Galliford Try Holdings (LON:GFRD) were part of the consortium) then it is serious OUCH in this case the payment they asked for and didn't receive was more than the current market capitalization.
https://www.constructionnews.c...
So yes if you are lucky with timing and company, it can give a good gain and dividends, but it comes with a very clear risk.
Oh yes ex-Carrillion were sunk on the Aberdeen job...
Cheers
Tommy
Thank you Paul for this mornings write up on £CER. When I bought this share last year it had a good Value Rank and the PEG was below 1. However, with Stockopedia showing the PEG recently rising to 2.3 I was beginning to wonder if the share price was becoming over valued. Hopefully, this contract win will bring the PEG back down to earth but like you say, there isn't enough detail to work out were the share price should be and hence what the PEG should be.
Can I just say that I agree with you about yesterdays Pre Amble about avoid buying blue sky companies and companies which promise jam tomorrow. Like you, I find that buying high quality companies which make a profit and have little or no debts means they have more money to pay dividends rather than have to pay interest to the banks or dilute shareholder value through fund raisings. Keep up the excellent work.
Interesting webinar from Mirriad Advertising (LON:MIRI) yesterday. For those who couldn't make it there is a write up on the stockopedia discussion page and a recording of the webinar can be viewed here.
Does Avingtrans (LON:AVG) qualify for a record as giving the least information ever in an RNS headlined as a "trading update"? "Trading conditions are gradually normalising" is the substance of it.
Lol, read J D Wetherspoon (LON:JDW) update on Monday - it may be an example of the worst TU I’ve ever seen. Several pages of guff from Tim Martin repeating the same anti-lockdown message he has been going on about since the market lost interest in Brexit - zero usable data.
Total information gained: sales were down 22.5% on the Saturday before the update. They were duly punished - the TU said they had only had 66 cases of CV19 across all staff since reopening. IWeb reported same story as “shares in JDW fell 4% as it emerged they had had 66 cases of CV19 since reopening”.
I’m just bitter because I closed my short position on Friday - forgot how tone deaf Tim Martin can be
Beeks Financial Cloud (LON:BKS) thought this was a decent set of results. The more important element to watch is the recurring revenue at the start of the year as this is a good guide to growth. It was £11.2m so this year should be up 20% before any new contract wins, thus a 30%+ growth rate seems reasonable to me. That should translate into EPS of 3.5-4p as there is some operational gearing in the mix. Kind of feels like fair value to me around 85-110p (20-30* earnings) so unsurprised there wasn't much move in price this morning. Tier 1 wins should start to propel that forward a bit though. On the whole I am still bullish then and remain happy to hold as I can see a 30%+ upside over next year or so and recurring revenues are always well received by the market.
Hi David, I can't work out what to make of the results because of the adjustments (which I readily confess to not understanding in general). Are you happy to adjust out the share-based payments, which have ballooned this year? If I understand correctly, these look set to balloon further over the next few years due to the options granted in October. I'm assuming that these are definitely going to vest despite the (I think undisclosed?) "challenging performance conditions"...
Hi - I know Paul thinks these are more a payroll item and prefers not to adjust them out. I see them more as a dilution.....note the below states that the company expect to (a) meet the vesting criteria and (b) meet the contingent first earn out for Velocimetrics
Thus the diluted EPS of 2.45p is actually taking into account that these options will become shares and using the increased share count measured against profits.
So to my mind the adjustment to profit is an accounting adjustment of fair value. This will not affect cash coming out of the business and the EPS is already taking the issuance into account. As long as this happens then not taking the fair value adjustment out of underlying earnings is effectively double counting the effect on EPS unnecessarily.
So irrespective of the options value I see EPS growing 30%+ this year toward 3.5p even if they don't win a Tier 1. They have invested in 5 data centres and these take 12 months to b/e so we haven't actually seen the operational gearing take effect yet in the EPS. So i think risk to upside of 3.5p as all this kicks in. Then latterly I think SaaS based analytics could be a really interesting business which will be highly rated if it proves successful.
For me then I'm happy with a 1year fwd PE of 25 based on conservative fully diluted EPS of 3.5p. I can easily see a case for that being 4p-4.5p. What they do is pretty difficult to replicate which creates a decent moat and should result in an equally decent ratings multiple.
Included in the weighted average number of shares for the calculation of underlying diluted EPS are share options outstanding but not exercisable. It is management's intention that the Company will meet the challenging growth targets therefore, based on management expectations, the share options are included in the calculation of underlying diluted EPS.
Also included in the weighted average number of shares for the calculation of underlying diluted EPS are the shares that will be issued to the owners of Velocimetrics in relation to the first earn out period ending 30 June 2020. The target earn out amount has been agreed following the statutory audit therefore these shares are included in the calculation of underlying diluted EPS.
As you've mentioned Surface Transforms (LON:SCE) again, I thought I'd add the post I just put on yesterday's thread...
Surface Transforms (LON:SCE) are in an interesting position because ceramic brakes are widely used and there is only one other competitor in the space. You know this, other readers may not.
The problem SCE always was going to have is initial orders. Brakes are mission critical components: if they fail, people die. And so no manufacturer wants to take a chance using a new brake supplier unless they are certain they work. Now SCE has 2 major clients, given that their product is better than the alternative, it is quite possible that they will quickly become the main player in this industry.
So having been a basket case company for 10 years plus, they are now in a sweet spot imo. I see no reason why there won't be many years of growth for SCE from here. They've done the hard work, its a market which has been a monopoly dominated by a BMW owned company that most manufacturers would want to be free from, and SCE have a superior product. I think for investors looking to park some money for a few years SCE will be a very good place.
I know Marks And Spencer (LON:MKS) isn't small but is definitely value....todays Ocado (LON:OCDO) trading statement would appear to be pretty positive to me. I know Paul invested earlier this year for recovery...seems like this deal may end up looking pretty good for £MKS. Pretty much impossible to forecast at the moment but if it avoids a rights issue it could end up looking very cheap indeed.
"New Look - in today's news, rumours are that BOO is interested in buying major competitor New Look."
From yesterdays SCVR.
That must have brought a smile to your face Paul! I remember your detailed analysis of New Look on The Motley Fool messageboards long ago (showing our ages here), I was a New Look shareholder in those days, even to this day it remains one of my most profitable investments. It just kept going up until it was eventually taken private by the founder.
Thanks to New Look and a couple of other lucky picks, for a few years I actually thought I was a good stockpicker, but I soon learned that the stockmarket is very good at humbling the arrogant. As the great author Douglas Adams wrote "We live and learn -or at least we live."
Yes, I remember NEW being a listed company too. It began its stellar growth prior to that, in the early 1990s, when I was the CFO at Pilot (a smaller competitor). I remember my boss scornfully commenting that NEW was only growing through reverse premiums (cash bungs from landlords as incentives to sign leases). But he was wrong, NEW was actually a great business, which got the product right for the younger female demographic, and they wiped the floor with us over the next decade!
Pilot went bust 3 years after I left, and now both the mighty New Look, and Philip Green's Top Shop are being crushed by BooHoo & Primark. The ironic thing is that the Kamanis were our biggest supplier, through their wholesale businesses, called Pinstripe & Jogo. At some point the penny dropped with them that they could sell direct to the end customer, and cut out the retailers sitting in between. What an insight that turned out to be, it's made them billionaires!
It's been a fascinating time watching the internet completely change retailing. A lot of people thought it would never catch on. I remember buying a £400 digital camera, taking some photos of clothes, and setting up a small website, purely to show my colleagues at Pilot that clothing could be displayed and sold online. They were amazed, and grudgingly admitted that there might be some potential for online clothing sales after all! People wrongly though that customers would want to try things on before buying, hence would not take to online fashion shopping. That argument didn't make sense from the start, because of course catalogue shopping had been around for decades. All online fashion is, is putting the catalogue on a website, instead of printing & posting it.
It's amazing how existing businesses are often blind, or very slow, to adapt to new technology. The disrupters are often completely new businesses, rather than existing firms adapting.
At the time of its listing New Look actually had quite a decent management team, and their flagship, at the West end of Oxford Street was quite good.
I've fished out Paul's first mention of New Look on PaulyPilot's Pub on The Motely Fool, on 23/11/2000. I was by searching for "new look" on the web that I stumbled across TMF, Paul, David Stredder etc. A life changing find for me.
"A sustained recovery in the New Year in retail shares is forecast, and that rings true to me. You only have to look at New Look - I've posted my review of the Interims on the NEW Board here, it looks set to deliver full year EPS of around 16p, same as last year, with future growth potential largely intact, and these shares can be yours for a P/E of just 4.4
A little while ago you could have joined me in buying them at just over 50p, or a forward P/E of 3.1
Now how could a rally fail to happen from that point ??!!!
The small matter of New Look's easily sustainable divi yield of nearly 10% is the icing on the cake !!
A price target of around £1.20 a share is entirely justified in my view for New Look in the next 6 months, healthy businesses with sound prospects, that generate buckets of cash don't come much cheaper than this one. It gets a Paulypilot 10 out of 10 after reading the results today.
I wouldn;t be surprised if the shares slip back to low 60p's though in the short term, at which level they are a must-have. There just isn't any downside or uncertainty, given the robust nature of the results."
That's a great find Mr Contrarian!
I remember those posts clearly. In those days I used to spend most of my time at work reading the TMF and other financial messageboards, until for some inexplicable reason I was made redundant.
If I remember correctly soon after New Look the poster Paulypilot had a huge winner with Indigovision(?) but it looked too risky to me so I invested my New Look gains elsewhere in what I thought were recovery shares.but which just turned out to be losers. For years I kept fantasizing about how rich I would have been had I followed Paulypilot into Indigovision instead.
And yes, David Stredder too, I think under the name Carmensfella? He did some great write ups and research on a housebuilder called Ben Bailey which was a big winner.
if only we could turn the clock back 20 years or so.
Haha, I was pretty certain of my point of view! That was a really interesting time actually. The TMT (Tech Media & Telecoms) bubble that had built up in 1998-2000 finally began to crack from March 2000 onwards, with a stupendous bear market from then until early 2003, with many shares dropping from bubble highs to 99%+ down from the peaks.
The boom was so prolonged, and so irrational, that it sucked money out of other sectors. This created some astonishing buying opportunities such as New Look, on a PER of 3-4, as mentioned above by me in 2000.
I'm wondering if the current tech boom could yet have further to run. So a signal of it coming to an end, might be watching out for value investors capitulating, and value shares becoming incredibly cheap, with everyone just throwing their money at tech companies instead.
Valuations of the second tier tech companies in the US are now firmly in bubble territory, although I understand why the top tier (FAANG etc) are valued how they are, because they are remarkable companies.
Regards, Paul.
My morning smallcap tweet:
Bidstack (LON:BIDS) Cerillion (LON:CER) Eden Research (LON:EDEN) Evgen Pharma (LON:EVG) Cohort (LON:CHRT) Tex Holdings (LON:TXH) OptiBiotix Health (LON:OPTI) Mountfield (LON:MOGP) eve Sleep (LON:EVE) Good Energy (LON:GOOD) Corero Network Security (LON:CNS) £FY(Ju, Avingtrans (LON:AVG)
Bidstack (BIDS) has signed agreement with Ubisoft to deliver native in-game advertising for Hyper Scape, its futuristic, free-to-play, urban battle royale game, on PCs and consoles. [SP=5.05 Cap=20m]
Cerillion (CER) wins its largest ever contract, worth £11.2m, with a major UK provider of enterprise connectivity solutions. Majority of income, including software licences and services, is expected to be recognised in the next 12 months, and the contract has an overall term of five years. [SP=295 Cap=87m]
Eden Research (EDEN) gets first patent for Sustaine encapsulation technology ("Encapsulation of High Potency Actives"), in Australia, [SP=6.48 Cap=25m]
Evgen Pharma (EVG) licence agreement with Juvenescence for non-pharmaceutical applications. Worth $10.5m milestones plus royalties on sales. Monetises one element of Evgen's sulforaphane technology platform . [SP=12.49 Cap=17m]
Cohort (CHRT) continues to expect that FY trading will be in line with last FY. Order book £210.0m (£183.3m). [SP=616 Cap=252m]
Tex Holdings (TXH) proposes to delist after very long suspension after it was unable to supply audited accounts for FY18. Working with the Company's major shareholder on possible refinancing proposals. [SP=0 Cap=NA]
OptiBiotix Health (OPTI) grants US co exclusive license for large scale manufacture and commercialisation of a number of SweetBiotix® products. OPTI gets modest license payments until launch then royalties. [SP=49.94 Cap=44m]
Mountfield (MOGP) Tardy FY(Dec) out. Hunkers down in outlook: "Group Companies will take a cautious approach to securing their current and mid-term turnover targets and will concentrate on servicing the requirements of core clients on contracts which are neither onerous nor carry a significant risk element. The Board acknowledges that this policy will impact of turnover and net profit." [SP=0.9 Cap=2m]
Eve Sleep (EVE) H1(June) rev down 5%, pretax -£1.3m (-£6.7m). Notes very recently raised guidance. [SP=6.42 Cap=17m]
Good Energy (GOOD) H1(June) - U/L performance of the core business in line with management expectations. [SP=192 Cap=32m]
Corero Network Security (CNS) H1(June) rev up 48%, pretax -$2.7m (-$3.9m). Order intake, including Juniper resale partnership, building across H2, emand for DDoS solutions remain strong. [SP=8.42 Cap=42m]
Beeks Financial Cloud (FY(June) rev up 27%, U/L pretax up 8%. FY div flat. Outlook - "positive market environment and considerably increased sales pipeline, confident in securing additional Tier 1 customers in the year ahead." [SP=NA Cap=NA]
In line: Avingtrans (LON:AVG)
Hi Paul, could i request Kape Technologies (LON:KAPE) please, some negatives as tedi sagri having 69% but they are executing on their strategy.
Increasing global demand for online security and privacy solutions continues to underpin strong financial progress and user growth:
o Revenues increased 97% to $59.0 million (H1 2019: $29.9 million), a 12% increase on a pro-forma basis
o Strong growth in recurring revenues to $50.8 million, an increase of 140% (H1 2019: $21.2 million)
o Organic revenue growth in the Digital Privacy segment excluding PIA was 47% in the period, $17.9 million (H1 2019: $12.2 million)
o Adjusted EBITDA[1] up 185% to $16.4 million (H1 2019: $5.8 million), an increase of 21.6% on a pro-forma basis. Adjusted EBITDA margin increased to 27.8% (H1 2019: 19.2%)
o Operating Profit up 142% to $3.4 million (H1 2019: $1.4 million)
o Increase of 142% in Adjusted Earnings Per Share2 to 6.3 cents (H1 2019: 2.6 cents)
o Strong cash generation; adjusted operating cashflow of $8.8 million (H1 2019: $0.2 million). Reported operating cash flow of $5.9 million (H1 2019: ($0.3))
o Secured a new senior term loan and revolving credit facilities of up to $70 million in March 2020, significantly strengthening the Group's balance sheet
· Trading towards the upper range of management's expectations
I hold this and quite like the company. But think the comments in the RNS about the growth in subscribers in the acquired US business are just a bit luke warm. Basically that part is not really growing strongly enough yet IMO (was part of the rationale for the acquisition to leverage the existing user acquisition model), but when it does get going I can see the shares re-rating