Small Cap Value Report (Tue 16 Jan 2024) - CHRT, CARD, EQLS, MCB, CRN

Good morning from Paul & Graham!
Today's report is now finished.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. OR it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom),
Frozen SCVR summary spreadsheet for calendar 2023.
New SCVR summary spreadsheet from July 2023 onwards.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Other mid-morning movers (with news)
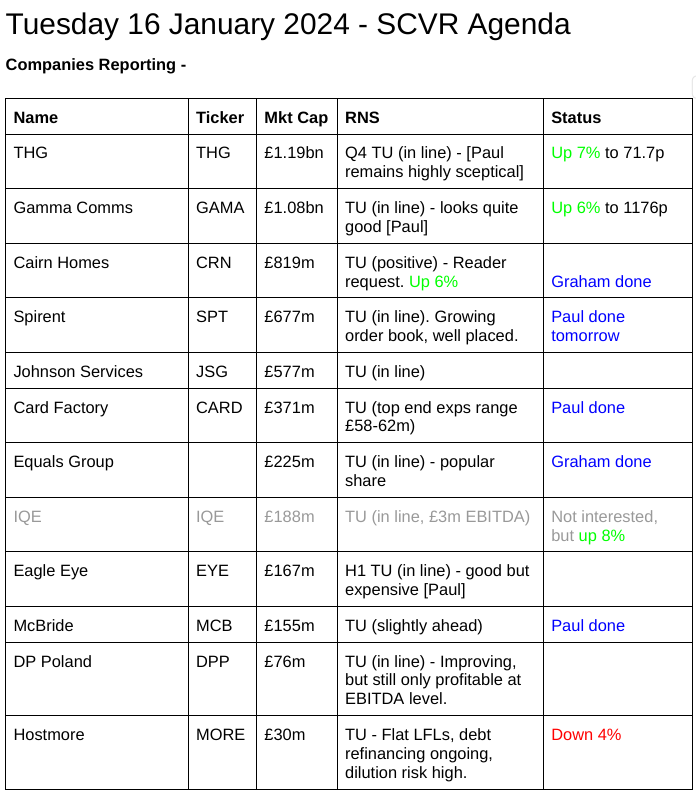
Northcoders (LON:CODE) - up 19% on big (£10m) contract win - looks potentially interesting, from a previous disappointer.
DP Eurasia NV (LON:DPEU) - up 5% to 100p - recommended & increased final offer.
Summaries
Cohort (LON:CHRT) (Paul holds) - down 1% to 541p (£224m) - Interim Results - Paul - GREEN
H1 results out yesterday look OK to me. Good growth in operating profit almost disappears by the time we reach EPS, thanks to higher finance and tax charges. Full year outlook (with a big H2 weighting) is confirmed in line. Huge order book, so good visibility. Balance sheet is fine. Despite recent rally, shares still look quite good value at 15x, for a quality business. EDIT: whoops, it turns out this was just the formal publishing of figures, and the originals were announced back in Dec 2023. So this section duplicates my review of interim results here on 13/12/2024. Sorry about that! Still looking at the figures twice is better than not at all! Thanks to grumpy5 for pointing out my schoolboy error.
Card Factory (LON:CARD) - down 8% to 100p at 08:34 (£342m) - Trading Statement - Paul - GREEN
Strange fall in price this morning, after its latest update says performance at top end of analysts range. Looks cheap to me, but selling overhang still seems to restrict any short-term upside. So one for patient investors?! The numbers look smashing to me, I think it might be usefully under-priced.
Equals (LON:EQLS) - down 3.5% to 115.74p (£217m) - Trading Update - Graham - AMBER
Equals provides an “in-line” trading update for 2023, which confirms the expectations set out in September. No update on the acquisition front, where there are ongoing talks with an American private equity investor. I remain neutral on this highly rated payments company.
McBride (LON:MCB) - down c.10% to 80p (£140m) - Trading Update - Paul - AMBER
Quite a good update today from this resurgent maker of white label goods for supermarkets. Debt still too high, but not dangerous any more, given much higher profitability, from a remarkable series of upgrades in 2023. Succumbing to profit-taking today it seems. Maybe the best gains have now been had? Still doesn't look expensive yet, providing higher earnings are not squeezed out in future by aggressive supermarket buyers?
Cairn Homes (LON:CRN) - up 5% to 120.8p (£811m / €941m) - Trading Update - Graham - GREEN
This Irish housebuilder reports operating profits in line with expectations for 2023 helped by a strong margin performance. The outlook for 2024 is very positive and supported by an enormous forward order book. I remain positive as the new-build market continues to boom.
Paul’s Section:
Cohort (LON:CHRT) (Paul holds)
(EDIT: sorry, this section is a duplicate of results I previously reviewed on 13/12/2023)
Down 1% to 541p (£224m) - Interim Results - Paul - GREEN
Cohort plc (www.cohortplc.com) is the parent company of six innovative, agile and responsive businesses based in the UK, Germany and Portugal, providing a wide range of services and products for domestic and export customers in defence and related markets.
Interim results are for the six months to 31 Oct 2023.
The Group achieved a strong first half, with growth in revenue, profit, and order book compared with 2022. The increase in the interim dividend reflects the Board’s confidence in the Group’s growth prospects and continued commitment to a progressive dividend policy.
Overall these figures look good to me, and the outlook for FY 4/2024 is confirmed as in line with expectations, with nearly all revenues already visible and ordered (95% full year revenue coverage, and a strong pipeline).
Revenue H1 £94.3m, up 22% (higher sales to UK’s MoD is noted)
Operating profit up strongly, +20% to £6.0m
H1 EPS only up slightly, from 10.12p to 10.36p - reason is higher finance charges and much higher tax charge than H1 LY.
As with last year, it confirms a big H2 weighting to profits this year too.
Massive multi-year order book is at a record high of £354m.
Order intake in H1 was £119m, 1.3x revenues, so healthy growth there.
Positive outlook in the medium term too, with more organic growth expected.
International conflict and tensions is an obvious tailwind for defence sector.
Balance sheet is good, with NTAV of £44m. Although receivables looks unusually high. Net cash of £13.3m is considerably improved from £0.6m net debt a year earlier. I get the impression there are considerable working capital swings throughout the year.
Cashflow also looks fine, with cash generated funding capex and divis mainly (also buybacks this year).
Valuation - broker consensus is 36.1p EPS (so a big H2 weighting as H1 is 10.4p) - hence PER is 15.0x
Forecasts are for only a slight improvement in FY 4/2025 EPS to 37.5p, leaving scope for upgrades I suspect, hence the PER would fall if forecasts are increased in future.
Paul’s opinion - this is one of my favourite value/GARP shares, offering high quality scores, an impressive long-term growth track record, carefully considered & executed acquisitions from time to time, long-serving and decent management, and a strong balance sheet. So it ticks all my boxes really for value/GARP shares.
It spent most of 2023 in a range from 425p-525p, and when at the lower end, was obvious value, which I flagged several times. The recent rise to 544p means there’s less value on offer, with the PER now near to 15x.
That said, it’s not my job to try and predict market prices, and as 15x is hardly overpriced, I’m happy to stick with my positive view, so it remains at GREEN.
Given the big order book and hardly any growth anticipated in forecasts, then this calendar year might produce ahead of expectations updates?
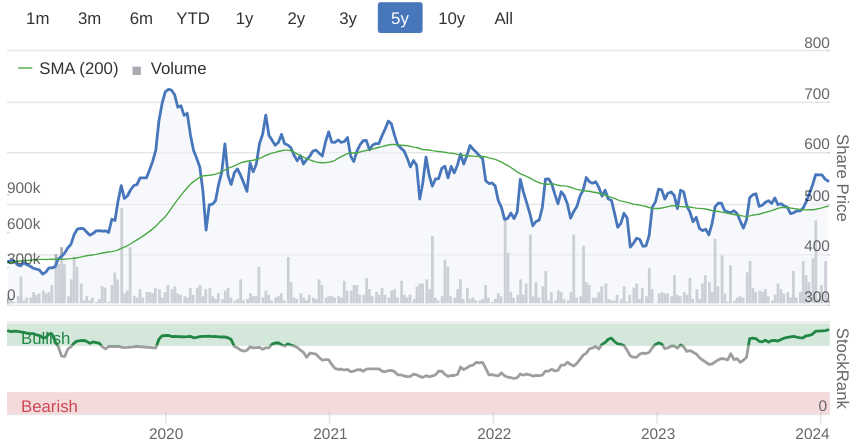
In the last 6 years, CHRT has usually commanded a premium PER in the twenties, so 15x now doesn’t look a stretch.
Good StockRank too -
Card Factory (LON:CARD)
Down 8% to 100p at 08:34 (£342m) - Trading Statement - Paul - GREEN
cardfactory, the UK's leading specialist retailer of greeting cards, gifts and celebration essentials, announces a trading update for the eleven months ended 31 December 2023.
Not quite year end then, but they should have a very clear idea now how FY 1/2024 will turn out. You might think greetings cards are old hat, but CARD was highly profitable & cash generative pre-covid, and has had a good sort out in recent years, and is now nicely back on track. The perilously geared balance sheet is now also no longer a problem, hence why I turned positive on CARD shares ages ago, and reported positively on it six times in 2023. The share price seems to have been held back by the largest shareholder dribbling out shares into the market - with the RNS showing its gradual selling.
That’s the background, what’s the latest? This looks good -
Full year adjusted profit before tax expected to be at the top of the range of market expectations
3 According to Company-compiled consensus estimates as of 15 January 2024, the current range of market expectations for FY24 adjusted profit before tax is £58.4 million to £62.0 million.
It makes analysis so much easier and more accurate when companies add these footnotes - everyone should be doing this. Apparently one or two dinosaur brokers actually stop their clients doing this - overrule or sack them, I say, if they try to stop a company communicating well with its shareholders!
Last year’s accounts show adj PBT c.£49m, when the boost from covid support is adjusted out. This year is likely to have a higher tax charge, as Corp Tax went up from 19% to 25% in April 2023 - something to bear in mind for all UK companies as a headwind, and quite significant size.
Other key points -
Strong store sales, up 8.2% LFL (11 months to Dec 2023)
Online still struggling, down -12.8% (but it’s a small part of the business - still a missed opportunity though) - improved a bit in Nov & Dec.
Outlook - all sounds on track -
Given the strength of performance in the year to date, the Board expects to deliver full year adjusted profit before tax (excluding one off items) at the top of the range of market expectations3 and remains confident in the achievement of the long-term financial and operational targets set out at our Capital Markets Strategy Update in May 2023.
Paul’s opinion - nothing is said about cash/debt position, which I think was a mistake. It’s not a major concern, but was previously, so I think investors probably would have liked some reassurance on that. Cash/debt is a simple enough figure to work out too, the company should have this info in real time - in my retailing CFO days, I reconciled all the bank accounts every morning, and that was 30 years ago! (for a business about a quarter the size of CARD though, and nowhere near as profitable!). I still remember the 14.4k dial up modem doing its “derrrrrrr, diddly diddly diddly” login process, it seemed almost miraculous at the time, as bank statements started coming out of the printer.
Another complaint is that CARD doesn’t get any broker research out to the great unwashed. Only the privileged get to see Peel Hunt notes on it, thus giving them an unfair informational advantage. So at this stage I don’t know if any brokers have updated their models, I would imagine the consensus will edge up a bit reflecting today’s positive news, and that usually drives the base year higher on their spreadsheets for following years. So small upgrades likely.
Around 13.5p EPS seems likely to this year. Put that on an undemanding PER of 10-12x, and I get to a target of 135-162p - well above the current price (08:31) of 100.5p (down 6%) - which strikes me as an attractive entry/hold price. So it’s another GREEN from me, but as always, make up your own mind.
This seems a share where holders need to be patient, as there’s clearly still an overhang of sellers. There’s always a worry that they might know something we don’t!
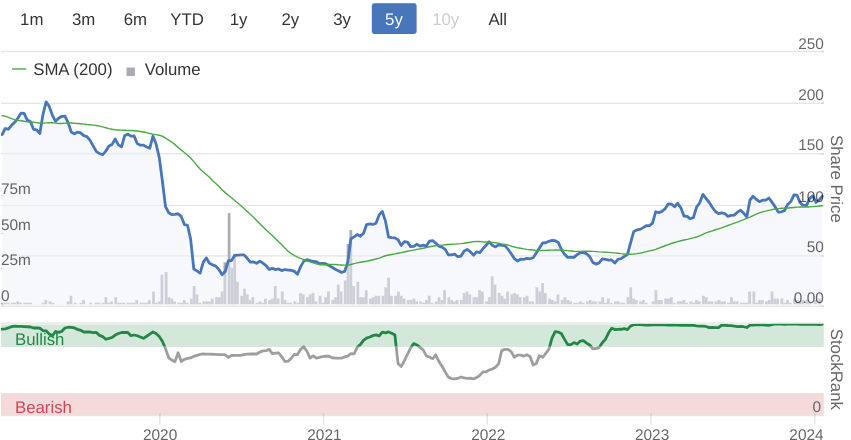
Note that there's been no dilution over the 5-years shown below, so in theory there's no reason why it couldn't return to previous peak share price, if performance continues improving. Very high StockRank too, encourages me -
McBride (LON:MCB)
Down c.10% to 80p (£140m) - Trading Update - Paul - AMBER
McBride plc (the "Group"), the leading European manufacturer and supplier of private label and contract manufactured products for the domestic household and professional cleaning and hygiene markets, today provides a trading update for the six months ended 31 December 2023 ("the Period").
An encouraging H1 update today -
The Group expects to report first half adjusted operating profit slightly ahead of our expectations.
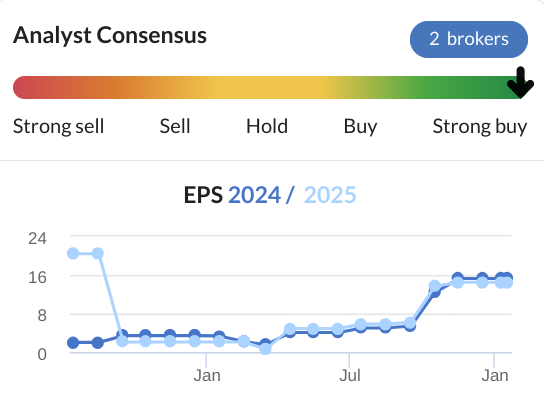
This comes on the back of stunning increases in EPS forecasts during 2023 -
Revenue growth of 10% combines both volume growth, and higher prices.
Inflation & supply chain - a bit of caution here - I'm surprised it says supply chains are still volatile, as most companies are saying the opposite -
While input costs have generally stabilised, energy, employment and financing costs continue to apply inflationary pressures. Additionally, the Group continues to manage significant supply chain volatility.
Net debt - previously at crisis levels, it’s now very much more under control - reduced somewhat, and with much higher earnings, heavy debt becomes less problematic. 2x EBITDA is within the range of what many investors and banks think is reasonable -
The Group's focus on reducing debt and maintaining tight control of costs resulted in net debt closing the Period at £145.7m (30 June 2023: £166.5m), with liquidity at £85.0m (30 June 2023: £59.3m), comfortably above the minimum requirement per the banking covenant. The Group continues to anticipate that net debt / adjusted EBITDA will be close to 2x by 30 June 2024.
As mentioned before, the bank has been extremely accommodating, which has enabled MCB to trade its way out of a crisis, rather than having to do a ruinously dilutive equity raise, which looked highly likely when the shares were bombed out.
So risk-takers did very well on this one, with it 4-bagging in the last year - well played!
Valuation - I can’t find any new broker notes. Going on the existing consensus figure of 15.3p for FY 6/2024, that gives a current year PER of only 5.2x. Although we do need to adjust for net debt being about the same as the market cap. If we eliminate the debt, then finance costs would fall a lot, so EPS would need to be adjusted up. So debt-free PER would probably be roughly something like 7-8x I’m guessing (haven’t got time to work out the detailed numbers).
That doesn’t look a demanding valuation to me, probably about right for this type of business?
Paul’s opinion - the big question is whether earnings are sustainable at this markedly higher level, or whether the supermarkets will once again squeeze the profit out, as they’ve done in the past?
I’ve read differing opinions on this, some saying that MCB has made effective internal reorganisations & efficiency savings (which often happens when companies are close to going bust), hence is now achieving permanently higher margins.
Or an alternative view is that it locked in some c.1-year contracts with customers that reflected higher priced raw materials, and is now making one-off margin gains as those raw materials are receding in price. Hence the next set of contract negotiations could tighten its margins again perhaps?
Also the debt has not disappeared. Servicing the interest costs, and reducing the amount outstanding suggests to me little prospect of generous divis any time soon. The last divi seems to have been paid in 2010!
So I see this as a low quality, overly indebted business, in a horrible sector (supplying supermarkets) that’s having an unusually good year, which may or may not continue in future.
Given the 4-bagging of this share, I can see why some investors are banking their gains today, on what has been a superb trade, no doubts about that.
I’m not convinced there’s quite as much upside potential from here on, but who knows, it depends on how it performs in future, which none of us knows yet.
Looking back at our reviews here last year, we reflected the improving performance, starting off at red, then shifting up to amber/red, before ending the year amber - good performance, but still far too much debt. I think that remains my opinion, which may well differ from yours, that’s the thing about opinions isn’t it! So I’m sticking at AMBER - some good points, and some not so good points, but nothing seriously wrong with it overall.
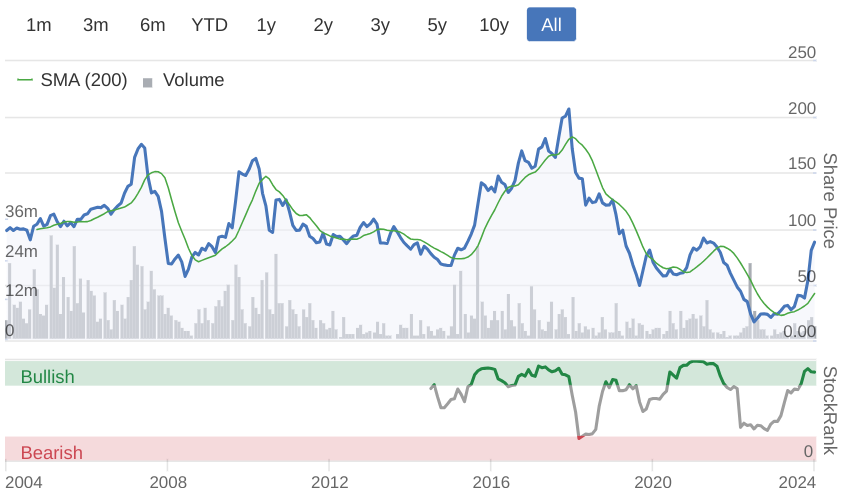
20 years to get back to where it started -
Graham’s Section:
Equals (LON:EQLS)
Share price: 115.74p (-3.5%)
Market cap: £217m
Equals Group plc (AIM:EQLS), the fintech payments group focused on the Enterprise and SME marketplace, announces, consistent with prior years, a pre-close trading update for the financial year ended 31 December 2023 ('FY-23' or the 'year').
This payments company put itself up for sale late last year. At the time, both Paul and I made some comments on the situation.
Here we are in mid-January and there is just one horse in the race to buy Equals, a Chicago-based private equity outfit. But will a bid eventually emerge and be presented to shareholders? We still don’t know.
I must reiterate that I found it unusual for a company in seemingly rude financial health and with good prospects to go out of its way to contact potential buyers.
But let’s turn to today’s trading update, which is in line with expectations. I believe these expectations were set following the September upgrade.
Key points:
Revenues up 37% to £95.5m.
Cash £18.3m at the end of 2023, plus another £2.3m received on 4th January 2024.
The company focuses on “revenue per working day”, which helps to strip out differences caused by bank holidays, etc. This metric reached £397.6k in H2 2023, with impressive growth versus H1 2023 (£362.9k) and H2 2022 (£301.6k).
CEO comment:
Whilst the Strategic Review announced on 1 November 2023 remains ongoing, we will continue with our plans in 2024 and look forward with confidence in our proposition, our teams, our technology and, ultimately, our sustained growth prospects.
Profit estimate: 2023 expectations, according to Zeus in September, were for adjusted PBT of £19.5m.
The company adds a disclaimer at the end of today’s RNS, in line with regulations, that profits for 2023 have not yet been fully audited - this is just a regulatory requirement.
Graham’s view
We have covered this one numerous times in the SCVR, and hopefully some readers have participated in its share price strength:
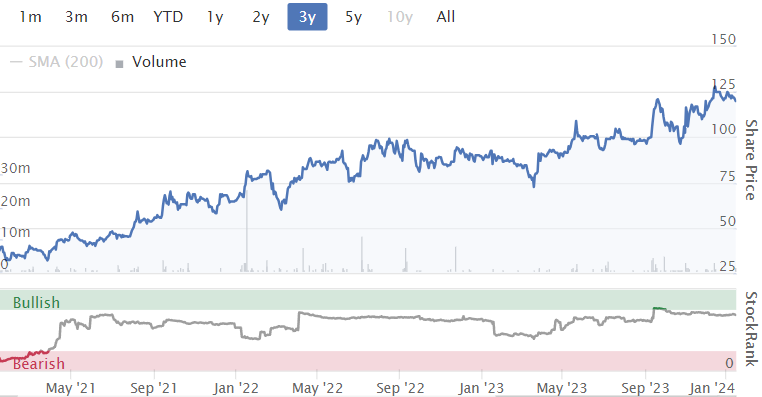
It’s a stock that I failed to get bullish on, due to heavy adjustments to its profit figures, what I perceived as a high valuation, and difficulty understanding its product set - a wide mix of B2B and B2C products.
With most financial stocks, including payments companies, I can instantly recognise what the company is doing or at least what it is trying to do. With Equals, I’ve never been entirely sure about their USP or what they are ultimately aiming to achieve. What do they have that makes them stand out from any other bank or payments provider? I still don’t know.
I do think the Equals Money website is attractive, and you can read many reviews from happy customers on Trustpilot.
Their ambition remains “to become the leading independent payments company of choice for SME’s and the professionally prosperous”.
Valuation is still on the higher end of the spectrum, and I’m remaining neutral on this one.
Cairn Homes (LON:CRN)
Share price: 120.8p (+5%)
Market cap: £811m
This Irish home builder reports a full-year update for 2023.
Key points:
1,741 new home sales (previous year: 1,526)
Revenues €665m (previous year: €617.4m) are just below the €675m level expected in September.
Gross margin 22.1% (previous year: 21.7%) seems to be a little better than expected.
Operating profit €113.4m (previous year: €103m) is within the range of expectations.
All in all then, 2023 has gone in accordance with the upgraded expectations.
The forward order book is over €900m, up from €374 million a year ago, due to 2,350 properties having been forward sold. A remarkable increase, “clearly illustrating the current demand for our homes across all tenures”.
Build cost inflation has cooled to 4% from 8%.
The company is focused on starter homes and notes that “over 80% of Cairn’s starter homes are available to our customers at prices which are below State support pricing caps”.
That may sound very affordable, but the price caps are set at up to €500,000, which is 60% higher than the median house price in Ireland! These aren’t cheap houses.
Share buyback - the company did a €75m share buyback in 2022, and is currently working on another €75m buyback it started last year. €42.6m completed so far.
The buyback - mostly done at lower prices compared to where Cairn is currently trading - is one of the reasons I gave this stock a green rating, as the reduction in the share count is significant.
But shareholders have also been getting a nice dividend; the company says:
Significant cash generation in 2024 and beyond will continue to fund consistent and growing shareholder returns.
FY 2024 Outlook is excellent:
Cairn starts 2024 with a forward sales pipeline of 2,350 new homes. Momentum is very strong entering the year with over 500 new homes due to close in the first three months of the year and 1,600 of our current forward sales pipeline expected to close in 2024.
Cairn is therefore poised to deliver an exceptional output and financial performance in 2024, and expects to deliver year-on-year turnover and profit growth of c. 30% and:c. 2,200 new homes;
operating profit of c. €145 million; and
15% return on equity.
Graham’s view
I don’t see any major reason to change my positive view here, even at a higher share price.
When previously covering this share, it was trading sub-100p.
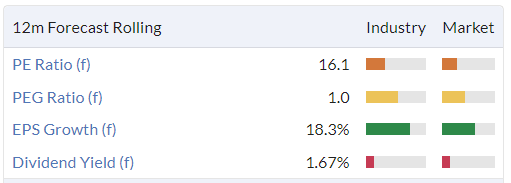
At 120p, it now trades at a modest premium to book value and at a more demanding earnings multiple:
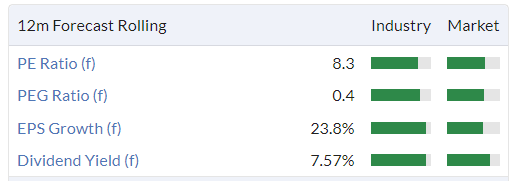
Even so, these numbers are justified to my eyes by the growth numbers and by the capital allocation - there are now only around 655m shares outstanding, vs. 755m a few years ago.
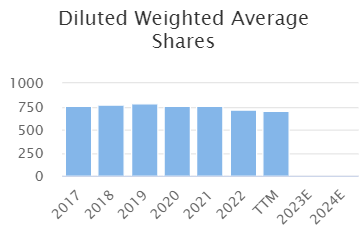
It should go without saying that this company - and its stock - are vulnerable to economic forces beyond its control and that there are unavoidable risks in the housing sector.
There is a degree of financial leverage involved, with net debt of €230m as of the end of H1 (forecast to reduce as inventories convert to cash). The company is also losing its CFO, with an “orderly transition” and “a smooth transition of responsibilities” being planned. Something to be aware of.
But my view is that if someone wanted to invest in the housing sector, this stock stands out as being of particular interest - a nice focus on starter homes where there is lots of government support and booming demand, and a great track record of profits, dividends and buybacks.
Cairn does command a higher valuation now than it did last year, but I see that as being justified. So I’ll leave my positive stance here unchanged.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

104 comments
Final post on Card Factory (LON:CARD) for today. Useful summary and broker comments on Proactive Investor - https://www.proactiveinvestors...
Card Factory (LON:CARD)
I have a medium size holding. Difficult to fathom the market reaction to a very positive update, down 11%. I suspect many punters expected an ahead of update given recent history, but the absence of a late November update suggested that this was not going to be the case. Also I see from 'X', Twitter that was, that Richard Crow, aka Cockney Rebel has significantly reduced his holding, which I suspect has also played a role in the sell off. For the time being I shall sit on my hands and see which way the wind blows.
Difficult first half of January, but plenty to play for.
So we have today Card Factory (LON:CARD) down 11%, McBride (LON:MCB) down 11% and Equals (LON:EQLS) down 6%, good job they did not put out poor updates. Tricky market.
Yes, I’m not sure I can take too many upbeat trading statements like Card Factory (LON:CARD) today!
Card Factory (LON:CARD) - It's my biggest position and today was really tough watching the SP grind down, all whilst knowing that the results show the company is doing well. At least with a profit warning you are mentally prepared after the morning RNS for a hit to the portfolio. I thought it would be flat, not 11% down!! The frustration will be even greater if over the next few days there isn't an RNS showing a decent chunk taken out of Tellios' mammoth holding. Problem is they held so much of the company they aren't clearing shares very quickly. Desperate for another institution to just wipe them out! Fingers crossed!
Graham/Paul,
Thanks for putting Cairn Homes (LON:CRN) on today’s list and covering it. I will do a bit more digging and may well open a starter position this week if I like what I find. They certainly look to be in the right place ATM.
Paul, didn’t realise you were in Malta, my wife has been watching the current Channel 5 series on Malta and has been hinting that we should go. Have a great break.
Gimmers Card Factory (LON:CARD) probably Teleios, who had c40m left to shift on last count, or possibly Stuart Middleton the former/original? Creative Director, who had sold a third of his and had 9m in hand in October.
Can't see the sp going further than the 110p area until at least Telios are out. Stuart may be happy to hold a little longer. Depends on his personal circumstances.
Hopefully an update on Debt/Divi prospects in the full year results may help. Drift til then? Would be nice if someone would take Telios out. If they have dipped below 10% now is that more likely?
Couple of companies finding some volume today/yesterday. Gresham Technologies (LON:GHT) Quartix Technologies (LON:QTX) Time Finance (LON:TIME)
Here's an interesting note that I made in my notebook about a decade ago that I thought I'd like to share ...
The idea is to calculate an incremental ROCE to see how much money it can currently/recently make on its capital. There are possibly a few problems with it, not least of which is that operational cashflows are subject to large variability.
To obtain the iROCE (incremental ROCE), take the difference in operational cashflows over 6 years and divide by the sum of capex over the first 5 years.
Some companies can have returns over 100%, which might seem a bit suss.
Unilever (LON:ULVR), which you might expect to have quite high iROCE, only came out at about 10%. SSE (LON:SSE), which you might expect to have a low iROCE, did in fact come out low, at around 6%.
Burberry (LON:BRBY), which is in the doghouse at the moment, actually has a respectable return of around 22%. Domino's Pizza (LON:DOM), which has wobbled a bit, has operational cashflows that have decreased. I fudged the figures a little, assuming that a more normal flow would be around 25pps for 2022, and came out with a figure of around 14%.
The results can be quite sensitive to the figures used, so you may want to treat it with some degree of scepticism. But it's an interesting exercise.
Return on capital is the basis of investing. It is just that there are distractions from this along the way.
Looks a decent update today from Gamma Communications (LON:GAMA)
Net cash £134, good free cashflow. Its not the fantastic 25-35% EPS growth of 2018-2021, more like 6-8% forecast but then the share price is 50% cheaper.
Talk of capital allocation at next results 25 March. Price has been in a long £10-£12 range for over 18 months, tend to find the longer the consolidation the better the breakout when it happens. Some good metrics also.
Any holders?
Yes Wolf, but only since last week... was attracted by the rock solid balance sheet and extremely low pe for a company in this sector, let alone the fact that it's still growing... with the cash flow generated, buybacks in the Spring would be a fantastic idea to break out of the range and cause a rerating as well.... I'm hoping to buy more after today's news, but trying to nickle and dime it ... will probably end up just buying the breakout instead on account of being too greedy...
Hi Wolf.
Yes I have held since 2021 and used recent share price weakness (when < £10.50 to top up). Ready and waiting for the shares price to break out of the narrow range. With a P/E of 14 (historic avg 30) and a solid balance sheet I believe the shares are cheap and will hopefully re-rate at some point.
Hi Wolf,
Gamma Communications (LON:GAMA) will almost certainly breakout at some point because I sold out in July 22 (!) after the big drop to the current range of £10-12. I did manage to top slice some profit at £19.86 but wished I had sold the lot!
Hostmore (LON:MORE) looking interesting imo. They have reduced net debt over the year by £5m and that was with the headwind of the horrible H1 they had prior to restructuring. Factor in those changes to a run rate basis and even if they don’t increase revenues then I reckon they will generate £10m of FCF for this year and net debt will be just £15m and well manageable. So I disagree with Paul that “dilution risk is high”. Certainly it is possible if they believe equity raise provides a better result/flexibility but this doesn’t look to me like a business that requires much/if any equity. I know management are keen to avoid it too. In my interaction with banks recently unsecured lending to business is feasible at 7.5% with EBITDA of 2*. That suggests to me that Hostmore (LON:MORE) should be able to refinance a good £20m as an RCF at reasonable funding costs given turnaround in performance.
So at £22m market cap feels like there could be a lot of equity leverage as that debt comes down over next 12 months, so I am long at these levels.
Central Asia Metals (LON:CAML), quite a jump in holding by FIL. I hold.
Yup, wonder who they are buying it from? We have quite high family weightings in this and I was considering buying more. I've held for over 3 years and am sorry they have not found a secure way to deploy cash yet, as the tonnage clock on Sasa begins to wind down, which may be depressing the share price case. This puts my finger back over the Buy button. But will wait to see if there's a divestment RNS to counter this later in the week.
Yeah, I am fairly ambivalent about Central Asia Metals (LON:CAML) per se. They seem to be at the better end of the smaller miners. I like the fact they have cash, their share count is not rising too much. I think the Kounrad operation is a good one, it seems as though the S/lb costs are fairly low and leaves them comfortable with a lower copper price. From what I can glean, I think the Sasa operation is ok, but not the success that they had envisaged at the beginning (zinc/lead isn't my investment thesis anyway). I dont like the geo-political risk in Khazakhstan.. but sized accordingly. As with most things, it is probably a choppy ride on the copper price between over exuberence in energy transition (which is going to happen, but not as quickly as anyone hopes or expects), and the likely recession and faltering market in China.
2 snippets from the Alliance News morning briefing on Interactive
Investment bank Berenberg said Northzone VI has sold its remaining
stake of around 5.2 million shares in Trustpilot (LON:TRST). The sale of shares in
the Copenhagen-based consumer reviews platform took place through a
placing, which was announced on Monday. Berenberg acted as sole
bookrunner and placing agent in relation to the placing. Northzone is a
venture capital fund that has backed Trustpilot for the past 12 years.
Northzone first backed Trustpilot back in 2011 as lead investor in a
series A funding round. That round valued Trustpilot at EUR7 million.
Since then, Trustpilot has floated, joining the London Stock Exchange
back in March 2021. It is currently valued at GBP690.6 million, though
shares are down from its 265p in initial public offering price.
City brokers Panmure Gordon and Liberum said they have agreed to an
all-share merger that will create the "UK's largest independent
investment bank" with over 250 quoted corporate clients. The combined
firm, to be called Panmure Liberum, will be led by Shane Le Prevost, the
founder of Liberum, as non-executive chair, and by Rich Ricci, the
chief executive officer of Panmure Gordon, as CEO. Financial support for
the merger will come from Atlas Merchant Capital, founded and led by
former Barclays chief Bob Diamond. The two companies said their merger
will be positive for the London equity market. "The creation of Panmure
Liberum will ensure that together it has the scale to be at the
forefront of key market initiatives to reinvigorate the appeal of UK
listed equities and of listing companies and funds in the UK," they
said.
Card Factory (LON:CARD) just seen Liberum Capital raised FY24 pre tax profit forecast by 6.3% to £62m and its FY 25 estimate by 4% to £66.7m, and also upped its SP target from 165p to 175p.
Quote - "We thinK the market has forgotten that Card Factory at its core is a disruptive, market-leading value player. We would also raise a note of caution that as Card Factory builds true momentum in its online business, one should maybe be concerned for competitors such as Moonpig and Funky Pigeon".
Personally I am scratching my head at the SP reaction this morning but WTFDIK?
hi Gimmers
Card Factory (LON:CARD)
How did you manage to get access to a Liberum broker note?
I thought Liberum broker notes were available on Research Tree (e.g Ramsdens broker note yesterday). I can't see anything on Research Tree today.
Sharepad have CARD's brokers down as Investec and UBS which would explain why nothing is on Research Tree but your reference to a Liberum broker note is a mystery.
Snazzy
Hi Snazzy - Went on Twitter - searched Card Factory - saw an article link to Shares Magazine and voila - its on the Shares Magazine news feed. :)
Shares News: Card Factory (LON:CARD)
https://www.sharesmagazine.co....
Thanks for sharing eParo
Decent upgrades on a value share and it’s down 10%. Shocker and a bit bizaare.
Just another example of how the UK market has become utterly disfunctional - if the market doesn't value things properly then these sort of companies will be taken private and you'll have no market left!
Cairn Homes (LON:CRN) Another Irish house builder that looks good value is Glenveagh Properties (LON:GLV) (I hold GLV)
Card Factory (LON:CARD) - re suggestions of a share overhang, I note that there are almost 4 million shares sold this morning compared with average daily total of 800,000!
I like Card Factory (LON:CARD) and probably is undervalued here but a couple of niggling doubts for me, and just to play devils advocate . PBT and EPS are only forecast to grow 2 or 3% this year (unless they've been upgraded today - UBS cut CARD to Hold and lowered target to 107p) . Tho this could be undercooking it to allow beats later on.
Minimum wage is due to rise 9.8%-14.8% depending on age in April, so will be a substantial cost to employers with large lower paid workforces. CARD employ almost 10,000 people, Id imagine a majority will be at or just above the minimum wage. Profit by employee is around £4.7k just now. Can see the potential headwind for profit growth.
Saying all this I still think its worth 10x earnings or 140p+
I had a look at Card Factory (LON:CARD) job openings, they already pay £10.73 - £11.13 to a number of staff, so the increase for them will be less than 9.8%, if they put the rates up to the new minimum rate. I couldn't find all the rates so no doubt there will be some who get the full rise. But overall it won't cost them as much as the headline figure, unless they choose to increase by that much.
It’s staggering that Card Factory (LON:CARD) is not trading higher to me.
Whilst they didn’t mention cash specifically net debt likely to be £40m or less given the results.
They will start paying a dividend most likely from May this year. They had to pay a debt tranche down due in January and once this is gone the restriction on divi’s disappear. So imo you will have a highly cash generative business capable of moving towards net cash over next year or so starting to pay dividends again with an EPS of circa 14p+ Is the clear market leader with plenty of scope for growth - should be trading on 11-12*
A fall of 8% on the back of being at rope end of most bullish analysts range whilst trading on a PER of sub 7 is bonkers to me.
Just checked again, and nearly 4.5m shares have been traded this morning …very much fitting Paul’s suggestion of a stock overhang from a large holding
Maybe Martin - If it is the large seller then you’d expect an RNS as it will be disclosable. I haven’t seen them reduce in a while though so I’m not convinced it is them. Let’s see.
Volume is indeed very high but actually only £5m worth against a market cap of £375m so could be anyone.
How do you access daily volume figures?
At the top left of the Stock Report you'll see 'Full Quote' in blue. Click on this.
Can't see that.
It is down towards the bottom of the page, don't know how up to date it is.
OK, I have found it now, not where I expected it. It is under the share price movement, really faint on my screen.
David I couldn't agree more. I know markets are imperfect but todays price action is ridiculous and Liberum make a good point re online and disrupting the likes of Moonpig and Funky P. With high street competition also getting squeezed and Card opening new concessions in other "value" retailers, in addition to designing and manufacturing their own cards, they have a great chance of grabbing a huge proportion of the market. As Paul said this could just be for patient investors - at some point Mr. Market will wake up....or at least I hope they will!
It is odd, some stocks are inline and the share price jumps up, such as Qinetiq (LON:QQ.) and MPAC (LON:MPAC) yet others beat or are top end and the shares fall quite a bit. I could understand it, if the shares had been soaring, like Warpaint London (LON:W7L) or MPAC (LON:MPAC). But they have hardly gone up in 4 months. PE is around 7. I think the fall is overdone.
As it happens, defense and security company Qinetiq (LON:QQ.) is on my radar (no pun intended) as a cheaper version of BAE Systems (LON:BA.). Its revenues have been growing nicely and are expected to continue. It has decent ROE, acceptable debt levels, is cheap, and a couple of other factors.
It looks pretty good to me, even though I don't have any shares in it. Perhaps others are thinking similar things and are willing to get on board despite being inline.
Qinetiq (LON:QQ.) some large director sales, about 6 months ago, caused the share price to fall. Probably just relief, after the director sales. Been looking for a while to get out, today was an opportunity, I took. Looks reasonable value as peers have done well recently, such as Chemring (LON:CHG) and Cohort (LON:CHRT). I do hold BAE Systems (LON:BA.).
I think market reaction has a lot to do with expectations. Not sure what the market was expecting from Card Factory (LON:CARD) though, a 10% fall does not seem right.
Hi Mark
Yes Qinetiq (LON:QQ.) are a firm hold and a firm favourite. In a sweet spot in the defence sector where I also hold Babcock International (LON:BAB) and BAE Systems (LON:BA.) . All the quality metrics point to a good future which is why when they acquired in US and Australia I latched on. So far apart from a slip to 290p ish when I added have not been disappointed. More to come I believe although patience is required
Exact same reaction to the Interims in September. Eventually got taken down to just below 90p before rallying. Its complete guesswork where the price will go when theres such a large seller in the background
Definitely an odd one on Card Factory (LON:CARD) - as you say last set of results was exactly the same. In between no rns from the seller around holding reductions.
I have a theory that the seller is “inside” and therefore can only really sell post trading updates. That would explain the trading - if investors anticipate this the shares will rise ahead of results, then traders will flock to the door expecting the large seller also to be selling. Seller then stops when it gets below target share price and has to wait for next results.
If we get an RNS on a reduction in their holding next day or two that will more or less confirm it. In which case I will ask management. However, if that is true I’m not sure why they haven’t just arranged a block trade type exit. There must be sufficient buying power.
Here are the largest trades of the day so far - hardly earth shattering but likely mostly institutional?
Yip - mainly all clips of 50k or multiples thereof. Looks like institutional selling. I hope it is Trellios (or whatever they are called) as their presence is definitely acting as an overhang and a brake on the share price. Even though they don’t sell around 115p that seems to be the cap until the prospect of the seller has gone imo.
Cinch now up from 8% to 9% of Vertu Motors (LON:VTU) - edit: sorry just seen Andy2205 mentioned this here 23 minutes ago.
Although recent newspaper reports that the FCA is investigating mis-selling of car finance, I wonder if that might become an issue? Any views?
This was raised by Topvest last week. I emailed Vertu on Friday to determine their exposure if any. I have had no reply. I was a holder but sold on the potential risk.
From what I can gather FCA report is due last quarter 2024. I did ask Secure Trust Bank (LON:STB) and the response was if a statement required will be after FCA report in last quarter 2024.
Although recent newspaper reports that the FCA is investigating mis-selling of car finance, I wonder if that might become an issue? Any views?
I normally take explanations by business correspondents on TV news programmes with a pinch of salt, but on ITV last week they said the FCA issue is that the finance company gave the car dealer a range of interest rates they could charge the customer at their own discretion. If the interest rate used by the dealer was high they would then get a back hander in the form of a discretionary "commission" from the finance company. So the dealers are not off the hook from what I understand, although IMO it'd be very difficult for this back hander to cause reputational harm to a car dealer :-)
So, at the very least these commission payments earned by elevating the interest rate charged to the customer (which is the issue being investigated by the FCA) have juiced the profits of car dealers.
All the best, Si
Why would anyone would accept finance from a dealer when banks are happy to lend out at sensible rates - as always its Buyer Beware
Discretionary commission arrangements were banned in 2021. It's the lender which is liable to pay compensation, not the car dealer.
It's likely to become a serious issue for finance houses and dealers involved Paul, commission paid to dealers has been an important source of profit. The enquiry has asked for those 'wronged' by this issue to contact them. It has all the makings of another scandal when officialdom takes on fat cats on behalf of consumers. We held Vertu and sold before the TDR Capital buying, I would still like to buy back in but the recent losses declared by Constellation tells me Vertu trading is likely to be tough too.
Constellation Automotive Group made a loss that includes Cinch and WeBuyAnyCar and BCA’s four businesses.
It’s not Marshall that made the loss-Marshall has halved its profits something expected by the market.
You have to distinguish these as Vertu Motors (LON:VTU) is a totally different business that has nothing to do with logistics.
Thanks
Are you taking into account Cinch losses revealed on the 11th yiannos1? They lost 181 million and the period does not include the high used car depreciation period. The bonanza on used car prices during and after the pandemic had to end, it has and Cazoo and Cinch have been hit very hard. Vertu is a well run business which will have a much better grip on used car values and turnover but I doubt if they can buck the cold winds blowing across forecourts. Thanks and good luck.
I am talking about Marshall that they made a profit and it is very clear what I have posted-you have clearly indicated that Constellation made a loss (they did) but that’s the group that has different businesses within it. Marshall made a profit that was about half of the one made a previous year and the same will happen with Vertu Motors (LON:VTU) already expected by the market.
Carrs
Harwood go to 19% from 15%
What is weird is they weren't buying at the level a month ago circa 1 pound .
Maybe when you are buying big chunks of a company you have to wait for the big chunks to have a willing seller.
Guess that gives the small PI an advantage as we can bottom fish the scraps at the bottom of the curves (hopefully) then when bigger buyers come in causes these sudden lunges upwards we have been seeing past month or so.
Anyway Carrs seems to be heating up nicely took a decent enough position but maybe with the rear view mirror should have gone balls deep .
Vertu Motors (LON:VTU) - I see Cinch % increased again to 9% - Surely something is brewing here!
A reader asked yesterday if any of the SCSW 2024 NAPS were on Paul's or Graham's NAPS list. Answer is no.
Hays Travel surpasses record ‘Sunshine Saturday’ trading | Travel Weekly
Jet2 (LON:JET2) and On Beach group (LON:OTB) amongst others should be experiencing similar I guess.?
Perplexed as to why Paul you have commented on Cohort (LON:CHRT) today - the interims were out on 13th December. Yesterday's RNS was just to say the report had been posted to shareholders!
I for one would always welcome a commentary from Paul whatever the timing.
Hi grumpy5,
Yes, you're right, I reviewed interims from CHRT here on 13/12/2023.
I did wonder why the RNS directed me to a fancy pdf, and didn't show the figures in the original announcement. Good thing I didn't have a rant about that. Schoolboy error, apologies. I'll edit the report to reflect this.
Regards, Paul.
That made me laugh Paul. Let this be a warning to everyone of the dangers of dry January :)
Nice write up on Card Factory (LON:CARD), Paul. How do you calculate an EPS of 13.5?
deleted
Hi Trendz,
Nice write up on Card Factory (LON:CARD), Paul. How do you calculate an EPS of 13.5?
I just took the broker consensus number from the StockReport of 13.3p, and added a little on top. Then sense-checked it to the last full year results. Although for more accurate forecasts, we'll need to wait for the consensus number to update, which is usually quite fast for something this size.
Let me know if you have a different, or more accurate forecast, especially if it's from one of the big brokers that don't less us see their notes.
Regards, Paul.
Card Factory (LON:CARD)
Revenues
2024:£511m
2025:£543m
2026;£581
EPS
Same 14p in each year.
Free Cash Flow
2024:£35
2025:£32
2026:£38
Card Factory (LON:CARD) Where did the free cash flow figures come from please?
UBS report ; not mine
Regarding Card Factory (LON:CARD) , there hasn't been an RNS from the big seller since early October. If they were still selling, wouldn't they have had to declare further falls in their holding?
My understanding is they have to declare each time they pass a whole percentage point.
Card Factory (LON:CARD) Good to see a solid update from Card Factory. The problem I had with the company, and why I sold my holding, was that all the cash generation historically seemed to be sucked up by lease payments, which looks to me like the equivalent of rent. Some canny investors are very keen on this stock and talk about strong cash generation so I am probably wrong in my understanding of these lease payments. Any enlightenment will be very welcome!
I have to agree, I don't understand why people think this is a good company. Look at the eps over time, its going nowhere. Debt is high too and doesn't pay a dividend. Retail should always be priced at a discount. Can't see anything attractive here.
Card Factory (LON:CARD) I agree it was a poor company under the previous management team, but seems to have really turned itself around now. Debt is coming down quickly and now at a reasonable level (if one excludes lease liabilities) and I expect dividend to be reinstated before too long. While it shouldn't attract a premium rating, I think a PE ratio of 10-12 seems very reasonable - this would put the share price around 150p so a good 50% upside from current level.
Why should companies with high debt pay a dividend?
How much of the debt is leases?
Quite a few US large caps don't pay any dividends.
Card Factory (LON:CARD) I think that like many retailers in the post IFRS16 world they don't include rent payments per se on the income statement rather they put through a Depreciation & Amortisation and Right- of-use asset depreciation charge under operating expenses (for 2023 £10.3m and £35.1m respectively) They then take out the payment of lease liabilities under cash flows from financing activities in the cash flow statement. I don't think the specifics actually matter, they are a retailer and rent is a decent part of their cash expense. What is important is by how much they have reduced the debt load in the past 2 years under new management. Last year £72.9m of cash flow went to repayment of debt and £65m in 2022. As of the latest interim's debt (exc leases) was down to £71m and I'd assume that this will be below £50m when the full year results come out, considering they also had £27.5m in cash, I'd been inclined to say it is safe to stop worrying about the debt. They are allowed to reinstate the dividend now (they couldn't pay one as a condition of a bond until Jan 24'). Starting this year if you remove those massive debt repayments (and get a little extra uplift from reduced interest expense) I think we could be looking at close to £100m of FCF on a £372m mkt cap. I'm not sure if this is a long term multi-bagger but 20p of EPS and a P/E of 10 somewhere in the not too distant future would give a double and doesn't sound too crazy to me. I'm certainly not an accountant so wouldn't take any of the above as gospel but I'm hopefully in the right ballpark.
After four beats this morning and all four are down the market is clearly telling us that there is no fuel left at this moment. Time to take some decent profits.
Yes, have been doing exactly that last few sessions. The Red Sea situation is not helping. Supply side inflation a worry now?
I am more worried when the rate cut cycle begins-every time there is one the average decline in the S&P500 is about 25% and takes about 7 months to reach the bottom-so I one can assume the same will happen here (at least!).
Hi Yiannos1,
At the risk of claiming 'this time it's different', have rate cuts occurred previously when the US is going into recession? (hence the S&P falls)
My hope is that the rises in rates this time was largely to quell 'extended' transitory inflation brought on by covid / Ukraine, and that rates will be cut because inflation is under control and not because the US is falling into recession (hence no significant fall in the S&P)
Recession follows after the inverted yield curve normalises-since the 1950’s this has always been the case.
thats a somewhat odd fact
if we take the viewpointb that stocks do poorly when rates/inflation rise (easy money goes elsewhere?) - should it not be the case that rates cuts should be good for stocks even if the past suggests otherwise - all other things being equal . I guess this is the fun of guessing does anyone really know what will happen and will the future be the same as the past ? - i see comment that rate reductions may have matched recessions previously if thats the case and there is no specific recession here heres hoping it may be different this time?
I would say looking at current expectations for the future i would say most companies at present should be very grounded with all the crapola thats gone on the last 2-3 years - is this perhaps different from us going into recession previously when rate cuts start where most companies have historically not been planning for future bad news in that regard?
I certainly wouldn't disagree with the direction yiannos, although the increased prevalence of low cost tracker investing ( amongst other factors ) hopefully means that cycles are shorter and shallower these days ( black Swan events aside )...
Hi Yiannos, i'm guessing one of those beats was McBride (LON:MCB). Are you selling the whole position or holding some back? can't understand the market reaction, seems crazy. debt down by £20m and liquidity at £85m. the company is clearly trading well and throwing off cash.
I will sell only shares equal to my initial investment on McBride (LON:MCB) and leave the remaining.
Ha - Yes my holding in bombed-out EQTEC (LON:EQT) near doubled this morning - to about £10 - not even enough to pay for the sale deal!
Interesting trading update today from Sulnox (OFEX:SNOX) after a big rise in the share price yesterday on the back of a tip in the Midas column in the Mail on Sunday.
I first came across this company a couple of years ago on a very enthusiastic Mello Zoom presentation from the inventor of the product. Subsequently I saw them present at Mello in London when the presenter gave me two samples of the product (one for petrol engines and the other for diesel engines). The presentation I saw focused on the huge African market because of the relative age of the cars and the relatively poor fuel quality and the huge impact it was having on improved fuel consumption and engine performance and to the livelihood of some of their customers (taxi drivers). My husband believes it has improved the running of his diesel car and now purchases the product from Amazon.
However, in my opinion, the much bigger and more important market of shipping is now being focused on by the company. New emissions reductions have been required from the beginning of this year and the Sulnox product will be a useful tool for the shipping companies in this respect, along with the ongoing problems with shipping making long diversions to avoid the Red Sea, thus increasing their fuel consumption and costs.
Not yet profitable, but making moves in the right direction and listed on Aquis, so not for widows and orphans but worth watching. (I hold).
Price to revenue on Sulnox (OFEX:SNOX) is pretty eyewatering. The shenanigans in the background in terms of leadership and ownership have been quite dramatic (and I believe there is stuff to understand about who owns rights etc)...I think its essential for a buyer of this stock to understand what's going on corporate governance wise to avoid a situation where value is wrenched away from PIs.
Additionally, I don't know much about the IP....however, I'd be naturally sceptical that a fairly simple polymerisation agent (I believe that is what it is...though don't hold me to it...I looked in the past and have forgotten and not looking back right now!) is fairly hard to protect in a general broad use sense...and/or competitors will offer alternate but effective solutions. I'd fear the issue is as much fuel companies are not incentivised to provide this solution (reduced fuel consumption) but if that becomes the case they will integrate it (ex Sulnox)
Take the above with pinch of salt...just be careful of newspapers tipping (well!) pre profit cos
Video postcard from Malta, my favourite island of them all!
Very quiet there. What time is it there? If you had longer there I’d say go pay a visit to an old friend of mine, Sam Misfud.
Happy memories of 6 weeks working in Malta along with my wife and 3 children 40 years ago. The only problem then was it was late in the year and a shortage of vegetables to eat. The government had an interesting solution to rising food prices, the price stayed the same but none available except for tourist hotels who got a limited amount imported. We loved Gozo too. You picked a good time, snow here. I remember the local wine, 50p a bottle and 10p return on the empty. Made up for living on pasta.
A good time to go Paul. Love the Bazinga shirt
Cairn Homes (LON:CRN)
https://www.cairnhomes.com/med...
Released a trading update for FY2023, operating profit up 10% with a slightly increased operating margin and a very bullish commentary. I think Graham usually looks at this one and as I have not had time to look any further I would be grateful for his thoughts.
EDIT 8.10am SP up 6%
Agreed. Look at this:
Cairn is therefore poised to deliver an exceptional output and financial performance in 2024, and expects to deliver year-on-year turnover and profit growth of c. 30%
With a current yield of over 7% and the costs of building a house almost halving, and expected div growth to double? there's an opportunity here. I hold.
Thanks Helvellyn,
I've added Cairn Homes (LON:CRN) to our already long agenda, either Graham or I will try to review it either today or tomorrow (I have to finish early today, to relocate from Valletta to Gozo).
Regards, Paul.
The DP Poland (LON:DPP) trading statement today is well worth a read for anyone interested in companies with great growth opportunities
The company reported record Q4 and record FY 2023 sales
The new management team led by Dominos expert Nils Gornall have done a great job and are optimistic about future opportunities. The full announcement is here
DP Poland (LON:DPP) agree with this. One thing to watch out is the cash generation which needs to turn positive to avoid any further capital requirement, but once this is out the way great growth here.
DP Poland (LON:DPP) I think they need more Yeast.
My morning smallcap tweet: An application of leeches on the body corporate
Microsaic Systems (LON:MSYS) Access Intelligence (LON:ACC) Blackbird (LON:BIRD) E-Therapeutics (LON:ETX) Hostmore (LON:MORE) Norman Broadbent (LON:NBB) £GMT Cab Payments Holdings (LON:CABP) Card Factory (LON:CARD) 4Global (LON:4GBL) Northcoders (LON:CODE) N4 Pharma (LON:N4P) McBride (LON:MCB), THG (LON:THG), Gamma Communications (LON:GAMA), Eagle Eye Solutions (LON:EYE), DP Poland (LON:DPP), Equals (LON:EQLS), Iqe (LON:IQE)
◄Microsaic Systems (MSYS)► £1.8m placing yesterday at 1.25p. AR and H1 results. Trading restored. [SP=0.01 Cap=m]
◄Access Intelligence (ACC)► guides FY-Nov up 2%. Adj EBITDA £7m (£2.3m) slightly ahead of consensus expectations of £6.7m. [SP=54.45 Cap=70m]
◄Blackbird (BIRD)► creator SaaS product elevate .io on track for end of Q1 2024 general release after successful early access [SP=6.13 Cap=23m]
◄e-therapeutics (ETX)► progress roundup. Guides YE cash c.£20.1m, above mgmt exp. [SP=13.72 Cap=80m]
◄Hostmore (MORE)► guides H2-Dec LFL rev flat (H1 -2%). H2 EBITDA £5.4m and positive in each month. Refinance talks continue. [SP=23.9 Cap=30m]
◄Norman Broadbent (NBB)► guides FY-Dec net fee income up 44% and U/L EBITDA c. £0.9m (£0.1m). Q4 NFI up 13%. In line? "Increasingly confident in our ability to overachieve against our previously stated target of £1.25m of EBITDA in 2025." [SP=6.84 Cap=4m]
◄CAB Payments (CABP)► guides FY-Dec income net of interest expense (excluding clearing costs) up c.25%. In line? [SP=96.7 Cap=246m]
◄Card Factory (CARD)► guides Feb-Dec rev up 10%. Guides FY-Jan adj pretax at the top of the range of market expectations of £58.4-62m. [SP=107.8 Cap=372m]
◄4GLOBAL (4GBL)► wins 2 contracts in Saudi Arabia worth £800k with the majority of the work scheduled for completion within the current FY. [SP=62 Cap=16m]
◄Northcoders (CODE)► wins £10m 18 month Gov't contract for its bootcamp. [SP=130 Cap=11m]
◄N4 Pharma (N4P)► places contract to start the formulation and sequence selection work to prepare its ECP105 product for testing in pre-clinical studies at Kings College, London. [SP=1.12 Cap=3m]
◄McBride (MCB)► guides H1-Dec rev up 10% and adj op profit slightly ahead of mgmt exp. [SP=89.8 Cap=156m]
In line: THG, GAMA, EYE, DPP, EQLS, IQE
Card Factory (LON:CARD) trading update looks great to me. Top end of market expectations. Revenue+10% yr on yr. In line but top end so £62m PBT. Only slight downside is online -11%, but I think that's only 3% of the business so no biggie.
i hold.not sure if they can reintroduce the dividend?
Great update. Such a solid business. The update won’t show the huge debt reduction and forthcoming dividend - that will be in the April results. Congrats to Darcy for a remarkable job so far as CEO. The future looks bright under his stewardship and a p/e of 7.5 looks far too cheap for a quality operator with a proven track record and massively improving balance sheet.
And down -4% couldn't make it up....
Guess the seller is using the volume to continue getting out.
Can't see retail selling on that news.
Not often you get such a good buying opportunity on that sort of TU! Sadly I am up to weight.
I'm fed up of this bear market too!Perhaps if risk free rates weren't where they currently are income fund managers would be more interested re potential .Roll on the next bull market!
Card Factory (LON:CARD) aren't allowed to declare a dividend/buyback until they have fully repaid their "tranche A" loans which have a final repayment date of 31st Jan 24.
From their end of FY23 results they commented on their future dividend policy "Subject to continued financial performance in line with the strategic plan, the Board envisages recommencing dividend payments at a level of 2-3x dividend cover based on profit after tax, subject to a Leverage ratio assessed across the financial year of not more than 1.5x (excluding lease liabilities) being maintained after the distribution is made."
From their HY24 trading update they mentioned aiming for a leverage ratio in the range of 0.5-1.5. At HY24 it was 0.6x exc leases, down from the HY23 when it was 0.9x. I expect this to now be under 0.5x.
So if net profit is somewhere around £45-50 mil area and there are no surprises with the leverage ratio there could be a £15mil-£25mil dividend (based on 2-3x div cover) as soon as this year which would be nice. Although I think there is a not insignificant chance that they may start a dividend much lower than they originally intended or delay a dividend policy entirely to help their growth plans.