Small Cap Value Report (Tue 16 July 2024) - JNEO, SPSY, TRU, BMY, VANQ, MCB, BRCK, TRST

Good morning from Paul & Graham!
We've run out of time, so have to leave it there for today.
Explanatory notes -
A quick reminder that we don’t recommend any shares. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech, investment cos). Although if something is newsworthy and interesting, we'll try to comment on it. Please bear in mind the "list of companies reporting" is precisely that - it's not a to do list. We typically cover c.5 companies per day, with a particular emphasis on under/over expectations updates, and we follow the "most viewed" list of readers, so if you're collectively interested in a company, we'll try to cover it. Obviously with the resources available, we can't cover everything! Add you own comments if you see something interesting, and feel free to discuss anything shares-related in the comments.
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to, if they are using unthreaded viewing of comments.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. And/or it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Others: PINK = takeover approach, BLACK = profit warning, GREY = possible de-listing.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom), Video update of results so far, June 2024.
Frozen SCVR summary spreadsheet for calendar 2023.
New SCVR summary spreadsheet from July 2023 onwards.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Phil Hanson's data analysis measuring performance of our colour-coding system in the SCVRs, from July 2023- Mar 2024 (with live prices). My video explaining/reviewing it.
My other video (June 2024) - How to screen for broker upgrades on Stockopedia.
Companies Reporting

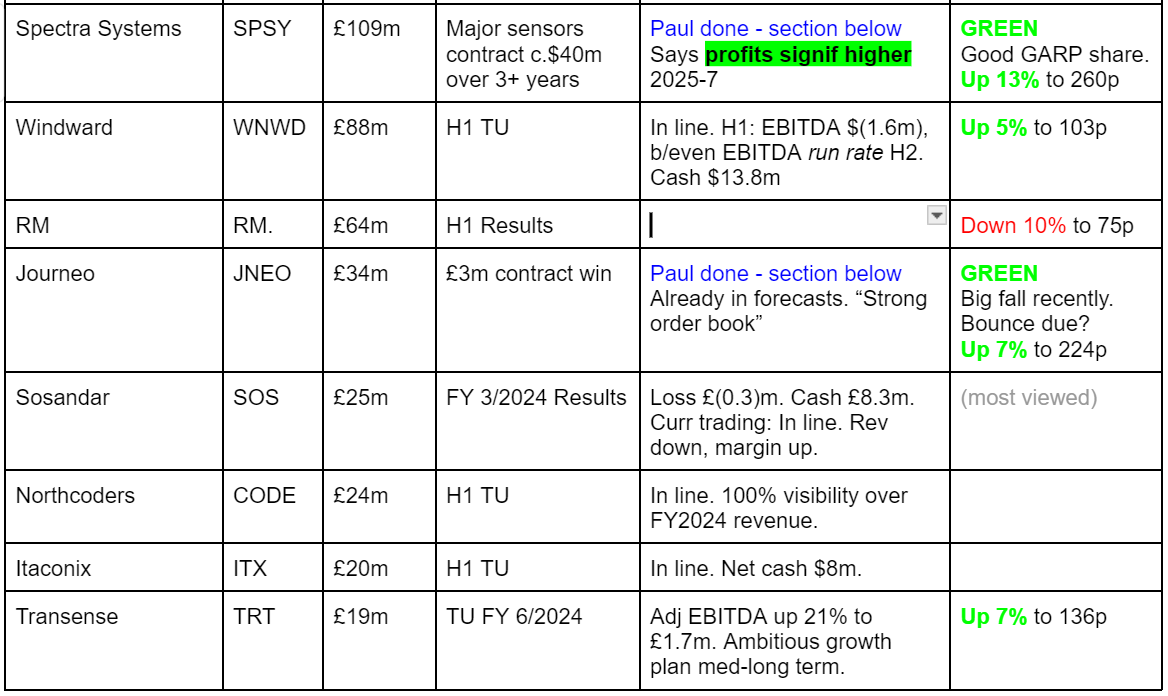
Other mid-morning movers (with news)
Trufin (LON:TRU) - down 32% to 52p (£54m) - Loss of customer - Paul - AMBER/RED
Its Satago division loses a significant customer (Lloyds Bank, which also had a NED on TRU’s Board, who steps down today).
Clearly this is a setback, but TRU tries to reassure -
“Based on the recent and continued strong performance of Playstack, which is trading ahead of expectations, the Board of TruFin confirms that the Group as a whole is trading in line with market expectations and remains on track to achieve EBITDA profitability in 2024. The Group also remains fully funded to profitability.”
Paul’s view - a quick look at the 2023 figures has put me off. EBITDA is meaningless, as it capitalised £5.5m into intangible assets. As yet no sign of this being a viable business. It’s trying to do too many things, and should maybe simplify to one core activity. I don’t see value here. Graham was RED last time on 4/1/2024, maybe a little harsh, so I’ll moderate to AMBER/RED due to the overall in line exps comment above, and the claim that it has enough funding. But I certainly wouldn’t want to get involved in this share, due to the very poor track record of continuous losses & cash burn.
Trustpilot (LON:TRST) - down 9% to 213p (£889m) - Secondary Placing - Paul - Graham is GREEN, Paul not so keen.
The curse of the secondary placing rears its ugly head again - where a major holder instructs a broker to flog a big block of shares, because there’s not enough market liquidity. Trafalgar Acquisitions is the seller, of 12.5m shares, 3.0% of TRST, and it’s taken a price of 220p, which looks to be a c.6% discount to the previous night’s closing price of 234.5p.
It now holds 9.5m shares, with a 45 day lockup that’s fairly clear that another sale is likely, which has put a 9% dampener on the share price today, to below the disposal price.
Paul’s view - if you like the company, then a clumsy seller might be providing you with a buying opportunity. Personally I’m not keen on this share, but it’s one of Graham’s favourites, so I won’t mess up his GREEN colour-coding by saying how I view it! (over-valued, and questionable business model). But the revenue & profit growth are impressive.
Summaries
Journeo (LON:JNEO) - 209p (£34m) - Contract Awards - Paul - GREEN
Two contracts totalling £3m with UK train companies are announced, but were already in the forecasts. It mentions a strong order book. Given the big share price sell-off (on no news), I think the company could have reassured more directly today, saying it's trading in line with expectations, but that wasn't done. Based on the information we have today, it looks a decent company at a fairly attractive valuation, so I see no reason to change from my previous GREEN view.
Spectra Systems (LON:SPSY) - up 13% to 260p (08:01) £125m - New $37.9m Contract - Paul - GREEN
Wins a big contract. This seems to have partly been in existing forecasts, but actual has come out much higher margin than planned, leading to a sharp upgrade in forecasts, but also re-phasing of the cashflows. I remain very positive on this interesting little company.
Bloomsbury Publishing (LON:BMY) - down 1% to 710p (£579m) - Trading Update (AGM) - Paul - AMBER/GREEN
A reassuring, in line with expectations update, and lovely clear profit guidance. One of our favourite shares here, but I reckon the big recent bull run has now re-rated BMY shares significantly, and are now looking up with events to me. So I'm moderating my view from green to AMBER/GREEN - still positive, but not the bargain it was when I picked it for my top 20 2024 share ideas.
Vanquis Banking (LON:VANQ) - down 14% to 45.5p (£133m) - Update ahead of interim results - Graham - AMBER
This credit card and vehicle finance bank announces it will need to write down some impaired loans, including their values on financial statements in prior years. Other balance sheet items will also see their values cut down. Current trading seems to be ok, but profitability and balance sheet targets won’t be met this year due to the writedowns. I see this as a highly risky bank share but already very cheap.
McBride (LON:MCB) - down 6% to 133p (£232m) - FY 12/2024 Trading Update - Paul - AMBER
A fantastic turnaround here, as we already knew. In line with expectations update today, reassures. Useful further reduction in the (still high) net debt. Have margins now peaked, I wonder? There could be a bit more upside on the share price, if it can maintain current profitability, but I think the major upward move has probably now mostly happened, so I'll shift down a notch to AMBER - which is a clean bill of health remember.
Brickability (LON:BRCK) - down 5% to 71p (£227m) - Unaudited preliminary results - Graham - GREEN
It was a tough year for Brickability, as expected, with revenues and profits done. However, the gross profit margin held firm due to price increases and the company still earned a profit that justifies an increased dividend. I’m happy to maintain our positive stance here, sharing in the company’s optimism for how it will perform whenever favourable conditions emerge again.
Journeo (LON:JNEO)
209p (£34m) - Contract Awards - Paul - GREEN
Here’s an interesting one. This widely followed share has gone into a nosedive recently, on no news. No idea why - someone must be selling clumsily? People obviously then start panicking, fearing bad news could be imminent.
Today’s RNS should reassure, and I imagine a bounce is likely today (writing this at 07:48).
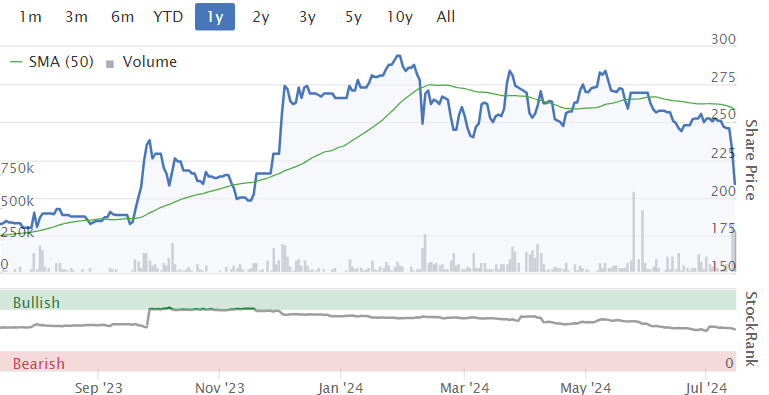
Contract wins totalling £3.0m won, but were already in the forecasts, it says.
Contracts are for on board CCTV and passenger counting solutions for rail companies in UK.
It mentions a “strong order book”
Paul’s view - the broker consensus graph shows 22.4p EPS for FY 12/2024, which at 209p is a PER of 9.3x, which looks good value I’d say.
They could have stated that trading is in line with expectations, which wasn’t done today. So some uncertainty might persist maybe? But on balance I expect buyers are likely to reverse yesterday’s plunge. But that depends on whether the seller feeds more stock into the market today, who knows? It’s background noise for long-term holders, but price moves can be tricky with small, illiquid shares. Also it shows the risk of using stop losses, as moves like this can stop you out without good cause.
No broker updates recently, so we’re in the dark a bit.
I don’t see any reason to alter my previous positive view, so GREEN from me. See 26/3/2024 SCVR, when I reviewed its strong FY 12/2023 results.
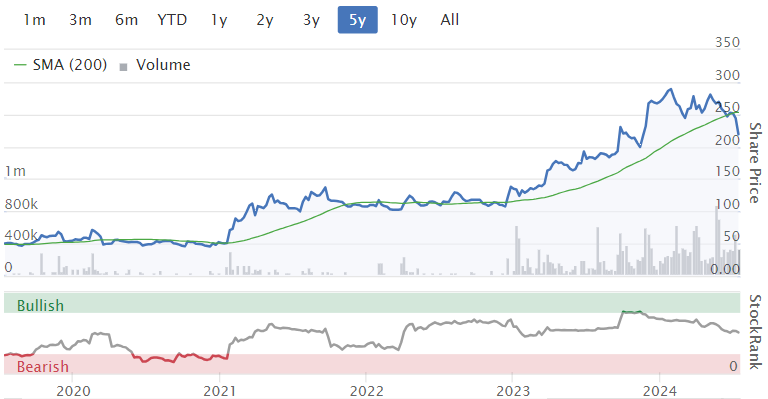
Spectra Systems (LON:SPSY)
Up 13% to 260p (08:01) £125m - New $37.9m Contract - Paul - GREEN
Spectra Systems Corporation, a leader in machine-readable high speed banknote authentication, brand protection technologies, security printing and gaming security software…
I like it when RNSs state the contract value in the title, as we can immediately see how material (or not) it is, helping prioritise our time in the crucial, manic 7-8am tidal wave of news.
SPSY is one of my favourite shares, we’ve reported at GREEN on it 3 times in the past year -
25/9/2023 - 166p - GREEN - Good H1 results. Strong cash, divis & outlook. Thumbs up from Paul.
12/10/2023 - 190p - GREEN - Large contract win. Paul likes it.
27/3/2024 - 218p - GREEN - OK results FY 12/2023. 4% yield. Exciting outlook section.
Unfortunately, it slipped through the net for my 2024 top 20 share ideas list, it should have been on that.
Today’s news is to manufacture sensors for an existing central bank customer.
Total contract value is expected to be $39.6m.
“Bulk of the revenues” receivable from Q1 2025 to Q4 2027, so spread over 3 years. With a smaller tail until 2029.
This is the best bit. Some element of the contract seems to have already been in the forecasts, but it’s much more profitable than originally assumed -
“ This manufacturing contract margin is expected to result in profits over its term that are significantly higher than previously estimated.”
This is another very interesting point - I’m a fan of customer-funded R&D, as it often results in big contracts at a later date (if all goes well), and is a good indicator that a company has strong IP & niche expertise -
“Dr. Nabil Lawandy, Chief Executive Officer, stated: "This long-awaited contract for the third generation of sensors follows after over $14.8 million of development funding by our customer and reflects both the continued need for banknotes as well as the trust our customer has in Spectra Systems."
Broker update - many thanks to Zeus, who provide additional colour, and up their forecasts significantly. In summary (I hope Zeus don’t mind me repeating this) - these are adjusted, fully diluted estimates below, in US$ cents -
FY 12/2024 - EPS forecast raised from 14.8c to 17.7c
FY 12/2025 - raised from 20.3c to 37.1c - good grief!
FY 12/2026 - lowered from 26.2c to 23.3c
It also brings in estimates for 2027 and 2028, but I think that’s way too far forward to be worthwhile trying to forecast, so I’ll ignore those figures.
Valuation - this is tricky, how do we value the shares? I think it would be a mistake to do a valuation based on growth, and a multiple of peak earnings in 2025.
We don’t know whether this big, obviously high margin contract is a one-off, or that start of a stream of contract wins. Hence there are a wide range of possible valuations here.
I’m leaning towards averaging the forecasts above, which gets me to 26c. Convert into sterling at 1.297, gets 20.0p EPS.
What PER to use? Given the highly impressive growth, I’m struggling to see why you wouldn’t rate it at between 15-20, hardly demanding.
That gets us to a crude valuation of 300-400p. Versus the current share price of 260p. Hence I remain GREEN on this share.
Paul’s opinion - I think there’s something special here. The valuation stacks up still ,even after today’s rise, although it’s not the easiest share to value due to the large lumpy contracts. Strangely, it comes up on a bearish screen, the James Montier “cooking the books” screen! I’ve never found anything untoward in SPSY’s accounts, so I think that’s probably a red herring, but it is a useful reminder to double-check everything in the annual report.
Remember that unusually for a growth share, SPSY also pays out nice divis, with the yield an attractive c.4%.
This looks very good, it has to be GREEN again. I’ll try to pick up a few personally if it drifts down in future.
Other SPSY news -
Lottery contract renewal - announced yesterday. Only $636k over 5 years. Talks about “renewed growth” of this business line.
Change of broker - Zeus has acquired WH Ireland’s capital markets division, taking its clients (including SPSY) with it, so broker notes will now be Zeus branded.
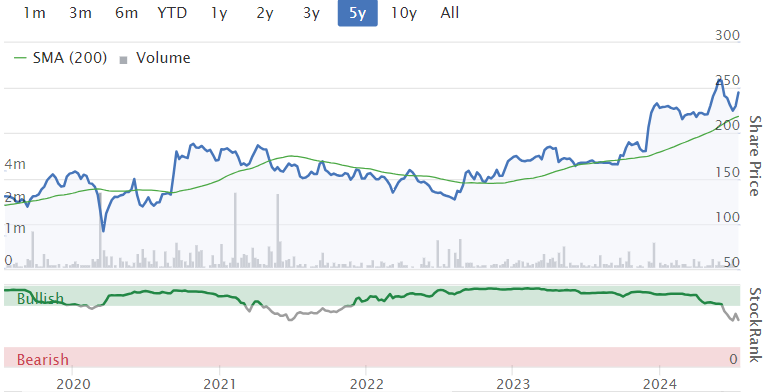
Bloomsbury Publishing (LON:BMY)
Down 1% to 710p (£579m) - Trading Update (AGM) - Paul - AMBER/GREEN
Bloomsbury Publishing Plc (LSE: BMY), the leading independent publisher, today announces its trading update for the four months ended 30 June 2024 ahead of the Company's Annual General Meeting ("AGM") at 12.00pm today.
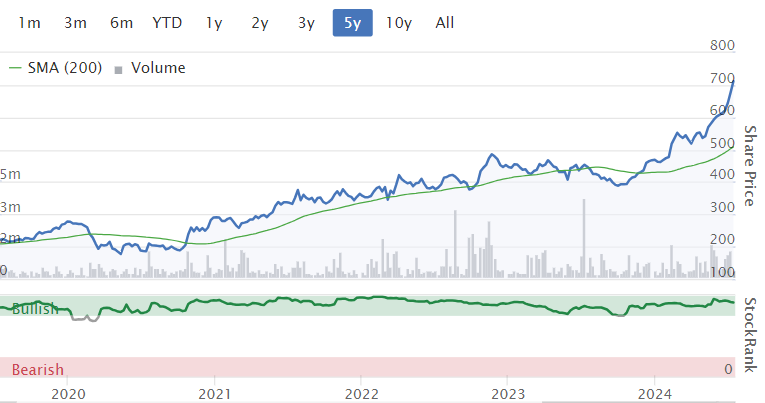
A long-standing favourite here at the SCVR, and one of my top 20 share ideas for 2024, currently up c.50% YTD in 2024.
Trading continues to be good - and excellent, clear guidance - why can’t all companies do this?! -
“Bloomsbury's trading has been in line with recently upgraded expectations, including the acquisition of Rowman and Littlefield's academic publishing business,* following a strong performance in the first four months of its financial year.
*The Board considers current consensus market expectation for the year ending 28 February 2025 to be revenue of £319.3m and profit before taxation and highlighted items of £37.6m.
No broker notes available, so I have to go with the StockReport’s broker consensus number, which is £28.4m PAT, which is consistent with the company’s £37.6m PBT, after taking off 25% for corporation tax. Stockopedia has 34.3p EPS, so a PER of 20.7x FY 2/2025.
Next year forecast rises to 41.0p, so that PER is 17.3x
Dividend yield is quite modest now, at 2.2%, due to the big upward move in share price.
Also the cash pile has been spent on the latest “transformational” acquisition of Rowman & Littlefield’s academic publishing division.
Paul’s opinion - an excellent business, which deserves the re-rating the shares have achieved this year.
We have to take into account value, and given the valuation now looking up with events, I think it makes sense to moderate my positive view from green to AMBER/GREEN, to reflect the much higher valuation.
If I use the “PRINT” button on the StockReport to view the historical StockReport at end 2023, the forward PER then was 14.4x at 470p/share.
Forward PER is now 19.4x, so that’s a big re-rating, and hence I don’t see the same upside that was the case at the start of this year, because the re-rating has already happened. So further upside now would have to rely on more forecast increases only (not a higher PER).
For the avoidance of doubt, I still think BMY is an excellent company, just priced up with events now, instead of being cheap.
McBride (LON:MCB)
Down 6% to 133p (£232m) - FY 6/2024 Trading Update - Paul - AMBER
McBride plc (the "Group"), the leading European manufacturer and supplier of private label and contract manufactured products for the domestic household and professional cleaning and hygiene markets, today provides the following trading update for the twelve months ended 30 June 2024.
Confirmation that trading is in line with expectations -
“The Group therefore anticipates that adjusted operating profit will be in line with the recently upgraded current market expectations (*).
* Current market expectations refer to a Group compiled consensus of broker forecasts for FY24 of:
· Adjusted operating profit £66.4m
· Net debt £129.0m
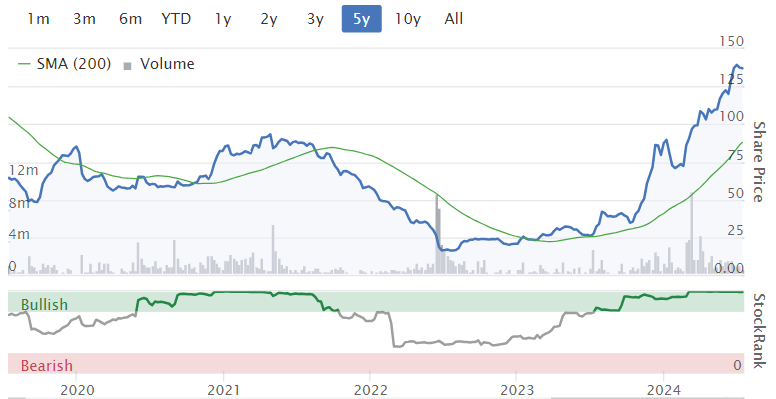
MCB reported £30.5m adj operating profit in H1, so H2 must be a rise to £35.9m. Remarkable stuff, considering the company was financially on its knees and looked a candidate for potential insolvency or at least a highly dilutive placing just 2 years ago.
Although operating profit is not a good measure for companies with heavy finance charges. In H1 adj operating profit was £30.5m, and adj PBT was £22.4m, 27% lower. So really they should be quoting adj PBT in trading updates.
If I double the H1 finance charges, FY 6/2024 could be around £16m, hence I get adj PBT of c.£50m. Take off 25% tax, gives £37.5m PAT, divided by 174m shares, is adj EPS of 21.6p.
My estimate is almost bang on the 21.7p forecast shown on the StockReport, I love it when that happens and the numbers work! Strangely satisfying.
I try to work out my own figures when there aren’t any broker notes available.
PER is therefore 6.1x - which is obviously low, but that’s because MCB carries a lot of debt. Which is one reason why it hasn’t paid a divi since 2010. My previous notes show that the pension scheme was consuming £4m pa cash in deficit recovery payments.
Debt - is still high, but there’s further progress in reducing debt here -
“The Group's improved profitability and continued focus on net debt reduction resulted in net debt closing at £131.5m, a £14.2m reduction versus the half year end (31 December 2023: £145.7m) and a £35.0m reduction versus the prior year end (30 June 2023: £166.5m). The Group's closing liquidity of £98.3m (31 December 2023: £85.0m) continues to improve and is significantly higher than the minimum liquidity requirement of £15.0m applicable under the Group's financing arrangements.”
As mentioned before I don’t see debt as an emergency any more, because it’s falling nicely, and profits/cashflow are so much improved, that the lenders will clearly see that MCB now has the capability to repay it over time. In an ideal world, I would say net debt needs to fall to c.£50m to be comfortable, and preferably less. Companies should plan ahead for downturns, and unexpected events, not max out their borrowings (as MCB previously did). Let’s hope management have learned that lesson this time, and won’t risk the company going bust again. The bank was exceptionally lenient in the terms it gave MCB, which allowed it to survive, and avoid heavy dilution.
Checking my previous notes, I did flag the high risk (with AMBER/RED) on 16/7/2023, but also noted at the time that it could be an interesting high risk punt at 31p. Also I should give a hat tip to subscriber Yiannos01 who strongly flagged the turnaround potential here last year, and has gained a c.6-bagger. Nice work!
Looking back, the absolutely key announcement was when the bank gave it a lifeline, removing the covenants for I think c.2 years. That was the point to dive in, because it largely removed the insolvency risk, so I’ll remember that as an important lesson to look out for in the future.
As 2023 moved on, and bank debt began falling, and it kept beating expectations, we moved up to AMBER, then early this year to AMBER/GREEN. Remember our colour-coding just follows the facts, figures & forecasts, we’re not trying to predict the future - that's your job!
Paul’s opinion - drawing this to a conclusion, I reiterate that MCB has been an astonishing turnaround from near-insolvency, to highly profitable - now well ahead of its lacklustre performance pre-pandemic even.
How sustainable is it though? We know that MCB has benefitted from squeezed consumers moving down from branded products to supermarket own label. I wonder whether the big brands will take back some of that market share in future, with more advertising and consumers once again seeing real incomes rising?
There was also talk that supermarkets might have allowed MCB to make temporarily better margins to avoid it going bust, and that falling raw material prices and lower energy bills might have allowed bumper , but temporary profits? Supermarkets are notoriously tough negotiators, so I’m minded to assume the big profits in FY 6/2024 might be peak earnings that could be difficult to sustain (which is what the historical performance tells us). Remember that contract manufacturers have no pricing power.
Bulls reckon that MCB management took drastic and highly effective action to strip out costs and improve commercial negotiations, declining unprofitable business, etc. I certainly can’t argue with the numbers, as whatever they did, it’s been remarkably successful.
What happens next then? Broker consensus is assuming a fall in EPS from 21.7p FY 6/2024 (confirmed today) to 19.5p FY 6/2025. You’ve got to decide if you think that’s a low bar, deliberately set to be beaten, or whether profits have indeed peaked in FY 6/2024. I have no idea, hence don’t have a strong view either way.
With net debt now at c.£131m (and falling), and a market cap of £232m, we could see shares re-rate from a PER of c.6 to maybe 8x, as debt reduces. That’s not madly exciting though. How likely are further earnings beats? I suspect they’ve already bagged the low hanging fruit on margin improvement.
It’s difficult to say, but overall I can see modest further upside, but probably not another transformational multi-bagging move like the one we’ve already seen.
Shifting down to neutral feels about right, so I’ll go AMBER.
Graham’s Section:
Vanquis Banking (LON:VANQ)
Down 14% to 45.5p (£133m) - Update ahead of interim results - Graham - AMBER
We don’t cover this one too regularly in this report. I last studied it in Jan 2023, when it was still known as Provident Financial (PFC ticker).
At the time it seemed to me to be in decent shape, but the wheels have come off since then:
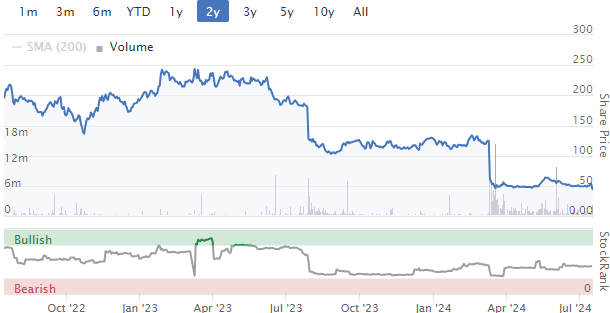
Paul covered the company’s most recent profit warning in April.
Today there is more bad news I’m afraid.
“One-off Items” - the headline for a section that outlines £40m of damage to the balance sheet.
First, there is a £29m “downward revaluation” of vehicle finance Stage 3 receivables, i.e. impaired car loans.
Most of this revaluation relates to prior years, meaning that Vanquis failed to get the values right in previous financial statements.
And that’s not all:
Management has now undertaken a full review of the balance sheet. This identified a further c.£11m of one-off items related to the write-down of development costs for a now redundant mobile app, property dilapidations and other sundry balances.
A reminder for all of us that financial statements aren’t a statement of fact - they are an expression of an opinion. £11m of value has just disappeared, as management decided to look again at the values on it.
Trading update: nothing terribly alarming here. Net interest income is stable compared to last year despite interest-earning customer balances falling 6% below December 2023.
£60m of cost savings are on track to be achieved by the end of 2024. A remarkable number given the market cap of £133m.
The costs of dealing with complaints “remain within previously guided levels”.
Outlook: will not meet its target of low single digit ROTE (return on tangible equity) and will end the year below its target capital ratio (Tier 1 ratio 19.5% - 20.5%). Looking on the bright side of things, the company says:
The Group's financial position is now clearer and more stable, with focus now on deploying capital for profitable receivables growth.
CEO comment:
"We have been carrying out a comprehensive review of our balance sheet and this has led to the revaluation of some historic balances. While finding these one-off items is disappointing, it does mean that our financial position is now clearer and more stable. Our trading performance towards the end of the first half of 2024 was encouraging, with year-to-date growth in customer numbers, at better margins, and a return to growth in receivables in June."
Graham’s view
I can’t express a strong view here due to the uncertainty around the numbers, but here are some observations on the company’s 2023 full-year results.
Adjusted ROTE was 3.2%, before any restatement that may be required. That figure is too low to get me interested in investing here, and the company’s target of low single digit ROTE in 2024 (which it is not going to hit) is also too low to get me interested..
2023 balance sheet equity was £583m vs. total assets £3.2 billion. Tangible equity c. £435m. Restatements will affect these numbers.
Clearly there is a large business available here for a market cap of c. £130m. The price to tangible book ratio based on unrevised numbers is about 30%, i.e. there is a discount of up to about 70% to book. And with £60m of cost savings being delivered, you would think that the outlook for the equity would be quite good.
But there are good reasons to stay away:
Higher leverage vs. other alternative lenders we could invest in.
A high volume of complaints. Even if they are spurious, they are an unwelcome distraction.
Weak profitability in the short-term. How long will shareholders have to wait for recovery?
Today’s revaluations are a reminder that the balance sheet doesn’t tell the whole story, as the numbers can and will be revised, sometimes in surprising ways.
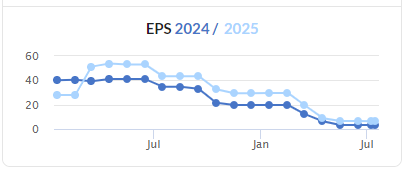
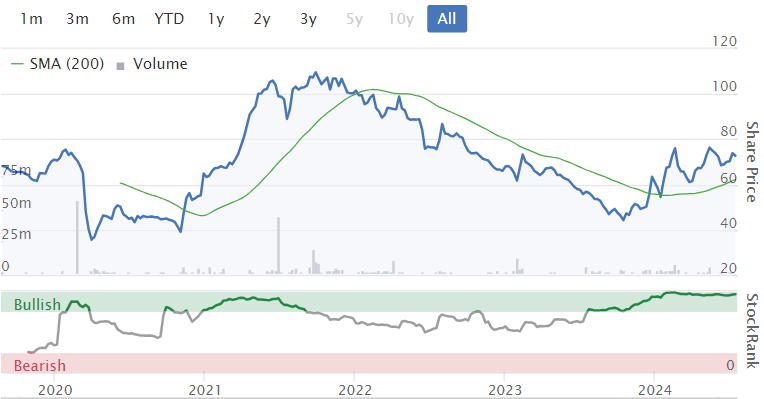
There is also the problem of profit warnings and negative earnings momentum:
For me personally, I consider the risks here to be uncomfortably high.
For someone with a highly diversified portfolio, who could afford to see this go to zero, maybe the risk/reward here could be acceptable, given the 70% discount to tangible book value (before any restatements)?
Since there is “value”, I’m inclined to take a neutral stance on this share. I imagine that some readers (and perhaps my co-writer?) will see this as an overly generous position to take.
Last year, there was a debate around Metro Bank Holdings (LON:MTRO) where I also took a neutral stance, due to the apparent value. Bank shares do have a tendency to look extremely risky, and they frequently disappoint - but in today’s markets when they are already trading for peanuts, and when they appear to be solvent, I prefer not to take a bearish view!
Even if VANQ’s tier 1 capital ratio falls below 19.5%, it should still remain at levels generally considered safe, e.g. still well above 10%.
Brickability (LON:BRCK)
Down 5% to 71p (£227m) - Unaudited preliminary results - Graham - GREEN
Brickability Group PLC (AIM: BRCK), a leading distributor and provider of specialist products and services to the UK construction industry, is pleased to announce its unaudited preliminary results for the twelve-month period ended 31 March 2024.
It was a tough year. But despite most metrics moving in the wrong direction, the dividend here still gets a raise. It is well covered by EPS:
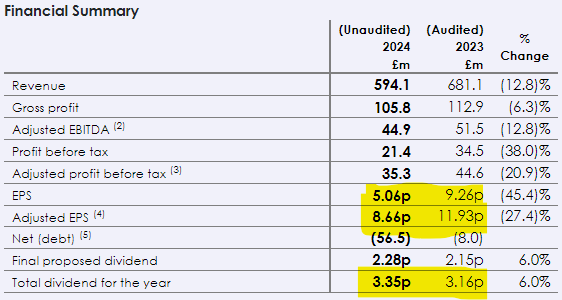
This is described as a “resilient” performance, given the challenging environment.
Outlook - currently trading in line. New CEO as of April. They are “well positioned to recover strongly as market conditions improve”.
However, there is also an acknowledgement later in the statement that “activity levels in the housebuilding sector remain subdued”.
The Chairman’s comment emphasises the company’s expansion into new product categories:
"Over the past year there have been a number of well-documented challenges impacting the housebuilding and RMI markets. Against this macro backdrop, the Group has continued to demonstrate resilience and deliver a robust financial performance. It is particularly pleasing to see the Group's strategic focus on diversification of products and end markets yielding benefits…
Indeed, it’s not just a brick company - it also sells cladding (boosted by an acquisition), pavers, blocks, balconies and other building materials.
Quick overview of divisions:
Bricks/building materials (68% of revenues): brick volumes down 28%, in line with the market. Like-for-like revenue declined 19% with price increases helping to offset the volume decline.
Importing (16% of revenues): like-for-like revenue down 34%. This division is extra sensitive to market conditions as weak demand means that there are more domestic bricks available to satisfy customers, and less need for imports.
Distribution (11% of revenues): marginally down on last year.
Contracting (10% of revenues): boosted by acquisitions that are performing as expected. This division includes various cladding companies.
Adjusting items: there is a £14m gap between adj. PBT (£35m) and statutory PBT (£21m). The biggest numbers here are amortisation and earn-outs relating to acquisitions. So the usual disclaimers apply - if you are happy to ignore them, you can give a greater weight to the adj. PBT figure.
The adjusting items also include £1.5m of share-based remuneration - I don’t think it’s controversial here to say that this should not be adjusted out.
Net debt of £56m is after paying out £43m for acquisitions and £5m of deferred consideration for previous acquisitions.
Graham’s view
I don’t have a strong view on this one, so I am happy to defer to the GREEN stance which Paul took in April, in anticipation of a cyclical recovery.
According to the company, conditions still remain soft, but they seem to be maintaining their optimism for how they will perform whenever things pick up.
In the meantime, the shares trade at a modest multiple and pay a yield that is covered by earnings even after a bad year:
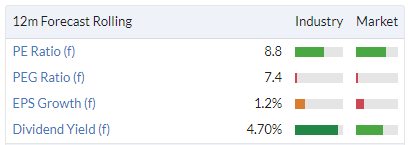
Can things get worse? Of course, but the company seems to be able to grind out margins and profits even in bad conditions.
The net debt figure stands out as having increased greatly, but with diversifying acquisitions being the main reason for this, I think investors can be reasonably relaxed about this for now. Of course it’s something that we’ll need to keep an eye on in future updates.
In summary: while this is a low-conviction stance for me, I’m happy to maintain the continuity of a GREEN stance on this share.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

62 comments
Spectra Systems (LON:SPSY)
I'm just catching up on Spectra.
I don't hold any more, but I like to keep any eye on this one.
I'm trying to understand why the contract announcement this week was so well received by the market. Wasn't it sort of expected? And isn't the contract lower than previous announcements?
As a reminder:
So surely revenue expectations are now lower than previously announced?
What am I missing?
SOURCE: https://www.investegate.co.uk/...
"...expected to result in sensor sales of approximately US$50MM from 2024-2026.
In addition, we expect a ten-year service agreement worth over US$8MM to line up with the delivery of the first advanced sensors in 2024."
Spectra Systems (LON:SPSY)
Clearly the new contract was not fully factored into the broker forecasts before the update this week with regard to the short term. If you look at broker forecasts they have been hugely updated after the announcement - on the basis that this is clearly change for the better ref immediate prospects to me it’s obvious that the price is going to go up. I don’t know if any if the contract was previously in broker expectations or not ? (Perhaps others can advise). Either way it’s looks like what was uncertain income at uncertain future time or was perhaps expected in later years is most definately in the hear and now now - I suspect the original news having been made so long ago means this contract probably wasn’t fully in forecasts (as not signed off) so the market rightly took the viewpoint we don’t believe it will fully turn up till the full contract is signed off which it is now
Very good point, abtan. I had also spotted it but decided that it balanced out roughly, in that (1) they got more for the development phase than the $8m they indicated back then (total now $14.8m).
And then there is the twist that the revenues are significantly higher margin, so presume they'd worked some clever way to save production costs of the sensors (so $37.9m vs $50m) but their ingenuity in cost saving is being "rewarded" so to speak with a higher gross margin.
Either way, I was also surprised by the SP reaction, as this was all public news already. Except, that the broker (Zeus) has in the past refused to include any rev+profits from non-firm contracts. Hence why Spectra Systems (LON:SPSY) keep beating forecasts usually, because the forecasts are only based on firm contracts, not extra won along the way from the pipeline.
(I hold in the Boon Fund)
Wise (LON:WISE) up 5.5% today after Q1 2025 results released. 26% YoY growth in quarterly active customers and volumes increased 18% YoY.
"Underlying income grew 22% YoY to £325.4m, with continuing growth in deposit balances (23% YoY) and strong card and other revenue growth (55% YoY)."
As a reminder, underlying income is revenue and first 1% of gross yield of interest income on customer balances. It does not include interest income above the first 1% gross yield or benefits paid on customer balances.
They continue to expect strong growth in FY25 with underlying income expected to grow 15-20% over FY24.
Interesting to see this share price recovery, since the same growth estimates are what disappointed the market and led to a big dip after FY 2024 results? I am probably missing something.
McBride (LON:MCB)
A very aggressive sell off today and so easy to follow the herd in fear, but I have made that mistake too many times over the last couple of years and now only trade the news, which in this instance is very positive.
If anyone has access to the full research note from Peel Hunt it would be great to hear what they say otherwise this is all I could find;
Peel Hunt: "The company is in far better shape and we have greater confidence in the outlook and balance sheet. We increase our target price from 130p to 175p and retain our Buy recommendation...
We increase our target price from 130p to 175p, based on 8x PE, 6x EV/EBITDA and 8% FCF yield. This reflects the higher risk appetite in the market, as well as the
improved profit performance and outlook."
Bloomsbury Publishing (LON:BMY) while I agree its no longer looking especially cheap, it's worth noting that management tend to be very conservative in their guidance and often do big upgrades towards the end of the year - so might actually be cheaper than it first appears. This year they've been very prudent and assumed no repeat of the Sarah J Maas surge - while no new Maas books are due this year the existing catalogue seem to be still selling well and of course there's always the possibility for a new author to suddenly take-off.
Bloomsbury Publishing (LON:BMY) - Agree Bouden - I think this is like so many examples of gaining a little more knowledge about the company. (mainly thru Stocko) otherwise I would be selling up now. In fact the only reason I'm won't be topping up on any weakness in the Mkt - am already at top end of my exposure on this great company. And don't forget possible film/ tv rights
Re the recent Bloomsbury Publishing (LON:BMY) SP strength, I suspect its less to do with the recent acquisition and more to do with the HBO HP TV series, originally announced in April 2023, where concrete progress is now more obviously being made, as per e.g. https://deadline.com/2024/06/h...
IMHO, a ten year TV series will probably put a rocket under what are still strong HP sales and help extend them for many years to come.
Bloomsbury Publishing (LON:BMY)
Hi Shanklin
For reference HP revenues were:
I'm of the opinion that revenues are back to the the £35m level at most.
Children OP% pre-covid/pre-'Maas hysteria' was 12.5% - 15.0%.
For prudence let's assume HP generates a 20% Operating Profit.
So HP OP = c£7m today and £8m at their peak in FY22?
The market cap of the company is currently £582m.
I can't imagine HP revenues ever going higher than the £39m that was achieved during covid and so the franchise, as recognisable as it is, is surely too small to have any impact on the market cap of the company, with or without a new TV series.
I think it's important to add that Bloomsbury do not own US rights to the HP books, nor do they own Digital Rights.
I should probably add that after much deliberation I sold my Bloomsbury shares and no longer hold a position.
A
Thank you abtan, That's very helpful re Bloomsbury Publishing (LON:BMY)
Given a number of past experiences, as soon as you mention “Israeli software story stock” many readers here will pack their bags and head for the hills. But Windward (LON:WNWD) (I hold) seems to be delivering on its potential as a key part of the maritime data world for an increasing number of different businesses. Todays report on the first half finds it increasing its revenue, extending its product range and bringing its losses down to level that confirms their forecast of breaking even at EBITDA level in the second half and building its net cash to $16.7mm , almost half its annual revenue.
WNWD has had limited visibility in SCVR with Paul’s “heavy losses with jam tomorrow” comment in February setting the tone, but I think it is now proving that it can take a proper seat at the table.
Good growth rate and the company obviously has a product/products that fill clients needs and after breakeven, hopefully operational gearing with increasing revenue.Seems decent and i've seen it mentioned on a few of Paul Hill's fund manager interviews.Perhaps another IQGeo (LON:IQG) for the seas give it a few of years more growth hopefully?
Long suffering holders (prisoners) of Home Reit (LON:HOME) , of which I'm one, finally got some clarity on this with the proposed managed wind-down.
As a landlord, I can't believe the lack of due diligence by the original managers - both in the purchase of the properties and contracted tenants. I can't blame Scottish Widows for wanting to end their involvement by insisting on repayment by the end of the year, despite them charging a penal 7% additional fee.
18 months after suspension, it is frustrating that just as the new managers have (mostly) got control of the data and tenancies that they will not be given more time to turn things around, but the FCA investigation and various legal actions have made it impossible to secure replacement funding.
Although not a complete zero, holders will have to endure a Woodfordesque wind-down with return of capital from the sale of substandard investments and a lengthy wait for any compensation.
Score card:
Housing the homeless - Fail
Steady yield for investor - Fail
Original board - Fail
Original investment managers - Fail
The only winners here are those who sold them the properties and the various professional firms brought in to sort it all out.
I also hold PRS Reit (LON:PRSR) and the difference between these has been like night and day
Yes; Home Reit (LON:HOME) was an awful REIT and you must be disappointed that you didn’t manage to get out on time.
Although the REIT sector has been hammered, thanks partly to higher interest rates making the big dividend yields on them less attractive, those lower share prices and sometimes very big discounts to NAV on quality REITS (which Home Reit (LON:HOME) wasn’t) means some are well worth still checking out.
And there’s sector consolidation and bids going on now too. E.g Tritax EuroBox (LON:EBOX) now up from a low of 45p to mid 60s now with several potential bidders. And some, including Aew UK Reit (LON:AEWU) Alternative Income REIT (LON:AIRE) Supermarket Income REIT (LON:SUPR) and Schroder European Real Estate Investment Trust (LON:SERE) and others could be very good buys with the sector possibly now on the road to recovery at last
The attractive Investment Trust REITS have been well covered on the Investment Trust threads here, , with a new such thread every month, and if you or anyone else posts either info or questions on that thread you’re very likely to get replies.
Here’s the link for the July Investment Trust bulletin board here:-
https://www.stockopedia.com/co...
TBH I have never really been a fan of REITs considering them simply a way to play interest rates. Clearly Home have added a good dose of incompetence into the mix!
Exciting couple of days in UK macro with BOE decision in August on a knife edge . Probably more important than tomorrow’s headline inflation number will be whether service inflaton finally cracks , and whether there are signs of labour market loosening in Thursday’s employment data . My favourite dirty dogs to play a rate cutting cycle Mission (LON:TMG) Saga (LON:SAGA) Cavendish Financial (LON:CAV) Liontrust Asset Management (LON:LIO) Eurocell (LON:ECEL)
Tomorrow also sees the King's speech, where the government will confirm their priorities.
With planning and housebuilding expected to feature prominently, it would probably be worth reviewing watch lists for estate agents, such as Property Franchise (LON:TPFG), and building products.
Earlier this month I made the case for green energy and infrastructure funds https://www.stockopedia.com/co... Both of these should see some recovery on lower interest costs.
Paul’s surprise that Spectra Systems (LON:SPSY) (I hold)fails the James Montier “Cooking the Books” test is understandable since it seems to include a price/TTMsales ratio being over 2 (among other things). This is a very conservative test and even so the forward sales forecasts might even carry it there. Remember, if calculating from Stocko, that the market cap is always in £ but in this case, and many others, the revenue is in $.
Like Paul, I regard the test as not suitable for SPSY. But I would just note, as I have done previously, that the company is still not holding normal annual meetings. They are held in Rhode Island and they are always cancelled for lack of a quorum, which could easily be reached by a few large shareholders if they wanted to even though the quorum is set at 20% of shares (last time I looked).
Journeo (LON:JNEO)
Had been keeping an eye on these with a view to opening a position but todays announcement has actually put me off.
Paul said - They could have stated that trading is in line with expectations, which wasn’t done today. So some uncertainty might persist maybe?
I think Paul has got it spot on here. This for me is a very intentional attempt to reassure the market, yet they have not told the market they are in line with expectations. It all seems a little coincidental that the contract is announced the day after a big dip in the share price. With Journeo (LON:JNEO) stating the contract is in the forecast already, there is potential it was completed some time ago and was rolled out to us this morning just to stop the rot. If they didn't tell us the company was trading in line, my gut feeling tells me, this is because it is not trading in line - they are not hitting forecasts.
Maybe I am being cynical and a little risk averse, but I will not be opening a position at least until after the next update.
Journeo (LON:JNEO) I think you're probably reading too much into this - last year they did a detailed H1 (to end of June) trading update at beginning of August, so suspect they're still finalising the numbers on this. If things had significantly deteriorated they would have had to say something, so you could take that as a good sign.
Yes I agree with Bouden that you're probably reading too much into this re Journeo (LON:JNEO) . On all of their recent contract win / purchase order RNS's they've stated;
"included in management's expectations of performance for the current year these add to the Company's strong order book and provide further future revenue visibility."
None have mentioned whether they were trading inline, above etc so they have been entirely consistent
I think the Journeo (LON:JNEO) contract wins with the big train rolling stock owners, who lease trains to Government owned train operators, can provide some assurance that, despite the change in Government, contracts are still being signed.
Journeo (LON:JNEO)
if one wants to take the pessimistic viewpoint here signing contracts is one thing and the booking of revenues as expected earlier in the year ref those shiny new contracts can be something else.
So there is still room imho for the company to disappoint ref revenue bookings and profits whilst at the same time still signing decent contracts and being positive about the future.
This is where good managment are needed to keep expectations at reasonable levels and ideally deliver what they promise. for companies like this any shortall can be brutal ref the year end outakes and many comapnies never seem to claw back shortfalls in obvioius fashion the following year. The update today confirms they need to book revenues ref these new contracts so imho they have soem work to do.
Is the update today - as it was people - confident of hitting targets or sketchy in that it leaves wriggle room for bad news later. I will sit firmly on the fence here and offer no opinion (not like me)
I do have a recently picked up modest holding here but dont know enough about tehnn company to know how much management can be relied upon. Then only good news if there is bad news (som to speak) is that the general trajectory seems on plan presuming no bad news is being held back.
Yes it could be that I am reading into things a little and I of course hope I am wrong and holders make some money on Journeo (LON:JNEO). Kouremenous makes a fair and reassuring point about the wording being consistent with previous updates. With the small market cap it could be hit really hard by any shortfall as rmillaree points out. Happy to sit on the fence without a position and watch to see what happens.
Journeo (LON:JNEO) management stated that approximately £1m of revenue would be recognised this year, which gives clear line of sight of revenue from the contracts signed.
Until recently the shares had held up pretty well since the Tracsis (LON:TRCS) profit warning in June, that referred to contract delays in the train sector due to elections / change of Government.
As an investor I'm pleased Journeo (LON:JNEO) management have moved to try to address a fall in share price with no other obvious trigger.
I'm with Ben, being of a sceptical nature. The relevant section from the Tracsis (LON:TRCS) trading update is below. I can't see why this wouldn't affect Journeo (LON:JNEO) too. Last year they had a trading update on August 1, so we should find out soon enough. I have reduced my holding as, although I like the company long term, I see the possibility for a further short term drop
"The unexpected recent announcement that a UK general election will take place on 4 July 2024 has initiated a period of pre-election activity restrictions, resulting in a one-off impact on the Group's trading in the final two months of the current financial year. The Group had been planning for an October/November 2024 election date.
The pre-election restrictions are temporarily impacting central government, local authority and Train Operating Company decision making and spending across the UK transportation sector. This action is resulting in the rescheduling of certain projects and a short-term contraction of new order activity, that was previously expected to occur in the Group's Q4 financial period."
Journeo (LON:JNEO) (I hold and topped up early today,
My impression is that Journeo's main market is bus operators, so two wins from rail operators feels like a bonus. Moreover bus companies are less politically exposed that their rail counterparts, so they may be less vulnerable that Tracsis (LON:TRCS) (I also hold but sold half on the profit warning).
Richard
Journeo (LON:JNEO)
management stated that approximately £1m of revenue would be recognised this year, which gives clear line of sight of revenue from the contracts signed.
The thing is if they have only just sannounced the contract and preuming they are releasing that news promptly then imho the tricky bit is just starting - ie they need to deliver said contract as planned and to customer satisfaction (so that booked work can be signed off come audit at year end) - with the best will in the world it may be tricky to reliable work out what they can deliver right now - as you rightly point out if they say they are expecting £1 mill i have no reason to doubt it - just that its always a potential recurring theme that the proof of the pudding is later on when delivered not now wehn they may be presuming nothing goes wrong . As rogerh as eloquently aluded too its also possible that external factors could come into play too.
Out of interest does anyone know if there are forecasts in place for 2025 or not ? slightly unhelpful that nothing is pencilled in ref next year (on stocky) - i think that having figures in place for following year can always help if there are any minor setbacks on the way - eg if they did say there are delays 2024 that would not be so bad if 2025 is known to not have knock on effect from any delays. anyway i am deffo over speculating here so back too sleep we go.
Transense
Decent little update seems to be getting into shape now .
I’d expect translogic to pick up in the next 6 months as the new staff and better management get those contracts over the line, that’s a good product easy to sell just no reasons for that to not succeed .
Sawsense long runway product so don’t expect anything next 6 months
Bridgestone royalty keeps filling up the bank and they buyback with it
Market likes it .
Looks ok and on track .
Good CEO and chairman have this moving in the right direction room .
Harwood and Onward/Dowgate both hold .
Today's announcement from Spectra Systems (LON:SPSY) provides a bonanza of revenues for now till FY Dec27.
US$38m over three years; in context FY23 revenues were only $20m....! Plus, super high margin, flowing to the bottom line.
Zeus broker note on Research Tree today is worth a read. They clearly have the inside track on how to construct the P&L forecast based on the various contracts/revenue streams the company has. In the past, they have been quite accurate with their forecasts, and usually beaten (as they take a very conservative approach to new business).
For example, just to illustrate the step change this new announcement has had, FY25 diluted EPS forecast went up from 20.3c to 37.1c.
And this EPS forecast is not including the service part of the contract (this is just the production/physical units delivery). The service contract will start from FY25 onwards, and value still TBC, IMO likely in the millions a year. So a further upgrade to FY25+ forecasts is all but guaranteed, once that service contract is signed in Q1-25.
------
I personally think these should be trading at 370p (vs current price at c260p). And my price target doesn't include any potential option value from their ambition to break into polymer banknote printing. This revenue is probably still 3 years+ out at the very least, and no firm contracts yet.
Zeus has their price target at 380p.
(I hold in the Boon Fund)
Thank you to Alan Charlton who brought this to our attention at Mello in May at the "Bash" and I bought.
Who was the genius at Likewise (LON:LIKE) who thought a £250k buyback was a good idea.
"Any Ordinary Shares acquired as a result of the Buyback Programme will be initially held in treasury and then may be cancelled periodically." So they aren't even cancelling them.
Meanwhile the directors
Hi Wolf correct me if I'm wrong but presumably the difference between full cancelling and cancelled and held in treasury is that if the cancelled shares are put in treasury they can be reissued again in the future with minimal ag ?
Regards
Andy
Phoenix, I'd think the treasury shares would be used for future share incentive plans etc
Thanks Wolf
Shares are either cancelled (ceasing to exist) or held in treasury (still existing but owned by the company), not both.
Synectics (LON:SNX)
Key takeaway from the IMC pres yesterday for me was the comment on Downing 10% shareholding. NOT BEING SOLD. Will transfer across to one of their funds that remains open. IMO this removes the possible overhang impact of a big seller and will hopefully allow appreciation of the SP as the year progresses. Could be wishful thinking as I hold.
I do wonder if they are still selling some. Looking at the trades yesterday there was a big seller still. Even if they did sell it wouldn’t take too long to clear, a month maybe or a little longer and it would give any people interested a chance to get in.
Fascinating update from former Stockopedia favourite Sosandar (LON:SOS) following a big strategic pivot from online only to omni-channel over the last year.
It confirms a massive uptick in gross margins (now running at >63% for Q1 this year) by moving towards a 'one price everywhere' strategy, with much less and less deep online promotions to make sure its pricing in new affluent-town retail stores work. The first 2 of these (Marlow and Chelmsford) will open in Sept. The downside to restricting promotions is that this will restrict revenue growth in the short run so no topline growth expected in the coming year although profit will be kept the same and opening stores will require them to show new skills to make an expensive channel deliver.
Success will be big if they can resume growth thereafter by rolling out (now self-funded) stores on top of making online sales through their app and 3rd parties like Next. The ambition of £100Mn in revenue (vs £46Mn now) and 10% margin looks doable in a few years if they continue to hit a fashion sweetspot with a core market who are willing to pay for as what they are doing. So far, the evidence seems to be they will. If that happens, they are going to build a really strong, valuable brand long term.
They certainly seem to now have the cash and set up now to give it a real go.
The biggest risk beyond fashion must be overreach. International sales sound glamourous and a truly globally successful retail brand would be extremely valuable but Canada has fallen over (partner failure) and total international sales were only £100K last year. How many fronts should they work on simultaneously?
Sosandar (LON:SOS) still feels like a start up. Major success or blowout failure still seem like very plausible outcomes.
Personally, I retain confidence in the fashion sense, practical nous and organizational capability of the co-CEOs. As long as they remain engaged, as at previous founder led fashion businesses, I think they will make it work. As ever, we will see.
Agree, fascinating update from SOS.
My reading is that they are still in the middle of executing their strategic shift from seeking revenue growth to seeking profit (with bricks and mortar shops as a means to elevate the brand). At this point they are in the difficult spot where revenue growth has stalled (a deliberate choice) and profit hasn't really grown (a desired outcome).
Regarding the brand, I find the statements and actions of the management a bit confused. Selling through Sainsburys/TU but then also prioritising middle/high income shoppers in places like Marlow and Chelmsford. I was in Marlow last week and the average yummy mummy (I believe their target demo) would turn their nose up at the brand if they found out the same clothes were retailing through a supermarket.
I hold Sosandar (LON:SOS) and wanted this update to deliver more progress. Overall, I'm a bit uncertain what to do with my position.. sell at a loss or give them a bit more time for the strategy to play out. To be decided..
The confused channel marketing strategy of Sosandar (LON:SOS) is precisely the reason I sold last year. I beg to differ with Zipmanpeter that Sosandar (LON:SOS) is showing the metrics of a growth stock. Of course, I wish holders luck.
The Sosandar (LON:SOS) numbers are pretty disappointing for a growth brand... right now it doesn't look like their 2023 strategy (more full price, more third party distribution is working).
H2-24 (to Mar24), should have shown some stellar results. Given that their D2C online is mature, and their distribution partnerships all in place and mature for at least a few months. What did we get?
Only a +12% increase in revenues YoY, and PBT down from £1.5m to £1.0m.
I would say that is a disaster.
Now their "Phase 2" growth strategy, international and stores, are also off to a wobbly start. Canada as you mentioned, and the delay in stores (they were meant to launch in spring24, rather than autumn24).
Given the barely profitable status here, I think the share price is susceptible to weakness. I can imagine it trading at like 0.25x revenue to 0.35x revenue. Which gives a share price range of 4.66p to 5.6p. Adjusting for the fact they have net cash, say £4m is surplus, could give a 6.3p to 7.2p share price range.
Not saying it will definitely go here; but in my mind that is a distinct possibility. Lack of profits for the rest of FY25 (given those stores will cost quite a bit initially, loss-making too) and the "Phase 1" (D2C online and partner distribution) not contributing any meaningful growth or profits this FY either.
Sosandar (LON:SOS)
Mike, this is what I think;
the brand is not growing, Q1 sales down 28% should tell you this, they still cant make a profit, in October 2023 they decided to open some bricks and mortar shops due to their perception that peoples buying habits were changing, but the first of these will not open until September 2024, fashion trends change quickly and who's to say that peoples buying habits wont have changed again within that year. Up until two years ago the founders had done a good job building the brand now they seem to have run out of steam and dont know which way to turn. This business should not really be listed.
We await the Masters thoughts then. I'm a little more positive my wife and her friends love shops, we are comfortable so the pennies dont matter, for myself I always buy the quality and experience. But I agree this does not make them a big winner. Time will tell, unfortunately like all I'm down, my last venture in fashion, like you say its very much a fad these days
I'm assuming that given his historic interest in this Company, Paul will be reporting shortly.. it's a fashion business so of course things change, that's what fashion means. Their job is to stay on the ball, if you think they can (and they probably haven't turned into idiots) this is a bargain. The dramatic sales increases suggest they might be in tune with the market, the concentration on margin suggests they are maturing as a business.
What was it Warren Buffett said ?
I think Paul from what he has said recently feels less attuned to his old experiences in Retail than he used to
Sosandar (LON:SOS) floated at 15p and market cap now is about £25 million. The hope (expectation even) as long ago as late 2020 (check out past analysis from Paul both then and subsequently on Results and trading update days to confirm) was that by now Sosandar would be very profitable, throwing off cash and a £multi million Company. The reality is inescapable and reflected in a share price now down to just 10p.
Any share can go up (e.g on a surprise bid) but with so many small companies and Investment Trusts at bargain prices I’m not remotely tempted to buy Sosandar (LON:SOS) until at long last there’s an update that reveals real signs of their business at last taking off. Best to buy on genuine good news and not hold for years dreaming of that happening? It’s been a very long wait already.
Experian (LON:EXPN) Not a small cap by a longshot, but I like to follow its progress as it's the second-largest holding in Finsbury Growth & Income Trust (LON:FGT, which is run by Nick Train.
It reports revenue increases of 7%, which is pretty good. What an amazing powerhouse it has been over the last decade, with share price increasing at around 13.4% pa on average. The share price is down 1.7% to 3577p today on the back of results as I write. The shares are on a fwd PE of 29, which already has lofty expectations baked in.
I thought it would be interesting to look at the Stockopedia report from a decade ago (those archived reports are a great boon, and I hope Stockopedia never gets rid of them). This is the actual link to it, in case you're interested: https://s3.eu-west-1.amazonaws... Even ten years ago, the company showed undeniable quality. Although its Quality score was only 74, it did have an average ROCE of 15%, and operating margins of 20%. Operating cashflow had been increasing a little over 10%pa over the preceeding 5 years, and book value ps at 12%. It was on a more modest PE of 18.
It wasn't exactly cheap as chips even then, but that did not stop it performing well over the subsequent decade. There's a pretty significant valuation headwind now, though.
I don't own EXPN (although with hindsight I wish I had, of course), and I thought it would be interesting to provide a little context behind EXPN.
Experian (LON:EXPN) : Hi Mike : Can't agree more about EXPN - always looks expensive and appears a very lethargic share price - but the longer term tells the picture. Have held since they split apart from Homebase (!) in 2006 (ignoring a 2 year period when I got bored). This appears like a real "picks and shovels" type investment, with their services appearing to be indespensible to other businesses - as similar reason to be interested as was the case for Washington Post when Buffet bought it in 1973. The question is how long can this last ? AI ? Keep an eye on the ROCE I think. [This ties in with BnB's post from yesterday - ROCE seems to be a common metric setting apart long term winners from run of the mill businesses. Interesting to share at least 4 of his listed shares]. While not wanting to talk the U.K down, it is depressing to see EXPN's breakdown of organic growth across their geographies : 8% for North America, 7% for EMEA/Asia Pacific, 5% for Latin America, 2% for UK & Ireland. ATB Geoff
I suspect partly because for EXPN, the UK is a mature, saturated market. The US has higher growth and more competition...
The team at Lindsell Train often state that investors persistently underestimate quality and fail to price high-quality stocks appropriately.
Sosandar (LON:SOS) Nicely drafted update, well seems that way to me (simple no bs), I think these guys have what it takes, just waiting for the Guildford store. Its going to take a while but in 5yrs if they can develop a loyal following they could do exceptionally well. What do we all think ?
Tbh while you say no BS I am sceptical of the approach that Sosandar are prioritising margin over revenue growth. I think they've been forced into that strategy because the product isn't selling well enough as evident by the post year end trading.
I don't think their clothes are clearly differentiated enough and I think their branding is a bit weak. Opening high street shops might provide a short term uplift but it's going to be a major test in how well they manage the brand.
Sosandar (LON:SOS)
Looking at the graph and their track record I strongly believe that these guys haven’t got what it takes!
I have warned many times on this especially now they will have their own high street stores.
All the best
On Sosandar (LON:SOS)
TL;DR Early promise not quite met. Profitable growth :) - just. Crowded market and lack of real income growth are headwinds. Shop chains that are aimed a relatively limited market are difficult to roll out. Best of luck but I pass.
Detail: From their investor page. Sosandar is one of the fastest growing women’s fashion brands in the UK targeting style conscious women who have graduated from price-led alternatives. The Company offers this underserved audience fashion-forward, affordable, quality clothing to make them feel sexy, feminine, and chic. The business sells predominantly own-label exclusive product designed in-house.
This may have been true in 2017. It is not 2017 anymore. It isn't particularly fast growing now. Back then, there was a gap between primark (young, cheap) and m&s etc (over 40(?), value). A web only offering could fill that gap and scale quickly.
I would argue that there is much less of a gap in the market now. M&S is resurgent and there is a number of web only retailers (BOO, Shein in the value segment). I was frequently reminded during the election that real incomes have not grown for the last 15y or so.
Setting / Scaling up a physical chain that is targeted on women who are not teenagers and have a bit of money to spare is not the same as a website. There will be a temptation to defocus the brand. Doing something 'different' is a sign that the core business concept is not succeeding (I think it is called a 'pivot')
They have never achieved positive FCF (I have learned the hard way that this is important).
So best of luck to them but I think the wind is against them and I pass. Writing this so that I can smile ruefully when I read this in 5 years time.
Sosandar (LON:SOS)
As I said earlier the founders had built a great brand but when online and partner sales growth started to drop off I feel that own brand shops was the last throw of the dice, but i think even if it is the right decision it will be too little and too slow, looking at some of the slides on their online presentation just now I think some of their assumptions are very naive, one of those is the assumed stock turn of 20 times, i would not of thought that possible, but would be happy to be corrected.
I have bought a few dresses, tops and jackets from Sosander in the past. (I frequent John Lewis, Zara, M&S type stores.) Sosander garments were ok when they were cheap. They have now doubled in price but the quality and value for money does not warrant it. They do not compare well with equivalent garments from stores mentioned. I used to own their shares a long time ago but, based on their product , wouldn't buy them now.
Journeo (LON:JNEO) Paul, Gervais Williams has been selling as announced in Https://www.youtube.com/watch?... 39:35
Gateley (Holdings) (LON:GTLY) - it would be interesting to get your thoughts on this Midlands based legal firm: solid full-year results.
My morning smallcap tweet: Hanging in the balance sheet
Vanquis Banking (LON:VANQ) Heiq (LON:HEIQ) Libertine Holdings (LON:LIB) Home Reit (LON:HOME) Journeo (LON:JNEO) Windward (LON:WNWD) Transense Technologies (LON:TRT) Likewise (LON:LIKE) Spectra Systems (LON:SPSY) Gateley (Holdings) (LON:GTLY) Trufin (LON:TRU) Sosandar (LON:SOS) Infrastructure India (LON:IIP), Itaconix (LON:ITX), Northcoders (LON:CODE), Iofina (LON:IOF), Tissue Regenix (LON:TRX), McBride (LON:MCB), Brickability (LON:BRCK)
◄Vanquis Banking (VANQ)► doesn't expect to meet its FY24 guidance of low single digit ROTE. Further c.£11m of write-downs. H1-June new bookings in second charge mortgages exceeded expectations,. [SP=52.7 Cap=133m]
◄HeiQ (HEIQ)► seeking to raise equity financing at the HeiQ AeoniQ subsidiary level. [SP=11.4 Cap=19m]
◄Libertine (LIB)► update on proposed financing. Expects first amount to be received this month but size unknown! Co may seek short-term funding via a placing. [SP=1.85 Cap=3m]
◄Home REIT (HOME)► proposes a managed wind-down. "The ability of the Company to make distributions to shareholders will be constrained whilst the Company faces potential group litigation and an FCA investigation." [SP=38.05 Cap=301m]
◄Journeo (JNEO)► wins 2 contracts worth £3m with £1m booked by Dec. Tcontracts are included in management's expectations. [SP=212.1 Cap=35m]. I hold.
◄Windward (WNWD)► guides FY-Dec rev lightly ahead of market expectations and is confident of achieving an EBITDA break-even run rate this FY. [SP=99.67 Cap=88m]
◄Transense Technologies (TRT)► guides FY-June rev up 18% and adj EBITDA up 21%, both slightly above market expectations. CO enters FY25 at a revenue run rate consistent with management expectations. [SP=129.75 Cap=20m]
◄Likewise (LIKE)► £250k max buyback. Free underlay. [SP=16.65 Cap=41m]
◄Spectra Systems (SPSY)► wins 'long-awaited contract for the third generation of sensors' worth $37.9m with a further $1.7m expected later this year. Expects bulk of rev from Q1 2025 through Q4 2027. [SP=235.9 Cap=113m]. I hold.
◄Gateley (GTLY)► FY-Apr. Guides FY25 in line. [SP=136 Cap=181m]
◄TruFin (TRU)► Lloyds Bank gives notice to terminate its 5-year commercial agreement with Satago. Trading in line. [SP=76.35 Cap=67m]
◄Sosandar (SOS)► FY-Mar rev up 9%. Guides FY25 rev miss but pre-tax in line as co prioritises margin over rev. [SP=10.25 Cap=25m]
◄Infrastructure India (IIP)► shares suspended today because board no longer quarate. [SP=0.01 Cap=m]
In line: ITX, CODE, IOF, TRX, MCB, BRCK
Macfarlane (LON:MACF) Appoint of Non-executive Director
Not normally riveting news. But in this case?
David Stirling, recently retired long time CEO of Zotefoams (LON:ZTF) has just been appointed NED at Macfarlane.
Intriguing? I had already sensed a strategic shift at Macfarlane (LON:MACF).
Sales at the largest division, distribution, have been falling . My assumption has been that the company is choosing not to compete upon price in low margin general packaging sales while increasing their focus upon higher margin specialist protective packaging.
Their rapidly growing manufacturing division both organically and through acquisitions has higher margins. Last week they acquired Polyformes a leading supplier of custom foam packaging and engineered parts to the aerospace and industrial markets - where Zotefoams is one of their main suppliers. In 2023 they acquired Barum and Dewar, a bespoke protective packaging maker (including engineered foam products) for the aerospace and defence markets.
The bespoke packaging industry supporting aerospace, defence and industrial sectors in the UK is very fragmented. It's much higher margin than corrugated cardboard and bubblewrap and tends to work on long term relationships. esp for shipping high value fragile items. This supports my view that Macfarlane (LON:MACF) is aiming to build a leading position in this specialist long term growth market?
I shall watch with interest. Long term I expect this to increase margins and rate of earnings growth,
cheers
Mark (liong term holder of Macfarlane (LON:MACF)
Good to see that Kinovo have finally managed to draw a line under their legacy issues. I hold.