Small Cap Value Report (Tue 16 March 2021) - SCS, EYE, LIT

Good morning, it's Paul & Jack here with the SCVR for Tuesday.
Agenda -
Paul -
Scs (LON:SCS) (I hold) - Interim results
Eagle Eye Solutions (LON:EYE) - Interim results
Jack -
Litigation Capital Management (LON:LIT) - litigation financing firm; revenue down due to Covid but but optimistic on future business
Mello Tuesday
Investing in Metals and Mining - a very topical subject, with this sector being buoyant at the moment. It's not something that I cover, but readers may be interested, I know a lot of you hold Sylvania Platinum (LON:SLP) for example. More information here, including a discount code for Stockopedia readers.
.
Paul’s Section
Scs (LON:SCS)
(I hold)
232p (pre market open) - mkt cap £88m
ScS, one of the UK's largest retailers of upholstered furniture and floorings, is pleased to announce its interim results for the 26 weeks ended 23 January 2021.
ScS has an unusual year end, close to the end of July each year.
It’s quite tricky to work out what has happened in each 6 month period, so I’ve gone back to the last year pre-covid (FY 7/2019), which looked like this:
H1 (26wks ended 26 Jan 2019) - Revenues £151.4m, Underlying EPS 2.2p
H2 (26 wks ended 27 Jul 2019) - Revenues £166.0m, Underlying EPS 28.1p
As you can see, in a normal year, ScS makes almost all its profit in H2. I think that’s because the busiest time for taking orders is Christmas & January sales, but due to the time lag between orders being placed, and actual deliveries weeks later (it’s delivering the finished goods to the customer that would trigger revenue being recognised), then the busy period feeds into revenues in H2.
Numbers for 2020 were normal in H1, ie. around breakeven, then H2 (26 wks ended 25 July 2020) bore the brunt of covid lockdown 1 (the most severe), generating only 2.9p u/l EPS, instead of the usual large H2 profit.
What seems to have happened is that, when the shops re-opened (in June 2020, I think), then there was a great deal of pent-up demand, which caused a surge in orders. The time lag then meant that a lot of this surge in orders were not delivered until H1 2021 (26 wks ended 23 Jan 2021) figures which were published today.
Therefore, instead of looking at the usual seasonally slower H1 period, we’ve got boom-time numbers, as all that backed up demand was fulfilled.
As you can see from this excerpt of the financial highlights below, the profit that was foregone in H2 last year due to lockdowns, has surged through in H1 this year. This is a key point that I like very much about SCS (I hold) and also demonstrated recently by larger competitor Dfs Furniture (LON:DFS) - that covid/lockdowns cause only delays in sales, which are then recouped later. As opposed to many other companies which lose sales forever (especially in travel/hospitality/leisure sectors) during lockdowns.
Another factor to consider, is the well-publicised trend for people revamping their homes, due to spending so much more time at home, which will have boosted demand for ScS.
Taxpayer support - another complicating factor is that ScS has been very open about receiving £6.6m in Govt support, mostly business rates relief, which has significantly boosted these numbers, and of course is being phased out this year gradually. ScS clearly didn’t need this taxpayer support after all, which raises the thorny issue of whether it should be repaid? It looks as if the furlough money is likely to be repaid;
As stated earlier in this statement, the Group intends to repay its current year CJRS grants if trading of our stores is in line with our expectations...
Outlook - the key question now, is how the latest lockdown has impacted orders for H2? Re-opening of ScS’s stores is scheduled for 12 April 2021, which sounds early enough for pent-up demand to be fulfilled by the end July year end.
There’s a lot of catching up to do -
Overall order intake decrease of 87.2% on a like-for-like* basis for the first seven weeks of the second half of the year to 13 March 2021 due to the current temporary store closures, resulting in order intake decline of 23.8% for the 33 weeks to 13 March 2021
Evidence from the last lockdown, is that demand springs back with a vengeance, so I would expect the same thing to happen this time as well.
I think the key phrase in the outlook comments below is “cautiously optimistic” -
With consumer confidence and the economic environment remaining uncertain, it is difficult to provide clarity on the Group's outlook for the weeks and months ahead. However, we remain cautiously optimistic as recent government announcements have provided further clarity on the anticipated reopening of our stores. The business continues to adapt and respond to trading conditions, with increased focus on the development of our digital channels....
Order book - this is important, it was a lot higher at 31 Jan 2021, than a year earlier (just before covid started), which gives me comfort that the company has enough work to tide it over through during this latest lockdown.
The Group's order book at the end of January 2021 was £90.5m (including VAT), which is £16.8m larger than at the end of January 2020.
Given that a normal half year is around £170m revenues, then 53% of H2 revenues should already be in the bag from existing orders. Then ScS should see a surge in new orders from re-opening in April 2021, which should be delivered before end July year end. Put that together, than I think the outlook for H2 is looking promising.
Online sales - growing fast, up 81% in H1 to £17.7m, but that’s only 10.2% of total revenues, a long way behind the 25% that Dfs Furniture (LON:DFS) recently reported, so there’s clearly an opportunity here for ScS to increase its online sales. Maybe they should look at what DFS is doing, and emulate it?
Online sales in H2 (first 7 weeks) are up 157.5% (no other figures given), an increase which I would expect given lockdown 3 is underway. On the results webinar, they've just said that online sales should be up to 15% by year end.
There’s some good commentary about further initiatives to boost online sales.
Variable cost base - I particularly like this analysis, showing how the cost base is mostly variable or discretionary, making the business model very resilient in a downturn -
Excluding government support, total costs before tax for the year were £171.2m (2020: £160.7m).
Of this total, 76% (2020: 74%), or £129.5m (2020: £118.5m), are variable or discretionary, and are made up of:
· £98.6m cost of goods sold, including finance and warranty costs (2020: £88.4m);
· £9.8m distribution costs (2020: £9.1m);
· £11.5m marketing costs (2020: £14.5m), and
· £9.6m performance related payroll costs (2020: £6.5m).
Semi-variable costs totalled £21.3m, or 12% of total costs, for the year (2020: £19.8m; 12%) and are predominantly other non-performance related payroll costs. Depreciation and interest (including ROU assets), rates, heating and lighting make up the remaining £20.4m (12%) of total costs (2020: £22.4m; 14%).
Balance sheet - NAV is good, at £39.5m. Removing £2.2m intangibles assets takes NTAV to £37.3m, still good.
There are large IFRS 16 lease related entries, which I also remove (£108.3m Right of use asset, and £24.9m current liabilities, and £103.1m non-current lease liabilities). Future years’ rents should not be on the balance sheet at all, simple as that, in my opinion. The old system was far better, with just a provision required for any loss-making sites. The IFRS 16 entries are a net deficit of £19.7m, so I would add that back to NTAV of £37.3m, to arrive at adjusted NTAV of £57.0m, a very healthy position.
The financial position is further helped by a very favourable working capital structure. Furniture retailers make the product to order mostly, so this means low inventories, and receipt of cash from customers well before suppliers have to be paid to make the furniture.
The Group operates a negative working capital business model whereby:
· For cash/card sales, customers pay deposits at the point of order and settle outstanding balances before delivery;
· For consumer credit sales, the loan provider pays ScS within two working days of delivery, and
· The majority of product suppliers are paid at the end of the month following the month of delivery into the distribution centres.
For this reason, whilst the current ratio of 1.15 is nothing special (current assets of £113.0m, divided by current liabilities of £97.8m), note that current assets includes a whacking great cash pile of £97.8m! There’s no interest-bearing debt, so that’s net cash of £97.8m, which is more than the market cap of the whole company!
I think this makes ScS a sitting duck for a private equity takeover bid. They’d strip out that cash in the blink of an eye, load it up with debt, and therefore get the company for free! There are no dominant shareholders, it’s all institutions, so agreeing a bid would probably be quite easy, and I reckon they would like the prospect of an opportunity to exit at a premium. A bid at 400p would get my vote!
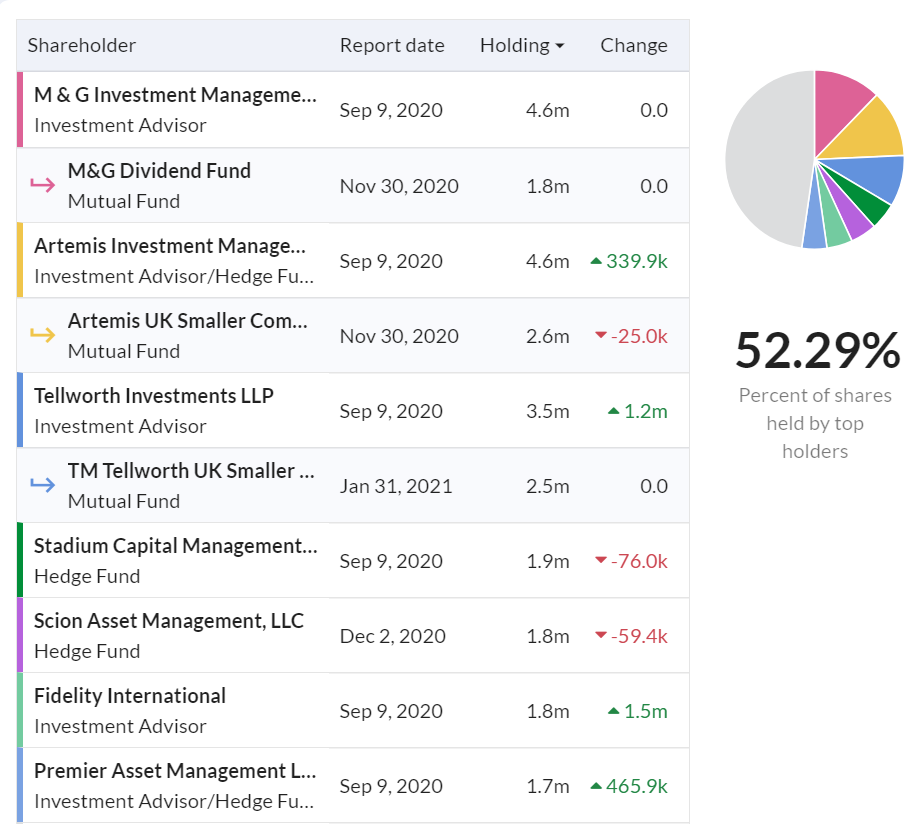
Valuation - it’s blown the 23.5p full year (FY 07/2021) forecast out of the water, with 37.5p achieved in H1.
I feel there are so many moving parts in last year & this year’s numbers, that we need to make lots of adjustments. I can’t find any broker forecasts. The most logical, and simplest, way to look at things, in my opinion, is to refer back to profitability before covid, and just assume it’s likely to achieve similar profits (or higher) in future. After all, it’s essentially the same business.
That means 30p EPS is the ballpark figure I’ll use for valuation. Put that on a PER of say 12-14, which looks about right to me, and I have a target share price of 360-420p - way below the current price of c.243p. To me, this share is quite obviously the wrong price, but I’ve been saying that for quite a long time! So it might be one of those frustrating shares that never seems to re-rate, despite being absurdly cheap.
The other issue is that ScS went bust in 2008, and I think that has weighed on sentiment ever since. The reason was that credit dried up in the credit crunch, which looks very much like a one-off. ScS has sailed through the covid/lockdown situation, thanks to a very much stronger ungeared balance sheet, and resilient consumer demand. Totally different situations. Hence I feel investors should see the ScS of today as a very much stronger business than in the past.
My opinion - a very impressive set of H1 numbers.
This is a very resilient business, and has a bulletproof balance sheet.
As explained above, I think this share is completely the wrong price. A more logical valuation is something like 300-400p, in my opinion, so there’s good upside here, from the current c.244p.
I’m just on the results webinar now, so might add additional points below if anything interesting crops up.
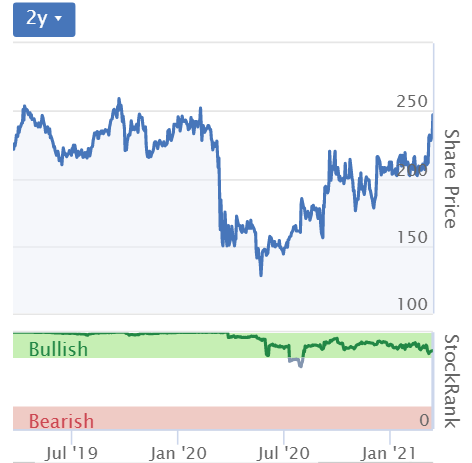
.
EDIT: Webinar - has just finished. Management come across really well, as down-to-earth, hands-on management. Very much what I like, if we can't have an owner/manager (my top preference).
Here are the presentation slides which were talked through by management on the webinar. They're really informative, so I do suggest you take a look at them - presenting key information in an easily digestible form.
Here are my notes from the webinar (not comprehensive, just things that I thought were noteworthy) -
- Over half the product is manufactured in the UK (slide 13) - so container freight issues from Far East less of a problem
- Online - now doing virtual walkarounds in stores (by appointment)
- Marketing spend is very flexible, can be adjusted up or down, deferred, etc, when needed. Big splash planned for re-opening in April 2021, will be similar to peak Xmas trading (augurs well)
- New CEO has 30 year career in retailing (mainly Sainsburys & Argos), been shadowing long-standing CEO for last 10 weeks, going very well, saying "The business is everything I hoped it would be, and more"
- Market share has grown from 9.4% to 9.8% estimated
Q&A
- What will you do with cash pile? Reinstate divis in due course, also looking at possible acquisitions
- Freight costs re containers from Far East a problem? So far just small cost increases, via UK distributor. If cost pressures come through, then would be passed on via price rises. Hoping that freight charges might return to normal now Chinese New Year has happened
- I queried difference between gross sales of £182.3m, and revenues of £173.9m. It's the cost of providing interest-free credit.
- Why did Trustpilot approval fall from 4.6 to 4.5? (from memory, I hope those numbers are right) - still very good, but was affected by product manufacturing & freight delays. Stores typically ring every customer fortnightly, to update them, even if not delayed.
- Might look at doing own manufacturing in the UK. Sofa.com do this, for example
- Rents - will they reduce? Yes there are ongoing opportunities, e.g. in weaker retail parks, but still good demand in better sites. Some reductions will feed through, but expected to be offset by other cost increases (e.g. distribution costs)
Recording of the webinar is now up on BRR Media's website - you can search for it , or hopefully this link might work. Not sure if it's personal to me, or will work for everyone?
End of edit.
.
Half year results
I've just discovered a really useful feature buried in Stockopedia, that I've never noticed before.
I often like to work out sequential half year performance on the profit & loss statement. It's easy enough to do manually, by deducting the interim H1 numbers from the full year figures, the difference is therefore the H2 performance (including any audit adjustments, so it may not be exact). It's important to do this, to ascertain what seasonality there is. Otherwise, if you just double the interim profit to get to a full year profit, you can end up making a hideous mistake on a highly seasonal business. A good recent example was the stellar interim numbers from Hotel Chocolat (LON:HOTC) but on closer inspection, it turns out that the company makes all its profit in H1, and is then loss-making in H2!
Well, it turns out the Stockopedia has done the work for us! On the StockReport, If you go to Accounts tab, then click on Income Statement, then change the "Statement period" from "Annual" to "Interim", then it shows results for each sequential 6 month period. This enables you to quickly check what the usual seasonality of the business is, by looking at revenues & the various profit measures.
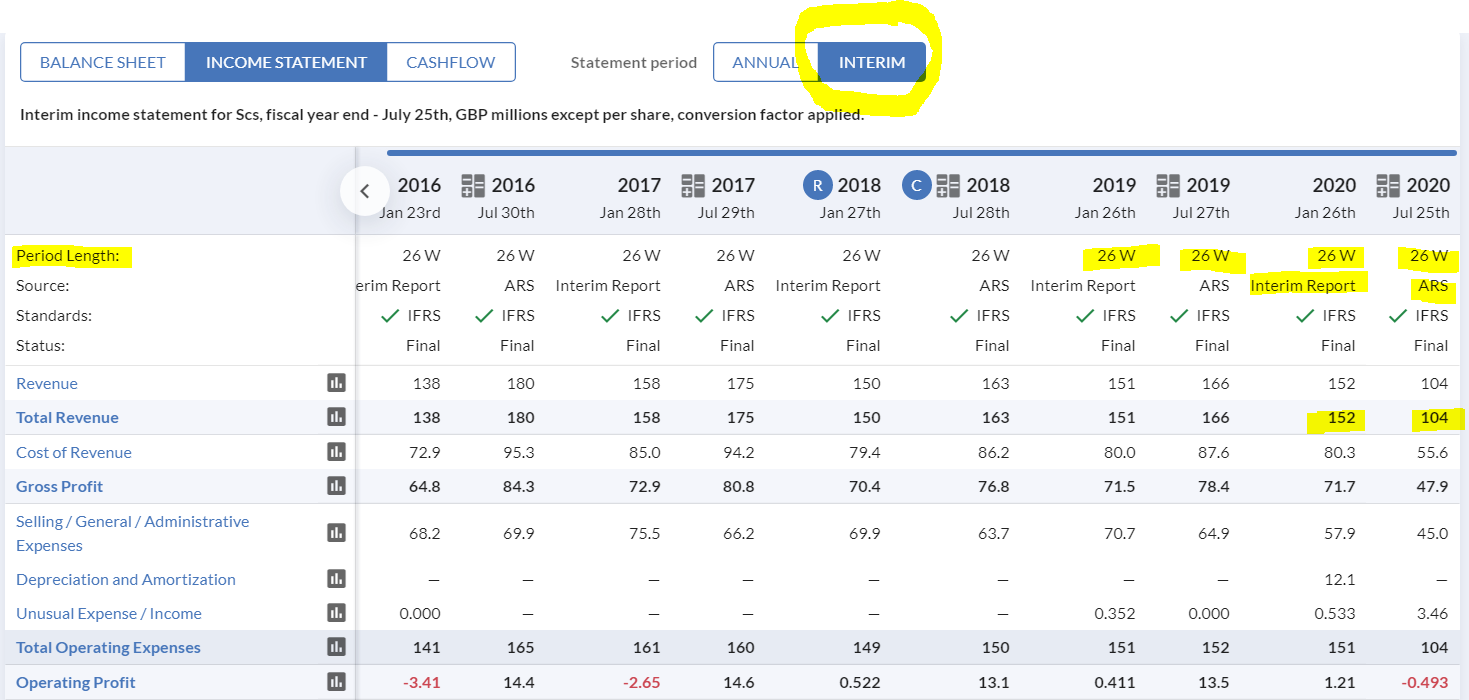
Here's an example from Scs (LON:SCS) (I hold), where you can clearly see the usual cyclicality is for H1 to be near breakeven, and H2 to be highly profitable -
.
So in this case, I've highlighted how each period is 26 weeks, H1 and H2. i.e. Stockopedia has worked out the H2 numbers by doing the calculations for us. You can see above how H1 (labelled "Interim Report") revenues for ScS are usually lower than H2 (labelled "ARS" - maybe Father Jack compiled the table?! Joking apart, I assume ARS that stands for Annual Results Statement). But in FY 07/2020, H2 revenue plunged to £104m, down from H1 revenue of £152m, due to the impact of lockdown 1.
So there's a really useful feature, that I'll be using in future to quickly check on normal seasonality, that should save me a good bit of time not having to manually work out H2 performance figures. I hope you find that useful too.
.
Eagle Eye Solutions (LON:EYE)
474p (down 5%, at 13:45) - mkt cap £123m
Eagle Eye, a leading SaaS technology company that creates digital connections enabling personalised, real-time marketing through coupons, loyalty, apps, subscriptions and gift services, is pleased to announce its results for the six months ended 31 December 2020 ("the Period").
The little PR heading is stretching credibility almost to breaking point, by saying -
Strong profit growth underpinned by new domestic and international customer wins
This is how I see it -
H1 revenues only up 8% to £10.8m
Mostly recurring revenues (73% of total), which is good. Balance is development & set up fees (see note on segmental analysis)
Churn very low at 0.2%, although I’d be interested to see how the figures are worked out, as some companies offset customer losses with increased business from other customers. Don’t know how EYE calculates churn, but with a very impressive large client list, it looks like revenues are indeed likely to be very sticky, once integrated into the systems of e.g. large supermarket chains.
High gross margin, so once systems are installed, it’s lucrative business.
EBITDA - is meaningless, because it ignores £1.3m of capitalised development spend in H1 (was £2.8m last full year)
In reality, EYE traded just above breakeven in H1, £197k profit before tax, a tiny profit for a company valued at £123m, but improved from £(632)k in H1 LY.
Taxation - I’m surprised it’s paying corporation tax on such a small profit, and given that I would have expected to see R&D tax credits claimed, so a query on this point.
Outlook comments - very bullish, with mention of a record pipeline. Covid has slowed down growth, fair enough that makes sense. Company says growth should accelerate. Good - it needs to, to justify the current valuation. Overall, trading in line with expectations for FY 06/2021. Is that enough to justify the huge rise in share price? I’d say not.
Balance sheet - threadbare. Only £0.1m net cash, but the company is relying on having access to a £5m borrowing facility. With the valuation this high, it’s a no-brainer to do a small placing, to strengthen the balance sheet, I reckon.
Receivables look high at £5.4m, which looks to be about 90 days revenues. Cash collection maybe could be better?
Weak current ratio. Negative NTAV. So quite weak overall, but with predictable recurring revenues, does that matter? Arguably not.
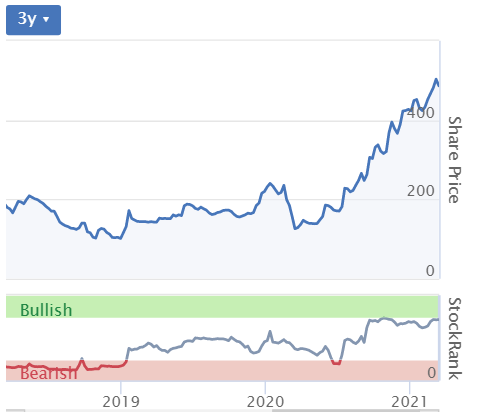
My opinion - these are not good numbers, for a company valued at £123m. I think the share price has run well ahead of reality. But, we’re in a roaring bull market for growth/tech stocks. The attraction of EYE is the blue chip client list, strong retention, recurring revenues at high margins, and the global market opportunity. So if you’re feeling gung-ho, then this could be the type of share to just buy, and ignore valuation altogether. Risky, but that’s an approach which has worked well for quite a few years now.
For me, the growth isn’t strong enough at EYE to make me want to take an interest. I think Pci- Pal (LON:PCIP) (I hold) looks a much better proposition - growing much faster, almost at breakeven on a monthly run rate, yet less than half the market cap of EYE.
.
.
Jack's section
Litigation Capital Management (LON:LIT)
Share price: 71.32p (-7.4%)
Shares in issue: 115,654,666
Market cap: £82.5m
Founded in 1998, Litigation Capital Management (LON:LIT) is one of Australia’s most experienced and successful litigation finance companies. It helps clients achieve recoveries from claims that, without help, would have been too costly and/or risky to pursue.
These alternative asset managers specialise in dispute financing solutions. Their accounts and operating characteristics are fairly unique (at times even controversial) in that revenue and profit recognition can be quite subjective on account of how long court cases take to resolve.
For LCM, the average case has lasted around 27 months over the past nine and a half years.
During that time, growing litigation managers also tend to exhibit large cash outflows as they raise capital and then deploy it into new cases. This makes them hard to value on a cash flow basis but, if you believe that this capital is being deployed prudently and competently into high return activities, then it is a logical use of cash.
LCM quotes a cumulative IRR of 78% and a cumulative ROIC of 135% over the past nine and a half years of operations.
But some of its peers have had similar metrics disputed in the past, with accusations of inflated revenue and profitability figures arising on partially completed contracts. Wherever you stand on this issue, the net present result is that these managers are cash hungry and tend to raise a lot of capital both from debt and equity holders.


Stockopedia’s algorithms struggle here: LCM qualifies for two short screens and is flagged up by our Earnings Manipulation Risk measure. This type of company requires more than your usual amount of due diligence into accounting policies and corporate governance.
For what it’s worth, LCM strikes me as more prudently managed than some others, with a cash-based accounting policy that recognises litigation at historical cost rather than on a fair value basis.
Today LCM announces its interim results for the half year ended 31 December 2020.
Financial highlights:
- Gross revenue down 68% to $7.7m, including the resolution of two single cases and two investments in acquisitions of claims strategy.
- Gross profit down 59% to $5m
- Adjusted loss before tax of $0.6m; statutory LBT of $1.2m
- Cash -83% to $5.8m
- Investments at cost up 108% to $71.4m
- Total capital invested up 21% to $22.3m
LCM accounts for revenue only when that revenue is earned or received. It’s interesting that a company feels the need to clarify this point but is indicative of the troubles the market has had in understanding these companies.
More specifically, LCM recognises revenue from contracts with customers once the performance obligation is satisfied and the transfer to the customer of the services has been satisfactorily completed.
Litigation service revenue is not recognised as revenue until the successful completion of the litigation project, which is generally once a judgement has been awarded or a settlement between the parties to the litigation has been agreed, and therefore when the outcome is considered highly probable.
The result of this is that the revenue line will appear lumpy. LCM is quite clearly taking a short term hit here, but what is more important is the general performance of investments over time and the maturity of the group’s portfolio of cases. On that point, the group’s cumulative IRR of 78% and a cumulative ROIC of 135% are notable.
LCM has a mature portfolio of investments, with 26 of its 40 investments more than 13 months old. Based on the group’s average case life of 27 months, investors might reasonably expect revenue to increase in the coming years.
Meanwhile, LCM is building scale. Its third party pool of capital was 64% committed by the end of December, and is now 70% committed. Applications are up and the group has entered into a $50m credit facility, which will be used to accelerate growth and provide access to larger investments.
The balance sheet shows a combined $26m asset of contract and portfolio costs in current assets and an additional $73m of contract costs in non-current assets. Together, these make up about 77% of total assets.
Those contract costs are estimated using a discounted cash flow model and uncertainty over their true value continues to be both an opportunity and a risk. Meanwhile, there’s a net cash outflow of some $35m.
Conclusion
Compared to its peers I have a favourable impression of LCM but still, the impressive growth in KPIs and optimistic management tone contrasts with the actual operating results.
The question is whether you believe the foundations continue to be built for growing future profits and cash flows.
Revenue is expected to be lumpy. Litigation finance involves a series of investments into disputes which historically take around 27 months to complete. Each case is different and it is tricky to anticipate the timing of completion.
And then LCM’s investments vary in size, further contributing to top line and net profit volatility. It’s true that in part this volatility is a consequence of LCM’s reasonably conservative accounting policies - but it is still a factor that prospective shareholders should consider.
Management says that investing in disputes is an ‘uncorrelated’ asset class, but I would suggest that LIT’s Covid-affected results have so far been highly correlated to global disruption.
Given the nature of lockdowns and their inevitable impact on court proceedings, that is perhaps understandable. I do take the point that litigation investment may have counter-cyclical properties, insofar as economic uncertainty or instability can lead to an increase in disputes.
It could therefore be that LIT stands to benefit from delayed Covid insolvencies, restructurings, and the rest.
On this point, LCM says it has seen a 68% increase in applications from corporates year-on-year. The CEO expects to see this come through in the form of new business in about 12-18 months and should then act as a tailwind ‘for many years thereafter’. Meanwhile the majority of LCM’s existing cases are approaching maturity.
A key variable is the deployment of cash into new litigation investments.

Source: company presentation
Assuming you are comfortable with this use of cash then the rest of today’s results shouldn’t be too much of a surprise given the scale of global disruption over the past year.
But the simple fact is this part of the market remains outside of my circle of competence. It’s a fast growing industry and LCM is generating some attractive KPIs - but for now I will leave this area to other investors that have more insight into the world of litigation financing.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

84 comments
Scs (LON:SCS) (no position)
Very new here and just getting started in direct investing. May someone please help me understand why the gross gearing of over 300% doesn’t appear to be mentioned as a bad thing? Thanks
Phenomenal write up on SCS!
I wouldn’t worry about a drop from 4.6 to 4.5 on a review site - if that were the figure, it seems like noise, within normal fluctuations.
Scs (LON:SCS) (no position)
Hi Paul
A few additional points to your commentary:
Note:
- £71m of Payables on its balance sheet (suppliers are paid at the end of the month after an order is received),
- £2.8m deferred rents expected to be paid in H2 (though the current lease liability on the balance sheet actually went up by +£4.0m so I'm confused why it's not this number, but I'll go with their lower £2.8m),
- £1.9m of deferred income tax on the balance sheet,
+ add back £4.5m Receivables
and the cash balance looks closer to £26.8m
(- £5.3m business rates relief would have brought this down to £21.5m, and then of course there was the £1.3m of job support that would have taken this down to £20.2m, but it's hard to take these off in such a "what if" scenario.)
Note that back in July 2020, when the accounts were as clean as they could possibly have been (no customer deposits and no suppliers to pay on the balance sheet), I predicted the true cash position to be closer to £16m (link here)
Still a good cash position, but sadly not as good as £97.8m.
NB1: The Variable/Semi-Variable/Fixed splits were as per their Annual Reports.
NB2: The covid benefit/support number is £8,633k and would need to be taken away from the £19,765k Operating Profit to get a more realistic profit number.
Nice breakdown abtan - I do something similar for stocks in which I have a perennial (not always financial) interest.
I am not at all up to date with SCS (LON:SCS) , but I'm puzzled by you 19/20 FY & H2 numbers for overheads. I'm guessing there must be something in the order of £10m covid relief in the 'other admin' line? Did they not itemise that?
Scs (LON:SCS)
Hi Gromley
Yes, there's a +£8,633k under admin costs (highlighted in red - that's my own annotation).
This was a balancing figure, but it didn't tally with the covid support number that they stated, I don't know why.
I checked all the other admin numbers and they were correct, so presumably something else is lumped in with this £8,633k, but that's a bit too much work for a company I don't hold and probably won't until the numbers are a little clearer.
Or I've made a mistake somewhere - happy to be corrected if anyone can spot it!
Cheers
A
Aha - thanks abtan, but I think you put it in the wrong column then?
Your 8,633 is in H1 21 (and superficially seemed to be in the right place, as there must have been some support in that Half).
But the FY20 (& H2) look like there is a missing cost offset?
Scs (LON:SCS)
Hi Gromley
I thought the same thing - where's the covid relief in FY20 H2?
I imagine it's bundled in with the 1,527 "other costs", which is a balancing number.
I must have forgotten to split it out of the FY results, or maybe it wasn't clear in the results. I'm not too sure, but I didn't really feel like going back to check.
The important thing about this exercise was to see how variable/semi-variable and fixed the other operating costs actually were. I'll be honest, I didn't really learn much from the numbers and I think that I just need to wait for the dust to settle.
Cheers
A
Fair enough abtan - thanks for the explanation - just don't send me any businesses cases as I'd always kick them back if there was an unexplained anomalous number.
(otoh DO send me business cases with an obvious anomalous number as once you've answer the question on that issue, I'll probably assume everything else is okay!)
Nope, never ever used that tactic, definitely not, how very dare you for suggesting such a thing. I am however led to believe that sometimes this happens, but you just have to know your target audience. Or so I'm told.
Duplicate post -deleted.
(If I can think of an interesting anecdote whilst edit is still available I will add it!)
Amazing analysis, tks!
Thanks abtan, good points on Scs (LON:SCS)
Although surplus cash is far higher than you indicate, because they don't have to pay off all creditors before they fall due, as your figures imply. The business model is such that ScS has negative working capital, therefore it should always have a lot of cash, on a rolling basis.
DFS shows how that cash can be removed, yet the business can still operate completely normally. That's why ScS would be so attractive to private equity. In practice, they could remove all the cash, put in a bit of gearing, and they've got the business for free.
See slide 10 - I think this is best way of looking at cash:
SCS (LON:SCS)
Abtan
"The company definitely does not have £97.8m of its own cash (sadly)."
Ignoring theis typo (actual figure being £91.8 mill not 97.8 per pauls original article ) I am with Paul here from a "technical description" despite your point being 100% valid and well presented - i would say the company most definately does have £91.8 mill of its own cash - to pretend the cash doesnt exist due to the fact there are payables is somewhat confusing the issue potentially for those less savy than yourself.
Note i agree with your comments ref what they owe out being important and these obligations should always be noted when mentioning cash to give the full picture. Particularly ref supplier credit - that may not be to easily available in future f the cash departs the buisness and also savy customers may be less likely to hand them cash as deposits.
Pauls main thrust to me though is 100% correct that this cash is unencumbered and could be used on what they see fit although there will be knock on considerations if it were ever to completely vanish.
Thinking about this form the flipside - we are always looking at "net cash" or "net debt" here really - sum of - if a company has £100 mill of net debt and oves suppliers £100 mill i am presuming you would not say net debt is £200 mill - if a company had nil net cash and owed suppliers £200 mill presumably you would not say it had £200 mill of debt - therefore if a company has £100 mill of cash and owes suppliers £300 mill we wouldnt say it was £200 million debt - the cash is there - exists and gives the company a measurable safety net of some sort (just not the solvency kind if thats all thats on the balance sheet)
I think we would all agree though the payables line on the balance sheet can be the silent killer with regard to business solvency genrally speaking - thankfully for scs holders thats not an issue "for now"
"if a company had nil net cash and owed suppliers £200 mill presumably you would not say it had £200 mill of debt"
Assuming that was the complete financial situation of the company, I certainly would say it had £200 mil of debt.
"therefore if a company has £100 mill of cash and owes suppliers £300 mill we wouldnt say it was £200 million debt"
Once again, I would personally say that company had £200 mil of net debt! Maybe I'm out of touch with modern financial lingo, but I see owing things as debt, whether it's to the bank or to suppliers.
More generally, companies that can manage negative working capital like this are great whilst they are expanding, but it's got to unwind in a contraction, you can't postpone paying suppliers for ever. Given that selling large ticket items direct to consumers has got to be pretty cyclical, then I wouldn't want to bet on no contraction.
Another record breaking day - bring out Roy Castle.
XLMedia (LON:XLM) looks like its testing a 50p breakthrough.
British American Tobacco (LON:BATS) has picked up (yesterday) +3% on scheduling a Dividend for May.
Plus500 (LON:PLUS) is up +4.5% on a relatively positive / sanguine trading update showing ok figures.
SCS (LON:SCS) turns around.
When is this turkey shoot / manna from heaven going to end?
A few people have mentioned Smart Metering Systems (LON:SMS) results today. FYI, there is a comprehensive note from Cenkos (available via Research Tree) with upgraded forecasts and a valuation 70%+ above the current share price. This is a fascinating company with a decent, inflation proofed dividend and a clear growth strategy. I hold and like SMS more than the typical infrastructure and renewable ITs because they are an operating company and more likely to grow my capital than dilute it to a standstill. For good measure, it has today broken into my top ten holdings and has excellent ESG credentials.
Cheers
Simon
Bango (LON:BGO) -> A much hyped and promoted stock (by mgt and punters that are suckers for promotional hype).
Absolute car crash results. Look at the numbers underneath the headlines. When the market works this out the price should come down a lot. I think BGO is at least 2/3s overvalued and if any problems out from 'messy' accounts it could b
A few questions for lovers/promoters of the stock:
1) How does Bango Marketplace actually work? Beyond just the buzz phrase of 'data monetisation'? IMO this is simple regulatory arbitrage. BGO do not employ a team of data scientist sorts, just your vanilla software engineers to bang together connections
2) new unexplained revenue...once you remove it the revenue from core activities look dreadful
3) operating CF includes discontinued ops which they don’t show in the RNS’s abbreviated results,
4) large software development intangible that I cannot understand where the cash was spend to create it in the year...it just seems like a piece of magic floating in the notes to the accounts unexplained in any meaningful way
5) Net profits aint the reported £4.7m as that includes £3.9m from disposal.
6) There's £2.9m of investment cash flow that is really opeational cost (£1.9m capitalised development and £1m to buy out the absolutely tiny remaining stake in Audiens before selling it to the Koreans for c.£5m....this £1m bought out a really tiny remainder of the company!!!0
Ra ra....ST loves it, moon shot, big data, data monetisation, the price is going up...
I'd suggest understanding what this business is if you've got risk on it
Bango by name and Bang & Go by nature
Mojo, I don’t have your ability to totally dismiss stocks I don’t understand fully (probably because if I did I wouldn’t have any left to invest in) but I have to say I totally agree here - I looked at and really wanted to invest in Bango (LON:BGO) a few weeks ago but after a very frustrating morning found myself unable to understand how they actually make money, therefore had to refuse the incredible opportunity they were offering me. Unlike you I’m fairly certain I’m going to regret my decision but hey ho...
A couple of people have corrected me technically on Twitter this morning re Bango (LON:BGO) - I'm not account expert. Nevertheless, it still leaves open questions re how they are accounting for things. And, yes, they seem to want to make their accounts difficult
I know Paul regularly states that the stellar performance of Boohoo (LON:BOO) should get a far higher rating. I came across the forecasts for Zelando the largest european online-only clothes retailer. In the 8 years up to Dec 22 its EPS is anticipated to increase by 162% and its PE would then come down to an eye watering 70.
Boohoo (LON:BOO) on the other hand during a similar 8 year period until Feb 23 is anticipated to increase its EPS by 1136% and its PE would then come down to a not very racy 23. And of course there does not appear to be allowance for the impact of its Debenhams and Arcadia purchases in the last couple of months in its forecasts.
I held Scs (LON:SCS) from c.150-220p (and nice fat divi) for few years. A decent rather than stellar investment. Well managed etc and operationally much higher quality than market gave them credit for. Had a brilliant growth strategy linked to House of Fraser outlets and expanding flooring offering and both ran in to trouble...HoF financial woes and SCS closed down with v little hit to earnings (well played mgt!) and flooring looks like it got hit by woes for CarpetRight as they had uneconomic competitor pricing going on (TBH I found the flooring slowdown a but inexplicable and unexplained...a little red flag).
But it wasn't the death and stutter of these growth avenues that pushed me. I hated that they bid for sofa.com. Fortunately the lost out to Mad Mike (Ashley). But IMO this signalled that ambitious expansion is the name of the game (sofa.com was cheap but it would have taken a lot of investment to make it viable and scaleable...in a market outside their core council-estate chic market)
SCS should be returning capital aggressively to shareholders through buyback and creating massive earnings appreciation through this. That they aren't doing this along with points above make me think that SCS mgt are in danger of wasting capital and creating value trap. They have carefully identified approx 30 site in UK that are optimal for one of their stores. Its a function of waiting for opportunity to open on desired retail park etc. That combined with buyback could make for really decent growth....but there's a danger they are going to go overly big!
I like the CFO and I was a little surprised that he wasn't the replacement for CEO. I know that some don't like that move...but as local Sunderland boy, with decent prior experience and an impressive knowledge/focus on biz operations at SCS (IMO based on speaking to him) I felt he would be right. I'm left with a niggling feeling that there may be some tension at senior/board level going on (this is speculative!) and I wondered if he'll be out the door soon?
Operationally much to admire but not when it comes to shareholder returns/capital
Scs (LON:SCS) - interesting comments, thanks.
There was a share buyback in 2019, of 2m shares I believe.
The new CEO is currently in handover period, so it will be interesting to see what he does next in terms of strategy. Maybe previous management were too cautious, having been scarred by the collapse in 2008?
Paul, I'm almost annoyed I don't own it....I want to...and if they announce a significant buy back (IMO they should target something like at least 5% pa for coming years....they could go more) then I'll be sick I don't...but my interaction has left me feeling like they want to expand.
Buy back means Scs (LON:SCS) re-rates mightily -> makes for a nailed on high growth company with chunky dividend
I wasn't too impressed with the new CEO at Mellow; I just got the impression he was a caretaker CEO until his retirement in the near future. A younger more dynamic CEO with a greater online vision would have seemed the obvious choice to me.
where can I find the webinar for Scs (LON:SCS) please?
Try this for the SCS webinar recording:
https://webcasting.brrmedia.co...
Rambler Metals And Mining (LON:RMM) (I hold)
definitely worth checking out this video
- and others on the channel if you are interested in basic materials...
Well, I wouldn't like to say checking this video was worthwhile, for myself it was like smoking sweepings from the shopfloor of a ropemakers. Ref my reply at 14.05 today to Bobnoyce00's query to Paul I feel quite exonerated and will hang my Rambler Metals And Mining (LON:RMM) shares on my wall like a headmasters cane to beat myself every time I think of doubling down on a dodgy miner that has never paid a divi nor kept its finger out. Full marks though to the Share Talk Presenter.
Massive thanks to Mr Scott and Stockopedia for getting myself and my Dad into SCS (LON:SCS) over the past 2 years.
I only have a small holding in SCS (after getting bored with it) but a 20% capital gain on the book gets my attention. Its a rare non-rollercoaster stock for me.
Its good to see SCS (LON:SCS) taking the moral high ground regarding Government support handouts.
I think your comments on SCs are very interesting . Do you have a view on why there is a substantial amount of DIrector selling?
Most of the selling in SCS (LON:SCS) is by Paul Daccus who has stood down, I did find this: "Sun European Partners has sold its remaining shares in ScS, 12 years after it bought the chain from administration.
It sold just under 10m shares at 220p, raising £21.67m.
As a result of the sale Paul Daccus, ScS non-executive director and Sun’s representative on the board has stepped down."
Also it qualifies for the Altman short selling screen. @Paul - can you give some insights on why pls.
Scs (LON:SCS)
Hi Paul, thank you for the great write-up of the SCS results. The only question in my mind is whether the pent up demand will be booked in H2 given the line in their results that:
"The temporary store closures during our key winter sale period (weeks 22 to 26), caused a decrease in order intake of 65.2%, resulting in a like-for-like* order intake decrease of 9.1% for the six-month period ended 23 January. This, coupled with the fact that all 100 stores are still temporarily closed, will impact our performance in the second half of the year. "
Hi Glorenfeld,
That's the big unknown isn't it, whether Scs (LON:SCS) (I hold) can rapidly recoup, and deliver the product, for the expected re-opening surge.
Normally H2 makes all the year's profit, which won't happen this year because H1 was so highly profitable for the reasons outlined above. Therefore, even a substantial drop in H2 profits vs last year, would still deliver an outstanding full year result.
It's complicated because the traditional seasonality has reversed this year due to lockdowns.
I think the overall tone in the RNS, and on the webinar, sounds pretty confident. But I agree with your implication that in the shorter term, there's a lot of uncertainty. I don't think that matters though, as I'm looking at this as a multi-year investment.
Buying now should lock in a lovely dividend yield in future too, over 5% by my calculations. I'm snapping up generous, and well-covered, sustainable future dividend yields, which are not showing up in the forecast figures yet, but can be easily estimated manually. I think that's a really good investing theme right now. ScS fits the bill for that, a bit like Headlam (LON:HEAD) (I hold) which we discussed recently here.
Regards, Paul.
Boohoo (LON:BOO)
“Somehow, though, it seems that Boohoo’s reputation has emerged from the scandal unscathed. Analysts at Berenberg, the German bank, noted that Boohoo’s Instagram following — a key metric for trendy businesses — has continued to grow despite the negative press, while there has been “no particular change” in purchase intent among 16- to 34-year-olds.
Michael Benedict, a retail analyst at Berenberg, said: “We think there are no particular signs that the negative publicity has resulted in a meaningful decline in brand sentiment among Boohoo’s addressable customer base.”
Via The Times via 1James1n1 on twitter.
https://www.thetimes.co.uk/art...
I hold.
My daughter is 16 & a regular Boohoo customer (I hold) - when I asked her opinion on the company she said "who are they?"
As far as she is concerned she is a Pretty Little Thing customer, she likes the clothes & the prices & has absolutely no interest in their corporate structure.
So any negative press on Boohoo will have no impact on her buying choices from PLT.
Interesting point.
To balance there is a 'Boohoo Man' as well as 'Pretty Little Things' on adjacent billboards so who owns them only PI nutters will know. Maybe they will have somewhere to show off soon. When down hit the marketing budget hard.
One area that seems to be moving up almost daily; the REIT's. Two old favorites on here Newriver Reit (LON:NRR) and Hammerson (LON:HMSO) Both have more than doubled since September. Big fan myself of the first as a recovery stock with all its pubs about to open and strong financial position. Recently bought a stake in a Sheffield centre JV at a bargain price. Waiting to see what the dividend will be.
Hi barnetpeter
Did you see Hammerson (LON:HMSO) are converting their Leicester Debenhams into 300 flats?
https://www.stockopedia.com/sh...
One to note for those who follow the retail landscape.
From the RNS ....... March 16 - Shopping centre operator Hammerson
HMSO.L said on Tuesday it has submitted plans to convert a
former Debenhams store into new homes for rent, amid a steep
fall in valuation of properties focused on the retail sector due
to the COVID-19 crisis.
Share up +16% today at time of writing.
I hold £MSO and Newriver Reit (LON:NRR) both being quite recent buys.
Regards
Howard
Like life, business finds a way. Debenhams 'occupied' a large block of listed building in Canterbury - fancy owning a 'Dickensian' style house opposite the Cathedral - bit busy but won't need a kitchen ever - or own the coffee shop below and live above. Or Browns of Chester. Had some cracking buildings in their day before sale and leaseback.
Scs (LON:SCS), I hold and have added more today. I can't be the only one that has spent more time than usual on the sofa in the last year; it was already tired but has got lumpier and grubbier as a result. When the shops open, a new one is needed. And I don't think I'll be alone in thinking like that.
yes, but with lockdown coming to an end soon and travel opening up, I can't see too many more people wanting to buy a sofa.
Hi Paul, if you have the time I would appreciate you having a look at LON:HWG. It has reported a 14.4% rise in operating profit and seems to have a solid balance sheet - but the stocko scores rates it red on value. This may be down to it having very lumpy results as a consequence of major property deals but I am not sure. It's northern based and into sheds and beds - so well positioned in IMO.
I hold - but more for historical reasons than out of conviction. Its colured amber (aka dither) in my portfolio and I need a nudge either way! All views welcome.
Too lumpy profits, majority dependent on land sales.
Agree its a good defensive NAV play if you get it at a discount or confident of increasing NAV yearly.
Morning Paul. You might be interested to listen to 2 minutes of a You Tube Video on Palisade Radio on 10 March by Rick Rule President and CEO of Sprott USA. He is a Mining veteran but he talks about how Advertising is far less effective compared to spending time and giving attention to Investors and educating them on the merits of the Company.
He is a brilliant communicator and its well worth a listen. Starts around 4 minutes in.
I really think in the last 12 months we have seen a sea change in how Companies engage with their Shareholders and you have been a shining light in drawing attention to the merits of doing so. The changes we are seeing are beneficial to all parties.
£LIT quoting an average ROIC of 135% is truly laughable. There is only a handful of companies in the world that generate those types of returns on invested capital. And if their numbers were true then they would be throwing off loads of cash. I can guess how this one will end.
Litigation Capital Management (LON:LIT) (I hold)
Hi Nebraska
I personally think IRR is far more important than ROIC.
After all a 135% gain is great but it's far more important to know if this is over 1 or 20 years.
The IRR of 78% is impressive though probably skewed by a few outliers and almost definitely historically smaller cases that conclude quicker than the current portfolio will.
Cheers
A
So where is all the cash then? An IRR of 78% implies they are more than doubling their money every two years. There is no cash coming back to support that. Or more likely, they have made that return on a tiny investment (a small number of claims that settled very quickly) and the rest of their investments aren’t generating anything like that return. I noted that Amanda Staveley’s laughable £600m claim against Barclays was supported by a litigation finance firm (who lost over £20m on that claim) which doesn’t look like an indicator of sensible investments being made in this industry. Buyer beware.
Litigation Capital Management (LON:LIT) and the IRR figure of 78%
"So where is all the cash then?" I believe you answered your own question correctly, Nebraska1977: "they have made that return on a tiny investment (a small number of claims that settled very quickly) and the rest of their investments aren’t generating anything like that return."
I would just modify the second part of the sentence - the rest of their investments have not yet come to a conclusion and we can't tell if they will generate the same return or not. I think the jury's still out on this. But I do like their cautious accounting policy, unlike (say) Manolete Partners (LON:MANO) which adjusts for the 'fair value' of claims.
I don't hold any of these firms, they are beyond my circle of competence.
Not looked closely at it, but I think also because they haven't yet achieved scale, so money from case wins not yet sufficient to cover operating expenses which have increased quite a lot (very expensive lawyers/litigation experts)
Litigation Capital Management (LON:LIT)
Hi Nebraska
I believe another subscriber answered the bulk of your question, but just to add one more thing - I personally wish that this company never has any cash sitting on its balance sheet.
Cheers
A
Here are my SCVR heat maps for today (prices as at ~9:00am).
I share these heatmaps with the intention of giving a visual indication of what is going on in the SCVR world: who’s reporting (and it's impact on the share price); and what’s moving more than 'normal'. There are no associated recommendations, implied or otherwise, just information. How, or indeed if, you choose to use that information is up to you.
Please read my heat map thread for keys to the heat maps contents, more (non-SCVR specific) heat maps, and an explanation of how I use heatmaps to guide me with my research.
Lot's of Big Movers today so looks like it's going to be an interesting day!
Small / Micro Caps reporting today:
Big movers today in the SCVR world (moving more than a 20d EMA of the ATR against either yesterdays close, or today's open):
Warm regards, stay safe, and best of luck!
greensiax
I hope Litigation Capital Management (LON:LIT) can perform. I sold out prior to today's results. Why? 1. No announcement of 2nd fund. 2. No announcements of deals closed. 3. H1 2020 was always going to be a hard result to follow (they did very well). Therefore, was not expecting exceptional results.
Intriguing to see, given the relative lacklustre performance, besides the recent pre-TU spike, the SP, so far, is on a rising trend...extremely bullish given the relative disappointing performance today as well as H2 2020. Goes to show the bullish market sentiment around!
What I really wanted to say was - car crash of a result today - what on earth is the SP doing at this level. Sorry to be frank!
Last time in Sept 20, when they disappointed - the share price was down 15% circa (Premier Miton selling off just before and during the TU did not help!) ,
Bango (LON:BGO) A good set of results this morning. But the market currently isn't doing much. It is a regular for Simon Thompson in the IC and I reckon it is likely to see another positive response from Simon on the back of these results. I hold.
Summary
·
Revenue and profit ahead of expectations and demonstrating strong growth.
·
New payment deals won in 2020 provide confidence for 2021 outlook.
·
Bango Marketplace adoption accelerating, enabling app developers to find paying users that drive more payment volume - the Bango virtuous circle.
·
Bango was certified as carbon neutral in 2020 with an ongoing commitment for continuous improvement.
FY2020 Financial Highlights
·
Revenue grew by 70% to £12.2M (2019: £7.2M)*.
·
End User Spend (EUS) increased to £1.9B, the sixth consecutive year of strong growth (2019: £1.1B).
·
Adjusted EBITDA** grew by 16x to £4.6M (2019: £0.3M)*.
·
Cash at 31 December 2020 was £5.8M (31 December 2019: £2.7M).
·
Net Profit was £4.7M (2019: loss £2.3M), including £3.9M profit from the creation of the JV with NHN.
·
Net Profit from continuing operations was £0.7M (2019: loss £2.2M) comprising:
o
£1.27M profit from the Bango Platform
o
£0.53M loss from the 40% share of the NewDeep JV
I'm going to play devil's advocate here and say that I wasn't impressed with the Bango (LON:BGO) results.
Yes, revenue grew by 70% to £12.2m but this included £2.78m of non-transactional payments from licencing of software, platform and technology services. Are these repeatable or one-offs?
The conversion of EUS of £1,852m into Revenue decreased by 14.81 bps to 50.70 bps (2019: 65.51 bps). I think this has been decreasing over the years perhaps through competitive pressures.
I also looked at the cash generated from operations (before Corporation Tax refund) after CAPEX and found this to be an outflow of £800k which is contrary to the headline Net Profit from continuing operations of £0.7m. There was a disposal of an operation during the year and this may be distorting the figures.
Overall, for a company that is valued at £164m, I would have expected a better bottom line result.
Liberum just announced a buy upgrade today, 260p price target. Seems analysts are taking the results positively though...
Morning Everyone,
Tremor International (LON:TRMR)
Tremor is considering a public offering of shares in the US. Is there any way we can ascertain the potential size being considered and where the shares might be coming from, existing or new?
Thanks.
Thanks Peter for flagging this. They have had one hell of a run. Is this good or bad for the share price. Guess that depends on the details.
Don't assume that just because Tremor International (LON:TRMR) shares might/will start to trade in the U.S. that will automatically be great news for the SP.
Just have a look at what's happened to the SP of Burford Capital (LON:BUR) since it started trading in NY on October 19 2020 (in case you can't be bothered - London price 778P on Oct 20 vs 613P as I write).
Discl - I hold both.
Morning Paul,
Would appreciate your views on Rambler (LON:RMM) if you have time please.
Cheers
Hi Bobnoyce00,
Sorry I don't cover the natural resources sector here, so won't be looking at Rambler Metals And Mining (LON:RMM) . Reasons being that there are too many companies for me to be able to write about on top of everything else, and I don't have any sector expertise.
Sorry about that, Paul.
As a newby coming up to my first First Day of Furlough (FDF) I have read vociferously and somewhat of an obsession - point - yes need to focus on the popular and quality few and not the reported many.
You can have my views on my experience with £RMM Bobnoyce, I would have thought that with the lucrative price of copper the firm would be running to the bank with cash. Alas, I bought at 3.989 pence in early my 2019 and last Friday its share price was 0.32 pence (I hate to look now). Doubling down has left me at 2 pence the share. You may well buy now and see the shares shine but Rambler Metals And Mining (LON:RMM) isn't for me.
Rambler Metals And Mining (LON:RMM) - Sorry to hear that Silver Moon. Yes previous investors completely and utterly shafted.
Now under new management (I believe the CEO involved in the turnaround of Shanti Gold) + super high copper prices , hopefully will lead to better results in 2021.
Bobnoyce - may i suggest - if you are seeking for futher information on RMM, you can search vox markets videos and podcast - where Alan Green + John Meyer discuss RMM in detail.
In addition, on the LSE BB, the resident experts on this stock on the RMM BB are dryan777 + Cornishknocker . These two investors have an indepth understanding of this company. If you go back to sometime around 15th December 2020 onwards, you will get a good picture of what is going on. Also, ignore the rampers. GL.
I bought at on average 0.41p during post Christmas time prior to recent placing which provided useful financing for the company's oeprations.
Computacenter (LON:CCC) have released a very strong final results statement this morning.
My morning smallcap tweet: FCA no friend of Amigo
Mountfield (LON:SPC) Amigo Holdings (LON:AMGO) Bion (LON:BION) Gulf Marine Services (LON:GMS) Inspiration Healthcare (LON:IHC) AFC Energy (LON:AFC) Pelatro (LON:PTRO), KRM22 (LON:KRM), Eagle Eye Solutions (LON:EYE)
U.K. SPAC (SPC) the new name for Mountfield. The most cynical move I've seen this year. [SP=NA Cap=NA]
Amigo (AMGO) FCA "extends the scope of its current investigation so that it can investigate whether Amigo appropriately handled complaints after 20 May 2020 and whether Amigo deployed sufficient resource to address complaints. [SP=13.7 Cap=65m]
Bion (BION) two of its four biogas power plants are now selling electricity to Malaysia's power co. Also opens UK office. [SP=2.41 Cap=10m]
Gulf Marine Services (GMS) announces "A New Dawn". Really! Banks agree new debt arrangements with its banks on significantly improved terms. Guides FY(Dec) underlying trading performance in-line with plan "with solid revenue progress and an improved margin". Yet adj EBITDA only $50-52m. This reduction, over previous guidance of $57-62m (previous guidance of $57-62m) due to reclassifying some costs as now non-exceptional. "The new Board has concluded that these costs are more appropriately treated as a normal cost of operations. They do not reflect any change in the underlying business performance." Outlook: 75% of the year's vessel utilisation secured (56%). [SP=5.98 Cap=21m]
Inspiration Healthcare (IHC) enhanced SLE 6000 machine and OxyGenie approved for use in Japan with initial order for c.£400k. [SP=113 Cap=77m]
AFC Energy (AFC) partners with the consultancy and construction business Mace to "develop long term UK and international deployment strategies that support a transition from highly pollutant diesel generators to zero emission hydrogen generators for construction sites." Companies will "identify multiple high-profile flagship sites for the deployment of AFC Energy's fuel cell system, on initial lease terms, to Mace construction sites." [SP=48.95 Cap=331m]
Pelatro (PTRO) wins orders for change requests total c.$400k for delivery this year. $6m orders for 2021 won in Q1. [SP=35.15 Cap=13m]
In line: KRM22 (LON:KRM) Eagle Eye Solutions (LON:EYE)
Litigation Capital Management (LON:LIT) Patrick Moloney, CEO gives an overview of H1 results, pupblished today. Scale is building across the business with strategic alliances with global law firms strengthening & market conditions increasing demand. LCM have a mature portfolio of investments, and is moving to a time when they'll mature into realisation. AUM increased 92%. The period has been affected by reolution delays due to CV19, which are expected to move to H2.
Video & Podcast.
Thanks Tamzin, well done, the Litigation Capital Management (LON:LIT) CE can talk a lot, so I was pleased with this short, sharp interview/presentation. Probably can be summarised as ‘jam tomorrow’ as revenue and profits have been delayed (against their usual timescales) by the impact of Covid.
On the one hand difficult to criticise as (unlike Burford Capital (LON:BUR)) they put nothing through the books as revenue or profits until they actually get it. On the other hand, unlike for example the recent Mello presentation of Rbg Holdings (LON:RBGP) there was no indication of the scale of likely returns and their timings.
That said I’m going to think about remaining in my smallish holding, as I’m curious to see how it works out. There is undoubtedly a lot of growth in this company; how profitable it is remains to be seen.
One thing I don't understand about this is that I'm sure Burford Capital (LON:BUR) and Manolete Partners (LON:MANO) are obliged to include unrealised profits under accounting rules?
So why don't Litigation Capital Management (LON:LIT) ??
Litigation Capital Management (LON:LIT) is an Australian business so different rules. https://www.lcmfinance.com/sha...
They were listed in Australia but moved to AIM in 2018.
Rbg Holdings (LON:RBGP) w.r.t litigation financing under Lionfish adopt same policy as Litigation Capital Management (LON:LIT) of recognising gains only when realized . So I suspect it is the company's internal decision which policy to adopt rather than specified by any FRS.
Volvere (LON:VLE) has issued a trading update this morning. I would welcome views.
Yes, would appreciate it if Jack could give an update on his thoughts about Volvere (LON:VLE)
Revenue has been impacted due to last of hospitality trading during the period but they have minimised losses and appear to be righting the ship at the newly purchased Indulgence division.
"The Group expects to report year-end consolidated net assets per share (excluding non-controlling interests) of approximately £13.29 and Group net assets of approximately £36.10 million.
Of the Group net assets, cash represented approximately £23.71 million". So 2/3 of net asset value sits in cash, following the placing last year.
It looks like they have struggled to find suitable opportunities to deploy cash from the placing as many companies continue to be propped up by banks and the government at present.
I would back them to be able to find good opportunities over the medium term.
Morning Paul,
Would appreciate you taking a look at Eagle Eye Solutions (LON:EYE) if you have time please.
Thank you.
Morning Paul, is £sms too big to be covered here?
Smart Metering Systems (LON:SMS)
Smart Metering Systems (LON:SMS) Looks too large at over £800m, rough limit is around £400m mcap I believe.
Paul - Shed a bit of light please on the TRMR note out today
This is, I believe, long planned, and a reaction to the management's frustration that their rating is well below that of their US peers. Only good news for holders.
Mr El-Erian in the FT this morning:
“Despite this, I believe it is still possible for investors to build higher confidence in their portfolios using careful bottom-up selection on individual securities. These securities should be screened for robustness in four areas: strength of balance sheets, positioning in the faster growing parts of the global landscape, a presence in sectors that are not vulnerable to lasting Covid-19 disruptions and solid management teams.”
I think most here would agree with that?
https://on.ft.com/3bRsI2s
SCS interims are a little surreal given events of the last year:
· Gross sales* increased 13.9% to £182.3m (2020: £160.1m)
· Revenue up 14.4% to £173.9m (2020: £152.0m)
· Gross profit increased 16.8% to £83.7m (2020: £71.7m)
· Gross margin improved to 45.9% (2020: 44.8%)
· Operating profit of £19.8m (2020: £1.2m)
· Profit before tax of £17.7m (2020: loss of £0.6m)
· Earnings per share of 37.5p (2020: loss of 1.4p)
· Government support of £6.6m (2020: £nil)
· Cash generated from operating activities of £24.0m (2020: £31.3m)
· Strong balance sheet with cash of £91.8m at 23 January 2021 (2020: £61.5m)
Re Scs (LON:SCS), very encouraging results, I'd agree, particularly since the comparator period was entirely pre covid.
But there was a note in there that shouldn't be overlooked:
"The temporary store closures during our key winter sale period (weeks 22 to 26), caused a decrease in order intake of 65.2%, resulting in a like-for-like* order intake decrease of 9.1% for the six-month period ended 23 January. This, coupled with the fact that all 100 stores are still temporarily closed, will impact our performance in the second half of the year. "
While the 2nd half results may well be good, there's a warning there that they may not be quite as sparkling as this half has proved.
Encouraging though, and I'm happy to have bought several times over the past 2 months