Small Cap Value Report (Tue 16 Nov 2021) - G4M, KINO, RBG, DOTD, IDHC, RTN

Good morning! It's Paul & Jack here with the SCVR for Tuesday. Today's report is now finished.
Mello - starting at 17:00 tonight, there is a free online event, on Investment Trusts & Funds. More details here. Also, we'd like to add our hearty congratulations to Mello's founder, David Stredder, who has won a lifetime achievement award at the recent Small Caps Awards. It's a very popular choice, as David has been a good friend to many of us over the last two decades, and has done more to connect private investors and small caps management, than anyone else I can think of. Well done David, and keep up the great work!
Agenda -
Paul's Section:
Gear4music Holdings (LON:G4M) (I hold) - Interim results are in line with expectations. However, there's a profit warning, due to Q3 (Oct-Dec 2021) sales being slower than expected, blamed on Brexit-related distribution problems. Recently opened new distribution centres in Spain & Ireland should resolve this problem in Q4, so doesn't look particularly worrisome. EBITDA guidance is reduced back to where it was back in June 2021, before a previous upgrade. Not a disaster, but clearly a setback.
Revolution Bars (LON:RBG) (I hold) - results for FY 06/2021 are as expected (awful, due to the pandemic). Current trading is still strong, although growth has moderated somewhat from the last reported number. Plenty of cash & facility headroom, means the company is now back in expansion mode, with 8 new sites, and many refurbs planned. I continue to believe this share is a good value opportunity, if you look forwards, rather than back.
Restaurant (LON:RTN) - a spectacular 19% rebound from a seemingly relentless downtrend in share price today. RTN says it's trading well, and gives us revised (upwards) EBITDA guidance for FY 12/2021, but I haven't been able to find out what the previous guidance was. With no broker updates available to us either, I can't take this any further.
Jack's Section:
Kinovo (LON:KINO) - positive update with revenue and profits up, and net debt down. This is an active turnaround, management is doing a good job, and there is further upside potential. But the historical performance has been patchy, the shares are illiquid, margins are typically low, and there are ongoing challenges around supply chain inflation and labour availability, so it's firmly in the higher risk bucket.
Dotdigital (LON:DOTD) - revenue up double digits but profit up by less. FinnCap is forecasting a declining trend in profit margins through to FY23, and the near-term growth forecasts don't appear to support the valuation in my view. Perhaps longer term there is a stronger case?
Integrated Diagnostics Holdings (LON:IDHC) - excellent Q3 results from this diagnostics services provider. The valuation is attractive considering the quality and growth profile, but I imagine its markets (most of its business is in Egypt) could keep it in the 'too difficult / risky' tray for some.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul’s Section
Gear4music Holdings (LON:G4M) (I hold)
800p (pre market open) - mkt cap £168m
Gear4music (Holdings) plc, ("Gear4music" or "the Group") (LSE: G4M), the largest UK based online retailer of musical instruments and music equipment, today announces its unaudited financial results for the six months ended 30 September 2021 ("the Period").
H1 numbers are in line with management expectations - i.e. well down on the exceptional figures last year, which were heavily boosted by lockdown 1. This is as expected, and brokers have for some time been forecasting a sharp reduction in profits this year, FY 03/2022, so no surprises there.
Profit warning for the full year - less pleasing is a shortfall in Q3 (Oct-Dec 2021) to date revenues. The problem is said to be Brexit-related supply chain problems - i.e. difficulty in despatching goods from the UK to the EU. This seems to be a temporary problem, caused by a slower than expected build up of the new distribution centres recently opened in Spain & Ireland.
The supply problems look very much temporary in nature, so I would imagine most shareholders are likely to look through this issue, with the company specifically reassuring -
… we are confident that the remaining Brexit related challenges will be resolved by FY22 Q4 and our European customer proposition will be significantly strengthened.
Guidance - is exceptionally clear -
… leading the Board to revise FY22 full year EBITDA guidance to not less than £12m (FY21 EBITDA: £18.9m, FY20: £7.8m)...
* Gear4music believes that consensus market expectations for the year ending 31 March 2022 (i) prior to release of this announcement are currently revenue of £156.6 million and EBITDA of £14 million; and (ii) before 22 June 2021 were revenues of £152.3 million and EBITDA of £11.5 million.
In other words, EBITDA guidance was raised on 22 June 2021 from £11.5m to £14.0m, but has now been reduced back down to £12.0m. That’s clearly a bit disappointing, but it’s not the end of the world, particularly as the solution (2 new distribution centres in the EU) is already underway.
Balance sheet - looks OK. Note that inventories have risen a lot, which the company says is deliberate, to stock up for peak trading period, underway now. Sounds sensible to me, given the known issues with freight coming in from the Far East.
My opinion - I’ve only quickly skimmed the figures, and have not yet seen any revised broker forecasts. Singers were forecasting 30.3p EPS for FY 3/2022, based on £14.2m EBITDA. So it looks as if a fall in forecast EPS to c.25p might be on the cards, given that the new guidance is £12.0m EBITDA.
EDIT: new forecasts have since come through, as follows:
Progressive: 21.5p this year, 29.4p next year
Singers: 18.6p this year, 29.8p next year - the analyst notes that this might be an excessive downgrade, and it doesn't yet factor in upside from the recent acquisition of AV.com, which is being relaunched, and widens the product range. So I think it's probably safe to assume the new forecasts could be overly pessimistic, time will tell.
End of edit.
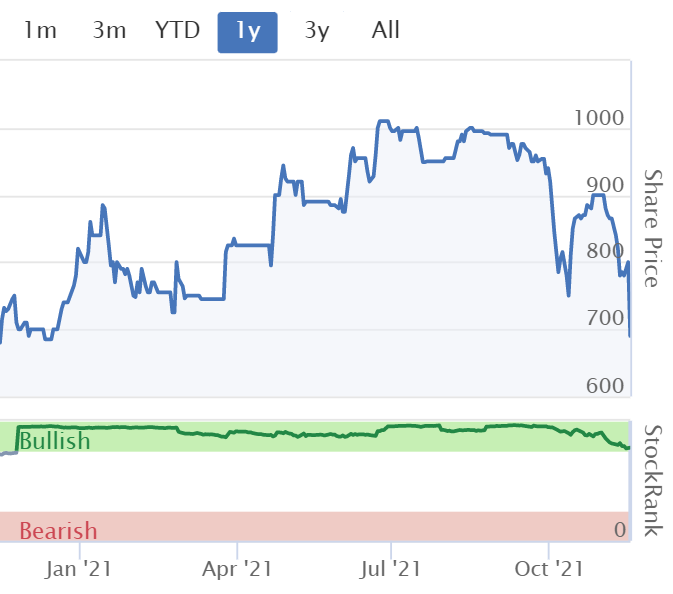
This is clearly a setback, but it’s only a temporary distribution issue that’s being fixed, so logically it shouldn’t do too much damage. Maybe a 10-15% drop in share price today? (written before the market opened). Although with a relatively illiquid share, you never know, because it only takes a few trades to move the price a lot.
.
.
Revolution Bars (LON:RBG)
25.75p (down 3.5% at 09:03) - mkt cap £59m
Revolution Bars Group plc (“the Group”), a leading UK operator of 67 premium bars, trading under the Revolution and Revolución de Cuba brands, today announces its preliminary results for the 53 weeks ended 3 July 2021.
Exciting return to normal trade following investment in all brands
It’s striking that FY 06/2021 was disrupted in some way, in all 53 weeks of the year. Hence these historic numbers are only of passing interest.
Revenues £39.4m (down 64% on FY 6/2020, which was itself impacted partially by lockdown 1 in Q4 (mar-Jun 2020)
Loss before tax of £(22.8)m
Losses were more than replenished by shareholders, in two equity fundraisings during the year, both at 20p, raising £34m net of fees. Horrible dilution occurred, taking the share count from 50m to 230m. Hence the business is well-financed now, with latest net cash reported as at 15 Nov 2021 of £4.6m
Balance sheet - this shows negative NTAV of £(25.2)m at 30 June 2021. However on closer inspection, this is caused by the IFRS 16 lease entries. These are -
Right of use assets: £64.0m
Current lease liabilities: £(5.1)m
Long-term lease liabilities: £(100.0)m
Overall IFRS 16 entries, net: £(41.1)m
I’ve queried this with the company, because a huge deficit on the lease entries doesn’t make sense to me, given that during the pandemic, the group did a CVA, to dispose of all the loss-making sites. Hence now the bars are trading profitably again (which they must be, given strong pre-pandemic like-for-like sales increases, and the strong cash generation evident in the elimination of year end (3 July) net debt of £3.6m, which has since (in 4 months + 2 weeks) turned into net cash of £4.6m), then there should now be no need for any deficit on the IFRS 16 entries.
My understanding is that when the balance sheet is next published for the half year, and assuming no further interruptions to trading from covid restrictions, then this big deficit on IFRS 16 entries should disappear.
For this reason, I’m going to delete the IFRS 16 entries altogether, as there is not a problem with lease liabilities, that issue has been dealt with via the CVA.
Adjusting NTAV to add back the £(41.1)m IFRS 16 entries, turns NTAV positive £15.9m, which is fine.
Current trading - like-for-like (LFL) revenues are reported at +14% versus pre-pandemic trading, since full re-opening on 19 July 2021, almost 4 months.
When last reported, LFL was +17%, so growth has slowed somewhat in the most recent 6 weeks.
I’ve put these numbers into a spreadsheet, to estimate what the slower growth rate is in the last 6 weeks, which comes out at +8.6% - still a very respectable number, but evidence that the pent-up demand is easing somewhat. That’s what I would expect, and we heard something similar from Nightcap (LON:NGHT) very recently, whose LFL growth had also moderated somewhat very recently.
Broker forecasts - seem ludicrously low to me. I queried this last time, and was told that the company doesn’t want to over-promise, so they’re keeping the forecasts low, especially because of uncertainty over possible covid restrictions over the winter, and uncertainty over corporate Christmas parties, which are widely expected to be smaller, if they happen at all, and often booked at the last minute.
In my opinion, and assuming no covid restrictions, then the upside case is that RBG could thrash the existing forecast. You can work that out yourself, given that LFLs are +14% on pre-pandemic numbers, for a third of the new financial year. That should mean it’s way ahead of forecasts already.
Finncap's note today hints at upgrades to come, but says it would not even consider revising up the forecasts before peak trading in Xmas/NYE is in the bag.
I would much prefer if brokers would give a range of scenarios in this type of situation - upside case, middle case, and downside case.
Instead they just leave super-cautious numbers out there. Hence why very often, broker consensus numbers need to be taken with a pinch of salt, as profit is a geared number, so no matter how good the analyst, they’re often wildly out from reality. Especially at a high gross margin business like RBG, where each extra drink sold is c.75% gross profit.
New formats - the company reminds us that its existing 2 brands are highly cash generative when allowed to trade without restrictions. For investors who feel the brands are tired, then there’s potential further growth from 2 new brands.
Founders & Co - has recently been launched by RBG, in a trial site in Swansea - see its website here. It looks an interesting hybrid concept, to generate more business (from coffee shop, artisanal traders, etc) throughout the day, rather than having empty sites during the day, then being rammed at peak times -
We have also been very proud of the launch of our third brand, Founders & Co. The new venture, in Swansea, has been performing well so far and receiving positive guest feedback. We are building a great business in partnership with our Founders, the food traders we collaborate with, and continue to offer a variety of events and reasons for our guests to keep returning. The test site for our fourth brand will open in November 2021, offering a competitive socialising experience, and we couldn't be more excited to see our guests reaction to this new offering.
Refurbs & new sites - RBG is back on a growth trajectory. 8 new sites are planned. Mgt has previously said it is targeting larger sites that will move the dial, not marginal locations in small towns.
3 sites have been refurbished already this new financial year, and I believe many more are to be refurbished in early calendar 2022. The company now has plenty of cash & bank facility headroom, and with less competition, this is an ideal time to be expanding again.
That should drive upgrades to earnings, and a higher PER multiple, in due course, as investor perceptions about the business gradually improve - admittedly a process which takes time, given all the problems of the last 4-5 years.
The fundamental, underlying problem with RBG, was that too many sites had been allowed (by previous management) to become tatty. That drove sales down, with an operationally geared impact on the bottom line. This issue should finally be fixed in 2022.
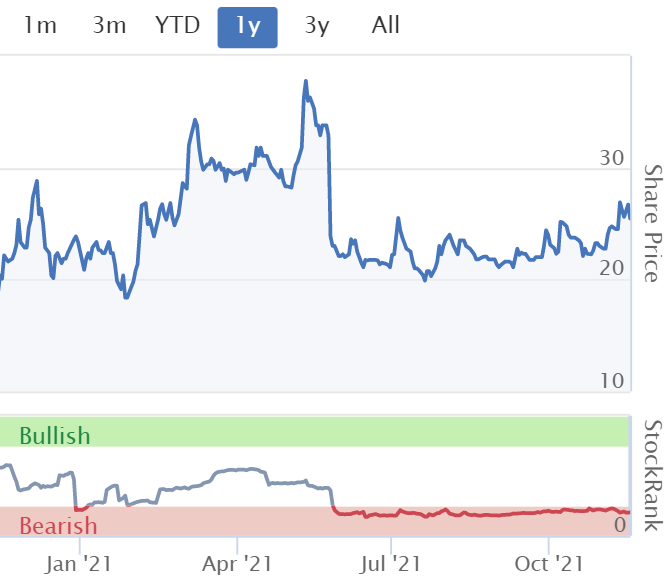
My opinion - it’s working out well now. I think we’re lined up for a substantial earnings beat, if peak trading over the Christmas holidays does well. The main risk is reimposed covid restrictions, so each investor can weigh up for ourselves how much emphasis we want to put on that.
There’s a lot of value here, at only £59m market cap, and all the historic problems fixed, or soon to be fixed.
Refurbishing the rest of the sites in 2022 should generate decent further sales growth, which at high gross margins, could transform the bottom line. Time will tell!
Plus the company now has plenty of funding to open new sites, and potentially roll out its 2 new formats as well, plus there's scope to make some bolt-on acquisitions too.
I talk to management every 6 months, and find them operationally strong, hands-on managers, with ambitions to fix, and grow the group.
.
Restaurant (LON:RTN)
94.7p (up 19%, at 12:42) - mkt cap £722m
The Restaurant Group is a significant player in the UK casual dining market with over 650 restaurants and pub restaurants. Its principal trading brands are wagamama, Frankie & Benny’s, Chiquito and Brunning & Price.
It also operates a highly diverse multi-brand Concessions business which trades principally in UK airports. In addition, the Wagamama business has five restaurants in the US and over 50 franchise restaurants operating across a number of territories.
(taken from the about us section of its website)
There’s plenty to like about this business, in particular some good brands, and the weaker brands were restructured during the pandemic. Of less appeal is the weak, overly indebted balance sheet. Also, I think it became significantly overvalued in the everything rally, but has corrected sharply in recent weeks (like many other shares).
Then today we get a huge +19% rebound on a positive trading update. This market is behaving very strangely at the moment, with investors seemingly unsure how to price many shares.

It’s trading well, but no mention is made of how much the reduced VAT and business rates relief has contributed to this performance. This relates to FY 12/2021 -
Since TRG last updated the market on 15 September 2021, The Group has traded well with like-for-like sales* out-performance versus the market** across our Wagamama, Pubs and Leisure businesses. We have also seen a minor improvement in UK airport passenger volumes leading to a partial recovery in the sales run rates in our Concessions business.
Revised guidance -
As a result, management's expectations for the Group's FY21 Adjusted EBITDA are today increased to a range of £73m-£79m (on an IAS 17 basis), subject to no unexpected Covid related disruptions being announced before the end of the financial year.
Unfortunately I cannot see a footnote to explain what the previous guidance was. I’ve just had to waste about 15 minutes trying to find the previous guidance in the interim results, but there doesn’t seem to be a comparable EBITDA guidance figure in that report.
Also, there are no recent broker notes on Research Tree.
This is such basic stuff, it’s not difficult to get right, e.g. Gear4music Holdings (LON:G4M) gave us crystal clear guidance this morning - this is what we previously expected EBITDA to be, and here is the revised number. Why couldn’t RTN have done the same?
Net debt - was £200.3m at the half year (too high, in my opinion), and is now expected to be £190m at the year end. A modest reduction. The problem is that RTN’s debt load is quite expensive to service, so finance charges eat into EBITDA a fair bit.
My opinion - neutral, because I don’t have access to any broker notes and would need to see the full numbers to assess this share.
On the positive side, EBITDA guidance has been raised (we’re not told how much), and net debt is expected to move down a little.
RTN says it’s beating the market, which is also positive, based on industry data, as explained in a footnote today.
It seems to me there should be read-across to TGI’s, owned by Hostmore (LON:MORE) (I hold), which of course hasn’t budged today, in its seemingly relentless downtrend since the botched demerger - I say botched, because Numis has clearly completely failed to drum up buying interest. So it could take some time for the shareholder base at MORE to be restructured via market forces. I only mention that here because some members were discussing it here last night in yesterdays report.
Jack’s section
Kinovo (LON:KINO)
Share price: 51.44p (+2.88%)
Shares in issue: 62,137,757
Market cap: £32m
Kinovo is a UK provider of specialist property services centred on safety and regulatory compliance, home and community regeneration and sustainable living through the installation of efficient and greener energy alternatives.
It’s focused on Regulation, regeneration, and renewables and is currently in turnaround mode. The direction of travel here is positive but the share price has also rerated, so the risk/reward is beginning to shift from immediate financial recovery to sustainable growth prospects.
Kinovo has continued to demonstrate resilient progress, delivering strong growth in revenues as COVID restrictions eased, earnings and cash generation from its continuing operations, despite the market challenges of supply chain inflation and material and labour availability.
In the six months to 30 September 2021, revenue from continuing operations has increased by 64% to £23.8m, with adjusted EBITDA growing 75% to £1.8m and operating profit up from a loss of £0.2m to £1.2m. Total profit after tax was £0.6m, up from a loss of £0.2m.
Kinovo has won a number of new contracts, most of which will be initiated in H2, ‘with a total potential value of £43.6m over the life of the contracts’.
The group also announces the likely sale of its Construction Division:
Following its rebranding and strategic review, Kinovo announces that it is currently in advanced discussions regarding the planned sale of DCB Kent Limited (DCB), the Company's non-core construction business. The disposal of DCB will allow the Company to harmonise its operations and increase the focus on its three strategic workflow pillars; Regulation, Regeneration and Renewables. These pillars are centred on compliance driven, regulatory led specialist services that offer long-term contracts, recurring revenue streams and strong cash generation. There can be no certainty that the sale will proceed, however further announcements will be made as appropriate.
Balance sheet - Net debt has reduced from £2.7m to £1.7m and the cash balance has increased from £1.3m back in March to £2.2m. The final dividend has been reinstated (£0.3m) and the group has also repaid £0.6m of deferred VAT.
Diary date - interim results for the period ended 30 September 2021 to be released on Tuesday 7th December 2021.
Conclusion
These look like encouraging results for a small company actively turning around. The share price has rerated in the days leading up to this announcement.

It’s a small, illiquid stock, so smaller trades can push the share price one way or the other. It also makes the company hard to get out of if anything goes wrong, which further adds to the risk here. There is upside potential remaining, but whether or not to get involved here depends on your risk profile.
Kinovo generates quite a lot of revenue - it’s still only trading on around 0.5x sales - but this can be lumpy, with the potential for setbacks, which exacerbates the liquidity risk. It’s also a low margin business, so any worsening in supply chain inflation and material and labour availability could also become a problem.

On the flip side, there’s an opportunity to improve profits, as well as take further market share here. And management does appear to be executing on the turnaround.
From these levels though, the investment case moves from immediate financial recovery to the group’s ability to meaningfully grow revenues and profits. The ‘non-discretionary’ aspect of Kinovo’s core business lines is a key part of the investment case. Disruption over Covid led to delays rather than permanently lost business as a lot of the services Kinovo provides are requirements for its property clients.
The potential sale of DCB will hopefully bring some more cash in and allow the group to focus on its core business. I can’t see any valuation attached to DCB, but perhaps it will be enough to move Kinovo into net cash, which would be a positive step.
The upside has reduced after the recent rerating and this does remain a risky investment due to the lack of liquidity in the shares and the volatility in the historical results. That said, the market cap remains small, management is executing a successful turnaround, and Kinovo is exposed to some promising structural growth trends, so there’s every chance the company can realise the growth it needs in order to drive further share price gains.
The current trading momentum is certainly in the group’s favour and I can see the appeal for more risk tolerant investors. I am positive on the prospects and what management has achieved so far, but there are also important risks to consider like the lack of liquidity and the possibility of inflationary pressures impacting margins.
Dotdigital (LON:DOTD)
Share price: 228p (-8.8%)
Shares in issue: 298,118,630
Market cap: £679.7m
Dotdigital connects marketers with customers through an automation platform that ‘unifies all digital channels’. This enables marketing teams to launch highly targeted and relevant campaigns at every touchpoint (with a particular strength in emails), resulting in faster and more effective marketing campaigns ‘with increased engagement and demonstrable ROI’.
There’s been an extremely strong post-Covid rally here, taking the shares firmly into all-time high territory. Market sentiment has moved on from the ‘everything rally’, however, and investors appear to be a lot more risk-aware at the moment, so companies with premium valuations and a lot of growth priced in are at risk of derating in my opinion.

Such sentiment swings can end up being minor fluctuations in the longer term growth trajectory for successful software companies of course, but they can still be psychologically painful, so worth preparing for! DotDigital does have its fair share of bulls who see a long term investment case.
Final results
As we enter the new year, trading remains strong. Our healthy balance sheet, strong recurring revenues and cash generation provides the flexibility to invest in our growth strategy, giving the Board confidence in the Group's long-term prospects.
Highlights:
- Organic revenue growth of 23% to £58.1m, recurring revenue up from 91% to 93%, and monthly average revenue per customer (ARPC) up 16% to £1,251,
- Adjusted EBITDA up 9% to £19.8m,
- Adjusted operating profit up 5% to £13.7m,
- Adjusted EPS up from 3.9p to 4.06p,
- Net cash up from £25.4m to £32m,
- Final dividend up from 0.83p to 0.86p.
The profit growth on display here is not tallying with the premium valuation in my view. The opposite of operational gearing seems to be in effect, with 23% revenue growth but just a 5% increase in adjusted operating profit, while adjusted earnings per share is up by 4.1%. The final dividend increase of +3.6% again seems rather meagre for a company valued at 56x FY22 earnings.
The forecast rolling PEG is some 17.2x, so understanding where the growth is going to come from is essential at these levels. Perhaps Covid disruption has obscured the underlying growth potential for now.
The decline in overall group gross margin comes from the growth of premium messaging channels such as SMS. Cost of sales has increased from 8.2% of revenue to 17.8% of revenue.
At the EPS level, there’s also a higher effective tax rate of 8%, (FY20: 5%). This results from R&D tax credits. I wonder how long companies can enjoy this kind of credit? Presumably, we can’t assume an 8% tax rate in perpetuity but then again, I’m not sure when rates would normalise either.
In fact, when you look at the actual income statement rather than the headline results, we see that EPS from all operations actually fell, from 3.9p to 3.76p (adjusted diluted). Not much information is provided on the nature of these discontinued operations in this particular update. It is actually the Dynmark/Donky part of Compai, acquired in 2017.
I note HHR’s comment below, which warrants further investigation. A cursory search does suggest the discontinued Dynmark business specialises in the type of SMS messaging that is currently a growing part of DotDigital’s revenue mix.
Cash generation was good - net CFO of just under £17m and free cash flow of around £10m, meaning strong cash conversion. The balance sheet is also fine, with no debt and cash growing from £25.4m to £32m (comfortably covering current liabilities of £10.4m). Around 34% of group total assets is intangibles and goodwill, which seems reasonable for a software company.
One of the group’s ‘Three Growth Pillars’ is international diversification.
- EMEA revenue increased by 23% to £44.6m,
- North America revenue was +19% to $12.5m and ‘presents the largest market opportunity for the group’, and
- APACrevenue grew by 47% to A$7.7m.
M&A - the board continues to evaluate the market for complementary acquisitions and its acquisition strategy is focused on: synergy technology for new revenue streams; bolt-on functionality to accelerate platform development, new talent acquisition and the expansion of expertise, and extension of the customer base in strategic territories.
Outlook -
High level of confidence in delivery of management expectations for the new financial year following a strong start…
As we enter the new year, we do so within a more normalised trading environment as our end markets transition out of the immediate implications from the pandemic. Trading remains in line with management expectation and our technology platform is uniquely positioned to capture the transition to online marketing across the mid-tier enterprise space. Whilst we remain mindful of the wider economic uncertainty, our healthy balance sheet, strong recurring revenues and cash generation provides the flexibility to invest in our growth strategy. The Board is therefore confident in the Group's long-term growth prospects.
Conclusion
FY22 targets seem quite undemanding, factoring in revenue growth of 11.3% and normalised EPS growth of 3.8%. I would expect most companies valued at more than 14x revenue and 61.8x forecast earnings to grow EPS by multiples of 3.8%. FY23 estimates are for revenue of £75m and adjusted EPS of 4.4p.
I wonder why this trend of double digit revenue growth translating into much lower profit growth is expected to continue. FinnCap expects the adjusted profit margin to fall from 27.4% in FY20 and 23.4% in FY21 to 21.7% in FY22 and then 20.7% in FY23.
Currently, there’s a shift towards more SMS messaging which is impacting margins. Perhaps this is the sole reason. If so, forecasts imply this trend is expected to stay for at least the next 18 months or so.
The company definitely has good Quality characteristics. A Quality Rank of 99, a strong and improving net cash position, no debt, 93% recurring revenue, and reliable cash generation. But I would need more from this update in order to get interested at the current valuation.
DotDigital has done tremendously well as an investment recently and it keeps clocking up double-digit revenue growth, so it must be doing something right. I don’t have any great insight into its ‘uniquely positioned technology platform’ and that’s the key to understanding if it’s worth such a premium.
I currently have more questions than answers though and I just can’t get comfortable with the valuation for now. Even after FinnCap ups its price target by 10% to 275p today, that still just reflects the price shares were trading at a couple of weeks ago.

Perhaps holders can present the counter-argument? It’s a growing market, and perhaps DotDigital’s platform is just miles ahead of the pack meaning long term and material growth is more or less guaranteed. That’s what I would be assuming if I held the shares anyway.
Integrated Diagnostics Holdings (LON:IDHC)
Share price: $1.27 (+1.75%)
Shares in issue: 600,000,000
Market cap: £568.7m
IDHC has fantastic quality metrics and consistently high Ranks - it’s rare to find this mix of quality, growth, income, and valuation.

But it is headquartered in Egypt, where it generates the vast majority of its business. This is not regarded as a stable jurisdiction and it’s possible that no amount of international accreditation or years of profitable growth can fully dispel such concerns for some investors.
The Group's year-to-date performance was supported by a record-breaking third quarter
Highlights:
- Revenue +126% to EGP 3,767m,
- Gross profit +161% to EGP 2,167m; gross profit up 7.8 per cent,
- Net profit +206% to EGP 1,148m; profit margin up 8%,
The number of branches has increased by 36 to 507. Patients increased by 56% to more than 7m and revenue per patient improved by 44% to EGP 504, while revenue per test grew by 70% to EGP 151.
Results are helped by both Covid-related testing and conventional test portfolios. Controlling for Covid-related tests, revenue increased 30% year-on-year for the nine-month period. Core Covid-19 tests made up 42% of consolidated revenue, while other Covid-19-related tests made a 9% contribution to consolidated revenue for the nine-month period.
So near enough a 50:50 split, with the trends nicely balanced: while normal testing was shut down, Covid testing boomed; as Covid testing recedes, normal testing picks back up.
In Q3 2021, IDH outperformed its already impressive results from the first and second quarters of this year to deliver quarter-on-quarter revenue growth of 27% and year-on-year revenue growth of 105%.
Egypt generated revenue of EGP 3,122 million (82.9% of group revenue), up 122% as both patient and test volumes posted solid year-on-year expansions for the period. Revenue growth came from both Covid-19-related and conventional tests, and was further bolstered by the group's house call service.
Controlling for Covid-19-related contributions in 9M 2021, revenue increased 30% year-on-year driven by a 21% increase in conventional tests performed versus last year.
Jordan revenue expanded 172% year-on-year to EGP 592m (15.7% of revenue). Top-line growth was driven by an 81% increase in test performed, coupled with a 50% rise in Biolab's average revenue per test.
Revenue increased 35% year-on-year ex-Covid tests on the back of a 32% increase in conventional tests performed. Biolab's house call service generated EGP 45 million in revenue, up 81% year-on-year.
Nigeria revenue was EGP 40m in 9M 2021, up 62% year-on-year (1.1% of group revenue). On a quarterly basis, IDH's Nigeria operations reported revenues of EGP 14.9 million in Q3 2021, up 54% year-on-year and 16% versus Q2 2021.
Sudan revenue fell 41% to EGP 12 million (0.3% of group revenue) due to the devaluation of the Sudanese pound in early 2021. Revenue in local currency terms increased by 169%. This represents a small proportion of group results but will still do little to counter the general market wariness.
Re. Sudan:
Moreover, we are continuing to monitor the mounting political and social unrest across the country, and our management team on the ground is well-prepared to take the necessary measures to protect our patients, staff, and operations.
Commenting on the group's performance, IDH Chief Executive Officer Dr. Hend El-Sherbini said:
During the third quarter of 2021, we successfully built on an already remarkable first half of the year to report our highest ever revenue and net profit figures for a single quarter. More specifically, during Q3 2021 we recorded top- and bottom-line quarter-on-quarter growth of 27% and 47%, respectively, an outstanding performance which was supported by growing demand across our entire offering.
Guidance - on track to deliver record high revenues of around EGP 4.9 billion in FY 2021 (representing year-on-year growth above the 80% mark) with a normalised EBITDA margin in the 50% range.
Conclusion
These are notably strong results but I imagine the discount will remain, as this kind of jurisdictional risk is simply a line in the sand for many investors. But, then again, share prices fundamentally track earnings growth so if the company executes and there is no external disruption then at some point, the stock should rerate more meaningfully.
There was a potentially concerning development recently with the group abruptly changing auditors, but I see an impressive level of detail and commentary here for a Q3 results update. It’s still neglected by institutions, but Fidelity, T. Rowe Price, and Norges Bank have been building their stakes.

All in all, the story remains the same: great financial results and attractive growth opportunities, but concerns about country and currency risks.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

63 comments
RE : Integrated Diagnostics Holdings (LON:IDHC) the revenue growth since 2016 does need to be adjusted downwards for EGP currency devaluation but the growth is still impressive even after factoring this in. The company is able to maintain and increase profit margins in the very high inflation environment of the Egyptian economy. I think the EGP reporting puts some investors off as they can’t be bothered with the conversion to USD or GBP.
Yes it's a business with an excellent management team and large runway in front of it. Great company but, so far, poor stock. I'd also be concerned about the unwinding of the Covid boost that is forecast for next year - est. revenues -20% - although this isn't the only stock for which you could make that observation, eg our own Sdi (LON:SDI), which I've trimmed for that reason.
Integrated Diagnostics Holdings (LON:IDHC) is one of my favourite and largest holdings alongside Airtel Africa (LON:AAF) . I would buy more london listed companies operating in Africa as the growth potential and valuations are more favorable than in most developing and emerging markets. Both companies pay decent divis but I would rather they reinvest these to grow their businesses and profits faster still.
For me, the issue with Integrated Diagnostics Holdings (LON:IDHC) is the poor performance of the stock relative to the first class fundamentals. I'm not completely averse and have owned profitably in the past. But It's flat since the start of 2016 and actually down since listing, all on relentless multiple compression. I guess that has to end some time but the fact is there are midcaps in the same field with equally great operating numbers in the US (eg Medpace) and even UK (eg Ergomed (LON:ERGO)) with relentlessly higher growth that have made much better investments without having to worry about war and political regime change - Capitol Hill riot aside.
Yes a very good point, l have held Ergomed (LON:ERGO) and it has done very well in the last 2 years. I do hold some shares in Airtel Africa (LON:AAF), I think there is a lot of protection but as you say some risk in Africa, there are major issues in some African countries such as Ethiopia, Nigeria it’s largest earner also has some on going issues. I don’t know Integrated Diagnostics Holdings (LON:IDHC), Egypt puts me off.
Hi everyone ,
It is crystal clear that many of the recommendations or opinions that have been expressed here are close to their stop loss price.
Regards
What recommendations?
What is a stop loss price?
Re: Dotdigital (LON:DOTD) The company's largest competitors are Twilio in US and Sinch in Europe. Both fell hard (20%-30%) on recent earnings so I wouldn't read too much into the fact that DotDigital has sold off as well. The falling margin story is going to stay with us (I'm an investor in all three) since the the other two, much larger and stronger in SMS, have considerably lower gross margins of 52% and 29%. But cashflows are good and that gives comfort and optionality.
These cPaaS companies are riding a huge wave of secular global growth in message-based customer comms and my personal view is that you stay on the bus for the long term. In fact, I topped up Twilio, by far the largest and least profitable of the three, on its big fall. I'd top up DotDigital here if the position hadn't already grown to one of my largest, even after today's haircut.
Tremor International (LON:TRMR) Just FYI I am told by IR the question around shareholder sales will be addressed at the IMC meeting at 2:30pm as I know several of you are interested in the rationale.
Re £RGB (I hold) Assuming that Covid does not cause closures - nightclub bars are the most exposed sector in hospitality - I am greatly encouraged by these results on the existing brands. They confirm that Covid has not altered the desire of (at least a big segment) of the young to go go out and party and that they feel rich/confident enough to spend on doing so. I was a bit worried low/no alcohol trends and As a shareholder, dilution is done, finances now secure and I am happy with (what's left of) my original investment!
However, what does worry me a bit is trialling 2 new brands. I'd much rather they seize the moment (and use the cash available) to expand the existing proven concepts whilst competition is down. Trials if done well, take a lot of Snr Mgt time and focus. There is still a lot going on. I like what Mgt have done but its a small team.
I think over analysing the numbers right now is pointless - it was survival, now it is stabilising and growing. Another 6-12months at the earliest before the dust really settles.
Revolution Bars (LON:RBG) (I hold)
Hi Zipmanpeter
I'm actually quite impressed by the idea of 2 new brands.
I'm not sure the 2 chosen ideas will actually work (not my sort of thing), but when I see the high gross margins of niche hospitality retailers (eg Escape Hunt (LON:ESC) and Hollywood Bowl (LON:BOWL) - no position in either) or the popularity of speciality evening venues (eg https://www.bouncepingpong.com...) I'm quite intrigued where this might lead.
And if there was ever a time to try something new, then now seems like a good time - rents are low and a desire to go out is seemingly still quite high.
One would hope that these new brands are supported by short leases, in case the new concepts don't work out, but in any case the main bars are so cash generative (my perspective now as well as pre-covid) that small risks every now and then are worth taking.
---
As for today's results, I remain a reasonably happy holder.
It looks like the company might have been previously including their dilapidation provision within debt, as I can't see anything else on the balance sheet that could explain the difference. It's a minor point, but I'm put off by a simple number not being communicated clearly.
But other than that, the future looks okay for now.
Cheers
A
Revolution Bars (LON:RBG)
Abtan
Some numbers have confused me, such as the year end net debt figure, which seems to have changed since the July TU: £5.0 (then) vs £3.6m (now).
The £5 mill figure previously notified had a c infront (circa) to indicate it was rough and ready - as one would expect 1 day after period end.
Revolution Bars (LON:RBG)
Hi rmillaree
Yes, I saw the 'circa' on the £5m, which would have been fine if it was within £0.1m-£0.2m of the final figure, not off by £1.4m (c.28%.)
A company cash/debt balance is really something every CFO should be able to access instantly.
And given that the company only makes about 5 RNS announcements a year, it's really something that they should communicate well.
But I'm being picky. I'm sure there's a reasonable explanation. I'm not angry...just disappointed.
A
Revolution Bars (LON:RBG)
https://www.lancasterguardian....
There is a general discussion post for Tremor International (LON:TRMR)
You may want to post there.
Georgia Capital (LON:CGEO) Q3 results. NAV is now £14.35 and you can buy it for £6.40 so its trading at 45p in the £1
good growing revenues in stable businesses, nothing flashy (ie Banks, Healthcare, Breweries) with a good chunk of the NAV in listed Bank Of Georgia (LON:BGEO) : looks like it makes up somewhere around 300p.
so you can buy £11 worth of decent quality private equity for £3.5.....hmm that's gotta be wrong
made me look...
Looking at the black sea as a clock, the ukraine is 9-12 Russia is 12-3 and georgia is 3-4.
Georgia has its own issues with russia as well, so there is some geo risk
Where is the FCF?
The bank of Georgia has a divi of ~7%, where is the yield on $CGEO ? - esp if a chunk of the assets pay a divi
Reminds me of Stanley Gibbons - 100m+ of stamps on the books as valued by SG, and this supported the value of the Co, until it did not.
If you believe the valuations and expect the area to become more stable, this is a massive bargain, but, there are (a literal army of) reasons to stop and think v. carefully first.
The geo risk I agree deserves a discount but not the level to which we currently see.
Arguing it reminds you of Stanley Gibbons is a bit bizarre. Stamps are a collectible, prone to wild swings in value whereas mMost of Georgia Capital (LON:CGEO) is made up of Georgias largest Bank, largest private healthcare provider, largest retail pharmacy, Water Utility, Insurance and some renewables. These are easy assets to assess. Less than 10% of NAV is made up of private investment in small companies that are less easy to assess a realistic valuation for.
So I'd imagine a 10% discount to listed asset NAV and 30% discount to NAV for the large companies and a 50% discount to the private investment seems more reasonable. Thats approx £10.50
Looks like dividend collection has begun to ramp up too and I'd expect £15m - £20m next year which against a market cap of £300m is beginning to get interesting.
I'd like them to start paying a dividend but they've been buying back shares instead given the NAV discount.
the link with SG was that a lot of those coins and stamps were v. rare and expensive. they were valued at SG's value and no-one could say otherwise until the value was about to be actually realised. There was a base value for the things that were easily saleable - like gold coins and property.
The same is true of the unlisted investments here - outside the bank of georgia (hopefully easily saleable) we are told the value of those businesses by the CGEO mgt.
I put this as a point to consider rather than a reason to avoid. If there is anyone out there who has 'boots on the ground' that would be v. useful.
davidjhill - Ive been very tempted by the discount on Georgia Capital (LON:CGEO) but was a bit put off by the director sales in July and August of this year. It made me question how real the discount actually was. Do you know if there's any reasonable explanations for those? Thanks
Sounds v interesting David given that the Bank is a highly rated stock in itself.. Also technically for me the chart looks reasonably progressive having held well at the 200DMA. I have stepped in with a small investment. Thanks for the heads up!
Gear4music Holdings (LON:G4M) A good start followed by poor customer service from G4M. I use my 2 City Centre stores, happy to pay a bit more for excellent face-to-face customer service. A great website but for some purchases I hope the High Street / City Centres survive.
Solid results from Focusrite (LON:TUNE) with acquisitions doing well. Successfully navigated supply chain issues ''The COVID-19 pandemic has challenged all businesses but as you will read in the following CEO and CFO reports, Focusrite plc has achieved outstanding results while overcoming disruption to component suppliers, assembly factories, international logistics and markets, as well as dealing with the challenges of enforced changes to everyday working practices.'' Hadn't realised they'd won the 2021 AIM company award. PE heady still, though.
Focusrite (LON:TUNE) Good results indeed, but the big question is whether they can repeat these results or how much is a covid boost?
Re Focusrite (LON:TUNE) (I hold)
Stocko consensus sales forecast for y/e 31st Aug 2022 = £160m against FY22 actual of £173.9m
Latest guidance from Carroll (who is noted for his cautious estimates) is
'Accordingly, we are now cautiously optimistic about the prospects for modest revenue growth in the current year.' and
'We look forward to another year of innovation and expansion.'
Seems like, for Focusrite (LON:TUNE) at least, the Covid boost was tied into underlying expansion.
Bought some Gear4music Holdings (LON:G4M) at 636 so very happy with this . Far too big a drop this morning and I am confident the long term prospects are excellent
There is an interesting article on a motley collection of 9 companies about to list on AIM here https://www.ii.co.uk/analysis-... . Looking at them cynically you would say most of them look as if they were all cashing in on current trends:
Two copper companies - copper price going up - needed for electric vehicles
DSW looks like a mini K3 Capital (LON:K3C)
A REIT focusing on life science properties - strong demand following the pandemic
and 5 following the needs highlighted by COP26:
A subsea equipment rental company - offshore wind market is expected to grow
A company that has developed a modular machine which can process hard-to-recycle plastic
An energy and water efficiency business
An Australian zinc-bromide battery storage company that has a M.O.U. to install 100 MWh of energy storage between 2022 and 2027 in Papua New Guinea.
A company developing hydrogen and ammonia production projects in Iceland and Paraguay. (To be spun out of President Energy (LON:PPC) by distribution to shareholders).
Gear4Music Holdings (LON:G4M) Thanks for your thoughts Paul. I agree that it is an overcomable problem but the sp is down 20% (08 20) illustrating your point on liquidity.
There is a note out from Progressive here with revised eps 21.5 this 29.4 next then 37.5p. There is a presentation at 16 30 tomorrow on IMC.
Kinovo (LON:KINO) - the trading update today confirms in advanced discussions to sell the building side of the business. extracting from H1 results it had turnover of c.10 and ebitda of 0.5m. but i've no idea of value from disposal. is 5times annualised ebitda possible = 5m?
debt at Kinovo (LON:KINO) has fallen in past couple of years from 10m to < 2m ( before disposal).
i think disposal will highlight the business delivering >4m ebitda(and growing strongly), with likely net CASH and operating in renewables space vs current MV of c.30m. there will be more news with results on 7 december.
disc i hold
Preliminary results for Revolution Bars (LON:RBG) this morning.
https://www.investegate.co.uk/....
A lot of to be expected red ink in the historic figures. Stand out stat for me is that they are now £4.6m net cash suggesting very strong reopening bounce still has legs coming into the peak Year End party season.
Gus.
Revolution Bars (LON:RBG) I suspect will have the Boris lock down effect holding them back somewhat especially what is going on in Europe, lets hope that the triple jab prevails and everything stays open, although I am a great believer in personal experience regarding investing, and the youth are the ones going to REV bars and most of them couldn't give a stuff about Covid and vaccinations they really want to party, interesting period ahead.
I'm holding cautiously.
Revolution Bars (LON:RBG) update looks pretty encouraging. LFL sales versus 2y ago have moderated from +17% in the 6 Oct update to +14% today - my rough calculation suggests the most recent 5 weeks were up +6%, so still fairly good. Cash also increased by around almost £1m since last update, which is very encouraging. Still find this one hard to value though, in terms of the the typical EPS it will deliver going forward.
£RBG Yes - I was thinking about this the last couple of days and decided that an interesting way of looking at it for now might be more of determining a valuation floor based on cashflow rather than an eps.
We know that a bar needs refurbishing every 5 years else revenues begin to drop reasonably rapidly impacting the profitability of the venue. So if we take 5* cashflow (adding back any capex in the period) that would estimate the cash profit the business would generate in wind down.
I estimate that at around £20m this year and £25m+ from next financial year so on a fwd basis circa £100m-£125m market cap which is around 40p moving towards 50p next year.
More Directors' selling at Tremor International (LON:TRMR) (I hold) making me nervous...
Morning Norfolk’n’Good.
Looking at the stock register, the Tremor International (LON:TRMR) directors seem to use their shares like an ATM so you must live in a state of constant anxiety!
Gus.
my guess is that the directors get share based compensation and regularly sell some down but I'd like this clarified, hopefully at the IMC meeting later today.
I'd also like an answer on why they want to sell at all given Tremor International (LON:TRMR) now trades on an EV/EBITDA of just over 5 for the year and they are bullish on future growth.
Re £TRMR
Thanks for replies Gus and David.
I notice today's announcement says 'Non-Discretionary Rule 10b - 5 Director Dealings'
Not sure what rule 10b is but your suggestion David would fit with all Directors selling but equally so would one or two others!!
RE Tremor International (LON:TRMR)
Here is a link to the Harvard Law School, no less, explaining what rule 10b is.
I would still like to know if David's point is correct and if so Tremor International (LON:TRMR) looks a very good prospect to me.
https://corpgov.law.harvard.ed...
Everything you ever wanted to know about 10b - 5 and possibly even a bit more …
https://en.wikipedia.org/wiki/...
Basically US anti insider dealing statute.
Gus.
That rule looks like an easy one to get around these days. You just issue a trading update saying you're trading in-line, the share price drops 20% then you can buy up the shares on the cheap.
Re Tremor International (LON:TRMR) I have managed to find this link explaining what Rule 10b is for anyone interested - Harvard Law School no less!
https://corpgov.law.harvard.ed...
I have no problem with this
They must spend more down the pub than I do!
They are presenting on IMC shortly. I am sure the Q&A will include discussion regarding the ongoing Director share sales in the days following the results, and the market's negative reaction to that. I have not looked into the details but I recall reading that the Exec of Tremor has egregious share based comp/ incentives....which they will likely want to sell down periodically. I look forward to the IMC webinar.
Progressive Equity has slashed EPS expectations for Gear4music Holdings (LON:G4M) this year from 29p to 21.5p (I don't hold - sold at 900p). Free broker note here. FY23 is also cut by a third to 29.4p.
Brexit-related issues sound significant here but at least Gear4music Holdings (LON:G4M) has a plan to build distribution centres in Europe, albeit sounds like it won't make much difference now until part way through FY23. It is probably worth being cautious about other shares with a decent chunk of revenue from Europe - Boohoo (LON:BOO) is shrinking in Europe at the moment and which will continue to be a headwind for the company without any plans for a distribution centre there I think. Marks And Spencer (LON:MKS) has also previously warned about Europe issues but is less dependent on revenue from the EU.
Is it possible to consider Integrated Diagnostics Holdings (LON:IDHC) please? Great 3rd quarter RNS for £IDHC today. Revenue up an impressive 126% year-on-year in 9M 2021 to EGP 3,767m. Net Profit recorded EGP 1,148m in 9M 2021, a 3-fold increase from same period last year. Net profit margin at 30% vs 22% in 9M 2020. On track to post record sales of c. EGP 4.9 billion in FY 2021, representing year-on-year growth >80%. Normalised EBITDA > 50% (Egyptian listing costs). highest ever revenue & net profit for a single quarter. top & bottom-line quarter-on-quarter growth of 27% & 47%.
It’s not only a Covid benefit…conventional sales Q3 21 & 9M 21 up 19% & 30% y-on-y & underlying test volumes back to pre-C-19 levels. On track for target of 30-35 new branch rollouts in ‘21. They also refer to considering potential acquisitions in similar markets.
Am holding as I think it’s an asset-light self-funding growth compounder - what’s not to like at this price? Not for everyone given non-UK but therefore fantastic value.
and Integrated Diagnostics Holdings (LON:IDHC) are “continuing
to assess potential value-accretive acquisition opportunities in new markets
across Africa, the Middle East, and Asia…”
Very happy with today’s results (I hold).
£dotd (I hold).
I have made this point a couple of times over the past two years, but just to repeat that I think Dotdigital's published figures are being enhanced by an accountancy 'sleight of hand'.
If you cntrl f 'Geographical revenue and results' in today's announcement, you will see that group revenue is actually up only 10.3%, rather than the 23% headlined.
This discrepancy between reported revenue and actual revenue is explained by the failed Comapi acquisition. Comapi's breakeven revenue is parked in a 'discontinuing' bucket in the accounts which is supposed to enable the reported figure to give a better view of the 'underlying' dotd business.
"Nothing wrong with that" you might say, "happens all the time".
But in Dotdigital's case I think it's a problem:-
• Dotdigital announced the closure of Comapi in May 2019 - 2 years on and it's still going strong, contributing £2.5m of revenue to today's group figures. £1m of that was generated in H2 so it looks like Comapi is going into its 3rd full year of being 'wound down'
• That would be bad enough, but in my opinion it's worse than that.
I suspect that the Comapi business isn't being 'discontinued' at all - instead I believe that Dotdigital is gradually moving the Comapi revenue out of the 'discontinuing' bucket and back into the 'reported' bucket, thus giving a falsely flattering picture of continuing operations growth.
The reason I think this is because by Dotdigital's own admission a lot of the growth reported in today's results (as well as those of the last 2 years) has been generated by UK based SMS revenue, i.e. precisely the area of focus which Comapi specialised in.
There's no way to prove this ofcourse. Maybe the 'continuing operations' growth really is genuine and nothing whatsoever to do with Comapi? Perhaps, but one thing is for sure, actual top line revenue growth at group level has been disappointing over the last 3 years;
7% actual vs 12% reported in 2018/19
9.9% actual vs 22% reported in 2019/20
10.3% actual vs 23% reported in today's finals
At the end of the day it's all money. We are shareholders in the Group, not just the 'continuing' bit.
£dotd I hold too and was concerned to read this in today’s release
“Direct marketing and partner commission were reclassified from cost of sales
to administrative expenses and tech infrastructure was reclassified from
administrative expenses to cost of sales to reflect more appropriately the
gross profit and administrative expenses.”
To me marketing and commission are cost of sales not admin! I would be interested in other's opinions.
I'm not an expert in the accountancy side of investing but yes, I would agree with you commission would seem better placed in 'cost of sales' - are you suggesting that moving it has enhanced profit figures? Personally I ignore gross and nett profit and track only pre-tax profit which I suspect is unaffected by this reclassification.
While I'm here, another concern I have is the old chestnut of capitalised and amortised intangibles - although dotd is a relatively minor offender on this well known dodge, I still think they are capitalising more each year than they write off.
What I find reassuring is there are no shorters making these points so perhaps I should leave dotd alone and let it climb it's 'wall of worry' - not much sign of that in today's price action!
£DOTD I find it irritating and unnecessary because it makes year on year comparison more difficult when trying to establish the health of the business and particularly when you then take their statement on gross margin into consideration :
“The gross margin for the period for continuing operations was 82% (FY20: 92%).
Whilst the gross margin for email and standard channels remained above 90%,
the decline in overall group gross margin comes from the growth of premium
messaging channels, (routing purchased via a third party on a per message
basis), such as SMS.”
I’m still holding, but perplexed!
Dotdigital (LON:DOTD) - imho being perplexed but still holding doesn't tend to end well
They are with Investor Meet Company this Friday and we’ll see how they answer the questions.
Re Dotdigital (LON:DOTD) I agree - for me they had it right before and I struggle with both reclassifications.
Any thoughts on the announcement from Kenmare Resources (LON:KMR) this morning to buy back upto 13.5% of shares in a tender offer (I hold). seems odd !
re Kenmare Resources (LON:KMR), why odd? The mine is currently throwing off cash, a return of capital seems sensible.
Yes - but not when the share price has already today overtaken the tender offer. The only people this will appeal to is those with no more than 500 shares - no dealing costs no spread. Everyone else will simply hold on - precisely because its cash generative......
Dotdigital (LON:DOTD) FY21 results today, here's an interview by CEO & CFO. Organic revenue growth +23%, recurring revenue 93%, Monthly ARPC +16%. Gross margin 82%. Cash £32m. A quality business. Video & podcast. (We should publish the DOTD analyst presentation in due course).
Highly recommend listening to Jeremy McKeown discussing the macro picture and what it means for investors. In a recent tweet he said in a year we might all be millionaires, but won't be able to buy any more. He's still investing in equities, but also likes real assets, including Scotch whiskey! Video & podcast.
The Stockopedia/PIWORLD StockSlam has been bought forward to January (from February). The new date for your diary 19th January, 6pm. A lot of new names, and some familiar names. Register here.
Also join the webinars for interim results from:
Ig Design (LON:IGR) 23rd November, 1pm
and Tpximpact Holdings (LON:TPX) (formerly The Panoply), 2nd December, 11am.
Thanks Tamzin. I tend to find one nugget in the interviews- this time it was on when to sell from Jeremy. Keep holding the stock until the reason you bought it no longer applies. I often get caught up in valuation or random price move, but sticking to the investment thesis would have kept me in for much longer.
Encouraging update from KINO this morning:
'Comparative revenues for continuing operations during the period grew 64% to GBP23.8 million (2020: GBP14.5 million), Adjusted EBITDA (after the effect of a charge for lease payments) increased by 75% to GBP1.8 million (2020: GBP1.0 million), with operating profit from continuing operations delivering GBP1.2 million (2020: loss GBP0.2 million). Total profit after tax was GBP0.6 million (2020: loss GBP0.2 million).'
Reads very well to my untrained eye, but are the headline numbers as good as they appear? I would welcome your thoughts.
I hold.