Small Cap Value Report (Tue 17 Aug 2021) - ELTA, FUL, GATC, VANL

Morning all, it's Paul & Jack here, with the SCVR for Tuesday.
Today's report is now finished.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to cover trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Agenda -
Paul's Section:
Electra Private Equity (LON:ELTA) (I hold) - update mainly focused on the smaller constituent part, Hotter Shoes. All sounds promising. I continue to believe this share looks an attractive entry point (i.e. cheap!) into the two forthcoming floats of TGIs and Hotter Shoes.
Van Elle Holdings (LON:VANL) - lacklustre results for FY 04/2021, but signs of recovery in current trading & outlook. Decent balance sheet. Overall it doesn't excite me, and is probably priced about right (already factoring in a recovery in trading).
Jack's Section:
Fulham Shore (LON:FUL) - final results of a Covid-disrupted year. The easy rerate has happened, with shares now above pre-Covid levels, and there could be more attractive reopening trades out there from a valuation perspective. But the company now finds itself in perhaps the most favourable market it has ever seen and is led by an experienced team that is well-placed to take advantage.
Gattaca (LON:GATC) - positive momentum continues. The company has cut costs and is investing in headcount, so could grow profits further with a fair wind, but the shares have now rerated considerably. These are exceptional conditions though with high demand for technical staff.
Paul’s Section
Electra Private Equity (LON:ELTA)
(I hold)
585p (pre market open) - mkt cap £228m
Realisation strategy; Hotter Shoes trading update
ELTA is a breakup situation where a investment company is splitting off its 2 main investments into becoming separately listed shares, scheduled for quite soon. The main one is casual dining chain TGI (plus a new additional brand of cocktail bars), the smaller one is Hotter Shoes (comfy shoes for over 55s), now sold mostly online. Both strike me as excellent businesses, and the package overall looks too cheap to me. Hence why I remain an enthusiastic ELTA holder - it’s not just an arbitrage on the sum of the parts being hopefully greater than the existing ELTA shares, both TGI and Hotter are shares that I want to hold long-term.
Today this is what we are told -
Reiterates that the strategy of demerging & listing the two businesses is the best way to maximise shareholder value - I completely agree. The alternative of trade sales would have given away a lot of the upside to a third party.
Demerger of Hostmore (the new holding company name for TGIs) is progressing well, and ELTA shareholders will receive Hostmore shares, as we already knew.
Name change - ELTA will be renamed “Unbound Group plc” once Hostmore has been demerged. That’s fine, it doesn’t matter to me what they call it!
More info on Hotter Shoes -
Change from retail, to multi-channel business during pandemic - most shops closed, and focus is now mainly on digital
“Hotter is now a fast growing, profitable and cash generative e-commerce focused footwear brand.”
Focused on a target demographic of over-55s - I very much like businesses targeting this demographic, because they’ve got most of the money, and are under-served, since so many businesses are obsessed with targeting younger people. Same with Saga (LON:SAGA) (my equal largest personal portfolio holding now) - this demographic have generally been hoarding cash over the pandemic, unable to travel, and often on fixed incomes - meaning there’s pent up demand, and a desire to spend now they've been vaccinated.
Broader product range - this is new I think, and sounds interesting -
Cultural and demographic shifts now provide an opportunity to further monetise the existing Hotter customer database and to grow it through the addition of similarly themed products beyond footwear…
Based on the foundations of Hotter as a trusted brand with market-leading digital infrastructure and strong customer personalisation through data insight, Unbound will provide a marketplace delivering a range of products and services that support the wellbeing and active lifestyles of our chosen customer community. Unbound's expanded offering beyond footwear will feature apparel and wellness brands alongside third party complementary brands. ..
Subject to the Hostmore demerger completing, Electra intends to seek shareholder approval to rename Electra as Unbound Group PLC ("Unbound") and to move its listing to AIM. Unbound will be the parent company of Hotter and the foundation of a fast growing e-commerce business serving and enhancing the lifestyles, health and wellbeing of our targeted customer community. We anticipate that Unbound will offer its first products beyond footwear from H1 2022.
That’s great, as long as Hotter management know what they’re doing, and don’t mess things up by expanding into new products that don’t work. Could Hotter Shoes become a “marketplace” for the over 55s, I wonder? That seems to be the way forward for brands - become a hub for other, smaller brands, and collect in fees for sharing your customers. Joules (LON:JOUL) (I hold) is doing that, as well as being a focus for Next (LON:NXT) , Asos (LON:ASC) (I hold), Debenhams (within Boohoo (LON:BOO) (I hold)) and even Marks And Spencer (LON:MKS) .
Diary date - 15 Sept for a Capital Markets Day for Hotter (to become Unbound)
Trading update for Hotter Shoes - these figures sound good, but there’s no context. The prior year numbers would have been heavily impacted by store closures, and lockdown 1. This year’s would have been impacted to some extent by lockdown 3. So this information is of limited use. I only really care about profits, which are not mentioned -
In the first 6 months of its financial year to January 2022 Hotter's UK Direct to Consumer sales have grown 39% on the comparable period in 2020.
In the same period overall sales growth has been 25%. Reflecting real progress in realising the benefits of Hotter's strategy, overall Gross Margin over the 6 month period was 63%, up from 53% in the same period in 2020 and over the same period fixed costs have reduced by 34% YOY.
My opinion - it’s all going according to plan. I’ve got high hopes for this, because the sum of the parts could be worth significantly more than the current valuation of ELTA, if the market takes to the new listings of TGI (Hostmore) and Hotter Shoes (Unbound).
Thinking about downside risks, there could be some short term indigestion as ELTA holders sell their new shares in Hostmore maybe? So I’m expecting initial volatility, which I’ll ride out. Also, eCommerce businesses have generally de-rated quite a lot this summer.
TGI is also subject to risk of any further lockdowns of course, being a casual dining chain.
I remain of the view that ELTA shares seem a highly attractive entry point (valuation-wise) into 2 forthcoming floats. See the research notes from Edison, which give their stab at valuation. Personally I’m hoping for an upside case of 1000-1200p per ELTA share, good upside on 585p currently, but of course it’s up to the market to decide what the new shares in Hostmore and Unbound will be worth, not me!
.
Van Elle Holdings (LON:VANL)
46p (unchanged, at 12:11) - mkt cap £49m
Van Elle Holdings plc, the UK's largest ground engineering contractor, announces its results for the year ended 30 April 2021 ('FY2021').
FY 04/2021 looks like another year of just treading water, very similar to the previous year (which was only briefly impacted by covid at the end, suggesting the business wasn’t firing on all cylinders before covid struck).
.
- FY 04/2021 revenue flat against FY 04/2020, at £84.4m
- Underlying loss before tax of £(1.2)m, similar to prior year of £(0.9)m.
Uninspiring so far.
The commentary talks up the recovery potential, and there are signs of life there, e.g.
… emerging in a strong position as market conditions started to recover…. Revenue run-rate at the end of the financial year returned to pre-pandemic levels.... Core markets saw a strong recovery in the final quarter of the financial year with all divisions, except Rail, operating at near capacity by the year end… Positive start to FY2022 with strong first quarter trading.
Outlook -
Assuming supply chain and labour challenges do not materially worsen, the Board anticipates delivering a profitable result in line with market expectations…
We are currently experiencing some current supply chain challenges, particularly with regard to cement, concrete and steel pricing and availability. There has also been an impact on employee availability, where our people have been required to self-isolate by the NHS test and trace app.
· Increased tendering opportunities and greater pipeline visibility for the Rail division, which supports an encouraging mid-term outlook.
· Order book at 9 August increased to £34.7m (1 June 2021: £26.4m).
That’s a good recent increase in order book, but it’s relatively small for a company doing £84m revenues, which suggests to me that there isn’t a lot of visibility more than a few months, in the order book.
It’s a very straightforward investment case then - we have to work out how much profit the company might make in future, now that business is recovering from the pandemic slowdown.

As you can see from the above, in its heyday a few years ago, VENL managed c.£100m peak revenues, and £8.4m peak profits, not bad. Although existing forecasts (the lighter coloured blobs for 2021 & 2022) show only a modest recovery to much lower than peak previous profits.
Hence the in line outlook today is not enough to get me excited. That would need a significantly ahead type of trading update.
Investor webinar - at 15:30 on 19 August, on InvestorMeetCompany. Should be interesting, I’ve registered to attend, and will report back if there’s anything interesting, in the usual way.
Dividends - currently suspended, but the company expected to reinstate them in FY 04/2022.
Balance sheet - as I would expect, it’s capital intensive, with £38.2m in fixed assets. Note also the small, but helpful £820k investment property. Inventories are usefully small at just £3.0m. Trade receivables stands out as having shot up from £12.6m to £32.0m, which needs an explanation.
Trade payables have almost doubled to £20.8m, and a new (current year) provision of £7.6m has appeared. So there are quite a few items on the balance sheet that need explaining.
Overall net assets of £44.0m, and NTAV of £40.2m look healthy.
Although I do have to ask the question as to why the company is not generating any profit or cashflow from this significant asset base? In that respect it looks a low quality business. What’s the point in buying all these expensive drills and rigs, if you can’t make a profit from using them?
My opinion - it doesn’t interest me very much, because the investment case is all about guessing what level of profit it might achieve in future, from the current position of small losses in FY 04/2020 and FY 04/2021. Personally I like investments with less guesswork.
The current market cap of £49m looks about right to me, at just over 1x NTAV. Why pay more, when it generates little return from those assets?
I think a more bullish case would be if you think VANL is likely to return to previous levels of profitability, on a sustainable basis, c.£7.5m p.a.. In that case, it might be worth say 50% more than the current price. Even then, not very compelling, because a contractor of this nature won’t ever attract a PER of much more than 10.
There are probably better investment ideas out there. This one’s not terrible by any means, but it seems a bit lacklustre. VANL has made a small acquisition, and mentioned it has the liquidity to do more acquisitions, so that might sprinkle some spice on an otherwise rather bland investment idea, possibly?
There are plenty of other more consistently profitable companies out there, trading on PERs of about 10, that look a lot better than paying up-front for a recovery here at VANL. Why does VANL have a stock market listing at all? It looks more suitable to being a private company.

.
As you can see above, the float in late 2016, with investor losing about half their capital.
Although it has paid about 8p in divis, which might numb the pain somewhat.
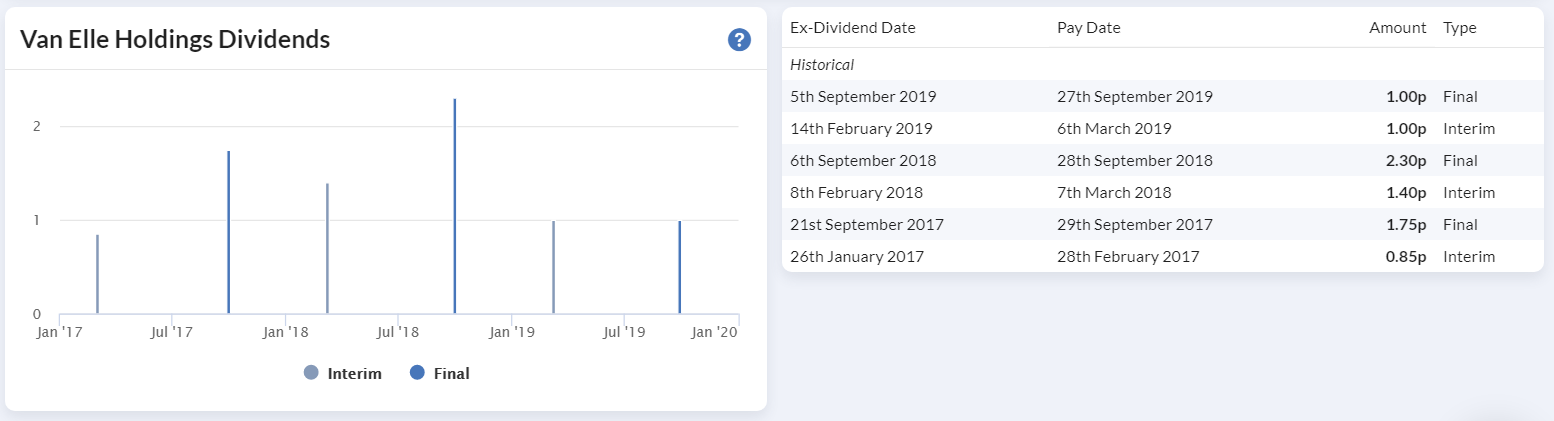
.
Jack’s section
Fulham Shore (LON:FUL)
Share price: 15.99p (-0.08%)
Shares in issue: 619,074,318
Market cap: £99m
(I hold)
Fulham Shore operates two growing restaurant businesses (Franco Manca pizzeria and The Real Greek), ably led by industry veteran David Page who played a key role in Pizza Express’ highly successful rollout in the 90s and into the 00s.
These are well run businesses in a competitive sector that can be hard for investors to make money in. What’s more, as with a lot of ‘reopening’ trades, Fulham Shore shares are now some way above pre-Covid levels.

There is a train of thought that goes some way to justifying this: market shakeouts can be net positive for quality operators, as weaker players exit the market, leaving less competition and more sites to go for, often at more favourable rents and better returns on capital.
Nevertheless, Fulham Shore now has a market cap of around £100m on forecast FY21 sales of £79.4m, having so far struggled to make a profit as it invests in its expansion. So there’s a degree of growth priced in here, and an assumption that the steady-state enterprise would in fact be profitable.
I do believe that to be the case but, at current levels, I also wonder how much upside is left on the table. The free float is small as well, with a lot of the shares held by management.
Results announced today are of course impacted by Covid.
Final results
Highlights:
- Revenue -41.3% to £40.3m, driven by Covid trading restrictions,
- Headline EBITDA -40.8% to £9m, or -77.1% to £1.6m excluding IFRS 16 (the difference here being rental expense),
- Headline operating loss of £2.2m (FY20: operating profit of £4.4m),
- Loss before tax of £7.5m (FY20 LBT: £0.8m),
- Net debt excluding lease liabilities is down from £9.5m to £3.6m as at 28 March 2021,
- Group now net cash as at 15 August 2021 of £3.5m.
EBITDA is stated after adding back £2.8m of finance costs, £11.1m of depreciation and amortisation, £1.5m of Covid-related exceptional costs, and £0.8m of brand amortisation.
Headline EBITDA adds back a further £0.2m of pre-opening costs and £0.1m of share-based payments, while adjusted headline EBITDA subtracts £7.1m of rent expenses.
The group describes ‘a tale of four quarters’:
- Q1 was loss making (April, May and June 2020),
- Q2 saw a return to profit at Headline EBITDA level,
- Q3 continued the positive progress
- Q4 to March 2021 once again contributed a loss although trading and profitability showed significant improvement compared with the first lockdown.
Fulham Shore says that sites in the West End of London continue to lag in the recovery, as do other city centre restaurants, with office workers and tourists yet to return. The group believes revenues will recover in the medium term, meaning this should in effect flip from a headwind to a tailwind at some point over the next year or two.
For now the disparity of performance between these city centre locations and the other restaurants is stark: the city centre site revenues were down 41% on a two year like for like basis for the 8 weeks from 21 June 2021 to 15 August 2021.
In contrast, some of the group's restaurant locations outside the major conurbations are over 30% ahead of 2019 figures.
Management expects that the substantial growth of delivery and take out services achieved during the financial year will remain at higher levels going forward.
Two new Franco Manca pizzeria and one new The Real Greek restaurant were opened during the year (2020: seven Franco Manca pizzeria and two The Real Greek restaurants). New openings have been funded ‘largely through existing operational cash flow’.
As of August 2021, all of Fulham Shore's 74 restaurants were fully open and trading. Of those 74 restaurants, 55 are Franco Manca and 19 are TRG.
One new TRG is under construction in Norwich, a lease has been exchanged for a new Franco Manca in Baker Street London, and some 12 additional sites are in solicitors’ hands.
David Page, Executive Chairman at The Fulham Shore commented:
Since the beginning of the current financial year commencing 29 March 2021, The Group has continued to trade profitably and ahead of management expectations, driven by strong performances across our suburban restaurants…
In line with our long-term expansion strategy we have developed a strong pipeline of new locations, supported by favourable rental terms and the Group's strong cash position. We plan to open 10 locations during the current financial year and have identified more than 150 additional sites in line with our medium-term plans.
Costs
Sterling weakness and the need to increase stock levels in case of a hard Brexit has continued to put pressure on food cost inflation. Supply chain capacity hits from volatile demand over the past year has also contributed to this inflation. FS has partially mitigated this through volume discounts and changes in suppliers where necessary.
There was also a 6.2% (2020: 4.9%) increase in the Government's National Living Wage at the beginning of the financial year for employees over 25 years old.
The other two material cost items are rent and utility costs. Here the group is finding more short term rent deals with landlords at improved prices. Utility cost inflation continues to be volatile.
Market and property
Analysts believe that the UK restaurant market in terms of numbers of locations in 2022 could have diminished by as much as 20% compared to 2019, possibly reflecting the contraction of retail space.
For years, the casual dining space suffered from over-expansion and higher rents as operators chased market share. Fulham Shore comments:
The CVAs and closures that have ensued across the sector have enabled both of our businesses to obtain sites at favourable rent levels and lower capital cost per site. Rents have halved in some cases, and we have opened some sites for less than £500,000 rather than the average of £650,000 which we were budgeting in 2019. Both these reductions should improve our return on capital over the next few years.
After years of sifting around the market for rare well-located sites offering acceptable returns on capital, Fulham Shore is no doubt rubbing its hands with glee here. After a series of ‘dynamic debates’ with its landlords, FS now expects to pay lower rents over the next few years across its existing sites.
Landlords are still facing a property glut. There are unlet premises all around the UK in unprecedented numbers. This will eventually recover to a normal supply and demand ratio but that could take a few years.
It is being offered many new sites, including former retail shops, ground floor offices, and chain restaurant units.
More than 125 potential FM locations and 30 more for The Real Greek have been identified, so the company is well on its way to building a 230-strong restaurant estate in the UK over the medium term. It hopes to reach 110 sites by the end of 2025, likely on improved terms than previously.
Conclusion
Fulham Shore is good at what it does, but how much upside is left at a £100m market cap? The obvious rerating has already happened and the company is once more being priced on its growth prospects.
FUL now talks about having 110 sites by 2025 and 230 beyond that. While the level of profitability at its sites is hard to gauge due to a disrupted year. If we take the FY20 headline EBITDA measure of £15.2m across the then 69 sites, that’s a contribution of £220,290 per site, meaning headline EBITDA of around £24m by 2025.
On the one hand, that figure will be helped more as the estate matures. But on the other, headline EBITDA brings with it a fair amount of adjustments which are further obscured by changes in accounting treatments to leases and whether or not this is treated as debt. So seeing what the end result might look like requires a little more thought.
Either way, it would lead to a much larger company in terms of revenue, and an increasingly profitable one as development capex becomes a smaller percentage of operating cash flow.
There are positives here. The property market has swung in favour of tenants and FS is seeing sites come up at ‘very attractive prices’. The group is in a position to take advantage of this while competitors have either left the market or continue to fix their estates and/or offerings.
FUL has struggled to generate profits in the past - this may be because of rapid expansion under experienced management, or it may reflect industry cost pressures. Personally, I believe it’s more the former than the latter. Management attaches more importance to operating cash flows than earnings.

On that note, FY21 cash flow was strong and there has been a swing to net cash pre-IFRS 16. That swing has been helped by:
- government support to the tune of £10.3m,
- a £2.25m placing,
- £2.8m of deferred rents, and
- a 76.4% reduction in development capex from £7.2m to £1.6m.
FUL has started to repay the CLBIL loan (‘Coronavirus Large Business Interruption Loan’) with the first repayment of £1.48m made at the beginning of August 2021 and intends to repay it fully ahead of the original date agreed.
Looking to the future, the group has created a new team to explore and progress international development. Management has already fielded enquiries here and the team has experience of successful expansion outside the UK.
Total Group revenues for the eight weeks from 21 June 2021 to 15 August 2021 averaged over £1.5m per week. This includes a restricted period until 19 July 2021 and subdued city centre performance, which is expected to normalise in time.
The figure represents an increase of over 8% in revenues compared to the equivalent period in 2019 and annualising that gives £78m of revenue, which should be beatable with a fair wind. The current year will be more indicative of the group’s prospects.
On that note, the UK economy and consumer spending in particular are forecast to bounce back strongly over the next year. Furthermore, the reduction in capacity in terms of site numbers could add to the expected greater demand for continuing operators.
So it’s a favourable backdrop for the good operators that remain in the market. At current levels, the shares look fair to fully priced, but on the other hand it’s an exciting time to be an experienced restaurateur so I’m intrigued to see what Page et al. do with this opportunity.
Gattaca (LON:GATC)
Share price: 232.1p (-6.03%)
Shares in issue: 32,290,000
Market cap: £75.2m
This is a recruiter that has rerated materially over the past couple of months.

Even now, with a one-year relative strength figure of some +267%, Gattaca is rated as a 99 StockRank Super Stock. Some of these ‘reopening’ businesses have had such fantastic reratings though that they are by definition not the bargains that they once were.
There are good signs of recovery here, but then again the share price has already tripled which reduces the upside somewhat. The balance sheet looks fine, although an outstanding dispute in the US is a key concern. This has already cost the company a fair amount and remains hard to quantify.
The group expects continuing underlying PBT and adjusted net cash to be above market expectations for FY2021. These expectations are fairly modest, having been reduced in the wake of Covid.

Getting back to FY19 normalised EPS of 18.6p would give a PER of 13.1x, which would probably be fair given the low margin and cyclical business model. So the question is whether an unlocking economy will translate into sustainably strong market conditions for recruiters.
The group is investing in sales and delivery across the business and there has been a 13% increase in front line headcount since January. H2 2021 continuing NFI was 7% higher than H1 2021, with the full year NFI at £42.5m (FY 2020: £52.8m).
NFI is Net Fee Income, which is revenues due to the company, stripping out the pass-through wages of the contractors they provide.
Subject to final adjustments and audit, Gattaca expects continuing underlying FY PBT to be in excess of £3m (market consensus £2.7m). A modest dividend is expected to be paid.
Adjusted net cash (excluding IFRS16 lease liabilities) is expected to be £20m (31 July 2020: £27m) largely driven by a £4.7m repayment of deferred VAT. Another £5.6m of VAT deferrals remains.
All businesses have been transferred to Gattaca’s global technology platform in Q4 enabling a consistent view of activity and performance across operating units.
Increased activity in RPO (Permanent Recruitment Process Outsourcing solutions), with further improvement to come on the contract front including in the group’s core infrastructure unit, which will benefit from strong demand driven by UK Fibre investment, HS2, and Offshore 2025.
The defence business continues to perform strongly and Gattaca also anticipates continuing high demand for technology skills as the pace of digitisation continues to accelerate.
Conclusion
It looks like work has gone into reducing the cost base here, with exits from its South Africa and Mexico businesses, while the completion of its move to a global technology platform also stands Gattaca in good stead.
It’s investing in headcount, so I can imagine continuing momentum over the next year - but this is now reflected far more in the share price than it was a couple of months ago. There are technological risks for recruiters, with LinkedIn and others moving into this space and, over a longer time frame, there is also the probability of a wider downturn at some point.
When though? That could be years away, and between now and then, this could continue to be a good trade. It’s not a stock I would put in the ‘buy and hold’ camp, but rather a way to express a view on ongoing strengthening markets over the next year or two.
I can see how there could well be further upside here but at these levels I’m more neutral on the stock than I was back in March, when the shares were 150p or in February at 105p.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

53 comments
Hi Paul, many thanks for all the amazing daily reports you write for us. The quality and consistency of your work is unbelievable. I have learnt so much from your commentaries, including about company accounts.
I read your updated view this morning on Saga plc and remembered a while back about Carnival plc - that it had also created a favourable impression. Is that still the case, or do you think that Carnival (LON:CCL) has run a little ahead of events? Plus unlike £Saga, it doesn't have a diverse earnings stream as a hedge against further losses.
kind regards
worth pointing out that #AAA of which I am a long term holder and is the bidder for #boom seems to be being listed on Nasdaq with the ticker #aascf - I really think this is a golden share, I have been in it since less than 3p and it will fly very nicely in the states. I am very biased so you should DYOR
I should add you can get UK exposure but buying #ASLR which should be £ 1.50 not 39 pence they own a significant holding in AAA again I am super biased and long DYOR
Re Fulham Shore (LON:FUL)
"There is a train of thought that goes some way to justifying this: market shakeouts can be net positive for quality operators, as weaker players exit the market, leaving less competition and more sites to go for, often at more favourable rents and better returns on capital."
In my view, this is not right. Barriers to entry in the hospitality sector are fairly low. In my local market town every other vacant shop is currently in the process of being converted into a coffee shop/ restaurant or bar. As a result, I think we're likely to see an increase in competition over the next 12-months. Not a reduction.
Great observation, making money in sit-down restaurants is very tough because of just this fact.
I am also worried about wage inflation and raw material cost inflation for Fulham Shore (LON:FUL) but they didn't mention anything about this. They did talk about wage and raw material inflation in the FY21 just gone. Looks like they are purposely cherry picking good news to publish in their outlook sections, not providing a balanced commentary for investors.
Or maybe wage inflation and input inflation isn't applicable to them? Doubtful.
They did skirt the topic by this statement: "We are always careful about our menu pricing. We choose our quality ingredients from local suppliers where possible and intend that our customers will be served by motivated teams of incentivised staff." and they could have easily inserted commentary on what they thought about the current news on wage inflation, staff shortages, raw material price inflation.
I also just picked up something else I didn't like in the Fulham Shore (LON:FUL) results.
They mention they're 8% up in revenues vs the comparative 2019 summer period (21 June 2021 to 15 August 2021). Sounds impressive. But its not like-for-like, as they had ~69 outlets then, and now ~74 outlets! Which is about 7.2% more outlets.
It would have been easy for them to just take all their existing stores in summer 2019 that exist now and do a sum of revenues, and provide a like-for-like.
Sometimes, its what isn't said or the way things are spun that tell the truth about management and their attitude to investors...
Gattaca (LON:GATC) . The first thing that I noticed was NFI 2020 of £52.8m and NFI 2021 of £42.5m . A 20% drop. I think that with COVID cases rising globally and more employee isolation will decrease company appetite to recruit staff.
wow - are you reading any market commentary on the labour market? Do you realise what a shortage there is with job vacancies at record highs?
I see the UK Consumer Price Index (CPI), Retail Price Index (RPI), Producer Price Index (PPI) and Consumer Price Index (EU) are due to announce their updates tomorrow. This should give a view on how inflation is progressing. Does any one have a view (either way) on how these updates could impact the UK markets (Up, Down, Indifferent)? Thanks, Andy
Gattaca (LON:GATC) somewhat surprised to see these down today on an update ahead of expectations. Strip out cash and this years earnings numbers will be around 17-18* which probably appears reasonably fully valued but given the very tight labour markets I can see them growing considerably so I expect that to fall to the low teens on a 1Y view. I guess given the run up in the SP there are a few people taking profits but looks to me like this is a business that is finally starting to realise its potential having serially disappointed under previous management.
davidjhill
Gattaca (LON:GATC)
somewhat surprised to see these down today on an update ahead of expectations.
are these ahead of may expectations are is there woring either sloppy or confusing - its highly unclear to me !
This is what they said today
Following our trading update announcement on 21 May 2021, we expect continuing underlying PBT1 and adjusted net cash (excluding IFRS16 lease liabilities) to be above market expectations for FY 2021.
They announced they were ahead in May - this wording IMHO is somewhat confusing referencing continuing and May in same paragraph as they say they are ahead - ie is it that are ahead as outlined in may - if they are ahead of may update why not say that clearly.
Note in may they said
We now expect NFI in H2 to be in the order of 10% up on H1 2021.
H1 was 21.1 - so in may they were saying expect £44.3 mill net fee income and today they are sayinmg
Now what they say today is
H2 2021 continuing Net Fee Income ("NFI") was 7% higher than H1 2021, with the full year NFI at £42.5m
stewth thats behind what they said in may not ahead!.
That may not be inconsistent though if sales have missed may targets and profits have beat may targets - don't think they spelled those taregts out in May though which hsan;lt helped.
It may be me being thick as two short planks here - but on my initial reading its somewhat confusing speak overall today - not helped by lack of recent broker updates on stocky or confirmation of prior expectations ref may trading update.
I think the bit missing is that they decided to shut the loss making Mexico and South Africa business so those would not be "continuing" in the revenue line. Agree it is slightly confusing and more helpful if they also showed how much NFI that reduces by.
But primarily the beat is in the PBT numbers which appear to be now expected around £3.2m versus previous analyst expectations of £2.9m
Equity Development report might be of interest if you have not already seen this.
https://www.equitydevelopment....
Gattaca (LON:GATC) trading update looked ok to me – Thanks for the writeup Jack! I added some more as the drop seemed excessive but this one does go up and down a lot.
While Gattaca (LON:GATC) is on the cards for discussion, does anyone have a view on MMGG Acquisition Ltd’s stake? They increased in May up to 20%. In June, founder and NED George Materna increased his stake to 25.01%
Gattaca (LON:GATC) - Founder George Materna buying circa £500,000 (the first time he has bought since 2015) and the MMGG stake is why I am so confident in holding.
Hi Paul, just had a look at the elta page on stockopedia, it seems very lacking in information, doesn't give stock ranks etc, just wondered what the cause of that is ? profitability seems a bitup and down these last few years, and predicted loss making for the next two years, on the face of it doesn't seem so great, can you share some of the history and your thoughts on why it's predicted to make losses in the future ?
K
Just had a look at the Electra Private Equity (LON:ELTA) page on stockopedia, it seems very lacking in information, doesn't give stock ranks etc, just wondered what the cause of that is ?
It's an investment trust. Stockopedia doesn't rank those.
timarr
“It's an investment trust. Stockopedia doesn't rank those.”
* Except when they do :)
Paul has done two very extensive write ups on ELTA, have a look at the discussions tab.
Hi kenobi,
Just ignore the stuff on the Stockopedia page for Electra Private Equity (LON:ELTA) (I hold) because it's a special situation - an investment company that is floating its main 2 investments, and giving shares in them to existing ELTA shares, at some point later this year. So what we need to do is value the 2 companies which it will morph into.
Regards, Paul.
Does anyone know about the situation at Abingdon Health (LON:ABDX) ? In a nutshell DHSC is refusing to pay a £6m bill which was contracted and delivered. The reason is that the Good Law Society took the contract to judicial review (due Dec 2021) - see https://www.bmj.com/content/37... for details. But surely, whatever the dodgy reasons for giving them the contract, once it is signed and delivered, they must pay up. Naturally not paying a large bill to a small company has put the company into difficulties, but I get the sense that they will survive and have bought a tiny position on this gamble.
Given the cash value on the balance sheet along with additional assets virtually covers the current share price, it could be an interesting opportunity.
Hotter. Are they buying from China?
Personally, for various reasons, I'm avoiding any company buying from China (if I know)
Hotter. Are they buying from China?
Where are you going to draw that line? I believe the shoes are made in the UK but I think that it's a final assembly operation using imported materials. I doubt the leather is from British cows for example.
On the face of it - excellent results H1 2021 from Plus500 (LON:PLUS). The active customer base has increased. The revenue and Ebitda figures look good to my untrained eye - $346.2 million and $187.2 million. These figures on first glance look poor in comparison to H1 2020 - however, Plus500 (LON:PLUS) does very well in volatile markets - so results in H1 last year are not likely to be repeated.
Healthy Interim dividend of $0.5921 per share and a share buyback programme announced as well.
Yes I think 2020 needs to be treated as a one-off exceptional year, but numbers look very good against 2019 and company seem to be progressing well. Still seems far too cheap to me. I like the spread betters as they're one of the few businesses that provide negative beta, so tend to do well when markets fall. This gives tremendous diversification benefits in my view. Also hold Cmc Markets (LON:CMCX)
I agree. Heavily undervalued. Margins of 50%+!! Market Cap less than half of Boohoo but way more profitable.
Lee Brown
CMC Markets (LON:CMCX)
I agree. Heavily undervalued. Margins of 50%+!! Market Cap less than half of Boohoo but way more profitable.
What a bizarre comparison.
CMC operate in an area that is subject to huge regulatory control and profits can be massively fluctuate due to circumstances beyond control.
Oh and ref profits looking at current year forecasts we have.
For boohoo we have expected net profit of £135 million and for CMC we have estimated of £105 - so on the face of it you are completely wrong to suggest that cmc IS way more profitable. Maybe was more profitable in the past but not now based on current year expectations as things stand.
I know that the PGM stocks are widely held by readers on here. Just wondering if anyone knows/understands why Jubilee Metals (LON:JLP) dropped by 9.2% yesterday whilst Sylvania Platinum (LON:SLP) dropped by 4.8% and Tharisa (LON:THS) by only 2.4%. I can understand the markets were volatile yesterday hence Sylvania Platinum (LON:SLP) & Tharisa (LON:THS) moves, but 9.2% is a big drop for Jubilee Metals (LON:JLP) without some reason.
I have held Sylvania Platinum (LON:SLP) & Jubilee Metals (LON:JLP) for some time and still feel they have more to give. Both becoming big cash-cows, but I recognise the risks of short-term pricing and region risk.
Best wishes all.
I feel that I have missed out on Sylvania Platinum (LON:SLP) but avoided as the macro factors that influence it are too many for me to understand.
Tharisa(LON:THS) has fallen a lot in the last month due to the South African situation although it was not affected .
Think its at crazy price at the moment even compared to the normal miner discounts
Morning Kevin
I exited Jubilee Metals (LON:JLP) yesterday for a modest loss, probably prematurely. As said in a previous post I am not up to speed with geology and geophysics and find much of the technical reports difficult to interpret and so have generally decided to giving mining stocks a wide berth, Added to which I am able to reinvest the proceeds in companies that I have more conviction in and better understand.
Anyway my simplistic view in selling Jubilee Metals (LON:JLP) was that the share price movement was inconsistent with the recent operational update, which was described in glowing terms by management. It may be that that investors were disappointed by the absence of reference to a future dividend policy or apprehensive of the cost of the ongoing investment in infrastructure or the current weakness, comparatively speaking in the rhodium price. There is off course the potential for adverse geopolitical issues given he location of the company's operations. However in truth I don't know what has caused the share price weakness. Anyway I wish you well whatever you decide.
Thanks Jonno.
Seems like we are all in the dark regards Jubilee Metals (LON:JLP) I thought it might be some of the more recent II's selling off, but volumes seemed to be very low.
I know the Chairman does not get glowing feedback from some quarters, although the CEO is thought of very highly. This I believe was one of the reasons II's weren't interested in taking up holdings in the past, but this seems to have reversed around the end of 2020 when a number of institutions bought into it.
There has been some negative movement in the basket prices of the PGM's, but even so the forecasts for Jubilee Metals (LON:JLP) look to be very positive.
Lets hope the price drop offers up an opportunity for buyers to come in.
K
Jubilee Metals (LON:JLP) - on one view, all that has happened is that the Jubilee Metals share price has fallen back to the 40 week moving average (check the chart tab). If the price bounces from here, the uptrend may continue. But if it falls, then it may go down a lot further.
Good luck everyone!
Ricardo (I hold, having bought at 4p)
Share price weakness in metals miners is usually caused by one of three things: 1) underlying metal price decline, 2) strengthening dollar, or 3) Total disaster at mining site (if a one-hole operation - e.g. Centamin).
When you buy a miner you are effectively buying an option on the underlying metal, it doesn't really matter how much cash the operation just threw off, markets are forward looking and future cash depends on metal price.
Check the price for Rhodium over last year:
Look familiar? You can pretty much lay that chart over Sylvania Platinum's share price. The chart for Platinum is similar
Since August, rhodium has gone from c.$1750 to c. $1450, and platinum hit $970 last week down from a high of c.$1250 in June. Therein is your share price slump. The question is, do you believe that either price of metals will rise or, USD$ will tank at any point in future, as both will likely send share price higher?
Happily I believe both will happen so am fine to hold.
That chart is for an ETC, the price of Rhodium from Kitco ( https://www.kitco.com/charts/r... ) is $18000/oz approx.
I suspect the problem for Jubilee Metals (LON:JLP) is the Zambian election uncertainty (a new President has been elected etc.), they are the only one in that cohort who have a Zambian operation.
I'm overweight Jubilee Metals (LON:JLP) from 2p.
Hmm good spot. KITCO chart clearly the right one, but point stands. Price down from peaks in May, however long-term underinvestment in mines will mean constrained supply in face of tightening emissions standards and EV conversion of world vehicle stock will take decades.
Hi KevinS1
Jubilee Metals (LON:JLP)
The low volume at the this time of year can make for surprising share price movements.
I have noticed over the last month or 2 that (LON:JLP) share price has not dropped as much as Sylvania Platinum (LON:SLP) or Tharisa (LON:THS) so there may be some 'catch-up' also.
Jubilee is also a small company so a few sellers can move the price a lot.
Michael
My morning smallcap tweet: Lancing the boil of BS
Surface Transforms (LON:SCE) Electra Private Equity (LON:ELTA) Argo Blockchain (LON:ARB) Gattaca (LON:GATC) TP (LON:TPG) Kanabo (LON:KNB) Zoetic International (LON:CHLL), ULS Technology (LON:ULS)
Surface Transforms (SCE) four year contract for brake disks from new customer, worth c. £5m PA. [SP=61.9 Cap=121m]. I hold.
Electra Private Equity (ELTA) wholly owned co Hotter Shoes H1(July) rev up 25%, gross margin 63% (53%). [SP=582.12 Cap=227m]. I hold.
Argo Blockchain (ARB) claims it's the first publicly traded cryptocurrency mining company to report it has become climate emissions positive. It's still energy going up in hot gaming chips. [SP=124.6 Cap=476m]
Gattaca (GATC) guides FY(July) U/L prerax over £3m, above market expectations of £2.7m. Will pay a modest dividend. [SP=246.4 Cap=79m]
TP Group (TPG) tells Science Group where to put its 5.8p offer, again [SP=5 Cap=39m]
Kanabo (KNB) subsidiary Materia will distribute German-produced medical cannabis extracts. "Adds a new line of cannabis extracts products for Materia Deutschland's curated portfolio." Curated? What are they smoking? [SP=18 Cap=66m]
Chill Brands (CHLL) new name and ticker for Zoetic. [SP=NA Cap=NA]. I'm short.
In line: ULS Technology (LON:ULS)
MrC,
Where did you find the RNS on Hotter Shoes as it’s not showing under Electra Private Equity (LON:ELTA) on Stockopedia and there’s nothing on the Electra Private Equity (LON:ELTA) website?
Electra Private Equity (LON:ELTA) RNS is on Stocko now. I found it on the London Stock Exchange.
Cancel that it’s there now!
Any opinion on Shield Therapeutics (LON:STX) ? Their lead drugs are starting to gain traction in Europe and launched in US. They have a generous cash reserve from successful fundraiser in March and cash burn seems controlled. Will they reach profitability in the next year as planned? If so 2 x analyst target price is around £2.50 now trading at around 50p.
What's happened to their revenues down to £0.5m?
Shield Therapeutics (LON:STX) (I Hold). Its because no royalties were registered in the last 6 month period, whereas, prior to that, they received £8m from the licencing of their Chinese partner. This model makes income quite lumpy. Consider this statement from todays update:
"We announced a licence deal on 12 August 2021 with KOREA PHARMA CO. LTD to develop and commercialise Accrufer® in South Korea. The terms of the deal includes an upfront payment of £500,000 and will be entitled to a further £1.5 million on first sale in Korea, 15% royalties and up to £4 million in potential sales milestones. We are also in early discussions with potential partners in several other countries."
They have decided to handle their own sales in the US market, so this should help to create regular income and make it less lumpy
Shield Therapeutics (LON:STX) (I hold), is one of my larger holdings. Registering a half year lost was expected. Since July they have hired a new sales team in the US, to get the product moving, so this is still in its infancy. This should generate a lot of upside as Shield Therapeutics (LON:STX) will gain a higher margin, from selling their own product, rather than going through a third party (like they have in Europe and China). No reason why sales shouldn't be good going forward, given the moat the company has with its Iron Deficiency product. I am no expert, but thinking the upside here could be excellent
A good announcement from Surface Transforms (LON:SCE) but would it be fair to say it is already priced in?
Any informed ideas as to the US manf? Curious (I Hold)
Surface Transforms (LON:SCE) definitely building a nice pipeline of future revenues. Key question is margin - can't infer from historic results as their BAU production facilities coming online now.
And then there's always the risk of product quality, especially something like brakes. When it hits the mass market and ramped up number of installs, will any flaws or defects be found, therefore setting back revenue growth curves and requiring expensive remediation? Always a concern with first generation of products hitting the mass market.
Surface Transforms (LON:SCE) (I Hold). Lets hope the 15 years they have spent in R&D and passing regulated quality control tests, ready for production release, go all the way to prevent such defects from occurring. There must be rigorous testing of products from any new manufacturing units before sales can be made :)
You say that, but one look at Tesla autopilot... Doesn't fill me with confidence that regulators are on the front foot with new technologies !