Small Cap Value Report (Tue 17 Jan 2023) - QUIZ, RBG, MCB, UBG, RFX, NWOR, DPP, EQLS, THG

Good morning from Paul & Graham.
Today's report is now finished.
In case you missed it, Graham published his own watchlist of interesting shares for 2023, which stand out as the most interesting ideas he's covered in the SCVRs. As always, we just throw ideas at you, for your own more detailed research.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Agenda
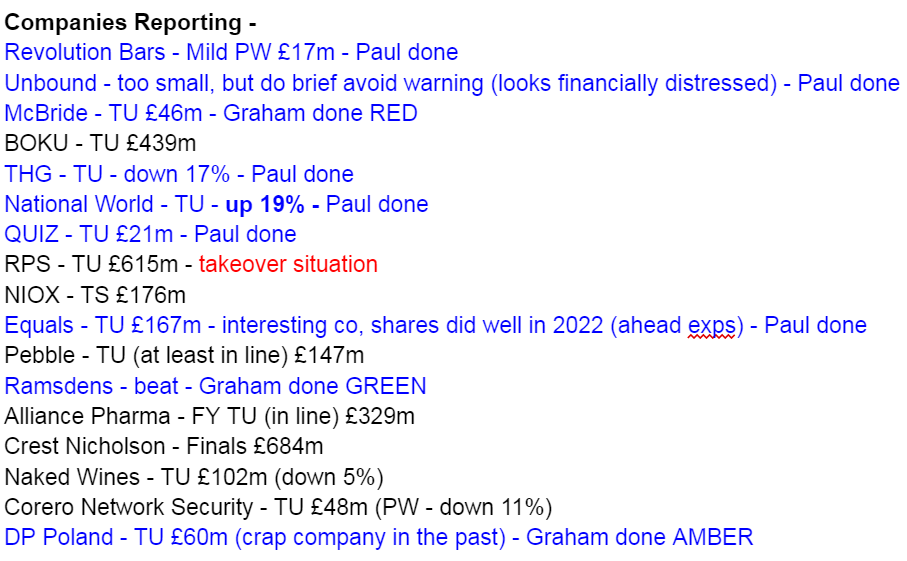
This is the final tally. I think we covered all the main above, or below expectations updates, which is the idea. Obviously we can't cover everything!
Do post a comment below if there's anything significant that we missed (that isn't just an in line with expectations update).
.
Paul’s Section:
Quiz (LON:QUIZ)
(16.75p y’days close - mkt cap £21m)
Trading update looks reassuring. Stores traded well over Christmas (revenues +19% in Dec 2022). Online revenues down -14%, due to reduced third-party website sales (in line with strategy). Own website revenues were flat vs LY. Gross margins good. International revenues good, up +20%.
Cash position healthy at £9.2m, plus headroom of £3.5m from unused bank facility (safe, with no covenants, and it’s not needed in my view, Expires June 2023, but has renewed without problems in the past).
Outlook - confident at least in line outcome for FY 3/2023, same wording as last update. "Well positioned" longer term, but mentions macro pressures which may impact demand (but that sounds a generic warning, not company-specific).
My opinion - after the restructuring in 2020 (which got rid of old leases, with remaining stores now on cheap & flexible turnover rents), QUIZ is resilient - surviving, and making profits again, when many competitors have gone bust or retrenched. Solid finances with plenty of cash. Looks good to me. Valuation still seems modest. So a thumbs up from me.
Revolution Bars (LON:RBG)
(7.4p pre-market, mkt cap £17m)
H1 trading update doesn’t read well I’m afraid, but needs to be seen in the context of a bombed out share price. Peak trading in December 2022 was well up on LY, with LFL sales +17%, but this is against a soft period LY due to omicron. Revenues down -9% vs pre-covid (despite most bars having been recently refurbished), which is no good (because costs have risen so much, especially labour). Good corporate parties, but soft walk-in trade, blames rail strikes and low consumer confidence. Recently acquired Peach Pubs has performed well though.
Revised guidance - pre-IFRS 16 EBITDA will be at bottom end of market expectations of £6.7m to £10.5m. Net debt of £18.5m looks too high to me, after a reckless decision to make the debt-fuelled acquisition of Peach, just as the economy was going into a downturn. Outlook is seen as “challenging & uncertain”. Closing some sites on Mon & Tue, to save money, makes sense.
My opinion - I wish they hadn’t acquired Peach, and loaded the company up with debt again, which seems a bizarre decision (the Chairman should have stopped it, I think) and makes the shares much higher risk than they would otherwise have been. We had 2 emergency, discounted placings during the pandemic. Avoiding another one should have been management’s key priority. So I have to flag the increased risk of having too much debt again, which combined with softer than expected trading, isn’t a good look. Lots of competitors likely to go bust though as 2023 progresses, giving greater market share. Also living wage rising by almost 10% in April 2023 should help put pounds in the pockets of the younger customers, as well as being another headwind for the business. So providing the bank doesn’t go wobbly on them, RBG could be one of the longer-term winners. Overall then, I’m neutral at the moment, but worried about increased risk from debt. The whole hospitality sector looks horrible at the moment, it's so difficult to make money against so many cost headwinds, and soft consumer sentiment.
Unbound (LON:UBG)
(3.7p down 42% at 08:46 - mkt cap £3m)
Probably my second to last comment on this share, to warn people off again. Bad profit warning today, together with excessive debt, means I think the equity is now probably worth nothing. It struggled to raise fresh equity at a deep discount last time (well short of the original amount it tried to raise, I know as a friend was inside on the deal). So next time, I doubt there will be any appetite at all to refinance it. Hence the bank probably now calling the shots. Small shareholders can at least salvage what’s left for a few pence, whereas bigger holders unfortunately are probably facing a wipe-out, sooner or later. It all now depends on what the attitude of the bank is. I imagine they’ll probably want a sale of the business, to recover some of their debt, which would probably leave trade creditors and equity holders with nothing. Who knows though, it could stagger on for a while, but the balance sheet looks insolvent to me. Management misled me previously, so I don’t believe anything they say. Complete bargepole stock, I’m afraid. I flagged, in strong terms, the likelihood of a 0p outcome here in July 2022. Previously, it had looked quite interesting, but subsequently turned out the forecasts were fantasy.
National World (LON:NWOR)
23p (up 24% at 09:35 - mkt cap £60m)
Trading Update - for FY 12/2022, this sounds positive, ahead of expectations. Revenue at least £84m (down 2% on 2021). Adj EBITDA ahead of market expectations at “not less than” £9.4m (ahead of forecast, but down 7% on 2021). Digital revenue up 25% (but fell to +12% in H2), print revenue down 7%. Maiden dividend coming (no figure given). Cost savings of £4m done. Cash £27m at end Dec. Targeted investments and acquisitions (looking mainly at digital businesses, eg 2 recent online content acquisitions, Scoopdragon, and Newschain).
Outlook for 2023 - “maintain our expectations”, but no figures given.
Dowgate’s updated forecast (many thanks) shows EPS of 2.6p for FY 12/2022, so a PER of 8.8 - not cheap for a structurally declining business, I would argue. However, the cash pile makes a big difference, as that’s 45% of the market cap. So the crucial question is what will be done with the cash in future, and that’s likely to drive shareholder value (or not).
My opinion - quite interesting. If experienced management is able to take this slowly dying newspaper business, and make something exciting out of it (on the digital side), then shareholders could do well. That’s not a bad bet at this stage, as the core business is generating plenty of profits & cash, and as we’ve seen with Reach (LON:RCH) the cash cow continues to pay out, as wave after wave of cost cutting is implemented. NWOR is also clean, with a small, but decent balance sheet, and no legacy problems such as pensions, which haunts RCH.
Equals (LON:EQLS)
93p (up <1% at 12:06) - mkt cap £168m
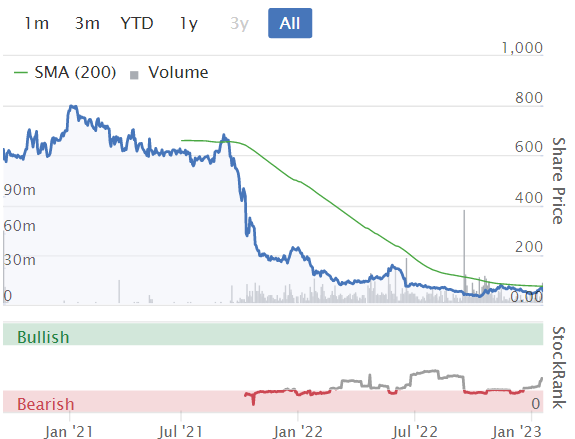
This share has had a great run since the covid lows, rising 4-5 fold. This has been driven by steadily improving broker forecasts, for both 2022 and 2023, as you can see -

I last looked at this forex/payments group here on 5 Dec 2022.
Trading Update today -
Equals Group plc (AIM:EQLS), the fast-growing payments group focused on the SME marketplace, announces a pre-close trading update for the financial year ended 31 December 2022 ('FY-22' or the 'year').
Very strong revenue growth of +59% to £69.7m (consensus forecast was £66.2m)
Adj EBITDA “marginally above” £12.0m (up 79%) - which is 6% above forecast from Zeus.
All very nice, but EBITDA is not meaningful here. That’s partly because the adjustment is to ignore £0.7m of share options costs (which is remuneration), reducing EBITDA for 2022 to £11.3m.
More importantly, there’s a depreciation charge of £1.4m, and a hefty £4.5m amortisation charge for R&D. As I mentioned last time, EQLS is a heavy capitaliser of development spend of about £4m pa, similar to the amortisation charge. So either way, we have to take this into account as a real world cost, and cash outflow.
Overall then, the £12.0m adj EBITDA is only expected to turn into adj PBT of about £5.0m, or statutory PBT of £3.7m (which includes a £1.3m charge for intangible impairment).
So I wouldn’t value this share using EBITDA, as you’ll over-value it that way.
Balance sheet when last reported was small, with NTAV of £12m. So not really any significant asset backing for a company valued at a market cap of £168m.
It’s an asset-light business model though, so this shouldn’t really matter, but worth bearing in mind there’s nothing to support the share price if earnings dry up (unlike asset-rich businesses like housebuilders or car dealers).
Although EQLS did have £15m in cash at end Dec 2022. It also previously (at end June 2022) said it had £272m in client cash, off balance sheet. So a key question (do any readers know the answer?) is who received the bank interest on this cash, now that interest rates have quite recently moved up from zero on cash held at banks? This could potentially be c.£5m interest receivable, if it all accrues to EQLS, which would be rather nice! It’s often not as simple as that, but it’s a key question to ask.
Outlook comments sounds upbeat -
The Group will continue with its strategy of investment in growth, platform and connectivity and the Board is confident of achieving a strong result for FY-23.
Diary date - 27 March 2023 for FY 12/2022 results, a Q1 2023 trading update, and it promises an audio webinar of the in-person analysts meeting will be published on the website later that day - very helpful.
My opinion - I’m certainly impressed with the growth here, and a move into profits in 2022. Although the adjustments and EBITDA numbers are not relevant, due to ignoring a load of costs (almost 20% of the payroll is capitalised, so that by-passes EBITDA completely!)
How you value the shares depends on what’s driving the growth, and a detailed assessment of the services offered by EQLS, and the competitive landscape, which is obviously not what I’m doing here - this is just a review of the numbers, which is only part of the puzzle when considering the investment case.
Overall, I don’t know enough to judge, but I do see signs of something interesting here at EQLS, hence it’s worthy of a closer look by readers.
THG (LON:THG)
57p (down 16% at 13:01) - mkt cap £760m
I don’t rate this share at all, but it’s come up on the top fallers list, so have to cover it. My review of the last interim results is quite detailed, and demolished the bull case.
Trading update - today is for FY 12/2022.
This is really complicated, and I’ve decided not to get into any of the detail. So just a few key points -
Discontinuing non-core activities - eliminating £20m pa losses.
Guidance for FY 12/2022 is £70-80m adj EBITDA. That’s down from £100-130m in the Q3 update, hence the plunge in share price today.
EBITDA is meaningless at this company, as it has large depreciation & amortisation charges, so in the real world, it’s going to continue making substantial losses.
Year end net debt of £200m (which excludes big lease liabilities), should reduce when £40m freehold proceeds received soon. It has plenty of liquidity, with a large cash pile, but even larger debt pile.
Outlook - some good things here, including -
Cost savings implemented should save £100m
US warehouse automation starts soon
“Substantially lower” raw materials prices (mainly whey)
“Broadly” free cashflow neutral in FY 12/2023, and “significantly positive” thereafter.
My opinion - it remains a big, loss-making business, that’s trying to sort itself out - not dissimilar to ASOS (LON:ASC) actually, but worse.
If the turnaround plans work, then profitability could become a possibility. But why would I want to bet on that happening? You’d have to do a lot more research to work out how likely it is that a decent business might emerge from this former tech darling, which it now transpires is a bit of a sprawling, loss-making mess.
Graham's Section:
McBride (LON:MCB) (£45m pre-market) [quick comment] - this European manufacturer of products for the “domestic household and professional cleaning and hygiene markets” gives us an update for H1 (that’s the period to December, since year-end is in June).Trading was in line with expectations. The company reports both price rises for customers and volume growth - it doesn’t say how much of each - resulting in overall revenue growth of 31% (at constant exchange rates, so the actual result could be slightly different).
Inflation continues to pose challenges; raw materials, energy and employment costs all rising to a greater or lesser extent. The company says that it will report “a small adjusted EBITA loss” for H1, which we can presume means that statutory net income will again be negative. Net debt at period-end was £169m.
With this level of net debt, and with the company making losses, I’m surprised that the company’s market cap remains so high. McBride was never a quality stock in the first place, and it’s now dependent on very high levels of bank funding which it is unclear how or when it might be able to reduce. Extreme levels of risk here.
Ramsdens Holdings (LON:RFX) (£69m) (+5%) [quick comment] - these full-year results for FY September 2022 are ahead of expectations as Ramsdens has benefited very well from the return of international travel. Unlike my favourite pawnbroking stock, H & T (LON:HAT) , Ramsdens makes a large percentage (33%) of its gross profits from foreign currency exchange, i.e. from people looking for holiday money, and these currency volumes have improved from £77m in FY 2021 to £364m in FY 2022. Full-year total revenues for Ramsdens are £66m and PBT is £8.3m (it’s not really worth comparing these results to last year, as last year was extremely poor and not representative of normal performance).
We also get a trading update for Q1 (October to December 2022). Interestingly there is still a major shortfall between the latest foreign exchange volumes and their pre-Covid levels, as volumes remain at just 70% of what they were before. But overall performance sounds fine and the outlook statement from the Chair takes a balanced tone as rising energy costs, staff costs and interest rates are balanced against the opportunity for increased pawnbroking business in an economy that squeezes household incomes.
I’ve been a long-term fan of this business, although never a shareholder, and I don’t see any reason to change my tune after these good results. Net cash reduces from £13m to £9m which is often a good sign in this sector, as it means the company is busier making loans and building up retail stock. The company’s broker has increased its FY September 2023 PBT estimate by another 5% to £8.9m, having already upgraded it last October. Up next is the company’s expansion into the South East of England, having traditionally stayed in Northern England, Scotland and Wales.
DP Poland (LON:DPP) (£59m) (unchanged) [quick comment] - since early 2021, this has been a much enlarged group after it merged with another large Polish pizza restaurant group. It also acquired Domino’s Croatia in a tiny deal (£2m). Today’s full-year trading update for FY December 2022 includes some impressive-sounding growth figures, including like-for-like sales in Poland up by 21%. The change in delivery numbers is modest but dine-in and carry-out sales were both up strongly in a post-Covid environment.
The company has just a small cash balance of £4m, which it has been using to fund store development, a TV advertising campaign, and other upgrades and improvements. Profitability is set to be “close to market estimates” for 2022. As for 2023, the company is hoping for improved trade from tourists and for inflation to stabilise, which it expects will boost both sales and profitability. Broker estimates for FY 2022 and FY 2023 are unchanged - these imply negative EBITDA in FY 2022, and a small positive EBITDA of £2.5m in FY 2023.
I’d like to be more positive here, after many years of terrible financial performance by this company, but I can’t get excited about a prospective EBITDA of £2.5m for a pizza business, when the market cap is £60m. The investment thesis here is that the new-ish management theme will be able to make this consistently profitable now that they have a much larger group and can enjoy the economies of scale that go with having over 120 stores. But even if they achieve LfL sales growth of 15% in 2023, they are still expected to earn only meagre profits. I also think it’s worth mentioning that Poland made it to the Round of 16 in the World Cup that we just witnessed, and this may have provided a temporary - artificial - boost to sales.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

67 comments
Medica (LON:MGP) trading update looked pretty good to me. Was slightly concerned at H1 and lack of radiographers but H2 has rebounded well as expected and looks like they have sorted capacity. Business in Ireland and US growing strongly too. PER of 13 for next year dropping to 10 in FY24 (with net cash at £15m) feels light to me for a business that is growing well both at home and internationally and with favourable long term market conditions.
It's up a bit today on recovery. I see analysts think 220p fair value, which for once I broadly concur with, so will hold. Anyone else have any views?
I've held Medica (LON:MGP) for a while, and tracked it for even longer. Am pleased with the SP reaction today of course. Had a quick skim of the results, will do more detailed analysis in the next day or two.
For me, several things jump out:
I don't quite have the broker optimism of 220p fair value, but definitely think 200p is achievable (in a bull market).
This along with Begbies Traynor (LON:BEG) are my two defensive plays, that will do well whether recession or not in 2023. But I would also say that the current pricing isn't cheap, but I don't think it is expensive either (otherwise would not be a holder).
(I hold in the Boon Fund)
Hi - I'm not sure why you think a PER of 13 for next year makes Medica (LON:MGP) not cheap? It's at a discount to peers and with a PEG of below 1 on a 17% expected eps growth I'd say it is undervalued for a stock with structural tailwinds.
How big are those tailwinds? Yes - population is aging. But is that single-digit or double-digit growth yearly, in terms of radiology scan required? FY22 and FY23 is going to be backlog-driven growth, but may not be from FY24 onwards.
Then just because demand for scans have increased, doesn't mean the actual volume of work that Medica (LON:MGP) will get will increase correspondingly. I have a dim view that NHS care will increasingly become rationed, wait lists longer. Many people will have to make do with longer waits between scans, or not at all. Because we cannot increasingly fund what is needed out of a weak-growth govt budget.
Are the number of radiologists in the UK growing at double digit rates to recruit? I don't know.
Yes - 13x forward PE is a decent price. But my assumption is single digit EPS growth rates for FY24-26 (3 years) and a max PE multiple of 16-18x (rich for the growth rate, but enough of a premium for the predictability of revenues and for the high margin), I'm not sure I would class 13x as Cheap (If the scale is Cheap>Undervalued>Fair>Overvalued>Expensive). Would say Undervalued is my opinion, in the scale above, hence why I'm still holding for now, but only target sell price of 200p-ish.
I'm not sure why you think a PER of 13 for next year makes Medica (LON:MGP) not cheap? It's at a discount to peers and with a PEG of below 1 on a 17% expected eps growth I'd say it is undervalued for a stock with structural tailwinds.
Optically cheap IMO but customer concentration is a worry along with the resourcing constraints. Competition in the niche could hit margins hard and fast should a bunch of hungry me-toos come chasing after the same experts around the world. And don’t rule out the disintermediation potential of AI, though that is not a short term risk.
Counterintuitively I think it’s a business I’d rather own 100% and be engaged in the thick of the action than sit at a distance on 0.001% extracting a rent.
Your thoughts on EQLS didn't do much for my decision making - have held since May 22, only 1% up and on my list to keep or dump
The one thing I disagree with Paul on for Equals (LON:EQLS) is the ebitda number being a wrong metric to use because of amortisation for R&D being £4.5m
CEO has been clear that there was a required investment in IT to scale the business over the last 24 months. That level of investment is not required into perpetuity though, so the ebitda (minus share based comp and some level of annual depreciation) is actually quite useful to see how the underlying business is performing.
Operational gearing has now kicked in too and CEO is talking about increasing margins - revenue is forecast at £80-85m now with ebitda around £16m. If we strip out say £3m for maintenance investment depreciation & share based comp then a normalised £13m PBT or £11m PAT feels about right- so maybe approx 14* PER as we stand.
I know Paul Hill thinks they are worth 150p. I own some and based on my won calcs am thinking north of 130p.
I don't know if that helps at all. The way I look at it is I want to see a 12m 25-30%+ upside if I continue to hold something. In this case I'm therefore happy enough to hold but you may have a different view of the forecasts/valuation metrics of course.
Surprised Equals (LON:EQLS) closed down 7.5% on the day. Seems to be a big fall just before the close.
Maybe a system glitch, upon opening today the price was around 92p, I was going to top up if still around 85p.
Completely unrelated to today's news but have been researching Robinson (LON:RBN) and see that there are no institutional holdings over 2% (if any at all) - this sems very unusual. The pension has gone, and it looks very cheap on most metrics, so perhaps a potential takeover target for one of the bigger packaging companies?
Plse excuse my extreme ignorance. I have always wanted to find a quick way to find out the holdings of company directors. Of course I know how to find out on Stockopedia their purchases and sales. And i also see them in the Investors Chronicle. The purchases and sales, especially the purchases, can be revealing.
But it would also be interesting to see the existing holdings of directors, to see what confidence they have in their company. It would be great if that can be found through the estimable Stocko. If not perhaps there is another easy way. Sometimes i have even struggled to find them in company reports.
It seems from the above that you may have cracked that this issue, and i may be missing something blindingly obvious. But that is often the case!
One way or another you have to pay for this amount of information, I do it through online Simply Wall St.
Check out the view buttons on the RHS of Shareholder Activity on the Stock Report.
Directors’ holdings should be stated in the annual accounts and if you then track directors’ sales and purchases since the last accounting date you should get an accurate picture of their holdings.
nettle - it should not be difficult to get this from the annual report. I randomly picked Medica as it has been discussed here today. Click on the link to the plc website on the stock report and then on 'investors' when you get there and then on the annual report. It was in the renumeration report:
The above is as at 31/12/21
Thence click on dealings in the stock report as you have found and add or deduct those - in this case just one deal:
many thanks for this v helpful, and for the others who so kindly bothered. Quite heartwarming! What a splendid example of this area of Stockopedia.
Hi Paul,
Noticed this LTIP for #NWOR (fully vest at 3.2p 24 EPS) - Seems reasonably interesting and set as if to be achievable perhaps! On a PER of 15 for that growth would give 100% upside from here !
https://otp.tools.investis.com...
Hi
Are you not mentioning KAPE which gave a TU today?
No, Kape Technologies (LON:KAPE) is above our usual top end market cap, it's £1.26bn.
RM group
RNS last night
New CEO mark cook receives nil cost share options on 873763 shares .
Quite a lot .
Not a fan of nil cost options .
Don’t come to fruition until 2026 to 2023 so admittedly long haul rewards .
Normally zero cost options wind me up , not sure on this one as it’s a big turnaround and he’s possibly been brought onboard encouraged by the likes of Christopher mills .
I’m on a 7% gain for a couple weeks and normally in these circumstances I’d Chuck all my teddies out the pram and sell up and move on .
Might keep the teddies this time.
PlanetX, you're mellowing or getting more pragmatic. Am still uneasy about the joint broker situation which often presages a fund raise and share dilution.
RM (LON:RM.) I too share your dislike of nil cost options; however, I also read last nights RNS & see that
“Sixty percent (60%) of the Award is subject to a performance condition
relating to the performance of the Company's TSR against absolute targets
ranging from 120p to 195p, with this condition also measured at the end of the
same 3-year period”
Today RM. is +3.09% to 63.4p which means the shares will need to at least double for him to get his money so let’s see
I’m +26% on my early December buy. I was tempted to top slice a few but am trying to sit on my hands and see what Mark Cook plans to do
NWOR
Another good update
My worst performing share continues to do well and continues to make some nice numbers .
Good acquisition of digital football assets the other week so finally deploying their cash like
Like a novice I cracked and sold 30% of my holding at the all time low of 15p
This is illiquid , thinly traded, and gets dragged down by Reach .
Always spikes after results then slips back
Loads of cash , loads of profit , good management albeit a bit self rewarding but the basket case of my portfiio .
They own the Sheffield star and Yorkshire post so that’s good enough to hold .
...and the Scotsman!
N Brown (LON:BWNG) - some hefty Director buys (from wealthy controlling family, so may not be that significant to them). The market seems to be reacting very positively to Director buying at the moment, so (as mentioned recently) even though I think BWNG looks a pretty rubbish business, the shares could be a nice rebound or takeover trade.
Got to say I am disappointed I did not see coming the affect of the strikes on retail business. I wonder what other businesses will be affected by the strikes.
It just goes to show that any retail business with a high debt stands a good chance of going bust. More pain for this sector and any other that relies on the public spending their spare cash as more results come in in the next year. Credit crunch will hurt these companies a lot. Even those with good cash will be affected imo, though they may survive the sp will drop. It will be a good time to make note of the good companies with the sight of buying when this sector turns around.
I, like many others have to sort out a new mortgage deal this year. Where the interest rate has dropped slightly recently, there are still plans to increase interest rates in the next 6 months which will mean the mortgage rates will still likely rise. If like me your mortgage is due in the next 6 months for a new deal, sort it out now and lock in a deal. It will not take affect until your current deal ends, and if by chance the rates do drop you can always scrap the deal and lock in another deal before your current one ends. So as for the house builders, I see more pain for their sp in the next 6 months still as the current situation has not shown up in results yet. When it does, it will be all over the news with doom and gloom and that imo will be the time to buy builders as their cycle runs 12-18 months ahead of the actual time.
Scary times!
Paul calls Unbound (LON:UBG) a "Complete bargepole stock" with a likelihood of a 0p outcome, and yet (as I type this) it has a Value rank of 68, Quality rank of 56 and Stock Rank of 45. Why the disparity? Why aren't the ranks all flashing red?
The StockRank for Unbound (LON:UBG) takes account of past performance across a range of metrics and broker forecasts. As Paul said:
Management misled me previously, so I don’t believe anything they say. [...] Previously, it had looked quite interesting, but subsequently turned out the forecasts were fantasy.
That's why the SCVR is such a valuable service, as a counterpoint to published forecasts. StockRanks are incredibly useful but they are only the result of a mathematical process at the end of the day. They can't incorporate experience and judgement.
Disclosure: I held Unbound (LON:UBG) briefly, lost around 25% on them and sold after losing confidence in the management. I would have lost a lot more had I held on.
Whitbourne, well done for losing only 25%. Wish I had!
Unbound (LON:UBG) was only ever a small position for me but is now infinitesimal at 97% down! As I said in a previous comment on the subject it isn't worth incurring the commission charge to sell it as that is nearly as much as the remaining value of the holding. Hardly buy a Costa Coffee!! The Private Equity team at @ Electra completely deceived the market with the flotation of Unbound (LON:UBG) and Hostmore (LON:MORE). The value of Electra at the time of the demerger of these two last remaining holdings of the private equity trust was around £5.50. Using Paul's simple model the current value of the combined businesses is around 40p - an effective loss of 93%!
However, until mid 2022 there was some fairly confident comment on Unbound (LON:UBG). Just a year ago Paul commented:
My opinion - I’d like to see the first set of proper numbers as a standalone listed company, before forming a clearer view. At the moment though, I like Hotter Shoes niche, and the market cap of only £26m seems a very gloomy assessment by the market.
It has been suggested that the price could be artificially depressed by forced sellers - some of the original ELTA shareholders are apparently not mandated to hold individual company shares, only investment trusts. In which case, we could have an opportunity to buy now, at an artificially depressed price - that’s just the sort of special situation that I like, buying a quid for 50p.
Personally I hold a small existing position here, and am waiting for more facts & figures, before deciding whether or not to increase my position (or sell, if the numbers are no good).
Clearly what transpired was a disaster and as Paul said in July 2022 the business was pretty much worthless so he followed through on his sell if the numbers are no good. As John Maynard Keynes reputedly said "When the facts change, I change my mind - what do you do, sir?". In the case of Unbound (LON:UBG) and Hostmore (LON:MORE) the facts most certainly have changed - though as Paul has mentioned the management and the private equity team,to put it mildly, must have distorted the facts from the very beginning. Remind me never to buy anything involving a sale by private equity in future!Same here, I also got caught on this one. I failed to act. I have had several previous successes with investment trusts winding up, and I treated this one the same, when in fact it was different - the assets were floated off, whereas in all the others the assets were sold, and the proceeds distributed to shareholders, which is a huge difference. Lesson learned the hard way (albeit within a managed risk model)
N.
Sorry Whitbourne, I find it hard to accept your explanation that even though the Stock Ranks are "only the result of a mathematical process" , which undoubtedly they are, it somehow excuses them from still being wildly misleading in January 2023, when the unexpected fund raise at 15p for Unbound (LON:UBG) was announced back in July 2022.
At the time (6 months ago) Paul said "Sadly, the only conclusion I can come to, is Unbound is now uninvestable.", and concluded his piece with "It fooled the StockRank system too, surprisingly". After Paul said that, the Stock Rank remained above 75 until September 2022, when it fell to 31, then rose gradually to its rank today of 45. If the Stock Rank can stay fooled and be so misleading for so long, how can we put any faith in any rank, for any company?
Luckily I never invested in Unbound, but it wouldn't surprise me if many people (including yourself perhaps?) were misled by the ridiculously high Quality, Value and Stock ranks for this company over the last 6 months.
I agree the maths should have perhaps had at least one red out of four greys.
The point for me is 'learning' how to use the Stockreport better and screening. For me the ROCE, ROCE, margin, F-score (under 6) and Z Score would have made me 'unbound' from looking at this further bearing in mind the number of winning companies out there. A loose rule is nothing under SR75 but that of course is is above the GARP/SCVR looking for the plays of the future.
I do not use the Stockranks to make investment decisions alone. They will be the last thing I would check and purely to see if there are any "alarm bells ringing".
Way before the final check I'd have looked at profits, debts, forecasts, history of earnings, RNS's & annual reports, cash, shares in issues (and history) and loads of other stuff.
You've got to be wary of something that relies purely on a system calculation alone, and whilst statistically holding a bunch of high SR shares will perform better than a bunch of low ranked SR's its almost like saying I hold shares starting with A-M and expect them to outperform those starting with N-Z.
Use it as a guide only, and combine it with whatever other metrics you think work and hopefully you'll do fine.
Quiz (LON:QUIZ) & Revolution Bars (LON:RBG)
Never have I never seen such positive commentary on two hopeless companies. These businesses seem to regularly go bust and someone loses money. They seem to have had the best years on government life support, is time to turn the light off permanently on these companies?
Definitely on my bargepole list.
As always DYOR.
BSV
I can understand your negativity towards Revolution Bars (LON:RBG) but not Quiz (LON:QUIZ) . Quiz has almost half of its market cap in cash and seems to be increasing its cash pile at a rate of £4m pa, ie in another couple of years it will be almost 100% cash.
Strip out its cash balance and you have a business with a tiny enterprise value of £10m turning over £100m, high margins, an estate on turnover based rents, the owners have large holdings, for me it has almost all the ingredients of a stock that should outperform over the medium term. It's just missing a generous dividend but I think that will come, I feel that they went on the defensive given the all impending doom and gloom in the retail market but that doesn't seem to have materialised yet...
Obviously I hold :)
£QUIZ
I think you are missing all the right off's the suppliers were forced to take, through the CVA., The second time the company went through a bankruptcy-like event. Of course, it is pretty easy to clean up a balance sheet if your creditors lose their money every so often. I am pretty sure this company will go through the same process again mark my word I give it 3 years.
BSV
I can see where your sentiment is coming from, on Quiz (LON:QUIZ) and Revolution Bars (LON:RBG) looking at their share prices. But on the other hand, both have survived the pandemic (albeit in RBG case needing big fundraising), which can't be said for many other fashion retail and hospitality businesses.
But they are businesses that can turn a profit. Agreed, might not be the "highest" quality, but at least they turn a profit.
My investment approach is more pragmatic. I don't do the easy strategies, like "buy the best quality companies" or "balance sheet needs to be rock solid" or "solid growth momentum with high operating leverage". Too many investors in these easy strategies. The gains, IMO, comes from being able to thread the needle where both "quality" and "balance sheet" and "growth" are not pristine, and requires a bit more thinking to get to a conclusion.
You still don't want to invest in a landmine that blows up and leaves you with a big 0. But you then hunt in shares that loads of PIs and Institutions just dismiss even looking at. Like RBG and Quiz.
Taking the case of RBG - it is now c£12.5m equity value and c£20m debt, so EV of £32.5m. It looks like they're running a total of 90 units, so the company valuation is c£360k per unit. If you think that each bar or pub needs about £300k+ of fixtures and fittings etc anyways (I am no expert, but this seems reasonable, and I foggily remember this ballpark mentioned by RBG when they do refurbs?) then it is trading at almost zero Brand and Organisational value.
Put it this way. If it takes £300k to fit out a new premise to make it a bar or pub. You could either build from scratch, 90 venues. Taking years and years. And lots of risk, time. Or you could buy RBG, and get thrown in a ready-made company, with a brand, management team, operations, and immediate trading.
Is it cheap enough yet? Probably not for my investment style. But for example, if the EV gets to like c£250k per unit, I would be tempted to invest. However, of course at that EV, the equity is almost zero if the debt is £20m, so that would then be a bargepole for me, as it will be hard to see shareholders not being wiped out with such a high debt load. However, it would be tempting for someone to take private - refinance the debt or convert into equity.
Wow, no idea there was an easy approach to investing, pray do tell me more about this approach, is this the new holy grail?
BSV
I know you're dripping with sarcasm, but there are easy investment strategies. Doesn't mean they're profitable though!
Ironically, we're on a website where one of their key customer props is to make investing easy - StockRank. One of the Stocko propositions is that you can just invest in the top StockRanks (90+) and it should outperform the market. Easy right? :)
Maybe not outperform - but not be a dud. A safety net. If get timing wrong and it falls back then comfortable being patient and it should move back to mean. A viable going concern, not blue sky stuff.
But that saying a portfolio of 90+ would be a bit boring and may as well stick it in a few ETF's - no da.
If you say so.
Keep getting burnt by RBG since floating they have kept going down, keep expecting a turnaround but seems to keep on failing to deliver. Buying Preach seems badly timed, getting a bit tired of the excuses, only decent trade was post covid for 12 months with no biomes rates, government grants, loans and a VAT reduction and the government paying for people to eat out.
Quiz (LON:QUIZ) - is this comment reflective in any of its strategic comments previously or is this just basically a made-up excuse?
The decline in online revenues through third-party websites was anticipated and in-line with the Group's strategic focus on growing sales through its own website.
I am wondering if this decline was actually due to postal strikes and maybe people deciding to go directly to Next (LON:NXT) stores instead of buying online? (Although that might not work for Very). Maybe there is also a potential negative read-across to Sosandar (LON:SOS)?
I think the Quiz (LON:QUIZ) update is OK. But +9% revenue on a pandemic affected period last year is not great when you factor in inflationary costs. With the cash balances and margin though it is attractive.
Patrick
Making notes on Freight & Logistics companies here and US. In London recently UK Mail have been dropping off owned by Deutsche Post AG (LON:0H3Q) and likely muscling in on International Distributions Services (LON:IDS). Clipper went to the Americans which leaves Xpediator (LON:XPD) and DX (Group) (LON:DX.
Competition is 'person in a van' but not sure these are all Redde Northgate (LON:REDD) vehicles.
Maybe a discussion blog poll on who see who where and in what location.
Once have that buttoned up will move onto warehousing Urban Logistics Reit (LON:SHED) etc.
As for physical shopping well I'm afraid Amazon.com (NSQ:AMZN) is my go to. SR38 worse than Unbound lol - not a cigar butt but possibly the whole box of Havanas.
Don't Wincanton (LON:WIN) and Logistics Development (LON:LDG) work in that sector?
Great results today from Equals plc and I will be adding to my position.
Zeus estimates for next year of revenues of about 84m are way too law. Equals is already generating revenue of 300K per day. The board will certainly be announcing a buyback programme.
Earnings estimates will easily be beaten for 2023 and this company is a genuine target for a takeover.
Morning yiannos1,
Thanks for flagging Equals (LON:EQLS) - it cropped up on my radar last year, after a series of good updates. I want to speak to mgt at some stage, when there's time, maybe after this busy run of year end trading updates.
Today's update sounds interesting, so either me or Graham will report back on it later this morning.
Regards, Paul.
Paul Hill conducted an interview with the Equals (LON:EQLS) CEO this morning following the results
&t=59sPaul
Equaks
Maybe ask Paul hill to arrange management to talk to you .
I know you know Paul and he seems very tight with those guys .
Equals is my biggest holding now, Not my usual stock but we use it at work and it’s better functioning than the Likes of moneycorp / argentex and has much better long term prospects if it can bridge the gap between buying / receiving / selling currency and holding currency accounts in multiple locations .
I have noticed though they can’t / don’t / won’t match the more regular currency traders on spot prices .
Nice company and seem to be hitting their numbers .
My morning smallcap tweet: Universally Challenged
Unbound (LON:UBG) Revolution Bars (LON:RBG) Naked Wines (LON:WINE) Corero Network Security (LON:CNS) Avacta (LON:AVCT) Pebble (LON:PEBB) Civitas Social Housing (LON:CSH) Ethernity Networks (LON:ENET) Quiz (LON:QUIZ) National World (LON:NWOR) Equals (LON:EQLS) Kanabo (LON:KNB) Niox (LON:NIOX) Renold (LON:RNO) £GMVH, Alliance Pharma (LON:APH), Medica (LON:MGP), McBride (LON:MCB), RPS (LON:RPS), Boku (LON:BOKU)
◄Unbound (UBG)► warns FY-Feb rev up only 3-4% and adj pretax -£4.25m to -£4.75m, below market expectations. Cost cuts. Outlook "Despite the short-term challenges experienced, the Group is well positioned for an enhanced Spring / Summer product portfolio launch". Well, that's a relief. [SP=4.15 Cap=4m]
◄Revolution Bars (RBG)► Xmas LFL down 9% on 2019 and H1 down 9.4% on 2019 as a whole. Blames hot summer, railway strikes and poor economic outlook. Guides FY IAS 17 EBITDA at the bottom end market expectations of £6.7-10.5m. [SP=NA Cap=NA]
◄Naked Wines (WINE)►guides FY-Mar adjusted EBIT £13-17m (previously £9-13m). Q3 rev flat but down 6% in const currency. [SP=NA Cap=NA]
◄Corero Network Security (CNS)► warns FY-Dec rev $20.1m ($20.9m), below market guidance. Blames "delays in customer decision making and buying cycles being extended". Adj EBITDA $1.4 - $1.8m. Order intake up 13%. [SP=NA Cap=NA]
◄Avacta (AVCT)► AVA6000 phase 1: "tumour biopsies obtained from six patients across several cohorts indicates that doxorubicin is being released within the tumour tissue confirming the tumour targeting potential ". [SP=NA Cap=NA]. I'm short.
◄The Pebble Group (PEBB)► guides FY-Dec at least in line with market expectations. Outlook: "Board is pleased with progress in both Facilisgroup and Brand Addition. We continue to invest significantly into the acceleration of growth in Facilisgroup". [SP=NA Cap=NA]
◄Civitas Social Housing (CSH)► enforcement notice in respect of My Space issued as expected. My Space is 1.3% of rent roll and is now in arrears. [SP=59.75 Cap=362m]. I'm short.
◄Ethernity Networks (ENET)► £1.55m placing at 7p, about par, to keep the lights on. Wanrns FY22 rev up only 10%. c. $600k delayed to FY23. "Rresources will be best utilised in these areas that will produce revenues and cash flows in the short and medium term...re-evaluating whether to continue the work with an Indian OEM customer which continues to experience repeated delays." [SP=7 Cap=5m]
◄Quiz (QUIZ)► guides FY-Mar profit at least in line with its expectations after Dec rev up 11%. [SP=15.67 Cap=19m]. I hold.
◄National World (NWOR)► guides FY-Dec rev £84m+ (in line) and adj EBITDA ahead of market expectations. H2 digital rev up only 12% due to "market and audience volatility, combined with the impact of changes to Google's search algorithm". A lot better than Reach (LON:RCH) last week. Mitigated by stronger yields and increased video advertising. Maiden div. [SP=22 Cap=57m]
◄Equals (EQLS)► guides FY-Dec rev up 59%. adj EBITDA up 79%, ahead of market expectations. [SP=94 Cap=170m]
◄Kanabo (KNB)► two new medical cannabis products for patients with severe pain. [SP=1.87 Cap=8m]
◄NIOX (NIOX)► guides FY-Dec underlying revenue growth of c.15%. Adj EBITDA c. £7m, ahead of mkt expectations. [SP=43 Cap=164m]
◄Renold (RNO)► wins 7 yr contract for £8.7m. [SP=26.92 Cap=61m]
◄Grand Vision Media (GMVH)► knows of no commercial or operational reason for the SP rise. [SP=NA Cap=NA]
In line: APH, MGP, MCB, RPS, BOKU
Hi MrC,
what is your reason for being short Avacta (LON:AVCT) out of interest? has today's announcement changed your view?
1. US pharma Arisaph did trials of the similar ARI-6000 FAP-activated doxorubicin in 2014 but we heard nothing of it after Phase II.
2. Only c.3% of candidate oncology drugs become approved.
3. Avacta (LON:AVCT) loudly trumpets the form of another horse each time the one it's backing disappoints: covid tests, Affirmer tech.
4. Co burning c.£20m PA even after acquisition of Launch Diagnostics. Likely to need more cash in 2024.
5. Last fund raise was a death-spiral.
6. It was the top pick in Stockchallenge 2023. High correlation with losers.
It is a risky short though.
National World (LON:NWOR) update EBITDA expected to be over £9.4m, shares up 16%.
Absolutely amazing news from Avacta (LON:AVCT) this morning:
"AVA6000 continues to be well tolerated by patients in cohort 4 with a marked reduction in the incidence and severity of the typical toxicities associated with the standard doxorubicin chemotherapy administration."
"Importantly, even at the highest dosing levels in cohort 4, equivalent to more than double the normal dose of doxorubicin, the typical drug-related cardiotoxicity of doxorubicin was not observed."
"Additionally, analysis of tumour biopsies obtained from six patients across several cohorts indicates that doxorubicin is being released within the tumour tissue confirming the tumour targeting potential of the pre|CISIONTM technology."
Strange the cure for cancer has gone up massively; only 14%...
Only on Phase 1a, got a long way to go to: a) prove this is the cure and b) get to commercialisation. My gut feeling is the SP will probably drop between now and Science Day on 23rd Feb. If this is to go anywhere it clearly needs a buyout or institutional investors to get involved.
But fantastic news, a step in the right direction and a time to reflect on the 19 people who have volunteered themselves to be guinea pigs for this cancer treatment. If this does prove to be a cure then we will forever be in their debt.
Morning ! Full year results for Ramsdens Holdings (LON:RFX) today and it looks like quite a big beat...forecast net profit was £4.2m and it has come in at £6.6m...with a similar beat for EPS...
Thanks, I didn't pick up on that, will take a look.
Positive updates by Quiz (LON:QUIZ) and Renold (LON:RNO) this morning. I hold Quiz (LON:QUIZ) and was thinking of buying Renold (LON:RNO).
Will you be covering either of these today Paul? Thanks.
Morning Revs8,
Yes I always cover Quiz (LON:QUIZ) and it's one of my watchlist ideas for 2023. Quick section now up.
Renold (LON:RNO) (also a top 20 watchlist idea of mine for 2023) is only a contract win, £8.7m spread over 7 years, doesn't look at all material in terms of revenue, so no I won't be covering that. Although it might be more significant in terms of profit maybe? CEO calls it an "excellent long-term contract", which I take as implying it must have a decent profit margin built in, but that's guesswork.
Just over £1m pa revenues isn't significant, given that Renold is forecast to do over £200m revenues this year. So not sure why they RNSd it?
Regards, Paul.
Any views on THG Paul as it is now a small cap?
THG is on the list!
any views on Inland Home?
any views on Inland Home?
The clown that ran this thing for years managed to create no shareholder value during a 15 year residential property boom.
Recent CEO has bailed out after a few weeks in the job.
That makes me very wary of INL.
THG (LON:THG) - one of those wait two years for all the promises to hit reality and value remain. Softbank baled out by Quatar sovereign wealth who see something to their advantage. Mr Moulding still holds a large stake and must have lost a lot of money along with others. The US Dermstore is of interest and its IT Ingenuity offering. Protein and vitamins is good, lots of youf weight-training (UFC and influencer Rogan maybe). Beauty products is a popular space. Lots of parts so needs a deep dive.
Yes, the Reynolds contract hardly seems worth RNSing, but perhaps this bit suggests the significance may be larger than this contract alone?
The contract award represents a significant extension of the Group's collaboration with BAE Systems for the supply of flexible couplings for naval vessels. Production of the couplings is expected to commence in early 2023, and will be machined on a new machining centre which was installed in Renold's Cardiff facility in 2022, specifically for naval programmes.
They are clearly hoping/expecting that this may be the first of more orders for these new (or modfified) naval couplings?