Small Cap Value Report (Tue 17 Nov 2020) - EZJ, SAGA, BOO, IGP, G4M, TUNE, EYE, SCPA, CRW

Good morning, it's Paul here with the SCVR for Tuesday.
Timings - update at 14:07, I've been working since 7am, so am having a break for now. Will come back later to finish off.
Update at 16:10 - I'm back at my desk, so finish time now likely to be 6-7pm, as there's lots to cover still. Update at 18:24 - that's me done, today's report is now finished.
Many thanks for all the thumbs ups for yesterday's report. People seem to like it when I do a personal portfolio review, maybe I should do those more often? Remember I only covered my top 10 holdings yesterday, to focus on the main conviction longs I hold. There are about another 18 holdings, making up the remaining 23% of my portfolio not included in the top 10 positions. Maybe we'll have a look at those on a quiet day.
Easyjet (LON:EZJ) - interesting comment from its CEO a moment ago on CNBC. He said that lockdowns are increasing pent-up demand. It seems to me that 2021 could be a bonanza year for travel companies, once they're allowed to start operating freely again. The elderly could be widely vaccinated by the spring or summer, and many of them love cruising. This is a key reason why I'm so keen on Saga (LON:SAGA) shares ( hold), as mentioned yesterday, as it has clear multibagger potential, once its 2 brand new cruise ships can begin generating cash again. The current market cap doesn't make any sense to me.
Boohoo (LON:BOO) - I hold - Last night Sky news reported that BooHoo has made the first of two heavyweight NED appointments, to improve its ESG (environmental, social, and governance) credentials. This was confirmed on the RNS today. Hopefully this might be the start of a comeback for the shares, since it's clear that BOO is serious about making changes being demanded by journalists, and I imagine some institutional shareholders in private.
Judith MacKenzie was recently interviewed in a MelloMonday session, and she emphasised just how important ESG is to fund managers now. That must be why the share price fell so far, on re-hashed news about its supply chain, and the auditor resigning because of reputational worries (nothing to do with the accounts, as it had repeatedly signed off clean audit reports).
ESG - This ESG issue could present us with more opportunities. It might lead to fund managers bunching into the same stocks (and them becoming over-valued as a result), but avoiding some good companies on ESG concerns. The most entrepreneurial companies, which perform best, often have dominant founder/CEOs who flout governance guidance/rules. If those shares are going to become cheaper, as fund managers avoid them, then that sounds rather interesting to me. I suppose the key issue is for us to assess whether ESG breaches are serious, or just part of a company still being entrepreneurial?
Improving trends - it's interesting how almost all of the companies I am reporting on here, are now reporting business steadily improving this year, and looking like it's gradually returning to normal. Not in every sector, but in most. For this reason, I think the strong market recovery in recent weeks is justified, despite worsening pandemic numbers on the news every night. Most businesses seem to have found work-arounds, and the second lockdown is not as severe as the first. Also, bear in mind that the stock market has very little of its total market cap in those most vulnerable sectors, so I think the pain is mostly being felt by private companies, and small businesses, not so much for listed companies.
Agenda - there are lots of interesting announcements today from companies I like, so it should be a busy day;
Intercede (LON:IGP) - contract win (I hold)
Gear4music Holdings (LON:G4M) - Interim results
Focusrite (LON:TUNE) - Final results
Scapa (LON:SCPA) - Interim results
Eagle Eye Solutions (LON:EYE) - AGM statement
Craneware (LON:CRW) - AGM statement
That's all I can do in one day. Sorry I ran out of time, so didn't get round to looking at DOTD or SYS1.
.
Intercede (LON:IGP)
Share price: 92p (up c.3% at 08:22)
No. shares: 50.5m
Market cap: £46.5m
(I hold)
Contract win - follow on purchase order
Intercede is a cybersecurity company specialising in digital identities, credential management and secure mobility. Headquartered in the UK, with offices in the US, we believe in a connected world in which people and technology are free to exchange information securely, and complex insecure passwords become a thing of the past.
This contract relates to the project from Guidepoint, which includes Intercede software as part of a package. I delved into this impressive contract win with the Department of State, in the USA, here on 30 July. Things must be going well, because a follow-on order of considerable size has been received;
Further to the contract win that was announced on 30 July 2020 and the receipt of an initial progress order that was announced on 20 August 2020, Intercede, the leading specialist in digital identity, credential management and secure mobility, is pleased to announce the receipt of a follow-on purchase order totaling $2.8m. The order includes software licenses and associated development, professional services and support & maintenance; the majority of which will be recognised in the current financial year ending 31 March 2021...
That sounds great, but before we get too excited, it was already included in the current year forecasts.
.
Gear4music Holdings (LON:G4M)
Share price: 715p (up 5%, at 08:59)
No. shares: 20.95m
Market cap: £149.8m
Gear4music (Holdings) plc, ("Gear4music" or "the Group") (LSE: G4M), the largest UK based online retailer of musical instruments and music equipment, today announces its unaudited financial results for the six months ended 30 September 2020 ("the Period").
There are two musical equipment companies, both reporting sparkling numbers & outlooks today, G4M, and TUNE. As Patrick Leahy comments below, the big question is how much of this year’s superb performance has been driven by covid/lockdowns, and how much is sustainable? We don’t know yet.
Here are my notes from the half year trading update provided on 22 Oct, where full year expectations were raised again.
Remember that G4M’s strategy this year has been to seek margin improvement ahead of revenue growth. The good news is that it’s delivering both, which combined have given a very strong increase of 61% in gross profit, and a move from breakeven last H1, to strong profits this H1, also helped by efficiency gains on overheads.
Current trading - excellent;
Very strong trading patterns have continued into November
Bear in mind that we have renewed lockdown for physical retailers in England, plus Black Friday coming up, Fri 27 Nov, according to Google. I reckon this should mean that eCommerce companies should see a bonanza, giving another boost imminently to G4M, and all the other eCommerce leaders, like Asos, BooHoo (I hold), and many others.
Retailers which have not integrated their online warehouses and physical stores, could end up with serious over-stocking problems in their stores once lockdown ends. There should be plenty of bargains in the January sales for consumers. Plus maybe a lot of insolvencies in January to come?
These numbers for H1 look really good, especially as it’s normally the seasonally softer half. Although bear in mind that Q1 (lockdown) was stronger still, at +68% revenue growth. So Q2 looks to have slowed somewhat from that very rapid growth previously;
.

.
Outlook - the key part says;
I am pleased to report that trading into November continues to be very strong, and we are well positioned for what we expect to be a busy peak trading period ahead of us. We therefore expect that results for the financial year will now be ahead of the recently upgraded consensus market expectations. The Board remains focussed on prioritising profitable growth and continues to look forward with confidence over the medium term."
As last time, it’s a pity they don’t provide a footnote to save us time, giving the figures for consensus forecasts. Plenty of companies are doing that now, and it’s a simple thing to help investors.
Labour costs - a point that stands out, is that labour costs have reduced from 9.4% of sales, to 7.8% of sales. So the business is becoming more efficient as it grows.
The same is true of marketing spend, down from 8.0% to 5.3% of sales. This was always the bull case for this share - that as it reached scale, profitability would come through, from reducing costs as a % of sales, and improved gross margins. That’s exactly what is happening, so it’s good to see a plan come to fruition.
Balance sheet - no issues here, it looks OK to me. NAV: £26.6m, less £9.6m intangibles, gives £17.0m NTAV That’s fine, since being an online retailer, G4M is paid in cash by its customers (i.e. little to no receivables). Hence as it grows, that doesn’t put a strain on working capital.
Net debt of £5.7m looks fine.
Cashflow - again looks OK to me. Note that it capitalises c.£2.8m p.a. in development spend, so EBITDA is meaningless.
My opinion - I remain very positive on this company. As readers have commented, forecasts for this year look too low. It has achieved 23.6p EPS in H1, and H2 is usually stronger. Although seasonality this year could be different, due to the lockdown boost in Q1, maybe?
Is it possible that the company might achieve 40-50p EPS this financial year? Who knows, but I think that’s within the realm of the possible.
The ridiculous bid/offer spread of 700/730p are not the real prices. I just checked with my broker, and there are 5k shares available on the bid and offer, at 711.5p/722.5p. So a real world spread of 11p, not the 30p quoted on price feeds. Why on earth do the market makers do this? It’s madness, because people see a 30p spread, and it puts them off buying or selling. So why don’t they just publish the real prices, with the actual 11p spread, which would help everyone including them, by generating more market activity!? What a ridiculous system.
Anyway, my view remains positive on G4M. Even though covid/lockdown has undoubtedly boosted this year’s numbers, I think the shift to online purchasing is probably permanent. Physical stores can’t compete, with more likely to disappear each year. They also can’t hold such a huge range (over 50k lines), nor have the scale to do own brand stuff cheaply, as G4M does.
I think the strong share price for G4M looks justified by its superb performance this year.
EDIT: the house broker has upgraded FY 03/2021 to 33.7p, a PER of 21.2, but the narrative in the note suggests the outturn could be higher still. Next year's forecast of 20.0p is clearly irrelevant now, so I'm ignoring that. Could be good upside here still, I reckon. End of edit.
It’s now recovered rapidly, to not far off the previous highs;
.

.
Focusrite (LON:TUNE)
Share price: 936p (up 2.4% at 10:22)
No. shares: 58.1m
Market cap: £543.8m
Another music equipment company, benefiting from the trends mentioned above. Although note that TUNE has also seen some reduced demand from covid/lockdown, e.g. from one of its smaller subsidiaries that does speakers for large events, or meetings.
Focusrite plc (AIM: TUNE), the global music and audio products company, announces Final Results for the year ended 31 August 2020.
As you can see below, the adjusted numbers show very strong revenue and profit growth. The organic revenue growth appears to be about 21.5% (highly impressive!), which I’ve calculated from a table shown in the commentary. The rest of the growth has come from acquisitions.
.

.
The adjustments of £15.1m are so large (statutory profit is actually down from £13.0m to £7.0m), then we need to take a close look at note 5 which says;
Note 5 gives the detail on adjustments to profits;
.

.
This looks fairly reasonable. The two highlighted items at the bottom total £13.2m, which is all related to goodwill/similar type charges, which is fine by me, I ignore those completely anyway.
As with all acquisitive groups, we have to take it on trust that only genuine one-off costs end up in the adjustments section. There is a risk at all such acquisitive groups, that these could become soft codes, for other costs to be booked to.
Assuming everything is alright on the accounting front (I have no reason to suspect otherwise, just to be clear), then these numbers looks really strong.
Profit before tax margin is very good, at 17% - indicating strong pricing power.
Adj diluted EPS rose over 53% to 32.8p - a fantastic result. This gives a PER of 28.5 - which looks fine to me, considering such strong earnings growth was achieved, and assuming growth continues.
Balance sheet - only has about £9m of NTAV, but that’s fine considering it has hardly any fixed assets (only £4.1m, if we ignore intangibles). The business is highly profitable & cash generative, which it is spending on acquisitions. So far, so good!
Cashflow statement - looks very impressive, but it has been helped somewhat by favourable working capital movements, which might unwind next year, as they often do.
Note it has capitalised £5.6m in “purchases of intangible assets” which sounds like development spend. Nothing wrong in that, but you need to adjust for it when looking at EBITDA, which would be inflated. The development spend also helps reduce the tax charge, due to R&D enhanced relief as noted in the commentary, which is helpful.
Outlook - the usual warnings are made about covid & brexit uncertainty, which is standard stuff we see in all company results at the moment.
I particularly like the comments about new product pipeline, and more acquisitions coming (although they need to be careful not to over-pay)
Since the year end, demand for most of our Group products has remained high and revenue is substantially ahead of the level achieved in the similar, pre-COVID-19, period of the prior year, helped by the acquisition of Martin Audio...
...We look forward to another year of product innovation with many new products and solutions coming to market across all three of our business groups.
My opinion - this looks a terrific group, and I’m highly impressed with the numbers published today. The outlook also sounds encouraging.
The highish valuation looks perfectly justified to me. Well done to the company, and shareholders!
I could see this share going higher longer term, once it’s taken a breather for people to bank some profits maybe?
.

Eagle Eye Solutions (LON:EYE)
Share price: 402p (down <1%, at 13:22)
No. shares: 25.75m
Market cap: £103.5m
Eagle Eye, a leading SaaS technology company that creates digital connections enabling personalised, real-time marketing through coupons, loyalty, apps, subscriptions and gift services, is pleased to provide the following update ahead of the Company's Annual General Meeting ("AGM"), to be held at 12:00 p.m. today.
It starts off by summarising previously announced contract wins with Woolworths in Australia, and the coffee subscription offering from Pret;
… positive start to the financial year ...underpinning the Group's continued growth.
The company’s year end is 30 June 2021, hence Q1 is July, Aug, Sept 2020. This is all self-explanatory;
While COVID-19 has continued to impact revenue growth, the Group nonetheless delivered revenue growth for Q1 FY21 of 11% on the prior year. The ongoing strategic management of the cost base and investment in line with revenue has resulted in a substantial increase in adjusted EBITDA profit for Q1 FY21, comfortably in line with management expectations.
The Group continues to benefit from high levels of recurring revenue and extremely low levels of customer churn.
Cash management continues to be strong, with the full headroom within the Group's £5 million banking facility with Barclays available at the end of Q1 FY21, ahead of management expectations and sufficient to support the Group's existing growth plans.
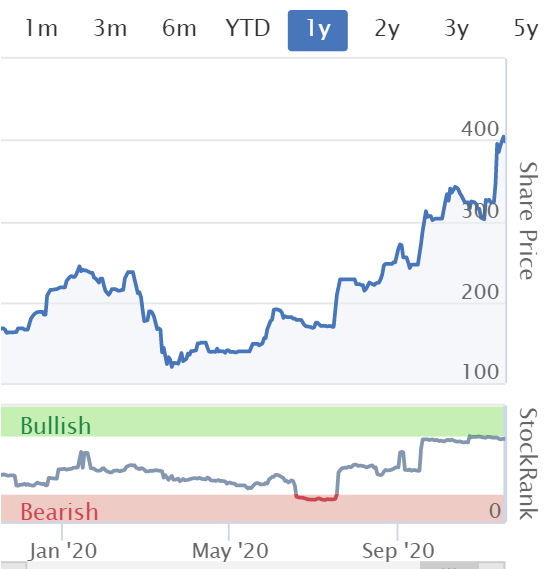
Q1 revenues growth of 11% looks slower than the 18% revenue growth in the consensus forecast figure shown on the StockReport.
Aus/NZ progress is to be used as a springboard for wider expansion in Asia, so “investment” will increase, i.e. more overheads.
USA sales pipeline is good;
The Board is encouraged by the increasing number of sales opportunities entering our pipeline, both through our direct marketing activities and via our partners in the US.
It mentioned being in phase 3 of an 8-stage implementation for one customer. This reinforces that these are complex, and time-consuming contracts to implement, as discussed in a previous SCVR. That concerns me a bit, because it seems to cap the amount of growth the company can achieve each year, and the danger is that decent profits might be pushed out each year, as more revenue sucks in more discretionary spending, maybe?
A cautionary note on lockdown;
However, with new lockdown restrictions recently introduced the Board anticipates this segment of the customer base and revenue will continue to be impacted for some time. Likewise, whilst the Group has a growing number of opportunities domestically and internationally, the Board anticipates that new customer discussions may continue to be protracted in the current environment.
Outlook - this seems to be saying that the Q1 growth shortfall should be recouped later this year;
… This provides an expanding opportunity and is expected to drive accelerated growth in the remainder of the year, in line with management expectations. The Group will continue to invest in its people, product development, sales and marketing, and in new geographies in line with customer demand, whilst carefully managing the business and cost-base, to capitalise on this momentum.
My opinion - there’s a lot I like about Eagle Eye. Clearly an excellent product, which has been sold to major retailers around the world, with low customer churn & high recurring revenues. That sounds great.
But, it doesn’t make any money! Nor is it forecast to in the current, or next year. This does make me question the valuation, which has now gone over £100m, after a spectacular year for the shares.
Do profits matter, when you could see this as a land grab for market share, and to become a dominant global business in digital vouchers, etc.? We’ve seen with many (particularly American) tech companies, they’ve expanded relentlessly, and not even tried to make profits in the short term, and have subsequently become very valuable businesses once they have achieved market dominance. That is a perfectly reasonable argument for EYE to just target breakeven at worst, but prioritise growth instead.
I can see the merit in both bull and bear arguments, so will say that I’m neutral.
This type of business could possibly have considerable value to an acquirer perhaps, as a backdoor way into many large organisations, for their client relationships, cross-selling of other services, etc. Or for another IT business to bolt on EYE, and accelerate its sales growth as part of a larger organisation. So a takeover bid wouldn't surprise me.
.
.
Scapa (LON:SCPA)
Share price: 162p (up 7%, at 16:26)
No. shares: 187.8m
Market cap: £304.2m
Scapa Group plc (AIM: SCPA), the diversified Healthcare and Industrial company focused on bringing best-in-class innovation, design and manufacturing solutions to its customers, today announces its unaudited financial results for the six-month period ended 30 September 2020.
The opening summary says;
First half results ahead of COVID-19 plan
Revenue and profitability expected to continue to improve in the second half
That’s great, but on my first skim of the numbers before 8am this morning, I did wonder if the results/outlook are good enough to justify the big recent rise in share price? Or whether subconsciously, I’m annoyed with myself for panic selling when it dipped below 100p a few months ago, despite being bullish on the fundamentals?! I’m sure most investors know that feeling. It’s really important to root out and destroy all such emotions, as it could cloud my judgement and lead to a second error, of missing a good buying opportunity now, possibly.
.

.
Results that include the first, more severe covid lockdown, are of limited value. All I want to see is that the company didn’t generate horrendous losses. That seems to be OK here;
Trading profit1 of £5.5m (2019: £14.2m) impacted by reduced volumes but offset by targeted cost savings and government subsidies
My next checklist item is that liquidity is OK, which it is here;
Adjusted net debt2 reduced to £21.8m (31 March 2020: £54.4m) due to reduction of working capital and net proceeds from the equity placement in May 2020 of £31.6m
Bear in mind that receivables & inventories are likely to go up again as business recovers, so future net debt might rise, but it doesn’t look a problem at this sort of level, given the size of the business.
Finally, my third checklist item is that trading is improving, and heading back towards pre-covid levels;
· Return to pre-COVID-19 demand levels in Industrial and encouraging progress in Healthcare are driving momentum
· Whilst uncertainty remains given the recent global resurgence of COVID-19 infections, revenue in both divisions in H2 is expected to exceed H1, with earnings benefitting from additional volumes and cost improvement programmes already implemented
· As a result of this momentum, we continue to track ahead of our COVID plan
There is a fly in the ointment with Scapa that it lost a lucrative contract with ConvaTec, which is subject to a highly material legal claim by Scapa against ConvaTec. I’m reluctant to buy this share when such a big legal action is underway. If it goes in Scapa’s favour, it would be fantastic, but there’s no guarantee it will.
Valuation - where might future earnings be heading? Without the ConvaTec contract, who knows? Maybe 10-15p future EPS? Although remember the share count has gone up from c.155m shares to 188m, due to the placing, a rise of 21% - quite significant. Therefore I should reduce my estimated future EPS range by a similar figure, taking it down to c.8-12p.
What PER to use? It’s quite a good business, with a sound balance sheet, so I think 15 is reasonable. That gives me a target share price of 120-180p. With the price currently 162p, then it doesn’t look there’s much potential upside here, using my valuation method.
Broker forecast for next year (the lighter coloured line below) is in the same ballpark as my estimate, which reinforces my figures;
.

.
Therefore the main upside for this share, is if you think it can not only recover to pre-covid levels of profits, but beat them. How feasible is that? Not sure.
Balance sheet & cashflow statement - I’ve quickly reviewed both, and they look OK to me.
My opinion - I liked this share more on a valuation basis, when it was sub-120p. Now it’s risen to c.160p, a rise that I feel was justified, it’s probably sitting at around what I consider to be a fair valuation. Hence not enough upside to get me interested in buying back in.
Upside could come from future earnings beating expectations, and/or the market deciding that a higher PER is justified. Or a takeover bid maybe? Or a favourable outcome in the big legal case.
I just see better alternatives elsewhere - e.g. Volex (LON:VLX) (I hold) which looks cheaper on a PER basis, and is growing profits rapidly, paying divis, and making great acquisitions. So why choose Scapa instead of that?
The StockRank is similar to my view - a reasonably good company, but all a bit grey. I want bright green!
.

.
Craneware (LON:CRW)
Share price: 2150p (up 12% at market close)
No. shares: 26.83m
Market cap: £576.8m
Craneware (AIM: CRW.L), the market leader in Value Cycle software solutions for the US healthcare market, is pleased to provide an update on trading ahead of its Annual General Meeting taking place at 10am today.
Trading update for FY 06/2021 to date -
The first four months of this fiscal year saw a return to strong sales growth, considerably ahead of the equivalent period of the prior year. Results are ahead of management expectations for this stage in the year and, we expect revenues and adjusted EBITDA for the Interim period to 31 December 2020 to be ahead of the equivalent period in the prior year, building the foundation for a return to double-digit growth in the future….
We continue to see substantial new opportunities entering the sales pipeline and the Board is confident in the continued strong performance of the business.
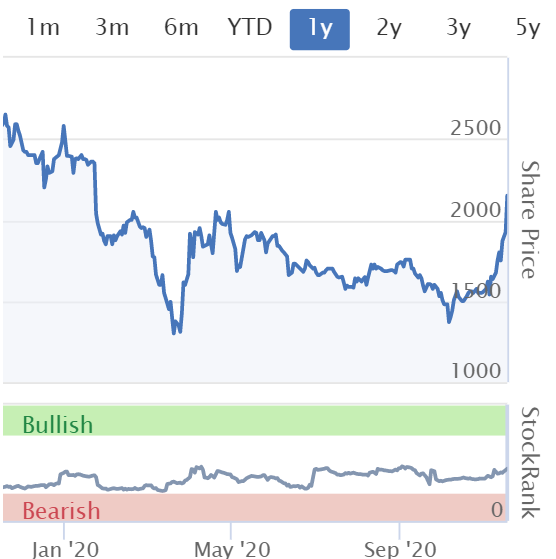
Checking my notes here from Sept 2020, I was concerned that the business looked expensive on a PER basis, and might have gone ex-growth. Today’s update addresses the growth concern, with good growth returning apparently. That’s pleasing, because growth has been lacklustre for the past 3 years.
My opinion - it’s a pity, as I was starting to get slightly interested in this company when it had fallen to about 1600p, but the recent surge to 2150p takes it well out of my range, in terms of valuation.
.
.
That's me done for today! See you tomorrow.
Best wishes, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

84 comments
Hi. Maybe I'm being uncharacteristically thick but I'm trying to find the Saga article in the above report. It's highlighted in the alert email.
I don't think you are being thick M10GUV but I can't see the comment about £SAGA either. What's more, I'm sure there was something about it here when I looked yesterday!
There is a comment under the Easyjet (LON:EZJ) for Saga (LON:SAGA).
Gear4music Holdings (LON:G4M)
I'm interested in hearing thoughts on the decline in email subscribers since last year (from 717,000 to 708,00,0 - i.e. a decline of 9,000 emails).
It seems such a small, irrelevant thing to focus on, but it's stopping me from pressing the buy button.
The company states that the decrease is due to GDPR and logging in functionality, but the sceptic inside me doesn't buy this when Active Customers has increased by a whopping +23% (181,000 customers.)
The only thing I can realistically think of is that Active Customers (defined as those that have made a purchase in the last 12 months) only went up because old customers who hadn't made a purchase for at least 12 months came back to the platform and the company already had their email addresses.
I'm not even sure if this is an issue when the company is growing so rapidly, but it would have been nice to have clarity on the proportion of completely new customers.
That aside , I really like the cash flow and that (most of) the numbers are pointing in the right direction.
Bystander for now.
A
"Many thanks for all the thumbs ups for yesterday's report. People seem to like it when I do a personal portfolio review, maybe I should do those more often?"
Absolutely!!
Focusrite (LON:TUNE) is one of those companies that haunts me. I bought back in May 2017 at 265p but I am not sure why and sold in October of the same year at 251p through boredom. What a mistake that was.
I would like to re-buy and must stop anchoring to the price I paid and see if it is still a great company at a reasonable price?
Regards
Michael
FREng - I saw the same and wondered if it is because it is normalised not statutory reported profit that is 6.0Mn - so it maybe implies brokers see some exceptional costs, perhaps arising from Corona virus costs or write downs/provisions.
I have believed to now that MCL e relatively books were conservative and quality focused (vs NSF which I own). But maybe they will have to take a write down on the Shopacheck acquistion given how low the whole sector multiplers have dropped! You really cant get a more hated sector now that sub prime lending. (Non-standard Finance (LON:NSF) had to write off ALL remaining value in ALL its subsids at the last set of results, partly for this reason)
Alternatively, they may have write downs on loans in the new digital division from i) Switching to a new provider from Wirecard - eg writeoff of software
Either way, if normalised profit remains positive it implies (to my limited understanding that the core business has not incurred huge losses and thus should be able to come back over time.
I am long Morses Club (LON:MCL) but nervous that the results have been delayed to the 11th hour so that the impact of corona can be calculated.
On Morses Club (LON:MCL), the consensus view - as Zipmanpeter says in his post - is that the delay in publishing the finals for the 53 weeks to 29 Feb 2020 is bearish. But there is a contrary view which I think is better (although as always DYOR).
The bullish view on delay is that MCL had their year end figures reasonably to hand because they published a detailed trading update on 11 March and said that the finals would be published on 30 April.
The long delay - as Zipmanpeter notes - is down to calculating possible impairments from COVID.
MCL applies IFRS 9 and therefore recognises impairments in its receivables (i.e. it "bakes in" impairments when the loan is made) and it used an impairment rate of 19% in FY 2019. Now, it would have been straightforward for MCL to increase the 19% figure to account for COVID (as, for example, S&u (LON:SUS) and Provident Financial (LON:PFG) have done) and get their accounts out.
Perhaps they can't reach an agreement with their auditors and have been haggling since April.
But the bullish thesis is that since the average loan duration is just over 6 months MCL have been using the extension for filing accounts to analyse the out-turn on the loans. This analysis of what actually happened with the loans would then (on this thesis) inform the judgement about the correct impairment figure for receivables due as at 28 February. For example, IMO it wouldn't give a true and fair picture to use an impairment figure of 35% if the actual outturn from the loan book as at 28 February was 25%.
If this hypothesis is right, it seems bullish because MCL would presumably not delay the accounts if it expected a worse outcome in terms of impairments than making an estimate as S&u (LON:SUS) and Provident Financial (LON:PFG) have done.
This is a very testable idea as the results are due by 28 November.
Hi Paul sorry to take you back to yesterday,s SCVR but I have only just read it . I looked at £Vlx (Volex) and £Luce ( Luceco) a while back as they are both operating in similar areas and after a bit of DOYOR I decided to buy the latter and not the former although they were both in the frame . So far I have been very happy with the decision as Luceco is well up . In making the decision I used the stocko tool for comparing stocks side by side and out of curiosity I reran the stocko comparison tool prior to putting pen to paper . Luceco still comes out the overall winner with some interesting metrics : they have similar MCAP ( £383 m for Volex versus £412 m for Luceco ) and similar PE's but after that there is no comparison
PE : Volex : 15.3 , Luceco : 16.4
Revenue Volex : 296m Luceco :161
Net profit : Volex : 11.1 Luceco :15.8
Oper margin : Volex : 4.37 , Luceco : 11.74
ROCE : Volex : 11.57 , Luceco : 26.37
ROE : Volex : 11.9 , Luceco : 29.3
What's not to like about those numbers . The only down side about Luceco is that the free float is only 41.4% but Volex is also relatively low at 68% .
Did you consider Luceco and if you did I would be interested why you chose Volex
I don't own either but the other way to look at £VLX is that it has an opportunity to significantly improve operating margin and ROCE which it appears to be focussed on. If they can double operating margin towards 9%, still below Luceco, that will more or less double profit and halve PE. Thus if I were looking at this I'd be inclined to say Volex (LON:VLX) can potentially double its share price without really growing revenue whereas Luceco (LON:LUCE) is already well run and efficient so we are relying on revenue growth to continue the upward momentum. If I had to choose one I'd plump for Volex (LON:VLX) based on the risk/reward but clearly Luceco (LON:LUCE) is a good business too, just more fully up with events.
Good reply, davidjhill.
Volex (LON:VLX) is delivering a very strong, and rapid turnaround. Therefore it is not a good candidate for using the comparison tool here, as that uses the historic data.
Luceco (LON:LUCE) is also performing very well this year. If you have a look at the archive here, I've covered both companies in a lot of detail this year, which will give you a bang up-to-date analysis of both.
I think both shares are excellent, but for me, there's probably more upside on VLX.
In the last year, LUCE has done better than VLX, at +136%, but Volex shareholders probably won't be complaining about being +119% in the last 12 months! Both smashing companies, both performing well.
Interview with £G4m by Private Punter, asking how it will keep growing.
https://martinflitton1.wixsite.com/privatepunter/post/g4m-hitting-the-right-notes-17-11-20
Gear4music Holdings (LON:G4M) useful MrContrarian. Thx. Interesting to see that they talk about a business able to grow revenues 20% p/a which makes my 10% look nicely conservative. Gives me more confidence in my own calculations. I had thought I'd read somewhere that 2021 forecasts hadn't been revised for a long time, so nice to see that confirmed as it appears to point to some very material upgrades on 2021 & 2022 consensus expectations at some point. I guess this is the difficulty for investors at the moment in that analysts and even management are reluctant (probably understandably) to venture much past 6 months in terms of revenue predictions. Whilst that is obviously a headache it could pay off nicely for the likes of those who can do their our own maths and spot opportunities that may be mis-priced.
I note your comments with interest Paul; I currently hold a sizeable steak in Jet2 (LON:JET2) and I’ve become quite uncomfortable with how far it’s risen recently but it’s good to read your thoughts on 2021 and I’m tempted to keep holding for now.
I do enjoy a sizeable steak.
I do get why people often ignore goodwill write downs, but I do thing one for Focusrite (LON:TUNE) at least bears some thinking about.
So they bought Martin Audio for £35.3m , but now as a result of Covid-19 they only consider it to be worth (implictly) £25.1m.
Martin Audio makes speakers for the gigs market, so it's understandable that business will have been massively hit by the pandemic, but it seems quite extreme to wipe of a third of its value as a result.
Or at least that was my first thought - but then on reflection I realise that is exactly what the stock market has done to a large number of listed businesses.
Of course the stock market may eventually reinstate that value, but the value of Martin's goodwill will never be restated in Focusrite's balance sheet. I cannot make up my mind now whether to think that MA is significantly damaged in the longer term or whether Focusrite will prove to have an over-productive asset on their books.
I probably overthought that!
(No position)
Many thanks for the TUNE write up. It’s one of my ‘core’ holdings and I think this is a good set of results.
Interesting that Onthemarket (LON:OTMP) is on a tear up 16% today. Can't see any news. I've long thought this looked too cheap and I do own some at £1 so pleased to see the market appreciate it a little more, but anyone seen any non RNS type news that might explain todays jump?
Interesting article on the the BBC website about poor working conditions in the garment trade in India. I thought it was only LON:BOO that was guilty of this? Well it would appear that Tesco, Sainsbury's, M&S, Ralph Lauren etc. may also be guilty. What amazes me is there is no prodding/questioning of the consumer on this matter. I am also surprised that Amazon escapes scrutiny.
Exactly, I've been saying this for a while now! The whole garment sector is "guilty" of using low cost production. However, it provides vitally needed economic development for the countries concerned. There was a fascinating recent report on this by the BBC news, about Bangladesh's garment sector, wish I could find a link to it. The people live in slums, with shared and very basic kitchen and bathroom facilities. BUT they need the work, and it supports a basic life, even on only 50p per hour minimum wage. It is also driving economic development, employing 4m people directly, and more indirectly through support services. Port facilities are being expanded, more hauliers needed, etc. It now adds something like $30bn p.a. to Bangladesh's economy. Over time, wages rise, a middle class develops, and then self-sustaining economic growth kicks in. We've seen this with many formerly poor countries, which have developed strongly, with China being the most obvious example, and India currently work in progress. Plus many other Asian & African countries are going down the development path too, with all the moral quandaries that accompany it, e.g. pollution, poor working conditions, etc.
I used to think it was not the UK retailers' job to police their supply chain (and it's practically impossible anyway, because so many orders are outsourced without the retailers even knowing). But on reflection, perhaps we should keep retailers under pressure to make sure they at least try to ensure workers conditions are humane?
My main gripe has been that Boohoo (LON:BOO) (I hold) has been singled-out for repeated criticism in the press, when the people making its clothing are living in relative luxury in Leicester, compared with how everyone else in the industry does it from abroad. That's not in any way to acquiesce to laws & regulations being broken (allegedly) by some garment manufacturers in Leicester, but it does need to be seen more in the big picture, in my view.
Internet boycotts frequently happen with fashion brands who are caught out using cheap suppliers. They last about 2 weeks at the most. Bear in mind that the press have been really going for it against BOO, but to date, it's not harmed sales at all, indeed Q2 (June, July, August) was a record-breaking quarter, and stellar interim results.
Current trading saw "momentum continuing into September", with guidance raised for the full year FY 02/2021, although expectations that the growth rate would slow down (!!!) to 25% p.a. in the medium term! What a remarkable business.
But to get back to your original point, yes, the whole garment, and homewares, and pretty much manufacture of everything, has issues with supply chain ethics. Singling out BOO is absurd.
Regards, Paul
Hi Paul, forgive me if you have already covered this. With regard to ESG. Mark Carney commented that company's that don't conform to the new green agenda will go out of business ( or possibly be forced out of business? ). As clothing manufacture and distribution can be un-environmentally friendly and given your thoughts on institutions offloading BooHoo. Do you not see BooHoo and similar company's struggling in the not too distant future? Thanks.
Mark Carney does do a lot of attention seeking. Paul has explained on multiple occasions that consumers are not as discerning as this.
Hi Shanklin100, an attention seeker (once) at the heart of government? Surely not!! Thanks, I totally appreciate what you are saying. Many consumers just want cheap fast fashion and are happy to be oblivious about how it was created and delivered but I'm just curious about this new green agenda. Do any of you think that there will be a concerted attempt to destroy company's like Boo? Consumers might love the product but if the financiers cut off the life blood of money they will slowly die. I know you have all discussed Boo to death but what about all the other company's that don't conform? Out of business or gobbled up by the multinationals?
NO ! Paul has said why - MANY TIMES !
Can anyone help me understand the analyst forcasts in the StockReport for Morses Club (LON:MCL) ?
Consensus for Feb 2020 is Net Profit £14.53m, EPS 10.84p, which appears to make sense as £14.53m divided by 132m shares is 10.84p. The forecast Net profit for Feb 2021 is £6.0m, EPS 11.06p, which seems to suggest that the share count will more than halve!
Forecast figures is one part of the SR I never trust. If you look here you will see a different and more creditable set of figures:
https://www.sharecast.com/equity/Morses_Club
I have noticed this on a couple of occasion before although not for £mcl. It would be interesting to ascertain where such disparate figure come from, ie sources and thd calculation. I remember a glaring howler like that for £jse
My Stockopedia is showing my portfolio as blurred.
Anyone else getting site issues, please?
@8888: my portfolios are showing as normal. I have only ever seen blurring when looking at US shares, which my subscription doesn't cover. Might your subscription have expired?
Just lending my support to both Paul and Jacks recent commentary about what you hold and the accompanying notes. Brilliant. Just brilliant. Would welcome this on a fairly regular basis /slow news days every so often...
Paul - you know you have arrived when Sky News start reporting on your share trades!
Do please elaborate.
I read Paul's comment that way as well, but actually he's saying the NED was reported not his holding!
" I hold - as reported last night by Sky, BooHoo has made the first of two heavyweight NED appointments..."
Oh I see, a misunderstanding! I'll tweak the wording to make it clearer what I meant :-)
Easyjet (LON:EZJ) Easyjet reported a Q3 $1.1billion loss due to Covid, (article below) that's not insignificant when taking into consideration their historical profitability and generous dividends. (I used to hold).
“Due to the impact of COVID-19, passenger numbers for the year ending 30 September 2020 decreased by 50.0% to 48.1 million (2019: 96.1 million)
Capacity decreased by 47.5%”
https://pageone.ng/2020/11/17/...
I believe it's too early to call on the travel/hospitality industry, and see it as high risk presently, even 6mths forward looking. I recall a few weeks back, Paul was also seeing this as a sector to avoid. Things are far from stable, even with 'pent up demand'.
I have done very well on Easyjet since last year, buying at £4.80, with the share price nearly doubling. I think that the rapid vaccination rollout will be a massive boost for this sector, including Saga and Carnival Group. I know, speaking to friends who are massive Cruise fans, that they are keen on getting back to Cruising once they have been vaccinated. I work for a company which specialises in travel software and the bookings for Easyjet Holidays are looking very encouraging. Most people who have been stuck indoors for the last year, will give an arm and a leg to have a holiday. Of course, always watching my stops, but looking at these investments in 2 years time, I believe will get a great return.
Regarding the spread on G4M (and all small caps for that matter) - I have recently started using a spread being account for individual shares (without significant leverage) and left my ISA in ITs and ETFs. While the real spread buying physical shares via a broker is narrower than the published spread that is not the case with IG (spread betting). Any comments about this? Do I need to mix and match spreadbets and physical shares dependent on the spread for each security?
Just ring up IG or Spreadex, and ask them to get a better price than quoted online, and they're happy to reflect the real market prices, inside the quoted spread.
Thanks Paul.
I rang HL the other day as I couldn't get a price on some junk I wanted to offload. Initially the spread they came back with was ridiculous so I asked them to only sell at a better price - 2mins later they came back and got me a slightly better price - only saved a few quid, but covered the phone dealing costs vs online and left me enough to pay for a good night out (whenever they happen), although TBH I lost so much on the rubbish I don't think I can afford a night out.
Paul
Absolutely agree with your comment on ESG. Like Beta, we should be thankful for another tool that enhances market inefficiency.
Here is evidence:
https://investorplace.com/stoc...
Two points:
I'm not a great fan of ESG investing because I think they conflate too many factors and I don't want to outsource my conscience to box tickers. But I also wouldn't want to invest on the basis that the worst ESG scores give the greatest returns.
JohnEustace,
I'm not a great fan of ESG investing because I think they conflate too many factors and I don't want to outsource my conscience to box tickers. But I also wouldn't want to invest on the basis that the worst ESG scores give the greatest returns.
Very well put, that is exactly my view too. I'm not saying ESG should always be a contrarian signal. Just that, in some cases, where a company is performing brilliantly on a financial results level, and the outlook is very strong, then I would be prepared to tolerate some ESG failings, particularly if the company is trying to fix its failings (as with BOO).
Some things for me are red lines though - e.g. I have never, and never will, invest in any tobacco company, as they are peddling a product which does immense damage to almost all its customers (unlike say alcohol which only causes a problem to people who over-indulge).
Regards, Paul.
I think there are opportunities re ESG, not least because ESG has become a mainstream factor for fund managers whose awareness, understanding and even commitment will be understandably variable. My further comments relate more to the E and S element. Hopefully most investors have reasonably shared understanding and views on the importance of Governance.
There is a huge degree of subjectivity that is often driven by the whim (or indeed ‘Wokery’ ) of the moment. A good example of this is dear old £Boo. Apparently it is much worse to pay some people in England £4-£7 ph (presumably many of whom will also have been receiving state income support or similar) than it is to pay £0.50 ph in Bangladesh. At some point the concern will change and the focus will be on exploitation of people in Bangladesh, etc.
Similarly for the E part, we all know recycling is good. But then we found that the majority of our (very) low value domestic recycling was being sent to China and other SE Asian countries, many of whom were then dumping valueless plastic in the sea. So ultimately recycling caused plastic pollution of the oceans. There is a similar story of unwanted outcomes when the effort to ‘save the Planet’, by reducing CO2, by promoting diesel cars, led to the outcome of unhealthy urban pollution, particularly damaging to children.
So there will always be opportunities for the fund manger herd to go charging off down a blind ESG alley only to change their minds a year later. The trick will be to spot this and find another unloved/unfashionable but great investment.
I think there are opportunities re ESG, not least because ESG has become a mainstream factor for fund managers whose awareness, understanding and even commitment will be understandably variable.
ESG at the moment is a moveable feast, which definitely creates some opportunities, but the IFRS Foundation have launched a consultation into standardising ESG reporting which would essentially integrate it into existing accounting standards:
https://www.ifrs.org/news-and-...
The aim would be to ensure that companies are actually minimising their ESG impact rather than simply greenwashing.
There's a clear direction of travel here, although it'll take years to get to the point of standardisation. But I'd be wary of dismissing this as simple wokery and virtue signalling, not least because those terms are increasingly used by people to dismiss ideas they don't like rather than engaging in any kind of constructive analysis.
I'd also be wary of dismissing this simply as a fund manager fad. Fund managers do odd things from time to time but they also have a keen eye on what their investors want. So if they're pulling out of investing in certain companies and sectors it's probably because they think that will make them more attractive to their investors. To the extent that's "virtue signalling" it potentially indicates a change in attitude from investors rather than fund managers.
A study earlier this year indicated that millenials are far more concerned about ESG issues than people of my late Boomer generation. That group is in process of receiving the largest inter-generational wealth transfer in history, so we should be careful about dismissing this as a fad:
https://www.triplepundit.com/s...
timarrI would agree on tobacco and it is one of my few investing red lines (I probably wouldn't touch defence either but then Avon Rubber (LON:AVON) is a top 10 holding for me so maybe...) and if it was the sort of investment I was after I might well buy Diageo (LON:DGE) or £LVMH, however I suspect that down the road we will find that alcohol is not quite as benign as we wish it was. I do drink by the way but do wish I had the will power not to!!
Regards
Michael
Here are my heat maps for today (prices as at 9:45am).
Overall state of the market by ICB Industry classification:
Key to the Industry heat map contents:
SVCR filtered to 'interesting' instruments (reporting soon or recently, trending, breaking out, or moving more than the 20d EMA of ATR):
Big movers today (moving more than 20d ATR EMA against either yesterdays close, or today's open - not limited to small caps):
And finally the key to the heat map contents:
The heatmaps are ordered by Stock Rank™, and are limited to the top 80 instruments.
The heatmaps are images and will be resized by your browser to fit your screen. If the heatmaps images are too small to read on your screen, right-click on the image and select 'Open image in new tab'. This will open the heatmap in a new tab in your browser where they can be zoomed as necessary.
I use heatmaps a lot and generate many as part of my research. I use them to help me quickly find instruments which pass my basic 'tradeable' criteria ('T': profitable, low-debt, reasonable liquidity), have a high Stock Rank™ and Quality Rank, and are trending (Tr+ or Tr++) or breaking out (Br+ or Br++) ideally on increased volume (V+). I then research the individual instruments further using the Stockopedia Stock Report.
How (or indeed if) you use the heatmaps is up to you, I contribute them here in the hope that others may also find them interesting or useful.
greensiax
Great Heat maps! Is this a feature buried somewhere in Stockopedia? Or is there a way of creating them by downloading data?
Thanks Mark :)
I have a database that I import data from various sources into, and use to generate the heatmaps.
Cheers,
greensiax
The quality of this Report and the Discussion section has improved tremendously. It has now become my daily read. It helps think about the companies and how to value them.
Thanks Jack, Paul and all the Posters/Contributors.
dotDigital (LON:DOTD) - positive market response this morning to the increase in profit, despite a fall - yes a fall - in "adjusted eps from continuing operations". The fall was down to an increase in the tax rate. I am very positive about dotDigital (LON:DOTD) as a company, but it is on a high valuation, and I would have thought the tax rate likely to go higher still.
Anyone with any thoughts on Scapa (LON:SCPA) interims?
I have been sceptical on the valuation ever since they lost the Convatec contract back in 2019, but have started to get interested again recently and took out a small position a few days ago
Despite being an "essential business" they were impacted by the pandemic, with revenues in HY to September down 24% (Q2 was 23% up on Q1 with business moving back towards normal).
There are a quite a lot of moving parts in the numbers, so I won't attempt much detail at this stage,
The posted a small loss overall of 0.2p / share (perversely less than the 0.6p they lost the previous year.)
Debt reduced to £21.8m (because they did a £31.6m placing earlier in the year.)
With trading returning to normal (and above plan) , the best stab at a valuation metric I think would be 2022 forecast earnings of 10.6p / share - I notice this forecast has nearly halved since the onset of the pandemic and in general I think brokers have been much too pessimistic in slashing the Year 2 forecasts for companies.
I don't think it is stupidly cheap by any means, but could be at the start of a useful recovery phase.
Anyone else been following more closely?
excellent opening salvo Paul -looking forward to the rest of today commentary.
Mark
Crimson Tide (LON:TIDE)
Further contract win and with a top tier company - this feels like they have a very good product at the right price which can be easily integrated to existing ERP systems that companies already. Improves reporting, communication, utilisation etc
Gear4Music's interims confirm £4.9m H1 net profit. Given the heavy weighting to H2 due to the Xmas trading season, the consensus forecasts look very low at £5.58m for the full year. Full year net profit to 31/03/2020 was £2.6m following a small loss in the first half of £0.2m. Revenue for FY 2020 was c£120m with a split of £49.4m H1 and c£70m H2. Given the clear H2 weighting shouldn't we be expecting nearer £15m FY2021, particularly given the gross margin gains YoY?
Gosh it appears you were right £15.6 now given as guidence by management.
Investing can be a dry subject. You bring some personality to it Paul wether it’s insights into your personal portfolio or tales of clandestine micturition down Bournemouth seafront. That’s partly why the SCVR is so popular IMO. Must be 8 years now I’ve been tuning in.
Oh don't mention that, I got into trouble for having a bit of fun. Unfortunately, there are a tiny number of professional offendees, who kick up a fuss over anything they don't like. These people now set the agenda everywhere it seems, I'm afraid, to the detriment of the vast majority.
Tell them to get stuffed. Enjoy your stories as much as your small caps insight :-)
This post is under review
Oh dear - what must be going through some people's minds?
It just proves my point, doesn't it!
It's a shame that the offended mini-minority can't just state their case in an adult way, and accept that other people have a right to open conversation and park it there. They might even persuade some to their way of thinking and move the conversation on instead of closing it down. Unfortunately it is the way of the world at the moment. And not helped by the equally bad people that would SHOUT at them I suppose.
Sounds like the whole Woke / Left agenda to me !
What's wrong with Boris acting woke and left handers?
I'm a fan of both.
All the best today Paul, with your little friend Paddy,
Thanks also for all your work.
Thanks Handykart!
Yesterday's trip to the vet went fairly well. We've got Paddy booked in for x-rays on 26 Nov so providing the cancer hasn't spread, he'll then hopefully be ready to have the lump removed, which our pet insurance should cover. Fingers crossed! I'll spend all day on today's report, to make up for being absent yesterday.
Best wishes, Paul.
That's great news Paul, I really hope the treatment works out well for Paddy and yourself.
Fingers crossed. Dogs generally tolerate chemotherapy much better than humans.
My morning smallcap tweet: Velocity reverses
£W7L GLI Finance (LON:GLIF) Two Shields Investments (LON:TSI) Eagle Eye Solutions (LON:EYE) Tekcapital (LON:TEK) Velocity Composites (LON:VEL) Intercede (LON:IGP) Synectics (LON:SNX) £RPO £G4M Palace Capital (LON:PCA), Idox (LON:IDOX), AFH Financial (LON:AFHP)
Warpaint London (W7L) a range of 15 W7 cosmetics products will now be stocked in 209 Tesco Express stores, following a trial. Also expands Tesco main store range. Sales in Wilko running ahead of mgmt expectations. [SP=64.85 Cap=50m]
GLI Finance (GLIF) placing, a refinancing of the Group's liabilities and a restructuring of the business. £4m max placing at 2.25p, a nil discount. [SP=5.3 Cap=17m]
Two Shields Investments (TSI) BrandShield wins 'major' US contract with Pharmaceutical Security Institute. No £££. [SP=0.11 Cap=7m]
Eagle Eye Solutions (EYE) AGM stmt. Q1 rev up 11%, adj EBITDA comfortably in line with management expectations. [SP=346 Cap=89m]
Tekcapital (TEK) £380k placing at 8p, a 9% discount, to enable Guident and Salarius take advantage of new commercial opportunities. [SP=6.25 Cap=4m]
Velocity Composites (VEL) recent trading weak. "Prospects for the current year remain subdued with no imminent indications of significant increases to build rates on major civil aircraft programmes as set by the primary manufacturers Boeing and Airbus." Slashes 40% of jobs. Guides FY(Oct) rev down 44%, adj EBITDA -£1.8m (+£0.6m). [SP=16 Cap=6m]
Intercede Group (IGP) wins follow-on purchase order of $2.8m. "Includes software licenses and associated development, professional services and support & maintenance; the majority of which will be recognised in the current FY." It's included in mgmt expectations. [SP=71.2 Cap=36m]
Synectics (SNX) wins €1.3m contract with Irish Rail, the first for on-vehicle heavy-rail solutions for its Security business. [SP=127.29 Cap=23m]
At 31 October 2020 the Group had around £310m in Remaining Performance Obligations (RPO)[2] demonstrating a significant year-on-year growth in the level of ongoing customer commitments. The increase in customer commitments was driven by total bookings of £180m, 60% of which was secured in the second half and £122m of which represented new business from new customers and upsells. [SP=NA Cap=NA]
Gear4Music (G4M) H1(Sept) rev up 42%, EPS 23.6p (-0.7p). Very strong trading patterns have continued into Nov so guides FY ahead of the recently upgraded market expectations. [SP=730 Cap=153m]
Palace Capital (PCA) H1(Sept) £7.2m loss (£1.2m loss) due to £10.5m loss on revaluation. EPRA earnings £3.2m (£6.7m). EPRA NTA 347p/sh down 17p in the half. "82% of all rents due on and since the September quarter day collected, a higher percentage than at the equivalent stage in the previous two quarters with December monthly payments still to come when collection is expected to exceed 90%." [SP=190.08 Cap=88m]. I hold,
In line: Idox (LON:IDOX) AFH Financial (LON:AFHP)
EasyJet losses announced. Good news is that the cash burn is reduced.
Fantastic half year results from Gear4music Holdings (LON:G4M) this morning - 23p EPS!!! House broker has upgraded full year to 33.7p given strong trading in November but I wouldn't be surprised to see this upgraded again on basis of potential further post Christmas lockdown. Next year they expect c.26p indicating how much of a one off boost the pandemic has provided, although note in Q2 (July to September) growth was still 21% which is good. I think the share price has a little further to run yet but I'm mindful this year will very much be a one off.
Hi Patrick
Can I ask how you accessed their broker note ?
Thanks
It's free: https://www.progressive-research.com/research/extraordinary-profits-in-extraordinary-times/
Thanks Patrick, I think its terrible that I subscribe to Research Tree & find out about Research that they publish on a Stockopedia forum.
Thanks again Patrick, I wonder how long it will take for it to appear on Research tree !
Gear4music Holdings (LON:G4M)
I disagree - I think the broker note is way too conservative. Last year in H2 they did £70m of revenue. Even if they only match that then with the increased margins they should do circa 45-50p of EPS this year by my calculations and looking back at previous H2s!
Next year will be interesting but I don't think this is anything like a one off. There is plenty of space to expand into in my opinion and whilst H1 certainly saw more growth due to lockdown they have a 26% customer repeat rate. If you assume a natural growth rate of 10% p/a (and I consider that reasonable) then you can assume that H1 might ordinarily have been £55m. The extra £15m might therefore be classed a one off but 26% of this repeats according to the company which means we are really looking at £11m of one off revenue due to covid trends. If we assume this trend is reversed back to normal next year and the "extra £11m" disappears it should be replaced with £14m+ of new revenue at circa 10% growth. Translated that works out at an expected £145-150m+ of revenues - ie still higher than this year with corresponding eps.
I am amazed it hasn't moved up more on todays news. It looks to me like the broker notes are creating a bit of a red herring - perhaps in their desperation to err on the side of caution due to Covid?
Perhaps I've missed something but I can't see how 33p of EPS this year is even a remote possibility given trading performance and H1 of 23p. They did £70m revenues last year in H2 (same as H1 this year) and we know from trading it's likely to be higher than that. Past accounts don't show any material change in admin expenses so looks to me like gross profit should be £22m offset by similar admin expenses to H1 - that puts EPS closer to 25p in H2 or 48p for the full year. That's a far cry from 33p but there's nothing obvious making up the difference and management haven't guided to lower profitability in H2. Looks odd to me.
Gear4music Holdings (LON:G4M) still looks cheap. Brokers seem always seem late in their view of reality. The shares have gone up 185% ytd, lets not get greedy and be patient for the market to catch up.
BSV
Having looked at more detail this evening I think it's also worth highlighting the broker estimates assume H2 YoY growth of just 7% (75.6m revenue for H2 versus 70.6m last year by my calculations). So I agree that broker target of 33p will probably be a considerable underestimate given the company is talking of strong trading going into November and it will surely benefit from physical retailers being shut for at least some of the run up to Christmas.
Gear4music Holdings (LON:G4M) market share is still only 8.6% so there is still plenty of room for further long-term growth even if next financial year's numbers don't end up being quite so glowing as this year's.
I'm not so sure this year's growth in revenue will be such a one off. If you look at G4M's revenue growth in the years prior to their logistics nightmare in Autumn 2018 it was running at 30%+. Prior trends are still in place albeit covid has accelerated them, cottage industry consolidation and bricks and mortar to online. I'd expect G4M to be able to maintain robust growth and if the margin improvements can accompany this the operational gearing should see continued strong earnings growth. If this view turns out to be correct and they turn in £13-15m net profit for the current FY, with a market cap of £142m and strong earnings growth I would suggest that the share price has a little more than a little further to run.
Dotdigital (LON:DOTD) FY20 results today in line with upgraded expectations. Now expect to exceed revenue forecasts in 21, but there will be additional investment. Here's an overview by CEO Milan Patel & CFO, Paraag Amin. Video & Podcast.
Argentex (LON:AGFX) release H1 results on Friday 20.11.20. Join us for a results presentation at 11am with Carl Jani, Co-CEO. They IPOd last year, and it's an interesting company. Register here.
Other results webinars over the next few weeks:
Ig Design (LON:IGR) H1 results: Wednesday 25.11.20, 2.30pm.
Tracsis (LON:TRCS) FY20 results: Thursday 26.11.20, 1pm
Panoply Holdings (LON:TPX) H1 results Monday 30.11.20, 12 noon
Register here for all.
Hi Paul
I just wanted to say how much I valued you sharing your stock positions and the commentary behind them. This made it both interesting and valuable as a learning opportunity. Your generosity is much appreciated.
Also I wanted to thank you for promoting Zane so effectively. So many charities are large corporations with sometimes dubious goals and practices. I can see every £ spent on Zane will have a big impact, so my task for the day is to set up a monthly donation.
Wonderful, thank you Martin! :-)
Gear4music (G4M) delivered excellent H1, with the strong sales and gross margin already reported. Current trading remains very strong going into November, so management flagging further upgrades. Nice uptick on customer conversions. Still looks undervalued with EV/sales under 1x this year.
I wonder if The Guardian etc will have much time for the newly announced Non Exec Board appointment at Boohoo (LON:BOO) ? Maybe they can turn it into a negative...
Radio 4 have just played quite a detailed piece commenting how allegedly Ralph Lauren are forcing workers into long hours for pittance in India , so maybe the heat will shift from Boohoo (LON:BOO)
M&S, Tesco, and Sainsbury’s are also mentioned in the article on the BBC website.