Small Cap Value Report (Tue 17 Oct 2023) - JUP, SHOE, FDEV

Good morning from Paul & Graham!
Graham's 11:30 (live) and recorded daily show will today be looking at Frontier Developments (LON:FDEV) , Jupiter Fund Management (LON:JUP) and one not covered in today's SCVR, Moneysupermarket.Com (LON:MONY) - simples!
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Summaries
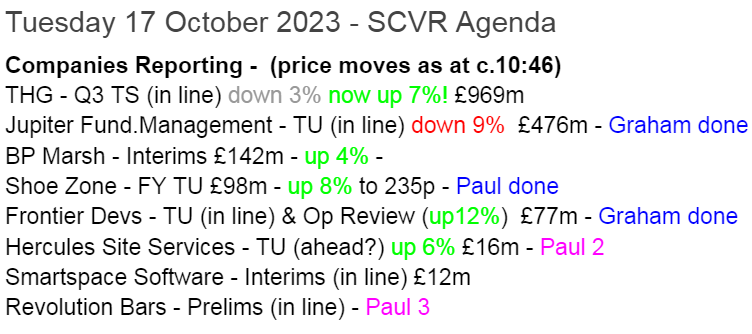
Jupiter Fund Management (LON:JUP) - down 12% to 77p (£149m) - Trading update (AuM declines) - Graham - GREEN
The year-to-date performance remains within expectations but the net outflows seen in Q3 are nevertheless a disappointment. A new fee structure is also going to take another small bite out of Jupiter’s profit margins in the short-term. I remain positive. PER 7x, divi yield 7%.
Shoe Zone (LON:SHOE) - up 9% to 233p (£107m) - FY Trading Update - Paul - GREEN
Knockout numbers for FY 9/2023 in this superb year-end trading update, they've more than just blown the bladdy doors off! There's so much to like about this company, which I rave about below, and even after today's rise, the valuation is still modest because forecasts have been beaten so much. Although I cannot ignore the looming competitive threat from Chinese direct-to-consumer competition such as Shein and TEMU - ignore at your peril, I would say, as we discovered to our cost with Boohoo (LON:BOO) and ASOS (LON:ASC) .
Frontier Developments (LON:FDEV) - up 11% to 215p (£85m) - Organisational Review and Trading Update (in line) - Graham - GREEN (under review)
This has more than halved since I took a positive stance on it at the start of the year. EPS estimates have been in a consistent downtrend but today’s trading update is in line and the company is cutting costs to stabilise performance. Still worth investigating, in my view.
Paul’s Section:
Shoe Zone (LON:SHOE)
Up 9% to 233p (£107m) - FY Trading Update - Paul - GREEN
Shoe Zone is pleased to announce its unaudited full year trading update for the 52 weeks to 30 September 2023 ("FY 2023").
Strong sales and highest recorded profits
This is obviously the retailer of cheap, Chinese-made shoes. It’s an impressive owner-managed business that has navigated recent years of almost permanent economic turmoil very well I think. The strategy has been to keep lease liabilities low, and relocate from small town centre stores into more efficient sheds on retail parks.
Checking our previous notes here for background, our last 3 comments were -
16/5/2023 - shares had a wobble, down 16% to 203p due to unimpressive interim results, and only an in line outlook on quite soft forecasts. I was AMBER, based on the facts & figures at that time.
9/6/2023 - up 11% to 233p - a much improved trading update, causing a good upgrade to forecasts. The facts improved, so I moved up to GREEN.
12/7/2023 - shares rose 10% to 257p on an ahead of expectations TU, and forecast earnings moved up a whopping 29%. I moved back down to AMBER, due to share price rise, and worries about competitive threat from TEMU (Chinese co selling direct to UK consumers).
So quite mixed messaging from SHOE earlier this year. Or maybe just a wobble in trading, before it returned to the usual, strong form, from June onwards?
Revenue £166m (up 6.1%)
Split: 81% stores, and 19% online.
Store numbers down from 360 to 323, which I imagine is due to the strategy to focus on the larger, more efficient retail sheds.
Notably strong gross margin of 62.1% (LY: 61.2%) - margin is absolutely key in retailing, but often overlooked by investors. Helped by lower shipping container prices.
Profitability - adj PBT looking very good at £16.0m+ (LY: £11.2m)
Modest adjustments, which look reasonable.
Dividends: interim of 2.5p (£1.2) paid in Aug 2023. Final divi to be determined. Note that it has paid several special divis of c.8p in recent years.
Big share buyback: 3.8m shares costing £8.1m (avg 214p), shares since cancelled. This is significant, as share count has fallen from a static 50m (2017-2022) to 46.2m now, a drop of c.8% in issued shares - thus boosting EPS for remaining shares.
Net cash was £16.4m at end Sept 2023, down from £24.4m a year ago, due to £8.2m divis paid, £6.4m buybacks, increased capex at £11.3m. As you can see, most of those outgoings were paid for out of cash generation, and in any case are not a concern because these items are all controllable cash costs (e.g. divis & buybacks are a policy decision by mgt, not something that just happens by accident).
Current trading - nothing said, which is fair enough as we’re only 17 days into the new financial year.
Outlook - nothing said about this either, which is a bit frustrating. I think we’ve had this problem with SHOE before, rather leaving investors in the dark about how they see the outlook. The closest it gets is this bit -
We continue our strategy to expand our Hybrid and Big Box formats via refits (15) and relocations and new stores (35). Shoe Zone continues to show how resilient it is, with a proven track record of delivering robust results during times of economic uncertainty.
We look forward to updating shareholders in more detail at the time of our final results in January 2024.
Broker update - many thanks to Zeus for its update. This is very good - Zeus says the adj PBT of £16.0m is 19% ahead of its forecast, which had already been raised twice in June and July.
Good grief! That translates into 26.1p EPS for FY 9/2023. That’s a fabulous outcome, given that original forecasts for this year were only c.11p - a terrific out-performance, with 3 big upgrades, and a big final flourish beating the latest 21.8p broker consensus by a country mile! I’m so impressed with this.
Zeus is forecasting a small drop in adj EPS to 24.7p for FY 9/2024. What’s the betting they’ll need to raise those numbers again? Although bear in mind that SHOE has almost reached a 10% PBT margin, so profit growth might be harder to come by from now on, given that the base figures for comparison are now strong.
Valuation at 233p/share this morning is now a PER of 8.9x - that’s clearly excellent value, for a strongly-performing, high margin business with net cash, and generous shareholder returns.
Paul’s opinion - I’m blown away by these numbers! Therefore there’s no alternative than viewing it positively, GREEN.
Although I have to mention my background worry, that the Chinese are trying to dis-intermediate retailers, by selling value products direct to consumers. Shein and TEMU are therefore a big worry for me - look how Shein has decimated the fast fashion sector already, wiping out its profit margins.
I did buy some cheap shoes from TEMU to try them out, and noted that they don’t post them boxed, they just come in compact soft parcels, which are air-freighted from China. Product was meh - you get what you pay for.
If Chinese direct to consumer companies take say 10% of SHOE’s business, at 62% product margin, that would be a loss of £10.5m gross profit, on a largely fixed cost base, the result would be ugly. It might also force SHOE to lower its selling prices to compete, thus imposing a further margin squeeze on the sales it retains. So ignoring this risk could be costly.
Do people really need to try on cheap Chinese shoes for fit? Maybe for rapidly growing kids, but personally I buy my trainers online, just ordering the same size every time, and have never returned any.
For that reason, I don’t imagine I’ll buy any SHOE shares, even though they look very attractive. If you don’t see Chinese competition as an issue (Why? Do explain!) then I can see why you would want to buy/hold SHOE shares. Certainly a remarkable performance, and reasonable valuation too, hence why I have to be GREEN.
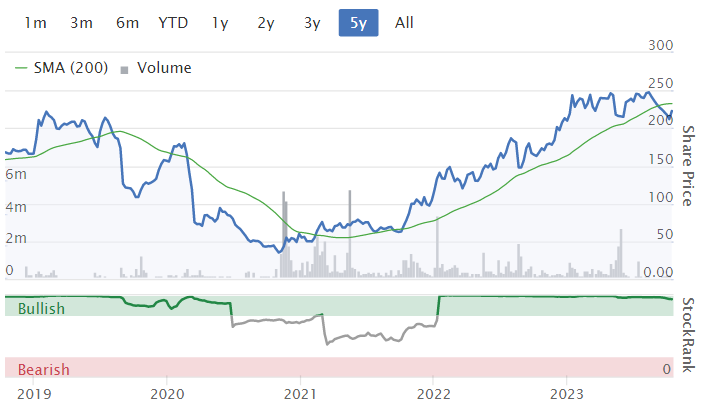
Note the StockRank is jammed on maximum!
Graham’s Section:
Jupiter Fund Management (LON:JUP)
Share price: 77p (-12%)
Market cap: £149m
I’ve been positive on this fund manager since last October, when I noticed the remarkably cheap valuation and the potential for some catalysts to improve the situation for shareholders.
The market seemed to initially share my enthusiasm, before selling the stock lower again. It is lower again today:

The company does pay a significant yield (around 7% currently) so that offers some consolation to shareholders nursing a capital loss.
Today the company has published a Q3 update to the end of September.
I’d summarise the key points as follows:
Quote: “Overall flows year to date remain within expectations.”
However, Q3 net flows were negative by £1 billion. This follows small positive net flows in the first two quarters.
AuM reduces to £50.8bn (down from £51.4bn at the end of Q2).
While overall flows for the year are still within expectations, the Q3 outflow is not good news and so today’s share price decline is understandable.
Institutional clients have contributed positive or neutral net flows for five consecutive quarters. But retail customers have been far more difficult to attract and continue to inflict outflows:

As an aside, I think institutions are less prone to pull money out of the market when stocks are cheap - they have systems and processes that don’t change too much over time, and so they stay invested and continue to invest more steadily than retail investors.
This is consistent with the fact that institutions are consistently putting money into Jupiter, or leaving it there, while retail customers are still taking money out.
Unfortunately for Jupiter, it is mostly a retail shop and four-fifths of its AuM is classified as “retail, wholesale & investment trusts”, as opposed to “institutional”. So its net flows remain highly sensitive to sentiment among retail investors.
We get an insight into the themes investors are most interested in currently: “The areas of client demand remained relatively unchanged from the first half, with inflows into Asian Income and Japanese Equities not enough to offset outflows from unconstrained fixed income and UK and European equities.”
CEO comment: a key reason I have been positive on Jupiter is my expectation that the new CEO could be a catalyst for change. Here’s an excerpt from his comment today.
We have rationalised our fund range and right-sized the business and are investing to ensure the company is aligned with clients' requirements which are fundamentally changing. Whilst progress will not be linear, the growth of our institutional and international businesses are encouraging indications of our ability to increase scale and grow our appeal to a broader range of clients.
His agenda for change continues today with the announcement of various actions:
Client-facing teams have been restructured. They will seek “alternative methods for clients to access our investment capabilities” (I think this means a more bespoke and personalised client service).
A range of thematic funds will be launched shortly.
A new tiered fee structure for UK unit trusts and OEICs. This might initially hurt the net revenue margin by a few basis points, but both customers and Jupiter will be incentivised for AuM to grow and to hit the higher tiers with lower fees.
Graham’s view
The share price is now 14% lower than it was when I first spoke positively on this stock a year ago.
AuM at the time was £47.4 billion. So AuM is actually up by 7% over the past year.
Thanks to a share buyback programme, the share count has reduced from 553 million to 545 million over the past year.
EPS estimates have been stable:

So the bigger picture here doesn’t strike me as discouraging.
The bad news today is that we’ve had a poor quarter in terms of flows, and the company’s profit margins will take an additional short-term hit from the new fee structure they wish to implement (on top of the gradual decline in margins that they are experiencing, along with the rest of the active fund management industry).
I don’t think these reasons are dramatic enough to sway me from my positive stance on these shares. Below is a reminder of the value metrics on offer here (calculated based on last night’s share price).
During the bull market, it was exceedingly rare to see opportunities such as this in large reputable companies:

Frontier Developments (LON:FDEV)
Share price: 215p (+11%)
Market cap: £85m
Frontier Developments plc (AIM: FDEV, 'Frontier' or the 'Company'), a leading developer and publisher of videogames based in Cambridge, UK, announces an Organisational Review and provides an update on trading.
A former stock market darling, this is down by over 90% from its high in 2021:

Let’s check the trading update first: the existing game portfolio is performing in line with expectations. Christmas always sees frenzied buying of video games and Frontier will release Warhammer Age of Sigmar: Realms of Ruin next month.
The financials this year (FY May 2024) are going to be poor, as is already known. It will include a dreaded loss at the adjusted EBITDA level:
The Board remains comfortable with market expectations for FY24, with consensus revenue at £108 million and consensus Adjusted EBITDA* loss of £9 million. The cost reductions from the Organisational Review are expected to be fully effective for FY25.
The pre-tax loss estimate from Zeus for the current year is £14.7m.
Now let’s see what the organisational review announced today has to offer:
The review will deliver enhancements to Frontier's leadership and structure, drive efficiencies across the Company and achieve a reduction in annual operating costs of up to 20%. The cost reductions will be achieved through a recruitment freeze, spending cuts and, unfortunately, redundancies, subject to consultation.
The Organisational Review and resulting actions are expected to conclude by early 2024, placing Frontier in a strong position to deliver efficiently on its strategic plan over the medium term, and capitalise on future opportunities.
Graham’s view
Given the scale of the current losses, I can’t argue against the company cutting costs.
The company has historically been cash-rich, but its cash balance fell to £28m as of May 2023, and then fell to £25m by August (as reported by Paul here).
With the company now incurring significant losses at the adjusted EBITDA level, the bleeding needs to stop before it gets into trouble. I think shareholders should be relieved that Frontier is taking action before the situation gets critical.
The main point about Frontier for me is that it remains a concentrated bet on a few titles selling well. The Formula 1 franchise was supposed to be a goldmine but it hasn’t worked out that way, with the 2023 edition failing to draw in a sufficiently large audience beyond the most devoted fans of the sport.
The company is now hoping that its Warhammer game can be a hit, and will then look to reinvigorate F1 with a new edition released at some point in 2024.
EPS estimates have been cut many times this year:

I took a positive stance on these shares back in January 2023, after a major profit warning, failing to anticipate that EPS momentum would remain so negative for the rest of the year.
The Frontier share price has more than halved again since then, and the price to sales multiple is now only about 0.8x. This is 10% of the price to sales multiple at which Activision Blizzard was recently trading (8.5x), prior to its shares being suspended to allow its acquisition by Microsoft. Activision deserves to be valued at a premium, of course, but a 10x premium is quite something!
Even with it trading horribly in the red, therefore, I think I have to again put out a positive view on Frontier shares. It’s rare to see a video game developer trading at a P/S multiple like this. Yes, it’s unprofitable, but management have today announced concrete actions to cut costs and get themselves onto a firmer foundation. So the risk/reward here must be worth researching at this valuation.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

71 comments
Jupiter Fund Management (LON:JUP) is this a realistic takeover target? They have cash almost equivalent to their market cap? Or do I read the net debt figure on the balance sheet incorrectly?
Pendragon (LON:PDG) Autonation AutoNation (NYQ:AN) drops bid…
Lots of posts on Jupiter Fund Management (LON:JUP) today but doesn't seem to be anything on fund performance. This is key for retail funds as clients tend to redeem if funds not performing well, at least on a relative basis.
Jupiter look pretty mixed on that front when looking at their largest funds - their large dynamic and strategic bond funds seem to be firmly 4th quartile over most periods. Same with their large European equity strategy. On the other hand their Merlin range looks to be doing ok, as does the Special Situations funds. Overall, not particularly inspiring, but I guess at current share price there's probably value here. That said you could say the same about Premier Miton (LON:PMI) or Liontrust Asset Management (LON:LIO)
Just bought a few Jupiter Fund Management (LON:JUP) . I didn't notice anyone commenting on the recent change to dividend policy, and the implications for dividends. The policy is 50% of pre performance fee profits plus maybe spare capital distributions. Quite what this implies is difficult for me to work out....
Accrol group (LON:ACRL) tops the highest volume this week.
Crap business going down the toilet or about to get on a roll? Sorry I couldnt resist.
Some decent director buying in Avon Protection (LON:AVON) and Midwich (LON:MIDW) recently also
What can Paul tell us about Revolution Bars? Wasn't that one of his favourites a couple of years ago?
* every subscriber yawns*
then scrolls on
Move on Ben ffs
Jupiter Fund Management (LON:JUP) looks cheap to me -bought this morning . Looking at valuations, there could be some consolidations...
Oct 17 (Reuters) - A Dubai-based investor has taken a
3.2% stake in Saga (LON:SAGA) , becoming one of the top three
shareholders in the British holiday group.
Eldose Babu picked up the stake last week, Saga's regulatory
filing showed on Tuesday. He is now the biggest shareholder
after Roger De Haan, son of Saga founder Sidney De Haan, and
investment firm Hosking Partners LLP, according to LSEG data.
Last month, London-listed Saga, which caters to over
50-year-olds, forecast double-digit growth in annual revenue and
said underlying profits would beat market estimates, betting on
resilient travel demand from retired and wealthy Britons who are
less impacted by the cost-of-living crisis.
Shares of the company were up 3.8% to nearly 119 pence by
1126 GMT on Tuesday. They have fallen 5.4% so far this year,
compared with a 5.7% drop in London's small cap index
The link to Grahams daily chat sends me to a Micheal Cain movie clip. Help please.
yes me too !!
Unfortunately Graham was in the van so the internet went down. :)
Reminds me of the time Michael Caine joined ADVFN and ended up buying Argo Blockchain (LON:ARB) at its peak.
*Dont watch if youre easily offended
Same for me.
Why tag Moneysupermarket.Com (LON:MONY) if it is not covered on the SCVR?
Tags seem to have from missing to including ones that only get a brief mention. It is quite confusing if you do a search on a stock.
Moneysupermarket.Com (LON:MONY) was covered by Graham in his daily live show at 11:30am:
Interesting to hear Grahams thoughts on Frontier Developments (LON:FDEV) and a possible capitulation phase
I wonder if we've hit peak gloom in the games sector?. The chart is interesting, I wouldnt touch it while it fell into the shredder a couple of months ago, but its starting to show potential now Id say. The downhill boulder is slowing, so maybe potential trend change on decent volume. Risky tho as its in a massive downtrend since 2021 . Ideally would like it to close near the high for the day, then a follow through day tomorrow.
Team17 (LON:TM17) Big volume spike 2 days ago. Price has puked like so many in the last 3 weeks.
Team17 (LON:TM17) had big volume today nearly 2m shares, a chunk went thru at 245p. Maybe that’s the seller out of the way, coupled with Frontier Developments (LON:FDEV) news perhaps the sector is turning.
Are there any holders of Digital 9 Infrastructure (LON:DGI9) here? It looks interesting and has bounced today on today's RNS:
------------
Further to the announcement of 28 September 2023, the Company's Board of
Directors confirms it has engaged with shareholders, representing
approximately 74% of the issued share capital, in conjunction with the
Investment Manager and the Company's Joint Corporate Brokers, J.P. Morgan
Cazenove and Peel Hunt, and in addition to hosting a retail shareholder-only
webinar on 10 October 2023.
The Board has received feedback from its shareholders on a number of areas
including D9's dividend policy and the future direction of the Company.
Having considered the shareholder feedback, the Board is developing a set of
actions focused on maximising shareholder value. To support the
Board's assessment, it has retained Goldman Sachs International as lead
financial adviser.
A further announcement will be made in due course.
XPS Pensions (LON:XPS) (I hold)
It appears to be reasonably well run (i do not work for them but know some who do) and is in an area where there are a lot of regulatory tailwinds (gmp reconciliation and equalisation) that have to be done over the next few years.
hoping for further outperformance. It wont last forever as it is hard to get a durable moat and the flow of regulatory and business change will ebb at some point. Also employee costs are rising.
Guessing 3 to 5 more good years. But I have been saying that since 2004.
I am gutted I sold out previously, must have been the key requirement for the continued success obviously :)
Quarterly flows were certainly disappointing. But the quarter is not looking as bleak as the headline numbers suggest when compared to other asset managers.
Jupiter's investment performance was better than many others which actually makes its overall AUM movement 'less bad' than most asset managers.
And net flows are also looking 'less bad' than most. (There are still a few AMs to report this quarter (Liontrust Asset Management (LON:LIO) on Wednesday, Schroders (LON:SDR) and Man (LON:EMG) Thursday) so we'll see how they did - but worth mentioning is that Singers, in a 4 Oct note, estimated Liontrust outflows (using Bloomberg data) for the quarter to be c£1.2bn (off an AUM base c40% less than Jupiter - we'll see if they're accurate tomorrow).
I wonder if there is some industry contagion following the (well deserved) SJP pummelling recently. SJP paint the industry with a very bad brush which I am not sure JUP deserves to be caught up in.
I cant see any reference to it in the update but is the huge net cash figure Stocko seems to indicate Jupiter Fund Management (LON:JUP) has correct or is it actually client monies not the companies ?
Thanks if anyone can clarify.
From their recent interims presentation
Thanks P Bryant you will have to excuse me being a bit dim is the most relevant figure expected capital surplus £147.3 ?
Hi
See my earlier post re SHOEZONE following TEINs earlier post concerning revenue per store
SHOE - I wouldn't ignore TEMU Paul but I would remind you the reason BOO and ASOS struggle is the fact they don't have click and collect and SHOE's returns are a fraction of those two. TEMU don't have click and collect. Buyers like the convenience and so do retailers.
A lot of Shoe Zone (LON:SHOE) customers won't do online shopping. Boo is online, according ti wiki: "Boohoo Group plc is a British online fashion retailer, aimed at 16–30 year olds." I think different sector of the market from Shoe Zone (LON:SHOE), most customers in the ones I see are over 60, maybe just my area, one concern is they never seem busy. I only buy slippers in there, not bad for £8, for the summer.
I find most chinese made shoes too narrow. I rarely buy shoes online because the sizes are not consistent, it is ok if you know the brand. I can buy NB trainers size 8 in an E fit and know they will be fine but other brands, no idea. Not many brands do wide fittings now. Clarks do. I stopped buying some brands because the fitting was too narrow.
I worked in a shoe shop for a little while when I was young. If the customer complained about shoes being too tight we used to tell them we would use the shoe stretching machine in the storeroom. We then had to put the shoe on the handle of the broom and force it around the inside. Customers often said "that's much better"! Probably doesn't work with man-made shoes though.
The good old days.
Hi Paul, RebelChat, I agree that one must not ignore cut throat assailants but there's more to Shoe Zone (LON:SHOE) retailing. Parents want kids to have feet measured and try on. Older people, and you see a lot in Shoe Zone, aren't going to move lock stock and barrel to the internet. Meantime, Shoe Zone are attacking higher price footwear retailers across the UK. Their online offering also has next day delivery. There is probably more scope for new sites once the estate rationalisation is complete.
My conclusion is that there are two key issues here:
1) The customer profile of Shoe Zone is not the same as the fast fashion retailers ASOS (LON:ASC) , Boohoo (LON:BOO) etc. Time will tell whether their profile is the same as Shein and Temu but I suspect not. That's not to say there isn't some overlap of course.
2) Shoe Zone is a bricks and mortar business + online. None of the above are.
Thanks for the analysis. The SP for Shoe Zone (LON:SHOE) is still below it's previous high so I agree there is still value.
For clarity I hold SHOE.
Regards,
TEIN
Agree, you only ever buy shoes online once. Never again as they always have to go back….and try fitting a shoe box in a post box.
you only ever buy shoes online once
The trick is to buy the first pair in a shop, I did with Ecco years back, and then keep buying the same model and size online when they need replacing!
I see Jupiter Fund Management (LON:JUP) is down 11% today. This is the lowest it has been in 20 years.
Asset managers have taken a caning this year. JUP is down 43% YTD, Abrdn (LON:ABDN) 13%, Investec (LON:INVP) 11%, Schroders (LON:SDR) 11%. M&G (LON:MNG) bucks the trend by being up 5%.
In comparison, the All-share index is flat YTD, which might come as a surprise. The FT250 is down 8% YTD.
The asset managers are looking really cheap.ABDN is near its 20 year lows, although not as cheap as 2009 or late 2022.
SDR has had a good track record share performance wise.
I'm getting quite excited about the whole fund/asset management sector almost as a geared way to play a market recovery. Wouldn't mind a couple cutting dividend payments, might hit the share prices a bit more.
I don't see any rush to buy just now as they all tend to track forward earnings forecasts. my simple plan is to 1. Wait for EPS forecasts to bottom and start to rise or 2. Wait for charts to reverse trend, then dip a toe in ...which can be added to once eps upgrades start to happen.
Jupiter Fund Management (LON:JUP)
Impax Asset Management (LON:IPX)
Ashmore (LON:ASHM)
Polar Capital Holdings (LON:POLR)
Liontrust Asset Management (LON:LIO)
Premier Miton (LON:PMI)
Tatton Asset Management (LON:TAM)
Abrdn (LON:ABDN)
What is your sector pick from the fund managers Wolf? I hold Polar Capital Holdings (LON:POLR) which has struggled badly over the past month or so, I like the company and maintain confidence longer term. In the short term, I am thinking of splitting the holding across two fund managers to add some diversification.
Polar Capital Holdings (LON:POLR) was top my pick but their funds not performing quite so well last time I checked and still too heavy is technology for my liking. Most of the others you've mentioned are too generic for my liking and don't have any particular specialisation.
I would say M&G (LON:MNG) is top pick now,. They are a hybrid insurance company/fund manager, but the fund management side is performing very well recently and they're seeing solid inflows. I can also see M&G being a bid target as their private market business would be attractive for one of the big US asset managers.
Hi Ben
I cut Polar Capital Holdings (LON:POLR) yesterday from the income side of the investments, like the company, and I will hold again, but right now capital preservation. I am not trying to fight Mx. Market and Mx. Market is giving a clear signal, which Wolf is a lot better at explaining than me.
I still hold M&G (LON:MNG) because this is bucking the trend at the moment, but if they reverse then I will exit for a while again.
Good luck
Tommy
I agree.... Although Im leaning more towards TP Icap (LON:TCAP) since they are a volume of trade play and will benefit from rates falling. I also feel the traditional fund management groups have a lot of issues around fees and performance. Performance is everything and Liontrust Asset Management (LON:LIO) seems to have its issues. Maybe AJ Bell (LON:AJB) or Rathbones (LON:RAT) / Hargreaves Lansdown (LON:HL.) are also better ways in at the right time. Personally feel like AJ Bell (LON:AJB) might be the right combination of retaining a growth trajectory and doing a good job for clients. Liontrust Asset Management (LON:LIO) are top of the share register which is a short term hurdle to cross so im not there yet.
Great post .... I agee it is too early to buy and but I continue to watch.
Jupiter Fund Management (LON:JUP)
I have a small holding, now smaller. I think that short sighted Mr Market has thrown the baby out of the pram because of the references to a points discount on funds as they grow and staff remuneration. Will wait for an expert view from Graham.
"The new model will be implemented from early 2024 with basis point discounts taking effect as a fund reaches various levels of assets under management. The first threshold will be when a fund reaches £500m of assets, at which point a 2 basis point discount will be applied. Although we cannot forecast client flows and business mix, at our current AUM this would result in an additional decline in the overall net revenue margin through 2024 of between 1.5 bps and 2 bps.
In addition to investing in our clients and in our technology infrastructure, we are also investing in our people. In today's competitive market environment, we have worked hard to ensure our talented investment professionals are remunerated appropriately, based around performance criteria that ensures interests are aligned between Jupiter, our people and our clients. Our thoughtful and competitive retention policies are designed to support the growth of the firm in key strategic areas.
If the performance criteria are reached, and assuming that there is no material market recovery, this will have an impact on our total compensation ratio. Depending on market conditions, we can reasonably expect the compensation ratio to be within a range of mid to high '40%'s through 2024, which we believe is in line with observable trends across the peer group."
Jupiter Fund Management (LON:JUP) trading update out. Retail outflows of £1bn over 3 months. SP has been tanking recently. Hoping Graham covers the update.
https://www.investegate.co.uk/...
A £1bn outflow out of a total of over £50bn seems pretty good to me. Obviously we don't know if that has accelerated in to the start of the final quarter or not. But an 11% drop in share price on that news seems overdone to me. I don't hold.
B.P. Marsh & Partners (LON:BPM)
Excellent update this morning - NAV per share up from 526p per share 31/1/2023 to 567p per share 31/7/2023. Not expecting this growth rate to be repeated but not going to complain with nice continued nav upgrades. With shareprice still under 400p i think i am less likely to sell if price returns to 420p recent highs than i would have been previously.
Its a long term hold for me having bought in at just over 200p quite a few years ago. it tends to grow between 5-10% most years and thats what it does. It never used to get a mention anywhere until the realization earlier in the year and now its on a few more people's radar which I am hoping to lead to a re-rate for a while. People do tend to get bored of this stock after a while and will sell it off again.
I will just keep holding
Hercules Site Services (LON:HERC) another impressive growth update at year-end (revs +60%) with progress in all 3 divisions meaning results well ahead of expectations. With strong growth trajectory and healthy forecast free cash flow, our Fair Value remains 60p/share vs 25p last close. New note is freely available here : https://www.equitydevelopment....
Bonds - a time to buy? I know this is off topic, but I wanted to ask the community for their views. If the interest rate cycle has peaked, locking in to fixed income should give good capital gains? I’m trying to learn about Bonds as I feel they may offer some relief from this grinding bear market. iShares £ Index-Linked Gilts UCITS ETF GBP Dist (LON:INXG) or iShares $ Treasury Bond 20+yr UCITS ETF USD D (LON:IBTL) appear to be a geared play. Of course if rates do increase they will continue their spiral.
I traded iShares £ Index-Linked Gilts UCITS ETF GBP Dist (LON:INXG) around Truss gate....not much wrong with it tbh however, be aware that the return of low coupon long dated bonds is tied up in redemption value. The market was very expensive for a long long time. Should long term yields fall it will do ok BUT at the moment, they are rising. It's been dead money drifting therefore. There are a couple of quite short dated Gilts you can buy for redemption 2024 or 2025...with low coupons if you want to avoid income...but decent 5% plus redemption yields.
The latest Howard Marks thoughts are getting airtime as he is suggesting high yield corporate debt...since it yields 9% to maturity and this is a higher expected return than pensions assume on equities. Ironically I think both your expectation of better return on long duration debt and better returns from high yield sow the seeds for better returns from safe boring equities too. Many of these are on sub 10x PEs and yields 5% plus....
Final thought would be this discussion is basically a move up and along the risk curve.... as this plays out the best returns will go where they always go. Ironically therefore turning the bear market you seek relief from.....into something more pleasing.
I lean towards combining short dated bonds I can hold to maturity and equities... this way you can't lose money on the bonds. Nominal money anyway....
I welcome discussions on Gilts, Bonds and other fixed income here. They are the largest market but do not get much attention here because they are not small caps!
And if you are looking at corporate bonds then pls buy a collective option, not individual bonds. There is huge assymetry to individual corporate bond returns - the upside is mostly the coupon (unless materially sub-par), while the downside on default is often 60-90%....
If you think you need 20-30 equities to diversify your equity holdings (I personally think the number should be much higher) then the equivalent is something like 100-150 bonds in the investment grade space, lower for junk.
Thanks Monty for these two posts - I had overlooked the exemption from CGT for holding gilts - however the example you give below, while technically fine does not seem so attractive when the maturity is so far ahead - 2031. Agree that best idea for holding bonds is a Fund - there are too many out there - I hold M&G Short Dated seems to be a good option
Well, I was just picking the lowest coupon as an example.
Amongst the shorter maturities you could look look at the UKT 0.625 06/25 which yields 4.63%. Still a very low coupon to minimise income tax.
Depends on your view of where rates are headed. The original poster questioned whether rates had peaked, so he would want to look at longer maturities with some duration to profit from rates expectations declining (a doward shift in the curve, in the jargon). Most private investors should stay away from 30yr bonds (where you could make/lose real money) given they won't hold to maturity and the market out there is quite technical. However 10yr bonds could reasonably be used to lock away savings for university fees etc.
With name like "Trader Jack" you will forgive me for assuming that holding to maturity isn't his style....
RDH - thank you - much appreciated. Any suggestions of Corporate Bond IT’s to research? Twentyfour Select Monthly Income Fund (LON:SMIF) TwentyFour Income Fund (LON:TFIF) I don’t like OEIC’s!
Should we start a separate thread for this?
If you are going to look at fixed income investment trusts then be prepared for the accounting hassle. UK domiciled funds will often declare two separate types of distribution - a dividend (like any equity) and an interest distrubution.
The tax treatment differs so beware.
I dipped into the bond market yesterday. Invested in a mixture of short duration bonds. iShares £ Ultrashort Bond UCITS ETF GBP (Dist) (LON:ERNS) iShares UK Gilts 0-5yr UCITS ETF GBP (Dist) (LON:IGLS) JPM GBP Ultra-Short Income UCITS ETF - GBP (dist) (LON:JGST) PIMCO Sterling Short Maturity UCITS ETF GBP (LON:QUID) . I'm probably wrong but I feel that this bear market in small companies has further to run.
It could be that a recovery in the bond markets would presage a recovery in the equity markets?
We should really copy & paste these posts to a separate thread in the DISCUSS section....
There is a decent opportunity if you are a higher-rate tax payer investing outside your ISA/SIPP, who is expecting to use up their CGT allowance for the year.
If you buy one of the very low coupon gilts which is trading well below par then you will get the bulk of your return from the "pull to par" i.e. the bond will redeem at 100. This will be a capital gain, and you don't pay CGT on gilts.
So you could buy the UKT 0.25 07/31, which only pays a 0.25% coupon, but the yield to maturity is around 4.3%. It is priced at 73.44 - so there is >26p of pull to par. So over 4% of the annual return if you held to maturity would be capital gain. You would need to put your money into a savings account with a interest rate approaching ~7% to achieve the same POST TAX return. These are rough numbers.
The place to look for closing price/yields for each individual gilt is:
https://reports.tradeweb.com/closing-prices/gilts/
Filter for "conventional" and "gilts".
So it is very gilt specific and it depends on your personal tax situation. You should also be aware that low coupon gilts have a higher "duration" - they are more sensitive to shifts in interest rate expectations. If the yield curve shifts higher you may make a mark-to-market loss if you sell before the maturity date.
If you buy the wrong gilt you will pay a lot of income tax on the running yield, and you may achieve a sub-inflation return.
If you are on a variable rate mortgage then paying that down is an option you should consider first.
I'm not a bond sophisticate so take my view with big pinch of salt.
For individuals I think traditional gilts and treasuries are tough decision even at these higher yields for PI seeking a buy and hold asset long term. Short term or actively trading them different scenario (and lots of ongoing judgement calls - holding some short dated as someone suggested when yields high enough makes sense).
In US real yields on linkers at approx at c.2.4% on 30yr and 2.6% 20 yr. That's pretty tasty and not a bad lock up and let it run if retirement planning for some or all portfolio. In a high (say from c.5%) to very high inflation environment it'll be hard to beat for capital and spending power preservation. I believe some financial repression lies ahead of us whereby rates are kept low relative inflation so as to make debt management easier. Sounds good for linkers...but I've got a nagging anxiety that governments could find ways to subtly defray costs to themselves of these inflation (so policy) busting bonds. Its my long held opinion that linkers are a tool govts will regret taking.
But above yields are US and not UK! Here the opportunity is less rich at c.1% due massive institutional demand for the product. Personally that isn't enough for me to buy and hold, particularly when in UK can pick up 'real' (in the inflation adjusting sense) companies paying out significant yields. The inflation adjustment of companies is volatile and not perfect but profound over time (assuming a society doesn't fail...in which case ILGs won't be much use to you either!).
So I'd rather pick my own dividend stocks (highish yields but yield growth too) rather than go ILG...or if want to outsource then fund or etf
As linkers are tied to a specific inflation index... published by the govt... is the risk of govt manipulation in that index a real possibility? Or just a false scare story?
As you say, governments worldwide will face fiscal pressures relating to interest on debt soon. It is not hard to envision highly populist pressure ("we're paying rich investors more interest than we fund the NHS, thousands of babies dying a year") to do some "restructuring" of government debt. And it seems like fiddling the numbers for something like linkers could be an easy way, instead of defaulting on debt.
Like how the "triple lock" pension right now has come close to multiple fiddlings to reduce that liability... despite the "lock" guarantee made...
Boon, I didn't say (or intend to) that they'd fiddle inflation...I'm not into the complex conspiracy about whether inflation is or isn't measured well (given the breadth and variation of our consumption its become a very complex task compared to the simple 50s etc). Though of course govts are alway going to tweak what they can.
I believe it was a mistake to issue linkers in the first place. A restriction and straightjacket govt shouldn't have chosen to wear. UK did it first and partly that was as we were seeking fiscal/monetary credibility.
In a persistent quite high inflation world (not my base case) needing to pay up and out on linkers could become a real drag on govt finance. TBH it probably only means a discontinuation risk...but there would be a chance of being forcibly pushed into an alternative more suitable to govt finances due to pressures of high debt and govt spending (part of general financial repression). And TBC I think holders today will be pretty safe. Its not an irrational allocation in any way...
...I suppose I should have stuck to my (better) point that if you have the ability to do it then a portfolio of yield growth is likely a better risk IMO (tho more complex and definitely with risk and volatility)
Inflaton is calculated by the ONS - not the Treasury or the Bank of England.
It cuts both ways as well e.g. student loans.
The ONS is independent of ministers and reports through the UK Statistics Authority to Parliament and the devolved administrations of Scotland, Wales and Northern Ireland.
So skulduggery possible? Yes.
Likely? No.
Within my Vanguard SIPP I hold Vanguard USD Em Mkts Govt Bd UCITS ETF USD Dis (LON:VEMT) and Vanguard USD Corporate Bond UCITS ETF USD Dis (LON:VUCP) currently. There are a whole other range of "Fixed Income" which give the exposure to particular areas such as US Government Debt, or UK Gilts. There will be the same in ishares (Blackrock) or whichever investment company you prefer.
Within the other investments there are some other holdings which are corporate debt, such as Twentyfour Select Monthly Income Fund (LON:SMIF) mentioned and CQS New City High Yield Fund (LON:NCYF) these are specific small holdings for the yield (income for mum's retirement as she is 82 years young). So learning the risk slowly and taking the income, with small (~1-2% holding) across several different investments. Like all holdings there is a manual stop loss on these!
Whilst I am not an active trader, I am nervous, emotional and impulsive, so the big thing with all of these is knowing that I can log in and sell on any given trading day.
I need to do more on the fixed income side of investment, given my mum's age and also my and my sister pending next stages, but that is on the to do list so yes to conversations!
But things like my SIPP I am slowly investing the cash pile on big down days, if I see that within the day then I will just drip some more into the various holdings on the basis it is good longer term!
Cheers
Tommy
Shoe Zone (LON:SHOE) brought a smile to my face this morning (as the shares have been weak of late and I was starting to wonder if someone knew something I didn’t)
Profit pre tax of at least £16m is a record & all the while buying back and cancelling 3.75m shares
Benefitting from lower container costs
They seem to be doing everything right so I’ll continue to hold
Shoe Zone (LON:SHOE) Strikes me as an acceleration as the forecast PBT is now 18% higher than the previous forecast made in July. Of particular interest is 6% increased group sales on a reduced number of stores, and aided by online sales being 17% higher and now nearly 19% of group sales. Upbeat current trading comments suggest value is king as higher consumer rent/ mortgage, fuel, home utility and Christmas costs start to bite. I predict Shoe Zone won't be one of the retail fallen come January.
Updating that there are now 10% fewer stores (323 vs. 360) would be a more useful statistic if alongside it the trading area/ sq.ft before and after was also shared. [I hold]
The shares in issue also reduced by buybacks (I dont have figures)therefore increased earnings per share from this factor also
Re SHOEZONE - Not allowing for part year store closures the revenue per store works out at £417k against £360k an increase of 15.75%. I know this will not be exactly correct but it gives an indication that not only online sales are up 15% but shop are following ghd same trajectory. I know Paul reckons Shein may eat their online lunch but online accounts for only 20% and I for one will always want to try shoes on. Getting ill fitting shoes is painful. Ouch!!
Happy holder if special divis are on their way
My morning smallcap tweet: Peeling the fruits of avarice
i-nexus Global (LON:INX) Frontier Developments (LON:FDEV) Vanquis Banking (LON:VANQ) Zinc Media (LON:ZIN) XPS Pensions (LON:XPS) Hercules Site Services (LON:HERC) Shoe Zone (LON:SHOE) 4Global (LON:4GBL) Abingdon Health (LON:ABDX) Smiths News (LON:SNWS) Software Circle (LON:GRA), THG (LON:THG), Smartspace Software (LON:SMRT), Nanoco (LON:NANO), B.P. Marsh & Partners (LON:BPM)
◄i-nexus (INX)► a major legacy customer decides not to renew at end 2023. Will lose £54k pcm. Board believes it has sufficient working capital for at least 12 months. Trading: Monthly Recurring Revenue up 16% to £289k in Sept. [SP=4.69 Cap=1m]
◄Frontier Developments (FDEV)► guides FY24 in line with f/.c of rev £108c and adj EBITDA loss of £9m. Review to lead to op cost cuts of up to 20%. "The Organisational Review and resulting actions are expected to conclude by early 2024." [SP=193 Cap=76m]
◄Vanquis Banking (VANQ)► guides FY23 adj pretax £25-30m. Retirned to profit in Q3. Guides H2 div only 1p max. Co has " taken immediate action to return the Group to a path to sustainable, profitable growth." Strategy review will complete by the end of Jan. [SP=115.6 Cap=288m]
◄Zinc Media (ZIN)► wins $9m contract, its largest ever in the US. Will be filmed towards the end of FY23 and throughout FY24, with final delivery in FY25. [SP=85.06 Cap=19m]
◄XPS Pensions (XPS)► guides FY-Mar ahead of its previous expectations. H1 rev rose 23%. [SP=199.5 Cap=414m]
◄Hercules Site Services (HERC)► guides FY-Sep rev £80m+ up c.60%. F/C is £73.1m. Expects adj EBITDA to beat F/C of £3.4m. Outlook - ""Further new revenue streams will also be delivered through our new Labour Supply specialisms, which are well aligned with industry trends. For our Civils business, we are working with our clients in the water space to upgrade sewage and water treatment works". [SP=25.4 Cap=16m]
◄Shoe Zone (SHOE)► guides FY-Sep rev up 6% and adj pretax £16m+ (£11.2m). Product margin increased to c.62.1% as container prices fell. In line? [SP=211.36 Cap=98m]
◄4GLOBAL (4GBL)► wins contracts worth $290k and $250k for delivery this FY. [SP=60 Cap=16m]
◄Abingdon Health (ABDX)► FY-June. No current requirement for additional funding. Cash £3.2m and FY end.. [SP=13 Cap=16m]
◄Smiths News (SNWS)► News UK contract (to 2029) extended to London. [SP=41.7 Cap=103m]. I hold.
◄Grafenia (GRA)► becomes Software Circle (SFT) tomorrow. [SP=10.54 Cap=41m]
In line: THG, SMRT, NANO, BPM
Seriously Paul, I don't understand people who blame you for their portfolio problems. You don't give recommendations or advise. Everyone has to do his own research. You did not twist their arms or force them to buy any share. They made the decision themselves. God gave them brains that they can use to think for themselves before buy or sell any share. As usual, your weekend podcast was brilliant. Thanks for the shout out. Couldn't believe it, I've sent the podcast to all of my friends. They said I became famous :) :D ;D
Whenever I need to find someone to blame for my portfolio problems, I look in the mirror.
Thanks Mo! I thought you'd be tickled if I gave you a fun mention in the podcast! It's nice to have enthusiastic & positive people around, especially in these difficult times :-)