Small Cap Value Report (Tue 18 July 2023) - UPGS, ZTF, LUCE, REC, JDG, NIOX, DX., BMY, REVB

Good morning from Paul & Graham!
Today's report is now finished.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £1bn. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk.
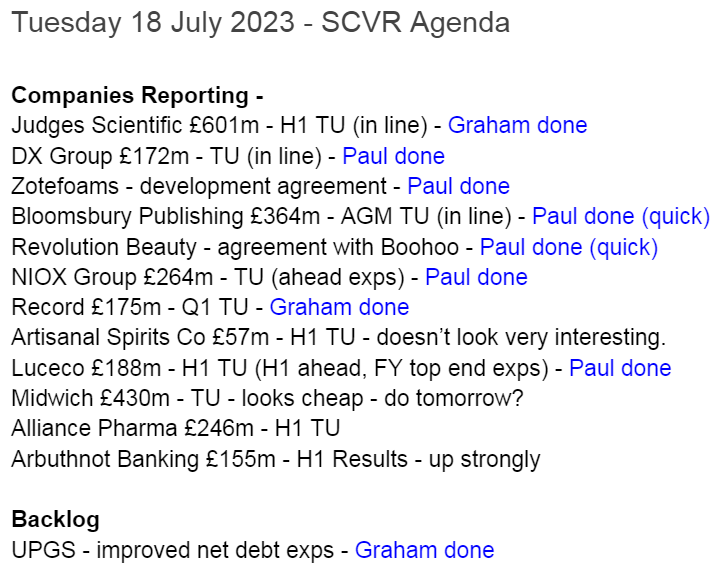
Summaries of main sections
UP Global Sourcing Holdings (LON:UPGS) - up 3% yesterday to 126p (£113m) - Improved Net Debt Expectations - Graham - GREEN
This household brand owner announces net debt at year-end (July 2023) is significantly below expectations (c. £15m vs. £21m). We don’t have info on average net debt and I’m not sure the improvement has come from sustainable sources, but the stock is interesting.
Zotefoams (LON:ZTF) - up 9% to 350p (£170m) - Joint development agreement - Paul - GREEN
Encouraging news about a partnership to develop the innovative drinks cartons project, ReZorce. This is one of my top picks for 2023, so it's good to see some positive newsflow.
Luceco (LON:LUCE) - Up 4% to 121p (£194m) - H1 Trading Update - Paul - AMBER/GREEN
Quite a good H1 update, and says towards top end of range of broker forecasts for FY 12/2023. Looks a decent, owner/managed business, maybe priced about right? I like that trading seems to have settled down now, after a boom & bust caused by the pandemic. Overall - I'm moderately positive on this share.
Record (LON:REC) - down 6% to 83p (£165m) - First Quarter Trading Update - Graham - GREEN
A reversal in fortunes at this currency manager as they suffer outflows in Q1. Passive Hedging, such a strong performer last year, saw $3 billion removed. I will maintain a positive view here as it has such a long and impressive track record. Hopefully this is just a blip.
Judges Scientific (LON:JDG) - up 3% to £93.99p (£621m) - Half Year Trading Update - Graham - AMBER
Judges returns to solid organic order growth, and organic results will be boosted by Geotek plus some smaller acquisitions. It’s full steam ahead for Judges, therefore, but I would not be in a rush to buy these shares at this level. Long-term holders will be happy.
Niox (LON:NIOX) - Up 13% to 72p (£303m) - Trading Update - Paul - GREEN
My first look at this company, which makes asthma diagnosis equipment. It's moved into profit, is growing nicely, with high operational gearing from good gross margins. Looks a very interesting growth company, worth readers researching more I think.
DX (Group) (LON:DX.) - up 1% to 31.9p (£193m) - Trading Update - Paul - GREEN
A solid update, in line with expectations for FY 6/2023. It's absorbed a lot of the business and depots from failed Tuffnells, which sounds positive. We like the cheapness of this share, with a low PER, decent yield, and a decent cash pile too.
Quick Comments
Bloomsbury Publishing (LON:BMY) - up 2% to 450p (£368m) - AGM Trading Update - Paul - GREEN
In line with expectations for first 4 months of FY 2/2024, with a footnote saying this is revenue: £273m, and aPBT: £32.5m. StockReport shows 29.4p EPS, so a PER of 15.3x.
Forecasts were upgraded previously, see SCVRs 15 March, and 1 June 2023.
Paul's view - Excellent steady growth company, nice balance sheet, lots to like here. So I’ll keep my GREEN view of it. High StockRank of 87.
Revolution Beauty (LON:REVB) - up 4% to 32p (£97m) - Settlement with Boohoo - Paul - AMBER
An agreement has been reached, but it looks more like a capitulation to me! Boohoo has ousted Chairman Bob Holt, with 4 new Directors joining the Board. Who knows what's gone on behind the scenes? Someone should write a book about it.
Paul's view - I can't assess the company itself, as we need much more information on the accounts, and current trading. Boohoo seems to have almost seized control, but without bidding for it, and with a 26.5% shareholding. I bet Mike Ashley has been taking notes!
Paul’s Section:
Zotefoams (LON:ZTF)
Up 9% to 350p (£170m) - Joint development agreement - Paul - GREEN
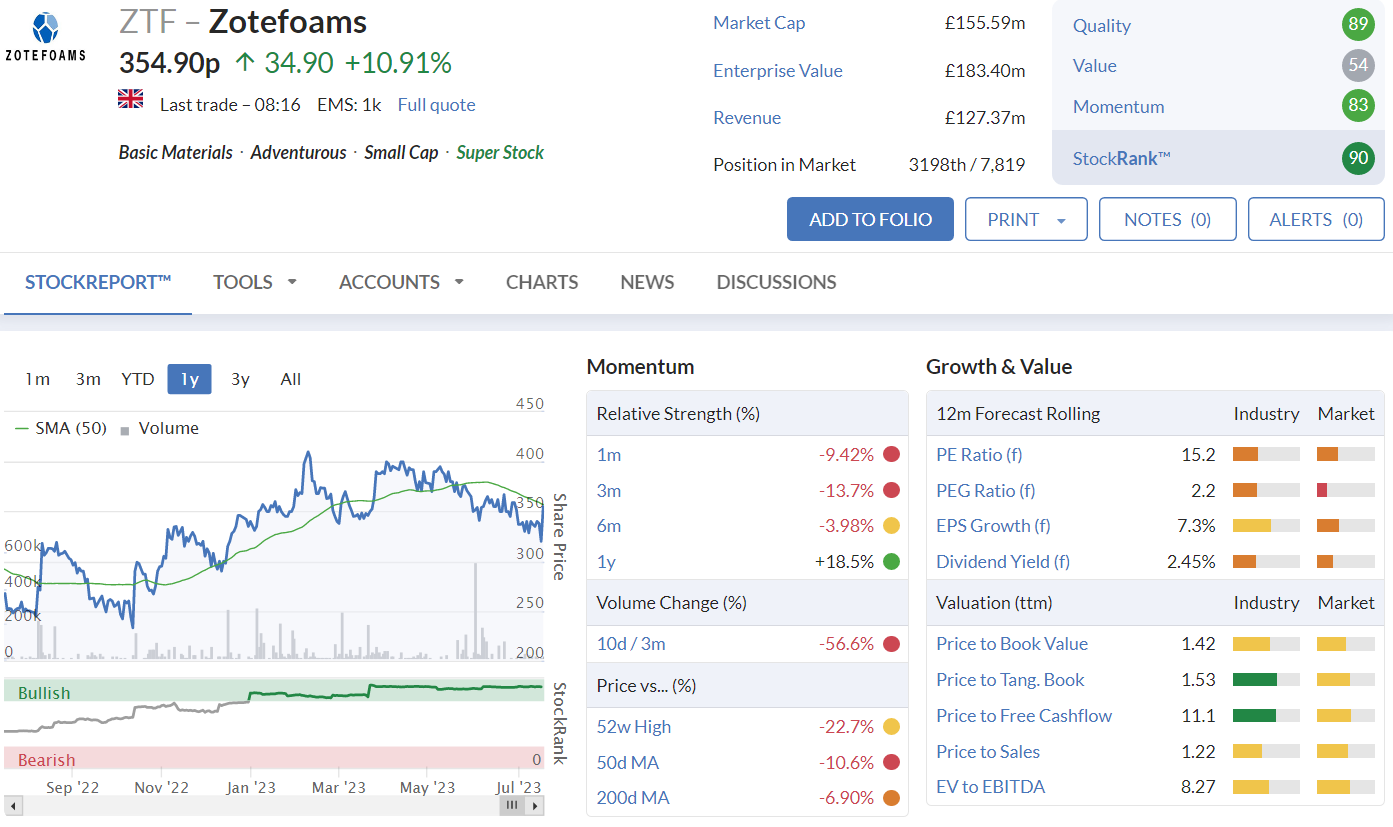
ZTF is one of my top watchlist shares for 2023. So far it's about flat year-to-date, so nothing exciting going on as yet.
This announcement today concerns ZTF’s blue sky development project, ReZorce - which is fully recyclable one-material drinks cartons. Existing drinks cartons are not recyclable, because they are made from laminates of different materials (eg plastic, aluminium, etc).
Another key advantage is that the ReZorce product, if successful, could be used in drinks packaging factories, on the existing machines, so no special capex required for the drinks makers.
ZTF had previously indicated that it wanted to develop this project with a large scale partner, so this sounds encouraging news -
18 July 2023 - Zotefoams, a world leader in cellular materials technology, is pleased to announce a joint development agreement ("JDA") with a world-leading packer of beverages.
Following successful internal trials, this agreement encompasses the further development of Zotefoams' ReZorce® monomaterial beverage carton packaging, and its planned use in in-market trials for a major European retailer.
The JDA covers all activities, including packing at industrial scale, to trial ReZorce® cartons in the retail market and non-binding provisions for further co-operation. Zotefoams anticipates that the initial scope of work will continue until early 2024.
David Stirling, Zotefoams Group CEO, notes, "This agreement confirms the significant technical progress we have made with our ReZorce® mono-material barrier range. As we have continued our development efforts, it has become clear that demand for a sustainable alternative material for beverage cartons is significant and in line with our initial market assessment.
"This agreement for ReZorce® development is an important milestone and we look forward to it delivering results that clearly demonstrate ReZorce® is the optimal material solution for beverage cartons."
Paul’s opinion - this is encouraging news I think. The way I look at ZTF shares, it’s a decent company making specialised products at fairly good margins. The biggest customer is NIKE, which recently extended its long-term supply agreement with ZTF, so single main customer risk reduced.
The upside potential from the ReZorce project is basically in for free, and at times management have sounded very excited about its potential. However in the most recent updates I perceived that management seemed to have cooled somewhat on ReZorce, which made me wonder if they’re softening up the market for it being quietly dropped?
Hence today’s news of a new partnership should reignite interest in ReZorce.
The valuation metrics look quite good, with a fwd PER of 15.2, and it’s nicely asset backed too with a strong balance sheet. The share price is only 1.53x tangible book value, so very nice asset backing there, including the freeholds to its factories, which have recently been re-equipped with new machines. So all well invested.
At some point I need to pick up a few of these for my own portfolio. Trouble is, there’s such a long list of decent, reasonably-priced shares that I want to buy, we’re spoiled for choice at the moment. Instead of being excited at these bargains, everyone seems scared witless. It’s funny how sentiment changes!
Luceco (LON:LUCE)
Up 4% to 121p (£194m) - H1 Trading Update - Paul - AMBER/GREEN
Luceco plc ("Luceco" or "the Group"), the supplier of wiring accessories, EV chargers, LED lighting, and portable power products, is pleased to provide the following update on trading for the six months ended 30 June 2023 ("H1 2023").
Encouraging first half performance.
Full year guidance towards the upper end of market expectations.
Remain vigilant to the changing economic environment.
Main points -
H1 revenue down 5% to £101m, although it says this is ahead of expectations.
Downturn due to reduced activity in the housing RMI (repair, maintenance, and improvements) market. This is obviously the hangover after the pandemic boom.
Gross margins improved.
Customer de-stocking “appears to have ended”.
H1 profit guidance -
Adjusted Operating Profit is expected to be no less than £10.5m, ahead of our expectations.
No figures on bank debt, but covenant net debt is 1.3x (target range 1.0 - 2.0x) - this sounds OK.
Working capital increased in H1, expected to unwind in H2 - that’s OK I think, it’s normal for working capital to fluctuate, especially after all the disruption in recent years.
2 recent acquisitions “both performing well”.
Full year guidance -
Assuming demand continues at current levels and is not impacted by macro-economic headwinds, we anticipate that Adjusted Operating Profit for the full year will be towards the upper end of the range of current market expectations*.
*consensus at the 17th July 2023, full year 2023 Adjusted Operating Profit £20.3m (Analyst Range £19.2 - 21.9m)
General moan - I wish we could get some uniformity for trading updates. Different companies seem to pick whatever benchmark they like. Most report EBITDA, which many investors (including me!) dislike. I prefer adj PBT, providing the adjs are reasonable, but most companies don’t report that in trading updates. I see the latest fashion seems to be reporting adj operating profit, which of course omits finance costs (which often include a lot of lease-related costs), unhelpful in a higher interest rate environment. Hardly anybody reports the most important measure I use, which is adj EPS.
So we’re forced to go to (often unavailable) broker notes to get the figures we actually need, and of course to find out if the company has slipped out a profit warning on the sly - another infuriating, and dishonest trend we’re seeing too much of lately.
Anyway, back to LUCE. We can see from the helpful footnote above that it expects FY 12/2023 operating profit to be near to £21.9m.
Outlook - this all sounds quite encouraging -
"It is encouraging to again see our gross profit margin improving and reassuring that our order book supports a good outlook for Q3.
Material and freight cost pressures continue to ease on the whole, but wage pressures remain.
We are excited by a number of product developments which provide us with good medium and long-term opportunities for growth, particularly within the EV business.
We continue to build an attractive M&A pipeline.
Historically the Group has enjoyed a stronger second half and, whilst we are mindful of the current economic environment, we expect a similar profile again this year."
Broker update - many thanks to Liberum for an update on the numbers. It highlights the importance of improving gross margin, as cost & freight pressures ease.
FY 12/2023 forecast EPS is now 9.3p (prev. 8.9p).
That gives a current year PER of 13.0x, which looks about right to me.
Thanks also to the Liberum analyst Charlie Campbell, who includes some interesting macro charts in the Luceco notes.
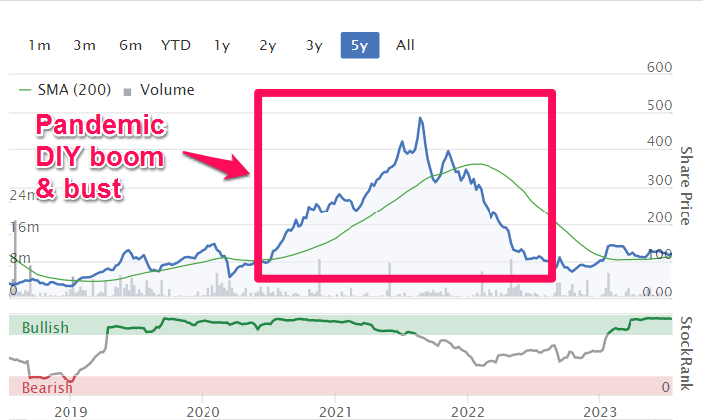
Paul’s opinion - it looks as if things have settled down now, with the boom & bust cycle having played out now.
The aggressive selling (in other sectors) direct into the UK by Chinese websites SHEIN and TEMU has unnerved me. So I’m generally avoiding all companies which just get stuff made in China, then sell it in the UK, because these could all be vulnerable to new, well-funded, and aggressively price-cutting direct competition from Chinese companies. So we need to be asking what defensible moats do companies like LUCE really have? Established, trusted brand names would be one potential moat for LUCE (also the same for UPGS).
The chart for LUCE seems to have found a floor over the last year, and maybe it can now start a fresh bull run at some stage? The valuation looks reasonable, and the newsflow today looks quite good.
There’s a nice StockRank of 94.
Owner/manager John Hornby has a healthy 18% stake. It looks like a private equity firm, Epic Investments, owns 22% - so maybe some delisting risk, given the top 2 hold 40%?
Pulling all this together, I think LUCE looks quite good. There’s a lot less guesswork needed now, than there was last year.
So I’ll give it a cautious thumbs up, so AMBER/GREEN.
I would ignore the pandemic boom share price movement, it's now reset back down to a more sensible level. So we need to avoid anchoring to the unrealistic spike in price that happened in 2020-21.
Niox (LON:NIOX)
Up 13% to 72p (£303m) - Trading Update - Paul - GREEN
Oxford, UK - 18 July 2023: NIOX Group plc (AIM: NIOX), a company engaged in the design, development and commercialisation of medical devices for asthma diagnosis and management, today announces a trading update for the six months ended 30 June 2023 ("H1 2023").
I’ve not looked at this company before, as medical devices is not a sector I have experience investing in. The early stage companies nearly always disappoint, but I can see a good case for investigating potential investments where a successful product is being commercially rolled out, which seems to be happening at NIOX.
Renowned fund manager Christopher Mills mentioned NIOX in his brilliant talk last night on Mello Monday (watch the recording if you missed it, this was quality stuff, from a man with a 40+ year superb track record at North Atlantic Smaller Companies Investment Trust (LON:NAS) - he reckons it’s 150-bagged in the time he’s been running it!)
There’s been a positive up 13% share price reaction to today’s trading update from NIOX, and this chart is signalling to us that something positive is going on - especially as this 1-year period has been a deep bear market for smaller caps, so this is a major out-performer -

Background - I’ve found a terrific article here from Jan 2022, which Jack Brumby wrote in the SCVR, detailing this company when it was called Circassia. Old management failed, and were replaced with new more commercial management, focusing on its most promising asthma diagnostics product called NIOX, hence the company name change.
Massive losses from 2017-2020 now seem to have been turned around into profit.
A special dividend of 2.5p was announced in June 2023 - looks a one-off.
Results for FY 12/2022 were boosted by £8.1m from a settlement with “Beyond Air” for a success fee, giving a total PBT of £10.5m, on revenues of £31m. The cash pile was £19.4m at Dec 2022. Strong recurring revenue. Gross margin of 71% gives excellent operational gearing as sales increase. Good balance sheet.
Latest news - today it says -
H1 revenue up 22% to £18.8m
Singers (many thanks!) estimates £37.9m revenues for FY 12/2023.
Adj EBITDA in H1 almost doubled to £6.2m.
Singers say £11.7m EBITDA for FY 12/2023, which is mostly real profit, as adj PBT forecast is £9.3m.
Forecast EPS for FY 12/2023 is 2.1p, so the PER is 34x - maybe justified, given the growth potential, and the operational gearing?
Net cash at June 2023 was £23.8m, but the special divi will make a £10.5m dent in this, when paid in Sept 2023.
I like this bit -
The Group is now generating sufficient operating cashflow to permit both continued investment in the development of its business and the payment of ongoing dividends to shareholders.
And this is good too! -
Ian Johnson, NIOX's Executive Chairman, said: "I am pleased to report continued growth in revenues and profits in the first half of the current financial year. It is particularly satisfying to describe the strong growth in our core Clinical business, which continues to benefit from a high degree of recurring revenues.
We indicated at the time of our AGM in May that adjusted EBITDA1 would be significantly higher than management expectations at the start of the year. After two further full months of strong trading, particularly in the APAC region, management's expectations for the year end outturn have been subject to further material upgrade.
The Company is now in a strong financial position and with positive momentum in the business. I look forward to updating shareholders again at the time of the half-year results."
Paul’s opinion - definitely not my area of expertise, but from what I’ve seen, this share looks attractive, and definitely worthy of further research. The hope is obviously that global sales of the product could really take off. With such high gross margins, that could be very exciting. Yet we can still value the company on traditional metrics like PER, and it’s paying divis too.
Plenty to like here! How to value it, no idea, but personally I’d be happy to have a punt on this. Vastly better than all the speculative rubbish we usually see in this sector, this is a proper company, making lovely margins, and generating cash. Is it worth £303m? I think that can be justified, providing growth continues. It’s about 20x Singers forecast for 2025, which I don’t have a problem with. An initial thumbs up from me I think, although as a credible growth company, not a value share. That’s based purely on a quick desktop review, not in depth research remember - that’s your job! ;-)
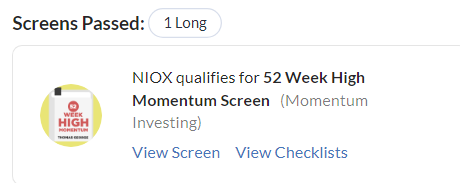
I see NIOX qualifies for the new 52-week highs screen - so let's have a look at this, and see what the other big winners are. There's a lot to be said for screening for out-performing shares, as winners often carry on winning. Or, they can be over-priced speculative bubbles! So sorting the wheat from the chaff may not be easy -
(picture is clickable link)
DX (Group) (LON:DX.)
Up 1% to 31.9p (£193m) - Trading Update - Paul - GREEN
DX, the provider of delivery solutions, including parcel freight, secure courier and logistics services, is pleased to provide an update on trading for the second half of the Group's financial year ended 1 July 2023.
We flagged the good turnaround, and cheap value metrics of this delivery company in the SCVRs on 15 Dec 2022, and 1 Feb 2023, with a GREEN opinion in both reports.
So what’s the latest?
Trading has been in line with management expectations for FY 6/2023.
Revenue up 10% to £470m.
Net cash rose 39% in the year, reaching £38m (20% of the market cap)
Targeting further improvements in operating margin.
“Major development” has been taking on 15 of insolvent Tuffnells depots, with £35m pa of customer work added so far (not clear what period this covers, or what it would be if annualised?)
Outlook sounds positive -
Despite the current economic headwinds, the Board remains encouraged about growth prospects for the Group, and the recent additional volumes secured should enhance profitability in the new financial year and beyond.
Paul’s opinion - it sounds as if DX has been a beneficiary of Tuffnells demise. Maybe that could drive broker upgrades?
I’m still not clear how much of the group’s profit comes from its specialist network for lawyers, which has been shrinking due to email substitution.
This is not the sort of business I would want to invest in, against lots of competition, and maybe the old legal business is a cigar butt that could expire at some stage, I’m not sure?
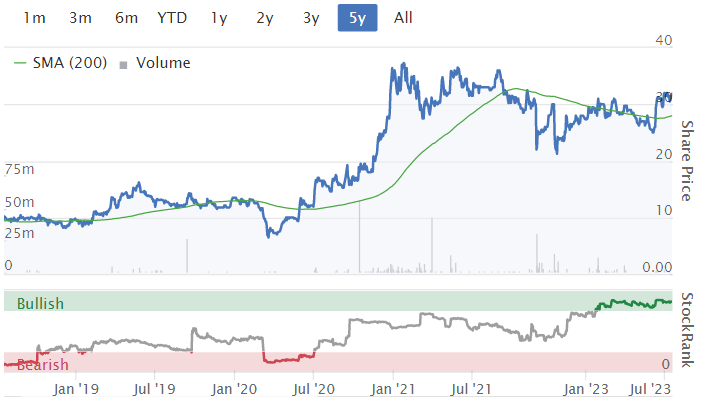
Finncap (many thanks) has edged up forecast EPS by 2% today. It’s now saying 3.8p FY 6/2023, and 4.3p FY 6/2024. So a PER of 7.4x looks good value, considering it also has a nice balance sheet with plenty of cash. Thumbs up from me again, more on cheapness than quality! The c.5% yield helps too.
So far it's been a good turnaround from previously quite serious problems -
Graham’s Section:
UP Global Sourcing Holdings (LON:UPGS)
Share price: 126p (+3% yesterday)
Market cap: £113m
This company owns a range of household brands, and you may already be familiar with several of them. Of the brands managed on its website, be careful to remember that the one it doesn’t own is Russell Hobbs - but it does have a licence to use that trademark.
Yesterday the company announced that it expects its financial net debt at year-end (July) to be “in the region of £15m, which is significantly ahead of current market expectations of around £21m”.
For some context, net debt was £19m at the end of H1 (January 2023) and £24m at the end of the previous financial year (July 2022).
The company’s debt is made up of the following: overdraft, term loan, RCF, invoice discounting, and import loans. In their own words:
The Group makes use of term loans for longer term funding, such as acquisitions, whereas our invoice discounting and import loan facilities are designed to fund our working capital, and automatically increase in relation to our levels of trading.
So what was the reason for the £6m reduction in net debt? After all, a reduction in trading activity could reduce the company’s debt level. As I’ve said before, there are some companies where I like to see debt rising, because it means the company is very busy!
The reason given at UPGS is: ongoing improvements in working capital management and the phasing of trading during the second half of the year.
“Working capital management” - to me, this typically means one of two things. Either the company has managed to convert receivables into cash faster than expected, or it has managed to stretch out its payables (paying its suppliers later than expected). There are other possibilities but these are the most likely. It’s good news, of course - it’s not the same thing as higher profits exactly, and it might end up reversing at some point, but it’s certainly good news.
“The phasing of trading during the second half of the year” - this is more nebulous to me. But if the company is talking about how the timing of orders over a six-month period has boosted its cash balance, then I would expect any reduction in net debt arising from this to be temporary. The company has a history of seasonality.
I see no changes to sales or profit forecasts arising from this RNS.
Graham’s view - I would treat this RNS carefully, as it’s not clear to me that the surprise reduction in net debt is coming from sustainable sources. I suspect that it’s coming from a mix of sources, some of which are permanent and some of which will reverse in future periods. It would be more helpful if companies such as this provided transparency around average monthly net debt, and indicated the highs and lows it reached.
The big picture here is that the stock does look interesting in terms of its overall financial metrics - on a PER of 8x and a yield of 6%, with a good track record of profitability. By all accounts they have dealt very well with the challenges posed by Covid and subsequent economic difficulties. UPGS has a StockRank of 96 and therefore while I haven’t studied it in depth on the back of this RNS, I will give it the thumbs up on the basis that it’s worthy of deeper research.
Record (LON:REC)
Share price: 83p (-6%)
Market cap: £165m
Record plc ("Record" or the "Company"), the specialist currency and asset manager, is pleased to announce its trading update for the three months ended 30 June 2023 ("Q1-2024").
This share took off after I no longer owned it (shouldn’t complain, though - I have had many graceful exits from shares which subsequently did badly!).
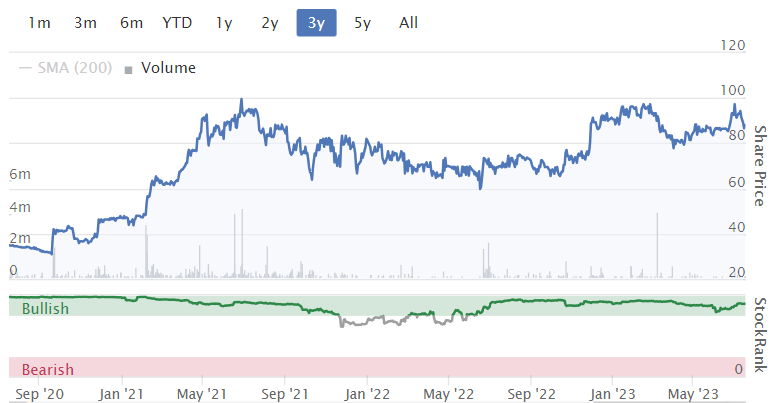
Here’s the Q1 news:
Performance fees of £0.5m earned.
AUME (“assets under management equivalent”) $86.4 billion, down 2% since the end of the previous financial year.
Performance fees come and go; in FY March 2023, the company earned £5.8m, but they only earned £0.5 in the entire financial year before that.
CEO comment:
"Notwithstanding the challenging macro-economic backdrop, we expect the business to achieve a number of important milestones in FY-24, and look forward to the rest of the year with optimism."
Net flows for the quarter are negative to the tune of $2.5 billion. This is poor considering that flows were positive $9.1 billion in the previous financial year.
The outflows are concentrated in the Passive Hedging product. This activity has seen steady fee compression over many years but in the most recent full-year results statement, Record claimed that this fee compression had levelled out and that new types of clients (asset managers) were using it. Last year, Passive Hedging saw inflows of nearly $5 billion.
Fee rates are “broadly unchanged”.
Graham’s view
I note that Record shares are off by nearly 6% today, and this may be a fair reaction to a turn in the fortunes of the company.
The CEO mentions a “challenging macro-economic backdrop”, which is understandable, but I’d like to think that Record sees opportunities in difficult economic circumstances - the need for currency advice and currency management should remain strong in these times. Or as Neil Record himself said in June:
Record is not immune from these [economic] challenges, but structurally we are positioned to be nimble and adaptable to client demand as it develops and changes. While cost pressures (particularly labour costs) will undoubtedly impact the business, the current pace of growth and change should allow the revenue to grow sufficiently to more than compensate for the cost-base growth.
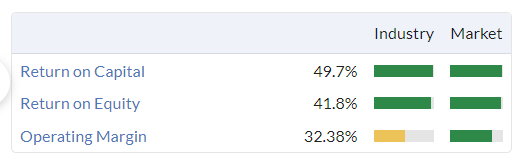
I will maintain a positive view on these shares as I think it’s reasonable to treat a disappointing quarterly update as a “blip” in an otherwise good business. This company has never reported an annual loss. And here are its most recent quality metrics:
Judges Scientific (LON:JDG)
Share price: £93.99 (+3%)
Market cap: £621m
Judges Scientific (AIM: JDG), the group focused on acquiring and developing companies in the scientific instrument sector, provides the following update regarding the Group's trading performance for the six-month period ended 30 June 2023.
This is a pleasant update: there have been “generally favourable markets” and “moderate progress in dealing with supply chain challenges, thus allowing the delivery of solid growth in both Organic order intake and Organic sales”.
Key points:
Organic order intake up 14% vs. last year, up 23% vs. 2019 (pre-Covid). It’s helpful to show both due to variability introduced by Covid, though remember that inflation has been significant since 2019.
Order book reaches a mid-year record of 22.4 weeks.
Organic revenue up 17% vs. last year. Total sales will be up significantly more due to the contribution of Geotek.
Outlook is in line with expectations:
The strong order book, and the general resilience of Judges' business give the board confidence that the current market expectations for the full year will be met.
Organic revenue growth is producing “double digit profit growth, albeit at a slower rate than revenue growth as measures taken to compensate for the inflationary pressures observed in 2022 Q4 are progressively having an impact”.
Graham’s view
Not much has changed here, so there is no need to change your prior view on Judges. I am impressed by the return to strong organic order growth, so it’s tempting to take a more bullish stance on the shares. But the price tag remains very heavy: price to book is 11x, and price to sales is 5x.
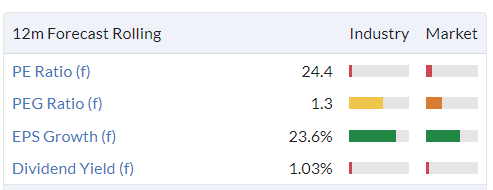
It’s a truly great success story, but there are times when the price excites me and times when it doesn’t. This is one of the times when it doesn’t excite me now, so I’ll stay neutral.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

72 comments
Paul, the 52 week high momentum screen, has a poor record over the last 5 years, down over 47%. Seems a lot of stocks, don't carry on winning, in this market.
Hi Rusty2,
Paul, the 52 week high momentum screen, has a poor record over the last 5 years
Yes, that's right. I was quite surprised the 52-week high screen hadn't done better. Although looking at the chart for this screen, it did very well from 2012 to the end of 2018, but then began under-performing - taking an obvious knock from covid, recovering in 2020 &2021, but it's then absolutely plummeted since the start of 2022, to now.
That makes sense to me, because we've had a horrible bear market, especially in small caps, since about mid-2021. So a strategy that picks shares that are at year's highs, would expect to do really badly in a bear market, as the high flyers often crash the most from unrealistically high valuations.
However, now valuations are on the floor, I reckon this strategy could come back into performing well, because it might select the early winners which are out-performing in a bad market. Maybe!
If you can time the market, I think there's a good argument for switching gears, ie using different strategies depending on what type of market we're in. Very difficult to execute that strategy well though!
Momentum is multi-directional - you need to recognise which way its going - could be up ... or down ...
True, but that screen is the 52 week high, so they must be going up to reach that figure?
However in the past 5 years, that screen has not performed very well, seems investors are taking profits at new highs. The momentum is not continuing, although that will not apply to all stocks, I have a few that have continued upwards, even small caps but many have fallen back.
Arbuthnot Banking (LON:ARBB) surprised there is no mention of the half year results today which are frankly superb. Looks like EPS is going to come in north of 250p versus a £10 share price so a PER of 4 with strong CET and liquidity ratios. Relatively simple business with tangible book value of 1470p and rising and good dividend yield. I hold and looks good to me.
NIM is probably around peak though so as this falls they will need to grow to maintain EPS but a 1 to 1.1* book value looks more appropriate, so I'm looking for 1500p to 1650p personally.
I had a quick look at Arbuthnot Banking (LON:ARBB) results, but soon realised it was too complicated for me, as I don't have a lot of experience looking at accounts of banks. But it does look cheap. Could be a bargain following the mini-banking-crisis? I also noticed that the shares were up about 20% on the results, so it could be one for people to look at, if you invest in banks.
Regards, Paul.
DSW Capital (LON:DSW) Full Year 2023 webinar from yesterday. This was a December 2021 IPO. Results were released a week ago, where revenues flat-lined year on year. To date they've been M&A focussed hence the flat revenues but they are diversifying to broader sectors eg. corporate recovery as the recent transaction with Bridgewood Financial Solutions.
They offer a licence licence model business who support professionals (commonly from the big 4 accountancy firms) building their own businesses.
For investors it offers a recurring revenue, capital light buiness. To date the buinesses they support have predominantly been corporate finance, now they are spreading This is a good overview by the CEO & CFO.
Or podcast.
Paul re DX (Group) (LON:DX.)
“Major development” has been taking on 15 of insolvent Tuffnells depots, and £35m of customer work (not clear what period this covers, or what it would be if annualised?)
The £35m is the annualised figure, as stated in the RNS:
Management estimates that the annualised value of the additional volumes secured from former Tuffnells customers is approximately £35 million to date.
The "to date" suggests to me that there may well be more to come from this source.
The latest broker forecasts do not seem to make anything like adequate allowance for the Tuffnells windfall, and I expect to see further upgrades in due course.
[Edit] I should add that it is throwing off cash, too, despite current high capex investment in the network.
Hi EC,
Great, thanks for clarifying. Looks like I slightly misread the DX update. I'm a bit tired now, but will edit the article later.
Thanks again, Paul.
That's sorted now. How did I manage to not notice the word "annualised" in the DX Group RNS, re Tuffnells work?! Doh! Schoolboy error, sorry about that. I've edited the article now to delete my query on this point.
Many thanks for flagging this correction, it's very helpful when readers spot, and flag up anything inaccurate, as I want to get it right every time! We don't make many mistakes, but want to hear about anything wrong, so we can fix it. There are no egos over this, everything has to be factually correct as our no.1 priority! :-)
Best wishes, Paul.
Pelatro (LON:PTRO) - re today's RNS...I wonder if senior company mgt really expected the company to receive payment for all services...
Funding looks hard later this year...so I expect the founders will just need to take all their hard work private, perhaps in a new Indian registered vehicle...
Who could have ever seen such a thing coming?
Here are some interesting facts, figures and commentary on construction and house builders with read across for Brickability (LON:BRCK) Taylor Wimpey (LON:TW.) Persimmon (LON:PSN) etc. I hope it may be useful. Apologies if twitter is still limiting tweets views to members. https://twitter.com/noblefranc...
When the market closes, prices shown on Stocko and HL are sometimes wrong, bids higher than offers, usually with a caveat...but does anyone know how these incorrect prices are generated and whether we can read anything into them?
I use Google Finance to track my shares throughout the day, I find that weird inaccuracies also pop up at close of play that didn't exist just before the close. Not sure what causes it though!
Hi Conistons
There will be someone who can put this a lot better than I can.
Often there are deals and trades going on in the background that only get reported at close, rather than real time. Sometimes this can be part of a larger sell or buy where the main party does not want to falsely crash (sell) or pump (buy) so brokers are picking up or releasing throughout the day and only report at the end of the day. Think of the Odey selling they didn't just go "Hi I need to sell 15,000,000 shares in this company, does anyone want to buy them all?" Or someone wanting to buy £50,000 in a small company that typically only trades £5,000 shares in one day. The broker will look at the Level 2 and slowly fill all the orders throughout the day and sometimes over several days and weeks, and then make one statement at the end of the day.
Hence RNS statements of the big holders going above or below thresholds, you hardly ever see that Pension Company ABC bought 10,000,000 shares in Large Company 123 @ 85p and see that major trade yesterday, just a Pension Company ABC now has a 5.34% holding in Large Company 123, it's previous holding was 3.57%.
I don't know where you see the uncrossing trades, and close out of Level 2 orders in auctions etcetera.
Tommy
Hello Paul Scott hopefully I am posting in the right area regarding your pod casts if not please redirect me as I couldn't see anywhere on the web page to do so. loving the pods very informative and a good way to round the week up so please keep going although I suspect they take a fair it of your time but I appreciate them. I am not sure if this is possible for the newer traders like me, for you to explain the various lines in a trading report see excerpt from Vertu (i hold) perhaps just picking one line per week and explaining what it is actually referring to and understand if they are good or bad or more importantly how they may effect the share price. worth asking would have added a smiling emoji but no facility....
If you click on the blue named text it will pop an explanation window
I’m learning too & have found the Stockopedia articles and videos on the ‘learn’ tab very useful - have a look at those. There’s a lot to get stuck into!
Off topic for today, SCS (LON:SCS) has had 2 large trades go through this morning for around £950k each from a support level around 145p which is about a 35% drop from the high of 227p back in February this year. Either Institutes buying or possible BOD buys.
SCS (LON:SCS) definitely not off Silver's topic since I am holding this. But were these deals buys or sells, it hard to tell from this:
There's a long way to go get back the the highs of last March. This must be of interest to members, if they had to stick to the RSN's of the current date then the SCVR would be the lesser for it.
I am presuming buys as the price has gone up even though listed as sells.
seems the market enjoyed it, up 7%!
this answers the question: 'what volume will move the price of SCS (LON:SCS)?'
Niox (LON:NIOX)
I've held this for a while (it was called Circassia at the time). The original reasons I bought it were:
A trading update today, reveals:
Anyway, it's been my best performing share of the past two years (EASILY) but as usual, I wish I had more money in it. I'd kept in investment smaller than usual because of the valuation.
Comments welcome.
Cheers
Chris
https://www.reuters.com/world/...
LONDON, July 18 (Reuters) - British grocery inflation eased for a fourth month in a row in July, seeing its steepest decline since it peaked in March this year, industry data showed on Tuesday, providing a bit of relief for cash-strapped consumers suffering from high prices.
Market researcher Kantar said annual grocery inflation was 14.9% in the four weeks to July 9, falling 1.6 percentage points from the 16.5% in its June data set.
Food inflation seems very high still given last year comparatives are becoming increasingly tough, so i think the news headlines today are a bit simplistically optimistic. As consumer group Which? said, food prices are now up 25% on a two-year basis and the wheat price seems to have risen markedly this week again. None of this bodes well for bringing down inflation fast.
Isn't the heatwave that is ripping through southern Europe going to further drive up food inflation? That heat can't be good for crops currently growing?
There's also Russia's withdrawal from the deal allowing Ukraine to safely export grain through the Black Sea to throw into the inflation pot
UP Global Sourcing Holdings (LON:UPGS)
I'm a holder for a long time and I really like company and mgt.
I thought the RNS yesterday was curious. I think it probably shouldn't be over analysed though I too went thro the exercise of guessing at what it means operationally (could mean that sales have cooled significantly towards end of period!).
But I think the explanation is simpler. 1) some investors give them some stick on debt level (I think they don't really understand the structure of the debt and how used imo) and 2) they are just signalling to the market outside of their scheduled updates that things are still okay and that sales haven't tanked. The price action implies a lot of scepticism.
As a speculative macro aside: Events in China are kind of a good thing for UPGS probably. The economic woes China is undergoing and transitional growing pains after the internal debt binge (and perhaps even the dreaded middle income trap) means that its overall demand for commodities is likely much cooler (so impacting global prices) and internally the deflation pressures will be persistent and high -> this means that product sourcing price for UPGS is likely to be good.
Obvs the big macro fear is massive fall out with China or Taiwan invasion. This is possible and would be very traumatic for UPGS...but much everything else would tank too. Its my belief that China have effectively lost their power play with the USA and that for reasons of self-interest and preservation the coming years will likely see an increasing (but subtle and not overt of course) kowtow of China to 'The West' to retain as much of its gains and status as possible. Tough times in China are a good thing for us (I don't say that out of malice...just a belief/observation)
As house analysts you can or course read our research, but mojomogoz I think has it spot on. This doesn't require over analysis. Its the company taking an opportunity to flag, on a tangibly improving number, that all is well, particularly when recent share price moves might imply otherwise. If you've been following it as long as we have you will know a) the management team is all quality (yes we're biased, but we've also met a lot of management teams) and b) they have talked a lot about ongoing efforts to make lots of small changes which over time add up to savings. I think we're just starting to see the benefits of this.
Brickability (LON:BRCK)
Following yesterdays FY results :
"Brickability Group plc (AIM: BRCK), the leading construction materials distributor, announces that John Richards, Chairman, Alan Simpson, CEO, and Mike Gant, CFO, will provide a live presentation relating to the Full Year Results for the year ended 31 March 2023 via Investor Meet Company on 19 July 2023 at 1:00pm BST.
The presentation is open to all existing and potential shareholders. Questions can be submitted pre-event via your Investor Meet Company dashboard up until 9:00am BST the day before the meeting or at any time during the live presentation.
Investors can sign up to Investor Meet Company for free and add to meet Brickability Group plc via:
https://www.investormeetcompany.com/brickability-group-plc/register-investor.
Zotefoams (LON:ZTF) the blue sky renewable beverage container moonshot would meet a tidal wave of demand from retail brands conscious of their eco credentials - if successfully delivered. But I’d caution that every packaging company under the sun is trying to develop the same thing with its partners. It’s not exactly a secret money fountain waiting for ZTF alone to unlock the key. Instead it’s a race to the production line.
Housebuilders are slowly recovering from the carnage of the last few weeks despite the worsening news regarding the housing market, interest rate and recession. The sector has plenty to offer for investors in large and small caps. I note from last night Mello that Christopher Mills has GLE in his fund. It is possible that the market has anticipated the worst and priced the sector accordingly
Patient investors in Housebuilders may wait a bit longer for the recovery but dividend pay out is good and the recovery will happen. Persimmon is down by 75% from the peak of £30 to £10. Others are priced lower by up to 50%. It seems they are priced for bankruptcy! It will not happen.
Following on from yesterday’s discussions regarding the value of meeting management either in person or online it would appear that if a ceo is impressively selling the company and appears genuine as in my view is the case with Zotefoams (LON:ZTF) then as Paul has said when they appear to be not so enthusiastic about a project, rezorze in this case ,we take it that there are difficulties. Thankfully this appears to be erroneous
The shares have been marked down recently on the view that the company is fully valued but volumes are small and it is a consistent theme with many companies so unless you’re a trader you are watching good companies slowly drop for little reason . Hence any good news is welcome
Just to flag, a news report suggests there are two cases filed against PayPoint (LON:PAY) for anti-competitive activity in the energy prepayment market. https://www.cityam.com/paypoin...
I imagine these may take years to resolve and it's not clear to me what the likelihood of success or financial impact would be. Would be interested to hear anyone's more considered view! They may also serve to underline the effective business model the company has developed... (I hold)
Hi Patrick
A few years ago my tenants defaulted and after a protracted legal process they fled about 30 minutes before the bailiffs arrived, very short version of a very painful experience.
I found that the electricity and gas had gone from a standard meter to a pre-payment meter, both the meters were in debt to the point there was no electricity or gas in the property.
So I had to go find a shop where I could buy two cards, one for electricity and one for gas, and then pay for credit to be added to each card, and then go back to the house and put the cards in the meters to turn on the lights, get the heating back on (winter obviously). It was then a long process with the utility company to prove who I was, who the tenants were and that they had left, to get a normal meter reinstalled before getting the house back to a state where it could be used again.
The basic lesson I learnt was that a pre-payment card is significantly more expensive than pay-monthly (direct debit) for both electricity and gas, so that those who are least able to pay are actually paying more than those most able to pay.
I will add that I have not looked at pricing recently, so the changes in legislation on pricing and also the impacts of the maximum pricing.
But might explain a bit behind the process.
Tommy
Had a very similar experience to yourself, shocking to see how much it actually costs on these prepayment meters. It is also extremely difficult to get rid of these and revert to a normal meter, they obstruct as much as possible as they are making so much money.
Thanks for flagging! (I also hold PayPoint (LON:PAY) )
A little bit of a complex situation. Paypoint had already reached an agreement with Ofgem on redressing this concern back in 2021...
But it looks like the complainants are launching an appeal now? Presumably they are claiming the Ofgem ruling was unfair and didn't go far enough to demand Paypoint make further redress payments to impacted third parties?
Does anyone have a little more insight into Gulf Marine Services (LON:GMS) ?
Interest on financing has decreased by 3.4% because leverage has dropped below 4x EBITDA, meaning the loan has decreased or EBITDA has increased, probably both. Now Gulf Marine Services (LON:GMS) has reduced the leverage to within normal parameters will they be able to refinance for a better deal or will the current deal be the best for them considering interest rates have risen?
Still, this looks good news to me today but there is still the risk of a dilution if the warrants get issued (137m). Would be grateful for any thoughts on this from someone who understands it better than I.
AI - companies which will benefit?
Fatima Iu of Polar Capital gave a very interesting talk on AI yesterday evening on Mello Monday. A key take away for me was that companies with proprietary data sets would benefit the most from AI (various artists and companies including Getty Images are currently suing AI companies for using copyrighted material to train their systems):
Cambridge Cognition Holdings (LON:COG) (I hold) is a share which has large, multi-year proprietary data sets.
A second key take away from Fatima Iu.s talk, included in Chat GPT's responses below, was that the last update was in September 2021.
Chat GPT was not helpful at all - possibly I didn't phrase the question correctly:
"Which shares listed on the AIM London market own large proprietary data sets?
As of my last update in September 2021, I don't have access to real-time data and cannot provide a current list of companies listed on the London AIM market that own large proprietary data sets. The composition of the AIM market may have changed since then, and new companies might have emerged or existing ones could have altered their business focus.
To find the most up-to-date and accurate information, I recommend checking financial news websites, market analysis platforms, or the official London Stock Exchange website. These sources will provide the latest information on AIM-listed companies and their ownership of large proprietary data sets, if available."
Try again:
"Which UK companies own large proprietary data sets?
As of my last update in September 2021, several UK companies were known for owning large proprietary data sets. However, it's important to note that the business landscape can change rapidly, and new companies may emerge with large proprietary data sets. Additionally, some companies might have shifted their focus or merged with others since my last update.
To find the most current information, I recommend conducting a search on financial news websites, market research reports, or consulting with investment professionals who can provide up-to-date insights into UK companies with significant proprietary data sets. Always verify the information from multiple sources to make well-informed investment decisions."
Are the answers intentionally vague to avoid giving financial advice?
It might help if you were to specify "Up until July 2021, which UK companies ...?" or similar.
Try something along these lines - though I'm not sure how useful the results are...
"What are some good examples of UK based companies that have large proprietary datasets?"
There are a number of UK-based companies with large proprietary datasets. Here are a few examples:
1. **DeepMind**: This company, a subsidiary of Alphabet Inc., is a world leader in artificial intelligence research. They have large proprietary datasets related to various aspects of AI research, including machine learning and deep learning.
2. **BenevolentAI**: This UK-based company uses artificial intelligence for drug discovery. They have amassed a large amount of data related to medicine, biology, chemistry, and related fields.
3. **Deliveroo**: This is a major food delivery company in the UK and it collects data on customer preferences, delivery times, locations, and more, to optimize its operations.
4. **ASOS**: An online fashion and cosmetics retailer. They have a large customer database and use customer behavior data for personalized marketing and product recommendation.
5. **Just Eat**: This is an online food order and delivery service that collects a large amount of data about customers' ordering habits, restaurant ratings, and delivery times.
6. **Revolut**: A financial technology company that provides banking services. It collects a large amount of financial data from its users, which it uses to improve its services and offer personalized financial advice.
7. **Tesco PLC**: This multinational grocery and general merchandise retailer has a vast amount of data from its Clubcard loyalty program, online sales, and physical store sales.
8. **Dunnhumby**: A customer data science company owned by Tesco. They use machine learning and data analysis on the large dataset from Tesco's customer base for targeted advertising and improving customer experiences.
Remember, companies that have large proprietary datasets must adhere to strict privacy laws, like GDPR in Europe, to protect their customers' data. They must be transparent about what data they collect, how they use it, and how long they store it, and they must give customers the right to access, correct, or delete their data.
I think Instem (LON:INS) and Bango (LON:BGO) say they collect data.
Robert Green3
Did you see Steppe Cement (LON:STCM) recent trading update?
https://www.stockopedia.com/sh...
They expect to pay a 2p to 3p dividend later this year. That’s their current expectation. If it changes it’s far more likely to be a cut below 2p than a surprise increase of more than 3p. Reading that downbeat update explains why.
I no longer hold.
Steppe Cement (LON:STCM)
Share price has dropped like a stone due to a poor trading update and I am concerned that they may suspend the generous dividend. Is there a way of finding out if they will suspend or reduce the dividend this year? (Ex date 17 Nov). Trying to avoid panic mode!
What's the dividend cover? That might give you a starting point.
Why is Stocko showing Zotefoams (LON:ZTF) down 5%, when it is up 9%? Getting fed up with Stocko share prices. This last trade price is nonsense.
I have sent a message to Stockopedia this morning on this topic. One share i follow was still not updated at 8.25am. Prices are delayed 15mins but at 8.20 am they should show prices at 8.05am
Agree that the way Stocko shows prices is rubbish - I use ADVFN or LondonStockExchange for prices.
Small caps with a fair spread are particularly affected. One trading all day at 98/102 may show an unchanged mid of 100 on other sites but Stocko will have it oscillating between +2% and -2%.
I use Google Finance which provides live prices for "free".
I use Google Finance too, but keep in mind it shows the last price a stock traded at and not mid-price, so it gives you a flavour of where your stocks are but can be a bit off, particularly for smaller and less frequently traded stocks.
Google Finance is pretty good (for what you pay......) but beware the following:
1. It runs on US time, not UK time - so the currency moves on the day are not accurate for UK users
2. I've noticed that it can do some very strange things to UK pricing after UK close (and it is not the auctions) - it sometimes reverts to the prior day's close price (this may be partly down to the timing mismatch above)
3. Certain tickers just drop out and generate errors for no reason now and then (e.g. PayPal vanished for several weeks recently). This may well be a "feature" to frustrate anyone considering commercial use.....
I've found the Microsoft 365 StockHistory function to generally be more reliable in an Excel environment (but 20min delayed), but even then it can fall over at times - it recently kept asking you to sign in to a valid account even if you already were - took them several days to resolve.
However, Microsoft doesnt do some indices (e.g. FTSE)
And as with Stocko, I suspect much of it plugs in to Refinitiv beneath the surface, and it is never quite clear where Refinitiv is the problem!
Just a note regarding MS365 excel stockhistory and indices - I had the same problem and it was extremely annoying, it being the only reason I had upgraded to a yearly subscription rather than the excel 2019 which was more than enough for my excel needs. Anyway, a long story short, I do a powerquery from googlesheets into excel (GoogleFinance function), from which you can get all the commodity prices as well as indices. Might be useful to someone.
Judges Scientific (LON:JDG)
In line trading update. Organic order intake up 14% v H1 2022 and importantly up across all regions. Order book at a mid year record level of 22.4 weeks. Expecting double digit profit growth and given resilience being shown, confident in meeting market expectations for full year. I hold.
Hi Paul,
Can you look at LON:QUIZ please. It has gone down a lot. It seems too cheap to me ? Thanks
There's plenty written about Quiz (LON:QUIZ) already - but I'd love to hear your thoughts, arshadte, why you think it is too cheap?
Decent looking update from Luceco (LON:LUCE)
Liberum up PBT forecasts 7.6% + 5.5% for 2023 + 2024
EPS 4.5% + 4.2%
Reasonable sized director buying in May hinted at an improvement. Earnings probably bottomed out barring serious economic slowdown.
H1 2023 trading update from Luceco (LON:LUCE) this morning. It looks another step towards putting its covid related issues behind it. "Full year guidance towards the upper end of expectations" but "remain vigilant to the changing environment". Revenue of £101m with gross margin percentage continuing to improve from the 2nd half of 2022. "Adjusted Operating Profit is expected to be no less than £10.5m, ahead of our expectations" and importantly for me "Post-pandemic customer destocking appears to have ended." A few companies have been saying this recently (finally). Debt under control and IMO a good recovery play. Market Cap £187m.
Trifast (Tri)
Some very smart investors building big stakes here notably Dbay and Rockwood
Pretty straightforward thesis by the looks of it
- supply chain is normalising with normal (actually lower than normal) freight costs and leadtimes back to normal
- this reduces costs and enables a company to run lean stock levels, increased stock turn improves cash significantly
- new management in at turn of year
- cost cutting seems to have been done already
Looks an easy to understand and relatively easy to apply strategy .
Some debt but the inflowing investors is a big sign this is a nice recovery play in a solid company and possibly has a reasonable moat as not that easy to build a company like this .
Looks a very nice takeover target too .
Was a sell recommendation by Investors chronicle last week but have to say I really don’t rate IC these days seems very poor on company specific analysis which is maybe understandable given the amount of volume they have to cover .
I’ve reduced core holdings Somero and Wynnstay to 1/3 and 2/3 positions and am repositioning into Trifast, and Filtronic . (At 1/3 and 1/3 for now )
I remember reading an article many years ago by Professor John Kay where he said the Investors Chronicle was a very useful publication but more for the data it contained rather than the conclusions it reached.
Not s fan of IC. Don't their sells out perform their buy tips?
Reluctantly ended my sub to IC last month after many, many years. It lost its way a few years back when it got taken over (by the Japanese? Can't remember the detail). There was an exodus of the best contributors and I remember saying at the time 'would the last decent journalist at IC please turn off the lights on the way out'. ST is a good contributor, but I don't do small caps any more so of limited interest. I found myself not reading it and decided it was time to stop.
I also ended my subscription to Investors Chronicle after receiving it weekly since I started investing many years ago for exactly the same reasons as Lord Gnome.
I also ended my subscription to IC just recently after many years, for a long while it as seemed to be not as good as it was. I also agree with Lord Gnome that you seem reluctant to finish, remembering how it used to be but hardly reading much of it now. I much prefer the reading on Stockopedia now, just a pity it's not as well as.
Trifast (LON:TRI) was also a Slater Growth stock, but it has been a disappointment in recent years. It is (literally) a "nuts & bolts" company, and I suspect many of its customers fall into the "cyclical" camp.
They've recently made an acquisition in the US called Falcon, and I think revenue growth is more likely to be on a "roll-up" basis (acquire & integrate) than from outright organic sales growth.
I decided to top up into the dip rather than sell, on the basis that the investment they have put in could enable margins to recover back to 10%, but I can't say I have the conviction to make it a large holding.
As for Filtronic....I went on a tour round their facility in Newton Aycliffe decades ago, and kept an eye on them for a while after. Such potential, but they seem to have a knack of seizing defeat out of the jaws of victory - back in the day it was engineer-driven (Prof David Rhodes was quite a character), and the commercial aspects suffered.
Hopefully all that has changed and there is a phoenix in the ashes, but it is one of those companies where I decided life was too short to keep hoping.....
My morning smallcap tweet: Deflating companies with little pricks
Revolution Beauty (LON:REVB) Litigation Capital Management (LON:LIT) Nanoco (LON:NANO) Carclo (LON:CAR) Osirium Technologies (LON:OSI) Gulf Marine Services (LON:GMS) Luceco (LON:LUCE) Niox (LON:NIOX) Pelatro (LON:PTRO) Zotefoams (LON:ZTF) IXICO (LON:IXI), Alliance Pharma (LON:APH), Artisanal Spirits (LON:ART), CPPGroup (LON:CPP), Bloomsbury Publishing (LON:BMY), Vector Capital (LON:VCAP), Judges Scientific (LON:JDG), Mirriad Advertising (LON:MIRI), DX (Group) (LON:DX.)
◄Revolution Beauty (REVB)► red-faced as it agrees to most of holder boohoo's demands. CEO Bob Holt and Derek Zissman will resign. 4 new dirs. CFO remains. [SP=31.21 Cap=95m]
◄Litigation Capital Management (LIT)► will move to the less conservative Fair Value Accounting, in line with peers. Peer Burford (for example) has suffered harsh criticism of its 'fair values'. 2.5p div reflects "strong financial performance". [SP=79.8 Cap=95m]
◄Nanoco (NANO)► activist investor Mr Hamoodi requisitions GM to change board. [SP=18.5 Cap=60m]. I hold.
◄Carclo (CAR)► mooted covenant changes signed. [SP=12.77 Cap=9m]
◄Osirium Technologies (OSI)► guides H1-June rev £1.1+, up 18%, and ARR up 34% to £2.16m. Strong start to H2 but still expects to raise additional capital before the end of the year. [SP=1.5 Cap=2m]
◄Gulf Marine Services (GMS)► interest cost falls 340bps as leverage now below 4:1. [SP=7 Cap=71m]. I hold.
◄Luceco (LUCE)► guides FY-Dec towards the upper end of market expectations. H1 rev down 5% and adj op profit £10.5m, both ahead of mgmt exp. [SP=117 Cap=188m]
◄NIOX (NIOX)► guides H1-June rev up 22% and adj EBITDA c. £6.2m (£3.2m). Guides FY ahead of mgmt exp. [SP=64.5 Cap=273m]
◄Pelatro (PTRO)► a key customer, owing $550k, will miss agreed payment deadline of July. Review (why does this need a review?) finds 'unusual' delays in payments from 4 foreign customers, tot c.$1.1m. The customers blame their gov'ts for slow approval of making payments abroad. Expects a positive resolution from talks. If it's really govt bureaucracy what difference will talks make? Cash at hand only $0.7m and c.$2.6m coming in by Sept. Exploring financing and funding options in case customers don't pay. [SP=7.68 Cap=4m]
◄Zotefoams (ZTF)► joint development agreement with a world-leading packer for ReZorce beverage cartons. [SP=338 Cap=156m]
◄IXICO (IXI)► $1.7m 4 yr contract. [SP=18.75 Cap=9m]
In line: APH, ART, CPP, BMY, VCAP, JDG, MIRI, DX.
Very good Mr Contrarian, some company directors have a lot to answer for but it is the share price that pays the price.
2024 first quarter trading update from Record (LON:REC). Average fee rates "broadly unchanged" (which translates to me as "lower").
2024 Q1 performance fee £0.5m compared to £2.3m 2023 Q1.
Total outflow of US$1.3m AUME, to US$86.4m, all in the passive hedging segment as far as I can tell: dynamic hedging, currency for return, and multi-product all rose.
Artisanal Spirits (LON:ART) "Investing in ultra-premium Scotch’s global growth" (new note here: https://www.equitydevelopment....)
Today’s Artisanal Spirits Company (ASC)’s FY2023 H1 trading update reported just over £10m in sales revenue compared with £9.9m a year earlier and included 7% growth in the second quarter. Importantly, there was a 9% increase in membership numbers. In addition, the statement reconfirmed the benefits of the company’s ultra-premium distilled spirits positioning, its focus on Scotch whisky, and the advantage of not only being international but also in control of its supply chain and distribution system.
While the ASC’s H1 sales growth was beneath our full year expectation of 14%, the company was lapping a particularly strong growth in the same period a year earlier when sales advanced by 25%. The company itself remains confident that full year market expectations for sales and adjusted EBITDA will be met. We leave our own forecasts unchanged at £24.7m and £1.3m respectively for these two measures.
We draw a positive read-across from Diageo PLC's investor presentation in Edinburgh on 1st June (“Delivering sustainable long-term growth – our vibrant Scotch portfolio.”) Diageo’s central investment messages focused on premium Scotch as a growth category and its value creating qualities relative to other distilled spirits categories. In our view ASC is already a clear beneficiary from these trends and opportunities.
We base our 150p fair value/share, which implies a 4.8x FY2023 EV/sales ratio, on a relative valuation comparison with other international distilled spirits companies and luxury providers.
Promising rns fromZotefoams (LON:ZTF) regarding rezorce joint development. Could be the start of something big.
I agree that there is still a lot of work to be done before we know whether ReZorce is going to be a major profit centre for Zotefoams (LON:ZTF), but I do not see any signs so far that the company has cooled on the project in recent updates. Quite the reverse, in fact.
The January 2023 update reported that the project was progressing well and was a "significant focus" of the team. The company then advised when it issued its final results that it was looking at involving a strategic partner to bring the project to market - ideally a packaging company or similar who could bring in expertise that the company does not have and share the development costs. The May 2023 TU said that the company intended further significant spend on developing ReZorce and in response to a question I asked at the InvestorMeetCompany presentation (well worth a view) it said that it was budgeting further expenditure roughly in line with what it had spent in 2022. (which I think was £2 million capex plus a circa £2 million operational loss). ReZorce has evolved from Mucell, which has been a ten year plus project. The company also volunteered that a .3% global market share would be as big as the company is in its entirety at the moment. If the product is successful, it should command a much bigger market share than that.
Today we learn that the company has actually secured two commercial partners. First, its JV packaging partner and secondly the major European retailer that will participate in in-market trials. The two are obviously linked and I attach at least as much importance to the announcement of the second partner.
The details released today are sketchy, but securing two significant major players is pretty good going and entirely in line with what the company has previously said it intended to do. If it gains traction, I could see this business being spun out of the company, which is also doing pretty well with its core (and profitable) business. I am happy to hold and possibly add.
Hi AndrewJames I agree that this project for Zotefoams (LON:ZTF) is showing significant progress. But why would they sell it off?
I am not suggesting that they would sell out, rather than spin out ReZorce. This is pure speculation, but ReZorce will probably have multiple investors if it really scales up and then the issue is how best to finance its expansion. Creating and possibly floating a separate entity is one option that would inevitably be considered. By the way, I am assuming that the JVA announced yesterday does not cover pouches, which is another product line. One of many potential questions for the IMC presentation next month.