Small Cap Value Report (Tue 18 June 2024) - NXR, MOTR, IGP, STEM

Good morning from Paul (early shift, posted overnight from Washington DC), and Graham (UK shift).
Just FYI, we'll be switching on Weds, with me (Paul) giving you my undivided attention back in the UK, whilst Graham takes a little time off. As I think we've already demonstrated, we can juggle things just fine, and get a decent report out each day!
Graham says: all done for today. See you in a while!
Explanatory notes -
A quick reminder that we don’t recommend any shares. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech, investment cos). Although if something is newsworthy and interesting, we'll try to comment on it. Please bear in mind the "list of companies reporting" is precisely that - it's not a to do list. We typically cover c.5 companies per day, with a particular emphasis on under/over expectations updates, and we follow the "most viewed" list of readers, so if you're collectively interested in a company, we'll try to cover it. Obviously with the resources available, we can't cover everything! Add you own comments if you see something interesting, and feel free to discuss anything shares-related in the comments.
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to, if they are using unthreaded viewing of comments.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. And/or it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom),
Frozen SCVR summary spreadsheet for calendar 2023.
New SCVR summary spreadsheet from July 2023 onwards.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
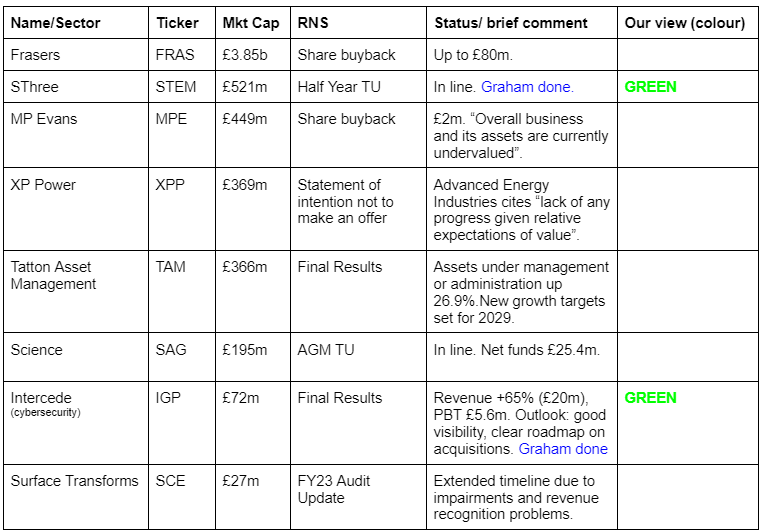
Companies Reporting
Summaries
Norcros (LON:NXR) - 212p (£190m) - FY 3/2024 Results - Paul - GREEN
FY 3/2024 results from last week were in line, and the outlook, but the value metrics are so favourable that I've circled back to it. I'm really encouraged that the legacy issues dictating a low valuation are now small, and maybe even resolved. That leaves a PER of only 6.7x, a yield of 4.8%, and recovery potential. It looks very attractive to me. Although we've been saying that for years and nothing ever happens! So one for patient value investors only.
Motorpoint (LON:MOTR) - 141p (£123m) - FY 3/2024 Results - Paul - AMBER
Lousy results for FY 3/2024, as expected. Not much balance sheet support, and forecasts mean you're being asked to pay up-front for 2 years' of trading recovery that has only just started. The bull case seems to hinge on an operationally geared recovery in used car sales on a leaner cost base. That may well happen, who knows? Although much higher finance costs could well blunt a profits recovery. Share buybacks seem inappropriate. I just don't want to pay up-front for a recovery, so the valuation doesn't work for me.
Intercede (LON:IGP) - unch. at 123.2p (£72m) - Final Results - Graham - GREEN
Sparkling results with the help of a large one-off contract to a US federal agency. There are recurring elements to this deal but it's mostly a one-off sale. After giving these results an overview, I give an example of how someone might try to value this cybersecurity software business with a mix of recurring and non-recurring revenues.
SThree (LON:STEM) - down 0.5% to 420p (£567m) - FY24 Trading Update - Graham - GREEN
Full-year results to November are still expected in line with expectations after a tough H1 with net fees down 7%. But looking past current challenges, I remain a big of this company for all of the same reasons as before. Progress in switching to a Contract-driven model continues with Contract now responsible for 84% of total revenues.
Paul’s Section:
Norcros (LON:NXR)
212p (£190m) - FY 3/2024 Results - Paul - GREEN
Background - this bathroom fittings group in UK & S.Africa always looks cheap, due to S.Africa risk (its second largest market), China supply risk, and a large pension scheme. When I last looked at it on 18/4/2024 I raised it from amber to GREEN at 175p, due to the exceptional value even allowing for the risks that everyone has known about for years.
Shares are usefully higher now at 212p, but we still have strong value figures on the StockReport of 6.7x forward PER, P/TBV 3.9 (so some asset backing), and a generous 5.0% dividend yield. Plus a stonking 99 StockRank.
We didn’t cover it last week, due to results & outlook being in line with expectations, hence nothing price sensitive, but the value scores have pulled me back to it. Also I’m curious how the pension scheme numbers now look, given this wasn’t mentioned in its April 2024 trading update.
Higher interest rates have had some intriguing effects on some defined benefit pension schemes, dramatically shrinking some deficits, and providing a potentially good upside catalyst for shares to re-rate. Remember too that Wincanton attracted a takeover bid shortly after declaring that its pension scheme was now fully funded. Reach (LON:RCH) is another one where the market could re-rate it if concerns about the pension scheme reduce. I’m sure there are others too worth seeking out where pension scheme changes could be a nice opportunity for investors.
Company headlines -
Robust performance in line with market expectations
Strong foundations in place to execute medium-term growth strategy
Unimpressive results, with profit down, but I don’t see this as a particular problem, given that most companies supplying home improvement products are struggling with tough macro conditions. Also, note that the fall in profit is entirely due to a weak S.Africa performance, where profit more than halved from £10.1m to £4.8m. Almost 90% of group profit came from UK/Ireland, so my leaning is to ignore S.Africa altogether, and just value this share on UK/Ireland profits only, and use a higher PER. Maybe it should sell the S.African business, in order to drive a potentially higher valuation for the group?
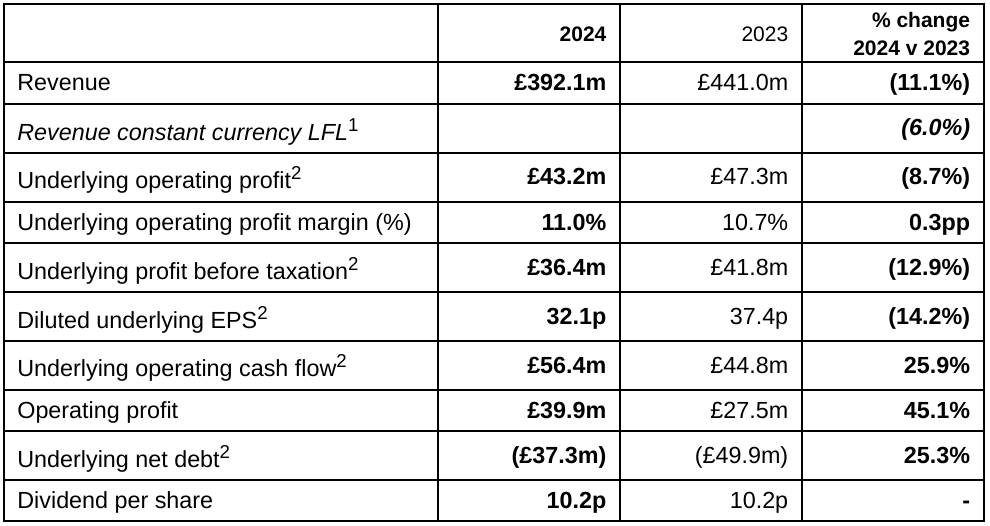
That’s a flat dividend at 10.2p, which is a 4.8% yield at 212p per share.
What it calls “underlying net debt” above of £37.3m is excluding IFRS 16 lease liabilities, which is the correct number to highlight in my opinion. Including leases, net debt is £59.5m. The underlying net debt of £37.3m is only 0.8x EBITDA, and with a useful reduction in the year, I don’t have any concerns about debt, it’s fine. Bank facility is a whopping £130m (plus a £70m potential accordion, with bank consent), so it has a lot of headroom for more acquisitions, although I hope management doesn’t go crazy taking on too much debt, which got it into trouble in the past. Bank facilities are committed until Oct 2027, which gives me comfort that the bank seems relaxed about risk here.
Adjustments look OK to me, so I’ll work with the 32.1p diluted EPS number above, giving us a PER of only 6.6x - which on the face of it looks a compellingly cheap valuation, as it always does with Norcros!
Pension scheme - is again showing an accounting surplus, increased about 10%, to £16.5m. However the last actuarial valuation in 2021 showed a deficit, requiring deficit recovery cash payments from NXR of c.£4m pa. The key question is whether the 2024 actuarial valuation will change this, in a potentially positive way? The existing overpayments are only about 10% of NXR’s profits, so it’s not a big issue any more - providing nothing big and unforeseen goes wrong with macro. Unfortunately I cannot find any guidance in the results commentary to indicate what’s likely to happen in future with the pension scheme. My feeling is that any changes are more likely to be positive than negative, since higher interest rates since 2022 should have helped reduce the actuarial deficit. Although it depends what has happened to asset valuations, since most funds are now invested in bonds, which often seem to have fallen in valuation. We’ll just have to wait and see, but I’m now assuming that the pension issue at Norcros is both relatively small, and probably improving. So I don’t think we need to take much off the value of the equity for the pension scheme at all.
Current trading - sounds OK, nothing exciting good or bad here -
Group revenue in the two months to the end of May 2024 was encouragingly 2.2% ahead on a constant currency like for like basis, adjusting for Johnson Tiles UK and Norcros Adhesives (UK and Ireland +2.0%, SA +2.5%). Group revenue was 2.9% below the prior year comparator on a reported basis.
Although market conditions are likely to remain uncertain, the Group continues to make further strategic progress and the Board's expectations for FY25 remain unchanged.
Paul’s opinion - I’m encouraged by my quick skim of the FY 3/2024 results. The traditional reasons investors avoid this share are now largely irrelevant in my opinion, eg -
S.Africa risk - as it only contributed about 10% of group profit, does it matter? I would argue that only a small discount is needed on the valuation to allow for potential country risk. Worst case scenario, the South African business could be sold off, and group profit would only drop about 10%.
Pension scheme - is likely to be close to fully funded, and even on 2021 actuarial deficit, only consumes about 10% of group profit. You could argue that S.Africa profit (£4.8m) pays for the pension scheme deficit (£4.0m pa), as the two numbers roughly offset.
Debt & balance sheet - look OK to me.
China supply risk - does this matter, as Norcros is like so many companies that get products made in China. If trade breaks down then the whole economy and many/most companies would be in turmoil. Although if/when China invades Taiwan then all bets would be off. So actually, it is a risk, maybe I shouldn't be complacent about it?
Overall then this share strikes me as significantly undervalued, and you get a 4.8% dividend yield whilst you wait (possibly a long time!) for shares to re-rate. I think it’s a decent quality business, making pretty good operating margins, and with well-established brands that many people recognise and are prepared to pay upper-mid prices for. I’m sticking with GREEN. Unless I’ve missed something, the low rating doesn’t seem justified by fundamentals any more. So it should re-rate at some stage, or maybe even attract a bid approach? Plus there should be cyclical upside when its markets recover.
Motorpoint (LON:MOTR)
141p (£123m) - FY 3/2024 Results - Paul - AMBER
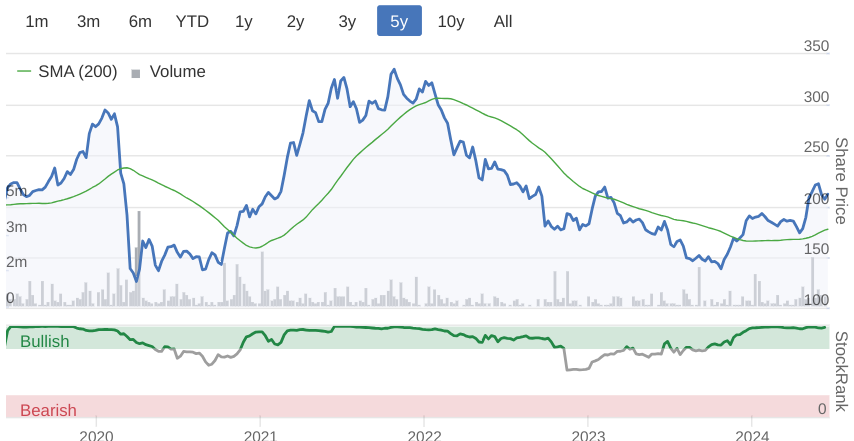
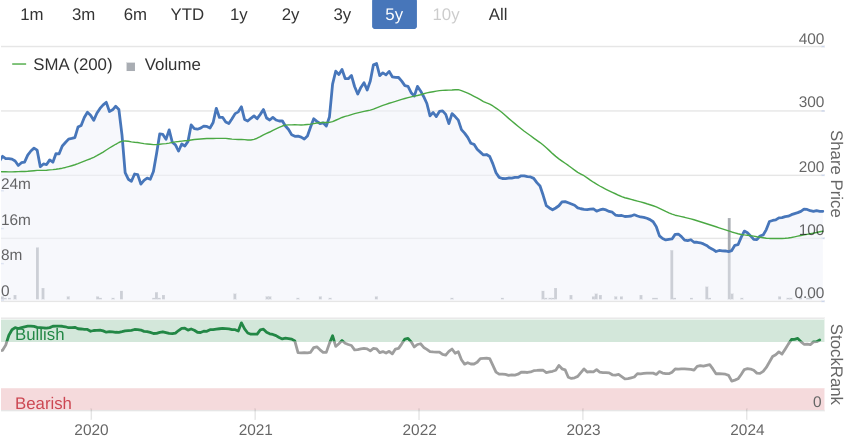
I must admit to be being perplexed by the recent strength in share price of this car supermarket, as its performance has been lousy in FY 3/2024. Still there are various ways of looking at shares. Bulls must be assuming it’s going to stage a remarkable recovery in profits, from the (as expected) £(8)m loss in FY 3/2024.
One thing I’ve pointed out before is that higher interest rates since 2022 mean that car dealers are now paying very much higher finance costs (on vehicle stocking loans). Hence we need to be careful not to get carried away with operating profit or EBITDA results, that are then engulfed with huge finance costs.
Note that this period covers a rough autumn, where used car prices lurched down unexpectedly quickly, hurting everyone in the sector. Although that’s a one-off I think, so probably OK to disregard. Maybe sector earnings have bottomed out?
Company headline - makes it sound as if MOTR is over the worst -
A challenging year driven by macroeconomic headwinds. Return to profitability in Q4 and good momentum going into FY25
Here are the highlights, or rather lowlights -
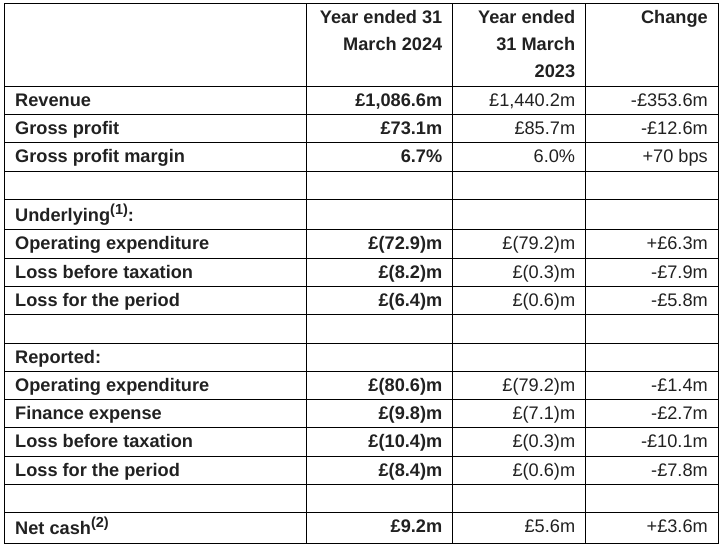
Outlook - quite interesting in that there’s obvious potential for operational gearing on a leaner cost base, with recovering demand. It mentions a move back into profitability, but at what level? Operating profit, I suspect, which as we know, is not the same as real profits, due to the hefty finance costs, eg £9.7m in FY 3/2024, and could rise further as higher inventories need to be funded with additional vehicle stocking loans (not included in net debt) -
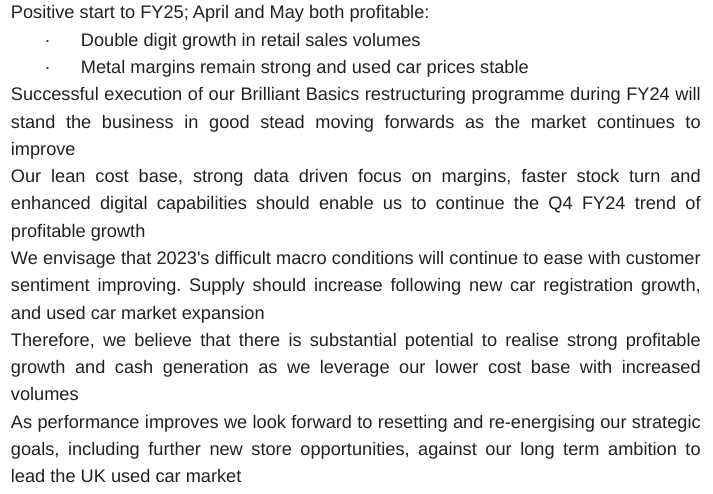
Forecasts - Zeus kindly give us an update, which forecasts a small £4.0m adj PBT in FY 3/2025, rising to £9.0m in FY 3/2026. Those are EPS of 3.4p and 7.8p respectively. That really doesn’t stack up at all well with a share price of 141p.
So bulls need to be very confident MOTR can beat forecasts.
Balance sheet - MOTR has NTAV of about £27m, which is only about 22% of the market cap. So unlike a physical car dealer like Vertu Motors (LON:VTU) which has full NTAV asset backing, MOTR has relatively little.
Share buybacks - don’t make any sense at all to me. The shares are expensive, and MOTR is highly geared (if you include interest-bearing vehicle stocking loans, which are set to soar as inventories rise) - exactly the opposite of the circumstances where share buybacks should be done, in my opinion.
Paul’s opinion - I like the potential for car supermarkets, and the online-only competition seems to be wilting, as expected, leaving potentially more market share for MOTR. It’s just that the valuation seems to have soared in advance of a proper recovery. Still, the valuation remains way below its previous growth company level, and there are excitable Americans on the shareholder list, who as we know pay higher valuations than UK value investors!
The current share price is asking us to pay 2-years up-front for a trading recovery which may or may not happen. I cannot predict the future, but generally I want a discount, not paying a premium for future uncertainty. Especially as this is an ultra low margin business with little asset backing. I’ll leave it to others to predict the future, I’m just assessing the facts figures and forecasts as of today, and on that basis MOTR shares look to have run ahead of themselves, so it’s not for me. Although it wouldn’t be fair to go below AMBER, as there’s nothing wrong with the business as such, it’s just pricing in too much future upside for my personal taste.
Potentially good upside if profits do recover to previous levels -
Graham's Section
Intercede (LON:IGP)
Unch. at 123.2p (£72m) - Final Results - Graham - GREEN
Intercede, the leading cybersecurity software company specialising in digital identities, today announces its preliminary results for the year ended 31 March 2024 ("FY24").
These are sparkling results as has been well flagged, e.g. see Paul’s coverage in April.
Key points:
Revenues +65% to £20m
PBT £5.6m (last year: £0.6m)
Gross margin improves to 97.2% (we might as well think of this as 100%?)
Cash more than doubles to £17m, and is nearly one quarter of the market cap.
The company also publishes an adj. EBITDA figure (£6.2m), with a detailed explanation of how it’s derived. But with such a small gap between adj. EBITDA and PBT, is it really necessary?
Highlights for the year
Intercede has enjoyed some major new contracts, and two in particular are highlighted.
Contract 1 - large US federal agency. $6.6m purchase order for perpetual licences, plus $1.4m annual support and maintenance.
A key disclaimer around this source of revenue:
This is the Group's largest single order to date and the Group highlights that this contract was an exceptional order and deemed 'one-off' due to the substantial number of perpetual licences purchased, which have been recognised in FY24.
Focusing solely on the purchase of licences, $6.6m of revenue is equivalent to £5.2m or one quarter of Intercede’s entire annual turnover for FY2024.
Contract 2 - a client in the US intelligence community. Perpetual licences plus support and maintenance for a total of $1m, plus a separate ongoing subscription for $0.2m.
Contract 1 is the one that really matters: without something of a similar size in the current year, then surely that will leave a big hole in the results?
Outlook
FY24 was an exceptional year for the Group. Intercede continues to invest in its colleagues, IT Infrastructure, product development, sales and marketing to maintain and sustain it current momentum.
We embark into FY25 with good visibility on the pipeline, known and fully resourced internal critical investments, and with a clear roadmap on our acquisition strategy. As mentioned earlier, the focus is on growth and execution of strategic plans to deliver it.
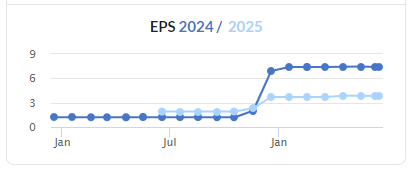
Estimates from Cavendish see revenues for the new financial year (FY March 2025) falling from £20m to £16.1m, and adj. PBT halving to £3m. Within that revenue forecast, recurring revenues (as opposed to one-off perpetual licence sales) are £9.1m.
Strategic Report - notes that the company has transitioned from phase one of its business plan (transformation) to phase two (growth). Additionally, the large cash pile now means that the company can “source, engage and execute on larger M&A transactions”. Some nice detail is provided on the company’s roadmap for the new year, i.e. their plans across various product categories such as password security management and multi-factor authentication.
Dividend - none. I agree that there is no urgent need to send money back to the shareholders.
Graham’s view
I can see why Paul has been so interested in this one; it has enjoyed eight earnings upgrades since 2022, according to Cavendish!
How to value it? Let’s start by noting the March 2024 cash balance, £17.2m.
We can then look at recurring revenues. This is perhaps about £9m now (FY March 2025), maybe £10m in FY 2026
My understanding is that US-based SaaS companies are currently trading at about 7x revenues. So we could value IGP’s recurring revenues (£9m) at £63m, for example.
(This revenue multiple for the market was as high as 19x during the Covid bubble. It never seems to get any lower than 5x-6x.)
We should also assign some value to IGP’s one-off sales. This is not an easy task: by their nature, one-off sales are difficult to predict! I’ll try to find a middle ground and give one-off sales half the value of recurring sales.
With £7m of non-recurring sales expected in the current financial year, I get a value of about £12.6m for this.
Adding it all up:
Cash £17.2m
Value of recurring revenues £63m
Value of non-recurring revenues £12.6m
Total: c. £93m, materially higher than the market cap £72m.
Of course these are really just back-of-the-envelope calculations, without studying Intercede’s specific products and customers in detail and figuring out the likelihood of large new contracts. If the company does get some deals similar to “Contract 1” in the next few years, they will blow these calculations out of the water.
We could argue that Intercede deserves a premium rating, thanks to the positive business momentum it has experienced in the last few years.
Or we could argue that it deserves a discount, as UK-listed software companies tend not to trade as richly as their US counterparts (at least not until there’s a takeover bid!).
Either way, I’m happy to leave Paul’s GREEN stance on this one unchanged.
SThree (LON:STEM)
Down 0.5% to 420p (£567m) - FY24 Trading Update - Graham - GREEN
SThree plc ("SThree" or the "Group"), the only global specialist talent partner focused on roles in Science, Technology, Engineering and Mathematics ('STEM'), today issues a trading update for the half year ended 31 May 2024.
My favourite recruitment company has the following H1 financial highlights. The year is still expected to finish in line with expectations.
Net fees down 7% year-on-year “despite the ongoing challenging backdrop and against a strong prior year performance”.
Contract recruitment (as opposed to Permanent) now 84% of total net fees (a year ago: 81%)..
Net cash improves to £90m (a year ago: £72m) (one-sixth of the market cap).
CEO comment:
Against the challenges experienced by the sector, we are pleased with our trading performance over the past six months, with strong Contract extensions partially offsetting continued soft new business activity. The Group's unique business model, centred on scarce STEM skills and flexible talent solutions, continues to be a source of strength…. We are well placed to take full advantage when the market returns.
We continue to execute our growth strategy, including the phased roll-out of our Technology Improvement Programme. Following our successful launch in the US, our deployment in Germany is well underway…
Business highlights: strong demand for Engineering, with Renewables the fastest growing segment. Life Sciences and Technology were down year-on-year. Technology is still the biggest skill group, accounting for 48% of net fees.
Geographically, there was strong growth in the Middle East and Asia, but the USA was down (again this reflects weakness in Life Sciences and Technology).
Headcount was “down slightly” at the end of the year.
Graham’s view
As it’s in line with expectations there is little need to change my positive view on this one.
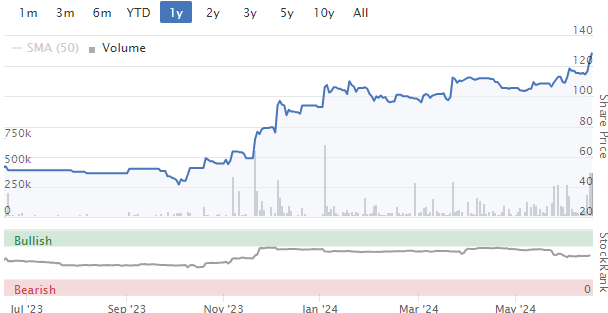
The StockRanks are in full agreement, giving it a score of 98.
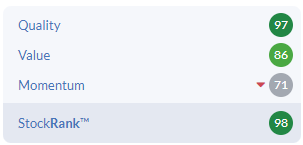
The PE ratio is 10.4x according to the StockReport, but remember that this is not adjusted for the strong balance sheet. After taking that into account, the “real” multiple is less than 9x.
The stock passes 7 bullish stock screens in a range of categories: quality, value, income and growth!
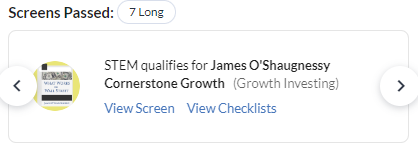
So from a quantitative point of view, this stock is ticking many boxes indeed. I also think that it’s a fine real-world business with a great track record, excellent geographic diversification, exposure to a wide range of STEM sectors, and Contract income that it can easily be argued is recurring in nature.
If economic conditions remain tough then SThree’s growth is likely to remain limited for as long as that prevails. But personally I would sleep soundly owning this one.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

71 comments
edit: wrong thread
Just seen most house builders off at the close anyone know any reason why the sector is down today other than interest rates staying higher for longer ?
As it's end of play I thought I'd put a BBC job application typo :-)
i see Argentex (LON:AGFX) (i hold) are probably a leaky share, they post results tomorrow and are 6% down as of today even thou the chart sentiment said othewise yesterday.... :(
They had an online investor meet today this morning i think.Folk bought in for it.Folk watched it.Folk got disappointed as the stragey update/potential turnaround is going to be longer than thought.I hold too but didn't watch it.Just repeating what i read off another board regarding the timeframe.Postiive,..the share price did bounce off the 32.5p a share level!
TY SD
Really good discussion on Intercede (LON:IGP) today with both bull and bear cases being put forward by a number of different contributors, all done so in a polite and considerate manner. A great write up from Graham on Intercede (LON:IGP) also. Thanks to all involved, these types of discussion are why I'm more than content to keep paying the subscription every year!
Much has been written here about Equals (LON:EQLS) recently. I am a long term holder since September 2020. Like many of you, I would have liked the strategic review to have finished ages ago. During this time, my experiences have led me to hold management in high regard. Equals have consistently demonstrated impressive revenue and margin growth and consistently beaten expectations. Last year the company was throwing off £1 million cash every month and this figure will be higher now. MDP pulled out after 7 months. I do not think they would have remained interested for so long, if there were some nasties lurking, but pulled out much sooner. I think the issue is price. Pembar, original investors, are looking for a decent exit or they will not sell, say 165p. I suspect MDP made an indicative offer around the 130p/ 140p mark which is too low. As a shareholder I am pleased that they will not sell for price they deem low. I suspect that the Consortium have offered more than MDP so MDP pulled out. It is also of note that MoneyGram owned by MDP are talking to Equals about a tie-up for 'B2C and their technology platform' which I think encompasses B2B as well. MoneyGram are massive in comparison to Equals so this could prove significant.
Compliance has been raised as an issue. Equals have always stated they invest heavily in compliance, regular training and external audits. All payments are across Tier 1 banks who know what Equals are doing and are subject to external audits.
These are just my views and I do not know what will happen but I think the share price has suffered due to the length of time taken and the information vacuum which accompanies these situations. I continue to hold the shares.
I noticed that Equals have recently published some important dates:
Important Dates | Equals Group Plc (equalsplc.com)
Great comments Michael & totally agree. I remain long & strong too
Hiya Michael, I share your views . EQLS is at the end of a period of investment and strategic developments from which they are only just beginning to reap the rewards. I believe that they had their hand forced into this strategic review. So, in short I concur that the price offered by MDP probably fell well short of EQLS' Management's expectations.
As shareholder it is easy to foresee the value of EQLS doubling and more at their current clip of growth - so if we don't see an offer giving a decent uplift - I'm happy to be patient.
Paul - Apologies if I have missed the link, but could you share the Google Sheets data which demonstrates the performance of the colour coding system. Many thanks, Daniel
if you scroll from the top Daniel, there are four links in the heading post everyday, to Paul's sheets :p
Patrick - Yes, I'm aware of those links. The one I was referring to was the numbers Phil Hanson crushed on the colour coding system. Paul discussed it during this (https://www.loom.com/share/75e...) video and indicated he would share the spreadsheet, but I have missed the link somewhere along the way.
SThree (LON:STEM) H124 Trading Update, here's the analyst call video & podcast. Graham, many thanks for your comments. As you say in line with expectations for the full year. I always find the recruiters interesting for the wider macro picture, here we see:
More detail at H1 2024 results on 23rd July.
Eurocell (LON:ECEL) Down 4.3% today
Announced share buyback programme in January "up to a maximum consideration of £5 million."
Latest Eurocell (LON:ECEL) RNS states "the Company will have 642,000 shares held in treasury and the Company's issued share capital (excluding shares held as treasury shares) will consist of 105,479,218 shares."
Rough calculation suggests they have purchased around £0.86 million worth of shares so far.
Any thoughts why the fall in the SP today?
Eurocell (LON:ECEL) spiked up a few % right at the end of yesterday for no apparent reason so probably just a reversal of this. Share price pretty flat over a few days.
"Eurocell (LON:ECEL) Down 4.3% today"
Rubbish! This is the distortion that particularly affects small caps and everyone should be aware of - namely taking the UT price as the closing one, and what happened at Eurocell (LON:ECEL) is typical.
At 16 29 yesterday the price was 132.5 (132/133). It opened this morning at the same and then moved to 131.5 (131/132). As far as I am concerned that is down 0.75%.
What causes the alarm is that in the auction last night 13,437 shares changed hands at 138p thus setting that as yesterday's price. I have seen the same happen with a very small number of shares. Indeed, this morning's auction saw just 9 shares traded at 134p so that became the official (not actual) opening price - the highest buy since has been 133p.
Thanks for the helpful (although somewhat supercilious) reply. I was misled by ADFN:
Eurocell (LON:ECEL)
turbo - thanks for your reply. If you felt my post was 'somewhat supercilious' please be assured that the 'Rubbish' was not aimed at what you had written but at the system that dictates that it is down 4.35%. I have been panicked many a time by that and have learned to check the 16 29 and UT prices as a first line of enquiry.
It is not just ADVFN - it is standard from the London Stock Exchange down:
Graham, re Intercede (LON:IGP) do you have any idea why Stocko has a forecast PE ratio in the low 30’s, I.e. well above your numbers? Thanks
This free event starts in 45 minutes...
Register for FREE for the Mello Investment Trusts and Funds show today 18th June 2024 at 1pm, hosted by Karin Schulte. The programme for the event is as follows:
1:00pm Andrew Hollingworth, Founder of Holland Advisors & Investment Manager of VT Holland Advisors equity fund
1:30pm Company presentation from JPMorgan European Growth & Income plc
2:00pm Company presentation from Nippon Active Value Fund
2:30pm Company presentation TBC
3:00pm Educational Session
Register for FREE here: https://us06web.zoom.us/webinar/register/WN_pLegtMeTS5aaxkqViRXWwA#/registration
Click here for more information: https://melloevents.com/mitf-18-0624/
We hope you can join us.
David
Lithia Motors have increased holding in Pinewood Technologies (LON:PINE) , formerly Pendragon to 24.78%. Christopher Mills of Harwood Captal seem to have called this one right, thank you Paul Hill - podcast.
BBC news yesterday: London becomes Europe's largest stock market again - first time in two years, overtaking Paris - "They say the French market has slumped because of the uncertainty around its election, while the UK market is recovering after several years of underperformance."
XP Power (LON:XPP) Interim results are August (so who knows could there be more potential gremlins in there?).I was just wondering if anyone has bought today on the fall or is considering buying, considering what the trade would have been willing to potentially pay (information that regular, non industry specialists, punters wouldn't normally get?Or do you think financing issues plus cyclical issues make it a red flag for now?
Looking at the Motorpoint (LON:MOTR) figures, narrative and SP trend, it set me to thinking about what we can expect in the motor trade in the next couple of years. Assuming Labour don't change the rules set down by the Tories, swinging fines will start to be applied if target %s of sales of electric versus ICE targets are not met, then there should be manufacturer andd dealer encouragement to buy electric and fewer sales of ICE cars (because the electric rake up increase will be a gradual one among the general public - mileage capacity, facilities for charging, price differential versus ICE equivalent cars}
I assume that hybrids do not count as electric cars for the purpose of the Government rules.
Will this tend to push up the price of second hand cars, especially if the overall car market recovers. In which case do the likes of Motorpoint (LON:MOTR) stand to benefit disproportionately?
Just thought I would start the discussion - and I haven't even mentioned the impact of cheaper Chinese electric imports if in fact that happens.
Card Factory (LON:CARD) Edison have released a research note with a target SP of 180p (if only!!!). Obviously paid for but useful nonetheless. There is also on Research Tree a detailed interview with the CEO - https://www.research-tree.com/...
No mention of the Telios overhang which dominates the price at the moment.
Card Factory (LON:CARD)
They did go down from 10% to 9% the other day (from memory - look it up for precision). We just need to wait another decade or two and they will be out.
Thanks Gimmers; really helpful.
Thanks for the link. Good they are getting some research out there, although I didn't really glean anything new from the note. No mention of what might be weighing so heavily on the share price (whether the Telios overhang or something else). However, they are forecasting further increases in the DPS to 5.8p in 2025 and 6.4p in 2026 - this is presumably what Card Factory (LON:CARD) has guided them to say, which suggests a nice yield of around 7% in a couple of years.
Nice news from CCS up 70% at one stage
Crossword Cybersecurity Secures Transformative Partnership with Global Defence Company
Norcros (LON:NXR) - thx for another good review, Paul, and you beat us out by about half an hour! We have both followed this quality stock for a long time, but note Norcros (LON:NXR) shares have had a good move in recent months (+ 50% from Oct '23) as new CEO markets the group's strengths. Full note out from us today, 6.5x PER '25E and 4.9% yield: current fair value seen at 253p / share....as you can read here https://www.equitydevelopment....
Norcros (LON:NXR) - Clear progress evident, and more to come (full report here: https://www.equitydevelopment....)
FY24 results clearly showed that UK portfolio management is already starting to bear fruit and collaborative actions taken should support further margin progress in due course. Our fair value, other peer group metrics and strategic earnings potential all suggest a share price above current levels.
Revenue and EBIT came in just above indications in the pre-close update led by a firmer outturn from UK/Ireland operations. Reported EBIT margins were 13.6% in the UK (+100bp yoy), 4.4% in South Africa (-260bp) and 11.0% at group level (+30bp). UK and group operating margins for continuing operations in FY24 were 15.0% and 11.8% respectively. DPS was held at FY23 level and year end net debt (pre IFRS16) basis was in line at c.£37m after strong H2 cash inflow.
FY25 has started positively for Norcros suggesting outperformance in markets where wider commentary remains generally cautious. GDP forecasts for both of Norcros’ primary countries of operations show modest expected growth and we have made no material changes to our underlying revenue and EBIT expectations, save for adjusting to prevailing £/ZAR rates.
Our fair value adjusts to 253.5p per share, down slightly due to peer group comparator effects. The previous analysis of group strategy and potential earnings implications is unchanged, with a prospective valuation in excess of 400p per share.
Another contract win for SAAS, good numbers on this small cap
Brickability (LON:BRCK)
Senior management have been significant buyers of the company's shares this year and continue to do so. Unless I have completely gone off piste, the two sizeable acquisitions of cladding/facade companies at the start of the year should be beneficiaries of the much publicised cladding remediation works.
"On 14 June 2024 Douglas Bryce, Managing Director within the Contracting Division, purchased 400,000 ordinary shares of 1 penny each in the Company ("Ordinary Shares"), at a price of 67 pence per Ordinary Share.
Following the transaction, Douglas Bryce is beneficially interested in a total of 1,209,750 Ordinary Shares representing approximately 0.38% of the Company's issued share capital."
Holders of Card Factory (LON:CARD) (not one of mine) might find Cardzone Group trading director James Taylor comments in the Retail Gazette this morning of interest. The Cardzone Group bought up the rump of 163 Clintons stores to add to their existing portfolio of 175 stores. Back in the day, Clinton operated 1,000 stores across the UK.
Taylor said the Clinton group was in a worse state than expect and he did not expect a return to profit until 2025. He admitted "we underestimated the work required to turn it around " and said "consolidating the two business this year was going to cause some pain, including the closure of some stores". One interesting observation is that he thought some of the stores were simply too big for the offer and expected to have to downsize some of the stores.
Hi James.
If I interpret the comments from Mr Taylor correctly the challenge for Cardzone integrating the Clinton acquisition should be positive for Card Factory (LON:CARD) ?
I wish Mr Taylor the best in his efforts, but as a holder of Card Factory (LON:CARD) I wish to see the company continue its successful turnaround. The quicker Telios makes up its mind off loads it stake the better, as it continues to create an artificial cap on the share price
Card Factory (LON:CARD) are gaining market share in a slightly declining market. I imagine that would be partly at the expense of Clinton Cards and Cardzone. I don't hold.
Hi James
Looking at our small town, Card Factory (LON:CARD) have a small store on the High Street in a central location, whereas Clinton are across the road have a store about 5 times larger. So given rates is on floor space, the overhead cost and associated sales required to recoup are significantly different.
Tommy
It is the same story in Inverness. Clinton's gross margin cash return per sq ft must be much lower.
No mention of Telecom Plus (LON:TEP) on their excellent results today ?
Telecom Plus (LON:TEP) Hardly a small cap.
Telecom Plus (LON:TEP) good looking headline numbers but deducting the share based payments give diluted EPS of 102.8p so now on a P/E of 19; not as cheap as it was. I'm more concerned with the cash outflow of 136m - big swings in both receivables and payables which need investigating.
My morning smallcap tweet: A guffaw unto themselves
Surface Transforms (LON:SCE) Crossword Cybersecurity (LON:CCS) XP Power (LON:XPP) £STBX Destiny Pharma (LON:DEST) Pipehawk (LON:PIP) Synectics (LON:SNX) AFC Energy (LON:AFC) Cordel (LON:CRDL) DCI Advisors (LON:DCI) Quantum Blockchain Technologies (LON:QBT), Science (LON:SAG)
◄Surface Transforms (SCE)► accounts are a grind as FY-Dec results delayed to late June due to matters resulting in write-downs and delayed rev recognition. Expects c.£9.2m impairments and £2m rev from FY23 and earlier recognised in future years. [SP=NA Cap=NA]. I hold a fag end of this disaster.
◄Crossword Cybersecurity (CCS)► partnership to jointly market Rizikon supply chain cyber platform. [SP=NA Cap=NA]
◄XP Power (XPP)► Advanced Energy will not make an offer. Blames XPP for not engaging. [SP=NA Cap=NA]
◄SkinBioTherapeutics (STBX)► positive results in AxisBiotix Acne food supplement tests. [SP=NA Cap=NA]
◄Destiny Pharma (DEST)► positive efficacy data on XF-70 in an in vivo model of ringworm. [SP=NA Cap=NA]
◄PipeHawk (PIP)► partnership with Unipart Rail has further expanded beyond the distribution of subsidiary TED's standard products. Expects rev from this to be c.£0.5m in FY-June. [SP=NA Cap=NA]
◄Synectics (SNX)► wins $10m contract for completion by end FY No 2025. [SP=NA Cap=NA]
◄AFC Energy (AFC)► delivered its highest power rated 200kW H-Power Generator to date. [SP=NA Cap=NA]
◄Cordel (CRDL)► wins first contract win in the Middle East, worth £370k. [SP=NA Cap=NA]
◄DCI Advisors (DCI)► FY-Dec audit delayed to 9 Aug or later. Blames KPMG for not even starting until 4 June (or perhaps later). Shares will be suspended from 1 July. [SP=NA Cap=NA]
◄Quantum Blockchain Technologies (QBT)► Sipem's appeal rejects except for reduction of liability for one of the former directors by €105k, reducing the total damage award to c.€6.1m. [SP=NA Cap=NA]
In line: SAG
Literally just woke up and need some time for my eyes to be able to read small text first, but noticed Synectics (LON:SNX) have released a RNS of a £10m contract. Their market cap is only about £27m of my head, so this looks promising and worth looking at.
Thanks to shore capital for early report out for Synectics (LON:SNX) . Her are some figures of theirs.
Hi GMT
Strange thing here tho is having announced the new $10M contract, Shore Capital have said they are not altering either 2024 or 2025 forecasts - what does that tell us??
I hold a small position here
It did say the contract would be later in the year. It may just come under 2024 financials or could well be 2025. That is probably the reason they have not updated. The brokers are often conservative and like to wait. I’m not concerned over it.
currently the sp is 10% up today. Resistance of previous high is holding it there. I imagine there are probably a few sell orders set for the current price. The volume looks good today so I’m thinking it’s just a matter of time before it breaks the resistance and Synectics (LON:SNX) sees the next resistance level around 220p.
This share has now turned from a good value share to a longer holding GARP. It’s a bit boring, but I like boring if I get a share at a low price and collect a steady dividend as well as a slow rise in the sp. What investors need to note is the low amount of shares the company has, which can make the sp have big swings. The sp has stayed up nicely though.
Ok GMT - that all makes sense. I also note that the contract is from an existing customer in SE Asia that is simply upgrading/replacing it's old (2014), now out of date systems. That also bodes well for future orders I'd say.
A lot of their orders do come repeat or upgrades
Great results from Intercede (LON:IGP). They'd already flagged increase in revenue in previous announcements but the growth in profit and EPS announced today is way ahead of expectations. Looks like they are gaining momentum. It would be interesting to see what others (inc. Paul/Graham) think.
Are there any “one offs” in Intercede (LON:IGP) revenues? Or how much can be extrapolated through until this year?
Intercede (LON:IGP) - they had their largest contract during the year; think it was with US Dept of Defence. So making 2025 comparatives challenging. But, overall, sparkling results, after many years of frustration!
I agree good results and the EPS increase is a nice surprise. A lot of this is due to the big contract win so I was most interested in the guidance:
We embark into FY25 with good visibility on the pipeline, known and fully resourced internal critical investments, and with a clear roadmap on our acquisition strategy. As mentioned earlier, the focus is on growth and execution of strategic plans to deliver it.
Personally I think this is super wishy-washy. Where is the depth and expected figures to support any of the statements. If they have good visibility then tell us about the numbers. Having a 'focus' is not going to cut it for most investors.
As a holder i will be interested to see the response this morning. I wonder if the increase in EPS will offset the fy25 guidance, or lack of it! Could go either way!
Thanks BenHazz
I did seem to remember that Intercede (LON:IGP) had a large contract that might be masking the forward profitability but wasn’t sure and haven’t followed closely enough.
Agree the outlook felt vague to me as well which suggests the PR doesn’t want us to know that perhaps this won’t be repeated for the current year maybe?
Nice story on focus on growth but I fear the forward statement will say something along the lines of “we’ve grown x% above our baseline from FY22 stripping out the large one off……blah blah”
Maybe I’m being harsh but it just has that feeling about it. Can’t argue with the tech or client base though.
Excellent results from Intercede (LON:IGP).
Whilst the prelims are a very good read, the investment case was summarised concisely by the partner from Guidehouse (formerly PWC’s public sector business, bought by Bain recently for $5.3 bn) who flew to the UK to present at IGP’s CMD and said (to paraphrase) that IGP has the best software, its team plays an active and constructive role in pitches for new business (unlike some software companies) and IGP is very supportive of the customer (e.g. rapidly resolving queries raised in the middle of the UK night).
The outlook statement is relatively non-committal (it’s 2.5 months into the year) but contains no “subject to” or “macro challenges” etc. The unqualified nature of the statement seems consistent with the conservative guidance in FY24, with consistent upgrades through H2 as new wins came in (and an outcome well ahead of even the year end TU).
Cavendish has raised forecasts for FY25 and FY26 from 3.7p and 4.1p to 4.2p and 4.5p respectively, reflecting Cavendish’s decision no longer to adjust out cash inflows from IGP’s R&D tax credits. It was always anomalous that payments on the same line item (tax) were factored into EPS if negative and adjusted out if positive and Cavendish’s change brings IGP into line with the presentation of other companies receiving tax credits.
With 29.5pps cash, IGP trades on a trailing PE of < 10. Whilst this is a product of the exceptional contract won in FY24, it’s worth noting that “exceptional” does not mean “unique”. There’s another very large US opportunity that’s expected to go to RFP in December 24 (although it’s unclear how long it will take to get to contract award and, whilst IGP is very well positioned, it might not win).
CEO Klaas van der Leest exercised 130k options at 27p today. There’s no announcement that he sold some of them to pay tax. There may be an announcement coming but, if not, his decision to fund the tax from cash and keep the shares suggests to me that he sees upside to the share price.
It’s the non-committal nature and slightly disingenuous nature of the “growth” statement I don’t like at Intercede (LON:IGP) this morning.
As you point out it is clear they don't really trade on a 10* PER at all but more like 25* which is far from cheap. Being reasonable strip out the cash and it’s 22* PER but still not cheap. Yet management don't say the EPS for the year will reduce - far from it, they talk about focus on growth. For me that is either a PR team or management blowing smoke and hoping people can’t see. I don’t like that at all.
As you say if they can continue winning large lumpy contracts (even if only every other year) that would merit a higher weighted EPS average over the cycle but to date they’ve only had one, so maybe lets see if the one in Dec is won.
I was initially intrigued when I saw the RNS this morning but rather less so now I’m afraid. I see the early price was up but some selling going through and back to 1p up.
Reasonable results but not “sparkling” and management have blotted their copybook for me in the outlook statement but I will watch it with interest as any step change in regular revenues could make a material diff to the valuation at some point.
Thanks for your thoughts on Intercede (LON:IGP), Alistair. I agree the company has very strong potential, it is why I invested initially. I would like to have had a little more substance to the guidance though, especially regarding recurring revenues, but is interesting you mention that it was very similar picture last year as well. I agree with David's thoughts on the forward statement, maybe I am also being overly harsh. I must say I was a little surprised to see it open in the green and sold half of my position at the open, admittedly I did not have access to the broker notes at the time so thanks for sharing those.
Intercede (LON:IGP) is my second largest holding so I'm clearly not impartial, but when I looked at potential 5 baggers over the next 4 years a few months ago, Intercede was one of the most likely. Their gross margin is 97% and their main cost is people so operational gearing is huge. They are the market leader in PKI (the most secure) credential management and secure 3 out of the big 4 US federal agencies (State, Homeland Security, Defence) with the 4th (GSA) going to RFP later this year. What's interesting is that Russia/China tensions mean the US is putting pressure on their allies to beef up their cybersecurity. At the CMD, they said that the UK is now rapidly increasing engagement with them and Europe/Australia/ME won't be far behind.
Add to that their integration of MFA/Enterprise password management into MyID and they are the only provider of the whole authentication pyramid on one platform. Large enterprises will be able to move employees to different levels of security without having to move between systems. Given that >95% cyber incidents are from credential mismanagement (I'm looking at you Microsoft), this ease of use is highly attractive to clients. Europe are introducing NIS regulations at the end of this year which, according to one of their partners on the CMD, will increase the European market 10x.
The CEO has done a great job over the last 5 years leveraging their technology. 94% of their revenues come from channel partners so they don't need a direct sales force. As Klaas says, they don't need to do marketing - they just point at their client list.
The downside is that forecast revenues aren't predictable and will be volatile due to the timing of the larger lumpy contracts (hence the outlook statement). Having said that, recurring revenues are running at around 11.5mm (MRA/PSM are recurring while the perpetual contracts have 20% sales & maintenance and they have a large element of recurring professional services) which covers 90-95% of their cost base so any contracts above that drop straight through. They're conservative on their forecasts so have had 8 upgrades over the last 2 years.
They're targeting underlying revenues of 24mm over the next 4 years which would give EPS of approx 20p. Put that on a PE of 25 and you get a 5 bagger.
In the meantime, their forecast ex cash PE is 21 at 120p with their markets growing at 12-20% for the foreseeable future and that's without any of the big government contracts of which there are likely to be an increasing amount over time.
Could Intercede (LON:IGP) not also then be considered a Defensive stock in terms of investing sentiment RE : security. thinking out loud ?
Intercede (LON:IGP)
Cavendish has the EPS falling back to 4.2p in the current year.
David, Ben
Thank you for your comments.
Intercede (LON:IGP) have, I think, tried very hard to be clear that the large US contract was exceptional.
They announced the contract win on 5 December 2023, saying in the third paragraph of the RNS: “The Group wants to highlight that this contract is an exceptional order and deemed 'one-off' due to the large number of perpetual licences purchased which will be recognised in FY24.”
At the recent CMD, slide 20 (see IMC website) is headed “Revenue Growth – Consolidated without exceptional Federal order” and says “Adjusting for the exceptional order, the revenue growth rate illustrates consistency in double digit growth plan.”
Today’s announcement says in the introduction “this is the Group's largest single order to date and the Group highlights that this contract was an exceptional order and deemed 'one-off' due to the substantial number of perpetual licences purchased, which have been recognised in FY24.”
The forecasts from Cavendish have always assumed that the FY24 order was exceptional.
I'm surprised by the reaction to Intercede (LON:IGP) results. In an ideal world the forward guidance would be more explicit - but bearing in mind they are bidding for big contracts (against competitors) it must be difficult to produce a meaningful prediction - the binary outcome could dramatically change the picture. The fact that they have recently been winning large contracts bodes well. Agreed the 4.2p eps for the current year looks bad when comparing to this years exceptional c.10p eps. But in 2023 eps was 2.16p. I'm happy with the direction of travel.
I’m not remotely surprised at the reaction to Intercede (LON:IGP) - I was surprised when they opened up 10p.
I don’t disagree that this is a good company but it has a problem - firstly it isn’t cheap and secondly EPS can double or halve one year to the next and these types of businesses don’t tend to command higher ratings. Investors (rightly or wrongly) like smooth consistency.
The business generally looks good and I like it - maybe in 3 to 5 years the profile will look better but as of today the price feels about right to me.
Graham has put recurring revenues on a US style multiple which I think is generous and he’s given non recurring revenues half that rating which I think is incredibly generous given those are in the past. Granted they may get more one offs - but they haven’t to date so we are taking a punt.
I personally get closer to a £65m market cap valuation which is 8% lower than current price. So I’d be keen to take a look if it drops back to 110p but no major desire to buy here. Seems mr market takes a similar view - people were selling up at 130p earlier and its dropped back to 120p level which isn’t far off my fair value calcs.
Clearly it’s a decent business though so sit and wait for an opportunity will be my position. May never get there but doesn’t feel like any hurry either so maybe some will get impatient.
I wasn't surprised either with the Intercede (LON:IGP) SP reaction either given the run up in recent days and the fact that forecasts were never going to get raised until H2 given the nature of their business.
A lot of your points are fair, but I do disagree with your view that they're just a "decent" business. Where else in the UK market can you find a global leader in probably the second most headline worthy IT sector (after AI) with limited competition in the high-end space - at the CMD, they highlighted how they were in 4 of the 5 bids for the recent large contract (including the 2 finalists).
There's a huge pull of reputational/financial costs to enterprises of cyber breaches (almost all of which are due to breached credentials) and a huge push of increasing regulation coming . One of their hackers at the CMD showed how he could crack even 12 character passwords in a couple of hours. One time codes can be intercepted by SIM/device cloning. AI means that phishing/fake audio/video calls are multiplying and indistinguishable from the real thing. Authentication will have to move from simple sign on to checking it's still you at every step of the process without making it cumbersome to use and yet most enterprises still use simple passwords.
I’d say to answer your question Brothersinarms Kromek (LON:KMK) share a lot of similarities. Big moat, fabulous tech, blue chip client base to die for - US government regularly buys. All other competitors in the CMZ space have been taken out in vertical integration style leaving Kromek (LON:KMK) as the only independent on the market……………based on other deals value of their IPR is several times the current market cap……
BUT
Commercialisation - regular profits have eluded them to date despite all this. Maybe that company is also turning around and they will become the great business they should be too.
The point I’m making is don’t correlate great tech IPR and customer base with great businesses necessarily.
As I say I am interested in Intercede (LON:IGP) I just think there will be a better price to get in for a longer term trade.
Agreed David, but Kromek (LON:KMK) (I hold a few) has never generated free cash flow in it's life whereas Intercede (LON:IGP) has generated nearly £25mm in the last 5 years.
davidjhill, great comment on Intercede (LON:IGP)! Can I just clarify one thing? - I valued the non-recurring revenues based on expectations for the current year, not on last year. Non-recurring revenues are forecast at £7m this year (FY March 2025) and £8m next year (FY March 2026). They were c. £11m in FY March 2024. Cheers. G
Hi Graham - noted and thanks for clarification.
If I’m a bit more generous then I get to circa current market cap. You get to maybe 30% upside so possibly somewhere in between our FV estimates may be about right.
Either way doesn’t feel particularly worth chasing right now to me, though I could easily be wrong. I certainly was with Filtronic (LON:FTC) but to be fair to me that was the Musk effect driver as much as anything.
In their presentations Intercede (LON:IGP) have also said they have 2-3mm repeating professional services revenues (from supervising upgrades, client requests etc.). It's not recurring revenue per se but it's pretty solid so really the forecast license sales for the year ahead are about 4-5mm.
Tatton Asset Management (LON:TAM) "FY24 forecasts exceeded, very strong start to FY25" - new research here: https://www.equitydevelopment....
It has been a huge few years for Tatton. The three-year growth target of moving from £9bn AUM on 31 Mar 21 to £15bn Assets Under Influence (AUI) by 31 Mar 24 was comfortably exceeded, with AUI closing 17% above target at £17.6bn – a 96% gain over three years.
Yet FY24 was without doubt the most impressive. AUM jumped +30% over the year purely from organic growth, with net flows of +£2.3bn (record net inflows for Tatton and a net flow rate far higher than all peers - page 4), and a tailwind from investment performance of +£1.5bn.
Tatton has exceeded our previous forecasts for FY24. It has set an ambitious new 5-year plan to reach £30bn AUI by end-FY29. And it has had an exceptionally strong start to FY25, with net inflows of £0.9bn in Q1-25 up to 14 Jun (matching the total inflows of H1-24), bringing AUI to £18.6bn.
We therefore increase our FY25 forecasts as detailed below, as well as our fundamental valuation which rises from 620p to 640p per share.