Small Cap Value Report (Tue 18 Oct 2022) - FCAP, RBG, 888, SOS, SED

Good morning from Paul & Graham!
Audio interview - this latest one is me talking yesterday to the CEO of Sanderson Design (LON:SDG)
I think Lisa Montague's passion for the business comes across really well in this discussion. Obviously in current macro conditions, anything could happen, but the company did confirm full year market expectations recently. Organic expansion in America seems the main growth strategy, where SDG is only scratching the surface of a large market. Bulletproof balance sheet too. This is near the top of my personal watch list, to buy back in at some point. Lovely strong balance sheet too.
I'll type up a written summary & post it here later today, for those who don't have time to listen to the audio.
Agenda
Paul's Section:
finnCap (LON:FCAP) - confirms press (Sky again!) reports that it has received a takeover approach from rival broker Panmure Gordon. I give my thoughts on this below, and hope that Finncap remains independent, as it has been a good friend to the private investor community, providing us with research, and access to company management teams. Whereas Panmures, not so much - could try harder.
Revolution Bars (LON:RBG) - announces FY 6/2022 results (due out today) will be "slightly delayed" because management are busy working on an acquisition, which has triggered the "substantial transaction" AIM rule 12, so out of curiosity, I have a dig into the AIM rules. Results are confirmed to be "consistent with previous guidance", so I don't think there's anything to worry about here.
UPDATE: news coming through from Propel, the sector newsletter, that this is the acquisition target -
| Revolution Bars Group set to acquire Peach Pub Company: Revolution Bars Group, which operates the Revolution and Revolución de Cuba brands, is set to acquire Peach Pubs, the 22-strong gastropub operator, in a deal valued at between £10m and £20m, Propel understands. |
Sosandar (LON:SOS) - a solid H1 update, trading in line with expectations for the full year (which is a profit of £2.0m). Stunning organic growth. No sign of consumers retrenching for SOS. There's obviously risk from a possible downturn, but I explain why SOS's outsourced business model should protect it. Long term, I think this share could be heading a lot higher. Short term, it should be OK I think. A firm thumbs up from me.
**Sosandar is the mystery share (best idea of the week) for this weekend's podcast **
Graham's Section:
888 Holdings (LON:888) (£381m) (I have a long position in 888) - this Q3 update includes a few disappointments. Pro forma revenues are down 7%, and interest costs are likely to rise. Against that, the integration of William Hill is underway and the Adjusted EBITDA margin for the year should meet expectations. The high-risk strategy to buy William Hill with debt has torpedoed 888’s share price, but I remain interested to see how it will play out. Cost synergies and careful cash control might enable the group to deleverage and restore market confidence. But it’s well within the realms of possibility that it doesn’t work out, and that further dilution is required (or worse).
Saietta (LON:SED) (£103m) - I take an initial look at this 2021 IPO that wants to be “a global eDrive solutions leader”. It has motor design patents, manufacturing capabilities in Sunderland, and joint ventures in the US and in India. Fundraisings have enabled it to hire staff and bring new products to market. I have no firm view on this yet but it looks like there is a huge cut to the revenue forecast today, as the company is changing its strategy in order to secure even bigger contracts with bigger customers in the years ahead. £23m of cash gives it some breathing room.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
finnCap (LON:FCAP)
17p (up 26% at 09:04)
Market cap £31m
This broker floated in Dec 2018. Its shares have obviously plummeted in the last year, due to market conditions, as have similar sized Cenkos Securities (LON:CNKS) and WH Ireland (LON:WHI) - all 3 are too small to be separately listed, I think.
Last night, Sky News reported (why is it always them?!) that Finncap is in early stage merger talks with Panmure Gordon (another city broker, which used to be listed, but was taken private in 2017).
This morning Finncap announces that it is indeed in talks, and Panmures has made an indicative proposal to buy Finncap in cash or a partial shares alternative. We’re not told what the price would be, which is the most important piece of information. It will be interesting to see what the share price does today, which might give an indication of any premium.
Finncap made large profits (relative to mkt cap) in FY 3/2022 and the previous year, but obviously conditions are now horrid. Its balance sheet looks OK, so this is not a distressed sale, in my opinion, therefore FCAP could remain independent. There are 4 big shareholders (each with about 10%), including former CEO Sam Smith, and well-known Vin Murria. It could make sense to combine Panmure & Finncap, and remove duplicated costs.
Finncap have been very good for the private investor community, giving us access to, and research on the companies they look after. So I hope this doesn’t change if they’re absorbed within Panmures, which have been a bit patchy - sometimes giving us research on Research Tree, but having seemingly now withdrawn - there’s no research from them currently on RT - a poor show. So I very much hope Finncap remains independent. I’ve been to their offices numerous times to meet individual companies, and for group presentations, so I’m a keen supporter of Finncap.
The main attraction of shares in brokers, is that they generally pay out good divis in the bumper years. But it's very much a feast or famine sector.
Revolution Bars (LON:RBG)
10.75p
Market cap £25m
Delayed publication of preliminary results
Normally an RNS with that sort of title would set alarm bells ringing.
However this seems to be only a slight delay, due to management apparently being busy working on a big acquisition -
Revolution, a leading operator of 69 premium bars announces that it is in the final stages of negotiating an acquisition, which is expected to be a "substantial transaction" pursuant to AIM Rule 12. As a consequence of the proposed transaction the Group's preliminary results for the 12 months ended 2 July 2022 will be slightly delayed to allow appropriate audit finalisation procedures to take place once negotiations have been completed.
It confirms that results are in line with expectations, so no cause for concern here -
The Group's preliminary results are expected to be consistent with previous guidance, in particular that provided in the Group's announcement of 2 August 2022.
The AIM rules are here (Jan 2021, which I hope is the most recent version).
This is what rule 12 says -
Disclosure of corporate transactions
Substantial transactions
12. A substantial transaction is one which exceeds 10% in any of the class tests. It includes any transaction by a subsidiary of the AIM company but excludes any transactions of a revenue nature in the ordinary course of business and transactions to raise finance which do not involve a change in the fixed assets of the AIM company or its subsidiaries. An AIM company must issue notification without delay as soon as the terms of any substantial transaction are agreed, disclosing the information specified by Schedule Four.
What are the “class tests”? They’re contained in the same document, schedule 4.
These tests are -
- Gross assets
- Profits
- Turnover
- Consideration for the acquisition (as a % of market cap of RBG)
- Gross Capital
If any of those are over 10% (the acquisition target's figures compared with the acquirer's figures), then the acquisition constitutes a “substantial transaction”. So what? Well, schedule 4 just specifies what has to be disclosed, so it's not really that important, as follows -
Schedule Four In respect of transactions which require notifications pursuant to rules 12, 13, 14 and 15 an AIM company must notify the following information:
(a) particulars of the transaction, including the name of any other relevant parties;
(b) a description of the assets which are the subject of the transaction, or the business carried on by, or using, the assets;
(c) the profits (or if applicable, losses) attributable to those assets;
(d) the value of those assets if different from the consideration;
(e) the full consideration and how it is being satisfied;
(f) the effect on the AIM company;
(g) details of the service contracts of any proposed directors; (h) in the case of a disposal, the application of the sale proceeds;
(i) in the case of a disposal, if shares or other securities are to form part of the consideration received, a statement whether such securities are to be sold or retained; and
(j) any other information necessary to enable investors to evaluate the effect of the transaction upon the AIM company.
My opinion - it’s interesting to occasionally dig into the rules! In this instance, it's just a rule that lists what has to be disclosed about an acquisition, if it's over a certain size (with the bar set quite low).
In this case, the substantial transaction could actually be quite small, as for example it would trigger this disclosure requirement under rule 12 if the acquisition is £2.4m+ in consideration (10% of RBG’s current market cap).
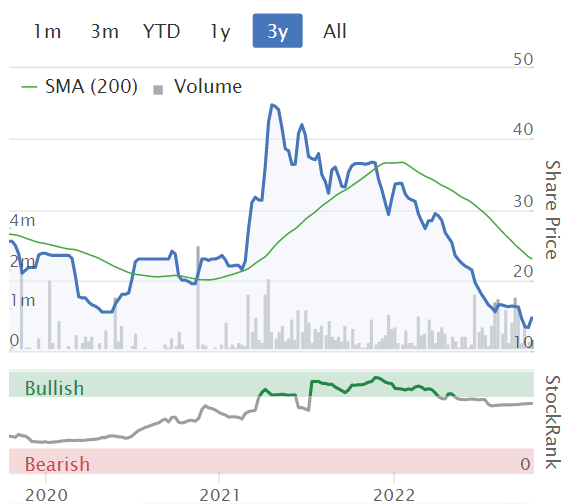
My main hope is that RBG doesn’t raise any more equity for this acquisition, because its own share price is so low, that further dilution would surely not be a good thing, at such a bombed out valuation.
The last trading update on 2 August 2022 was good, and forecasts have been raised several times this year. How come? I think they set the bar low, due to uncertainty, and an extensive refurbishment programme is giving sites a boost. Plus the CEO is a highly regarded, effective, hands-on operator, who I think is doing an excellent job.
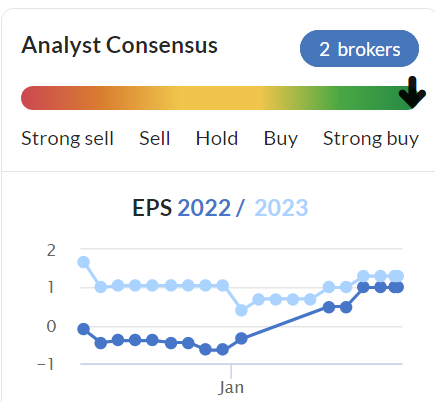
RBG is well-funded now (after 2 placings at 20p), and had net cash of £2.6m at 2 Aug 2022, and is self-funding its renovation programme of existing sites.
It’s in a good position to expand. Although obviously investors are not interested in operationally geared consumer stocks right now, hence share prices across the sector are bombed out. But that’s where we find the bargains for the next bull market. This could be one of those, I reckon.
I’m not currently holding, but there’s nothing to read into that, as I had a clear out of everything in my geared accounts, which was where most of my small cap positions were held. If only I could wind the clock back a year, and do things differently! But I can't so it's pointless even thinking about it.
I still like RBG shares a lot, as I think it could be a fairly easy doubler, once more stable conditions return (that's true of so many small caps right now). Also the insolvency risk looks very low, because it holds net cash, is cash generative, and restructured the site leases during the pandemic, removing all the problem properties. Plus of course these are ideal conditions for expanding chains, with remarkable ("once in a generation" according to the CEO of £XPF [I hold]) property deals available on new sites.
I’ll keep my eyes peeled for details on the acquisition & will report back in due course.
Bear in mind that the share count has risen from 50m, to 230m, massive dilution, from the 2 placings at 20p. Therefore the chart probably won't ever get back to previous highs of c.200p.
UPDATE: Propel (sector newsletter) says the acquisition is Peach Pubs, a gastropub chain with 22 sites. The deal is said to be £10-20m, which Propel reckons will be funded from existing resources (i.e. no dilution) cash & debt.
Sosandar (LON:SOS)
15.75p (up 10% at 11:02)
Market cap £35m
Sosandar, one of the fastest growing fashion brands in the UK, creating quality, trend-led products for women of all ages, is pleased to provide the following trading update covering the six-month period ended 30 September 2022.
Trading in line with FY23 market expectations. Revenue +72% yoy and the second six-month period of positive PBT
Note: The Board believes that consensus market expectations for the year ending 31 March 2023 are revenues of £42.8m, EBITDA of £2.2m and PBT of £2.0m.
I’m delighted to see SOS refer to PBT (profit before tax) as the profit number in this announcement. Previously they used EBITDA, which generally doesn’t seem popular with private investors (and certainly isn’t with me), because it often gives an inflated version of profitability.
Key points -
H1 revenue £20.9m (up 72% vs H1 LY) - that’s a terrific performance, given that it’s all organic growth, and occurring at a time when many eCommerce businesses are struggling to even match, let alone thrash their prior year numbers.
Profitability - slightly above breakeven, with PBT of £0.1m in H1, much improved from a loss of £(1.1m) in the prior year comparative period. H2 tends to be seasonally stronger.
Repeat orders - is the stand out KPI - with almost 77% of orders (266k/347k) being repeat customers. That’s highly significant I think, and shows that SOS is building a loyal, repeat customer base. Whereas many eCommerce businesses have to spend a fortune on digital marketing, and only attract one-off sales. This is a key point of difference for SOS, which gives me a lot of confidence in the brand & the future prospects.
Gross margin is down a bit, but still good at 54.4% (H1 LY: 56.5%)
Net cash down from £7.0m a year earlier, to £4.2m. Credible reasons provided, it’s due to larger, and earlier stock intake for the peak season. Also increased use of cheaper sea freight (as opposed to air), which increases lead times & hence inventories. This is all fine I think.
Current trading -
Early autumn trading has been very positive with particular success in key growth areas of outerwear, knitwear and partywear.
Maybe people are buying more jumpers, to keep warm this winter, with the thermostat set lower to save fuel?
…The period saw the Company navigating numerous macro challenges and successfully mitigating the headwinds faced so far. The current economic backdrop continues to be challenging; however, October trading has started well both on the Company's own site and with its third-party partners. There remains a high degree of external economic uncertainty, but the Company is confident that it can continue to navigate the challenging and volatile conditions and take mitigating actions as appropriate to protect margins and profitability.
In the current environment the Company expects consumers to become more selective about where they spend and also more demanding of those brands with which they spend. However, Sosandar is confident that the Company will continue to benefit from its unique product offering and brand proposition that clearly differentiates it from the rest of the sector. As such, the Company is confident of continuing to make market share gains…
Selling Sosandar products through JD Williams will further increase the brand's reach and deliver profitable growth. The partnership has got off to a promising start and together with M&S, Next, John Lewis and the Very Group, there are significant opportunities for further growth.
My opinion - the most important information is the note right at the end, saying it’s on track to make £2.0m PBT this year.
That means, the business now seems home, and dry - it’s now profitable, and growing tremendously fast, organically.
There’s obvious risk that growth could slow, and fashion risk (although that’s mitigated by test & repeat model). Also concentrated key person risk here is high, with the joint CEOs very much being the business. If they lose the plot, or something bad happens, then the main driver of the business would be lost.
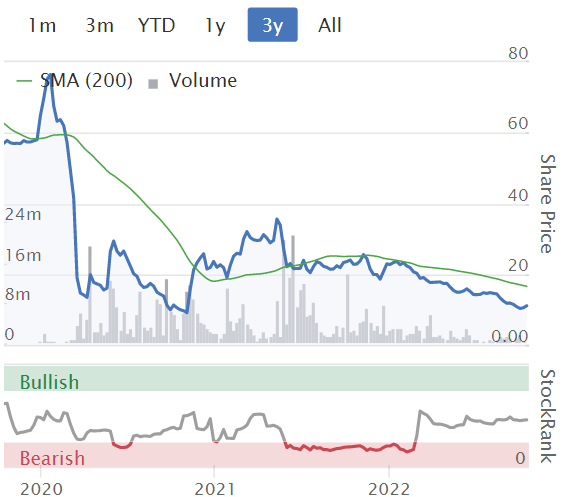
In terms of risk:reward, it seems to me that SOS shares have never looked better. The business model is working, a decent level of (full year) profitability is on the way, it shouldn’t need any more cash, and yet the valuation is a modest £35m.
I think patient holders here could do very well, long-term. It’s very rare to find an emerging new brand, that’s really going places, but I think it’s becoming increasingly clear that’s what is happening here.
Overall, a thumbs up from me. In a bear market, and consumer downturn, I can understand why the share price is where it is. But good businesses thrive in recessions, and competitors fall by the wayside. So longer term, I think this share could end up maybe 2-3 times the current level.
There’s good downside protection too, because SOS outsources logistics, and has little in the way of fixed costs. So even in a nasty recession, it could easily scale back marketing spend, and run for cash. Physical retailers don’t have that luxury, so as we’ve seen, they can bite the dust during a downturn.
I'm surprised the StockRank is still so low, that has some catching up to do perhaps?
Graham’s Section:
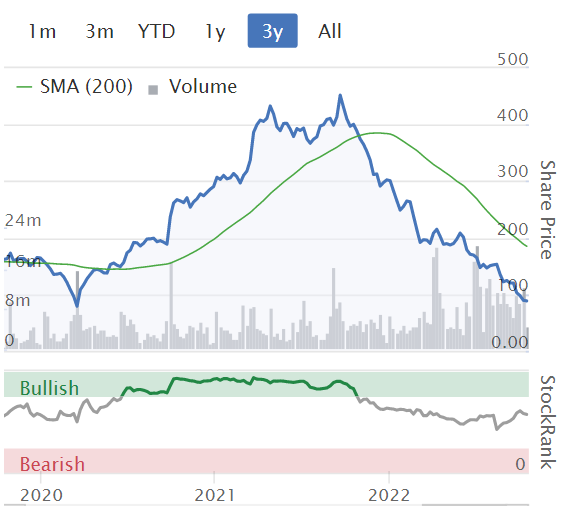
888 Holdings (LON:888)
Share price: 85.46p (-5%)
Market cap: £381m
(At the time of writing, Graham has a long position in 888.)
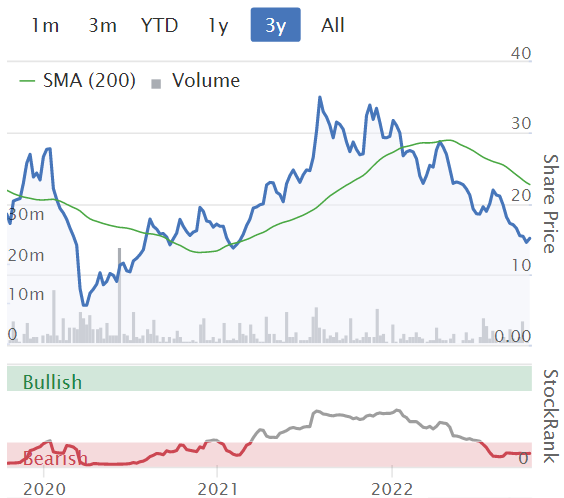
This is now a little bit of an embarrassment for me: I’ve been holding it all the way down from the peak at 452p. A smarter person would have sold out at some point, but I’ve taken a deliberately “hands-off” approach to my portfolio, only selling shares out of necessity and doing my best to let all other positions run for as long as possible.
Also, this has been my smallest position for some time - currently just 3% of my highly concentrated portfolio. I accept that my strategy of holding onto shares on an effectively permanent basis will see some casualties in the portfolio, from time to time.
Let’s see what this Q3 trading update has in store for us.
888 is “one of the world's leading betting and gaming companies with internationally renowned brands including 888, William Hill, Mr Green and SI Sportsbook”. It has been described as “one of the internet’s oldest casinos”.
Today’s numbers are presented as if William Hill had been owned in all periods, and as if 888 Bingo was never owned (William Hill was purchased, 888 Bingo was sold).

Key points: total revenues are down 7%, and the William Hill UK Online segment is responsible for most of the fall. The core 888 brand did not do well, either.
Let’s break down the key talking points:
Players safety measures - this is one of the main reasons for the online revenue decline. The measures, which had the effect of reducing average spend per player, were introduced in Q3 and Q4 of 2021.
Netherlands - another reason is the closure of the Netherlands market, which was previously worth about 4% of revenue at the 888 segment (and 6% at the William Hill International segment).
This is only a temporary issue: the Netherlands used to be a market where companies would operate without a licence. It is now moving to a licensed regime, but one of the conditions of this is the operators must stop trading until they get their licence!
888 should hopefully be back up and running in the Netherlands again soon (perhaps before the end of the year), and that portion of revenue should return.
Retail revenue - this was flat despite “c.£4m impact from three days of temporary closures together with sporting fixture cancellations / postponements during the period of national mourning”.
Sports - Euro 2020 took place in 2021, so it’s a tough comparison in 2022 with no major tournament yet. Of course we do have the World Cup coming up!
Ok, so there are a lot of excuses for the revenue decline. It’s up to you if you think they are reasonable excuses or not, and if future periods will be better.
I think that future periods will be better: the Netherlands will come back, there will be fewer days closed, and of course the World Cup and the Euros come around every two years. Although of course there is always scope for more rules and regulations which could further hamstring revenue and profitability.
William Hill - the elephant in the room is this acquisition (details published in April here).
This was a £2 billion deal, causing 19% dilution and very high leverage. Everybody, not least 888’s management, knew that the major task after the deal would be to pay down the debt and get the balance sheet back onto a solid footing.
Deleveraging will be much easier if the c. £100m in potential synergies are realised:
The Group has made strong early progress with realising synergies, creating a more efficient operating cost base during the Period and helping to deliver an improved Adjusted EBITDA margin in Q3 2022 versus H1 2022, with further improvement expected in Q4, with the primary focus of the business on integration, execution and deleverage
Debt load - this is not a situation where you can have great confidence that the equity is going to be worth something, after all the debt is taken into account.
Today’s update informs us that cash interest costs are expected (based on the forward curve of interest rates) to be around £170m for the full year 2023.
- Gross debt is £1.81 billion (high interest rates are being charged on this).
- Cash is £186m.
- Undrawn facilities are £150m (so total headroom is £336m).
There aren’t any significant maturities until 2027, so at least 888 has time to study the bond market and make its plans for future refinancing deals.
The operating profit forecast for the current year is around £190m, rising to £260m next year.
Depending on capex and cash conversion, that does provide some scope for debt reduction, based on current interest rate projections. 888 might want to take out some more rate hedges, to fix a greater percentage of its interest costs.
Outlook
Despite the changing macroeconomic environment and ongoing pressure on UK revenues from long-term focused enhanced safer gambling measures, the Board expects revenues in Q4 2022 to grow over Q3 2022 and be similar to Q4 2021 levels
The Group has taken actions to accelerate synergies and drive a more efficient operating cost base, and expects an improved Adjusted EBITDA margin in H2 2022 to meet the current market expectations for full year 2022 Adjusted EBITDA
My view
I have a relaxed attitude to this one. If it doesn’t work out, I plan to take the 3% hit to my portfolio.
Am I already resigned to it not working out? Not completely.
If the company aggressively pays down as much debt as it can over the next year or two, that will set it up for a slightly easier debt reduction profile over the medium-term.
For what it’s worth - I know that ratings agencies are often treated with scepticism - 888 has a credit rating of B1 from Moody’s (positive outlook) and BB- from Fitch (negative outlook).
This means that the agencies believe 888 is somewhere between “high credit risk” and “likely to fulfil obligations - ongoing uncertainty”.

Of course, one way that obligations can be fulfilled is by diluting shareholders: debt holders can be saved, but at the cost of wrecking the value of the existing equity.
This stock is not for the faint-hearted, that’s for sure. But if the debt is successfully managed and shareholders avoid dilution, then we will end up owning a huge, diversified global gambling company, with major online assets and a familiar retail presence. There is potentially a big reward, if it works out.
Cognisant of the risks, I’ll continue taking a chance on this one.
Saietta (LON:SED)
Share price: 100p (+5%)
Market cap: £103m
We’ve never looked at this one before, so let’s briefly describe what this is. Saietta is a “multi-national business which designs, engineers and manufactures complete Light-duty and Heavy-duty e-drive systems for electric vehicles on land from scooters to buses… as well as marine applications.”
It listed on AIM in July 2021 at an IPO price of 120p. As it has fallen by only 20p since then, that makes it a top-performing 2021 IPO!

The company is undergoing rapid growth: it had 28 employees when listed, and now has 200, and has joint ventures in both the US and in India. According to today’s trading update, it is experiencing “very significant positive momentum” with its current strategy.
Saietta has patents over two types of motor design and these underpin its hopes for a new partnership with a major light vehicle manufacturer in India, to hopefully commence at some point in 2023.
The company has cash of £23m and a recently acquired factory in Sunderland; if it’s going to achieve its ambitious goals, it needs to be very careful about how it uses this cash. Accordingly, its strategy includes joint ventures, outsourcing and government grants.
Outlook
There are some exciting points in the outlook statement:
As a reaction to the unexpectedly positive response from substantial customers with more significant longer term contract potential, the Board has decided to divert resource away from pursuing near term lower volume standalone motor sales in order to secure far larger contracts for higher value product systems…
In summary the strategic vision of Saietta has continued to expand significantly which has created the opportunity to increase shareholder value by concentrating on working with some of the world's largest OEM's and achieve 1st mover advantage in multiple sectors and regions.
FY March 2023 revenues are likely to be lower than previously forecast, though the company says they will still be at least 250% of the result in the prior year.
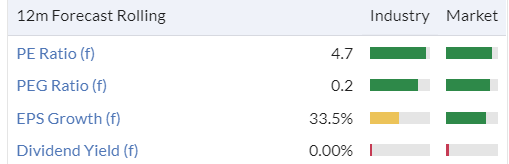
This looks like a huge cut in the revenue forecast: 250% of the result in the prior year (£3.6m) is only £9m, while the existing revenue forecast according to Stockopedia is £22m!
The plan is for “a projected step change into high volume production in several markets during the following financial year”.
My view
I’ve not been studying this for long enough to have a firm view, but the huge cut in the revenue forecast has thrown me. The previous consensus forecasts suggested £22m of revenue would be forthcoming in FY 2023, followed by £67m of revenue in FY 2024.
The company has slashed next years’s forecast but done so while saying that the company is actually more ambitious and has even bigger goals than it did before.
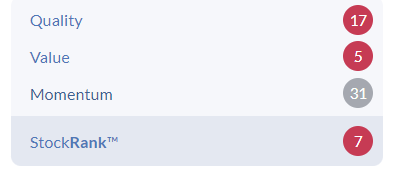
Stockopedia classifies this as a Sucker Stock. Maybe it will be another AIM stock that eventually ends up in the trash heap, but I thought it was worth mentioning. We’ll have something in the archives to refer back to, if this company does eventually come up with the goods!
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

52 comments
Thanks Paul. Here's the Sosandar (LON:SOS) H1 23 trading update call from this morning, a great Q&A: video & podcast.
"A smarter person would have sold out at some point, but I’ve taken a deliberately “hands-off” approach to my portfolio, only selling shares out of necessity and doing my best to let all other positions run for as long as possible".
Not dumb but an investor as opposed to trader. Did that for THG (LON:THG) Boohoo (LON:BOO) Ferrexpo (LON:FXPO) Volex (LON:VLX) - oh well one day my prince will come.
Two strategies, but can do both - need some trading to get in some wins and keep the confidence (hope) going.
Tried spread betting - good god - how can things be so unpredictable - know Mr Market watches the RNS's and take out the shorts but not on the daily moving average supports. This has no pattern at all just a lottery.
The Bears are not hibernating yet methinks.
£SDG Thanks Paul for the detailed CEO interview with Lisa M; she clearly understands the business , finance & marketing. I was out a while ago but it is back on the watch list.
As others , i do appreciate your personal , polite & in depth manner in these interviews; which leads to a far better understanding of Company dierctors.
Thanks Funderstruck!
My pet hate is interviewers who are always rushing, and interrupting. So in mine, I try to put the interviewee at ease, then let them talk on each point without interruption, and with no specific deadline (although 40 mins is usually enough!). I think it works quite well, and everyone I've interviewed so far seemed to enjoy it & got a lot of useful information across. Plus I think we pick up on what they're like as a person, and just the little asides can sometimes be quite revealing - e.g. Lisa Montague at Sanderson Design (LON:SDG) is clearly ambitious for the company, and a bit frustrated that the pandemic has slowed them down a bit. I've got a good feeling about her and the business, so think this could be a good long-term investment. I must buy some, when I have some spare cash.
Regards, Paul.
Hargreaves Landsdown. I am in need of another internet broker which is reliable and easy to work with. I am not looking for advice or recommendations. Low cost is not important but service is. I already have accounts with Youinvest and HL. Suggestions much appreciated.
Lennart
Never had a problem with AJ Bell...but guess that's Youinvest.
ii works for me.
IWeb for a simple service (owned by Halifax but lower fees than their own brand for exactly the same product that I can tell)
If you want service (but not advice), then Charles Stanley Telephone Execution Only. Possibly not the same as CS Direct. Having been a CS advised customer for years, who wound up deciding we didn't need advice any more, we are probably rare beasts with this, but it enables us to call real people, who know me as I am relatively active. They are an in-house dealing desk and admin service and can deal in a wide variety of stocks, work orders etc, but you can email anytime as, as I do from other countries. I'm not sure if there's a minimum amount for this, but message me somehow if you want a direct contact.
Lennart - you may not see this, it's late in the day so I may have to re-post tomorrow. I am with Hargreaves for my SIPP which is almost all cash at the moment - I know £HL is receiving much negative press and I am just wondering whether your motive for seeking ideas about alternative brokers is founded on fear of big problems to come or something else.
I use IG for one of my share dealing accounts, and found it decent. No advice at all, pretty no-frills interface. Live share data (at least for the UK) and possibly able to get DMA (free) and L2 (paid). Cheap execution fees. App works 100% without issues, but again is really no-frills.
They are also now big enough that I don't worry about them going under in an economic crisis and my funds and shares being frozen. (maybe famous last words!)
After today's ‘positive’ update on £SED , I've turned negative on this share. I think the products have huge potential, but they’re burning through their cash. They just raised £23 million in August after raising £35.2 million in July last year. Today’s update states it burnt through £35m since last summer and now revenue will be £12m below forecast and that will be more heavily weighted to the second half, ie H1 revenues haven’t met the expectations set out in the fund raise 3 months ago and cash burn was higher too. The wording of today's update did not impress either. It was sugar-coated with wording like “unexpectedly positive response from substantial customers”, whereas reality is that to reach profitability my calculations would be they need to raise at least £30 million or a third of the company’s market cap within the next 6 to 8 months! It reminds me of another ‘great little company’, Trackwise, which had so much potential but just believed nothing could derail its success and failed to have sufficient finance lined up when success was ‘delayed’.
Thanks for sharing your views on SED, qimotte. I can see myself turning outright bearish on this one in due course.... sounds a bit shaky alright. G
Does anyone else on here follow Avacta? I know Paul doesn't and I know a growth share in an environment where money is being taken out of the system isn't always a good idea. But...I really like this co and have followed it for a long time. I hold. Today they have announced they are taking over Launch Diagnostics, which distributes Diagnostic kits, makes sense but costs £24m in cash plus future performance payments. Now they probably needed to raise money in 2023 anyway so they have announced a convertible issue (25% over offer with 6.5% coupon) and small placing. So possible dilution down the road. So I see the business sense in what they are doing. I see they way they are funding it. It all looks good to me. If anyone else out there follows this company I would be interested to hear what you think. (I think I am suffering from bear market jitters).
Does this help?
https://www.trinitydelta.org/r...
The raise is a death spiral. £10m+ of shares could be issued at a discount to market price each year to pay interest and principle on the convertible. In other words, the state of the business may not be totally correlated with the outcome for the shares.
The raise is a potential issue. £10m+ of shares could be issued at a discount to market price each year to pay interest and principle on the convertible. In other words, the state of the business may not be totally correlated with the outcome for the shares. The next few years are not ideal for loss making blue sky companies.
Thankyou.
Thanks for the write-up on Sosandar (LON:SOS) Paul. The stockopedia computers suggest expectations are for £3.65m net profit which doesn't tally with Sosandar (LON:SOS) statement today. Does anyone know if a broker is expecting some kind of tax credit maybe, or is the data incorrect?
Thank you Paul
That's a fascinating interview with Lisa Montague. Good to hear her being so open about the challanges faced by £SDG since she joined the company, and the opportunities and challenges ahead. I look forward to your next interview with LM :-)
Shanta Gold (LON:SHG) spiking on news of a possible bidding war for the company (I hold). Tbh I’d rather it wasn’t sold as the long term outlook was excellent, oh well…. Same happened earlier this year with Contourglobal (LON:GLO)
I almost added to Shanta Gold (LON:SHG) early this morning as I was aware it is going ex-dividend next Thursday but my wife had gone shopping taking her mobile phone leaving me unable to complete the bank's security check. C'est la vie, I will look at again next week when the price may have cooled. We hold Shanta Gold (LON:SHG) in our 4 accounts and they are all underwater of course.
Hi Paul, can I ask whether you still use spreadbetting? I still have an account but have obviously found it very tough in these conditions.
Thanks
Andrew
Hi Andrew,
No, I've wound down my spread bet accounts, as it's just not suitable for this kind of market. Also, it stresses me out, having to constantly check the account, and deal with margin calls, etc. I need to live a quieter life, more in the slow lane in future, as I'm not getting any younger.
Regards, Paul.
Saga (LON:SAGA) Director share purchases
Today: Gemma Godfrey Non-Executive Director purchase 12,438 shares
5 Oct: Sir Peter Bazalgette Non-Executive Director purchase 212,249 shares
Anand Aithal Non-Executive Director purchase 24,500 shares
Propel are reporting that Revolution Bars (LON:RBG) are acquiring Peach Pubs. They are widely respected operators.
The purchase price is very vague but I assume will be detailed in due course as it's a substantial transaction.
So the animal spirits are still very much alive in this sector.
FWIW I think Revolution Bars (LON:RBG) were undervalued and have potential. I see this as a positive, but the purchase price needs to be at the lower end of the range indicated. This may tempt me in.
Revolution Bars Group set to acquire Peach Pub Company: Revolution Bars Group, which operates the Revolution and Revolución de Cuba brands, is set to acquire Peach Pubs, the 22-strong gastropub operator, in a deal valued at between £10m and £20m, Propel understands. The company announced this morning that it was in the final stages of “an acquisition, which is expected to be a ‘substantial transaction’ pursuant to AIM Rule 12”. It is thought the rationale behind the deal will see the 69-strong Revolution tap into more daytime, less late-night trade, and more early week business balancing its estate. Peach will also provide a more affluent guest base. It will also provide the Rob Pitcher-led Revolution with a further platform for growth. It is thought the deal will be funded from immediately available cash and banking facilities. Propel understands a deal for Peach, which was founded in 2002 by Hamish Stoddart, Lee Cash and Jo Eames, could take place as early as later today (Tuesday, 18 October), or this week. Earlier this year, Propel revealed Peach had appointed advisors as it undertook a strategic review of its business. The company has been working with FinnCap Cavendish on the review. It came off the back of strong trading by the group. Co-founder Stoddart told Propel earlier this year: “2021 we were solidly more than 20% like-for-like. The team was amazingly flexible and enthusiastic, and we got most things right, which continued even with covid pressure. In the last five weeks we have traded at 16% versus 2019, that’s 13% ahead of the Coffer Peach Tracker. We are in a position of strength, with no net debt and a fund of cash ready for acquisitions, and we are acquiring single sites already. We are privately owned, which means we have choices on what to do and when. We do review our strategy regularly, and we have chosen to do it with FinnCap Cavendish this time. Our pub Ebitda is more than £6m now, and the business is positioned to grow. We may well choose to accelerate growth, which may require funding.” The company previously explored the market in 2018 and received interest from The Restaurant Group, Punch and Brasserie Bar Co, with the former understood to be in exclusive talks on a deal, before its attention turned to acquiring Wagamama.
Hi, from the Propel newsletter this morning:
Revolution Bars Group set to acquire Peach Pub Company:Revolution Bars Group, which operates the Revolution and Revolución de Cuba brands, is set to acquire Peach Pubs, the 22-strong gastropub operator, in a deal valued at between £10m and £20m, Propel understands. The company announced this morning that it was in the final stages of “an acquisition, which is expected to be a ‘substantial transaction’ pursuant to AIM Rule 12”. It is thought the rationale behind the deal will see the 69-strong Revolution tap into more daytime, less late-night trade, and more early week business balancing its estate. Peach will also provide a more affluent guest base. It will also provide the Rob Pitcher-led Revolution with a further platform for growth. It is thought the deal will be funded from immediately available cash and banking facilities.
For anyone interested in Sigmaroc (LON:SRC) their Q3 TA is this Thursday and I can see they have helpfully announced a presentation specifically for "its valued private shareholders" at 7pm - PI's can contact ir@sigmaroc.com (note the announcement mis-spells!) to ask to attend. A few days ago that announced that this talk was taking place at the Isokon (London) and limited to 25 PI attendees but is this now going to be streamed and available to watch online I wonder, it doesn't say, and I have asked.
Jack previous;y concluded that "The situation must be monitored, but all in all, SigmaRoc continues to come across as a competent and ambitious operator that can continue to consolidate in the sector". I hold, comments and thoughts appreciated!
Hi Mark
I emailed Sigmaroc (LON:SRC) and received confirmation of my attendance at the Isokon Gallery on 20th September, the day the retail investor presentation was announced. The announcement by Sigmaroc (LON:SRC) this week, seems to suggest that the retail investor presentation may have moved on-line, although of course it may be live streamed from the physical event at the Isokon Gallery.
I have emailed Sigmaroc (LON:SRC) seeking clarification and will post the reply, once received.
Best wishes
I neglected to add that the tone of the trading update notification appeared positive and the share has remained relatively stable at around the 40p during the recent market turmoil, albeit it has fallen by more than 50% since the start of the year.
I have watched several presentations by Max Vermorken CEO, including at the physical Mello in May and think that he comes across very well. David Barrett, the Chairman is very experienced in the aggregates arena and hold 3 million shares or thereabouts. Also the company seems innovative, the development of low carbon concrete products being especially noteworthy as is the recently announced joint venture with ArcelorMittal.
It would be naive to think that £SRC has been unaffected by the current economic turmoil, especially in Europe, but provided it can maintain financial discipline, I am of the opinion that it will come through it successfully.
I added to my holding at 40p, foolish or otherwise time will tell.
Mark,
I received a prompt and very helpful reply from Sigmaroc (LON:SRC) that I have pasted below. i sought clarification regarding the time of the Isokon presentation as the reply mentions the afternoon. A further email from Sigmaroc (LON:SRC) confirmed the presentation at the Isokon will take place at 7pm. The webinar presentation mentioned in the more recent announcement is at 11am on Thursday.
I admit to being impressed by the helpfulness and speed of response. A plus for the company. Here's hoping that the update is positive.
Best wishes
"Hi John,
The event will still take place physically!
We will be releasing our Q3 Trading Update in the morning through the usual webinar format and then hold a physical event at the Isokon in the afternoon
I assume the management will be commenting on the trading update in the afternoon as well but if you’d like to join the morning webinar let me know, I can send you a registration link.
Hope this helps,"
Florian Werner
Marketing & Communications
SigmaRoc PLC
I agree with the positive comments around SRC management capability. For me the CEO Max comes across very well. I also think they have managed to successfully navigate energy cost challenges so far (concrete is very energy intensive) and don't seem to be suffering from a softening in demand.
That said there is quite a lot going on with the Group and I was disappointed only £19.3m operating cash flow was generated from a headline EBITDA of £47.6m. Very little was left after £15m of Capex. £18m of difference was due to seasonal working capital but I was disappointed a reconciliation of operating profit to operating cash flow was not provided (although I did request one from the IR team).
Needless to say I'll be hoping for some better news on the Group's cash flow at the trading update.
Starting to see some earnings announcements changing the mood a bit in the markets, yes times are tough but not every company is facing bankruptcy and actually some are doing pretty well.
Had some good results from £CNIC yesterday and some very solid results from £BPM this morning thats still trading at a 40% discount to NAV.
Good to see a decent response to Looker's TS this morning, PBT to be no less than £75 million, hopefully there's a read across to Vertu (we hold) as imo both companies are undervalued. If any other Stockopedia members hold Mercia Asset Management or Capita as we do, I'd be interested in their thoughts on their respective statements today.
SOS look good. Investor presentation at 9am this morning. Register here. https://bit.ly/SOS_H122TU Cash down but they address this, increasing inventory to meet growing demand and meet Autumn/Winter demand which is what you would expect from a growing business. 72% increase in net revenue and second 6 month period of positive PBT. Looks like the business is coming together well. In my view the share price should move up a bit today to reflect progress but recent experience suggests no hunger for the sector so some will look to sell into strength.
£TAM - "exceptionally strong half-year of net inflows" - link to full new research note from Equity Development: https://www.equitydevelopment.co.uk/research/exceptionally-strong-half-year-of-net-inflows
Even in more ‘normal’ economic times, Tatton’s net inflows over H1-23 (to 30 Sep 22) would have been impressive. But given the weak economic and market environments, it is an exceptional performance. Net inflows totalled £907m (annualised rate of 16% of opening AUM), averaging £150m per month. This is a sharp increase (+39%) over H1-22 which saw £652m of net inflows (annualised rate of 14.5% of opening AUM), averaging £100m per month.
Falls in financial markets, however, offset most of these AUM gains. The MSCI PIMFA Private Investor Balanced Index fell 9.6% over the period with market movements and investment performance being responsible for a £905m reduction in Tatton’s AUM (-8.0% of opening AUM). AUM closed the half-year marginally up at £11.343bn (31 Mar 22: £11.341bn).
While net inflows are ahead of our forecasts by some margin (previous estimate £1.3bn for the full FY23), market falls lead us to reduce our end-FY23 AUM forecast from £13.0bn to £12.2bn (Tatton has also flagged that H1 inflows were boosted by several ‘wins’ with H2 net inflows likely to be lower than H1). This, coupled with the jump in UK Gilt yields (the risk-free rate in our DCF valuation), reduces our fundamental value from 540p to 460p, still 30% above the current share price.
We also highlight that while only a limited data set is available, it seems that Tatton’s H1 performance of net inflows exceeding negative investment performance (i.e., a net increase in AUM) appears to be a standout performance among London-listed asset and wealth management peers (see page 2). We will revisit this comparison when interim results are released in November.
£UPGS today announced an important step forward in its licensing agreement for the Russell Hobbs brand as it moved from its previous fixed term arrangement to a rolling four-year basis. (Link to research report: https://www.equitydevelopment....) The move stands to increase certainty around the brand and justify increased investment behind it. Since mid-2021 all other brands in the portfolio have been wholly owned, which augurs well for both predictability and valuation. We reiterate our 250p per share fair value.
The change from fixed term licence arrangements to a rolling four-year basis for Russell Hobbs stands to raise UPGS’s certainty around the brand. The licence with the ultimate brand owner, US listed company Spectrum Brands (NYSE: SPB), will always have a minimum of four years to run, enabling UPGS to invest with greater certainty. The new agreement refers to the UK, Europe, Australia and New Zealand for non-electrical kitchen and laundry products.
We base our 250p fair value assumption on what we feel are deserved ratings of an FY2023 EV/sales ratio of 1.5x and 12x EV/EBITDA, which implies considerable potential upside. Further reassurance comes from the shares being on a miserly PER whilst offering a prospective 7.4% yield.
UP Global Sourcing Holdings (LON:UPGS) is a great business. For last 30 months its underlying powerful growth engine has ensured that the top line has not been ensnared by the many serious headwinds...the question remains whether it can sail through the current headwind or whether it's a more powerful retardant. I dunno. Will be great business that comes out the other side strong regardless. My guess is that the current trading period is going to revolve around how German/European penetration going. UK probably sticky...what they gain somewhere they likely lose on some slow or de-stocking elsewhere.
Forecast very hard. Outcomes in quite a wide band. My view is on target to moderate surprise. PIs likely to continue to fear the cycle through it. Prominent opinion maker Leo Investor trashed it on his way out (scorched earth style). His negative was that west will cut off from all things chinese. I think this is unlikely as a form for economic MAD. No doubt the slow divorce is real tho. However, despite the trauma of zero covid (and prior to that energy) and the alarming headlines it produces the evidence is that China does everything to support export markets as its needs the coin as support for its troubled internal domestic market.
Not sure what the short term trajectory here. If we're lucky the price gets hit more and a real gift is provided. Everything by management to date has been superb execution.
UP Global Sourcing Holdings (LON:UPGS) - PIs likely to continue to fear the cycle through it
Guilty as charged. I stepped off this bus when it became clear to me that its two main markets are amongst those most exposed to a consumer slowdown, notwithstanding management’s strong execution. But I will jump back on when I feel the coast is clear (or calamity priced in). Good company.
That's how sentiment cycles go...regardless of actual cycles!
I've owned for years and prior lows. I sold some near the top. I bought some more on the way down here (approx 120-150 area). I haven't bought more. That's me simply watching the sentiment roll on and not fighting more. However, I want to own despite short term as I see the upside long term growth as strong and all that has happened in the last few years show how strong that underlying growth engine is. But the nature of the business is that there can always be a weak half due to temporary shifts in buying and therefore a stock to avoid buying high for that reason. The current price is v low relative to proof/potential...and if I'm lucky I may get a lower price to buy more. Medium term I expect mgt to find a way to surprise expectations meaningfully. Tough gig tho as AIM can be slow to recognise achievement and fast to reward hype ;)
Good news regarding SA miners and transnet strike
https://www.reuters.com/world/...
Is retail starting to bottom out?
Several retail / hospitality announcements this morning:
BooHoo (LON:BOO) JP Morgan takes 5.18%
Revolution Bars (LON:RBG) announces a forthcoming acquisition.
Frasers (LON:FRAS) buys remaining shares in MySale (LON:MYSL)
Sosander (LON:SOS) decent update.
I do not own any retail or consumer discretionary.
Things seem quite positive and certainly some interesting prices around, but I cannot get away from the "normal" recession thinking that we haven't really hit hard times yet, with reduced spending impacting Co's profits and leading to a raft of profit warnings and cost cutting.
But........maybe that is what a light recession is - no major long-term deep cuts/pain. Who knows, but I am still looking to stand on the side-lines, but recognise the risks around this that I might be kicking myself in 6 months time. Currently I am still thinking next year (Q2/3) will be a better opportunity. My watch-list grows by the day.
With huge macro headwinds for Clothing and Bars (see Barclaycard's Sep spending data, and their consumer survey) - you really need to be able to pick the winners, as majority will either struggle (mild profit warning) or do very badly (go to zero).
And it is not only Barclaycard data showing this, but also the retail standard GfK monthly data.
never pointless - it's an essential accompaniment to my morning coffee. Thank you
Good morning Paul, Graham,
Sosandar (LON:SOS) have released a trading update this morning. Seems quite positive on first reading. PBT improved significantly, compared to H1 2021.
Amy chance of reviewing the figures?
Morning mcav82,
Yes we always cover Sosandar (LON:SOS) :-) I'm getting started on it now, so should be up by 11am.
Best wishes, Paul.
P.S. Tip - if the £+ticker thing doesn't work, then just edit the comment (can be done in the first hour) and put a carriage return immediately after the ticker. It then works. Then go back in, and edit it again to remove the carriage return. (if you can be bothered!!)
I am very pleasantly surprised by Sosandar (LON:SOS) update today. I was expecting a profit warning, given that they've been running "20% off everything" for many, many weeks now.
I used to be a holder and its still on my watchlist, will re-evaluate soon as on first glance the update sounds good.
Revolution Bars (LON:RBG) delayed results!!! Normally bad news I assume, however due to large acquisition, so maybe good news, holds onto hat to see which was this one goes.
they have re-affirmed trading as per last update - "in line" so no surprises to the downside I hope.
Word is Peach Pubs, 22 gastro operator, for £10-20m. Sounds OK