Small Cap Value Report (Tue 19 Mar 2024) - CRST, DFS, STEM, MAB1, EYE, ZTF

Good morning, it's Paul & Graham here!
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. OR it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom),
Paul's 2023 share ideas, with live prices.
New SCVR summary spreadsheet from July 2023 to date, updated at weekends (very useful quick reference tool, search for ticker using CTRL+F). Hover over cell for pop-up notes.
Frozen SCVR summary spreadsheet for calendar 2023.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
I'm trying to avoid going into meltdown when looking at how large the list of companies reporting is today! As usual we can only do some of these, not all. We prioritise (1) ahead or behind expectations updates, (2) big price movers, (3) "most viewed" list on the home page, (4) companies we like and think are good value.
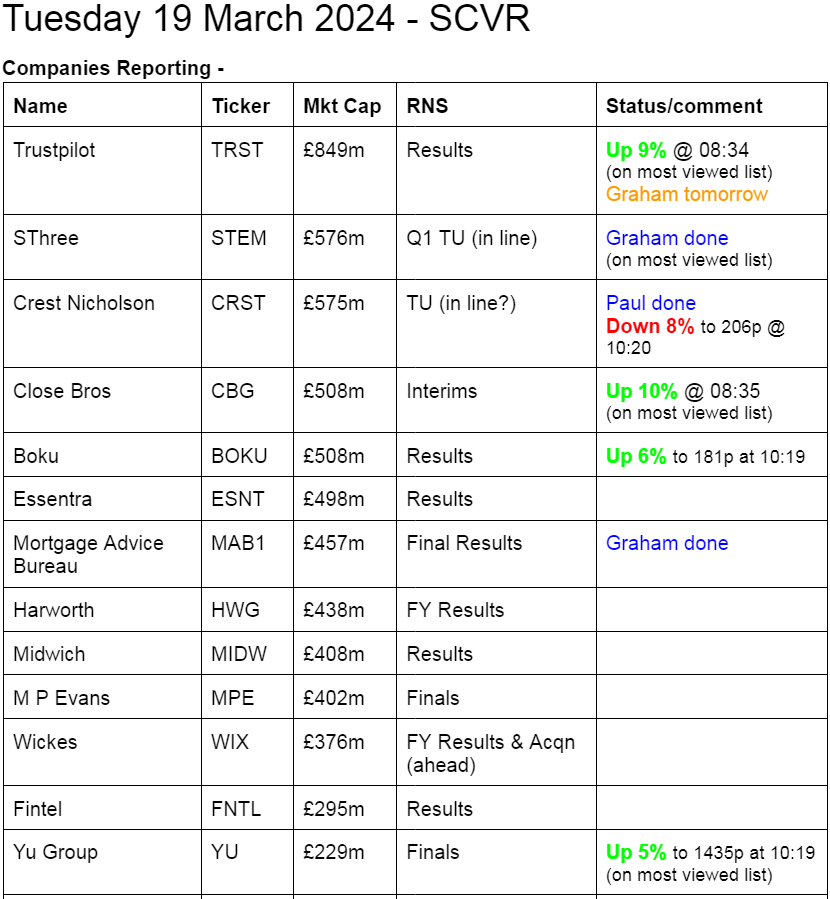
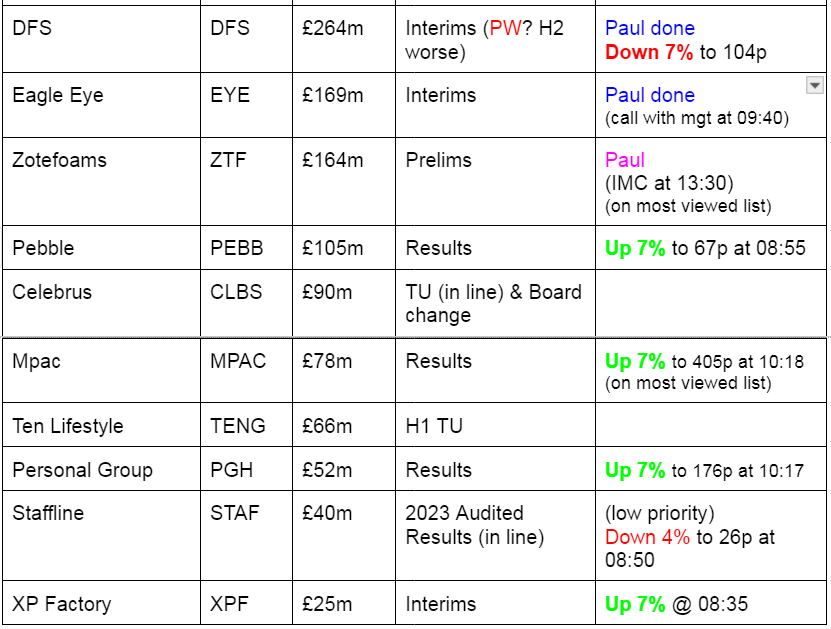
Summaries of main sections
Crest Nicholson Holdings (LON:CRST) - 224p (pre market) £576m - Trading Update - Paul - AMBER/GREEN
Lack of clarity on overall trading in this AGM update, but it sounds as if they're in line. However, more legacy problems have emerged, with another £15m estimated liability for remediation. Worryingly, external consultants appointed to review existing provisions - what's the betting another hefty provision will be required? High, I reckon! So I'm moderating from green to AMBER/GREEN. It's still a big discount to NTAV, and might attract a bidder, but these legacy issues are troubling.
DFS Furniture (LON:DFS) - down 7% to 104.8p (£246m) - Interim Results [with profit warning] - Paul - BLACK (on fundamentals: AMBER/RED)
Soft H1 results, with little profit. Also it warns that FY 6/2024 adj PBT guidance reduced by £10m to £20-25m due to soft order intake in Jan & Feb. Red Sea delays could have a minor impact too. Awful over-geared balance sheet is the main problem - hence me having to be AMBER/RED, even though I quite like the business and its recovery potential once consumers relax the purse strings later this year maybe?
SThree (LON:STEM) - down 1% to 419.5p (£566m) - Q1 Trading Update - Green - GREEN
Full-year expectations for this STEM-focused recruiter are unchanged. Their cash balance remains enormous allowing them to easily ride out continued softness in Technology and Life Sciences and their strategic shift away from Permanent recruitment.
Mortgage Advice Bureau (Holdings) (LON:MAB1) - down 3% to 776.9p (£444m) - Final Results - Green - GREEN
2023 results are poor vs. 2022, as expected. However, their market share grew, the dividend is unchanged, and they are seeing initial signs of recovery in the mortgage market. Normal growth to hopefully resume in 2025. Shares not cheap but I still like the quality on offer.
Eagle Eye Solutions (LON:EYE) - unch 570p (£169m) - Interim results - Paul - GREEN
I dig into the H1 results, with everything looking as expected, in line. Cashflow is the only weak bit I found. A brief chat with management today was interesting, and I'm hoping to do a proper CEO interview. This remains one of my favourite UK growth shares, although valuing it is tricky.
Zotefoams (LON:ZTF) - up 6% to 356p (£173m) - Unaudited preliminary results FY 12/2023 - Paul - GREEN
Good numbers for 2023, ZTF seems to have shrugged off tough macro. I remain of the view that this is a decent business, fairly priced, but with free upside from the ReZorce project, which looks close to either success or failure.
Paul’s Section:
Crest Nicholson Holdings (LON:CRST)
224p (pre market) £576m - Trading Update - Paul - AMBER/GREEN
This housebuilder gives an AGM trading update today, for FY 10/2024 to date.
It’s a frustrating update, with lots of detail, but no clear statement about performance vs market expectations, which is supposed to be the whole point of trading updates.
The main issue is that more defects on old sites have surfaced, estimated £15m cost of remediation. Appointing consultants to assess adequacy of its existing provisions - that sounds ominous, I’m not the only one worried about this, as CRST shares trade at a significant discount to NTAV due I think to repeated problems surfacing with legacy sites. Who knows what other skeletons are in the closet here?
Current trading - this all sounds reassuring, and confirms the general view that the sector is beginning to recover -
- Reservations in line with expectations.
- “Reduced activity” before Christmas, “stronger performance from mid-January”
- Sales prices in line with expectations.
- Cancellations - “remained at normalised levels”.
- Lower building activity is resulting in “lower labour costs in some areas” - interesting.
- Build cost inflation overall “has largely stabilised and at a level lower than prior year” - ambiguous, presumably it means the rate of cost inflation is lower, not that actual costs are lower.
- Planning system remains challenging - same as all the housebuilders are saying.
Outlook - interesting, but I would have preferred a simple statement that they’re trading in line with expectations -
The Group continues to focus on optimising value and expects FY24 completions to be in the range of 1,800 to 2,000 homes, with completions weighted approximately 35/65% in favour of the second half of the year, reflecting the opening order book and the low level of reservations in the first two months of the financial year. Sales prices are expected to remain stable in FY24. Net debt at the end of February 2024 is tracking lower than expected as a result of lower build and land spend and this trend is expected to continue in the remainder of the financial year.
Paul’s opinion - the additional £15m remediation costs today is c.3% of CRST’s market cap, so the share price being down almost 5% in early trades (at 08:09) looks a sensible market reaction - ie factor in a bit more bad news than what is disclosed.
It’s all very well CRST shares trading at a c.30% discount to NTAV, but how many more unexpected liabilities are going to pop up from old sites, each of which undermines both NTAV and confidence in the company?
Appointing external consultants to review its provisions says to me this could be a can of worms, with the risk of them kitchen-sinking the legacy issues with another large provision.
The whole industry is grappling with remediation costs re the Grenfell tragedy, and CRST has additional problems for its own sites, which seems to be escalating rather than being resolved.
The amounts involved are not ruinous though, and checking CRST’s last balance sheet, it’s ridiculously strong, so I think the company could absorb the costs of even more remediation problems without any solvency worries.
I see dividends are forecast to be slashed this year.
Overall then, it’s a straightforward choice with housebuilders - pay a premium to NTAV for the better companies (eg Vistry (LON:VTY) ) or get a valuation discount for CRST because it’s been so accident-prone.
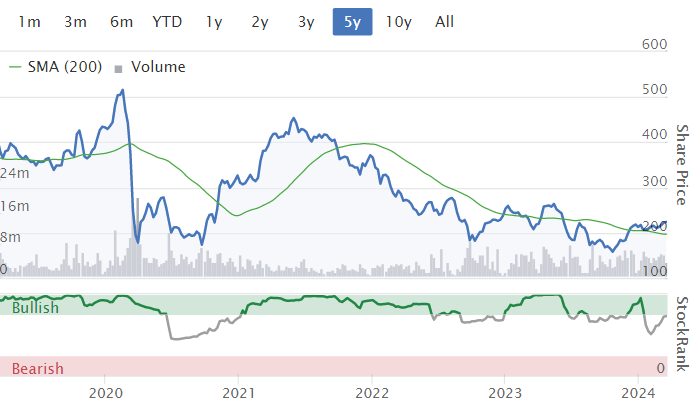
Not far above 5-year lows, and with no dilution over this period, could this share be a bargain? Possibly, it depends!
DFS Furniture (LON:DFS)
Down 7% to 104.8p (£246m) - Interim Results - Paul - AMBER/RED
DFS Furniture plc, the market-leading retailer of living room and upholstered furniture in the United Kingdom, today announces its interim results for the 26 week period ended 24 December 2023 (H1 FY24)...
Weak H1 results, with only £8.7m adj PBT (up 23% on H1 LY) on £505m revenues.
Statutory PBT was c. breakeven at £0.9m
Checking back, and ignoring pandemic distortions, H2 seems to be the seasonally stronger half.
Order intake down 10% on LY, below plan of -5%
Market share gains, with 38.5% claimed UK market share - so this is very clearly the market leader, and I think it’s a good business, nicely poised for a consumer recovery.
Net bank debt is way too high at £134m, and was accumulated in a reckless strategy to fund shareholder returns - this is my main issue with DFS shares, and due to the elevated risk (and cost) of bank debt, I’ve previously seen this share as amber/red.
Outlook - to save typing, here it is in full (all interesting) -

Balance sheet - as always, this is the deal-breaker for me.
NAV was £233.6m at 24/12/2023, which includes £536.4m intangible assets. Deduct those, and NTAV is negative £(303)m. Although that includes negative lease entries of £(95)m net liabilities - so there must be a fair few loss-making sites with onerous leases. Adjusting out all the lease entries improves NTAV to a still very bad £(208)m.
In a nutshell, for non-accountants, the whole business is financed by trade credit (suppliers allowing DFS to pay for the products after it’s sold them), and the bank.
DFS management seem to have learned nothing from the pandemic, in that they’ve geared up the balance sheet again after almost going bust and being forced into a (well supported admittedly) equity fundraise when business ground to a halt in the 2020 lockdown.
Paul’s opinion -
Bear view -
The H1 figures and outlook are poor, and it’s got a dangerously geared balance sheet.
Bull view -
As the clear market leader, and historically strongly profitable business, it should be well set up for a consumer recovery that is looking increasingly likely from April 2024 big pay & benefit/pensions increases.
The debt arguably leverages up the returns for equity, so in a recovery, worries about debt/dilution would recede, with all the benefit flowing to equity.
Overall, I can see both points of view, and there’s merit in both.
Note that a Polish furniture manufacturer Adriana, owns 9.4% of DFS, so could it possibly come into play as a takeover target I wonder?
I’ll stick with AMBER/RED, purely to flag up the considerable balance sheet risk, but I do like the actual business. It wouldn’t surprise me to see this share double in a consumer recovery, if it started issuing ahead of expectations updates later this year, so it is quite tempting, providing the bank manager doesn’t get cold feet.
Eagle Eye Solutions (LON:EYE)
Unch 570p (£169m) - Interim results - Paul - GREEN
Eagle Eye, a leading SaaS technology company that creates digital connections enabling personalised, real-time marketing through coupons, loyalty, apps, subscriptions and gift services, is pleased to announce its unaudited interim results for the six months ended 31 December 2023 (the "Period" or "H1 2024").
This is one of my favourite growth companies. We’ve followed it for years, and it’s great to see a small cap formerly jam tomorrow company actually succeed (the odd one does!)
The investment case here is strong organic growth, recurring revenues, great client list of international retail groups [typically supermarket chains], very little customer churn, and proven results for its customers from bespoke loyalty/rewards schemes, and genuine use of AI (not just a buzzword!)
Figures & outlook in H1 results today are in line with expectations, no surprises.
Key numbers -
H1 revenues up 20% to £24.1m
Recurring revenues 78% of the total, which should reduce the risk of any profit warnings in future, because most of the revenue is already in the bag before each year starts.
Period end ARR (annualised recurring revenue) £35.4m
H1 adj PBT £2.6m (up 49%)
Adj net cash £7.8m, says it has a bank facility too which it doesn’t envisage needing to use again.
Outlook - sounds fine -
We have entered the second half of the financial year with good momentum. Our sales pipeline has increased considerably versus this time last year, with EagleAI now accounting for 30% of the pipeline, demonstrating the strong interest in the product. As the wins previously announced go live, we will see continued growth in all areas of Win, Transact and Deepen revenue.
Trading since the Period end has continued well, providing confidence in the delivery of another year of profitable growth, in line with the Board's expectations.
I had a brief call with management this morning, and indicated that I dislike the phrase “profitable growth”, as it’s meaningless, and doesn’t necessarily mean that profits will grow at all! Management said we hear what you’re saying, what we mean by this is that the business is past the previous cash burning, loss-making stage, it’s just to reinforce that.
And to be fair, it does clearly state that FY 6/2024 should be in line with expectations.
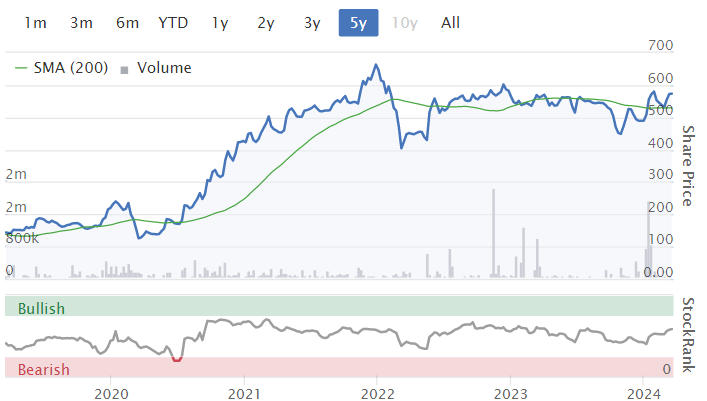
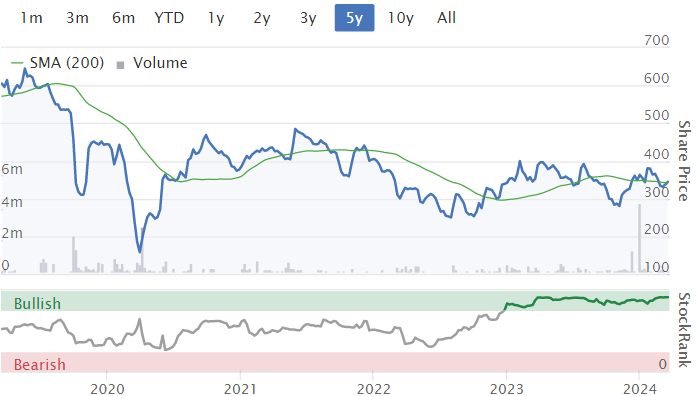
As you can see, it’s been quite a long haul, but EYE has clearly moved from speculative, into credible growth company territory now its profitable -

Most of the growth has been organic, although it bought a small French competitor mainly for its tech and its team about a year ago, called Untie Nots.
Broker research - many thanks to Shore Capital who make their notes available on Research Tree. It’s forecasting FY 6/2024 adj PBT little changed from last year, at £4.2m. This is adj diluted EPS of 12.0p, so a lofty PER of 47.5x - expensive yes, but adj PBT is forecast to double to £8.0m two years later, and the strong ongoing revenue growth makes that seem credible to me. So investors are effectively having to pay for 2 years growth up-front, which is a challenge for value investors!
Longer term the target is to reach £100m+ revenues and 25% EBITDA margins.
I told management I don’t like EBITDA.
Management remuneration - I also challenged this, especially the generous 2023 LTIP awards, saying that some of us had concerns. Management defended this, saying it was a scheme worked on for about a year, in conjunction with major shareholders, and the dilution isn’t excessive, and is based on stretch and super-stretch targets - see this excerpt from the 2023 Annual Report, I don’t suppose anyone would mind if the share price got to hurdle 3 or above, from its current 570p -

Capital Markets Day - Feb 2024 presentation setting out the longer term plan is here.
Balance sheet - looks OK, about £6m NTAV. Cash of £9m, it also reports adj net cash of £7.8m. This type of business tends to have little need for capital, although big customers do like robust balance sheets. So I think it should let the cash accumulate before paying any divis in future. It hasn’t paid any divis in the past, because this is a growth company.
Cashflow statement - not great, it has to be said.
Capitalised development spend is high, and rising, £3.5m in H1. This, and adverse working capital movements, saw a £1.3m cash outflow in H1.
I’d be looking to see cashflow improve in the future. I can imagine cashflow would be an area that any bears on EYE shares would latch onto. However, in my experience at fast organic growth companies, the cashflow can lag behind during the growth phase, and then often follow on later. If it doesn’t, then there’s a problem!
Paul’s opinion - no change, I really like EYE as an impressive tech growth company, which seems to be highly credibly in its niche, with lots of big name retailers on its client list. I asked about churn on my call today, with only Sainsburys being a major client that’s winding down due to its focus on Nectar.
Is its talk about AI just using a fashionable buzzword? Management says no, it not only handles billions of data items, but has competing algorithms, which challenge & learn from each other, so competitors can do simple loyalty schemes but nothing as sophisticated and personalised as what EYE does.
My view is that the impressive compound growth from big name clients, globally, tells me everything I need to know.
How to value these shares? That’s the most difficult bit. I always say that EYE looks expensive, which it does, but it’s gone almost sideways for the last 3 years, during which time the business has made great strides in performance. So you could argue its better value now, than previously.
For full disclosure, I hold a tiny position personally, just to keep it on my portfolio page, as a reminder that I want to buy some more if the price dips down at any point, and if funds are available.
Also, my brief call with management today went well, and I’m hoping to get them on for a CEO interview on my podcast channel at some stage.
Five year chart below - is it poised for another leg up, I wonder?
Zotefoams (LON:ZTF)
Up 6% to 356p (£173m) - Unaudited preliminary results FY 12/2023 - Paul - GREEN
I like the way it splits out the core foams business, with a strong rise of 22% in PBT to £17.2m, from the group total (which includes the loss-making ReZorce development project) of £12.8m PBT (up 5%). Personally I’m happy to value this share on the core business only, as the ReZorce project can be shut down if it doesn’t work.
On ReZorce it says -

If it works, this could provide exciting upside on the share price. If it doesn’t work, then the losses would be eliminated as the project is closed down. Any time travellers in the house, please tell us how it works out! For the rest of us, we can only guess, and apply probabilities.
Outlook - the detail sounds a bit mixed, but overall it concludes -
We have made a positive start to 2024, with overall sales ahead of the previous year's record first quarter…
while we remain mindful of the uncertain economic backdrop, 2024 is expected to be another year of good progress for Zotefoams".
Input costs “remain relatively stable”.
Quality scores - bears have questioned ZTF, saying it’s capital intensive and low quality. It’s true that it is capital intensive, but Stockopedia’s computers say that it generates a decent return from those assets. The quality score is 90, and the quality metrics are all green -

The commentary touches on this today -
Zotefoams targets improvements in the Group's return on capital over the investment cycle, while recognising the short-term impact on the return of sizeable capital investments during their construction and early operations phases, where they initially run at lower utilisation and mix optimisation levels. When Zotefoams embarks on investment in a major expansion or new location, such as the installation of extrusion and high-pressure capability at our existing Kentucky, USA site, which we commissioned in 2018, or the most recent investment in foam manufacturing at the Poland site, commissioned in 2021, we take into account the importance of scale and dilution of heavy infrastructure cost over a (future) second or third line. As such, the first step is invariably more dilutive to capital return than any subsequent investments…
Starting in 2015 with a programme to add the first and second stages of the Zotefoams manufacturing process into the USA, continuing with the addition of HPP capacity in the UK to support the Footwear opportunities and ending with the commissioning of the Brzeg, Poland, manufacturing facility in 2021, Zotefoams experienced a period of high capital investment. Over this period, we invested £91.4m in property, plant and equipment, of which £67.1m, or 73%, was directed to growth. With this programme complete, and over the medium term, the Group expects to return to levels of capital expenditure more in line with depreciation.
Balance sheet - looks fine to me. NAV of £116m becomes NTAV of £106m.
Net bank debt is £30.2m (I’ve deducted £1.4m leases) (up 13%), but the leverage multiple is fine at 1.2x (covenant limit is much higher, at 3.5x). To me, it’s just not an issue - particularly because ZTF has considerable freehold property supporting the borrowings indirectly.
I’m not sure why the bank debt is shown in current liabilities. Note 4 is odd - saying it becomes repayable each 3 to 6 month “loan interest period”. Elsewhere in the commentary it says the bank facility has a renewal date of March 2027.
So that’s a query point.
Cashflow statement - operating cashflow was static at £24m in both 2023 and 2022, but adverse working capital movements in 2023 absorbed half of that, £12m. So that’s another query point. It should be swings & roundabouts long-term, but worth asking the question.
Capex wasn’t particularly high in either 2023 (£5.7m physical, and £2.7m intangibles) or 2022 (broadly similar figures).
Overall then, I’d want some reassurance from management that the negative working capital movements are set to reverse in 2024.
Forecasts - many thanks to Singers for publishing its research. I know a lot of work goes into these. It makes very minor tweaks to 2024 and a 5% rise to 2025 forecasts, but that’s too far out in the future to be relied upon (generally, not just for ZTF).
22.3p adj EPS for 2024 means a PER of 16.0x, which I’d say is probably about right. Although remember that includes losses of £3.7m for ReZorce, strip that out, and the multiple on the core business is a good bit lower.
Paul’s opinion - I like the core business, it’s good, and sailed through both the pandemic and the energy crisis, so we know it’s well managed and has pricing power.
Shares are reasonably priced on the core business I think. Yes I do accept it’s capital intensive, that is a fair point, but the returns are OK from the capital utilised I think.
ReZorce is then thrown in for free, and the upside from this is genuinely exciting.
So it remains a nice each-way bet in my opinion. Still GREEN for me.
For disclosure, I should add that I only hold a placeholder position, to remind me to buy more (similar to EYE above) when funds permit.
Graham's Section
SThree (LON:STEM)
- Share price: 419.5p (-1%)
- Market cap: £566m
This is a Q1 update; SThree’s financial year ends in November.
SThree plc… the only global specialist talent partner focused on roles in Science, Technology, Engineering and Mathematics ('STEM'), today issues a trading update covering the period 1 December 2023 to 29 February 2024.
FY 2024 is still expected in line with expectations at this early stage.
Key points:
Net fees down 6% “against a record prior year performance and the ongoing challenging backdrop”.
Contract fees are now 84% of the total and they fell 2% year-on-year.
Contractor order book down 1%; it provides “sector-leading visibility with the equivalent of c. 4 months of net fees”.
Net cash is up year-on-year to £97m. The strong balance sheet has been one of the big attractions here for years.
CEO comment:
"Once again, we have delivered a good performance against a strong comparative and within a market environment that remains difficult from a new business perspective. Whilst the sentiment we are reporting is much the same as the prior period, the strength of our Contract extensions continues to be a particular highlight, demonstrating our clients' need to retain critical STEM skills and flexible talent.
Regions and countries - net fees were down across Europe except for the Netherlands which saw continued strong demand for Engineering and Technology talent.
Japan did very well but from a low base:

Demand for Life Sciences has been on the decline ever since the Covid boom, and Technology has also been softening, with the result the Engineering is now responsible for a much bigger slice of the pie:

Graham’s view
At the end of the day, this is an “in line with expectations” update so few people are likely to have any reason to change their view on this stock today.
The weakness in the core “Technology” segment is a slight concern but over the long-term I’d feel more comfortable in this area of recruitment (focused on software development and Salesforce) than I would with recruiters in many other areas.
Valuation remains modest (and remember that the PE Ratio doesn’t adjust for cash on the balance sheet):

And it has an extraordinary StockRank of 98:

With Permanent Recruitment now only responsible for 16% of SThree’s net fees, the ongoing decline of that category will be less and less relevant to SThree’s future results.
So I’m still positive here and wondering if the share price can get back to the highs seen last year?

Mortgage Advice Bureau (Holdings) (LON:MAB1)
Share price: 776.9p (-3%)
Market cap: £444m
This stock made it onto my 2024 best ideas list despite already generating a return of 60% in 2023. It was a strong contender for banking gains and moving on, but I decided to stick with it for a while longer. Let’s see how it’s going to repay my loyalty!
Results for 2023 aren’t good against the prior year: as we all know, 2023 was a tough year in the mortgage market.
Revenue +4% to £240m (organic revenue down 4%).
Adjusted PBT down 15% to £23m
Actual PBT down 7% to £16m
The total value of the mortgages (including transfers) they helped to complete fell by 8%. The number of advisors in the MAB network fell by 4% (to 2,158).
Dividend is unchanged at 14.7p.
You could be forgiven for asking why I’ve made such a fuss about this share, given the weak year-on-year performance.
One key reason is that if this is what the company can do in a really really bad year, then I’m still excited to see what they can do in a good year!
House purchase lending fell 23% in 2023; in that context, I think MAB’s performance was very good!
They estimate that their market share of new mortgage lending improved from 7.5% to 8.3%.
Refinancing work became more important in 2023 and accounted for 35% of revenues (2022: 32%).
Profitability was hit by rising administrative expenses which reflect “the planned further investment in the Group’s growth strategy”.
CEO comment:
Against a very challenging backdrop in 2023, MAB continued its exceptional track record of outperformance and market share growth in all market conditions…
He also covers the outlook but let’s go straight to the outlook section for that.
Current trading is in line with expectations:
Following the modest improvement in trading towards the end of last year, we have seen a very positive start to 2024 across both purchase and re-financing, including a long-awaited recovery in Buy-to-Let activity… mortgage rates have reduced notably, the availability of mortgage products has increased, and mortgage underwriting criteria are starting to signal a more positive outlook.
Although we expect it will be the second half before we see organic adviser growth recommence, our AR firms are eager to resume their growth plans and are preparing to do so now…
Graham’s view
Perhaps I’m too easily persuaded, but I agree with MAB when they say:
It is very rare to see such a severe downturn in UK purchase related mortgages as the one we have experienced, and it significantly affected what would otherwise have been an incredibly strong year for MAB. This was clearly a setback for the business but only one of timing.
That being the case - 2023 being an unusually bad year for mortgage lending - I’m excited to see what MAB can do this year, especially in H2, and then in 2025.
I also remain very interested to see Fluent Money succeed. This was bought for £72m so it’s important to get value from this deal, but the timing of the acquisition could not have been any worse (mid-2022).
MAB shares are not cheap but I would expect growth to pick again sooner or later. They do say “we do not see normal growth in organic adviser numbers resuming until 2025”, so some patience is likely to be required.

Therefore, while I do still believe in the long-term future of this company, and I give it the green light, I could also understand if the share price drifted until the business rediscovers its underlying momentum.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

106 comments
MPAC (LON:MPAC) - Investor Presentation video recording with Q&A *** Adam Holland (CEO) and Will Wilkins (Group Finance Director) of Mpac Group conducted an Investor Presentation covering their FY Results for the period ended 31 Dec 2023. After a short video ("Innovation Unleashed"), management ran viewers through highlights of the period including strong financial performance, returning the Group to revenue and profit growth, and positive net cash. The team updated investors on progress towards strategic objectives and discussed the Group's ambitions, as well as providing a detailed financial review and answering questions in a wide-ranging Q&A session. The full video is available here, divided into chapters:
MPAC (LON:MPAC)
This is how you run and scale an engineering business in my view. Culturally set up to succeed. Customer and people centric with blue chip client base and repeat business. Worth a watch. I'm an even happier shareholder having seen some of the presentations today - seeking to double EPS in 3 years - ie c. 55p and in 5 years to double revenues.
On Equity Developments site today
I listened to the podcast version of Paul Hill's interview with MPAC (LON:MPAC) and it's a good investment case, I like it. My only reservations are:
MPAC shares have already factored in considerably more growth, and have doubled from Dec 2023 to now. So why chase this one up, when there are so many other great recovery stories out there that are still on bombed out valuations?
They were very open about saying orders are lumpy in nature, and that the only solution to this is doubling the size of the business - a fine aspiration, but easier said than done!
Aiming to significantly increase margins and revenues. They almost made it sound easy. If it was easy, surely it would have been done before?
Performance has been erratic in the past, with the occasional disappointing year (pre-pandemic too). So I wouldn't want to pay more than a lowish PER, to factor in the risk of another series of disappointments on contract deferrals, etc.
The share was over-promoted in previous years, resulting in an excellent bull run, ending in 2021, but it then lost two-thirds of its value when results disappointed. So are we not in danger of the same thing happening again? It's a risk anyway, as nobody knows how the future will pan out.
Management seem dull, but credible. There's a lot to be said for dull though!
Overall I was impressed, and think it looks a positive situation, but I'm not interested in joining the party as I've missed the best bit!
Good luck with it!
Regards, Paul.
Blimey David. I hope you can tolerate a dissenting voice. The product and processes might be strong - I’ve no idea having never researched the name. But a less impressive assembly of talking heads it would be hard to find. Are they the driving force and strategic vision of the business? I’ve been accused of banalysis for judging management so perfunctorily in the past. But I’ve spent a lot of time in the C-suite, as director and key partner, including many years as a headhunter, where it was my task to identify leaders. And, believe me, I’m not seeing it. Someone was impressed yesterday that the CEO is an Oxbridge physicist. Well, I’m married to one. She’s got a terrific range of abilities but that doesn’t make her a business leader. My overall impression from this video alone is that this is a steady niche business, run by plodders. It’s been a good investment of late and I salute your perspicacity in spotting the undervaluation. But I don’t see any special sauce in the video presentation. Perhaps I need to investigate further.
I don’t mind dissenting voices - I take no offence as to whether anyone agreed with me or not.
The video I shared is a separate video around the culture at the MPAC (LON:MPAC) business. I have been C suite for a long time in large companies and I know that in businesses like these 2 things significantly enhance chances of success. Neither guarantees it, but you can be pretty sure without it the business will not achieve their objectives. Those are the culture around Client and People. What MPAC (LON:MPAC) are doing that is impressive is building very strong relationships with blue chip clients through excellent service delivery and innovation. That is leading to significant repeat orders and a service revenue base that has gone from virtually zero a few years back to almost 30% of revenues. The second element is people. Clearly the workforce has the same culture and message and innovation is at the heart of what they do. That invisible R&D is likely to pay dividends well into the future.
Given the order book (60% of this years revenues are covered) but add in the 30% service revenue and that means almost all of the 39p EPS forecast is covered. That’s impressive.
I think lots of people saw Paul Hills podcast Q&A but had possibly missed the Equity Development videos - there were 2 ; the first focused on the results and there are some good snippets in there that weren’t in the one Paul did and the other one was the one I shared which was about MPAC (LON:MPAC) culture.
Putting all of the elements together I think that MPAC (LON:MPAC) have good business momentum, a potential batter storage blue sky type project, but even without that are well set to hit that 50p+ eps over the next 3 years. Therefore I still see good upside from here.
Thanks for the reply, David. I always take your views seriously and I hope you enjoy and/or derive some benefit from my occasional challenges to your viewpoint. I live not far from Tadcaster, to the extent that anywhere in mighty Yorkshire is close to anywhere else ;-) Perhaps I should pay MPAC a visit.
If you decide to pay MPAC (LON:MPAC) a visit I’d love to hear your views BnB.
I never mind challenges to my hypothesis. In fact it’s a big factor in being on here and posting. I actively want to know what other (sensible) people think. Frankly a lot of boards are a waste of time and energy but this, being a closed forum, has plenty of wide ranging experience and intelligent investors on it. Lots of different styles and opinions. For me that sort of feedback should be welcomed not frowned upon. The last thing we need is group think, it’s certainly not going to help me or you become a better investor.
For those invested in Palace Capital (LON:PCA) it would appear that they have now got another of their high value apartments at Hudson Quarter sold subject to contract (was listed for c £750k).
SKY first with the leaks.
https://news.sky.com/story/inf...
"UK inflation is expected to come in at 3.5% on Wednesday - down from 4%. "
SKY first with the leaks.
https://news.sky.com/story/inf...
"UK inflation is expected to come in at 3.5% on Wednesday - down from 4%. "
Is that a leak, though? Or simply a poll of economists such as every other media outlet is quoting?
These are the estimates two weeks ago. Not a leak ;just estimates as there are estimates for next months US CPI.
Always has been the case.
Celebrus Technologies (LON:CLBS) Trading Update and Board Change (I hold)
At first sight, not very exciting this 'in-line' update on the current year - just ending Mar-24 - for this small cap provider of software for sales/marketing relationship managment - now often termed 'CX' or customer experience - and associated fraud detection platform.
It is worth remembering that there were questions at the half-way stage over the size of the trade receivables
https://www.stockopedia.com/co...
and the SaaS invoicing model. Unlike monthly billed SaaS companies - Celebrus Technologies (LON:CLBS) licenses annually on multi-year non-refundable contracts where licence payments, the highest margin part of the revenue, are invoiced annually. Today's in-line TU continues to provide confidence that the company can deliver against challenging forecasts.
Helpful that they actually state the market expectations. Appreciated. And on that basis they expect to be at least £32m revenue against £32.1m expectation, and around £5.5m adj pre-tax profit, against expecations of £5.4m. Just under on revenue, and just over on adj profit. Better than the other way around?
Cavendish (house broker) have released an updated research note this morning - free on research tree. Again, appreciated.
The revenue growth of 50% YoY is distorted by the slipping of a large, relatively low margin, contract from H2 FY23 to H1 FY24. Revenue growth of 22% compared with ttm is consistent and agrees with the TU figure of 20% YoY growth in ARR licences, maintenance, support and cloud services.
So far so good? But not much to get excited about? Especially on a multiple of around 22x current year and 18x FY Mar25?
Maybe. It's more of a compounder than an overnight multi-bagger. But sometimes those are the most hidden in plain view? It's certainly not my normal value share level of price, but I think that there are good reasons to be cheerful.
[1] Celebrus Technologies (LON:CLBS) business model has changed significantly in recent years. The large lumpy relatively low margin contracts, of the sort that slipped into H1, are now the exception and not the rule. Which is because:
[2] Previously products were exclusively sold via 'channel-partners' who controlled future sales, up-selling and cross-selling. Celebrus now focuses upon it's recently launched private cloud based products which allow direct selling and without low margin hardware.
[3] The private cloud implementation allows a land-and-expand sales approach. Upgrades and extensions can be switched on overnight. Generally faster than the clients own IT services can manage.
[4] Once won, customers tend to be very sticky which is an advantage. But winning sticky customers from other clients is hard, which is the other side of the coin and a disadvantage. As third party analytics and cookies are withdrawn there is a window of opportunity for Celebrus to 'land-and-expand' new customers needing to change with its private cloud based applications and CX 'customer experience' vault, as well as its it's fraud detection capabilitites.
[5] As well as meeting customer needs the new Celebrus implementations are inherently built to scale up allowing more rapid growth - should it happen!
Of course I can't predict the future. Whether Celebrus will be successful in winning new customers more rapidly, and whether the new customers will expand greatly once they land increasing the revenue and profit trajectory... I just can't foresee.... but it looks to me that the company is in the right place at the right time with the right products and doing the right things to succeed. Not something I often get to see. Which promises to be an interesting, maybe even a moderately exciting, ride?
Cavendish estimate the cashpile will have grown to £20m at the end of the month - worth another 50p a share, despite investing for growth in staff, R&D, paying a small dividend and continuing to buy-back its shares. And that excludes the £3m expected from the sale of the no longer required HQ building.
i wouldn't say its looking cheap today, but then I had the benefit of buying more at the lows in 2023, and successful compounders often don't look cheap on the day?
cheers
Mark - Disclosure Celebrus Technologies (LON:CLBS) is my third largest holding after MS International (LON:MSI) and Macfarlane (LON:MACF) and a relative newcomer, having first bought 5 years ago, in my concentrated portfolio of 12 UK small and micro-caps.
Completely agree Mark on Celebrus Technologies (LON:CLBS)
This is very misunderstood as a company and business model. Revenue visibility is actually pretty good despite the fact that a lot of multi-year contracts pay their annual upfront fees in H2 so there is a nasty skew in H1/2 every year. Check out annual revenue and ARR on a longer term bar chart and you will see how this business is actually really starting to perform.
Strip out cash and it isn’t expensive at all. I do hold but am considering topping up to a more full position myself as I see these as a big winner over 3-5 years.
SThree (LON:STEM) Graham, many thanks for the FY24 Q1 write-up above. Here is the recording of the meeting with analysts from this morning video & podcast.
We are also working on the analyst meetings for Fintel (LON:FNTL was SimplyBiz) and Eagle Eye Solutions (LON:EYE) so these will follow over the coming days. BTW with FNTL I had no idea MoneySupermarket was a (new) customer where they facilitate their comparison services. I don't know how extensive their service with MONY but an insight for any MONY holders.
Also, today, Pebble (LON:PEBB) FY 2023 results with a management webinar on Thursday at 3pm. Register here. Today, the share price is +10% granted they massively sold off after the November 2023 warning. FY23 we see the gross margin has materially improved to 43.6% from 39.3% which is credited to both, 'increased value delivered by Brand Addition and the growing proportion of Facilisgroup as a percentage of overall sales' and with ARR +12%. Otherwise, the top line figures are lower than last year. For the outlook, they are in line with expectations and they intend to implement a share buy-back programme.
Thursday 21st March, is a busy day, at PIW, at 4.45pm, we host a Judges Scientific (LON:JDG) FY23 webinar with all the team there, please join us to hear about their results and ask any questions: Register here.
Some sad. news - well at least I feel a bit sad . Ted Baker's owners have called in the administrators. I rather think Superdry (LON:SDRY) will be next.
On Eagle Eye Solutions (LON:EYE) I've had it on my watchlist since 2020. Agree with Paul that it is a solid growth company. But every time I've relooked at it, while the quality and growth rating is strong, the share price was just too high.
Indeed, we see this now - all the prospects of the company were priced in to the shares since 2021... as it has gone sideways since then, despite very good progress on revenues and profits.
Is this now an inflection point? Or is the current price still already baked in too much of the future potential? Time will tell! But this is a good example of why sometimes the "coffee can" approach doesn't work - just buying based on solid quality/prospects. One also has to look at the price, to see if that has been priced in already.
Puretech Health (LON:PRTC) $100 million proposed tender offer, or special dividend otherwise, using some of the cash they got from Karuna Therapeutics (NMQ:KRTX) , which they licenced out their technology for, and their $14 billion buyout by Bristol-Myers Squibb Co (NYQ:CELG RT) .They have managed to not dilute shareholders since listing, which is extremely impressive for a biotech/pharma.Recently completed a $50 million share buyback too .Focusing on developing their own drug pipeline themselves now, which will be lengthy naturally and the board say they intend to maintain three years cash runway (but who knows totally with expensive trials to run), but going by previous platform success of 2 FDA licenced out approvals and Karuna Therapeutics (NMQ:KRTX) 's expected... the odds could be better than the average for pharma?Verona Pharma (NMQ:VRNA, which used to be LSE listed, but moved to the Nasdaq a few years back has done well (not a similar model and much more dilutive which is always the big issue) but proof that pharma can still provide outsized returns occassionally!They still need to get their drug FDA approved however.PDUFA date June 26,2024 for Verona Pharma (NMQ:VRNA.Fierece Pharma have Verona Pharma (NMQ:VRNA) 's potential new drug on their top 10 most anticipated drug launches in 2024 in 9th spot and Karuna Therapeutics (NMQ:KRTX) as number 1.
Surprised Litigation Capital Management (LON:LIT) aren’t doing better. Trading below conservative book value whereas these type of litigation firms usually trade higher. Yet, it is making money and now has a good Asset Mgmt business that adds fees and performance fees to the mix which is neat. Upside with no equity dilution and plenty of downside risk protection. Looks like a good model.
Surprised they aren’t trading north of 125p but hey ho……. I will continue to hold
Hi David
I hold Litigation Capital Management (LON:LIT) and agree with your sentiments although I calculate that they are trading at a slight premium to book value: NAV AUD185m no of shares 119m gives NAV 80p/share at AUD1.95/£ against share price of 93p
Litigation Capital Management (LON:LIT) Worth watching the excellent IMC presentation - the NAV is probably hugely understated and could be double reported level if you base it on returns in line with historic average and include future performance fees.
Equals (LON:EQLS) - Yet another PUSU deadline tomorrow, SP=109p
2024 fcst Revenue £114m, shares in issue 188m. Exit values:
2.5x multiple, value = £285m, price = 152p
3.0x = £342m, price = 182p
3.5x = £399m, price = 212p
Also £18m cash on BS.
Any followers?
Yes - can’t help but think there is no deal to be done here for Equals (LON:EQLS) . Two things kill deals - time and surprises. In this instance I think the former is likely. Discussions look like they probably got close but apart on valuation and they haven’t been able to bridge the gap by the looks of things. Could be wrong of course but it shouldn’t take this long.
That said I think it is worth north of 150p irrespective of the potential bid and closer to 200p assuming it is trading in-line or better so I’d like them to either get on with it themselves and kill negotiations or if a deal is to be had do it quickly. Irrespective of physical amount of time in discussion there is a mental load/distraction that is unhelpful running a business day to day. Let’s see. I will continue to hold if no deal materialises which is now my base case assumption. Obviously if trading changes that would alter things but so far they’ve said in-line.
I hold - although with increasingly less hope for a deal. I just feel if there was a deal to be done, it would have been done by now.
That being said, if the 2023 results match the trading statement, the shares don't look expensive as they are - although I couldn't reconcile the cashflow - by my calculations there should have been more cash in the bank than they stated.
Equals
I hold
Good company doing well .
But bored senseless with the whole sideshow and hope the management haven’t wasted time effort and cash on extensive due dilligence. That would be a serious own goal , you would hope not but hard to see it not consuming management time .
Equally they might have learnt sone things .
Interestingly we keep getting by the currency trading team at Equals for our currency business, happens every 8 weeks or so . I’m undecided if this is a good sign or a bad sign .
Shout out to BNB writer if your around!
A year or so ago I posted my top 5, noting I brought Ashtead Technologies at IPO but was too slicing for moving profits and selling down. BNB recommended re checking the figures - I brought my stake back after going back through everything (I was thinking move the funds elsewhere after a nice run), but still had plenty of room to grow.current price means I have a nice free carry trade at a good portfolio size.
- mental note; don’t just sell after good rises, could be plenty more to come! Also it’s been the quieter shares on the bullet boards which have done me well over the years…
Please can everyone stop talking about GAMA Comms! Been building a position there for a few years now and finally waking up.. I was enjoying the time of growing profits and cash whilst the share price went nowhere just fine thanks !
Shout out to BNB writer if your around
If you mean me, you’re welcome :-)
I do indeed!
I'm in a similar position, after top slicing Judges Scientific (LON:JDG) and IQGeo (LON:IQG) thinking they'd had a good run and expecting the price to settle back to buy back at a discount and increase my holdings but IQG has a fairly wide spread and JDG just kept going, although softer this week.
Must remember to run my winners a bit longer and be patient.
Decent ahead of expectations results from Boku (LON:BOKU) today, accompanied by a very effusive statement (he’s beyond excited ) from the CEO:
Stuart Neal, Chief Executive of Boku, commented. "These results demonstrate that Boku is in strong financial shape and poised to fulfil its potential to grow significantly in the world of Local Payment Methods, which now represent two thirds of all global online payment volumes. It is testament to our focus on delivering for our customers, combined with a clear long-term strategy, that we are expanding the relationships with all of our key global merchants, beyond our Direct Carrier Billing ('DCB') product, to now incorporate Digital Wallets and Account to Account ('A2A') schemes across the globe. 2024 has started strongly and with deals that are already in place, we have the ability to double the business over the mid-term, as previously stated, with additional value to be created from expansion into new verticals. I am beyond excited at the potential for growth in this business as we create the global network for localised payment solutions."
During 2022 they disposed of their identity division to focus on their payments divisions and this does seem to have paid off. They are debt free and have a very impressive client list including Google, Meta, Microsoft, Amazon, Disney, Netflix, Spotify, Samsung, Sky and EA Games. There is a live investor presentation at 5.30pm which sadly I am unable to attend. Registration details in today’s RNS for those interested.
I have held this share since April 2019, so some patience has been required.
Midwich (LON:MIDW). I was happy with MIDW results this morning with the Revenue up 7%, PBT up 47%, adj PBT up 11%. and the Divi up 10% (being covered 2.3x).
The net debt ratio is down to 1.1x. They cite the highest ever GM's of 16.8%. Looking forward the company "continues to see a robust future acquisition pipeline". They are "confident that 2024 will see yet another year of growth in excess of the overall market" which sounds encouraging.
This is an acquisitive business and so lots of moving parts. It also brings a lot of adjustments into the mix. I generally allow adjustments related to acquisition charges and integration costs, but do not see share based payments as anything other than employee remuneration.
Given the forward P/E has been more than double the current valuation in the past, the company continues to grow and is improving profits and margins, I see upside at the current valuation.
Would be interested to hear Paul or Graham's views on this should time allow.
This one won’t appeal to everyone but the plus points are potentially so strong that it’s worth posting on it for anyone wanting to check further.
Coal producer Thungela Resources (LON:TGA) issued their results yesterday. Link here:-
https://www.stockopedia.com/sh...
The share price is down 70% from the £18 peak in September 2022.
Why?
Because the spot coal price is also down 70% from $450 a tonne peak in Sept 2022 to just $130 now and that’s a slight recovery from the recent $120 low.
The good news reported by Thungela Resources (LON:TGA) yesterday?
Results as expected and fairly optimistic outlook too. KEY plus is the 10 rand a share dividend. That’s about 42p to give 9% yield just for that one dividend! The next dividend in September will again depend on the level of the spot coal price. If it holds around current level then it could well be another 42p, and if coal rallies then coukd well be higher. So potentially a near 20% yield!
It goes ex dividend on 18th April and pay day 7th May.
For those who like buybacks Thungela Resources (LON:TGA) also announced a R500 million buyback.
Stockopedia 91 for quality and 99 for value.
I bought after the trading update last month and because the coal price looks as though it might have bottomed at long last! The share was up 26p yrstetday to £4.70. It bottomed at £4.20 last month.
Thungela Resources (LON:TGA) is easier to assess for potential share price gains or losses than many shares. A higher coal price feeds through to a higher Thungela Resources (LON:TGA) share price and vice versa.
Here’s a link showing coal price and a lot of other commodity type prices:-
https://tradingeconomics.com/c...
The big question, as asked by KevinS1 when I posted most of the above on the “How to win in bear markets thread” yesterday is whether the spot coal price falls are likely to resume and perhaps even back to near the pre bubble prices?
Time will tell on that. What China does might be key perhaps?
That and much more in this recent article:-
https://www.gisreportsonline.c...
Hi Ken,
I seem to recall that Thungela Resources (LON:TGA) have suffered in the past due to rail network issues impacting their ability to transport their coal - is this still the case?
Yes, and I think it would help if TGA were to buy the railway as per England in the 19th Century.
Derbion
The answer to your Thungela Resources (LON:TGA) question is yes. It’s always well worth reading Results statements imo. Thungela Resources (LON:TGA) have covered the rail network disruption issue and their diversification to try and minimise the negative effects of it, in some detail, including this extract which you’ll see answers your question:-
“Managing the impact of continued poor rail performance
Inconsistent and constrained TFR performance has once again significantly compromised the South African coal mining industry. In 2023, TFR railed 47.9Mt of thermal coal to the Richards Bay Coal Terminal (RBCT), compared to 50.3Mt in 2022, a decline of 4.8%.
We continue to work closely with other industry players and Transnet to remedy rail performance. Through RBCT, the industry has strengthened security measures by deploying additional security on the coal line for the past 18 months. While the impasse between TFR and Chinese locomotive supplier CRRC continues, RBCT (on behalf of the industry) is also helping Transnet to acquire the critical spare parts necessary for the maintenance of locomotives from alternative suppliers.
The cost of the spares and security deployment is recovered by the coal exporting parties through the mutual cooperation agreement signed between TFR and RBCT (representing the coal exporting parties). Further collaborative efforts will address critical systems, such as signalling, to improve overall performance.
We have responded to TFR's persistent poor performance by curtailing production at our underground mines, renting sidings to improve our rail distribution pattern and driving efficiencies at our rapid loading terminals. Acting swiftly and decisively in the face of rail challenges has allowed us to benefit from additional trains when they are available, and rail 12.3Mt of export saleable volumes in 2023. Given the uncertain nature of TFR's performance, we have agreed to extend the existing long-term rail agreement by one year, to 31 March 2025, to allow TFR to demonstrate sufficient stability before the contract is renegotiated.
Building a sustainable and long-life business across multiple geographies
2023 was a year of significant accomplishments for Thungela as we executed our strategic priorities - successfully unlocking new markets and mitigating risk through our geographic diversification strategy, increasing the life of our business and building an organisation optimised for further diversification. These actions demonstrate our singular focus on creating long-term value for our stakeholders.
The acquisition of a controlling interest in the Ensham Business in Australia marked a significant milestone on our diversification journey, as it expands Thungela's presence beyond South Africa. This mitigates our reliance on a single operating geography and opens up new markets, notably in Japan and Malaysia, diversifying our customer base and providing exposure to the Newcastle Benchmark coal price.
Ensham will benefit from our operational expertise as it extracts coal using mechanised underground bord and pillar mining methods, similar to those used in our South African operations. Since we assumed operational control on 1 September 2023, our focus has been on improving productivity. Operational performance has stabilised at an annualised run-rate of 3.2Mtpa, up from 2.7Mtpa at the acquisition date. We believe there is opportunity for further improvement to approximately 3.6Mtpa through the introduction of an additional production section in 2024. Resource development studies are underway to define the full upside potential of the Ensham resource by identifying brownfield opportunities and their related capital requirements.”
Thanks, Ken.
A couple of weeks ago, I mentioned on here that I'd written a crime novel from the perspective of a private investor. When I was writing the book, it felt like this forum was my audience and I'd like to encourage as many people on here as possible to read it. I think four or five Stockopedia subscribers bought the book after my last post and a few people I know also bought it over the last couple of weeks. I said that I’d donate half the royalties over a one-month period to Zane, the charity that Paul and others have supported here. I’ve decided that I’ll donate all the royalties, so we’re at about £25 (the royalties are about £2 per sale). I can’t help thinking though that we can do a lot better than this. The e-book is only £4-99 and around £2 will go to a very deserving charity. You’ll also get a read that I think many people here will find interesting, and hopefully entertaining.
Please check it out at the following links. You can download the Kindle app for free and read it at your leisure on your mobile. Alternatively, you can listen to the audiobook narrated by yours truly. I’ve had some very positive feedback on my Greek and Indian accents!!
Book: https://mybook.to/PigsGetSlaughtered
Audiobook: Pigs Get Slaughtered by A.D. Vaughan | 2940191660875 | Audiobook (Digital) | Barnes & Noble® (barnesandnoble.com)
https://play.google.com/store/...
https://www.audiobooks.com/aud...
Thanks.
You’re right to remind us we’re a lazy lot, I’ve just bought it on Kindle! Good luck and a good cause!
Thanks Ox. Please leave a review when you’ve read it.
Hi Gnome2, I purchased it and thoroughly enjoyed it so congratulations. I would recommend it to anyone on here. Are you going to do a sequel?
Colin, I’m so glad you enjoyed it. If you could leave a review on Amazon that would be great. I’d like to do a follow up but so much time and effort goes into it, I just need to believe that it’s going to find an audience. You’ve definitely given me some encouragement! All the best.
I already left you a review on Amazon
I have a name for it…”Bringing the bacon home”
Just ordered it Gnome2 but being a dinosaur I ordered the paperback.
Sounds a bit like the novels by Michale Ridpath which I always enjoyed although he moved onto fantasy stuff after a few finance/banking/investment novels.
Looking forward to giving it a read.
ATB, Kevin
What a great idea and thanks for the reminder Gnome2. Have made my donation and downloaded - I look forward to reading,
cheers
Mark
Bloomberg story:
DFS Furniture (LON:DFS) trimmed its annual pretax profit outlook by a third and warned that continued disruption in the Red Sea could defer another £4 million ($5 million) of profit to the following financial year.
The sofa maker now expects pretax before of £20 million to £25 million in 2024, down from a previous range of £30 million to £35 million, it said in a statement. The new guidance assumes that conflict in the Red Sea and the resulting delivery delays are resolved soon, which isn’t guaranteed.
DFS Furniture said market demand has dwindled over the past two months after a solid start at the beginning of the year. Order volumes were down around 16% across January and February.
Headwinds will continue for DFS until sofa market volumes recover to pre-pandemic levels, Jefferies analysts Andrew Wade and Grace Gilberg wrote in a note.
I guess prople aren't moving so no need for new sofas.
MPAC (LON:MPAC) results looks super to me. They say in-line but looks to me like a slight beat in EPS terms. On track for 38-39p eps this year and 44-45p next. Layer that on to historic ranges of say 13* PER and we have 580p. Net cash also estimated to go up to £7m this year (+5m).
Nothing factored in for the battery storage (Freyr) so could give an additional fillip.
Overall I’m happy - and see price has risen a little in response. Will watch the company presentation but the overall tone in the statement felt good.
Here's today Youtube interview. MPAC are a client of Vox Markets.
&t=137sSuperb interview Paul, you addressed all my questions and some. Particularly pleased with the 28% share of revenue as services (and increasing) and strong order book visibility. Just reading the CEO is a Cambridge physicist and ex Rolls Royce, Siemens and JCB, how assured and impressive is he?
I'm surprised you don't own these Paul, I'm going to be topping up this morning because I think the buy case even at these levels is just too strong to pass up.
Many thanks Burnt Onions & very well done.
This morning, Paul detailed his approach to buying micro caps in yesterday’s SCVR. I thought it was worth highlighting here as people might have missed it and I thought it was v interesting.
It’s currently the most recent post.
Thanks Indie! Here's the direct link to my post.
Thanks Paul. Its such a daft sweeping statement to say micro caps are for fools, just because one individual lacks the skills to make money in them. I cant make money day trading because I lack the skills, but theres people who make a good living doing just that. They certainly arent fools.
Lots of people being emotionally owned by the 'tape' as the yanks say.
Wolfie the person merely implied that only fools buy on a 10% spread. I think we all agree on that as you need a 20% move basically to be in the money.
On that basis that’s a fools game.
Actually it only needs a 10% move. Working through an example proves it.
B1.00-A1.10 I buy at 1.10
Bid moves 1.10-1.20 still losing money on commission.
B1.20-A1.30 you can only make money after a 20% move.
Working through an example does actually prove it.
Daylight robbery in my opinion.
All the best
Commission is low, unless you buying very small amounts. I pay £3 per transaction. Even on £500 that is under 1%.
A lot of micro caps are under 10% spread, see Pressure Technologies (LON:PRES) and Plexus Holdings (LON:POS)
That was an example on a 10% spread that you pay eventually if you want to build a rather large position (75K+). I am well aware of the commission etc.
My point is that this should not be allowed and the spread should be at 1% max. This is one of the reasons most fund managers and investors move to the US market. Easy entry and quick exit.
it’s fair on investors and will create the much needed liquidity.
Yiannos, I will provide everyone with a PROPERLY worked example so that everybody can see that, for a 10% spread it only needs a 10% increase in the share price to break even. Company XYZ trades at Ask price of 100p and a Bid price of 90p. This is a spread of 10%. I invest £10,000 which buys me 10,000 shares. I then sell my 10,000 shares for 90p each to get £9000. So I have lost £1,000 on the round trip which is 10% of my initial investment. So I do not need the share price to go back up by 20% to break even. A good way to look at this situation is that I have paid 5% of the spread when I bought, and another 5% spread when I sold. It is a fallacy to state that a 10% spread requires a 20% share price increase to break even.
You need a 20% increase on a 10% spread to make money.
Simple maths.
This is what I have said. my example is still there to read it again….. you can only make money after a 20% move.
No need for highlighting letters as well as I take it that you are trying to dictate something,
All the best
Your example does not make sense. On 10% spread, you start making a profit after a 10% price rise,. A 20% rise you will be making around 9% profit, Buy at 110p, sell at 120p.
Is it so difficult?
The bid has to move 20% to make money.
Oh for crying out loud yiannos. Bid 90, Offer 100 equals 10% spread (on the buy price). Therefore, bid has to rise 11.11% to break even and at 12% it would be in profit - e,g. 90 x 1.12 = 100.8. Whereas 20% rise would deliver a larger profit - e.g. 90 x 1.2 = 108.
Let’s move on - please!
Please as the bid moves by 10% increments in a 10% spread.
My example is a real stock market example.
The bid has to move 20% in order to make 10%. This is not fair and drives away investors to more liquid markets that when you buy a stock you are not down immediately 10%.
Move on please
Why is it so difficult for you ? You don't need a 20% increase to make a profit on a 10% spread. After 10% you will start to make money.
We are not talking about spreads on a large cap which are very tight and would typically take large volumes to move the spread. With micro-caps, only small volumes can move the spread, and so in the real world Yiannos1 is correct.
It obvious not many here use level 2, or understand it. My point wasnt so much about an exact 10 percent spread on micro-caps, it varies, but as Yiannos1 has pointed it is daylight robbery.
So now you are moving the goalposts and when you sell the spread has now become 20%.
Yes spreads do do vary. I have bought shares like Bioventix (LON:BVXP) when the quoted spread was around 10%, but I got them for 2% above the selling price.
.
If the spread is 10% when you buy and when you sell, then you only need the price to increase by 10% before you start making some profit, you don't need it to be 20% increase before you are in profit.
What are these 10% microcaps anyway. I looked at 2 yesterday, one was 5.7% and other 2.45% spread.
No need Guybrush.
I get your point and I have raised it today with an email to the FCA as it is something that concerns me as well.
If someone wants to pretend that they do not sell on the bid price ?
Bid 1.00-Ask 1.10 and I buy at 1.10
Then it moves Bid 1.10-Ask 1.20
Then the next level Bid 1.20-Ask 1.30.
Now if this 10% from 1.00 to 1.20 for Rusty let it be then!
The point is that market makers are supposed to be creating liquidity and not making money!
The point is that across the pond such daylight robbery does not exist-hence more liquidity available.
All the best
So you buy at 110p and sell at 120p, yet you say you don't make any money? 10p gain on 110p is 9.09%
There is hardly anyone buying, nearly everyone has left the small cap UK retail market, that is why often I try to trade and there are no live prices, or I can only buy and not sell or vv. Funds are having to sell shares because investors are withdrawing their money.
The bid price has to move 20% to make money unless you are a market maker.
If you buy at 110p then the bid was 100p on a 10% spread. The bid to go to 120P is 20% from the original quote.
Rusty no need to answer back.
All the best
Yes but you will have made 9%, if the bid goes up 20%.
Yes correct this is what I have been saying in my first post. Is still up there.
The bid has to move 20% to make money.
Yiannos. If your aim is to create a fog of confusion around what gain in share price is required to break even to compensate for a 10% spread, then you are doing a remarkably good job! However, those of us that rely on logic, mathematics, plain English and a clearly worked through example, know that a 10% spread requires a 10% share price rise to break even.
I didn't say that day traders are fools. On the contrary, I was day trading successfully for years. In fact it takes great skill to consistently beat the markets in this field, and one has to be constantly at the top of his or her game in the areas of reading charts, managing risk, and being mentally disciplined. The spreads are very tight in the markets I traded, mainly indices. I caught some very big moves trading the DOW.
Now contrast that to micro-caps, where one is already down ten percent from the spread on the buy, followed by another ten percent down on the sell. Not to mention all the other issues such as liquidity, and increased total wipeout risk. Careful research can mitigate some of these risks but the odds are clearly not in ones favour. But one can always rely on luck I guess.
Paul, sorry this may be a foolish question but what's your limit, mkt cap wise for micro caps
Indie
Thanks for highlighting, yes agree it’s a great post .
I would also add to that list some points about investing in UK PLC as opposed to the recent and much vaunted claims of sure fire gains in investing in US stocks .
First and foremost, I am British and I want to support the British economy so I only invest in British companies .
The urge to invest in US stocks and specifically the “big 7” many of whom have morally repugnant tax policies concerning the UK I find morally bankrupt . That’s just me but I am Black and white aspergers type brain .
I’d rather invest in a UK microcap than a tax dodging behemoth like google or Facebook , we need nurses doctors and teachers .
Have you ever received an invoice from Facebook or google ? I signed off plenty and all invoicing was done from Dublin despite the business being conducted in the UK .
There are reasons to invest in the UK , one of which we are indeed British .
Might not make any money of course but at least my son will have a teacher .
Anyway I’m a non neuro typical weirdo and I choose to do battle in the UK market .
When you and I and others here founded businesses in the UK, grew them, created jobs, trained the young, paid tax on profits, helped families (I could go on), we invested in and supported the UK economy. But when you and I buy shares in UK listed companies, we do nothing more than replace the money already invested at IPO with our own. There is no net boost to the company in question, nor to the UK. At best we offer an exit strategy to entrepreneurs who wish to loosen their grip on the reins - the very opposite of what the country needs.
So I do not buy the argument that investing in the UK is patriotic. It’s attractions consist only of being in the right time zone to react promptly to news that is delivered in my first language, for assets in my home currency, and which diversify my portfolio from the high quality, international names that typify my larger holdings, the UK representatives being less highly valued, small to midcaps.
That said, I’m all for having a set of guiding principles and no one can or should tell you how to invest your money. You only have to answer to yourself and I sense that you are happy with your discipline, whatever the rationale of your approach. The best of luck to you.
And, as an aside to your earlier post, or perhaps a warning that the curse of BnB may fall, I’m into VP and Speedy Hire recently. Estate agents and house builders are calling the bottom, while houses in my home town are getting four offers on opening day - and this was in January.
BnB
Acrually don’t fully agree with your comments.
For example I’m holding Transense and consider myself a supportive company owner to an engaged management . I’m staying just below 3% level because filling in all those RNS is a nightmare .
Due to go up there next month .
With the right company and right management supporting what they are trying to achieve is much more than offering an exit strategy to an founder / shareholder .
The Warren Buffet “owning a company” as opposing to trading a share is the subtlety that we generally forget when in the day to day stock market and looking at stock prices go up and down .
With the right company and right management supporting what they are trying to achieve is much more than offering an exit strategy to an founder / shareholder
I absolutely agree if you are taking your engagement to that level - although it is a rare board of directors that willingly accepts guidance from its minority shareholders. And I have repeatedly stated my philosophy of ownership and engagement with the journey taken by the companies I invest in. However I am prepared to rent cyclicals at what I hope turns out to be the right point in the market cycle. But these probably represent only 5% of my portfolio.
Investing in UK companies. True, private investors have little direct impact, but the effect of their collective buying can push up the share price. Obviously there are other factors as well, but a higher share price enables the company to raise cash via placements, rights issues etc to finance expansion. There is, therefore, a potential indirect benefit.
IPOs that transfer funds from investors to the former proprietors also add value - by providing entrepreneurs who set up their own businesses a potential exit route. These days, private equity can act as a go-between, but the broad thesis still applies.
Hi planetx,
Your post reminds me of a Brexit manifesto :)
Somero Enterprises (LON:SOM) that you have invested and mentioned so many times here (maybe you still are a shareholder) is not a British firm.
By Investing and making money in foreign companies you are helping the British economy more than investing in these small illiquid caps with a spread that kills probably ending losing money.
I have yesterday sold almost all my iShares Bitcoin Trust (NMQ:IBIT) and all my Celsius Holdings (NAQ:CELH) and I am definitely investing all my profits in another student property.
I do understand the comfort zone thing but making money abroad and bringing them here you will be helping the much needed British economy tremendously.
All the best
Yiannos
I’m not invested in Somero any more though I did used to hold as you correctiy ssy .
They actually had their UK operation based in Chesterfield 10 miles away, plus they paid UK taxes on UK earnings as well as being listed on the UK market.
There is also the “outflux” of cash from the UK market that everyone bemoans and then of course everyone follows suit .
UK market has sone stupidly illogically cheap businesses that I think are businesses worth owning .
I do also own bank of Georgia and Georgia capital before that gets raised .
Still think it’s ironic the outcry to an I’ll functioning market with net outflows then everyone follows the same pattern .
Also think sometimes pays to not follow the herd, we all know what happens to sheep .
And google , Facebook and Apple with their Silicon Valley robber Barron mentality are repugnant .
Ps - don’t think it had anything to do with a brexit manifesto
HSS Hire (LON:HSS) for example you have mentioned yesterday and today.
Its debt is close to its market cap. They have recently sold one of their businesses just to cut down debt. Revenues have stopped growing the last five-six years.
Where is the growth coming from?
Maybe for trading purposes this might bounce for a 10-20%-is this what you are suggesting? They might bounce.
Sanderson Design (LON:SDG) you have mentioned the other day has stopped growing its revenues-what happened to its price? It has stopped growing.
Real Madrid , Liverpool , Barcelona , Man Utd , Man City , PSG are followed by the herd but they keep winning everything over the years. They will always do.
As always all the best
Yiannos
Not entirely convinced myself that a good company you own needs to grow revenues .
I built Planet X to a yearly revenue of 15 million with 80 employees making our profit and paying our taxes and giving money to our shareholders .
A good business is a good business full stop and a real business is one that generates cash .
I quite like the fact that SDG isn’t growing , has 20 million quid in the bank, makes 10 million a year (currently on license ) and owns the William Morris archive that I consider a lovely rising tide asset.
What I also like is that I sent Lisa Montague a WhatsApp message at 7.45 this morning about a project I’m working on and she replied at 7.55.
No need to argue with me today I’m having a nice relaxing day .
was planetx a welding company
Zotefoams (LON:ZTF) , certainly one of the most confusing stocks I hold -160mil market cap, I recognise it's not huge but by no means a tiddler. Profit up 9%, comfortable balance sheet, ROCE up to 14.2%, Strong start to FY24 with Q1 sales ahead YoY, dividend increased, small upgrades to longer term forecasts for 2025, Singers upgraded price target of 500p from 480p (330p currently). This before we mention the huge potential of the ReZorce packaging, which is on the cusp, with 150k fruit juice cartons being prepares for filling for market trial, results in Q2.
Now I recognise I am shaping a bull case here, but normally you would think such a share would really grab investors attention, especially with the potential of a multibagger with ReZorce but then with the added with the comfort of a company performing well in a challenging backdrop. So far there has been about 10 trades this morning as of 8.35am, total of about 13k shares and its down 1%, with a spread of about 4% still, I just can't see why there isn't more interest here, no buyers or sellers. (I hold)
Zotefoams (LON:ZTF)
Zotefoams has had history of having good patches and not so gopod patches , perhaps the market is wary about future projections due to past issues where they have for whatever reason taken steps backwards every time they have moved forwards. Perhaps the outlook statement today has caveats that may seem to be saying yeah there are some mini headwinds coming up , perhaps continued spend on MEL takes away the attraction. Albeit they have reported good year (record profit for foams) the bottom line EPS is down year on year (due to increased taxation only i guess) - pe is 15 * here so perhaps the market is not assigning premium rating. Note this buisnes is capital intensive so they do have to work hgard to earns their wad and that can be an issue If they ever hit tough times.
Overall though IF 2024 expectatioons ref profits have not been downgraded and IF 2025 expectations ref profits HAVE been ramped upwards - slightly surprised price isnt up today. Do you know what new forecasts EPS totals are for 2024 and 2025 ?
I agree, the Zotefoams (LON:ZTF) established business isn't particularly exciting. It's capital intensive, cyclical and highly reliant on Nike. Meanwhile there's a lot of uncertainty around ReZorce:
Despite these concerns I hold largely for the reasons BenHazz outlines above, but I think its important to be aware of the bear case too
I know Graham is bullish on Trustpilot (LON:TRST) and might write up the results today. I looked at this recently but I am not convinced it's got particularly good growth. Most of the revenue increase in FY23 seems to have come from milking existing customers for more money which can only continue for so long. In these results they slightly mask new paying customer growth (which really should be a KPI stated up front) noting simply it is 26,000 (I assume rounded) without saying what the % change is.
Looking at FY22 they say they had 25k customers which had increased by 9% over the previous year. So increasing by 1k in FY23 is a 4% increase - not exactly stellar growth for a company on a p/e rating of 238 according to estimates for this financial year on Stockopedia.
We're told in today's results (which as far as I can work out is a new statement):
"Importantly, our strategy is to increase the revenue opportunity within our installed base, principally by
focusing our direct selling into the enterprise market, typified by larger deal sizes and lower churn, whilst
addressing the smaller business market via self-service channels. Therefore, we do not see growth in the
absolute number of paying customers as a critical data point per se; instead, we believe we should focus on
increasing average contract values and increasing retention over time"
That's fine but I am not sure I want to pay for a very racy p/e ratio for a company that isn't able to grow new users beyond low single digits. There will surely be a limit on how much money Trustpilot (LON:TRST) can ultimately squeeze out of existing customers and the higher its prices go the more company marketing teams may question the value of using Trustpilot.
Trustpilot (LON:TRST) - i see this is the second company in aweek capitalising sales comissions paid out on - looks like this is the new fancy thing to do for us leaning stocks.
Practicably speaking if they have previously not prepaid these costs that may flatter current numbers compared to previous as they didnt capitalise before. Over time these adjusts will likely end neutral once the charge to profit and loss equalises with capitalilastion totals. So probably most relevant in year that they fisrt turn upm (which is the case here) if this years profit totals have the benefit that was not present last year.
On the Trustpilot (LON:TRST) call, they said they'd much rather sign up one large enterprise customer than lots of SMEs so it's not a KPI they focus on.
Maybe they could separate out the size of their customers so that we can more transparently see what the growth in new customers is by customer size.
Harworth (LON:HWG)
Time constrained this morning, but Harworth (LON:HWG) prelims read very positively. given the poor climate for property related companies.
NAV increased by 4.5% to 205p versus current share price of around 134p. No financing concerns with loan to value reported at a negligible 4.7%. Clearly not a dividend share but dividend increased by 10%, it all helps. Will get to grips with the detail in the prelims later.
I have held since before the pandemic and added below 110p so hopefully patience will be rewarded.
All the best.
HSS / Speedy etc
Spent a lot of time last night looking into the current malaise concerning these specifically but also similar .
Then spoke to a few friends who develop properties and then layered on what I know from one if the businesses I own (salvaged marine lighting business) .
What is clear is in layman’s terms
- about 24 to 12 months ago everyone freaked out with inflation, raw material increases and basically a total lack of confidence so a huge number of developments and building work got mothballed . No one wanted their head above the parapet .
- hire companies etc would have gotten the brunt of this for sure
What I know is happening right now is the mood has changed and everyone is now cracking on , developers are getting back in the game and the money is starting to flow freely .
I also know this is replicated in forestry , not specifically connected but the point is funds are starting to be deployed in the economy not held .
So I’ve moved to rather positive as when I strip it right back to what I can see and feel on the ground forward looking I’m going to say we have come out of a nationwide paralysis and the entrepeneur a of the UK are going to start driving their projects forward as opposed to sitting on the sidelines taking a time out .
Gut feeling only, but my gut feelings are generally good .
Yu (LON:YU.) final results sounding v confident.
Expect to deliver organic growth of c. 50% in FY24 despite lower commodity prices
£520m contracted revenue at end of 2023 for FY24 delivery (2022: £247m for FY23), plus strong bookings momentum and further non-contracted book.
Strong profitability expecte
Very strong operational cash generation forecasted for FY24
Dividend increase
(I hold)
Liberum Yu (LON:YU.) price target raised from 1,883p to 2,050p.
They've only gone and blown the bl**dy doors off!
https://twitter.com/MylesMcNul...
Yu (LON:YU.)
Revenue up by 65% YoY, to £460m;
Fully diluted EPS up 50
7%, to 182p (consensus had been 154p - a beat of 18.2%);
Full year dividend up 1,233%, to 40p.
Liberum increases its 2024 EPS by 8.3%, to 185.8p; its DPS by 128%, to 48.9p; and its target price to £20.50.
At £13.65, using Liberum's new numbers, the shares are trading on a 2024 PER of 7.3x, an EV/EBITDA of 2.4x and yield 3.6%.
Unilever (LON:ULVR) - exciting news about separation and demerger of their ice cream business. Owner of Magnum, Ben and Jerry's and Wall's. This could be a quality new addition to the LSE in 2025 like the Haleon spin out of GSK.
On the small cap side, it would be interesting to get Graham or Paul's thoughts on Personal group (LON:PGH) and their results today. Seems to have turned the corner on its medical insurance business with annual premiums now running at c£32m (FY23 revenue £28.7m), so pretty much underwrites FY24 results growing nicely.
TMT Investments (LON:TMT) solid results. Nothing unexpected. Unlikely to move the dial much I would think. NAV about 60% above trading price with conservative valuations, but this has been the case for a while.
MPAC (LON:MPAC) - Going for Growth: FY23 results ahead on all metrics
Detailed new research report here: https://www.equitydevelopment.co.uk/research/going-for-growth-fy23-results-ahead-on-all-metrics
For the year to 31 December 2023, Mpac Group reported results which were ahead on all key metrics.
Revenue of £114.2m, +17%YoY, was 7% above ED outlook and EBITDA (adj.) of £10.7m, 12% above our outlook, a 9.4% margin (FY22: 7.0%). The closing order book of £72.5m was up 8%YoY, backed by record £118.5m order intake, an impressive +41%YoY.
Mpac achieved its initial goal of a return to normalised operations and has established a firm platform for growth. Accordingly, the Group has launched a new five-year roadmap with an ambition to broadly double revenue from their existing businesses.
We have raised our Fair Value from 485p/share to 530p/share with the prospect of FY25 adj. EBITDA c.40% above FY23.
MPAC (LON:MPAC) (I Hold) Really pleased with these numbers, so much to like.
Forecast EPS of 44p for FY25, net cash and that doesn't seem to include any upside from the Freyer battery business potential. The new CEO seems to be red hot. Looking forward to the investor presentation on Friday and hearing how they plan to double the top line from here.