Small Cap Value Report (Tue 19 Oct 2021) - D4T4, MCB, OMG, GETB

Good morning, it's Paul & Jack here with the SCVR for Tuesday. Today's report is now finished.
Agenda -
Paul's Section:
D4t4 Solutions (LON:D4T4) (I hold) - H1 trading update, which is in line with expectations, and also expected to meet FY 03/2022 expectations, with a strong pipeline. Like a lot of software companies, D4T4 looks expensive, but has healthy net cash, and interesting products with large addressable markets.
Mcbride (LON:MCB) - profit warning from this maker of householder & personal hygiene products. It's being squeezed by higher that expected cost increase, and now expects a £10m H1 loss. This is a wake-up call, that investors need to steer clear of low margin businesses with little pricing power.
Getbusy (LON:GETB) - a couple of tiny bolt-on acquisitions are announced, with deferred/performance-linked consideration. Trading update avoids mentioning whether the company is trading in line with expectations or not, but sounds reasonably OK.
Jack's Section:
Oxford Metrics (LON:OMG) - good quality scores for this motion software company. FY revenue and adjusted profit better than expected and an upcoming capital markets event will set its stall out for growth over the next five years. The shares look fully valued right now, so the group's CMD presentation will be useful in assessing how much of an opportunity remains.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to cover trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul’s Section:
D4t4 Solutions (LON:D4T4) (I hold)
355p (pre market open) - mkt cap £143m
D4t4 Solutions Plc (AIM: D4t4, "the Group", "D4t4"), the AIM-listed data solutions provider, provides the following trading update for the six months to 30 September 2021.
Trading Update, CEO succession, and Notice of half-year results
It’s in line with expectations, so this update shouldn’t move the share price much, if at all -

.
“High levels of interest” in new Fraud Data Platform software
Acquisition of Prickly Cactus going well
Further enhancements made to CDP software
Continued sales & marketing push (extra costs) which has been flagged before
New contract wins mentioned briefly
Planned CEO changeover is effective from today
Diary date - 1 Dec 2021, for interims to 9/2021
Outlook - sounds fine to me -
The board remains confident in delivering a solid full year FY22, in line with management expectations. Prospects for H2 are strongly underpinned by a significant pipeline of new business from existing clients wishing either to increase the footprint of the Celebrus CDP software or to extend the use of the Celebrus hybrid CDM platform solution, as well as from new customer opportunities for both CDP and FDP products…
"We remain confident about our prospects for the full year. We have strong visibility for H2, with several new contracts in the final stages of negotiation and are building a strong pipeline for our newly launched FDP as well."
My opinion - no surprises here, it all sounds OK.
It certainly isn’t a value share, with Stockopedia showing the forward PER as 43.8 times. Hence investors are clearly assuming the company has scope to beat forecasts. Software companies often attract premium ratings at the moment.
The reason I hold D4T4 shares is because of the growth potential in very interesting markets, which could scale up considerably if they execute well.
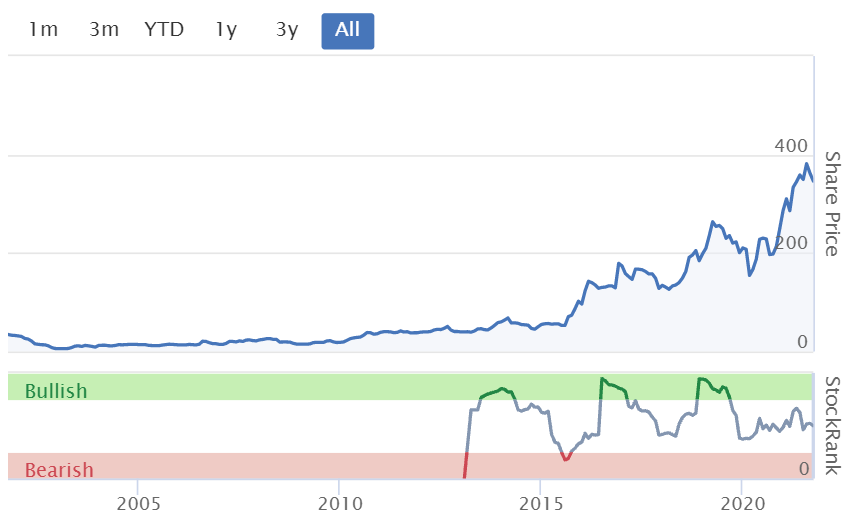
The long-term chart below is interesting, as something happened in 2015 to put a rocket under it. As you can see, D4T4 has been a serious multibagger over the last 20 years. It used to be called IS Solutions, but changed its name to D4T4 in July 2016, presumably to prevent any confusion with terrorist groups?
.
Mcbride (LON:MCB)
69.4p (pre market open) - mkt cap £122m
Trading Update (profit warning)
McBride plc (the "Group"), the leading European manufacturer and supplier of private label and contract manufactured products for the domestic household and professional cleaning and hygiene markets, provides the following trading update ahead of its 2021 Annual General Meeting later today.
Input cost inflation continues to rise
Global supply chain issues worsen
Shareholders in McBride will have already assumed the brace position - the only question is how much will the shares fall today?
Here’s the update in full, as it’s all relevant -
Since providing the Company's outlook for the current financial year on 9 September 2021, global supply chains have continued to tighten. Raw material and packaging costs have moved faster and to a higher level than previously expected. In addition, the shortage of haulage capacity and higher fuel costs has continued to substantially inflate distribution costs - again ahead of the Board's expectations - which show no sign of abating in the near term.
As a result, the Group has begun to seek a second round of substantial price increases from all its customers across all divisions, which, dependent upon specific mix, could result in a minimum of mid to high teen percentage increases.
The Group's manufacturing facilities and logistics activities have operated well in the period and have shown strong resilience despite all these uncertainties and supply chain disruptions and have worked tirelessly to maintain the best possible customer service. It is pleasing to report that coronavirus restrictions at our Asia operations have recently been lifted and our new facility in Malaysia is ramping up production.
As previously indicated, earnings for FY22 are expected to be weighted to the second half of the financial year, but now with the first half expected to deliver a loss of up to £10m at the EBITA level. Given the unpredictability of current global supply chain and ongoing uncertainty over input costs, the Board is unable to update the full year outlook it provided in its preliminary results on 9 September 2021.
That’s clearly a bad situation. Last year’s H1 results showed £363m revenues, and adj profit before tax of £16.9m. That’s all been wiped out, and a £10m loss this year (at EBITA, i.e. operating profit level) is a serious deterioration.
It’s a pity, because McBride had previously been through restructuring, cost-cutting, and was showing promising signs.
My opinion - this is a stark reminder of how low margin companies which lack pricing power, are probably the worst place to be invested right now, with costs rising sharply, and a time lag in passing those on.
We probably all need to review our portfolios for similar things which might also be facing the same cost pressures.
It all hinges on how much, and how quickly, McBride can pass on the price rises to customers - many of which are supermarkets, and hence notoriously difficult to force through price rises.
That said, McBride’s competitors will be facing all the same cost increases, so I doubt whether customers could switch to other suppliers for cheaper product.
Investors should also think about the potential risk from breaching bank covenants, as MCB had a fair bit of bank debt, when last reporting numbers.
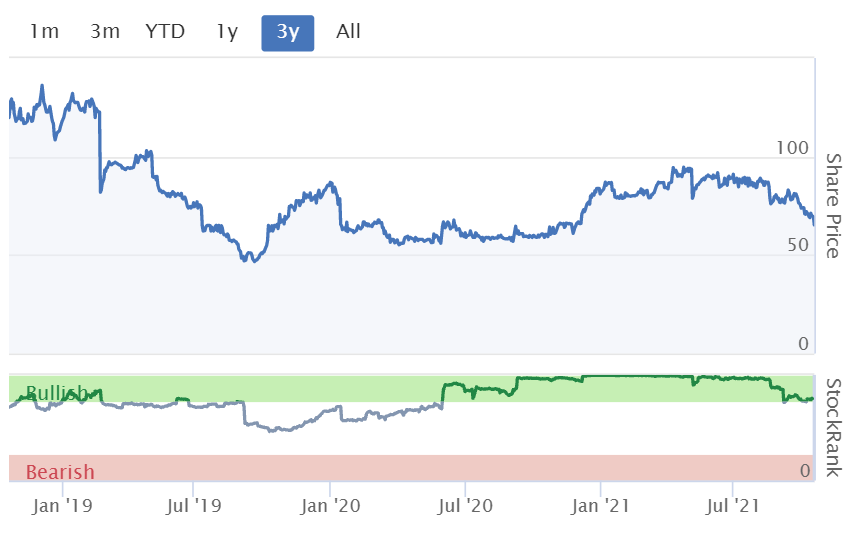
EDIT - I'm very surprised the share price has only fallen 6% today, to 65p. I was expecting a very much larger drop (to c.50p) on what is a grim trading update. Maybe investors had already taken into account supply chain problems & inflation, to some extent?
.
Getbusy (LON:GETB)
67p (up 1% at 10:04) - mkt cap £34m
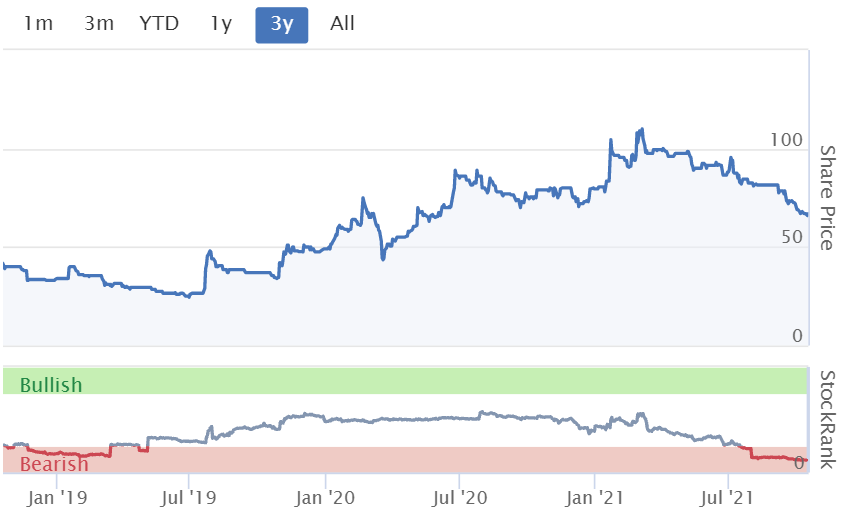
To recap, here are my notes from the last interim results, published on 30 July 2021. There wasn’t anything particularly exciting in those numbers - GETB has a profitable established software business, which is part-funding startups, which have so far not really gained much commercial traction. The share price has continued falling, and is now a long way off the everything rally peak in the spring of this year.
Trading Update & Bolt-on Acquisitions
Trading Update -
Trading has remained robust since the half-year, with progress made in all elements of the Group's strategy. The recurring revenue growth rate from H1 (12% at constant currency) has been sustained in Q3, and net cash at 30 September 2021 was up £0.3m at £2.3m. The Board looks forward to the final quarter of 2021 and into 2022 with increasing confidence.
Trading updates are supposed to tell investors how the company is performing versus market expectations. That question is dodged by today’s update, so we’re left to assume that it must be trading in line with expectations. Not directly saying so, just leads to investors asking questions, and wondering if maybe the company isn’t confident enough to say it’s meeting market expectations? So a bit of an own goal here.
Acquisitions -
GetBusy plc (AIM: GETB), a leader in productivity software for professionals and financial services, is pleased to provide an update on trading and announce the completion of two bolt-on technology acquisitions within SmartVault, DocDown and Quoters.
This is what the acquired companies do, which seems a good fit with GETB’s existing operations -
Quoters (www.quoters.io) automates proposals and quotes, simplifying a core part of the client workflow for accountants and financial services professionals. DocDown (www.docdown.io) uses online web forms, web hooks and APIs to automate the population of forms and templates, removing the need for error-prone manual transfer of information.
GETB says the terms are attractive, being weighted to future performance (good job, as GETB doesn’t have the balance sheet strength to be making significant acquisitions from existing resources).
Financial details - these are such small deals, there’s not much point in spending any more time on it -
GetBusy is paying a non-material amount of upfront cash for each asset, with a cash earn-out payment in early 2023 of 1x annualised recurring revenue ("ARR") from the acquired products as at 31 December 2022. The respective earn-out payments are capped at US$0.5m each, with the total potential consideration being funded from the Company's existing cash resources and such that neither acquisition constitutes a substantial transaction pursuant to AIM Rule 12.
My opinion - I like this share a lot more, now its market cap has reduced to a more realistic £34m. At that level, there could be speculative upside, if growth were to accelerate. I’ll keep it on my watchlist, but can’t see any burning need to buy any yet.
.
.
Jack’s section
Oxford Metrics (LON:OMG)
Share price: 111.71p (+1.1%)
Shares in issue: 126,937,668
Market cap: £141.8m
Oxford Metrics provides software for infrastructure asset management and motion measurement. It does this through two divisions.
Yotta has been operating in infrastructure asset management since 2006, enabling clients to make better, more informed decisions about the way they manage their assets. Clients include central and local government and other infrastructure owners working in highways, street lighting, street works, waste and utilities.
For over 35 years’ Vicon has been the world leader in high precision movement analysis, supplying motion measurement systems ‘for an astonishing range of applications from analysing the gait of a child with cerebral palsy, examining an athlete’s performance, to creating visual effects in Hollywood blockbusters’.
Clients are diverse and include highways authorities, hospitals and clinicians, and Hollywood studios.
It’s a software company that has been around for a while, boasting a Quality Rank of 84, strong cash generation characteristics, and a net cash position - so you’d hope we are on safer ground here.
One of the first things that jumps out is a lack of real revenue growth over time, although Covid may have temporarily obscured a more positive recent trend here.

The forecast PEG is just 0.8x, although this reflects a return to historical levels of earnings per share after Covid disruption, rather than new highs.

The group expects to report revenues of approximately £35.7m and an adjusted profit before tax (after adding back non-cash items like share based payments, amortisation and impairment of intangibles and one-off exceptional costs) of approximately £4.6m for the financial year.
This is better than the consensus noted on Stockopedia of FY21 revenue of £32.7m, due to a good performance across both divisions. Vicon experienced growing demand during the second half and has had ‘a very profitable year’ with a solid order-book. Yotta achieved its ARR year-end goal and is also expected to deliver a full year of profitability.
As in many industries, Vicon is currently experiencing some short-term supply chain challenges arising from the well-publicised global semiconductor shortage. This may impact revenues in the first half of the next financial year but, longer term, Vicon ‘is very well placed to capitalise on the substantial market opportunity’.
Yotta is expected to achieve continued growth in ARR and improve profitability further.
The net cash position has increased to £23.0m, with no debt. The group as a whole, remains in a robust financial position which enables the business to pursue its internal investment and M&A objectives in the year ahead.
Oxford Metrics will announce preliminary results for the financial year on Thursday, 2 December 2021.
The group is also holding a Capital Markets Day and five-year growth strategy update today:
It is the Group's view that the strength of its current platform, combined with the strong financial footing it has achieved over the past five years of organic and inorganic revenue growth, provide it with routes to capitalise on latent opportunities for growth.
Conclusion
Circling back to that cash generation, note how the trailing twelve month price to free cash flow of 20.2x is much better than the forecast PER of 36.2x. FY20 did seem to be a particularly cash generative year, however, so it’s uncertain how sustainable that level is going forwards.

Oxford Metrics believes it can significantly increase its Total Addressable Market (TAM) over the next five years. The materials from its capital markets day will be published on its website.
The group has been solidly cash generative for a long time now, with increasing payments to shareholders and a few special dividends. It also has deep experience in its markets, so there’s a good foundation for future growth.

But there does need to be growth at the current levels. The valuation is quite high and the shares have rerated from the Covid lows.

It’s certainly worth revisiting once the capital markets day presentations are up, to assess the group’s prospects in more detail, as there are signs of quality here. It just needs to be coupled with a suitable, sustainable growth opportunity.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

94 comments
The energy and 'renewables' debate is mainly irrational and a source of problems. As its currently performed it risks doing more environmental harm than good.
Earth -> energy -> social constructs -> markets -> affluence and 'freedom'
I believe that Biophysical Economics is the key perspective for humanity -> understanding the whole system we inhabit. No-one comes close to this in the policy sphere...least so the whack job green movement where fantasy and idiocy are a sign of intelligence. Its a movement that will cause more environmental harm thro its ignorance and indifference on how society works. Why? Energy crisis will cause energy desperation which will cause rapid environmental destruction.
The key concept is energy return on investment (EROI). This is a ratio of how much energy use we get from each unit of energy input. The central factor that drives our economy which we never model or truly price. It is estimated that EROI needs to be >10 for us to maintain society.
I believe the work of Charles Hall (eg Energy and the Wealth of Nations) and a few other Biophysical Economists is the base we need to work from. I think Hall may be a bit pessimistic or eccentric at points, nevertheless is good (essential IMO!).
Here is a recent podcast by Hall laying out some views. It is 50 mins well spent re-orientating oneself:
https://www.podbean.com/ew/pb-...
Heat pumps are probably a relatively good step in EROI terms, tho I do not now the full energy economics of them which includes the resources used to build and maintain them and obvs need to have a good source of electricity too...note, solar and wind are not the spine for our electricity system.
I'm pro nuclear as I see it as the only energy source that can drive sustainably high EROI that supports our affluent society. There has been a lack of investment and innovation in nuke due to political opposition for decades (initially funded significantly by old USSR to undermine western nuke industry). There is much gains to be had from innovation to improve the EROI well above the crucial 10:1 level. Financial costs can be reduced drastically too as much of the regulatory oversight and objections are not aligned to modern nuke capabilities
I'm pro nuclear as I see it as the only energy source that can drive sustainably high EROI that supports our affluent society.
Fair enough, I personally think the big nuclear reactor at the centre of the solar system that gives us all free energy all day every day is the better energy source. We just need to capture and store it better. But hey ho.
So how do you make the energy and resource economics of solar work? Use the UK as an example and explain how solar can drive a 24/7 society like UK (which is fairly low industrial intensity...so not even needing to get to German or Chinese level). Or are you one of the people (majority so don't take it personally) that thinks energy is a meme to vibe into being? In the past I would be agitated by the inane ignorance of renewable cheerleaders but now I just view it as a really bad joke telling. Either we are rational and plan to avoid an acute crisis or we let the crisis dictate and cajole us to rational behaviour.
No one suggests that solar on it's own can provide a complete solution. But combined with storage, other renewables (wind tide etc) and some back up in the short term from gas, and a contribution from nuclear, there are possibly workable solutions. And those can be combined with measures to reduce overall energy use (insulation, more efficent/less transport use etc), But it's not going to be pain free, just less so than the alternatives.
This is a fantastical view sadly and talks to how we don't think about the total system. How much energy and resource does it take to produce and maintain the 'renewables' system when it dominates energy supply?
It seems that people disengage critical thought just as the term 'renewable' has been uttered. Both directly and indirectly renewables are subsidised by our current dominant energy source -> hydrocarbons. This is for many reasons with how China uses cheap coal to drive down costs for solar so it can be global leader the best known critique. But much less thought about is an energy balance issue. If we move from the current 10% renewables/90% hydrocarbon (and this is deliberately round number that overstates renewables and just throws nuke in with hydrocarbons for simplicity) to the other way round then renewables are the energy source funding new energy production required to maintain system energy and do all the things we need. That means renewables build the houses and bridges etc...no more 'subsidy' from bad hydrocarbon. This balance problem is little understood and whilst energy efficiency, new materials and recycling are necessary and good they are not enough.
I wish for a greener world but I can't indulge in fantasy. Much may change over say 50-100 years but right now we need a lot of nuke, a heap of work on carbon capture and a lot of investment in new hydrocarbon production to keep the price down of energy down to avoid a future existential societal crisis.
It's not hard to find studies that show wind having as good or better EROI than nuclear. Granted the confidence limits for both are wide, some studies suggesting nuclear is well below 10, others that it does better than wind. However, I'm not going to pursue this further here. It's perfectly clear that we have to take major action or the end costs are far worse. And as I argued earlier, there isn't a single solution. Cutting energy use is critical, and a mix of existing and developing technologies to provide future needs.
What nobody seems to be talking about is the pollution created by the global society, where no country is self sufficient any more. Why does the UK need to import apples from Chile for example, is that not something we can grow here? All the lorries coming in from the continent as is evident when you drive on the motorway towards Felixstowe or Dover, is all of this really necessary? I would say not, but there seems to be no will to even discuss becoming more self sufficient to stop this insane movement of goods around the planet. It seems easier to blame the private motorist for it all and extort money, which will not even go towards any mitigation but join the general pot.
I didn't say solar.
Also, I never said anything about creating a crisis, I offered no time frames.
There's a whole range of ways the sun's energy can be harnessed. "Fossil" fuels being one of them. Poor little angry man shouting at the internet again.
Cheers IGPJ...once again you say absolutely zero whilst trying to strike a pose of informed by speaking in a vague way...vogue on dude.
I'll skip out of dialogue with you now as I have assessed you to be a bit silly and unable to personally collate things into sense.
Seek help
Ciao
Sure, the planet literally runs on the energy created by the sun, every last living cell, the ocean and air currents - there's so much energy beating down on deserts they can't sustain life. You saw the line "big nuclear reactor" and could only come up with "solar", that's how little critical thought you gave it, whilst chastising others for not thinking critically.
We're already looking to get home batteries cheap enough to make so you can run a house for three of four days and arbitrage between cheap grid and expensive grid prices
But Mojo says it can't be done and we needs lots of little suns to provide our energy.
The unit cost of electricity went negative last night because there was so much wind, but nope, it's not worth investing in storage techniques because Mojo has said they won't be good enough for 50 -100 years.
At least I only used four lines to say nothing.
Re discussions re Air/Ground pumps - these are tangential to most of our investing discussions but as a strong 'green' supporter and activist as well as investor, I am dismayed at the economically illiterate and inefficient approach being taken by Govt.
It is going to undermine the strong, positive economic case for other green actions where the payback is <10years (& thus better than nearly all private investment) and already available.
First, energy efficiency is once again largely ignored. We could have taxes/regulations than incentivised efficiency. Some as low cost as clear communication of the COST in £s of say 100hours of use of appliances at a standard /watt cost vs relative . Laws could mandate year on year efficiency gains – as was done on cars in places - and leverage the creativity of business when given a steady regulatory regime.
Secondly, heat pumps are a poor solution even long term for many flats/terraces/city homes – why pin so much on an unproven tech. Other distributed technologies like solar (and especially solar + battery) are already proven on 1mn+ roofs in UK and getting cheaper. They avoid distribution losses and increase energy security. Incentivise their take up now vs having heat pumps as an 'ambition' in 10 years.
Finally, even if there is a long term on-cost for green measures, the case for an insurance premium to avoid the worst of global warming must merit more aggressive action than we see. If there is even a 1% chance of a humanity-ending environmental catastrophe in 50 years, we should be prepared to pay a high price now.
A responsible MD/Finance Director of an established firm certainly would.
Hi Zipmanpeter, you make a lot of good points in your post. However, there are many things to bear in mind and which I will do my best to answer them before I sign off for the day. Like I said previously there isn't enough room on this forum to discuss ASHP in detail. There is a lot more involved to installing an ASHP compared to installing a gas boiler, there are both positives and negatives, the obvious negative being cost.
I have previously been informed that the gas fields in the north sea are about 40% dry and they will be 100% dry within the next 7 years unless some new gas fields are discovered and tapped into. Moving over to Heat Pumps to heat our homes gives the UK better energy security because we don't have to rely on Putin for gas to heat our properties. You many remember many years ago Putin turned off the gas supply to Ukraine (I call it tap off-ski)!! because it owed Russia somewhere in the region of $2billion. After something like 2 days without gas, Ukraine very quickly paid its gas bill. Europe and the UK are on that gas pipe line, in fact the UK is at the very end of that gas supply pipe. Moving to renewable energy reduces the UKs reliance on gas. By having our own gas reserves in the north sea in some way partially helps to insulate the UK from the full price rises in gas. However, once the north sea runs 100% dry, the UK will then become 100% dependent on the world market for all its gas and it will have no option but to pay whatever is the world market price. Moving away from gas (as well as coal and oil) powered electricity power stations and onto carbon neutral electricity power stations such as renewable and nuclear is the future because if the UK does run out of gas to both heat our homes and to generate electricity, then obviously there will be power cuts and then nobodies gas central heating and hot water will work (unless you have an offgrid solar system and batteries) because you need electricity to power the electric central heating pump, ignite the gas and control the thermostat. The only things that will work in a power cut are a coal fire and log fire (which is carbon neutral) to heat your home and heat your water for a good old brew!! Thankfully I have both my own solar system and log fire.
You mention that Heat Pumps are an unproven technology but it may surprise you but ASHPs have been around much longer than solar & the F.I.T . Also, they are a proven and mature technology and their design has been improved upon over the decades which is one reason why they are typically between 300- 400% efficient. Mitsubishi's ASHP manufacturing plant is located in Scotland and its biggest customers are the nordic countries (where it gets much colder than the UK). The UK is unique in that 98% of its homes are heated by gas, no other country has such a high percentage of houses heated by gas. Other countries have a mixture of ASHP and gas but no where near 98% on gas.
The best action to take initially is to insulate all our homes as much as possible so that we use less energy in the first place to heat them, before moving onto heating solutions.
David.
"The UK is unique in that 98% of its homes are heated by gas"
I don't think that can be correct. When I was looking to move to Suffolk I was surprised how many areas did not have gas. Even parts of central Essex are not on mains gas. Looking at the map, even in parts of central London, many homes are not on gas.
Figures I have seen are around 85% of homes have gas.
"The UK is unique in that 98% of its homes are heated by gas"
I don't think that can be correct. When I was looking to move to Suffolk I was surprised how many areas did not have gas. Even parts of central Essex are not on mains gas. Other areas I have stayed in were not on mains gas either, such as Derbyshire and Wales.
Figures I have seen are around 85% of homes have gas.
I agree homes should insulated as much as possible but it's not always that easy. Even if you have cavity walls, retro fitting cavity wall insulation can cause problems. Solid floors will have to dug up to fit insulation or the floors be raised. Solid walls will either have to have insulation fitted inside which will lose space or fit cladding on the outside.
I will investigate cavity wall insulation again for my house.
I share your concern, Peter the Zip.
However, as someone who is doing a house renovation and extension, I was struck at just how much has changed in the regulations so that if you are doing a substantial amount of renovation, e.g. a new roof, or building an extension, then there is a lot to take account of to comply with part L1b of the building regulations. So, there are regulations there for existing houses.
When it came to putting in the solar panels, I also discovered that the VAT reduction for doing so is some encouragement but also it has encouraged me to put in a battery too to take advantage of the VAT reduction on that. So, there’s tax incentive there.
And of course, here in London Town, the ULEZ scheme for vehicles is being extended out to the North and South Circular. So, more incentives there. Plus, aren’t there incentives for company cars to be EVs too?
I guess that the point is that, yes absolutely we need to do more and go faster, and yes I would up the financial incentives to export electricity to the grid to encourage more solar panels but let’s also praise the good stuff that’s been done and is being done.
Graham F - I accept your point about needing to praise progress. The tide is now clearly moving in a positive direction. For instance, setting a time limit on both net Zero and ICE car phase outs has massively increased business confidence to invest and innovate towards this end. I also think really dull, quiet changes like requiring appliances to have genuinely accessible parts for repair will make a difference long term and they are many more and larger projects (and further cause me to drift from SCVR territory - memo to self, avoiding rising to off-topic bait!).
However, I think it is fair to focus on the decisions being made now and challenge the speed. (More) new well flagged housing regulations come in from 2025 - if they came in 2 years sooner, that's 500,000 better insulated houses that wont need expensively refitting in 2035. I trust business to make incredible adjustments when given clear, steady plans to work against. But almost everyone (often for very different reasons) does not believe the govt's now "ambition" re heat pumps - perhaps a Ministerial 'clawback if announced targets not met is required!
So much fruit is low hanging and just needs clear vision and good execution. Without being party political, I would say the current executive would be replaced if PE bought UK inc !!
Anyway, headdown and back to investing for a while methinks.
Hello Paul.
Re the £D4TA name change in 2016, at about the same time, the company which managed the Baronsmead VCTs changed its name from Isis to Living Bridge for the same reason.
Steve
I said last week that I had placed a Shein order out of curiosity and some people asked me to provide an update so this is my experience:
The order was placed on Oct 7th with estimated delivery for Oct 20th to 22nd.
It shipped in two parcels. The first arrived via Hermes on October 12th and the second by Royal Mail on October 18th.
The first parcel contained some pajamas. The top was good quality cotton, the pants nasty viscose so they had to go back. But Shein ask for all returns to go in one parcel to qualify for free return shipping so they had to wait - fair enough.
The second parcel had a polo shirt made from laughably thin material – the like of which I have not seen before. So that’s rejected too. And some socks which are actually quite good and fit well which is lucky because they are non-returnable.
So to the returns process. It could definitely be easier. Lots of hassle getting a label printed which the Hermes drop off could read. 50/50 fault shared between Shein and the unhelpful Hermes drop-off chap. I should have used the Royal Mail returns option.
My conclusions? Clearly I’m not a target Shein customer and won’t be troubling them again - assuming my refund arrives that is.
The property giant JLL predicts that the proportion of flexible workspaces will increase from 5% to in excess of 20% of the total global office estate. Carrying out the technology conversion which supports this change is incredibly complicated and Essensys is actually the world leader. Not only does the niche itself promote the development of a moat but the software is incredibly sticky.
D4T4, on the other hand, it’s just one of thousands of data analysis businesses. It might turn out to be more profitable than the former. It might be a better investment. But it is unlikely to build a moat anything like as strong. D4T4 is riding a powerful trend, but Essensys is actually forging one.
Essensys is on my watchlist so I’m hoping the Stocko experts can take a look.
Hi BnB,
I've had a quick look at the results from Essensys (LON:ESYS) but didn't feel there was much for me to report on. It's got a sky high valuation, £173m, for a small, loss-making company.
Revenue for FY 7/2021 fell by 2% to £22m.
It made a loss before tax of £(2.9)m, much worse than the prior year's profit of £0.3m, which they say is due to increased "investment" - i.e. higher costs.
Capitalised development spend was £2.5m in the year, hence EBITDA profit is not real.
Balance sheet - fantastic, following an equity raise to accelerate growth, includes £36.9m in cash.
Based on the above, and the historical track record, the value in investor in me would value this share at very little - there's no cashflow, no earnings, no divis, nothing apart from a recently raised cash pile which may be depleted driving growth (with higher overheads).
But, before you go into a rage at me, this is clearly not a value share! The company has ambitious growth plans -
"Growth targets
As announced at the time of our fundraising in July 2021, we have set an internal target for 2025 of ARR of £68 million, equalling approximately 8%. market share and representing an increase of £22 million against existing targets, growing to £100 million ARR in 2026.
essensys' longer-term plan is to increase its market share by 10% from current levels. If achieved, this would result in a market share across North America, Asia Pacific and the United Kingdom and Europe of 18%, 10% and 22% respectively, and an overall market share of 17% by 2030."
If it can succeed with those targets, then I can see why the valuation would be justified.
So this share is really all about doing proper research on the software itself, and looking at competitors (there must be loads out there, including cobbled together ways of doing things with a mixture of spreadsheets, etc). If, after doing your research, you think Essensys is a long-term winner, then let us know!
Personally, I'd want to see stronger reported growth, rather than just aspirations for growth, so at this stage Essensys doesn't interest me - it's too jam tomorrow. There are so many jam tomorrow companies out there, claiming that they're going to achieve global dominance in some niche, but hardly any of them actually succeed. That's why I'm sceptical of big growth plans, until companies can actually demonstrate in the numbers that the growth is actually happening. Essensys isn't there yet.
Regards, Paul.
Thanks Paul. I did recognise it’s not your usual area of interest.
To understand the complexity of the software, it’s not about a simple back office for landlords, instead imagine a network infrastructure that has to support multiple clients and users all using the same ports and floor space but expecting a seamless experience which isolates them securely from the building’s other clients. And a billing system that captures every network transaction. Spreadsheets won’t cut it!
A speculative investment nonetheless.
Hi BnB,
Thanks Paul. I did recognise it’s not your usual area of interest.
To understand the complexity of the software, it’s not about a simple back office for landlords, instead imagine a network infrastructure that has to support multiple clients and users all using the same ports and floor space but expecting a seamless experience which isolates them securely from the building’s other clients. And a billing system that captures every network transaction. Spreadsheets won’t cut it!
A speculative investment nonetheless.
Thanks for this, and also thanks for not attacking me! Although we're value investors at heart, here at the SCVR, we also like convincing, reasonably priced growth shares. So I'm very receptive to good ideas for companies that are about to take off & deliver stellar growth. I just don't like paying up-front, for growth that often turns out to be elusive.
Essensys does sound potentially interesting though, so thanks for flagging it, and we'll keep it on the watch list. Once growth really kicks in, that's when I'll be more interested. No sign of that yet, in the reported numbers. As you say, still speculative.
Best wishes, Paul.
Thanks again. I really appreciate the efforts you made today.
Not at all, thanks for flagging it! We love new ideas.
Hi BnB
I hold Essensys (LON:ESYS) , but after today's update I remain in two minds about whether to sell.
My main gripes from today's results:
I wondered whether it might be a dilutive affect from so many new Connect Sites, but this doesn't make sense as the ARR is extrapolated from the last month of the period only.
As far as I'm aware there are loads of companies like Essensys (LON:ESYS) out there - it's a fragmented market (unless I'm googling the wrong thing) - so this is a concern if the strategy is a loss-making land grab.
The company has a 30 day payment limit.
I question why this is being allowed.
The company says this is for growth in APAC, which could well be fine though my notes say an office was opened in Germany in 2019 and nothing has happened there as far as I can see.
If 1 of these:
then this is a big concern.
For balance some positives I noted:
The number of Connect Sites has grown from 199 to 286 in the last 18 months...ie throughout all the madness.
US revenue increased by 20% from H1 to H2, and this would have been higher at CCY.
This is excellent and keeps me interested.
---
I think the issue for me is not whether the company will grow into its valuation, because I think it will, but how long it will take to do so.
Given these results, I'm more inclined to believe things will take longer than I expected, which is why I am more inclined to sell right now.
But then there's the US growth, which of course makes things more interesting. I do wonder if growth here will now accelerate even more.
There will be a presentation tomorrow, so I will listen to that and then make a decision afterwards.
Cheers
A
Thanks Abtan. Incredibly helpful. The delinquency numbers are pretty horrifying - although we can all understand how tough it has been for landlords.
Market has shrugged off the report as a non-event so it must be seeing the same balance of good and bad as you are. Hopefully tomorrow's presentation will be enlightening.
Any reason why £ Morses Club (LON:MCL) is dropping like a stone at the moment?
Surprised to see drop in Tekcapital (LON:TEK) today given the 2 RNSs - likely US IPO of Lucyd . (I hold - thanks to Stockslam.)
Tekcapital (LON:TEK) I hold also. A bit of a roller coaster lately, shares down 20% and then up 40%.
Maybe it's sell on news?
Hi Roger
Ref Tekcapital (LON:TEK) 2 RNSs this morning about US IPO Lucyd.
Yesterday I looked at their other recent IPO onto AIM of Belluscura (LON:BELL) . I believe IPO price was 45p, price this morning is 92.66p. Tekcapital (LON:TEK) holds 15% of Belluscura (LON:BELL), so that almost 106% gain fell directly onto Tekcapital (LON:TEK) s NAV. But as you see from Belluscura (LON:BELL) s chart (below) it is quite bouncy so I perceive a noticeable drop on Belluscura (LON:BELL) s SP might flow through to Tekcapital (LON:TEK) just as a nice rise might.
I also hope that the US Lucyd IPO might also have a positive gain to its IPO price (whatever that might be) and thus lift Tekcapital (LON:TEK) s NAV further (in the future).
I sense Tekcapital (LON:TEK) s SP will always be volatile within quite a wide range, but with its 55% services revenues then with added revenues and gains from its portfolio activities an investor seems to have quite a bit of inherent diversification if they can tolerate the bounces.
Further, what I find interesting is investing in Tekcapital (LON:TEK) gains a direct diversification into the US market. First, as they list there as well. Second, as their portfolio companies trade in US as do their portfolio trading activities.
I have recently started a small position, so many thanks for yours, and others, comments in the recent SCVR. I watched Tekcapital (LON:TEK) for quite a while as it aligns to one of my investing themes .. 'invest in the investors'. On this theme I hold several such as Draper Esprit (LON:GROW) , Ip (LON:IPO) , Augmentum Fintech (LON:AUGM) several ITs, some VC and PE trusts as well. Tekcapital (LON:TEK) fits in nicely I think.
Regards
Howard
Tekcapital (LON:TEK) : "Lucyd's U.S. operating subsidiary, Innovative Eyewear, Inc., has closed its crowdfund raising approximately US$154,000. Innovative Eyewear Inc. ended the offering early as they believe the company has made substantial progress since the crowdfund began."
So way off the $500k target, and a BS reason thrown in our eyes. Simon Thompson retipped it last week so maybe some sell off from that as well.
This is a bit off topic but Norbert Lou of Punchcard Capital increased his holdings in Naked Wines (LON:WINE)
If you haven't heard of Norbert he is worth researching and following.
I would take this as a rather strong buy signal.
Re Naked Wines (LON:WINE) it does look as if Norbert Lou may have successfully bought the dip - or maybe he has bought enough to make a new base. I'm a Wine Society member and their recent communications have been saying how much more wine they have been selling and how as a co-operative they are able to pass on price reductions to members through their greater buying power.
So that makes me think the whole mail order wine sector continues to do well and I have bought a starter position in WINE.
Heat pumps Maybe a help to Sureserve (LON:SUR) price
Not suitable for many older properties and are at their most efficient when the temperatures are warm, when freezing cold they are less efficient. Even in some modern homes there are complaints they don't provide enough heat.
They are expensive and this ruling does not come in until 2035. Also you will probably have to change your radiators to much larger ones or convert to underfloor heating, again more expense. I think there will be quite a lot of resistance to this. Gas boilers can be more efficient than heat pumps it has been found.
They are also not very flexible, gas you can just turn up on demand.
The expense is usually understated as it hardly ever mentions the installation costs (especially of a ground sourced heat pump) and external repairs and re-decoration necessary as a result of installation.
Given that heat pumps (especially air sourced pumps) are inefficient in cold temperatures why would anyone want to spend £5000+ (net of £5000 grant) on buying an inferior product. It's just bonkers economics.
Exactly.
I don't understand why we are aiming to go' net zero' when we are supposedly only producing 1% of the world's pollution? Surely, it is unlikely to make a difference when you factor in the major polluters such as China, India and Russia et al.
It will definitely have a marked effect on the population's bank balances though.
Boris seems 'hell bent' on having this as his legacy, despite the vast majority of the electorate being against it.
As you point out, why would anyone wish to replace a system with an inferior one at a greater cost , it just doesn't make any sense?
I think we should all be contributing, yes we are only a small proportion but it still counts. China and the USA are the biggest polluters by far. The USA could easily switch to more renewables such as solar, there is loads of space and plenty of sunshine in some states.
Depends on how you define "cost" I guess but your response does suggest there will be a need for Governments to show leadership and restructure financial incentives. away current ones.
I don't understand why we are aiming to go' net zero' when we are supposedly only producing 1% of the world's pollution?
The hope is that everyone will go to net zero. If everyone takes the view "we only contribute a small part" and does nothing then we're all screwed. We have to start somewhere, and many have, but the rate of progress is too slow at the moment. The world needs to act unless we want to see mass migrations on a scale Patel can't imagine, mass starvation and significantly heavily populated parts of the country, London included, under water.
None of that may matter much to people in my age group, but I don't want that for my son or grandchildren.
The hope is that everyone will go to net zero. If everyone takes the view "we only contribute a small part" and does nothing then we're all screwed. We have to start somewhere, and many have, but the rate of progress is too slow at the moment
We also need to take into account that we export a lot of our carbon production - something like 30% of China's output is to serve the export market. Plus there's the historical context - the UK is the 5th largest polluter in history. Without that legacy we wouldn't have the same global problems we have now.
It's important to keep it in context but if the UK, as one of the world's greatest historical polluters, isn't willing to shoulder its part of the burden then we can't really expect the likes of China and India to take much notice of us. And if they don't then it's going to be a pretty miserable world for our descendents.
timarr
It is also worth remembering that although the the UK is a small contributor now, we are responsible for a huge amount of the historic CO2 emissions, as we (the UK) were the first to industralise and hence have a responsibility for much of excess CO2 which is currently in the atmosphere.
Whilst I do believe we need to decarbonise our heating sources as quickly as possible, I do share some of the concerns about air source heat pumps, and how feasible they are for some kinds of buildings. I live up in Glasgow, and am really not sure how you could fit them to tenements (4 story stone buildings), or if they are up to the job of heating in our cold winters. I do take this seriously, and spent a lot of money reducing the energy consumption of our tenement flat when we moved in and renovated, but am struggling to see what more can be done, unless we have external cladding applied to the whole street, which is hard to do, given the shape and the detail of the stonework. This may turn out to the best and cheapest option however, and is being done for a lot of the social housing.
The real issue to my mind, is energy efficiency and we desperately need to to reduce the amount of energy leakage from our exisiting housing stock, and go to passive house standard for all new builds. If the currently governing party had not scrapped the 'Zero Carbon Policy' standard, we would have been doing this for the last five years for new builds, instead we have knee jerk actions, that are not properly thought through.
Costs can be considerably more, on the local news someone has just spent £15k on a ground source heatpump, happy at the moment but we have not got into winter yet. On new housing it's probably the way to go but I have reservations on retro fitting.
You need an awful lot of garden area for a ground source heat pump, or dig a deep bore hole. I don't see many people being able or willing to put them in outside of new builds or complete restorations.
It will give a steadier result in cold weather than an air source pump.
https://www.isoenergy.co.uk/la...
Agree - in which case what use is a heating system that works less well in cold weather? Bonkers! Hopefully by 2035 improved and cheaper systems will be available.
As my mother says, if it's chilly, "add another layer".
I'm very much penny wise, and pound stupid. So I'll blow thousands on some speculative market idea, but won't put on my heating until November, at least.
Best solution - I've buggered off to Madeira again for a few weeks! Electricity bills at home near zero (useful, as my green supplier, Blue Planet, confusingly, has just gone bust). And I can sunbathe & do gym/pool detox in the afternoons with the utility bill savings, here at 26oC on a volcano in the Atlantic Ocean!
Detox is going well - being in London was sending me round the bend, so Madeira is much better. Surrounded by German pensioners, here in the Melia Mare Hotel. They're necking back sparkling wine over breakfast, then passing out by the outdoor pool, leaving the indoor pool & gym literally empty for me! (after having done the SCVR of course)!
Best wishes, Paul.
Who can't be in awe of a man who saves energy bills at home by jetting off to Madiera? Paul, I salute you sir.
All heating systems work less well in cold weather - that's why we use more gas in the winter. I am not sure of the relative difference in energy use between gas CH and heat pumps as the temperature drops - sure a quick Google would find it though!
I don't agree. Gas works just as well in cold or hot temperatures. Yes you will need more heating but that is a different thing. If temperatures are say -5C then there is not much heat to extract. "A heat pump works best when the temperature is above 40 Fahrenheit . Once outdoor temperatures drop to 40 degrees, heat pumps start losing efficiency, and they consume more energy"
I cannot find the reference now, but I did look at the efficiency of heat pumps recently, and the CoP i.e. ratio of heat energy out to electrical energy in, is about 3 at +10C air temperature and about 2 at -10C air temp. So they do still work, but not as well.
Which just goes to prove what many knowledgable people are saying, we really need to reduce the heat loss from buildings first, not just try and replace one heating technology with another!
On retro fits there can also be extensive insulation costs (eg loft insulation, cavity wall insulation, double glazing). If the house insulation isn't upgraded then all you've bought is an ineffective heating system. I really can't see the grants being taken up in any sort of volume on older housing stock. Costs are way in excess of affordability for those who really need it. I have perfectly satisfactory gas boiler and am presently having double glazing installed but heat pups are not even on the radar for me, irrespective of price.
Should we not be insulating our houses anyway? Not specifically denying your point, Snazzy, but the way this is talked about implies that we don’t really need to insulate our houses if we are using gas CH for example.
I did think about an ASHP for a house renovation recently but unfortunately it was impossible to insulate the existing concrete slab that the house has been built on.
My friend, however, is moving into a well insulated new build that will use ASHP.
Heat pumps - I think noise will be an issue with air heat pumps. Imagine a quiet suburb or village and a still winter night or summer evening (heating hot water). Every house humming away - what a nightmare! No doubt the dB will be low on paper but I suspect noise will be v annoying. (Just a pet hate!)
Yes noise can be an issue. Imagine a street of terrace houses or blocks of flats. Also they need to run longer than a gas boiler, as designed to run at low temperatures, to be most efficient.
Also another demand on electricity, will we have enough as EVs will be using electric instead of petrol/oil. Will renewables deliver when the weather is cloudy/still and freezing cold?
Better insulation will probably cut more CO2 than changing to heat pumps, I'm not convinced it's a good idea.
Yes you are right about the noise RayStraw. This is the reason I would never install an air heat pump even if the system was free of charge.
I have an air source heat pump on my swimming pool and certainly noisy so wouldn’t want one right next to the house. I have looked at fitting a ground source pump as I get through 5000 litres of oil a year but impossible to use on a property of my size unless all of the exterior walls had a layer of insulation added on the outside and all radiators changed to underfloor heating. Hopefully some new tech will come along in the next 10 years and I’ll revisit it then.
I suspect underfloor heating and more wall insulation are inevitable for you! More timing than or not. A ground source system too I suspect!
You’re probably right but in the meantime I’ve got 10kw wood burner being installed next week to reduce heating oil cost. Should also keep me fit collecting and chopping wood !
ASHPs (Air Source Heat Pump) work well on properties which have a footprint (upstairs & downstairs combined) of upto 123m2. 123m2 is a typical size of a semi detached house. Above this size of house, the property has to very well insulated for the ASHP to cope with the heat loss. However, the biggest ASHP you tend to get on a single phase supply is around 14Kw because of the current they draw. Modern houses tend to have a 100 Amp master fuse and an ASHP will use a high percentage of this power rating, and remember you still have to have some spare capacity for the rest of the electrical appliances in your house otherwise you could overload the 100A master fuse and blow it. There comes a time when a house is so large that it will require a 3 phase supply to cope with the power demand of a Heat Pump. If you want a GSHP (Ground Source Heat Pump) you either need to have a garden that is 2.5 - 3 times the size of the house footprint or you need to bore a hole which adds to the cost. The noise of a modern ASHP is similar to the noise of a desk fan turned to max. You cannot have an ASHP on the wall of a flat because an ASHP cannot be installed where the public can walk underneath it. You could have a communal system installed on the flat roof of a block of flats. ASHPs work down to around -15 degC provided a house is well insulated. It makes more sense to get a house well insulated first before doing anything such as installing a Heat Pump. Even if you are staying on gas, oil, LPG for the foreseeable future, insulating your home makes good sense. Another advantage of having an ASHP is that if your heating is electric and your oven is electric (so that you no longer have any gas appliances in the house) then you no longer need to be connected to the gas national grid, hence you no longer have to pay a daily standing gas charge. This daily charge saving adds up over time. There are a lot of factors to consider when installing a Heat Pump and there is not enough space on this forum to answer them all.
David.
And I installed, about 8 years ago, a Daikin Altherma system in a 450m2 house, upgrading one radiator. OK, I didn't remove the old oil boiler as I had room. But we used 95% less oil afterwards.
People loved to say, what's the payback on that? Actually there was (about 7 years with the RHI), but when I rejoindered, what's the payback on your fossil-fuel boiler? Answer came there none! Apparently gas and oil boiler don't need one.
But our son's Swedish girlfriend wasn't impressed. Fossil-fuel boilers were outlawed there years ago...
Probably easier in Sweden as nearly twice the size of the UK and only 15% of the population. About 45% of their electric is produced by hydro and 30% by nuclear.
Would love to know more. How do they work in tandem?
#OMG Why aren't retail investors given a chance to particpate in today's Capital markets day? The strategy for the next 5 years is being presented; surely this is too important not to share?
Oxford Metrics (LON:OMG) (I once held) is actually pretty good at investor communications. You can expect a very professional looking explanatory video to appear on their investor relations website soon. The two products are in attractive niches (metaverse, smart cities) but I sold because I felt they lacked resources to compete with accelerating competition from better capitalised participants and that I should seek higher growth from more aggressive players within the investment theme. Management is competent but not visionary.
Is it possible to screen for companies with poor pricing power? Am on the hunt for shorts in these turbulent times....Would low operating margins be a good place to start?
Hi colin1862,
Is it possible to screen for companies with poor pricing power? Am on the hunt for shorts in these turbulent times....Would low operating margins be a good place to start?
I would normally start with the gross margin. But screening on that, and the operating margin too, would probably be a good place to start.
It's really easy to set up stock screens on Stockopedia. I usually experiment with different values & fields, it's trial and error, and quite fun to do!
Also you can screen on various elements of the StockRanks, so checking your own portfolio for low quality scores can be a help. Although I'm not sure the Quality scores are going to be quick enough to pick up on fast changing things like soaring inflation & shortages, because the computers won't know about that! For example, Mcbride (LON:MCB) which announced a lurch into losses in H1 today on higher costs, has a Quality score of 86!
Its very low operating margin of 2.7% is the telltale on the StockReport though, so I would say screening on operating profit margin is a good place to start, as you suggested.
Best wishes, Paul.
Interesting to see Edison Group publishing a note on Smiths News (LON:SNWS) which very much confirms Paul's view that it's an undervalued cash-generating machine. They have a target of 75p, twice current price, and a yield of 6.2% with the prospect of "specials" Bought yesterday as it had fallen back recently on distribution worries. Will it turn out to have been a bargain?
Hi Quilleron,
Yes indeed, I read the excellent research note from Edison on Smiths News (LON:SNWS) (I hold) yesterday afternoon. It explains the business model very well. It's now a focused, highly cash generative, albeit slowly declining distribution business. With long-term contracts, and geographic monopolies, the business should continue generating reliable cashflows for years to come, as cost savings continue on a 3-year basis.
Yes newspapers & magazines are declining, but a lot of the reduction in circulation is partially offset by cover price rises. Hence SNWS works on the value of items sold, which cushions its downside.
Also, people always go on about how young people don't buy newspapers, and it's a dying industry. However that ignores a point I've noticed, which is that some people start buying newspapers when they retire. Indeed, I've found that staring at a computer screen or tablet is so tiring, that it's a nice ritual to walk to the corner shop, and buy a Sunday Times. I've recently started doing that. So maybe newspapers might find a level where they stabilise, if they offer unique content?
Also, it's quite surprising how you very often find magazines in the toilets of houses that I visit! My nieces love fashion magazines, and they're mid-twenties to thirties, so there's still plenty of life in the sector. SNWS is still a £billion revenue company.
The free cashflow at SNWS is the interesting bit. They're on track to reduce bank debt to 1x EBITDA, then it should be a gusher for divis - currently limited by the banking agreements. Hence, as Edison points out, buying now should lock in a double digit future dividend yield.
I've spent a fair bit of time on this company, jointly researching it with a friend, and we've done Q&A with management, to make sure that we properly understand the situation.
It's not a company I want to own forever but Edison's conclusion is absolutely right - it's worth about double the current share price. And we'll get increasingly generous divis over the next few years, as we wait for the re-rating.
It's a nice special situation, for patient, value investors. All IMO obviously, and DYOR, and unforeseen things can change, so nobody knows for sure what will happen.
Regards, Paul.
Thanks for that Paul. Im being patient, Im really t....r....y....i....n.....g to stay patient. With Smiths News (LON:SNWS) though, its rather like trying to put off going to the loo when there isnt one close by!!! Must have been your mention of visits to your nieces that brought the loo one to mind!
Hi ridavies,
Very droll! I don't understand why so many investors are incredibly short-term in their thinking? It genuinely mystifies me. The way I see it, I do my research thoroughly, often monitoring companies for years, then buy some shares (often in small parcels to begin with, then loading up as my confidence grows), then sit back and see what happens over the next say 2-3 years.
Some of them work well, others don't.
If something goes fundamentally wrong, then you chuck it out.
Regards, Paul.
Sanderson Design (LON:SDG) A Sell tip from Questor this morning.
Thanks was wondering why it had fallen so much.
Crazy the power of the press to push a share down with a sell request! Not a member of the Telegraph, what does he give as the reason for selling?
Been on a good run -gets more difficult from here, sell and find something with more runway
The gist is just profit taking:
Many of the best returns from a stock come when the picture goes from truly awful to merely less bad, because expectations are low and valuations are often accordingly bombed out.
Sanderson has proved to be a classic example. When we first looked at the Aim-quoted concern, a flood at one factory, a fire at another and a profit warning had hammered the share price and persuaded John Sach, the chief executive at the time, to step down.
Since then, new leadership has come in and overseen both £3m in cost savings and huge improvements in the online and digital offerings, while focusing on both international markets and the potential for brand licensing deals.
A strong balance sheet helped see the firm through the pandemic and its strategies have started to pay off, as the profits and 0.75p-a-share interim dividend suggest.
The issue now is that the shares are way up from their lows and expectations are therefore higher. The shares trade at twice their net asset value, rather than at a discount. Past peak adjusted net earnings were around £7.5m a year and the current market value represents almost 20 times that figure.
Such multiples are not unusual for luxury goods firms by any means, but the rise in the earnings multiple may be largely played out now and that means investors could be left to rely on earnings growth for the bulk of their capital gains from here.
Advertisement
There is nothing necessarily wrong with that either, especially at a firm that can generate double-digit returns on capital when all is going well. But it also means that the share price may take greater heed of any stumbles or disappointments.
Dianne Thompson, chairman of the board, flagged the now market-wide themes of rising costs and supply chain complications in her outlook statement. While the board is working hard to reduce their impact and have the powerful Sanderson brand range to help them, this could put a lid on any positive surprises and increase the risk of more disagreeable ones.
It may therefore be time to (reluctantly) draw the curtains and take profits on Sanderson. That dividend, by the way, will be paid on Nov 26 to investors who are on the register on Friday.
Questor says: sell
Questor does not have a strong track record on its recommendations - buying or selling. Although I do accept that Russ Mould (who wrote this tip) has a better track record than some of the other writers.
I would urge everyone to DYOR before listening to these tips - too many lack good fundamentals and often are way too late to the party for developing growth companies ie. buy at the top. They have also made recommendations into massively high-risk stocks that have subsequently plummeted.
In fact, despite being a DT subscriber for the last 3 or so years I can't think of a single company that they have recommended that I have bought into.......................that probably says it all.
these newspaper share tips seem to appear when fund managers want to trim or exit their winning positions.
I thought that was brokers upgrades or downgrades if they have large order to fill.
Share tips should be independent of funds.
Deleted, duplicate due to system error.
Any observations on Essensys (LON:ESYS), priced similarly to D4T4 on EV/revenue but with a moatier niche? Results in line today.
re Essensys (LON:ESYS), why is its niche "moatier" than D4t4 Solutions (LON:D4T4)? I don't know the sector, but it looks like a more competitive niche to me. Question seems to be how robust their sales projections are.
Getbusy (LON:GETB) trading update today and announcing the two bolt-on acquisitions within SmartVault, DocDown and Quoters. Quoters automates proposals and quotes simplifies the client workflow for accountants and financial services professionals. DocDown uses online web forms, web hooks and APIs to automate the population of forms and templates, removing the need for error-prone manual transfer of information. They are paying a 'non-material amount of upfront cash, with a cash earn-out payment in early 2023 capped at $0.5m each. Further they update on trading, which has been robust since the half year.
Here is a Getbusy (LON:GETB) CEO interview where Daniel Rabie outlines what the business does, the market drivers and the growth strategy through organic growth and acquisition. GETB aspire to double their ARR over the next 5 years. Video & podcast.
Separately, do join us next Wednesday, 27th October, 6pm for the Stockopedia/PIWORLD StockSlam. 10 investors pitch their best stock idea in 3 minutes to a huge audience of investors who then ask questions. Great fun and lots of ideas. Register here.
Hopefully, you've now seen Sell it to the City. Video & podcast, which came out of a tweet by Andy Brough, “A stock I have never heard of or met, maybe I should just have an information forum where people pitch ideas to fund managers. Just need to get a few more. Could be like judgement day (for those who remember his column in The Sunday Times) in reverse. Any other fund managers up for it?” We put together a panel of 3 fund managers: Andy, Judith MacKenzie and Stephen English and a brave panel of four PIs who did an amazing job presenting their stock. We're now looking for the next 3 PIs to pitch. If you feel inspired by the challenge, or know a young person who wants to get a job in the City, perhaps this is an idea forum. Ryan in this last pitch has certainly got his name out there. For anyone interested please contact me here.
”McSlide fried on supply side”.
Surely headline of the year?!
To underline Paul’s snapshot overview yesterday - narrative today in an update from McBride Mcbride (LON:MCB)
Since providing the Company's outlook for the current financial year on 9 September 2021, global supply chains have continued to tighten. Raw material and packaging costs have moved faster and to a higher level than previously expected. In addition, the shortage of haulage capacity and higher fuel costs has continued to substantially inflate distribution costs - again ahead of the Board's expectations - which show no sign of abating in the near term.
As a result, the Group has begun to seek a second round of substantial price increases from all its customers across all divisions, which, dependent upon specific mix, could result in a minimum of mid to high teen percentage increases.
I can't understand how the Federal Reserve keeps referring to inflation as transitory. It doesn't seem transitory to me and many countries have already been forced to raise interest rates. To me it seems that the USA are abusing their position on the dollar as being an international reserve currency. The problem is no other country can afford that stance and do nothing but in time the value of the dollar will go down?
I guess "transitory" is a useful term because it is non-specific and calms people down.
Transitory could mean 1 year, 3 years, 5 years or 10 years.
Transitory means that inflation is working its way through the system and based on the current policy signalled by the FED is expected to peak within tolerated bounds and then moderate to an acceptable range.
Something like energy price inflation can be transitory. ie as prices rise from $60-$85 it acts as inflation but as long as the price then moderates (stays at $85 say) then so does inflation. Remember that inflation is compound, so it is only when prices continue to rise above rates in previous periods for any meaningful duration that it merits a change in policy.
At the moment there are some one off effects - energy, freight, supply chain issues related to covid disruption etc and these are indeed increasing prices but are not expected to continue to rise, thus inflation will moderate. The US is not seeing a sharp increase in labour wage costs yet, which would be more concerning.
The key is "signalled policy" - the FED use wording very carefully as analysts pour over any change in language that might indicate a need to change the rate or direction of interest rates, so even subtle language changes market expectations. It does not mean that they don't anticipate the need to raise rates or temper QE just that they don't expect to deviate from their expected rate of change.
Note : monetary policy has little impact on supply side inflation, it will only impact the demand part of the equation.
But food prices have been increasing sharply which is a big problem. Salaries have also been increasing. As food prices rise employees demand higher salaries so it can continue on and on. It is not the high oil and gas prices that are the problem - they are just exacerbating the problem. The problem is too much money chasing limited products and the value of money itself losing value.
Not really - employment cost index in the US is pretty much bang on trend line since 2002
I used energy as an example, not "the" reason. It is certainly quite a large contributor at the moment as prices rose quickly but these again are supply side driven.
You asked why the FED use the term transitory and that's what I responded to. They see supply driven inflation not demand driven inflation and are not seeing persistent higher wages or labour markets out of control, thus they see no need to change their rate of planned increases. Since the US market is not suffering from labour shortages employees can demand what they like but employers are unlikely to cede to those demands, particularly as their employment law allows them to terminate employees on just a couple of weeks notice with no big pay off costs and they can re-hire at will.
The UK is seeing labour shortages in certain sectors and this could exert inflationary pressure here but that's not the FEDs problem.
Slightly different take on supply side issues this morning from mid cap builder Bellway (LON:BWY) . On the subject of materials costs/logistics etc., they state:-
“Notwithstanding our strong commercial disciplines, overall cost inflation during the year has been in the mid-single digits, although this, in general, has been offset by rises in house prices. We continue to see price inflation on commodities such as steel, timber, MDF and polymers, but there are signs that some of the more pronounced price increases over recent months are beginning to subside.
There remain ongoing constraints in the supply chain and intermittent labour shortages across the sector as, despite the vaccine success, colleagues, subcontractors and suppliers are subject to self-isolation requirements to curtail the spread of COVID-19. In addition, the national shortage of heavy goods vehicle drivers and recent disruption to fuel supplies has had some impact on the availability of materials. In general, these constraints are manageable by adopting good procurement disciplines and forward planning. They will, however, mean that construction output in the first half of financial year 2022 is likely to remain similar to that achieved in the first half of financial year 2021.”
Possibly relevant to make a distinction between “price takers” that are in a weak position to pass on costs to end customers and “price makers” that can pass through costs to end customers - Mcbride (LON:MCB) being the former, Bellway (LON:BWY) being the latter given a buoyant housing market. Also the case that some companies are in a better position to control their supply chains through a combination of more robust infrastructure and bulk purchasing power. Stonking set of results for Bellway (LON:BWY) by the way, albeit out of the remit of SCVR given the market cap. Revenues up 40%, EPS up 102%. Definitely making hay while the sun shines. (I hold).
https://www.investegate.co.uk/...
Gus.
Re price inflation pressures - Good counter point Gus, nicely named
Stocko Price Makers Screen high on everyone's priorities?
As one who owns an apartment built by Bellway (LON:BWY) I wish them every success. When the inevitable bill arrives for remediation works relating to the cladding scandal it is slightly reassuring that the original developer is still around and in a healthy financial state. At this point they have not accepted liability but they haven't walked away from it either.
Barratt Developments P L C (LON:BDEV) gave a very similar take on the raw material shortage / cost situation very recently.