Small Cap Value Report (Tue 19 Sep 2017) - PRV, EYE, FCCN, ESCH, CCT, SDY, BGO

Good morning, it's Paul here!
There are loads of results & trading updates today, so I'll wade through as many as I can manage.
End of the momentum trade?
It's intriguing how so many share price charts look remarkably similar at the moment. When we're doing well on the markets, it's tempting to think that this is due to one's own genius! However, then you realise that many similar type of shares are all going up. In the last couple of years, the action has mainly been in growth/momentum shares. So anything that's showing decent growth, has been re-rated upwards. Then other people just started buying those shares because they had gone up a lot, for the momentum trade.
I think the momentum trade has possibly come to an end now. We're seeing lots of momentum shares falling sharply at the moment, as people bank profits. Also I think it's dawning on some people that a lot of shares have risen far too much, and are now over-priced.
Significant price corrections have happened recently on Purplebricks (LON:PURP) (in which I hold a long position), Fevertree Drinks (LON:FEVR), Hotel Chocolat (LON:HOTC) , Porvair (LON:PRV) , Frontier Developments (LON:FDEV) , Tristel (LON:TSTL) , and loads more shares that are popular with private investors. So I've been looking at these recent big fallers, hunting for bargains. However, even after a sharp sell-off, I'm really not finding any value.
Take Hotel Chocolat (LON:HOTC) for example. As you can see from the chart below, it's fallen a lot recently. However, Stockopedia shows the forward PER as being 30.7 - nowhere near value territory. The company is growing, but at a fairly pedestrian rate, so I certainly wouldn't pay anything near a PER of 30 for it. So what on earth were people thinking, when they chased the share up to 400p in May 2017? Maybe they thought that growth would be faster than existing broker forecasts?
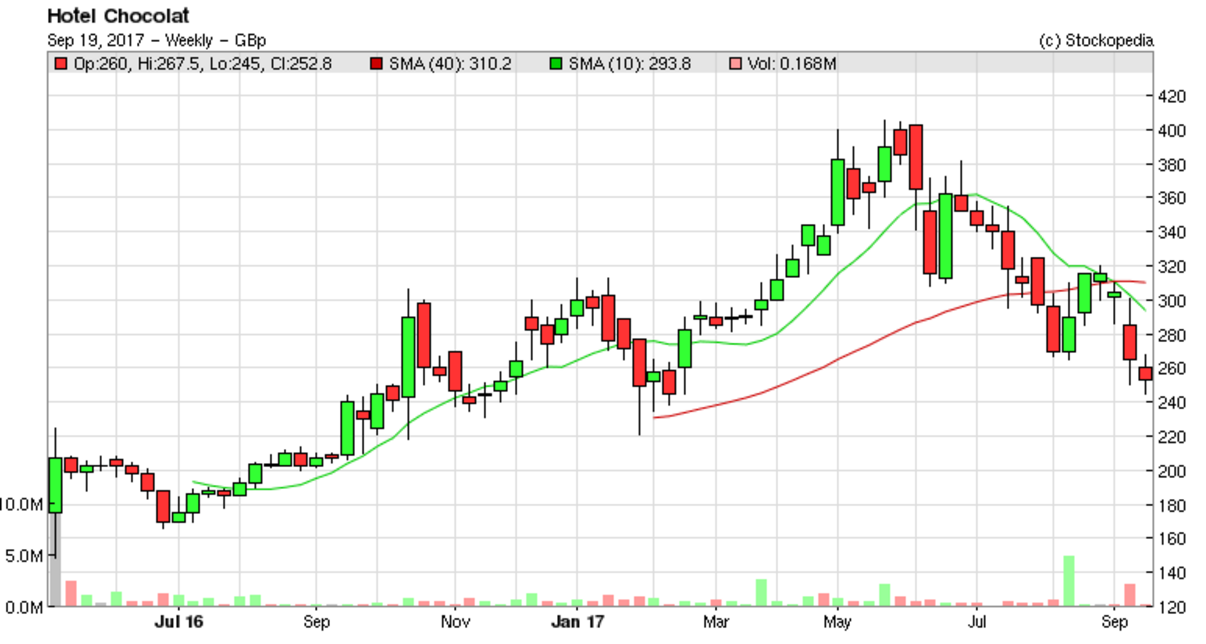
My feeling is that, with valuations already stretched, there's no room for any disappointments. Any highly rated company that does disappoint is likely to see 25-50% wiped off its share price, instantly. Quite a lot of risk. The upside is that companies need to out-perform against forecasts, in order to drive the share price even higher.
So that means that overall, risk:reward doesn't look at all good right now, for highly rated companies generally. It's only the truly exceptional growth stocks, which deliver continued strong newsflow, that are likely to continue rising from already elevated levels.
So personally, I'm being a lot more cautious at the moment. Maybe I'm being too cautious? After all, "buy the dip" has been by far the best investing strategy in recent years. Possibly the sell-offs in highly rated stocks are a buying opportunity? Who knows?! My feeling is that it needs strong newsflow to take shares to higher highs. Without strong newsflow, I wouldn't buy, or continue to hold anything highly rated.
Many of us have done extraordinarily well in the last couple of years, so it is tempting to lock in the gains, and not get too greedy. A correction has to happen sooner or later, we just don't know when, or what will trigger it.
Porvair (LON:PRV)
Share price: 480p (up 5.5% today)
No. shares: 45.5m
Market cap: £218.4m
(at the time of writing, I hold a long position in this share)
Trading update - this company makes specialist filters for a variety of industries.
It's another example of a growth company whose shares became over-valued earlier this year, and have since corrected. This share peaked at 605p in Jun 2017, and recently bottomed out at 430p. I managed to pick up a small scrap of stock at 440p, a few days ago, which was lucky timing.
It surprised me how tricky this share is to trade, despite a £218m market cap - it's quite illiquid, and the quoted spread is often wide. Although quoted spreads on small caps are meaningless actually, because they don't show the RSP machine prices, which are inside the quoted spread. To find out the real prices on small caps, you need to either use a telephone broker, who will tell you the real prices, or put a dummy trade into an online dealing account.
So looking at PRV, the quoted price is currently (at 11:30) Bid 470p, Offer 490p. Here is the Level 2 (courtesy of MoneyAM);
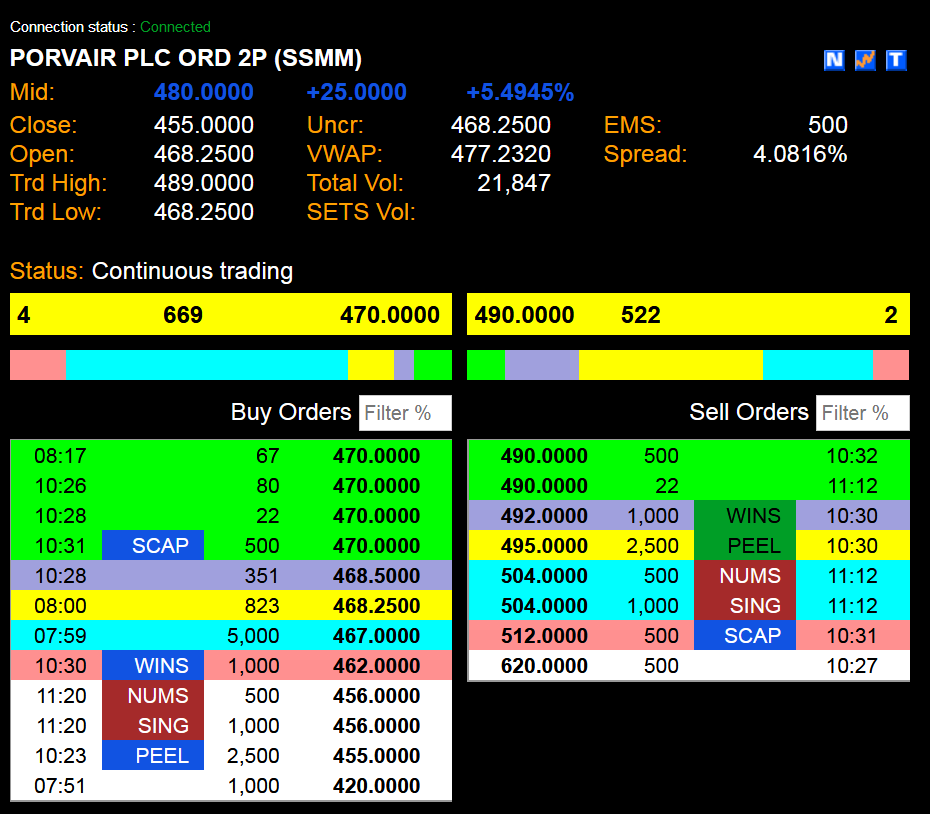
That's a very wide spread, of 4.3% (worked out as a percentage on the mid price of 480p).
To find out the real prices, I've just rung my broker, and he tells me that one market maker is offering stock at 485p (size 2,500 shares), and a different market maker is bidding 475p for 1,000 shares. So the real price is not 470/490p, it's actually 475/485p, which is a more palatable spread of 2.1%
Therefore, as you can see, the above reality means that any analysis based on published prices & spreads for small caps, is actually meaningless. The published prices are not the real prices.
This is particularly relevant for those of us who use spread bets as a tax-free wrapper for small caps trades. In case you haven't seen it, I put your questions to Tom Salmon of Spreadex, in an audio interview late last week. Here is the link to my website, to listen to the audio. It's 37 minutes long, but covered a lot of ground. Of particular relevance for small caps, Tom confirmed that they will happily "work an order" for you, inside the quoted spread, for small caps. They will give you the best prices on the RSP. That's what I do with my small caps trades, most of which I put through Spreadex.
I think the best way of using a spread bet account for small caps, is not to use any gearing at all. i.e. if you want to go long of a share that is 100p, at £100/pt (equivalent to buying 10,000 shares), then I find the best thing is to deposit £10,000 in cash into the account for that trade. That way there is no gearing, and there cannot ever be a margin call. Risk:reward is then identical to actually owning the shares. Although the funding cost of a spread bet is quite pricey, something like 4-5% p.a., plus there's the opportunity cost of getting no interest on the £10k that you deposited with them. Although those costs pale into insignificance when you get a multibagger, with tax-free gains.
Obviously the big danger with spread bets, is that people use far too much gearing, and then end up blowing up in a bear market, or if a particular share collapses in price. That's exactly what happened to me in 2008, so lessons learned the hard way for me, that's for sure.
Sorry, back to Porvair's trading update. Key points;
- Covers 9 months to 31 Aug 2017
- Good progress
- Revenue growth of 8%. Q3 growth is in line with H1 growth (reported on 27 Jun 2017)
- Profit before tax ahead of management expectations
- Underlying revenue up 13% on last year - this adjusts out forex movements, and also (controversially) strips out large projects - not sure I'm happy with that.
- An acquisition contributed 5% of the underlying growth - so that's not really underlying then, is it?!
- Order books healthy
- Net cash nearly £4m
My opinion - a good quality company, but the rating is still expensive, based on existing forecasts. I've not yet seen any revised broker forecasts, but they might possibly be increased, based on today's update.
I'm not inclined to buy any more, but will stick with the little scrap of stock I already hold.
Eagle Eye Solutions (LON:EYE)
Share price: 248p (down 2.4% today)
No. shares: 25.4m
Market cap: £63.0m
Final results - for the year ended 30 Jun 2017.
This is a technology company, which provides electronic discount vouchers for retailers, e.g. supermarkets. This clearly is better than traditional, paper vouchers. So the product reduces administration costs, and tracks individual customers. It has some impressive, big name clients, including Asda and John Lewis Partnership. So this looks an interesting company - albeit still currently loss-making.
Key points;
Impressive revenue growth of 71% to £11.1m
Very high gross margin of 88% - so in future, the operational gearing could kick in nicely
Placing of £5.5m done in June 2017, so these results include the benefit of that cash injection
EBITDA is negative, at -£1.8m (similiar to last year). Take off £1.6m depreciation and amortisation, and £431k in share payment charge, and the operating loss was £3.8m (reduced from £4.1m prior year)
See note 3, which indicates that £3.5m of revenues are "development & set up fees", so non-recurring. The balance of £7.5m are subscription & transaction fees, which are recurring in nature.
Current trading /outlook - sounds good;
Q1 FY18 revenue expected to be at least £3m, 32% growth on prior year, with growth anticipated to accelerate in future periods as our significant clients begin to transact through the platform at scale and from the impact of new strategic partnerships that drive increased transactions
Balance sheet - looks reasonable, following the recent placing.
NAV is £8.9m. Deduct intangibles of £4.8m, gives NTAV of £4.1m - which is probably adequate for the size of business.
Note that net cash is £3.7m, which is only about 1 year's worth of cash burn. So more fundraising(s) are likely, unless cash burn reduces from increased revenues in 2017/18. I don't think this is necessarily a problem though - because the business is demonstrating such strong growth (top line), that investors will probably be eager to fund another placing, if one is required.
The problem would be if growth stalls, and the business then would have to raise more equity from a position of weakness. If that coincided with a bear market, then they could struggle. That's a downside risk to consider, but not something that worries me at the time being.
My opinion - this does look an interesting company. However, I'm baulking at the £63m market cap, which seems very high given that the company is still significantly loss-making, and will probably need (at least) one more fundraising.
When I held the shares and tried to sell them, it was a nightmare. So that's an added risk with something this illiquid - if there is any company-specific bad news, or just a general stock market downturn, you could really struggle to dispose of them.
I'm tempted to buy back in, but not at the current price. So it's going on my watchlist to possibly buy back in at some point in the future.
French Connection (LON:FCCN)
Share price: 44.1p (down 0.8% today)
No. shares: 96.3m
Market cap: £42.5m
(At the time of writing, I hold a long position in this share)
Interim results - for the 6 months to 31 Jul 2017.
This company is a fashion label, which has a successful brand licensing & wholesaling business, attached to a heavily loss-making retail business. Although note that 29.2% of the retail division's revenues are now online.
This business has an H2 trading seasonality, so the interim results usually look awful most years. Historically, I've made good money buying after the interims in some years.
Key points;
H1 operating loss of -£5.7m - clearly bad, but a useful improvement of £2.2m from the prior year H1 loss of -£7.9m. Last year, the company made a £2.6m operating profit in H2. Therefore, with an improved performance in H2 this year, I reckon that we might be looking at a £4-5m profit in H2, which would bring the company close to full year breakeven for FY 01/2018.
Net cash of £6.7m, is only down £1.0m on prior year. Mid-year cash is always low, but should be a good bit by year end of 31 Jan 2018. Note that the commentary says the minimum net cash balance during the year was £4.9m. This is a well-financed business, and I have no worries at all about solvency.
Outlook comments sound the most upbeat I can recall for some time, in particular;
We have definitely seen positive momentum build in the first half of the new financial year with improvements across all the divisions despite difficult trading conditions.
With full price sales in Retail up during the early part of the second half, combined with the strong Winter 17 order books in Wholesale and very strong reaction to the Spring 18 collection, I am confident that we will see a good performance during the rest of the year.
In November we will be opening our first new French Connection store for a number of years, in Manchester, reflecting our strategy to open new stores in appropriate locations where we believe the brand will trade profitably.
We have been working with the goal of returning the Group to profitability as soon as possible and, while there is still much to do, I believe that we have made significant steps to achieve that in the near future.
I'm not at all keen on the company opening any new stores. Surely the lesson from the last few years is that French Connection just doesn't work in standalone stores. It does however trade well on a wholesale basis, online, and in-store concessions (in Dept stores).
My opinion - I'm quite encouraged by these results. The long-term value from the highly profitable wholesale & licensing divisions should be unlocked at some point, once the heavily-loss-making retail leases have expired. I can't find anything in the narrative about lease expiry dates, which would have been useful.
It's probably too long-term an investment proposition for most people, and it doesn't pay divis at the moment either. However, I remain pretty sure that one day I'll be able to say, "You see! I knew there was some value there!" - most likely from a trade sale of the business. Stephen Marks is getting on a bit now, so presumably at some point he'll want to cash out for the maximum possible price. Of course we're all in his hands, given his dominant shareholding, which is rather scary, hence why I'm keeping my position size here fairly low.
Quick comments now, as I've got a headache, and want to go out for a pizza & a pint soon!
Escher Group (LON:ESCH) - poor interim results are published today. It's a software company for postal service companies around the world. H1 2017 was a loss of -£27k, versus a profit of £1.8m in H1 2016. The reason seems to be because one-off licence sales dropped considerably. That exposes the flaw in the business models of many software companies - profits are often totally dependent on winning lumpy licence sales.
Outlook comments indicate a good pipeline, but caution as follows;
While there is an adequate pipeline of opportunities to deliver a material licence sale in H2, the spending patterns of our traditional customer base are such that the timing of these sales remains difficult to predict and can therefore impact the Company's earnings in the short-term.
I really cannot see any appeal to this share at all - other than that a bigger company might want to buy it, for its customer relationships & the cross-selling opportunities maybe?
It's very surprising that it has a high StockRank of 93. Maybe the Stockopedia computers have seen something good that I've missed? I rarely invest in small software companies now - profitability is usually totally unpredictable, as it's dependent on lumpy contract wins.
Character (LON:CCT)
(at the time of writing, I hold a long position in this share)
Trading update - which came out tonight after the market had shut.
Underlying profits for y/e 31 Aug 2017 are;
... expected to meet current market expectations
Conditions "remain challenging at the consumer level".
Notes that Toys R Us has gone into bankruptcy protection in the US & Canada - noting it is a "major customer";
At this early stage, we do not know the extent to which this will impact our trading position with them both in the UK and internationally. Consequently, we do not currently have reliable visibility on the important 2017 Christmas trading period and its effect on the current financial year ending 31 August 2018.
Oh dear, that doesn't sound too good. I read on CNBC today that Toys R Us operations internationally (outside of USA & Canada) have not gone bust.
Unfortunately, I think this announcement is likely to trigger a negative share price reaction tomorrow morning - at a guess I'd say 10-20%. It depends what financial impact this is likely to have. Character might suffer a bad debt from goods already delivered to Toys R Us, but not yet paid. We'll have to wait and see what amount that is likely to be.
From other stuff I've read today, the intention seems to be for Toys R Us to continue trading. It just needs to restructure its debt, hence entering bankruptcy protection. So long term, this shouldn't be a problem for Character. For that reason, if there is an excessive fall in CCT's share price tomorrow, then I might well snaffle up some cheap shares, and then ride out a few months of poor sentiment. Although it would be safer to wait for the company to update us again, on the financial impact.
Speedy Hire (LON:SDY) - this tool hire company has put out a fairly good update today. Various details are given, but the key paragraph says this;
Adjusted profit before tax for the full year is expected to be well ahead of the prior year and slightly ahead of the Board's previous expectations.
Net debt at 30 Sep 2017 is expected to have reduced from £85.4m a year earlier, to £70m. That's very pleasing.
This company seems to be getting back on track. It doesn't particularly interest me though, although it's looking better value now than it has done for a while. You would need to be very confident about the UK economic outlook though - as tool hire companies are not good things to own if a recession is looming.
Action Hotels (LON:AHCG) - this is a hotel operator in the Middle East & Asia, listed on AIM (why?!). I had a quick skim of its interims this morning, and am deeply unimpressed. The company doesn't generate much operating profit, yet has a mountain of debt to service, so overall it's loss-making.
The only appeal is that it trades below book value. However, in my view, if assets are not generating an economic return, then the book value needs to be written down.
Surprisingly, it does seem to pay divis, yielding over 5%. However, as that's not covered by earnings, then it's unlikely to be sustainable.
The only upside here, is if profitability greatly improves. Until then, I see little to no value in the equity, so I wouldn't touch this share.
Augean (LON:AUG) - interim results today aren't too bad - adjusted profit before tax down 7.2% to £2.9m for H1. The share looks amazingly cheap, on a forward PER of 4, and a divi yield of over 5%. So I started to get interested in it this morning.
Then I noticed a plunge in share price in late Aug 2017, so I had a brief look at the RNSs at that time. Sure enough, there's a disastrous announcement on 25 Aug 2017. HMRC reckon the company hasn't paid enough landfill tax, so is going after it for £2.1m. However, here's the real sting in the tail;
Should HMRC make further such assessments, for this and one other subsidiary, the total amount that could potentially be claimed could be very large. Augean intends to work with stakeholders in the sector about the broader adverse implications for the continued and necessary proper treatment of hazardous waste.
That makes it uninvestable, as far as I'm concerned.
Bango (LON:BGO) - I had a chat with the CFO of this company a while ago, who kindly briefed me on what it does. The company processes small payments for phone apps, via the end user's mobile phone bill. It does this in various countries.
The bull case for this share is that it has operational gearing, and the capacity to process much larger volumes of transactions, on a largely fixed cost base. This has seen the market cap shoot up to a remarkable £160m. That seems orders of magnitude too high, for what has been achieved so far.
H1 2017 shows revenues of only £1.7m, and an operating loss of £2.0m. There's an impressive uplift of 102% against revenues for H1 2016. However, there doesn't seem to be any uplift in revenues against H2 2016 - in fact H1 2017 is slightly down on H2 2016.
The operating loss was £2.0m in H1 2017, down from £2.8m in H1 2016. So clearly this company needs to dramatically increase revenues to get anywhere near breakeven, let alone profits.
Cash isn't an immediate concern, with net cash of £5.6m.
My opinion - there's no way I would pay £160m for such a small, loss-making company. Clearly investors believe that this is the next big thing. If anything goes wrong, or the company fails to live up to growth expectations, then this share would drop vertically, like a stone. Much too risky for me.
Swallowfield (LON:SWL) - am wishing I looked at this one earlier, as it rose very nicely throughout the day. Results (for the 52 weeks ended 24 Jun 2017) look excellent, boosted by an acquisition. Note that the narrative says it benefited from some unusually large contracts in the period, which may not repeat.
Full year divis are up 68% to 5.2p.
Outlook comments sound upbeat.
There's a massive share-based payments charge of £1.76m, which strikes me as excessive.
Pension deficit - looks small, and overpayments are only £108k p.a., for 10 years, so not a worry.
Balance sheet is middling - so satisfactory, no worries there for me.
My opinion - I like the look of this, and am going to do some more research on it. What do readers think - does anyone hold this one? If so, would be great to hear your view.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

49 comments
Guys,
That comment was tongue in cheek. I had hoped I had made that clear with the !, but clearly not in the slightest. Sorry if that wasn't clear Paul. No offense intended! A shame that my poor opening probably discredited what was (IMO) some useful facts.
Hope the quick analysis helped quantify the matter beyond what Paul noted. I had framed it conservatively, and it has turned out to be too aggressive. Felt it was fair the price corrected over the course of the day.
Re. Swallowfield (LON:SWL) , I believe about 9% of the company is held by the listed London Finance & Investment (LON:LFI) investment vehicle. No big deal perhaps but this represents about 30% of LFI's own market cap and last time I looked, LFI was trading at something like a 35-40% discount to its NAV so this could be worth considering as a back door in to Swallowfield exposure on the cheap. I did a short piece on LFI a while ago (they also have a significant holding in Finsbury Food (LON:FIF) ) looking at the make up of their investment portfolio. Check out the discussion thread if of interest.
Gus.
While it is quite funny to think that someone posting on a board would be able to wildly affect the share prices of listed companies (unlikely even with small ones, but I have seen people suggest it in regards to the likes of HSBC as well), it is also quite insulting to the poster to suggest they would act with such ill intent.
I have bought some Character (LON:CCT) this morning. It wasn't easy, I was quoted above the spread for not a particularly large trade. There aren't many shares on offer at the reduced price. I think the market makers got ahead of them selves and marked it down too quickly and are now back-tracking.
Paul,
Thanks for another fine report.
One point that interested me about the spread betting. I see your point about not gearing. However, if that means depositing the money with the spread betting company, I'm guessing there is no protection against the spread betting company going bust, so did you check their accounts as well before placing the money there ?
Hi jonesj,
"One point that interested me about the spread betting. I see your point about not gearing. However, if that means depositing the money with the spread betting company, I'm guessing there is no protection against the spread betting company going bust, so did you check their accounts as well before placing the money there ? "
That's a very important point you raise. Yes, I always check the accounts of spread betting companies, before putting any money with them. IG and Spreadex have very sound finances.
Also I looked at how they coped in the 2008 crisis. Robustness of IT systems is also critical - if their systems go haywire, and let through loads of uneconomic bets, then the business could go bust quite quickly. Although I'm sure they all have kill switches, to stop trades being placed, if systems go wrong.
A mate of mine put all his eggs in one basket, and then the company went bust (part of Man, I think?). He then had a terrible wait, to see if he'd lost most of his money, or not. He got most of it back, but a long time later.
For that reason, I think it's always best to spread money around several banks, brokers, spread bet companies, etc, so that if anything unthinkable happens at one, then it won't cripple me.
It's best for most people to steer clear of spread bets, etc. There are so many horror stories (including my own from 2008), that I think it's only for very level-headed people. You have to resist the urge to do wild, leveraged punts. So anyone with even a vague gambling urge, should definitely avoid spread betting, as it's too dangerous unless you have total self-control, and an analytical, disciplined mind.
If in any doubt, then steer clear, is my view.
Regards, Paul.
Good evening Paul. Very interesting your analysis of what is possibly the end of the momentum trade. You have put into words what has been on my mind for a while. It would certainly explain why my portfolio has been seemingly struggling for the past month or so. It is all to easy in good times to take our eyes off the ball, to get complacent and think that any retrace in our share holdings share price is only temporary and is bound to recover and push higher. We need to remain vigilant.
I have a copy of Jim Slaters' book "The Zulu Principle", which although a little dated these days since it was written pre internet, raises many very relevant issues. Access to information these days is far superior; we can find things about almost any company at any time and not have to rely on press releases, copies of financial journals and/or have to phone up and question our broker - how did we manage pre internet?. It really has to be much easier to make better decisions these days. In the book JS mentions a number of factors he used to look at before contemplating investing in any company. The list is too long to go into here, but I would recommend the book as a good read.
Using just 2 of the above factors, a low PEG factor (preferably under 1.0), and a reasonable PE of around 20 or less (before looking at other factors), I recently did a fairly extensive trawl of companies within the FTSE AIM All Share Index to see which would qualify for deeper research. It could equally be used for other indicies. I found very few companies meeting that criteria and had to widen it a little. In the past I would come up with a list of maybe 10 or even 20 companies to whittle down by looking further into the companies financial situation, RNS, Director dealings, latest trading update - was the outlook positive, are profits and earnings per share increasing?. Are there macro economic factors to take into account? (ie likely interest rates?), looking at the share price graph - does it look healthy?.
The conclusion I came to was that many companies are over priced, that there is limited upwards movement in the share prices. Yet, because things have been so rosey for so long there is a real danger that we can think that is the norm., that the situation will continue. Not so. Reading bulletin boards there is too much over optimism, "we all know which direction this share is going to go in!", etc. Really?!. It can be very difficult to let go of a company which has seen us do very well with, to call it a day and say "thank you Mr. Banker....deal!", and move on.
If we are not careful we can end up watching what is in effect a pan of milk on the stove, watching in excitement as the milk rises up and up, before boiling over leaving us with nothing more than a burnt pan, a nasty smell and a dirty stove. All too easy to watch ones profits disappear. I recently lost 20% of my profit in one company by being too greedy - a company which suddenly became far more popular on the bulletin boards with posters, having been quiet for a long time - usually a sign to contemplate ones position in my opinion.
You are absolutely right Paul, with valuations already stretched there is no room for disappointment. And strong news flow is needed to push the share price higher and can't be reliant on news already out in the open. Is there any surprise that a number of the recent high flyers are being increasingly shorted?.
Thank you to you and Graham for your hard work. Regards
CM
Swallowfield (LON:SWL) I too hold and agree with Metatron on the rather wide & off putting spread.
It would be interesting to hear Paul how far inside the spread you can get should you decide to buy
Swallowfield is a well managed company however it does have quite a wide spread and if buying one has to aim to hold John Lee style through volatile share movements.The nice dividend helps
I don't see the ToysRus Character (LON:CCT) news as all that bad, certainly it doesn't justify a large fall in the share price. The future still looks bright for CCT and I believe it is significantly undervalued regardless. If there is a large fall I will be greedy.
I've been a holder of Swallowfield (LON:SWL) for a while. The story is that they were a contract manufacturer of cosmetics and have moved into marketing their own brands of cosmetics with considerable success, as well as growing their manufacturing business. Higher sales & higher margins have come about and I think will continue. Following their recent report, I now expect further significant progress.
Thank you Paul for an excellent view of the current market together with the intriguing approach to buying small caps using Spreader, well worth studying. I have been taking profit at opportune moments but sooner or later they have to reinvested, where and when is the issue. I love the lunchtime missive and would be bereft without it - a bit sad perhaps.
SWL I run a Kirkpatrick Bargain model using my own scripts and it picked this up August last year and sold it at the end of July for a nice profit. UnfortunatelyI didn't buy it.
Paul,
I'm a big fan of your blog here, and 99.99% of the time, the quality of analysis is excellent. Sadly, with your CCT analysis today, I think you are either being emotional, or looking to snap up shares on the cheap! (And I admit I'm a bit biased as I hold CCT, but read below).
In 2016, there were only 2 major customers (10%+ of revs), totalling together about £26.5m. Those customers were located in the UK and the Far East. I think it's fair to guess the UK customer could be Toys r Us, so let's pretend they are, conservatively. But that's irrelevant, as their European, Aussie and Asian operations are NOT included in the bankruptcy. Why? Because as you know, US bankruptcy half the time is a voluntary move to just restructure 'Long-term' creditors and debts. It's not to shut down operations, as they explicitly note. It's to provide heavyweight wording towards restructuring long-term bondholders and creditors.
So first off, I'm not at all convinced this has a major impact on CCT at all. So why did they mention it? Because quite frankly it could have an impact down the line, and they'd be stupid not to mention it. Similarly though, there is no way in hell they have the remotest idea what it actually means for them, given it hasn't even been a day since the Toys r Us announcement, and they were probably drafting the RNS at midday!
Anyway, so we know that US Toys R Us is not 10%+ of revenues. I've done some numbers and reckon it could be, at maximum, 6-7% of revenues. So conservatively, that's £8.5m of revs, and big-box has lower margins, but let's just say that's an £8.5m revenue base that could be impacted. Now, as we know, this is NOT Toys R Us shutting down its stores, so that revenue base is not going to vanish. Anyway, that's a revenue line, but chuck on 30% gross margins and be super bearish in saying they lose half that custom, that's a £1-1.5m ongoing gross profit hit.
Marginal is the right word. What, as you think, is more meaningful, is if there is a bad debt hit. Even assuming Toys R Us (N America) holds 1 full turn of inventory, then that's £8.5m impacted. That seems illogical to me given that Christmas shipping will not have started yet, and suppliers have been tightening for a while.
To put that together, that's possibly £8.5m (desperately desparately unlikely) of a write-down, and £1.5m (worst case) of gross profit lost going forward. I.e. £10m on a market cap of £107m, or very worst case as I see it of 9%.
My more sensible numbers drag towards maybe 4% of headwind for 2018. In reality though, I'm not even convinced this will end up being a headwind. If Toys R Us are doing what I think they are doing, then not sure why short-lead suppliers would be even remotely affected. As before, only the US ops - e.g. the Asian Toys R Us is completely distinct as a legal and financial entity.
To predict as much as a £21m hit to the share price tomorrow is ridiculous IMO, as is even a sustained 10% hit. They've just confirmed they'll hit north of 50p of EPS for the last financial year, so it's on a PE of sub-10, and has cash on the balance sheet of about 17% of the market cap by my reckoning, so close to 8-8.5x ex cash.
If this sort of, minor, event is not priced in (i.e. this drops 10%+ and stays there), then I'd be astonished. Toys R Us may be a big customer, but the likely impact is small. Character are just being cautious here.
Unusually we'll only have to wait 12 hrs of so to see whether Paul is correct, fwiw I'm convinced you'll see a fairly big markdown (10% plus) on the open ,as to whether that's a buying opportunity only time will tell, I'm not tempted as BoD/mgt appear to be hugely overpaid, & I say this as an ex holder who didn't do my homework
Dan7710,
I did NOT appreciate this comment from you;
"I'm a big fan of your blog here, and 99.99% of the time, the quality of analysis is excellent. Sadly, with your CCT analysis today, I think you are either being emotional, or looking to snap up shares on the cheap! (And I admit I'm a bit biased as I hold CCT, but read below)."
CCT is an illiquid stock, and some people will panic sell in the morning, so I completely stand by my view that a 10-20% drop in share price in the morning is highly likely.
I also hold a long position in this share, and have no intention of selling. If it drops disproportionately, I'll buy some more.
My golden rule with profit warnings is to differentiate between;
1) Structural problems
2) Temporary, fixable problems.
If the profit warning is no.1, then I would sell immediately, and not look back.
If the profit warning is no.2, then I'll try to wait until it stops falling, then buy some more.
I think CCT falls into category 2. I say that because Toys R Us is not going to cease trading, it will carry on, restructure its debt, and after some temporary problems, everything will get back to normal.
Also, if Toys R Us is not able to stock product for Xmas, then other retailers will be more than happy to grab the business. People are not going to buy fewer toys just because one particular retailer has gone bust.
CCT has a strong balance sheet, so should be able to cope with any bad debt from Toys R Us.
So long term, it should be fine.
Short term, the price is likely to plunge in the morning. That's fine, it could be a buying opportunity, who knows?
Paul.
Another CCT holder here and I have no complaints about Paul's comments.
It was an after-hours RNS with some negative-sounding news in it, whatever the facts may eventually prove to be. In my experience those are rarely taken well by the market, which more often reacts first and thinks later.
I hope Paul is wrong, but I more expect him to be right. Either way I can completely follow his logic.
We'll see soon enough anyway. If the price is down in the morning, I don't think it will be because of Paul's views though.
Hi DAB26,
Thanks. My family hold over £50k of £CCT
The price is going to drop in the morning, potentially quite a bit, due to illiquidity. Such is life. I'm not vexed about it at all, because it's probably a category 2 profit warning - i.e. fixable, short term problems.
Actually, I should probably reverse my system, so that category 1 would be fixable problems.
What really pissed me off, is someone coming on here, and suggesting that I'm being either emotional or mischevious. Keep that crap on advfn please, it's not welcome here. I always give an honest appraisal of the facts, irrespective of whether I hold the share or not. Sometimes wrong, but usually right. There might be a buying opportunity with CCT tomorrow? However we don't know what the bad debt might be from Toys R Us insolvency. So incomplete info right now.
Paul.
Hi Paul - I just would like to underline your comment. BBs such as advfn are populated with soulless, nasty, dog-eat-dog type of posters. The more we protect our open, mutually respectful ethos and encourage a diversity of views, the better we will all be.
Casually accusing Paul of committing a crime (market manipulation) is not on. I'm sure that was not your intention Dan7710, but you should think before you post.
You arse...
"I think you are either being emotional, or looking to snap up shares on the cheap!"
Hear Hear!
Re Character (LON:CCT) I'm rather glad they told us about this at 4.45pm, giving the markets time to think it over and put it in perspective rather than panicking at 7am. Through their troubles management have shown themselves to be quite open. It might not be that bad, and a spread bet back up might ease the pressure for me... do another Revolution Bars (LON:RBG)...
The frustration I have with French Connection is the clear path to profitability is being totally ignored by Stephen Marks and is inexcusable. For me, the retailer should have done a WH Smith, where it focuses on their profitable travel stores while closing down their high street stores.
So, reduce bricks and mortar to key cities in the UK, and invest in licensing and wholesaling divisions which will result in £10m-£15m PBT.
Reference Paul's general sentiment of heat coming out of the Market, having reviewed all my holdings, including some funds, with the exception of a small handful, all seem to have followed a recent trend down over the past month or are stuttering, all displaying a general value peak around two to four weeks ago - my [predominantly AIM] portfolio is down about 3% from ten days ago. Hmmmm, is this a blip or the generally indicative of a gentle bear run (with half an eye on the FTSE100 too)? Is it time to turn to cash.....
Paul, I would be interested for your views on Anpario which is up 9.5% on the back of a rise of 22% in adjusted eps in their half yearly report where a reduction had been forecast and the share price has been flagging recently. They seem to be making useful inroads into overseas markets - although the costs of doing business appear to have risen as a consequence. I bought a few first thing before the rise kicked in. I admit I was a bit put off by the spread.
Hi homosap,
Sorry, I didn't get round to looking at Anpario - there were so many companies reporting today, I was rather overwhelmed!
Regards, Paul.
Following on from the note from Danyou (5 of 11) on Keyword Studios ( $KWS), I see that FinnCap have downgraded the company today from 'Buy' to 'Hold' on the basis that their future growth can only come from further acquisitions.
I reluctantly sold my holding today.
...just a few corrections after the interims today. Current end user spend is just over half billion (dollars) not 1 billion. But capacity for $5bn is confirmed.
There is more useful info on margins than has been revealed in the past. Revenue generated from end user spend is 1.9% of revenue processed. So there's your margin. Small but if they reach that $5bn capacity, at that margin that is still ill near on £100m profit from EUS alone and assuming no margin growth.
Thanks for the interview with Spreadex. Very interesting. I still have reservations about spread betting, but it is interesting to hear not using margin being discussed at all. The fact that financial spread betting is combined with sports betting and even casino games does still make me wary though.
One of the first restrictions to expansion is the capacity of their payment systems to process payments. I think they are currently approaching $1bn dollars processed and their platform is set up to handle $5bn. Once they get there they will already be well in to profitability and will have the means to expand further. I did a while ago find a reference to the amount they get from each dollar from one of their deals and I can't remember what it was! And it might vary from partnership to partnership. That's why it's so complicated to work out the potential profitability. But the evidence is there in terms of that end user spend figure which is a key measure and is growing very rapidly. To keep it growing they need to keep signing up carriers (vodafone, EE etc) and retailers (amazon, app store etc) in various countries. And they have been doing that continually and increasingly and now have tie ups in seriously big countries like India and Indonesia, Japan, Brazil, UAE and plenty more. Doing this gives customers the capability to use DCB but of course it doesn't mean they are going to use it. That's where the end user spend figure comes in and so long as it's growing that shows that people in these countries with these networks are using DCB for buying stuff with these online retailers. So long as the retailers and carriers promote DCB themselves to their customers, BGO is laughing.
As for competitors, again it's hard to determine who they are. BGO has a virtual monopoly on DCB processing - their main competitor was in the US (bill-to-mobile) and they bought them last year. That is proving to be an astute move as they had good carrier and retailer penetration in the US and Latin America. They have quoted figures in the past, something like 80% of global DCB payments are handled by them. That was before the BTM takeover. For me, their biggest competition comes from alternative payment methods, esp contactless. As such their strategy has been to look to partner with those other methods such that, if you used Apple or Android pay, it could go on your bill rather than off your bank card. Although I'm not sure how far they've got with that and if it is an option for customers yet.
My sense is it's a very high barrier to entry field because few if any payment processing firms have attempted to muscle in on DCB because of the leg work required and a lack of belief or certainty that it will catch on. So all the years forming partnerships across the globe (which has a cost and no immediate return) is paying off for Bango because no-one else can be ar*ed to go and do it when there's another company that has deals tied up already. That's what makes BGO very attractive as an easy way to move in to the field and tie it all up at a stroke. If the payment processing big boys decide they need to be involved with DCB, they will move in, aggressively or otherwise, I'm almost sure of it.
It's easy to double EUS for a couple of years at a constant revenue % EUS margin of 1.8% and get to some staggering numbers. What makes me nervous about Bango (LON:BGO) is the volatility around the revenue % EUS margin, how much it moves from period to period, and how little the incremental EUS seems to bring (relative to what they already have).
The improvement from 2H16 to 1H17 is not particularly impressive. 1H17 EUS was £92.3m and 2H16 EUS was £86.13m for sequential growth of 7.2%. The revenue on EUS in 1H17 was £1.65m as against £1.64m in 2H16 for sequential growth of just about 0%. They generated an extra £10k on incremental EUS of £6.2m for revenue as % incremental EUS of 0.16%. This lead to a decline in revenue as a % EUS from 1.9% in 2H16 to 1.79% in 1H17. Equity Development have a free research note available which cites seasonality. Not sure that's enough of an explanation for me.
Looking forward and using the Equity Development numbers for 2017, they have EUS of £266m and revenue of £3.7m. That implies 2H17 EUS of £173.7m and 2H17 revenue of £2.05m. Revenue % EUS in 2H17 is expected to decline to 1.18%. That implies an extra £400k in revenue in 2H (vs 1H) from an £81m increase in EUS. So the £81m of incremental EUS is bringing revenue % EUS margin of 0.5%.
Some of this could be explained by the Amazon Japan contract where it would be easy to imagine a revenue % EUS margin way below what they might be able to achieve elsewhere. But the 2H16 to 1H17 movement (ie prior to Amazon Japan) also suggests that their contract tiering might actually be quite aggressive. It could be the case that they earn only marginally more revenue on an existing contract the subsequent year even with a healthy year on year growth in EUS.
Thanks for all replies on BGO. I can't be quite as dismissive as Paul if only because he ought to be right but an awful lot of investors including institutional investors clearly don't agree and have been piling in before and since the latest interims. This article is quite useful and gives a clue as to where there is added value in the company above just the payment processing. It's the data capabilities and handling they have that also has huge potential. They already use this to inform clients about customer behaviour and this is another strand of their business.
http://www.proactiveinvestors.co.uk/companies/news/184144/bango-has-some-high-expectations-to-meet-184144.html
Thanks for the information a1canary. I have done a bit more research and it appears that there are larger competitors, such as US-based Boku, which have excellent access access to capital and are expanding at least as fast as Bango but it is difficult to compare them to Bango as they are either private companies or, like Zong, are part of much larger companies so they do not provide separate financial figures. I do not know enough about the sector to have an opinion on the relative strengths of Bango's service offering or whether the sector as a whole will end up being dominated by relatively few players so at this stage I think I lack the confidence to invest.
Hmm, that's really useful info Peter. I must admit as a longer term holder and not a very proactive investor, I must admit I hadn't come across Boku - they are relatively new I see but have raised plenty of investment capital from a number of sources. I don't know quite how to interpret that. Confidence in Boku's ability to succeed vs Bango despite Bango having a big head start... or confidence in the whole payments sector and belief that there's plenty of room for both. Interesting to note that Boku began life as a UK start up.
Know nothing about the sector or Bango, but it might be worth noting that under the forthcoming PSD2 regulations, due in January and applicable to all countries in the EEA, the maximum single DCB payment is €50 and the total monthly is €300. Above that the MNO's need to get themselves regulated, which is the intent of the restrictions and which most would probably not want to do.
But I have no idea if this will impact Bango's revenues.
timarr
@Thunderball - I'm a long term Bango (LON:BGO) holder who had filed them under "yet another tech disappointment" but they have really come out of hibernation this year. I totally understand why people lost patience with them as their path to profitability has seemed interminable plus they have infuriated small investors with their policy of never revealing the commercial value of their partnerships with carriers and retailers. So while they have spent the last 5 years creating large numbers of promising sounding partnerships, we never knew if they were worth a bean. What we did know is that they were going to need massive - and that means many millions at least - of people buying stuff using DCB on their phones. So most people said, "pah, I'm tired of waiting for these and I'm not convinced we're all going to be paying for stuff on our phone bills" and the share price tanked as you will know! But they have proved many many people wrong by targeting the middle east and asia where they are much much more receptive to DCB. Suddenly you can be looking at big populous countries and the potential is suddenly enormous. Hence the share price and investors has had a big change of heart!
We still need this to translate to BGO's bottom line and as with so many tech stocks their price does not stand up to the usual metrics and ratios for measuring value. But for me, if you can hold for another year or two, it's pretty clear that these are only on one trajectory. I'm in profit myself now and could sell - i think they are likely to come off in the short term with some profit taking and after latest interims have digested - but medium/long term the picture is rosy. They are also imo, very ripe for being swallowed up by VISA, Worldpay, or even Google... any big player involved in or wanting to get involved in the payment sector while BGO is still only valued at under £200m. Chicken feed against most Tech merger deals we see!
Thanks for the info on Bango a1canary as I have been monitoring this company for a while. I have difficulty assessing Bango's competitive position so would be grateful for any help. Direct Carrier Billing is nothing new and has been well established in Asia and some other countries for many years and, according to my internet research, revenues passing through this mode of payment amounted to about $18 billion in 2016. The proportion of this business currently going throuygh Bango's systems is tiny. There is clearly huge expansion potential and its financial figures are moving in the right direction, but I am concerned that its competitors must already be well established and with much larger businesses than Bango so I wonder how easy further expansion will be?
@a1canary - Despite Paul's previous view Bango remains one of my larger, high-conviction long holds, and has done nicely since buying in January. Figures looked terrific today but short of spectacular, outlook looks very promising, but need to read the RNS in detail. This business could scale massively.
FCCN - turning the corner, or not? But then, does it really matter when you're CEO and Chairman and you already have plenty banked from past glories?
Disclosure: the only lifestyle business I will invest in is my own...
Any chance on Bango (LON:BGO) please Paul? I know you don't like it and claim it a 'Jam Tomorrow' stock, but they seems to be delivering and due to enter into profitability at the years end with huge growth potential. The price is up 8%+ on the day.
Paul,
I know are you reviewing Keywords Studios ($KWS) later. It seems to be a classic example of a really good quality growth share whose SP has run away a bit too much. It is just as you have described in your introduction regarding momentum shares. Nothing wrong with today's results, but market clearly expecting a lot more....That said, as a long term B+H, it still is very appealing.
Hi danyou,
I looked at today's results from Keywords Studios (LON:KWS) but in the end decided that i didn't have anything to say about it, so moved on. KWS has done so many acquisitions, and is so highly valued, that it goes in my "too difficult" tray.
Regards, Paul.
Looking forward to hearing about Eagle Eye Solutions (LON:EYE) (small position), reaction desn't seem to live up to the good results. Maybe it was all in already. I do wonder where this end of momentum leaves Paul's large £G4M position, which still seems to be creeping up slowly atm. Versarien (LON:VRS) seems a better-quality spec graphene play.
Paul lovely analysis of the current market conditions trend before starting the reports, more of this when applicable. thanks
I totally agree. As an amateur investor, with limited time for following stocks and shares, Paul's overview of what's happening in the wider market is invaluable.
Does anyone know why there's supposed to be a statement from Advanced Medical Solutions (LON:AMS) ? Or where it is?
I always thought it looked odd being scheduled a week after the half year update but both stockopedia and LSE both say there should be an announcement today.
Any clues?
it was a couple of days ago ! interims i think.
[edit - ah, youre after an update AFTER the interims - next one usually a pre close update december 15th]
My morning smallcap notes:
Speedy Hire (LON:SDY),NAHL (LON:NAH),Porvair (LON:PRV),Versarien (LON:VRS),French Connection (LON:FCCN)
◄Speedy Hire (SDY)► Adj pretax exp to be slightly above mgmt expectations.
◄NAHL Group (NAH)► H1 rev £24.9m (£25.8m). EPS 9.0p (3.2p). Div 5.3p per share (6.35p). H2 'has continued in line with our expectations.' FY F/C are for a 6% EPS fall to 23.7p, 14% div fall to 16.2p. F/Cs are from March & April though.
◄Porvair (PRV)► 9 month pretax ahead of management's expectations.
◄Versarien (VRS)► has won an order for ongoing supply of nanomaterials, including graphene, to the Centre for Process Innovation. Versarien will be supplying up to 1.2kg of graphene. No value given.
◄French Connection (FCCN)► H1 EPS -5.9p (-8.2p). Outlook 'confident'. 2 NEDs out, 2 heavyweight NEDs in. Good luck trying to advise Stephen Marks.