Small Cap Value Report (Tue 19 Sept 2023) - MOON, STEM, EYE, XAR, SFE, CODE, ROL

Good morning from Paul & Graham!
Reminder - Megan & Lawrence at Stocko HQ are doing a webinar tonight at 18:00, called "Unlocking US Equity Markets: Your Path To Finding Quality Abroad" - previous webinars have been brilliant I think, giving me lots of ideas, so I'm looking forward to this one too (and no, they haven't asked me to plug it, I just plug stuff that I think is useful to you!). Subscribers should have received a sign up email link already.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
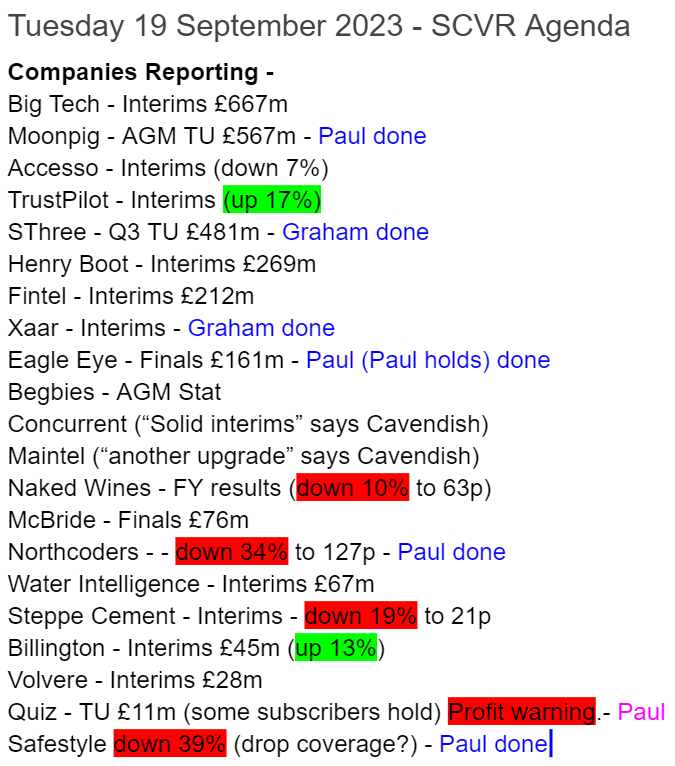
Very busy for news today - we'll probably be covering about half of these at an initial guess, as always focusing on the ones that look most price-sensitive (above or below exps), or in some other way look more interesting -
Summaries
Moonpig (LON:MOON) - 164p (pre market) £564m - AGM Trading Update - Paul - AMBER/RED
Trading is in line with expectations, but with precious little detail provided. I run through the valuation, which looks OK if you ignore the weak, overly indebted balance sheet (hence no divis). I weigh up the pros and cons below, but stick with AMBER/RED in order to highlight the unsatisfactory (to me) balance sheet weakness. That may or may not matter to you - your money your choice!
SThree (LON:STEM) - up 4% to 373p (£503m) - Q3 Trading Update (in line) - Graham - GREEN
Q3 net fees are down 7% year-on-year, but this is in line with expectations and reflects a 6% reduction in average headcount during the quarter (vs. Q3 last year). 2022 was a bumper year and I give SThree credit for tightly managing its costs in a year of fewer opportunities.
Eagle Eye Solutions (LON:EYE) (Paul holds) - flat at 553p (£165m) - Final Results - Paul - GREEN
FY 6/2023 results come out slightly above what was indicated in the last (ahead of expectations) update. I've got a few niggles, explained below, but overall I think the strong organic growth, quality of global clients, big market opportunity, and very sticky recurring revenues, make this share a potential long-term winner. Shareholders have to stomach a high valuation, and overly generous management rewards in the meantime though.
Xaar (LON:XAR) - down 7% to 163.3p (£128m) - 2023 Interim Results (in line) - Graham - AMBER
These interim results are in line but the market might be running out of patience with this one, judging by the share price reaction. The company is betting on a factory upgrade and its next wave of products to turn things around, but I have my doubts.
Safestyle UK (LON:SFE) - down 50% to 4.3p (£6m) - Profit warning - Paul - RED
This is a very concerning update from one of the UK’s largest double glazing companies. It says the market is down heavily (-24% over the summer), and although it is only down 11%, this will result in an underlying trading loss of about 10m for FY 12/2023. This is expected to cause year end net debt of c.£6m. It needs to do an emergency equity fundraise -
The Group intends to engage with stakeholders to strengthen the balance sheet in order to support its recovery and help facilitate future growth.
Paul’s view - I’m sorry to say, it’s clear as day that existing equity is probably now worth little to nothing. New equity (if they can find it at all) is just able to name their price, which is likely to dilute existing holders out of the picture. Or administration is the alternative. Please don’t be tempted to bottom fish here, unless you’re fully prepared to lose 100% of your money. 3 major shareholders might push for a delisting, then refinancing away from prying eyes, perhaps? This won't end well for small shareholders in my view. [no section below].
Northcoders (LON:CODE) - down 33% to 130p (£10m) - Interim Results (and H2 PW) - Paul - RED
A tiny IT training company, much too small to be listed. Small loss in H1 on revenue of £3.5m. Warns that H2 will be “significantly below expectations”, due to customers cancelling or deferring contracts. Hopefully the £1.0m net cash will be enough - balance sheet seems OK, so I think dilution risk is OK. No track record to speak of, so I’m surprised it’s still valued at £10m. Concentrated share ownership, so delisting risk looks high. I can’t see any good reason to get involved here. [no section below]
Rotala (LON:ROL) - up 42% to 59.5p (£18m) - Possible offer at 63.5p - Paul - GREEN
Smashing news just out for shareholders in this bus operator - a possible cash offer from the Directors at 63.5p - from my reading of the announcement, this sounds like it's likely to go ahead, and strikes me as a fair price. ROL caught our eye here at the SCVR on 28 Dec 2022 as a possible buying opportunity at 36p, and was my podcast mystery share that weekend too. So if the outcome is a 63.5p cash bid, then a healthy 76% profit has been made by anyone who followed up the idea. Although liquidity is so poor, I'd be surprised if anyone was able to buy many shares. I forgot to buy any myself, and probably didn't have any spare cash available anyway, oh well never mind! Still, it's nice to get the idea right, even if we don't make any money from it (helps mop up the inevitable mistakes too).
Paul’s Section:
Moonpig (LON:MOON)
164p (pre market) £564m - AGM Trading Update - Paul - AMBER/RED
Moonpig Group plc (the "Group"), the leading online greeting card and gifting platform in the UK and the Netherlands, is holding its Annual General Meeting today. In advance of this, the Group provides an update on its performance for the current financial year (commencing 1 May 2023) to date.
Nothing much to report here, it’s in line -
Trading remains in line with expectations and we reiterate existing guidance.
Except that they’ve forgotten to reiterate what that guidance actually is! Wasting everybody’s time having to look it up.
No mention of cash, liquidity, or in fact any numbers at all.
Outlook -
In the context of the continued challenging macroeconomic environment, we continue to expect pro forma revenue to grow at a low single digit percentage rate in the first half of the current financial year, underpinned by the Moonpig brand, which remains in growth. For the full financial year, we continue to expect consolidated revenue growth at a mid to high single digit percentage rate, with all our brands returning to growth in the second half. Adjusted EBITDA margin is expected to remain resilient.
"Pro forma revenue" - what does that mean?
Who actually wants to be told about EBITDA? Hardly any private investors in my wide network of contacts see EBITDA as a main profit measure. Indeed, most of the fund managers I speak to or listen to on webinars/podcasts also seem to dislike the focus on EBITDA. So why on earth do companies/PRs/brokers give so much focus to a profit measure widely seen as unreliable? It’s an ongoing bugbear, where the city is simply not doing its job of communicating to companies what many/most investors actually want to see in trading updates. Surely it’s the (adjusted if necessary) EPS figure that matters most, and is the most useful? Why not give us several measures, including EPS, and EBITDA, to keep everyone happy?
There are no broker notes available to us on MOON either, another basic error from the company & its advisers.
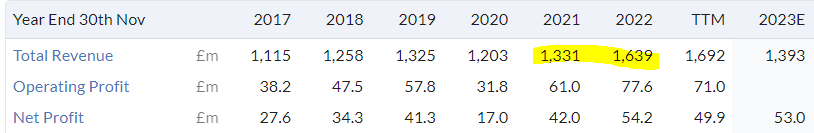
Valuation - the StockReport shows consensus of 10.3p for FY 4/2024. There are two ways of looking at that -
Bullish view: it’s double the pre-covid EPS level.
Bearish view: EPS has gone nowhere in the last 4 years.
Take your pick! There are always different ways of interpreting the numbers, it’s what makes investing so fascinating.
At 164p per share, the PER is 15.9x - not bad given that it’s perceived as a growth company (although an acquisition masked a drop in revenue & profit earlier this year).
Balance sheet - don’t forget the awful, overly geared balance sheet. This is the main reason it doesn’t pay any divis too - lack of available cash. Moonpig ruined its own balance sheet with an over-priced, ill-timed acquisition.
It’s up to you whether or not you care about the balance sheet weakness. On the upside, it’s a decently cash generative business, so I don’t see the excessive debt as creating an existential crisis here, it’s just something to be aware of, and factor into your valuation calculations. Plus of course debt is expensive now - another reason to ignore EBITDA, as it pretends that debt is free (and that tax doesn't have to be paid).
Paul’s opinion - the main negative is the horrible, overly indebted balance sheet.
On the positive side, Moonpig is a nicely cash generative business, operating at a decent profit margin, and with a very well-known brand name. With the squeeze on consumer incomes now easing (pay rises above inflation now), then perhaps organic growth might resume?
It’s held on to the growth achieved in the pandemic, although it remains to be seen how much additional growth can be achieved, and there’s plenty of competition of various types.
Do you want to pay a higher rating for MOON, when you can buy a highly profitable physical cards shop retailer Card Factory (LON:CARD) (I hold) at a bargain PER of 7.7, about half the rating of MOON?
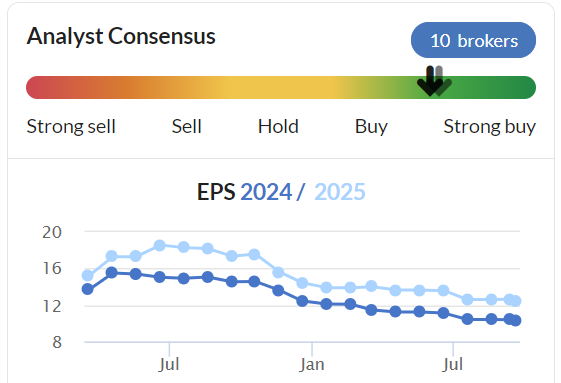
Note that MOON’s forecast earnings have been steadily declining, whereas CARD have been steadily increasing, another reason calling me towards CARD, and away from MOON.
On that basis I find CARD much more appealing than MOON.
I’ll stick at AMBER/RED for MOON, which is my way of highlighting the weak, overly indebted balance sheet. You might decide that risk is worth taking, that’s up to you, I just like to make sure that people are armed with the full facts.
MOON broker consensus trend -
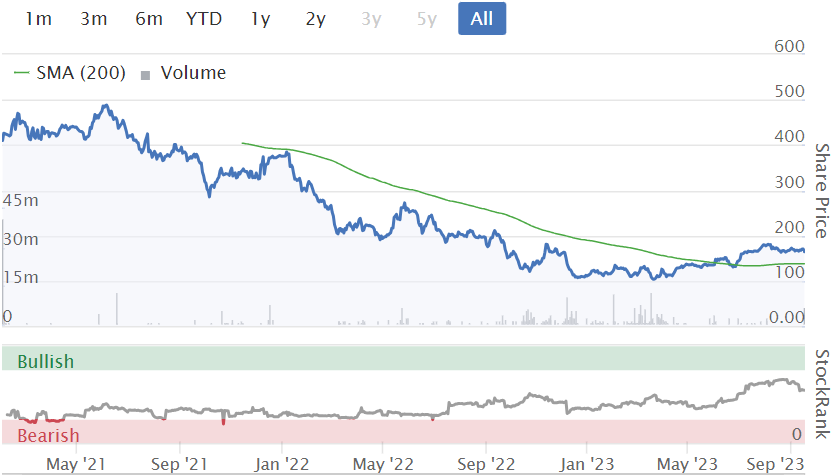
I see from the chart that MOON seems to have moved above a widely-watched moving average, which could pull in buyers who follow the charts, either entirely, or partially for their decision-making.
Note that it's a 2021 vintage float - so over-priced and opportunistic, like many others of that batch. Still, nobody is forced to buy IPOs -
Eagle Eye Solutions (LON:EYE) (Paul holds)
Flat at 553p (£165m) - Final Results - Paul - GREEN
Eagle Eye, (LSE: "EYE"), a leading SaaS technology company that creates digital connections enabling personalised, real-time marketing, is pleased to announce its audited results for the financial year ended 30 June 2023 (the "Year").
An impressive highlights table, but a pity it doesn’t give me the figures I need the most - adj PBT, and adj EPS -

I reviewed EYE’s year-end trading update here on 11 July 2023, and the actual numbers above look slightly ahead of upwardly revised expectations, which is nice.
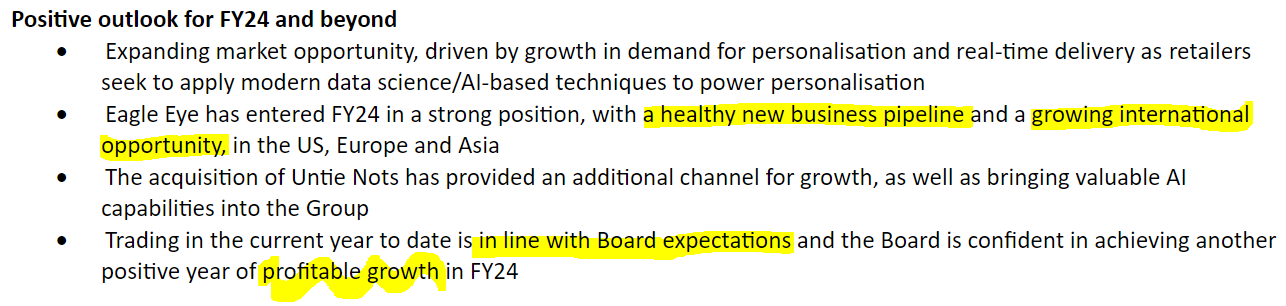
Outlook - sounds fine - but my hand reacted violently when I read that horrid, meaningless PR phrase “profitable growth” - which doesn’t mean anything! I recoil whenever I see this awful phrase -
Share-based payments - strike me as rather too high, at £2.4m (LY: £1.85m). I seem to recall there’s also a generous performance share plan, although that is based on very demanding stretch targets. Management need to be careful not to let greed take them too far from what is reasonable. That said, they seem to be performing well, so I won’t rock the boat too much (and anyway I’m only in steerage, with a small position, so they won’t hear me over the engine noise!)
Adjustments - note that all the profit comes from adjustments. Bolded figures are FY 6/2023, unbolded are prior year comps. Also note the healthy boost from R&D tax credits, under the UK’s generous support scheme for innovative companies (let’s hope it continues) - Shore Capital's note assumes the taxation is about nil in FY 6/2024, rather than a large credit, which is why the forecast EPS growth is only modest. That would be a good point to investigate - if more R&D tax credits are likely, then it could beat forecast EPS maybe? -
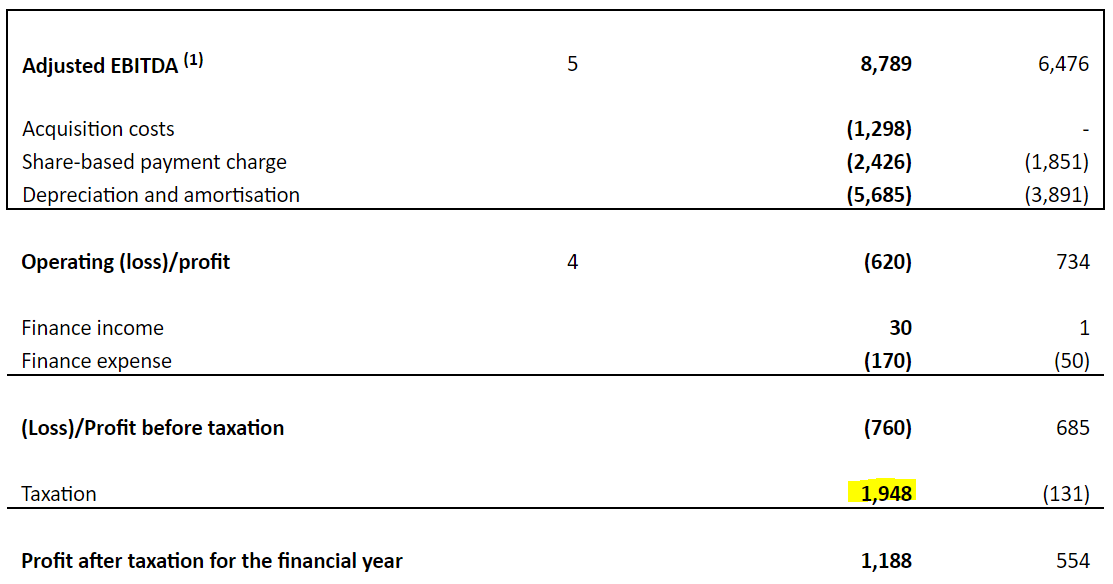
The Untie Nots acquisition was a one-off, and there seems strong strategic rationale for it, judging by an excellent webinar management did at the time explaining the benefits of that deal.
Balance sheet - gives minimal support to the share price, with NTAV of just under £5m. So this share is all about profit growth, not asset backing. The same can be said of many SaaS companies, so it’s not a criticism. EYE has a history of running lean in terms of cash, but that looks OK now, with £9.3m net cash, as expected, at year end.
Although be aware that, as with many software companies, it benefits from getting paid before it pays suppliers. The net current assets position is more realistic, at £4.0m, so a lot of the cash pile is really favourable timing differences, rather than permanently surplus capital.
An unusual item is £2.56m asset shown in non-current assets, called “Contract fulfilment costs”, I’m not completely clear what these costs are, so could do with some clarity on that - something to ask on a webinar perhaps.
Cashflow statement - note that a favourable increase in trade payables boosted cashflow by about a third (which may not necessarily repeat).
The £12.2m cashflow generated was all spent on heavy £5.4m capitalised development spend (which I see as just a normal cost of running the business, that has to keep innovating to survive & prosper), and £6.3m spent on the acquisition of Untie Nots.
The only other big item is £7.1m from an equity raise (to fund Untie Nots).
Nothing untoward here.
Paul’s opinion - as shown above, I do have some niggles with Eagle Eye. To summarise -
Bull points:
Strong organic growth
Blue chip large retailer clients, globally
Big retailers are seeking more relevant, tech-led ways to engage their customers
Proven success of EYE-backed loyalty schemes - becoming a sector leader maybe?
Mostly recurring/repeating revenues
Negligible customer churn, so product clearly works well.
Bear points:
Valuation multiples are high
Overly generous management reward schemes
Balance sheet OK, but doesn’t provide any meaningful valuation support (may not matter though)
New contract implementations take time.
I think that’s a fair appraisal. I have various compartments in my portfolio. EYE is in the long-term hold section, where I’m prepared to pay a lofty valuation for something that could be a big winner long-term, and seems well on the way. It might go wrong at some stage, but so far the figures and newsflow have been very convincing, over the 9 years I’ve been following EYE’s journey as a listed company. I was sceptical for most of that time, but the facts & figures have decisively turned to the positive side - nobody should be ignoring a performance like this, it’s worth investigating more thoroughly, to see if you can tolerate paying the ambitious market cap for it, or not. It takes a lot to get me to pay up for a tech company, but I think this is a rare case of an AIM growth company that actually achieves what it set out to achieve!
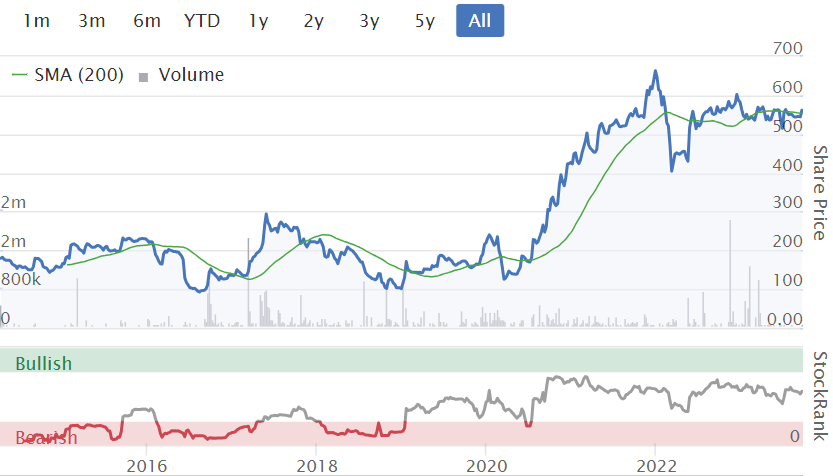
Here's the share price since it listed - impressive, but with high performance in one big swoosh up (not a technical term!) -
Graham’s Section:
SThree (LON:STEM)
Share price: 373p (+4%)
Market cap: £503m
SThree plc ("SThree" or the "Group"), the only global specialist talent partner focused on roles in Science, Technology, Engineering and Mathematics ('STEM'), today issues a trading update covering the period 1 June 2023 to 31 August 2023.
This is a Q3 update, as the year-end is in November.
We covered SThree’s H1 results in July, with the company failing to match the boom conditions of 2022 and allowing its Permanent recruitment revenues to shrink further. But I’ve been a fan of this business for years and remained positive on its long-term prospects.
The stock is not too far off its 52-week lows:

Here are the Q3 highlights.
Trading is in line with expectations:
Net fees are down 7% year-on-year, in line with the trends seen in Q2, “against a strong comparative period and ongoing global macro-economic weakness”.
Contract net fees were flat in the quarter. They are now 84% of SThree’s total net fees.
Permanent net fees fell 31% in the quarter, and are now only 16% of total net fees.
“Technology Improvement Programme” is on track and on budget.
SThree has allowed headcount to fall by 21% in its Permanent segment. I continue to view the decline in net fees from this segment as being at least partially a strategic decision. Though it also reflects less opportunity in this segment in the short-term.
In the aftermath of a Covid-related boom, I see that total Life Sciences revenues are down 24%. I believe that this has had a noteworthy impact on Permanent revenues.
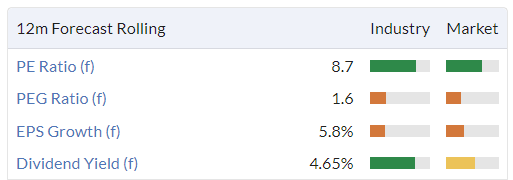
Net cash rises to £83m (it was £72m at the end of H1). This underlines my belief that the company could pursue more, low-margin or even unprofitable revenues if it wanted to, but is instead making solid strategic decisions. The net cash position also leaves the company in a strong position to continue making dividend payments (the yield is 4.6% according to Stockopedia).
CEO comment: describes this as “a resilient performance, underpinned by the Group’s strategic focus on Contract”.
Our long-term opportunity is clear, underpinned by structural megatrends driving the acute need for scarce STEM talent. While we remain mindful of the macro-economic uncertainty across global markets, with all lead indicators of the Group's performance monitored closely, we look ahead to the opportunities facing us with optimism… we remain well positioned to source and place the best STEM talent the world needs."
Geographic breakdown: for two consecutive quarters, the Netherlands has been the only country showing revenue growth, and the USA has been the country with the steepest decline (I suspect that this has a lot to do with the USA having the heaviest percentage exposure to Life Sciences).
Graham’s view
This hasn’t been a terribly exciting year for SThree, as it is unable to match the excellent result seen in 2022.
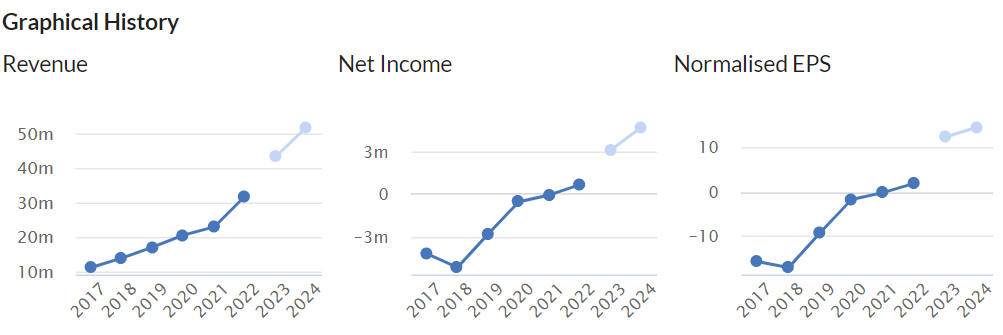
However, that 2022 result was truly remarkable. Growth rarely happens in a straight line and I still think the long-term trajectory is very good:
More context for the 7% decline in net fees is given by the fact that SThree’s average headcount in Q3 was down 6% year-on-year.
So I do view the decline in net fees as being to some extent the result of the company’s own decision-making, rather than being purely the result of forces beyond the company’s control. It has an operating margin KPI which it has no hope of achieving if it does not ensure that headcount is as profitable as possible.
So there’s no change to my view on this one: it’s a well run and attractive recruitment stock, trading at an interesting price for potential investors. Stockopedia gives it a StockRank of 93.
Xaar (LON:XAR)
Share price: 163.3p (-7%)
Market cap: £128m
Xaar plc… the leading inkjet printing technology group, today announces its unaudited interim results for the six months ended 30 June 2023.
We looked at this company’s trading update in August.
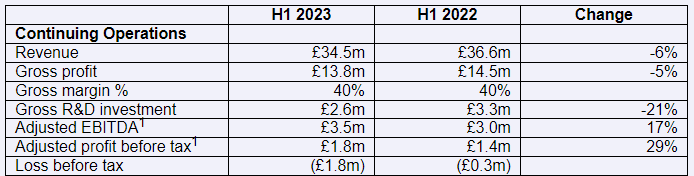
Today’s H1 results are in line with expectations, and the company is “confident of delivering full year results in line with its expectations”.
However, with the shares down by 7%, the market doesn’t seem all that impressed.
Revenues are lower and if you ignore the company’s adjustments, the pre-tax loss widens:
As we noted in August, net cash has fallen to just £7.3m. There are some good reasons for this, including a factory upgrade. But for a company with such a volatile financial history, the current cash figure leaves me with little comfort.
CEO comment:
"We remain focused on the successful delivery of our strategy and taking advantage of the significant opportunities that will drive profitable growth. We have seen continued positive momentum across the business, with increased visibility over customer product launches and a robust pipeline.
Our products, especially Aquinox, are generating strong interest from existing and new customers, underlining our leadership in printing highly viscous fluids…
The company provides commentary on its market opportunities and product development initiatives - more detail than is required here.
Printheads - the company says it has maintained market share in the core printheads business. Rising interest rates “have directly impacted capital equipment purchases by some customers in the period”.
Gross margin maintained at 40% “despite inflationary cost pressures and the closing of the Huntingdon factory for two months to complete Phase 1 of the operational re-organisation”.
Outlook excerpt:
Despite the lifting of COVID related restrictions in China, sales volumes in the Printhead business continue to be affected, but we expect market conditions in the sectors in which we operate to improve during H2 2023 and this, coupled with increased customer product launches, will drive higher demand for Xaar printheads.
We have maintained our policy of increased investment in inventory during 2022 and 2023 to ensure the Group is well placed to capitalise on our targeted opportunities and satisfy customer demand.
The “increased investment in inventory” could be a fine source of cash, if it unwinds, but it’s unclear when that might happen.
Estimates: Progressive Equity Research have left their estimates unchanged, including an adjusted PBT estimate of £2.5m for the current year. They also introduce “conservative” 2024 estimates, suggesting a small increase in revenues and adj. PBT rising to £4.2m.
Graham’s view: I’m still neutral on this one, and I’m continuing to lean more towards concern than optimism. Xaar has always been turbulent but this may be its last chance to get things right before it ends up in a net debt position.
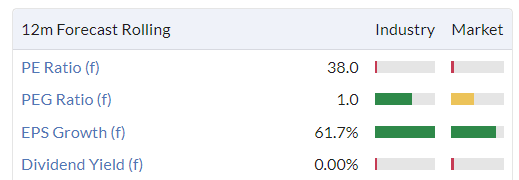
Valuation continues to price in an earnings recovery in which it is difficult to have any faith.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

57 comments
I see Timo Lehne, CEO at SThree (LON:STEM) has just bought £135k in shares. Does anyone know if this is simply exercise of options or a purchase out of his own pocket?
If the latter, I would consider it more than material as he is still new into his first C-suite appointment following a long career as loyal employee. Therefore likely not as flush as a career CEO with a big history of SBC accustomed to making big purchases. The hiring recession is also getting a bit long in the tooth now, though there is no time limit!
Hoping to hear thoughts on McBride (LON:MCB) ....
McBride (LON:MCB) A lot of debt, £23.7m in interest and refinancing costs, compared with £5.1m, previous year.
Mcbride always had debt on its books (at least the last 5-6 years).
The commentary today on its 2024 outlook was simply a well hidden upgrade. ROE for 2024 and 2025 is well above 20% and the debt will come down by at least £30m. As long as a debt is being serviced and gradually coming down this is a bullish factor for any stock,
Revenues are probably going to hit the £1B mark this financial year (only 940m expected) and free cash flows for a £70m market cap company will be massive.
i expect a very positive update regarding revenues , profitability and debt reduction around mid January 2024 that will drive the price much higher.
Thanks
Agreed with BOTH yiannos1 and Paul. Not a high quality company to hold forever, but right now I think the market is not giving enough credit to the volume growth and also (temporary) margin growth in this private label sector.
There's only so much manufacturing capacity here, so the huge demand from retailers is allowing McBride to have (temporary) pricing power.
As the cost of ingredients, shipping fade this will give a positive (temporary) margin boost too.
Notice how I've used the word temporary many times. But by end of this year, they'll be in a better shape financially, and I see rerating potential to 90p+
(I hold in the Boon Fund)
Hi doctor dave,
I don't rate McBride (LON:MCB) . Lots of talk about recovery, but the numbers are very stark - a wafer thin operating margin of barely above 1%, and literally ALL the operating profit is consumed with finance charges on the enormous debt pile.
Balance sheet has negligible NTAV.
Why get involved? The supermarket won't let it make big margins, even in the good times. Banks have given it more time to sort itself out, but it's very difficult to see how the major debt problem can be resolved without a big placing at some stage.
We've reviewed it 3 times in 2023, RED on 17 Jan 2023 and 28 Feb 2023, but I grudging improved to AMBER/RED on 14 Jul 2023 on publication of a more upbeat year-end trading update.
Regards, Paul.
Thanks Paul and All. I'm in already at 25p and maybe I should get out but I like a good momentum turnaround......will keep a watchful
Are those figures for 'Share Based Payments' and 'Profit after Tax' at Eagle Eye Solutions (LON:EYE) correct?
Share Based Payments of £2.4 million and PAT of £1.2 million? So Management think they deserve their Salary, Bonus, Ancillary Benefits AND double the PAT? Bleeping hell!!!! I wouldn't go near management like that with three barge poles. The company/its technology may well be great, and I do hope it works out for holders, but greed like that, and there really is no other word for it, is scandalous.
More names to add to my list of Directors to avoid.
Hi Paul. Hope you get better soon. Sorry to hear about your COVID infection. You said if any interesting FTSE 250 company reported, you will have a look. Team17 (LON:TM17) released half years results. Do you mind having a look. Kind regards and much appreciate your efforts
Sorry Mo, we've been swamped with newsflow today, so didn't get round to looking at Team17 (LON:TM17) interims today. I see the share price fell 5%, so looks like there's nothing of interest to see there.
Thanks Paul. Hope you recovered from COVID. It's alright. Shame that Paul hunt's research is not on Researchtree. Any suggestion how to access their reports? Appreciate it.
Naked wines are third rate - bought a mixed case once and never again!
Interesting view on potential sale of Missguided to Shein. Maybe this was Frasers aim when taking stakes in Boohoo (LON:BOO) and ASOS (LON:ASC) . Shein may be a much better vehicle now tho. Quick delivery/returns from Shein would be a nightmare for other online only fashion retailers I'd imagine.
"Shore Capital said that the deal could result in a "strategic partnership" between Shein and Frasers, given Shein's recent investment in SPARC Group, which operates high street name Forever 21.
"As part of its deal with Forever 21, Shein is considering providing customer services like returns at Forever 21’s physical locations. A similar arrangement could be made with Frasers' stores, offering customers more flexibility and thus enhancing customer experience," the broker said.
"Given Frasers' strong retail network in the UK, the company could serve as a distribution hub for Shein, reducing shipping times and costs for the latter’s UK customers.Partnering with Frasers could offer Shein a more mature and possibly more affluent customer base, while Frasers could gain access to Shein's younger demographic."
Meanwhile, Shore Capital suggested that Frasers could stand to benefit by listing stock as a third-party retailer on Shein's platform, which would open up 120 million further users across the globe.
"A potential partnership with global online retail player Shein could represent a transformational milestone for Frasers, which is already undergoing a significant strategic elevation and implementation of its credit offerings."
If this is true then ASOS (LON:ASC) and Boohoo (LON:BOO) UK heavily automated and scalable storage, shipping and returns handling might be useful to Frasers (LON:FRAS) / Shein somewhere down the line? If only Mike Ashley had a stake in ASOS or Boohoo....
The more machiavellian move would be to use Shein as a battering ram to damage Asos, Boohoo and others, who aren't exactly flush with cash right now, then make a move when they're at their weakest.
I don't have shares in any fashion retailers but I do find Ashley an interesting guy.
Fot those who keep an eye on RM (LON:RM.)
Rockwood Strategic / Harwood have upped their holding from 10.3% to over 11%.
Will be interested to see, if either of you get round to it, what you makes of -90% club member Naked Wines (LON:WINE)
Surprised it's only down 7%, maybe it's the smooth reassurances from the Chairman. On first glance the results were bear keyword bingo.
8 X mention of Material uncertainty ✓
Challenging conditions✓
First quarter below expectations✓
Trading currently volatile✓
Etc, etc ,etc
Trustpilot (LON:TRST) ( I hold)
Trustpilot decent numbers again today. It’s generating cash and looks a low multiple of ARR for such a relatively well known brand. I think Graham has had a look in the past. All thoughts welcome!
I thought the webinar this morning was very positive (copy on their website later today). Good chemistry between new CEO, CFO and the founder CEO, who is taking a back seat. New CEO came across very well, has a relevant background and seems to possess good integrity. Not to forget the Chairman is now Zillah Byng-Thorne. $83M net cash
I hold and I think the market has completely missed the opportunity here. Decent move today though! July update was better than expected as well. Chart looking good. Plenty of momentum.
Another good set of numbers from Billington Holdings (LON:BILN) . They are benefitting from continued demand for structural steel for data centres, giga factories, EFW plants and studios and are operating at full capacity. H2 2022 margins benefitted from one-off steel prices rises and H1 2023 has benefited from one-off steel price falls! Cavendish have had to sharply raise H2 forecasts but leave 2024 alone which implies a sharp margin fall. One is bound to wonder whether further one off benefits will lead them to revise 2024 in time given strong cash guidance and the description of the pipeline. It is not as if the market is easy at the moment with inflationary pressures, contract deferrals and continued weak commercial property and warehouse markets. Strong balance sheet with net cash at a third of market cap by year end and fully invested asset base. Not expensive even if numbers are as forecast on 7x with a 6% yield.
EBITDA is a helpful metric as it helps you understand the core business performance but I think all investors agree it shouldn’t be used as a main KPI. It is too often becoming the default measure for companies to report on and I dislike that. What I want to know is the PAT, the cash flow and the bridge to the EBITDA.
So I like to exclude positive interest and include negative interest for example and I like to know whether depreciation is acquisition related goodwill or capex I need to factor in as that gives better clues as to how a business will perform longer term but it’s a secondary metric.
"Who actually wants to be told about EBITDA? Hardly any private investors in my wide network of contacts see EBITDA as a main profit measure. Indeed, most of the fund managers I speak to or listen to on webinars/podcasts also seem to dislike the focus on EBITDA. So why on earth do companies/PRs/brokers give so much focus to a profit measure widely seen as unreliable? It’s an ongoing bugbear, where the city is simply not doing its job of communicating to companies what many/most investors actually want to see in trading updates. Surely it’s the (adjusted if necessary) EPS figure that matters most, and is the most useful? Why not give us several measures, including EPS, and EBITDA, to keep everyone happy?"
Amen to that. I don't even look at EBITDA, if it's the only number they give I go to the brokers note for EPS forecasts. If there's no brokers available then I'm not buying.
Cynically, it is a lot easier to show a positive figure with EBITDA than with Post Tax profits - the heart of the matter. Also the ratios look smaller using EBITA and so seem more attractive.
You should read what Warren Buffet says about EBITDA. From memory, and I paraphrase, he says why stop at Earnings Before ITDA - why not use Earnings Before all expenses ?
RNS releases today alone I think we had
’The question is,’ said Alice, ‘whether you can make words mean so many different things.’
’The question is,’ said Humpty Dumpty, ‘which is to be master — that’s all.
Litigation Capital Management (LON:LIT) results out and we’re predictably excellent given news flow. EPS up massively as cases resolve but I ignore that as it can be lumpy.
The focus here should be on the move to fair value accounting from book cost. This is a move the company resisted for a long time as they are very conservative but something the likes of Burford Capital (LON:BUR) had been taking advantage of for years.
From first glance fair value shows that the company book value is about twice its current market cap so seems plenty of value left in this one despite its recent rise. Dividend of 2% is ok nothing to write home about.
But this sort of business usually trades at book or above so 0.5 * looks anomalous to the sector. I need to check the fair value number only relates to own assets (and not any of the funds assets) but I would expect that to be the case. Plus I do like the asset mgmt approach as that adds a nice dynamic and lowers capital risk.
I own so prob biased but think it looks interesting.
The announced share buyback of £10m at current price reduces count by circa 8m shares, taking the count back to pre 2020 levels.
At current market cap this implies a share price of £1.30ish without the addition of any re-rating to book value.
Becoming a very interesting compounder with revenues reinvested in more and larger cases.
I hold.
Hello Paul and Graham :-)
Wouldn't mind you casting your educated eyes over DP EURASIA NV?
Any Team17 (LON:TM17) holders here? Somewhat positive H1 results. Good top-line growth of 31% but increased overheads - caused by larger headcount, upfront marketing spend, attendance at live events and general inflationary costs - saw adjusted EPS fall 16%. I don't feel particularly confident in how these might unwind in H2 thanks to a relatively cautious outlook (noting less reliance on top-line H2 and competitive landscape though they did say adjusted EBITDA margin would improve largely thanks to timing...)
Further operational risk is Debbie B leaving (albeit a very decent 4-month handover). Large cash position of £45m is a positive but I was very surprised not to see any finance income on the cashflow statement (rather £36k outflow.)
I also remain aware of the large capitalised development spend which is a real cost and pretty hefty at £18m in H1 (vs cash from ops of £27m). This spend grew 80% whilst cash from ops grew 12.5%. Including their acquisition spend and related costs could you argue that they're actually breakeven and/or slightly loss-making? Either way I'd like to see cash from ops grow quicker than development costs, or a clearer sign that this considerable spend is leading to greater returns.
Keen to hear what others think.
Team17 (LON:TM17) is a long-stayer in my kennel but not the worst.
Hat tip to you ,Jacxx, for spotting the strange absence if finance income!
I'm a holder of Team17 (LON:TM17) and have been hovering over the sell button for several months. I can be patient with income and understand games production is a lumpy type of business where cash is necessarily spent upfront to develop new software. Capitalisation of costs is justified, though I'd bet there are software companies out there (not necessaily Team17) who downplay the matching amortisation entry.
Anyway with £45 to £51M net cash over the 6 month period you'd expect to see say 3% interest x 6 months. Why isn't there around £750K of interest income? It's a both perpexing and disquieting.
Yes I agree even based on 2% would expect to see around £450k even allowing for cash fluctuations !
Glad I could help by pointing it out. With the fall in profits I was curious to see how much they had been flattered by the finance income, to then be surprised the answer was 0!
I too have been hovering around the sell button, having entered at approx £3.40 where there had previously been some resistance. Few reasons:
*if you aren't aware of this take a look - bought for £30m in cash and shares, tried to 'commercialise' the gameplay, making it more accessible and less strategic - only for the core player base to get royally p*ssed off and start review-bombing it on popular platforms e.g. Steam. The player base still hasn't recovered - averaging about 4-6k from previous highs of of 8-10k.
Some bull points though:
On balance I remain happy, at this valuation, for it to be taking up 5% of my portfolio. It's not without risk, and I don't see the valuation re-rating in the next 6 months, unless it just drifts up with more positive market sentiment.
If they do provide a more bullish outlook and/or the profit margins rebuild I can see this fetching a more racier valuation which the industry has previously commanded - e.g. 20 PE
Pets at Home (LON:PETS) looks good. Is this a good time to buy and enter? And will Superdry (LON:SDRY) go back to from where it was once or its a dead end for this giant of a brand.?
Concurrent Technologies (LON:CNC) results look good and getting back to growth. Order backlog at record levels underpinning future revenue
Hi Paul and Graham,
Water Intelligence (LON:WATR) has what look to be excellent interim results out today. All metrics appear positive.
if you have time, it would be great if you could cast your eagle eyes over the numbers.
Regards
Ricardo
Hi Ricardo,
We couldn't cover everything today, due to high number of companies reporting.
I see that Water Intelligence (LON:WATR) H1 results are in line with expectations The StockReport shows a fwd PER of 13.5x. Combine that with an impressive track record of good growth in earnings over the long-term, and I think this is starting to look a nice GARP share. So if I had covered it in the main report, would probably have reported positively, since the valuation has now come down to a sensible level (after getting very stretched back in 2021).
Regards, Paul.
QUIZ and online retail .
Seems to be predicting a continued decline and a 1.5m loss next year ?
I find it quite a strange update as they don’t seem to offer any efforts or commentary to say what they are going to do about it
I wonder if they intend to take private and so from their persiective a car crash into loss making with no positive news is the desired effect .
What is now clear is that online retail is now under extreme pressure to the point where the business models are no longer credible .
Incredibly saturated market and relative easy to set up an online brand means low barrier to entry .
New entrants can get traction quickly and are agile, old players are outmanoevered, out of date , out of ideas and end up spending so big making mark Zuckerberg rich with increasing Facebook / google / Instagram soend that profits evaporate .
There are more fish in the sea PLUS it is a falling tide so virtually impossible right now to grow an online brand .
We’re seeing this daily now so anyone holding online retail should be looking very closely at their holdings .
It is a lot lot tougher out there in online retail than people are acknowledging and there is no light at the end of the tunnel and very hard to see anything to improve .
Quiz (LON:QUIZ) problems go far behind their online retail. Their offline retail stores are also seeing declines.
I'd argue that they have failed to use the three years of covid to transform their brand and proposition. They were doing badly pre-covid. They did not transform enough. So why would post covid trading be any better?
Agreed , my post was more about online retail in general being under extreme pressure and quiz being latest one to show what’s going on under the bonnet .
But fully agree with you Quiz is simply in mind just not a very good company full stop
I have been watching Quiz for what seems like ages. Watched it jump from 10p to 18p a while ago and drift down. Last week I wanted to buy but I just couldn’t. Now? Nope.
Quiz (LON:QUIZ)
I find it quite a strange update as they don’t seem to offer any efforts or commentary to say what they are going to do about it
to be fair to them they have provided more info (some targets !!) than alot of similar companies do - note it is only a trading update today too so not sure you should be expecting info about their grand plans (or lack of em)
If sales suddenly drop in your market for external reasons sometimes there is little to nothing you can do about it - particularly if they don't have a grand plan. Commentary below whilst not saying much sounds like they know they need to tighten the belt buckles.
The Group has been focused on preserving its balance sheet and maintaining an
appropriate net cash position.
Whilst the impact of cost of living pressures on consumers' disposable income persists, management continues to retain a tight control on costs and is proactively reviewing all aspects of the business to mitigate the impact ofthe current economic and trading environment
Your point about taking it private is very valid. There is significant family money by buying firms from the inside and then refloating them when good times return. That is certainly the way I would be thinking.
Do you reckon any chance of a delisting here at Quiz (LON:QUIZ) ?
Founding family does own a sizeable chunk of shares, would not take much more to get to a 75% threshold?
No one should be surprised at the Quiz (LON:QUIZ) update today after they previously claimed in a Q1 update that -15% sales at the same margin as last year and a challenging H2 outlook would somehow lead to the same profits as last year. It never made any sense.
I've never been impressed by management here and their marketing seems to rely on using yesterday's minor celebrities.
I believe the strength of the Quiz (LON:QUIZ) founder is in sourcing and buying clothes. I think I heard him nicknamed as a "rag trader" in past comments on SCVR. His strength is not in the marketing or operations. They were lucky that in years past that's all that mattered - they were able to source and stock clothing that were cheaper than the incumbents, and more on-trend (given their expertise in quicker from design-to-shop).
Now, that's a table-stakes capability in the entire industry. With the newer players (Boohoo, Shein, Temu, Sosandar, etc) all able to do what they do - plus better marketing and operations.
I somewhat agree with the comments re online retail - it’s so easy now to set up a website and start selling things, especially fashion where a third party prints your design and ships on your behalf for a cut. All you need to then do is pop some money behind social media ads and you’re already reaching an audience.
However, I do think something needs to be said for brand loyalty. It’s potentially hard to measure because a lot of the biggest brands will have high street presence (Nike, Addidas, Next, JD…) but there’s been less evidence of sales being cannibalised by smaller players for these stalwarts.
I guess the point is that smaller companies with little brand recognition will find it tough. Why go to Quiz when there are soooo many other retailers offering the exact same product at very similar prices. Same for Boohoo, ASOS etc.
Interesting dynamics for sure.
My morning smallcap tweet: SUN and MOON in line, QUIZ eclipsed
Barkby (LON:BARK) Scancell Holdings (LON:SCLP) Quiz (LON:QUIZ) Poolbeg Pharma (LON:POLB) Avacta (LON:AVCT) Aurrigo International (LON:AURR) Spaceandpeople (LON:SAL) Chill Brands (LON:CHLL) Volvere (LON:VLE), Moonpig (LON:MOON), Begbies Traynor (LON:BEG), Surgical Innovations (LON:SUN), accesso Technology (LON:ACSO)
◄Barkby (BARK)► Mammoth takes five-year global license enabling it to manufacture a Smart Mattress using BARK's SleepEngine platform. Royalty is £75 for a single mattress and £150 for a double. [SP=7.03 Cap=10m]
◄Scancell (SCLP)► positive data from the first stage in its Phase 2 SCOPE trial with SCIB1 cancer vaccine delivered by needle free injection. "These results, if confirmed in a larger cohort, will be a significant improvement on what patients can expect from available treatment today." [SP=13.13 Cap=107m]
◄Quiz (QUIZ)► warns Apr-Aug rev down 15%, below mgmt exp. If trend continues FY rev would be c. 6-7% lower than market expectations and pretax -£1.5m. [SP=8.28 Cap=10m]. I hold.
◄Poolbeg Pharma (POLB)► opposition to one of its European patents (Immunomodulator I) is to be withdrawn. Tallks have resolved it without any financial compensation between the parties. [SP=6.84 Cap=34m]
◄Avacta (AVCT)► successful completion of sixth dose escalation in the ALS-6000-101 dose escalation Phase 1 clinical trial. [SP=106.14 Cap=296m]. I'm short.
◄Aurrigo (AURR)► gets €275k grant for its participation in the Living Lab for Autonomous Public Transport Project. [SP=133.3 Cap=54m]
◄SpaceandPeople (SAL)► further extension to Sept 2024 to commercialisation agreement with Network Rail for the provision of exhibitions, events and distribution activity. [SP=77.25 Cap=2m]
◄Chill Brands (CHLL)► AGM stmt, largely about possible band of disposable vapes. Has designed "rechargeable devices thatmirror the look and feel of a disposable vape but accommodate pre-filled e-liquid cartridges". [SP=3.7 Cap=11m]
◄Volvere (VLE)► H1-June NAV 1400p/sh up 10p from Dec. "Group performance improved significantly following closure of Indulgence Patisserie, the Group's frozen desserts manufacturer in 2022." [SP=1050 Cap=25m]. I hold.
In line: MOON, BEG, SUN, ACSO