Small Cap Value Report (Tue 2 Apr 2024) - DUKE, FDEV

Good morning from Paul & Graham!
Once again, April Fools caught me off guard. Top marks to my nephew, who dumbfounded me by saying their cat, Nigel, had just produced a litter of kittens. Well played indeed!
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. OR it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom),
Frozen SCVR summary spreadsheet for calendar 2023.
New SCVR summary spreadsheet from July 2023 onwards.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Summaries
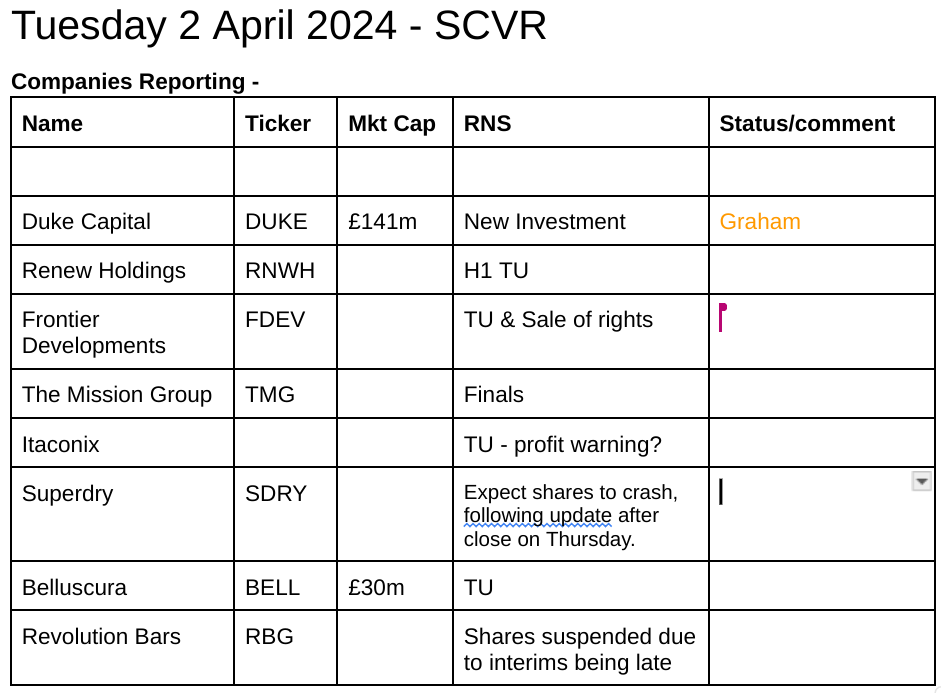
Duke Capital (LON:DUKE) - down 0.3% to 33.4p (£139m) - New Capital Partner - Graham - GREEN
After recently announcing some disposals, Duke has impressively come to the market with the announcement of a new £14.5m investment in a group of nursing homes in the South East. Given its track record since 2017, I think Duke deserves to trade around book value.
Frontier Developments (LON:FDEV) - up 17% to 164.4p (£65m) - Trading Update - Graham - AMBER
Today’s update offers both stability in terms of the cash position (£23m) and good news as Planet Zoo has successfully crossed over to games consoles. I think my three reasons for optimism are intact but having been bitten by previous profit warnings, I remain neutral.
Graham's Section
Duke Capital (LON:DUKE)
- Share price: 33.4p (-0.3%)
- Market cap: £139m
We covered Duke last Thursday when it had a trading update. Noting that it recently made £19m of disposals, I suggested that it would want to reinvest the proceeds without much of a delay.
Today it announces a £14.5m investment in a new “capital partner”.
The deal has some unique features that are worth mentioning.
The £14.5m will go to “a newly formed entity” (name not given?) which in turn will acquire Integrum, an operator of six nursing homes in Kent and East Sussex. It employs 475 people and caters for over 300 service users.
In addition, the funds from Duke will be used to replace a rent deposit with the owner of Integrum’s four leasehold properties. Two of Integrum’s six properties are freehold.
On top of royalty payments to be received over 30 years, Duke becomes a 49% shareholder of Integrum.
I’ve said before that I have some concerns about Duke being an equity investor, but Duke would argue that the equity stakes it receives are merely “sweeteners” with the bulk of the value of their deals being in the royalty payments.
That being the case, the equity value here must be considered very low, if a 49% equity stake is just a sweetener for the royalty deal!
Integrum has a buy and build strategy and is likely to continue acquiring care homes; Duke has agreed in principle to potentially support this with additional funds. So it’s easy to imagine that the initial £14.5m investment could quickly enough become a £19m total investment, soaking up all of the funds received from Duke’s recent disposals.
Neil Johnson, Duke CEO:
"Duke is excited to invest in Integrum and looks forward to contributing to its ongoing success in the future… Integrum has demonstrated a strong track record of buying and integrating quality elderly nursing care homes run by best-in-class home managers and we look forward to supporting the group as it embarks on its next phase of growth."
Adrian Pancott, Integrum CEO:
Duke's unique capital offering is a great fit for Integrum at this time as we look to continue to invest in and improve the homes we already own, whilst looking to further M&A. Duke's existing Social Care sector expertise and the importance they place on quality of care makes them the perfect partner for us, and we are delighted about the opportunity to work together going forward…
Graham’s view
This seems like a promising deal for Duke. For a start, everything I’ve heard about nursing homes as an investment has been positive, and I can’t imagine that there is going to be any reduction in demand any time soon.
If you’re interested in the sector, you might have already looked at Target Healthcare Reit (LON:THRL), an investor in properties that are let to care home operators.
As usual, I tend to worry about the riskiness of Duke’s individual investments. Integrum’s equity value is considered so low, after Duke’s financing, that Duke is being handed a 49% equity stake. This suggests to me that the equity value is considered minimal, and could ultimately prove to be worthless, with repercussions for its lenders? But then I have to remind myself that Duke has been listed since 2017 and that its overall portfolio performance over all of this time has been excellent.
From a portfolio perspective, the £14.5m investment in Integrum is a nice size for Duke, whose total assets as of the interim results were some £225m. It’s not so large as to cause undue risk for shareholders, while still being large enough to potentially make a useful contribution to shareholder returns.
And it’s nice to have the option to fund Integrum’s growth, which would presumably be on the basis that its existing nursing homes continue to perform acceptably.
The company should also be commended for being able to announce a new investment so quickly after making its recent disposals. It certainly can’t be faulted for not putting its funds to work.
I’m going to continue to give Duke the thumbs up at the current share price (33.4p). For me, it would make more sense if it was trading around 39-40p, i.e. around book value. Above 40p, I might be tempted to switch back to neutral.
Frontier Developments (LON:FDEV)
- Share price: 164.4p (+17%)
- Market cap: £65m
This is “a leading developer and publisher of videogames based in Cambridge, UK”.
I looked at its interim results in January and continued to express optimism that a turnaround was possible, following on from arguments made in November.
Here are the key points from today’s trading update:
Sales in line with expectations, led by sales from its core category of games, i.e. “creative management simulations”.
Planet Zoo (previously on PC only) had a successful launch on consoles, including sales of a “season pass” for this game.
The “season pass” is very helpful from a cash flow point of view: cash is received upfront for content that is delivered over 12 months.
From an accounting point of view, cash flow gets boosted now (in FY May 2024) but the associated revenues are recognised across both FY May 2024 and FY May 2025.
Sale of publishing rights: the old game Rollercoaster Tycoon 3 has been the subject of lawsuits over the years - see the Wikipedia article. The story ends now with FDEV selling the publishing rights of this game to Atari for $7m ($4m now, and $3m defcon). The proceeds will be used “for general working capital purposes”.
Cash position: the cash balance improves from £20m (Dec 2023) to £23.4m (March 2024). FDEV has not yet received the funds from sales of Planet Zoo but it has received the $4m upfront payment for Rollercoaster Tycoon 3.
Outlook:
The Board remains comfortable with the financial guidance previously provided for FY24, before taking into account the incremental profit and cash from the sale of the RollerCoaster Tycoon 3 publishing rights. The Board expects to provide an update on the outturn for the financial year in June 2024.
Graham’s view
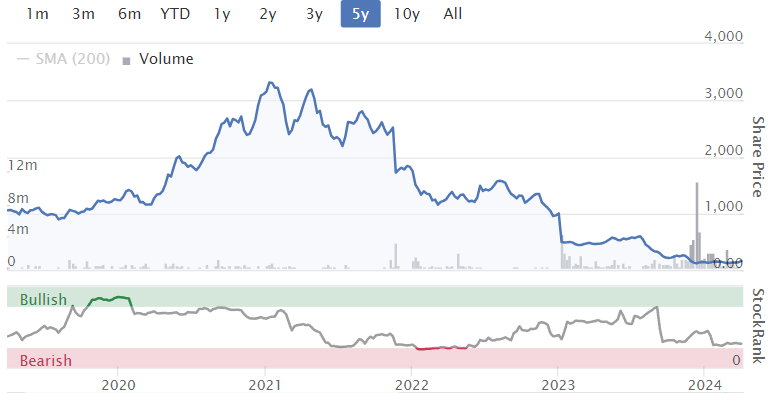
This has been a difficult stock to cover - its share price has utterly collapsed, and I turned positive on it too early (even though the share price had already fallen by 80%!).
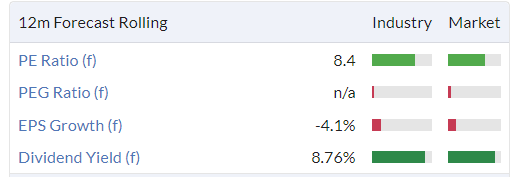
More than a third of the current market cap is covered by cash, so you make a “value” argument for it on that basis.
My three reasons for optimism in a turnaround have been:
The cash balance supporting a chunk of the market cap - that remains the case today.
A low EV/Sales multiple compared to other video games companies. That remains the case today with FY 2024 revenue guidance of £80-95m, and an enterprise value of c. £40m.
The possibility that future titles might perform better, as the company goes back to its roots in “CMS” (creative management simulations).
Unfortunately, it remains impossible to predict the success or failure of future titles. Like a small film studio producing one or two films each year, this stock offers little when it comes to risk diversification.
My stance on FDEV has oscillated in recent months. For now, I’m most comfortable sitting on the sidelines with an AMBER stance. Yes, there are reasons for optimism. But it’s a very difficult one to call.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

43 comments
Apropos Plexus Holdings (LON:POS) and their dependence on SBL (Schlumberger) (tag may be wrong) I see earlier they bought ChampionX (NSQ:CHX) in an all-share deal worth $7.7bn Big bucks, does anyone know if ChampionX (NSQ:CHX) CHX and Plexus Holdings (LON:POS) compete at all? Does this change anything? From a cursory look ChampionX (NSQ:CHX) offer well head engineering but is this a threat or an opportunity? Thoughts welcome.
"Once again, April Fools caught me off guard. Top marks to my nephew, who dumbfounded me by saying their cat, Nigel, had just produced a litter of kittens. Well played indeed!"
I love a well thought out April Fool, I remain proud of informing my brother one year that his method of bouncing his ten pin ball down the lane in his local league was putting his fellow league players off and damaging the lane, and that maybe he would like some lessons in correct bowling. I left my contact number (in a different format), and the ensuing phone call told me it had worked a treat !
What a time to be alive!
Thanks for the input, certainly will save a lot of frigging around when sorting Screens. Screens
Wait a moment, ......no, it's April 2nd.
GEORGIA CAPITAL
Weird bit of weakness past few trading days even dipping under 1300 today .
Bank of Georgia strong Georgia capital weak is just really strange how they are unable to move in sequence . Bank of Georgia looks to be heading back north after it’s recent acquisition that slightly broadens it’s geographical coverage (arguably reducing the much touted “geopolitical risk” from the bears )
I held a decent cash position after selling one of my investments so have put a chunk of it in Georgia Capital as can’t see much downside and as it is pretty liquid with a rightish spread so I’m taking it as “better than having cash in the bank” scenario .
Not sure if that logic is valid but seems to make sense, replaces Avingtans as my largest holding .
Georgia Capital (LON:CGEO) It’s really just low levels of liquidity Planetx. The downside of your strategy is that the company doesn’t pay a dividend so you are dependent on the gap to NAV narrowing, which you’d certainly hope would continue/not get worse given its already 45%. However, no one can be certain of the timing of that.
Bank of Georgia (LON:BGEO) good to see acquisition going through with reg approvals in place. Moodys ratings improved too.
Following the fall in the share price of Georgia Capital (LON:CGEO, the discount to NAV has now risen to 51.7% which makes the shares look even cheaper.
Can someone much brighter than me explain what is happening today with regard to Mondi, is it just takeover talks, but the notices read as if the stock is being shorted. Can anyone help by checking the News section for me. I hold Mondi but I was considering selling to use the cash for another more productive stock. Should I short it? Any help gratefully received.
More bad news for the AIM market. Redx Pharma’s shares have slumped following the announcement that it plans to take itself private.
Jane Griffiths, Chair of the Board of Directors, Redx Pharma, commented: "Following an extensive review, the Board has unanimously concluded that it is in the best interests of the Company and our Shareholders to delist from AIM and re-register as a private limited company. Redx has a strong track record: over the last five years we have delivered six molecules that are in the clinic and established four major partnering deals, validating our scientific and partnering capabilities. Despite completing some of the largest AIM capital raises for biotech companies in recent years, Redx is still liquidity constrained on AIM. As a result, we believe our current market valuation is not reflective of our track record or future potential and is not conducive to raising the level of capital required for our growing clinical portfolio. The Board believes that as a private company we can access a broader universe of specialty investors and, accordingly, a larger quantum of future funding required to execute our strategy and maximise our value in the interests of all our Shareholders.
AIM is like a watching a slow motion train crash at the moment really. It needs some sort of intervention but I guess that is frowned upon.
The AIM will bring about it's own demise. The existing regulator does nothing to stop the incessant market abuses - tweets, FB promotes etc of news that (if they were true) should be announced via nomad / rns. Take yesterday's latest example; talking about Red Rock Resources from the very much respected and trusted David Lenigas (not) - "gold, gold, gold f###ing everywhere" quote from their geologist apparently. Now if that's true we can all see that's rather price sensitive info and the regulators should be hauling Lenigas and nomad over the coals - but equally we all know that the regulator will do bugger all. No wonder the no. of co.s on the AIM is falling - would you want to float your co. on such a poorly regulated market and be in the same company as such folks? No wonder the US is in ascent but the UK is in reverse.
Lenigas is not a fit person to. have insider info on any co. IMHO
From the Mark Kleinman story factory: Autonation (NYSE: AN) said to be mulling a bid for the UK network of £INCH. Which would take a potential bidder for Vertu Motors (LON:VTU) off the table, at least in the short term. At the weekend MK also rehashed news of a week or 2 back that brewer Adnams (Aquis: ADB) has appointed advisers re selling their business. With news of Revolution Bars (LON:RBG) suspension this morning, more confirmation, not that it is needed, that life in hospitality is tough.
Quiet day does anyone have a view on Yellow Cake (LON:YCA) ?
I almost caught this at c. 400p but didn’t and watched it fly upwards as uranium spot prices moved higher. Reluctant to chase as felt like a retrace was on cards and indeed it had come back towards the 600p mark but up 30p today. I think TNAV is closer to 700p or maybe more.
So whilst I have pondered some Uranium commodity exposure long term the problem I have with this stock is that I can’t find any relatively transparent pricing of spot uranium prices. I use Trading Economics which does give an accurate price but it is intermittent - ie more like weekly than daily. Always feel slightly uncomfortable that if uranium price was dropping fast for some reason I wouldn’t know in a sensible timeframe. Ie. Would see the share price falling but wouldn’t be able to tie that back to the underlying commodity and thus at a disadvantage.
It seems there must be more accurate spot data out there as the share price is always moving in advance of the Trading Economics data updating but anyone know where?
https://markets.businessinside... This site gives daily updates although may be information from the previous day. Quite a scary chart.
I am v bullish on this sector long term, but due to volatility prefer to play this via the ETF VanEck Uranium and Nuclear Technlgs U ETF USD A (LON:NUCG)
If you want to track the daily Spot price for Uranium, use:
https://numerco.com/NSet/aCNSe...
But note that only a small amount of Uranium trading is done on the spot market.
There are some other threads here on Uranium which you should look at if you're interested in the sector.
David, I think the following report just out might be of interest:
Production of Uranium globally is projected to increase and also to reach all time highs
Yellow Cake (LON:YCA) NAV is around 700p. Some calcs here:
https://docs.google.com/spread...
Very good results this morning for Gaming Realms (LON:GMR) with reported EPS 15% above forecasts.
Equals (LON:EQLS) - How can MADISON DEARBORN PARTNERS, LLC as a possible bidder hold a short position? Anyone know what's the rationale, tia?
https://www.investegate.co.uk/...
I think it’s GS who are reporting the trade, not MDP
GS reporting on behalf of MDP. Equals (LON:EQLS)
Great question eParo.
Personally I suspect yesterday's RNS is simply a reflection that a wealthy investor/trader of Goldman Sachs has decided to close part of their EQLS short position.
As such given Goldmans is also separately an advisor to MDP. Then GS needed to formally file the trades with the UK Takeover Panel.
I decided rightly or wrongly they were doing one of two possible things. Covering a potential downside on some shares they hold, or just taking a punt on the fact that negotiations will fail. As a US bidder I don't know what consequences they would feel they face if there were to be any finding about trading on potential unreleased market info . Either way I took this as a signal to sell my holding, and take a profit, as I have been nervous about the time these discussions have been taking, as that is usually an indicator of ultimate failure to get agreement. Its also not a great signal to a buyer that you allow them so much leeway, so seems a weak position for management to hold.
From what I can tell, MD are reducing their short position. Shares are up 3%. The market appears to think this makes the deal more likely. Frankly, I haven’t got a clue but it all feels rather irregular. Can you really take out a short position on a company that is subject to bid negotiations infelation to which you have, not just inside information, but actual decisive influence?
It’s GS reporting the trades not MD, GS have a market making arm who are involved in the stock and because of ‘Chinese Walls’ (if one can call them that anymore!) they have to report any trades in the stock since their Investment banking corporate arm is advising MD.
Equals (LON:EQLS) Well at least they are reducing the short position - I have to confess the note is completely unclear to me.
As an aside quite a lot of trading on EQLS today - don't know if it means anything (numbers on the right are today's volumes and average volumes)
Just a final update and thanks to those that bought my novel Pigs Get Slaughtered. The royalties for March were just shy of £100, but I made it up to this figure and passed the donation on to the charity Zane. Please check out the great work they do. For anyone who was good enough to read my book, I'd really appreciate your review on Amazon when you have the time.
Many thanks.
Will certainly buy when return to UK next month. Well done for donating to Zane which is a charity I support having lived in Rhodesia ( now Zimbabwe) for many years .
I bought it!
Results from Gaming Realms (LON:GMR) this morning (I hold). I only have time for a quick skim but looks like a slight beat on revenue with a small miss on PBT glancing at Stocko forecasts. Seems to be reasonably priced for a growth company with good cash generation and no debt. Lots of capitalisation of development spend and adjusted EBITDA to the fore but I’d be keen to hear what Paul or Graham make of the results? I can’t help thinking it’s the type of capital light growth business that would get a far racier valuation across the pond and perhaps will get taken out.
The negatives for me were that no material new markets were entered during 2023, and the decline in social revenues.
Slight miss or beat? I think the tax credit they get means the EPs was a c15% beat but stand to be corrected. I think Paul holds or did until recently so maybe a review from him?
TT electronics (LON:TTG)
I hold having bought close the current low on the basis that despite the debt, which is being reined in and its areas of expertise, electrification and connectivity, TT electronics (LON:TTG) was just too cheap. Peter France, the new CEO, previously CEO at Rotork appears a good fit and started the ball rolling regarding debt reduction by the sale of three business units that collectively were loss making for £20m.
Completion of the sale was announced this morning with the company to receive £17.8m net of transaction costs. Not a stellar amount amount but it helps with debt reduction and exits three businesses that were taking up management time and not contributing to the bottom line.
Congratulations to Nigella and family
My morning smallcap tweet: Russian roulette
X5 Retail NV (LON:FIVE) Frontier Developments (LON:FDEV) Intercede (LON:IGP) Guild Esports (LON:GILD) EQTEC (LON:EQT) Insig Ai (LON:INSG) Redx Pharma (LON:REDX) Belluscura (LON:BELL) Itaconix (LON:ITX) Picton Property Income (LON:PCTN) MTI Wireless Edge (LON:MWE) Cizzle Biotechnology Holdings (LON:CIZ) National World (LON:NWOR) Software Circle (LON:SFT) Revolution Bars (LON:RBG), Cordel (LON:CRDL), Gaming Realms (LON:GMR), Mission (LON:TMG)
◄X5 Retail (FIVE)► gets claim from Russian Gov't seeking a suspension of corporate rights in its Russian subsidiary. [SP=NA Cap=NA]
◄Frontier Developments (FDEV)► trading in line. Sells Rollercoaster Tycoon franchise for $4m + $3m deferred. If you want to see a real rollercoaster, look at the FDEV chart. [SP=141 Cap=56m]
◄Intercede (IGP)► contract and subscription renewals worth over $4m. Underpins revenue for FY25. [SP=111.36 Cap=64m]
◄Guild Esports (GILD)► issues £250k convertible at 8%, strike 0.375p, a 25% premium. [SP=0.3 Cap=2m]
◄EQTEC (EQT)► Verde Corporation Subscription delayed in exchange for improved commercial terms. [SP=2.26 Cap=5m]
◄Insig AI (INSG)► warns FY-Mar rev c.£1.3m, missing £1.4m+ guidance. Two licence contracts worth £1m total, did not close by YE. Considering £250k subscription by chmn at 20p, an 18% premium. [SP=17.25 Cap=19m]
◄Redx Pharma (REDX)► proposes delisting due to liquidity and SP. [SP=18.3 Cap=72m]
◄Belluscura (BELL)► warns FY-Dec 24 rev $16-19m and adj EBITDA -£0.75-1.5m, both below mkt exp. Blames delay in acquisition of TMT Acquisition plus sales and manufacturing progress on both the X-PLOR and DISCOV-R pushed back at least 4 months. Will make write-downs for FY23. Accounts not till June. Must be a bell-ends joke there somewhere. [SP=18.5 Cap=30m]
◄Itaconix (ITX)► warns FY25 and FY25 rev and adj EBITDA below mgmt exp due to not reaching satisfactory commercial terms with one of its major existing merchandising customers in North America for supply in 2024. Guides FY24 rev $6-6.5m. [SP=270 Cap=35m]
◄Picton Property Income (PCTN)► sells its second largest office asset for £29.6m. Property is only 50% occupied. [SP=65.2 Cap=355m]
◄MTI Wireless Edge (MWE)► repeat order for military antennas worth c.$1.2m to be delivered within six months. [SP=45.14 Cap=40m]
◄Cizzle Biotechnology (CIZ)► MoU "for a strategic and exclusive licensing agreement to develop and offer its proprietary test for the CIZ1B biomarker which is highly associated with early-stage lung cancer, throughout the USA and Canada". [SP=1.8 Cap=7m]
◄National World (NWOR)► sells non-core Press Computer Systems for £3.5m. [SP=15 Cap=39m]
◄Software Circle (SFT)► sells domain printing. com for for $2.27m. Co incurs further write-down and charges due to failure of sale of Works Manchester . [SP=17.55 Cap=70m]
◄Revolution Bars (RBG)► suspended as it failed to publish H1. [SP=1.15 Cap=3m]
In line: CRDL, GMR, TMG
NEIL WOODFORD
Though this might be an interesting blast from the past ...
I came across some old notes of mine from March 2018. Here's what I scribbled down when Neil gave an interview. Here's what I wrote down: "We're in a momentum market, insensitive to valuation. He thinks the value of Capita and Provident Financial is higher. Dangerous bubble in Chinese credit. Bifurcated market, with good values in places. Equity markets look stretched. 'We have a portfolio of prfoundly cheap investments.' He doesn't like oil/miners - macro China. Consensus negative, but Woodford likes housebuilders, banks, some retail."
So, where are we now? Well, CPI (Capita) is down an astonishing 89% over 5 years, and PFGA (Provident Financial) has hit the skids. It changed its name to VANQ (Vanquis Banking), which is down 90% over 5 years. Pretty damn shocking, I'd say. Oh, Woody, how the mighty have fallen.
PFGA did door-to-door lending. That is a huge red flag to me. I repeat my rule for avoiding investment disasters: NEVER INVEST IN BOTTOM-FEEDERS, CONSUMER SCAMS, OR SEMI-FRAUDULENT COMPANIES. (You would have similarly avoided catastrophe in HOME, and many others). PFGA ditched doorstep lending in 2023. On August 2021, the BBC headlined "High Court backs compensation for Provident customers".
In terms of Woodford hitting the skids, just the tip of the iceberg, those.....
You could add:
Kier
Purplebricks
Eve Sleep
Industrial Heat (cold fusion....or not - what did Woodford know about this, anything?)
Rutherford (proton beam clinics that went bust)
RM2 (trackable pallets)
Mafic (basalt fibre)
and many, many more.....
On the other hand he did better with Open Orphan (now hVivo, as discussed on this forum) and Oxford Nanopore.
Quite why so many investors believed Woodford was suddenly an expert in emerging speculative technology plays and biotech investments is a bit of a mystery that those who lost money in his funds prefer not to talk about.
Ed's analysis from 2019 What went wrong at Woodford is on YouTube, showing the analysis of the shift in types of shares. It includes lessons for investors at about 1hr 4m.
Plus throw in the energy reselling firm (can't remember the name of them now) but Paul Scott flagged the aggressive accounting they were using and pretty sure they ended up going bust also.
Woodford's problem was he left an area of the market he knew well and got involved with something he didn't understand and believed the blue sky stories he was sold.
There was also the cold fusion business from memory.
Cold Fusion. Mercy.
It seemed that Woodford decided that he was part venture capitalist, not realising that it's a specialist field that he wasn't qualified to handle.
Like us with our investing...stick to your knitting; So many investors followed him when he started his own fund that so much money was sloshing around he did not know what to do with it. Instead of closing to further investors, looks like he got greedy, the only place left to invest was outside his normal realm. Happily i sold out as it started to dip; Technical analysis does have its benefits.