Small Cap Value Report (Tue 2 Feb 2021) - STAF, ASC, DX., IDOX, MOON, GYG

Good morning, it’s Paul here with the SCVR for Tuesday.
Timing - today's report is now finished.
Agenda - here’s something I prepared earlier (last night) -
Staffline (LON:STAF) - trading update - OK, but looks like it needs to do another fundraising
Asos (LON:ASC) - acquisition of Arcadia's top brands. BOO (I hold), Next & Asos as "marketplace" platforms.
Dx (group) (LON:DX.) - positive trading update, but looks expensive now.
Today's news -
Idox (LON:IDOX) - a quick review of its results FY 10/2020
Moonpig (MOON) floats
Gyg (LON:GYG) - my first look at this superyacht painting company. FY 12/2020 trading update.
.
Staffline (LON:STAF)
56p - mkt cap £39m
Trading & Business Update
Staffline, the recruitment and training group, is pleased to provide the following trading and business update for the year ended 31 December 2020.
It looks like 2020 ended decently -
The Group expects to report underlying operating profit marginally ahead of expectations for the year ended 31 December 2020.
Strong peak trading over Christmas, thanks to good demand from food retail, ecommerce & logistics sectors.
People Plus division moved into u/l operating profit in H2, after ditching its apprenticeships operation
Net debt - heavily flattered by £42.9m VAT arrears. Good disclosures though, of this boost, and also giving the average net debt figure, which is more meaningful than the snapshot at the year end, I wish all companies would provide this important information -
At 31 December 2020, the Group had pre-IFRS 16 net debt2 of c. £9.0m (2019: £59.5m), with average net debt throughout the year of c. £38.1m (2019: c. £85.2m).
The year-end position represents an improvement against expectations resulting from the increased focus on working capital and cash generation during 2020, as well as a number of timing effects, including the benefit of deferred VAT relief from Q2 2020 of £42.9m.
VAT is repayable in instalments between Mar 2021 - Mar 2022 - a highly significant cash outflow. Will the bank be happy to finance that, I wonder? Possibly, at least in part, because the bank lending is now secured against the receivables book.
Covid - still disrupting things.
Refinancing - it raised fresh equity in June 2020, but admits today that it needs another fundraise -
Notwithstanding the combination of corrective measures taken in 2020, which has resulted in a significant improvement in working capital, the board continues to evaluate its options in relation to strengthening the Group's finances.
Looking back at its interim results as at 30 June 2020, it shifted the bank borrowings onto a receivables financing facility. This jogs my memory, and I think we discussed it at the time, with this being done at banks’ behest, in order to make the borrowings secured, as opposed to unsecured. I think that’s correct. Which is good, as it makes the bank more likely to maintain the lending facilities, being secured against a receivables book of blue chip clients, i.e. lower risk lending than say an overdraft.
Balance sheet - even after the fundraising in June, STAF has a really bad balance sheet. NAV was £28.9m, less intangibles of £88.5m, takes us to NTAV horribly negative at £(59.6)m.
Therefore, this business needs another, substantial fundraise. The market cap is only £39m, so allowing for a discount on the placing, it would really need to do a 2 for 1 equity fundraising to just bring the NTAV back to zero! That would be a tripling of the share count.
My opinion - if you’re going to bet on a recovery in this sector (not a bad strategy actually, as recruiters should be doing well in a recovery, and when lots of people get made redundant and hence need a new job), then I think it would make sense to find a share which has a solid balance sheet, not one like STAF which is financially very stretched.
The business has basically only survived because the VAT man has extended it a huge loan, and the bank has maintained the borrowing facilities. That’s not a secure base. Best avoided in my view, as risk:reward is not favourable, given heavy dilution being likely in 2021 at some stage.
Staffline shares recovered strongly in the so-called "dash for trash" in recent months, which gave a good selling opportunity when it spiked up to 75p.
I’m perplexed as to why the StockRanks system has delivered such a positive verdict? Maybe I’ve missed something positive? Mind you, the computers don’t know it has a massive VAT bill in arrears, and I do, so I’ll rely on my analysis more than the computers in this case!
For me, this share is an avoid until the balance sheet is fixed with an overdue, substantial equity raise. Even then, I don’t trust the company given its history of accounting irregularities, and poor acquisitions, despite new management now.
.

.
Asos (LON:ASC)
4784p (up 7% yesterday) - mkt cap £4.8bn
Someone forwarded me a very interesting article (many thanks) over the weekend, pointing out that online fashion in the UK is concentrating into “platforms”, or “marketplaces”, which sell multiple brands, as well as their own brand.
The market leaders online are -
Boohoo (LON:BOO) (I hold) - teenage customers mostly, but is now broadening out into older demographics with Karen Millen, Coast, Warehouse, Debenhams, and possibly Wallis, Burton & Dorothy Perkins (if that deal happens, as expected, shortly)
Asos (LON:ASC) - very successful selling to twenty-somethings, multiple brands
Next (LON:NXT) - very successful selling to thirty & forty-somethings.
I'm coming round to the view there’s a strong argument for just buying all 3 of those shares, and keeping them forever.
Asos in particular is starting to look a lot more interesting of late, since it’s finally started making a decent profit, after years of low margins, and minimal free cashflows.
Acceleration of ASOS Brands strategy - this announcement yesterday confirms Asos has won the bidding war for Arcadia’s best brands (TopShop, TopMan, and Miss Selfridge, HIIT), pipping Next at the post apparently.
Has Asos overpaid? Maybe, but given its own equity is on such a high rating, then that gives it scope to pay up. The additional profits could even reduce Asos's PER over time.
The rationale is that Asos already stocks these brands, they’re strong sellers, so by buying them, Asos can increase its margin on those products, and drive growth in them, instead of having to share the profits with Arcadia. Apparently Next spotted that buying these brands also opens up the opportunity of attracting the best people back to TopShop (designers, buyers, etc) that drove its 1990s & noughties heyday, but were repelled by the (widely seen as) obnoxious & bullying Philip Green, who as it turns out did a good job of destroying TopShop.
The rationale from Asos is hard to argue with -
- Accretive to margin and double-digit return on capital (post tax) in first full year (FY22)
- Fully funded from cash reserves; cash position remains robust
I reckon BooHoo’s £55m acquisition of Debenhams is likely to produce a very much stronger return in due course, but they’re much cannier management than Asos, and better organised, from what I’ve heard.
My opinion - I’ve got Asos and Next on my watch list, and am looking to buy if/when they have a plunge, as these shares sometimes do. It’s not just BOO, the whole sector has ESG risk, because even with the best possible systems, no retailer can be 100% sure, despite their best efforts, that all factories, all over the world, are doing things absolutely correctly. Hence we could see buying opportunities in future, if that issue rears its ugly head again. Or, Next & Asos might have it fully buttoned up already, I don’t know.
Apart from that, I'm only interested in niche online retailer (with some shops as well) Joules (LON:JOUL) (I hold). All other fashion and non-food retailers, are probably best avoided. I reckon Works Co Uk (LON:WRKS) could be a value trap - looking cheap, but probably won't survive long-term.
Why mess around in shares of declining businesses, when we have the opportunity to back the winners, in Boo, Asos, and Next?
.
Dx (group) (LON:DX.)
36p (up 3% yesterday) - mkt cap £209m
It’s been a while since I looked at this specialist freight company, which also operates the declining DX secure postal service for solicitors (being gradually usurped by email attachments). I had written it off in my mind as a basket case, so am surprised to see the market cap now over £200m. Something good must be happening.
What an impressive recovery in share price in 2020 -

.
Trading Update
DX, the provider of delivery solutions, including parcel freight, secure courier and logistics services, is pleased to provide an update on trading for the 27 weeks ending 2 January 2021, the first half of its current financial year.
This looks good -
Trading over the period continued to track materially ahead of last year up until Christmas. Since then momentum has remained encouraging although B2B volumes have been modestly impacted by the national lockdown imposed in December.
Nonetheless, the Board now anticipates that DX will materially exceed current market expectations for adjusted profit before tax for the financial year.
“Materially” usually means at least 10%. Timing also has to be taken into account. Being this positive half way through the year, usually means that performance is well ahead of expectations, and that the outlook is also positive. Otherwise they probably would have held back, and kept any out-performance in the back pocket, as a contingency reserve, in case H2 disappoints. So, all good.
Other points -
- Strong performance of DX Freight - volumes & margins both up vs LY
- DX Express - volumes slightly better than expected, but margins softened due to mix (more B2C, less B2B)
- Pipeline of new business “very healthy” for both divisions
- 3 new depots opened - for growth & better productivity, 3 more underway
- Liquidity high, significant headroom re invoice discounting bank facility
- Diary date - interims in early March 2021
My opinion - I’m impressed with this upbeat trading update.
Research Tree has two broker update notes, from Finncap and Liberum, many thanks to them for helping us with access to this important information. Both have substantially raised EPS forecasts for FY 06/2021, by about 30%, but have held back on changing future years’ forecasts. So there could be more upside to come on next year's forecasts, with future increases possible maybe?
Both brokers are forecasting 1.4p EPS this year, so that’s a PER of 25.7 times - that seems awfully high for a freight company. The reason seems to be that future years assume substantial further earnings growth, to a range of 2.6p - 3.1p for FY 06/2023. That would bring down the PER to between 11.6 to 13.8, which looks about the right price range for this sector. It’s a low margin, highly competitive sector that needs a lot of capital, hence why the shares should be valued on a PER in the low teens.
We’re being asked to pay up-front for 2 years’ future growth, and a doubling of profits. Why would I want to pay up for growth that hasn’t happened, and isn’t guaranteed?
DX looks fully, or over-priced to me. After such a stellar price rise, I’d be tempted to bank the profits now at 36p.
Note that the balance sheet is weak - when last reported at 30 June 2020, it had negative NTAV of £(8.0)m , calculated as NAV of £23.0m, less intangible assets of £31.0m. That limits its ability to pay future dividends, and increases risk. Note also the large lease liabilities.
.
Idox (LON:IDOX)
54p (up 1%, at 08:24) - mkt cap £240m
Quite good figures - adj EPS up 39% to 1.81p (LY: 1.3p)
PER 29.8 looks pricey
StockReport says consensus forecast was 1.87p, so looks a slight miss, but not enough to worry about
Outlook - in line with expectations so far in FY 10/2021.
Good H2 order book
Recurring revenues from public sector clients
Weak balance sheet - NAV £47.0m, less intangibles of £81.7m = NTAV negative at £(34.7)m
Lots of debt - long term borrowings of £35.1m, plus Bonds in issue of £11.8m. Although it also has cash of £30.8m - probably a seasonal spike, otherwise it wouldn’t need the borrowings.
My opinion - doesn’t interest me, due to weak balance sheet, unreliable/erratic historic performance, and negligible divis.
.
£MOON
An interesting company floating today, the popular greetings card app/website.
Priced at 350p per share
342.1m shares in issue = £1.2bn market cap!
Only raising £20m in fresh cash for the money. The rest of the shares being sold (148.6m shares) is selling shareholders, banking their profits. Let's hope it's not an opportunistic sale after the boost from covid? (I agree with MrC's comments below)
Prospectus is not on their website yet, but should be published later today they say.
Financial information available on Moonpig's investor relations website section looks remarkable - a rapid growth, highly profitable business.
My opinion - this looks very interesting, I'll be rummaging through the Prospectus once it's published. I imagine the vendors are delighted with the £1.2bn valuation.
Gyg (LON:GYG)
76p (down 2%, at 11:05) - mkt cap £35.6m
This company floated in July 2017, and so far I’ve never properly looked at it. Why? Too small, and I couldn’t see any reason why it would be a listed company. Taking a quick look at its Admission Document, the answer seems to be that it floated as a partial exit route for existing shareholders (£21.5m raised at 100p per share) and to raise some fresh money for the company too (£6.9m at 100p). Zeus Capital floated it on AIM.
It seems to have only paid a 3.2p divi in June 2018, and that’s it. The share price now sits 24% below the listing price. Therefore, it has not been a successful float, so far anyway, for investors. The vendors and the brokers did nicely out of it though.
As you can see below, it generates meaningful revenues, but not much profit. Are they busy fools, is the first question in my head? It claims to be the market leader in painting superyachts.

.
Looking at the shareholdings structure, a couple of things jump out at me;
1)Woodford fund seems to hold 20.0%. Is that an overhang? Or since cleared?
2) There’s very little free float, with about 80% of the shares concentrated in >3% holders, according to the company’s website. What was the point of floating it then, with such concentrated shareholdings? Zeus clearly didn’t give any thought to creating a liquid aftermarket, and most days there are only a few small trades.
There’s been a flurry of big blocks of shares changing hands recently, see the Holding in Company RNSs;
- Lombard Odier has increased to 26.19%
- Oryx International Growth Fund (run by Harwood Capital, activist Christopher Mills) also bought more, holding 17.16% now
- Lonsdale Capital Partners has sold its 16.77% stake.
Mills has a great track record of identifying undervalued companies, and often shakes things up, including lowish takeover bids from himself (e.g. Essenden, which I still bear a grudge about, as it was floated again at a much higher price, after he whipped it away from us in a lowball takeover bid a few years ago). However, Mills is very shrewd, so finding him on the shareholder register with a big stake, indicates that this share is almost certainly too cheap, and that something might happen in terms of a deal or restructuring, so I’ll have a closer look now.
Interim results 06/2020 - a quick skim of the figures reveals these key points -
- Hit by covid, so revenues down 12% to E29.1m (reports in Euros)
- Loss before tax of £(460)k
- Lumpy contracts
- Impressive growth in order book, and good visibility
- Net debt of E10.9m
- Outlook - confident in meeting market expectations
- Weak balance sheet, with negative NTAV of £(6.7)m, or £(4.3)m if we remove deferred tax liabilities - not good, but not a disaster either. It seems to get money up-front from customers, so probably OK to operate with a weakish balance sheet, providing orders don’t dry up
- Cash generation - nothing really in the last 2 years, which does make you wonder, what’s the point? The instis buying more shares must see some opportunity to improve performance, I suppose.
Full Year Trading Update - issued today.
GYG (AIM: GYG), the market leading superyacht painting, supply and maintenance company, today provides the following trading update for the year ended 31 December 2020.
This sounds a bit mixed -
Overall the Group delivered a robust performance and effectively managed the considerable disruption caused by the pandemic, albeit some Q4 projects were delayed into Q1 2021 with associated deferral in revenues. As a result, the Board expects to report revenue of €58.5m with Adjusted EBITDA also marginally below current market expectations, and additional COVID-related exceptional costs incurred during Q4.
The Group has focused on delivering further operational improvements and has started the new financial year well positioned to deliver an improved level of profitable growth.
What a pity they didn’t give us any figures for profits, or market expectations.
Many thanks to analyst James Tetley at N+1 Singer, for coming to our rescue, making estimates available on Research Tree, which is incredibly helpful.
FY 12/2020 forecast is E2.4m PBT, and 3.6p EPS (I’ve converted from 4.1 Euro cents) - that’s a PER of 21
Future years look more interesting, with a big rise to 6.3p in 2021, and 8.0p in 2022, which would lower the forward PER to 12.1 and 9.5
My opinion - the growing order book suggests it makes sense to expect growth in profits. If the forecast 2021 & 2022 numbers are achieved, then I think that could propel the share price up maybe 50% at a guess? So quite reasonable upside there. Maybe divis might be paid in future, if forecasts are hit?
Overall, this share looks quite good I reckon. Watching TV programmes about superyachts, it seems to become an obsession for the owners, who want bigger & bigger superyachts as soon as they take delivery of a new one, like spoiled children. Therefore GYG is probably well positioned to benefit from that fashion. Its order book is impressive too. This lends weight to the idea that profits could increase in the coming years.
To conclude, it gets a thumbs up from me. I can see the merit in taking a small position here, since it looks a decent GARP share (growth at reasonable price), reinforced by having a noted shrewdie on the major shareholder list (Christopher Mills).
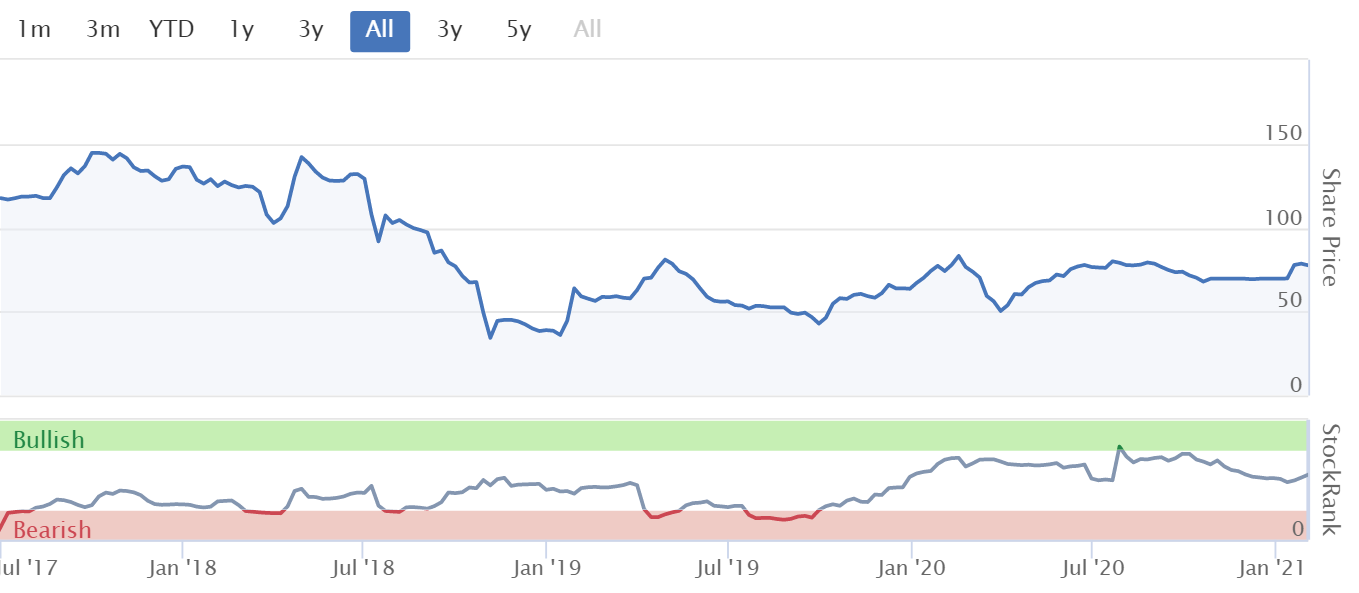
The StockRank is middling, at 54, although it almost got into the green zone (see below) in 2020.
.
.
All done for today. A couple more items from today will be in tomorrow's report.
Regards, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

102 comments
£GME
GameSpot plunges 60% at the close.
There's going to be some misery out there. I doubt the amateur traders will be able to fight off the pros.
It's not really about fighting of the pros, it's more about not being able to fight off reality. Glob Mar Ener Ord (LON:GME) doesn't have a business worth anything like the current valuation, nor is it ever likely to. So it really doesn't matter what reddit or hedge funds do in terms of long term valuation, there's only one way it can go.
Sure some of the smart ones behind the reddit play will have exited for serious profits, and hurt the shorts, but the end result for the vast majority of those jumping on the bandwagon was always only ever going to be losses.
£MOON
Looking at their last filing at Companies House Moonpig did approx £99m turnover, and had a pre tax profit of circa £17m.
That appears to be one hell of a multiple on old fashioned metrics.
Haven't seen the prospectus yet, so current figures may look better, but still....
Maybe they're planning to sell video games delivered by AI powered self driving electric cars recharged with renewable energy, which of course can by paid for with cryptocurrency.
Hi Paul
I did look at the Financials for Moonpig. I do know a little about the Co.
It was founded 20years ago by Nick Jenkins of Dragons Den fame who sold it for £42m in
2011. The buyer sold it to Electra & Exponent in 2016. I am always suspicious when a Company wants to talk about EBITDA and not profits. According to Retail News 19 Jan 2021 Moonpig predicts Net Debt at 30 April 2021 at X2.
The growth in business in 2020 was surely largely due to Covid with card shops closed for long periods.
Moonpig got the IPO away because Black Rock and Dragoneer agreed to be cornerstone investors at 350p.
The open price today was 440p and it closed at 426p down 5%.
I think this is worth at best £400/500m. I could be wrong of course but I will not be buying that is for sure.
Bona fide turnaround at Gfinity (LON:GFIN) (I hold) . They operate in a Esports – a very popular sector. New CEO who came in last year, John Clarke, formerly Heineken, has done wonders. Cut costs significantly. Self-helped. Rev down YoY because company departed from low margin biz.
Company had always had ability to bring in big name sponsors and have collaborations with Cadburys, F1, EPL, Abu Dhabi Motorsport Management among others.
They just had TU tody, 1st quarterly positive EBITDA in company’s history. Cashed up with £1.6mn. Company has found a new media section that only in Oct 20 was monetized and now is expected to bring circa £2mn rev (from advertising I believe).
Yesterday dipped likely attributable to being guilty by association to Bidstack (LON:BIDS) (I believe Bidstack (LON:BIDS) ) uses Gfinity (LON:GFIN) as an advertising media. Today, excellent TU. One of those, buy on the rumours and sell on the news, SP falls (now recovering).
John Story, renown investor, is an investor. Recently, the company appointed former GM of Apple Europe as NED (very impressive to have joined this small cap ) and beefed up their management team with a lady from Activision (big players in e-gaming). In addition, another bonus, is company is undergoing formal strategic review including potential sell-off to suitors. Therefore, TO could be on the cards.
SP chart says it all, could we be at the curve up from the trough? Anyways, besides all the hype of e-gaming (BTW e-sports will be appearing in the 2022 Asian Games ! ) , Gfinity (LON:GFIN) appears to be starting to find its way after many years of financial struggle.
Slightly outside the £400Mn small cap guideline at £553Mn/90p today but anyone got any views on Marston's (LON:MARS) takeover situation? Board apparently kicked back 2 offers pre Christmas but now 105p on the table. Board say too low as 19% below start of 2020 and since then Carlsberg JV and Brains leasing deals.
Since presumably the acquirer sees at least 20-30% upside, does this make it a buy and hold opportunity on 1-2 year basis (to recover) with a speculative upside of another bid in this order of magnitude in the short run.
I already hold at around current levels and was already expecting they will be a survive and flourish candidate within the hospitality sector which I expect to recover. I favour freehold pubs (around for 1000 years) over largely leased fast food/casual dining. Plus most of Marstons assets are suburban/small town based - a good place for pubs to be.
Personally, I support the Board. I don't think the current offer price is attractive. Would need to be >130p to be interested.
Totally agree with your points. Was previously a holder to December 2019 and sold on the share price starting to weaken at that time (at 125). Have just bought back in as I see good upside now. Additionally the other consolidation in the sector is persuasive that the value in the overall sector is now being recognised. And the management seem to have managed competently during and since the first lockdown last year.
Marston's (LON:MARS)
I have been a long term marstons holder (somewhat fanboy) - i would say its a tricky situation - debt has always been the elephant in the room with them - this wasn;t really an issue pre covid as it most mostly very long term dated stuff that in theory the cashflow from their "newer pub estate" and brewing should have conformtably been able to manage through to 2030.
There was always the divi as the backstop.
They havent really done as well as i would liked debt wise but not really an issue pre covid.
Obviously covid is a spanner in the works (and possibly an opportunity at the same time to take over from other operators who throw in the towel) - they have sold part of the crown jewels with the deal with the devil (Carlsberg) - i think they got a very decent price but the problem is that money will partly have been consumed by covid troubles.
Personally i dont think its worth as much as it was pre covid - but it might be we just have to see how it all pans out. Main risk here was that they needed to raise funds when shareprice was lower - hopefully carslberg deal will see them ok.
Would i take 105p now for my shares - probably not but based on where price has been last 6 months its not a ridiculously lowball offer. If they strugle in a post covid world or with ongoing covid world there really isnt ANY real downside proection with this share due to the level of debt. Although i would like to think that IT shoudlnt really be an isue if pubs ar 90% back to normal sometime in next 6 months give or take.
As you say i think the board have probably done the right thing playing hardball - and i would agree 130p in current climate would probably seal the deal. Shareholders should be under no illusions that with current uncertainty that short/medium or even longer term the shareprice may perform very poorly when compared to that 105p offer. We need to get back to proper unrestricted drinking days for us to expect Mars to be back somewhere near it was at 140p plus - those days seem long gone at present.
The Marston's (LON:MARS) bid is intriguing. One might have expected the share price to race up to 105p or more in the expectation of other parties joining the fray. Covid has made it much more difficult to value. Also if the Board is determined to stay independent at all costs then I'm sure something could be sorted with Carlsberg and I don't think even a cash rich PE house would fancy a fight with them. From memory Marstons now has a 40% interest in the brewing business. If the bidder is successful would they want to retain this. Suspect the Marston's (LON:MARS) people will be taking soundings from their larger institutional holders to gauge their views.
Thanks for thoughtful response re Marston's (LON:MARS) I think your phrase "We need to get back to proper unrestricted drinking days for us to expect Mars to be back somewhere near it was at 140p plus." is correct. As with so much, it depends on Covid.
If this summer is good (my hope!) and travel to Europe remains limited but the UK lifts most restrictions (meaning Tier 2-ish), my expectation is that Pubs with gardens will do an absolutely roaring trade. You can buy a lot of pub lunches with what it costs to fly to Spain. Marston's (LON:MARS) will boom and the share price will follow it up and divis resume. If SA Covid keeps us all in masks, far less fun and much less/no upside on the share price.
The 2nd question I guess is how much competition will actually go under. Although the hospitality industry has been hit terribly hard and claims X% of outlets will close by Y, so far with govt helpthey have done just enough to survive and promise the bank manager - "give me this summer to trade my way out". The banks know that foreclosing will not give them great assets to sell in a slump whereas squeezing them via charges is very profitable.
£mars - where does the offer figure of 105p come from? It feels cheap but valuation is difficult because of the evolving Covid. I hold
Reckon you have hit the nail on the head - Marston's (LON:MARS) This summer with most of us staying in UK - be they holidaying in UK - or simply staying at home - the pubs/brewers stand a good chance of catching up - including supermkt sales for home BBQs. But who knows - things are changing by the day.
£MOON I bet the vendors are delighted at £1.2 BN valuation Paul. Madness in my opinion.
Cards normally fail just look at Clintons and Card Factory.
Moon is for lazy people but £1.2BN is just crazy.
Hi portugull,
Have you looked at the financials for Moonpig? It's growing fast, and making big profits.
We can't dismiss the valuation without crunching the numbers, after all!
Is this sutainable, or a flash in the pan? Last 6 months figures on the right are stunning!
Regards, Paul.
.
Also, when googling Moonpig I discovered it is having an issue with customer behaviour as we near Valentines Day:
Hi Paul, I agree, the val made me wince initially , but who is driving sales. ? Moonpig has a fanbase similar to BOO and ASOS - a younger crowd who send cheap personalised Xmas/bday/special event/jokey cards .My teenagers and their mates use regularly so def. worth a closer look.
Paul , please don't tell me that warning from Moonpig was aimed at you ha ha !!
Robbie the Naked Trader writes on his website he is going to put a giant short on £MOON if its valuation soars to £1bn. By what i see here on SCVR, I guess there is a market.
Re Card Factory (LON:CARD) vs £MOON I would have a much simpler, more profitable plan. If I had £1bn in capital to splurge. Rather than invest in Moonpig, I would rather :
1. Pay off all Card Factory debt - £175Mn.
2. Invest £5MN/month for the next 5 years (5x12x5) = £300Mn to promote my brand online and exploit my 86% brand recognition. This will also drive traffic to my hugely profitable (outside of COVID times) offline stores where I can hope to have a nearly 50% market share in a few years as my offline competitors fail or struggle vs my integrated low cost operation and now heavily advertised brand (Clintons, Cards Galore, Paperchase etc) . Online stores still expected by Moonpig to be selling 80% of all single cards by 2025! See their market report from same consultants as Card - 10% online share now growing at around 13% CAGR post Covid = 20% (v roughly - see report for accurate numbers assumed)
3. Upgrade my website further and pay a top notch CEO, Mkt Dir and app developers/data analytics team an obscene amounts to defect from Moonpig and do anything my just relaunched system can't do £25Mn over 3 years. I have much more customer data to harness from all my stores - I just haven't leveraged it properly yet.
4. Retire to the beach with my remaining £500 Mn (1200-175-300-25=500)
What CARD has lacked is a bold and entrepreneurial CEO. It has a new one coming but I don't know what they are like. I hold so I hope they are better than the previous 2 CEOs who have been very incrementalist. Just adding 50 stores per year and cutting some cost. Worthy but dull.
I hold CARD and may buy more if £1bn is what Moonpig is worth.
brilliant! I would give you 100 thumbs up if I could. I do not hold Card Factory (LON:CARD) but watching closely how the refinancing will pan out.
Excellent comment. As you say previous CEO's had no spark about them.
You really can't compare £MOON to Card Factory (LON:CARD)
Yes, you can buy cards on both websites, but Card Factory is more for buying non-personalised cards and boxes of cards.
If you try the personalisation feature on both websites, you'll see that £MOON is streets ahead.
If I had to make a comparison to the grocery sector, Moonpig is like Ocado, while Card Factory is like Aldi or Lidl. Nothing wrong with being Aldi or Lidl, except they've had the worst luck with COVID.
"Moonpig is like Ocado, while Card Factory is like Aldi or Lidl. Nothing wrong with being Aldi or Lidl, except they've had the worst luck with COVID."
Agree - except I would see Card Factory (LON:CARD) as Tesco - by far the largest share in the overall market, targeting the main mass market (pre-printed offline cards) but including premium /niche ranges (online).
Luck, CEO's and website functionality change; market share and changes much more slowly.
Hi portugull. Re £MOON I don't hold
Another advantage of an online card (FOR THE LAZY or SKINFLINT) is getting it posted locally in Australia or New Zealand (Or them over here) - We had a couple arrive in time for Christmas that way from Down under. The ones posted before the snail mail deadlines only arrived mid January. I know which business my children prefer to use. Think Global
Hi Paul, I wondered if you were going to look at Dr Martens? I don’t think it’s been loaded up on Stocko yet. Another strong IPO debut, though coming from private equity always makes me wary. I think they claim 60% of their business is online.
Hi MH1,
Yes I've already looked at Dr Martens, it's here:
https://www.stockopedia.com/co...
Regards, Paul.
Many thanks! Missed it:)
Mike
I have seen a lot of poor reviews of the Chinese made Doc Martens boots in various sources. Their Trustpilot is also poor: https://uk.trustpilot.com/revi... . Also the private equity factor. Would not touch them.
Those trustpilot reviewers are really putting the boot in ...
I don't agree that Dx (group) (LON:DX.) is over-priced at the moment although arguably the price is up with events. My reasoning is much of investment is about the direction of travel for key metrics. So earnings increasing, debt falling, returns on capital stable - that sort of thing.
With Dx (group) (LON:DX.) we know that forecasts are lagging operational performance because the 2021 forecasts have just been raised 14% (from 1.06p to 1.21p). This puts them back to where they were pre-Covid and up 167% from the April low when all forecasts were slashed. Since we're only halfway through the year it's pretty likely that these numbers will be raised again.
For the 2022 numbers the forecasts are not yet back to pre-Covid forecast of 1.8p but I suspect that they'll end up at 2p or above making for a forward P/E ~16. My reason for believing this is that the business turnaround is demonstrably working for both sides of the business. This means that rather than Freight losses outweighing Express profits (and more) both parts of the business are now profitable which is a double benefit to the bottom line.
Hi Damian
I am a current Dx (group) (LON:DX.) holder but as always a ~10% drop in a day is ouch.
I guess the question is do you back the turnaround here? Which is where I am at personally. I had taken profit from my original stake to reduce back to a ~5% of portfolio holding (medium sized position for me). On the basis of lets just see where it goes from here as I think there is potential or a 2-3 year basis, e.g. standalone continued performance, opportunities to buy others and opportunities to be bought themselves.
I agree the pricing is probably ahead against this year, but this has been with several upgrades in recent months. But forwards facing would appear reasonable to good in my opinion.
For comparators I would look at Clipper Logistics (LON:CLG) is PE of 20.6 and up ~3% today. Wincanton (LON:WIN) is PE of 8.8 but has a large pension deficit from memory. As for Eddie Stobart Logistics (LON:ESL) that is a different discussion page in its own.
Cheers
Tommy
Hi Tommy,
You're right that it's all about the turnaround here. Fortunately management are very experienced on this front (having done it before) and they've put a lot of personal money on the line. Since I started following them about a year ago every update has been more positive than the last - which suggests to me that they're reaping the benefit of three years hard work. Also management are definitely not finished yet and are motivated to make this a higher margin, more cash generative outfit.
Clipper Logistics (LON:CLG) is an interesting company although very different from Dx (group) (LON:DX.) - both are doing well from our general switch to online shopping and deliveries.
Cheers, Damian
I got an email from IG this morning which was interesting (Key excepts below):
We are in the midst of an unfolding situation in global markets which is attracting a significant number of new traders to trading platforms to buy particular stocks in a coordinated way.
This has caused a significant increase in trading volumes and demands on our platform.
3.
We have temporarily paused new account opening so that we can focus on providing our existing clients with the service they deserve.
We have also made the difficult decision to temporarily suspend new trading on GameStop and AMC Entertainment.
Whatever way you look at it, we may be seeing a massive new customer recruitment drive to spreadbetting sector akin to March/ April last year. That boost was enormously valuable because these customers were "free" (i.e. no marketing recruitment costs). The media attention and "stick it to the man while getting rich" storyline appears if anything even more infectious (I've had multiple people asking me for advice over past week who never traded before).
I hold Cmc Markets (LON:CMCX) Plus500 (LON:PLUS) Ig Group (LON:IGG)
A view for what its worth on this subject. At the moment we have a 2 tier system for equity trading. On the one hand one set of traders are paying stamp on the purchases and CGT on the profits. The others that are using spread betting are doing neither. Is this something that the government in the current fiscal enviroment could look at.
I'm watching the chatter on Rishi's budget (3rd March) like a hawk at the moment, Trevor. It's extremely hard to pick which way it will go - will he start moving taxation up or is it still too early because of CV19 disruption. My guess is that there will be a few headline moves but the economic risks to the UK are still too vast to start loading tax on - more likely in my opinion to reduce tax burden than increase right now because of Covid/ Brexit disruption.
Specifically on stamp duty, this still has to be paid now if the platform moves the trade to the market - the price is just covered for you in the spread. On CGT if they tax, it means the customer can also write off losses against liability. Since most people lose money spreadbetting, the government has no incentive to do this.
Seen that argument before about most people losing money on spreadbetting - but surely only a few of those that lose are likely to have capital gains to offset the losses against, so I'm not sure what the treasury loses in cash terms. For the apparently small number of people who spreadbet profitably, they are likely more professional and make bigger profits so seem to me to have a big advantage in not paying CGT (especially if CGT rises).
You may be right. Certainly, for me my trading is SIPP (longer term holds typically 1-2+ years), ISAs (shorter term trend following typical hold period 2 - 6 months) and spreadbetting for short term stuff to avoid tax. I don't do any trading outside of these and therefore pay no tax. The spreadbetting is easily the most profitable (by a massive factor) of the three strategies.
Hi Trevor, there is no way the Govt would want to tax spread betters as 70% + lose money.If CGT were due then most spread betters would be offsetting their losses.If HMRC deem you to be trading as your main income you may have to pay income tax on a self employed basis.Careful what you wish for - if you see spread betting as a loophole to reduce tax then use it !
Thanks for all for your comments. First time that I have posted and grateful to you all for your wisdom.
And you have CFD's with capital gains tax, but no stamp duty.
Hi Paul, I notice an interesting trading update from Gfinity today. Any thoughts your end? E-sports dong well, but their comment about profitability not always assured was interesting.
Gfinity (LON:GFIN) - Per RNS - As a result, on an adjusted EBITDA basis, Gfinity was profitable for the final quarter of the 2020 calendar year. Whilst this is a strong performance, the Company notes that due to the project-based nature of the Company's revenue streams and some seasonality in the business in the short term it does not imply the Company will always be profitable on a MONTHLY basis going forward.
This infers to me is that there may be some MONTHS that are profitable and with seasonality, some MONTHS that are not profitable. So in some quieter quarters, they may not be profitable. This is very natural for all businesses.
So I presumed John , the CEO, was simply managing expectations of PIs and not to expect month in month out profit to be benchmarked standard.
Fair play mate. Thanks for your view
You're right about the lousy balance sheet at Staffline (LON:STAF) which is a legacy of past management. However I don't think that you're giving the new management much credit for examining the business from top to bottom and coming up with a route back to profitability.
The best way to understand the challenges, and opportunity, facing the board is to watch their recent Capital Markets Day: https://webcasting.brrmedia.co...
In short the underlying business remains strong but there was a lack of investment and joined-up thinking with the previous management. Now they are focusing very intently on working capital and cash-flow while getting rid of unprofitable contracts and breaking different business units out of their siloes.
Clearly it's early days in the turnaround for Staffline (LON:STAF) but I don't think that the shares should be avoided even if a fund-raise is in the offing given the potential risk:reward.
Staffline (LON:STAF) - why take the fundraising risk though Damian? If there's not much appetite for the next fundraising, then existing holders could see horrible dilution in a deeply discounted fundraising. I cannot see why any investor would want to take that unknowable risk at this stage.
I'm sure new management are doing a good job. They've managed to stop it going bust, no mean achievement. I'm happy to look at it again, once the balance sheet is fixed.
Yeah it's a fair point Paul. A messy fundraising is one potential outcome. On the other hand it's clear that the CFO is extremely focused on sorting out working capital, cash flow and the balance sheet. Moving to invoice financing, away from an RCF, is one element of that process. It's possible that Staffline (LON:STAF) will be able to trade it's way to profitability without further dilution but it's certainly a risk!
And the Next (LON:NXT) chart.
This has already been moving with some momentum, so personally I'd prefer to see a consolidation and squeeze back to the 50SMA.
If it does keep moving higher, a break above the recent could be a viable entry, but considering the distance from the 50SMA, a pullback may not be far off IMO.
Greater volume is seen on the up days, lower volume on the down days, which is constructive.
Over a £billion market cap for a greetings card company is ridiculous in my opinion. (£MOON) - It is obviously positioning itself as a 'technology' company with "proprietary technology platforms and apps, which utilise data science capabilities" - It basically allows customers to personalise cards!! Cards do not seem to do well as stock market investments : Card Factory (LON:CARD) & Clinton Cards for example. I think that they are floating at the best time possible for them to benefit from the lockdown boost in business.
Is this a business that Warren Buffet or Nick Train would buy?
No Way!
No!
£MOON
I am/was inclined to be very cynical about this IPO (as I am with all IPO’s) but I think the company has possibilities.
The 2020 P&L shows sales up £53m (up 44% on 2019) & PBT up £17.8m (up 130%). I think that gives a PE of about 38. Management are predicting revenue growth of between 30% and 34% in 2021 & 34% and 38% in 2022.
If that drops through to the PBT line as it did in 2020, then this might be reasonably priced.
Further in the six months to Oct 2020 revenue was almost the same as the FY. Six month revenue to October 2020 was £156m versus £173m for full year to April 2020 (6 months to Oct 2019 revenue was “only” £66m). This leaves them “just” £76m to do in the second half to hit their 34% growth target. So based on H1 and H2 being evenly split it would appear that they are going to easily exceed the target.
This of course could be a Covid effect but my understanding is that most people under a certain age never go into a shop and buy a physical card, they use Moonpig. I have only used it a couple of times. Once when I used the option to print my hand writing on the card, you could hardly tell it wasn’t written by me rather than printed. I liked the service I just don’t send many cards.
Addressable market is £2bil in cards alone (£53b in gifting) in their geographical market. Do they have any competition in the online market? I cannot think of one and I certainly think that there is high brand awareness.
The company does not seem to be over burdened with debt.
They have 403 employees (at the last half) which gives revenue per employee of £429,575 and PBT per employee of £78,846 based on 2020 FY figures. But based on half year figures these may be much higher (double). This seems pretty impressive. Fevertree Drinks (LON:FEVR) have £1.37m/employee. Bioventix (LON:BVXP) figure is £644k/employee
I have only skim read bits of the document this morning so may well have missed something but I actually think this could be quite interesting investment on a three year view.
Registration document (all 162 pages of it) is at:
https://www.moonpig.group/medi...
I do NOT hold
"Do they have any competition in the online market? I cannot think of one and I certainly think that there is high brand awareness."
Funky Pigeon, Thortful, Scribbler and Etsy are competition that I can think of. FP cards can be personalised in the same way MoonPig ones can, Im not so sure about the others. But in the past, Ive used all four of those Ive mentioned much more than Ive used Moonpig.
And actually, Card Factory (LON:CARD) themselves. I gave up on them when I saw how much they weren't putting into their digital offering.
Re Card Factory (LON:CARD) vs Moonpig online - watch out for 2 potential catalysts that will make them much more competitive
1. New online site this year that is much better and cheaper than Moonpig. Low awareness of this as yet. Card Factory also has cost advantages from scale and integrated production of the cards.
2. New CARD CEO stating in March (from memory). The latest Capital Day strategic refresh led by the interim was indeed very underwhelming on Digital. SO much so that it is an easy bar for incoming guy to beat expectations on
3. In 6M when shops are open again, CARD will be generating cash again - it can fund an online war, despite its debts and it has by far the strongest brand amongst 'mass consumers' of cards like Mum's attending endless birthday parties (vs younger or tech savvy Moonpig customers). So yes the market is moving online but still surprising early stage.
Worth looking at its pre-Covid presentations and market research in the analysts pack on the size/value of digital to physical cards.
Moonpig IPO timed to sell at the top of an online Covid driven surge? Why sell so much if the future is so bright - they don't need the money for new CAPEX.
I have heard of Funky Pidgeio and Etsy (though would not imediately think of either if I wanted to send a card online) but not hear of the other two.
I will be watching from the sidelines but will be interesting to see how it plays out.
Great analysis! It does indeed look like an interesting business and it's not saddled with a mountain of debt, like many PE floats. However, for me the biggest red flag (in addition to low barriers to entry, lack of any LT 'secret sauce') is in that latter acronym - 'PE'. Time and time again PE floats have demonstrated that the sellers are usually the smart money and the institutional buyers are the dumb money, be it as to the quality of the business or just market timing. Just look at Debenhams and Trainline to name just two. My question would be if such phenomenal growth can be maintained in the mid-term why are Electra / Exponent exiting right now. I mean think how much more nominal £ return they could enjoy by just holding the business for an additional year or two more. Now they would probably argue that they bought at the back end of '15 and hence it's not an unusually short holding period. So just their usual MO. Not unfair. But ask yourself is it nor more probable that Covid has given the business a massive one-off turbo charge boost and the capital markets are nicely frothy. To me the fact that they have chosen the IPO route rather than a trade sale is also an indictment in and of itself. A trade sale is always nearly always preferred by PE as it offers a 'clean' rather than 'stepped' exit. An IPO exit is more time consuming, expensive and uncertain. And yet they chose it. Could it be because they knew it would be catnip to UK fund managers looking for the next digital B2C 'growth' story!? Sorry, call me an old cynic but I've just seen this movie play out too many times before...
Interesting to put Next, ASOS , Boohoo (and Burberry as a different play) into the Stocko comparator. Next is clear winner https://www.stockopedia.com/co... . But Boohoo (I hold) much higher on Quality and Piotroski score. Marks and Spencer are starting to bring some different brands in so they may go down this route too.
Next (LON:NXT) was one of the few companies I bought in last years March lows- I bought it as a buy and hold but in typical fashion sold it at around 20% less than the recent peak. My thinking was that I couldn't see where it's growth above the 2019 revenue was going to come from and I struggled to justify it's valuation. If memory serves me right revenue was remarkably consistent for a few years pre 19 so given its revenue and earnings growth declined significantly last year it seemed sensible to use the 2019 figures as a reasonable short term ceiling. Perhaps it's existence as one of the few remaining retailers on the high street could help justify the current price but footfall is bound to be badly hurt for the foreseeable future.
There was a mention of international growth but I believe they tried international expansion in the 90s and it didn't go too well for them. The overseas expansion they're seeking now might be more successful given its primarily online but we'll just have to wait and see.
I agree on Asos (LON:ASC) I think it is and Topshop/ topman are remarkably strong brands which will be around for a long time to come. An additional £1 Billion of own brand revenue would do do wonders for their earnings. Let's just see how much of that revenue converts online. I'm reasonably confident a good proportion will given that they are retaining certain suppliers and near term orders- meaning it's existing customer base will get more of the same. I find the chinos hard to beat for example and will be purchasing some more safe in the knowledge that they'll likely be the same fit and material as they have been for the last 5 years or so.
Here's the Asos (LON:ASC) chart.
Looking quite constructive to me.
It's been consolidating since August / September last year, within a 20% range.
A break above 5600 should see the next leg up IMO, but personally I'll be looking out for potential entry points below the breakout level to start building a position.
Pandemic fashion changes are going to be included in business school case studies for years to come.
I concur with comments about JD Sports Fashion (LON:JD.) (I hold). I am not too clear on how they have continued to be such a successful player in the athleisure market, nor how they successfully replicate this in their overseas operations. I think that they have one eye on post-Covid where their stores will become go to places to see the latest designs in trainers etc. that young adults aspire to own. I think that there’s still going to be a role for physical retail shopping as a leisure activity once we are out of lockdown, particularly if there’s an experience aspect to it. We’re used to seeing some online exclusive offers. I can see that flipping and becoming physical shop exclusive offers.
Interesting little story on pandemic fashion on the BBC basically demonstrating the need to be nimble.
https://www.bbc.co.uk/news/newsbeat-55773751
I like the comments about online retailers. I still hold Naked Wines (LON:WINE) and I am astonished at the growth. I bought at 220p and today it is at 731p. The key to their success was the unique operating model. The challenge will be scaling supply to meet demand, maintaining quality and retaining customers post Covid.
These online fashion platforms have virtually unlimited ability to add brands and product categories. They can target new demographics as we have seen with Boohoo. The global supply is enormous. The high street is decimated and I can't see a return to big stores on the high street. Some flagship stores for brand awareness maybe.
Funny how when you call something a "marketplace" it attracts a high valuation.
Yet for all intents and purposes, it is basically a "department store", where you also have different brands, most of them on concession agreements where you don't take stock, cost, volume risk. Just that it resides online, instead of bricks and mortar.
Surely a department store is just an inside market?
RNS Reach from Novacyt SA (LON:NCYT) (I hold).
Essentially it sounds like they are rolling out a test that specifically looks at DNA markers that identify particular coronavirus variants. Distribution to the research market first then the wider market once approved.
Their existing PCR test detects the different variants. This new assay tells you which variant you’ve got.
The advantage is basically speed of the test result (compared with current tests that can distinguish between these genetic variants, which have limited capacity) and that it can be performed locally helping to track the spread of the variants.
The share price took a bit of a tumble when the trading update was not as upbeat as expected. Although, this new innovation may not be materially significant yet, it does bode well for the future, demonstrating the company’s ability to keep innovating at the leading edge of its market. So, the market likes it.
Still in the balance as to whether the company kicks on to become a significant player in the diagnostics market once the situation with Covid is under control. But it looks like there is a good chance that they will. Their increased presence in labs all over the world should provide an excellent base to sell additional diagnostic tests. They are also making substantial profits that can fund acquisitions. The other possibility is that they may be acquired themselves.
Novacyt Sa (LON:NCYT) has been amazing for investors over the last year. I hold although not as much as prior to the results. There are two issues for me. Firstly, the market cap of over £600 million discounts a lot. Secondly, where next after covid testing? This is key I think. Over 65's will be called for vaccination in the UK next week. It will not be long now before all 50 plus in the UK are called. The UK has now bought 400 million individual vaccines for a population of below 70 million. Testing is still going to be needed for a good while but competition is fierce and the World is full of testing kits. Move on 18 months and what will the company be doing? The management has proved itself to be agile and well above average. They may already have seen other opportunities.
forecasts are for around net cash of 400m end ‘22 so in theory if they use this to buy back shares to get to zero cash the PE is 7*
Moonpig interests me. I think this is the future of the physical card. Online and personalised. However, does the physical card have a future in the long term?
Morning Paul,
Don’t forget £jd (JD sports) as another leading market place online retailer, with quite a niche - the high end trainer/sports wear market. This is a huge market, taken very seriously by some and somewhat underestimated or misunderstood by some (older) investers. I think they are targeting a slightly different market to Boohoo (LON:BOO) and Asos (LON:ASC)
They have also recently made some good purchases to move into the USA market.
I hold, as you may have guessed.
Someone forwarded me a very interesting article (many thanks) over the weekend, pointing out that online fashion in the UK is concentrating into “platforms”, or “marketplaces”, which sell multiple brands, as well as their own brand.
Paul, Which publication carried the article pls? Would be interested to read it.
Might have been MoneyWeek possibly? It didn't really add a lot of detail above what I already mentioned - just that the winners are emerging as not just websites selling their own fashion items, but a curated marketplace for many other brands too, creating a one stop shop for customers.
This is the moneyweek article if this works
https://reader.moneyweek.com/2021/01/25/city-view-241/pugpig_index.html
Good morning,
Excellent results from £Sure this morning, will you have a look please Paul?
Regards.
Sure Ventures (LON:SURE) - It's on the list. A rather boring company that has struggled a lot since floating, so I wouldn't get over-excited about it. Used to be called Lakehouse I think. I'll try to do a brief review of its numbers later.
Paul, I believe John Doe is referring to Sureserve (LON:SUR). Yes, this used to be Lakehouse.
Yes, Sureserve, thanks for that!
I believe from my look through this morning that Paul has previously mentioned its a low margin business of not much interest - Check the Stock Report and then click on Discussion - As I say, this is from early morning memory.
Hi. Low margin yes, however, strong performance ahead of expectations, no debt, dvi doubled, growing order book, profit and EPS growth...
Creightons (LON:CRL)
Innovaderma (LON:IDP)
Interesting M&A activity at the tiddler end of the market.
Arguably the merger looks beneficial to both, but Creightons (LON:CRL) not being particularly generous to Innovaderma (LON:IDP) at the moment. Interesting line of defense for the Innovaderma (LON:IDP) board (given all share) would be "How can we advise our shareholders when Creightons (LON:CRL) do not disclose any forecasts to the market".
Phil
(I hold £CRL )
Arguably the merger looks beneficial to both, but Creightons (LON:CRL) not being particularly generous to Innovaderma (LON:IDP) at the moment.
Well, Innovaderma (LON:IDP) are trying to get a placing away at 35p a share. The offer doesn't look that unreasonable, particularly when the Innovaderma directors haven't informed their shareholders of the alternative.
timarr
Timarr,
Agree with the comments about the offer not being particularly generous, the market has responded and no doubt Creightons (LON:CRL) (I hold) will need to up the ante if the acquisition is to progress. Innovaderma (LON:IDP) seems a really good fit for Creightons (LON:CRL) and has some great brands (which are probably undervalued based based on the current MCAP valuation) additionally a great way to continue building on £CRL already impressive growth.
watch this space.
Innovaderma (LON:IDP)
Thanks Timarr - wasn't aware of that - makes it more interesting.
Creightons (LON:CRL) won't get Innovaderma (LON:IDP) unless there is major shareholder support for the deal and my guess is that this isn't likely at anywhere near this price. Mark Ward has only just bought 12.5% of the company and become a director and he is underwater on the trade. With the placing done they don't need Creightons (LON:CRL) cash and they've just replaced management who are equally unlikely to want to be replaced before putting their strategy/mark on the business. Plus it is an all non cash offer. That's very unattractive to individual shareholders particularly as Creightons (LON:CRL) hasn't exactly blown the lights out over the last few years (though they've done better than Innovaderma (LON:IDP) ). I'd guess they would have to pay circa 70/80p as a share deal to get it. Somewhere around 10-11* pre pandemic earnings, but I doubt they will want to pay that as it will mean Innovaderma (LON:IDP) shareholders owning 30% of the overall business.
From an Innovaderma (LON:IDP) perspective if you believe in the value of the brands and your ability to grow revenues post pandemic then there is far more upside to staying a separate company. If I recall they were doing very well prior to retail lockdowns and probably don't wish to throw in the towel at the low point. I can see Creightons (LON:CRL) growing steadily going forwards, they look like a respectable enough business, but can see Innovaderma (LON:IDP) quadrupling from here if they even get it half right. Not sure I'd want to trade that optionality at this stage.
RE: Innovaderma (LON:IDP)
With the placing done they don't need Creightons (LON:CRL) cash and they've just replaced management who are equally unlikely to want to be replaced before putting their strategy/mark on the business. Plus it is an all non cash offer.
Well, obviously, otherwise they'd have announced the Creighton's offer, noting that the latter specifically indicated that they wouldn't criticise the management if they did.
The whole thing is a bit curious but I suppose it puts down a marker for Innovaderma's management. And it might bring other bidders out into the open.
timarr
yeah it is a bit odd. I can only think Creightons (LON:CRL) published the letter to try and force Innovaderma (LON:IDP) management to discuss it further with them but it doesn't strike me as a particularly good way to get the other side on board.
Don't need the other side on board - if the institutions go for it, it's a done deal.
Though, having said that I note there aren't many institutional holders listed on the Stockreport.
That's the point. The largest guys - make up around 25% (over half is one director) won't wish to play. Thus you have got to get 76% of what are most likely very small shareholders to agree even just to get majority control. That is massively unlikely through (a) inertia and (b) better risk/reward sticking with standalone entry.
I hold some against my better judgement and I would vote against. Only a poll of one granted but I'm active.
Now give me 80p in an all share so I can participate in the upside and I might become tempted
There was an innovaderma holdings RNS on 18 January saying that Roger Macdowell (the non exec chairman of Brand Architekts and many other appointments) had increased his holding to over 5%. Maybe there will be more than one interested party.
Bearing in mind that I'm a Boohoo (LON:BOO) holder, does anyone know what the impact of the proposed Buy Now Pay Later regulation might be? Looking at the money.co.uk report Boohoo brands are the ones that get the most mentions:
https://www.money.co.uk/guides...
It's also clear from that report that the age group with the most BNPL debt is Boohoo's target demographic.
I also wonder how long it will be before the government acts on retail business rates. The discrepancy between the High Street and warehouse led retailers is striking. At this point it would be shutting the stable door after the horse has gone on a round the world tour but the loss of tax revenues will presumably force a change here sooner rather than later.
And, of course, there are going to be secondary effects. The ASOS purchase of Arcadia brands yesterday means 13,000 people are made redundant on Thursday along with all of the other people in retail in the same situation. This has got to have an impact on the economy as unemployment spikes, surely?
The markets don't seem to be pricing any of this in, at the moment, which seems a bit complacent.
timarr
Timarr,
I think there are several risks associated with fast fashion (on a medium term basis) which are underpriced in a rapidly evolving world.
1. Buy Now Pay Later - the Woolard Review into high cost credit published a 68 page report this morning https://www.fca.org.uk/publica.... (I am interested from the POV of unsecured credit lenders like Non-standard Finance (LON:NSF) ). I have not digested it yet but first glance says BNPL regulation will be introduced and possibly onerous - see below. If BNPL gets tagged with causing 'harm' you can expect action and regulation. Broadly I expect Woolard to say any product that acts like credit needs to be regulated like credit, making it much less agile and costly to implement
There has been significant growth in unregulated BNPL products
in recent years. The products and business models in the market,
as well as those which may be developed in the future, can lead to
harm. Regulatory oversight is appropriate to ensure that the product
develops in a way which is beneficial to the end consumer. As a
matter of urgency, the FCA should work with the Treasury to ensure
the necessary amendments to legislation are made to bring BNPL
products within the scope of regulation. Once the necessary powers
are obtained the FCA will need to develop a proportionate regulatory
framework including addressing how credit information should work
within this market. In defining the regulatory framework for BNPL,
the FCA and the Treasury should take care not to include other nonfinancial organisations that rely on the current exemption, including
healthcare services and sport clubs.
2. Online taxation - Must be coming in some form to raise revenue and hel d bricks &£ mortar retailers (buy offsetting return of business rates at previous levels). A tax of 50p /delivery has 3x more impact on an order of £33 than £100
3. Environmentalism - Growing realisation that fast fashion has negative consequences for the planet (water use, waste generation, labour exploitation). As Paul says these are inherent for ALL retailers and most consumers do not care. But a segment does and politicians do. Measure to reduce consumption will affect cheap goods ie disposable fast fashion the most.
For this reason whilst I buy the platform argument and the Boohoo (LON:BOO) market appeal I prefer Next (LON:NXT) consumer and product base as being better over time (unless BOO are so successful they move up to cover higher price successfully. I understand £ASOS less well.
Having now read the Woolard report in full, it absolutely nails BNPL and calls for urgent action and for this to be included in the next possible parliamentary bill - The Financial Services Bill. This has already had second reading I think and is in line by line committee review. Woolard saw tackling BNPL as so important he has written to Committee already about it.
"Innovations in the market can bring significant benefits, but also pose potential
consumer harms that need to be addressed as soon as possible. In particular, the
unregulated BNPL market more than trebled in size in 2020, poses potential harms
to consumers and needs to be brought within regulation to both protect consumers
and ensure it is sustainable. " (No 1 reco, P6 of Woolard report)
Bonitabeach
Good news for N Brown (LON:BWNG) who, I believe, are regulated?
Not if they also introduce stricter regulation on who can BNPL be sold to, how much, an interest rate cap, stricter rules around chasing delinquent payments, etc.
Looks like Boohoo uses a third party, called Clearpay?
The other big players in the market is Klarna and Paypal Pay in 3.
It would be interesting to know how much Boohoo (LON:BOO) gets in terms of commission / fees for every BNPL transaction that goes through Clearpay.
Presume if Clearpay suddenly disappears, or criteria to qualify is a lot stricter, this will reduce the basket size and conversion rate of Boohoo.
It would be interesting to know how much Boohoo (LON:BOO) gets in terms of commission / fees for every BNPL transaction that goes through Clearpay.
Boohoo don't receive commission. It's the other way around.
BNPL is free to the customer at the point of sale and the companies make their money by charging the merchants (i.e. Boohoo) a fee - somewhere between 2% and 8% of the price. There are late payment fees for customers and various other charges if they're not careful.
Compared to credit card fees, at the lower end that's not overly onerous, especially as the refund process is a lot easier and cheaper - and given the rate of returns on fast fashion that's not to be sniffed at.
The big benefit, however, is that BNPL results in an uplift to basket size - somewhere around 30%. So restrictions on BNPL will cut revenues, although how much is unknown as there don't seem to be any public figures about how much money Boohoo or any of the other fashion brands collect using the various methods.
BNPL isn't going to disappear, but if it's classified as credit - which it is - then it'll be less attractive to use. However, given that the average debt is in the hundreds then it probably won't make a huge difference.
Thinksmart (LON:TSL) (which I also hold) which owns 10% of Clearpay ended up down just 3% yesterday, so the market is relatively sanguine about the prospects.
timarr
My morning smallcap tweet: SPSY busy
Diurnal (LON:DNL) Creightons (LON:CRL) £MOON Gfinity (LON:GFIN) Dev Clever Holdings (LON:DEV) GYG (LON:GYG) Spectra Systems (LON:SPSY) Netscientific (LON:NSCI), SEC Newgate SpA (LON:SECN)
Diurnal (DNL) extention to Phase II study showed Chronocort suitable and safe for the rare condition congenital adrenal hyperplasia. [SP=61.75 Cap=85m]
Creightons (CRL) all paper approach to buy Innovaderma rejected out of hand. Will pursue. [SP=66.64 Cap=43m]
Moonpig (MOON) the online greeting card co to float at 350p, capitalisation £1.2bn. I had no idea the market had become so big. How long will the covid boost last? [SP=NA Cap=NA]
Gfinity (GFIN) turned a profit in Q4 but "due to the project-based nature of the Company's revenue streams and some seasonality in the business in the short term it does not imply the Company will always be profitable on a monthly basis going forward." Appointed by Formula 1 Esports to deliver the Formula 1 Esports Virtual Grand Prix 2021. Formal Sale Process talks continue. [SP=5 Cap=40m]
Dev Clever (DEV) Equity Subscription Agreement with One Nine Two raising up to £10m. Initial £4m at 20p, a 1p premium. £6m is at 30p contingent on share price. Loads of warrants natch'. [SP=19 Cap=93m]
GYG (GYG) guides FY(Dec) rev €58.5m with adj EBITDA also marginally below current market expectations, and additional COVID-related exceptional costs incurred during Q4. Blames project delays into Q1. Order book up 21%. [SP=77.04 Cap=36m]
Spectra Systems (SPSY) agrees second phase of the Central Bank sensor development originally announced on 21 Oct. Worth $5.6m. "Will lead to the production of a yet unspecified number of sensors for their advanced cash processing operations." [SP=176 Cap=80m]. I hold.
NetScientific (NSCI) suspended due to notification obligation pending in respect of one of its portfolio companies. NSCI is currently not in a position to issue it. What is going on? [SP=47 Cap=7m]
In line: SEC Newgate SpA (LON:SECN)
Creightons (LON:CRL) and Innovaderma (LON:IDP) Creightons reporting that they made a preliminary offer to Innovaderma's board on 26 January which was rejected by Innovaderma on 29 January.
Offer of 2 Creighton shares for every 3 Innovaderma shares valuing the offer at roughly 44p per share. Seems an opportunistic offer. No RNS from Innovaderma yet.
I know there is a new board now but I have never particularly warmed to £IDP. There have a few governance amber/red flags along the way, most recently the Chairman suddenly resigning, the founder selling out previously, and capitalisation of customer acquisition costs which I know the merits of which have been debated at length on Stockopedia. So I personally wouldn't be keen on this arrangement (I hold Creightons (LON:CRL)).
Creightons (LON:CRL) meanwhile continues to look like reasonable value at its current share price. In a PI World video on 11 December the company said it expects to make £60m+ sales this financial year ending 31st March with net income of around 7% which I make to be around 6.4p EPS. It is currently trading under 11x earnings - good value for a company that has a good track record and is now showing ambitions to acquire other businesses.
To me, it appears incongruous with Creightons business, albeit they are in the same field.
Are IDP actually worth it? I would say no. It is basically an acquisition of Skinny Tan, whose competitive advantage is at the moment is that they have a distribution agreement with major high street shops.
But to continue that into the future, the brand needs investment. The reviews of the actual product are quite mixed as well. Looking at their other products, that kind of marketing is a competency Creightons do not have. They tend to sell their brands on once they get some success.
Apologies for hiatus in these posts and comments. I have started a new demanding role which, along with other aspects of life have zapped little nuggets of time. I'm glad you guys still appreciated this! Cheers Dan
Nice one Paul - Thanks a lot for the early stuff again, much appreciated as always, hope you caught the worm :)
The webinar on Oxford Biodynamics Oxford Biodynamics (LON:OBD) last night with Yellowstone Advisory was very interesting. I have held OBD shares for a while without fully understanding the technology involved. I would need a couple of extra degrees in order to appreciate everything but I came away with a much clearer overview of the company. They are releasing this quarter in the US a predictive blood test, which will tell you with accuracy whether or not you would be likely to develop a more severe form of Covid. There are apparently 10 million immunocompromised Americans who cannot be vaccinated and many millions more who, for one reason or another, mainly safety concerns, will not take up vaccination. Thereafter, throughout the year, they will be releasing various cancer biomarker tests. One such will be for prostate cancer. I suspect there are quite a few people on this list who pay more attention to their prostate than they did 30 years ago. There is still only the PSA test, which is notoriously unreliable. An improvement on that is much needed. It will take time for the OBD tests to gain traction in the US. Management made a very capable impression. A recording of the video should be available today or tomorrow.