Small Cap Value Report (Tue 2 Jan 2024) - HVO, POS. Link to my 2024 top 20 ideas.

Good morning, and happy new year, from Paul & Graham! Did I get the date right above, yes! That's the first hurdle cleared.
Today's report is now finished.
Some links to start us off -
1. Ed's 10th year of running the automated NAPS system, which has out-performed all relevant fund managers over the long term. Check out this article to see which stocks it has selected for 2024.
2. Megan reviewed how the StockRanks system performed in 2023, with some interesting data and conclusions.
3. Graham's review of 2023, where his top 10 share ideas delivered a stunning 25% return!
4. My review of 2023, where I delivered a more pedestrian 17% return for my top 20 share ideas here, but a rather better performance from taking on more risk, and concentration, in my real life portfolio.
My top 20 share ideas for 2024
Remember these are just ideas to research, never recommendations. We cannot predict the future, so some shares ideas will work, and others won't.
I see it as my "best of the SCVRs", so you'll be aware of all of these shares already. The spreadsheet is now finished, it's here. I'll do a proper article when time permits, probably tomorrow.
I'm expecting some pushback on the 3 smallest items! The other 17 are all pretty conventional value/GARP shares that you'll recognise.
I have a list of 42 more companies that were good contenders for my favourite value/GARP shares, but didn't quite make it, for various reasons. So I'll do another post at some stage listing those, so masses of good stock ideas for you to have a look at are in the pipeline!
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. OR it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Very quiet for news today, so once I've looked at the above, both Graham and I will focus on preparing our 2024 stock ideas articles, which is probably a better use of our time.
Paul’s Section
hVIVO (LON:HVO)
Up 7% to 25.5p (£173m) - £6.3m contract signed - Paul - GREEN
hVIVO plc (AIM & Euronext: HVO), the world leader in testing infectious and respiratory disease products using human challenge clinical trials…
Checking our previous notes, we steadily became more enthusiastic about HVO as 2023 progressed, moving in stages from amber up to green by 13/12/2023 (ahead expectations update), and 12/9/2023 (good interims, and forecasts raised).
Well done to patient holders, as it’s had a smashing move up recently, in the almost everything rally we’ve seen in Nov-Dec 2023.
The positive newsflow continues today -
…signed a £6.3m contract with a biotechnology client to test its antiviral candidate using the hVIVO Human Rhinovirus (HRV - common cold virus) Human Challenge Study Model…
Revenue will be recognised in both FY 12/2024 and FY 12/2025.
HVO’s new state-of-the-art quarantine facilities in Canary Wharf will be used.
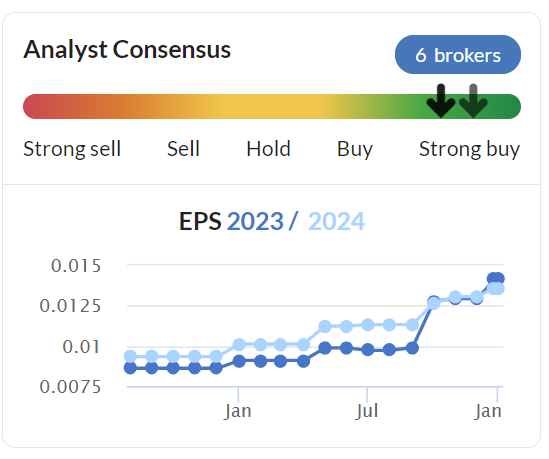
Broker update - Cavendish helps us with an update. It leaves forecasts unchanged, but they’re looking quite modest, given the strong newsflow. So I suspect beats against forecasts are likely for both 2023 and 2024.
As you can see below, there’s already been an impressive upward trend in forecasts, and I’m pretty sure this is all organic growth too.
Paul’s opinion - HVO really seems to be on a roll, and is producing very impressive newsflow. It’s increasingly looking like one of the UK market’s best growth companies.
Valuation doesn’t seem particularly stretched, once you factor in likely beats against forecast.
I also like that cash is received up-front from clients.
Despite a strong surge in share price, I remain positive on HVO shares, so it’s GREEN again.
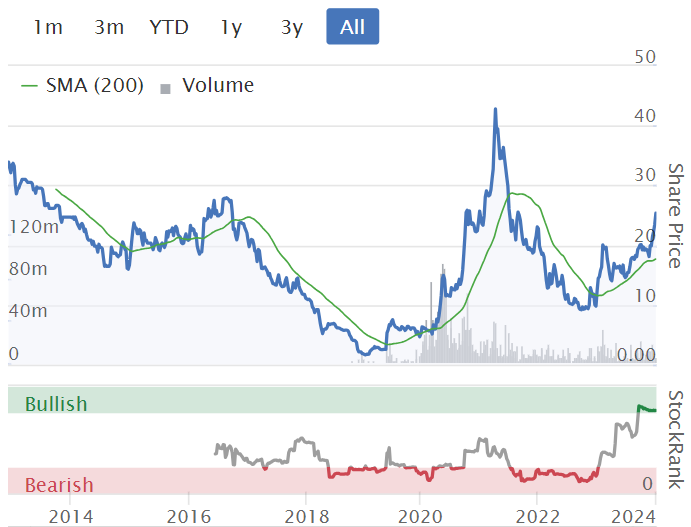
Shares have been volatile in the past, but this current bull run looks much more firmly based on excellent company fundamentals -
Plexus Holdings (LON:POS) (Paul holds)
Down 18% to 17.25p (£18m) - $5.2m licence with SLB (Schlumberger) - Paul - GREEN
A new licence agreement with SLB has brought in a very useful $5.2m in cash. This effectively resolves the question mark over cash, and the going concern worry (material uncertainty in recent results statement).
A new update note from Cavendish (many thanks) today ups forecast revenue for FY 6/2024 by 30% to £14.0m (a remarkable 833% increase on FY 6/2023 actual revenue), and adj PBT moves from just above breakeven, to a much more interesting £3.5m. This also moves Plexus into a reasonably healthy forecast net cash position of £3.8m at 6/2024. Although Cavendish rightly stresses that this $5.2m licensing deal is a one-off.
The way I see it, is that today's deal takes the pressure off management, who can now get out there and sell their specialist products/services more readily than when scratching around for day-to-day cash.
I've had a long chat with the company, and have to say it's all complicated, and well above my pay grade in terms of understanding the detail. In a nutshell though, they made a decision that it was better to bank much-needed cash in return for limited rights over a specific product set that Plexus had no intention of competing with - i.e. high volume, relatively low cost wellheads. Licensing this out to SLB (the world leader) means that over time, SLB products using Plexus tech could become the industry standard of completely leak-free wellheads. The idea is that SLB would take the volume business (and yes, they drove a hard bargain), whilst Plexus then picks up all the specialised and bespoke wellhead work (much higher value per job, like the £8m major contract win announced in mid 2023). They made a commercial decision that this was the best route to take.
Yes it means forgoing a future royalty stream, but to date there has been nothing received in royalties, and it could have potentially taken SLB years to switch over from selling 33k pa existing tech wellheads, to the new ones with Plexus IP in them. A bird in the hand, I guess.
Q1. I asked if the upside case had been diminished by this deal. A1. Upside has not been diminished at all.
Q2. i asked why the RNS today gave a negative impression to investors? A2. Because confidentiality agreements meant that a lot of the original announcement, which explained the deal fully, had to be cut. They're thinking of ways to clarify things to the market.
Paul's opinion - I don't fully understand the detail here, and of course as I have a big position size here, I may well be seeing things through rose-tinted spectacles. However, now the cash position is sorted out, I can sleep much better at night. This deal proves up that the world's largest oil engineering group wants to use this proven tech. Plexus reckon there should be rich pickings, from more specialised (rather than high volume) projects. Although they have foregone (uncertain - they've never published any forecasts) royalty income at an uncertain time in future.
I do think this deal needs explaining better to the market. In the meantime, it's net cash, and profitable for the time being. As always, the shares are likely to react to ongoing newsflow, so it's difficult to predict what happens next.
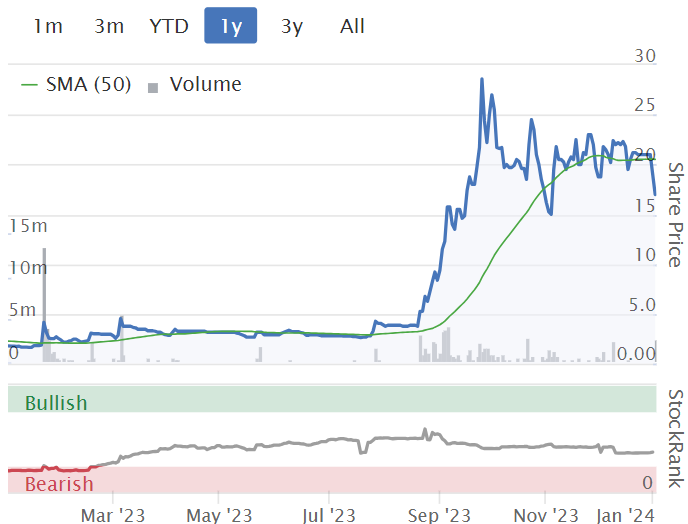
A remarkable chart in the last year, 8-bagging - because a year ago it looked bust, and today it's funded up with net cash, and is (at least for now) profitable. So a very dramatic improvement in fundamentals has caused this share price movement -
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

77 comments
My first moan about this for the year!
Can people please make clear what company they are talking about in posts? It's not hard.
Many of us don't find theaded reading of Stocko discussions effective, so when I look at a post and think - "I have no idea what you are talking about", I'm more likely to skip it, than grasp your pearl of wisdom.
For me, Plexus have sold off a part of the business that is too expensive for Plexus itself to run. The fact SLB have bought this, shows, they're expecting a demand for it.
I think Plexus have held on to the more monetising part for them of the business where they can expand and make decent money.
In my opinion, Plexus have done the right thing here. They have the money now to expand the more lucrative part of the business.
I'm sure SLB would love to have bought all of Plexus and didn't get the chance.
Personally, I prefer Plexus going for the specialised business where they get all the money and not just royalties.
I find where there are royalties to be paid, then these businesses don't put enough work into selling the products. Where businesses don't have to pay royalties, then more time etc., is devoted to selling the products. This can only bode well for Plexus' pos grip technology because it will get more and more known worldwide. So, all in all, a far better chance for Plexus to pick up specialist projects where much more money can be made by them.
POS
Apologies but I don't believe any company does this
Huh - not sure if this is getting lost in translation but with regard to forecasts for next year there is plenty of companies that have expectations up for next year up on the stocky site - if we take a company half the size of plexus like Northern Bear (LON:NTBR) stocky have numbers pencilled in for ye 31/3/2025 now. Note i dont expect stuff to come directly from managemnt - i am well aware Northern bear figures probably come from their broker Hybridan - but as the house Broker i would expect the views of Hybridanwould have been "proof tested with management" unless the company have gone to the trouble of advising otherwise or the numbers are so outdated as to be meanungless (ieg f broker removes coverage)
However unknown the future is to me if you are a listed company you want to be advertising what the following years figures will be if you want peeps to take you seriously. I am not saying companies cant mange without forecasts - i think northern bear used to say nowt about the future themselves - i would kinda accept that for a consisntently profit making company - but if your company is making no profit and you wont give an estimate of what next years numbers would be what is the investment case here other than some sort that can be proof checked progress wise.
Plexus might be a special situation here based on what they have - it might be impossible to say , justa shame they dont make public "their best gues" as a i would gobsmacked if they dont have any numbers pencilled in internally. If they have been short of funds i do semi understand not payinga broker whatever it takes to come up with numbers that may not seem to be value for money - but without something to pin the mast to it doesnt really help trying to make some sort of buisness valuation.
It annoys me when companies like saga are so cagey about current/future numbers when other like Norcor and Redde are happy to to pin the exact contents and summary of broker notes on their websites (or at least confirm consensus)
Re Plexus
It should be easy for the company to produce some forward information. They employ a broker/nominated advisor and a financial PR firm, so if there were forecasts, they would surely have enough resource to put something out. The problem with omission is that it breeds suspicion.
It may be that forward information isn’t that important from today. It is possible that Schumberger have tied this deal up quite nicely and what Plexus sell and who they sell to is now pretty much influenced by Schlumberger. Private Investors could be a long way down the information chain on this one.
Up to Plexus to be more transparent here.
Hi Paul, Thank you for your 20 top GARPs.
Something I'm encouraging the groups I work with is to be bold and put a target valuation on their research / picks. Can you do that for your top 20?
Keep up the good work.
Regards
Daniel
Personally not a fan of price targets - if it's a good quality business and attractively valued then I tend to just hold until something happens to change that view. I think it's very difficult to put a precise a figure on exactly what a share is worth, and of course things constantly change (both within the company and at the macro level) which means any target could go out of date very quickly.
So. My Plexus Holdings (LON:POS) knowledge is poor. I tweeted something out. Twitter is a playground so my tweets are often a bit joking, nonsense, provocative, etc...this POS one is latter partly seeing what the response would be. Here you go:
you really think the owners of (Plexus Holdings (LON:POS) want to sell out for the current market cap with absolutely no premium?
I don't know much about Plexus Holdings (LON:POS) - today's RNS looked to me like they had sold rights to their current commercial product for $5.2m. On a very simplistic arithmetic basis after paying down liabilities that meant that its implied there's c.£15-16m of value (this morning pre open) in what remains (in terms of commercial rights)...
So what do you say that 15-16m is valuing?
If I'm analysing wrongly then put me right on how to put the bits together
My understand Mojo is that Plexus Holdings (LON:POS) have two uses for their IPR
The part they sold to Schlumberger for cash was for low margin surface wellheads. Generally high volume but low margin and therefore require a decent and global sales force.
The higher margin specialised stuff they can still do (although not quite sure if they need SLB permission as it appears they might on a case by case basis?) - much lower volume, but high margin rental type stuff.
I guess the management theory is that they are now on a firm financial footing with a specialised rental market opportunity but I have no idea of how easy that market is to sell into.
I don't hold - have to say I find the deal odd so management probably need to explain where their opportunity lies and what sort of market they think they can get. Absent of that kind of information there doesn't appear much reason to get involved
(With little knowledge) it looks like Plexus Holdings (LON:POS) need to clarify what their commercial opportunity is and their position (in what and how) to transact ex Schlumberger NV (NYQ:SLB)
yep - agreed.
According to the identities allocated by Google to viewers of Paul's 2024 'Top 20' I'm a dinosaur. I'm choosing to read into it that my portfolio performance will be huge in 2024. On the other hand, extinction might be just around the corner.
Plexus Holdings (LON:POS)
Are there any forecasts for ye 30/6/2025.
If there are none it would have been helpful to have some and see how confident the company are with regard to that year - it would have been helpful too to have had prior to now estimates for 2025 year to see how much they would have expected later year to reduce based on this news.
My question here is what were investors prior expectations of profits ye 30/6/2025 and what are thois expectations after todays news. If investors were previously expecting say $5 mill profit ye 30/6/2025 - it seems like the broker have gone out the way to this is one off income - did they not make any mention of improvement in trading ensuring this amount would not be mostlky clawed back by increase in expected profit anyway ye 30/6/2025?
i am left with feeling communication here should have been better if the one of amount is likely to be clawed back by increased profits on other areas of the buisness ye 30/6/2025.
to me this would have been perfect time to provide ye 30/6/2025 forecasts if none existed previously.
Must admit i know nowt about this company so answers to my questions may be fairly simple.
Apologies but I don't believe any company does this ... when you have recurring revenue it's one thing to endorse analyst models of what might happen... but companies don't make forecasts. The best you can hope for is they give you their investment plans and you can calculate expected returns and therefore revenues. I see the CEO also exercised his option to acquire the KMS stake from the co. which is also an odd move. It looks to me like he is getting everything he can out of it .... leaving the rest a bit of a punt.... not sure how the co. can justify selling IP to the CEO really... I wish holders best of luck.
Tavistock Investments (LON:TAVI) A micro cap investment manager up approx 25% today on a fair bit of volume.
Caught my eye following their results last week. Interesting acquisition recently of an insurance and protection business.
I've been looking at potential opportunities to benefit from what will hopefully be a better year for investment managers . It's been covered a few times by Investors' Chronicle in the last year. I'd be interested and grateful to hear any thoughts re this company. I hold as small position as of this morning.
Plexus Holdings (LON:POS)
“If you’ve been in the game 30 minutes and you don’t know who the patsy is, you’re the patsy.”
- Warren Buffett
A big riser on AIM today is Base Resources (LON:BSE, a small cap basic materials company with good quality and value metrics. Does anyone here know them?
Base Resources (LON:BSE) looks like a gamble on go ahead at Toliara project in Madagascar. They are not even talking to the new Govt yet so highly speculative even the proposed project looks fabulous. Good luck.
Plexus Holdings (LON:POS) - the deal was positive in my view as the company was running on empty which is not sustainable for a company that wishes to rent out wellhead equipment. The founder of Plexus is an impressive intelligent fanatic - they have, and always have had, an investor communications problem. He can never explain anything clearly - RNS after RNS is too technical with paragraphs of endless text. I haven't held for c10 years, but it was the same then as it is today, albeit the share price was over £2 - probably more of a tailwind on the technology now though, but the company is much smaller after nearly winding-up.
The technology is undoubtedly great, but whether or not it can be properly monetised in the next 10 years or so is questionable. Best wishes to holders though. He deserves to succeed. Great to have 1st class british technology!
Re Plexus Holdings (LON:POS) - I don't know much about the company (I'm from Aberdeen and did ask back home whether oil people I know know them...tiny company so was always unlikely)
My simple read of today's RNS is that they have effectively sold their IP for their general wellhead sealing tech (wherever and however used) to Schlumberger NV (NYQ:SLB) for $5.2m.
This suggests that Plexus do not believe they have the commercial capacity to penetrate the market for the product on their own.
I'd guess that Schlumberger would prefer to buy the company...but baulked at the £20m ish price...and so the perpetual IP deal was struck.
It seems unlikely that Plexus wouldn't accept an offer for the whole company...but if we imagine they did but agreed to $5.2m for their primary IP...well then you are left with a cash shell and some people with O&G engineering knowledge looking for their next innovation to succeed. Effectively a R&D engineering biz...
The above is super simplistic and very lightly informed. What am I missing in terms of Plexus capability?
It is my opinion that you are not missing anything and have explained this exactly how I interpreted things from the beginning-another jam tomorrow company.
Thanks for your analysis Mojo, One question remains for me. If Schlumberger were interested in buying Plexus why not make an offer before September when the share price was still peanuts?
Listened to another good podcast from Paul over the weekend - liked the introduction of adjusted performance numbers. Remove the poor stocks from the portfolio and add in a couple that performed well and your overall performance numbers are much better! Not something you can do to real portfolios but made me chuckle.
Many thanks Paul for all the podcasts in 2023 and looking forward to listening to many more episodes in 2024.
This is a chart of Mag7 ETF...so it's equally weighted virtually... relative to the Dow.... it's not a particularly pretty picture. It presents a headwind for indices but one WE.can pretty much ignore. The absolute chart is not showing much weakness.... and so it's more a case of not participating in Index strength...than losing money. It's worth watching....as clearly this is positive for broadening out of strength ....esp too small cap. Im not making any calls about the Mag7, simply observing that their weakness has been to the benefit of lots of overlooked areas so far.
Crikey, Just seen Plexus down 17% (LON:POS) what's caused that then.
I know there's been quite a bit of noise around this one and a few people here have quite large holdings in it so hopefully it starts turning back up :)
All the best
See comments earlier in the thread. Paul will be speaking to the management and will report back later today
FWIW I have added to my position at 17p
Plexus Holdings (LON:POS)
Just seen Plexus down 17%
To be honest based on the rapid increase in sharepice recently investors should be expecting 20% moves on the slightest bit of news (its taht kind stock) . Anyone not comfortable with swings like this on perhaps "broadly neutral" news probably shouldnt be invested here. Its also a good reminder that for any companies like this us the investors are generally at the bottom of the chain news wise.
Bottom of the chain news wise……….
Excellent!
Happy New Year all, I hope you all have a happy, healthy and prosperous one!
Container Rates on the up .
Suez Canal issues and pirates of the high seas causing container rates to shoot up .
We had a shipment due out of Indonesia mid December when freight was circa 2k now it’s up to 6k.
Shipping lines are run by a mafia of money grabbing extortionists so don’t expect rates to come down and any excuse they will keep rising .
First warning shot of the year if Suez Canal stops working efficiently then that’s maybe 2-3%. Imcrease in landed cost of goods
Great intel planetx.
Supply side inflation on the cards again then?
I think the shipping industry as a whole has more than its fair share of crooks - the latest example being those Greeks who have sold ships & tankers to the Russians (via intermediaries of course) enabling them to circumvent Western sanctions. I doubt very much whether the Greek shipping industry pays its fair whack to the Greek exchequer.
Yemen terrorists using Iranian drones causing shipping to go the long way around the Cape of Good Hope not helpful either.
They are buying though as well football premiership teams injecting much needed millions in the British economy!
All the best for the new year.
Thanks for this planetx.
Could this account for the sudden slide in Ultimate Products (LON:ULTP) before Christmas albeit after a strong run?
Think it UP went ex div before Christmas. It also hit a level key.
Yes thank you. Eye off the ball before Christmas
The only surprise is that the price of Oil hasn't shot up.
Sky news ran a piece on rising shipping costs too:
https://news.sky.com/story/fre...
I'm not gonna claim shipping expertise but...
My guess is that this isn't a rerun of the covid spike as the ships and containers keep flowing and the global (ie US) goods demand is not way elevated with labour supply problems thro the supply chain. So prices will rise but only as much as some extra utilisation time and fuel push it which is not massive. I believe there is a relative oversupply of capacity
I just had a chat to my forwarder
- freight rates are currently up around 100%
There is a spike always before Chinese New Year so that’s not helping
They are hoping after CNY that rates will normalise
He also said shipping companies will latch on to any excuse to lift prices and there is not much a customer wanting to ship goods can say or do .
So definitely here for a couple months .
We cancelled our shipment and are leaving goods in Java .
Thanks. I'm definitely no expert!
I've looked at shipping in the past having investment (for a business) very (very!) significant amount in a shipping investment biz from Scandi. So good access and info from times past. I'll be honest that what I learned isn't don't invest direct myself and always leave it to experts (aka insiders!)...outsiders don't win in the shipping game
Happy New Year to all readers here and to all the incredible contributors and team at Stocko for the hard work and incredible insights (this past year's SCVR content and Ed's webinars have all been immense).
I'm feeling optimistic for the start of this New Year although the ongoing deterioration of global events from Ukraine to the Middle East and the looming horror of the forthcoming US election, make the "wall of worry" appear especially vertiginous this year.
Focusrite (LON:TUNE) have marked the start of the year with perhaps the most unusual use of an RNS by announcing the award of an OBE for their CEO - the venerable Phil Dudderidge (ex. Led Zeppelin roadie). Congratulations to him. I hold and feel optimistic that this quality UK business can turn it around. For a long term hold, I can't help feeling this is a wonderful opportunity (the current SP rather than the award of the gong).
Plexus Holdings (LON:POS) announcement today reads rather strangely to me - it certainly sounds like Schlumberger NV (NYQ:SLB) had them over a barrel and have come away with the technology and the upper hand. I held a tiny amount but I've moved on today to other opportunities. It was a nice little trade but today's news removes the compelling longer term proposition so far as I can understand it.
Good luck to everyone in 2024.
Plexus Holdings (LON:POS) This doesn't negate all the other positives in terms of P&A opportunities, growing market demand, new contracts etc. but it moderates the assessment of their overall financial outlook in the long run. There was an expectation of a fund raising which has been lifted. I'm assuming they balanced the costs of a fund raising with the loss of future revenues due to the new agreement and determined that the latter was the better deal. Other more informed views are probably on their way!
Yes, I'm talking to Plexus Holdings (LON:POS) management later today, to get a better handle on the deal they've announced. I don't want to jump to conclusions. But yes, it's clearly good news that the funding position has been resolved in one fell swoop without any dilution.
Be interesting if they have any feedback on how they see the convertibles playing out.. probably covert at some point with an open offer matching for other shareholders ? plus how much a new well head costs to commission and how many they see building their fleet to ? to get a feel for future capex commitments.
Many thanks
Rich
Plexus Holdings (LON:POS) - although they have handed over the rights to surface wellhead production to SLB, they have retained rights to sub-sea welded markets. The former is projected to be worth $10bn in 2031 (https://straitsresearch.com/re....) while the latter is projected to be worth $15bn by 2030 (https://www.offshore-mag.com/s...).
I know nothing about the wellhead market so am hoping that others who know more may share any insights they have into the growth rates of the two different markets and Plexus's opportunities. It seems that there is still a huge addressable market in sub-sea wellheads
Plexus Holdings (LON:POS) What worries me on this one was the comment from SLB - providing our customers with additional rig time savings through ease of installation and enhanced seal integrity assurance for onshore and offshore applications. We are very excited about the prospects for this technology." So it looks like they have the rights to offshore as well
Plexus Holdings (LON:POS) I think this deal makes sense, gives immediate cash for selling IP to SLB for standard products, leaving POS to concentrate on non standard higher margin product opportunities. POS retain IP for the Methane leak capping solutions which is going to be a huge market in the future. This MorningStar article e4plains the possible costs to the oil companies of methane leakage https://www.morningstar.co.uk/...
"Plexus Holdings (LON:POS) announcement today reads rather strangely to me - it certainly sounds like Schlumberger NV (NYQ:SLB) had them over a barrel and have come away with the technology and the upper hand."
SLB has a market cap of 58 billion whilst POS has a market cap of 22 million and a relatively weak financial position. The larger company will usually come out ahead in such a position.
SLB could have presumably made an offer for Plexus if it thought that it had useful technology so I am intrigued why it sees Plexus as a supplier rather than an acquisition.
I wonder if the management of Plexus knew of this situation when it made the recent positive announcement.
I sold out as well (only a small holding) on a strange RNS whichresulted in a major shareholder (Paul) feeling the need to seek clarification from management. But Good Luck to those who continue to hold.
Very volatile but LungLife AI (LON:LLAI) is a fun hold.
They seem too be really onto something with regards to early cancer detection. They came out with some positive test results today.
I just have a small holding as it bounces around very aggressively
LungLife AI (LON:LLAI)
This sounds potentially very interesting. I'm probably being a bit dim, but I can't find a reference to the actual published paper. The reference(2) in the rns is to the study published in June.
Paul, excellent spreadsheet with live price tracking, cool.
ps. Renold (LON:RNO) STOCKRANK is top of the pile, 100/
And a nice rise to start the year off for Renold (LON:RNO), on large volumes.
Good luck for 2024 all - wishing everybody a healthy and prosperous year to come. The last couple have been tricky to navigate, so let's hope for calmer waters and a good tailwind. Have at it!
I was thinking about buying Plexus Holdings (LON:POS) but it's had such a good run think I'll leave that one. Took an initial holding in Altitude (LON:ALT) as a first buy of 2024. they seem to be doing all the right things but the SP has just kept going down H2 2023. Not sure if anyone else has looked into this one but seems to be growing well with a depressed sp?
Thanks, Newinvestor 1972. Altitude (LON:ALT) crtainly looks intriguing. Momentum is poor and there have been director sales and the broker has revised their opinion from BUY to HOLD in the past few months. PEG of 0.4 and dividend of 14% !
What was your analysis that triggered your decision to buy?
The next trading update should be interesting. Are their sales seasonal?
Looked good as a recovery play to me, CAGR of 26%, they seem to be turning a profit and the EPS is going in the right direction.
Good morning and a happy and healthy new year to everyone.
On Altitude (LON:ALT) it is my opinion that the remaining loan facility is not enough and they will be running out of cash.
At the moment they are burning cash-about $2m pa and they will definitely need a new fundraise.
They seem comfortable with cash flow but who knows...
"The Directors have prepared cash flow forecasts extending to November 2024. These show that the Group has sufficient funds available to meet its trading requirements.
· The Group's year to date financial performance has been factored into the cash flow forecasts.
· The Group has a financing facility in place of $1.7m which provides additional comfort and headroom to the cash forecasts. We expect that with future additional growth this facility can be increased to support any excess working capital requirements.
· The Directors have considered the position of the individual trading companies in the Group to ensure that these companies are also in a position to continue to meet their obligations as they fall due.
· There are not believed to be any contingent liabilities which could result in a significant impact on the business if they were to crystallise."
I look at 3 year forward cash flows and it is evident to me that they will need a new fundraise as they are losing about $2 pa. They only rely on a finance facility and not on any future cash coming in-very risky and not for me.
I have referred to Cornerstone FS (LON:CSFS) about a couple of weeks ago-it my opinion that even after todays 15% gain that it is still massively undervalued. All research available is totally wrong in my opinion and I feel they will be beating these estimates for the next couple of years (I hold).
I have started adding Good Energy (LON:GOOD) today as well as I feel they will be beating the market estimates as well.
DYOR
All the best for the new year.
My morning smallcap tweet: What's the score in '24?
Tan Delta Systems (LON:TAND) Dialight (LON:DIA) Jade Road Investments (LON:JADE) Angle (LON:AGL) LungLife AI (LON:LLAI) Plant Health Care (LON:PHC) Plexus Holdings (LON:POS) hVIVO (LON:HVO)
◄Tan Delta Systems (TAND)► another recent IPO (Aug) pins a 'Kick Me' note to shareholders' backs. Warns FY-Dec rev down c. 10%, below original management expectations. Blames customers delaying trials. Adj net loss broadly in line at c. £0.4m due to slow recruitment of new staff. Outlook: "we look forward to 2024 with great optimism". Why am I not reassured? [SP=21 Cap=17m]
◄Dialight (DIA)► Sanmina litigation: court denied Sanmina's motion to dismiss Dialight's fraudulent inducement claim. Also court affirmed its prior opinion and denied Sanmina's motion for summary judgment on its accounts receivable claim. [SP=140.84 Cap=59m]
◄Jade Road Investments (JADE)► proposed disposal of legacy Asian assets, restructuring exercise and strategic direction. Legacy assets will be moved into an SPV which will then be given to shareholders in specie. The some loan note rigmarole. Smells. [SP=1.75 Cap=7m]
◄Angle (AGL)► $250k contract for pilot study for co's Portrait HER2 assay. [SP=11.7 Cap=31m]. I hold.
◄LungLife AI (LLAI)► validation of LungLB in multi-site, prospective clinical study. "LungLB performed strongly in participants with smaller lung nodules." [SP=50 Cap=12m]
◄Plant Health Care (PHC)► Brazil approves TEIKKO to control nematodes in soybeans. [SP=3.4 Cap=13m]
◄Plexus (POS)► $5.2m perpetual P Licence Agreement with SLB replacing an existing surface production wellhead licence with HB seals (what are they?). [SP=20.9 Cap=22m]
◄hVIVO (HVO)► £6.3m contract to start H2 2024, with revenue recognised in 2024 and 2025. [SP=23.93 Cap=162m]
Just listened to my first Paul Scott podcast. Really excellent, why haven't I tried it before?.........
Thank you GreyInvestor! Good to start the new year on a positive note :-)
I enjoyed the weekend one Paul and the reflections on 2023. Many thanks for that.
Happy New Year Paul and thanks for all you do with the SCVR's, the podcasts and the additional reports you put out - Much appreciated
Noticed a Plexus Holdings (LON:POS) update there this morning (I don't hold) in case you missed it - Seems perhaps a lowball perpetual agreement with a major player does it not?
Anyway - All the very best for the year ahead and look forward to the valuable content - Cheers!!!!!!
(Sorry - You too Graham !)
Morning matylda! Happy new year to you too :-)
Yes I'm currently trying to work out the implications for Plexus Holdings (LON:POS) (I hold) $5.2m replacement licence deal with SLB announced this morning. Cavendish has put out an update note, where it raises adj PBT for FY 6/2024 from just above breakeven, to £3.5m. Although it emphasises this is a one-off deal.
So my initial thought is that it solves the tight cash position, hence solvency/dilution no longer issues, which worried some people. However, what I need to find out is how this affects the future, because it sounds like Plexus has given up a potential future royalty stream for some products anyway.
It looks really complex, so I need to find out more and get a better understanding of it before commenting further in detail.
Regards, Paul.
P.S. I'm trying to get a Q&A call with management set up, so I can get a clearer idea of what this all means. Leave it with me!
Plexus Holdings (LON:POS) While this takes away some of the more speculative upside, it seems unlikely that, having got this far, the owners would dispose of the major part of the upside for such a trifling sum.
Cavendish notes
we note that the larger volume, lower cost surface production wellheads is an industry area that Plexus has not been recently focussed on. Plexus has previously participated in the surface production wellhead market, such as with the 2022 single well 10,000 psi production gas wellhead solution in the North Sea, and retains the ability to operate within the sector, albeit with some limitations, as well as ownership of the original Plexus IP
Having trusted management's judgement for so long, it would be perverse now to assume that they have done a very poor deal unless SLB was, somehow, threatening to put them out of business.
I would argue that the news is, on balance, net positive. The market seems to disagree with me. I hold
hVIVO (LON:HVO) , the world leader in testing infectious and respiratory disease products using human challenge clinical trials, announces that it has signed a GBP6.3m contract with a biotechnology client to test its antiviral candidate using the hVIVO Human Rhinovirus (HRV - common cold virus) Human Challenge Study Model.
Great start to 2024. Follows a £16.8m win a couple of weeks ago.
Super start for hVIVO (LON:HVO) - really what I like is the forward visibility. They must have 2024 revenues in the bag by now and much of 2025, which helps a lot. I suspect this will be the year for some corporate action assuming markets are reasonably strong but we will see. still trading well below my own fair valuation.
I see hVIVO (LON:HVO) in the same light as Ergomed, which was trading on a PE of 50 much of the time it was listed (albeit in different market conditions). I'm suprised hVIVO is still so cheap, although that appears to be correcting now.
Good luck for the New Year
Jim
PS hVIVO my second largest position, after Pershing Square.
Agreed - I think hVIVO (LON:HVO) is more than capable of generating £75m of revenues at 20% ebitda margins. Given they should also have close to £40m of net cash that means maybe £17-18m of total cash profit. With tax losses prevailing I assume in the region of average 20% tax. So I can see maybe £14m PAT in next couple of years. On a conservative CRO type valuation of 20* thats £280m + £40m cash giving a fair value EV of circa £320m or roughly double current share price.
As you say though CRO's can go for considerably more than 20* and I would argue that as the only credible global player in this space and with a strong moat preventing anyone easily replicating the model they should be on a premium rather than a discount.
Anyway that's my rationale but I am long and therefore biased. I note Cavendish thinks next years revenues are conservatively pinned at £60m but I reckon those are designed to be well beaten personally but I see the broker also has a 20% ebitda margin. I think the interest at £0.9m is also too low.
Cavendish have a 12 month price target of 35p so I guess I am considerably more optimistic though mine is a 2 year view. Either way 40-80% fair value upside feels reasonable risk/reward to me.
Morning all - happy new year .... here we go again! good luck and happy hunting. Big thanks to everyone, esp Paul Graham and Roland for 2023... what a great forum this is.
Worth noting that although UK equities might have failed to keep pace with the US last year ....the two year picture is quite different....with S&P 500 unchanged and Nasdaq -15% ....whilst the FTSE 100 is up 5% and small cap and mid cap indices are similar to Nasdaq. Aim is down a lot -36%....which to me is interesting when compared to a lot of private equity portfolios which don't appear to have fallen much.
For me personally the year was not too bad.... my equity portfolios were up about 12%... and start the year with 80% or so in the same 5 stocks, Sherborne Investors (Guernsey) C (LON:SIGC, Yellow Cake (LON:YCA) Volvere (LON:VLE) Serica Energy (LON:SQZ) and BT (LON:BT.A) . The arithmetic mean of these 5 stocks was 17% in 2023 and Im pretty sure I will just run them. Serica Energy (LON:SQZ) was the worst and fell 20% excluding dividends but I am still happy to hold taking the 10% yield and waiting more deals. BT (LON:BT.A) may have turned the corner FCF wise but we need a few more periods of progress to prove this one out... I plan to hold Uranium exposure for another year reflecting demand supply.... and then Sherborne Investors (Guernsey) C (LON:SIGC) and Volvere (LON:VLE) are both special sits.
In the near term there is plenty of scope for a pull back and the market could use the jobs data this week or the inflation data on January 11. Given there seems scope for inflation data to continue to fall over the next few months this months` number would have to be really bad to change things.... Im not sure what would cause that....so for now I think we are most likely fine.... and markets drift up. ( But never linear). Not much change from me... steady as she goes should continue to do ok given valuations... will be an interesting year as always ... best of luck and happy hunting.