Small Cap Value Report (Tue 2 June 2020) - IGP, TED, DLAR, QTX, VNET, CARD, XAR, ZTF, GMR

Good morning, it's Paul here.
As usual, this post is initially just a placeholder, to allow readers to post any early comments re the 7:00 RNS, as I write up the main article throughout the morning.
This is what has caught my eye this morning;
Intercede (LON:IGP) - final results
Ted Baker (LON:TED) - more thoughts on its placing announced yesterday
De La Rue (LON:DLAR) - more thoughts on yesterday's stellar rise in share price
Quartix Holdings (LON:QTX) - trading update
Vianet (LON:VNET) - final results
Card Factory (LON:CARD) - preliminary results
Xaar (LON:XAR) - trading update
Estimated timings - that's probably enough to keep me busy until the official finish time of 1pm, which I'll aim to achieve.
Update at 13:02 - so close, but not quite! I've done most of today's report, but want to finish off the last 3 on the list, with shorter comments after lunch. Falling asleep on the hammock again is not an option. Therefore, I'll say 4pm for final completion.
Edit at 16:12 - today's report is now finished.
Intercede (LON:IGP)
Share price: 71p (up 3% today, at 08:30)
No. shares: 50.5m
Market cap: £35.9m
(I hold a long position in this share, at time of writing)
Final Results (pdf version here with graphics))
Intercede, the leading specialist in digital identity, credential management and secure mobility, today announces its preliminary results for the year ended 31 March 2020.
Today's results statement is very detailed, giving us useful background & information about the company.
Here are the main points;
Results for FY 03/2020 are in line with last trading update
Most revenues are contracted, recurring, or repeating - many contracts with large organisations are extremely long-term in nature, with large annual support & maintenance contracts. Hence excellent visibility.
Modest increase in revenues, up 3% to £10.4m
Big increase in profitability, due to continued tight cost control - operating profit up from £59k LY, to £1,152k this time
Note large finance cost on P&L of £600k p.a. - this is mainly interest on the convertible loans, which should be repaid, or convert into equity in the future, hence this hefty cost should disappear, nicely boosting future profits
Taxation - the company receives R&D tax credits, hence tax charge is negative.
Profit after tax £1.0m, versus £449k last year - this is a satisfactory result, given that there were few big new contract wins - most new business was follow-on orders from existing clients
Sales pipeline up 40% on LY, and several times the company emphasises that it is expecting strong revenue growth this new financial year. This could be highly significant, because the operational gearing here is as big as it can get - with gross profit being almost 100% - hence strong revenue growth in FY 03/2021 means profits could go through the roof. Obviously that's not a given, it depends on converting that pipeline into actual contracts, but the smoke signals are looking very positive to me
"Extremely relevant" product in these times;
In comparison to many companies, Intercede is well placed to weather the Covid-19 pandemic.
Our products and services are extremely relevant in the current climate, particularly our derived credential and mobile technology, as they allow our customers' staff to securely work remotely with full access to systems that they would use in their normal place of work.
While we've seen some postponement of decisions on new sales opportunities, this has been offset thus far by the realisation of orders delayed from March and from existing customers preparing for their staff to work from home.
That's very encouraging, I reckon.
Staff attrition rate down substantially - this is very important - down from 33% LY, to 9% (and falling) now. Happy staff mean management must be doing a good job, and augurs well for the future.
Customer advisory board in USA was a great success. Will replicate elsewhere (although it's mainly a US business). It's easy to dismiss things like this, but personally I see an engaged customer base as being very important. It keeps the churn rate very low, and encourages follow-on orders.
R&D is very large, at £2.8m p.a. - none of which is capitalised, a very prudent accounting treatment. Again, I very much like large R&D spend, targeted at the best commercial opportunities. The narrative gives more detail on this, and it sounds encouraging.
No plans to pay divis - fine, as this is a growth company, so I don't want any divis.
Balance sheet - OK overall. NAV is slightly negative, at £(1.38m), but improving.
Very important to take the convertible loans of £4.8m into account. This would use up most of the cash pile to repay, or lead to dilution if exercised. See my previous articles for details on this (I'll put in a link later).
Receivables look high, at about half revenues. I have a call scheduled with management tomorrow, so will ask about this.
Cash - was £4.74m at year end (almost enough to repay the convertible loans), but note that another £3.7m was received on 1 May 2020, just a month after the year end. Therefore, the cash position looks fine. Let's hope the convertible loan note holders opt to receive cash, and don't convert - I don't want to be diluted! It's about 20% potential dilution from memory, so not too bad, and of course that would eliminate debt & leave a strong cash position if the loans are repaid. Directors own a lot of them, so a conflict of interest there.
I would like to see the daily average net debt/cash position disclosed (for all companies, not just this one). This is much more meaningful than a year-end snapshot figure, which is so easy to window-dress.
Broker update - Finncap notes are excellent, and easy to access, bravo to them! There's a nice update note out today, which is worth a read. Again, reading between the lines, it sounds like upgrades could be in the pipeline.
My opinion - I see a lot of potential here. It's all about backing ne-ish management, executing well on a 3 year turnaround plan. They've done everything they said they would do, lots of things have been sorted out. We should, hopefully, now see revenue growth kick in strongly, which would be absolutely transformative. The narrative mentions several times that strong revenue growth is seen coming, but depends on customers being prepared to sign contracts - which can't be assumed, given the current covid situation & recessionary economic conditions.
If this works, I think we could be looking at a multibagger. Risk:reward looks excellent to me. I don't see this as a share to trade. It's a long-term, core holding for me. The share price is very volatile, due to lack of liquidity. It's annoying when small traders get involved, as they whip the price up & down too much. That said, it adds to badly needed liquidity. I try to ignore the share price completely, or buy the dips if I have any spare cash.
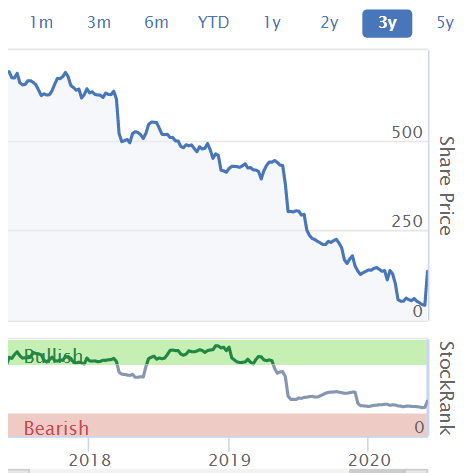
Note that the 3-year chart below shows that investors clearly believe in the turnaround story, as they should. Note also how the StockRank system has also become a lot more positive about it since mid-2019.

.
Ted Baker (LON:TED)
Share price: 129p (flat today, at 10:05)
No. shares: 171.3m (after placing)
Market cap: 221.0m
(at the time of writing, I have a short position in this share)
This announcement came last night, and no real surprises, as the placing was underwritten, so could not fail.
However, it's worth taking a look at it, and to dwell on the huge dilution to existing holders. This is what happens when a business gets into serious trouble, and needs to refinance. I can think of other companies that could end up in a similar situation, Superdry (LON:SDRY) springs to mind, so I want to flag the risk.
TED did include an open offer for existing shareholders, but that's only a small proportion of the new shares being issued. Institutions taking part in the large placing get to dilute existing holders heavily, without existing holders having any say in that. I understand why placings are used - they're cheaper & quicker than a conventional rights issue, particularly important in times of crisis, like now. However, it leaves existing small shareholders, who don't even know a fundraising is being undertaken until it's a done deal, at a serious disadvantage.
That the share price has remained as high as 129p, when the bulk of the shares in issue have just been issued at 75p, doesn't make any sense to me. Therefore I see this as a selling opportunity. If I held the shares, I would want to take up my open offer entitlement shares at 75p. However, I would lock in the current 129p selling price by opening up a short position now, equivalent to my open offer entitlement. That way, people can take up the open offer, sure in the knowledge that a 54p profit per share has been locked in.
I decided to short the share yesterday, in a modest position size, just because I feel the share price is likely to be pulled down to near the 75p placing & open offer price.
Shorting can be dangerous. Particularly in this case, there's an aggressive major shareholder, Tosca. I vaguely recall an episode a few years ago, where they smashed short sellers by mounting a bizarrely over-priced takeover bid, for a company they had a big stake in, which was a complete crock. Speculation was that their motivation might have been to preserve their reputation, and disappear an embarrassing mistake by making it look like a success. Hence I'm wary of anything Tosca is involved in - what happens is not necessarily logical or sensible.
The main point here is, that there's obvious read-across from a deeply discounted, highly dilutive placing at TED, to other companies. Just because the bank is being supportive in the short term, doesn't mean shareholders are out of the woods. With generous Govt backed schemes available, it makes sense for companies to extend bank facilities in the short term, to provide breathing space to tap shareholders for more equity.
Last week I was toying with the idea of buying equity in more financially stressed companies, on the basis that the Govt has backstopped the downside with loan guarantees. The distressed equity raising at TED has completely put me off that idea now!
.
De La Rue (LON:DLAR)
Share price: 154p (up c.278% in last 2 days!)
No. shares: 104.0m
Market cap: £160.2m
(at the time of writing, I hold a long position in this share)
Post-script to yesterday's very positive trading update.
I've done a bit more work on it, and belatedly decided to join the party, with a new long position. It was really difficult deciding to buy this, when it was already up 100% on the day yesterday - not normally something I would do, because such a huge euphoric price spike would usually be expected to reverse considerably.
However, this struck me as a very unusual situation, where the outlook for the company seems to have radically improved. Prior to yesterday's trading update, it looked as if DLAR was in potential trouble - very weak balance sheet, profit warnings, etc.
Although on my review here on 6 Mar 2020 (at 124p per share) I concluded that, despite the problems, it was starting to look like a credible turnaround., with speculative upside possibility. That helped me push the button yesterday, buying at around 84p. Amazingly, the price has almost doubled again from my buying point yesterday, when it had already doubled. Is this a speculative bubble then? I don't know, because I cannot get hold of any broker research.
On balance though, I've decided to run with this, and see where it ends up. The share price was so beaten up to start with, that a huge percentage rise from such a bombed out level, doesn't really mean much. The company's prospects seem to have dramatically improved, and it's quite a big business. Maybe I should sell half, and run the rest for free?
.
.
Quartix Holdings (LON:QTX)
Share price: 376p (down 2% today, at 12:33)
No. shares: 48.0m
Market cap: £180.5m
Quartix Holdings plc, one of Europe's leading suppliers of subscription-based vehicle tracking systems, software and services, issues a further update and trading statement, as promised in its statement of 27 April.
This sounds positive;
The Board reports that trading for the first four-month period to 30 April 2020 was strong, and ahead of the equivalent period last year.
The Company's cash balance was £9.5m at 1 June.
All staff working from home.
New installations - very low in April (-60%), but improved significantly in May (-25%).
Process improvements - this is an interesting theme. Management of another company told me recently that having people working from home has helped them examine everything they do, and make improvements to processes. Sounds as if QTX are saying the same thing here;
Significant development has been carried out over the past two months on productivity, process and activity measurement reporting for the Company's sales operations, and this will help the Company in maximising the effectiveness of future investments in sales and marketing.
I wonder also whether the current crisis may have given many companies' management the opportunity to think about the way they do everything. In some cases I'm sure that a crisis actually can sow the seeds for future success, because everything has to be challenged. People that were tolerated in the good times, but who contribute little to the business, tend to be let go in a time of crisis.
Fleet activity - data is given on this, if you're interested see the RNS.
Subscriber base - not yet seen any material decrease in subscriber revenues from the covid crisis. Attrition rate steady, at 12% p.a. Some risk from 6% of the subscriber base, that have asked for payment relief/deferral. Some issues with direct debits, but not yet any significant increase in bad debts. This is a helpful reminder that if we enter a prolonged recession, then some of QTX's revenues are bound to fall away from possible insolvencies. Well done to the company for being up-front about this.
Guidance - this is a cop-out I think, because with recurring revenues, the company should be in a good position to provide base case, downside, and upside cases. Then investors can pick the outlook that fits their preconceptions about the macro outlook.
As stated in the trading statement of 27 April, The Board's view is that the COVID-19 pandemic is unlikely to have a material impact on profit and cash flow in the first half of 2020 but given the uncertainty that remains, the Board is still unable to provide guidance for the financial performance in the second half of 2020 and for 2021.
Unwilling, rather than unable, would be a better word!
This does however reinforce the reality, that if the UK/France (bulk of QTX's revenues) go into a prolonged recession, then revenue & profit could drop considerably. Remember the operational gearing effect of losing say 10-20% of business, would be considerable. That said, Quartix is very secure financially, so there would never be any hint of it getting into financial trouble, even if business did drop. So shareholders could just ride it out.
My opinion - really good company, and terrific management. But for me, the current price looks too high, given the risks & uncertainty.
.
Vianet (LON:VNET)
Share price: 93p (up 13% today)
No. shares: 28.95m
Market cap: £26.9m
Final Results
This is the group which owns Brulines, the flow monitoring equipment for pub beer sales, and a vending telematics business.
Very brief points, as the company doesn't really interest me as a potential investment;
Adj operating profit up 4.5% to £4.0m
Final divi withdrawn, due to covid situation, as many companies have done.
Recurring revenues mostly, at 92% of total.
Covid-19 - sensible measures taken to conserve cash. £3.5m loan under Govt's CIBL facility. Confident it has healthy cash runway into 2021.
Brulines - contract renewals achieved. Assisting customers by offering reduced monthly fees during shutdown. I like this a lot - as do their customers, naturally. People remember who helped them out in the tough times & often reward them in future.
Trading well ahead of revised forecasts for April 2020.
Vending division trading well.
My opinion - neutral. It sounds as if management has acted fast & sensibly to protect the business. The main reason to hold this share was the divis, which have probably now gone away for a while, as the focus will need to be on debt reduction. I wonder how many pubs might never re-open? Hence that's likely to dent the Brulines business permanently.
I don't see any logic in this company being listed. Growth is anaemic, and why incur all the costs & hassle of a listing?
Card Factory (LON:CARD)
Share price: 39p (down 3% today, at 15:06)
No. shares: 341.5m
Market cap: £133.2m
Preliminary Results FY 01/2020
In normal circumstances, this share would look an astonishing bargain, being on a PER of only 2.5 times underlying basic EPS just reported, of 15.7p. However;
1) Covid. So profit this year FY 01/2021 are likely to be severely lower
2) Even before covid, the company was on a downward profit trajectory
3) The big one - debt. I was relaxed about the debt previously, but this is much more of a problem now that covid has caused a likely collapse in profits, with the shops being forced to shut.
Online trading has been strong since lockdown.
Re-opening strategy - planning to re-open c.10% of stores c.15 June. This is interesting, and it supports my hunch that many retailers would only open their most profitable sites whilst the furlough scheme is still paying staff wages, and acts as a major incentive to retailers to keep their less profitable sites closed, an unintended consequence.
Liquidity - it says borrowing facilities are enough, but I suspect an equity fundraising is looking a near certainty now. Banks seem happy to plug the gap, especially when Govt guarantees are available. But banks don't like taking on risk, hence extended bank facilities tend to come with pressure to raise fresh equity.
My opinion - it doesn't interest me at all now, due to the stretched balance sheet, which is likely to look grim once all the covid shutdown losses have been factored in. Shareholders should be braced for heavy dilution from a future equity raise. If it ends up being a distressed raise (like the one from Ted Baker (LON:TED) yesterday), then that could destroy a lot of the remaining shareholder value. It seems safest to steer clear of CARD, in my opinion. Obviously that's just an opinion, which could turn out to be right or wrong.
A few quick comments before I head to the hammock;
Xaar (LON:XAR)
- Short term order book is healthy
- Outlook for H2 "remains uncertain" - so too early to assess impact of covid
- Confident on medium term strategy
- Liquidity - no details given, but says it has "an appropriate level of funding", and is well positioned
My opinion - I don't have enough information to form a view. This was a fabulously successful company in the past, but it seems to be seriously struggling to get back on track. Personally, I'd rather pay more, once/if there is clear evidence that it's getting back on track. Rather than taking a complete punt at this stage.
.
Zotefoams (LON:ZTF)
I've run out of time now, but just want to flag up an impressive-sounding update today from this speciality foams company.
It's picked up some PPE contracts, which give it a confident-sounding outlook.
This is a decent quality business in my view, so it's worth a closer look.
Gaming Realms (LON:GMR)
There's an impressive-sounding update today from this company today. Sorry I don't have time to research it in detail.
... the Board expects that EBITDA for the year ending 31 December 2020 will be significantly ahead of current market expectations.
We're not seeing many of those updates at the moment! Hence it looks worthy of a closer look.
That's me done for today. Thanks for tuning in, and contributing your comments. See you tomorrow!
Best wishes, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

55 comments
Held Quartix Holdings (LON:QTX) previously but ditched it at the start of the year as I also thought it looked to expensive. Yet somehow the share price is almost back where it was, and this latest trading statement is looking rather mixed. I think this is a very valid point:
As noted on 27 April, the Company believes that the full impact on its subscription base will not become apparent until the autumn, as the UK government's financial support measures are withdrawn and as the Company's SME customers potentially exhaust their cash reserves
There is a lot of companies out there conserving their cash right now, and cutting back on costs. I wonder whether vehicle tracking systems is really essential to most business's? Really like this one and its quality metrics, but ill wait for the next set of results to give a clearer picture.
If I wasn't so underwater on Card Factory (LON:CARD), I think it would be an opportunity for a punt as a recovery stock.
I am not in the mood particularly to try and average down, until evidence of an improvement is in train. Could this be a bid prospect? It was a cash generative business when it was in its pomp, paying divis, so might be back in the sights of Private Equity or the like.
I can't help think someone will take a serious slug of it before too long.
And within 24 hours of your comment, Aberforth Partners LLP acquire 6.6% of Card Factory (LON:CARD).
With CARD it might be worth pointing out they make most of their profit at Christmas when hopefully normality may have returned. I found it odd that there was no mention in the market update of how many of their 1000 shops qualified for the 10k/25k grant per shop ( depending on rateable value ). I would have thought it would be well over half.
Re £CARD - Also worth thinking about competitor set over time. Nearest direct competitor, Clinton (9% mkt value share vs 20% for CARD) was in trouble before COVID I think. CARD's merchandising instore is so much better. Will Clinton's survive/cut back? Lots of "general merchandise independents who sell cards will go under in next 6months . In the land of the blind, will the one eyed man be king : some UK mkt share gains may be had to offset lower footfall/market size?
CARD can similarly take more advantage of non-card sales (already 46% of revenue last year) and replace some of the cheap jewelry/ paper/ballons sales in these shops also going under. Claire's nearly went in 2018 I think. With ave. lease only 2.5years they will also have a lot of chances to upgrade/ relocate /expand to better locations which is relatively cheap for them to do or to drop rent, a major cost element. Wages/staff turnover, the other long term issue that was squeezing margins is likely to be a bit quieter as unemployment rises. It is not all bad. I also like them experimenting with card rack displays elsewhere (eg Aldi, Matalan). It helps drive volumes for them/takes it from others. Lower margin but gives them options if standalone branded stores start to decline. Their announcement also said they were killing Getting Personal as a standalone 2nd brand so all the focus is now on the main brand. That's very good. However, they also hinted at more international focus. I'm worried by this at the moment. Focus should be to survive and flourish in UK again and get online moving forward.
So IF (the big IF !!) by 2021 physical cards return to anything like the >£1150Mn 2019 market in which CARD are clear leaders (and pre-covid they forecast only a CAGR decline of only 3% over next few yrs) , they should recover fast and their brand should eventually give them a cashcow to build a much bigger online share. If we say COVID has sped online development up 5 years, that still leaves them leader in a near £1bn mkt. Their vertical integrated UK cost base also makes them lowest cost producers - especially to deliver wide range of designs, no 1 consumer need according to their research. So with scale and (historically) great margins, even a permanent 20% volume reduction will leave a good if smaller business by cherry picking the best stores.
Re financials and debt - yes post covid it will be high once we reach a new normal and so divis will not be as good as before. But as long the cashflow is positive, I am sure they will get funding relatively easily. There is no big capital programme at risk. Bit dull but left to itself to grind away for a few years, I think this will recover a lot of lost ground. I bought after Feb profit warning and am not minded to sell yet.
Panoply Holdings (LON:TPX) webinar today, 2pm, with Neal Gandhi, CEO & Oliver Rigby CFO. Following their very positive trading update last week.
Do join , or there should be a video of the webinar in due course.
Register via this link.
Also, we have another piworld Thursday webinar, this week 4th June, 1pm, with David Stevenson, Private Investor. The Adventurous Investor column writer for the FT, also contributor to Citywire and Money Week. He'll give his views on markets. What he's been buying/selling. And where to find income. Again, register via this link.
I hold IGP - I think the high receivable balance refers to the large government contract awarded in March . Nothing to worry about, Tuck it away,
Thanks for your views on Dlar Paull,managed to pick up some CRS yesterday who have over 19% stake in Dlar,on my quick calculations it's added around 35/40p to it's nav.
Yes at one point yesterday Crystal Amber Fund (LON:CRS) showed as up 32% before dropping back but I see it’s up 17% today. Nice to have a pick up after being brutally down for a wee while!
Hi Paul
Thank you for the update on De La Rue (LON:DLAR). This is a share I held long ago as a long-term investment in a quality manufacturing company, and got out of (at much higher prices than now) as problems began to emerge. Like yourself, yesterday's update triggered me into a small purchase, and I was duly gobsmacked at the price near doubling in a day. That has never happened to me before. The trading update does not mention any financials - for that we will have to wait until 17 June - I would have thought there is surely going to have to be a capital raise, but if the new CEO really has turned the corner on trading then it could be at a reasonable price. I will be interested in your thoughts as this develops.
Would be great to hear your thoughts on VNET :)
It's on the list of stocks above.
my bad, should have said I look forward to your thoughts on VNET!
Galliford Try Holdings. £GFRD. Contract news today....another. 42 million deal this time. Very highly rated here on stocko. Stock rank 98 and value 99 . Bought more today. "Galliford Try remains a well-capitalised business with no debt or bank covenants" from their last update statement sounded good to me.
Anyone else holding these? They do seem to have missed out on the market rally although moving well today.
I used to work for them (Linden Homes) great business. Was always very well run and the FD would always encourage staff to take up the share save as he truly believed it was a ‘great business’ I hold Vistry now since Bovis brought Linden Homes out and the shares transferred across but I will absolutely be buying GT again.
Hi Paul - Any chance please about a few words on £WAND They have been a roller coaster for some time - mostly down - but some interesting news today. Is their offering truly something 'special' ?
The thing I don't like about Wandisco - it's supposed to be awesome at data. Yet they STILL haven't released their results for y/e 31st Dec 2019.
Great handle you've got there on the data guys.
I've made good money on Wandisco (LON:WAND) in the past buying around 500p and selling circa 1200p when the valuation got well ahead of itself. I also bought back at 380p a year or so ago but that position got closed in the market meltdown around 480p so I am kicking myself about having no position today :)
But here's the rub : what always concerns me about these shares is the lack of serious revenue growth. It persistently misses revenue targets, share price gets whacked and then gets forgiven by the market. I feel it has a great product and Microsoft and Amazon clearly like it so I can see the "story". I just haven't seen it translate into big revenues and that concerns me. Results were also due out and haven't been released. The cynic in me says that they wanted the last 2 big "strategic" announcements out to give a good rise to the shares thereby softening any blow to the share price when the results are released and people focus on the revenues again, but I could be wrong.
I won't buy at this price. Feels over-valued to me until we see actual revenue growth. I want to see the results first. Interestingly it has now hit/exceeded even the broker price target of 800p!
Thanks David and others - its good to know I'm not the only one worrying and wondering whats going on. You are right - the growth is revenue is lacking - they put out announcements about big new contracts worth what... half a million - Come on these should be regular new buz not worth a mention...... as you say, with Amazon and Microsoft in the marketing where is the growth - well lets see when and what the annual results show !
I've got a full list of things to cover today already, so no room for any more I'm afraid, unless something exceptional crops up.
I've looked at Wandisco (LON:WAND) before, and done well on the shares as a trade, but don't feel I can really add any value to our understanding of it.
Paul what are thought on Gaming realms GMR. Up 20% today on good results?
Looks interesting. I've not had time to look into the details, but worthy of a closer look, on a quick skim of the announcement.
Intercede (LON:IGP) - the first time I have seen a link to an illustrated RNS which is here https://www.rns-pdf.londonstockexchange.com/rns/6071O_1-2020-6-1.pdf
Paul - how do you cope with this one being illiquid? Following the last trading update I bought at 55p. It went to below 50 in Mid May and I tried to add but it was impossible over several days to get an electronic quote for anything more than a nominal 100 or 500 shares. Looking at the trades list very often deals of a couple of thousand £ are outside the spread.
I'm afraid I'm probably one of the small traders Paul is referring to! Sorry Paul. Well not that small or that sorry! :) A man's got to eat. Thanks for the article.GL
Simon,
Absolutely! If you can make money trading IGP, then good for you! I just get irritated when the price movements cause big gyrations in my portfolio valuation. But that's my problem, and on days like today, it's a nice problem!
Regards, Paul.
Hi sharw, re Intercede (LON:IGP)
Paul - how do you cope with this one being illiquid?
I bought most of my long position in IGP in the summer of 2018, when the turnaround plan was starting to look potentially interesting. Since then I occasionally add to the position on red days, or when the price drops sharply because someone is selling.
But I agree with you, that trying to buy on a blue day, on positive newsflow, is nigh-on impossible. Or you have to pay top dollar, and then probably watch as it falls back again afterwards.
It's just not a trading share in my view, it's a long-term buy & hold which should pay off handsomely if mgt delivers on the hoped-for ramp up in revenues. If it all fizzles out, then I'd be left high & dry, with a large, illiquid position, nursing a loss! On balance, I think risk:reward is positive, hence am happy to continue holding for the foreseeable future, or for as long as the newsflow continues improving.
Regards, Paul.
Hi Paul,
Card Factory please. I'm surprised it's only opening 10% of it's stores on June 15th with Fathers Day a week later. I'd appreciate your thoughts.
INTU properties would be my request. It looks from their statement today that they have sufficient cash to meet this years requirements. Very bombed out stock of course.
Edit....soared now.
How interesting, thanks for flagging up this one. I might have a punt on it, for a possible short squeeze.
Can anyone please suggest a good alternative rns feed other than LSE?
Spantic. Here. If you set up your portfolio in folios it will tailor it to RNS. London Stock Exchange is pretty good. London south east is muddled, takes months to update, totally misleading trade information and random updates on RNS. I did get a full refund on the prime service which wasn't much better when I complained, and how I ended up here thanks to contacting the Naked Trader who also uses and contributes here.
Agree Simon - the RNS feed on this website is brilliant - just load up your portfolio and up come all the news stories every day on the home page - a real winner!
Morning Spantic,
I'm with you,the new LSE feed is really terrible,I've found the research tree site is much better and I think there is a free offer to join at the moment.
Thanks guys for your suggestions; Research Tree seems very good and got on it for free (thanks Spongbob) and no annoying page after page of ISHARES...ishares...
The LSE feed was OK last week, but the new version is awful. Please remember to provide feedback at the LSE site. After all, if they don't understand customer sentiment, it's unlikely to get fixed.
Aah, was wondering what was going on; was scratching my head thinking it was me having a senior moment, looking in the wrong place! (Feedback left on their website).
For stocks I have in my watch list, ADVFN seems reasonable. Set up your monitor, then before the market opens any stocks with an RNS will be highlighted, and that service is free.
I find this site, I believe because they rely on a third party, can be a little slower in finding RNS, so if you need the data bang on 7am, it might not be there. At least that has been my experience hence why I go somewhere else early morning. If it is better here now, I'll bin the ADVFN check.
I also check my portfolio news around 7:01 and my company RNS feeds tend to be there.
Ok, I'll start looking here first. Thanks for letting me know
Hi Paul,
I looked at Intercede (LON:IGP) a while ago and dismissed it as i thought the amazing client list but poor revenue etc didnt stack up. Why is the US military etc buying a security product but sales are not through the roof & why not bought out already by a security player. Cant remember why i looked no further but interested in your thoughts on this?
Secure Multi Factor authentication is built in to a lot of cloud services natively. Google, Facebook, Microsoft and the like identities are commonplace, work well for enterprises and don't require much effort to plug into existing services, which is why I was, and remain, sceptical about this company ever being anything more than niche. But niche can be profitable and I might be overlooking the market they work in, an example of knowledge of an industry working against you.
Happy to be proved wrong, and good luck to holders.
Note: I work for a company that has a large presence in the identity space so whilst I am trying to be a neutral observer of the market, I have an inherent bias that may cause me to misunderstand / misevaluate.
Hi john652,
I've written loads of stuff about Intercede (LON:IGP) - here's the link to our archive: https://www.stockopedia.com/share-prices/intercede-LON:IGP/discussion
The short version is that there were previously lots of things wrong with the company, and the new CEO set out a very clear 3-year turnaround plan. We've now just started year 3, which is all about driving revenue growth through channel partners.
Before they could do that, the software needed a lot more development, staff had to be stabilised & incentivised, and new channel partners recruited. It was a fairly extensive sort out job! Plus of course costs had to be slashed, and the various non-core development projects had to be culled.
The proof of the pudding therefore, is if sales do kick in with strong growth. If they do, then we have a multibagger. If they don't, then it would probably fall back to the 20-30p level.
Regards, Paul.
Hello Paul,
I’ve just read your comments & the last few rns updates from Intercede (LON:IGP) and they read really well, as do yours of course :) and the share price does seem to tick up each time too. Would you share your findings from management tomorrow if you speak to them? They do look interesting as a a year 3 turnaround with good tech & recurring revenue.
Would you be able to ask management tomorrow & post back, on IgotpoesJacket (most unusual name here Mr Poes !! ).
Secure Multi Factor authentication is built in to a lot of cloud services natively. Google, Facebook, Microsoft and the like identities are commonplace, work well for enterprises and don't require much effort to plug into existing services, which is why I was, and remain, sceptical about this company ever being anything more than niche.
Thankyou
J
Sure, I'm happy to pass on my impression from call with Intercede (LON:IGP) mgt tomorrow, but it's late afternoon, so anything I post here would be on Thursday.
I think the results statement today is so detailed, that it updates us very comprehensively. Hence I see it as a straightforward investment proposition - it's all about delivering on the plan for strong year 3 sales growth. Only time will tell if that works or not.
Morning Paul.
I am interested to read your opinion of #IGP. Results read v well to me. Profit and cash substantially ahead of expectations. Sales pipeline 40% ahead of last year. Rev ahead but a slight miss due to contract slippage / corona. Large holding for me.
In your PI World interview you said IGP was a top three holding for you.
I'm interested to know what the other top 3 holdings are?
Michael
Hi I believe his top holding is Big Dish £DISH.
Could I tap the wisdom of the crowd for thoughts on Galliford Try Holdings (LON:GFRD)?
Price to book is 0.2 and the ROCE is 11.6% which is reasonable, and yet the market doesn't seem enthused. An impending recession isn't helping I'm sure, but still; 0.2.
Could I tap the wisdom of the crowd for thoughts on Galliford Try Holdings (LON:GFRD)?
It does look very cheap but remember they're not a housebuilder any more, since they sold Linden Homes to Vistry. You'd need to look quite carefully at the recent accounts to figure out if the PTBV is still current. But I do note that the Stockopedia book value doesn't seem to have changed much from last year, which would be unlikely, I'd have thought?
But I haven't looked at them, so please don't take that as gospel.
timarr
Re GFRD.Yes has been some mystery around its performance recently with the stream of contract news. Obviously you have seen its Stockopedia ranking. There were 3 smallish shorts on it recently. Hit £1.64 before sliding down a low of @1.11 which is ok for a tech stock, not quite what I expected for a construction company with a seemingly sound work schedule and financial position. Update due soon. I blame algorithms. Not been any institutional notifications of share trades. I think/hope it will correct itself in due course and continue to hold/buy on dips.
£clg update looks very positive. Current year is only broadly in line but they expect to comfortably exceed expectations in 2021:
"The Company-compiled consensus for EBITA for FY21 is £25.8m. Whilst COVID-19 still presents some risk, the Board believes that EBITA will be comfortably ahead of these expectations."
Looks well placed so bought a few when the market opened
My morning smallcap tweet:
Driver (LON:DRV) Card Factory (LON:CARD) Intercede (LON:IGP) Gaming Realms (LON:GMR) Quartix Holdings (LON:QTX) Gusbourne (LON:GUS) Novacyt SA (LON:NCYT) Concepta (LON:CPT) Zoetic International (LON:ZOE) Clipper Logistics (LON:CLG), Xaar (LON:XAR), Hargreaves Services (LON:HSP)
Driver Group (DRV) CEO scarpers. He is thanked.
Card Factory (CARD) FY(Jan) rev up 4%, adj EPS down 13%. Will open 10% of stores Jun 15. Is there a Congrats on Your Reopening card? Confident co has access to sufficient liquidity for navigating the times ahead.
Intercede (IGP) FY(Mar) rev up 3%, EPS up 12%. Outlook: some postponement of decisions on new sales opportunities, offset by realisation of orders delayed from March and from existing customers preparing for their staff to work from home.
Gaming Realms (GMR) recent 5 months licensing revenue up 80% cf FY19 90%. Guides FY EBITDA significantly ahead of market expectations.
Quartix (QTX) first 4 months rev up YoY. New installations in May down 25% cf Apr down 60%. UK vehicle mileage fell 54% to its lowest point and partially recovered to 32% down. Covid has not yet had a material impact on subscription base.
Gusbourne (GUS) rev in first 3 months of '20 ahead of directors' expectations but hit from March. Co engaged in a number of new sales initiatives to mitigate this impact. New £10.5 million asset-based lending facility.
Novacyt (NCYT) sales of Primerdesign COVID test €45m and orders for, or been contracted to deliver, a further €90m. In H2 additional COVID related sales expected from new products: Exsig Direct and Exsig Mag, and from co's mobile testing solution. France regulator has not approved Primerdesign's COVID test for reimbursement.
Concepta (CPT) A repositioned myLotus fertility tracking and pregnancy self-testing system 'will emerge' from June along with a digital campaign. New App after that.
Zoetic (ZOE) £350k placing at 4p, a 45% discount, to an existing holder, John Story. Will fund additional distribution contracts announced today for Chill brand products in USA.
Clipper Logstcs (CLG) guides FY(Apr) broadly in line with expectations. EBITA ~£24m up 19%. Significant increase in tender pipeline. Guides FY21 EBITA comfortably ahead of expectations of £25.8m
In line: Xaar (LON:XAR) Hargreaves Services (LON:HSP)
A view on Intercede (LON:IGP) if possible please Paul.
Agree, would welcome a comment please on IGP. Having shot up to 74p when the directors started buying it fell all the way back to 50p and has been climbing again rapidly in the last couple of weeks in anticipation I guess. Although £1 million profit may seem like small fry. it seems to have turned a corner and worth mentioning the 40% increase in sales pipeline compared to this time last year. That is impressive in this environment. I see someone gave me a minus vote for suggesting GFRD yesterday lol. Is it that boring? The sp movement certainly hasn't been. I guess we may as well wait for a trading update shortly from them.
Intercede (LON:IGP) is top of the list! I've spent most of the key 7-8am hour reading its results & making notes. It will probably take me another hour or so to type up my notes above. Preliminary impression is positive, looks good.
Thanks Paul. Rather muted reaction so far on sp. Basically confirms last update wit h a little more info. Notice a separate comment about no dividend yet, but there is obviously intent there!