Small Cap Value Report (Tue 20 Aug 2024) - BKS, CGS, HAT, ZOO

Good morning from Paul & Graham!
We've run out of time for today. I might circle back to some of the other companies reporting today, with short comments tomorrow possibly.
Explanatory notes -
A quick reminder that we don’t recommend any shares. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech, investment cos). Although if something is newsworthy and interesting, we'll try to comment on it. Please bear in mind the "list of companies reporting" is precisely that - it's not a to do list. We typically cover c.5 companies per day, with a particular emphasis on under/over expectations updates, and we follow the "most viewed" list of readers, so if you're collectively interested in a company, we'll try to cover it. Obviously with the resources available, we can't cover everything! Add you own comments if you see something interesting, and feel free to discuss anything shares-related in the comments.
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to, if they are using unthreaded viewing of comments.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. And/or it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Others: PINK = takeover approach, BLACK = profit warning, GREY = possible de-listing.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom), Video update of results so far, June 2024.
Frozen SCVR summary spreadsheet for calendar 2023.
New SCVR summary spreadsheet from July 2023 onwards.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Phil Hanson's data analysis measuring performance of our colour-coding system in the SCVRs, from July 2023- Mar 2024 (with live prices). My video explaining/reviewing it.
My other video (June 2024) - How to screen for broker upgrades on Stockopedia.
Companies Reporting
Summaries
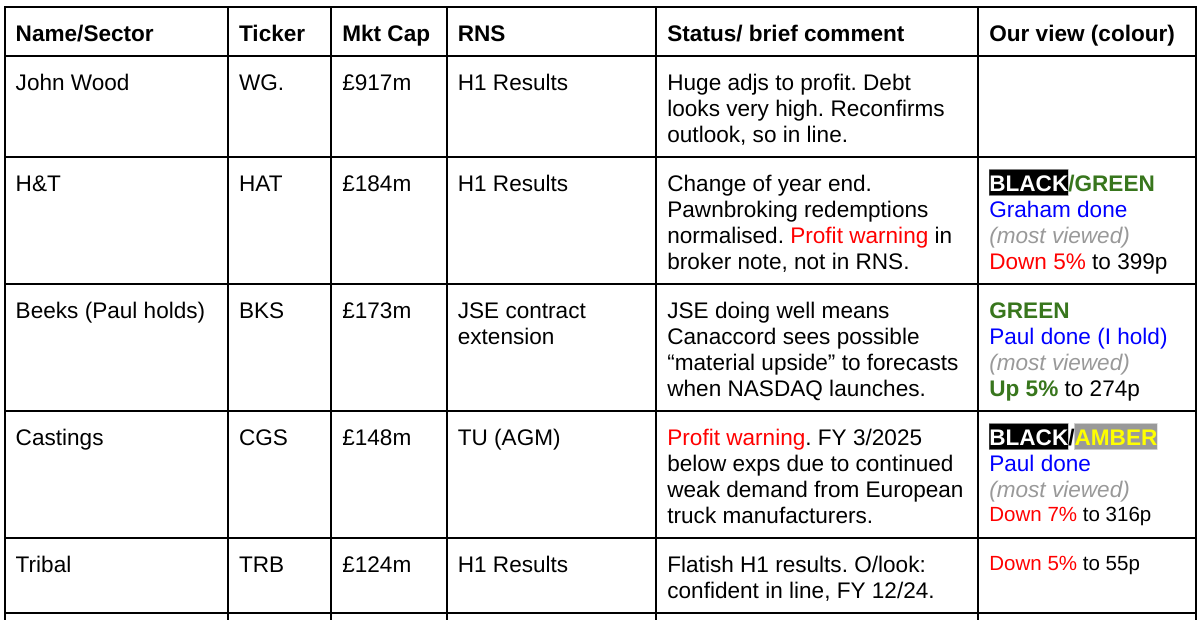
Beeks Financial Cloud (LON:BKS) (Paul holds) - 260p (pre-market) £173m - Extension of JSE contract - Paul (I hold) - GREEN
More food for the bulls this morning, with the large Johannesburg Stock Exchange contract once again being extended to a second data centre location (for backup/security I think). No financial details are given. Canaccord flags that if NASDAQ launch goes well there could be "material upside" to forecasts. I remain very bullish, but as the price rises it becomes more difficult to value the shares, and there's bound to be some profit-taking at some stage.
Castings (LON:CGS) - down 5% to 322p (£141m) - AGM Trading Update [profit warning] - Paul - BLACK / AMBER
Continued soft demand means a fairly hefty 32% reduction in forecast profit for FY 3/2025, which can't be ignored. Hence I'm dropping a notch from Graham's amber/green on the last profit warning in June. Shares have fallen a fair bit before today, but don't look good value yet. That could change if trading improves, so it depends on your view of where we are in the earnings cycle. For now, I'm sitting on the fence because forecast earnings have now more than halved this year, which is a lot! Superb balance sheet is a considerable comfort.
H & T (LON:HAT) - down 4% to 402.4p (£177m) - Interim Results - Graham - BLACK/GREEN
I’m a little frustrated with H&T today for two reasons. Firstly, their house broker has cut EPS forecasts by 10%+ but there is no acknowledgement of reduced forecasts or a profit warning in today’s RNS. Secondly, they are changing their accounting reference date which is something I almost never welcome but H&T says it is needed to address increased seasonality. Despite these annoyances, I still like the stock at a PER of about 7x and with medium-term prospects which I still regard as very good.
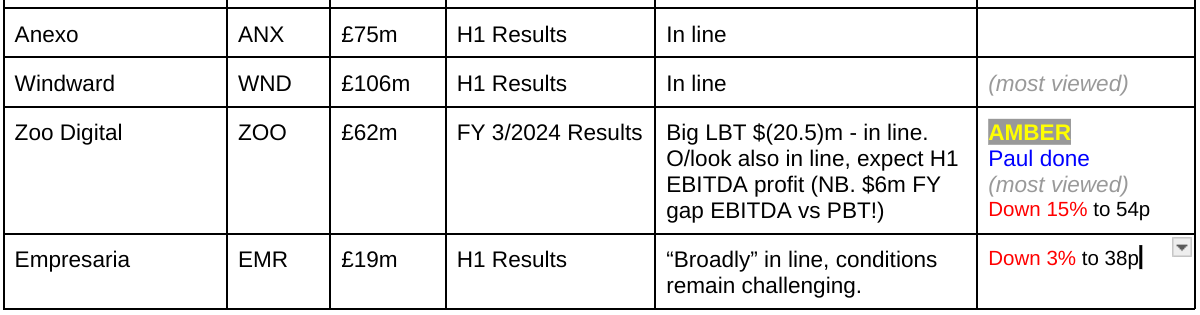
Zoo Digital (LON:ZOO) - down 10% to 56.5p (£56m) - FY 3/2024 Results - Paul - AMBER
Terrible results for FY 3/2024, but as expected, due to the Hollywood strikes. Outlook comments strike me as lacklustre. Cash looks adequate, and going concern is clean. Recovery could take longer than expected, as the broker points out long lead times. Personally I don't see any attraction at all, it's just a punt on hoped-for industry recovery. Forecast is only for breakeven in FY 3/2025 - I point out below why EBITDA figures are nonsense here.
Paul’s Section:
Zoo Digital (LON:ZOO)
Down 10% to 56.5p (£56m) - FY 3/2024 Results - Paul - AMBER
ZOO Digital Group plc (AIM: ZOO), the leading provider of end-to-end ("E2E") cloud-based localisation and media services to the global entertainment industry, today announces its audited financial results for the year ended 31 March 2024.
Diabolical numbers for FY 3/2024, as expected, since this period was greatly disrupted by the Hollywood strikes.
Revenue down 55% to $40.6m
Massive loss before tax of $20.5m, versus a LY PBT of $7.9m.
Net cash fell from $11.8m at 3/2023 to $5.3m at 3/2024. However, that includes the disappearance of $15.5m equity raised during the year supposedly for an acquisition (that hasn’t happened, sorry it’s “postponed”). Instead all that cash (and more) has been squandered on operating losses. Why didn’t they slash their overheads when the strikes started? That’s what good management does in a downturn - act quickly to slash costs. Instead this lot burned through their cash pile before belatedly cutting costs once the cash looked like it was running out. This is why I flagged it as AMBER/RED back on 28/3/2024, as at that point in time the risk of cash running out looked high, although there were also some early signs of trading improving after the strikes ended.
Graham took a fresh look on 13/5/2024, where he shifted up a notch to AMBER, because the news had improved - bank facility extended for another year, giving more cash headroom, and broker upgraded EBITDA forecasts. Strong Q1 and good visibility. So when the facts change, we reflect that - which to clarify yet again for any slow learners, is what our colour-coding is all about - it’s a snapshot view on that specific day, of the facts, figures, and forecasts. It’s not a prediction of what is going to happen in the future. So when the facts, figures & forecasts improve, we up our view, and vice versa.
Anyway, back to today’s FY 3/2024 accounts, they’re awful, but in line with expectations, so no surprises on the enormous loss and cash burn.
Let's move on to the outlook comments, some excerpts here -
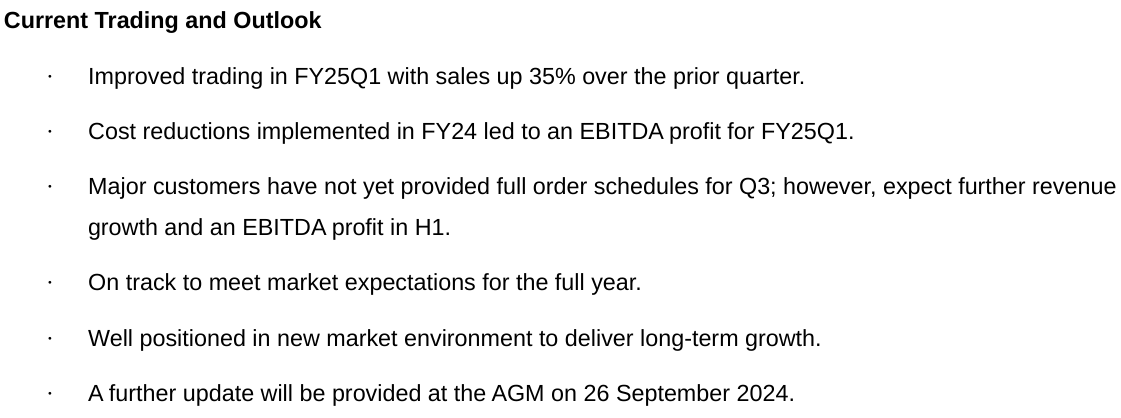
“Most recently, in Q1 2025, our order book expanded by 35% over the prior quarter as work delayed from 2023 was eventually completed and we were profitable at EBITDA level as the improvement in revenue coupled with the cost reductions implemented in FY24 came through. With a stronger year-end cash position than previous market expectations combined with its renewed debt facilities, the Company has sufficient working capital for FY25.”
Full year guidance sounds in line -
“Our major customers have not yet provided full order schedules for Q3 onwards; however, the Board expects further revenue growth and an EBITDA profit in H1 2025, putting us on track to meet market guidance for the full year.”
Further detail is given in the bullet points below, which sound lacklustre to me (reminder: $6m EBITDA is PBT of zero) -
Broker forecasts - many thanks to Singers for its FY 3/2025 estimates, which are a 50% recovery in revenues to $60m, $6.5m adj EBITDA, and adj PBT of err, nothing! Or rather a $(0.1)m loss.
The company reckons industry recovery should mean further improvements, which is vital to justify anything near the current market cap of £56m.
I don’t have any particular view on whether or not ZOO will be able to move into sustainable profits or not, that’s up to you to predict.
The broker reckons that AI isn’t a threat. Again that’s up to you to have a think about, but personally I would have thought that as language models get better & better, it’s bound to have some impact, but I have no idea how much. Why get involved in a share where you have to make that type of guess about the future?
Going concern - is clean, saying that the $3m invoice discounting facility (to 31/8/2025) gives enough cash headroom, and that they could take mitigating actions if necessary if trading disappoints. Let’s hope they act much more quickly than last time.
Balance sheet - what they call “borrowings” are actually lease liabilities, see note 7. A presentational own-goal there, which I think we’ve mentioned before.
NAV is $27.7m, including $15.1m intangibles, and $3.1m in “equity accounted investments”, which I’m inclined to write off leaving NTAV of $9.5m - not a great deal.
It’s worth noting from the reserves part of the balance sheet (that records numbers since the company first started), where shareholders have injected $72m in share capital, and the company has burned through almost all of it, with retained losses of $67m. This reminds us that ZOO has not yet established itself as a reliably profitable business. Although this should mean it won’t be paying corporation tax for some time if it does move into profit in future.
Cashflow statement - is obviously awful for FY 3/2024, due to the industry effectively being partially shut down due to the strikes.
Some numbers to note - it capitalised $2.7m of development spending, which renders EBITDA meaningless of course.
There was also $2.2m of physical capex, a reminder that to do what it does, ZOO needs a fair bit of kit which isn’t cheap. Again, making EBITDA a nonsense number.
The equity raise of $15.0m net of costs saved the day, and without that, I think ZOO would have gone bust.
Paul’s opinion - I have no idea why some investors get so excited about this share. It just strikes me as very ordinary. The only decent profit it has ever made was in FY 3/2023 when streaming services were spending big on international expansion. We can’t blame ZOO for the collapse of profitability in FY 3/2024, as the Hollywood strikes caused that.
However, even with the forecast 50% recovery in revenues this year FY 3/2025, it only gets ZOO back to breakeven at PBT.
To get to a market cap of £56m, you’re guessing that performance will improve strongly beyond the recovery already factored in this year. Management say they can get back to previous peak profits - which if achieved, would probably make this share double or triple. That's the bull case.
With rather lacklustre outlook comments, it seems to me that ZOO is struggling to gain traction, and as Singers points out, the recovery timescales for new films from being written and produced, to requiring ZOO’s services, is long.
It wouldn’t surprise me if ZOO warns again on profit in Q3 or Q4. Cash could get tight by then if a more convincing recovery hasn’t started.
So for me, risk:reward is not at all attractive at this stage, and I see this share as a complete punt.
Good luck to holders, but for a £56m market cap you can get much better quality companies with dependable, consistent performance, and decent divis. So why get involved in this, where you’re hoping for a recovery to happen before it runs out of cash?
That said, management talk a good story in the commentary today, and if you believe it’s likely to pan out as bullishly as they suggest, then this share could do well.
I’ll go with AMBER, because I don’t know what the future holds, but I remain sceptical about ZOO, so am happy to sit on the sidelines. Good luck to holders, let’s hope the facts improve and you do well on the shares.
Castings (LON:CGS)
Down 5% to 322p (£141m) - AGM Trading Update [profit warning] - Paul - BLACK / AMBER
Castings PLC ("Castings" or "the company"), the leading iron casting and machining group primarily focused on the European heavy truck market, announces a trading update..
This year is FY 3/2025.
Profit warning - an admirably clear explanation of what’s gone wrong, but what’s missing is quantifying how much of a profit miss this is likely to be -
“We previously reported in June that demand from our commercial vehicle customers (80% of group revenue) was at a lower level, relative to the elevated demand in the year ended 31 March 2024, with the potential for a slight increase in the autumn.
Demand has remained at lower levels and our customers have now indicated that there is unlikely to be any improvement before at least early 2025. The OEMs are citing caution in the end customer buying decisions, particularly in Europe. In the light of this, the result for the full year to 31 March 2025 is anticipated to be below market expectations.”
Broker updates - both Zeus and Canaccord have issued updates, thanks to them for sharing these with us via Research Tree, which I find very helpful.
This is a hefty miss, with Zeus lowering FY 3/2025 forecast adj PBT by 32% to £10.1m = 17.3p adj EPS = PER 18.6x (hardly a bargain).
The City seems to use EV/EBITDA multiples for valuation purposes these days, so in this case forecast adj EBITDA is down 20% to £18.3m. Forecast EV I will calculate as today’s mkt cap £141m minus forecast y/end net cash of £18.7m = EV 122.3m
So I make EV/EBITDA 6.7x - a fairly modest level, but possibly in the right ballpark for an ex-growth business that is overly dependent on one specific sector (with question marks over the longevity of its market for diesel truck engines).
Vvaluation depends on whether future earnings might recover. This share would look cheaper if an operationally geared recovery were to happen in FY 3/2026.
It’s quite tricky to know what the settled level of profitability is likely to be, as we’ve had so much disruption over the last 4 years from pandemic, stocking up, destocking, energy crisis, supply chain issues, etc.
Balance sheet - CGS has a strikingly strong balance sheet, with NTAV of £134m at 3/2024. I feel that my EV calculation above doesn’t fully capture the surplus capital on the balance sheet by just including forecast cash.
Paul’s opinion - Graham eased us down a notch from green to amber/green with his review on 12/6/2024, when soft demand was mentioned, and forecasts were reduced. With forecasts sharply reduced again today, likely performance for FY 3/2025 is now less than half the EPS that was originally forecast.
So the key question is to what extent do you expect earnings to recover next year & beyond? It needs a recovery in earnings to justify a higher share price, as the valuation is not cheap on a PER of 18.6x the current year’s forecast earnings. Divis are likely to be cut I imagine.
On the basis of the above, I would normally be inclined to go down another notch to amber. However in this case the balance sheet is so strong, and the long-term track record is impressive, plus some recovery in earnings next year seems likely, that I was minded to stick at amber/green.
Shares had already sold off a fair bit before today, and a modest 5% share price fall today on a 32% forecast PBT reduction, suggests that shareholders here are not easily spooked. Or maybe sellers can’t sell, given the lack of liquidity in this tightly held share?
I don’t feel at all motivated to buy any of these shares myself, so maybe I should be amber after all, given the steep fall in forecasts this year, and that we don’t know if/when a recovery will happen. Yes, I think I’ve made up my mind, to reduce a notch to AMBER - which is not bad remember - it’s just saying I’m not sure what will happen next, and I can’t ignore another 32% drop in forecast earnings. The fall in shares of only 5% today is a clear mismatch with that 32% forecast fall, so I feel that a better buying price would be something nearer 250p than the current 322p. The difference of 72p is people factoring in a future earnings recovery, but personally I'm not keen on being asked to pay up-front for that.
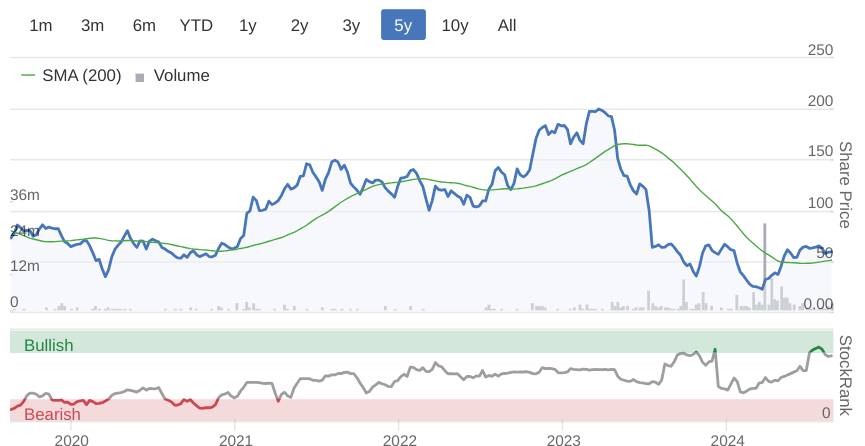
Shares haven't gone anywhere in the last 10 years, but it has paid decent divis over that period - which was great in a 0% interest rate environment. But now you can earn close to 5% on cash, why get involved with shares in ex-growth companies paying a similar dividend yield? Things have changed.
Beeks Financial Cloud (LON:BKS) (Paul holds)
260p (pre-market) £173m - Extension of JSE contract - Paul (I hold) - GREEN
Beeks Financial Cloud Group plc (AIM: BKS), a cloud computing and connectivity provider for financial markets, is pleased to announce that the Johannesburg Stock Exchange (JSE) has signed a further significant contract extension for the provision of Beeks' Exchange Cloud, to a second data centre location. The multi-year contract extension further supports the Board's confidence in its financial expectations…
It’s encouraging to hear this important, large contract with the Johannesburg Stock Exchange is going well, and has been extended again (in terms of scope, rather than duration).
It’s good to get third-party comments, this is from the JSE itself -
“Tebalo Tsoaeli, Chief Innovation Officer at the JSE, commented: "Since the launch of Colo 2.0 in September 2023, JSE has seen significant adoption of the Colo 2.0 service by customers, demonstrating a clear demand for the product offering. This has resulted in additional demand for a secondary solution aimed at addressing the redundancy and Disaster Recovery requirements of existing customers. Through our partnership with Beeks and IPC, JSE seeks to power a truly cloud-based marketplace infrastructure that is modern, hyper-scalable, ultra-resilient, highly performant, and accessible to all market participants."
Beeks comments once again mention that more exchange deals are in the pipeline, so I think we’re likely to have continuing exciting newsflow from Beeks for some time to come (which is necessary, to back up the strongly rising share price) -
“Gordon McArthur, CEO at Beeks, commented: "We are delighted to announce this further expansion with the JSE to meet the growing demand for the Colo 2.0 service from the JSE's customers. Exchange Cloud continues to be a unique offering in the market, and the success of the solution at the JSE is supporting our discussions with other global exchanges, underpinning our confidence in continued momentum."
Paul’s opinion - given that JSE is clearly going very well, and NASDAQ is the next project to start, having just achieved regulatory approval, Beeks is clearly on a roll.
Thanks to Canaccord for a brief note this morning which has one line which caught my eye in particular, saying that successful implementation and customer uptake of the new, large contract (which is NASDAQ, but can’t be disclosed due to an NDA),
“could create material upside to our forecasts”.
My view remains that BKS is a very exciting situation, but it’s difficult to value the shares right now. There are bound to be bouts of profit taking along the way. Personally there’s no way I’m selling, as the NASDAQ contract could (pretty obviously!) be a monster, if there’s big customer uptake of the service. The fact that much smaller JSE is clearly working well, and has been extended twice now further reinforces my confidence that the upside potential here is not a moonshot, but actually seems quite likely - providing nothing unforeseen goes wrong.
We’re also reminded today that there are advanced discussions with other exchanges globally too. Another reason to sit tight I think.
The bear case is basically that it’s overpriced, and that cashflow has been unimpressive. It’s up to you which side of the fence you’re more comfortable on!
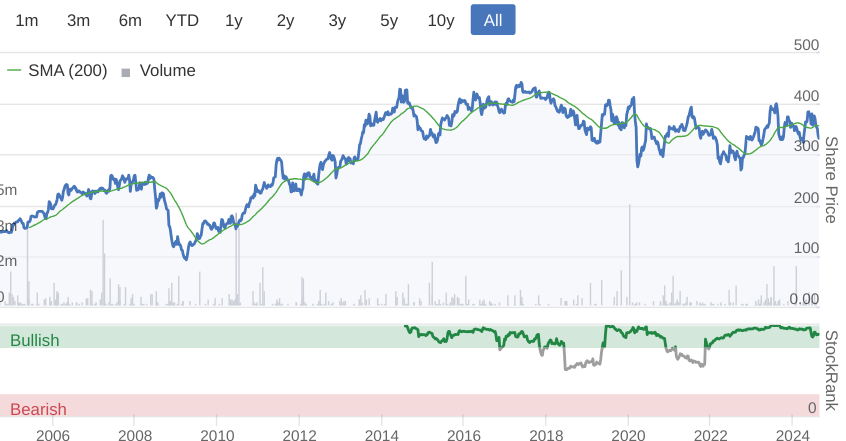
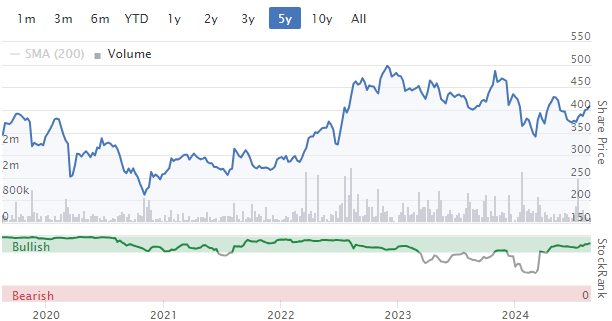
Here's the BKS chart since it listed in late 2017 -
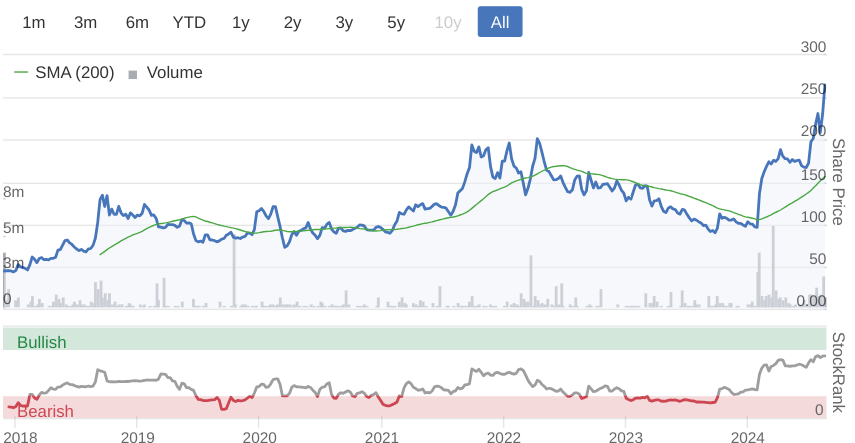
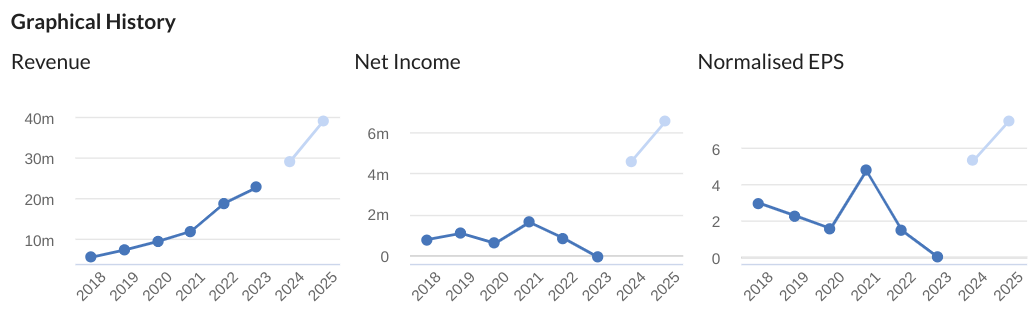
Look at the progress that has been made on fundamentals though, and I would argue it was overpriced between 2017 and 2023, and is now actually quite reasonably priced in comparison, since highly impressive compound growth has been achieved, with a lot more to come now the NASDAQ contract is limbering up for implementation - which isn't in the forecasts yet remember, so expect serious upgrades if that goes ahead without a hitch -
Graham’s Section:
H & T (LON:HAT)
Down 4% to 402.4p (£177m) - Interim Results - Graham - BLACK/ GREEN
We covered the H1 trading update here in July, when high redemptions (i.e. customers ending their loans quickly, to get their items back) were the hot topic.
Today we have confirmation that redemptions are back to normal, “albeit later than anticipated”.
As a reminder, the pawnbroking pledge book here has a capital value (excluding accrued interest etc.) of £105m, by far the largest in the industry. This capital value is up since December 2023, but that’s with the help of an acquisition. Excluding the acquisition, the capital value of the pledge book would be slightly lower than it was six months previously.
The boom period in pawnbroking may be on hiatus, perhaps to return again before too long?
Estimates: the house broker Shore Capital has published a research note today, in which they reduce all of their EPS estimates (for 2024, 2025 and 2026) by 10%+. This is attributed to the “increased seasonality” in pawnbroking.
We therefore have an effective profit warning, but you have to read the broker note to see it! There is no profit warning in H&T’s RNS today.
Change in accounting reference date: this is never something I look forward to.
Following consultation with a number of shareholders and after careful consideration, the Board has made the decision to change the Group's financial year end from 31 December to 30 September with effect from September 2025. This will result in financial performance being more evenly spread across the two half year reporting periods.
Changing the accounting reference date creates complexity for historical analysis, makes a mess of financial statements during the transition period, and what does it really accomplish?
H&T says that financial performance will be more evenly spread across the two halves, but the split wasn’t too uneven last year. I guess that seasonality has become more pronounced in 2024.
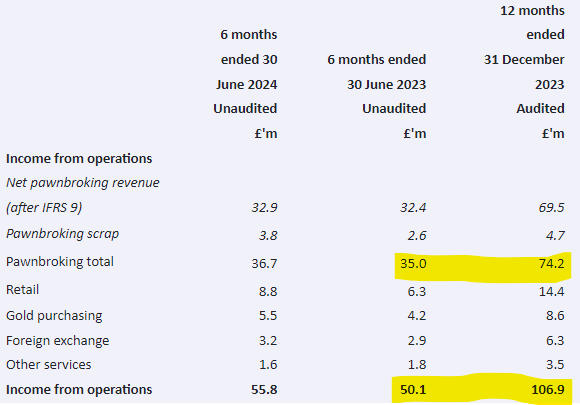
The most worrying aspect of a change in accounting reference date is the suspicion that it’s being done because the regular results aren’t too inspiring, and the confusion caused by the change suits the company.
However, I normally associate that tactic with junk companies, not with reputable firms like H&T! So I can only assume that the motivation for this change is legitimate and is purely to do with increased seasonality.
Let’s get back to today’s results and highlight some of the key points.
H1 PBT £9.9m (no adjustments), up 12.5%.
Diluted EPS 17.7p, up 8.6%.
Interim dividend: 7p (last year: 6.5p).
Maxcroft acquisition: H&T acquired a “posh” pawnbroker earlier this year. Its integration is “proceeding as planned, with valuable insights being applied in other stores”.
CEO comment (emphasis added):
"I am pleased to report that we have continued to make positive progress in the first half of 2024.
Our core pawnbroking business continues to attract increasing numbers of new and returning customers, for whom alternative sources of small sum regulated lending are much constrained. Retail sales have also been encouraging, with margins on all product categories improving in the second quarter and expected to further improve through the remainder of 2024. This performance has been supported by growing demand for our foreign currency service and improved margins on over-the-counter gold purchase.
Maxcroft has performed well since the acquisition in February. We have begun to apply our learnings from their foreign currency business to selected H&T stores, and we have seen an increase in footfall and sales as a result.
Readers may remember that there was volatility in the 2nd-hand watch market last year. Thankfully, that problem seems to have gone away as prices have stabilised. The issue is mentioned today with an acknowledgement that H&T reduced its exposure to watches last year. However, with the volatility of watch prices having “abated”, they are now ready “to cautiously increase activity in this asset class once again”.
Compared to other items, watches are associated with larger loans to customers and lower redemption rates (i.e. H&T are left in possession of watches more often than they are left holding other customer items). So it’s a tricky asset class. Fortunately, H&T are the experts as they own Swiss Time Services, “the UK’s largest independent watch servicing centre”.
Here’s an interesting YouTube video published recently by a watch collector, discussing the H&T offering - link.
Net debt has increased since Dec 2023, from £32m to £49m. The Maxcroft acquisition (£11m price tag) occurred during this period. I generally like it when H&T’s net debt increases, because it means that they are growing!
Outlook - very confident in the medium term. They remain interested in opening new stores, in refreshing existing stores (50 store refreshes per annum), and in acquiring stores from independent operators. 8 to 12 new stores to be added in 2024. I’m comfortable with that rate of expansion.
In pawnbroking, they want to target business owners who can pledge valuable personal assets for business purposes. The Maxcroft acquisition makes sense in terms of making a quick start in this strategy.
In costs, payroll is the major expense and the minimum wage is a key factor. We’ve discussed this before in relation to Ramsdens Holdings (LON:RFX).
I would have appreciated it if the company had acknowledged in today’s outlook statement that they needed to reduce forecasts, instead of leaving it up to the brokers to reveal that.
Graham’s view
As usual, there are a lot of moving parts here, and macro-economic forces at play. Foreign travel boosts FX revenues. The gold price boosts (or hurts) scrappage prices. The (shortage of) supply of alternative credit boosts demand for pawnbroking loans. Minimum wage determines payroll costs. Et cetera, et cetera.
The investment thesis here is ultimately unchanged: this business has been around since 1897 and despite the occasional hiccup, it continues to go from strength to strength.
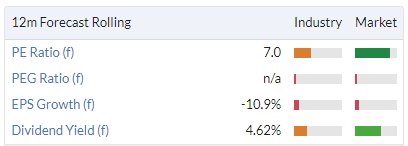
In exchange for some macro risks and perhaps some day in the future, some regulatory risks, you get a PER of 7x and a nice dividend yield:
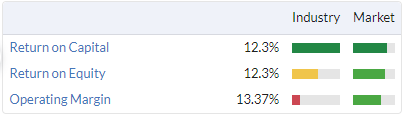
The company has sometimes struggled to generate an attractive ROE/ROCE, but it is doing pretty well on that front now:
Putting it all together, I continue to think that H&T holds many attractions for investors, with very little to dislike. At a PER of 7x, I suspect that the prospects are good from here. But I must admit that I’m a little frustrated by the manner in which the cuts to EPS forecasts were revealed, and I never like to see a change of accounting reference date. So today’s results have left a bad aftertaste.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

77 comments
H & T (LON:HAT) H124 results webinar
We did a webinar with HAT yesterday which is here video & podcast.
I won’t repeat the content of the results which Graham has covered.
Yes, the ShoreCap forecasts (house broker) were downgraded, however the growth over the last 2 years is still respectable. Here H124 PTP +12.5%. (Silly that they forecasted more since this alone would have looked ok!) It offers a 5% dividend while you wait. Interestingly, Canaccord forecasts were more accurate. Perhaps unusual for the House to be less accurate than non house broker.
The issue for them has been early redemptions of pledges. Obviously, if the loan is redeemed earlier, they get less interest.
Positive were the new initiatives being rolled out by the group. inspired by Maxcroft acquisition last year, which are benefiting their fx volume and profits. And, in the small business loans, which is much bigger for Maxcroft, HAT are upping their sales efforts to get out and about networking with small business owners. It will be v interesting to see how the pawnbroking to small businesses grows. Obviously the average pledge size here is larger, say £5k rather than the £200 median.
FWIW, I thought it was interesting that the price for gold, which will serve them didn’t come into the webinar.
Hello Paul,
Warpaint London (LON:W7L) may be an opportunity for a starter position, soon...
Thanks JD,
Indeed, Warpaint London (LON:W7L) is twitching away on my radar, with recent falls!
I'd be tempted if it drops further to 400-450p range.
Regards, Paul.
I'd be tempted if it drops further to 400-450p range.
Of course that would make for a classic head and shoulders which would have to make you ask “what is it that might have changed to cause the sell-off?” Although the possibly challenging valuation at 25x next year’s earnings at its recent peak looks to be part of the answer.
Maybe my maths isn't great, a 450p share price would put this on a cash adjusted forward PE of about 13?
Miserly!
Yes, my maths is bad, it's around 16
Maybe my maths isn't great, a 450p share price would put this on a cash adjusted forward PE of about 13?
How are you getting to that figure of 13x? Cash, after adding back leases is just under £20m according to Sharepad. That hardly puts any dent in a market cap of £400m. At a SP of 450p and allowing for that cash, I make the valuation around 16x for FY24. Quite reasonable nonetheless and certainly a great buy if it falls to 400p purely on sentiment.
Warpaint London (LON:W7L) Schroders are sellers here going from 13.25% in May to 10.9% by the end of July (with two sales in June and one in August. Watching to see if they keep offloading.
Big Technologies (LON:BIG)
I believe this is a fundamentally good company and given there are aren't enough prison places to satisfy demand their electronic tags business looks an obvious beneficiary. Healthy margins and a huge cash balance of £86m and rising, share price down to £1.09 near to all time closing lows, so far so good.
However the Board are horrendously greedy and helped themselves to £17m in free shares in the last two years with a further two larger tranches to come (which if I understand correctly are based on a share price of £3.10 or higher however the remuneration committee retain the right to adjust the LTIP criteria if they think appropriate) and there is a legal dispute over part of their ip which they are contesting.
It's a dilemma, I abhor this level of greed from the directors but the product is good and should prosper over the next few years, I want to own it but can't endorse this level of corporate theft, I think I have talked myself out of buying any......Any holders out there with arguments to support these levels of LTIPS? Thanks
Big Technologies (LON:BIG) I’m afraid you’ve ably summarised my own vacillations on the name, so I’ve nothing of use to add (except company)
Beeks Financial Cloud (LON:BKS) and Intercede (LON:IGP) have been rocketing lately on back of news regarding affiliations with one of the largest exchange groups globally (likely NASDAQ) and Microsoft respectively. Got me thinking that UK based tech companies that announce major relationships with US based companies / organisations are likely to attract US investors that are looking to move money out of overvalued US tech stocks (magnificent 7). Just a thought although one could argue that Beeks and Intercede valuations are starting to look punchy (continuing to hold though given potential of both). More of a general point.
Got me thinking that UK based tech companies that announce major relationships with US based companies / organisations are likely to attract US investors that are looking to move money out of overvalued US tech stocks (magnificent 7). Just a thought although one could argue that Beeks and Intercede valuations are starting to look punchy
I think you answered your own question there.
Valuations are up for debate and could be argued both ways depending on how you see the potential of these two companies but more of a general point as I said.
Dear Graham
H&T (I hold)
Just as an observation, there are three brokers covering this company whose research is publicly available. The house broker, Shore Capital, has reduced estimates twice this year, in January and again today both by double-digit percentages. This suggests to me that either management is not being sufficiently cautious in its conversations with Shore Capital or the analyst is deliberately shooting too high in the belief that challenging targets will be met. By contrast, a note published today by Cannacord on the ResearchTree website produces earnings forecasts similar to the revised lower figures now offered by Shore Capital. The third report, that of Hardman, was published in July and I suspect their earnings estimates for 2024 (55p), 2025 (60p) and 2026 (67p) will also have to be reduced closer to that of circa 50p, 55p and 58.5p which is now nearer the consensus for this year and the following two years.
Personally, I am not too concerned about the change in the financial year-end if it means that sales, profits and earnings are more evenly spread over the two half-year periods providing the company is transparent in its comparisons.
Kind regards
Phillip
Having just listened to the results webinar in full, I feel happier about H & T (LON:HAT) progress, although I noted that they didn’t comment on the reduced profit forecasts. They were also a bit vague on cash generation.
I like the management, who seem open, committed, honest and likeable. I will continue to hold. A Hold for me.
Frankly I just don't get changing the accounting ref dates in Holding Companies, and invariably find the prime motivation is to adjust the view of the onlooker rather than to adapt to some new reality.
I think people underestimate how much CEO's/Board''s dislike reporting bad news to the markets, and like most of us would rather sit under a waterfall of praise, or to smooth out a period where it just so happens are important for some remuneration purpose.
So inevitably someone in the Finance Dept will think up an adjustment that is bigger than all the other adjustments, and that suddenly appeals. Don't be surprised if this happens after acquisitions, when perhaps they are not quite performing as hoped, and a change of accounting date buys extra time for pipe line to come good.
Its never a good look in my view, on the basis if they are prepared to do this what else are they prepared to fudge? But that's just my cynical personal view
Exactly this. It is not like H & T (LON:HAT) has massively changed in the last year or two, so that a change in year end date makes sense.
The excuse to "better align seasonality" just doesn't hold... I don't think I've ever heard of management or shareholders in the last few years raise a concern that the year end date is causing problems at H&T.
Feels like there's some bad patch of trading upcoming, and this is the way to obfuscate this.
As an "inline" Windward (LON:WNWD) (I hold) is not attracting any comment today, but I think this is more interesting than "inline" suggests. Firstly, it is inline with estimates upgraded in July, and although it is still projected as at a net loss for the year it is declining, H1 23 $5.7m loss down to a H1 24 loss of $4.0m (they are forecasting to reach an EBITDA breakeven run rate in the the second half, EBITDA may be a wonky measure but I like the trend. I also like the trend of Operating Margin which having declined to 78% (!) has now recovered to 81% and is forecast to stay above 80%.
The revenue trends are good too, both in the growth of 37% and in the quality, since they have added 34.8% of new contracts and widened the non-government sector. Cash burn is now minimal compared to its $13.8m net cash position. I am also encouraged that they expense virtually all their R&D and what is not expensed is more than covered by amortization.
Israeli software companies have a rather uneven history on AIM but I am comfortable with this one.
Aislabie, FWIW,
Windward (LON:WNWD) I watched the investor presentation of the results, this morning, through the LSE website. I got it from the companies Windward (LON:WNWD) RNS notice of results. First one for me on this company. I hold.
I was impressed with the progress so far this year and what I saw and heard. the CEO seems straight and the CFO knew his figures. Looks like they could grow well, and the problems for shipping don’t look like they’re going away anytime soon. With everyone trying to cut costs and quickly, knowing all the data to achieve this, accurately and quickly must be of great help. Also Governments need to know what’s going on in their respective waters, so accurate data must be essential for security. Although they are trying to get more custom from the private sector.
They seem to want to always be improving the AI software and keeping their advantage and appeal to customers
Good luck,
Graham.
Hi Paul & Graham
Not sure this is possible but will ask.
I would find it helpful if you could maybe put a target price for the green / green amber shares or a PER that you think would make it fair value.
thanks for all your amazing work
Alex
I've always thought that target prices are a great idea but what's missing is the timing; when's that target price expected to be achieved. Without that they are meaningless.
All that can usefully be said is whether, knowing what's known, the shares appear to be over, under or fairly valued and that, I think, is reflected by the colour rating-scheme. And inevitably over time that'll change.
You can get a summary of analyst targets from sites like investing.com. There are so many ways to put a target and its so nebulous. More importantly, each investor needs to decide how they are going to know when to sell? A price target? A fundamental valuation? or keep them forever in a coffee can portfolio.
Yes I realize you can get broker forecasts I was just interested in Pauls and Grahams views as I value their opinions.
Problem is.....what you are requesting is technically far more complicated than you may have thought.
Share valuation is a relative game.
Markets are like a small harbour - all boats float higher as the tide rolls in, and many get stranded when the tide goes out, regardless of their individual merits.
Absolute price targets need constant refreshing as broader market levels change (including FX markets and bond yields), sometimes with breathtaking alacrity. A price target when the FTSE is 8000 is not the same as a price target when the market falls to 6000 and the risk free rate derived from the gilt market just halved.
And if you go for P/E ratios (or EV/EBITDA, or EV/Sales, or the fashionable ratio of the day) targets you double the problem. The E can move a lot as well as the P and you get some very counter-intuitive shifts.
Many asset management companies have tried to set up mechanisms for tracking their internal analyst's valuation opinions and then found the hamster wheel spins faster than their analysts can run.
In the end you always need something dynamic, not a static number someone holds you to 3 months later when the world has changed. Even then you really need to go sector specific and adjust for currency shifts.
It really does get very difficult, very quickly. If not done well the users (the portfolio managers) soon give up and ignore everything.
Hi Alex,
I don't think I'd want to put price targets against each share, as valuation is so tricky and subject to so many factors.
Although we do quite often work through our own valuation figures on particular shares, saying something like, I think a PER range of 12-15 is reasonable, which would give a valuation of xp to yp, which compares to the current market price of zp, therefore it looks reasonably priced/cheap/expensive.
But formalising that into price targets feels too rigid to me, and not something we should be doing. I think it's better we leave price targets to the brokers! Also, nobody knows what the future holds.
Thanks for your kind comments, appreciated!
Regards, Paul.
Off topic today but possibly of interest to investment trust investors. After reading an in depth analysis of Lindsell Train Investment Trust by Maynard Paton we've opened a starter position. I couldn't find it in discussions here but Paul and Graham might be familiar with Nick Train's investments. Basically it's had a very tough time but has plenty of quality assets. Observations welcome if anyone on here is well informed about this trust.
I like Lindsell Train Investment Trust (LON:LTI) as a long term, diversified global quality play, currently trading at a reasonable discount to NAV, I think it can provide a sensible spine to a portfolio. Although Nick Train has lost his halo of late with the disastrous collapse of Burberry (LON:BRBY) and the poor performance of Diageo (LON:DGE, I think there is value here if you believe in the longer term prospects of his quality first style in the manner of Terry Smith and Buffet. I'm not quite as convinced by his arguments around perpetual premiumisation (a narrative around consumers trading down could be equally persuasive I believe). Nonetheless I do believe that at these levels, and with a discount to NAV, this is a good time to get on board for long term exposure to a quality fund run by an honest, decent manager.
Someone noted recently here that Michael Lindsell has been regularly topping up so if it's good enough for him, then it's good enough for me.
£LTI remember with this one that the unlisted fund management company (Lindsell Train) makes up 30% of the portfolio. This is hard to value and has been performing poorly recently - no particular view either way but something to keep in mind.
Lindsell Train Investment Trust (LON:LTI) I think there is value here if you believe in the longer term prospects of his quality first style in the manner of Terry Smith and Buffet
While equally focused on well established businesses, I don’t see the same methodology here, or comparable moats. Terry Smith is all about the highest quality operating numbers across a wide range of industries with far more emphasis on the secular growth embodied in technology (Microsoft, Meta, Visa) and Health (Novo, Stryker, IDEXX) and Buffet is looking for toll booths (railways, Apple’s ecosystem - yes, he sold some after a stellar run, Moodys, Amex) and oil, lots of oil!! Meanwhile, LTI is stuffed full of staples, which make up half the top ten.
Discount or no discount, I would respect the chart.
LTI
I was an investor in LTI some years ago. It traded at an eye catching 75% premium in 218. It has some good quality stocks which have underperformed. Bear in mind that the recent (last year) high performers have been mainly cyclicals (banks and asset managers are up by 50%) rather than quality stocks.
Some shares are permanently at discounts and stay there despite good quality (Caledonia Trust is at 40% discount).
but some shares reverse discounts and may go premium. 3i was at a discount a year ago and now is at a premium of 40%. PHP was at premium of 40% now at a discount of 15%.
Which category the LTI will fall to ? In my view it is likely that the discount will narrow in due course and now may not be a bad time for a starter . plenty to ponder!
Take over bid for I3 Energy (LON:I3E) today at 10.43p. The share price is up to 12p.
Was just about to put (I hold) but I no longer do - the offer was too tempting! Wondering if Beeks Financial Cloud (LON:BKS) is still attractive given it’s up so much already (I do hold some already but fancy some more)
Anyway, morning all and thank you Paul for the stock reports and your fabulous Podcasts. Love hearing your take on things and laughed so much when you tried to disguise the beer can opening the other week by coughing
FWIW I keep on thinking of topping up Beeks Financial Cloud (LON:BKS) however, my position size keeps increasing, currently 13%. I'm on holiday in beautiful Llanelli (it's been raining everyday!) so having some time to go through my portfolio and look at position sizing amongst other things.
With regard to Beeks Financial Cloud (LON:BKS) what keeps me in, is the clear uptrend of getting contracts, which keep providing extra recurring revenue. The hard work has been done, it's now about getting real traction in the market place, which is happeneing and today's JSE announcement shows that once the tech is in, people like it and want more.
I expect the same to happen to NASDAQ, which as brokers say, will materially affect revenues. The one clear downside is if they fail to make the tech work, which haven proven it elsewhwere and also getting regulatory clearance seems slim.
I think given the cloud market, someone like AWS would happily pick it up - and knowing Amazon.com (NSQ:AMZN) at a decent price, and write the expenditure off....
Viz - don’t know if you or anybody else can clarify, but I am confused why NASDAQ has not been named in a BEEKS RNS, although NSDAQ itself has named BEEKS (so it is in the public arena!)? Many thanks to anybody who can explain..
Hi Graham,
" I am confused why NASDAQ has not been named in a BEEKS RNS, although NSDAQ itself has named BEEKS (so it is in the public arena!)? Many thanks to anybody who can explain.."
My understanding is that Beeks contract with NASDAQ contains a non-disclosure clause.
However, as you say, it's now in the public domain following publication online of a document re regulatory approval by NASDAQ itself. Although you could argue that probably not many people have read that document, but it's been in the public domain since 28 June.
Regards, Paul.
Bit late with this question, but if anyone reads this and can give me an answer it would be appreciated.
In my share transactions on several northern European stock exchanges there has been mention of Nasdaq as the apparent exchange owner, and checking on google this morning it appears that Nasdaq own at least seven such exchanges. Was there any indication in the announcement that the BKS work included these exchanges or just New York? If it included the nordic exchanges presumably it would make the contract substantially bigger, but extend the installation programme, if not, presumably there is a good chance that it will become a follow on contract.
I have absolutely no idea, but, if I were installing such a mission critical technology, I’d try it in one location only at the outset.
Yes BnB, that was my "most likely" conclusion too, which would presumably make follow on work, assuming the Nasdaq installation is a great success, 2025 work if the small nordic exchanges warrant such expenditure and/or if clients press for it. My impression over the years of investment there is that a greater proportion of trades are by institutions rather than private investors compared with UK /US.
"laughed so much when you tried to disguise the beer can opening the other week by coughing"
LOL yes I think a few people rumbled me on that!!! All good fun! ;-)
I learned that technique from my Granny, who used to violently cough when taking the post out of the clattering letterbox each morning, hoping not to wake us up with the loud clang it made as the spring snapped shut. Of course, Granny's coughing fit was a remarkably reliable alarm clock, which made far more noise than the postbox & woke up the whole household!
Another story, for another day, is when austere Aunty Mary, who was an absolute battle-axe, stuffed a pillow into the grandfather clock to stop it chiming on the hour, every hour, overnight, when she was visiting. That practically caused a diplomatic incident. I was only about 5, so didn't care or know.
BKS has I believe further to go. The Nasdaq contract could be pivotal for this share. I’m with Paul this is one of the most exciting shares on the market at present. If the contract with Nasdaq is successful it must surely lead to further contracts.
Graham had warned of a quiet year for Castings in May but it was a very disappointing TU today. As it is still Green on Stockopedia we added to our holding just after 8.00am and picked up a few shares at 299p, we will buy more once it settles. I look forward to Paul or Graham's observation if they get time to cover it.
Morning JASVFS,
Yes I'm sure either Graham or I will cover Castings in a bit more detail, we usually do that with profit warnings, and we like Castings on fundamentals too, so that motivates us to write about it.
Regards, Paul.
Interesting approach to investing. "Very disappointing" trading update so you pile into more at 8am without finding out the extent of the downgrade or whether the Stocko team is maintaining its positive view. Now that's what I call unshakeable faith in your decision making!
H & T (LON:HAT) H1 webinar today 12 noon. Join here. Grey Investor has covered below but I can't delete this message to reply to his.
H & T , Ransdens
Lots of followers on here and always look good .
My only issue is based on my walk to work where I pass by both stores in the centre of Sheffield .
Just not something I could own . They are well just a bit crap .
If I am a part owner of a business I cant own those two businesses .
At least clean the windows .
Books and covers planetX, to paraphrase the well know saying.
Of the two Ramsdens Holdings (LON:RFX) is my pick for a variety of reasons, diversity of revenue streams, CEO skin in the game, cash positive (unlike H & T (LON:HAT) and of course the recent trading update which was ahead of expectations.
As Graham anecdotally remarked Ramsdens has a much more positive vibe about it, more glass half full versus H & T (LON:HAT)
I have a modest holding.
I bought H & T (LON:HAT) after Graham's report, for four reasons
We hold Ramsdens planetx, I was taking part in an event in Derby last year and noticed their outlet there. I didn't need to pawn my watch but went inside out of interest. The staff were handling the queue professionally and inside and outside were clean, including the windows. To me they looked a far cry from the dingy pawn shops many years ago. I agree about the windows but disagree about the two business being a bit of crap. I hope they've cleaned the windows next time you walk past.
No half year TU from Eurocell (LON:ECEL) yet but they had one in July last year. Have I missed any narrative as to why they haven't issued one? Thanks
It does make you wonder if Eurocell (LON:ECEL) are going to put out a profit warning. The demand for doors and windows must have reduced with the reduction in newbuilds. Presumably it will be all about the outlook. They issued a trading update on July 25, 2023/July 13, 2022/July 20, 2021/July 8, 2020. According to Stocko, their earnings release will be on Sunday, 1st September...(Eurocell's site has September 4, which is more believable)
Agreed it does make you wonder. However, many directors were buying Eurocell (LON:ECEL) shares throughout May, and did again on August 6th, maybe indicating they are not heading for a profit warning.
I hold Eurocell (LON:ECEL) but worth noting they were only purchases through the share purchase plan. I guess what was more telling was the increase in the buybacks at the AGM update.
I have received a reply from Eurocell (LON:ECEL) stating HY results will be 4th Sep and that the board preferred to drop the July TU due to being so close to the AGM update and the HY results.
Thanks for sharing that on Eurocell (LON:ECEL) Newtarrow. I think this more likely reflects changes at Board level - and not understanding, or caring slightly, less about Investor Relations with Retail Investors. Perhaps a function of having been listed a little longer now too? They have got comfortable..... and a little less attentive to shareholders and more inwardly focussed
Interims out of H & T (LON:HAT) today, I hold.
EPS +8.6%. Interim divi +7.7% at 7p. This is the post acquisition benchmark that matters.
Financing costs have jumped a fair bit. Post tax profit up 9% v Pre tax + 12.5%. Flattered by an acquisition.
Net assets 416p v 386p +7.7%.
My reading is that short term growth has slowed. The overall business seems sound. I rate this as a Hold. The half year EPS is up but there is a fair way to go to achieve full year expectations. However the same was true of last year.
The company is changing it's year end, which is a pain. I never fully see the point of such changes.
The acquisition is going OK, so far, which is a relief because it seemed very expensive. It remains to be seen if it represents good value for money.
Other comments appreciated. I also hold Ramsdens Holdings (LON:RFX) . A smaller holding.
My morning smallcap tweet: The Merchant of Venom
Sosandar (LON:SOS) Kooth (LON:KOO) Light Science Technologies Holdings (LON:LST) Sabien Technology (LON:SNT) OptiBiotix Health (LON:OPTI) Beeks Financial Cloud (LON:BKS) Renalytix (LON:RENX) Castings (LON:CGS) H & T (LON:HAT) Empresaria (LON:EMR) MobilityOne (LON:MBO), Tribal (LON:TRB), Windward (LON:WNWD), Anexo (LON:ANX), Zoo Digital (LON:ZOO)
◄Sosandar (SOS)► signs lease for its third store. Are we going to have an RNS for every shop lease and opening? [SP=9 Cap=22m]
◄Kooth (KOO)► begins delivery of its services as part of its initial one-year partnership with Aetna Better Health of Illinois. This is Kooth's first private sector engagement. [SP=312 Cap=113m]
◄Light Science Technologies (LST)► Contract Electronics Manufacturing division has received a third order from its customer in the sports entertainment segment, worth £134k. This is a sign of 'strong trading' seemingly. [SP=3 Cap=10m]
◄Sabien Technology (SNT)► gets funding facilities from exec Chmn. Tides it over for 12 months without the need for a placing, based on current sales forecasts. Two directors and co's broker to take shares in lieu of payment, at 9.175p/sh, a slight discount. [SP=9.75 Cap=2m]
◄OptiBiotix Health (OPTI)► commercial update. It certainly reads like a commercial. Good progress in H1 on aims of securing a number of commercial agreements and direct to consumer sales. And something about tomato soup. [SP=24.8 Cap=24m]
◄Beeks Financial Cloud (BKS)► significant extension of Johannesburg Stock Exchange contract. No £££. [SP=252.84 Cap=168m]
◄Renalytix (RENX)► formal sale process terminated since there is no realistic prospect of an offer in the near term. Advanced discussions with key stakeholders for funding and a 'refreshed business plan'. Has cash till Q4 2023. [SP=14 Cap=33m]
◄Castings (CGS)► warns at AGM that FY-Mar25 will be below market expectations. "Demand has remained at lower levels and our customers have now indicated that there is unlikely to be any improvement before at least early 2025." Surely it should not have waited till the AGM to inform holders. [SP=348 Cap=151m]
◄H&T (HAT)► H1-June EPS 17.7p up 9%. Long outlook stmt is positive but no summary. Loan me a frickin' bone here. [edit] Shore Cap cuts f/c: "To reflect the impact of this increased seasonality, we have reduced our adjusted EPS estimates for FY24F, FY25F and FY26F by 11%, 13% and 12% respectively." [SP=419.57 Cap=185m]. I hold.
◄Empresaria (EMR)► H1-June. Guides FY only broadly in line with market expectations. [SP=38 Cap=19m]
◄MobilityOne (MBO)► FY-Dec out at last. Unsuspended. Outlook - "a challenging business environment and remains cautious about the outlook for the remainder of 2024". [SP=2.7 Cap=3m]
In line: TRB, WNWD, ANX, ZOO
Investors pile back into equities after early-August sell-off
Deutsche bank data shows rapid recovery in confidence as markets bet on ‘Goldilocks’ scenario for US economy
https://archive.ph/TEj3v
Not to be trusted imo - exactly what they would say at potential market "tops" or close too. Not what I want, but my opinion.
The top is reached when confidence is high and all sellers have sold and all buyers have bought. Impossible to say if we are at the top but it is possible.
Definitely agree with points 1 and 3, but the fast moves down come when there are still sellers out there, but no buyers to soak up ?
I get your point, dont want to to be nit picky but this is the point just after the top, because there are now sellers. As you say when the sellers find few buyers panic sets in and prices slump.
Market goes up by the stairs and comes down in the lift. Or sometimes by jumping out of a tenth floor window.
Accumulation, participation, distribution. .............According to Dow Theory, the primary trend passes through three phases: the accumulation phase, the public participation phase and the distribution phase.
This discussion sounds like nervousness. For our own VIX indicator, how much is everyone in cash? I'm 5.3%.
FREng
I generally stay 100% invested as experience has shown me it's impossible to time the market - that said, I am now 15% cash (high for me) as I sold a couple of things that were starting to look fully priced and wasn't able to find anything else to re-invest in (again unusual for me as I can normally uncover a bargain or two). Quite happy with this positioning as Sep/Oct are often volatile months and feel this year could be choppy ahead of the US election.
Agreed Bouden54... currently 6% cash, which is a lot for me ... but like you, I'm struggling to find exciting opportunities after the run up that we have had this year ....I'm maybe being too unrealistic... after all, if you've taken profit on a couple of things, you can't expect to be finding inspiring ideas at 52 week lows... or resting on the 200 day m.a. at the bottom of upward sloping channels :) ... if anyone has any potential candidates for further research, I would be most grateful ... not sleeping well with cash sitting uninvested when the economy is positioned well...
Cancun
I’m only 2.55% cash in our ISAs but still nervous. A few holdings are precious metals and miner ETFs which have done well and give some feeling of ‘security’ for bad times (perhaps). FWIW my watchlist includes Mears (LON:MER), Alpha International (LON:ALPH), PayPoint (LON:PAY) and ME International (LON:MEGP) though not fully researched as yet.