Small Cap Value Report (Tue 20 Dec 2022) - GDWN, XPD, NANO

Good morning! It's Roland here with today's report, I'm picking up the reins from Graham. Today's report is now finished (11.00).
In the last few days before Christmas, company announcements are thinning out as the City prepares to take some time off! However, there are a handful of stories in our small-cap universe that merit a look.
Agenda
Roland's Section:
Goodwin (LON:GDWN)(£246m) - today's half-year results from this family-controlled British engineering group impress me. The order book is significantly increased and profitability has also improved. Although this is too illiquid for traders, I think Goodwin is a class act, and could be attractive as a long-term compounder.
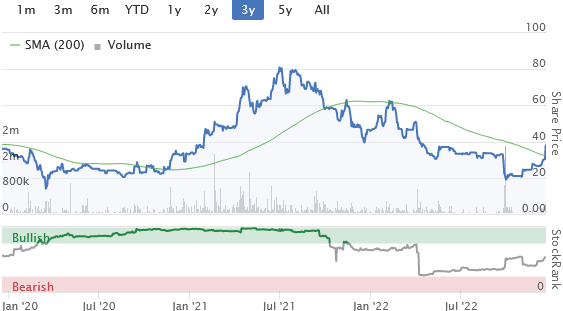
Xpediator (LON:XPD) (£53m)(+25% ) [no section below] - this fast-growing logistics group has received a possible offer of 42p per share from a private-equity consortium led by the firm's former chief executive, Stephen Blyth.
Mr Blyth remains the largest shareholder through his vehicle Cogels Investments, which I believe has a 26% stake. No firm proposal has been made yet, but this looks opportunistic to me after the stock's recent sell off -- XPD traded over 60p earlier this year and hit 80p in 2021.
The latest trading update was positive and confirmed full-year guidance. The shares still don't look expensive to me, so I would be minded to continue holding here if I was invested.
Nanoco (LON:NANO) (£128m)(-1%) [no section below] - AGM statement from this nanomaterials specialist. Financial performance during the four months since August is said to have been "comfortably in line with the Board's expectations".
Nanoco says it is continuing to deliver R&D services under a number of contracted programmes with customers in the sensing market. Management has "a high level of confidence" that the firm will receive production orders in calendar 2023, based on visibility of customer validation plans.
An ongoing patent infringement case against Samsung is also noted as a possible source of "potentially significant shareholder value".
However, for now Nanoco remains in the jam tomorrow camp, as far as I can see. Consensus forecasts show full-year revenue of just £2.9m, with a £3m loss. Although the firm appears to have enough cash to operate for the coming year, I wouldn't bet against a further fundraise here. Nanoco is too speculative to be of interest to me.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Roland's section:
Goodwin (LON:GDWN)
Share price: 3,150p (10am)
Market cap: £246m
Shares in this 139-year-old family-controlled engineering group have 30-bagged over the last 20 years. Today’s results look very positive to me, and suggest to me that Goodwin’s long-term growth trend may have further to run.

Goodwin’s operations are divided into two divisions:
- Mechanical Engineering (47% of H1 profit): produces mechanical and electronic components and complete systems for industries including defence, mining and energy (including nuclear). Examples include air-traffic control radar and components for naval and military aviation programmes.
- Refractory Engineering (53% of H1 profit): produces mineral-based products to sectors including mining, construction, and jewellery. Examples include products such as vermiculite, silica sands, jewellery casting plasters and moulding rubbers.
Profit margins are notably higher in the refractory division (~16%) than the mechanical business (~9%).
Commentary on recent trading and order intake is very positive:
“I am pleased to report that at the time of writing the workload has increased to £242 million (2021: £157 million). This increase relates to the materialisation of some of the major projects that the Mechanical Engineering Division has been pursuing within the military and nuclear waste re-processing markets.”
Chairman Timothy Goodwin notes that Goodwin has been moving away from oil and gas into business streams that are more likely to avoid the effects of a global recession he thinks is “almost certainly going to feature over the next two years”.
Financial highlights: Today’s numbers show a healthy performance during the six months to 31 October.
- Revenue +18.8% to £89.3m
- Trading profit +17.9% to £9.1m
- Trading profit margin: 10.2%
- Pre-tax profit +58.4% to £12.2m
- Earnings per share + 58% to 113.9p
Trading profit represents operating profit excluding unrealised derivative gains, so it's a realistic measure of operating profitability.
The company’s reported pre-tax profit for the period was distorted by an unrealised £3.1m fair value gain on an interest rate swap. This derivative caps the group’s interest rate at 1% on the first £30m of debt and extends to August 2031. I’m not sure when the swap was taken out, but it’s clearly likely to pay off handsomely for Goodwin.
Net debt rose by £11.3m to £46.1m during the period and free cash flow was negative. This is due to ongoing investment in increased inventories and CO2 emission projects, such as solar panels. Based on current electricity prices, the payback period for a recent solar panel project is expected to be just two years – a good investment.
I don't see have any concerns about Goodwin's debt levels or balance sheet.
Inventories/working capital: inventories have risen by £6m to £43.3m over the last 12 months, which I estimate is equivalent to around three months’ supply. The company says this investment has “significantly aided the Group’s ability to meet [customer] demand”.
Outlook: although macroeconomic risks are a concern, the company says that "activity and profitability levels are expected to increase over the next twelve months as a result of the increased workload."
Goodwin doesn't appear to pay for broker forecasts and the firm hasn't provided any guidance on the timeline for delivery of its increased order book.
However, past years have seen a fairly even split between H1 and H2 profits. Assuming this remains the case, I think it's reasonable to expect the 18% increase in H1 profits to be extended to the full-year result.
My view: I’ve not spent a lot of time looking at Goodwin before, but I can see plenty to like here. This appears to be a good, well-run business, operating in some attractive niches.
The current valuation does not look unreasonable to me:

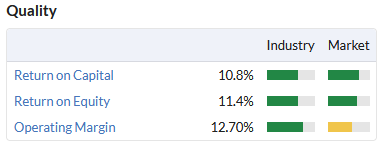
Quality metrics are fairly good for a capital-intensive manufacturer, too:
Liquidity is limited, with a free float of just 33% and an indicated spread of 5%.
However, for investors looking for businesses with the ability to deliver long-term compound growth, I think Goodwin could be worth further investigation.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

22 comments
Interesting suspension of Trackwise Designs (LON:TWD) by LSE. Wondering how that will pan out for short sellers who can't actually settle stock? Hope they get burnt.
Not a very generous point of view. It's not their fault that the company is doing poorly.
Serica Energy (LON:SQZ) update....
Obviously the market doesn't like this today. The private investors esp. The headline price looks high relative to Serica Energy (LON:SQZ) on a reserves basis. Chatroom comments focus heavily on this. Gas prices are high and my buy some Serica Energy (LON:SQZ) for a trade for a couple of months over the winter where unhedged production should see upgrades and a buyback... has been kiboshed. I understand why some would say well that didn't work and move on.
However, I think its worth bearing in mind that Mercuria will retain a 25.2% holding, £270m. Could be tax reasons why they wanted equity... and not more cash... but still, its a lot of money to be tied up in an entity you have just dumped dodgy assets into. In fact no-one saying the assets are bad...just expensive. The thing is, the company can't really say, so no-one knows with certainty what they have paid. There are substantial tax losses in Tailwind to confuse the hell out of us. BUT maybe those with most confidence, Mercuria, have hinted what they think. So production returns could well improve.... obviously I don't know...
If you value the tax assets at 10p and deduct from consideration of $780m - $240 / 42 = price per 2P reserve = $12.8 .... doesn't sound horrific. To all those who seriously love gas ill just say you couldn't give it away two years ago. So things can change quickly....
They have used about £336m of their cash pile... £277m net debt plus £59m consideration. This should leave £85m ...so balance sheet remains healthy.
Net net Im going to stick with the idea. Serica Energy (LON:SQZ) will continue generating lots of cash over the winter and next year. More info will come out re the tax losses. I think the institutions will come round but as the story has now changed.... it could take a month or so to reorganise the register. 12 months ago before the gas price roofed it... everyone was desperate for them to do a deal like this. Now it looks dilutive because the market does not put much value on future gas production. The market also discounts cash. I think the rating will improve on Serica Energy (LON:SQZ) as Mercuria and their message gets out there.
Actually I think the calendar year end net cash balance will be over £200m (not £85m) if you read the presentation.
Mercuria have history of retaining equity stakes. They wouldn't do it if they thought they were getting something overvalued, they are smart. Certainly a direct relationship with them will help Serica Energy (LON:SQZ) too in hedging and trading.
Diversification to a 50/50 split of gas to oil seems sensible to me. As I understand it the tax assets can only be applied to the entity not the enlarged group (but I could be wrong). Nonetheless given how cash generative Tailwind is and the current UK tax regime the $2bn+ should be worth a lot to the financial metrics of the deal, certainly more than 10p in the £.
Not sure why the private investors took such a disliking to it, other than they all seem to want buybacks. Often buybacks don't actually work to push the share price up but pi's seem to overlook this in their clamour. Dividend is maintained so no major change there.
Not a Nanoco (LON:NANO) expert but the sp revolves around an IP dispute with Samsung re use of their more environmental 'microdots' (?) in Samsung TVs. The two companies had a research collaboration in the earlier 2010s and then Samsung broke away c.2015/16. A few years later Nanoco took Samsung to court. The dispute is being heard in Texas in Jan 2023 and will be resolved over the course of the trial. Nanoco are suing over c.$250m US revenues. They could take the case elsewhere too (they've got off balance sheet legal funding). Some pre hearing papers seem to support the Nanoco case -> I think that is why this low revenue company has a high price. Compensation could extend to an ongoing cut of related Samsung revenues - sweet.
I can't call the case nor any compensation. My guess is that its a lot in the price. An ongoing payment from Samsung could push sp up quite a bit higher.
For me this is only investable after the legal event.
From memory, the (company sponsored) broker note suggested c.$400m if found in NANO favour for the US, which if the judge decides is wilful (given their past relationship it's hard to see how not) this can be multiplied up to 3*
Separate proceedings have also commenced in Germany, so if USA is successful this could lead to an injunction on sales (which is why Germany was chosen second) which I suspect would force Samsung to the negotiating table. If not, they will continue to roll out the case to other jurisdictions.
Results so far e.g. PTAB have all gone in favour of NANO so plenty of reason to be optimistic, but as ever there are no guarantees!
Sorry, just double checked and broker indicated $200-300m range not the $400m I stated above
Hi would you happen to know by any chance if the figure of $200-$300 mil includes the maximum 3 x willful multiplier ?
Regards Andy
No, that multiplier is applied to the award & will be decided by the judge (Gilstrap).
The trial begins on the 6th January (assuming no delay) and verdict expected on either the 12th or 13th Jan
i was wondering who was going to cover when I saw Pauls twitter postings around 5am. Love the energy :-)
Yes, I'm sorry about that. My usual routine was overcome by an urge to sample the Christmas products procured from Majestic Wines yesterday afternoon, and express myself at great length on Twitter (it's good to be back, Elon has granted me an amnesty).
Thanks to Roland for holding the fort this morning.
We're lucky that, this time of year, there's usually little of interest in the announcements. I've reviewed the RNS for results/trading updates, and the top % risers/fallers, and can't see anything additional to what Roland's already covered, so guilt is receding at this end.
Best wishes, Paul.
What? Not even a review of the various wines? ;-)
Let Trustpilot (LON:TRST) do the reviewing with respect. Whilst energy/defence/shipping even are 'hot' wine is to be savoured in better times.
Its what makes you unique, never apologize for being you. No one should do that
Hi Paul,
Delighted your enjoying your run up to Christmas.
Maybe worth a look at Velocity #VEL after its $100m 5 year composite kit order from GKN in the US. They have stumbled a number of times, both operationally and then covid meant they had to scale back their operations & costs as aircraft build numbers fell.
This deal is to set up a local operation to GKN, so reducing deliver time/expense whilst benefitting presumably from skilled labour in the area, with VEL becoming their exclusive supplier of composite for a plane(s) which they are commissioned to build (presmably), reading between the lines. VEL have made c.25% GP on this business historically.
Wouldn't be surprised to see a equity raise shortly, but pre-announcement they were only valued at c.£10m with alittle net cash.
Broker is now looking for £1.5m PAT or 3.8p EPS, for Oct 2024 after a heavy £1.1m depreciation charge, whilst Operating Cashflow is actually forecast to be £3.5m, much more healthy. Y/E October 2024 being first full year of the contract.
Based on past it still is a risky stock, but could easy trade nearer £1 + if it executes successfully. Certainly could be sitting at twice yesterdays SP today on this contract.
did you get resuspended already, Paul? Or have you got a new handle? The @paulypilot one says account suspended.
@sco15375772
Merry Xmas vegpatch. I haven't seen you around for years!
£BMS buying a US broker of tanker vessels for an initial $7.25mn.
Southport Maritime specialises in brokering fuel tankers in the North American, Caribbean and Latin American markets. It employs 18 staff and made a pre-tax profit of $1.1mn last year. It has gross assets of around $6.4mn.
Just don't know enough about shipping. Ardmore Shipping Co (NYSE) looks very good. Clarkson, Taylor, Braemer, Ocean Wilson all on watch.
Stuff needs to go from A to B and currently fuel is hot.
Posted to yesterday in error - apologies.
21 minutes ago
Serica Energy (LON:SQZ) substantial acquisition announced this morning. Not such an easy deal to get your head round.... so chatroom / twitter crowds jumping to their own conclusions. They don't like North Sea due to UK tax position and don't like the deal because of debt and dilution. However there are substantial tax losses that may well make the deal look attractive and Serica Energy (LON:SQZ) can absorb the acquired debt pretty easily. A very broad fag packet looks to be doubling reserves into oil for 30% dilution so it needs to be a terrible deal for the market to not like it..... what could be wrong? Contingencies in the detail around the deal, decommissioning liabilities , drilling commitments etc etc.... flowback on the issued equity ( 28.9% BUT Mercuria to become a 25.2% strategic investor in Serica - so not substantial).
Most obvious negative is it postpones a buyback....and market loves the instant gratification of those. Confusion just before Christmas never good but the meeting at nine should clear up a lot of that. I think you have to trust management.... having said that initial reaction suggests market thinks the deal is dilutive. That would be most annoying ....fingers crossed management do a good job on the call.