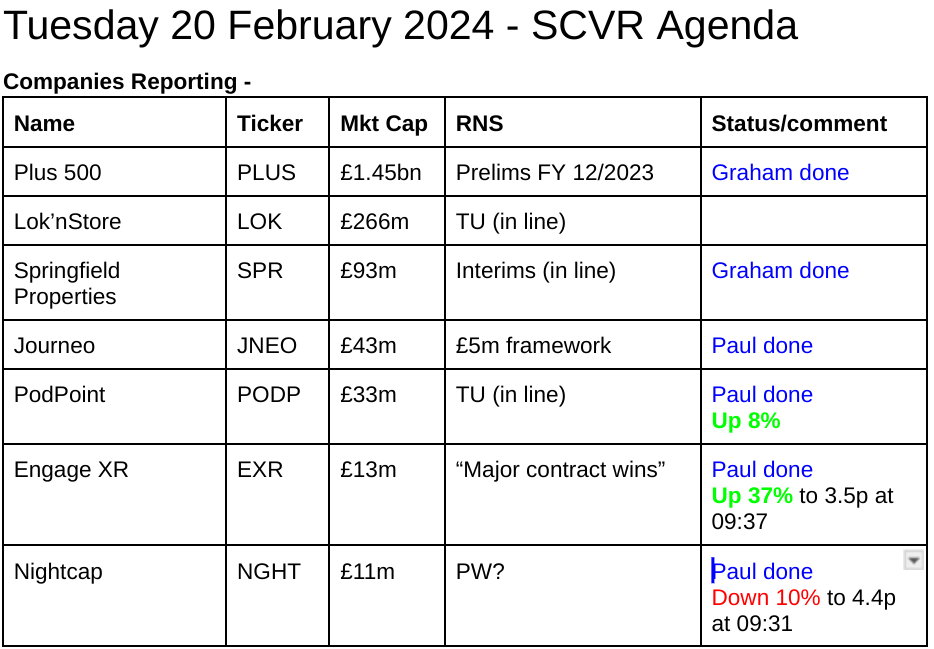
Small Cap Value Report (Tue 20 Feb 2024) - JNEO, NGHT, SPR, EXR, PLUS, PODP

Good morning from Paul & Graham!
Live Masterclass - is tomorrow (Weds) from 18:00 - full details here. The series on finding multibaggers was absolutely brilliant, and I'm sure this latest one will be too - the subject being:
Forensic stock analysis masterclass: How to get the most out of the StockReports in 2024.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. OR it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom),
Paul's 2023 share ideas, with live prices.
New SCVR summary spreadsheet from July 2023 to date, updated at weekends (very useful quick reference tool, search for ticker using CTRL+F). Hover over cell for pop-up notes.
Frozen SCVR summary spreadsheet for calendar 2023.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Quiet again -
Other mid-morning movers (with news) -
Mobico (LON:MCG) - down 11% to 74.9p - audited results for FY 12/2023 are now delayed by up to a month, due to audit problems. Onerous contract in Germany requires additional provision of £40-70m. Guidance unchanged though -
The Board continues to expect Adjusted1 EBIT for FY 2023 to be within the range of £175m-£185m, as provided in the Q3 trading update on 12 October 2023. Covenant gearing is anticipated to be broadly in line with the half-year position and with significant headroom.
Revolution Beauty (LON:REVB) - down 6% to 26.3p (£mkt cap) - changes its auditor. BDO “resigned by mutual agreement”, and MHA appointed. The year end is in 8 days’ time, so this is not a typical time to be changing auditors! Has there been a falling out I wonder? BDO confirms nothing required to be brought to the attention of shareholders, which is standard.
Summaries
Journeo (LON:JNEO) - 262p (£43m) - £5m Framework Agreement - Paul - GREEN
A pleasing contract win, although it's spread over 4 years, and is already baked into existing forecasts, so reassuring rather than exciting. I remain positive on this share overall, which has been transformed by new management and acquisitions. Still reasonably-priced too.
Nightcap (LON:NGHT) - 4.9p (pre-market) £11m - Acquisition, Trading update, and fundraise - Paul - RED
Presented in reverse order, this is actually most importantly a nasty profit warning - current trading is "far softer" than expected. It raises £1m from existing shareholders at 6p, and makes a small acquisition from the administrator in a pre-pack deal. I suspect equity might end up being worth nothing, for this struggling chain of unremarkable bars.
Springfield Properties (LON:SPR) - down 5% to 74.3p (£88m) - Interim Results - Graham - GREEN
These interim results are poor but full-year expectations are unchanged. Net debt should reduce quickly as working capital unwinds and as proceeds are received from land sales. This housebuilder is not without risk but the odds may be favourable with a TNAV of £145m.
ENGAGE XR Holdings (LON:EXR) - up 37% to 3.5p (£18m) - Major Contract Wins - Paul - AMBER/RED
A £1m+ contract win in the M.East sounds impressive. Plus a smaller existing contract is extended. However, the reality is that EXR is small, heavily loss-making & cash-burning, so the shares are a long shot. That said, I do see speculative potential here, that £1m contract is attention-grabbing.
Plus500 (LON:PLUS) - up 2% to £18.63 (£1.48 billion) - Preliminary Results - Graham - GREEN
Today’s full-year results are ahead of prior expectations but in line with January’s trading update. The cash balance ($900m+) is remarkable and allows a further $175m to be directed towards dividends and buybacks. I am positive on all stocks in this sector.
Pod Point group (LON:PODP) - up 8% to 23.4p (£36m) - Trading Update [in line] & Board changes - Paul - RED
Horrendous losses continue, and another big loss is forecast for 2024 too. So in line with terrible expectations. The cash pile is forecast to almost completely disappear, so does it matter if shares are now priced below net cash? New CEO appointed, let's hope she can make radical changes needed to create a viable business out of the existing mess.
Paul’s Section:
Journeo (LON:JNEO)
262p pre-market (£43m) - £5m Framework Agreement - Paul - GREEN
I’ll start with this company, as it’s fresh in my mind from reviewing it here -
28/11/2023 - GREEN - 216p - ahead exps TU.
12/2/2024 - GREEN - 249p - in line TU FY 12/2023. Vague but positive-sounding outlook.
We were rather late to the party here at the SCVR, only picking up quite slowly on the transformational acquisitions and performance of this transport-related tech products/services group.
Today’s news is that it’s won a significant sized £5m contract -
Journeo plc (AIM: JNEO), a leading provider of information systems and technical services to transport operators and local authorities is pleased to announce the award of a new Framework Agreement ("Agreement") with a Northern Transport Partnership ("Partnership"), following a competitive tender process.
Revenue will be recognised through to Jan 2028, so about 4 years.
Revenue for FY 12/2024 is forecast at c.£48m, so this deal isn’t particularly material to revenues, if we assume maybe £1-2m might be recognised this year, out of the £5m total? It depends on the phasing of the supply of goods and services though, which we’re not told.
Ahead of expectations? No, because this deal was within the expected pipeline, but it does improve visibility.
CEO comments are upbeat -
Russ Singleton, Chief Executive of Journeo plc, commented: "We are delighted to continue this relationship with the Partnership, installing our latest technology to enhance the passenger travel experience. This latest agreement follows a highly successful year in 2023 of contract awards and purchase orders which together have built a strong order book. With each new contract we are demonstrating our innovative approach and technical expertise, which in turn is creating new opportunities and building momentum in the business."
Paul’s opinion - a pleasing contract win, but I don’t see this announcement on its own moving the price much (writing this at 07:54).
My main reservation with JNEO is whether it can keep the contracts rolling in, or whether it’s just enjoying a flurry of big, one-off contracts. So each contract win announcement reassures on that point.
Shares look priced reasonably, on 11.4x forward EPS forecast. I probably wouldn’t want to chase the price much higher than that though.
Overall, I remain positive on JNEO shares, so am happy to stick with GREEN.
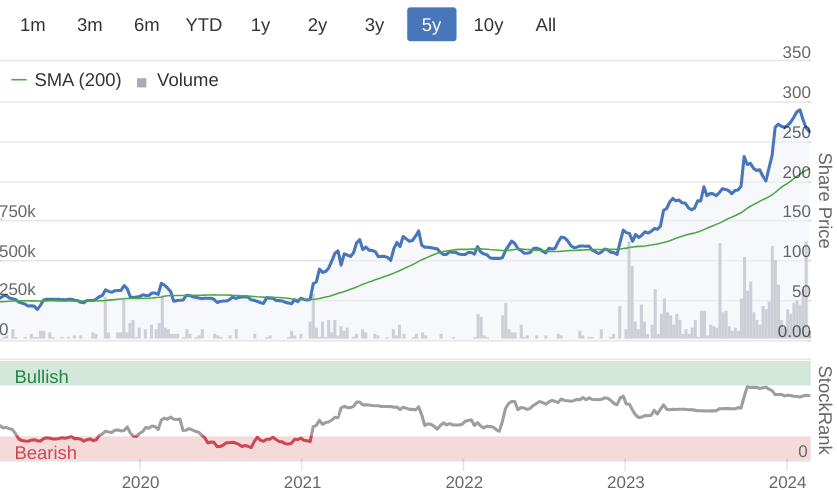
Things started to dramatically improve from 2021 - all the more impressive, since this 5-bagger has happened in a nasty bear market for small caps - well done to subscribers who spotted the opportunity much earlier than we did! -
Nightcap (LON:NGHT)
4.9p (pre-market) £11m - Acquisition, Trading update, and fundraise - Paul - RED
I’ve renamed the announcement today, which is actually titled “Acquisition of The Piano Works and other matters”
Piano Works - acquisition is costing £200k (being paid piecemeal in monthly instalments), buying its assets in a pre-pack administration. Which does raise questions about the quality of the business, as with NGHT’s other formats too. It traded at breakeven for FY 6/2023, we are told. My thinking is that if they’ve already gone bust, there’s a good chance they might not be very good businesses, even after a restructure. Although the commentary today says it was forced into administration due to an onerous lease in Soho. The format is to be rolled out to more sites, and sounds quite interesting - live music with audience participation, I might have to mystery shop it!
As a group, NGHT has so far failed to demonstrate any consistent profits. Although it has been through a nightmare trading environment in recent years, in common with the whole sector, so it’s difficult to judge what the steady state level of profits (if any) would be. There are further big hikes in staff wages coming in April 2024, as a further blow to this sector where wages typically make up 30-35% of revenues, up to half gross profit. It’s very difficult to make any profit at all from bars. Even the large chains, with their greater buying power, are only managing slim profit margins at present. Could a recovery in the economy gradually improve things though? Who knows!?
I did a review of NGHT here on 11 Jan 2024, and came away unimpressed, AMBER/RED. Problems being that it’s loss-making, has too much debt, and management pay is excessive.
Equity fundraising - is with existing shareholders, and is at a premium price, 6p (last night’s close was 4.9p), to raise £1m - which looks a good deal. It says this is to fund the Piano Works acquisition, but it clearly isn’t - it’s to fund the precarious state of the group overall, which is obviously strapped for cash.
Convertible loans - terms are amended, to extend maturity from Sept 2025 to Sept 2026, and lower the minimum conversion price from 12p to 10p. I think that seems fair.
Trading update - it’s a profit warning - and it sounds bad, “far softer” trading -
Following positive Christmas trading, as announced on 10 January 2024, the Group's trading since the start of 2024 has been far softer than the Board expected, in line with reports from across the hospitality sector.
It confirms that an important lease is terminating shortly, which is something that I believe was first revealed via a whistleblower by Tom Winnifrith.
New guidance -
As a result of the above factors and their impact on the second half of FY 2024 in particular, the Board expects that, whilst revenues for FY 2024 will be in line with expectations, adjusted EBITDA* is expected to be in the range of £2.0 million to £2.5 million.
* IAS 17 Earnings before interest, tax, depreciation, amortisation, share based payments, exceptional items, acquisition related transaction costs and pre-opening costs.
The only note I can find is an old one (June 2023) from Allenby, which forecast £5.1m IAS 17 adj EBITDA. So the new guidance of £2.0m to £2.5m looks a large drop.
The £5.1m old EBITDA forecast turned into a loss before tax of £(336)k. So the new guidance implies this will probably have ballooned to a LBT of something like £(3)m or worse.
Paul’s opinion - I didn’t like this share to start with, and it strikes me that the new guidance means NGHT is now heavily loss-making.
Therefore I’m shifting down from amber/red, to RED.
With too much debt, greedy overpaid management, and now heavily loss-making I think, the future looks very grim for equity, which I suspect might end up being worth nothing.
Hence I’ll be steering clear of this share at any price, because I think it’s worth zero. Sector read-across for other struggling bars eg. Revolution Bars (LON:RBG) also looks grim, so I'm resisting the urge to bottom fish with either of these shares, as the risk of things ending badly is now looking quite elevated. I note that the remnants of the old Luminar nightclubs business recently went into administration again, for the umpteenth time.
ENGAGE XR Holdings (LON:EXR)
Up 37% to 3.5p (£18m) - Major Contract Wins - Paul - AMBER/RED
This Irish company is involved in virtual reality, or metaverse. It floated on AIM in Mar 2018, so the story is getting a bit stale by now I think.
As you can see in the graphs below, the solid (actuals) blue blobs show a rising revenues trend, but at a cost of substantial, and worsening losses - which does make me wonder if they’re buying in revenues by offering deals at below cost? That’s what the figures are suggesting -

In the absence of any facts/figures showing that this is a viable business, we’ve been consistently negative, RED, on this share. Remember that nobody pays us to give a distorted positive view on any company, unlike the army of PR people out there, this is independent, and brutally honest analysis here.
Checking my previous notes, I was unimpressed with weak H1 results on 11/9/2023, but noted it had good cash reserves to continue trading for maybe another 18-24 months from then.
Then on 19/12/2023, EXR issued a bad profit warning, saying contract delays had caused large slippage of revenues, now falling way below forecast.
Looking at it with fresh eyes today, I’m intrigued by the share price being up 37%, although that’s only a 1p rise to 3.5p.
Major contract win - said to be in 7-figures, so probably just over £1m I’m guessing.
The client is an (unnamed) large Middle Eastern company, in education & training, and the contract is partnered with accountants PWC.
Contract extension - said to be in 6-figures, this is with a US bank that’s an existing customer. I’m encouraged that an existing customer wants to extend the project, which implies they’re probably happy with the services provided to date.
Outlook - nothing specific, but generally positive-sounding comments today -
As previously announced, the last financial year was impacted by delays in signing some contracts and therefore some revenues the Group had hoped to be recognised in FY23 will now be recognised in FY24. The Group's sales pipeline continues to grow, and the Group continues to see strong demand in the education, training and development verticals…
… we expect education, training and development to be the primary driver of revenue this year.
Our understanding of the needs of customers in these areas has accelerated during 2023, and we are better placed to target and win more business as a result. We are also pleased that our pipeline is beginning to convert again, after customers delayed signing contracts in the second half of last year.
We believe 2024 will see growing interest in spatial computing / metaverse services as Apple releases its Vision Pro headset in February and new devices are expected to be released from Sony, Samsung, Google, and Meta later this year. Overall we are excited at the opportunity before us and believe that the Group is well placed to take advantage of the increasing interest in spatial computing and the metaverse."
Cash - nothing is said about the current cash position, but I suppose this is a contract win announcement, not a full trading update.
Paul’s opinion - I’ve been rather dismissive of EXR in the past, because the figures were so bad. It’s not possible to value this share accurately, since it’s a heavily loss-making, cash-burning jam tomorrow share.
Cavendish withdrew forecasts after the Dec 2023 profit warning, so ignore the outdated forecasts shown on the StockReport (I’ve just green blobbed the office, asking for these outdated figures to be removed).
However, today’s contract news, particularly the 7-figure M.East deal impresses me considerably. This is clearly telling me that the product must be desirable to a big customer. It also shows the company has international reach.
Where we’re in the dark, is whether this can all be turned into a profitable company before the cash runs out?
Is £18m an attractive valuation for what can only really be a complete punt at this stage? For me personally, I’d say no, it’s not cheap enough to give me attractive risk:reward. For me, I want the potential of a 5-bagger, to get me to take the risk of losing maybe half my money in 6-12 months if things don't go to plan. But I am intrigued by the possibilities. I suspect it’s likely to burn through the existing cash, and need another fundraise in late 2024 or 2025. Cash burning micro caps always say they have enough cash to reach breakeven, but that’s hardly ever true in reality. I’ve seen numerous jam tomorrow companies tell us that they don’t need another fundraise, then go on to do multiple additional fundraises!
Overall, I’ll shift up from red to AMBER/RED, to reflect that this share is a long shot, but there does seem to be potential here maybe?
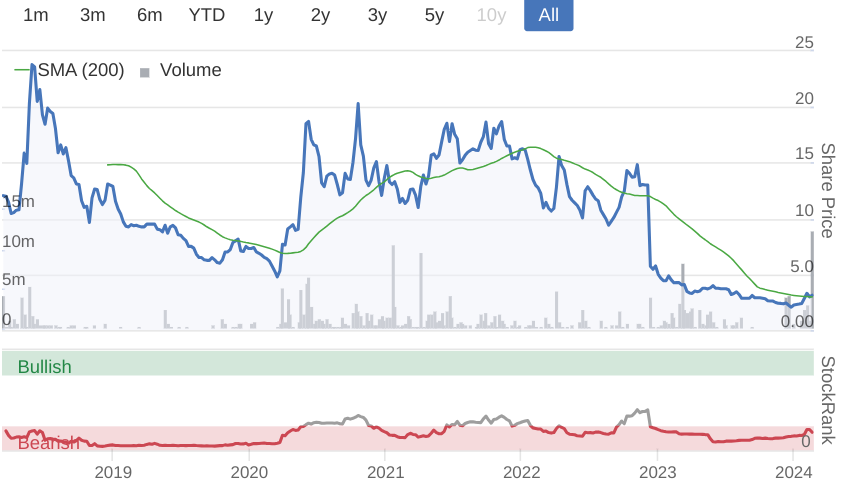
Note below the chart may seem to show a cheap share, but the share count has risen from 193m to 525m. So the market cap when it floated was about £19m (10p * 193m shares), compared with today's almost the same market cap of £18m (3.5p * 525m shares in issue).
Pod Point group (LON:PODP)
Up 8% to 23.4p (£36m) - Trading Update [in line] & Board changes - Paul - RED
Pod Point, a leading provider of Electric Vehicle ('EV') charging solutions in the UK, is pleased to announce the following trading update ahead of audited full year results for 2023 to be announced in April.
This is one of the worst business models I’ve ever seen. It embarked on a suicidal squandering of a large cash pile, with resulting immense damage to shareholder value, as you can see -

This is the latest update today -
Group results are expected to be in line with previously announced guidance of revenue of at least £63m and adjusted EBITDA loss of no greater than £16m.
At 31 December 2023, net cash was £48.7m, slightly ahead of the guidance of at least £47m.
Zeus says (note dated 20/11/2023) that £(16)m EBITDA turns into a loss before tax of £(24.3)m. This note was issued after the company’s restructuring plans were announced in a Capital Markets Day (CMD) held on 16/11/2023 - details here.
Guidance for FY 12/2024 is another huge loss, £(14)m, with only £15m in net cash expected to remain by end 2024. EDF (largest shareholder) has provided it with a £30m borrowing facility, suggesting that PODP is expecting to burn up all its remaining cash pile.
Investors might be looking at PODP and saying that the market cap is attractive at £36m, being well below the company’s own net cash pile of £48.7m at Dec 2023. However, as the company is planning to burn the entire cash pile, then I would value its cash at nil. Unless activists get involved, unseat the board, and stop the cash burn. Which won't happen because EDF owns 54%, so controls PODP. It sounds like the existing restructuring costs (exiting loss-making activities) will consume cash in closure costs.
New CEO - the original evangelical clown running PODP was sacked a while ago, and a permanent replacement has now been found -
Melanie Lane as Chief Executive Officer ("CEO") with effect from 1 May 2024. She will succeed Andy Palmer, who has acted as Interim CEO since 6 July 2023 during the course of the executive search and appointment processes.
She seems a good fit, with relevant experience -
Melanie joins the Group from Shell Recharge Solutions ("Recharge"), having led the standalone unit following its acquisition by Shell in 2017 to become a prominent e-mobility solutions provider across key EU markets. Prior to her time running Recharge, Melanie led extensive and successful turnaround programmes for Shell's Aviation and Retail units, which delivered significant operational improvements, resulting in strengthened competitive positions and profitability.
Paul’s opinion - as things stand, it’s a total basket case. Whether the new CEO will be able to create a viable business out of the existing mess, who knows? There’s an obvious need for a large scaling up in the provision of EV charging points, but that in itself doesn’t make a good business model. PODP has very little recurring revenues at the moment, it basically instals EV charging points at below cost, which is very philanthropic and public-spirited of them, but not something I find attractive as an investor.
The depleting cash pile, and backing from major shareholder EDF, does at least buy it some time to see if a revised business model can be implemented.
This share remains bright RED for me.
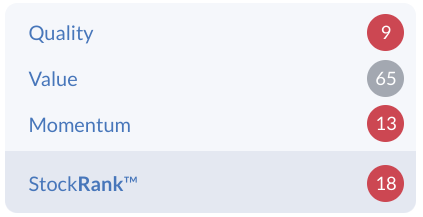
Stockopedia also takes a dim view, although note the value score is quite high, so the algorithms must have detected the big discount to cash -
Graham’s Section:
Springfield Properties (LON:SPR)
Share price: 74.3p (-5%)
Market cap: £88m
We took a quick look at this one yesterday, as the company announced a land sale to help meet its debt reduction targets.
Today we have interim results for the period ending November 2023. Here are the key figures:
Revenue falls 25% to £121.7m (includes a 26% fall in the largest segment, private housing, and an 82% fall in contract housing).
Gross margin up 70 basis points to 14.7%
Operating profit down 37% to £4.8m
PBT down 80% to £1.2m
Net bank debt rises to £93m but of course the company has been taking action since November to reduce this.
It’s clearly been a very tough period. Completions fell by 36% to 432, “reflecting entering the year with a lower forward order book due to challenging market conditions”.
Demand was impacted by “high interest rates, mortgage affordability and homebuyer confidence”.
On the brighter side, as we’ve discussed before, the company has re-entered the contract housing market, with £40m of affordable housing contracts having been signed for delivery in H2 of this year and beyond.
As the net debt level can’t be justified given historic/prospective levels of profitability, Springfield are taking the following steps:
Only commencing building homes when they are reserved.
Admin expenses reduced to £12.6m (H1 last year: £14.7m)
Land sales of £18m agreed so far.
No dividend payments until debt is reduced.
Outlook is in line with expectations, “including meeting target to reduce net bank debt to c. £55m by 31 May 2024”.
There are “initial signs of recovery” in private housing reservations, and “advanced negotiations” for more land sales. A rent cap in Scotland is due to expire on 1 April 2024.
Build cost inflation is stabilising around 2.5%.
CEO comment excerpt:
"The fundamentals of our business and our position within the Scottish housing market remain strong. We have one of the largest land banks in Scotland with over 6,421 owned plots, 86% of which has planning permission, and a further 3,217 acres of strategic land… while there remains uncertainty in the near term, with our position having been strengthened through the decisive action that we have taken, we remain confident in Springfield's prospects."
Graham’s view
The profitability figures are obviously very poor, but it’s to be expected given that the six months to November 2023 were some of the toughest months in the housing market for many years.
Springfield’s share price has reflected the malaise:

Looking ahead, adjusted PBT for the current year (FY May 2024) is forecast at £10.1m by Equity Development, rising to £13m for FY May 2025.
The adjustments to these figures don’t seem too heavy, e.g. in H1 the only exceptional items were £0.9m of restructuring expenses associated with the company reducing its ongoing cost base. So the numbers are relatively clean.
One of the main reasons I’ve been positive on this share is the balance sheet, and we have a fresh balance sheet from the company to look at this morning.
Total assets are £327m, about 98% of this figure being tangible assets. Assets mostly (£277m) consist of “inventories”.
Total liabilities are £176m, including long-term bank borrowings of nearly £100m.
Net assets are therefore £151m, or about £145m in terms of tangible net assets.
Against a market cap of £88m, I continue to view this as potentially offering investors a bargain.
However, this does hinge on the company’s debt reduction plans and its ability to continue operating profitably or at least without incurring heavy losses as it makes its planned asset disposals. As the company itself highlights, the upcoming expiry of the rent cap in Scotland will be important from the point of view of bringing PRS investors back into the sector.
It’s not my highest-conviction share by any means but I do suspect that risk/reward remains attractive at this level. It seems to offer value both on the balance sheet and against its forecast earnings, and it’s a “Super Stock” with a StockRank of 94.

Plus500 (LON:PLUS)
Share price: £18.63 (+2%)
Market cap: £1.48 billion / $1.87 billion
The headline here is “FY 2023 results significantly ahead of market expectations” but the company is referring to previous upgrades. Today’s results are in line with the January trading update from the company.
Key points:
2023 revenues down 13% to $726m
2023 EBITDA down 25% to $340.5m
Cash balance down 3% to $906m
As this Israel-headquartered company reports in US dollars, I also translate its market cap to dollars and get $1.87 billion.
That leaves an enterprise value of $964m for the business after deducting the cash balance from the market cap. But it’s important to bear in mind that the company needs to hold hundreds of millions of dollars for risk management purposes, to help shield it from adverse market movements. So we have to be a little bit careful if we want to value it on its enterprise value.
Shareholder returns
EBITDA of $340m translated to $271m of post-tax net income, allowing for very significant shareholder returns to be announced today. $175m will be paid to shareholders: $100m in the form of a new buyback, plus $75m in dividends.
Shareholders at Plus are well-acquainted with high returns, having seen $350m of buybacks and dividends announced last year.
Strategy
A wide variety of new platforms, licences and products have been achieved, for example:
Retail trading platform in Japan went live.
New licences in the UAE and the Bahamas.
Futures trading platform for retail traders in the United States (link).
Like its UK rivals CMC Markets (LON:CMCX) and Igg (HKG:799) (which I hold personally), Plus now offers a conventional share dealing service.
Outlook is “confident”.
Graham’s view
I think the company has presented these results extremely well, considering that there was a 17% fall in the number of active customers.
Even this sharp fall-off in customers was presented as a positive:
The number of Active Customers during FY 2023 remained robust at 233,037 (FY 2022: 280,769) thanks to the Group's customer retention, monetisation and activation technological capabilities.
New customers onboarded also fell off, from 106,00 to 91,000.
One of the major worries around this stock over the years, at least from my point of view, has been the quality of Plus’ customers - are they experienced and sophisticated traders who will keep an account open for several years, or are they beginners who will bust their account quickly and give up in less than a year?
One simple way to analyse this is to compare active customers vs. new customers.
This logic might be too simple, but here goes:
The company had 280,000 active customers during 2022.
It then onboarded 91,000 new customers during 2023.
Adding together, this implies up to 371,000 active customers during 2023.
But the actual number of active customers during 2023 was 233,000.
Take the difference. This implies that during 2023, 138,000 customers from 2022 became inactive.
This chain of logic suggests that half of the active customers in 2022 became inactive during 2023. This churn requires a great deal of ongoing marketing spend to replace inactive clients, but Plus has demonstrated over the years that it is very good at this.
Average revenue per user increased from $2,966 to $3,116 (5%), so those customers who did continue to trade remained active. They also deposited significantly larger amounts, with the average deposit up by 25% to $10,300.
I’m going to stick with my positive stance on these shares, as I don’t think it would make sense to remain neutral on Plus while I am so positive on its UK rivals.
After so many years of profitability and having reached this scale, it has become a credible, diversified, international trading services provider. They point out today that since IPO in 2013, they have delivered $2.1 billion to shareholders in dividends and buybacks.
And yet they continue to trade cheaply (along with the rest of the sector):

The StockRank is remarkable:

Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

84 comments
Springfield Properties (LON:SPR) - Investor Presentation (Interim Results) full video recording - February 2024 *** Innes Smith, CEO, Iain Logan, CFO and Martin Egan, COO of Springfield Properties hosted an Investor Presentation where they discussed highlights of their Interim results (period to 30th November 2023). The team talked through the decision actions they have taken to strengthen the company's position and commented on current trading being in line with market expectations. Management provided a detailed Financial Review and insights into the Scottish housing market. They also answered a wide range of questions from the viewing audience. Full video (divided into chapters for ease of viewing) is available here:
?si=3Z_Vlx-9FPT9pOMKYet more activity in the REIT space, with Urban Logistics Reit (LON:SHED) now making a counter offer for abrdn Property Income Trust (LON:API) which Custodian Property Income Reit (LON:CREI) had only recently bid for. Consolidation seems to be the way forward, with fewer, larger REITs.
Looks like Regional REIT might be in serious trouble. The bonds are priced for an equity (partial) wipe out.
I am less concerned with the ability of Journeo (LON:JNEO) to grow its business given the opportunities in the UK, Scandinavia and possibilities the recent acquisition of Infotec presents for growth in the US rail market. I am a little more concerned at the inability of Journeo to convert sales into cash. I know they have invested £5 million in product development over the past 5 years, and they also did an equity raise last year to finance the acquisition of Infotec, but a cash generative business this is not.
I nearly forgot to add I hold a small position.
Not one of mine, but nonetheless interesting: Superdry (LON:SDRY) founder Julian Dunkerton is in talks with several parties about financing his desire to take the company private. He is talking to US-based Davidson Kempner, who own Oak Furnitureland and the Gordon Brothers who own Laura Ashley. The shares have popped 19.61% as a result but nothing is in the bag.
The brand looks desperately tired to me with no clear focus but I wish him luck and any holders.
Yesterday’s popular stock MicroSalt (LON:SALT) is down about 25%.
I have seen over the years many horrible trading updates that the price hasn’t fallen so much.
https://ukinvestormagazine.co....
From UK Investor Magazine
MicroSalt is an excellent IPO opportunity with a strong management team and carefully planned growth strategy.
When details of its major B2B customers are made public, the company will hit the public investing consciousness fast.
As usual, there are risks — but the rewards on offer are correspondingly promising.
From me, maybe, a good buying time now for MicroSalt (LON:SALT)
https://us06web.zoom.us/webina...
Rick Guiney, CEO at MicroSalt, will talk us through what it's like being the new kids on the block on AIM, raising £3.1 million on 1st February 2024 following its spinout from TekCapital (AIM:TEK), and why they believe they are perfectly placed to benefit from the increasing demand for low-sodium products.
Webinar registration link above for Tuesday 27 February 2024 at 5:55 PM
Thanks for sharing
Thanks but not interested as there is no value in MicroSalt (LON:SALT) No need to tag my name again on this.
Give it a break, Jonny. You've made your point, multiple times yesterday. You're beginning to come across as a ramper.
So sorry peterg. For me, MicroSalt (LON:SALT) is worth a punt because if it does take off, then it could be huge. So, for me, a £1000 punt could well be worth the risk.
Dear All
Apologies in that I have messed up a little with my post on Avingtrans (LON:AVG) in that I had intended to publish it as a new post, but have also posted it on this thread.
Mea Culpa
The Advanced Engineering Systems (AES) division is worth more than the current market cap. This leaves the nascent medical division and its significant potential in the price for free
Your maths and mine agree. But while the new division consumes cash and embodies the very real possibility of failing to meet its objectives, then its effect on the conglomerate valuation is negative. That’s the bear case, as I outlined below, requiring a good margin of safety. You perhaps see that security in place at today’s price. I’d be happier nearer 300p. But wouldn’t all buyers?!
Fair point BnB.
Given the apathy towards UK shares, especially small caps, Avingtrans (LON:AVG) may well drift lower. The interims are due for release on 28th February so that should shed more light on how the company is performing as a whole and progress within the medical division.
Avingtrans (LON:AVG)
does this company have any excess value on the balance sheet that isnt instrinsically needed to operate business going forward , seems to be quite a bit of value on the balance sheet - not sure if it all needs to stay there though for them to be able to earn their crust?
Plus500 (LON:PLUS) strange sudden drop after starting well - not sure if there's been a broker note or similar? Results looked pretty solid - the key positive for me is the improving quality of their clients (and hence earnings). Worth looking at their results presentation which has a few slides on this - compared to a few years ago they now have a much higher proportion of long term clients who've been trading with them for several years.
Avingtrans (LON:AVG)
Apart from the general apathy to UK small caps the shares have been additionally marked down because in my view Mr Market is incorrectly focussing on the investment the company is making in its medical division that comprises Adaptix (portable 3DX-ray) and Magnetica (portable MRI). This capital allocation will result in a significant decline in reported EPS over the next couple of years.
I see the potential success of Adaptix and Magnetica as a large cherry on top of a profitable cake. If Adaptix and Magnetica are successfully commercialised they are likely to be worth significantly more than the current market cap of the company.
My thoughts and views in no particular order.
To conclude the management team, CEO, Steve McQuillan and CFO, Stephen King are a class act who have demonstrated their ability to allocate capital and buy and sell businesses well over several years and I am happy remain invested.
These are my views only. I have added to Avingtrans (LON:AVG) this morning at 349p.
All the best.
I've been looking at the UK GDP per head numbers. It's quite an eye opener!
GDP per head has declined since Q1 2022 or 8 quarters in a row. We have therefore effectively been in an "unofficial" recession (explaining the cost of living crisis) for the whole of 2022 and 2023! Population growth or net immigration of c1% per annum must be the reason for escaping an "official" recession (2 quarters of negative total GDP) until H2 2023.
GDP per head is still only 5.6% above pre-GFC at the end of 2007.
We are now ranked #27 in the world and slightly lower than the EU average. Ireland are 3rd!
EDIT - Apologies, I didn't mean to start a political debate on the advantages or disadvantages of net immigration!...key point of my post was the negative GDP per head numbers for 2 years which is very relevant to UK small cap investing.
....that clown Johnson's Brexit legacy.
Net immigration contributed £43B net to the British economy.
People thinking the recession is due to immigration?
The contrary, that immigration kept us out of recession.
The role of immigration is complex. GDP per capita is declining. Each of us is getting less productive. Immigration has done nothing to arrest this, it has just increased the number of people being less productive. Arguably immigration may even be to blame, as countries with labour shortages tend to focus more on increasing productivity.
Also remember that GDP includes public spending. So if an immigrant comes into the UK, has to be housed by a local authority, then falls ill and needs expensive medical care, that all adds to GDP. Whereas if I decide to grow vegetables rather than buy them, that reduces GDP. It is a very perverse measure.
You are talking about illegal immigration and I agree with that.
But overall your assumptions I believe they are totally wrong-a look at the USA will probably help you get a better , clearer , and an unbiased view.
Imagine the UK without all these workers that cover the shortage in labour.
Imagine the UK without all these foreign doctors and foreign nurses.
Imagine the UK without foreign students.
Imagine the UK without all these Turkish , Greeks , Chinese , Indian , Italian , Spanish people that support the food industry and the the people they employ.
All these taxi drivers , accountants , lawyers.
Imagine the UK’s house market without all these hard working people.
I can go forever.
22m people in the UK receive some form of benefits!
yiannos,
That is simplistic. Look at Japan and see a country with appalling demographics and very little immigration. They find a different way of doing things, relying heavily on robotics and automation.
The UK has chosen a model of not investing in infrastructure or productivity and instead importing cheap labour to plug gaps. This increases GDP, but doesn't increase prosperity, as everyone ends up getting poorer, because productivity is not growing.
What is frustrating is that we have never had an honest debate about it. Of course the country would grind to a standstill without immigration. But this is a country where trains still have drivers and the Post office workers go on strike at the introduction of scanners to sort parcels. Where the average NHS worker spends 30 minutes a week trying to log onto an out of date computer system.
You can always plaster over failure to invest through importing workers. But having 10 people do a job that could be done by 5 because it is cheaper in the short term isn't the best way to run an economy.
Japan’s GDP is lower than it was 25 years ago. The UK’s has almost trebled!
All the best
The problem without doubt is the number of people of working age not working, particularly where they are being supported by the State. But that also needs to be considered alongside the total number employed in the economy. Then there is the consideration of productivity levels and it’s lack of growth.
The Conservatives answer to this is Rwanda and small boats. I don't think Sunak can talk to his former colleagues at Goldman Sachs .
Agreed but what is the answer ? Whether you support the large increase in immigration or not, the political problem is that the vast majority of the electorate do not !! We are such a tiny island , already far more crowded than anyone would surely want , with an aging population, a hopeless NHS, poor political leadership ( which is unlikely to improve under Labour) and a large and growing “ black “ economy.
I have little confidence in UK plc and although I certainly invest some of my free assets here, the majority is overseas .
Whether you support the large increase in immigration or not, the political problem is that the vast majority of the electorate do not !!
True, few would support a "large increase in immigration". But immigration is not generally amongst the most important issues when people are polled, and there is no clear overall majority for drastic steps to reduce it. If you start breaking down opinions by the type of immigrant it's only low skilled workers for whom there is a significant group thinking it should be more difficult to enter (an overall majority think it should remain as now or be easier). For all other categories (even including finance sector workers!) the generally favourable trend is even stronger. (From the Migration Observatory Sept 2023).
The govt keep telling us the reducing immigration is the "will of the people" (an entirely evidence free statement, as usual) but it's not even clear that's true amongst Tory voters.
Given Britain's large net immigration last year it is shameful that we are now in a recession.
I think the main reasons are:
a. The current fashion for early retirement.
b. Working from home with all it's built in inefficiencies and its impact on businesses that support people who turn up for work.
c. Long term sickness.
d. The sheer volume of inactive people of a working age.
None of this helps inflation either with too much money chasing too few goods.
I think this country needs a different mind set in order to get back on track.
b. Working from home with all it's built in inefficiencies and its impact on businesses that support people who turn up for work.
There are plenty of studies that people working from home are generally more productive when not in the office. That tends to break down when people are never or rarely in the office, but for most places of work 2-3 days at home a week is most likely to increase productivity.
Sure it's not good for city coffee bars though!
It is noticeable that many US firms are insisting on employees turning up for the full week, and there are many reports that home working isn't effective.
In my view mentoring, training, swapping of ideas, good practice and team spirit is insufficient when people are missing for 2 or 3 days per week. Also whilst some people will work very hard from home others will I believe take the opportunity to pursue their own interests.
The initial post was interesting, some of the commentary is getting in to politics. I like this forum, but not peoples politics, I hope Stockopedia will step in and moderate.
I hope Stockopedia will step in and moderate.
I really don't understand why people can't just skip past if they don't like a comment. This constant patrolling by individual users over what can and can't be said is ridiculous. You do not own this forum and it is not up to you as to what is relevant or not to the rest of the community (its called democracy, people are allowed their opinions even if you dislike reading them). Politics does sometimes have an impact on an investment thesis and therefore is certainly relevant and important to some peoples thinking. If someone isn't being rude / disrespectful and has something they believe is relevant (politics wise or other), then I would like to hear it and I don't want them to think their views are not appreciated and are being shut down.
100% agree .
OK, I will complain directly to Stockopedia. There are 14 comments (including my two comments) which are not related to small caps (or medium caps), out of 63 comments today. That's a lot of scrolling and a group/forum can lose its effectiveness if it doesn't keep to its main content, small cap shares.
On the plus side no one has mentioned Microsalt today..
EDIT - no I see that yiannos has managed a quick comment.
And he said he wouldn’t comment on it anymore - LOL
Personally I find that probably 80% or so of the forum posts are not really relevant to my investments. This is usually due to it being company or sector specific, and I personally will either read it out of general interest, or just scroll past - it really doesn't take much time to scroll past. If I have to scroll through the 80% to get to the 20% then that is fine with me - its all part of the research process. However there are lots of people that will benefit and engage around the posts I don't engage with, and it is not up to me to decide if these are relevant to other people or not. If you feel that strongly about it, then as you say, by all means report it to stockopedia. I just hope they don't start to micro manage the content as I personally think we get a good mix of contributions with very varied thinking and this should be protected and not censored imo.
When discussing politics, some people exhibit strong prejudices, cherry pick data and are prepared to argue that black is white. I find it useful to be reminded that the same weaknesses are almost certainly present in the share discussions and therefore to take everything that is said on any investment forum with a large pinch of (Micro)salt.
Avingtrans (Jonno advice)
It’s probably my most confident holding
Right at bottom of its range
Lots of smalll sells forcing orice down
Nothing seems on the horizon to change the slide
Heading into the 340s
There is going to come a point maybe a brief touchdown to circa 300p when I’ll. sell the house and the kids and take it to a 2times position (20% portfolio value)
Not there yet but getting closer
What’s your thought Jonno I. Just have this as zero long term downside and 100% upside .
Think the market really doesn’t like this outflow of cash developing the new imaging stuff .
Avingtrans (LON:AVG) I'm not Jonno but don't do it planetx. The kids love you.
The figures look bad. I don't see any reason to get excited unless you are shorting the stock.
Avingtrans (LON:AVG) I like the business positioning but how am I supposed to value it? PBT is less than a quarter of EBITDA, earnings are a tenth of last year’s numbers and there’s no free cash flow. And yes, it’s a mini Halma (LON:HLMA) but there’s a rather risky blue sky element to the Medtech investment. FDA approval is all very well, but my sustained experience in Medtech is that commercialisation of innovation is a longer, riskier and more expensive process than usually anticipated.
Anyway, here goes. Adjusting out the MII annual losses and estimated associated interest payments, I come back to a PBT in the region of £9.3m which supports a share price of around 425/450p at current valuation norms. The question is therefore, what additional valuation should we ascribe to MII, or should we discount the current valuation to account for the risk of sunk costs and wasted management attention if the segment disappoints? I’m leaning towards the latter camp and wonder if 350p provides an adequate margin of safety.
Very interested to hear from proponents and share bears.
Bear case with Avingtrans (LON:AVG) is that they spend a few years' cashflows and a lot of management time trying to scale up their new imaging businesses which turn out not to be commercially viable.
I think you're correct in that the UK market isn't mature enough to stomach the drop in eps caused by the investment in the Medical Imaging Division.
Sum of parts is my preferred valuation for Avingtrans (LON:AVG, PE ratio is plain daft.
You could easily argue that getting the rest of Adaptix for a sliver of the previous valuation round could turn into 'the Steve's' best piece of M&A which is a high bar after Booths & PB.
Barclays (LON:BARC) seems to now be priced like a micro cap sucker stock. I usually avoid banks because their balance sheets are bewildering, so I confine my comments to the P&L and free cash flow. Not only are they aiming to sustain the 8p divi, but intend to return £10bn (45% of market cap) over the next 3 years. Around £3bn will be in divis and £7bn as buybacks. Meanwhile, IF they hit their targets (grow revenue to £30bn from £25bn) and reduce costs by £2bn, in 2026 they will earn £14bn in pbt (up from £7.5bn today). Assuming the buybacks are executed around today’s share price that would put the market cap at £15bn. So assuming that £14bn pbt equates to £11bn net profit a 2026 PER of 1.35. Of that isn’t alluring enough, what will the distribution be in 2027? They may continue with buybacks if the share price is still in the doldrums or they could instead triple the dividend to 15%, which would still be covered over 4x
Barclays (LON:BARC)
IF they hit their targets (grow revenue to £30bn from £25bn) and reduce costs by £2bn, in 2026 they will earn £14bn in pbt (up from £7.5bn today).
errrrrr really - can i fact check this bit of logic/maths please. Note normally when company say they are cutting costs that does not stretch to other costs not going up particularly - if they are adding 20% of sales at the same time.
Note it could simply be that costs need to be reduced by £2 billion to stay where they are - eg if they know staff costs are going up by £2 billion , they need to cut £2 bill out to stay where they were. Then if they have £5 bill extra sales theer will be normal costs ref that extra income - ie prbabaly 15% margin or whatever
Broker notes detailing expected profits are the sanity check here.
Yes fair point, and they are talking about overhead, so quite right. However, they also state they they are working toward cost/income ‘in the high 50s’. At 58% I make pbt £12.6bn. So not quite £14bn but still, if they get anywhere near it will make today’s share price look ridiculous. I struggle to understand free cash flow of large banks, but am encouraged that the divi plus buybacks imply that profit does indeed turn to cash. I’m not sure I can triangulate the historic stocko free cash to the accounts.
Barclays (LON:BARC)
trying to make any sense of of bank financials is nigh on imposssible for us mere mortals - all i would tend to look at is book value and ability to geenrate excess money that does not need to be retained for regulatory reasons - low pe seems to be a given here , presumably onthe basis next time it goes wrong it will be a biggie.
Not sure why they think the future will be much rosier than the past - perhaps they a e living in ideal world without recessions / liquidity issues / bad debt issues / political issues and their ability of the board to run the bank in an honest non shyster type manner.
As you say the promise of divis and buybacks sounds very promising as long as its not at the expense of leaving an underivtsted bank where all the customers move elsewhere or they find that the reality of cost cutting doesnt always pay long term dividends!
I was thinking the same Barclays (LON:BARC) but it is very difficult to achieve these on forthcoming lower interest rates.
Barclays (LON:BARC) elephant in the room -I can’t begin to imagine how they are going to grow their UK banking business when they are reducing back office support costs so drastically while their customer service and support is so appalling?
However, they are not acknowledging that the business has been so badly run despite the fact they announced today they will eliminate 500 legacy IT systems. 500! That is a big number. You would be forgiven for thinking it was part of the government.
[For clarity, I both hold (possibly not for much longer) and have some legacy commercial accounts. Numpty that I am!]
Pity we don't see more of this straight talking.
https://archive.ph/nHLtE
Boe Risks Deepening UK’s Recession, Former Chief Economist Warns
“It’s one thing to have missed inflation on the way up, which happened, it’s quite another to then have crushed the economy on the way down,” Haldane said. “That double blow to credibility is one if I were a central banker, in my old job, I would be looking to avoid.”
Interesting article in the DT today re Currys - quotes John Stevenson - analyst at Peel Hunt saying, "Ultimately you've got a retail sector that's had 2 or 3 really challenging years in terms of the consumer, supply chain, and everything else. Now it feels like we are starting to come out of the other side of that, and that's not being reflected in valuations.....the outlook for M&A from both PE and trade buyers seems likely to pick up.....He flagged a number of market leaders were trading at low PE ratios - including DFS, Halfords, Topps Tiles, Card Factory and M&S."
Things could get interesting....
Have just posted my thoughts on Byotrol (LON:BYOT) and thought I would flag it on the SCVR. No RNS today but references the previous 4 RNSs.
Why?
Byotrol has a profile very similar to Tristel* before it took off (*far and away my most successful investment). I’m already invested and think maybe some market pointers have been missed by investors. Ideally, I would have asked Paul to review it but it’s (now) too small for the SCVR, doesn’t seem to have a following and always seems to publish an RNS on a busy day. So, in DYOR mode, I took the initiative of calling the Company and the CEO David Traynor very kindly scheduled me 45 minutes of his time. If nothing else the exercise has given me an appreciation of what Paul and the Team need to do to provide an insight and also the frustrations of running a small, listed AIM company. I thought I’d share my observations.
Anyway, hope it is use to some of you.
Berksbee, thanks for your thoughts. Elsewhere there is concern about cash flow/burn and the sudden departure of the CEO. Any concerns, please?
Include this in my write up on the Bear case. Cash burn is a concern but it is "sufficient to execute the strategy" - not to be ignored though - this is not a widows and orphans share. Reading between the lines the previous CEO was good for sorting out the strategy but poor for putting out a very optimistic RNS that was not realistic. The company has 2 lines of revenue - product that is predictable, appears to be growing, and looks like it soon wash its face and - licenses which are highly unpredictable and lumpy. The licenses are not in this years forecast (YE March) but will be "material" next year. I asked the CEO about the possibility of raising funds and he said that is not a given in this market whereas several years back they it would have been a breeze. He did not say that this was what he was doing or even investigating.
In summary cash flow is the main risk for me. The CEO going is much less of a concern as its now back with the ex CEO who was/is on the Board.
Overall I think there's lots of bad news baked into the share price. If the cash issue is managed as indicated and it turns a profit then it will take off IMO.
A great example to all Cos on AIM of the perils of putting out over optimistic RNS that then have to be withdrawn a few weeks later!! You will be punished.
Thanks very much for your thoughts on Byotrol (LON:BYOT) here is the link to save people searching https://www.stockopedia.com/co...
I like that you start with the bear case (downside). I agree with your point on cash being the #1 concern and also that this is too small to be a quoted company, even on AIM. The cost of maintaining a listing is significant at this level. It is also thinly traded so the spread is quite something - 0.65 to buy, 0.5 to sell though in practice I am being offered 0.56 to buy which isn't terrible.
As you say, it is impossible for the company to raise fresh equity at this price, they could not justify the dilution. So it is a question of hanging on for trading cashflows to save the day. An interesting special situation. Good luck with it - FWIW I think you are wise to wait for the next update. Mostly, I wanted to say thank you for taking the time to share your research.
Plus500 (LON:PLUS) The company has had a volatile history but has provided high level of returns to shareholders. Plus 500 is a changing animal moving into the competitive US market and B2B. I also think the company has not provided quarterly statistics that it has done in the past.. So from my point of view the black box syndrome has increased. I remain a happy shareholder but would be wary of my holding becoming more significant.
Interesting appointment at Pod Point group (LON:PODP)
CEO Appointment & Directorate Change
Pod Point, a leading provider of electric vehicle ('EV') charging solutions in the UK, today announces the appointment of Melanie Lane as Chief Executive Officer ("CEO") with effect from 1 May 2024. She will succeed Andy Palmer, who has acted as Interim CEO since 6 July 2023 during the course of the executive search and appointment processes.
Melanie joins the Group from Shell Recharge Solutions ("Recharge"), having led the standalone unit following its acquisition by Shell in 2017 to become a prominent e-mobility solutions provider across key EU markets. Prior to her time running Recharge, Melanie led extensive and successful turnaround programmes for Shell's Aviation and Retail units, which delivered significant operational improvements, resulting in strengthened competitive positions and profitability.
And a trading update (cash of £48.7m):
https://www.investegate.co.uk/...
CMD (16/11/23) video here - https://www.piworld.co.uk/comp...
PODP sits on a negative EV and has big losses, but Melanie might just turn this around (potential deal with Shell?). I've lobbed a few £s from the speculative pot. Not for widows and orphans.
Pod Point group (LON:PODP)
As an EV user, I'm not so sure that Shell Recharge will be interested in Pod Point group (LON:PODP) , as their model of forecourt chargers is significantly different to how PODP see the future.
Octopus have integrated their smart tariffs with other home charger suppliers such as Ohme, Wallbox and Myenergi, so why not with PodPoint too, especially if PODP chargers are solar compatible??? Will need a willingness from PODP to make it happen.
https://www.shell.co.uk/about-..
"As part of the agreement, Shell and Octopus have also signed a memorandum of understanding to explore a potential international partnership to bring the best possible experience to their EV charging customers, including Shell Recharge subscribers. Options will be explored for possible joint promotions and brand activations, alongside co-operation on out-of-home charging and other activities across the EV value chain. Shell is already a leading EV charging provider with a global charging network set to expand to around 200,000 public charging points by 2030".
How much of Airtel Africa's revenues originated from Nigeria - the stock has been rapidly falling these last few days
According to Sharepad, 40% of telecoms revenues and an additional proportion of fintech, itself 10% of total but probably higher margin. In that context, the sell-off looks wholly justified - moderate even. Until the currency stabilises, this looks uninvestable. But an opportunity perhaps if/when stability returns - until the next crisis.
Huge PO cut by JPM says it all.
i thought that stocks go up when inflation is high as happened in Turkey/Argentina though?
i thought that stocks go up when inflation is high as happened in Turkey/Argentina though?
They possibly would if listed in Nigeria and in local currency, but Airtel Africa (LON:AAF) reports in USD, unless I'm mistaken. So the collapse in the Naira creates a massive headwind to earnings. From the local Nigerian press:
"Telecom powerhouse Airtel Africa was only a breath away from loss-making in the nine months to December after net profit crashed by 99.6 per cent.
A free fall in the value of the naira in Nigeria, its biggest market for mobile service, battered earnings, according to details of its unaudited financials Thursday."
Plus, I believe with Airtel Africa (LON:AAF) that there is still legacy debt on the holding company level, in USD.
They have been moving debt to the Operating Company level (ie Airtel Nigeria) and denominated in local currency. But it has not finished I believe? Hence the Naira devaluing is extra double whammy. Lower USD revenues, but the debt and servicing still remains in USD...
Huge PO cut by JPM says it all
???
Huge PO cut by JPM says it all
???
Bloomberg terminal speak for Price Objective
I had a fairly rapid investment into Airtel Africa (LON:AAF) last year followed by an equally rapid exit.
My thoughts were the the exposure to rapidly growing mobile phones/data markets in Africa and the expanding fintech. With lower fixed cable infrastructure there, mobile comms becomes all the more important as they develop economically.
Then I got cold feet. Not from any deep analysis, but thinking about a company with income from soft currency nations to support substantial US Dollar borrowings. Too risky for me, and I'm happy to miss out on this particular ride.
anyone following what's going on in Nigeria and the implications for PZ Cussons and Airtel Africa PLC?
https://www.reuters.com/world/africa/nigerias-naira-hits-record-lows-stocks-sink-2024-02-19/
How much of Airtel Africa's revenues originated from Nigeria - the stock has been rapidly falling these last few days
AAF and PZC
Interesting read, thanks for posting and the link. Sadly I hold both shares!
I believe its around 1/3rd
Seplat Energy (LON:SEPL) is my largest holding but fortunately isn't impacted by the drop in the Naira as it sells in USD. I do wonder if the reducing Naira positively impacts their staffing costs. I imagine most workers are paid in the local currency but profits come in USD. Results are next week so I am hoping for solid production, a special dividend announcement and announcement of the completion of the Exxon Mobil (NYQ:XOM) deal. Maybe I am being greedy!
Hi Ben
This was my concern the other day about Seplat Energy (LON:SEPL) regarding salaries , capex , day to day operations etc. Surely they must have accounts in Naira. Still there is very good value and I have started following it (I do not hold).
As a long term holder of Seplat Energy (LON:SEPL) I hope you’re right Ben! That would be the hat trick that could get the SP moving out the wedge.
Also in the sector, but with different country risk, Arrow Exploration (LON:AXL) could be making a solid move on drilling news (I hold). Positive news flow highly likely to continue through the remainder of this year too.
And finally, Kistos Holdings (LON:KIST) is looking interesting at current price levels. More so with today’s announcement of acquisition of gas storage facility following recent restart of the Shetland gas plant (new holding). Management here are ex Igas, anyone know if this should be a red flag?
O&G not always a topic here but I would welcome any discussion on those companies from the group here.
Journeo (LON:JNEO) (I hold so I am biased) Just to add to Paul's comments which I agree with, I would say Journeo are forecast to have almost £8m cash on their balance sheet so if you strip that out they are on under 10 x FY24 earnings.
I did ask the CEO at Mello what the runway looks like because I was also concerned about the drying up of orders but he reassured me they have a huge addressable market in the UK (many years) plus potential further orders in New York and Europe and an increasing shift towards recurring revenues albeit from a small starting base.
No heavy capex spending forecast and given the continued positive momentum in orders I think anything under £2.80 is a good entry point into a niche growth stock with a rock solid balance sheet and very competent management, if it was rated anything like Tracsis share price would be a lot higher.
Core holding for me.
ENGAGE XR Holdings (LON:EXR) a tiny company, winning contracts with some very big companies. Currently loss making, but recurring revenue/ SAAS type model and interesting play on VR, XR Spatial computing space...
Twitchy Finger Syndrome ? If I’m doubt do nowt” ?
After doing a big chop and cull week or so ago have to say I am finding it hard to control the dopamine induced twitch buy sell button
Think I’m bored or need a cold shower or something or maybe it’s nice having some cash actually in the bank and that’s a warm blanket feeling I hadn’t had for s while .
Though I’ll just spend it on something else or some other project that seems a great idea at the start and turns out to involve something called work which is getting harder to do. Did a full day last week moving stuff around and couldn’t move for 2 days just haven’t got those 12 hour hump and grunt days in me any more .
I’M still inclined to
- cut my last 2 or 3 smaller positions (1% weighting or less) namely Comptoir and saatchi
And increase on a few good holdings at bottom of range .
Not sure what to do, maybe switch off for s while as on s great run at the moment with some great bounces on some key holdings that have rewarded holding my nerve at the bottom of the bear doom and gloom .
- Hargreaves , Wynnstay , bank Georgia , Georgia capital , Filtronic
mmmm , probably best to follow my dads advice
“If in doubt do nowt”
Just waffling sorry think the point is sitting and holding like Charlie and Warren tell us to do isn’t a particularly natural state of affairs .
Ditto.
Hi planetx,
Adding the tree cutting in your portfolio will do no harm!
All the best
Springfield Properties (LON:SPR) as expected todays Interim numbers show a big drop in revenue & profit pre tax versus last year but are Inline with expectations
Debt reduction has been the key focus (through land bank sales & cost cutting) & they’re well on their way to their stated goal of c£55m by May
Re engaging with the Scottish Government on building social housing now that the SNP have moved the goal posts back too I see
I hold & have since IPO (so it’s been a rather rocky road ;-)
My morning smallcap tweet: Created with AI: A̶r̶t̶i̶f̶i̶c̶i̶a̶l̶ I̶n̶t̶e̶l̶l̶i̶g̶e̶n̶c̶e̶ Actual Idiocy
Nightcap (LON:NGHT) ENGAGE XR Holdings (LON:EXR) Journeo (LON:JNEO) Skinbiotherapeutics (LON:SBTX), Pod Point group (LON:PODP), Lok'n Store (LON:LOK)
[edit]◄Nightcap (NGHT)► slots a grim trading miss like a visit to a shitty toilet after a couple of glasses in the lounge, right at the back of "Acquisition of The Piano Works and other matters" RNS. Trading in 2024 'far softer' than mgmt exp. Greater than expected integration costs for two acquisitions. Still guides FY24 rev in line (how?) but adj EBITDA only £2-2.5m. Holders should call time on this.
◄ENGAGE XR (EXR)► wins 'major' contracts: a seven-figure contract with a large Middle East-based co plus an additional six-figure contract with an American bank. [SP=2.6 Cap=14m]
◄Journeo (JNEO)► wins Framework Agreement with expected £5m rev through to January 2028. Rev included in this FY exp. [SP=261.77 Cap=43m]. I hold.
◄SkinBioTherapeutics (SBTX)► set to launch Pheet and Dermatonics Once Heel Balm in Asia, Middle East and Africa. Collaboration with the mfr and distributor Umesh Modi Group is currently at an early stage so no change to market expectations at this stage. [SP=10.4 Cap=20m]
In line: PODP, LOK
Springfield Properties (LON:SPR) - Interim Results - "Looking to the future with confidence" - new research report with audio summary here: https://www.equitydevelopment.co.uk/research/interim-results-24-looking-to-the-future-with-confidence
Springfield has reported encouraging H1 results, reiterating full year expectations and confidence in longer term growth prospects. The strategy to maximise cash generation is bearing fruit, costs are being carefully controlled and there are signs of market recovery, both in terms of Affordable contract successes and, more recently, a pick-up in Private Housing activity since mid-January. It is too early to extrapolate but the average weekly reservation rate in Private Housing since mid-January has been 62% higher than for the year to that point
Debt reduction is a clear priority for management and today’s results highlight the progress that has been made in realising cash from the land bank in recent periods. Springfield has one of the largest land banks in Scotland and an excellent reputation in both Private and Affordable Housing.
With increasing confidence in forecasts and improving market sentiment, we believe the 40%+ discount to sector peers is unwarranted and reiterate our ED Fair Value/Share of 130p (Price/ Book multiple of c.1.0x).
Well that explains the 10% drop in Cavendish Financial (LON:CAV) yesterday, they are not daft, why pay more for their Cip shares.