Small Cap Value Report (Tue 20 July 2021) - SDG, GTLY, SOS, WIL, SDI

Good morning, it's Paul & Jack here with the SCVR for Tuesday, a very busy day for updates.
Timing - today's report is now finished.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to cover trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research) - don't blame us if you buy something that doesn't work out. Reader comments are welcomed - please be civil, rational, and include the company name/ticker.
Agenda -
Paul's Section:
Preamble about current market volatility.
Sanderson Design (LON:SDG) (I hold) - a strong trading update for H1. Cash rich, trading well, and priced on a PER of 14 (before today's rise). Looks good, and modestly valued.
Sosandar (LON:SOS) (I hold) - Results for FY 03/2021 show decent revenue growth, and slashed costs, but still loss-making. However, I focus on the superb 256% revenue growth in Q1 (April-June 2021), suggesting Sosandar should now be at breakeven or better, for the new financial year FY 03/2022. Looks like a game-changer, if current stellar growth can be maintained.
Sdi (LON:SDI) - I review the in line results for FY 04/2021. Excellent figures. Finncap flags that one-off large orders completing could cause earnings to fall next year, so this is a key point to be aware of. Although more acquisitions are likely, and could offset this headwind, with management very experienced in M&A. Taking into account the one-off orders, I think the valuation looks a bit too high maybe.
Jack's Section:
GTLY - solid results from expanding professional services firm. This has been a year of consolidating existing acquisitions and ensuring safe passage through lockdowns, but management is optimistic of the acquisition pipeline going forward.
Wilmington (LON:WIL) - resilient results and net debt is down. There are signs of quality in the education businesses, but the balance sheet could be stronger.
.
Preamble for Tuesday - market conditions
Lots of people have emailed me (Paul), and asked for some market comment.
As a value/GARP investor, I’m not really interested in market fluctuations. I tend to just research things in as much depth as I can, then buy & hold for several years. Some of them work, some don’t. If the results & trading updates disappoint, then I chuck them out. There shouldn’t be any emotion involved at all, and buy prices are best ignored & forgotten, because the market doesn't know or care what we paid for our shares. It’s the occasional multi-year, multi-bagger, that makes the money & mops up all the mistakes.
Where are we now? This is what I see -
- Takeover bids - loads of them, especially from overseas, suggesting that the UK market is cheap - which is bullish.
- Low broker forecasts - results are mostly ahead of expectations, and there are many forecasts being raised a lot - this is bullish
- V-shaped economic recovery, based on the economic data - this is bullish
- Companies are generally reporting that they have adapted to covid, stripped out costs, profits are rising - this is bullish.
Set against that -
- Momentum arguably carried many share prices too high in the anything & everything rally since Nov 2020
- Balance sheet weakness was ignored by some punters - with inevitable consequences when reality comes home to roost & fundraisings are needed (I got caught on Revolution Bars (LON:RBG) in this regard, and there are plenty more banana skins out there - watch out!)
- Stretched valuation multiples
- Naive punters, new to the market, don’t know how to value anything, so prices are highly volatile
- Thin summer markets, with little volume = extreme volatility
- Mixed messages from central banks over interest rates
- China threatening to nuke Japan
- Profit-taking snowballing
- Blah blah blah
- Take your pick, it’s all nonsense to a certain extent!
Lots of people have emailed me, asking what I’m buying. The truth is, when you’re 100% invested, there’s not much cash on hand to buy anything. Although I have eked out a little cash to buy what I think are terrific bargains: SAGA at 303p. JOUL at 235p. BOO at 275p. As usual, just my personal opinions, and DYOR. We’ve discussed them all at enormous length here, so just search the archive for the bull & bear cases, if you’re interested.
As I always say to people who email me with great concerns about price movements - just try to work out your own strategy. Are you a trader? Or an investor? Most people think they are investors, but are actually traders - flitting in & out of things, trying to time the market, losing confidence when prices fall. Not many people can do that well, consistently, in my experience, and it’s a horrible way to live, being permanently on tenterhooks - who wants to live like that?
I think that, if we seek out great companies, with entrepreneurial management, they usually do well over the long-term. Nearly all the self-made multimillionaires I know, have made their money from a handful of major multibaggers - typically about 4 big investments over their career that have made them the really big money - which usually means holding, for a long time, often when the share was unfashionable. Everything else was a sideshow.
.
Paul’s Section
Sanderson Design (LON:SDG)
(I hold)
147p (at close, last night) - mkt cap £116m
Sanderson Design Group PLC (AIM: SDG), the luxury interior design and furnishings group, will hold its Annual General Meeting ("AGM") at 9.00am today. Ahead of the AGM, which will take place as a closed meeting as detailed in the Notice of AGM, the Company provides the following trading update in respect of the first 23 weeks of the current financial year ending 31 January 2022.
Recovery continues with forward momentum
It’s more good news from this convincing turnaround situation -
The positive trading in February, March and April 2021, outlined in our full year results announcement on 18 May 2021, has continued throughout the 23-week period with the result that profits for the six months ending 31 July 2021 are expected to be ahead of Board expectations.
Total group sales for the 23 weeks are up 39.8% vs LY, and up 1.4% vs the previous year (a more meaningful comparison, pre-pandemic).
Pandemic has still had an impact this year, so recovery is good in that context.
There's lots of detail in today's update, here are some points covered -
North America is the best performing region, and makes up 20% of total brand product sales. The UK is the largest market, at 52% of brand product total sales
Figures for the manufacturing division are shown in a separate table, and look very good, up 52% on LY, and up 21% on the pre-pandemic year
Licensing income is also up strongly
Collaboration with Next (LON:NXT) (Morris & Co designs for clothing) has performed “very strongly” in the first few weeks - note that deals such as this tend to be short-lived, so it’s a bonus rather than anything to get too excited about, in my view
Liquidity - net cash of £13.9m on 16 July 2021, down from £15.1m on 31 Jan 2021, due to seasonal factors & payment of corporation tax
Dividends - objective is to resume divis, more details with the next results
Diary date - mid-October 2021, for half year results
Employee engagement survey now 78% positive, up strongly from 58% two year ago - an important factor, often overlooked by investors, the staff are the business, so we should want them to be happy
Positive external factors are mentioned, which are quite interesting -
The Board believes the Group is benefiting from the convergence of three positive impacts:
(1) pent up demand for home interiors,
(2) the trend towards maximalism, and
(3) the post-Brexit increased demand for British design and manufacturing.
“Maximalism” - there’s a new word for me!
Outlook - caution is expressed, but I don’t think that’s anything in particular to worry about, it sounds more a generic thing - supply chain issues are affecting almost everyone at the moment it seems -
"Whilst the Covid-19 pandemic and potential cost inflation continue to create some uncertainties for the near-term outlook, our focus remains on mitigating the potential impact of those uncertainties and continuing to progress the Company's strategic development.
My opinion - the newish CEO Lisa Montague has worked wonders here, modernising the company’s operations (e.g. product launches & sales are done online now), reducing costs, and halving the product lines to focus on best-sellers (thus reducing inventories & boosting cash).
A strong balance sheet means no need for equity to be raised during the pandemic. There’s plenty of scope to resume divis, due to the recovery in profitability & bulging coffers.
I can’t see any broker updates today, but on existing consensus forecast, this share is only on a multiple of 14.0 times. With a cash rich balance sheet, and an ahead of expectations update today, that’s great value. Mr Market has thrown an impromptu mid-season sale in recent days, which in my view is a good buying opportunity here.
High StockRank too.

.
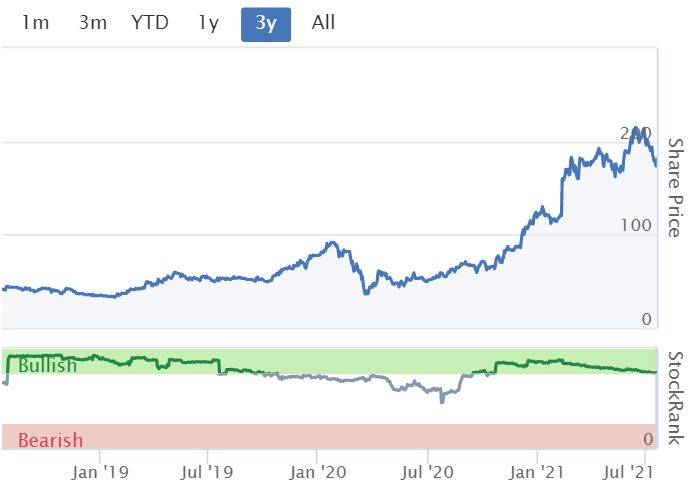
A little more detail on the X-axis below would be helpful, but each blob is a month, so it’s easy enough to see what period this covers. Note that forecast EPS was reducing last year, but this year forecasts have shot up, and what’s the betting they’ll be more positive earnings upgrades? Seems likely to me.

.

.
Sosandar (LON:SOS)
(I hold)
24.75p (up 3%, at 08:50) - mkt cap £55m
I’ve got to pop out shortly, so can’t go through the numbers at the moment. However, I do want to flag up remarkably strong current trading, which looks like a game-changer to me.
A few key numbers from FY 03/2021 first -
Revenues £12.2m (up 35%) - this needs to be seen in the context of the business conserving cash during the pandemic, slashing marketing spend, etc. So it’s actually not bad.
Big reduction in EBITDA loss from £7.7m in FY 03/2020, to £2.9m loss in FY 03/2021 - still bad, but a lot less bad than previously, due to costs being slashed.
Year end net cash of £3.9m - the company surprised me a lot by being able to trade for a year at negligible cash burn - showing the big advantage eCommerce businesses have, in that costs are variable, and can be slashed in an emergency, unlike fixed costs physical retailers.
Recent trading - this is what we need to focus on.

.
Revenue of £5.7m in Q1 suggests to me that the full year revenues could be in the ballpark of £25m - double last year, and enough to take Sosandar to breakeven or modest profits I reckon. That is highly significant in my view, and means the business model has moved from struggling to get anywhere near to breakeven, into profits.
Cash position - is now very good, with £9.1m in cash at 30 June 2021. Moreover, it looks like the operational cash burn is now likely to be eliminated, so the cash pile can be used to build up inventories for the successful & growing third party sales through Next, John Lewis, and Marks & Spencer.
My opinion - I’ll do some more work on this later, but just wanted to flag up the importance of tremendously strong revenues in Q1 (April-June 2021), which I think greatly improves the investment case for Sosandar shares, and largely removes risk now. It’s probably around breakeven on a run rate now, and has plenty of cash, which shouldn't deplete as it did in the past with operational cash burn.
Today’s update tells me that the business model is now proven, which makes the shares much more attractive than before when it was highly speculative.
.
Sdi (LON:SDI)
182.5p (up 5%, at 14:27) - mkt cap £180m
SDI Group plc, the AIM quoted Group focused on the design and manufacture of scientific and technology products for use in digital imaging and sensing and control applications, is pleased to announce its final audited results for the year ended 30 April 2021.
Sparkling results out today. Key numbers -
Revenue up 43% to £35.1m, of this 19% is organic growth, which is very impressive, the rest obviously from acquisitions - the core business model at SDI is to grow from acquisitions, and so far it doesn’t seem to have put a foot wrong. Looking at slide 3 of the results slide deck, the Board has a lot of finance, and M&A experience.
Adj profit before tax of £7.4m, up 71%, and note this is a very impressive profit margin of 21% of revenues, indicating quality businesses with pricing power, and seems to have been very resilient in the face of the pandemic.
Adj diluted EPS up 74% to 5.97p - a PER of 30.6 times - not unreasonable, given the growth, with the key point being whether growth continues or not - the company did mention some one-off orders previously, I recall.
Two acquisitions made during the year.
Outlook comments mention one-off orders -
The outlook, thanks to our agile business model, is positive and we are planning for further organic growth, including from one-off COVID-19 related orders, and appropriate acquisitions during 2021-22. Trading in our 2021-22 financial year remains in line with market expectations and we look to the future with confidence."
Broker update - a very useful note from Finncap is out today, which helpfully gives us an idea of what performance might be like once the one-off orders are completed.
This shows EPS of 6.4p in FY 04/2022, falling to 5.0p in FY 04/2023. Shareholders need to hope those forecasts are comfortably beaten, because they don’t support a share price of 182p in my view.
Finncap does mention that more acquisitions are expected, which should provide a boost to earnings.
Dividends - it doesn’t pay any, which is fine for an acquisitive group, in my view. People are in this share for capital appreciation, not income.
Cost increases are mentioned, but it doesn’t sound alarming -
Due to the increase in the price of raw materials, labour and logistical costs, our costs of goods sold are increasing. However, our operating expenses are not yet at pre-pandemic levels. We intend to continue reviewing all costs and will where appropriate pass on cost increases to our customers to maintain profitability.
Balance sheet - acquisitive groups often become top heavy with intangibles. SDI has £26.2m in intangibles, not excessive. It has modest tangible fixed assets, so doesn’t need a particularly strong balance sheet.
NAV is £26.8m, deduct the intangible assets, and NTAV is only £0.6m - so quite a lean balance sheet. There’s only modest gross debt, offset by year end cash, and given the high profits & positive cashflow, I think this balance sheet looks OK. More acquisitions would turn NTAV negative though, unless more equity is issued to part-fund them.
Cashflow statement - favourable working capital movements helped boost cashflow by £2.8m, but the post-tax operating cashflow is impressive at £10.3m, of which about 27% comes from working capital movements.
Capex is modest at £667k, and only £367k development spend was capitalised, so this is a good business model - high profit margins, from a capital-light balance sheet.
Cashflow was mainly used for funding acquisitions, a good thing since management seem good at M&A, and debt reduction.
My opinion - this looks very good.
I can’t see anything of concern in the numbers, it all looks fine.
The main issue here is that current profitability is being boosted by one-off orders. Hence I think a PER of 30 times is probably too high, given the risk that earnings could plateau or even fall once those orders complete.
Therefore, I think it’s probably high enough for now. The risk is that earnings could run into a brick wall for FY 04/2023, with investors being disappointed by growth stalling from those big orders completing. It’s a potential headwind, which the company has been very open about.
On the positive side, more good quality acquisitions could outweigh any issues over one-off orders. And one-off orders could repeat, who knows?
As long as everyone is aware of the one-off orders issue, then people can make a fully informed decision about valuation.
High StockRank too.
.
.
Jack’s section
Gateley Holdings (LON:GTLY)
Share price: 210p (-0.94%)
Shares in issue: 117,888,007
Market cap: £247.6m
Gately is a legal and professional services group. It listed in 2015 following changes to the law to adopt an Alternative Business Structure (ABS), allowing non-lawyers to own and invest in law firms. There are a couple of similar listed plays now, including Rbg Holdings (LON:RBGP) which we discussed at the Mello BASH last night. There’s a consolidation and disruption opportunity in this part of the market.
Since floating in 2015, the group has acquired:
- Capitus and Hamer Associates in 2016,
- GCL Solicitors, Kiddy & Partners, and International Investment Services in 2018,
- Persona Associates and T-Three in 2019, and
- Paul Tweed and The Vinden Partnership in 2020.
More specifically, the group has built a ‘platform’ of market-facing structures on which complementary legal and consultancy services are aggregated.
Unlike RBG Holdings however, 90% of group revenue still comes from legal (for RBG it’s something like 66% of FY20 profits from legal and an expected 50% of FY21) so it is more concentrated but this could change pending further acquisitions.
This was last covered in the SCVR earlier this month by Paul, noting the delay to accounts.
High levels of activity, strong trading momentum, overall sense of optimism and confidence… have continued into the new financial year and the Board is confident in the outlook for FY22.
Highlights:
- Revenue +10.5% to £121.4m,
- Underlying profit before tax (PBT) +7.1% to £19.3m; PBT +10.5% to £16.3m,
- Adjusted diluted EPS +5.8% to 13.17p; basic EPS +8.1% to 11.18p,
- Net assets +32.2% to £59.3m; net cash +£20.5m to £19.6m.
Non-legal revenues increased by 27.3%, thanks in part to a £14m contribution from Gateley’s consultancy businesses. Cash generation looks very good, with Covid cost savings and working capital management allowing for the repayment of all bank debt.
Net cashflows from operating activities was £25.4m (FY20: £13.3m) representing some 193.2% of profit after tax. That’s arguably not sustainable, but cash conversion in the prior year was an encouraging 113.5%. Free cashflow was £20.8m.
Staff bonuses and dividend payments have been resumed. Total personnel costs increased by 21.9% to £77.5m (FY20: £63.5m) - that’s 64% of revenue. No surprise given the business model, which relies on retaining and recruiting human capital.
Other operating expenses reduced by £2.7m or 11.5% to £21.0m as the cost of travel, marketing and premises reduced following a full year of remote working.
The second half of FY21 was ‘extremely strong’ with high levels of activity, which more than compensated for the impact of the first National Lockdown. The turning point arose just before the half year-end, when activity levels returned and the group’s pipeline strengthened significantly.
Outlook - Strong trading in the first two months of the new financial year with good pipelines of new work and acquisition candidates. The latter is to be ‘widened and enhanced’ in FY22 and beyond.
The dividend policy remains to distribute up to 70% of profit after tax (PAT) to shareholders, typically one third following its half year results and two thirds after the full year results are known.
Conclusion
The above values GTLY shares at 16.3x adjusted diluted earnings, 19.2x basic earnings, and about 12x free cash flow. Not obviously cheap, but not expensive either if you believe in the growth prospects.

Gateley took a conscious decision not to make any acquisitions during FY21, and instead focused on integrating its FY20 acquisitions. It intends to resume acquisition activity now.
There’s a consolidation and expansion opportunity in this space that a couple of players have identified. Gateley’s own strategy of creating a market-facing ‘platform’ to which it can bolt on complementary professional services businesses looks to be sound. The key will be in identifying appropriate acquisitions, purchasing them at attractive prices, and successfully integrating them.
I’ve a favourable impression of a couple of these legal and professional services firms. The opportunity should reward entrepreneurial operators with a deep history in the space, Gateley being one of them.
Is there a ceiling to the strategy, I wonder? It’s a fragmented market but how big can these platform companies become before they begin to get unwieldy? Perhaps there’s more to aim for before that becomes a serious consideration.
Wilmington (LON:WIL)
Share price: 214p (+2.88%)
Shares in issue: 87,569,384
Market cap: £187.4m
Since floating on the London Stock Exchange in 1995, Wilmington has evolved from a UK publishing business to a global company with information, education and networking services. Acquisitions and developments over the years include:
- 1999 - First training business acquired: Central Law Group (CLG),
- 2000 - healthcare data and market-intelligence services Binley’s
- 2001 - creation of International Compliance Association (ICA) in response to growing importance of compliance regulation in financial institutions,
- 2007 - sale of non-core trade magazines in move away from advertising revenues,
- 2010 - Axco Insurance Information Service acquired
- 2015 - Financial Research Associates LLC (FRA), expanding US healthcare presence
- 2016 - Wellards acquired, since rebranded as Digital Learning Academy and is part of Wilmington Healthcare. SWAT UK purchased and integrated with Mercia.
- 2017 - HSJ added and combined with Wilmington Healthcare
Education businesses can be attractive, but the consistent acquisitions does mean that £97.6m of Wilmington’s £166m total assets are goodwill and intangibles. Meanwhile, total liabilities of £123m include £48.5m of debt. The current and quick ratios are tight.

The group appears to be solidly cash generative however, and interest cover is a comfortable 4.8x.
Wilmington has struggled to grow in recent years and this is reflected in its rangebound share price.

Wilmington ended the year ahead of expectations for revenue, Adjusted PBT and net debt.
(Adjusted (PBT) is calculated as PBT after adding back amortisation of intangible assets except computer software and profits/losses on disposals and business closures.)
Trading in both the Information & Data, and Training & Education divisions was strong in H2 resulting in group revenue for the year being unchanged, despite the lack of face-to-face training or events.
Revenues excluding events have grown year-on-year in both divisions.
Full-year adjusted profits are ahead of FY20 as a result of the digitisation of its products and services, strong revenues, tight control of overheads, and actions taken to reduce less profitable lines of business.
Cash flows have been strong with group net debt at 30 June 2021 down to £17.7m (30 June 2020: £27.7m).
Conclusion
A short update, but a positive one from a trading perspective I would say.
This could be a collection of nice, defensive businesses with predictable revenues and cash flows.
Falling net debt levels is a good result. You can argue there’s a weak balance sheet here if you strip out goodwill and intangibles, which results in negative net tangible assets. But then again Wilmington generates solid cash flows from its business franchises, which comfortably covers debt payments. The working capital position looks unnecessarily tight.
All in all, the company can work on strengthening the balance sheet in my opinion.
That aside, a lack of positive growth CAGRs stands out on the StockReport. There are some hints of quality and potential here, but it would be good to see that coupled with more definite signs of profitable growth and greater financial security.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

90 comments
Sdi (LON:SDI) does anyone know why the share price has fallen so much recently, can't see any news, it is now down to around 152p.
Let the subscribes post as they wish,
Stocko has some clear rules of what should be removed if red flagged for anything offensive or misinforming.
BSV
Hi timarr
I wouldn’t want Paul or Jack ever being restricted on what they can write on, and their non stock commentary is often superb.
The problem comes not when there is some comment on their non stock commentary but like today when posts on covid almost take over. Some enjoy reading covid posts so there’s a place for them. My point is that it’s not here but on a separate covid or pandemic thread.
I think the Covid situation is integral for any discussion on the markets at the moment, so personally welcome any posts on this SCVR.
I agree that it’s a shame that Paul and Jack’s excellent Company updates sometimes see replies on off topic themes (that may be of interest to some) instead of focusing on those updates.
Simple answer (as has already happened with BOO and then Investment Trusts) is for someone to start a thread on covid and then those wanting to post on it can do so without clogging up the Small Cap Value Report threads.
spot on Ken!
I agree that it’s a shame that Paul and Jack’s excellent Company updates sometimes see replies on off topic themes (that may be of interest to some) instead of focusing on those updates.
Mea culpa but when the board goes oft piste it's nearly always triggered by some general commentary by Paul or Jack - in this case, the market conditions preamble which, as an early poster today noted, ignored the Covid elephant in the room. Cue a Covid debate.
So perhaps the request should be to Paul and Jack to avoid non-stock commentary in order to avoid non-stock related posts?
timarr
Timarr please keep commenting as you see fit. Your contributions are as useful as the main writers. As for covid, it has been the main driver of the markets since Feb last year so all discussions on this topic are very helpful, wherever they occur. Thanks all.
Timarr please keep commenting as you see fit
Thank you, but I actually agree with most of the comments. The largely off-topic commentary (a good part of it by me) detracts from the sterling work that Paul and Jack have put in. I think I'd be pretty p*ssed off if I spent a load of time analysing stocks in depth and then the board goes off on one about something else.
We could set up a board for CV-19 specific commentary - but that would rely on people pushing SCVR violators over to it. But it's largely worked for Boohoo (LON:BOO) with Paul's support, so perhaps that's a solution?
timarr
I do think that a separate Covid thread would be a good solution. This is one of three bulletin boards that I visit every day, and every one of them gets bogged down in discussions of Covid.
Shoot me, but it seems to me that the endless posts about Covid hospitalizations and other related things has become as repetitive as the back and forth we had on pros/cons for Brexit several years ago. Clearly Covid is relevant to our portfolios, but the constant back and forth, discussing minutiae of data, makes it exceptionally difficult to read the actual discussion of individual stocks, which is why I (and I expect the majority of others) read this report. Please take the discussion to a separate thread, or twitter... All the best, Will.
This is why stockopedia needs to provide us with blocklists. There are too many windbags here who simply use it as a platform for their tedious opinions or to spam their podcasts or blogs. Stockopedia will not moderate these threads or keep them on topic so we should be allowed to turn off people who do not add any value to us.
I miss the red "thumbs down" button.
Especially on the 'replies'! I would only give a 'thumbs down' to Paul/Jack if I could produce something better and wave a highly profitable share portfolio at them. Easy to criticise extremely hard to do better.
To be honest i dont agree, in my opinion yesterdays pull back was very much Covid related and i learned a lot from some very learned posters on here .
I have been out helping a friend most of the day and it did not take me very long to scan through the comments, disregarding ones that i was not interested in , eg. Companies that dont fit my investment style etc.
Richard
Hi Paul, thanks for your comments on the markets and approaches to investing. I found that helpful and reassuring. It’s the approach I’m naturally drawn to (companies I think have great potential and staying invested for some time).
There’s a Cloudcall presentation later on IMC- I plan to attend that one. It looks like their business wins in H1 have been pretty good.
Best regards,
Andrew
I would be interested to have the people thoughts on Quiz Vs Sosandar. Quiz is roughly 1/4 of the market cap of Sosandar.Yes the company has massively disappointed since his floatation but it seems to offer a better investment opportunity at this stage.
Different ends of the fashion market. Not really comparable. Quiz (LON:QUIZ) also have legacy shops and not so good online capabilities. Sosandar (LON:SOS) is online first, online only.
A quick lunchbreak update
I just want to say thank you for the various posters yesterday around the "Sea of Red" and those who shared with honesty that they are down for the day, week, month, year to date etcetera.
It is lovely to hear when someone does amazing and spots the bargain and makes a load (please can you just come round and make me sit down and place an order next time you see such an opportunity), but this is an imperfect world and I am just a beginner in comparative terms (value invested, time to commit (e.g. day job and parent) and years of experience).
I guess looking at the three portfolios I am responsible for (mum, big sister and mine) just now this would appear a stage 4 portfolio proverbial car crash, but other than an emotional response I have not the time to think through do I sell/buy so hence it is a do nothing but that is not a wrong decision. Looking again just now there are no companies in there I would not buy now, yes it is always nicer to buy 20% lower and sell 10% higher, but I am not a genius or omnipotent.
Paul, thank you for your thoughts on emotion versus conviction.
Having got a lot better in the last year on research, check list, position sizing. Yes it emotionally hurts when a 10% holding goes down >10% in two days, or large single figure in one day, just like it feels wow when you get that large rise in a day or week. This is not the end of my world, or mum's or my sisters, not the best month in the office, but in the game, still fighting, still learning and hopefully I will be here next week, next month and next year too.
I have a holiday next week, for the first time since last August and yes I really need it, and so does my wife too. Maybe I will take the tablet and start that next part of research to find the big multi-year winner, or maybe I will just sit with a good book and glass of wine and watch the sun go do.
Thank you
Tommy
ps. I hold, and have not sold anything today, yet...
"Maybe I will take the tablet and start that next part of research to find the big multi-year winner, or maybe I will just sit with a good book and glass of wine and watch the sun go do."
I would recommend the latter. There is always another day and another way to make money but not always another family holiday
I too would recommend the latter. Enjoy your family holiday and focus on them. Our last one was in Aug 2019 and we were looking forward to a short one in a few weeks time.
Just to show how perilous life is, my wife received an insect bite (at home in the UK) just over a week ago and developed a life-threatening infection. She is still in hospital but thankfully now improving. I scarcely care what the markets are doing as I've had a sharp reminder of how precious life is. Enjoy your holiday.
Well said Northender. I'm so glad your wife is improving.
Hi Northender
I am sorry to hear about your wife and I hope that she continues in her recovery.
Tommy
Something Paul said a while back stuck with me, along the lines of "lots of stocks are doubling and they don't normally do that". I'm wondering if what we are seeing is a hyper-accelerated bear, bull and bear market.
One of the maxims that gets tossed around is sell a stock when it drops below the 200 MA and stays there. That's apparently a sign of stage 4 and its going to keep going down. Running through a few of the popular stocks at the moment there are a lot hovering just above the 200 MA and quite a few testing below it. Maybe it's an intermediate correction?
Hi Paul
Cloudcall (LON:CALL) released six month trading update today, looks to be heading in the right direction , CEO very bullish. In your last review you were indicating frustration that profits still seem to be elusive and could remain so as costs were increasing at the same pace. Any change on that view following today’s update ?
Thanks in advance
Rob
My worry is what if we start getting 100,000 cases of covid cases a day? Won't the market panic and people start offloading indiscriminately? Businesses won't have the support that government provided at the beginning.... The positive is of course the vaccines but will this be enough to stop the panic?
It was conceded (in as many words) during the press conference yesterday that its very plausible to approach 200,000 cases per day in the August peak. I think those types of numbers partially drove yesterdays movements as the stories broke on Sunday so I would suggest its now already priced in
It was conceded (in as many words) during the press conference yesterday that its very plausible to approach 200,000 cases per day in the August peak. I think those types of numbers partially drove yesterdays movements as the stories broke on Sunday so I would suggest its now already priced in
You can price in the numbers but you can't price in the response. If, for instance, the government imposes vaccine passports on bars and restaurants as well as nightclubs or reimposes social distancing then that has a material impact on some business models.
Markets hate uncertainty because they can't figure out how to price anything. So yesterday's fall is no guarantee that there isn't another big one coming. Equally we could see a quick recovery.
I'd also add that these numbers were all available well in advance of Saturday. Markets are doing a lousy job of pricing in known information, and have been during the entire pandemic.
timarr
Agree, but think a lot of the pricing at the moment is retail, driven by media. There is no volume to the market - the institutions are on holiday.
Cases are not particularly relevant though for a variety of reasons. (1) increased testing scope where the UK is miles in front of even the next largest testing nation in Europe, which is France. Plus we are doing a lot more testing than during the 2nd wave.
(2) Immunisation clearly impacting positively on duration and severity of illness. (3) Hospitalisation and death rates far below previous waves.
In my view the key potential economic problem is in the "self isolated" pinged by the NHS app. They will need to sort the NHS tracker out else the whole country will be isolating! It is a ridiculous tracker imo as it goes through walls. So if you sit in a car and someone else with covid sits in their car for 15 mins nearby you will get pinged to self isolate! It appears to be a very blunt tool formed in the early stages of the pandemic that hasn't been re-designed with re-opening in mind. Another oversight perhaps?
Businesses are already struggling to get enough staff and if rates go up considerably and too many people are told to self isolate then this is clearly going to damage hospitality in the short term and the impact will depend on how long that persists. I think it is this uncertainty coupled with the number of absolute cases being banded around by the media without context that is un-nerving people a bit, but appears to be mainly retail, at least at the moment.
This is not massively surprising as certain governments appear to be targeting a fear campaign to encourage vaccination take up and for that you use the media, but it has the unintended consequence of also spooking investors. In US I think it was Faucci for example who told the media yesterday that the Delta variant was the most serious illness you would ever contract, or words to that effect. He almost might as well have said "get the vaccine or die"!! (yes, I know that's an exaggeration but you get my point). It's a tried and trusted psychological marketing tactic, one that was also used here in the UK at the start of the pandemic to get people to obey the stay at home orders btw. For a Government there are clearly positives and negatives to this approach both short and long term but we, as investors, should at least be cognisant of the approaches being used as they can mask underlying realities.
it amazes me how many still obviously use the damn App. Deleted mine ages ago. Have had my two vaccines and are careful and considerate but bugger me if I am going to self isolate on the whim of some dodgy tracker !!
To get 200k per day, you’re going to need to test a heck of a lot of people. Where will these people come from, as the vaccines will create a larger % of asymptomatic cases. And with people getting increasingly fed up with lockdowns/rules/media fear etc. I can see fewer and fewer people being tested and fewer pings.
Also, the sceptic in me thinks that after the summer hols, there will be fewer people trying their damnedest to get pinged/tested… just for a few days off work to spend sunny days in the back garden!
The testing is irrelevant, only insofar as it feeds the modelling of the pandemic.
200,000 pd will get infected with Covid in August, regardless of whether they are tested or not, pinged, self-isolating etc. The data shows this.
To get 200k per day, you’re going to need to test a heck of a lot of people. Where will these people come from, as the vaccines will create a larger % of asymptomatic cases
Not really the point, is it? 200,000 cases a day, tested or untested, leads inevitably to a decreasing pyramid of symptomatic cases, severe illness, hospitalisation, intensive case and then death.
It's not measuring the 200,000 cases that's the problem, it's their existence.
Given the rate of reproduction of the delta variant 200,000 cases a day in a month can be seeded by 25 cases today.
timarr
According to the ONS about 9 in 10 adults now have antibodies for Covid either as a result of previous infection or vaccination, or both.
So that must make a difference - I guess our current nationwide experiment will determine how much.
According to the ONS about 9 in 10 adults now have antibodies for Covid either as a result of previous infection or vaccination, or both.
While agreeing that's a positive thing we have to be careful how it's interpreted:
Manaus in Brazil achieved herd immunity levels via natural infection but then had a massive second wave when the Beta variant struck.
Also, of course, the vaccines don't stop infection or transmission entirely - so a huge third-wave would inevitably find its way to the vulnerable and unprotected. Which would lead to a spike in hospitalisations.
About the best you can say for it is that it's better to get the inevitable third-wave out of the way before the inevitable winter spike in other respiratory conditions ....
timarr
I think his point is the reverse....... ie in the 2nd wave the UK was testing far less people so even though cases existed they were never on an official count. Now they are detected. So 200,000 cases today might have been 300,000 cases in the 2nd wave but we didn't have that data. Thus the absolute number of cases is only really relevant in context.
But we are not comparing the same pyramid since reference points have changed and even if we were, the pyramid shape has radically shifted anyway via immunisation (vaccine or natural t-cell). And therein lies the uncertainty - the prediction is that the pyramid has now narrowed in so significantly that 200,000 new cases per day will not lead to an over capacity NHS or death rates.
Interesting analogy to investing - our recent reference points shape our view irrespective of whether facts have changed. ie I buy a share for 100p so that becomes my reference or anchor point. If the company doubles share count the next day my psychological reference point doesn't change, even though it should. In the case of covid 200,000 cases is very high against our recent reference points but since the number of tests (share count) has doubled and the immunisation programme has massively reduced serious illness we should factor this in but we are psychologically biased not to do so.
Interesting analogy to investing - our recent reference points shape our view irrespective of whether facts have changed. ie I buy a share for 100p so that becomes my reference or anchor point.
Technically that's anchoring or, in this case, recency. It's a trigger for loss aversion, one of the worst behavioural biases investors can suffer from. But that's not the issue here.
We know that because of the higher rates of vaccination and natural immunity that it will take much higher rates of infection to cause hospitalisations. But because we're relaxing safeguards like social distancing, mask wearing and mass events at the same time as the highky transmissable delta variant is prevalent we know we will get far higher rates of infection.
So our pyramid base - numbers of infected people - will be broader.
What we don't know is how that translates into numbers further up the pyramid. We know for sure it won't translate into the tsunami of death that it would have prior to the vaccination program, but we don't know where it will peak. That's what the scientific models are trying to figure out, but there are lots of variables, including peoples' behaviour, which is notoriously difficult to predict.
However, the one thing we do know is the more people that get infected the more people will become symptomatic, ill, hospitalised and dead - albeit all of those will be lower than pre-vaccination. Those numbers may peak at levels well below the capacity of the NHS but the models are showing some scenarios in which that is not true - and those are all in the range of where we get to between 100,000 and 200,000 actual (as opposed to app pinged) infections per day.
timarr
i think we have to understand that "cases" are not usually people with symptoms and the pcr test is not accurate, depending on how many cycles they run it on. So while there may be panic I do not think hospitals will be overwhelmed especially since we are not in the winter flu season.
Let's do a back of the napkin calculation.
According to NHS England there are 96,000 'general and acute' hospital beds in the UK not counting psych wards, maternity wards, physical rehab wards, beds for nurse triage in A&E, etc. The occupancy of those beds is recorded but has varied over the course of the pandemic, but let's use Sept 2020 figures to represent a summer lull in cases. Occupancy was at 74,000. So let's assume that we have 12,000 beds + a 20% buffer for beds the NHS can repurpose so roughly 14,500 beds free right now.
Let's assume 200,000 cases per day in August but that roughly 90% of adult population have been single-jabbed at least, BUT that vaccines are 95% effective.
200,000 * (1-0.9) = 20,000 +
200,000 * 0.9 * (1-0.95) = 9,000
So 29,000 people at risk of hospitalisation every day in August. What's the true hospitalisation rate of unvaccinated COVID patients? Let's use the second wave day rates as an approximation (since we had basically no testing at all in first wave, which means cases are low and therefore hospitalisation rates are unfeasibly high).
So daily cases at peak was 61,757, and hospitalisations were 4,134, so roughly 7% of all people with COVID got hospitalised.
29,000 * 0.07 = 2,030 hospitalisations a day.
Which would mean the available hospital capacity would fill up within one week.
Still so sure hospitals won't be overwhelmed?
(I'm 35% in cash and moving higher)
refs:
https://www.england.nhs.uk/sta...
https://nhsproviders.org/news-...
er but that assumes amongst other things (a) that testing is the same now as it was in the 2nd wave which is far from being the case. It is now much higher (b) that every case ending in hospitalisation is still there a week later whereas lots of hospitalisations only require a day or so of treatment if that. If you go to hospital (even if you are sent home) that is counted as an admission in the official numbers, so hospitalisations do not equal beds and (c) the hospitalisation rate is the same as in the 2nd wave prior to vaccinations whereas the age range of the unvaccinated has changed to those less likely to be hospitalised
not saying it can't happen, but I think you've made the stats fit your investing case there. No issue in people choosing to hold cash if they are concerned though.
All good counterpoints David. I would agree that a) and c) are basically unknowable for sure, but on point b) if we assume that every day 2,000 patients are hospitalised but 1,000 are released, which is generous, we still bust through the available capacity in 13-14 days.
To be honest, this was more a fun thought exercise, main reason for moving to cash is impending implosion of Tether and with it crypto in general, hence reason for my sizeable gold miner portfolio.
That was before the vaccines, hospital admissions are much lower now due to most adults being vaccinated.
AFAIK the ONS figures are a random sample, tested and then scaled. So the numbers just come from the prevalence and from statistical distributions. You don't need a lot of people asking to be tested because they have symptoms.
Thank you Paul Scott. Your write ups are soo informative and your analysis are always to the point. I for one find it very helpful to read your views on stocks and general market, which leads me to do further research.
Really appreciate the good work you're doing. Keep it up.
Yes, thanks Paul!
From last week, the Accrol Group (LON:ACRL) full year presentation worth a look in my view. Two main KPIs are gross margin and market share growth. GM% now 27.7%, market share 15.9%. They feel, in the main, they can pass on increase in paper cost. Here you get a sense of the whole team - granted with 4 people on one webcam difficult to see their facial expressions, but good to see them all together. Video & podcast.
Yesterday Ultra Electronics Holdings (LON:ULE) reported interim results, bought forward due to the proposed offer by Cobham. Their turnaround strategy is achieving better than expected results. Here's the analyst and investor presentation. Video & podcast.
Last week, we ran the second event for LPeC (Listed Private Capital). Three private equity funds presented, about 15 minutes each. A neat overview, providing vehicles to get into unlisted and PE opportunities. There is often greater exponential growth for private companies prior to listing, so these funds allow retail investors to access these growth companies, with diversified risk.
BMO Global Asset Management
CVC Credit Partners (Leader in global credit & private equity)
Oakley Capital
Part 2: Video & podcast
Part 1 featured:
NB Private Equity Partners (Investing in private companies for LT growth)
CapMan Oyj (Investing in real estate, infrastructure, special situations, growth, buyout and credit opportunities in the Nordic region).
Gimv (Specialist European mid-market investment company that invests in innovative and entrepreneurial growth companies.
Part 1: Video & podcast
Coming up this week, we should have the Sthree (LON:STEM) H1 analyst presentation (here's their H1 overview), and Begbies Traynor (LON:BEG) FY analyst presentation.
And, join us for Sosandar (LON:SOS) FY results presentation tomorrow Wednesday, 11am and the Tekmar (LON:TGP) Capital Markets Day Thursday 22nd July, 4.30pm. Register for both here.
Results from Supreme (LON:SUP) look perhaps a little bit better than expected. The company has plenty to go at and an entrepreneurial CEO who has plenty of skin in the game. It is a new listing so to an extent caution is the byword, however a reasonably encouraging start. I have a smallish holding at present.
Paul/Jack I would be interested in your thoughts, time permitting.
Paul, thank you for the market commentary. For me, it’s great to be reminded that I’m holding quality shares (many the same as yours) for the long-term. I’m pretty much fully invested.
I’ve recently decided to only look at RNS for my shares (which I’m emailed automatically) and your report on updates (and others’ comments on these).
It’s very liberating not to be looking at prices so regularly. The only time this will change is if/when I come into cash and look at what prices are being offered by the market at that time. Thanks to you and Jack for your wonderful work.
Fevertree Drinks (LON:FEVR)
Quick OT mention ref fevertree (my largest holding) - numbers today look fine and dandy although not liked at all by the market.
I will completely ignore margin woes as they are still in high expansion growth phase overseas so will not be anywhere near "max efficiency"
Uplift of £10 mill on expected sales for 2021 is nice - they now expect to do £300 mill 2021 compared to £250 mill in 2019 (pre covid year) . This is with q1 2021 being in lockdown ref their uk on trade so numbers still delfated somewhat. h1 sales up 36% compared to crappy 2020.
Note fevertree are now primarily an overseas brand ref sales - with uk sales down to 35% of the total.
US sale up 42% in constant currency to over 25% of total sales - ramping up very nicely.
ROW sales up 71% constant currency
and Europe up 81% constant current lfl (compared to woeful 2020)
Ok these numbers are compared to crappy 2020 but overall the company remains on track to establish itself as a global brand player on note in their niche - are you watching Coca Cola?
A key risk to the sustainability of Fevertree Drinks (LON:FEVR) has been whether it could repeat its stunning performance in the UK in overseas markets. It is clearly succeeding in achieving this again under the noses of the big drinks companies. The large margins have been whittled down and are apparently not expected to recover quickly but 44% is not too shabby. (I hold)
I agree re Paul's commentary. Very helpful in these difficult times. I would like them to be a regular item. Thank you Paul
Ref market outlook/turbulence
Nice video by the popular investor on youtube with regard to general market outlook. I know any one persons view on the market can be very biased and its very easy to cherry pick data you like to substantiate your view - but if nothing else some really useful info being presented here that gives a decent flavour of where some of the macro elements seem to be trending at present.
https://www.youtube.com/watch?v=yD0YevLZlpQ
hi rmillaree - appreciate this link to The Popular Investor (very good & great to see his points on manufacturing trends using national data).
Your opening remarks are just what the doctor ordered today, Paul! Thank you.
FR
Great opening commentary Paul. Thank you. And great SCVRs too from you and Jack of course :)
The buy & hold forever strategy would work for me if I didn't use stop losses. I try to be strict with these and was actually stopped out of Sanderson Design (LON:SDG) yesterday. Perhaps I should forget about stops altogether?
Mr F if its any consolation I got blasted out of Luceco (LON:LUCE) and Gattaca (LON:GATC) on same basis. However, I got back into latter at much lower price - so its a strategy not entirely without its benefits!
Hi Mr F,
Interesting point.
I have been reluctant to use stops in the past, started using again then have been stopped out a few times past week! Including trailing stops.
I think to be a true buy and hold strategy, stops cannot be used. Only my opinion, of course!
The data in "100 baggers" by Chris Mayer would support this...
Regards.
I generally work with manual stop losses as I got tired of being stopped out of positions by an intra day spike down. I’m no trader and try to avoid making decisions while the market is open.
I make an exception if I genuinely can’t make my mind up about a share and decide to give it one last chance or occasionally if I’m going to be away on holiday and out of touch for a while, Then I set some automated stop losses.
Of course with manual stops you need the discipline to actually act on them.
Mr F - I have stopped using stop-losses. I had a couple of triggers last year that have cost me dear. So now I tend to look to invest in solid companies and closely watch market updates. I sold nothing on the back of yesterday confident that over time things will come back.
I try to remember I am an investor and not a trader so as long as the investment case remains intact I will take the bumps along the journey.
I stopped using automatic stop losses as I have been stopped out of good companies in the past, I would have been stopped our of Alumasc and Sanderson yesterday if I had, I draw the line at 20% or nearest resistance after carefully weighing the options and news flow, I have to be Disciplined and keep on top of my holdings.
Good morning Paul, wonderful common sense preamble. Maybe we should all have a picture of Corporal Jones on our desks to help remind us….
Thank you for all the first class reports you chaps keep serving up!
Corporal Jones - never thought of him as an investment guru before, but you are bang on!
Well he is certainly better than Private Fraser.
Thanks for the excellent market comment Paul. A good solution for anyone worried about the always unpredictable markets is to sell anything we’re worried about, be ruthless with shares that let us down (e.g profits warnings) and to raise enough cash to feel relaxed about the value of our portfolios falling, and to have firepower for good value investments should there be significant market falls.
i hope you can update on Sosandar (LON:SOS) results.
The text was bullish throughout but is it taking too long to get to profitability?
Also unless I’m expecting too much too fast, some of the figures seem underwhelming suggesting perhaps that it’s going to be a long time for profits really to take off?
e.g the number of orders is only up from 214,000 to 276,000, and active customers only very modestly up from 131.093 to 135,381. And repeat orders only up from 1.69% to 2.08%.
Sosandar (LON:SOS)
I have generally not been a fan of their reporting methods , its always being tricky to get a handle on where they are at or going ona consistent basis. I would say whatever way you look at it the following numbers seem stonkingly good - note i know they are comparing to lockdown numbers but £5.7 mill seems a fantastic 3 month bottom line number "whatever" in the context of £12 mil sales for year just ended - does anyone still keep rolling 3 monthly sales tables for this company or have a handle on what normal % split is for q1 compared to year total? . Ok they have probably hit a total sweet spot with their customers coming out of lockdown and the summer approaching and there haveing been 12 monthsn plus waiting to buy sum summer fun outfits but nontheless q1 numbers look so good "it gives one hope" - still happy to be on the sidelines though i must say.
Q1 2022 was a record quarter for revenue with each month improving sequentially:
o Revenue of £5.7m up 256% against Q1 FY21 (lockdown period last year)
o Q1 increased 45% against Q4 driven by very strong sales of spring summer product from early in the season
o Versus Q4 FY21, both new and repeat orders increased by 40%
· Active customers increased by 23% on Q4 FY21
Note these stonkingly good q1 numbers should be taken in the context that sales this year are expected to double from 12 mill to 24 mill. Previously i did kinda have the "24 mill" number as having a bit of a jackanory look to it (unless they raised more cash). Certainly if they hit £24 mill this year and eak into profit the company will IMHO start to justify its current shareprice.
RE ''..note I know they are comparing to lockdown numbers but £5.7 mill seems a fantastic 3 month bottom line number "whatever" - it's a top line number actually.
yep, agree rmillaree.
£5.7m for Q1 is very strong, I am blown away by that and very surprised the share price has not reacted a lot more positively.
I believe Q1 is usually a quiet period of their year although perhaps less so this year as re-opening has led to a refresh of wardrobes perhaps?
But it does lend weight to analyst forecasts of £24m revenue for the year. In fact I'd say it makes that forecast number look a bit light to me. Christmas quarter is usually about double - I may have my maths wrong here so if anyone has better analysis please feel free to correct me, but I am now expecting circa £28-30m for the full year and a breakthrough into profits and positive cashflow.
Like you I was a bit circumspect at the forecast growth given historic performance but this has woken me up a bit. As Paul says, if nothing else it proves the business model is good and profitability can be reached.
Ken:
Re repeat orders - that's not a percentage but a rate. I.e. I take that to mean the average customer is making two orders now. Off the top of my head I am not sure how that compares to other online retailers but that doesn't sound negative?
Agree that number of active customers could have grown more but they cut their marketing budget this year.
What matters for me today is Q1 and the revenue increase looks very promising.
I don't hold but Q1 has sparked my interest and I might buy today.
Patrick L
Good point re those repeat order figures. When I posted I had only had a quick glance the figures and was just quoting direct from them.
AND. I’ve just seen Paul’s very reassuring summary too.
On Sosandar (LON:SOS) the stand-out from the update for me was the fact that revenues are increasing every month in Q1 (Apr-Jun). Which is different to £ASOS who warned that they saw softening of sales in June.
So I take it that they have a winning product portfolio, marketing, and target market demand. Sweet spot.
Plus the fact that they've been able to deliver such a high growth rate with prior constrained inventory and working capital.... and now they've raised more to ramp up their Autumn/Winter stock, we could be in for a massive revenue growth in FY22. Supply is no longer then constraint, as it was in H2 FY21.
(I Hold).
Sosandar (LON:SOS) (no position)
---
Does anyone know how the Next + John Lewis sales are being accounted for in Sosandar's accounts?
From memory Next (LON:NXT) (I hold) charge a 16% platform fee. Is this simply deducted from revenues? Or is it added to Costs of Sale?
In both cases I would have expected a marked decline in Gross Margins, but that doesn't seemed to have happened.
Given the 25% decrease in Administrative Expenses, it doesn't seem like this 16% Next charge is here either.
Where is it?
---
Positively the returns rate decrease seems quite impressive. My own quick check shows a decrease from 48% to 36.1%, whilst officially it's gone from 50% to 43%.
Impressive it if can be maintained.
---
One last point.
Next + John Lewis sales started in August 2020, so I imagine a lot of the growth in recent months is coming from comparison vs a time when these channels were not being used.
It will be interesting to see how Year-On-Year sales compare from August 2021 onwards.
Cheers
A
On topic of John Lewis / Next - the range being stocked is actually quite extensive. See John Lewis website for example with 350+ products: https://www.johnlewis.com/sear...
Positive TU from Sanderson Design (LON:SDG) (I hold) ahead of their AGM today. I was impressed by the turnaround detailed in Paul's bullet point summary on PI World recently.
Morning Paul, fantastic commentary this morning. I must admit I have been one to panic in the past, but feel that I am a little wiser now. Thanks for all the hard work and that little bit extra that you do. If you get chance can you please look at Supreme (LON:SUP) ( I hold), looks like strong results today.
Saying it like it is Paul; the lone voice of reason when all around us panic. Great preamble - thanks.
Great Begbies Traynor (LON:BEG) update today. Highly cash generative, moved from debt to net cash for the first time in spite of multiple acquisitions. This is all before government support has been withdrawn, so the prospects for this business look great as a counter cyclical. The dividend increase shows great confidence from the management also.
For me Begbies Traynor (LON:BEG) is in a sweet spot at the moment.
Even if V-shaped recovery is real, lots of continued gov subsidy and zombie companies survive, it'll still deliver a good increase in profit this year, and be sub-15x PE. I think the current broker forecasts for FY22 are achievable even if insolvencies don't escalate. Contribution from new acquisitions as well as stripping out overlapping costs will drive this year's forecasted profits. In this scenario, I think it really should be trading at around 160-180p range.
But if insolvencies do escalate, then that's where we could see a >200p share price. And there are many scenarios that will enable this - Brexit causing long term damage, lack of labour and increase in labour costs, component shortages, inflation of raw material prices, strong pound making exports difficult. I'd be very surprised if we don't see a double digit increase of insolvency business over the next 12 months.
(I hold)
lots of common sense there Paul. The last paragraph in particular.
Brilliant preamble today Paul, one of the best things you've written and a vital sense-check in these turbulent times.
Keep up the good work & take care.
My morning smallcap tweet: 22 companies covered
Midwich (LON:MIDW) Induction Healthcare (LON:INHC) Maestrano (LON:MNO) Sanderson (LON:SND) NAHL (LON:NAH) Corero Network Security (LON:CNS) Insig Ai (LON:INSG) A G Barr (LON:BAG) Virgin Wines UK (LON:VINO) Wilmington (LON:WIL) Boku Inc (LON:BOKU) Eurocell (LON:ECEL) Arena Events (LON:ARE) Audioboom (LON:BOOM), Wise (LON:WISE), Dianomi (LON:DNM), 600 (LON:SIXH), Kape Technologies (LON:KAPE), Alliance Pharma (LON:APH), Fireangel Safety Technology (LON:FA.), Cloudcall (LON:CALL), SDI (LON:SDI)
Midwich (MIDW) guides FY(Dec) rev and profit comfortably ahead of the top end of analyst expectations (£742.5-791.6m and £21.3-23.2m) after strong H1. [SP=526 Cap=467m]
Induction Healthcare (INHC) NHS Wales has renewed its existing contract with Attend Anywhere with an update and expansion of its current scope. Worth £1.6m with £1.2m this FY. [SP=68 Cap=63m]
Maestrano (MNO) contracts worth AUS$218k in Australia. [SP=10.5 Cap=18m]
Sanderson Design Group (SND) AGM stmt: guides H1(July) ahead of mgmt exp after strong performances from manufacturing, the Morris & Co brand and the US. [SP=NA Cap=NA]
NAHL (NAH) guides H1(June) rev down 3% but pretax £0.6m (-£0.4m). "Whilst encouraged by both businesses experiencing improving trends in volumes, the Board remains cautious about the rising levels of COVID-19 infections and the impact of any additional restrictions." [SP=45 Cap=21m]. I hold.
Corero Network Security (CNS) guides H1(June) rev 34% and order intake up 13%. In line? [SP=11 Cap=54m]
Insig (INSG) SaaS contract for Insig AI's proprietary Data Tool.to an alternative investment manager. [SP=66.15 Cap=68m]
AG Barr (BAG) guides FY(Jan) ahead of expectations (whose?) with pretax slightly ahead of 2021. [SP=527 Cap=590m]
Virgin Wines UK (VINO) guids FY(June) rev and EBITDA marginally higher than previous expectations of £73m and £6.3m. [SP=199.5 Cap=111m]
Wilmington (WIL) guides FY(June) rev, adj pretax and net debt ahead of expectations (whose?). Net debt down £10m at £17.7m. [SP=210 Cap=184m]
Boku (BOKU) guides FY(Dec) ahead of expectations (whose?). H1 rev up 37% and adj EBITDA up 50%. "Our Identity division performed strongly returning to growth with revenues up 30% in the first half and further reduced EBITDA losses. We are particularly encouraged by the growth in revenues from new products to new customers, primarily in Asia." [SP=163.02 Cap=482m]
Eurocell (ECEL) guides FY(Dec) ahead of market expectations (quotes f/c pretax £22.8m). H1 LFL rev up 21% on 2019. [SP=264.6 Cap=296m]
Arena Events (ARE) wins multi-million pound contract for the 2022 Commonwealth Games. Most of the rev will be booked in FY23. [SP=15 Cap=49m]
Audioboom (BOOM) Hq(June) rev up 93% and pretax -$460k (-$2m). Does not mention yesterday's approach from All Active Asset Capital. [SP=921 Cap=145m]
In line: Wise (LON:WISE) Dianomi (LON:DNM) 600 (LON:SIXH) Kape Technologies (LON:KAPE) Alliance Pharma (LON:APH) Fireangel Safety Technology (LON:FA.) Cloudcall (LON:CALL) SDI (LON:SDI)
Positive final results from Sdi (LON:SDI) today. From what I can see there is nothing we didn't already know.
I think Paul highlighted the unknown is the one of Covid impact and how much of the income and profit is sustainable.
They are cash generative, debt is reduced and they remain focussed on further acquisitions.
This remains a long term hold for me. I think some of you term it a coffee can share? I intend to hold for a long time.
Positive update from Sosandar (LON:SOS) this morning!
Apparently. Cowardly reporting though, using 2020 as the comparator !
I am not sure I understand what you mean? 2020 is the right comparator surely? We're now in FY22 for Sosandar (LON:SOS)
Really not. As Sosandar (LON:SOS) is an online only company, outperforming against last Apr-Jun q1 (full lockdown, no retail stores open) is impressive.
The Q1 figure looks amazing - it's already higher than the whole of H1 last year and 45% up against Q4. And this might now avoid another fundraising with £9.1m cash at 30 June. This has piqued my interest and I might buy on this update.
Would appreciate a look at £SUP
Paul , great common sense from you. I expect many of us know someone who is forever in a panic if their particular share falls a little ! My advice is always , get used to it because the market goes up AND down OR dont invest if it bothers you that much ( you are saying similar ).
Todays sell off brought many good businesses back into what I'd consider good risk/reward prices
Not quite full blown panic yet but we may get there soon. The psychology of the market is endlessly fascinating.