Small Cap Value Report (Tue 20 Sept 2022) - G4M, JIM, STEM, APP, EVE

Good morning from Paul & Graham.
Agenda -
Paul's Section:
Gear4music Holdings (LON:G4M) - a mild profit warning was reported on 9 Sept 2022, which I belatedly look at today. Profits from the pandemic boom have largely evaporated now, so maybe the market's brutality towards the share price is justified? It's looking good value to me now, if you can cope with the increased debt.
SThree (LON:STEM) - it's another positive update, ahead of expectations. This remains a firm favourite value share for me. The outlook sounds a little more cautious though, hardly surprising given macro conditions. Strong balance sheet, nice divis, and a low PER. Should be fine long-term, even if we see possibly tougher conditions in 2023.
Graham's Section:
Jarvis Securities (LON:JIM) (£42m) - a bombshell RNS on Friday afternoon resulted in JIM’s shares selling off by almost 50%. Something has prompted the FCA to intervene and to require JIM to hire regulatory consultants at its trading subsidiary. In addition, this subsidiary won’t be able to pay dividends to Jarvis or engage new clients without the FCA’s consent, and this will have some real (albeit hopefully limited) impacts on both the business and ultimately on Jarvis shareholders. Only insiders will know the nature of the investigations and whether or not Jarvis is guilty of any regulatory breaches. While I can’t rule out the possibility of very serious problems (and the market hates this sort of uncertainty), I would view the shares as underpriced on the basis of my opinion that most companies emerge from these reviews with their reputations intact and/or with fines which don’t break the bank and allow them to continue trading.
Appreciate (LON:APP) (£47m) (+2.7%) [no section below] - this Liverpool-based gift voucher provider publishes a trading update for its AGM. Trading is in line with expectations. With actions taken to emphasise profitability in the consumer business, and improve retention levels in the corporate business, it is set up “strongly” for the key Christmas period. The company thinks that seasonality might be even higher this year as both individuals and businesses adjust their budgets. I guess this reflects broad restraints on discretionary spending, apart from Christmas gifts. The company is currently looking for both a permanent CEO and a permanent CFO. The former CEO Ian O’Doherty oversaw some disappointing years for Appreciate, obviously not helped by Covid, and the company needs to be reinvigorated. I continue to find it interesting as a possible value investment, and the StockRanks share my interest with a StockRank of 93, and a ValueRank of 87. The market is rightly pleased to see it performing fine despite the lack of leadership at the top. [no section below]
eve Sleep (LON:EVE) (£1m) (-36%) [no section below] - the fat lady has had a glass of water, has cleared her throat, and is about to start singing. Eve Sleep reports another underlying EBITDA loss for H1, worse than last year, on declining revenues. As of 31st August, the mattress company had cash left of just £1m after drawing £0.7m from a borrowing facility. Big ticket items are being hit hard as consumer confidence reaches arguably its lowest ever level, and eve Sleep - an unprofitable, speculative business even in the best of times - is the type of company that goes bust in this environment. Great efforts have been made to cut costs and the CEO argues that there is now a “greatly reduced breakeven point”, for whoever is willing to continue funding its expansion plans. Unfortunately, the formal sales process has not yet resulted in any firm offers, and more funding will be needed in October. Without new funds or a firm offer, “the Board will take the appropriate steps to preserve value for creditors”, which will presumably involve the company going into administration. I can’t imagine that the existing equity is worth anything here - future plans are likely to be determined in talks between administrators and new investors.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul’s Section:
Gear4music Holdings (LON:G4M)
112p (last week’s close)
Market cap £24m
Gear4music (Holdings) plc, ('Gear4music' or 'the Group') (LSE: G4M), the UK's largest retailer of musical instruments and music equipment…
This update came out on 9 Sept 2022, and updates us on progress so far, for FY 3/2023.
"As previously reported, we were expecting inflationary pressures to restrict operating margins during FY23, and despite the weaker consumer environment we are pleased to have achieved sales growth during Q1. Trading during July and August has, however, been further impacted by the widely reported cost of living crisis and unusually hot weather across Europe.
We expected a return to a more normalised seasonal trading pattern during FY23 with less demand during summer months than winter months, and early indications are that trading has improved in September. However, given the lack of visibility over the timing of any improvement in consumer sentiment and wider macroeconomic conditions as we approach H2, we believe it is now prudent to moderate our full year expectations accordingly.*
We now expect FY23 revenue to grow to approximately £155 million with EBITDA of £9m. In line with our stated strategy the Group will continue to focus on delivering profitable growth as its first priority.
Our pipeline of growth orientated projects, including AV.com, continues to make good progress, and we are seeing strong results following last year's investment into our new European distribution hubs. We remain well funded and profitable and the Board retains its confidence in our medium and longer-term profitable growth strategy.
* Gear4music believes that consensus market expectations for the year ending 31 March 2023 prior to release of this announcement were revenues of £163.9 million and EBITDA of £11.9 million.
That doesn't sound a disaster by any means, and seems a sensible trimming of current year expectations, given that consumers are generally being more cautious.
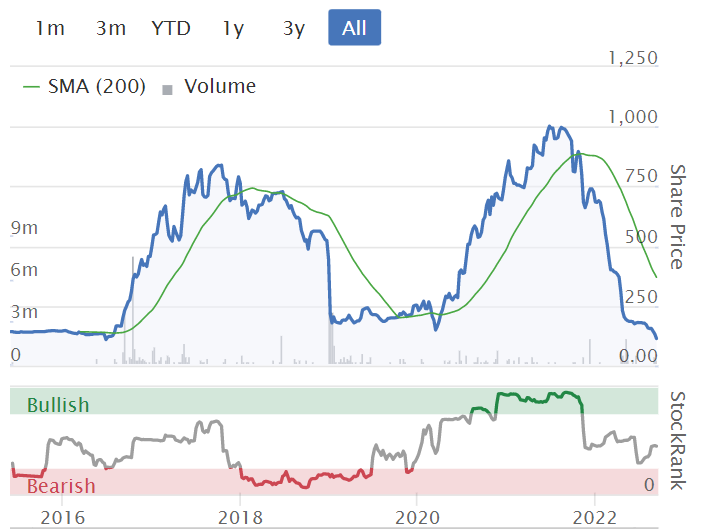
But just look at what the share price has already anticipated, which seems quite extreme -
.
This share is a really good example of why I’m seriously questioning the wisdom of a long-term buy & hold strategy with small caps.
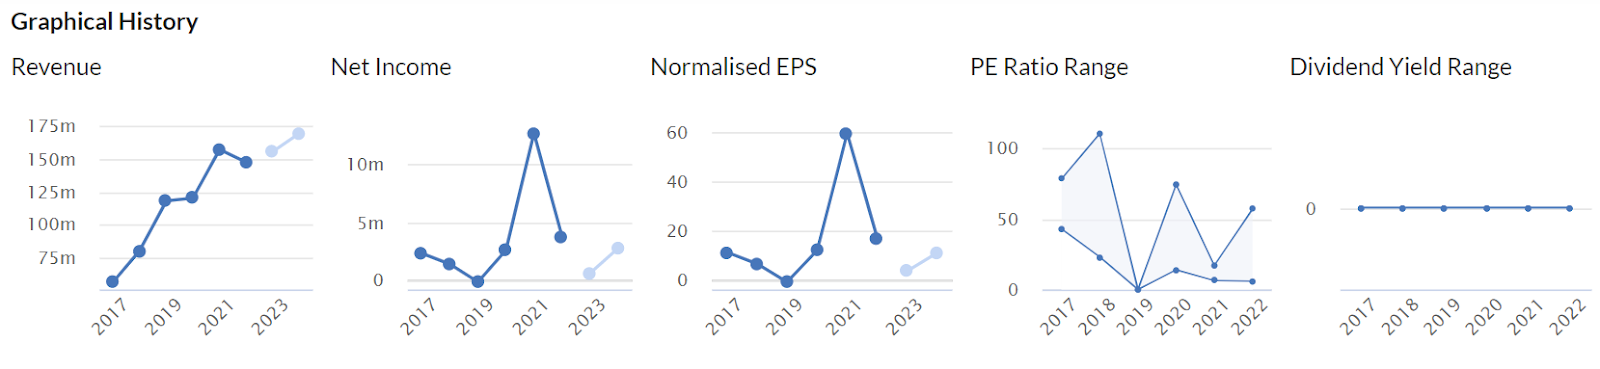
The Stockopedia historical graphs, as usual, encapsulate things so well - very good revenue growth, a rollercoaster ride of profitability as the pandemic boom came & went, wild variations in stock market sentiment on valuation, and no dividends (as it’s a growth company).
.
Valuation - I don’t like the focus on reporting EBITDA, because as with many companies, it’s not a meaningful number here in the real world (or as close to it as I get, anyway!).
Adj EBITDA of £9.0m (the latest company guidance) is only adj PBT of £1.3m, per the latest Singers forecasts (with my thanks), a large gap.
Balance sheet - so important these days, as economies slow, and bank managers get more nervous. Looking back at the FY 3/2022 balance sheet, the most noticeable things are a big increase in inventories, and increased gross long-term bank debt - to fund acquisitions. That could make some investors nervous in these trickier times.
However, the good thing about eCommerce businesses, is that most costs are variable, not fixed. So if G4M were to run into cashflow problems, it could run down inventories (which don’t perish, and are not subject to fashion risk), and slash marketing spend if required.
For that reason, I’m not ringing the alarm bells over balance sheet or cashflow.
My opinion - eCommerce is such a difficult sector at the moment. I’ve been waiting for a sector recovery, but there’s no sign of it so far, and given that we’re now in mid-late September, then it looks like a duff theme for 2022. But who knows, sentiment can turn on a dime, and things are not driven by arbitrary dates like year ends.
Is the current share price oversold? That depends on your longer-term view. Looking at the shorter term, this time last year, brokers expected G4M to generate about 40p in EPS for FY 3/2023. Current forecasts are only about one tenth of that. It’s such a reminder that profits are operationally geared, and it doesn’t take that much of a movement in revenues and margins, to make profits collapse - a lesson that I continuously forget in bull markets, and then have to re-learn again, every time there’s a bear market.
With G4M, I’m confident that management is committed & capable. I’d rather it hadn’t taken on more bank debt recently, but it looks OK given that inventories are higher than gross bank debt, so could be run down (inventories were deliberately increased, to improve availability of a very big range of products, given supply chain issues). It strikes me as nowhere near a crisis liquidity or gearing situation.
Overall then, the £24m market cap looks a potentially nice entry point, for investors who are prepared to take some risk. So it remains on my watch list.
.
SThree (LON:STEM)
366p (up 5% at 08:23)
Market cap £491m
SThree plc ("SThree" or the "Group"), the only global pure-play specialist staffing business focused on Science, Technology, Engineering and Mathematics (‘STEM’) skills, is pleased to issue a trading update covering the period 1 June 2022 to 31 August 2022.
STEM has a year end of 11/2022.
Headline - looks good -
Full year profit performance expected to be ahead of consensus
The Board now expects that profit before tax for the 12 months to 30 November 2022 will be at least 7% ahead of market consensus(3)
(3) Current consensus PBT expectation is £71.2m for FY22. Source: SThree compiled consensus.
There’s lots of additional detail in the announcement, but the key point is that Q3 net fee income was strongly up at +19% - even more impressive as it’s said to be against a strong prior year comparative.
Net cash is a healthy £57m as at end August 2022.
Visibility looks good -
- "Contractor order book(2) up 24% YoY, underpinning continued confidence in our full year performance"
The only slight negative I can see, is that it sounds as if staff are being over-worked (see clarification below) -
- "As previously guided, we expect productivity to remain above pre-pandemic levels, though it will reduce from the current exceptional levels over time, as the Group’s headcount grows."
"Good progress has also been made in the execution of our wider strategy, with the investment in our people, talent acquisition and digital infrastructure moving forward as planned. This investment is designed to underpin our long-term success, with costs starting to be incurred in Q3 as previously indicated.
Whilst we remain mindful of the macro-economic uncertainty across global markets, with all developments and lead indicators of the Group’s performance monitored closely, our strong market position underpins our confidence in the medium to long-term future of the Group.”
My opinion - this is the latest in a series of impressive updates from STEM. Although maybe the outlook comments are starting to sound a little more cautious? Hardly surprising, given the grim macro outlook.
It looks as if STEM should be heading for about 40p EPS this year, hence its shares are only priced on a PER of 9, despite it operating in what seems a resilient niche.
There’s a decent divi yield, and strong balance sheet too. Obviously we don’t know if, or when a downturn might come, but this business looks a quality outfit that should be fine longer term.
EDIT: the company's advisers contacted me after the above was published, and wanted to clarify over my point above saying that it sounded like staff are overworked. They said it's more about expansion, and taking on new consultants, who take a bit of time to gradually build up to peak productivity. Rather than existing people being overworked. That makes sense to me, so am happy to clarify this point. End of edit.
Graham’s Section:
Jarvis Securities (LON:JIM)
Share price: 94p (-49% on Friday)
Market cap: £42m
Commiserations to holders of this one, who saw the share price collapse by 49% on Friday afternoon.
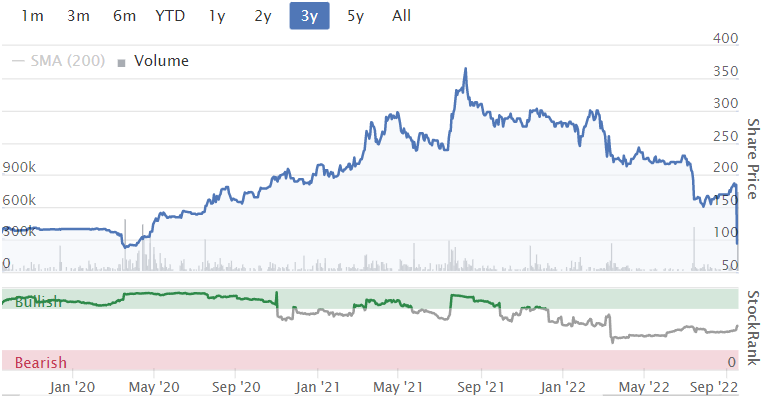
At 2.39pm, just before the long weekend, it published a “Company Update”:
The facts
Jarvis have hired the regulatory consultants Ocreus Group to review the systems and controls at Jarvis Investment Management Limited (JIML).
(JIML is the trading company, while Jarvis or JIM is the holding company. I hope that’s not confusing!)
In simple words, the FCA has ordered this review. Here is some background reading on the relevant legislation:
Under section 166 of the Financial Services and Markets Act – known as s166 – the regulator has the power to require a firm to appoint a ‘Skilled Person’ to produce a report on specified matters or to appoint a skilled person directly. This could be, for example, a review of past business in a particular area or sales of a particular product; a review of a firm’s compliance with the client money and asset rules; or a review of a firm’s systems and controls.
In addition, JIML has “voluntarily” agreed to restrictions with the FCA (although I doubt they had much of a choice).
The restrictions include:
1) not taking on new clients at JIML’s “Model B” service without the FCA’s consent, until Ocreus has provided assurance re: JIML’s systems and controls.
2) JIML can’t pay dividends to its holding company Jarvis without the FCA’s consent.
Jarvis provide the following brief comment:
The outcome of the Skilled Person's review is not yet known but, in the meantime, the restrictions should have a limited impact on JIML's forecasted revenue and profitability as anticipated new business from Model B clients is not reflected or built into the published forecast. The additional professional fees and associated costs, and the asset restriction, however mean dividends payable to the Company (and therefore dividends payable by the Company) may be reduced and/or delayed pending FCA approval. JIML will continue to work with the Skilled Person and FCA with the aim of having the restrictions lifted as soon as possible.
My view
Despite the RNS only being a few paragraphs in length, it torpedoed the Jarvis market cap and leaves us with much to ponder.
Let’s first assume that the problems are not serious. What costs would Jarvis and its shareholders face?
- Professional fees - Ocreus will not be cheap. Perhaps a few million will be spent on the review, which could take up to six months.
- Revenue - even though “Model B” clients were not expected to grow to any meaningful extent, this is one source of revenue growth which has been cut off.
- Reputational - this would be unfair, but the perceptions associated with an FCA review might have an impact on future business at JIML’s Model B service (in case you’re wondering, “Model B” refers to outsourced settlement and custody services).
My view is that if the problems are not serious, then Jarvis is today worth almost the same as it was worth last week, before we knew about the possible existence of regulatory problems and the FCA review.
However, the share price was knocked lower by 50%. From the simple point of view of implied probabilities, it seems to me as if the market was pricing in an almost 50% chance that these problems were going to utterly ruin Jarvis as an investment.
Of course, the problems might be serious and could, in a worst case scenario, lead to large fines and other serious consequences that could indeed be ruinous.
While of course I agree that Jarvis shares should have been marked down on Friday, I can’t get on board with a 50% markdown. In many cases, won’t a Skilled Person review lead to little more than a slap on the wrist?
We are in a horrible market for any stock that has a regulatory problem, a profit warning, or faces uncertainty. On Friday afternoon, Jarvis went from a stock which had none of these problems to a stock which had all of them.
From that point of view, it’s understandable that many people will have rushed for the exits. In the fullness of time, they might be proven correct as the issues, whatever they are, may turn out to be very serious.
However, I do believe that the 50% markdown was premature, on the basis that many companies emerge from reviews such as this with their reputations intact and even if fines are imposed, they are often far from ruinous. But of course we can only speculate as to what issues might currently be under investigation at Jarvis.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

29 comments
Disappointing news about Jarvis.Out of the public listed UK Stoockbrokers feel they are the most customer friendly.Their X-O has very low charges while the last time i looked Jarvis still offered a service to sell shares held in a share certificate
Re SThree (LON:STEM)
The only slight negative I can see, is that it sounds as if staff are being over-worked -
Hi Paul. That's not how I interpreted the comment. I feel it's more an observation on the current mix of employees, where they must have a high proportion of experienced and productive consultants who are very happy with their bonuses! That mix is in the process of dilution by a cohort of new recruits who will be considerably less productive as a group - indeed many will fall by the wayside as a sunk cost - and whose training will itself mildly affect the productivity of experienced hires called upon to mentor them. In due course, some will become highly productive. It's the normal cycle of life in a recruitment firm.
As for the share price, I can't see that recovering until the fear or actuality of a recession in Europe, let alone the US, subsides. Good company in a market with consistent, secular growth, performing well. And cheap. What's not to like?
Thank you for your comments on Jarvis Securities Graham, we hold and my timing couldn't have been worse adding to our modest holding recently . I should have had the gonads to have bought more first thing today as I agree with the more optimistic side of your observations while noting the worst outcomes.
You're welcome, JASVFS - good luck! G
If it's any help there was an FCA investigation at H & T (LON:HAT) a while back, which weighed on the share price and seemed to drag on for ages, but was eventually resolved and share price has since been really strong.
The update from Appreciate (LON:APP) today was nothing special, and I think holders have alot to chew on in terms of the short term prospects.
On the one hand, the next few months is seasonally the critical bit for the business, just when there's going to be an inflation and consumer spending squeeze storm. They are very dependent on Corporates buying vouchers to drive the out-turn for the year.
On the other hand, it is trading at a stunning valuation. Only 5-6x current year PE, over 8% dividend yield (and well covered over 2x), with a huge cash pile as well, making up a substantial chunk of market cap.
My view is that there will be three macro factors that make Appreciate severely undervalued. I was disappointed that none of the three were mentioned in the update today, maybe I am barking up the wrong tree?
However, we are only likely to get all this detail in January, after the key trading period at the end of the year, which is a long hold from now. So definitely a share that will only realise it's value in 2023, rather than 2022. I continue to hold, as in the meantime I'm being compensated with a 8%+ dividend yield, and a current SP that is well underpinned by NTAV.
(I hold in The Boon Fund).
Under Housing Shares, In your Boon Fund, I suspect you refer to Harworth (LON:HWG) and not £HWT whoever they are.
Interesting read. Keep it up.
Thanks for the heads up! I'll get that fixed in my article later today.
Is there any plan to look at Unbound (LON:UBG) today? Mkt cap might be too low now though. Interims out this morning. Work is stopping me from having a look and coming up with an opinion. Forecast for 3p EPS at full year according to the Stockreport, and an 11p share price, something is wrong. I'm hoping the price, not the forecast!
Had a chance to skim the management statements. Seems todays update represents a profit warning compared to the StockReport forecasts, with a loss between 0 and £1m, so between 0 and -1.5p (65 million shares in issue).
Re Unbound (LON:UBG) – H1 results this morning are interesting. H1 revenue (ie Jan-July) is up 10% mostly from retail store recovery with online flat (+2% vs PY). Online was 75% of the total sales.
Gross margins are high and up at 63%, reflecting lower shipping costs and some other cost-saving efforts plus price rises ahead of costs. Genuine online KPI’s are shared for the first time in a similar fashion to other online businesses. This shows such metrics as 3.4% conversion, £64.17 ave order size and 619K number of active customers. These seem OK but not brilliant to me vs online peers but are now at least clear and relevant so we can see progress.
What is grating is the blurb about the strategy and new online trading website (I refuse to call it a platform as the model and structural advantage is closer to an eBay reseller). This cost £0.7Mn in H1 in one off set-up costs and no revenue. I could still be happy with this given the aspiration to cross sell with minimal working capital investment to a largely 55+ female market brought into the site seeking “comfort” shoes. Clear strategy and reasonable upfront costs.
However, despite saying is has “unique insight into the 55+ female market”, on looking at the new website today, the allegedly curated and relevant brands mostly seem to be organic bamboo underwear and wasp-waisted leather jackets.
Most of the 55+ ladies I play tennis with – ie absolutely target market for Unbound (LON:UBG) - will not be buying this sort of stuff, I suspect. Whilst I do see Goretex shoes and other more relevant brands as well, the business has a long way to go to prove to me the website diversification is going to succeed unless it has a far more relevant and broader range of complementary products. In other words, the strategic opportunity is there but the execution is not – let’s hope the other barnds are coming on board fast!.
Some other, more financial matters included: reference to selling off Hostmore shares (at a lost to book) and selling other assets to raise cash, plus of course the £3.1Mn equity raise post H1 end. Given good inventory stock levels (said to be a rebuild from low base last year due to supply chain issues), cash should be OK going forward if sales continue to come through as now - but not much margin if sales turn down, I would say.
Taken as a whole, I think the business is very under-valued at the current price but also risky - I am not convinced by the CEO. The CFO has just left (to similar sized Science in Sport) so he was probably either pushed or shared my view. Neither reflect well on the CFO.
Net, given we face a tough year economically and how small caps have cratered of late, I understand why the share price for a new listing is where it is. Personally, I think will be one of those that rewards the brave (perhaps under a new CEO in 12M time or via a takeover) so I continue to hold some. As ever, we will see.
Nice write up.
The thing that worries me about the "platform", on top of your points, is the completely unmemorable name that is likely to get confused by a company that does book binding(!) and the complete lack of marketing for it with no mention of marketing costs going forward. It's starting to seem to me like the CEO and CFO decided they'd give themselves a couple of years of a hobby with decent salaries, having cashed in the major cash from the ELTA wind down, as they contemplate retirement. That might be harsh, I don't know them and haven't met them, but the fact that the CFO has scarpered already with them having a big net debt and having to need to tap the market for funding so soon after "float" doesn't look good.
Absolutely agree - Unbound (LON:UBG) is a good code name for a project that makes sense from the inside looking out ie as a corporate, but not the outside looking in ie as a consumer. They even have the dead weight of group in the website name https://www.unboundgroup.co.uk...
I've only seen the CEO on a video presentation, Again pure prejudice and assumption on my part but I recall he has a trendy man bun - nothing wrong with this per se but it aggravated the impression I had that I really did not see him connecting with his target market. Too flash. Similarly, it would have been so much simpler to build on the established Hotter shoes name.
As PE manager, I like the turnaround he has achieved. As standalone business leader......we will see but I doubt he will see in 2024 still in charge.
buy and hold or don't... ...has been on my mind and probably many others over the last few months.
in essence (from what I understand) the model here in the scvr is you buy a small cap share that looks to be good value and hold until it until the investment case fails or you see a much better opportunity elsewhere. Personally I like this model.
But it is not for everyone. That something is of value today does not mean the sp cannot drop by another 50% over the next month.
Capital preservation just isnt in the model. This is fine if your time is infinite. Mine is not. There is a conflict there.
I have started to use a checklist based approach to selling (outside profit warnings) and it works to the extent that when I break the rules I usually lose. The essence of my rules are essentially momentum based but small caps are volatile by nature and I suspect my rules are 'right' because the entire market has been down trending.
Other people (chris dillow and ed shing) have proposed very simple index based rules like if the index is below the 200d ma, sell. But their model is that you are holding a tracker and the cost of trading is v. small.
The only firm conclusion I can gather is that investing in small caps is messy and there are no 'right' answers.
However if someone can suggest something less wrong, it would be gratefully received.
Hi Andrew
I know that Ed has done a book "The Idle Investor" set on a basic simple model process using momentum with four levels. Interesting read and some useful ideas came from it at the time. So there will always be a link to that theme within his writing. It will work for some and not for others. I guess my active company pension is something on these lines, I buy units every month and do nothing. Similar with the kids JISA's, just deposit every month and do nothing. Not wrong, not right, just the right things for these particular times for those particular investments.
I would concur with the process of what is my model, checklist, process. There is no right or wrong. I keep an open mind and do look back and see if there are things that could be better and update it. Some of the challenges are time related, so I don't always get access during trading hours, so always good to read a profit warning two days later and you are down 40%, but sometimes that does save the spike down and up again.
Simple parts are, I can understand what it is the company actual does to make money, it makes a profit, the forecasts are level up upward trajectory, dividend if paid is well covered, not excessive debt etcetera.
I find that emotion is wrong about 90% of the time, and when I look it is missing items that I would normally require for a buy, sometimes FOMO and sometimes boredom, other times short of time and instead of finishing the research pressing "buy" too early, probably both FOMO/Boredom combined.
I will admit that the one thing that I am trying to get better on, lesson from 2020, is what are the hold or sell rules. So profit warning is one, just sell and add back to the watchlist with a note in my pad to why and when sold. The other is absolute loss from initial purchase, with a current amendment of loss from peak.
For the current conditions I am doing a "sleep at night" strategy, so I am largely cash across the three main portfolios that I manage (mine and sisters future life, and mum's pension (all held in ISA). I have been selling on a defined drop, either absolute from entry or from a peak. This is about capital retention. I have been taking small/starter positions in what I feel are good companies on the basis that I cannot predict the bottom, but some of these are doing ok, and obviously some have been sold as they go down beyond the defined stop. It can be painful but it is a process. Mum's is slightly different as it is about income, so again rules on capital but looking at level of income, confidence of future earnings, level of cover, level of debt.
The only part that needs a real polish, probably not in the current market, is what my target or sell price is, so what I think is value and what I think is time to move on as it is overpriced. Would be a nice problem this month! Actually this last year, I think that the only one was British American Tobacco (LON:BATS) and that should have been a hold for the dividend rather than take profit, but we keep learning.
Good look
Tommy!
I would add as a post note, is that currently I am depositing each month as working. Big Sis is capital for the future not required. Mum is income over the state pension to add quality to life and nice days out/holidays, with money for adjustments to the house, supported living and all that some point in the future.
Any thoughts on Moonpig (LON:MOON)? Under £600m market cap so only just too big for these pages.
They've reiterated guidance this morning and seem to be trading well (especially in the current environment). Still dropped over 10%. This market is pretty tough.
Moonpig (LON:MOON) looks over sold to me and can see some short term upside from 180p. Its a punchy P/E but they have control of pricing so can't see the inline update is any sort of -10% bad News.
Opened a small position with a tight stop.
Litigation Capital Management (LON:LIT) full year results 2022released today. Here's a short overview video and podcast.
They are transitioning to an asset management company with Fund 1 fully committed and two thrids of the targeted US$300m raised for Fund 2 with commitments commenced.
There's a management webinar at 11am today (29.9.22) register here.
Stuart Morgan, Director of IR at Capita (LON:CPI) will present at a webinar for investors on at 12pm today. Stuart will update on performance in the first half and talk about the outlook for the second half of the year.
In the HY results which were released on 5 August, the company reiterated that they were making material progress in their strategy to build a more focussed and sustainable business.
The balance sheet continues to be strengthened through asset disposals and only last week the company announced the sale of Pay360 for £150m. Revenue growth is expected to accelerate in the second half and management is focussed on delivering expectations for FY 22. Hear the investment case for yourself.
Register here
I remember posting that the investor club (what news of that?) seemed to be buying at the top at 900p. (Mind you they sold NBrown #BWNG at the same time for 40p which I thought was the probable bottom). I bought around 180p thinking it was oversold. Holding for a few years now but agree with Paul the volatility is such that you have to try to time both entry and exit, which is tricky. Buy low, sell high. Should be easier than it is!!!
Two contrasting shares that I hold : Gear 4music (Lon :Gear4music Holdings (LON:G4M)) described so eloquently above by Paul ( I am still wiping away the tears ) and SThree (Lon:£Stem). The latter issued a trading Statement today with that wonderful expression "ahead of market consensus :
The share however is still down 40% YOY!!! God knows what will happen on opening today .
Like you I am seriously questioning how I manage my small cap holdings but unfortunately I went in to this particular period with the view that shares (small or otherwise ) were a long tem hold and it would be ok over time . Not sure if we have reached the bottom yet but changing this approach would mean crystallising the losses over the last 12 months and there is no guarantee that any new investments would fare any better than existing ones -after all the reason I hold them in the first place is because I believe they are quality companies .
Mentally very hard at the moment
Totally agree with the Small Cap sentiment expressed here.
P.s. I had already reached the conclusion that on the SCVR the companies talked about are the most volatile Small Caps and doctor dave seems to be on the same wavelength as myself. Buy low, sell high, don't keep for too long or else....
Silver
Cambridge Cognition (LON:COG).
Very pleasing results from this tiny fast growing 'picks and shovels' pharma company.
80% GM
Cash ahead at £8.6m and growing
Profitable
Largest ever order book
Qualified pipeline of sales opportunities
Seems to be well-managed.
Really like picks and shovels as not so dependent approval of drugs.
Nice clear outlook:
"The Company has made a great start to 2022, and has a positive outlook that is not only sustainable but well positioned for further year-on-year growth. The outlook is built on the strength of an attractive contracted order book and a qualified pipeline of opportunities, increasing investment in commercial activities and continued product development, a rising cash balance and supportive shareholder base.
There are possible challenges ahead with inflation increasing across global economies. The Company has limited expenditure on gas and electricity, though is subject to other inflationary pressures. Inflation may also impact on pharmaceutical companies and dampen demand, though we have not seen that at this time and our order book provides the Company with visibility over revenues in the short to medium term.
Cambridge Cognition will continue to grow in this rapidly expanding market by leveraging our validated portfolio of digital assessments, investing in R&D to keep pace with the evolving demands of the industry, investing in opportunities that enhance our product offering and safeguarding our reputation for exceptional customer service."
At one point Matthew Stork CEO said his biggest concern was finding Software developers so pleasing to read:
"Enabling efficient growth by software development in a lower cost country. Having established a subsidiary in a lower cost country, this has expanded our talent pool and we now have an office with more than 10 software developers that will enable the continued development and improvement of our full product set at a lower cost."
I hold
Investegate |Cambridge Cognition Announcements | Cambridge Cognition: Interim Results
Hi Michael and with 20% of the market cap in cash too! Hopefully Paul or Graham will cover these results today.
DH2.
Dieselhead2 Agreed
Great podcast over the weekend Paul - it’s really helpful to hear you look back and reflect on themes and the context of individual updates.