Small Cap Value Report (Tue 21 Feb 2023) - TRI, NMRP, REVB, SPR, FIF

Good morning from Paul & Graham.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Agenda /Summaries

.
Paul’s Section:
Trifast (LON:TRI)
63p (down 32% yesterday)
Market cap £86m
Trading Update & Directorate Change
London, Monday, 20 February 2023: Trifast (LSE: Main Market symbol: TRI) provides the following update on the trading performance for the financial year ending 31 March 2023 ("FY23") and notification of a Directorate change.
This announcement hit the shares very hard (down c.40% in early trades yesterday morning), although there was some partial recovery later yesterday.
Profit warning - adj PBT guidance for FY 3/2023 is reduced from £14.3m to £9.0m. Obviously that’s a disappointment, but the trouble is, it doesn’t take a lot to change, on £243m forecast revenues, for the profit number to change a lot. This is why the PER is quite a bad way to value companies, because profits can be so volatile, depending on circumstances that can't be predicted easily.
What’s gone wrong? The main factor seems to be de-stocking by an Asian customer, which has offset gains made from price rises & cost savings. Higher interest costs on “elevated” net debt of £44m is also mentioned.
What are they doing about it? Another strategic review has been carried out, resulting in cost savings of £5m annualised (it’s not clear if these are new savings, or increased savings from what was originally planned).
The long-standing CEO has stepped down immediately, and been temporarily replaced with a NED.
My opinion - this isn’t a disaster, assuming all the bad news is out. The risk is that a new CEO might kitchen-sink the figures, to get all the bad news out in one go, and to provide a nice platform to demonstrate improved performance thereafter.
The last balance sheet looks pretty good, with almost £100m NTAV, with the market cap below that figure suggesting shares might be cheap. Although inventories of £103.6m now, £102.8m when reported at the last balance sheet date of 30 Sept 2022, are still stubbornly high, and need to come down. The risk is that high inventories often contain obsolete or slow-moving items, which have to be written off. So it seems to me that there’s a fair chance we could have another profit warning from Trifast, to clean up the year end accounts maybe? Although that’s guesswork on my part, so is more a risk than a certainty.
Bank financing doesn’t seem to be a problem, with yesterday’s update confirming it remains within facility limits, and covenants.
Overall then, I don’t see this share as being in a crisis situation. The risk of insolvency or a deeply discounted fundraising strikes me as quite low.
The trouble is, it’s now a fairly low margin business, in a sector that’s probably very competitive. So I’m struggling to see any reason to invest in this share.
It all depends on the extent and timing of a recovery in trading, and whether there’s likely to be another profit warning in the meantime? That’s impossible for me to gauge. I don’t see anything too serious in the profit warning, and with little balance sheet risk, I’ll declare myself as neutral (amber) on this share.
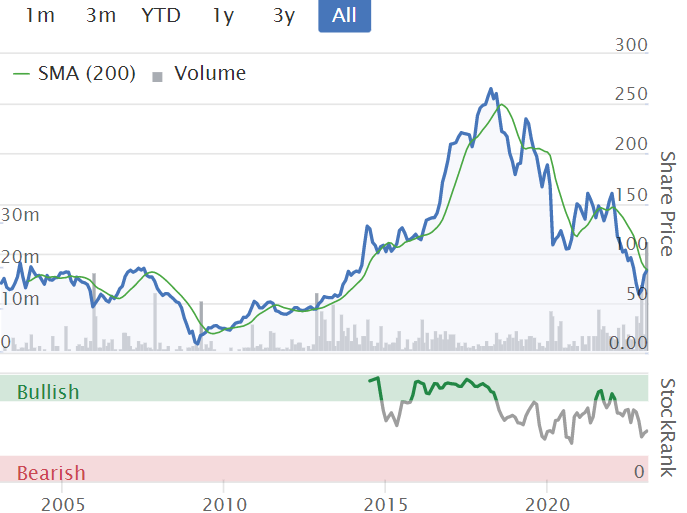
Looking below at the long-term chart, it's interesting to see that the share price has now given up all of the bull run, and is back to a similar price 10 years ago. The share count hasn't risen a huge amount in the last 6 years either, so a recovery in margins could trigger a decent share price recovery.
Finsbury Food (LON:FIF)
97p (down 2% at 09:56)
Market cap £126m
Finsbury Food Group Plc (AIM: FIF), a leading UK speciality bakery manufacturer of cake, bread and morning goods for the retail and foodservice channels, is pleased to announce its unaudited interim results for the six months ended 31 December 2022.
The company gives itself a pat on the back -
Encouraging H1 performance
The context here is that the food industry has been hit hard with cost increases - raw materials, energy, and labour. So for FIF it has been all about managing these cost increases, and passing them on to customers.
Some key numbers for H1 -
Revenues up 15% to £190.9m (the increase has all been due to higher prices, with volumes said to be “broadly flat”)
Operating profit margin is tight, and lower, at 3.4% (H1 LY: 3.9%)
Adj PBT of £4.4m vs £5.0m in H1 LY
Outlook - challenging macro, but on track to meet FY 6/2023 forecasts.
Net bank debt £22.8m, which is only 0.8x annualised EBITDA, which looks fine to me.
Balance sheet looks adequate, with about £35m NTAV
Cashflow - capex, increased working capital, and dividends paid absorbed the cash generated by the business.
Pensions - I didn’t quite understand the note about this, which could have been explained better -
The Group has one Defined Benefit Pension Scheme within its Memory Lane Cakes business in Cardiff. All remaining Group companies have Defined Contribution Schemes. The Memory Lane Cakes pension Scheme has been closed to future accruals and new members since 31 May 2010. The net pension deficit (before related deferred tax) was £6,582,000 at 2 July 2022. The Company entered into an Asset Backed Contribution (ABC) arrangement on 18 May 2022 to improve the funding of the Scheme. An investment of £16.0 million will be invested by the Company to the Scheme, the trustees have purchased a loan note from the Group via a Scottish Limited Partnership (SLP) structure, which will pay a defined income return to the Scheme over 20 years. The fixed repayment plan amounts to an income of £763,000 being paid to the Scheme annually. The estimated duration of the liabilities is around 15 years.
Valuation - it is forecast to make 10.7p EPS this year, so at 97p per share, the PER is 9.1x, a modest rating. Although as noted before, FIF shares always seem to attract quite a low rating.
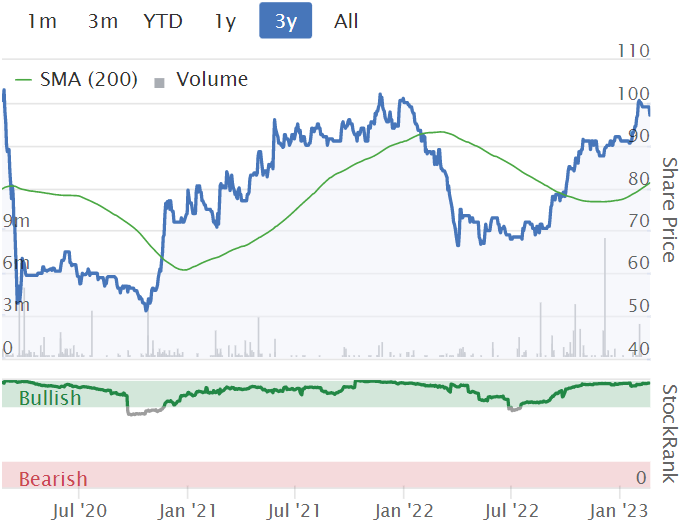
My opinion - the share price has now fully recovered last autumn’s spurious fall, giving a c.50% gain from the lows. So it’s gone from stupidly cheap to just cheapish now. For that reason, I’ll go from green to amber.
It’s still a nice enough business, but the 3.4% operating margin doesn’t leave a lot of margin for error.
One interesting angle on this share, is whether the headwinds of the last year (higher energy, and raw materials) could become a future tailwind, as costs moderate? If so, that would possibly enable FIF to improve its profit margins in future? Given how much cheaper gas prices have become of late, then maybe we should be thinking beyond the energy crisis to what happens next, which might boost profits?
Graham’s Section:
National Milk Records (OFEX:NMRP)
Share price: 120p (-2%)
Market cap: £25m
This is one of the few Aquis-listed stocks (not AIM) I like to report on, because I have the impression that it’s a high-quality business.
It’s an information services provider to the UK dairy industry, whose customers include farmers, vets and milk buyers. Milk recording, milk testing and disease tests are the flagship categories. About 50% of the UK herd is tested by NMRP.
Here are the H1 highlights for the period to December 2022:
Turnover plus 5% to £12m
PBT plus 5.3% to £0.79m
Net debt reduces slightly to £0.9m
Net assets plus 30% to £9.3m
Comment from the FD:
"The results for the first half of the financial year show a solid performance year on year, albeit with EBITDA held back by the differing accounting treatment for vehicles not under finance leases, reorganisation costs for consolidating milk testing at our Four Ashes laboratory, and our investment in the opportunity for GenoCells in the US. On a like-for-like basis, EBITDA was approximately £290,000 higher, representing a year on year increase of 17%. At this level of analysis, the figures continue to demonstrate sustainable growth in revenues and earnings, in line with our medium term growth ambitions. In addition, the Group has increased its capital investment, whilst also reducing net debt and paying an increased full year dividend.
As I mentioned previously, NMRP is currently investing in a genomic testing service. The financial return it will make on this is unknowable, but I think it’s important to mention when there is a “wild card” attached to a stable, profitable business. This genomic technology, called “Genocells”, is to be launched in both the UK and the US later this year, with the aim of enabling farmers to manage mastitis in their herd more efficiently.
Management - the MD is currently undergoing medical treatment, and the FD has operational control on an interim basis.
Outlook
Some familiar inflation themes in the outlook statement:
Cost input inflation is “significant”; NMRP has “increased prices for its services, across the board, to maintain margins”.
Employment market creating (upward) pressure on wages.
Milk prices remain 50% higher than average over recent years.
It sounds like a favourable environment for NMRP:
Inflation has led to a scenario where marginal decision making for farmers carries more risk: higher costs for investment and higher input costs are making the need for robust data insights becoming ever more important. Furthermore, maximising the efficiency of a herd is the single most direct route for the dairy industry supply chain to achieve its sustainability objectives.
My view
I think there’s enough in this statement to retain my positive view on the company. Admittedly, growth in the short-term is not too exciting. However, revenue from “Genomics” has doubled compared to H1 last year, and while it’s still very small, I think this could add a fresh growth spurt to NMRP’s results over time.
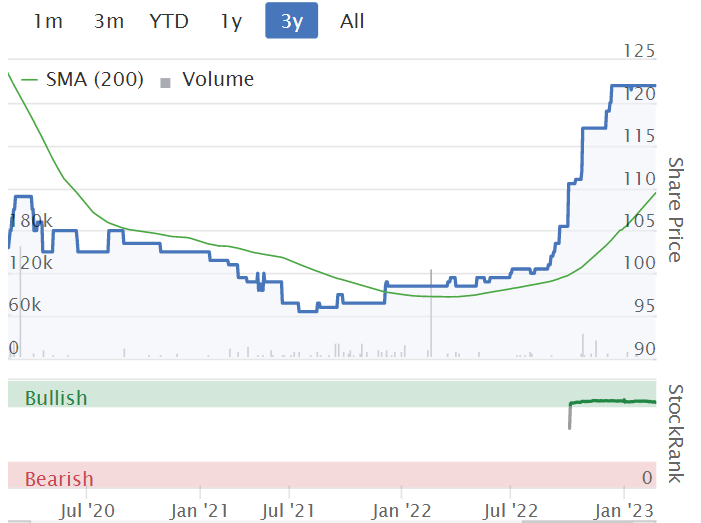
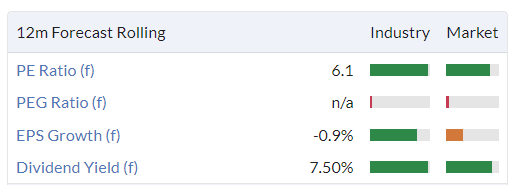
Valuation has remained reasonable, with a PER that would be suitable for companies of much lower quality:

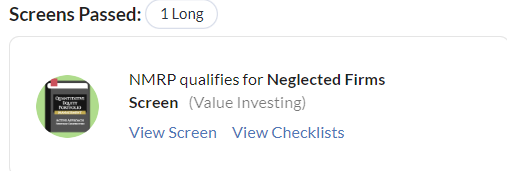
Helping to confirm its status as an under-the-radar stock, it passes Stockopedia’s Neglected Firms screen:
In summary, while I don’t see any immediate growth drivers for NMRP, I think Genomics could help to accelerate results over the medium-term. I also think the underlying business is very high-quality (as demonstrated by its high market share and financial returns), and the valuation is reasonable. So it gets the thumbs up from me.

Springfield Properties (LON:SPR)
Share price: 80p (-9%)
Market cap: £95m
Let’s take a look at the interim results from this Scottish housebuilder, for the period ending November 2022.
Revenue +85% to £162m (helped by acquisitions)
Gross margin 14% (H1 last year: 18.5%)
Adj. operating profit +21% to £8.2m
PBT down 5% to £5.9m
The profit result looks disappointing compared to the revenue growth, but we do get the explanation very quickly, and promised actions:
Significant impact from build cost inflation, particularly on fixed-price contracts in affordable housing, affecting margins across the Group.
Decisive action taken during, and post, period across the business to address the market conditions, resulting in expected annualised cost savings of approximately £3.0m
Housing categories
Private housing is by far the largest category at Springfield (ahead of affordable housing and contract housing), where I note that “reduced homebuyer confidence impacted private housing reservations towards the end of the period”.
More encouragingly, “since period end, the Group has been encouraged by the reservation levels across its brands”.
When it comes to affordable housing, Springfield has decided “to temporarily pause entering new long-term affordable housing contracts until market conditions improve”.
Similarly, plans to produce contract housing for the private rented sector have been withdrawn, “ following the Scottish Government's intervention in rent control”.
So the two smaller categories are both on hold, and Springfield looks set to focus instead on private housing.
Land bank sounds healthy with 16,975 plots (31 May 2022: 16,652), having Gross Development Value of £3.7bn (31 May 2022: £3.5bn). Given the market conditions, they reduced their land buying activity and wanted to make additional land sales, but could not get “acceptable value” for them.
Net debt rises to £74m (previous year: £43m) after two acquisitions. Land sales could be useful to keep a lid on this debt figure.
Facilities: the company has an £87.5m RCF and a temporarily increased £12.5m overdraft. My impression is that headroom is limited.
Dividend: possibly confirming my impression that headroom is limited, the company cancels its interim dividend. The company says that it does have a “strong financial position”, but that cancelling the dividend is “an appropriate and prudent measure to preserve liquidity in these uncertain times”.
Outlook is cautious, given the market backdrop. But official guidance is unchanged for the current financial year (Progressive are forecasting adj. PBT of £17m, rising to £20.2m next year).
My view
On balance, I’m inclined to think that this one could be undervalued. The factors impacting margin are, in my view, likely to be temporary in nature. Affordable housing will be purchased again, at margins which make it feasible for the builders. And rent control policies - which affect Springfield’s “contract housing” category - don't usually last forever. But of course the timing of when these categories might recover is uncertain.
Tangible net assets of £137m are significantly higher than the market cap.
Also, the land bank is very healthy and is possibly even too large, given Springfield’s debt load and lack of headroom. Some strategic land sales would be welcome.
Overall, I’ll stay neutral on Springfield, pending further research. Without the financial risk associated with using a temporary overdraft, I could consider taking an outright positive view on it.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

44 comments
Finsbury Food (LON:FIF)
The ABC is a bit like a "sale & lease back" with your own pension scheme.
The one most people have heard of was what M&S did with their pension scheme - they transferred properties to their pension scheme via an SLP (Scottish Limited Partnerships are used for technical reasons) and then the pension schemes benefitted from the rents of those properties.
If the sponsor goes bust the pension scheme has possession of the properties (or a lease on the properties).
I would guess the loan note is just structuring to avail the pension sceme of the income from the assets contributed.It is a fairly neat way of plugging a deficit in your DB pension scheme with assets you have on your balance sheet, without losing control of those assets in practice.
There are several flavours and the assets involved may not be real estate - it could be inventory or a portfolio of brand rights etc.
The problem with making big cash contributions to a scheme is that you can't ask for the money back if the deficit gets smaller, whereas contributing the assets (or in effect the income from the assets for a fixed period) smooths the hit to cashflow, while persuading the trustees that they are still OK if the sponsor goes bust.
Reading Paul's comment about Finsbury Food (LON:FIF) pension's scheme. As an experiment, I decided to see if ChatGPT could simplify the paragraph. I copied and pasted the following:
This was ChatGPT's reply:
"This statement is about a group of companies that provide retirement benefits to their employees through pension schemes. One of the companies, Memory Lane Cakes, has a pension scheme that promises a specific benefit amount to employees when they retire, regardless of how much money is put into the scheme. This is called a Defined Benefit Pension Scheme. All the other companies in the group have pension schemes where the amount of retirement benefits is based on how much money is put into the scheme. This is called a Defined Contribution Scheme.
The Memory Lane Cakes pension scheme has been closed to new members since May 31, 2010. The scheme currently has a shortfall of £6,582,000, meaning that it doesn't have enough money to pay all the promised retirement benefits.
To help fund the pension scheme, the company has entered into an agreement called an Asset Backed Contribution arrangement, where they will invest £16.0 million into the pension scheme. The trustees of the scheme have purchased a loan note from the company through a Scottish Limited Partnership structure, which will pay a fixed income of £763,000 annually to the pension scheme over the next 20 years.
The company estimates that the pension scheme will need funding for around 15 years to meet its obligations to employees who have already earned retirement benefits."
Not bad, I am impressed that it could simplify the paragraph. I need to understand how it works. At the moment ChatGPT is just a black box to me. But I can understand that Google has to do something soon.
Still did not explain what an Asset Backed Contribution really is...
It reads like me in high school trying, badly, to write an essay by just paraphrasing stuff :)
On Springfield Properties (LON:SPR) - from the SCVR article - "Given the market conditions, they reduced their land buying activity and wanted to make additional land sales, but could not get “acceptable value” for them."
Looks like another way to read this is that there's a lack of market demand now for housing land. Or the prices of housing land has plummeted, below the value that Springfield is willing to sell.
Either way, this is bad for valuations for existing landbanks in housebuilders, as well as land sellers like Harworth (LON:HWG) .
I'd be careful of extrapolating either across the sector or to valuations of existing landbanks.
The market is dislocated right now but think of it as liquidity led. The volatility caused in the mini budget has led to a pause in purchasing of land but not necessarily of valuations. What you are seeing is a 3 month lag effect filtering through. In essence major buyers are waiting to see if there is any distress to pick up assets cheaply. If you are not a forced seller then generally land and housing values aren't plummeting but buyers are sitting on their hands waiting for stability. A better indication will be in 2 to 3 months time.
Exactly. But wouldn't Harworth have less land sales in the meantime... Which means less revenues reported. Hopefully it is just a temporary freeze, and the pent up demand comes roaring back... with no loss of pricing...
Today in the times.
Some intelligent (Mensa) people have no common sense. I knew one, could not even change a lightbulb. High IQ is not always a good indicator.
I've known many people in my career whom could work out the area of a jam jar but couldn't get the lid off! lol.
I couldn’t open a jam jar at breakfast, so decided to have jam tomorrow.
underrated comment Raleigh. had me chuckling
My dart-throwing monkey would beg to differ.
Hi Caduceus, The FT covered the thorough Swedish research properly if the subject interests you.
May I ask if you could direct me to said article please?... or maybe provide useful search engine keywords?
No worries if not!
Intelligence is merely one factor. Other factors are things like agreeableness, dedication, work ethic, location, ambition, reliability. Intelligence (or lack of) only goes so far, it works the other way too. If you're not very bright but work long hours in a dangerous job you can make serious money.
Somebody posed the question, would you rather have a high IQ or luck? Then he said it is better to have luck because then you can pay people with high IQ.
Bango (LON:BGO) once again features on my watchlist, £200m market cap or so, software for marketing and sale of products/bulk payments and services to mobile phone users. Amazon, Google, and Microsoft use their technology to acquire more paying users. Today Bango have partnered up with Dropbox. 2022 seems a transformational year for the company after their earnings enhancing corporate acquisition last year. Any views or observations on what appears to be a fast growing co.
Bango (LON:BGO)
Company seems to be on a bit of a roll newsflows wise - the problem is its all a leap of faith as to whether they will start making real decent profits anytime soon. That date seems to be continually being pushed back - in some respects that makes complete sense reinvesting cashflow into expansion - facts are they have been starting year saying they will do x and end up doing y ref profits. I am currently invested here but i see my "investment" as being of the complete punt variety.
Even if we say they will make £7 mill profit - pe is still expensive. So i guess you either have the faith and take the gamble or wait on the sidelines.
It would be nice if they were organically smashing expectations ref sales - excluding an acquisitions. With recent intergration of whatever it is how decent organic growth is is is somehwat clouded.
Despite all then amazing signups they have - reality is is its slow progress ref explosion of growth in profits that holders are hoping for.
Take for example dropbox partnership - how will they profit from this partnership.
It would be great if they received commission ref signups - but i would be worried that the only way they may benefit is selling the extra data that turns up on their servers ? would be intersted if those in the know know if that is the case. Again if they need to get all the it in pace to integrate dropbox and have to wait for payback that is again pushing the pot of gold down the road.
Being honest i would be more comfortable sat on the sidelines with this share but i seem to have the inability to keep punts out of my portfolio. Not a recommendable investing characteristic ! In my defence here when i bought we were only 12 months away from first decent profits - problem is that is still the case today and may be the case in 12 months time!
Been a long term holder of Sylvania Platinum (LON:SLP)(LON:SLP) and as long as the company continues to be as well run as it is at present will be holding a long time into the future with it’s yield of around 10% and large cash reserves
Worth watching the investor presentation tomorrow at 12pm on the excellent
https://www.investormeetcompan...
Sylvania Platinum (LON:SLP) Chart of share price (*10) against platinium spot price.
Sylvania Platinum (LON:SLP) most of the profits actually come from rhodium rather than platinum. Rhodium prices have been weak recently which makes Sylvania's strong performance even more impressive
Sylvania Platinum (LON:SLP) Platinium group metal prices tend to pretty tightly track each other so irrespective of where SLP makes its profirts, the platinium price is an excellent guide, based on recent years experience, to SLP's share price. https://matthey.com/products-a...
I don't think that's really the case - Rhodium down from 30,000 a couple of years ago to around 11, 000 today. Platinum fallen by a much smaller amount over that period. The two metals have quite separate dynamics, and even over the last year have performed very differently.
I listened to an interesting Investor Meet Company presentation yesterday at 2pm by Polarean Imaging (LON:POLX) . Noticed the company first here on Stocko on the Speculative tab of an Excel spreadsheet at the start of the year (which I can't now find). Then Paul mentioned that he "know(s) a lot of shrewd investors who hold POLX shares, hence why I’m keeping an eye on it."
Anyway, whilst there might well be concern of a fund raise in due course (although they did say they had enough cash to last for Q1 2024 (I think), I can't understand why the share price has dropped by 20% since just before the start of the presentation yesterday!
Nor me. I have some shares in this and thought it would do well after it received FDA approval but the opposite seems to have happened. I understand the execution risk etc but even so, how can it be worth half what it was before?
It was "buy the news sell the fact" - it had been built up on the basis that the FDA would ultimately approve it, which they did. People were watching that event like hawks so there was a lot of hot money in it. They then sold into the rise to take profits and it drifted back.
The attention then turns to fundamentals - ie sales and revenues. Right now there are very little by way of revenues despite the tech. They are burning cash quite heavily so another fundraise appears almost inevitable to me. They have said it is likely themselves. Markets don't like that as it is uncertain - how much dilution, what price etc. In my view they would have been better raising immediately on FDA approval when there was good interest/liquidity to give themselves a 2 year runway.
But not having done that I guess it is now all about sales and the timing thereof. If they can get a couple of decent sales and demonstrate a growing pipeline I suspect the shares will perk up and the amount required in a raise diluted but until those sales are signed investors will be cautious. Plenty of great tech has never commercialised remember.
Ive never held Polarean Imaging (LON:POLX) but have watched it. If I see solid progress I may well get interested but thats my take on it right now.
PIs were seeking for short catalysts for the SP to rise. They didn't get any assurance from the management. Not only that, management did not take any questions on the spot, asking viewers to send in questions, this led to another immediate fall of c10%, driven by ST traders. All in all, seen the same trend in Angle (LON:AGL) , Diurnal (LON:DNL^K22) and now Polarean Imaging (LON:POLX) . In addition, biotech is certainly NOT soup of the day.
What's the attraction? Hyperpolarized Xenon gas requiring a 10-15 second breath hold inside a confined MRI scanner. I can't see much in the way of a requirement for this in a day to day hospital setting. Research sure, clinical trials maybe, but for everyday patient evaluation, I don't see what it adds, besides it can be used with IV contrast agents can it, so that rules out doubling up with perfusion imaging, which would be useful.
Hi Paul. In your comments on Trifast (LON:TRI) you say that "This is why the PER is quite a bad way to value companies, because profits can be so volatile, depending on circumstances that can't be predicted easily." Please can you tell us which method would normally be your first choice for valuing a company?
Thank you for your comments on Trifast Paul, maybe I should have been braver early yesterday but for now we've got enough! I look forward to Graham's comments on Carrs, another long term hold.
Sylvania Platinum (LON:SLP) has made the agenda, maybe we have a convert, or maybe not, time will tell
NextEnergy Solar Fund (LON:NESF) quarterly results this morning, this caught my eye, therefore sharing, numbers are from the IMF
Inflation rate (UK RPI) assumptions
31 December 2022
30 September 2022
2023
11.60%
12.40%
2024
7.00%
5.90%
2025
4.20%
3.60%
2026
3.90%
3.40%
2027
3.80%
3.90%
2028-2030
unchanged
3.00%
2030 onwards
unchanged
2.25%
Sylvania Platinum reads like an absolute stonking set of results. Although it's share price often linked to basket price of the stuff they unearth.
I agree. Rolling dividend 3p interim + 6p final (projected, based on new dividend policy). Net profit up 33%.
I agree, although there seems to be some negative correlation in shareprice with Tharisa (LON:THS) despite the fact that they both do the same thing - and both very well it would seem! I sometimes sell one to buy the other, then make the contrary trade, as their prices oscillate up and down - but not enough to change the price significantly!
Good update from Sylvania Platinum (LON:SLP) I hold, I did have concerns after Jubilee Metals (LON:JLP) update last week and falling platinum prices, surprised the shares are only up 3%. I don't currently hold Tharisa (LON:THS) but have been considering it.
Tharisa (LON:THS) I notice one director has been selling quite a few shares recently, there is the AGM tomorrow, maybe worth watching.
Options were expiring - Tharisa (LON:THS) management explain their selling on LSE BB.
Thanks, I did no know that, had enough trouble finding out, if they were buys or sales. Why can't they just state sold/bought x number @ x pence.
Tharisa (LON:THS) has not reacted to the Sylvania Platinum (LON:SLP) update.
That's what makes the results even more impressive. Spot prices on PGMs have declined during the period, and they still increase profits/dividend/cash/buybacks. Superb.
Sylvania Platinum (LON:SLP) The interesting thing is that Net Cash at 31 Dec was $123.9mm (102.4mm), almost 40% of the market cap, so the PE should be about 3. What are they planning to do with all that cash?
There is an Investor Meet Company presentation tomorrow at 12 noon, which is free to sign up for. They may answer the question then.
David
My morning smallcap tweet: Wake up and sell the coffin
Versarien (LON:VRS) Aurrigo International (LON:AURR) Spectral MD Holdings (LON:SMD) Zoo Digital (LON:ZOO) Revolution Beauty (LON:REVB) Scancell Holdings (LON:SCLP) Everest Global (LON:EVST), Carr's (LON:CARR)
◄Versarien (VRS)► FY-Sept. FY was extended to 18 months. Material uncertainty going concern stmt. Assumes it wins some grants, otherwise will need fundraise, another death-spiral etc. Graphene rev £2.1m (£0.7m). Loss £8.4m (£8.1m). Cash at hand £1.4m end Sept. Co "streamlining the business" ie loads of jobs gone. Ricketts laments "current macro-economic conditions combined with the disruptive nature of our products has delayed the commercialisation we were anticipating". [SP=6.82 Cap=15m]
◄Aurrigo International (AURR)► partnership agreement with Changi Airport Group for the continued joint development and testing of co's autonomous vehicles plus airport simulation software platform Auto-Sim. [SP=119 Cap=50m]
◄Spectral MD (SMD)► EU clinical study for its Diabetic Foot Ulcer application for the Company's DeepView technology. "There is currently no diagnostic tool available for early wound healing diagnosis." [SP=32 Cap=41m]
◄Zoo Digital (ZOO)► major Hollywood studioadopts ZOO's Globalisation Management Platform to support their content localisation. This client is also using ZOOstudio to manage localisation of content across its vendors. [SP=164 Cap=146m]
◄Revolution Beauty (REVB)► expects to publish delayed FY22 accounts on or around 30 Mar. Remains suspended. [SP=19 Cap=26m]
◄Scancell (SCLP)► encouraging early efficacy data fr.om monotherapy part of ModiFY Phase 1/2 clinical trial [SP=18.5 Cap=151m]
◄Everest Global (EVST)► will miss deadline for FY22 Results (1 March). Due to being unable to get an auditor with Public Interest Entity Auditor Registration Regulations approval. Co expects to finalise the appointment of an alternative audit firm shortly. What a shambles. [SP=3.5 Cap=2m]
In line: CARR
Profit warning (re FY23 EBIT of £60m or c.11% lower than consensus) from GB Group today.
Saying that it expects FY'24 LFL revs to improve to circa high single-digits by the y/e vs 4% LY - alongside flat 21.5% EBIT margins