Small Cap Value Report (Tue 21 June 2022) - REC, G4M, ASTO, HSS, K3C

Good morning! Paul & Graham are here with you today, for our usual trawl through the RNS, looking for opportunities in the small caps space.
Agenda -
Paul's Section:
Gear4music Holdings (LON:G4M) - my initial review of the final results for FY 3/2022 leads me to believe this share could be very cheap, taking a longer term view. In the short term there are obvious macro headwinds. Big changes in the balance sheet are worth noting, and not all investors will be comfortable with the large increase in inventories & bank debt. Slide deck is here.
Also, I had a quick Q&A with G4M management, with brief notes added here below.
K3 Capital (LON:K3C) - readers have asked me to review a strong trading update today. This looks an interesting, and highly profitable professional services business. If profits are sustainable at this level, then it looks cheap.
Graham's Section:
Record (LON:REC) - this currency manager is trying a new strategy of moving into fund management, after many difficult years of price compression in currency services. The strategy is already bearing fruit with large increases in revenues, margins and profits. I’m excited about the potential for the company to grow over time and become a larger, much more profitable business. It has built up an excellent reputation over many years, so I rate its chances of success highly.
Quick comments from Graham -
Assetco (LON:ASTO) [No section below] - As recently as February 2020, the purpose of this company was to provide “management and resources to the fire and emergency services in the Middle East”. That business suffered a revenue collapse, but was cash-rich, and so the company changed strategy. It is now involved in “acquiring, managing, and operating asset and wealth management activities and interests”.
It is led by three former top executives at Standard Life Aberdeen, including the co-founder of Aberdeen Asset Management. Today it announces the debt-funded, conditional acquisition of SVM Asset Management for £9 million. SVM is a well-known and long-established but, in an industry context, small-scale fund manager based in Edinburgh. This appears to be a sensible acquisition, both strategically and in terms of the purchase price.
HSS Hire (LON:HSS) [No section below] - this equipment hire business reports Q2 revenue up 10% versus 2021. Adjusted earnings are still set to be in line with expectations. As noted in previous SCVR, this company’s balance sheet has improved and strategy has evolved, meaning it is less of a basket case than it was when private equity dumped it on the market. Risk/reward has improved with net debt of just £45m as of the most recent year-end.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul's Section:
Gear4music Holdings (LON:G4M)
175p (before market open)
Market cap £37m
FYI, I’m not currently holding this share (as mentioned in April here), but want to buy back in at some point (subject to newsflow, and funds being available - which is a bit of an issue right now!)
Gear4music (Holdings) plc, ("Gear4music" or "the Group") (LSE: G4M), the largest UK based online retailer of musical instruments and music equipment, today announces its financial results for the year ended 31 March 2022.
PR headline -
"Good progress following an exceptional prior year"
These are audited accounts, and are in line with broker consensus -
Revenues £147.6m (as indicated in the April trading update)
Profit before tax £5.0m (no adjustments)
EPS (diluted for share options) 17.3p
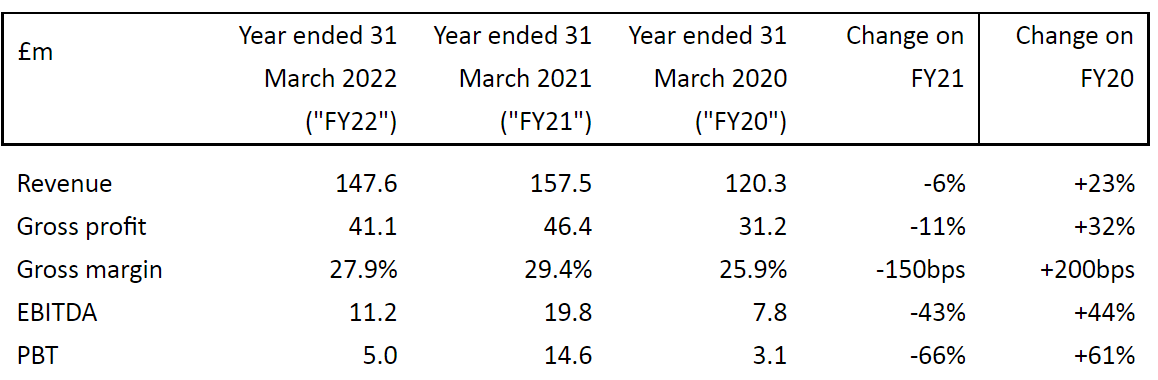
This table shows the huge boost last year got from the pandemic. Although note revenue, gross margin, and profit are all ahead of the pre-pandemic comparison year of FY 3/2020 -
.
Recovery in eCommerce shares - this is a key investing theme for 2022/3, for me.
I reckon a lot of eCommerce shares might have sold off too much, because the market has currently de-rated them as ex-growth. That’s happened because more normal trading now looks weak against last year, when the figures were hugely boosted by the pandemic lockdowns.
Yet many eCommerce businesses are still showing good 2-year growth rates. If growth resumes from now (when the last pandemic-boosted prior year comparatives disappear) to a more structural, long-term growth rate, of maybe 10-20% p.a., then I reckon many shares in this eCommerce sector could be tremendous bargains, and re-rate upwards, once people realise some of them actually still are growth companies.
There’s also potential help from freight & carriage (in & out) costs, and supply chains gradually normalising over time, although maybe that’s more likely to be 2023, rather than 2022? (judging from what other companies have been saying).
The key point being that there’s a continuing shift to online, in many areas of life, not just retailing. But the pandemic pulled forward a lot of that growth into year 1, making year 2 look soft in comparison, as physical competition re-opened. Now year 3 should compare more favourably against year 2. That’s the opportunity for good quality online businesses to see their shares re-rate to growth companies again. Maybe! It’s only a theory at this stage.
On the downside, we all know about inflationary pressures, and more cautious consumer demand, so that’s already in the price I would suggest, given calamitous share price falls across the whole sector.
It’s time to look for bargains, I reckon, if you’re brave. Or sit on the sidelines, and pay more once there’s more economic certainty. It’s a tough call. Or do a mixture of the two, with small initial purchases maybe? That’s my preferred method when unsure - dip my toe in, to get me focused on a share, then either build as confidence grows, or ditch them if it was a mistake.
Key points from FY 3/2022 results -
I’ll go through the figures & commentary again, in more detail, later. Also I have a call with management at 10 am, so have jotted down some questions.
On my first skim, these points jumped out at me -
Pretty solid results in the circumstances - the company remains profitable at £5.0m PBT, and doesn’t massage the numbers with adjustments.
Gross margin - of 27.9% looks low, and is down on (exceptional) last year, but up on pre-pandemic. The commentary makes an important point - that G4M’s prudent accounting policy means it absorbs outbound carriage costs into the gross margin. Adjusting this out boosts the gross margin to a more decent 34.9%. Also, when demand is soft, due to macro factors, having a lowish gross margin, and mostly variable costs (labour & marketing), is a good thing!
As I’ve mentioned before, yes the gross margin is quite low, but the average order value is decent at £125. Therefore the cash margin per order is £35 - which is not bad. Factor in lower returns than fashion businesses, and it’s a viable business model.
Outlook - sounds sensibly cautious, given macro factors -
As a result of Brexit, Covid, and now the war in Ukraine, the general outlook for many retailers during 2022 remains challenging and difficult to predict, with increasing product and overhead costs forcing up product retail prices and potentially impacting profits.
To help combat these challenges, we have a strong pipeline of growth orientated projects launching in FY23, and we will retain a sharp focus on productivity, efficiency and overhead cost control.
Inflationary pressures and weaker consumer confidence are likely to constrain growth in profitability in the short term. However, with the strategies and actions we are taking, along with our strong balance sheet and significant working capital headroom, we believe we remain well positioned to take market share and are confident in our medium and longer-term profitable growth strategy.
Growth projects sound interesting, and include -
AV.com being launched in Europe, after “successful UK launch” (this was a recent acquisition) - entered home audio/visual market
New range of own-brand premium products, with worldwide distribution planned.
Secondhand platform for musical instruments to be traded in.
Additional European warehouses now open, so should be scope for a resumption of growth in the EU, now delivery coverage is improved. A key advantage, is stock is now imported directly into the EU, rather than coming via the UK.
Current trading - sounds OK -
Trading in line with consensus market expectations for FY23
Balance sheet - some big changes here.
NTAV looks sound, at £28.7m - so the market cap of £37m is now strongly asset backed. This includes £8.8m of freehold property, which is a big plus for investors, as it reduces risk (banks are usually happy to lend against freeholds, and they appreciate in value long-term, especially when inflation takes hold).
The big moves are increased inventories, now up to a very high £45.5m. The company explains this as being a deliberate strategy, to get round supply chain problems. That makes sense to me.
The commentary points out that being heavily stocked up now, is presenting margin opportunities (i.e. higher inflation means raised prices, hence higher margins on existing stock bought cheaper).
Working capital is very healthy, with £53.3m in current assets (mainly inventories), and £17.4m in current liabilities, a very healthy surplus of £35.9m. This is a current ratio of 3.06, very healthy indeed.
However, remember that the bank debt is further down the balance sheet, with £28.0m borrowings in non-current liabilities. So make no mistake, the business is now dependent on bank financing. Not all investors will be comfortable with that. I am, because about a third of the bank debt is covered by freehold property, and the large inventories could be run down somewhat to generate cash and reduce (or even eliminate) bank debt at any time it might be required. There’s a lot of flexibility here, which I like.
Bank debt - a new facility of £35m was set up quite recently, which has been used to finance the higher inventories, and some acquisitions. Maybe the timing wasn’t great, given the economic slowdown now.
Going concern note - there’s some key information (positives) in here, which reassures me. Going concern notes are vitally important, and all investors should home in on them & read carefully, given current macro problems -
In FY22 the Group secured a £35m three-year committed Revolving Credit Facility with its bankers, HSBC, to make acquisitions and invest in stock for precautionary reasons during a period of potential supply chain disruption, and early in a period of inflationary cost price increases, putting the Group in a strong competitive position heading in to FY23.
The Directors have considered the Group's position and prospects in the period to 31 March 2023 based on its offering in the UK and improved proposition in Europe and concluded that potential growth rates remain strong.
There is a diverse supply chain with no key dependencies.
The Group's policy is to ensure that it has sufficient facilities to cover its future funding requirements. At 31 March 2022 the Group had net debt of £24.2m (31 March 2021: net cash of £2.7m), with £3.9m cash (31 March 2021: £6.2m cash), with a good and appropriate level of headroom that has been factored into the Directors going concern assessment.
The Group has conducted various budget flexes principally on a reduction in revenue, and performed a reverse stress test. There is no plausible scenario where the Group breaches its covenants, re-affirming the assessment of the Group as a going concern.
To reiterate a point I made above, as a lowish margin business, with variable costs, G4M should not be under threat of insolvency, even if demand drops a lot. It could de-stock, and slash marketing spend to survive, for example, if things really fell off a cliff. Modest fixed costs are a big advantage of eCommerce businesses, which is another reason I now really like this sector, which I see as irrationally cheap right now.
Cashflow statement - reflects the big balance sheet changes, so bank debt has shot up, which has been used to finance acquisitions, and a large increase in inventories. You’re either comfortable with that, or you’re not - I can see both points of view. Risk averse investors might not be happy, but for the reasons explained above, I’m fine with it.
Competition -
The competitive retail landscape in musical instruments and equipment is seeing a continued channel shift to online, albeit understandably at lower online penetration levels than during lockdowns. We expect the current challenging economic environment will add further pressure to less agile competitors already struggling post-Covid, thereby allowing us to take further market share. This, in turn, may present future growth opportunities for the Group.
My opinion - I need to re-read the results more thoroughly, and I’ve also got a call with management at 10 am, so am frantically trying to finish this section and think up some clever questions, so I don’t sound a muppet when speaking to them!
My initial impression now, is that this share looks really cheap, if you take a long-term investing perspective. It’s still a growth company, with plenty of good stuff in the pipeline.
I like the low operational gearing, and soft prior year comps it’s now up against, which makes a disastrous profit warning very unlikely, even if demand does fall a fair bit, which is possible of course.
Would I buy it at £100m market cap? No. But the market cap is only £37m. That’s ridiculous I think, taking a 2-3 year view, I reckon this could be 2-3 times the current price,with patience, and the fortitude to continue riding out this current bear market. There’s a ton of cash on the sidelines remember, so if we wait for happier days, then the price might have already taken off.
I’ll definitely be buying back in here, but need to find some cash first!
EDIT:
Q&A with management
This is the rough gist (from memory) of some questions I was able to ask mgt this morning -
Raising prices - yes prices are going up, a lot of it is automated. Have high inventories, so well positioned. Inflation is actually helping raise the average order value, which helps dilute carriage & marketing costs. So some advantages to higher inflation.
Supply chain - is improving now.
Wage inflation - is it difficult to attract & retain staff? Didn't say much in reply, but said yes we're having to pay people more, and given the exceptional year during the pandemic, that is the right thing to do. Pandemic boost gave the funding to considerably expand the team.
Distribution - I was surprised carriage costs fell, from 7.3% LY to 7.0% TY. How come? Product goes direct to 4 distribution centres (DCs) in EU & 1 in UK. Local fulfilment in Europe is important - speed, and keeps carriage costs down if it's within the same country. More expensive if dispatched from another country, even within the EU. Works well with smaller, country-specific DCs, different model to competitors (e.g. Thomann distributes from one large DC in Germany). Also gives competitive advantage with faster delivery, better customer service.
Customer returns rate - is only 5.5%. And lower still for own brand. Customer pretty much know what they've ordered. No issues with fashion, not perishable.
Online marketing costs - google & others seem to be price gouging online businesses - a problem for G4M? Very careful on marketing spend, to target & measure against results. Expert digital marketing team. Profitable from first order: cost of acquisition is £14, profit on first order is £33.
Brexit - G4M has its own distribution within the EU, so see opportunities for growth there. Is it easier to compete in the UK due to Brexit border friction for EU competitors selling into the UK? Some initial difficulties with Brexit, but companies are using a scheme called One Stop Shop, which is smoothing things over somewhat.
Growth initiatives - we're excited about AV.com (recent acquisition). New brand "G4M" for more premium, own brand products, will be higher margin, and looking at global distribution, including wholesale. It's next step in company's growth. We're not interested in sitting still, it's all about growing, and we want to be one of the world's largest musical companies. That's why we put in place the bank facility, so we could stock up to ease supply chain issues, and make some good acquisitions. Net debt is reducing now, as are inventories, as planned
Pandemic impact - presumably you're now coming up against softer comparatives, as the prior year pandemic boost washes through. Yes, from round about now the comps get easier. Still some pandemic boost in H1 LY, but H2 this year is up against softer comps.
Product categories - live gigs are back now, are you seeing boost from that? Yes, product categories selling best have switched around, with the big boost from playing at home in pandemic, to now seeing products for live playing (e.g. amplifiers) now taking up the slack. Very much as we expected.
Secondhand platform - how will this work? A lot of work has gone into this behind the scenes, will be launched later this year. Allows customers to sell secondhand musical equipment back to us. Has to be in perfect working order. Utilising the existing returns infrastructure, it's picked up from the customer in the same way, checked, then offered for sale. Good margins, and we'll only buy known bestsellers.
How are investors & analysts reacting to the results/outlook? Brokers seem pretty positive about the future.
My opinion - I learn a bit more about businesses each time they report, and it's great to have the opportunity to talk to management as well. Our time constraints & breadth of coverage mean that I only talk to mgt at the companies I think are the most interesting, and where I understand the sector.
The CEO & CFO at G4M are not at all flashy, they're quiet and measured in style, so I always get the feeling that everything the company does is well thought-through, not impulsive - clearly a good thing. There's no denying the ambition of the business, they want to grow this into a big business, and are focused on the next 5-10 years.
It's heavily IT-driven too, with an amazing 90 in-house software developers, plus a big marketing team.
As mentioned above, for patient investors who can cope with macro uncertainty & volatile markets, I do think sub-200p could be a very good long-term entry point for G4M. Nobody knows though, so as always, DYOR.
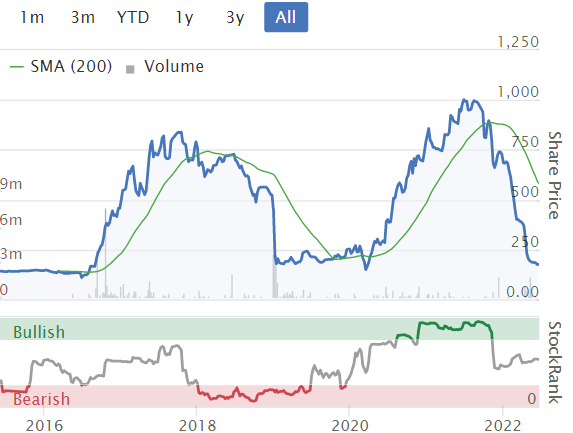
There have been 2 great bull runs for G4M shares in the past. I reckon we could get a third, it's the timing that is unknown. Meanwhile, on value metrics it stacks up - with the current PER only about 10. Hence nothing in there for planned growth. I think that's attractive.
It's astonishing to see the share price right back down to where it started, on listing 7 years ago. Yet the business is multiples the size, profitable, and international now. Yet the same share price! There's no even been much dilution: from 18m to 21m shares in issue over that 7 years. Mgt has sold a lot, but the CEO still owns almost 23%, so plenty of skin in the game.
.
.
K3 Capital (LON:K3C)
258p (up 10% at 11:03)
Market cap £190m
K3 (AIM: K3C), a multi-disciplinary and complementary group providing specialist advisory services to SMEs, incorporating Business and Company Sales, Restructuring and Insolvency and Tax Advisory services, announces an update on trading for its financial year ended 31st May 2022.
PR headline -
Revenue and EBITDA expected to be comfortably ahead of market expectations
Jack used to cover this company, so I’m re-acquainting myself with it today.
Headline numbers are certainly eye-catchingly good -
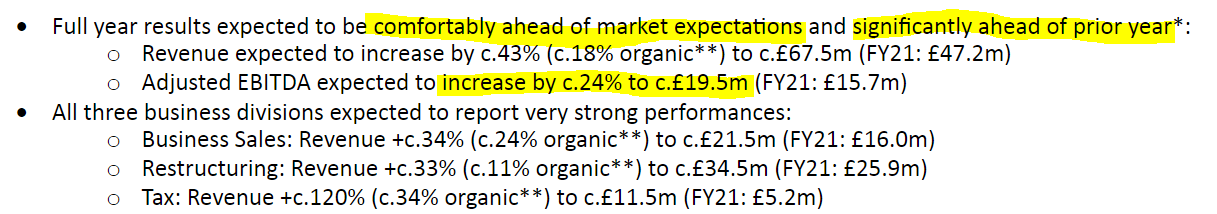
*Market expectation based upon Numis research note of May 22 (£63.5m revenue and £18.2m EBITDA)
It doesn’t provide the split of EBITDA by division in this update, but the last interims do, and show that EBITDA margins are highest (both around 50% of revenues!) at the M&A, and Tax divisions.
Restructuring has a still good, but lower 18% EBITDA margin.
The M&A division looks the profits powerhouse, making £5.0m EBITDA in H1, 48% of the group total. So you could argue that profits might be vulnerable to a slowdown in M&A.
There again, restructuring is counter-cyclical, so could offset that maybe? I don’t know the business well enough to say, but it’s clearly doing very lucrative work, which makes me wonder how it manages the split of the loot between staff & shareholders, which is often an issue with professional services businesses.
Readers who know the company better than me might be able to answer some of these queries. I’m just doing a quick review of the figures.
Balance sheet - the company calls it “robust” with £12.0m in net cash. Although on checking the last published balance sheet (interims, as at 30 Nov 2021), it only had NTAV of £7.9m, which is adequate for a people business (negligible fixed assets), but not what I would call strong.
Outlook - I was worried that M&A could be a problem area in an economic slowdown, but the pipeline sounds good -
"We are continuing to demonstrate over-delivery against market expectations, highlighting the resilience of our diverse business model. Against a backdrop of wider macro-economic challenges, our growing base of SMEs turn to us for essential services throughout their business journeys. Whilst we are seeing a growing demand for Restructuring services as SMEs navigate economic headwinds and unwinding of covid Government support, the opportunity across Business Sales and Tax is buoyant as we grow our footprint and apply our specialist skills. My thanks must go to all our employees for their dedication and hard work in delivering these results.
"We anticipate another year of growth across all divisions, supplemented with an attractive pipeline of M&A opportunities."
Valuation - last night’s numbers show a value share here - low PER, and great dividend yield (although negligible asset backing -
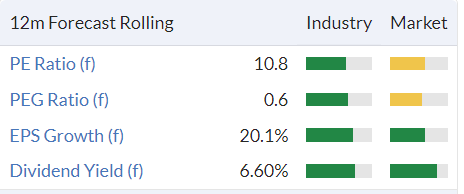
The big question is whether bumper profits can be maintained?
I don’t have a view on that, and can’t access any research (Numis - enough said!).
My opinion - I can see why several readers like the look of this - the figures seem highly impressive.
Also, management seem to have made skilled acquisitions, without constant dilution. The share count was flat at 42m for 5 years, then jumped to 70m in 2021, so it looks like there has only been one fundraising since listing in 2017, yet it has achieved massive growth in profits and EPS recently. If mgt can repeat that trick with further acquisitions, then this could get a lot more interesting.
With some counter-cyclical work (e.g. restructuring division), and a good pipeline in the more cyclical M&A side, then profits might prove resilient, or they might not, who knows?
The valuation has dropped by about a third this year, presumably as the market discounts a slowdown in M&A if we go into a recession? That’s flattering the market by assuming it’s rational of course, which it isn’t necessarily, especially at the moment, where selling is often led by momentum and fear.
Given the disconnect between this sparkling update today, and the drop in share price this year, then I imagine this share would be a comfortable hold, or even one to top-up maybe? That’s providing you don’t expect profits to nosedive in future.
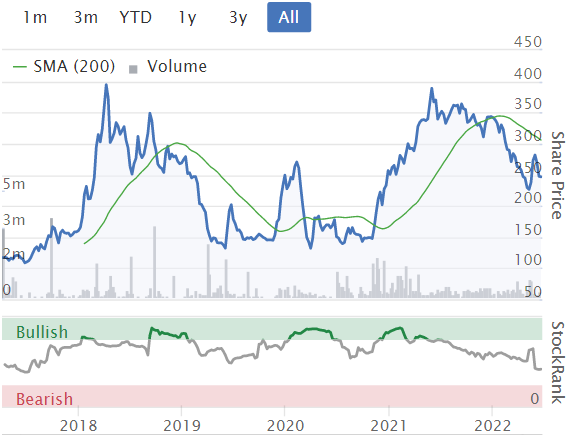
Looking at the long-term chart, something seems to have gone wrong from 2018-19, so it would be worth seeing what caused that, and if it could happen again?
.
.
Graham’s Section:
Record (LON:REC)
This is a currency manager that remains under the stewardship of its founder Neil Record, who first started it back in 1983, and who still owns 7% of the company.
I heard him give a lecture about returns in the currency markets quite a long time ago, and didn’t forget the name.
I even ended up buying a few shares in REC back in early 2018, but didn’t have the conviction to stay with it for the long-term. So I missed out on the share price rally which did eventually occur, but not until 2021!
In recent months, the share price has been softening again:

Today’s results are for FY March 2022, and show that 2021 was indeed a very successful year:
· Revenue +38% to £35m
· PBT +76% to £10.9m
The operating margin improves to 31% (from 24%), and dividends are massively boosted.
Why so successful?
For most of the time that I’ve been studying this company, it has been struggling to raise AUM and struggling to charge its clients properly, as currency services become cheaper and commoditised.
After all, if you’re a large corporation who needs hedging services, there is no shortage of banks and smaller firms who will line up to assist you. The forex market is incredibly efficient, and always changing to become even more efficient. It’s no easy task for a small company in this market to remain fresh, innovative and competitive!
Record allowed its basic fees to erode, but hoped to make up the loss with performance bonuses. This didn’t work too well.
More recently, it has branched out into new products and is, according to the new CEO, moving “from a pure currency management specialist to having a broader offering in the alternative asset management space”.
In her own words:
Whilst our core skills in currency and derivatives will continue to provide an important and robust source of hedging revenue, our focus on innovating and collaborating on higher revenue-margin products will continue to increase our profitability, as evidenced this year by the increase in our operating margin.
In my words: Record is now looking to become a fund manager with currency expertise.
While that’s easier said than done, I am inclined to believe that this is the right move for the company: it has the credibility to move in this direction, it will already have many of the right skills, and from an economic point of view, it makes far more sense than continuing to suffer the margin erosion in currency services.
You can find some details about Record’s EM Sustainable Finance Fund here. According to the FT, the fund currently has a size of £909 million, with an ongoing charge of 0.82% (so you can start to guess at the prospective revenue from this product!). The objective is straightforward enough: “to achieve capital gains over a medium to long term time horizon.”
Note that Record’s AUME (assets under management equivalent) only increased by 4% this year, but management fees increased by a staggering 37%. The margins on fund management are vastly greater than the margins on currency management. So I’m not sure if the comparison of AUME to prior years is even worthwhile at this point, since we are comparing apples to oranges.
Neil Record says this is “the start of a new chapter in Record’s history”. I’ve added the bolding below:
We plan to diversify into areas where specialist skills are well rewarded; where investor appetite is high, and where our existing expertise can be put to use… I am pleased to report that we plan to launch further funds with a variety of different investor appetites and asset classes.
Financial performance
For as long as I’ve been watching it, this has always been a cash-rich, cash-generative company which paid out generously to shareholders. That remains the case today. Cash inflows from operating activities for FY 2022 were £11.4 million.
Net assets finished the year at £26 million, or about £20 million even if you deduct the value of all non-current assets.
The dividend policy is aimed at 70%-90% of annual earnings for the ordinary dividend, and a special dividend if the company can afford it! Very few companies are able and willing to do this - either because their earnings are non-cash, or because they need to reinvest whatever cash they generate!
Outlook
Neil Record is positive on the outlook for the company he founded, but very worried about the wider economic outlook.
As I have already mentioned, we are witnessing a fundamental change in the business, which I believe has the potential to transform for the better Record's scale and resilience within the next few years. This leaves me feeling very optimistic for the firm.
CEO Leslie Hill writes:
I believe we can combine the flexibility and agility of a small business - as is shown by our Tech transformation, with the scale and credibility of a much larger business, as is demonstrated by our asset base, our growing global reach and the scalability of our product and service offering.
My view
I’ve allowed myself to get excited about this change in Record’s strategy. Now I’m going to have to go and reflect on all the reasons why it might not work!
But a successful fund management company does great things for its shareholders (assuming that it does a decent job for its customers, of course!).
The shares are up 12% this morning, leaving the company with a market cap of £147 million. Given the potential of the new strategy, and the growth already achieved in FY 2022, this looks to me like an unflattering valuation.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

49 comments
hi Graham
Just a follow up on your recent write up on Record (LON:REC)
Your write up was very positive although in your summary you said 'I’ve allowed myself to get excited about this change in Record’s strategy. Now I’m going to have to go and reflect on all the reasons why it might not work!'
Over the weekend I had a read of the FY '22 Annual Report and one particular aspect (Directors' Remuneration) rather took me by surprise and I'd appreciate your views on this please.
The CEO, Leslie Hill received total remuneration of £2.395m (£724k fixed, £1.671m variable) whilst the CFO, Steve Cullen, received £258k (£153k fixed, £105k variable). So the CEO's total remuneration was a multiple of 9.3 times the CFO's. I find this quite staggering.
I wonder what the CFO thinks of this and what effect it might have on their working relationship?
In the company's defence the Remuneration Committee Chair states;
'The Group is in a three-year transitional phase where the current senior managers prepare to hand over to the next generation under our succession plans'
and
'To deliver the Group's three-year strategy, the Board believes that it is imperative that our current CEO, Leslie Hill, continues to drive this strategy. Our new Remuneration Policy for our CEO has therefore been designed to ensure that she is motivated and incentivised to deliver this three‑year
strategy'
Although Leslie Hill does appear to be doing a good job in this transitional phase the huge imbalance in total remuneration between CEO and CFO seems way out of kilter to me. I'd very much appreciate your views please.
I hold.
Looks like they had to pay her in excess to get her to stay. She will get up to around 30% of the total forecast increase in revenue (over the next 2 years). I'd think that if they really feel they need to pay those sorts of sums to keep her they should be speeding up their transition.
Paul; Thanks again for your extensive indepth analysis. Particularly welcome in this difficult period.
Gear4music Holdings (LON:G4M) has a high volume of trades today without the price moving after the opening rise. If ADVFN's trades screen is to be believed, there have been almost no sales and that high (for G4M) volume has been almost all buys. Seems odd.
There might be a broker faciliating a big sell order which will be late reported.
I bought Record (LON:REC) 10 months ago at .92p, have I done the correct thing in still holding them?
Ask yourself why you bought them. Ask yourself if anything has changed. Consider the change and ask yourself if you are still happy with them. If you want advice see an adviser I am sure they will be happy to take your money.
Gear4music Holdings (LON:G4M) (I hold) have increased inventories by £17m in a year. They're far from the first figures I've read over this year where a company has significantly increased inventories to handle supply chain issues. So, speculating vaguely, when supply chains return to normal is there not quite a risk of a significant slow down as inventories are unwound, particularly for B2B businesses?
jape
Surely being able to reduce inventories will increase profits assuming constant sales and other costs.
Not for their suppliers.
FREng
Surely being able to reduce inventories will increase profits assuming constant sales and other costs.
generally reducing or increasing inventories with static sales will be profit neutral - if you reduce inventories you simply take the cost from your available stock rather than having to buy it in - so the cash cost of buying in stock items will be less but the profit will be the same as the stock item is moved from balance sheet assets to profit and loss costs which creates the same p and l charge as buying in similar item.
Morning Paul Scott to differentiate from confusing (to me) Paul.S. Would you have a look at K3 Capital (LON:K3C) please. For some reason it seems to have slipped off your radar this morning.
For months now in report after report they say they are doing well and even on one occasion recently had to put out an RNS which said we don't have any idea why the SP is behaving as it is.
The latest Trading Update does what the company says on the can. This is a well diversified well run company which is firing on all cylinders making well thought out acquisitions and just getting on with the job. Yet the SP is 38% off the year high, and the relative strength is showing gradual deterioration month after month.
Now it comes in with a stonking FY trading update with positive outlook and it puts on a respectable but not exciting 9-10% which no doubt in the current market sentiment will drift off during the day.
The Stocko rating is really not exciting at 42 - versus 76 a year ago - and is even showing Momentum as declining. Really? I'm bemused. Please help me to understand things I'm missing.
Morning ridavies,
I don't know K3 Capital (LON:K3C) because Jack used to cover that. But I see it's up c.10% today, and your synopsis has engaged my interest, so I'll have a fairly brief (nearly lunch time) and non-expert look at it next!
Regards, Paul.
LON:K3C
"it’s clearly doing very lucrative work, which makes me wonder how it manages the split of the loot between staff & shareholders, which is often an issue with professional services businesses."
I asked a related question at an InvestorMeetCompany presentation. The CEO explained that their clients are small and so the nature of their M&A business is high volume, relatively low value. This means they don’t rely on expensive ‘rainmaker’ partners to drum up new business. The business model is partially predicated on embedding clients into an on-line ‘support community’ with multiple resources available and managing data to identify client cross sell opportunities e.g. tax optimised post M&A Capex or restructuring.
Unfortunately, the answer to my specific question wasn’t included in the available recording but I thought the presentation was excellent and well worth watching.
https://www.investormeetcompan...
Paul - of Gear4music Holdings (LON:G4M) you say "Mgt has sold a lot, but the CEO still owns almost 23%, so plenty of skin in the game".
The same is true of K3Capital (LON:K3C) where CEO John Rigby has 10.36% (a smaller % but around twice the value cf G4M and nothing substantial sold since 2018). It comes across to me that he is very much the vision and drive behind what is going on there and I very much agree with Cuddlesticks that the best way to get the feel of that is to watch the most recent interim presentation at IMC - https://www.investormeetcompan... If you only have a couple of minutes watch the bit on Growth Strategy starting 13m 14s in.
Regarding Gear4music Holdings (LON:G4M) I think the bank facilities are reassuring. Banks will scrutinise the latest management accounts and forecasts.
I would however suggest that they bank facilities are quite highly leveraged against the asset base. Property would typically be considered at 70% loan to value. Inventory would typically be considered at 20-30%.
That would suggest they have very profitable forecasts that show debt servicing capabilities.
I am well under water with Gear4music Holdings (LON:G4M) but still see it as a long term hold.
Regarding Gear4music Holdings (LON:G4M) I think the bank facilities are reassuring. Banks will scrutinise the latest management accounts and forecasts.
It looks like the increased debt is at least partly due to build up of inventory. You'd imagine this will be a common theme for a lot of businesses moving from just in time to just in case delivery models due to supply chain problems.
To some extent it's a one-off effect, because once inventory has been built-up it's largely a case of incrementally adding to it as it's depleted. However, for businesses whose competitive advantage lies in high turn over and quick responses to trends it's a problem as they'll presumably end up with stock that they can't shift and will need to write off.
I don't know but I'd imagine most of G4M's stock has a long life, so simply having it sitting on a shelf somewhere is capital tied up rather than (potentially) permanently lost.
timarr
PROCOOK (LON:PROC)
Interesting to note stake-building in this direct-to-consumer cookware company by large established ( in 1919) family owned German cookware company Fackelmann.
PROC recently listed and the shares are currently hungover from lockdown sales boom and cost of living pressures.
Long term it looks interesting given:
-large family holding (>50% from founder, brother and wife)
- endorsement of Fackelmann
- excellent trustpilot reviews 4.8/5
- continuing growth in customer numbers even as average spend falls in short term
Good piece Graham. I am a long term holder of Record because they have always paid good dividends, have a great founder and share holder in Neil Record and a very strong balance sheet. My impression is the combination of Leslie and Neil works really well. Having worked in the fund management industry for years I can vouch that it is not easy building assets and remember currency isn't assets under management but the impact, which is why they use AUMequivalent. That said if I was building a business, one with the history and contacts into significant funds and houses would be one that would in my opinion have a clear advantage. The industry is all about knowing people. They are very shareholder conscious. What's not to like?
Thanks Camtab, nice points...!
Encouraging to see this morning that Gear4music Holdings (LON:G4M) thinks it continues to trade in line with expectations for FY23 at this early stage. I've bought this morning based on that update.
Some thoughts from me based on this update:
Pros
Negatives
Even if the company misses broker forecasts (as it did during FY22) I think this is still an attractive long-term entry point. The last time Gear4music Holdings (LON:G4M) was this cheap was in March 2020 and in early 2019 when it had prioritised revenue growth at the expense of margin - something management have since corrected.
Edit: One further reflection this morning is you can buy two different online retailers at wildly different prices. Boohoo (LON:BOO) is trading at 26-36x (depending on broker) current year estimated earnings with no current end in sight for US & EU revenue decline while Gear4music Holdings (LON:G4M) is trading at around 14x current year estimated earnings with stable UK and international revenue in Q4'22 against presumably tough comparatives. Brokers expect low single digit revenue growth for Boohoo (LON:BOO) and double digit growth for Gear4music Holdings (LON:G4M) during FY23. I'd suggest Gear4music Holdings (LON:G4M) is the better investment.
Patrick L
Brokers expect low single digit revenue growth for Boohoo (LON:BOO) and double digit growth for Gear4music Holdings (LON:G4M) during FY23. I'd suggest Gear4music Holdings (LON:G4M) is the better investment.
Its not all about revenues though is it - short term Boohoo's profits have taken a massive hit but they are currently expected to double profits next year - so yes of course it will look expensive in comparison to pretty much everything if you ignore the expected doubling of profits next year (and hopefully further progress after that) . In similar manner G4M probably looked expensive on current year metrics compared to boohoo or pretty much anything else in 2019 when they temporarily hit the buffers ref profit evaporation!
VLX (I Hold) - report final year on Thursday, which looking at Q4 trading statement (which was really bullish) will be ahead of expectations and they did reassure that they had pricing power in that trading statement (again pretty bullish).
Following Q4 statement and a blip the SP continued to fall.
If the same language is used for the year end, and backed up by the ahead Y/E then I feel a bounce is on the cards.
A positive week would add fuel to the fire.
Sosandar (LON:SOS) seems to look interesting at current levels. Down ~35% since it’s excellent trading update in April. Management expect no hit from cost of living crisis either due to “affluent” customer base
Paul, final results from James Cropper (LON:CRPR) with stellar performance from TFP (£8.7m profit) with other divisions lossmaking and hampered by energy costs. Quite a few moving parts - would you be willing to take a look? (I hold)
I really like this company (James Cropper) but I wish they would do something about liquidity. Very difficult to get scale in.
Hi Paul can you comment on the potential acquisition by Tremor International (LON:TRMR) ? According to sky news it could double their profits ?
https://news.sky.com/story/lon...
Finncap released a short note on the extended VIDAA investment/agreement today. Basically saying they will keep targets the same until more information is released with Q2 results. No mention of the potential Amobee acquisition.
they have to do something with all that cash...
Re Tremor International (LON:TRMR) and Amobee, this was on Morningstar this morning.
Alliance News) - Tremor International Ltd on Tuesday confirmed it is in talks to take over an American advertising company, and announced an investment in the connected television market.
In response to a Sky News report, the London-listed digital advertising firm confirmed it is in talks to acquire Amobee, a digital marketing technology company.
The talks come "alongside a number of ongoing strategic discussions with other third parties, which is considered normal course of business by management and in line with its stated [mergers and acquisitions] policy", Tremor said.
Hi truegent,
I'm sceptical on Tremor International (LON:TRMR) and it's a complicated one, so not something I follow. Am happy to look at the next results, if readers want me to, but I don't have anything to say about potential acquisitions. Feel free to discuss here though, if you think it's interesting :-)
Regards, Paul.
paul, if you have the time/inclination please add some comment on takeovers.
It seems EMIS (LON:EMIS) (I hold and is not really a smallcap) is being taken over
Great news for EMIS (LON:EMIS) holders, at a nice bid premium. I used to own this stock but felt it was a bit pedestrian, with all of its eggs in the NHS basket. There were some scary cases of hackers/ cyber attackers gaining access to health care systems around the world, and installing ransomware - basically shutting down health care provision for weeks! I was concerned that EMIS were vulnerable to this, with potential reputational damage. Clearly my concerns were of little merit, and I'll add this one to the list of bad calls!
Good update from K3 Capital (LON:K3C) that highlights the disparity between the business and share price performance in the current market, especially for UK small caps. I hold.
In such markets I try as best as possible to follow the advice of many great investors to be patient and do as little as possible., which is difficult.
Jesse Livermore “It was never my thinking that made the big money for me, it always was sitting.”
Anyone think it looks odd they were up 6.38% yesterday on higher than normal volume the day before a good update
Can you specify which company you are talking about please. It really helps.
I agree. It really does help if people can name the company they are refering to when posting about it in the comments section.
These statements only lead to a short term up tick going by recent moves. Will be back to 230p soon. Just look at £vlx
Can you specify which company you are talking about please. It really helps. It is surprising that you already have 3 ticks since they dont know either!
Attempt 2, I'm referring to volex £VLX. I hold both btw
I agree. It really does help if people can name the company they are refering to when posting about it in the comments section.
A reminder that £CGS CEO Adam Vicary and FD Steve Mant will present the FY results at a webinar for private investors today at 12pm
The company has been written up positively by @Roland Head and @ Graham Neary and was most recently called “A dividend hero with a track record of profitability stretching back decades” by Graham.
Hear for yourself why the company is looking forward to the future with confidence.
Register here: https://us02web.zoom.us/webinar/register/4616520829694/WN_mpyiGGF5TSO1zPTrLZGI8w
Record (REC) final results out today with continued diversification strategy and good management paying dividends, literally. I hold.
RE: Record (LON:REC)
Revenue up 38%, PBT up 76%, dluted EPS up 60%, 57% increase in ordinary dividend and 104% increase in special dividend. Not much not to like.
It'll always be fairly niche and a bit volatile, but the new management team seems to be making progress after the company was static, albeit profitable, for many years.
timarr
Yes, Record are very interesting. Diversification strategy is working. Possibly a bid candidate when Neil Record eventually retires as well. Could do well in an era of rising interest rates if currency for return takes off as a product again. I hold.
Sam Smith today announces she is stepping down after leading £FCAP for 24 years. We will see if this prompts any consolidation among the smaller brokers.
For what it is worth Vin Murria is a 10% shareholder
K3 Capital (LON:K3C) confirming that business is going well and ahead of forecasts (a simple clear quantitative report). The recent SP consolidation appears to be entirely due to market conditions IMO. Hopefully todays report and confident outlook will result in a change in momentum. Any wise words would be appreciated.